scroll top

According to the S&P CoreLogic Case‑Shiller U.S. National Home Price Index, U.S. home prices rose sharply during the pandemic years and remain roughly 40%–45% higher than pre-2020 levels, even after recent market cooling. Prices surged due to historically low interest rates, tight housing supply, and strong buyer demand, and while growth has slowed, prices have not meaningfully returned to pre-pandemic norms.

Data from the National Association of Realtors shoqw that today properties spend close to a month on the market on average.

After multiple rounds of interest-rate hikes aimed at controlling inflation, the housing market has shifted. Higher mortgage rates have reduced buyer affordability, cooled demand, and made price growth uneven across regions. For homeowners, this means selling is no longer guaranteed to be fast or friction-free, especially without pricing aggressively or offering concessions.

If you need to sell your home quickly — because of divorce, foreclosure risk, job loss, or other financial pressure — a traditional home sale may not be the best option.

While you’ll usually receive less money selling your home for cash to an investor or cash buyer — around 10%–15% below market value, according to academic and industry research — it can be a practical option if speed, certainty, and simplicity matter more than maximizing price.

How does a cash house sale work?

In a cash house sale, a buyer pays the seller an agreed-upon amount to purchase the home, without a mortgage or other financing. Cash sales can be made by individual buyers, real estate investors, or by companies that regularly buy houses for cash, called iBuyers.

Some of the biggest and most reputable iBuyers are Offerpad, Opendoor, Zillow Instant Offers, and RedfinNow. 

If you sell directly to an iBuyer, the process typically works like this: 

  1. Go to the iBuyer’s website to submit information about your home, including videos and photos if possible. 
  2. Receive a cash offer from the iBuyer based on the information you’ve provided. 
  3. If you are happy with the initial offer, accept it and set a date for the home inspection and closing. If you aren’t happy with the offer, you may be able to negotiate a higher price if you are able to prove your home is worth more. 
  4. The iBuyer will order an inspection of the home and recommend any repairs or a decrease in the quoted offer. 
  5. Close on the home and move out (learn where to find affordable movers). 

How to sell a house for cash before or after divorce agreement finalized

In general, attorney legal advice is to not sell any assets acquired during a marriage, or that may be considered marital assets until the divorce is finalized. However, if you and your soon-to-be ex agree, you could sign an agreement through an attorney to put your house on the market to free up much-needed money for both spouses to buy new homes, pay for attorneys, and otherwise get on with life.

If you choose to sell your house — through an agent, For Sale By Owner, or for cash to an investor — typically if it were purchased during the marriage, then any profits would be split 50/50 between you and your partner.

You can use that cash to pay off debt, buy a new home, invest in a different career, save for retirement, or to pay for your kids’ education.

How much do I get if I sell my house as is for cash?

How much money you get selling your house for cash as is depends on the type of cash buyer you sell to, as well as the current state of the market and the condition of your home. 

According to research from the University of California, San Diego, home buyers who took out a mortgage paid an average 11% over what all-cash home buyers paid for a home (which means you could make about 11% less selling your home for cash).

Real estate investors and iBuyers will usually try to buy your home for cash below market value so they can turn around and sell it for a profit. 

Tomas Satas, a real estate investor/flipper and founder and CEO of Windy City HomeBuyer, an iBuyer based in Chicago, says the maximum he pays for a cash deal for a home is 98% of the listing price.

“This is for a property that I am not going to have to rehab before I can sell it,” Satas says.

Rinal Patel, a licensed Realtor based in Philadelphia, says that while you may have to accept a lower selling price if you choose to sell your house as is for cash, you will avoid paying a real estate agent’s commission (6% is standard) and traditional closing costs (typically 3-6% of the home price). 

Some iBuyers do charge a commission fee to cover the eventual closing costs involved in selling your home. For example, Offerpad’s service fees range from 4-7%.

“If you’re looking to sell your home fast and don’t mind a lower price, selling for cash may be the way to go,” says Patel.

Where and how to sell used furniture online or locally

How do you negotiate a cash offer on a house?

If you don’t believe an initial cash offer is fair, you can negotiate with the buyer to arrive at a price that works for both of you. For example, Offerpad allows you to discuss with your Offerpad advisor why you think your home is worth more and try to negotiate a higher price.

Bill Manganaro, a real estate agent and investor in Columbia, Tenn., says a seller negotiating a cash offer on their house should aim to get enough money to cover what’s left of their mortgage. He says cash buyers typically look for homes that would be a good flip, so they have to determine the cost to fix the home, put it on the market, and sell it at a profit. 

“Based on these costs, we can arrive at a fair offer amount to present to the seller,” he says. “Whoever the buyer is, if he’s ethical, he should never make his offer based on how desperate a seller is to sell.”

Who buys houses for cash?

There are several types of cash buyers: 

  • iBuyers – These are companies, like Offerpad, that buy houses for cash directly from homeowners and sell them for a profit. 
  • Investors – Real estate investors might work on their own or as part of a team of investors to purchase properties and either sell them as is, rehab or “flip” them, or turn them into rental properties.
  • Traditional cash buyers – These are buyers who can afford to buy a home outright without taking out a mortgage. They might be looking to buy the home as a primary residence or vacation property. 

Are companies that buy houses for cash legit?

“We pay cash for your house.”

“We buy ugly homes.”

“Cash 4 homes.”

There are many quality local real estate investors who will pay cash for your home.

Offerpad and some of its competitors are legit, as are many local investors. If you plan to sell to a cash buyer, read previous customer reviews to ensure you’re selling to a reputable company or person. 

Sell house for cash? Pros and cons

Selling a house for cash isn’t for everyone. Here are some pros and cons to selling your house for cash: 

6 pros of selling your house for cash

1. Selling your home for cash is nearly always faster than selling on the market — there is one offer, and no financing required. “Financial distress typically comes with a tighter timeline and doesn’t allow for a financed sale,” says Andy Kolodgie, owner of The House Guys in Virginia. “If a foreclosure or tax sale is set to take place in two months, a financed purchase will not occur in time. This is where selling your home for cash can provide value with a faster close.”

2. You only negotiate with one party: The buyer. If you put your home on the market, you likely have to make concessions with the real estate agent and negotiate with one or more offers, as well as deal with the lender, inspector and appraiser.

3. It’s easy — you don’t have to clean up, fix up, repair or show a home if you are selling for cash. No open houses, keeping the yard kept or the rooms tidy. The buyer likely an investor with plans to tear down, renovate or otherwise has plans for what they are buying. Sold!

4. No dealing with a lender, and financing that can fall through. “When you sell a house for cash, you avoid the complications that come with a traditional home buyer’s loan application,” says Chris Chavez of DFW Fast Home Buyers in Fort Worth, Texas. “Your buyer may not get the loan approval when it was anticipated or they may change their mind altogether. Since most cash buyers use their own cash to buy houses, we can close quickly and aren’t at the mercy of banks. This means a faster closing with less hassle than going the traditional route.”

5. Selling a home quickly might save money — especially if you do not live there. Each month that goes by without a sale means another payment for mortgage, taxes, utilities, yard maintenance, and lost interest on any profits!

6. You are behind on mortgage payments or taxes and a quick sell will help save your credit score.

3 cons of selling your house for cash

1. You will likely get less money for your home. Most cash buyers want to buy your home below market value so they can turn around and sell it at or above market value. 

2. You may have to pay some fees. Offerpad, for example, charges service fees ranging from 4-7% to cover the closing costs involved in eventually selling your home. 

3. Some cash buyers may request repairs or lower the offer price on your home before the sale is finalized based on an inspection of your home. Some cash buyers only want to buy homes that require minimal repairs.

3 ways to avoid foreclosure

If you are behind on your mortgage, or otherwise worried you can’t afford your home, there are ways to avoid the bank declaring your house in foreclosure and taking the property from you:

Forbearance

If your lender believes that you have a valid reason behind the missed payments (medical emergency, job loss), it may grant you a forbearance: a repayment plan that temporarily lowers or suspends your payments under the agreement you will stick to the new payment plan.

Mortgage Modification

Mortgage modification allows you to refinance your loan or extend its term to allow for lower monthly payments.

A repayment plan may also include the regular monthly mortgage payment plus a prorated amount of arrears be paid each month.

Reinstatement

Reinstatement lets you pay back mortgage in one, lump-sum payment (which may include any interest and penalties) by a specific deadline.

Reverse mortgage

f the homeowner is at least 62 years old and there is enough equity in the home to cover the defaulted amount, you may be able to get a reverse mortgage. The basics of a reverse mortgage involve a lender taking on your mortgage and paying you a lump sum, fixed monthly payment, or line of credit for the value of the equity in the home, minus interest and fees. A reverse mortgage allows homeowners aged 62 or older to tap into their home’s equity without making monthly payments. 

The loan amount is based on the value of the home, with no monthly payments required. Instead, the loan is repaid when the homeowner sells the home, moves out, or passes away. Reverse mortgages can help supplement retirement income, but it’s important to remember that the loan balance increases over time due to interest. Additionally, homeowners are still responsible for maintaining the property and paying taxes, or the loan could become due earlier than expected.

The entire loan balance then becomes due when the borrower dies, moves out permanently, or sells the home. 

Refinance

If you have equity in your home, a refinance may lower payments, net you a cash payout you can use to catch up on missed payments, and otherwise make your house more affordable.

Short refinance

A short refinance is when the bank forgives a part of your debt and refinances the remaining debt into a new loan. 

Sell your home

Of course, if you can’t afford your home, you can always sell before you fall behind on payments and ruin your credit.

Frequently asked questions about selling your house

Who benefits from selling a house for cash?

Manganaro says the people who benefit the most from selling a house for cash are people in some sort of distress, whether they’re facing foreclosure, divorce, or bankruptcy — or have an old home that needs a lot of repairs.

“Or maybe the house was inherited and the new owner couldn’t or didn’t want to care for the property and just wanted to get rid of it,” Manganaro says.

Is it wise to sell your house for cash?

For many sellers, especially those who need to get money quickly, a cash sale can make sense. Do your homework first!

Single mom $500 stimulus grant

Is it quicker to sell a house to a cash buyer? 5 tips for selling to a cash buyer

  1. Check the online reviews of the buyer, including Better Business Bureau, Yelp, as well as ask around on local Facebook groups, Nextdoor, and your local friends and neighbors.
  2. Some agents recommend at least trying to sell your home on the open market first — either with an agent or for sale by owner.
  3. Before agreeing to a sale, require the buyer provide proof of funds, as well as an Earnest Money Deposit (EMD) — funds in escrow while the deal closes.
  4. Beware of very high offers. “An investor may offer way over the home’s value to lock you in with them only to bring an inspector through and severely lower the price,” says Kolodgie, who is a real estate investor. “You’re then stuck with that investor even though their offer is now the same as all the rest you previously received.
  5. Get multiple quotes, including from iBuyers like Offerpad and Opendoor, as well as local cash investors.

Is it better to sell a house for cash?

Most homes benefit from being sold on the market with the help of a realtor. However, there are some houses, and some sellers, who should consider a cash sale to a quality buyer or investor.

  • Your house is in need of major repairs, you have few interested buyers, in part because no bank will give anyone a mortgage for your home.
  • You are behind on mortgage payments, are facing a tax lien or are already in foreclosure.
  • You are going through a divorce, and selling your house for cash makes the divorce settlement fast and easy, and helps pay for a new life for both of you.
  • You need the money quickly.
  • You don’t have the time, inclination or patience for showings, negotiations or contingencies.
  • You’re not getting any regular offers, and tax and mortgage payments are accruing. In other words, you don’t have many other choices.
  • You are eager to buy another property, and without a fast cash sale of your current house, you may miss out on your dream home.
  • There are emotional reasons you need to get out of a property quickly: Maybe you are selling a home you inherited and need to settle a loved one’s estate without family drama, your relationship ended and you want to settle any debt owed to your ex, or you have a business debt that needs paying.

Can you sell a house for cash without a Realtor?

Yes, you can sell a house for cash without a Realtor, either as a For Sale by Owner seller or in a direct sale to a company that buys houses for cash. 

Bottom line: What is the fastest way to sell a house for cash?

There are just as many shady cash real estate investors as there are legit ones. iBuyers are increasingly popular, thanks to their easy customer experience and streamlined technology. A quality local investor can be a great option, especially if you live outside of a metro area served by an online cash home buyer.


Please be advised that the operator of this site accepts advertising compensation from companies that appear on the site, and such compensation impacts the location and order in which the companies (and/or their products) are presented, and in some cases may also impact the rating that is assigned to them.

How does a cash house sale work?

In a cash house sale, a buyer pays the seller an agreed-upon amount to purchase the home, without a mortgage or other financing. Cash sales can be made by individual buyers, real estate investors, or by companies that regularly buy houses for cash, called iBuyers.

How much do I get if I sell my house as is for cash?

How much money you get selling your house for cash as is depends on the type of cash buyer you sell to, as well as the current state of the market and the condition of your home.

How do you negotiate a cash offer on a house?

If you don’t believe an initial cash offer is fair, you can negotiate with the buyer to arrive at a price that works for both of you.

Who benefits from selling a house for cash?

Manganaro says the people who benefit the most from selling a house for cash are people in some sort of distress, whether they’re facing foreclosure, divorce, or bankruptcy — or have an old home that needs a lot of repairs.

Is it better to sell a house for cash?

Most homes benefit from being sold on the market with the help of a realtor.

Can you sell a house for cash without a Realtor?

Yes, you can sell a house for cash without a Realtor, either as a For Sale by Owner seller or in a direct sale to a company that buys houses for cash.

I see it all the time, and you likely do, too. People fall apart when their marriages end. No matter if it is an amicable, Gwyneth Paltrow uncoupling, your decision or his, whether there was plenty of money or everyone is now destitute, divorce is trauma. 

Every single vertical of your life unravels: finance, real estate, the kids of course, and how much you will see them and where. 

Money is a giant, scary question mark, and your relationships with friends and extended family likely change and are challenged.

If you are like I was, your ideas about your own sexuality, identity, and future are questioned, and your health can take its toll.

However, divorce is just one life experience. It is so common, so commonplace, and there are so many success stories about life after divorce, that I need you to know right now:

You will be fine.

There is trauma, yes.

Pain and suffering.

But you will get through it!

11 tips for moving on and finding yourself after divorce

There is no one-size-fits-all path you’re supposed to take in life. The post-divorce period is all about discovering what you want. Practice some self-care, pick up a new hobby, or even learn how to meditate. 

After divorce, you get to have a fresh new start. Here are some tips to discover the new spouse-free version of yourself: 

  1. Grieve your divorce
  2. Get therapy or try a self-help course
  3. Co-parent like Paltrow
  4. Get a physical, and maybe a makeover
  5. Declutter your house and your life
  6. Heal your heart
  7. Make new friends
  8. Create a lifestyle you can afford
  9. Build your career
  10. Start dating
  11. Build your own wealth

1. Grieve your divorce

Even if you are relieved to be out of your marriage, there will be an adjustment period. It’s OK and 100% normal to feel lonely after divorce. In fact, you can experience a range of emotions, and that is also normal.

Merriam Saunders, a licensed marriage and family therapist (LMFT) and certified divorce mediator, says that the first year after a divorce is often the most difficult — even if you left a bad marriage and even if you’ve started dating someone new.

“The grief may not necessarily be due to missing the former spouse, but rather the life that was built together, the identity forged as a couple, the thought that others might view you as somehow having failed,” Saunders says. 

She says if there are children involved, you may also be grieving your ability to raise them in an intact family, as if you’ve somehow failed them, as well.

Saunders says it’s normal to experience grief because it is a loss. However, how you express and deal with that loss is different for every person. 

“A newly divorced person can expect that just like with any loss, uncomfortable feelings might come up when you least expect them (a sad song on the radio, someone at a stop light who reminds you of your wedding day), and it’s normal,” Saunders says. “Breathe through the discomfort and know it’s just part of the process of moving through change.” 

Give yourself time to navigate life after divorce. If you need help to get through this time, consider seeking help through therapy. Options like BetterHelp and other online therapy sites are legit choices — if you don’t want to go to an in-person therapist.

2. Get therapy — or at least try some self-help books and courses

Divorce can do a number on your mind, body and soul. Take charge.

If your insurance includes coverage for therapy, get yourself a counselor. It is so freeing to talk with someone with absolutely zero stake in your personal life. Relatives and friends can be judgy about your breakup; a counselor just wants to help you move past it.

(And if your insurance coverage doesn’t include therapy? Look for affordable – and maybe even free – help through online counseling services.) Online therapy site BetterHelp takes quality, PhD or Masters degree level therapists, and makes them accessible by video or phone sessions. Connect with a certified mental health professional through BetterHelp.com. Read our review.

How therapy can help

Here are some reasons to try therapy:

  • Therapy has been proven to help people struggling with all kinds of life transitions, and divorce definitely qualifies as a big-ass, major life transition!
  • Therapy can help you understand why your marriage didn’t work out.
  • It can help you process any grief, anger and loneliness.
  • You can learn how to navigate co-parenting and caring for your kids during their own difficult time.

Post-divorce counseling of course can help — whether this means working with your regular therapist, joining a post-divorce support group, or seeking out services like online therapy — sometimes just an objective, patient ear to listen can change your life.

Try a support group

Support groups for divorce can be powerful. I had an incredible experience with group therapy around the time of my own divorce, and connecting with other women going through a similar situation, as well as those who are both ahead of you, and following you in their divorce journeys, can be informative, healing and humbling.

One common topic in divorce support groups is the decision to get a pet. After a life changing event like a divorce, many people find solace in the companionship of animals. If you are considering adopting a dog, cat, or smaller pet, visit honestpet.com for a furry friend that can provide emotional comfort during the healing process.

Take an online course

Udemy has some free and inexpensive online courses that can help transition to life after divorce:

Life 101 Considering that stress levels and poor lifestyle choices in college students are increasing at an alarmingly fast pace, this course may serve as an effective educational tool to teach healthy lifestyle choices, promote students’ well-being and help them to recognize and manage their stress.

Life 101 is taught through a combination of lectures, multimedia videos, workshops and group discussions that would foster active learning.

This course will encourage, challenge, motivate, and inspire students to make positive changes in their lifestyle and the way they interact with others and their environment.

The Science of Well-Being – In this course you will engage in a series of challenges designed to increase your own happiness and build more productive habits.

As preparation for these tasks, Professor Laurie Santos reveals misconceptions about happiness, annoying features of the mind that lead us to think the way we do, and the research that can help us change.

You will ultimately be prepared to successfully incorporate a specific wellness activity into your life.

Finding Purpose and Meaning: Living for What Matters Most! Learn how science, philosophy and practice all play a role in both finding your purpose and living a purposeful life.

You will hear from historical figures and individuals about their journeys to finding and living a purposeful life, and will walk through different exercises to help you find out what matters most to you so you can live a purposeful life.

By the end of this course, you will:

  1. Understand that having a strong purpose in life is an essential element of human well-being.
  2. Know how self-transcending purpose positively affects well-being.
  3. Be able to create a purpose for your life (don’t be intimidated, this is different from creating “the purpose” for your life).
  4. Apply personal approaches and skills to self-change and become and stay connected to your purpose every day.

3. Co-parent like a Paltrow

It can also help to focus on positive co-parenting with your now-ex. Create a plan that works for the new relationship you have with your ex-spouse. Visualize what the future looks like for your whole family.

Custody X Change, a tool for creating parenting plans and schedules, offers the following tips for making a successful plan:

  • Make a parenting time schedule that clearly defines when your child spends time with each parent. In addition to a regular weekday schedule, you should note holidays and vacations.
  • Define the legal custody for each parent.
  • Write down how you will handle child support and issues like claiming your child as a dependent at tax time.
  • Include decisions about designated exchange areas including when and how the exchange will take place. 
  • Write down decisions about medical care, child care, education, extracurricular activities, travel, screen time, and any other topic that relates to the child’s lifestyle and wellbeing.
  • Outline all accepted forms of communication.
  • Write about how you will handle disagreements.

Read my tips in: Rules for co-parenting with even the most toxic ex.

4. Get a physical, and maybe a makeover

Next, talk to your primary care physician. Explain what’s been going on in your life and get a full physical. It could turn out that your exhaustion is due to an underactive thyroid rather than breakup-related stress.

Talk with the doc about any issues that concern you – weight, cholesterol, disease risk – and ask for help mapping out a healthy lifestyle.

Weight loss after a breakup isn’t always an issue, of course. Some people are just naturally slim. Others have already lost weight due to the “relationship breakup diet” of stress and worry.

But if you do decide to drop those extra pounds, the divorce weight loss transformation could do wonders for your self-confidence — and for your overall health, since you’ll be doing it through better eating and regular exercise. Adding a total body collagen supplement to your daily routine can also support skin elasticity, joint health, and overall vitality as you rebuild your healthiest self.

Bonus: When you’re ready to date again, you’ll feel totally up to the challenge. The comedian Elayne Boosler once referred to post-breakup food and exercise as the “new people are going to see me naked diet.” She’s not wrong.

Nothing wrong with cultivating a “revenge body.” Let’s be honest: Doesn’t part of you really want your ex to hear about (or see) how great you’re doing – and how great you look?

5. Declutter your house and get rid of stuff with negative energy

While Marie Kondo is great at helping you get stuff out of your house, she doesn’t help you figure out what to do with it! Consider selling some of your unused items and make some cash.

How to get rid of junk: 24+ free and cheap junk removal options

  • Donate household goods, furniture, blankets, bedding, and clothes: You can donate your stuff to Goodwill, Salvation Army, churches, shelters, outreach centers, and thrift stores. Remember to collect a receipt for any donations, as a tax write-off can make more sense then trying to sell your items individually.
  • Sell clothing: If you have high-quality, name-brand clothing that is only gently worn, you can likely make some cash by selling on consignment sites.
  • Sell jewelry: Many relationships involve precious jewelry. When the relationship ends, those antique, estate, or just used rings, watches, necklaces, earrings, pearls and bracelets can linger in velvet-lined jewelry boxes for years — or even the remainder of the new owner’s life! If you don’t use it, it becomes clutter. Sell it.
  • Sell electronics, old books, video games, DVDs, CDs, iPhones, and Xbox: You can sell your stuff to Decluttr.com to make some cash. Whatever doesn’t sell, donate.

After a divorce, your house and your stuff can give off negative energy. As part of your decluttering process, look to feng shui your house and remove that negative energy.

P.S. After I worked with a feng shui consultant and decluttered, I felt a sense of lightness and control as I looked at my kitchen cupboards and knew just what selection of grains and spices were at my disposal for dinner.

When I needed a certain drill bit the other day, I knew exactly where to find it. In the past, I would have clenched up at the thought of slogging through a giant drawer of hardware and left the window blinds uninstalled.

There is a serenity that comes with knowing that I have more than enough, and yet am closer to the leaner, more purposeful life that I crave.

If you’re refreshing your home as part of this reboot, consider small, high-impact upgrades. Swapping a bulky tub for a modern shower conversion can open up space, simplify cleaning, and boost safety—perfect for busy single-mom mornings. This step-by-step guide explains what a tub-to-shower conversion is, common reasons to do it, and how to get started so you can create a calmer, more functional bathroom without a full remodel.

Downsizing after divorce: how to declutter and take charge

6. Heal your heart and be open to love

You might be ready to date weeks, months, or even years after divorce. But once you heal the wounds of your past relationship, it is possible to find love again. We’ve written lots of articles about post-divorce relationships: 

7. Make new friends

Having a tribe after divorce is so important. Good friends can comfort you at your worst, make you get out of the house, and just make you laugh your ass off. Learn how to make friends after divorce and check out our list of apps to make friends and meet new people in 2023. 

I run a 100% Millionaire Single Moms support group for women on Facebook, where women share about all the joys, traumas and realities of parenting solo.

8. Create a lifestyle you can afford after divorce

After divorce, your income and financial outlook will change. Downsizing after divorce can help you get on track financially and build a successful post-divorce life.

Here are some tips for making and saving money after divorce:

Molly Rosenblum, owner and founding attorney of The Rosenblum Allen Law Firm based in Las Vegas says you should also set up a new budget when divorce is imminent — one that will reflect your income and debts after divorce.

“This way, you will know what it will cost to live independently and be self-supporting,” Molly says. “It will also give you a good insight into what you should ask for in terms of alimony and potentially child support.”

Rosenblum also recommends consulting with a financial planner and a tax professional.

The financial planner can give you ideas on how best to handle funds from alimony, your ex’s retirement benefits, or a lump sum payout from the sale of marital property. If you will receive alimony, a tax professional is one of the best people to have in your corner.

“Alimony is taxable to the payor and the person receiving it,” Rosenblum says. “A tax professional can help structure payments and a division of assets to avoid significant tax consequences.”

9. Build your career post-divorce

Thanks to technology and a changing work culture that values parents, there are countless quality, legit jobs and careers that pay well and provide the flexibility to spend time with your family, work out, build a side gig, or otherwise enjoy life. These opportunities include remote work and other work-at-home opportunities.  

In fact, working from home tops my gratitude list most days, as it has allowed me to devote concentrated sums of time building a business that I love, pays well, and allows me to spend as much (or little! Let’s be real here!) time with my kids as I need to.

High-paying WAH jobs includes careers that often pay $100,000 or more:

My favorite job board for moms is FlexJobs — the leading job site specifically for telecommuting, part-time, flexible-time, online, work from home, and other alternative work arrangements that make such a big difference in families’ lives.

10. Start dating after divorce

I was terrified to date after divorce, and only went on a date after a full year because my friend forced me onto a blind date. I had never dated as a single mom, my body had changed, and the world had changed (hello, smart phones and online dating).

Today, I can attest that dating as a single mom is truly wonderful, as many women can attest. I write all about the reasons in this post on why dating after divorce is so thrilling (including the sex).

Online dating can seem intimidating or desperate if you’ve never done it, but surveys find that is the No. 1 most common way for marrying couples to meet. I have gone on hundreds of dates that originated online, including my three-year relationship with my current boyfriend.

Learn about all the popular online dating sites and apps for single parents in my rundown.

For finding a serious relationship, a boyfriend or a husband, eharmony is the leader:

  • Free 150-point personality report
  • Apps for iOS and Android
  • 100% of members are proven to be real (no catfishing or married people!)
  • Free version
  • For paid memberships, eharmony has one of the lowest prices.
  • 3-month free guarantee
  • A Better Business Bureau rating

Learn more about eharmony in my review.

Post-divorce dating can be exhilarating — when you’re ready. The joys of connecting as a mature adult with other evolved people, dating and sex without the pressures of marriage or commitment, are some of the great surprises at this time of your life.

Eventually, if you want and when you are ready, you will join the countless other formerly heartbroken women and find love after divorce.

11. Build your own wealth after divorce

You likely left your marriage poorer than when you were married, even if you did get the house and a share of investments.

Keep going.

Especially if you were a stay-at-home mom before divorce, you might be struggling with money right now. But there are a lot of great jobs out there, even ones that don’t require a degree. Here are some posts to help you make more money: 

If you don’t already feel confident about investing, learn. Here is my guide to build wealth. In addition, our 52-Week Money Challenge will help you earn more, save more, spend less and feel joyful about your funds. Sign up for the weekly FREE emails:

FAQs about moving on after divorce

Is life over after divorce?

Oh god, no.

Is life better after divorce?

Is life better after divorce? That may entirely depend on the person. Typically, there are four post-divorce experiences:

  1. Life is so fucking better after that asshole leaves!
  2. Meh. At first it seemed great but after a while I realized he was not so bad and I was just bored.
  3. Whew! At first I was devastated that he wanted to leave, but with time I realized what a horrible relationship it was and that he did me the biggest favor!
  4. It is 27 years later and every day I am angry/bitter/remorseful.

Are people happier after divorce?

Women and men can thrive after their marriages end — build communities, careers and find love, and raise great kids. For more, check out my bestselling book The Kickass Single Mom (Penguin), which the New York Post called a “Smart, must-read.”

How hard is life after divorce? How bad is it?

The answer to this question is entirely personal, and can be measured by many factors, including emotional pain, financial stress, romantic loneliness and of course the stress and pain of your kids. A few factors that help women thrive after divorce:

  • Aim for a low-conflict, uncontested divorce.
    This will set you up for a healthy co-parenting arrangement and create fewer things for you to be pissed about long-term.
  • Aim to be financially independent of him. Say no to alimony and child support and find a fair way to split out-of-pocket expenses for the kids (insurance, child care, sports, school supplies). Instead, build your career, start a business or find ways to work at home.
  • Insist on 50/50 time-sharing. Moms who don’t end up resentful, and poorer, according to my survey of 2,279 moms.

What is life after divorce really like? Thoughts from our readers 

Here’s what some of our readers had to say:

Single motherhood can be amazing if you allow it to be. You get to be a mess for a year. yes- that article was a game changer for me because it put a deadline on the self-pity that I see so many other single moms trapped in. After that find the joy. I remember once sneering at the thought of “the Disney dad”. The parent that focuses on fun. And one day when I was being the obnoxious, scattered, can’t get my shit together single mom and looked at my 3 year old looking back at me not sure why I was so miserable it hit me. I had to be more like that disney dad. So when I needed to rush into before care I would race the kids to the door rather than drag them. When my tough nut little one resisted getting ready in the morning I made up the game “Soldier! Report for duty!” She loved me calling out steps to her, “soldier! Arms up for t shirt!” It changed our relationships and now with happy, healthy 10 and 12 year olds fun is the foundation of our threesome. Letting go in that way has allowed me to make serious leaps I wouldn’t have otherwise. I handle stress so much better. So do my kids. I love my life now in a way I never even imagined before.

– Kiki

After I took the time to really heal both from my marriage and other traumas it’s been great. I have more confidence, a better job, a fantastic friend circle. I’m dating someone wonderful (and it’s amazing not to have to pressure to escalate the relationship beyond our comfort), I love my freedom, and I feel so much less stress. I’m a few years out and it took awhile to get here, some of which was difficult and painful, but I’m literally the happiest I’ve ever been in my life.

– Janelle
  • Janelle

Someone said that marriage is like the womb. And divorce is the birth.

I love my post-divorce life. And a wonderful thing to have happened to me as it made me spread my wings. I met me.

I felt traumatized by the separation. The bouncing back was hard and painful. The healing journey helped me re-discover myself. I grew exponentially as a person. My ex-husband and I are friendly with each other. He is married now. And we have a good rapport. We are very different people with some very different values and it makes sense now to not be married to each other.

Someone who is considering divorce or going through it right now… While most of us don’t enter a marriage thinking of divorcing… the end of a marriage is inevitable… either by death or by divorce. The timeline varies. The contrasts co-exist. Yes, it is painful. It is a loss at a very deep level.

My advice: grieve it. Feel it fully. Grieving is beautiful. Get support. Take your time. Consciously heal. There is always, always light at the end of the tunnel. One can make it a journey of metamorphosis or staying broken. That is in our hands.

Don’t make the children a part of the mess. Divorce is between husband and wife. Not between the father and mother. Father and mother… they always remain.

– Shruti

There are so many days that I feel like I’m doing it all wrong and I’m a hot mess. But then I look at my kids, how great they’re doing, and how great my relationship with them is and I realize that I’m definitely doing something right. I get down and battle depression periodically and wish I was in a good relationship but then I look at how much I’ve grown as a person on my own and I wouldn’t trade that for the world.

– Christine

What should I do with my life after divorce?

Here are just some of the million things that women do with their happy post-divorce lives:

  • Start a new career
  • Open a business
  • Go to grad school [27 scholarships for single moms]
  • Travel
  • Make new friends
  • Get closer to their children
  • Date
  • Have lots of interesting, new sex
  • Find love
  • Remarry
  • Have more babies
  • Relocate
  • Build wealth
  • Remodel their home
  • Downsize
  • Get closer to God
  • Find a new church/temple/mosque
  • Revisit an old hobby/passion
  • Find a new passion/project
  • Volunteer/give back
  • Get in shape
  • Explore new sports and fitness routines
  • Develop intellectual pursuits old and new
  • Relax
  • Binge on TV shows and movies that make you feel good
  • Do nothing

The bottom line: There is life after divorce

The best way to move on after a breakup?

Time. Patience with yourself. Self-reflection. Focus on thriving as a single woman while also being open to fun, dating, partnership, and being a good co-parent.

But to get there, you have to get rid of stuff: furniture, dishes, old photos, and sell that engagement ring already. Sell that engagement ring, anniversary ring, diamond necklace, or push-present earrings and use the proceeds to get your nose pierced!

Another self-care option: going for a dramatic new look after divorce. Dye your hair! 

Purge the super-basic wardrobe you somehow accumulated in the past decade! (Hint: Moms don’t have to wear mom jeans.)

A divorce makeover won’t happen overnight, unless you’re financially secure enough just to dump everything and start over.

Take your time, make thoughtful decisions about what you want your life to look like after divorce. Give yourself the time and permission to discover — and to meet — your own needs and desires, now.

What to do now? 

Watch:

Read:

How to recover from divorce in the first year

Is life better after divorce?

Is life better after divorce? That may entirely depend on the person.

Are people happier after divorce?

Women and men can thrive after their marriages end — build communities, careers and find love, and raise great kids.

How hard is life after divorce?

The answer to this question is entirely personal, and can be measured by many factors, including emotional pain, financial stress, romantic loneliness and of course the stress and pain of your kids.

What should I do with my life after divorce?

Here are just some of the million things that women do with their happy post-divorce lives: start a new career, open a business, go to grad school, travel, make new friends, get closer to their children, date, and more.

If you have a used or inherited watch, you can likely sell it for cash — even if it is broken.

CashforGoldUSA buys all luxury watches, as well as gold and silver watch parts. The the family company has been in business since 2005, has an A+ BBB rating, insures your item up to $150,000 and pays within 24 hours. Get a quote for your watch now >>

If you’d rather not sell your watch, you can also use it as collateral to secure a personal loan. Read our Diamond Banc review and borrow up to $500,000 in 24 hours or less with Diamond Banc >>

Here is what you need to know about selling your timepiece for the best price, quickly.

How to sell a watch in 3 steps

Whether you choose to sell locally, or online, the basics of selling a luxury timepiece are similar:

  1. Understand the value of the watch you’re selling.
  2. Research all the options you have for selling watches.
  3. Get quotes for online watch buyers before going “near me.”

Interested in selling your timepiece? Keep reading to learn more:

How to sell watches “near me”

How to sell a watch online 

What you should know about selling your luxury watch

FAQs about how to sell my watch

Bottom line: Is there a market for used watches?

How to sell a watch: Step 1

First, understand the value of your watch:

  • Start with any documentation you have of the timepiece: receipts, box, certifications, appraisal, any documented history of past ownership
  • A Google search of the make and model, year, as well as an estimation of its condition — see what others are selling similar watches for on sites like ebay, Chrono24.com and Worthy.com.
  • Get a quote from an online watch buyer. CashforGoldUSA will give you a quote quickly through its website.
  • Consider taking your watch to a local jeweler near you to get an appraisal

How to sell a watch: Step 2

Research your options for selling timepieces, chose the one you feel most comfortable with, that promises the highest price.

  • Selling to a watch dealer near, you, pawn shop or consignment may feel safer if you know the business or can speak directly with the store
  • Online watch buyers have the benefit of allowing you to research multiple buyers easily without leaving home, and read through dozens or hundreds of Better Business Bureau or Trustpilot reviews from all over the country. Plus, selling online is private and discrete.
    CashforGoldUSA, Worthy, and myGemma have BBB ratings of A+, and all insure your item, with the option to have your item shipped back to you free and insured should like. 

How to sell a watch: Step 3

To sell a timepiece to an online watch buyer: 

  1. Go to the watch buyer’s website and answer their questions to see if you qualify to sell through them. CashforGoldUSA accepts all luxury watches and gold and silver watch parts. Worthy and myGemma have stricter criteria.
  2. Request a Fedex or USPS mailer. Reputable sellers will send the mailer for free, as well as provide sufficient insurance, tacking number and a guarantee to return your item without charge, should you choose. 
  3. Send in your watch.
  4. Get a quote. Negotiate if you think your watch is worth more. 
  5. Get paid — most online watch buyers will pay via ACH, Paypal or even paper check in the mail. 

Jewelry stores or watch buyers near you will require a visit to their showroom. They will inspect your timepiece, and if interested, make an offer, typically in cash. Be sure to negotiate a higher rate.

How to sell watches “near me”

Typical local places for selling watches include pawn and consignment stores, local jewelers, estate sales and auctions. To sell near you:

  1. Get an appraisal via a jeweler, watch dealer, antique/estate jewelry dealer or otherwise do your research online to understand your timepiece and what it is worth.
  2. Get a few quotes locally from reputable jewelers, appraisals, pawnshops or collectors. 
  3. Sell your item, get paid on the spot, typically in cash.

How to sell a watch online 

Increasingly, there are many more trustworthy options for selling your watch or luxury timepiece online, including directly to other buyers through sites like ebay, Chrono24.com as well as to reputable watch buyers like CashforGoldUSA, Worthy and myGemma. 

By working with a reputable online watch buyer, you can have a more private sale and potentially reach a global buyers’ market — which is exactly the market for luxury watches.

Sell a watch via CashforGoldUSA

CashforGoldUSA directly buys any luxury timepiece, broken or working, watch bands, branded and unbranded. Unbranded timepieces or watch parts can be sold for scrap gold or silver.

Read our CashforGoldUSA review, or get a free estimate now >>

Brands CashforGoldUSA accepts include:

AccuristAdriaticaA. Lange & Sšhne
Alpina WatchesAnsonia Clock CompanyAudemars Piguet
Abraham Louis BreguetAaron LufkinDennison
Antide JanvierAntoni PatekAdrien Philippe
Baume et MercierBall Watch CompanyBell & Ross
BlancpainEdouard BovetBreguet
BreitlingBulgariBulova
Carlo FerraraCartierCasio
CharlesFrodshamCertina
Chaika watchesChopardChronovski
Chung nam groupCitizenCompany Volmax
CorumCymaDaniel Roth
Doxa S.A.DreffaEbel
Elgin National Watch CompanyErnest BorelEdward
John DentETAE. Howard & Co.
F. P. JourneFestinaFortis Uhren AG
FossilFranck MullerFrŽdŽrique Constant
Franciszek CzapekFerdinand BerthoudGirard-Perregaux
GlashŸtte OriginalGlycine WatchGeorge Graham
George DanielsHamilton Watch CompanyHindustan Machine Tools
HublotIkepodIllinois Watch Company
International Watch CompanyInvicta, ISAIngersoll
Jaeger-LeCoultreJoseph JohnsonJules Jurgensen
JunghansJohn ArnoldJohn Harrison
KolberLancashire Watch CompanyLip
Louis CartierLonginesLorus Luminox
Marathon Watch CompanyMarkusRubyMaurice Lacroix
Minerva Watch CompanyMolnija, MondaineMontblanc
MovadoNixon WatchesNomos GlashŸtte
OmegaOrientOris
PaneraiParmigiani FleurierPatek Philippe
PhenixPiaget SAPolar Electro
PoljotPR & A Watch SaglPulsar
Pierre Jaquet-DrozPeter HenleinPeter Litherland
RadoRaymond WeilRodania
Roger DubuisRolexRotary Watches
SeikoSeikoshaSekonda
SinnÊSkagen DesignsSlava
SuuntoSwatchTAG Heuer
TimexTissotTitan
IndustriesTitoniTourneau
Thomas TompionThomas EarnshawTutima
Ulysse NardinVacheron ConstantinValjoux
VenusVostokVictorinox
Waltham International SAWaltham Watch CompanyWenger
Webb C. BallWincenty GostkowskiYema
Zenith  

Selling your gold to CashforGoldUSA is straightforward:

  1. Visit CashforGoldUSA.com and fill out a form requesting a prepaid mailer be sent to you, free of charge. 
  2. Place your items inside the mailer and send it back to CashforGoldUSA. You can have the mailer picked up at your door (opposed to taking it to the shipping center).
  3. Your items will be appraised within 24 hours of receipt to determine the value of the gold, and you’ll be sent an offer.
  4. If you accept the offer, you’ll be paid by either check, bank wire, or directly through PayPal. You can be paid in as little as 24 hours after accepting the offer.
  5. If you don’t accept the offer, your item will be returned to you free of charge. 

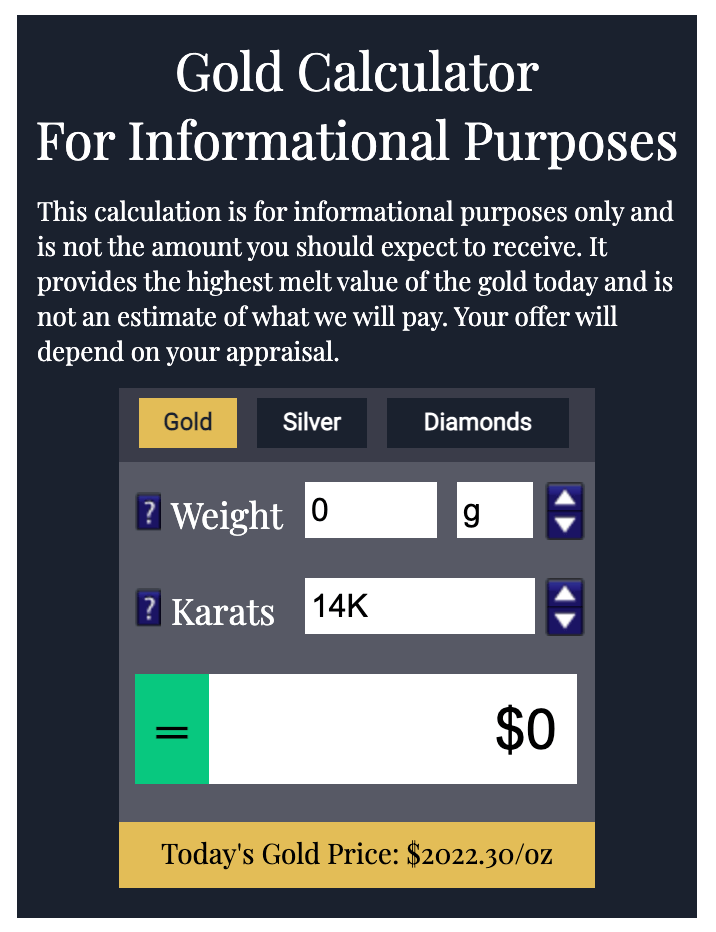
Get an idea of the value of your item before you send it in for appraisal. Just enter the weight and karat of gold into CashforGoldUSA’s gold calculator:

CashforGoldUSA informational gold calculator

It is important to note that this is just melt value, and not a final offer. The only way to get an accurate offer is to send your item in for appraisal. 

Sell a watch via Worthy.com

Worthy.com is an online marketplace specializing in diamonds and branded jewelry and directly buys luxury watches. Worthy only accepts items that will re-sell for at least $1,000.

Watches Worthy.com accepts include:

Alain SilbersteinBreitling
GlashütteLange
Patek PhilippeTAG Heuer
Audemars PiguetBulgari
Harry WinstonMB&F
PiagetTudor
Bell & RossCartier
HublotMontblanc
Richard MilleUlysse Nardin
BlancpainChopard
IWCOmega
Roger DubuisVacheron Constantin
BreguetFranck Muller
JaegerPanerai
RolexZenither 
  1. Go to Worthy.com
  2. Get an online quote from a site like Worthy to understand if their estimate is in line with a price you feel comfortable with.
  3. If they and you are interested in proceeding, Worthy sends you a free FedEx mailer overnight. 
  4. Send in your watch, 100% insured up to $100,000. 
  5. Your timepiece is authenticated by Central Watch, a New York City watch repair, appraiser and buyer founded in 1952.
  6. Worthy will professionally clean and photograph your timepiece in high-definition. You set the minimum price you are willing to sell.
  7. Your auction goes live to hundreds of vetted buyers globally.
  8. Get paid within as little as 24 hours by Paypal, or by check mailed to your home. 

Worthy has an A+ rating with the Better Business Bureau.

When your watch or other jewelry sells, Worthy.com takes a fee of up to 22 percent of the sale price.

That’s something to keep in mind, but remember that anyone selling anything for you is going to take a cut — they just might not be transparent about it. 

Keep in mind that the whole process withy Worthy will typically take about 2 weeks.

If you chose not to sell, or the minimum price is not met, Worthy will return your watch for free.

Read about Worthy in this review.

How much can I get for my watch on Worthy?

The amount your watch will bring depends on many factors.

You won’t be surprised by the final sale prices, since you will receive an estimate from Central Watch beforehand, and you yourself set the minimum you are willing to accept for a sale at Worthy.com.

That said, here are some things that can affect the value of your watch: Limited production numbers, brand and model, proof of Swiss craftsmanship, manufacturer-made movements, construction using precious metals, the quality of jewels and stones in the piece, the conditions of the clasp and band, and piece’s history and age.

Worthy points out that some of the watches it deals with have sold for more than $1 million.

For a quick reference, though, Worthy reports that on its site, a Rolex Submariner recently sold for $6,120, a Hublot Big Bang recently sold for $4,725 and a Breitling Motors recently went for $2,929.

Learn more about selling Rolexes.

Sell a watch to myGemma, formerly WP Diamonds

myGemma only buys luxury watches, including:

RolexCartier
IWCBreitling
Patek PhillipeOmega
Tag Heuer Jaeger LeCoulture
HublotA. Lange & Söhne
Audemars PiguetBaume & Mercier
Bell & RossBlancpain, Breguet
Bremont, BulgariChanel
ChopardChronoswiss
Franck MullerGirard-Perraguax
Gashütte, Hublot 
  1. Go to myGemma.com
  2. Get an online quote 
  3. If they and you are interested in proceeding, myGemma sends you a free FedEx mailer overnight. 
  4. Send in your watch, 100% insured up to the full value of your item. More expensive items can easily be sent by MALCA armored delivery.
  5. Your timepiece is authenticated, and a formal offer will be sent by email, or in a phone call.
  6. If you accept, you can get paid within as little as 24 hours by Paypal, or by check mailed to your home. 

myGemma also accepts in-person appointments in its locations in New York City and London.

myGemma also buys diamonds, branded jewelry, luxury handbags and sneakers, offering trade-in deals in addition to direct payment.

How much will myGemma give me for my watch?

While myGemma does not publish its commission, most jewelry and watch buyers take at least a 20% commission off the top of the market value of what they will pay you.

Is myGemma a trustworthy company?

myGemma, formerly WP Diamonds, has an A+ Better Business Bureau rating, 4.8/5 stars on Trustpilot based on more than 2,300 reviews, and physical offices in New York or London. 

How will I get paid by myGemma?

myGemma will wire you the money or send a check out the same day. If you choose a wire, the money will go straight into your bank account and be available in as little as 24 hours.

If you sell your watch at one of their locations, myGemma will pay in cash, check or wire transfer. Sellers with an offer under $400 will receive a check only.

What you should know about selling your luxury watch

Similar to jewelry, watches of high quality can be valuable for decades and centuries after purchase. While there are some exceptions, the price you paid will likely be more than the price you get in resale.

  • Antique watches are at least 100 years old.
  • Vintage watches are at least 20 years old.
  • A watch less than 20 years is likely to be classified as simply “old.”

To determine the age of a watch, as well as an antique watch’s value, and how to determine the value of a vintage watch or pocket watch, you must open the timepiece and find a serial number on the movements. If your watch does not have a serial number, a highly trained watch expert may be able to determine the make, model and year of your piece.

In fact, before you sell your timepiece, it is important to get an appraisal from a reputable jeweler who can offer you a certified appraisal, or authentication. Worthy has all the watches it manages sent to Central Watch for authentication.

What affects the value of your watch?

Here are some of the factors that can help determine the price you will receive for your watch:

  • Brand and model (see below for a list of luxury brands buyers are most interested in)
  • Limited production numbers
  • Swiss Made
  • Manufacturer-made movements (not replacements or repairs)
  • Construction using precious metals including gold and platinum
  • High-quality jewels and stones
  • Age and history of the watch
  • Quality of the clasp and band

What if you don’t know the brand of your watch? How can you check the quality and value of your luxury timepiece, whether your watch is gold, chrome or has a leather band?

If you have determined that yours is not a name-brand watch that is valuable as its own, you might investigate how much it costs to repair. For most vintage watches, the cost can be $200 to $500 — or more. This is likely more expensive than you would get to even sell the gold pieces in the watch — especially since today the price of gold per ounce has been near record highs. 

Inherited a watch? Learn more about selling estate jewelry.

Which luxury watch holds its value best?

According to Watch Time magazine, Rolex and Patek Philippe watches hold their value the best.

More on how to sell your Cartier

How to find the value of a luxury watch (i.e. How much is my watch worth?)

If you have a vintage or antique watch — or simply a used luxury timepiece you no longer want — gather all the information you have on it, and start with one of the online marketplaces like Chrono24.com or even eBay, to understand a ballpark price you may receive.

You can take your old watch to a local jeweler or watch repairer, who can give you an appraisal, which is a written statement of the estimated replacement value of your watch. Replacement value is not the same as the resale value, which will be much lower. An appraisal is useful to understand more about your timepiece, and for insurance purposes.

From there, if you understand that your watch is worth in the thousands of dollars, consider taking it to one of the big auction houses like Sothebys or Christie’s, which all have qualified watch experts on staff.

Also, you can send your watch to Worthy.com which will send your watch to be authenticated by CentralWatch, a trusted and well-known watch repair and service provider.

Recently sold Cartier Tank

sell cartier tank watch online price

Recently sold Patek Philippe

Recently sold Patek Philippe watcg

Recently sold Omega

Recently sold Omega watch

Recently sold Hublot

Recently sold Hublot watch

Recently sold Chopard

Recently sold Chopard watcg

Recently sold Bulgari

Recently sold Bulgari watch

FAQs about how to sell my watch

Know that if you have a gold, or gold-tone watch that is not a known brand name, you may be able to sell for the value of the metal — which is great news since gold prices have been at record highs in recent years. Learn more about selling gold. 

Have more questions about how to sell a watch? We have answers:

Can you sell your ex’s watch?

What if he moved out and left his watch in the dresser drawer or safety deposit box. Is it yours to sell?

The division of assets in a divorce is tricky territory best left to an attorney’s advice, but some general guidelines:

  • If he or she abandoned the home and did not make claims to any property, it may be yours to keep.
  • If the watch was a gift (from you or someone else), as well as an item he inherited, it would likely be deemed his alone.
  • If the watch is of significant value and something you purchased together as a couple, it would likely be considered a marital asset, the value of which would be divided equally (you can of course sell it, and divide any cash proceeded).
  • If you made a good-faith effort to return the watch to her, but she did not accept it, it could be considered yours.

Again, ask a lawyer.

How do I find out how much my watch is worth?

To sell your watch, start by getting an appraisal.

How can I sell my expensive watch?

If you have a luxury watch that is worth a very high amount of money more than $100,000, call one of the major auction houses. However, Worthy and myGemma are connected to the watch-buyer and collector community and can help you find the highest price for your timepiece.

Can I sell old watches for cash?

Pawn shops, consignment stores, many jewelry stores and even high-end jewelry and watch buyers are accustomed to paying cash for old watches. CashforGoldUSA is recommended for old, broken watches.

Bottom line: Is there a market for used watches?

Yes! There is a robust market for used watches and timepieces. You have learned how to sell a watch online, so we recommend you start with CashforGoldUSA now >>


Can you sell your ex’s watch?

The division of assets in a divorce is tricky territory best left to an attorney’s advice.

How do I find out how much my watch is worth?

To sell your watch, start by getting an appraisal.

How can I sell my expensive watch?

If you have a luxury watch that is worth a very high amount of money, say, more than $100,000, call one of the major auction houses. However, online watch buyers are deeply connected to the watch-buyer and collector community and can help you find the highest price for your timepiece, no matter the price.

Can I sell old watches for cash?

Pawn shops, consignment stores, many jewelry stores and even high-end jewelry and watch buyers are accustomed to paying cash for old watches.

Selling a watch — or any fine jewelry, for that matter — can be intimidating.

Traditionally, there’s the process of finding a qualified appraiser and figuring out where to sell it.

And then there is the question about whether you trust the quote your local jeweler or watchmaker gave you.

Are you getting ripped off?

Fortunately, there are options today that make it easier and safer than ever, without ever having to leave the house.

You can even get cash for your watch without selling it by using it as collateral to secure a personal loan from a company like Diamond Banc.

Get a jewelry loan through Diamond Banc in 24 hours or less >>

Bottom line: Best place to sell a watch?

There are ways to get the most money for your timepiece, quickly and safely. My No. 1 recommendation is Worthy.com, an online auction platform rated B+ by the Better Business Bureau.

Read about Worthy in this review.

Where to sell watches? Worthy

Worthy is an online marketplace, and each watch auction attracts bids from hundreds of qualified buyers all around the country — if not world. Worthy works with leading watch experts to accurately value each timepiece, takes professional, 3-D photographs using specialized digital equipment, and merchandises each watch. You control the reserve price, and are paid within a few days of the sale. 

Most of Worthy’s buyers prefer brands whose watches retail for tens of thousands of dollars (and sometimes more).

Though Worthy.com is my top choice, there are other places to sell a watch to consider. 

Where to sell watches

Today, you have a few choices to sell your watch:

1. Sell watches online

Sites including Worthy, WPDiamonds, and other online marketplaces and jewelry auctions can help you get a fair price for your watch. Benefits of selling online include ease of use, transparency and privacy — you don’t have to be embarrassed walking into a local jeweler or pawn shop.

Online platforms also typically have lower overhead than brick-and-mortar jewelers or other businesses, so they have the margins to offer you higher prices — and are incentivized to do since the competition online is higher than in local markets. 

Other places that buy watches include:

2. Search for “sell watches near me” or “watch buyers near me” 

You may find reputable jewelers, pawn shops, watch buyers and retailers in your area via Yelp, Google or other listings. One way is to use “near me” in your searches to find local watch buyers. You might also want to ask around for a recommendation.

3. Scrap metal buyers

If you have a gold watch that can be melted for scrap, send it to CashforGoldUSA.com, which has an A+ with the Better Business Bureau, pays within 24 hours and pays a 10% bonus.

CashforGoldUSA buys all kinds of watches, gold and silver jewelry, coins and silverware as well as diamond rings, necklaces, bracelets, earrings and other jewelry — and they pay within 24 hours of receiving your item.

4. Pawn shops

You may consider pawning your watch to a pawn shop near you, although it may be better to sell your jewelry online. Online gold buyers may pay more, as pawn shops typically pay 25% to 60% of the retail value of your item. 

5. Consignment shops 

Jewelry stores and antique shops both may purchase your estate and vintage jewelry and watches — either for a flat rate or on a consignment agreement.

Consignment shops typically accept an item for consignment and then pay the original seller a percentage of the sales price if and when the item sells. Online consignment sites like TheRealReal deal in fine jewelry and higher-end watches. 

Expect consigning your watch to take longer than pawning and direct sales or online sales.

6. Facebook Marketplace

Facebook Marketplace has become a bonanza of buying and selling any number of goods and services, including timepieces. Simply post your watch with a few pics, a thorough description and suggested price — and then try to figure out which responders are scammers, crazy or potential buyers!

7. Give it away 

You may want to give your watch to a family member or close friend, leave it to them in a will or your estate plan, or donate it to a charity thrift store. 

Watch buyers near me and online

Top watch buyer: Worthy.com 

Worthy is a leading marketplace that will do the heavy lifting of marketing your watch or fine jewelry to its network of professional buyers. Worthy.com will also have your watch authenticated by Watch Central, a partners specializing in timepieces.

Worthy.com chooses which brands to buy based on their buyers’ preferences.

Here’s a list of watch brands that are in demand by Worthy’s buyers:

  • Alain Silberstein
  • Breitling
  • Glashütte
  • Lange
  • Patek Philippe
  • TAG Heuer
  • Audemars Piguet
  • Bulgari
  • Harry Winston
  • MB&F
  • Piaget
  • Tudor
  • Bell & Ross
  • Cartier
  • Hublot
  • Montblanc
  • Richard Mille
  • Ulysse Nardin
  • Blancpain
  • Chopard
  • IWC
  • Omega
  • Roger Dubuis
  • Vacheron Constantin
  • Breguet
  • Franck Muller
  • Jaeger
  • Panerai
  • Rolex
  • Zenith

In fact, unlike retailers who carry these brands, many of whom sell only newer watches, Worthy’s buyers actually prefer vintage or antique versions of these big names – particularly ones in excellent condition.

The rarity ups the value, which increases the amount you’ll be paid. So, that watch of your grandfather’s … ?

Once you decide you want to part with your watch, go to Worthy.com. 

  1. Go to Worthy.com
  2. Get an online quote from a site like Worthy to understand if their estimate is in line with a price you feel comfortable with.
  3. If they and you are interested in proceeding, Worthy sends you a free FedEx mailer overnight. 
  4. Send in your watch, 100% insured up to $100,000 by Lloyds of London. 
  5. Your timepiece is authenticated by Central Watch, a New York City watch repair, appraiser and buyer founded in 1952.
  6. Worthy will professionally clean and digitally photograph your watch in special, high-definition images. You set the minimum price you are willing to sell.
  7. Your auction goes live to hundreds of vetted buyers globally.
  8. Get paid within as little as 24 hours by Paypal, or by check mailed to your home. Total sale time from sending in your timepiece to getting paid is about two weeks.

Worthy has a B+ rating with the Better Business Bureau.

When your watch or other jewelry sells, Worthy.com takes a fee of up to 22 percent of the sale price.

That’s something to keep in mind, but remember that anyone selling anything for you is going to take a cut.

Worthy scores points with its transparency.

If your jewelry doesn’t get sold for at least your reserve price, Worthy will return it for free, and you don’t wind up paying anything before the sale.

Second best watch buyer: myGemma

myGemma, formerly WP Diamonds, specializes in diamond jewelry, as well as luxury timepieces, handbags, and accessories. Their model is straightforward purchases, especially if you already have receipts or lab reports from your item.

Read our myGemma review.

Scrap gold watch buyer: CashforGoldUSA 

CashforGoldUSA specializes in buying all things gold, silver, diamond, jewelry and coins. Watches that are best sold for scrap gold are a good fit.

Read our CashforGoldUSA review.

Where to sell watches FAQs

Can you sell a watch to a jeweler?

Jewelers often appraise and buy fine and luxury watches of all kinds — it really depends on the jeweler and the market. A jeweler can be a good place to start to learn about your timepiece and get an initial offer. A jeweler is also helpful in providing an appraisal for insurance purposes.

Where is the best place to sell a watch?

Many people chose to sell their watch locally to a jeweler or watch collector who they know and trust, or who comes recommended.

There are many benefits to using one of the reputable online watch buyers. Online buyers tend to work in large volume with connections globally — which is really the scope of the international watch market.

Watch sellers find it useful to easily check sites like Better Business Bureau and Trustpilot for online businesses since the established ones can have hundreds or thousands of reviews and ratings.

Online businesses potentially can work on smaller margins, and pass those savings on to the seller, given they are not beholden to expensive retail real estate.

Further, many watch and jewelry sellers prefer the privacy and anonymity of selling their watch for cash, from home where there is no chance of running into a neighbor during the transaction!

Where can I sell my Apple watch?

Apple and other digital watches fall into another category entirely, though you can certainly resell your Apple watch for cash. eBay, Gazelle or even locally on Craigslist or Facebook Marketplaces are good places to sell watches. Pawn shops and consignment stores are also places to sell electronic watches.

23 sites like Craigslist to buy or sell stuff in 2023

Can you sell a watch to a jeweler?

Many local jewelers will buy your timepiece. First, do your best to understand your watch’s value, and then make an appointment with a few local jewelers, to see who offers you the best choice. Many people prefer to sell jewelry and watches locally to businesses they know and trust, and negotiate face-to-face.

Where is the best place to sell a watch?

Selling your watch online is our No. 1 recommendation. Online buyers can reach an international market, have less overhead since they do not rely on expensive retail rent, and have the capacity to do large volumes of deals, allowing for smaller margins — which are passed along to sellers.

Where can I sell my Apple watch?

Apple and other digital watches fall into another category entirely, though you can certainly resell your Apple watch for cash. eBay, Gazelle or even locally on Craigslist or Facebook Marketplaces are good places to sell watches. Pawn shops and consignment stores are also places to sell electronic watches.

If you live with consumer debt, you are not alone. According to Federal Reserve data1, U.S. households have on average $6,300 in credit card debt and $33,090 in student loans, while the Consumer Financial Protection Bureau reports that a full 52% of credit bureau filings are for medical debt. Single mothers are especially likely to struggle with poverty.2

Mama, if you find yourself drowning in debt, rest assured you are not alone. But don’t use this fact as an excuse not to work like crazy to pay off your debt. If you live month-to-month owing others money, then the money you earn is not really yours. You are enslaved to your debt.

 You are not the only person asking:

  • How do I get out of debt if I’m broke and have no money?
  • How do I get out of debt so I can stop living paycheck to paycheck?
  • How do I get out of debt with no money and bad credit?

This post gives a 9-step plan for reducing and paying off your debt.

Here’s what’s inside:

How to get out of debt when you are broke

  1. List your debts, expenses, and income
  2. Research lower credit card rates and refi debt
  3. Negotiate interest rates with creditors
  4. Create a monthly budget of all your expenses and debt payments
  5. Choose a method for paying off debt: Debt snowball vs avalanche
  6. Sell stuff to earn money to pay off debt
  7. Get a side job, and put that money towards debt
  8. Consider professional help to pay off debt
  9. Be honest with yourself about your personal finances

FAQs about how to pay off debt on a low income

More debt relief resources for single moms

How to get out of debt when you are broke

As you figure out how to get out of debt on a low income, keep in mind that not every step on this list will reflect your situation. Follow as many as you can to get the best results:

1. List your debts, expenses, and income

Time to look the personal finance monster in the eye and lay out the FACTS.

Collect statements for each and every one of your debts: credit cards, medical bills, student loans, car note, mortgage, home equity line, personal loans from your parents or cousin.

Create a list of all your debt, including interest rates, monthly minimum payments and any deadlines.

My favorite app to help make this as simple as possible is You Need A Budget (YNAB). This app automatically pulls in all your income, debt, and expenses from your bank accounts. From there, you can set goals — and reach them! No matter what your financial goals are, it is so handy, so satisfying to see all these numbers in one place, and watch them move to meet your goals, day after day.

Don’t know what debt you have? You aren’t alone:

I have debt, but don’t know where it is. How do I find it?
byu/dumbandconcerned inpovertyfinance

Here’s a tip for what to do:

2. Research lower credit card rates and refi debt

Here are the most common and easiest ways to lower your debt payment and pay off debt quicker:

Refi your student loans:

There are many options to refinance your private and government student loans. See what you student loan refinance options are.

Refi your auto loan:

Can’t afford your car payment? See if you qualify to refinance for a lower payment.

Auto Credit Express is A+ rated with the Better Business Bureau:

  • Average Saving:  $1,700 or $143 per month
  • Minimum Credit Score: 525
  • APR from 3.99%
  • Loan Amounts: $5,000 – $45,000
  • Vehicle Criteria: Under 10 Years/150K Miles

Get a refi quote from Auto Credit Express in 30 seconds >>

Refi your mortgage:

Chances are, mortgage rates have fallen since you first got your mortgage.

Transfer your credit card debt to 0% or lower APR:

See if you qualify for a 0% balance transfer credit card for a limited period, such as three or 12 months. Depending on your credit score, you may qualify for credit cards with lower rates long-term. This is a great way to pay off debt, as you save on interest along the way.

It only works if you are very organized, read all the fine print, and make sure you pay the premiums on time, and either pay off the balance or transfer the balance before the end of the promotion period.

But be honest with yourself: If you are not good with this kind of bookkeeping, this might not be a good option for you.

3. Negotiate interest rates with creditors

How to lower interest rates on credit cards

Another way to get a better rate on your card is to call your current credit card company and simply ask for a better rate. Here is a script:

“Hi, as you can see I am a longtime cardholder, and I love using your product. I am committed to paying off my debt and improving my credit history, and I’d love to stay with you. However, I need a better rate on my balance. Based on my research, I can get a [insert honest quote you received from another card] rate. Can you match it or do better?”

If your current card refuses to give you a better rate, research a 0% balance transfer credit card with another company.

Negotiate medical and other debt

Call the holder of any outstanding medical bills and negotiate.

4. Create a monthly budget of all your expenses and debt payments

Figure out how much you can afford to pay toward your debt by setting up a budget.

It is time to get serious, cut out any extra spending, and lower your overhead. Remember: Overspending is how you got in this pickle in the first place. Imagine how AMAZING it will feel to be debt-free! Check your student loan information at the National Student Loan Data System.

5. Choose a method for paying off debt: Debt snowball vs avalanche

When it comes to eliminating debt—whether credit cards, personal loans, student loans, or other debt—there are a number of popular strategies that you can employ. Two of the most common strategies, which you may have heard of, are the Debt Snowball and the Debt Avalanche. 

While both are highly effective, each is better suited to helping you achieve different goals. Below, we take a look at each option to understand which will best help you reach your money goals. 

16+ financial help resources for single moms

What is the debt snowball method?

Debt snowball is a debt repayment method to pay off credit cards or loans with the lowest balances first. 

Finance guru Dave Ramsey made the debt snowball method popular, and for good reason: The advantage is that you get the psychological and emotional thrill of paying off accounts quickly. Imagine if you could actually remove a whole credit card account from your life?

Here is how to use the debt snowball method:

  1. List your debts from smallest balance to largest balance — regardless of interest rate.
  2. Make minimum payments (set up autopay) on all your debts except the debt with the smallest balance.
  3. Pay as much as possible on your smallest debt.
  4. Repeat until each debt is paid in full.

In the debt snowball method, you start by paying off the loan with the lowest balance first. This is beneficial for a number of reasons:

  1. First, paying off any debt will give you a psychological “win” that you can use to propel yourself forward and continue hitting your goals. It stands as proof: You can do this! By paying off the debt with the lowest balance first, you’re getting this satisfaction quicker, which can help you stick with it for the long term.
  2. Second, paying off the lowest balance will allow you to free up money in your budget. You can use this money to live a more comfortable life—or, ideally, to continue paying down your remaining debt.

How it works:

  1. First, list out all of your debts, from smallest balance to largest balance. Ignore any other factors, such as interest rate.
  2. Continue making your regularly scheduled minimum monthly payments on all of your debts. You don’t want to fall behind on anything—that can destroy your credit score!
  3. Each month, pay as much extra as you can on the loan with the smallest balance. This will drive down the balance, saving you money in interest payments.
  4. Once the debt with the lowest balance is paid off, take note of the minimum monthly payment you were paying toward it. Roll that amount over into the loan with the next lowest balance, so that you’re paying more toward it. Continue paying as much extra each month as possible.
  5. Repeat until you have paid off all of your debts.

The method gets its name from the way that a snowball continuously grows as it rolls down a hill. As you pay off each debt, you free up more money each month that you can apply to the next debt. By the time you’ve got a single loan left, you’ve got the collective power of all of the money you’ve freed up, like a runaway snow-boulder!

Do you have disability insurance? What you need to know (especially if you are self-employed)

Debt snowball example

In the example below, this mom has $44,500 in combined credit card, car, and student (“Other”) debt.

Using the snowball debt payment method, you can see here how quickly she was able to pay off her debt, compared with if she were to simply pay the minimums on each of these four accounts:

Example of a snowball payment schedule.

In the example below, this mom has $44,500 in combined credit card, car and student (“Other”) debt:

An example of the total interest you'd pay if you use the snowball debt payment method.

Using the snowball debt payment method, you can see here how quickly she was able to pay off her debt, compared with if she were to simply pay the minimums on each of these four accounts:

Using the snowball debt program, she slashed her debt to $0 in 3 years and 7 months, compared with 13 years!

This quicker, more aggressive repayment saved her $4,853 in interest.

Shows how much faster you can pay off debt using the snowball method.

What is the debt avalanche method?

In the debt avalanche method, you instead start by paying off the loan with the highest interest rate first, regardless of how large the balance is. 

The key benefit behind the debt avalanche is that by paying down the balance with the highest interest rate first, you are saving the most money over the life of the loan. While you won’t necessarily have the psychological perk that comes with paying off a low balance, it can still be incredibly empowering to know that you’re sticking it to the banks and reducing their ability to profit off of you.

How it works:

  1. First, list out all of your debts, from the loan with the highest interest rate to the loan with the lowest interest rate. A budgeting tool like YNAB (You Need A Budget) can be incredibly helpful. 
  2. As with the debt snowball, continue making your regularly scheduled minimum monthly payments on all of your debts.
  3. Each month, pay as much extra on the loan with the highest interest rate. As the balance decreases, you’ll pay less in total interest over the life of the loan.
  4. Once the debt with the highest interest rate is paid off, note the minimum monthly payment that you were paying on it, and apply that towards the loan with the next highest interest rate. Continue paying as much extra each month as possible.
  5. Repeat until you have paid off all of your debts.

As you pay off more and more of your debts using this method, the amount that you save each month will compound into an avalanche of savings.  

How to make money as a teenager: 25 best ways to earn cash this year

Debt avalanche example

Here is an example of the avalanche debt method:

A single mom I know budgets $500 toward debt payoff. She uses YNAB to document her debt goals and strategy, and to create a budget. Her loans include:

  • $1,000 due on a credit card debt with a 20% interest rate
  • $5,000 left on her student loans, with an 8% interest rate
  • $1,250 monthly car payment at a 6% interest rate

To keep things simple, let’s say each debt has a minimum monthly payment of $100.

This mom will set her car and student loan payments to the minimum of $100 each.

The remaining $300 of her monthly debt budget is devoted to her highest-interest debt: the credit card at 20%. The card debt will be entirely paid off by the third month. Whoo hoo!

Now, the extra $300 (plus the current $100 minimum = $400 monthly) goes toward slashing the second-highest interest-bearing debt: the student loans. That will be paid off after 1 year and 1 month. Yay!

Finally, all $500 goes to the debt with the lowest rate of interest, the car loan, which will be paid off three months later.

Congratulations, mama!

Debt snowball vs. debt avalanche

In choosing which method you pursue, it’s important to know the personal goals behind your debt elimination journey. Specifically, what are you trying to accomplish?

The debt snowball method might be right for you if:

  • You want a quick psychological win
  • You need to prove to yourself that you can pay off your debt
  • You need to free up money in your budget for other expenses

The debt avalanche method might be right for you if:

  • You don’t mind potentially going years before you pay off your first balance
  • You want to save as much money as possible
  • You have a moral disposition against interest

It’s also important to note that you don’t necessarily need to commit fully to just one method. If you decide to pursue the debt avalanche method, for example, that’s great.

But if you’re working on it for two years and begin to feel burnt out or weary, go ahead and pay off the loan with the lowest balance! It’ll give you the boost that you need to return to the avalanche method and commit for the long term. 

Additionally, there may be other factors that you might want to take into consideration. For example, if you’re paying off your student loans, do you have a mix of unsubsidized and subsidized federal loans?

If so, paying off your unsubsidized loans, which come with fewer benefits, may be the wiser move—regardless of interest rate or balance.

Ultimately, snowball vs. avalanche debt payoff is about which one feels best for you, and which plan you are more likely to stick to!

6. Sell stuff to earn money to pay off debt

As long as you are cleaning out debt, you might as well also cleanse your closets, drawers, garage and basement. Declutter your home, sell unwanted stuff, and put that extra cash towards your debt paydown program. Here are some things you can sell:

7. Get a side job, and put that money toward debt

When the loans are all put to bed, this new income stream can go toward savings, investments, vacations, a home — the sky is the limit!

Here is a roundup of some of my favorite high-paying work-at-home jobs that can be done part-time or full-time, and online remotely.

Hiring a professional resume writer or resume editor is a huge advantage. A quality resume service will help you not only create a professional resume, but also help you frame your experience and goals in a way that you cannot do on your own. It always helps to have a second set of trusted eyes when it comes to important career moves.

Going back to school? Learn about 49 grants and scholarships for single moms.

8. Consider professional help to pay off debt

If you’re totally overwhelmed with the debt-payoff process—or truly believe that you cannot dig out of debt on your current income—professional services can help.

A professional debt-relief service can help if you have:

  • Large sums of medical debt that you have no immediate way of paying off
  • So many loans and credit cards that you can’t manage on your own, and you may even be considering a hardship loan just to stay afloat
  • Poor credit, which means high interest rates, which makes payoff even harder, and you don’t know where to start to stem the chicken-and-egg problem

Debt relief services will negotiate down some of what you owe in exchange for a fee of 25% or more. The sum that is reduced is likely taxable, but it may still be a good deal. Here are some of the more reputable tax relief companies:

By comparison, a debt consolidation company will consolidate all of your debt into a single payment with a lower interest rate than all of your debt combined. The benefit is a shorter repayment term, fewer individual bills to manage, and less interest paid over the long-term.

Meanwhile, if you have poor credit, a credit repair company can help by disputing old or erroneous negative credit items, and counsel you to repair your credit history and score — which will help you qualify for a mortgage, car loan or better terms on existing credit:

Alternatively, if you only want to speed up the process of paying off your credit card debt,  you can opt for credit card consolidation, unify the debt from different card issuers, and pay them off slowly.

Correct errors on your credit report

Legally, every person in the United States is entitled to correct errors on their credit report. It is not uncommon for your score to be hurt by old debts that have actually been paid off (but still appear on your report), debts or bankruptcies that are not yours, or legitimate debts that erroneously are reported multiple times.

Getting these red marks off your credit report is within your legal rights, but it can be a huge pain in the butt. If you are strapped for time and patience, it can be worth the investment to pay a reputable credit repair company to take over this task for you.

A credit counselor can help. Start your search for a reputable credit counselor at the National Foundation for Credit Counseling.

9. Be honest with yourself about your personal finances

If you are stressing about your debt and credit, likely you are avoiding the facts of your financial situation. Below I will show you how to easily manage all your debt, bills and income, but first you have to deal with the emotional side of this problem.

Facts are that financial stress is REAL, and it takes a toll on your relationships, physical health and mental health. You may join those of us who struggle with deep money issues stemming from childhood, and therapy may be in order.

  • Be honest with yourself about how your money situation makes you feel. Living paycheck-to-paycheck is really stressful, right? Moving money around each week to make sure some bill clears is a shameful waste of energy and time. Living beyond your means is scary. Not having control of your money is embarrassing. Own all those feelings. They are normal, and they are real.
  • Face the facts about how you got here. It is easy to blame your parents for not teaching you about money, or the federal education system for failing to make personal finance mandated schooling, or banks for ripping people off, or your boss for underpaying you, or your ex for screwing you in the divorce, or your friends for pressuring you to overspend.
  • Ultimately, you are responsible for your money. You are smart and resourceful, and trust me: dumber people have gotten out of debt and even gotten really stinking rich. You can figure this out, and I will help you. But first, you have to own your responsibility in this mess.
  • Focus on the future. Think about how incredible it will feel to have all your bills set up on autopay, and never think about them because there is plenty of cash in the bank. Imagine how amazing you will sleep knowing you and your kids’ future is secure. Visualize how powerful you are each day as you make decisions about your career, your children, your home and your life.

FAQs about how to pay off debt on a low income

How do I get out of debt if I have no money?

Here are your options to get out of debt:

  • Budget, cut back your expenses and pay off your debt over a long, systematic term on your current budget 
  • Find ways to refinance and consolidate your current debt
  • Earn more money while maintaining your lifestyle, putting any extra money towards your debt first, even before savings and investments.

If you have reason to believe that you truly cannot ever get out of your personal debt, consider bankruptcy. 

How do I get out of debt if I live paycheck-to-paycheck?

If you feel you don’t have any extra money to pay off your debt, your options include:

  • Refinance your credit card, student, auto and mortgage debt.
  • Lower your monthly bills. This might include moving into a lower-cost home, getting a roommate, refinancing your mortgage or car, canceling some subscription services, adopting a more affordable lifestyle (less eating out, less shopping or vacations), as well as refinancing your credit card debt, tax or student debt. 
  • Earn more. Can you negotiate a raise, get a new job, start a side business or side hustle? 
  • In extreme situations, you may qualify to discharge some of your debt through bankruptcy. 

More debt relief resources for single moms (and anyone struggling to make ends meet)

A credit counselor can advise you on your financial situation and debts and help you put together a feasible budget. The Federal Trade Commission3 suggests finding a reputable nonprofit organization that offers free credit counseling services to help you get on track.

Here are a few to research:

  • American Consumer Credit Counseling — Offers a free debt counseling session
  • National Foundation for Credit Counseling — Provides online resources to help you learn about the debt management process and connects you to certified financial counselors
  • GreenPath Financial Wellness — Offers free debt and credit counseling by phone
  • Debt Reduction Services — Shares do-it-yourself debt management tools but also offers a free session with a certified credit counselor 

You can also contact your credit union, church, or a local charity to ask about debt counseling services.  

Bottom line: Use these tools for how to get out of debt on a low income

The upside to the personal debt crisis is that there are tried and true methods for getting rid of it – and plenty of analog and tech resources to help. Even if you have a low income or are living on one income.

Here are some more resources if you have a low income:

Help for single moms: 16+ resources$500 monthly single mom grant
Free laptopsScholarships for single moms
Free carFree Christmas gifts
Free smartphoneFree food
Free wifiFree and low-cost prescriptions
Free formulaFree clothes
Free toysGovernment assistance for single moms
Free gasFree daycare
Free preschoolFree prescription glasses
10+ charities that help single mothersLow-income home loans
Health insuranceHow to use EBT on Amazon

SOURCES

  1. “Changes in U.S. Family Finances from 2016 to 2019: Evidence from the Survey of Consumer Finances,” Federal Reserve Bulletin, September 2020, Vol. 106, No. 5. Board of Governors of the Federal Reserve System. federalreserve.gov/publications/files/scf20.pdf
  2. “The Changing Profile of Unmarried Parents,” by Gretchen Lingston. Pew Research Central, April 25, 2018. pewresearch.org/social-trends/2018/04/25/the-changing-profile-of-unmarried-parents/
  3. “How To Get Out of Debt,” Federal Trade Commission Consumer Advice. https://consumer.ftc.gov/articles/how-get-out-debt
How do I get out of debt if I have no money?

Here are your options to get out of debt: cut back and pay off your debt with your current budget; reduce or consolidate your current debt; and earn more money while maintaining your lifestyle.

Who can help me get out of debt?

A debt or credit counselor can help you create a plan to get out of debt.

Single women accounted for 20% of first-time, and 18% of repeat home buyers in 2021, according to the National Association of Realtors. That same year, a Freddie Mac study found that 58% of single female head of household renters didn’t believe they would be able to afford a home.

Even though the journey to homeownership has its challenges, it is possible for single moms to buy a home with the right knowledge and resources, including steady employment. And home ownership has many benefits, like equity and tax deductions. However, while preparing for homeownership, some individuals may explore short-term financial solutions to manage temporary expenses or cash gaps before securing long-term mortgage financing.

Keep reading to discover affordable mortgage loan options and education programs to help single moms with aspirations of homeownership:

How hard is it to buy a house as a single mom?

How can a single mom afford a house?

Home loans for low income

  1. HomeReady® Mortgage from Fannie Mae
  2. FDIC loans via Operation HOPE Home Buyers Program
  3. FHA Home Loan
  4. Home Possible® home loan from Freddie Mac
  5. Fannie Mae
  6. VA Home Loans
  7. USDA Single Family Housing Direct Home Loans
  8. USDA Single Family Housing Guaranteed Loan Program
  9. Habitat for Humanity

Home-buying programs

FAQs about buying a house

Bottom line: Home loans for single mothers are available, along with assistance

How hard is it to buy a house as a single mom?

Let’s face it. If you’re a single mom, it can be hard to buy a home. The most obvious hurdle is your financial situation, since you’ll be buying a house on one income. 

And even though the gender pay gap is narrowing, women are still earning less than men according to the U.S. Census Bureau. Women consistently make 30% less in annual income than men, and that number creeps upward as women age.  

“Buying a home is never an easy process, and being a single mom makes it more difficult — but not impossible,” says Zackary Smigel, real estate expert and creator of the real estate education program, Real Estate License Wizard.

Smigel, a licensed realtor and mortgage broker, points out that single moms with low incomes can take advantage of home-buying assistance programs. 

These programs often have low loan interest rates or offer grants that don’t require repayment.

Check out our post on how to buy a home as a single mom.

How can a single mom afford a house?

When you are ready to buy a home, you have many options to help you become a homeowner.

These are some tips to afford a home as a single mom:

  • Search for programs that help you buy a home at a discount like HUD’s Good Neighbor Next Door or through the HUD home inventory. 
  • If you need down payment or closing cost help, check out programs like The Chenoa Fund and Fannie Mae Community Seconds. Research HUD home buying programs and check with your state housing finance authority (HFA).
  • Apply for low-income home loans such as Freddie Mac Home Possible and Fannie Mae HomeReady. You can find these programs by attending home buying seminars, talking to lenders and real estate agents, or searching for “low income mortgages” online.
  • Connect with organizations and nonprofits like Habitat for Humanity which builds affordable homes for qualified applicants who are willing to help build the house and can pay a mortgage that does not exceed 30% of the person’s income.

If you have another single friend or family member who is looking to buy a home, you can also discuss pooling your resources to buy one together.

You can also create a housing fund and ask friends and family to contribute to it in lieu of gifts for birthdays and holidays. Sites like GoFundMe make it easy for people to help.

Low-income home loans

There are a lot of home loan options available for low-income households. Learn more about these helpful programs so you can choose the best fit. Ask your preferred lender which programs they offer for creditworthy, low-income borrowers.

1. HomeReady® Mortgage from Fannie Mae

As a borrower, your income must be 80% of the area median income (AMI). You can use the Fannie Mae AMI lookup tool to check your geographic area’s AMI.

You’ll need a minimum 620 credit score to apply, though 680 can unlock better rates. Down payment options are as low as 3% and funding from relatives, grants, and Fannie Mae Community Seconds is allowed. There are no geographic restrictions. 

You can get reduced mortgage insurance that cancels when the loan balance falls below 80% of the loan-to-value (LTV) ratio (the amount of the mortgage versus the value of the property). Finally, you must take the Fannie Mae HomeView online course or an approved alternative HUD-approved course to be eligible. 

2. FDIC loans via Operation HOPE Home Buyers Program

Operation HOPE Home Buyers Program helps low-income home buyers through FDIC-approved loans, down payment assistance, and first-time buying assistance.

Operation HOPE offers multiple programs to increase financial knowledge in underserved communities. Its first-time home buyer education program provides HUD-certified coaches to guide you through the home loan process.

You’ll get group training as well as one-on-one coaching that extends beyond the classroom. When you are ready to pursue an FDIC loan, your Operation HOPE team will continue to provide support. They can also connect you with other professionals along the way.

3. FHA Home Loan

Check into getting a Federal Housing Administration (FHA) loan, which offers lowered closing costs and down payments. The FHA offers fixed-rate loans available in 15- and 30-year terms nationwide.  

Borrowers enjoy low down payments and closing costs. It’s ideal if you have moderate to low income and a low credit score.

With a score of 500 to 579, you’ll need a down payment that is 10% of the cost of the home. At 580 or more, you’ll only put 3.5% down.

With an FHA loan, you must pay mortgage insurance, and if you put down less than 10%, you will pay it for the life of the loan. 

The property you want to buy must meet FHA eligibility requirements. For example, the FHA loan limit range for homes across the country is $472,030 to $1,089,300. You can check your specific area with this FHA lookup tool.

4. Home Possible® home loan from Freddie Mac

If you’re looking for low income home loans for single mothers, a Freddie Mac Home Possible mortgage could be right for you. With as little as 3% down, you can become a homeowner. To be eligible, your income cannot exceed 80% of the area median income (AMI).

Use the Home Possible Income and Property Eligibility Tool to look up a specific property’s AMI limits.

There are no geographic limits on loan amounts, and you can apply even if you do not have a bad credit score due to lack of credit history (though approval isn’t guaranteed). Mortgage insurance is required on one-unit properties, but once your loan balance is less than 80% of its value, it is no longer required. 

5. Fannie Mae

HomePath properties are Fannie Mae-owned homes offered to the public at a discount after the previous owner defaulted on a Fannie Mae-owned mortgage. These mortgages come with low down payments, renovation loan eligibility and closing cost assistance of up to 3% of the home’s purchase price.

6. VA Home Loans

If you are an active duty or reserve member of the armed forces, veteran, or eligible spouse, a VA loan could be the best way to go. If approved, you won’t need to provide a down payment or mortgage insurance. Plus, closing costs are kept to a minimum. There are no loan limits if you can afford the property.

The VA guarantees part of the loan and works with private lenders to offer affordable interest rates. The VA loan is available in every state and tribal lands via the Native American Direct Loan (NADL).

7. USDA Single Family Housing Direct Home Loans

The U.S. Department of Agriculture helps rural borrowers refinance their mortgages. This offer, in response to borrowers who did not have to pay a monthly mortgage because of COVID-19, helps keep payments affordable once they resume. 

These direct home loans are available for very low- to low-income borrowers who were approved for a mortgage payment stoppage due to COVID-19. You must meet or fall below the income limits for your area to be eligible. Your credit score is not a factor unless you have substantial federal debt.

8. USDA Single Family Housing Guaranteed Loan Program

The USDA Single Family Housing Guaranteed Loan Program offers a year-round application process. If you live in a rural area, this loan provides a way to purchase or build a home with no money down for qualifying applicants. The program offers 100% financing from approved lenders because it guarantees 90% of the loan.

To be eligible, you cannot exceed 115% of the area median income (AMI). You can use this USDA tool to check eligibility for properties and income. There is no set credit score, but you must show a history of making an effort to repay any debts you have.

9. Habitat for Humanity

Habitat for Humanity fixes up and builds affordable homes. The nonprofit serves 50 states and about 70 countries. If you are willing to take home ownership classes, volunteer at a Habitat ReStore, or help build your own home (or someone else’s), you could be one of the next Habitat homeowners.

To be eligible, you must demonstrate a need to secure safe housing and be able to make affordable monthly payments.

Are there any home buying programs for single moms?

In addition to low-income mortgage loans, there are also home buyer programs for single moms, which can help to find affordable properties and programs that offer mortgage assistance. Some lenders also offer low credit home loan options designed for buyers who are rebuilding their credit, making homeownership more accessible even if your score isn’t perfect yet.

Some of these federal, state, and nonprofit home-buying programs also educate you on the home-buying process from beginning to end. 

Check out the following resources for single moms:

Department of Housing & Urban Development (HUD)

You buy a home directly through HUD. In fact, a key purpose of HUD is to help more people become homeowners. 

HUD properties are lower priced because they are foreclosures or defaulted properties. They are owned by HUD as a result of a foreclosure on an FHA mortgage and are currently available in most states, although inventory changes constantly.  

To buy a HUD home:

  1. Contact your local HUD counseling agency
  2. Work with a lender to find out how much you can afford
  3. Choose the right mortgage type based on your circumstances
  4. Use the HUD inventory list to search for your new home
  5. Make an offer and prepare for the closing upon acceptance

HUD offers an online homebuyer’s kit that details the homebuying process. If you need help or have questions, you can contact a HUD housing counselor. They offer free or affordable advice to guide you through the process.

Public housing authority

Your state housing authority may have leads on local homeownership programs. Some may be designed especially for single parents. These programs, run by HUD, usually require counseling for prospective homeowners.

For example, under the Section 32 homeownership program, a PHA may sell one or more units in a public housing development to a low-income family. Plus, the PHA can offer Capital Fund assistance to help the family buy the home.

The Capital Fund is administered by the Public Housing Investments (PIH) Office of Capital Improvements. Each year, it awards grants to PHAs so that they can assist prospective homeowners as well as improve and update public housing developments and management systems.

Other options include:

  • Choice Neighborhoods Funds
  • Rental Assistance Demonstration (RAD)
  • Section 8 vouchers for mortgage payments

 Find and contact your local housing authority.

Free legal aid help

The Chenoa Fund

The Chenoa Fund is a government-chartered organization that provides up to 5% down payment assistance for those with a FICO Score of 600 or higher. The financial help can go towards a down payment, closing costs, prepaid items or you may direct funds to all three.

You are eligible for the best pricing if your income is less than 135% of your area’s median income.

The Chenoa Fund offers two options: a 10-year fixed-rate repayable loan or a 30-year forgivable loan. The 30-year loan has a 0% interest rate, requires no monthly payments and is forgivable under these conditions:

  • A 3.5% loan is forgivable when you pay your mortgage on time for 36 consecutive months
  • A 5% loan is forgivable after you make 120 payments on your primary mortgage.

Community Seconds

Community Seconds is a Fannie Mae-approved second mortgage that allows you to use the funds available from state and local governments as well as housing nonprofits to put together a down payment, get help with closing costs and even complete minor renovations.

Single mom home loans FAQs

Does my state have a homeownership assistance program?

Every state has some type of program to help homeowners — from government programs to private and nonprofit options. To find local help, start with a Google search on “homeowner assistance programs near me” or “first-time home buyer help in (your state).” 

Find state-based programs offering assistance with down payments, closing costs, and special financing options. 

How can a single mom build a house?

Check with organizations like Habitat for Humanity. They build houses with affordable mortgage terms. You can apply and have a chance to help build your own home.

The FHA and USDA also provide home loans you can use for new construction.

How can a single mom get home loans with bad credit?

If your credit score is bad, you’ll want a home loan that does not require a credit score or has options for low credit scores (less than 600).

For example, VA loans don’t require a minimum credit score or down payment, and FHA loans have options for single moms with a score of at least 500.

Home Possible® home loans from Freddie Mac also don’t require a credit score to apply.

How do I clean up my credit to buy a house?

A good credit score is important for buying a house. Fortunately, there are ways to fix bad credit. Here’s how to build your credit systematically:

  • Keep an eye on your credit score and report. Once your score reaches 700 or more, move on to a regular, unsecured credit card — one with no annual fee, a good points system, and other perks that you can now enjoy thanks to a solid credit score!
  • Get a co-signer with good credit for a regular credit card. Their good credit will affect your credit.
  • Become an authorized user on the credit card of someone with good credit, such as a parent, friend, or mentor.
  • Be a good credit user. Keep the total borrowed at 30% or less of the credit limit.
  • Make all of your monthly payments on time. The most important factor that makes up your FICO score is your payment history. As a result, you need to make it a priority to make all your monthly bills on time. Learn how to get help with energy assistance costs.
  • Dispute inconsistencies and errors on your credit report. If you find errors or downright lies, make sure to dispute them via the formal process offered by the Federal Trade Commission (FTC). You may choose to hire a credit repair company to do this for you.

As your credit score improves, you’ll be able to apply for some of the home loans mentioned earlier in this post.

What is the fastest way to raise your credit score to buy a house?

If you do not have any recent credit history, you can build a good credit history with the credit rating company FICO, within six months.

Tools to quickly raise your credit score now:

  1. Secured credit cards. A secured credit card requires you to put down a cash deposit to secure your own credit line — and as long as you make regular charges, and regular payments on time, your score will increase quickly.
  2. Check your credit report and FICO score for free, and see if you qualify for an immediate credit score increase of up to 20 points with Experian Boost, a legit way to boost your score.

Continue reading to learn more on how to build credit fast.

Can I get help with my mortgage if I am a single parent?

Home loans will help you to fund the purchase of your home, but you may be wondering how you can afford a mortgage payment, and if help is available. 

Fortunately, there are mortgage assistance programs for single mothers:

  • If you have a Fannie Mae home loan, you can get mortgage payment help such as forbearance or loan modification. Use the Fannie Mae lookup tool to search for options. 
  • If you have a Freddie Mac home loan, you can use this lookup tool to learn about helpful programs to keep you in your home.
  • The Homeowner Assistance Fund (HAF) is a federal program that helps homeowners pay their mortgages if they can prove financial loss from COVID-19. The HAF program is closed in Alaska and Florida.
  • If you have an FHA loan, HUD offers a list of resources to help you stay in your home if you have trouble making the mortgage payments, such as the Making Home Affordable (MHA) program.

You can also contact your mortgage lender and inquire about foreclosure prevention programs.

What are hard money loans?

Hard money loans are short-term real estate loans secured by the value of the property itself, rather than the borrower’s creditworthiness. These loans are typically provided by private lenders or specialized companies and are known for their speed and flexibility, though they come with higher interest rates and shorter repayment terms than traditional loans. 

Bottom line: Home loans for single mothers are available, along with assistance

There are home loans available for single moms. While loan amounts, interest rates, and fees vary, there is likely an option that will work for your financial situation. Plus, you can get assistance to pay your mortgage through grants, tax credits, and government programs. 

Before, during, and after the home buying process, be diligent with your finances, which will help you to build credit or improve your credit score.

Research all options to find mortgage assistance programs that best suit your needs. You can also talk to an HUD housing counselor or enroll in a first-time home buyer class to get more information on assistance programs so you know what to expect as you start the process.

Discover first-time home buyer grants for single mothers

25+ options for single moms seeking loans for emergencies and more

If you are struggling with money and need financial or other assistance, check out this list of resources:

Free help for single moms$500 monthly single mom grant
Government assistance for single momsFree beds
Free carFree money
Free money for billsFree gas
Free wifi10+ charities that help single mothers
Home buyer grantsFree housing
Free ipadAffordable movers
How hard is it to buy a house as a single mom?

No matter your income, there are many programs to help single moms achieve homeownership. It can be an uphill battle to ensure you are financially capable of owning a home and making regular payments, but there are many programs available to help you buy a house as a single mom.

Does my state have a homeownership assistance program?

Every state has some type of program to help homeowners — from government programs to private and nonprofit options. To find local help, start with a Google search on “homeowner assistance programs near me” or “first-time home buyer help in (your state).”

How can a single mom build a house?

Check with organizations like Habitat for Humanity. They build houses with affordable mortgage terms. You can apply and have a chance to help build your own home. The FHA and USDA also provide home loans you can use for new construction.

How can a single mom get home loans with bad credit?

If your credit score is low, you’ll want a home loan that does not require a credit score or has options for low credit scores (less than 600). For example, VA loans don’t require a minimum credit score or down payment, and FHA loans have options for single moms with a score of at least 500. Home Possible® home loans from Freddie Mac also don’t require a credit score to apply.