scroll top


Gold prices keep hitting new highs, thanks in part to market turmoil amid tariff wars. Spot gold hit a record April 14 at $3,245.42 — a 23% increase for 2025.

If you want to sell your bullion while prices are high, this post outlines the best, safest ways to sell — both locally and online.

We also go into detail about why our No. 1 recommended gold bullion buyer is CashforGoldUSA, which pays within 24 hours and has an A+ rating with the BBB, plus 100% free, trackable FedEx insurance.

We also explain the process of how to sell gold bars and bullion, if you’ve never done that before:

Understanding gold bullion

How to trade gold bullion

How to know what your gold bullion is worth

Where to sell gold bullion locally

Where to sell your gold bullion online

Is it a good time to sell bullion? Where can I sell safely?

Understanding gold bullion

First: What is gold bullion?

Bullion is physical gold and silver of high purity (99%+) that is usually kept in the form of bars, ingots, or coins for the purpose of investments.

Bullion can sometimes be considered legal tender, and is often held as reserves by central banks or held by institutional investors. However, the gold standard is not currently used by any government, and the United States abandoned the system in 1933.

Learn more about understanding whether your coin is more valuable as scrap, a collectible or bullion.

15 coins worth money now: Do you have any at your house?

How to trade gold bullion

Those who actively trade in bullion typically do so through dealers with access to one of the gold bullion markets, though it is simpler to trade through futures contracts or ETFs, such as iShares Gold Trust Micro ETF of Benef Interest (IAUM), VanEck Merk Gold Trust (OUNZ) or Goldman Sachs Physical Gold ETF (AAAU).

More casual, individual investors may chose to buy and sell gold bullion through gold bullion dealers, pawn shops, and online gold buyers. Costco has made headlines for selling gold bullion recently.4

How to know what your gold bullion is worth

To assess the value of your gold bar or ingot, multiply the current spot price of gold times the weight of the bar or ingot.

The weight of a gold bar or bullion is typically stamped on its surface. However, you can also use a digital scale to find its weight, use the scale at your local post office, or ask to use a scale at a local jeweler or pawn shop.

A gold buyer should pay 90% or more gold bullion (while the percent will be less for scrap, jewelry or dental gold).

How much is one gold bullion bar worth?

The most common gold bullion bar — a.k.a. a gold brick — weighs 400 ounces. At a spot price of $3,200 per ounce, it would be worth about $1,28 million.

How much is a 1kg gold bar worth? 

At a price of $104 per gram, a 1kg gold bar — 1,000 grams — would be worth about $104,000. 

What is a 5 lb gold bar worth?

At a price of $3,200 per ounce, a 5 lb gold bar would be worth about $256,000.

How much is one 24k gold bar worth?

That depends on its weight. A 24K gold bar is 99.99% pure and will be worth its weight times the current spot price of gold.

Where to sell gold bullion locally

If you prefer to sell locally, or want to get a quote, this post explains how to find a reputable pawnbroker in your community. A gold buyer, jeweler or recycler can also be a good place to sell. Check local Yelp and Google reviews and ask friends and family for recommendations.

Do banks buy gold bars?

For the most part, the answer is no. When the United States operated on the gold standard — a system in which the value of money maintained a stable rate in exchange for gold — banks often accepted gold bars and gold bullion. 

Since that went away, banks don’t deal in precious metals anymore.

CashforGoldUSA display ad

Where to sell your gold bullion online

Learn about all the top online gold buyers for selling your gold bullion online.

The process to sell gold bars and bullion to a reputable online gold bullion buyer typically works like this: 

  1. Request a quote online through the gold bullion buyer. Gold bars and gold bullion are nearly always 24k gold, so you’ll likely be able to sell close to the spot price of gold. 
  2. A quality gold bullion buyer will send you a free FedEx or USPS mailer, along with a tracking number. Most buyers will insure your gold bullion up to a certain amount.
  3. Within a few days of receipt, the gold bullion buyer should make you an offer, which you can accept or reject. 
  4. A gold bullion buyer should then pay within a couple business days via PayPal or send a check overnight. CashforGoldUSA pays within 24 hours.
  5. A quality online gold buyer should also return your item for free via a trackable shipper if you reject the offer. 

CashforGoldUSA is our recommendation for the best place to sell gold bullion and gold bars, based on our criteria for very high reputation, history of paying a fair price, speed, and overall intent to treat customers well.

In addition to paying within 24 hours, CashforGoldUSA offers a 10% bonus if you ship your gold bullion within a week of receiving your mailer. No minimum weight or resale value. Learn more in our CashforGoldUSA review.

google-maps-usa-image

Bottom line: Is it a good time to sell bullion? Where can I sell safely?

As gold prices have hit two record highs in the past few months, it is an excellent time to sell any gold. Gold bullion is easy to sell and for a low commission.

Always shop around locally and/or online for a reputable gold buyer who guarantees a minimum payout for your bullion, offers free shipping and insurance.

If you choose to sell your bullion online, we recommend selling to CashforGoldUSA for a few reasons:

  • Payouts within 24 hours
  • Better Business Bureau A+ rating
  • Insured up to $150,000 by Lloyds of London while held
  • Price-match guarantee
  • Free return guarantee
  • 10% bonus if you ship within 7 days

Get a quote with CashforGoldUSA now >>


How do I sell my gold bar?

The process to sell gold to any reputable gold bullion buyer typically works like this: Request a quote online through the gold bullion buyer. Gold bars and gold bullion are nearly always 24K gold, so you’ll likely be able to sell close to the market price of gold. Make sure to get a written offer from a buyer.

How much does gold bullion sell for?

Gold bullion typically sells for 90% to 95% of the current resale value of gold. In comparison, most gold buyers offer between 70% and 80% for gold jewelry and other gold items, which are not usually pure gold.

Is gold bullion easy to sell?

Selling gold bullion is no harder than selling any other gold item. You can get an estimate on the price of your gold bullion gold calculator that is based on the current price of gold.

Will banks buy gold bars?

Banks nor credit unions buy gold anymore, including bars and bullion.

What is bullion gold worth?

Gold bullion — whether in bars or coins — is the price of 24K gold. Reputable gold bullion buyers will pay you close to the current price of gold, since the buyer stands to make money as the value of gold appreciates.

How much is a gold bar worth?

The value of a gold bar is the spot price of gold times its weight. For example, at a spot price of $3,245 per ounce (April 15, 2025 price).

Ladder Life insurance promotes its low premiums with an easy online signup process and no medical exam for policies up to $3 million. 

These claims are accurate. However, if you have any medical conditions or you’re overweight — like me — you may not be able to get coverage through Ladder.

While Ladder is one of the newer life insurance brands, its coverage is backed by long-established and reputable life insurance providers. 

Or, keep reading for our full Ladder Life insurance review:

What we found when reviewing Ladder Life

  1. Ladder is a legit life insurance company
  2. Ladder is not for everyone
  3. No medical exams
  4. Flexible policies

How we evaluated and rated Ladder

Ladder customer reviews

How much does life insurance from Ladder cost?

How does Ladder Life insurance work?

Pros and cons of Ladder

My Ladder Life insurance experience 

Ladder alternatives

What we found in our review of Ladder Life: 4 things to know

These are the main things you need to know if you’re considering Ladder Life insurance coverage, based on our deep research and personal interaction with the product: 

1. Ladder is a legit life insurance company

Ladder Life insurance policies are issued by A+ Better Business Bureau-rated insurance providers, who have been paying out claims for decades: 

  • Fidelity Security Life Insurance Company, A.M. Best rated A
  • Allianz Life Insurance Company of New York, A.M. Best rated A+
  • Allianz Life Insurance Company of North America, A.M. Best rated A+

2. Ladder is not for everyone

Ladder only issues new policies to people who are between the ages of 20 and 60 in relatively good health (your age is determined by your nearest birthday). You may be denied coverage if you: 

  • Have a high BMI 
  • Suffer from chronic medical conditions
  • Have financial issues (for instance, if you are unemployed)

Ladder will not cover you past 70 years of age. If you are 55 years old, for example, the longest term you can get is 15 years.

Ladder Life insurance only covers U.S. citizens or lawful permanent residents who have lived in the United States for more than 2 years.

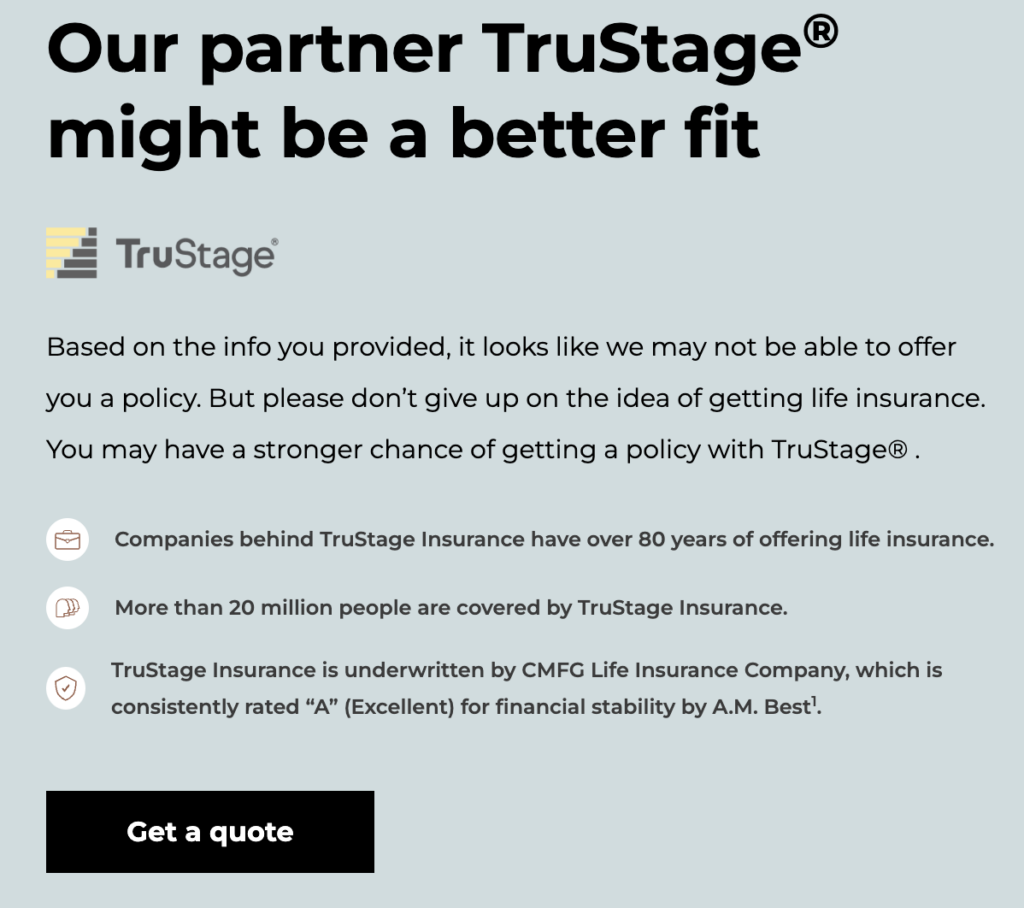
A representative from Ladder said the company has no set criteria to determine a person’s eligibility, and each application is considered on a case-by-case basis. However, after inputting my height and weight in the initial form, I was instantly directed on the next page to check out another life insurance company, TruStage, one of Ladder’s partner insurers. 

This wasn’t an outright denial but rather a suggestion that Ladder likely wouldn’t be able to cover me if I submitted my questionnaire. 

3. No medical exams

Ladder does not require a medical exam for policies less than $3 million. The company uses a pre-screening questionnaire to weed out unqualified candidates, so you don’t have to waste your time going to a health check only to be denied coverage. That said, not everyone will pass this stage and be offered a policy.

4. Flexible policies

A unique feature, Ladder gives people the option to change their coverage level overtime as their financial needs change. They call this “laddering up” or “laddering down,” which can be requested at any time from your online account, no extra fees involved.

Ladder promotes this feature as being as easy as a few clicks on your smartphone. However, the process is really more manual and old-fashioned than that.

If you request to ladder up your coverage, it will likely take time for the underwriting team to process your application, since they treat the request like a new application. If you are not instantly approved, it could take anywhere from two weeks to two months to hear back about a decision.

This new policy will be based on information you submitted in your initial application, though Ladder’s underwriting team may follow up with questions about your previously submitted or current health/financial information. You may not be approved for the increased coverage. 

However, if you choose to ladder down your coverage, there is no waiting period, and the change is effective immediately.

Note that changing your coverage options will increase or decrease how much money you pay for your policy.

How we evaluated and rated Ladder

We evaluated Ladder in comparison to other online life insurance companies based on:

  • Coverage – Amount of coverage available, variety of coverage options
  • Ease of application – Online questionnaire, medical exams, overall user experience
  • Price – Cost of coverage
  • Customer service – BBB reviews/my personal experience with customer service
  • Customer reviews – Customer ratings across major review sites 

These are our ratings:

[wp-review id=”31831″]

What others say about Ladder

Online Ladder Life insurance reviews are overwhelmingly positive:

BBB rating and reviews

Ladder itself does not have a Better Business Bureau profile. However, its policies are issued by three insurers that all have an A+ BBB rating:

  • Fidelity Security Life Insurance Company
  • Allianz Life Insurance Company of New York
  • Allianz Life Insurance Company of North America

None of the reviews on these pages specifically mention Ladder. 

Trustpilot rating and reviews

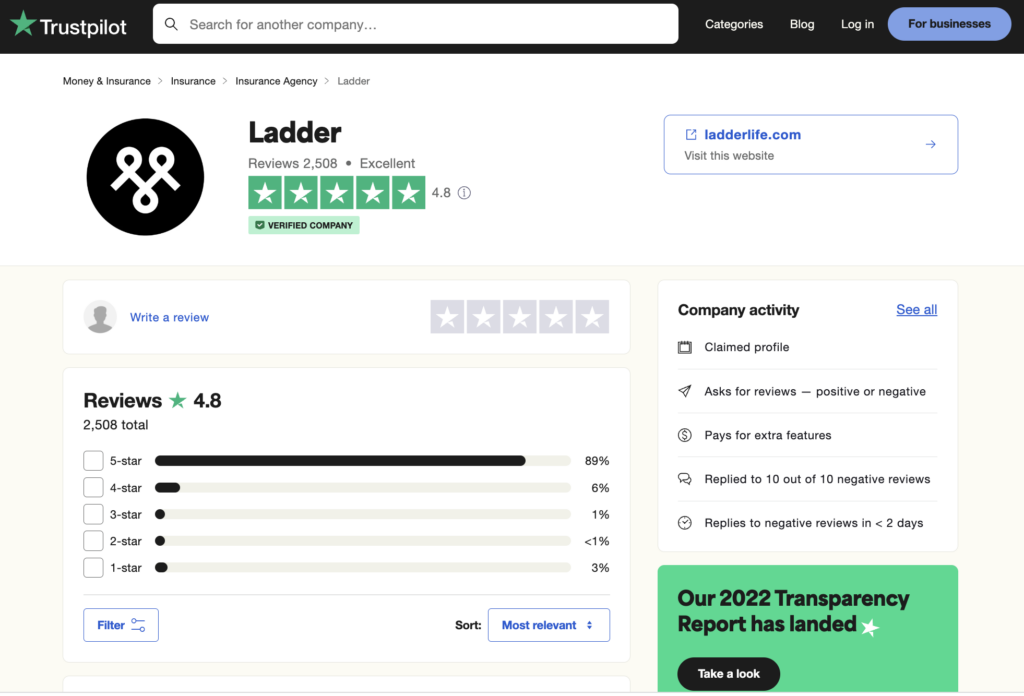
Ladder has 4.8 out of 5 stars on Trustpilot based on more than 2,500 reviews, most of which are 5 stars. 

Ladder Insurance review Trustpilot page.

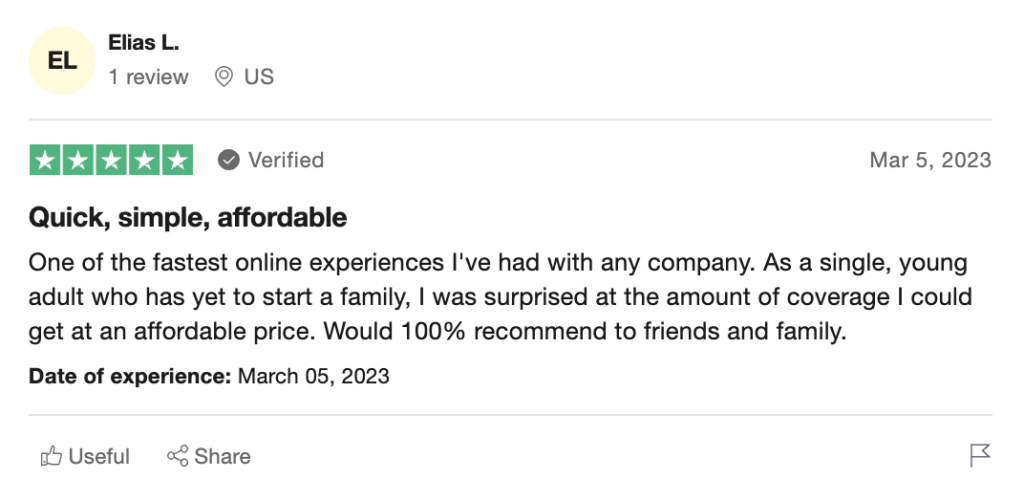
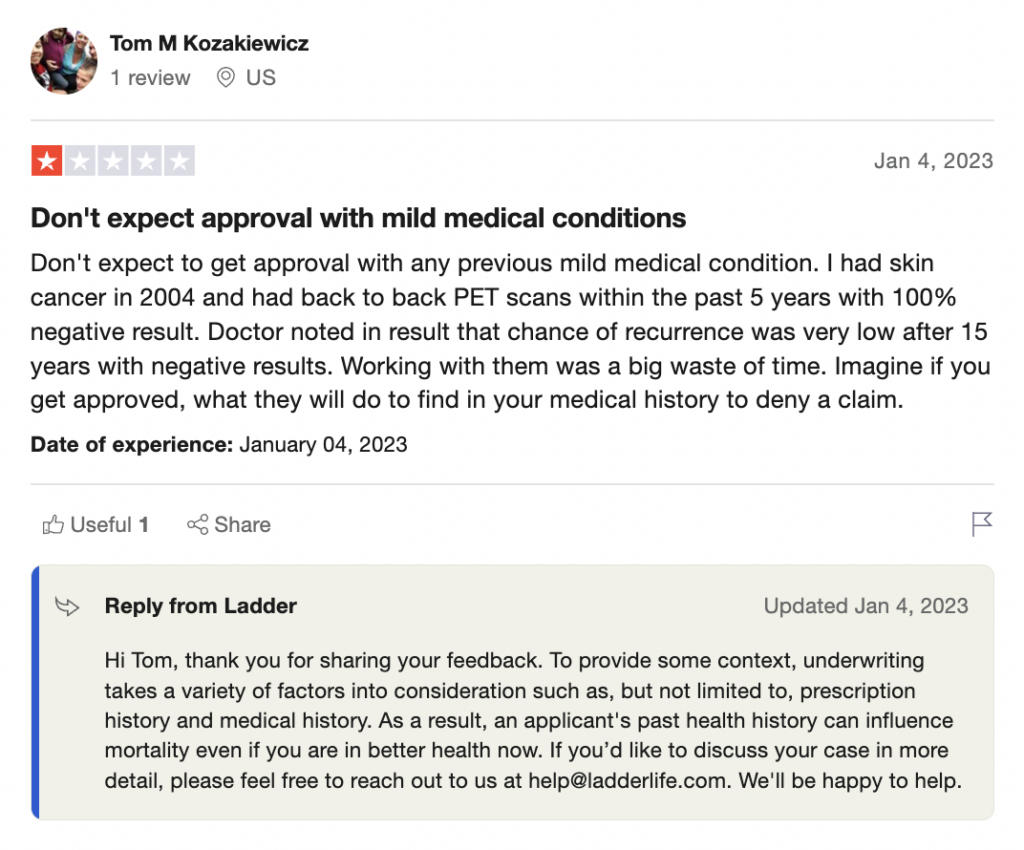
Reviewers note the ease of application and low policy pricing. The rare negative reviews are typically from people who were denied coverage based on a medical condition: 

5-star Ladder Insurance review on Trustpilot.
5-star Ladder Insurance review posted on Trustpilot.
1-star Ladder Insurance review posted on Trustpilot.

What Redditors think about Ladder

There is a Ladder_Life_Insurance subreddit that appears to be run by Ladder, since most of the content is informative and advertises the benefits of signing up for Ladder.

Other Reddit threads are individual users scoping out life insurance policies, though few users have responded: 

Ladder Life + Marijuana Use
byu/rideonup inLifeInsurance
How many are using Life Insurance Ladders to save money?
byu/DoctorLinus inFinancialPlanning

Common complaints

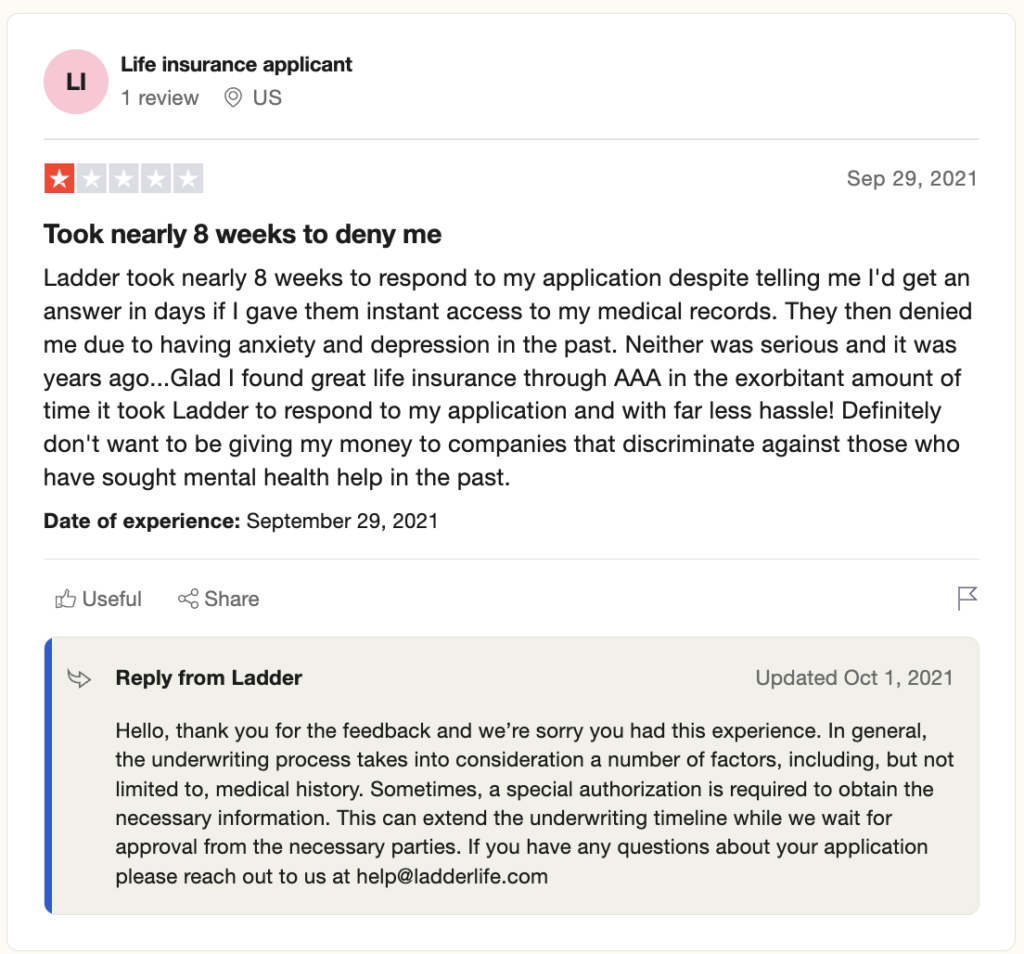
Most complaints about Ladder are from people who were denied coverage. Others note that it may take a long time to get a coverage decision if you aren’t instantly approved — one person claimed to have waited 8 weeks before being denied. 

1-star Ladder Insurance review complaint posted on Trustpilot.

How much does life insurance from Ladder cost?

Ladder life insurance premiums start at just $5 per month, with coverage ranging from $100,000 to $8 million.

As a real-life example, I sought policy estimates for a 50-year-old male with the following stats: 

  • 6’ tall
  • 250 pounds
  • Used tobacco/nicotine products weekly in the last 12 months
  • Income of $100,000 
  • 2 children
  • Remaining mortgage balance of $100,000

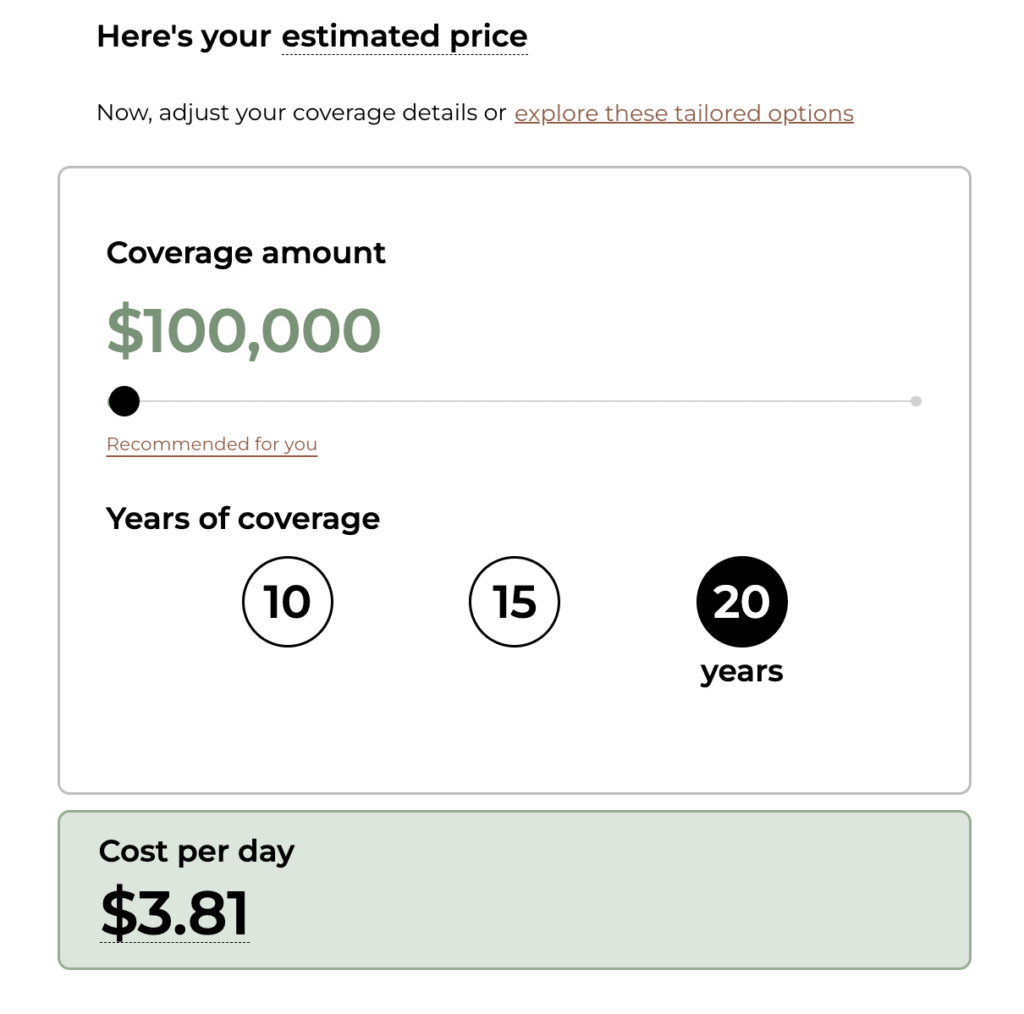
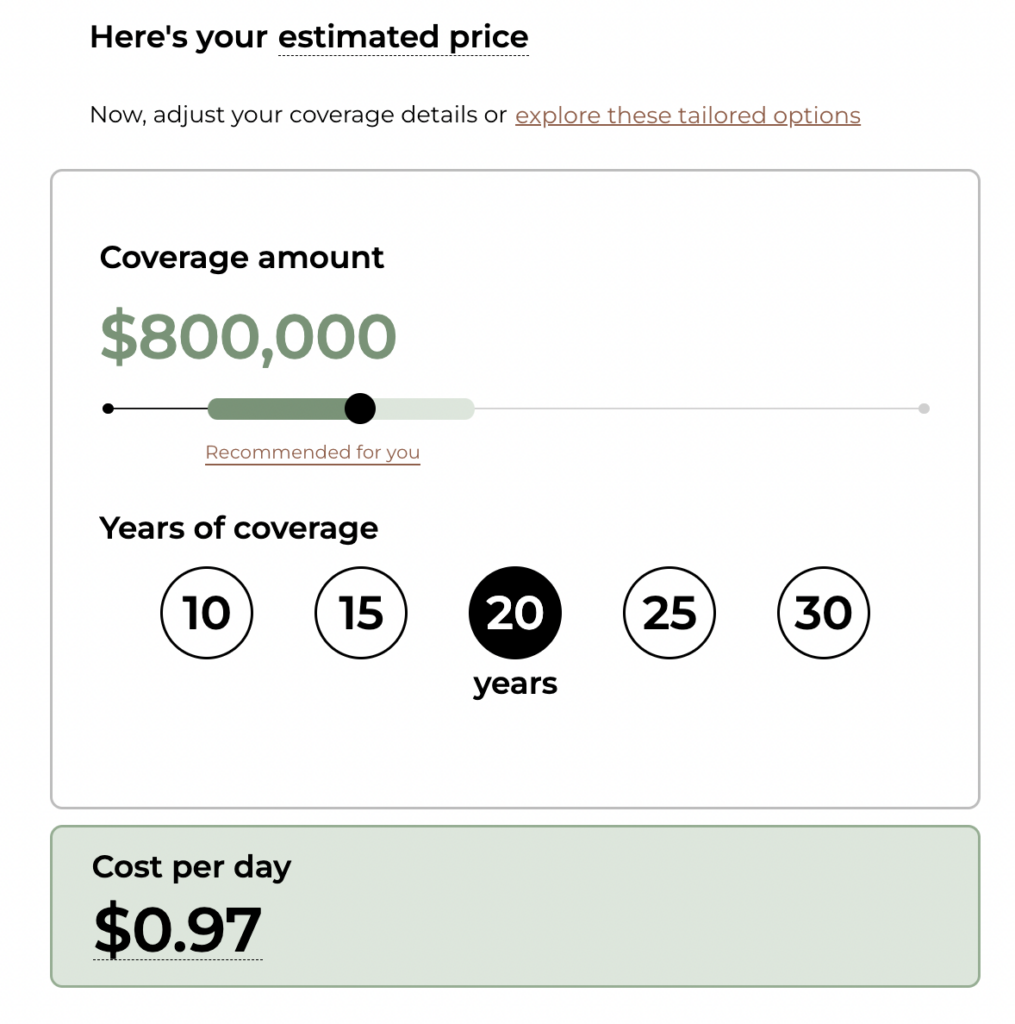
Based on $100,000 of coverage (which is the only amount this man was recommended), this is his estimated price if approved for a policy: 

  • 10 years – $2.62/day
  • 15 years – $3.13/day
  • *20 years – $3.81/day

*This is the longest policy he would be able to purchase through Ladder since they don’t issue coverage past 70 years.

Ladder Insurance review estimate for 50-year-old man.

As a cost comparison, I requested an estimate for a 30-year-old woman with the following stats: 

  • 5’5” tall
  • 150 pounds
  • Non-smoker
  • Income of $40,000/year
  • No children
  • No mortgage balance

This woman’s suggested coverage range was between $400,000 and $1.2 million. However, for the purpose of direct comparison, I set her coverage at $100,000:

  • 10 years – $0.34/day
  • 15 years – $0.37/day
  • 20 years – $0.40/day
  • 25 years – $0.51/day
  • 30 years – $0.52/day
Ladder Insurance review estimate for 30-year-old woman.

How does Ladder Life insurance work?

Ladder uses a simple online application process to determine eligibility for life insurance coverage. Based on your answers to their questionnaire, you’ll either be: 

  1. Instantly denied or approved
  2. Notified if you qualify after a thorough underwriting process, which may take anywhere from two weeks to two months

Ladder’s questionnaire asks information about:

  • Medical history
  • Income/financial status
  • Beneficiaries
  • Other life insurance policies you have in place
  • How much coverage you need and for how long
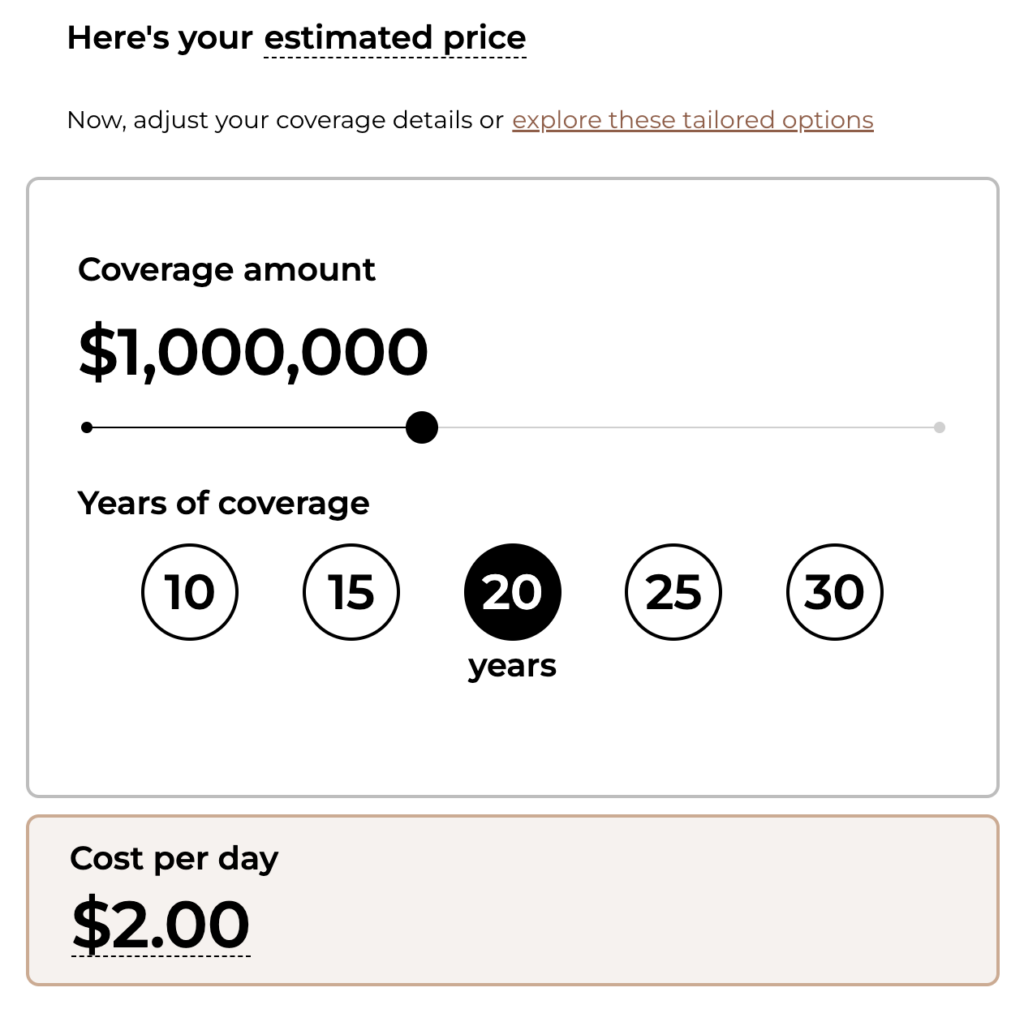
Ladder Insurance review estimate for one million dollars.

If you are approved for coverage, Ladder will pay out your coverage amount — known as a death benefit — to your beneficiaries in the event you die while covered. 

Details about Ladder life insurance policies

If you’re considering a Ladder Life insurance policy, here’s what you need to know: 

What kind of insurance is Ladder Life?

Ladder Life only offers term life insurance coverage, which means they cover you for a set period of time at a fixed rate, with a specific sum paid to your beneficiaries at the time of your death. 

This differs from whole life insurance coverage, which provides permanent coverage that builds cash value over time. Forbes did a cost comparison of whole vs. term life insurance policies and found that whole life policies were about 5 to 7 times more expensive, depending on the person applying for coverage.

What policies does Ladder offer?

Ladder offers term life insurance coverage from $100,000 to $8 million for a period of 10,15, 20, 25, or 30 years. 

Use Ladder’s life insurance calculator to determine how much life insurance you need. 

Does Ladder offer riders?

Ladder does not offer riders — add-on provisions that provide additional insurance coverage — because they “believe that riders complicate life insurance and do not provide a significant benefit for their added cost.” 

Examples of life insurance riders include guaranteed insurability, accidental death, waiver of premium, family income benefit, accelerated death benefit, child term, long-term care, and return of premium riders.

Self-employed? You need disability insurance

Does Ladder Life pay out?

Ladder policies are issued by insurers with long, proven histories of paying claims. As long as the death occurs within the policy term, your beneficiaries will be paid your death benefit at the time of your passing in one lump sum. If you die after the policy term, there will be no payout. 

Ladder does not pay out claims for deaths by suicide within the first two years of coverage and in cases of fraud. 

Pros and cons of Ladder

These are some of the benefits and drawbacks of Ladder Life insurance coverage: 

Pros

  • No medical exams for policies less than $3 million
  • Policies up to $8 million
  • Quick questionnaire that takes less than 20 minutes to complete
  • Instant decisions if you don’t have major health concerns
  • Locked-in pricing that doesn’t increase if your health status changes or as you age
  • Ability to “ladder up” or “ladder down” coverage based on your needs
  • App available for iOS devices
  • Live chat customer service option (with actual human people) from 7 a.m. to 4 p.m. PT
  • No cancellation fees
  • $50 referral credit given for each friend you refer who receives a coverage offer (not available in Louisiana, Michigan, Mississippi, Montana, New Mexico, Washington or West Virginia)

Cons

  • Does not cover people with certain health conditions, including obesity
  • Approval may be delayed if your application needs further review — for instance, if you have medical conditions that don’t automatically disqualify you from coverage
  • If you are older than 60, you cannot be covered, and you can only purchase coverage that lasts until age 70
  • Only offers term life insurance 
  • No riders or supplementary coverage
  • Live chat and customer service only available weekdays from 7 a.m. to 4 p.m. PT

Can’t afford health insurance? 5 health insurance options for single moms

My Ladder Life insurance experience 

Before I started Ladder’s application process, I was pretty positive I would be denied coverage based on my high BMI and medical conditions — namely asthma, PCOS, and a condition called IIH. I have tried and failed to apply for life insurance coverage in the past through other online providers. 

For reference, I am a 32-year-old, non-smoking woman. I want life insurance to replace my income for my husband and two children (4 and 9) in the event that I die before they are financially independent. 

It’s frustrating not being able to provide that safety net for my family, but I know I’ll have a tough time getting life insurance from any provider until I lower my weight. I’m not sure if my medical conditions alone would disqualify me from coverage. 

I’ve previously applied for coverage from Ethos Life Insurance and was instantly denied after going through the questionnaire, which included questions about my health history and financial status (income, debt, mortgages, etc.).  

I applied for Ladder on my laptop computer, though they do have a mobile-friendly site and mobile app available for iOS if you prefer. 

After inputting my age, weight, height, sex, and smoking status, I got a screen that suggested one of Ladder’s partner insurers, TruStage, might be a better fit for me. (Spoiler alert — it wasn’t. I was denied.) 

Ladder Insurance review referral to TruStage.

I was curious if changing my weight on Ladder’s application would change my result, and when I did, I was allowed to continue through the rest of the questionnaire. (Note that I did this strictly for research purposes, with no intention of actually starting a policy. If you open a life insurance policy with false information, you can be charged with fraud or your loved ones may be denied a payout at the time of your death if the information you provided isn’t accurate.) 

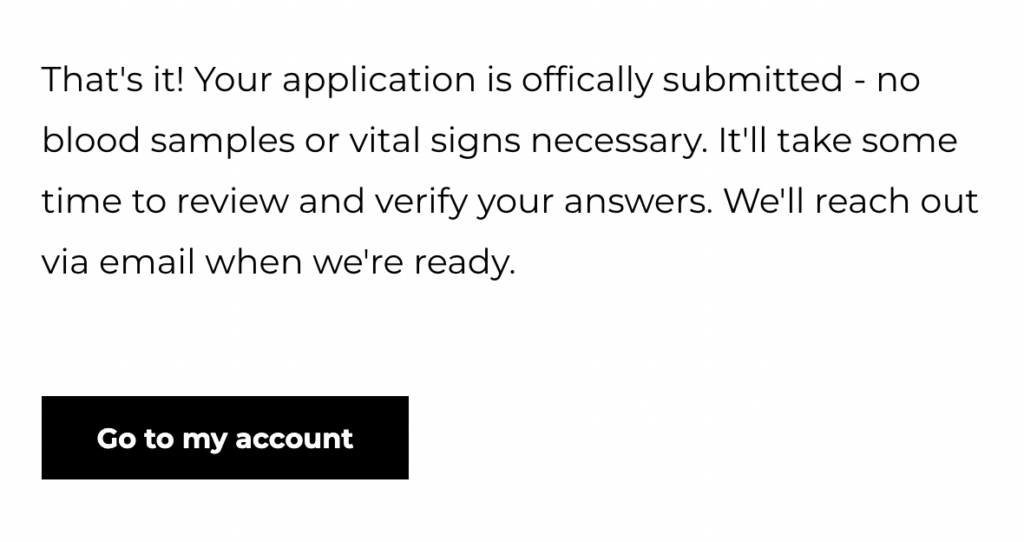
After I finished answering the questions, I wasn’t given an instant decision but was instead told that Ladder’s underwriters needed more time to review and verify my information, a process they said usually takes about two weeks but could take up to two months.

Ladder Insurance review application complete.
Ladder Insurance review waiting period.

Ladder vs. other life insurance companies

While most life insurance coverage is relatively the same, Ladder stands out because of its: 

  • Low premiums
  • Easy online application process
  • No medical exam for policies less than $3 million
  • Ability to increase and decrease coverage as your needs change

You can also check out our reviews of Bestow Life Insurance and Ethos Life Insurance, two other online insurance providers that offer term life insurance coverage with no medical exams.

Bottom line: Ladder is worth considering if you need to buy life insurance

If you are a relatively healthy adult between the ages of 20 to 60, Ladder is a solid life insurance option.

If you’re not sure how much life insurance you need or you want to learn more how to choose the best policy for your needs, check out our guide to life insurance for single parents.

Does Ladder Life require medical exam?

No medical exam for policies up to $3 million.

Does Ladder Life pay out?

Ladder policies are issued by insurers with long, proven histories of paying claims. As long as the death occurs within the policy term, your beneficiaries will be paid your death benefit at the time of your passing in one lump sum. If you die after the policy term, there will be no payout. Ladder does not pay out claims for deaths by suicide within the first two years of coverage and in cases of fraud.

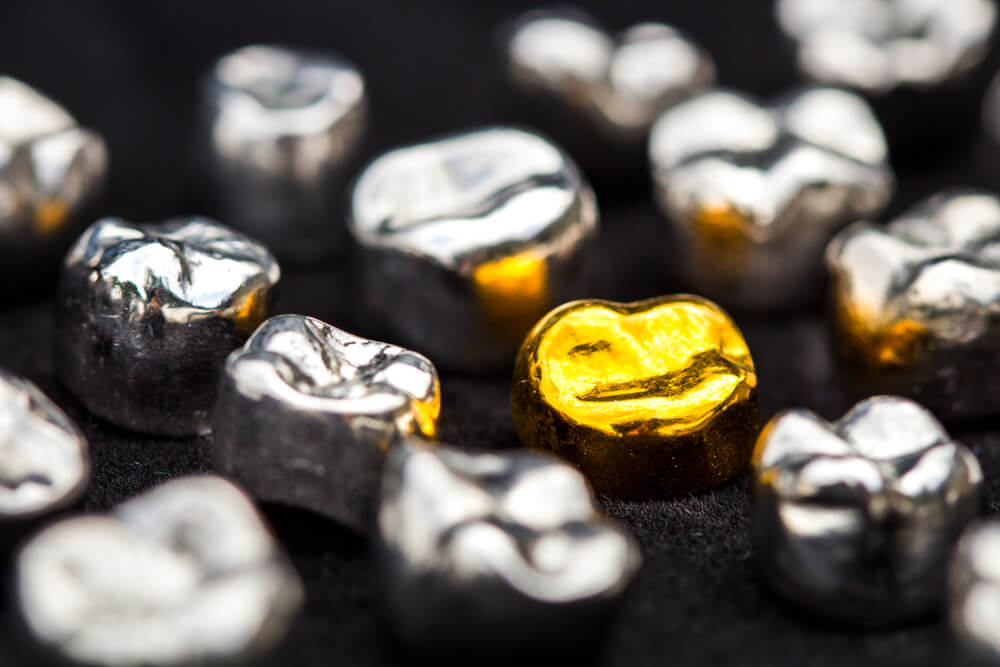
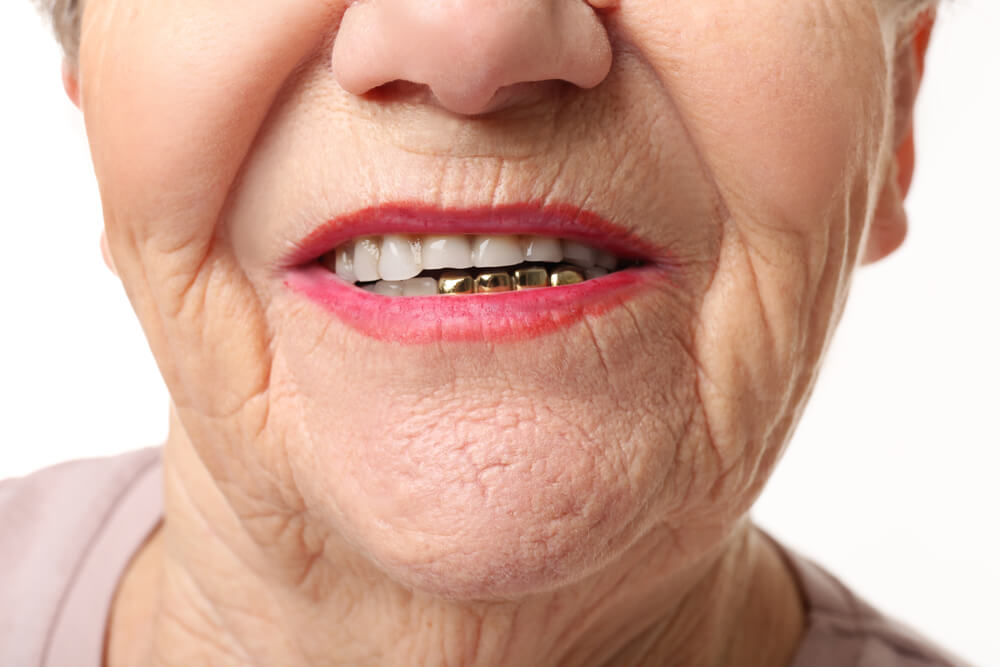
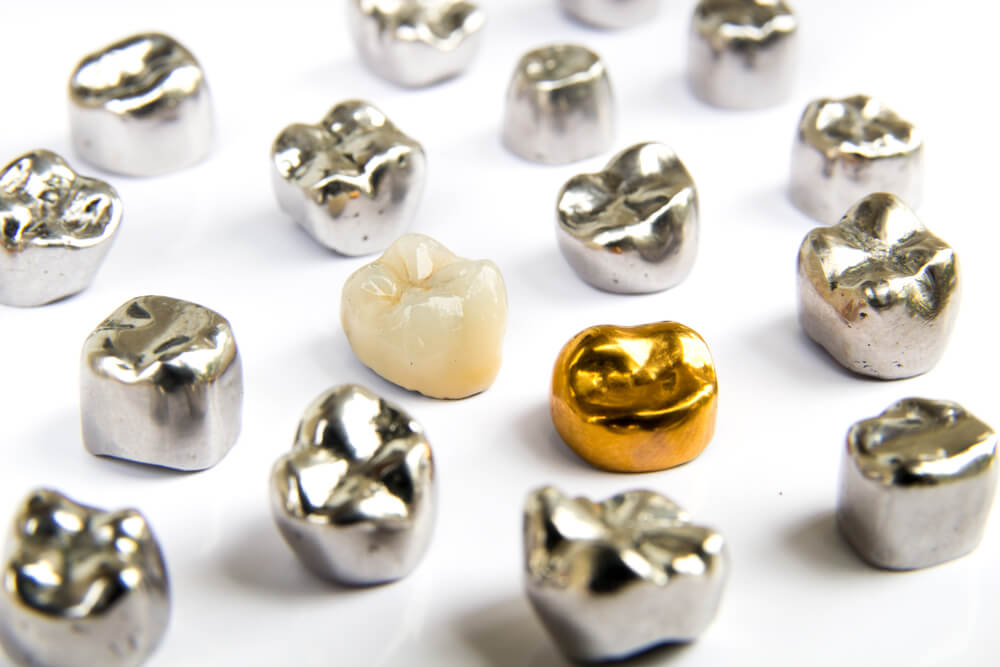
Gold teeth and caps, gold dental implants, gold fillings, bridges, bridges, gold inlays and onlays are valuable dental scrap that can add up to a nice profit.

As gold prices in general have skyrocketed in the past few years, dental gold is worth more than ever.

At current spot gold prices, a 3-gram, 16K gold tooth is worth about $300, and a 10-gram, 16K gold bridge is worth about $1,000+, before buyer commissions.

Tip: If you’re having gold fillings redone, ask your dentist for the dental scrap. Legally, it’s yours.

What you need to know about selling dental scrap:


Gold prices keep hitting new highs, thanks in part to market turmoil amid tariff wars. In January, 2026, gold is hitting new record highs near $4,700, nearly double a year earlier:

Yahoo finance ticker price of gold gold futures january 19 2026

Below are different ways you can sell your dental gold, answer commonly asked questions about gold dental scrap, and details on our No. 1 one recommendation for places to sell dental gold:

CashforDentalScrap, whose parent company has an accredited A+ BBB rating, and pays within 24 hours. Free FedEx or USPS shipping. Get a free quote now (no minimum value).

3 types of dental gold scrap buyers

Read more about selling gold scrap of all kinds and learn about the best ways to sell your gold for the most money possible, safely:

1. Online dental gold scrap buyers

Online gold buyers offer a more private and convenient process if you don’t want to sell your dental gold in person.

Our number one recommendation for dental gold buyers is CashforDentalScrap.com because they’re known to pay top dollar, fast, especially since they offer a highest price guarantee.

Here are a few of the biggest reasons we we think CashforDentalScrap.com is the best dental scrap buyer:

  • A+ rating with the BBB
  • Free shipping
  • Insured up to $150,000
  • Payment in as little as 24 hours
  • 10% bonus payment if you send your dental gold in for appraisal within 7 days of receiving your mailer
  • Buys gold in any form: Gold crowns or caps, gold teeth, gold bridges, PFMs — porcelain fused to metal — or PFGs — porcelain fused to gold — as well as jewelry and coins
  • Buys gold, silver, diamonds, or platinum: CashforDentalScrap.com has sister sites that will buy those materials from you, all with the same guarantees.

Read more about this family-run company in our CashforGold review post.

Other online gold buyers you might consider include:

  • Abe Mor
  • American Bullion
  • APMEX
  • CashforGoldUSA
  • Goldco Precious Metals
  • Gold Geek
  • JM Bullion
  • Kitco
  • Liberty Gold and Silver
  • Luriya
  • Money Metals Exchange
  • Royal Refining
  • SellYourGold.com

2. Search for: “Dental scrap buyers near me”

If you would specifically like to deal with a local business when selling your dental gold, doing an online search for “dental scrap buyers near me” or “where to sell dental gold near me” will give you a list of local buyers you can consider. This will most likely include pawn shops, gold exchanges, and maybe even jewelry shops. 

Read more about our investigation of selling gold scrap locally and online.

It’s important to note that not all pawn shops or gold exchanges will purchase dental gold, as it can be more difficult to determine the purity of the gold quickly. If they do buy dental scrap, you can expect them to pay less than an online buyer. Do your research when you are looking for who buys dental gold “near me.”

Read more about our investigation of selling gold scrap locally and online.

3. Local cash for gold businesses

Searching for “cash for gold places near me” will most likely return a similar list to the one above, including pawn shops, jewelry stores and gold exchanges. The upside of businesses is you will get cash quickly — usually immediately. Depending on the business, you may also get a good price.

How to value dental gold

Learn how to value dental gold.

Ultimately, the dental gold value of your dental scrap depends on its purity, weight, and how much work must go into extracting it from the dental component.

Gold buyers, including CashforDentalScrap.com, buy:

  • Dental sweeps
  • Gold crowns
  • Gold bridges
  • Silver crowns
  • Silver bridges
  • Platinum crowns
  • Platinum bridges
  • Palladium crowns
  • Palladium bridges
  • Mixed precious metal dental work
  • Bridges
  • PFM’s (Porcelain Fused Metal)
  • PFG’s (Porcelain Fused Gold)
  • Inlays
  • Onlays
  • Caps
  • Gold partials
  • Casting grain
  • Polishings

What karat is dental gold?

The purity of your dental scrap is essentially its karat value, which determines exactly what percentage of gold the metal contains. Dental gold is most commonly an alloy of 16K, but can range from 10K to 22K. If you are unsure about the purity of your gold, it’s even more important for you to choose a trustworthy dental scrap buyer who you are confident will be honest with you as they complete their analysis.

Karats% of gold purityApprox. value per gram (spot gold = $4,665/oz Jan. 2026)Fineness
9K37.5%$56375
10K41.7%$63416 / 417
12K50.0%$75500
14K58.3%$88583 / 585
18K75.0%$113750
22K91.7%$138916 / 917
24K99.9%$150999

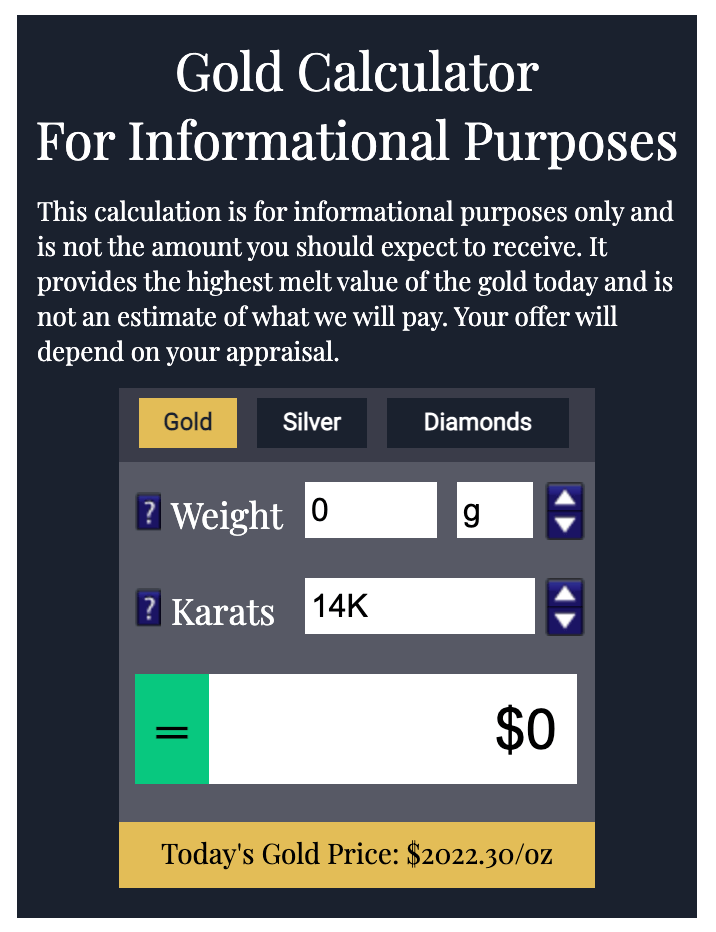
You can get an idea of the value of your scrap dental gold with CashforGoldUSA’s gold calculator, which factors in the current price of gold, before the gold buyer’s commission:

CashforGoldUSA informational gold calculator

How to tell if your gold is real

Is dental gold worth more than regular gold?

Gold value is based on weight and purity, whether it is dental gold, a necklace, coin, or gold bar. However, sometimes dental gold is worth slightly less than these other assets if the buyer needs to work to extract the tooth from the other materials.

How much is a gold tooth worth?

At a spot price of about $150 per gram of pure gold, before the buyer’s commission, the estimated melt value of a gold tooth ranges from about $300 to $600, depending on weight.

WeightGold purityEstimated melt value*
3 grams16K / 67%$300
4 grams16K / 67%$400
5 grams16K / 67%$500
6 grams16K / 67%$600


How much are gold grills worth (to resell)?

A grill, or grillz, is a decorative metal fitting across the front of your teeth — they can be fitted with gold, silver or gemstones. Learn more about selling your diamonds. Grillz can be any karat gold, and are weighed based on the number of teeth in the grill x ~1 gram per tooth. Based on a spot price of $150 per gram, your 6-tooth grill may be worth about:

Based on a spot price of $150 per gram of pure gold, a 6-tooth grill (6 grams total) may be worth approximately:

Karat Gold purity Estimated melt value (6 teeth)
10K 41.7% $375
12K 50.0% $450
14K 58.3% $525
16K 67.0% $603
18K 75.0% $675
22K 91.7% $825


How much is a gold dental crown, filling or dental bridge worth in scrap?

A typical gold crown or filling weighs 2–5 grams of alloy at 60%–85% purity. Larger crowns and caps can weigh 5–20 grams.
At a spot price of about $150 per gram of pure gold, before the buyer’s commission, the estimated melt value of a 16K (67%) gold crown or cap is approximately:

WeightGold purityEstimated melt value*
2 grams16K / 67%$201
3 grams16K / 67%$302
4 grams16K / 67%$402
5 grams16K / 67%$503
10 grams16K / 67%$1,005
15 grams16K / 67%$1,508
20 grams16K / 67%$2,010

How much is a porcelain fused metal (PFM) tooth worth?

PFM is very low value, worth only up to $10 per gram and bought in large batches from dentists and dental labs.

FAQs about selling dental gold scrap

What’s dental gold, anyway?

Dental gold is typically an alloy, which means it’s a mixture of pure gold with another metal such as silver, palladium, nickel or chromium. Dental gold can be used as a crown, filling, or other restorations. In the last couple of decades, some pop culture icons have adopted gold “grills” or “grillz,” which are, basically, dental jewelry.  

What do dentists do with gold crowns and dental scraps they remove?

Dentists should offer the gold to their patients and let them know that the gold can be sold for scrap. According to our research, most patients say no thank you. It could be because they don’t realize there is no difference between dental gold vs real gold!

Many dentists sell the scrap gold back to the labs that make gold fillings, gold teeth, gold crowns and gold dental overlays.

How do dental gold buyers make money?

Dental gold buyers make money using a pretty simple business model. 

First, they buy gold dental scrap from dentists and dental offices — or directly from individuals. Then, they process the scrap, if necessary, to separate the metal from any other components (such as teeth, porcelain, etc.). Next, they must melt the dental scrap down in order to separate the pure gold from any other metals which were added to make it stronger, or sell the alloy to a refinery who takes on this step.

What remains is pure gold, which will typically be cast into an ingot, bar, or other form and then sold on to a buyer who will use it to create something brand new with the gold. 

Dental gold buyers ultimately make money by reselling the gold that they purchase and process. For this reason, when a dental gold buyer buys your scrap gold, they’ll never pay you the full value of your gold. If they did that, they wouldn’t be able to turn a profit themselves, and there’d be no reason for them to be in business. 

The question then becomes: How much money should you expect for your gold? What percentage of the value of your gold is a good deal? 

The answer to that question will depend on the buyer you ultimately sell your gold to.

What are dental gold buyers paying?

How much money you’re paid for your dental gold will depend on the current spot price of gold.

Online buyers typically pay more for your gold than other buyers, like pawn shops or in-person gold exchanges. A good deal will pay somewhere between 70% and 90% of the dental gold value.

Bottom line: Sell dental gold online to get the best price from a scrap gold buyer

Online buyer CashforDentalScrap.com is our No. 1 recommendation thanks to:

  • Better Business Bureau A+
  • In business since 2005
  • Get paid within 24 hours of accepted offer
  • Free, insured shipping up to $150,000
  • Free, no-questions-asked returns
  • Buys all gold of any purity and weight

Get started selling your dental gold with CashforDentalScrap.com now.

CashforDentalScrap and its sister sites CashforGoldUSA, DiamondsUSA and CashforSilverUSA buy all quantities and quality of gold, diamonds, silver, flatware, coins, jewelry and fine watches.


How can I sell my dental gold?

You have three options for selling dental gold: online gold buyers, local gold buyers like jewelry shops, and cash for gold shops like gold exchanges.

What karat is dental gold?

Most commonly, dental gold will be 16 karats.

How much is dental gold worth?

Ultimately, the value of your dental scrap will depend on three key factors: Purity, weight, and how much work must go into extracting it from the dental component. A gold tooth can be worth $300 to $1,000

What are dental gold buyers paying?

How much money you’re paid for your dental gold will depend on the current spot price of gold.

How much is a gold dental crown worth in scrap?

A typical gold crown will be 2 to 5 grams of alloy at 60% to 85% purity can fetch $350 to $2,000 in scrap.

How much is a gold dental bridge scrap worth? 

A typical gold bridge will be 5 to 20 grams of alloy at 60% to 85% purity, and fetch $250 to $1,400 in scrap gold.

Can you ever be truly prepared for divorce? While you can’t see the future, there are some key steps you can take to get ready for the process, according to top divorce experts. 

Below, experts share their best advice on how to prepare for divorce, providing you with a detailed roadmap before proceedings are underway.

Wondering how to prepare for divorce? Here’s what you should know:

Table of contents

How to prepare for divorce: Decide if you are ready

If you’re on the fence about getting or preparing for a divorce, there are some telltale signs you might be ready. Ultimately, speaking with a divorce lawyer for women can provide early clarity on your position, helping you understand your rights, options, and what a fair outcome may look like. This kind of guidance can also make it easier to plan your next steps with confidence, particularly if there are children or complex dynamics involved.

“Overall, it’s a question of personal happiness that includes not only relationship satisfaction but also child and financial considerations,” says Susan A. Hansen, partner at Hansen & Hildebrand, S.C., based in Milwaukee. Hansen is also the co-founder of the Family Mediation Center, which provides collaborative divorce and mediation services.

In this section, we’ll review the most common signs and causes of divorce:

Should I get a divorce? Signs you might be ready

  • You stop arguing
  • You prefer to spend more time with your friends or family than your husband or wife
  • You stop making future plans
  • You regret getting married
  • You have reason to be secretive about your phone
  • You start worrying about money in the event you find yourself single
  • Your spouse is showing signs he or she is ready for divorce

Hansen recommends anyone contemplating divorce to consider joint therapy with a professional who has experience in marriage discernment counseling. 

“A skilled couples counselor can help couples consider what needs to change to remain married or what is needed to move forward with divorce with dignity and compassion,” Hansen says. 

More in this post if you’re thinking about divorce.

Common causes of divorce

Here are common causes of divorce, according to studies and polls, including those published in a 2020 edition of Journal of Sex & Marital Therapy, as well as Journal of Divorce & Remarriage and a 2019 edition of Journal of Divorce & Remarriage. 

  • Money
  • Lack of respect
  • No sex or bad sex
  • You grew apart
  • Cheating
  • Parenting disagreements
  • Addiction
  • Irreconcilable differences

Katherine Eisold Miller, founding attorney at the Miller Law Group in New York, says in a lot of divorces, there is a breakdown in communication, where each person feels misunderstood and maligned by the other.

“That mistrust — whether or not it is based on reality — is malignant, and if left unaddressed for too long will poison the relationship beyond repair,” Eisold Miller says.

Some states require divorcing couples to legally separate for a set period of time. Other states, including Texas, do not offer legal separation as an option at all — you are either married or not married.

If you are 100% ready to end the marriage, you are ready to divorce. However, there are some financial and legal advantages to both being legally separated as well as divorced.

Reasons people stay legally married, but attain a legal separation include:

  • Uncertainty about ending the marriage
  • Health insurance that one spouse can get for free or lower cost through his or her spouse’s employer or business
  • Staying married for a certain period longer allows one spouse to be eligible for the other’s pension, Social Security, or other retirement benefits
  • One or both spouses want to avoid divorce for religious reasons
  • Tax reasons

How to prepare for divorce: Steps to take if you’re ready

Once you’ve decided you want to move forward and start preparing for divorce, there are some things you should do before filing:

1. Make a self-care plan

Enlist a trusted therapist for support. “Divorce is emotionally and mentally draining,” says Statesville, NC-based divorce lawyer Dustin S. McCrary, who was recognized by Super Lawyers as a Rising Star in 2019. “You need to be proactive in taking care of yourself.” 

Family and friends can act as sounding boards, but you need an objective professional to confide in, according to divorce and family lawyer Raiford Dalton Palmer, author of the best-selling divorce guide I Just Want This Done.

Affordable therapy options, even free ones, can help reduce the financial burden of counseling. Connect with a certified mental health professional through BetterHelp.com. Read our review.

Take care of yourself: take walks outdoors, eat nourishing meals, get proper sleep, and engage in relaxing practices like meditation or yoga.

2. Set goals

McCrary suggests proactively setting goals for the divorce to help keep you on track. “You must know what you want before you can start on the journey,” he says. Write down what you want from the proceedings and revisit these goals throughout the process to help you stay focused. 

Whether you want to start a business, buy a home, or invest and build wealth, give yourself something to work toward post-divorce.

3. Lead with your head, not your heart

It takes work and some self-control to have an amicable divorce. 

“Strong emotions come up, and what you do with those feelings will have a big impact on how amicable a divorce will be,” Eisold Miller says. 

Try not to get too nostalgic about your spouse either. “Don’t underestimate your spouse and don’t trust their threats,” says Jill Spielberg, the matrimonial and family law partner at Abrams Fensterman, LLP in White Plains, N.Y., who specializes in high-net worth cases and high conflict custody litigation.

“Do not let your spouse scare you into staying married. They are likely trying to manipulate you.”

4. Get familiar with the process

Every state has its own rules and processes for filing for divorce. Familiarize yourself with the divorce process in your state. 

“Before filing, bone up on your state’s laws governing divorce,” advises award-winning financial journalist Margaret Price and financial planner Jill Gianola, co-authors of Single Women and Money: How to Live Well on Your Income. “Find out what legal steps are required to file, and which rules cover distribution of assets and allocation of alimony and child support.”

Also assess the pros and cons of alternative dispute resolution (ADR), such as mediation or collaborative practice, versus going to court. Although avoiding court may seem tempting, you can’t predict how amicable your spouse will be before proceedings begin.

5. Set up a P.O. box, change your email, phone, and computer passwords

You will need to be able to privately and confidentially communicate with your lawyer, as well as anyone else you might speak to about your divorce.

To receive correspondence from lawyers, and other important and private information, get your own personal address via a P.O. Box. This is especially important if your spouse does not know that you are considering a divorce and if you would prefer to keep it that way.

Also get a separate email address, if you and your spouse share one.

Changing your passwords can also protect any electronic evidence you may need for the divorce, Spielberg says. “Spouses often try to delete proof of wrongdoing when they see a divorce is imminent,” she explains. 

According to a Pew Research report, 67% of spouses share passwords. Protect your information and privacy by securing your online accounts. 

6. Locate and secure important documents and valuables 

Aside from gathering financial documents, put your passport, your children’s passports, and any jewelry or valuables you want to ensure possession of in a secure place.

“Spouses can take these items and temporarily hold them as leverage,”  Spielberg says. “This step prevents that from happening.” 

Bank accounts.

These include checking, savings accounts, CDs, money market accounts.

List of all assets of any value

If there is any question, get them appraised. These can include:

  • Real estate
  • Jewelry
  • Art
  • Cars and other vehicles of significant value. Check the value at KellyBlueBook.com
  • Time share
  • Any personal items of significant resale value, such as clothes, handbags, sports equipment, furniture, furs, electronics

If you’re self-employed or missing recent pay records, using an online pay stub maker can help you generate accurate pay stubs for income verification and budgeting during divorce.

Names and birth date of minor children you have together

If you and your spouse share children, you’ll need to collect the following:

  • Birth certificates
  • Social Security Numbers
  • Dates of Birth
  • Medical records (including for eye doctor and dentist)
  • Allergy information
  • List of prescriptions and any special care instructions 
  • School records (including their current class schedule and extracurricular schedule)
  • Current childcare arrangements (daycare, preschool, etc)
  • Current custody arrangements and child support arrangements (if applicable)
  • Child-specific expenses, such as tuition, medical bills, and the cost of extra-curricular activities

Co-parenting with a narcissist

Financial information

Collect the account numbers and current balances of each of the accounts below for the past year. Ensure that you have the correct login information for joint accounts.

  • Savings and checking accounts.
  • List of the contents in any safety deposit boxes
  • Inheritance details (what was inherited, from who, when)
  • Credit cards
  • Health Savings Accounts (HSA)/Flexible Spending Accounts (FSA)
  • Retirement accounts (401ks, IRAs, 403bs, pension,etc.) and other investments, such as brokerage accounts, bonds, etc.
  • Life/disability insurance policies
  • A copy of your and your spouse’s credit report

Payment history

Make a list of all of the monthly bills paid by you or your spouse and copy a year’s worth of statements. Be sure to write down the account numbers and current balance.

  • Mortgage / home equity line of credit
  • Any non-mortgage debt (car loans, student loans, personal loans)
  • Utilities (electric, water, phone, cable, etc)

Marital home information

Your marital house is likely the most valuable asset and its value will be a big part of how you divide assets in your divorce.

  • Take photos of each room in your home, being sure to detail any damage, current conditions, etc.
  • Obtain an appraisal of the home
  • Copy of the deed
  • Final escrow statement from close of escrow/settlement statement
  • Renters or homeowners insurance policy
  • Leasing agreements
  • Real estate/property tax bill for the past year

Vehicles

You will need a copy of the title, registration, and loan statements (if necessary) for any vehicles owned by you and your spouse, including:

  • Automobiles
  • Boats
  • Trailers
  • Motor Homes
  • Machinery such as tractors, excavators, bulldozers, and the like

Personal property

If you have any valuable property not already discussed, be sure to document them in a list alongside the purchase price, estimated resale value, ownership records, appraisal value, receipts of purchase (if possible). It can also be beneficial to photograph the items. This should include:

Retirement accounts

Retirement accounts that you need to consider include IRAs, Roth IRAs, 401(k)s, SEP IRAs, 403(b)s, 457’s Thrift Savings Plans, TIAA-CREF,  pensions and Social Security benefits.

This will all need to be discussed and likely divided, in your split.

Income information: Pay stubs, tax returns

  • Copies of state and federal tax returns for the previous three (3) years and all corresponding W-2 or 1099 statements.
  • Copies of corporate tax returns for the previous three (3) years if one or both spouses have a business.
  • Paystubs for you and your spouse (past six months is fine)
  • A list of any employer-provided benefits such as employer-provided health insurance, life insurance, disability insurance, stock-options, etc. 
  • Related post: What single moms and dads need to know about taxes

Life and disability policies

Every parent of a minor-aged child should consider life insurance, no matter how much money you earn, or whether you are dependent on child support, public benefits or others’ generosity. Fortunately, there are affordable, and easy ways to find affordable life insurance for almost every budget.

You need disability insurance. Those who do not have disability insurance through a job, including the self-employed, can find individual coverage through reputable companies for an affordable price. Learn more about disability insurance and how to buy it if you are self-employed.

Will and estate document

Even more important now than ever, as a single parent, if you do not have a will, you need a last will and testament (also known as a legal will), as well a living will.

Related: Rocket Lawyer review

7. Assemble your divorce team

These are some professionals you may need to hire during the divorce process: 

As you prepare for divorce, assembling a reliable team of professionals, including legal and financial experts can help you navigate the process more effectively.

For guidance through the legal steps and to ensure your rights are protected, consider consulting experienced divorce lawyers in Newcastle who can help navigate the process.

8. Focus on low-conflict and equality

“How you start a divorce will have a profound impact on whether it is amicable or high conflict,” Hansen says.

She says it helps to view divorce as a restructuring of family and finances rather than a win-lose battle.

Studies find that when parenting time is shared equally between parents, the kids fare better, there is less conflict in the divorce overall, and both men and women fare better as single parents.

Beware of these 18 sneaky divorce tactics so you can overcome them

9. Focus on earning more

Often divorcing spouses find ways to lower their incomes, forego promotions or raises, hide money or otherwise make it appear on the books that their income is lower than it actually is — all to angle for paying less alimony or child support — or qualifying for more.

Once exposed this will look bad in court or result in any negotiations breaking down. I advise divorcing women not to fall into the trap of financial dependency — but focus on earning and financial independence.

“The whole point of divorce is to move on into a new and better life — and you can’t do that if you spend your energy trying to be financially tied to this man,” says Johnson, who wrote The Kickass Single Mom (Penguin), a No. 1 Amazon bestseller.

Check out these posts for ways to make more money: 

10. Gather your financial records

Molly Ward, a certified financial planner (CFP) and certified divorce financial analyst (CDFA) with Equitable Advisors in Houston, says you should gather important documents such as: 

  • Tax returns
  • Pay stubs
  • Employee benefits
  • Current statements for all bank, investment, and retirement accounts
  • Insurance information
  • Pension estimates
  • Credit reports from the three major bureaus (Equifax, TransUnion, and Experian) 

11. Create a post-divorce budget

You need to know as soon as possible what your new financial situation will look like and you need to be realistic — including if you are a stay-at-home mom, McCrary adds. “There is going to be a change in your standard of living,” he says. “Be prepared for that.” 

How can you best prepare? Price suggests setting up a budget your expected costs of necessities, which includes food, clothing, housing, and transportation for both you and your children, and then compare that cost with your expected post-divorce income.

You should also consult Social Security for details about claiming your entitlements as a divorced spouse and take changing health insurance options into account if you’re on your spouse’s plan.

12. Evaluate the true value of your assets 

Know what your assets are really worth.

“For example, a traditional $10,000 IRA may be worth only $7,500 after you pay taxes on the withdrawals, while qualified withdrawals from a Roth IRA are tax-free,” Gianola explains.

This goes for your valuing and selling your house, too. “Don’t request to keep your home unless you can afford to,” Gianola says. “Instead, use cash from your share of the home as a down payment on a more affordable residence.” She adds that by giving up the house, you could receive a larger portion of joint savings and investments.

Jay Mota, a CFP and CDFA based in New York City, says it’s important to understand what all of your assets are worth, even if you don’t necessarily want them. 

“If you know an asset has a value and you have no interest in that asset, you could still use it as leverage in the negotiation,” Mota says.

Learn more about jewelry appraisals, including diamond appraisals.

13. Separate your income

Once separated, transfer your income into an account that your spouse can’t access. Consider withdrawing half, or all, funds from your joint accounts into this one, Spielberg says.

“Angry spouses who are surprised by divorce filings typically drain the bank accounts as a first act of retribution, so get ahead of that possibility,” she advises. 

How to prepare for divorce: When to start the divorce process

When you’re finally ready to get divorced, here’s how you should approach it:

When it becomes real: How to start the divorce process

If you are initiating divorce, or just learned that your spouse is ready to separate:

  1. Get money in your own name, in your own account that no one else has access to. However, do NOT take money that is legally both of yours (which may mean that income from your job may be legally your husband or wife’s, too). Open a checking and savings account in your name only, as well as a credit card. If you need to move quickly, some banks allow you to open a checking account online instantly. 
    Ward also suggests freezing your credit so that your name can’t be added to new loans. 
  2. Make sure your bills are paid, and paid on time. Keep an eye on your credit score.
  3. Call a few attorneys in your area to understand what you can expect. You don’t necessarily need to hire a divorce lawyer, but insight from attorneys in your area will be very helpful.
  4. Do not do anything rash. Do not move out of the house (yet). Do not take the kids away from their other parent. Do not quit your job, spend a bunch of money, or flaunt a new girlfriend or boyfriend publicly. Be an adult.
  5. Be kind and decent at all costs. This is horrible for everyone. Keep the drama as low as possible — at least for now.

12 tips on how to have a happy, friendly divorce

Amicable or friendly divorce does not mean that the spouses are friends, or even friendly — but they are not at war, either.

Eisold Miller says it takes work and some self control to have an amicable divorce. 

“Strong emotions come up, and what you do with those feelings will have a big impact on how amicable a divorce will be,” she says.

  1. Focus on being fair and honest, and aim for compromise.
  2. Be kind — to our ex (this is hard for him, too), yourself, and those around you. This is a loss and change for everyone.
  3. Expect it to be hard. “Amicable” is nice word, and sometimes this process is referred to as a “friendly” divorce — or you may seek mediation or a collaborative process. A positive vernacular, but all very hard and painful.
  4. Commit to full financial disclosure, and no sneaky business to keep your income low.
  5. Do not threaten or aim for majority time with the kids. Studies show equally shared parenting is best for children — and moms’ income
  6. Aim for no child support or alimony — women and men can now support themselves financially, and should. Best work-careers for moms
  7. Commit to self-care. Divorce will go down as one of your most difficult and painful experiences.
  8. Find a positive tribe. One study found that when divorcing couples receive negative feedback from their friends and family (“Take him for all he’s worth!” “I always hated that bitch! Make her pay!”) the divorce conflict was higher than in separating couples who had kinder support networks.
  9. Open yourself up to rewriting your ideas about who you are — and who you will be going forward. Let go of your old identity as a married person. 5 limiting beliefs that keep single moms broke, angry and alone.
  10. Work through any guilt you may have about leaving him/her.
  11. Recognize that this process establishes the tone of your new relationship going forward. If you share children, your husband or wife will be in your life for a long time.

How to prepare for divorce: Choosing what’s right for your situation

Depending on your relationship with your soon-to-be ex, you may be able to try for an amicable divorce, which will likely save you time, money, and a lot of stress. Here are common modes of divorce:

Uncontested or amicable divorce 

Marina Shepelsky, CEO and founding attorney of Shepelsky Law in Brooklyn, N.Y., says an uncontested or amicable divorce is a divorce in which both spouses mutually agree to end their marriage without contesting any issues. 

In an uncontested divorce, couples may be able to get divorced without a lawyer.

Free legal aid help

Collaborative divorce

In a collaborative divorce, both parties work together to create a settlement agreement by addressing common divorce issues like child custody and support, equitable distribution of property, and alimony. Collaborative divorce can be handled with or without attorneys. 

“Uncontested divorces are private, focused on the couple’s unique circumstances, and can be settled out of court, making it a more cost-effective and convenient way to divorce,” Shepelsky says.

Divorce mediation

Divorce mediation is a process where divorcing spouses meet with a trained, neutral professional to work through dissolving their marriage and drafting a divorce agreement.

Contested divorce or divorcing with a lawyer

If you’ve made up your mind and there’s no alternative but divorce, talking to at least a few lawyers is always a good idea. The first consultation is sometimes free, so you’ve got nothing to lose. And you can gain a lot of information during divorce attorney interviews if you head into the conversation armed with the right questions.

If you’re based in New South Wales, speaking with a Sydney divorce lawyer can also help you understand local laws and the best strategy for your situation.

These are some reasons to hire a divorce lawyer:

  • You have a very high-conflict divorce with someone who is abusive, addicted, suffers extreme mental health issues.
  • You have a very complicated financial picture that requires an expert to untangle.
  • You and your ex are committed to a low-conflict uncontested divorce, but want an attorney to look over your final divorce settlement.

DIY divorce

You can always sort out the details of your divorce between the two of you. Divorce papers are available or free from your local court house, or you can use an affordable online divorce service.

In any of these scenarios, you can always hire a mediator if you get stuck on an issue or two, as well as pay an attorney for a couple hours of their time to go over the paperwork to ensure everything is legal.

How to prepare for divorce: Who can file for divorce online?

Yes! In most states it is possible to file some or all of your divorce papers online. Nearly everyone who files online has an unmessy, uncontested divorce. Before you sign with an online divorce service, make sure the company has:

  • High Better Business Bureau rating
  • Some kind of money-back guarantee
  • Clear instructions for filing
  • Strong customer service
  • Clarity about what is included in the fee

5 steps for how to get a divorce without a lawyer

If you plan to get a divorce without a lawyer, Molly Rosenblum, founding attorney of The Rosenblum Allen Law Firm in Las Vegas, Nev., recommends following these steps: 

1. Familiarize yourself with the laws in your jurisdiction

This is some basic information you should know before filing on your own: 

  • Whether your state is a community property state, where nearly all assets acquired during the marriage (property, debts, income, etc.) are split 50-50
  • Whether your state considers fault in divorce, which can affect how property is divided and whether alimony is granted
  • How child support is calculated
  • Whether your jurisdiction has a preference for joint physical custody
  • How your state handles dividing pensions/retirement savings

2. Review required documents in your jurisdiction

To find the documents you need to file for divorce, search “YOUR COUNTY/STATE divorce forms,” then click on the link to your county or state’s judicial website (these websites usually end in .us, .gov, .org, or with your state’s abbreviation — i.e. .pa or .ca). 

You can also get divorce documents by visiting your local courthouse in person (search “courthouse COUNTY/STATE” to find the address). 

In most cases, you can download the forms from these sites for free, though you will have to pay the corresponding fees to file them with your local court. If you cannot afford the filing fees, you may be able to have them waived after showing financial eligibility.

3. File and serve paperwork

In most cases, a copy of the divorce petition or complaint must be filed first with the court — in person or online — then served to your spouse. 

Some states require your spouse to be served in person, typically by a third person not related to either individual or involved in the divorce case. This might be a sheriff/officer or process server, a person who delivers legal documents under a specific direction for a fee. 

Other jurisdictions allow service by mail, which means you mail the documents and complete a declaration to the court stating the date you mailed the paperwork.

4. Wait for your spouse to respond

Once your spouse is served, you will need to wait the required period of time in your jurisdiction for them to respond. 

If your spouse agrees to the main terms of the divorce, your divorce will be considered uncontested. If your spouse does not agree to one or more of the main terms of your divorce — for example, how to divide shared property, or a custody arrangement — it will be considered a contested divorce and require court or attorney intervention.

5. If the divorce is uncontested, complete and submit paperwork.

If your divorce is uncontested, you may be able to submit final paperwork to the judge and be divorced quickly, depending on where you live. 

You and your spouse can discuss and decide the terms of your divorce on your own, or you can work with a mediator, a trained, neutral professional (typically a lawyer) who can help you divide assets, set up custody schedules and child support agreements, and more. 

How online divorce services can help with your paperwork

Legit online divorce services can help you complete and prepare your paperwork for filing in the appropriate court in your state.

Typically, either you, or an online divorce service described below, will download and prepare the documents according to your state guidelines.But before that, there must be a discussion — typically several discussions — between you and your ex-husband or ex-wife to discuss and agree upon many points of the end of the unhappy marriage. These agreements are then summarized in a settlement agreement, and filed with the court.

How to prepare for divorce: Understanding the financial side

“Divorce is a difficult season to prepare for, and I have seen so many clients positively change the course of their life and their family’s life when they are financially prepared,” Ward says.

Mota says assets should be divided based on: 

  • What makes the most sense for the future
  • How the asset will play into your lifestyle post-divorce
  • How the assets being divided in conjunction with other benefits such as social security in retirement will benefit you

He adds that taxes should always be considered when dividing assets, as well as the timing of when the assets may be of use to you.

Property and assets division guide

These are some answers to common questions about dividing assets that should be included in a divorce agreement: 

Who gets the house in a divorce?

The marital home is most commonly considered an asset that is divided equally in divorce. Aside from situations where one spouse pays for the house before marriage and keeps it after, specific marital circumstances, including children and finances, usually dictate the fate of the couple’s home. 

Who owns the engagement and wedding rings in a divorce?

Jewelry is marital property if purchased during the marriage. If the jewelry in question was a gift or a form of inheritance, it’s separate property and not divisible. Jewelry acquired before marriage is also separate property. This can include a watch given as an engagement or anniversary gift to a man, or fine jewelry given to the wife as a gift — including an engagement ring and other jewelry.

Who gets everything else in a divorce?

Divorce law varies by state, and every divorce differs. If you wonder who will get what when you and your spouse break up, the answer will depend on many factors, including where you live, how long you were married, and what each of you brought to the marriage in terms of property.

However, no one ever gets “everything” in a divorce. At a minimum, each spouse will get to leave with any assets or possessions that they brought into the marriage, and barring any prenuptial agreement, half of any assets like equity in a home or retirement investments acquired during the marriage.

What is the difference between community property and equitable distribution?

Community property states split any assets or debts acquired during the marriage 50/50, while equitable distribution states divide the assets and debt equitably — but not necessarily equally.

For example, in a community property state like Arizona, any assets in the house would be split 50/50. In an equitable distribution state like Illinois, the equity in a home would be split according to various factors, including:

  • The sum of money each spouse put towards the downpayment, mortgage payments, or renovations.
  • Whether either spouse’s family contributed to the downpayment
  • Etc.

Marital property vs separate property—what is the difference?

Marital property is anything that is owned jointly by both spouses. This can include real estate, cars, savings, checking and investment accounts, jewelry, furniture or businesses. Marital property can also include debt that was acquired during the marriage, including credit cards, mortgages, business and personal loans, and sometimes student debt.

Separate property is typically not subject to division during divorce. This means that any property or debt acquired by each spouse before the marriage, as well any inheritance and gifts acquired by a spouse during the marriage, will most likely remain their own after the divorce is finalized. 

Are assets always split 50-50?

In community property states, theoretically, the answer is yes—assets acquired during the term of the marriage are split 50-50. 

In practice, marital property cannot always be divided exactly 50/50. Typically, spouses and attorneys and sometimes judges work together to divide the property in a way that complies with standard practices in that jurisdiction, as well as — hopefully — is fair and reasonable. Spouses may still also maintain some personal property.

What to ask for in a divorce settlement agreement

  • The house, or proceeds of a sale
  • A co-parenting plan
  • Relationship building
  • Documentation
  • Money

Learn more about things to ask for in a divorce and how to ask for a divorce.

How to get through divorce without going bankrupt

Fact: Divorce is one of the leading predictors of both bankruptcy and home foreclosure.

Women are especially prone to a long-term financial fallout from divorce, according to the Institute for Financial Literacy.

Mota says the easiest way not to go bankrupt during divorce is to minimize the expenses of divorce. 

“I call it the price of peace,” he says. “All too often, couples will argue over something in the divorce and spend more money paying their attorneys or mediators than what the item being disputed is worth.”

Mota offers these tips to avoid going bankrupt during divorce: 

  • Remove the emotions when negotiating a settlement
  • Work with a financial professional to help understand what assets are worth and understanding what you are reasonably entitled to
  • Take time to itemize your income, expenses, and debt

He says before divorcing, you should consider whether you can pay back your debts as a single person. 

“If you cannot, perhaps you work on paying down the debts before you divorce or find a higher paying job that will allow you to afford your lifestyle and debts post-divorce,” Mota says.

Insurance after divorce: How to handle life, health and auto policies

Ward says you need to know what types of financial protection you have in the form of life insurance, disability, and long-term care insurance and what coverages are on your soon-to-be ex-spouse, especially if you are going to be depending on child support or spousal support.

Life insurance after divorce

There are two types of life insurance: term and permanent. Term life insurance has no cash value and simply pays out a tax-free death benefit to a named beneficiary upon the passing of the insured person.

This means that until and unless the insured person passes away, there is no financial value in the policy. As such, term policies will not be considered a financial asset subject to division in divorce.

Read our roundup of top term life insurance policies.

Health insurance after divorce

Health insurance is one reasons unhappy couples stay together — and some platonic friends get married in the first place! That said, if one spouse has enjoyed being on the other’s health insurance, or you have a lower rate of insurance bought on the marketplace as a married couple, then you have to make some adjustments. 

If your ex-husband or ex-wife maintains a health insurance plan through their employer that covers you, it is likely that you will no longer be eligible to stay on their plan.

If you maintain the health insurance plan that covers your spouse, it is likely that they will no longer be eligible to stay on your plan. However, children will be able to stay on your (or your spouse’s) plan until they reach the age of 26.

Car insurance after divorce

Car insurance is an often overlooked component of a divorce and because the consequences can be so costly, it is important to know the risk of not doing it correctly. 

Driving a vehicle without car insurance is illegal, so removing your ex-spouse or their vehicle from your insurance policy is not allowed without their consent, and they cannot remove you from their policy.

How much does divorce really cost?

For many years, the figure $15,000 per spouse has been tossed around as a general rule of thumb for how much it costs to get divorced in the United States. However, as a journalist who has covered divorce for more than a decade, I believe this number is misleading and inflated. Here are some things to consider:

  • The cost of divorce varies greatly by geography — attorneys in coastal cities charge more per hour than other parts of the country, but people in those areas also earn more.
  • Expensive divorces are usually had by people more likely to afford them. Keep in mind that your attorney will have access to all of your financial information — the more money you and your spouse have, the more likely your attorney is incentivized to drag out your divorce.
  • The more money you have, the more you have to fight over — both in terms of assets to divide, and child support and alimony.
  • Overall, the trend of divorce is moving away from high-conflict, lawyered-up battles, to more collaborative, amicable, mediated and uncontested divorce — as it should.

Fewer young people are marrying and more moms are unmarried when they have babies. These families tend to be younger, with less education and lower incomes than families that stay married, so even if they do go through family court and/or use a family law attorney, there is less to fight over and usually a simpler legal process that costs less.

What is the cheapest you can get a divorce?

The cheapest divorce you can get is a $70 filing fee (average throughout the state) in Wyoming — assuming you and your spouse agree to the terms and file yourself without any outside counsel or support. 

The cost of divorce can quickly go up as hourly attorney fees can average $300 or more in costal cities, bringing even an average divorce bill to $20,000 or more per spouse. 

If your divorce is uncontested, you can get an affordable divorce online through a service that fills in your divorce papers based on your answers to a questionnaire, like these. Check out our reviews of the best online divorce services.

However, you do not need to pay for divorce papers because you can find free divorce papers at your local courthouse.

How to prepare for divorce: Time required

The length of time it takes to get your final divorce decree after filing for a divorce depends on your state laws, how backed up your local courts are, and whether you filled out all the paperwork properly.

In most states, it takes at least 30 days from the date you file to finalize your divorce.

Divorce: Moving on after you’ve filed

There is no one-size-fits-all path you’re supposed to take after divorce. The post-divorce period is all about discovering what you want and need from your future. These are some tips for moving on after divorce:

  • Get therapy — or at least try some self-help books and courses
  • Get a physical, and maybe a makeover
  • Co-parent like a Paltrow
  • Make new friends
  • Date, when you’re ready
  • Get your finances together, and make sure your kids are protected

Divorcing a cheater? How to get over your cheating husband

“A breach of trust makes the divorce process more challenging, but, depending on state law, it may not carry weight in determining the legal outcome,” Mota says.

These are some tips for getting over a cheating spouse: 

  • Put your spouse’s cheating into perspective with therapy
  • Make it your goal to forgive the infidelity, heal and thrive
  • Take responsibility for the dissolution of the marriage and forgive yourself
  • Realize that worse things have happened to people (no matter how much this hurts)
  • Invest time, self-care and perhaps therapy to rebuild your self-confidence, and remember that you are a lovable woman
  • Recognize that repeating and focusing on the story of his unfaithful acts ultimately hurts you, and holds you back
  • Focus on rebuilding your own incredible life post-divorce

How to catch a cheat

Change your name

Changing your name officially can take a lot of steps if you want to do so with the state and federal governments. Here’s how:

Name change with Social Security Administration

To change your name on your Social Security Card, download all the documents and follow the steps on this SSA name change page, which include:

Show original or certified documents proving your legal name change and identity. If you are a U.S. citizen, you also must show us a document proving your U.S. citizenship.

To prove your legal name change, you must show one of the following:

  • Marriage document
  • Divorce decree
  • Certificate of naturalization showing a new name
  • Court order for a name change

To prove your identity, you must show an unexpired document showing your name, identifying information, and photograph, such as one of the following:

  • U.S. driver’s license
  • State-issued non-driver’s identification card
  • U.S. passport

If you don’t have one of those documents available, we may be able to accept your:

  • Employer identification card
  • School identification card
  • Health insurance card
  • U.S. military identification card

To prove your U.S. citizenship, you must show one of the following:

  • U.S. birth certificate
  • U.S. Consular Report of Birth Abroad
  • U.S. passport (unexpired)
  • Certificate of Naturalization
  • Certificate of Citizenship

Name change with DMV

Each state has its own process for changing your name officially with its motor vehicle department, and on your driver’s license. Typically, you will need:

  • Application
  • Your most recent driver’s license or learner’s permit
  • Divorce degree, marriage license, or court order reflecting the name change

Name change for passport

To change your name on a U.S. passport, this State Department page has all the information and forms you need, including:

  • Your original passport
  • An original or certified name change document, such as a marriage certificate, divorce decree, or court order
  • Color passport photo

There may be a fee associated with your name change on your passport, depending on your situation.

Name change services

  • LegalZoom
  • UpdateMyName.com

How to prepare for a divorce FAQs

How do you silently prepare for a divorce?

To quietly and even secretly prepare for divorce, you can consult with an attorney about your options, shore up some cash, ensure you have a way to earn a living to support yourself, be mindful of your spending, debt and credit score, and seek emotional support through a therapist, and your social community.

These steps will help you feel strong and ready when you do initiate divorce, and set you up for long-term success.

What is the first thing I should do if I want a divorce?

Meeting with an attorney to understand what your divorce options are is a good first step — but be sure to seek out several consultations to find a lawyer who will truly look out for your best interest: In most cases a very low-conflict, amicable divorce in which assets are split fairly and custody is shared equally.

How to emotionally prepare for divorce?

Focus on what a positive, independent post-divorce life will look like: Earning and spending your own money, financial and social independence, a lower-stress home life, freedom, and a new romantic life.

How do I protect myself when preparing for divorce?

  • Get access to all financial accounts, and keep statements
  • Make sure your name is on any shared property, vehicles and businesses
  • Invest in your own career, and make sure you will be able to financially support yourself long-term
  • Invest in friendships, community and social support for yourself and your kids

What is a good divorce preparation checklist?

Here are the basics of what you will need to file for divorce:

  • Your marriage certificate or domestic partnership certificate
  • Pre- or post-nuptial agreements
  • Any divorce-related documents, such as a restraining order, child custody order, visitation order, or separation agreement
  • Drivers licenses, passports, or other official IDs
  • Social Security Numbers and most recent statement (you and your spouse)
  • Date of birth/ birth certificate
  • Estate planning documents, such as wills, living wills, powers of attorney, durable powers of attorney, advance health care directives, trust, etc

2. Child information

If you and your spouse share children, you’ll need to collect the following:

  • Birth certificates
  • Social Security Numbers
  • Dates of Birth
  • Medical records (including for eye doctor and dentist)
  • Allergy information
  • List of prescriptions and any special care instructions 
  • School records (including their current class schedule and extracurricular schedule)
  • Current childcare arrangements (daycare, preschool, etc)
  • Current custody arrangements and child support arrangements (if applicable)
  • Child-specific expenses, such as tuition, medical bills, and the cost of extra-curricular activities

Co-parenting with a narcissist

3. Pet information

If you have pets, make sure you have a copy of:

  • The bill of sale
  • Adoption records
  • Registration
  • Medical/veterinary records
  • List of medication and/or care instructions

4. Financial Information

Collect the account numbers and current balances of each of the accounts below for the past year. Ensure that you have the correct login information for joint accounts.

  • Savings and checking accounts.
  • List of the contents in any safety deposit boxes
  • Inheritance details (what was inherited, from who, when)
  • Credit cards
  • Health Savings Accounts (HSA)/Flexible Spending Accounts (FSA)
  • Retirement accounts (401ks, IRAs, 403bs, pension,etc.) and other investments, such as brokerage accounts, bonds, etc.
  • Life/disability insurance policies
  • A copy of your and your spouse’s credit report

5. Income history

Ideally, you should have copies of each of the documents listed below, going back at least three years. This helps with calculations for child support, alimony and property division.

  • Federal income tax returns
  • State income tax returns
  • Your and your spouse’s W-2s or 1099s
  • Paystubs for you and your spouse (past six months is fine)
  • A list of any employer-provided benefits such as employer-provided health insurance, life insurance, disability insurance, stock-options, etc. 

Best career-level jobs for moms

6. Payment history

Make a list of all of the monthly bills paid by you or your spouse and copy a year’s worth of statements. Be sure to write down the account numbers and current balance.

  • Mortgage / home equity line of credit
  • Any non-mortgage debt (car loans, student loans, personal loans)
  • Utilities (electric, water, phone, cable, etc)

7. Marital home information

Your marital house is likely the most valuable asset and its value will be a big part of how you divide assets in your divorce.

  • Take photos of each room in your home, being sure to detail any damage, current conditions, etc.
  • Obtain an appraisal of the home
  • Copy of the deed
  • Final escrow statement from close of escrow/settlement statement
  • Renters or homeowners insurance policy
  • Leasing agreements
  • Real estate/property tax bill for the past year


Colorado readers may benefit from local guidance that keeps your home and kids’ routines front and center while minimizing conflict. Experienced Colorado family and divorce lawyers can help you evaluate options for the marital home and create a custody and property plan that protects stability, privacy, and long-term family well-being.

8. Vehicles

You will need a copy of the title, registration, and loan statements (if necessary) for any vehicles owned by you and your spouse, including:

  • Automobiles
  • Boats
  • Trailers
  • Motor Homes
  • Machinery such as tractors, excavators, bulldozers, and the like

Find low-cost car insurance

9. Personal property

If you have any valuable property not already discussed, be sure to document them in a list alongside the purchase price, estimated resale value, ownership records, appraisal value, receipts of purchase (if possible). It can also be beneficial to photograph the items. This should include:

  • Vacation/second home
  • Rental properties
  • Vacant land
  • Furniture
  • Electronics
  • Appliances
  • Jewelry, gems, and precious metals
  • Art
  • Antiques
  • Collectibles and coin collections
  • Firearms

Beware of these 18 sneaky divorce tactics so you can overcome them

Bottom line: Preparing for divorce does not have to be overwhelming

Here are five steps for a quick divorce:

  1. Agree to settle out of court, without lawyers
  2. File your own divorce papers 
  3. Share custody equally
  4. Go to divorce / co-parenting counseling
  5. Do not fight over child support

Although you may never be fully prepared for divorce, being as ready as possible allows you to go into the process more confident and less worried about the outcome. Take care of yourself as best as you can, McCrary says.

“The legal process is the easy process,” he explains. “The hard part is the emotional and mental drain that it can take on person. You need to be proactive in taking care of yourself so that you can be a better person each day.” 

Putting yourself and your financial health first will help you get through the divorce process.

If you’re wondering how to buy a house as a single mom, especially on a low income, know that it is possible with the right resources.

Sarah Coleman-Lee, a single mom and one half of a mother-daughter realtor team based in Charleston, says she regularly helps single women achieve their dreams of homeownership. 

“You are more than capable of buying a home,” Coleman-Lee says. “It may take a little longer, but it’s 100% achievable.” 

This post will help you get in position to buy a home on any income. We’ll cover: 

Buying a house with government help vs. the traditional way

Steps for how to buy a house as a single mom

  1. Improve your credit score
  2. Figure out how much house you can afford
  3. Look at ratio of debt to income for mortgage
  4. Save your down payment (if required)
  5. Research your mortgage options
  6. Determine if it’s the right time to buy

Ready to buy a house? Here’s what you can expect

  1.  Prepare for homeownership
  2. Find a real estate agent (if you choose to use one)
  3. Search for a property
  4. Make an offer 
  5. Close and move into your new home

Buying a house with government help vs. the traditional way: 3 differences

If you have a low income or receive government benefits, you may be eligible to purchase your home with help from a government-backed loan or through a special home-buying program like these:

Peter Bieda, a real estate agent and mortgage broker based in Chicago, is the COO of FHA Lend, a mortgage lending company licensed in 48 states. He says there are several differences between buying a home through a government program vs. using a conventional mortgage: 

Government-backed loanConventional loan
Lower down payment: If you are working with a government-backed loan such as a Fannie Mae HomeReady or Freddie Mac Home Possible mortgage, you can pay a down payment as low as 3% of the home’s purchase price. Down payment: With a conventional loan, lenders set their own down payment requirements — you might have to put down 15% or more. 
Government insured: When the government backs a loan, lenders are protected if the buyer stops paying the mortgage. This often translates into lower interest rates and better odds of approval for low-income home buyers.Not government insured: When a loan isn’t government insured, it’s riskier for the lender, so they may demand higher interest rates or deny loans to borrowers with financial challenges or low credit scores.
Accept credit scores in the 500s: For an FHA loan, you’ll need a credit score of at least 500 to qualify (580 for a 3% down payment), while VA and USDA loans have no minimum score requirement. Minimum credit score requirement: Most conventional home loans require a minimum FICO score of 620.
Some income limits: Some homebuyer programs have a maximum income limit. For example, you can only qualify for a HomeReady Mortgage if your income doesn’t exceed 80% of the Area Median Income for the property’s location. However FHA loans do not have a minimum or maximum income requirement.Debt-to-income ratio limits: Most conventional loan lenders care less about your income level and more about your debt-to-income ratio, which should be 50% or less to qualify for a conventional loan.
Program purchase limits: For example, the FHA loan limit is $472,030 in most parts of the country.Individual purchase limits: You are only limited by the amount of money a lender approves you for based on your income/credit score. 
Mortgage insurance: Mortgage insurance is typically required on FHA and USDA loans because you’re putting less money down on the home. Mortgage insurance: You’ll likely only need to pay for mortgage insurance If you make a down payment less than 20% of the purchase price of the home. 

Keep in mind that all lenders don’t work directly with government home-buying programs, so you’ll have to do some research to find one that does. Most state housing websites have a directory of approved lenders.

Check out our post on low-income home loans for single mothers.

How to buy a house as a single mom: 6 steps

These are the steps for how to buy a house as a single mom:

  1. Improve your credit score
  2. Figure out how much you can afford for a house
  3. Look at ratio of debt to income for mortgage
  4. Work to earn more and save your down payment (if required)
  5. Consider your mortgage options
  6. Determine if it’s the right time to buy

1. Improve your credit score

Do you know your credit score? Lenders use that three-digit number to measure your level of risk as a borrower. Scores range from 300 to 850, and most conventional home loans require a credit score of at least 620. The higher your credit score, the lower your interest rate.

Here are some tips to help improve your credit score: 

  • Request a credit report to see where you stand. You can get a free report from the Federal Trade Commission (FTC)-approved site AnnualCreditReport.com every 12 months.
  • Request the removal of wrong or negative information from your credit report. The FTC offers guidance on how to address errors. For negative information, you can contact the creditor directly and negotiate a pay-for-delete agreement, which means you agree to pay off the collections account in exchange for a removal of the negative mark. If the account is old, you can also request a goodwill deletion or adjustment. Otherwise, you can wait for the negative mark to be removed from your report, which typically happens after seven years.
  • If you need a quick credit score increase, check out Experian Boost. It’s a free service that factors in on-time, positive payment history from accounts like your cell phone bill or streaming service. Experian reports those who qualified for a boost improved their FICO score by an average of 13 points. 
  • Pay your existing accounts down. This can positively impact your credit use rate.
  • Ask for a credit line increase. Contact your credit card companies, or make an online request. This can immediately improve your score.
  • Pay your accounts on time. If you have trouble remembering when to pay, you can often sign up for automatic payments.
  • Keep accounts that are in good standing. Do not cancel them after you have paid them off.

2. Figure out how much house you can afford

There are a lot of costs involved in homeownership:

  • Mortgage: For a $200,000 30-year mortgage with a 7% interest rate, you can expect to pay about $1,300 a month.
  • Mortgage insurance: Mortgage insurance lowers a lender’s risk of approving a loan and is usually necessary when you make a down payment less than 20% of the home’s purchase price. If you put 3% down on that same $200,000 at 7% interest, you’ll pay about $100/month in mortgage insurance until you reach 20-22% equity in your home (at which point the policy will be canceled).
  • Property taxes: According to investing advice company the Motley Fool, the median real estate tax paid in the United States was $2,971 in 2021 (the most recent data available).
  • Home insurance: Bankrate found that the average cost of homeowners insurance in the U.S. is $1,428 per year for a policy with $250,000 in dwelling coverage.
  • Utilities: Energystar.gov reports the average annual energy bill for a single-family home is $2,060. Check out our post on how to get free money to pay bills. 

    You can also consider energy-efficient modern heating solutions to reduce your utility bills. UK Radiators offers a wide range of stylish electric designer radiators that can help you cut long-term heating costs while keeping your space comfortable.
  • HOA fees: If you live in a development with homeowners association fees, expect to pay between $100 and $1,000 per month to cover things like lawn maintenance, pool maintenance, snow removal, and trash removal.
  • Home maintenance and repairs: According to internet services company Angi, the average American spends $3,018 a year on home maintenance and repairs.

Freddie Mac offers a calculator to help you determine how much mortgage you can afford.

If you are in the process of buying a home, you’ll need a mortgage pre-approval, which will show a specific, maximum amount you’re approved to finance. That letter is only good for 90 days, so wait until you are ready to buy to obtain pre-approval.

3. Look at ratio of debt to income for mortgage

Certified Financial Planner R.J. Weiss of Geneva, Ill., suggests a 50/30/20 budget to assess whether you can afford to buy a home.

The 50/30/20 budget involves allocating your net take-home income like this: 

  • 50% toward necessities (food, shelter, transportation, clothing)
  • 30% toward wants
  • 20% toward debt payments and savings

Weiss says to rethink buying a home if adding a mortgage tips your necessities category over 70% of your monthly income.

Another common budgeting tactic is to ensure your housing costs are no more than one-third of your income. To calculate the percentage of your housing costs, divide the monthly cost of homeownership by your total monthly income. 

The New York Times offers a calculator to help you determine whether you should rent or buy a home.

4. Save your down payment (if required)

Depending on the type of mortgage you plan to get, you’ll need to save at least 3% of your home’s purchase price for a down payment. If you’re taking out a conventional loan, you may need to save 15% or more. 

Some loans — like VA loans, which are for veterans, members of the armed forces, and their spouses — allow you to put $0 down. However, that’s not advisable for several reasons: 

  • You’ll pay more money in interest over the life of your loan
  • You won’t be able to afford as much home as you would if you put money down
  • You’ll start out with zero equity in your home (which means it will take you more time to build substantial equity in your home)
  • You’ll have to pay for private mortgage insurance (PMI) until you reach 20-22% equity in your home. Expect to pay 0.1% – 2% of your loan amount per year (the less you put down, the more you’ll pay).  

Here are some ways to save money for a down payment:

Open a high-interest savings or checking account

Many banks pay 5% or more on savings accounts these days.

Increase your income

Earning more money is the best way to save your down payment.

This post offers strategies for negotiating a higher salary, while this one has high-paying jobs you can do without a degree.

Apply for down payment assistance

States often offer grants and forgivable loans for down payment assistance to low-income home buyers. Research HUD home buying programs in your state and check with your state housing finance authority (HFA).

For example: 

  • In Alabama, single mothers can get 4% of the sale price — up to $10,000 — for down payment assistance through the “Step Up” program. 
  • Idaho homebuyers can get up to 10% of the sale price of a home they want to buy to pay their down payment or closing costs
  • Florida Housing offers $10,000 in down payment and closing costs in the form of a deferred second mortgage loan on FHA, VA, USDA and conventional loans

These down payment assistance programs are available to homebuyers nationwide: 

  • The Chenoa Fund (excludes New York state): The Chenoa Fund is a national program that offers second mortgage loans to prospective homeowners who need help to fund a down payment and/or closing costs. Borrowers must be seeking an FHA-insured loan for their first mortgage, have a FICO Score of at least 600, and choose from one of these assistance options:
    • Repayable: 10-year term with a fixed interest rate 2% higher than the first mortgage interest rate
    • Forgivable: 30-year term with a 0% interest rate and no monthly payments. This loan is forgiven at the borrower’s request when forgiveness conditions are met, which are determined by the down payment assistance amount:
      • 3.5%: Forgivable after 36 consecutive, on-time payments on the first mortgage
      • 5%: Forgivable after the initial 120 payments on the first mortgage.
  • Fannie Mae Community Seconds: If you plan to purchase a home with a Fannie Mae-backed mortgage, you may also be eligible for a Community Seconds loan, a  second mortgage on your home to cover your down payment, closing costs, and/or minor home renovations. These loans are:
    • Offered by your primary lender but may be funded by local/state housing agencies, nonprofit organizations, and even local employers
    • In some cases, deferrable until the first mortgage is repaid or may be completely forgivable — the lender sets the terms, which must comply with these guidelines set by Fannie Mae
    • If the lender allows, they may be deferred until the first mortgage is repaid or forgiven without repayment. 
    • Freddie Mac has a nearly identical Affordable Seconds program. 

Home buyer grants

Some organizations and charities offer grants to help low-income families buy a home. Check out our post on 12 first-time home buyer grants for single moms.

5. Research your mortgage options

If you’re self-employed or run your own business, navigating the mortgage process can feel more challenging. Many lenders require extensive income documentation that doesn’t always reflect your actual earning power. Some specialized home loan lenders, such as Griffin Funding, cater to self-employed buyers by offering flexible qualification standards and tailored mortgage options based on unique financial profiles.

You can also inquire about low-income home loans at your current bank or join a credit union. Both may have programs or discounts for home financing or work with outside organizations to help you buy a home.

6. Determine if it’s the right time to buy

Even if you have job security, money saved for a down payment, and a high credit score, be strategic about when to purchase a home to save money in the long term. 

While home prices remain high, U.S. News and World Report predicts a 5.3% decrease in existing home sale prices in 2023, as long as mortgage rates remain relatively high. 

As of March 2023, mortgage rates are over 7% for a 30-year fixed-rate mortgage. 

Rocket Mortgage reports that home prices are typically lowest in the winter, though you will likely have less homes to choose from. 

Interest rates and home prices regularly fluctuate throughout the year, influenced by everything from local to global factors.  

Ready to buy a house? Here’s what you can expect:

According to the National Association of REALTORS®, there are six main steps involved in buying a house:

1. Prepare for homeownership

Build your credit history, get pre-approved for a mortgage, figure out how much mortgage you qualify for, and save for a down payment and closing costs.

2. Find a real estate agent (if you choose to use one)

Your agent will be paid a portion of the seller’s commission fee from the final sale price of the home.

Northern Virginia Realtor, Darren Robertson, advises to look for an agent who has a deep understanding of the market and a proven track record.

Working with someone who understands the local market can make the process easier, particularly when you’re comparing neighborhoods and evaluating properties. A realtor in Arlington Heights can help buyers navigate local listings and negotiations.

3. Search for a property

If you work with an agent, they’ll schedule times for you to tour local houses for sale until you find one you’d like to buy. Once you find a potential match, it is highly recommended to find property records to check the home’s history, previous sale prices, and property taxes before making an offer.

4. Make an offer 

Once you’re pre-qualified for a mortgage from your lender, you can make an offer on a home. If you’re working with a real estate agent, they’ll handle back-and-forth negotiations with the seller’s agent.

5. Close and move into your new home

The average closing period is 30-45 days, during which time you’ll have to pay for a home inspection ($300 to $500), provide financial proof of mortgage eligibility, schedule utilities at your new property, and plan a move-in date. 

During closing, you’ll sign paperwork to transfer homeownership into your name and pay closing costs, which are typically 3% to 6% of the loan amount. 

Unless the seller specifically requests to continue occupying the home for a period after closing, you can typically move into your new home right away — the ultimate reward after all of the hard work it took to get here.

Check out these other resources for single moms:

Help for single moms: 16+ resources$500 monthly single mom grant
Government assistance for single momsScholarships for single moms
Free money for billsFree home repairs
Free car repairsFree food
10+ charities that help single mothersFree daycare

If you need money quickly, a jewelry loan may be a good option — as long as you have fine jewelry worth more than you want to borrow.

Can you get a loan for jewelry?

Yes. If you have fine jewelry you do not wear that is worth more than $500 — like an engagement ring, or diamond earrings — you can use that jewelry as collateral to secure a personal loan through companies that specialize in jewelry loans. Most do not require a credit check but use your jewelry or other luxury item as collateral.

How a jewelry loan works

This is how Diamond Banc’s process works to obtain a jewelry loan online: 

  1. Fill out an online submission form with a description of your jewelry and desired loan amount to get an initial quote.
  2. Diamond Banc provides a free and fully insured shipping label to send in your jewelry for final evaluation. 
  3. If you accept the loan offer, you’ll be issued payment immediately via check or wire transfer. If you don’t, your jewelry will be immediately returned.
  4. Once your loan has been fully repaid, your jewelry will be securely returned to you. 

Most jewelry loans are issued for 50-75% of your jewelry’s estimated liquid wholesale value. For example, if you purchased a diamond from a competitively priced retail store for $6,000. The wholesale value would likely be about $4,500. Diamond Banc would then loan you 75% of that value, or $3,375.

Jewelry loans tend to have low interest rates — typically between 3% and 8% — and are meant to be repaid in a shorter amount of time than a traditional loan.

Diamond Banc’s loan period starts at 30 days, which can be extended indefinitely as needed. The longer you take to repay your loan, the more you’ll pay in interest.

Alternatively, you can use pawnshops to get cash for your loan, though the interest rates tend to be much higher at pawn brokers at 10% to 20%.

You might consider a jewelry loan if you:

  • Want to secure a loan with a low interest rate
  • Need money in a short amount of time
  • Have a low credit score and can’t qualify for a traditional loan
  • Want a loan with flexible repayment options

Keep reading to learn more about jewelry loans and how they work: 

How to get a loan on jewelry

If you are considering a jewelry loan, here’s how to make sure you get the best deal: 

1. Get an idea of what your jewelry is worth

If you want to find out how much your jewelry is worth and how much you could potentially borrow, you should start by getting a jewelry appraisal, which is a statement of value that spells out the worth of your item. 

When you apply for a jewelry loan, the company funding the loan will issue their own appraisal, but having one ahead of time can help you determine if you’re getting a fair offer. 

During an appraisal, an appraiser will inspect your jewelry to determine its dollar value.

Jewelers Mutual insurance company says you can expect to pay a flat or hourly rate of $50-$150 for an independent jewelry appraisal, depending on the complexity of your jewelry. However, a jewelry loan provider like Diamond Banc will not charge a fee to appraise items you send in.

Local jewelers, pawn shops, and gold or diamond exchanges are all good options to get appraisals.

If you have diamond jewelry, you can also get a diamond appraisal from an independent association like the Gemological Institute of America (GIA), which will detail key characteristics of your diamond, like its: 

  • Color: The whiter the diamond, the more valuable it’s likely to be
  • Clarity: Clearer stones with fewer inclusions (defects) are usually worth more
  • Carat: Measures the physical weight of diamonds (the higher the better)
  • Cut: Certain diamond cuts are more popular than others, which affects their value

Note that there is a difference between a certified jewelry appraisal and jewelry grading, the latter of which does not include your jewelry’s estimated resale price.

If you don’t have time to get a professional appraisal, you can see what similar items have recently sold for on ebay and other resale sites. Check out our post on symbols stamped on jewelry to determine the type and quality of any precious metal jewelry you have. 

2. See who offers loans on jewelry online

If you search online for “jewelry collateral loans,” you’ll get a list of local and online companies that offer jewelry loans.

These are a couple of the bigger companies that offer jewelry collateral loans online: 

Diamond Banc

  • A+ BBB rating (accredited since 2014)
  • Secure mail-in process 
  • Also has locations for drop off in Tampa, Boca Raton, Miami, Aventura, Orlando, Nashville, Atlanta, Charlotte, Kansas City, Columbia, and Rochester
  • Borrow between $500 and $500,000
  • Rates as low as 2.5%
  • Receive funds in as little as 24 hours
  • Accepts diamonds, fine jewelry, luxury watches, gold and precious metals
  • Loans 65%-75% of the estimated liquid wholesale value of your jewelry
  • Assets are fully insured and stored in alarm-protected, 24-hour security monitored, fireproof vaults
  • Offers 30-day loans that can be extended for as many 30-day periods as needed

Check out our Diamond Banc review.

Borro

  • A+ BBB (accredited since 2017)
  • Secure mail-in process
  • Borrow between $2,500 and $5,000,000
  • Average rates of 3% to 8%
  • Receive funds in 1 to 2 business days
  • Accepts fine jewelry and diamonds, luxury watches, gold and silver, designer handbags and accessories, luxury and classic cars, fine art, luxury auction-quality assets
  • Loans 50-70% of current fair market value prices
  • Assets are fully insured and stored in high-security vaults with video surveillance

3. Do searches for “jewelry loans near me” and “jewelry collateral loans near me” to find local options

If you search for “jewelry loans near me” or “jewelry collateral loans near me,” you’ll get  a list of local jewelers, pawn shops, and loan companies that offer jewelry loans.

4. Get answers to your questions before you take out a jewelry loan

When you’re choosing a jewelry loan company, these are some questions you should ask:

What are the loan terms?

Most jewelry loans are meant to be paid back in a short amount of time over a period of days, weeks, or months. Some require payment over time, while others can be paid off all at once. In general, the longer your loan period, the more interest you’ll pay. 

In most cases, you’ll receive your jewelry back when the loan principal and interest are paid off.

Is a credit check required for the jewelry loan?

Most jewelry loans do not require credit checks, which means there is no negative impact on your credit score if you cannot repay the loan. However, you will have to surrender the item you pledged as collateral.

When do you get your money?

You can usually receive your money within a few days of sending in your jewelry as collateral. 

How will your jewelry be stored?

Reputable jewelry loan companies store your jewelry in a highly secure storage facility under 24-hour surveillance. 

Is your jewelry insured?

Reputable lenders will insure your jewelry while in transit and in possession. 

If you use an online secured jewelry lender, who pays for shipping and insurance?

Typically, the lender pays for shipping costs and insurance, though every company has its own way of handling business. 

5. Decide whether a jewelry loan is right for you or should you sell your jewelry

If you need money quickly, getting a jewelry loan is a good option if you want to hold onto the jewelry you’re using as collateral. 

However, if the jewelry is something you no longer wear or want to keep, you can sell jewelry for cash instead. The best part? You won’t have to pay it back (or pay interest on it). 

These are some places you can sell fine jewelry: 

Jewelry loan FAQs

Have more questions about jewelry loans? Keep reading: 

Why would you get a jewelry loan?

Tracy Cauley, a chartered financial analyst (CFA) from Dallas, says there are a couple benefits of getting a jewelry loan over a traditional loan: 

  • Faster and easier application process, with less paperwork
  • No credit checks or financial disclosures

Who offers loans on jewelry and what kind of jewelry do they accept?

Some local jewelry stores and pawn shops offer loans on jewelry, as well as online lenders like Diamond Banc (which also has physical locations). Most accept these jewelry items as collateral:

  • Fine jewelry
  • Diamond jewelry
  • Gold and silver jewelry
  • Luxury watches

Bottom line: Do your research before you take out a loan on jewelry

Cauley says these are a few red flags you should look out for when you’re shopping for a jewelry collateral loan: 

  • Additional or hidden fees (like appraisal and storage fees) 
  • High interest rates, which could signify predatory lending practices

If you’re considering selling your jewelry instead of taking out a loan, we recommend Diamonds USA, sister site of CashforGoldUSA, because: 

  • A+ Better Business Bureau rating 
  • Gem Institute of America appraisals 
  • 100% guarantee highest price
  • Offers free insured door-to-door FedEx shipping
  • Pays within 24 hours
  • 10% bonus when you send in your diamond or jewelry within 7 days
  • Accepts all diamonds, as well as gold, silver, and platinum items

Get a free estimate today from Diamonds USA >>

Related posts:

Can you get a loan for jewelry?

Yes. If you have fine jewelry you do not wear that is worth more than $500, like an engagement ring from a previous marriage, you can use that jewelry as collateral to secure a personal loan through companies that specialize in jewelry loans.

Why would you get a jewelry loan?

Tracy Cauley, a chartered financial analyst (CFA) from Dallas, says there are a couple benefits of getting a jewelry loan over a traditional loan: faster and easier application process, with less paperwork and no credit checks.