A holiday living room refresh works best when it follows a clear sequence: settle the room’s function first, reset the layout, upgrade the seating, set a restrained palette, build one focused display, solve the clutter with lighting and storage, and cap the budget before a single purchase is made.
Applied in order, these seven steps cost less than a full seasonal cart, reuse more of what you already own, and leave the room in genuinely better shape in January than it was before the holidays began.
A living room physically cannot do everything well at once. Choosing one primary function before moving any furniture gives every downstream purchase a specific job to justify itself against.
Different holiday functions carry distinct layout and storage needs. A morning gift zone requires clear floor space near the tree alongside a lidded basket to stash wrapping debris quickly.
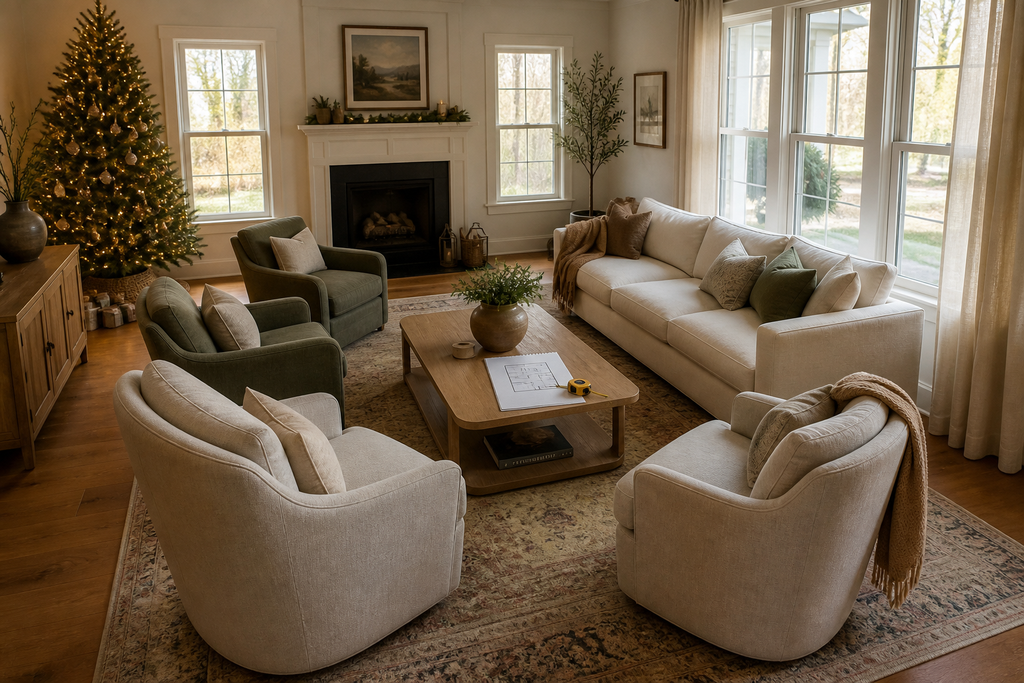
For a movie marathon with six people, the space demands angled seating that keeps everyone facing the screen. Meanwhile, evening guests require a host station centered around a conversation circle with clear traffic lanes from the door.
Pick one distinct role. Every rearrangement and purchase earns its place only if it serves that chosen function.
2. Reset the layout before decorating
The holiday layout problem in small rooms comes down to geometry. A tree, arriving gifts, and additional bodies create traffic jams that push everyone to the edges of the room.
When sofas line the walls, the space reads like a waiting room with long sight lines and no natural focal point. Pulling the furniture inward fixes all three problems at once.
Three concrete layout principles solve most small-space movement problems.
First, keep a clear path from the room’s entry point to the primary seating zone. A pathway clearance of 36 inches must be maintained at the face of the access door. You must also maintain a 36-inch clearance behind a chair for proper access.
Next, identify one corner or wall segment to designate as the seasonal display zone before moving heavy furniture. This is where you establish a focal anchor by laying out Christmas decor from Michelle’s aDOORable Creations like premium wired-edge ribbon or dimensional signs.
Everything else arranges around that visual anchor point rather than fighting against it.
3. Make a daily-value seating upgrade
A folding chair or a floor cushion bought purely for December solves nothing past early January. The seating upgrade that actually earns its place functions just as well on a random Tuesday in March. It needs to meet four specific criteria before qualifying as a smart purchase.
The seat needs to be deep enough for a two-hour movie rather than just a short visit. The layout should also rearrange around a tree or a conversation circle without requiring tools or a second person to lift it.
Removable, machine-washable covers are a baseline requirement after inevitable hot cocoa spills. The unit must also feature under-seat space where extra blankets and gift-wrapping supplies disappear without creating a floor pile.
These criteria point directly toward modular seating rather than a static sofa or a temporary seasonal add-on. Home Reserve’s high-quality deep sectional sofa offers sink-in depth sized for a full movie marathon alongside machine-washable covers that remove without tools.
Hidden under-seat storage comes standard across every individual unit to hold seasonal overflow. The modular components easily reconfigure from an L-shape to a straight layout as the room demands.
Pro Tip: Modular seating with machine-washable covers, hidden under-seat storage, and reconfigurable components makes a holiday seating fix last as a year-round investment.
4. Build a restrained holiday palette
A new set of matching seasonal items often arrives in whatever color story is trending that year. Layering these on top of existing furniture produces visual chaos instead of the cohesion pictured on the box.
A restrained palette built from what you already own sidesteps the trap entirely. It makes every new piece work harder by providing a clear visual context.
The three-touch palette method requires no new purchases to set up. Your dominant neutral is already in the room through a cream throw, a warm-toned rug, or a natural wood coffee table.
The warm accent also exists in items like a brass candleholder or a dark wood tray. The seasonal pop is where new items earn their single slot, using one specific texture or material that brings the holiday inward.
Deep red ribbon, frosted greenery, or metallic gold ornaments each work well on their own. Combining all three simultaneously creates visual competition.
You can also carry the same color palette into your bedroom for a cohesive look throughout your home. A plain or textured bedspread from Terry’s in a complementary shade can tie the rooms together without going overboard on holiday decor.
5. Add one focused seasonal display
One well-executed display has more impact than small items scattered across every flat surface. A focused vignette gives the eye a destination and makes the surrounding space feel intentional.
The mantel and entryway console offer the highest visual return. The mantel sets the tone from the seating area, while the entryway console creates an impression before guests reach the main room. Choose one location rather than dividing your attention between both.
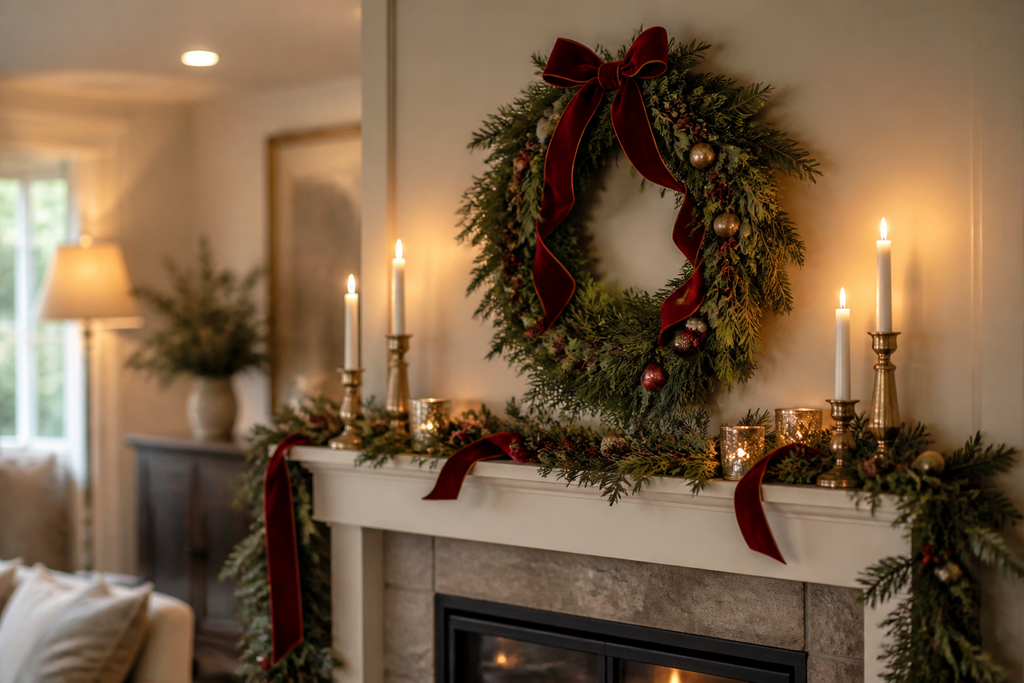
Build the vignette around four elements: a wreath or dimensional sign as the focal anchor, ribbon for movement and texture, pinecones or seasonal botanicals for depth, and a taper candle for warmth after dark.
Premium wired-edge canvas or velvet ribbon holds its shape, while poly deco mesh adds fullness around seasonal signs. Position the sign or wreath at eye level, then layer ribbon in a loose cascade and tuck ornament clusters at different heights for depth.
Key Insight: One display, in one location, executed with care, reads more powerfully than scattered decor spread across every flat surface in the room.
6. Let lighting and smart storage declutter
December clutter arrives in predictable categories regardless of early planning. Extra throw blankets multiply on every surface, while holiday books and board games lack a permanent home. Cord tangles from new light strands mix with gift bags waiting for contents.
Three lighting adjustments shift a room from bright to seasonally warm in under an hour. Replace one overhead light source with a floor lamp to create pools of warm light that draw attention toward styled areas.
Group three or more candles on a single tray to unify scattered small objects into a deliberate arrangement. Adding a plug-in timer to string lights removes one daily operational task.
Audit the flat surfaces accumulating clutter to identify what those items actually are. Storage spaces should be located between 18 and 48 inches from the floor for easy access.
The hidden under-seat storage built into modular furniture provides a logical home within this optimal height range. Board games stack neatly and extra throws fold flat, allowing the room to reset in under five minutes.
7. Cap the spending and plan the January reset
Set a total budget before the holidays begin, separating long-term investments from seasonal accents.
This gives every purchase a defined lifespan and helps prevent a cart full of items that will be donated by mid-January. Long-term investments include daily-use pieces, such as a warranted storage ottoman.
Reusable seasonal accents, like wired-edge ribbon and quality wreath forms, should store flat and return next year in good condition. Fresh greenery, pillar candles, and paper gift wrap belong in a separate annual budget because they need replacing.
Keep the January reset simple: reconfigure modular seating once the tree corner is clear, pack ribbon and mesh into a labeled stackable bin, and return the mantle to its neutral anchor pieces. Replace one holiday item with a fresh green plant to carry the space into the next season.
The path forward
A structured holiday room relies on clear traffic paths, defined storage, and controlled lighting. Flexible seating with washable covers and built-in hidden storage functions identically on a February afternoon as it does during a family gathering.
Quality seasonal materials, including wired-edge ribbon and dimensional focal pieces, pack flat into labeled bins to return next season.
These deliberate choices break the annual buy-and-discard cycle of holiday decorating. Reconfiguring the layout around a clear focal point ensures the space remains functional once the temporary displays come down.
Most morning and night routine advice assumes you have 90 uninterrupted minutes, a journaling habit, and motivation that peaks before sunrise. Most people have none of those things on an average day.
A routine needs to be easy enough to repeat without thinking, which is a design problem rather than a willpower problem.
The five lazy routines below rely on environmental design rather than discipline. Adjusting passive elements around you reduces the cognitive load of both waking up and falling asleep.
Start with the simplest upgrade possible: what sits in your mug.
The laziest morning ritual happens the night before. Load the coffee maker, pick the flavor, and set the timer so your future self wins before the alarm goes off. There is nothing to decide or prep once you wake up.
When coffee actually tastes good, getting out of bed carries a small physical pull. Research on anticipatory reward suggests the expectation of a pleasurable experience can reduce the friction of waking. Flavor creates an incentive where caffeine alone falls short.
Key Insight: The anticipation of a flavorful morning coffee can trigger a reward response that eases waking, even before the caffeine takes effect. Setting up your coffee the night before turns it into a compelling reason to get out of bed.
2. Do one thing the night before
Stress often carries into the evening, making it harder to fully switch off before bed and that disrupted rest can make mornings feel even more demanding.
According to data from the Sleep Foundation, approximately 40% of adults claim to have high day-to-day stress levels, and 90% of that group say their stress leads to sleep problems.
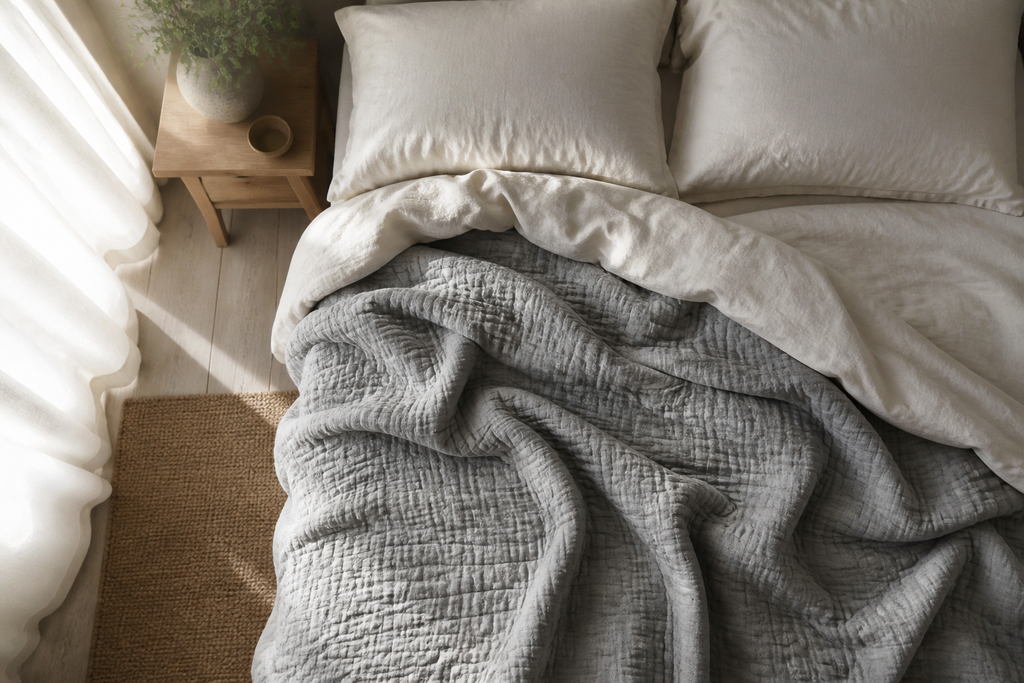
A helpful night-before habit is to choose one small action that supports more restful sleep. For example, Baloo Living’s breathable cooling weighted blanket can add gentle, even pressure as part of a more calming bedtime routine.
Pairing a comfortable sleep environment with a simple task, such as setting out clothes, preparing breakfast, or writing down tomorrow’s top priority, can reduce the number of decisions waiting for you in the morning.
Lowering that morning cognitive load can help ease the residual anxiety that often carries over from the night before.
Key Insights: People who describe themselves as “not morning people” are often just meeting a morning that has too many unresolved decisions and that is a fixable structural problem.
3. Make your wind-down desirable
Most evening advice asks tired people to journal, meditate, or track metrics across four devices. A lazy wind-down removes stimulus instead of layering in new activities. Dimming the lights and putting the phone physically across the room requires zero active energy.
Adding one consistent sensory cue signals the body that the day is over. A specific playlist, dropping the room thermostat to 67 degrees, or a quick spray of a linen mist acts as a reliable trigger for settling down.
The nervous system learns this pattern and begins relaxing automatically upon receiving the signal.
4. Upgrade what you sleep under
People spend significant money on mattresses and sleep-tracking apps while treating the blanket itself as an afterthought. What you sleep under directly dictates how quickly your body settles into rest. Upgrading your bedding requires zero active behavior at night.
The underlying mechanism relies on deep pressure stimulation, where even weight applied across the body activates the parasympathetic nervous system. This pressure lowers the heart rate and mimics the sensation of being held so the mind calms down automatically.
Since deep sleep makes up between 10% and 20% of total sleeping time for most adults, maximizing that restorative window dictates how you feel the next day.
The two most common hesitations about heavy blankets involve trapped heat and feeling pinned down. Breathable designs built with 100% natural cotton and quilted air channels solve the temperature problem. Using lead-free mini glass beads ensures the weight distributes evenly without suffocating the sleeper.
A 9-pound mini blanket measuring 40 by 60 inches works perfectly for anyone wanting a lighter introduction. Multi-sized quilted pockets allow the fabric to hug the body closely while keeping the interior weight concentrated.
Quality construction with durable materials means the bedding survives regular washing and lasts for years.
Pro Tip: Unlike meditation or journaling, a weighted blanket requires zero effort. The deep pressure stimulation does the work for you, signaling your nervous system to relax as soon as you get under it.
5. Choose flavor over the daily grind
A routine that feels like a chore gets skipped by Wednesday. The difference hinges on whether the morning habit belongs to you or just serves as another functional obligation. Reframing your first beverage from basic fuel to a daily pleasure shifts that dynamic immediately.
Flexible coffee subscriptions remove the final layer of friction from the morning setup. The coffee arrives before the pantry runs dry, eliminating the need to remember another errand. You wake up knowing a bold, fresh roast already sits in the kitchen cabinet.
Rotating through options keeps the morning cup interesting rather than letting it fade into background noise. Selecting a Rainforest Alliance certified, small-batch roast ensures the beans arrive fresh instead of warehouse-aged.
The bottom line
A functional routine accommodates the tired version of yourself rather than expecting unlimited willpower.
Preparing a flavorful coffee the night before removes the physical inertia of waking up. Sliding under a breathable weighted blanket at night forces the nervous system to settle without requiring a complex meditation sequence.
Environmental subtraction is the core strategy connecting these habits. Dropping the room temperature, limiting morning decisions, and relying on passive pressure stimulation systematically strip friction from the day.
Raising children changes the way money needs to be managed. Everyday expenses grow, unexpected costs become harder to absorb, and long-term goals such as education or retirement have to compete with more immediate priorities.
The biggest financial mistakes are not always dramatic. Often, they come from leaving too little room for emergencies, focusing on one goal at the expense of another, or failing to plan for expenses that do not arrive every month. Avoiding a few common problems can make family finances more resilient.
Monthly bills such as rent, groceries, utilities, and childcare are relatively easy to anticipate. The expenses that cause more trouble are often the ones that appear only a few times a year.
School supplies, sports fees, medical copays, birthday celebrations, clothing, car maintenance, and travel can all disrupt a budget if no money has been set aside for them.
A more useful family budget separates regular expenses from irregular but predictable ones. Parents can estimate what these occasional costs add up to over a year and set aside a smaller amount each month.
That approach reduces the chance that a known expense has to be treated like an emergency simply because it did not appear on last month’s budget.
2. Relying on credit cards for every unexpected expense
Credit cards can be useful financial tools, but relying on available credit whenever something goes wrong can gradually turn short-term problems into longer-term debt.
An emergency fund gives families another option. It does not need to cover every possible crisis immediately. Even a smaller reserve can help with a car repair, urgent travel, an insurance deductible, or a temporary increase in household expenses.
Parents can build that reserve gradually while deciding what truly qualifies as an emergency. A broken refrigerator may require immediate attention. A holiday purchase or upgraded phone usually does not. The goal is to create some distance between an unexpected bill and the automatic use of borrowed money.
3. Forgetting about the cost of major life changes
Families often budget carefully for normal months but underestimate how expensive transitions can be. Moving, changing jobs, separating households, welcoming another child, or arranging new childcare can create several costs at once.
Housing changes are a good example. Moving may involve application fees, moving expenses, utility setup costs, and an upfront deposit before the previous deposit has been returned. Parents trying to estimate how much are security deposits may also need to consider how that upfront cost will be covered if savings fall short, whether through a payment arrangement, rental assistance or a loan.
Planning for those costs together gives a more realistic picture of what the move may require and helps avoid treating a predictable housing expense like an unexpected emergency.
4. Saving for children while neglecting retirement
Parents naturally want to provide as much as possible for their children, but directing every available dollar toward education or other child-related goals can create another problem later.
Retirement deserves its own place in the family financial plan. Parents who postpone saving for themselves may have fewer years to build retirement assets and could eventually become more financially dependent on their children.
The right balance will differ between households. Some may contribute to a workplace retirement plan while gradually building education savings. Others may need to prioritize high-priority household expenses and retirement before adding a dedicated college fund.
The important point is that supporting children and preparing for retirement should not automatically be treated as competing goals where the parent always comes last.
5. Focusing on a child’s future without protecting the present
Long-term planning matters, but a family’s current financial protection is just as important. Life insurance, disability coverage, health insurance, beneficiary designations, and basic estate documents can all affect what happens financially if a parent dies or becomes unable to work.
The appropriate protection depends on the household. A single-income family may have different needs from a household with two earners, while parents with young children may need to account for childcare and housing costs that would continue even if one income disappeared.
Reviewing these protections periodically can be especially important after a birth, marriage, divorce, home purchase, or major change in income.
6. Keeping children completely outside money conversations
Children do not need to know every detail of household finances, but excluding them from all money discussions can make financial concepts harder to understand later.
Age-appropriate conversations can start with simple choices. Younger children can learn the difference between wants and needs or save toward a small goal. Older children can become involved in comparing prices, planning a budget for an activity, or understanding how a bank account works.
Parents can also make everyday decisions part of the lesson. Comparing grocery prices, saving before a large purchase, or explaining why the family is waiting before buying something can demonstrate financial habits without turning every conversation into a formal lesson.
Children often learn more from seeing how money decisions are made than from being told abstract rules about saving.
7. Managing each financial goal in isolation
Household finances are interconnected. Increasing a college contribution may reduce the amount available for emergencies. Taking on a larger car payment can affect the ability to save for retirement. Moving to a more expensive home can change childcare, transportation, and utility costs at the same time.
Parents can get a clearer picture by reviewing major commitments together rather than making each decision separately. A periodic financial check-in might include:
Monthly income and essential expenses,
Emergency savings,
Outstanding debts,
Insurance coverage,
Retirement contributions,
Education savings,
Large expenses expected during the next year.
Looking at these areas together makes trade-offs easier to see. It can also reveal when a goal needs to be adjusted because another part of the household budget has changed.
Building a financial plan that can adapt
Family finances rarely stay the same for long. Children grow, expenses change, careers develop, and unexpected costs appear. A good financial plan therefore needs room to adjust rather than relying on a perfect month-to-month forecast.
Parents can strengthen that flexibility by budgeting for irregular expenses, building emergency savings, preparing for major transitions, protecting their own long-term security, and reviewing financial priorities together. The goal is not to eliminate every surprise, but to make those surprises easier to manage when they arrive.
Nicolas Franchet had spent 13 years at Meta and worked his way up to senior director, the kind of tenure that usually comes with a bigger salary and richer benefits, when the February 2025 layoffs pushed him out at 54. His lawsuit says workers 40 and older were 1.5 times as likely to lose their jobs as workers under 40, and workers 50 and older were 2.5 times as likely.
He’s not the only one making that argument. Other major employers have faced the same accusation for years: as workers near retirement, they get more expensive to keep, and that makes them easier to cut. Age discrimination lawsuits tied to layoffs have hit tech companies including IBM.
Nearly a quarter of workers 50 and older say they are being pushed out of their jobs specifically because of their age, and about two out of three say they’ve seen or experienced age bias at work firsthand.
Pay tends to climb with tenure, and health insurance costs climb with age even faster. A full price health plan bought on the individual market averages 752 dollars a month at 40 and 1,598 dollars a month at 60, more than double for essentially the same coverage.
Employers feel a version of that same math. Companies where at least 35 percent of the workforce is 50 or older pay noticeably more for group health coverage than companies with a younger mix, on both single and family plans.
Premiums aren’t leveling off either. Employers are projected to spend more than 18,000 dollars per worker on health coverage in 2026, and an aging workforce is part of why.
None of that makes it legal to act on. A manager comparing two employees doing similar work, one of whom costs more in salary and benefits because of decades on the job, is looking at a number that tracks almost perfectly with age. Courts have treated cost tied to age as a stand-in for age itself for a long time, which is exactly why companies rarely say that’s the real reason out loud.
They assume you don’t have much runway left
Image Credit: Shutterstock
If you look like someone who might retire in a few years, some managers quietly stop investing in you. Why train someone for a leadership track, hand them a multi year project, or spend money developing them if the assumption is that they’re already halfway out the door.
One in five older workers report being passed over for training opportunities that went to younger colleagues instead.
The assumption rarely gets tested against reality. Nobody actually knows how long any individual employee, at any age, plans to stay. Older workers typically stay in their jobs longer than early career workers do, which usually saves an employer money on recruiting and training rather than costing it. A growing share of workers in their 50s and 60s are also holding onto their current jobs longer than planned, since many say they haven’t saved enough to retire on schedule, which cuts against the flight risk story some managers tell themselves.
The short runway story also assumes retirement means checking out well before it happens, which isn’t how most people who are still showing up to work every day actually behave.
They assume you can’t keep up with the technology
Image Credit: Shutterstock
Every rollout of new software, a new system, a new AI tool, seems to come with a quiet assumption about who’s going to struggle with it.
About a third of older workers say colleagues have assumed they’re less comfortable with technology, and about a quarter say they’ve been assumed to be resistant to change.
The data tells a different story. Workers 50 and older have added skills like AI to their professional profiles at a rate of 25 percent over the past five years, nearly double the growth rate among younger workers over the same period.
Other common assumptions round out the picture: roughly a fifth of workers 50 and older say coworkers joke about generational differences or overlook their accomplishments and expertise.
That disconnect between assumption and reality matters, because deciding someone can’t learn a new system based on their birth year is close to a textbook example of what the Age Discrimination in Employment Act was written to stop, even when nobody says the word age out loud.
They can replace you with someone cheaper
Image Credit: Shutterstock
Sometimes the plan is simpler than a spreadsheet. Cut the person earning a senior salary, hire someone with less experience for less money, and the line item shrinks.
Franchet’s lawsuit lays out exactly that pattern for one company’s 2025 layoffs: workers 40 and older were 1.5 times as likely to be cut as workers under 40, and workers 50 and older were 2.5 times as likely.
It has cost other companies real money before. Hewlett Packard and its spinoff paid 18 million dollars in 2023 to settle claims that they pushed out older employees, and Google paid 11 million dollars in 2019 over hiring discrimination allegations tied to age.
A cheaper replacement isn’t automatically illegal. What crosses the line is when age, not skill or salary on its own, is the reason an older worker gets selected for the cut while someone doing similar work does not. That distinction, age as the deciding factor rather than a coincidence, is the difference between an unfortunate business decision and an unlawful one.
They use a reorg or a layoff as cover
Image Credit: Shutterstock
Individual firings for cause draw more scrutiny than they used to, so a lot of this now happens inside something bigger: a reorganization, a reduction in force, a round of cuts framed around performance.
Franchet says he was rated a low performer in the same round of layoffs, despite years of strong reviews and a stock award that came with a personal note from the company’s CEO the year before.
It isn’t a new playbook. Internal emails at another major tech company once surfaced showing executives discussing wanting to hire more young workers and let older ones go.
Bundling age based decisions into a broader restructuring makes them harder to challenge, because the company can point to the reorg itself as the reason rather than any one employee’s age. It doesn’t make the underlying decision legal. It just makes it more work to prove.
The law firm representing Franchet says it’s looking into other claims from the same round of cuts, including potential violations of the WARN Act, the federal law requiring advance notice before mass layoffs.
Signs it crossed into age discrimination
Image Credit: Shutterstock
The Age Discrimination in Employment Act protects workers 40 and older at companies with 20 or more employees, covering hiring, firing, pay, promotions and layoffs.
A layoff alone isn’t proof of anything. A pattern is worth paying attention to: strong performance reviews for years followed by a sudden negative one right before a termination, a much younger and less experienced person doing your job within months, comments about energy, fresh perspective or culture fit aimed specifically at older employees, or training and stretch projects that consistently go to younger colleagues instead of you.
Numbers matter more than any single story. If a round of layoffs skews heavily toward employees over 40 or 50 while retaining younger employees in similar roles, that’s the kind of statistical pattern that shows up in age discrimination lawsuits like the one against Meta.
Both an employer’s stated intent and the actual outcome count under the law. A neutral sounding policy, like cutting anyone above a certain salary, can still violate the ADEA if it lands overwhelmingly on older workers.
Where to take it if you think it happened
Image Credit: Shutterstock
If you’re offered a severance agreement, you don’t have to sign it on the spot. Federal law gives workers 40 and older at least 21 days to consider an individual severance offer, or 45 days if it’s part of a group layoff, plus 7 more days to change your mind after signing.
In a group layoff, the company also has to disclose the ages and job titles of everyone who was and wasn’t selected, so you can actually see whether the cuts skewed older.
To bring a formal complaint, you generally have 180 days from the termination to file a charge with the Equal Employment Opportunity Commission, extended to 300 days if your state has its own age discrimination law and an agency enforcing it, which most states do.
An employment attorney can tell you quickly whether what happened looks like a pattern worth pursuing, and many take age discrimination cases on contingency, meaning you don’t pay unless they win. Keep copies of your performance reviews, any layoff communications, and anything showing who replaced you, before you lose access to your work accounts.
A friend of mine called herself “just a CNA” for eight years, like the job was something to apologize for. Then she picked up weekend differentials at a skilled nursing facility, added a dementia care certification, and watched her annual pay climb past $50,000, more than plenty of jobs that sound better at a dinner party.
Care work gets written off as minimum wage with good intentions attached. That’s wrong more often than people assume. The median hourly wage for a certified nursing assistant was $20.53 as of May 2025, which works out to about $42,700 a year at a full-time schedule, and that’s before shift differentials, specialty units, or travel contracts get added on top.
Certified nursing assistants handle the physical, unglamorous parts of patient care: bathing, feeding, transferring, and checking vital signs every few hours. It’s also one of the fastest routes into healthcare without years of school, which is part of why the pay gets written off before anyone looks at it closely.
The baseline is modest but not as low as most people guess. The median hourly wage for a certified nursing assistant was $20.53 as of May 2025, about $42,700 a year full time, and government employers, state hospitals, and veterans’ facilities in particular, tend to pay noticeably more than nursing homes or home health agencies. Picking up night differentials, working in a higher-acuity unit like an ICU, or adding a wound care or dementia care certification can push an hourly rate up fast, often within the first year or two.
None of this makes CNA work a six-figure career by itself. But the difference between what a new CNA earns and what an experienced one earns in the right setting is wide enough that calling it a minimum wage job misses the point.
Home health and personal care aide
Image Credit: Shutterstock
Home health aides and personal care aides help people stay in their own homes instead of moving into a facility: bathing, meal prep, mobility assistance, medication reminders. It’s demanding work, often with clients who need near-constant attention, and the agency pay for it is low enough that it rarely gets mentioned as a real career option.
The median hourly wage for a home health or personal care aide was $17.36 as of May 2025, about $36,100 a year full time, when working through an agency. But families looking for private, non-medical in-home care paid a national median of $35 an hour in 2025, which works out to more than $80,000 a year at a full-time 44-hour week. That difference exists because agencies keep a significant cut for scheduling, insurance, and overhead.
Caregivers who build a small roster of private clients directly, through word of mouth, a local senior center, or a platform like Care.com, keep far more of what families are actually paying. It takes longer to build that client base than taking an agency job, but the ceiling is considerably higher once it’s there.
Travel CNA
Image Credit: Shutterstock
Taking a CNA license on the road changes the pay picture completely. Travel staffing agencies place certified nursing assistants into short-term contracts, usually 8 to 13 weeks, at hospitals and long-term care facilities that are short-staffed and willing to pay a premium to fill the gap immediately.
Weekly pay on these contracts has recently averaged just over $1,000 a week, and contracts in high-demand locations or specialty units can run well above that, sometimes into the $1,500 to $2,500 range. Most packages include a housing stipend or per diem on top of the hourly wage, which is often tax-free if the traveler maintains a permanent home address elsewhere.
The tradeoff is obvious: no long-term stability at one facility, a new workplace to learn every few months, and licensing paperwork that has to transfer between states. For a CNA without kids in school or a mortgage tying them to one city, though, travel work can roughly double the take-home pay of a standard facility job, without any additional schooling or certification beyond what they already have.
Phlebotomist
Image Credit: Getty Images via Unsplash
Drawing blood sounds like a narrow skill, but phlebotomists work everywhere blood needs to move from a vein into a tube: hospitals, outpatient labs, blood donation centers, even mobile units that visit nursing homes and workplaces. The training is short, usually a matter of months, which keeps expectations about the pay low.
The median hourly wage for a phlebotomist was $21.88 as of May 2025, about $45,510 a year full time, ahead of several jobs that require a full college degree. Outpatient care centers paid phlebotomists more than hospitals or physicians’ offices on average, and the states with the highest wages, California, New York, Massachusetts, and Washington among them, pushed the number noticeably higher still.
Phlebotomists who cross-train into related skills, like EKG monitoring or basic lab processing, become more valuable to an employer without adding years of schooling. Mobile and travel phlebotomy, where a tech drives to collect samples rather than working a single site, often pays a premium on top of the base rate because fewer people are willing to do it.
Medical assistant
Image Credit: Shutterstock
Medical assistants are the people doing double duty in a doctor’s office: taking vitals, prepping patients, drawing blood sometimes, and also scheduling, billing, and managing the front desk when things get busy. The job blends clinical and administrative work in a way that makes it hard to categorize, and that confusion seems to carry over into how people guess at the pay.
The median hourly wage for a medical assistant was $22.17 as of May 2025, about $46,110 a year full time, with those working in outpatient care centers earning more than those in smaller physicians’ offices. It’s also one of the faster-growing jobs in healthcare, since outpatient clinics keep expanding and need staff who can do more than one thing well.
Becoming a Certified Medical Assistant through a recognized program, rather than learning everything on the job, tends to open doors to higher starting pay and more choice in where to work. Specializing in a busy specialty practice, cardiology or dermatology for instance, where procedures are more involved, often pays better than a general family practice role doing the same basic tasks.
Dental assistant
Image Credit: Shutterstock
Dental assistants sterilize instruments, take X-rays, prep materials, and hand the dentist exactly what’s needed before they even ask for it. Almost all of them work inside dentists’ offices rather than hospitals or clinics, which gives the job a steadier, more predictable schedule than a lot of healthcare support roles.
The median hourly wage was $24.13 as of May 2025, about $50,190 a year full time, which puts it ahead of several better-known entry-level healthcare jobs. Dental hygienists, who need an associate’s degree and a license, earn roughly double that, but the difference narrows considerably for assistants who pick up an Expanded Function Dental Assisting credential, where states allow it, since that credential lets them take on tasks a hygienist would otherwise handle.
Government and public health dental clinics tend to pay above the private-practice average, and assistants who learn orthodontic or oral surgery specialties, rather than general dentistry, usually command a higher hourly rate because fewer people are trained for those procedures. It’s a job most people assume caps out low. In practice, the ceiling moves a lot depending on the credential and the specialty.
Veterinary technician
Image Credit: Shutterstock
Veterinary technicians do for animals roughly what a nurse does for people: drawing blood, running lab tests, placing IVs, monitoring anesthesia during surgery, and comforting a terrified Labrador while all of that is happening. It takes a two-year degree and a credentialing exam in most states, more training than people assume walks in off the street.
The median hourly wage was $23.61 as of May 2025, about $49,110 a year full time, and demand for the role is growing much faster than average as more households spend more on pet care than they used to. Specialty hospitals and emergency clinics, where the work is higher stakes and often overnight, pay more than a general small-animal practice.
Techs who earn a Veterinary Technician Specialist credential in a niche like emergency and critical care, anesthesia, or dentistry move up the pay scale noticeably, the same way a nurse moves up by specializing. Research laboratories and universities, where the work involves lab animals rather than pets, also tend to pay above the general practice average, mostly because fewer people seek out that kind of setting.
Massage therapist
Image Credit: Shutterstock
Massage therapy gets filed under spa indulgence in most people’s heads, which undersells how much of it is actual medical and rehabilitative work. Therapists treat chronic pain, sports injuries, and post-surgical recovery alongside the relaxation sessions, and a license is required in nearly every state to practice at all.
The median hourly wage was $30.69 as of May 2025, about $63,840 a year full time, well above what most healthcare support jobs pay and ahead of plenty of office jobs that require a degree. A lot of massage therapists are self-employed, which means that figure is really a floor. Setting your own rates, building a loyal client base, and working in a higher cost-of-living area can push personal income considerably past the median reported by employees.
The field is also growing fast, as more employers and insurance plans treat massage as legitimate medical therapy rather than a luxury. Therapists who specialize in sports massage, prenatal work, or medical massage tied to physical therapy referrals tend to book out faster and charge more per session than someone offering general relaxation massage alone.
Occupational therapy assistant
Image Credit: Shutterstock
Occupational therapy assistants work under a licensed occupational therapist, helping patients relearn the everyday tasks an illness, injury, or disability took away: getting dressed, cooking, returning to work safely. It’s hands-on, patient-centered work that requires only an associate’s degree, not the doctorate an occupational therapist needs.
That’s what makes the pay surprising. The median hourly wage for an occupational therapy assistant was $33.99 as of May 2025, about $70,700 a year full time, nearly double the pay of an occupational therapy aide doing similar but less clinical support work in the same building. It’s also one of the highest-paying jobs on this entire list that doesn’t require a bachelor’s degree, let alone a graduate one.
Settings matter here too. Offices of physical, occupational, and speech therapists tend to pay well, and the job outlook is strong as the population ages and needs more rehabilitation support after strokes, falls, and surgeries. For someone weighing a two-year program against a four-year degree somewhere else, this is one of the clearer cases where the shorter credential pays off faster.
Physical therapist assistant
Image Credit: Shutterstock
Physical therapist assistants carry out the exercises, stretches, and mobility work a physical therapist designs, spending far more hands-on time with patients than the therapist who wrote the plan usually does. Like occupational therapy assistants, the role needs an associate’s degree rather than the doctorate a physical therapist now requires.
The median hourly wage was $33.04 as of May 2025, about $68,720 a year full time, almost twice what a physical therapist aide earns doing adjacent but less clinical work. Demand is growing fast, driven largely by an aging population that needs more rehabilitation after joint replacements, strokes, and falls, which is also pushing up pay in markets where PTAs are in short supply.
Outpatient clinics focused on physical, occupational, and speech therapy pay the most on average, ahead of hospitals and nursing homes. Assistants who build a reputation in sports medicine or orthopedic rehab, where patients often pay privately or have better insurance coverage, tend to see faster raises than those in a general outpatient setting. Two years of school for pay this close to a four-year-degree job is a rare combination.
Psychiatric technician
Image Credit: Shutterstock
Psychiatric technicians work directly with patients managing serious mental illness, developmental disabilities, or substance use disorders, often in psychiatric hospitals, residential treatment centers, or state-run facilities. The work is intense and the turnover is high, which tends to push the pay up faster than people expect once they actually look.
The median hourly wage was $22.41 as of May 2025, about $46,610 a year full time, and state government psychiatric hospitals in particular pay noticeably above that average because they struggle to keep the role staffed. The job is projected to grow much faster than most healthcare support roles over the next decade as mental health and substance use treatment both expand.
Most states don’t require a license to work as a psychiatric technician, though some, California among them, do, and voluntary certification through the American Association of Psychiatric Technicians can help with pay and advancement either way. For someone drawn to behavioral health but not ready to commit to years of nursing or counseling school, it’s a direct entry point with pay that holds up better than its reputation suggests.
Pet sitter and dog walker
Image Credit: Shutterstock
Pet sitting and dog walking get treated like a teenager’s summer job, something you do between real jobs rather than a job itself. Animal caretakers broadly, the category that covers shelter workers, boarding facility staff, and caretakers like this, had a median annual wage of $33,470 as of May 2024, which does look like a side hustle wage on paper.
But that number doesn’t capture what independent dog walkers and sitters in dense, dog-heavy cities actually bring home once they build a client base outside an app’s cut. One New York dog walker with two decades in the business and a loyal roster of clients now makes up to $120,000 a year, charging $20 to $25 per dog on group walks and running multiple walks a day. That’s an extreme case, but it illustrates how far the ceiling moves once reputation replaces an app’s algorithm for finding clients.
Holiday season boarding, where travel-heavy clients pay premium overnight rates, is where most independent pet sitters see their biggest income spike of the year, often covering a slow month or two elsewhere.
Professional nanny
Image Credit: Shutterstock
A nanny isn’t a babysitter with a longer commitment. The job usually involves a set schedule, defined duties around meals, education, and routines, and increasingly a level of professionalism that includes background checks, CPR certification, and sometimes a dedicated industry credential through a group like the US Nanny Association.
Pay has climbed with that professionalization. Families paid nannies anational average of $870 a week, or roughly $21.75 an hour, in 2026, and that figure moves considerably higher for nannies with a college degree, a second language, or several years with the same family. Full-time nannies in major metro areas with specialized skills, infant care certification or experience with a child who has additional needs, for example, routinely earn well above that national figure.
Going through a reputable placement agency rather than a casual arrangement found through a parenting group tends to mean better documented pay, actual benefits, and a contract, all of which push the real number higher than the informal rate most people picture when they hear the word nanny.
Newborn care specialist
Image Credit: Shutterstock
Newborn care specialists take over the overnight shift for exhausted new parents: feeding, soothing, diaper changes, and sleep coaching for a baby who hasn’t figured out day from night yet. It’s sometimes called night nannying, though the training involved, infant sleep science, feeding troubleshooting, and often postpartum recovery basics, goes well beyond general babysitting.
Pay reflects that specialization. Recent guidance puts newborn care specialists at $30 to $40 an hour or more, with some charging above $60, which lines up with what experienced specialists report charging in major cities. One certified specialist who built a reputation over several years of overnight shifts now earns up to $50 an hour working nine to twelve hours a night, several nights a week.
The hours are brutal by design, and burnout is real in a job that runs entirely on someone else’s sleep schedule. But for someone who can genuinely function well overnight, which not everyone can, the per-hour rate is considerably higher than most daytime childcare work, and families in a sleep crisis tend not to negotiate hard on price.
Postpartum doula
Image Credit: Shutterstock
A postpartum doula supports the parent, not just the baby, in the weeks after birth: helping with recovery, lactation questions, light household tasks, and simply making sure a new parent isn’t drowning alone. It’s different work from a birth doula, who’s only present for labor and delivery, and different from a newborn care specialist, who’s focused mainly on the baby overnight.
Postpartum doulas typically charge $25 to $50 an hour, with overnight rates often running higher, and many build ongoing relationships with a family over several weeks rather than a single visit. Some package the first few weeks into a flat fee instead of billing hourly, which can work out even better for a doula with a full client calendar.
Training and certification vary by organization, and plenty of experienced postpartum doulas build their reputation through word of mouth rather than a single credentialing body. For someone who likes the newborn chaos phase and has the patience for 2 a.m. questions about nursing positions, it’s steady, well-paying work that most people have never heard of as a real job title.
Birth doula
Image Credit: Shutterstock
A birth doula provides continuous support through labor and delivery, coaching on breathing and positioning, advocating with hospital staff, and simply being a steady presence for many hours in a row. It’s not a medical role. Doulas don’t deliver babies or provide clinical care, but hospitals and families increasingly value the support enough to pay well for it.
Most doulas charge $800 to $1,500 per birth outside of Medicaid coverage, and established doulas in expensive metro areas charge up to $3,500 depending on experience and location. A handful of states have started covering doula care through Medicaid too, which is opening up paid work supporting lower-income families who couldn’t previously afford it.
The income is lumpy by nature. A doula on call for a birth might wait weeks between clients or get two calls in the same week, and burnout from being perpetually on call is a real occupational hazard. Still, a doula who takes on four or five births a month at the higher end of that range is earning real money for work that, a decade ago, barely existed as a paid profession outside a handful of cities.
Geriatric care manager
Image Credit: Shutterstock
Geriatric care managers, sometimes called aging life care professionals, coordinate everything a family can’t manage alone when an aging parent needs help: doctor’s appointments, finding the right assisted living facility, tracking medications, and acting as the point person when something goes wrong and the kids live three states away.
It’s a job built for people with a background in social work, nursing, or counseling, and the pay reflects that professional training. The median annual salary was $81,359 a year, with top earners making more than $122,000. Many care managers are self-employed and bill by the hour for assessments, ongoing coordination, and crisis intervention, which means a manager with a full roster of clients controls their own ceiling more than someone on a facility’s payroll does.
The demand side of this is only getting bigger. More adult children live far from their aging parents than a generation ago, and fewer families have someone able to drop everything to manage a parent’s care in person. For someone who already has the clinical or counseling background, this is a largely overlooked way to use it.
Lactation consultant
Image Credit: Shutterstock
Lactation consultants help new parents troubleshoot breastfeeding: latch problems, low milk supply, tongue ties, and the dozens of smaller issues that can make nursing miserable instead of manageable. The most recognized credential, International Board Certified Lactation Consultant, requires supervised clinical hours and a board exam, more rigor than most people assume sits behind the title.
Independent IBCLCs typically charge $75 to $200 an hour, with home visits running $100 to $300 per session, and package deals covering several follow-up visits often land between $250 and $600. A consultant seeing even a handful of clients a week, which is a realistic caseload for someone building a private practice, adds up to solid income without ever setting foot in a hospital as an employee.
Insurance coverage is improving but still inconsistent, which pushes a lot of this work toward direct, out-of-pocket pay from families who simply want the problem solved. Lactation consulting is also IRS-eligible as a medical expense, so many parents pay through an HSA or FSA account instead of straight out of pocket, which keeps consultants busy and makes the price easier for families to absorb.
None of these jobs are easy, and none of them pay what a surgeon or a software engineer makes. But most of them pay more than the job title suggests, which is worth knowing before writing off a short certification program in favor of years of debt for a four-year degree.
Your Social Security check already got bigger once this year. The average retirement benefit climbed from $2,015 to $2,071 a month in January, a 2.8% raise that most retirees watched evaporate fast once Medicare took its cut.
Now three different research groups are penciling in next year’s number, and all three estimates land well above that 2.8%. AARP’s latest projection sits at 3.6%, and even the lowest of the three would still be the biggest raise retirees have gotten since 2023.
Nothing is final until the Social Security Administration announces the real number on October 14, once September’s inflation data closes out the calculation.
The new estimates already beat this year’s raise by a wide margin
Image Credit: Shutterstock
Three different groups publish Social Security COLA forecasts every month once summer inflation data starts rolling in, and right now their numbers cluster in a tight band. The lowest of the three, from the Committee for a Responsible Federal Budget, comes in at 3.4%. The highest, AARP’s 3.6% projection, sits at the top of the range. In between is the Senior Citizens League’s latest figure of 3.5%, a notch down from the 3.6% it had projected a month earlier.
All three numbers run well ahead of last year’s raise. The 2026 COLA landed at 2.8%, and 2025’s came in at 2.5%, so even the low end of this year’s range marks the sharpest jump retirees have seen in a couple of years. A 3.4% to 3.6% raise would also be the largest annual Social Security increase since 2023, when inflation was running far hotter than it is now.
The reason three groups put out three slightly different numbers comes down to timing and methodology, not disagreement about the underlying inflation data. Each one updates its model every time a new monthly inflation report drops, and each weighs the still-missing September figure a little differently. That’s also why the estimates move around from month to month instead of sitting still. A retiree checking back in October will likely see the range narrow even further as the final puzzle piece falls into place.
The real number isn’t locked in until the September inflation report lands
The COLA formula is mechanical, not political. The Social Security Administration takes the average CPI-W reading for July, August, and September and compares it to the same three months a year earlier. Whatever that percentage works out to becomes next year’s raise, no rounding tricks and no congressional vote required.
Right now, researchers only have two of those three months in hand. August’s CPI-W came in up 3.5% from a year earlier, which is why the current estimates cluster where they do. September’s reading, due out alongside the official COLA announcement on October 14, is the only piece still missing. A sharp move in gas or grocery prices during that one month could still push the final number outside the 3.4% to 3.6% range, though a dramatic swing this late in the year would be unusual.
These estimates have already moved once this year. Midsummer readings had one projection running as high as 3.8%, and they’ve eased down toward the mid-3% range as inflation cooled slightly in July and August. That drift lower is actually a small piece of good news, since a smaller COLA usually tracks with slower price growth elsewhere in a retiree’s budget, even if it means a smaller check bump than the early estimates suggested.
What a raise in this range actually adds to a check
Image Credit: Shutterstock
The exact dollar figure depends on which estimate you use and which starting benefit it gets applied to. Using the current average retired worker benefit of $2,071 a month, a 3.6% raise works out to roughly $75 more each month. Apply the lower 3.4% estimate to that same starting point and the increase drops to about $70.
The Senior Citizens League’s own figures use a slightly different starting benefit, which is why its numbers come out differently even at a similar percentage. Using its baseline average benefit of $1,940.08, a 3.5% raise would bring the monthly check to $2,007.98, a gain of $67.90.
Either way, the shape of the story stays the same. A raise in the 3.4% to 3.6% range would be the biggest cost of living increase retirees have seen since 2023, landing on top of two years of comparatively modest raises. An extra $70 or so a month isn’t life changing on its own, but it’s real money, and it’s noticeably more than the roughly $56 bump most retirees saw this January.
Medicare premiums take a slice before the raise reaches your account
Image Credit: Shutterstock
Most retirees never see the full COLA, because Medicare Part B premiums come straight out of the check before it gets deposited. For 2027, the standard Part B premium is projected at $209.50 a month, up from $202.90 in 2026, an increase of about $6.60.
That’s actually good news by recent standards. The projected rise would be the smallest percentage increase in the Part B premium since 2023, and it was lowered from an earlier projection that had put 2027’s premium at $218.60. Against a COLA somewhere between 3.4% and 3.6%, a roughly $6.60 premium increase takes a smaller bite out of the raise than it has in some recent years, when premium increases outran the COLA itself and left some retirees with a smaller net check despite the official bump.
The official 2027 premium won’t be confirmed until November, and this projection has missed before. Budget around $209.50 for now, and expect the real figure to land close to it rather than exactly on it.
Why many seniors say the raise still won’t be enough
COLA increases get calculated using CPI-W, which tracks the spending patterns of working age, urban wage earners rather than retirees. That mismatch is a long running complaint among seniors’ advocates, since retirees spend a bigger share of their budget on healthcare and housing, two categories that have been rising faster than the basket CPI-W actually measures.
The frustration shows up in survey numbers too. In a June survey, 89% of seniors said the 2026 raise of 2.8% left their benefits short of covering inflation, even though that raise sat above the 20 year average Social Security COLA of 2.6%. And the stakes keep climbing: an estimated 24.8 million older Americans, about 44% of retirees, now say Social Security is their only source of retirement income, up from 39% a year earlier.
None of that changes how the 2027 estimate gets calculated, but it explains why a raise that looks generous on paper, the biggest in several years, still won’t cover rent, groceries, and medical bills that have been climbing just as fast.
The real figure arrives on October 14, once September’s inflation data is final. Wherever it lands within the 3.4% to 3.6% range on the table right now, 2027 is already shaping up to be the best raise most retirees have gotten in a few years.