scroll top

Did you inherit your grandfather’s buffalo nickel? What about a silver dollar collection? Rare quarters or Canadian silver dollar or French franc? If so, do you want to sell silver coins?

Silver prices experienced a significant increase in over the past couple years, doubling in 2025 and continuing its rise to $77 in May.

Additionally, the market for rare coins is stronger than ever, making it a great time to dig into those collections and assess its value.

In this post …

How to sell silver coins

Take a few steps to ensure that you understand your coin, and get the highest price in cash:

1. Start with learning about the value of your silver coins

Spend some time researching the value of your silver coin by way of Google. Read about the history and collectibility of your coin, and reference the annually updated coin bible: A Guide Book of US Coins 2026. Get feedback from a coin buyer or collector.

2. Determine if your coin is worth its weight in scrap metal, or is a collectible.

Keep reading for more details. If your coin is worth scrap, you

For scrap or junk silver coins:

  1. Determine the weight of the coin and understand the day’s price of silver.

November 12, 2026, silver futures closed at $50.07, compared with $30 at the beginning of 2025.

2. Local metals buyer, some jewelry stores, pawn brokers, and online metals buyers will happily pay cash for your silver scrap.

Regardless of where you shop, try to get multiple offers and negotiate.

For rare and collectible coins:

If you can take your coin around locally, a pawn shop, antique dealer, coin dealer, or gold and silver buyer can give you a quote for how much they’d pay for your silver coins. Some local or online auctions may be interested.

The upside to selling your coins locally is that you get cash immediately. A quality pawn broker can be a good way to get a fair price, and get cash-in-hand immediately.

How to understand what your silver coins are worth

The value of a silver coin is dependent on its rarity, grade, and how desirable it is as a collectible. If it is not worth much as a collectible, then its value is based on its silver content.

This value can be significantly higher than the coin’s face value, depending on the current price of silver.

For example, a 1942 dime has a face value of 10 cents. Its silver content is worth about $5, however, when silver is at a price of $77 per ounce (May, 2026 pricing). That said, an uncirculated 1942 dime with an “S” mark can easily be worth $10 to $40 — and more than $2,000 for rare Mercury dimes.

What are 90% silver coins worth?

Dimes, quarters, half dollars, and dollars minted in the U.S. in 1964 or before will contain 90% silver by weight, with the remaining 10% coming from copper. These coins are also known as “constitutional silver” or “junk silver.” Those same coins minted later do not contain 90% silver.

Here’s an estimate of the melt value:

  1. Weigh your coin (in grams).
  2. Multiply that weight by .9 (since only 90% of the weight is silver). This number is how much silver, in grams, your coin contains.
  3. Find the spot price for a gram of silver.
  4. Multiply the number from Step 2 by the number in Step 3 and you’ll have the value of your silver coin.

November 12, 2026, silver futures closed at $50.07, compared with $30 at the beginning of 2025.

That said, if your silver coins are rare, old, or otherwise have value as a collector’s item, your coin collection may be worth more than you would get simply by melting it down for its silver content. There are many numismatic (coin collecting) websites where you can search for the value of your coin to determine if it has any collector’s value.

This video offers more detail about the value of 90% silver coins:

How much is a silver dollar worth?

Silver dollars will often sell to collectors for at least $20 a piece. Rarer silver dollars can sell for hundreds or thousands of dollars, with exceptionally rare specimens going for millions.

As a general rule of thumb, any silver dollar minted before 1965 will contain 90% silver, or about 0.7735 troy ounces of silver. The weight varies slightly by coin, but they are close. At the current price of silver (May 6, 2026: $77) that means that the silver content of these silver dollar coins is worth about $21.

Silver dollars that are at least 90% silver include:

  • Flowing Hair Silver Dollar (1794-1795)
  • Draped Bust Silver Dollar (1795-1804)
  • Gobrecht Silver Dollar (1836-1839)
  • Seated Liberty Silver Dollar (1840-1873)
  • Silver Trade Dollar (1873-1885)
  • Morgan Silver Dollar (1878-1921)
  • Peace Silver Dollar (1921-1935, 1964)

Additionally, the “American Silver Eagle” bullion coin minted from 1986-present contains 1 troy ounce of .999 silver, making it the silver dollar with the highest percentage of silver. Currently, these coins are worth about $80 as of May 2026.

“Eisenhower” Silver Dollars (1971-1978) and “Susan B Anthony” Silver Dollars (1979-1999) do not contain any silver, but can hold value to collectors.
Sell silver coins to CashforSilverUSA

Value of common U.S. minted silver coins

How much is a half dollar worth? 

Kennedy half dollars are the most common of this type of silver coin, though Franklin and Liberty half dollars are also common. These are worth between a few dollars, up to prices in the six-figures for very rare Kennedy coins.

What 50-cent pieces are valuable

Any U.S. half-dollar piece minted before 1965 will contain 90% silver. This increases their value to be higher than their face value of 50 cents.

Each of the coins below contain about 0.36169 ounces of silver. At the current price of silver ($77.30 per ounce as of May. 6, 2026) that means that the silver content of these 50 cent pieces is worth about $27. The list of 50 cent pieces that are 90% silver include:

  • Barber/Liberty Head half dollars, minted between 1892-1916. Barber Head half dollars coins often sell for around $20 but can reach prices of $1,000 or more.
  • Walking Liberty half dollars, minted between 1916–1947. Walking Liberty half dollars often sell for about $20 but have been known to reach $1,000+.
  • Franklin half dollars, minted between 1948–1963. Franklin half dollars typically do not sell for less than $10 a piece, and valuable coins can go for thousands.
  • Kennedy half dollars minted in 1964. 1964 Kennedy half dollars are worth at least $20 a piece and can sometimes sell for hundreds or thousands of dollars if they are in good enough condition.

Kennedy half dollars minted from 1965 through 1970 are 40% silver.

Kennedy half dollars

Rare or otherwise desired Kennedy half dollars can fetch a significant amount of money from collectors. As recently as 2019, for example, a particularly rare 1964 Kennedy half dollar sold for $108,000 at public auction.

For Kennedy half dollars without collector’s value, the value of your coin will depend on when it was minted, as the silver content of these coins varies by year.

Kennedy half dollars contain roughly 0.36169 ounces of silver. At the current price of silver ($77 per ounce as of May 6, 2026) that means that the silver in a 1964 Kennedy half dollar is worth about $30.

Kennedy half dollars minted between 1965 and 1970 contain 40% silver — significantly less, but still worth salvaging. These coins contain roughly 0.1479 ounces of silver and are worth about $15 just due to its silver content.

Any Kennedy half dollar minted from 1971 onward does not contain any silver.

Silver dimes

Silver dimes from 1964 contain about 90% pure silver, or about 0.0723 troy ounces of silver. To calculate the silver value of one of these dimes, you can multiply 0.0723 by the current price of silver. 

November 12, 2026, silver futures closed at $50.07, compared with $30 at the beginning of 2025.

Common silver dimes and their values:

  • Mercury dime value – .07234 times current silver price
  • Roosevelt dime value – .07234 times current silver price

Modern silver dimes (from 1965 onward) are not made of silver but a low-value metal alloy coated in silver.

Silver quarters

Silver quarters issued in 1964 and earlier contain about 0.1808 ounces of silver, which means the silver quarter value is 0.1808 times the current silver price.

Silver pennies

Silver pennies, which were minted in 1943, are actually made of steel coated in zinc, so they do not have silver penny value based on their silver content. These coins are fairly common, so their value as a collector’s item is minimal.

Collectible silver coins

Collectible silver coins, especially those with historic value, may be worth more in their current state. If you believe that you may have a valuable silver coin, a coin shop or appraiser can help you understand the value of your coin before you sell it. 

More on selling coin collections here.

These are some common silver coins in the United States and their value based on current silver prices as of Jan. 5, 2026:

U.S. Silver Coin Melt Values as of May 6, 2026

CoinSilver Value
Morgan Dollars$58
Peace Dollars$58
Liberty Head (Barber) Half-Dollars$27
Walking Liberty Half-Dollars$27
Franklin Half-Dollars$27
Kennedy Half-Dollars (1964)$27
Liberty Head (Barber) Quarters$14
Standing Liberty Quarters$14
Washington Quarters (pre-1965)$14
Liberty Head (Barber) Dimes$5
Winged Liberty Head (Mercury) Dimes$5

Any silver coin minted before 1965 contains a significant amount of silver and holds an intrinsic value due to that silver content.

The following coins contain a large amount of silver by content:

  • Morgan Dollars (90% silver)
  • Peace Dollars (90% silver)
  • Flowing Hair Silver Dollars (90% silver)
  • Draped Bust Silver Dollars (90% silver)
  • Gobrecht Silver Dollars (90% silver)
  • Seated Liberty Silver Dollars (90% silver)
  • Silver Trade Dollars (90% silver)
  • Barber/Liberty Head Half Dollars (90% silver)
  • Walking Liberty Half Dollars (90% silver)
  • Franklin Half Dollars (90% silver)
  • 1964 Kennedy Half Dollars (90% silver)
  • 1965-1970 Kennedy Half Dollars (40% silver)
  • Liberty Head/Barber Quarters (90% silver)
  • Standing Liberty Quarters (90% silver)
  • 1932, 1934-1964 Washington Quarters (90% silver)
  • Liberty Head/Barber Dimes (90% silver)
  • Winged Liberty Head/Mercury Dimes (90% silver)
  • 1946-1964 Roosevelt Dimes (90% silver)

How much is a buffalo head nickel worth?

Buffalo Nickels were first minted in 1913, and were replaced by the current design in 1938. Buffalo coins have some unusual and interesting anomalies, including some with three-legged buffalos, a notable lack of mint date and varying designs that are often forged and also add much value:

  • 1913-S Type 2
  • 1916/16 (doubled die variety)
  • 1918-D 8 over 7 (doubled die variety)
  • 1921-S
  • 1924-S
  • 1926-S
  • 1937-D Three legged Buffalo

Buffalo nickels can fetch dozens to tens of thousands of dollars.

Where to sell silver coins

If you have collectible or rare silver coins, a local coin dealer, antique store, jeweler or pawnshop can be a good fit, as well as a reputable online silver buyer.

Where to sell silver coins locally

If you are searching for places to “sell silver coins near me,” you’ll probably get a list of local coin dealers, pawn shops, and gold and silver buyers.

You can also search the Professional Coin Grading Service directory of authorized coin dealers to find a reputable person to buy coins worth money.

Where to sell silver coins online

There are many options for selling silver coins online, including some quality silver buyers. This post reviews the most popular online silver buyers, though our No. 1 recommendation is CashforSilverUSA because of its A+ BBB rating, high-quality customer service, very fast service, and reliable shipping and insurance.

Selling silver coins FAQs

Are silver coins worth selling?

If you have silver coins and need the money, it is always a good time to sell. Today, now that silver prices are high, it is a more universally good time to sell silver coins, though analysts expect silver prices to go up in the next couple years.

Who buys silver coins?

If you have found that your coin is indeed collectible seek out a dealer, collector, or auction house to maximize your profits, though a local pawnshop can also give you a fair price.

Silver coins worth their scrap, or junk, value can also be sold to pawn shops, silver exchanges, and silver buyers, each of which will give you cash in exchange for your coins (based on the weight of the coin) and then proceed to melt them down.

Is this a good time to sell silver coins?

The value of collectible silver coins often fluctuates with the price of silver, which has been very high recently, breaking records.

November 12, 2026, silver futures closed at $50.07, compared with $30 at the beginning of 2025.

What is considered junk silver?

Junk silver is the same as scrap silver: a term used to describe a silver coin that has no value as a collectible. Junk silver coins are worth more than their face value due to their silver content, but do not have any additional historical, collectors, or antique value. Junk silver coins are often melted down and sold.

Scrap silver with no collectible value is worth its silver content. To determine that value:

  1. Determine the silver content of the coin.
  2. Determine the weight of the coin (in ounces).
  3. Multiple that weight by the current price of silver (in ounces).

Learn more about the value of your scrap silver and how to sell it for the highest price.

Do banks buy silver coins?

Most banks will only give you the face value of whatever coins you turn in, regardless of their metal content. So, a silver nickel would be worth 5 cents, for example.

Get started selling your silver coins for cash within 24 hours with CashforSilverUSA now >>

Are silver coins worth anything?

Yes. The value of a silver coin is dependent on its rarity, grade, and how desirable it is as a collectible. If it is not worth much as a collectible, then its value is based on its silver content. This value can be significantly higher than the coin’s face value, depending on the current price of silver.

How much is a silver dollar worth?

Silver dollars will often sell to collectors for at least $20 apiece. Rarer silver dollars can sell for hundreds or thousands of dollars, with exceptionally rare specimens going for millions.

How much is a half dollar worth?

Kennedy half dollars are the most common of this type of silver coin, though Franklin and Liberty half dollars are also common. These are worth between a few dollars, up to prices in the six-figures for very rare Kennedy.

How much is a silver dime worth?

Silver dimes from 1964 contain about 90% pure silver, or about 0.0723 troy ounces of silver. To calculate the silver value of one of these dimes, you can multiply 0.0723 by the current price of silver.

Are silver coins worth selling?

If you have silver coins and need the money, it is always a good time to sell. Today, now that silver prices are relatively high, is is a more universally good time to sell silver coins.

Can you sell silver coins online?

You can sell silver coins online. If your silver coin is a collector’s item, you can sell online through an online auction house, on ebay, or to a reputable coin dealer. However, if you want to sell silver coins online that aren’t worth more than their scrap metal value, you can sell them to a reputable online metals buyer.

If you’re a single mom in Washington, D.C., struggling to make ends meet, keep reading for resources that help with: 

Every month, I give out $500 cash to one single mom struggling with money, health, stress, child care, illness or loneliness — no strings attached. 

Qualifications are simple:

1. You’re a single mom.

2. You need the money right now.

Fill out this form to apply:

(Note that the figures and information in this post are current as of publication date.)

Number of people in family/householdAnnual income
1$15,960
2$21,640
3$27,320
4$33,000
5$38,680
6$44,360
7$50,040
8$55,720

For families/households with more than 8 people, add $5,680 for each additional person.each additional person.

You can also look up your area median income (AMI) here.

Emergency cash for low-income families in Washington, D.C.

If you need cash to pay bills, buy gas, feed your family, or for any other reason, these programs can help: 

Temporary Cash Assistance in Washington, D.C.

Washington, D.C.’s Temporary Assistance for Needy Families (TANF) program provides cash assistance for qualifying families with children or to relatives who have court-ordered custody of a child placed in their home. 

The amount paid out depends on your family size and household income. For example, a family of three can receive up to $696 a month. 

Cash assistance is available for a lifetime total of 60 months for adults.

Qualifications:

  • U.S. citizen or a qualified non-citizen
  • Washington, D.C., resident
  • Currently pregnant or have children under under age 19
  • Must have social security number
  • Meet income requirements
  • Households must have less than $2,000 in resources, or $3,000 if the household includes a person who is age 60 or older
  • Complete orientation and assessment through the Office of Work Opportunity (OWO)
  • Develop an Individual Responsibility Plan (IRP)

Find out if you’re eligible online. 

How to get help: 

More emergency cash help in Washington, D.C.: 

Single moms in Washington, D.C., can visit 211.org or dial 2-1-1 to ask for assistance.

Check out these posts for more ways to get emergency cash: 

These are some more tips for getting cash quickly: 

Housing help for single moms in Washington, D.C.

If you need help finding a place to live or paying your rent/mortgage, these programs can help: 

Rental assistance in Washington, D.C.

There are multiple programs in Washington, D.C., to help renters find housing and pay their rent:

District of Columbia Housing Authority 

The D.C. Housing Authority (DCHA) provides affordable housing for low- to moderate-income households. Here is a list of D.C. Housing properties.   

Public Housing and Housing Choice Vouchers (Section 8)

The U.S. Department of Housing and Urban Development (HUD) offers affordable housing and vouchers to help low-income households pay their rent.

Qualifications:

Vouchers and housing are based on household income and family size. You can find your county’s income limits on the HUD website. 

How to get help: 

Emergency Rental Assistance Program

ERAP provides funding for overdue rent, including late fees and court costs in cases of potential eviction. The program also provides security deposits and first month’s rent payments for residents moving into new apartments. 

The amount households receive depends on their income and available resources at the time. ERAP may provide up to five times the rental amount based on the area zip code and bedroom size of the apartment/house.

You can apply for and receive ERAP once within a 12-month period.

There is a similar program called STAY DC that is not currently accepting applicants but may in the future. 

Qualifications:

  • Current DC resident
  • Household income is less than 40% of AMI
  • You can apply for a security deposit and first month’s rent for a unit in a neighboring county (Prince Georges County, Montgomery County, Arlington County, etc.)

How to get help: 

  • Apply online
  • Submit a completed paper application with supporting documents at any of the 6 Community Based Organizations that provide ERAP (find the list at the bottom of this page)

Mortgage assistance in Washington, D.C., 

If you need help buying a home in Washington, D.C., these programs can help: 

Family Self-Sufficiency (FSS) Program 

The FSS Program is a 5- to 7-year program aimed at helping D.C. residents achieve economic self-sufficiency through education, employment and homeownership. Each participant is assigned to an FSS coordinator who meets with them regularly to help work toward their goals.

Some of the program benefits include: 

  • Education – participants can receive up to $2,000 a year towards tuition
  • Employment – participants receive $600 for every 12 consecutive months of employment and an income exclusion
  • Homeownership – participants can receive up to $10,000 toward their mortgage

Qualifications:

The head of household and/or applicants must be in DCHA’s Housing Choice Voucher Program (HCVP) or public housing program. 

How to get help: 

Washington, D.C., Home Purchase Assistance Program 

The D.C. Department of Housing and Community Development’s Home Purchase Assistance Program (HPAP) provides interest-free loans and closing cost assistance to help qualified applicants purchase a home in the District. The loan amount is based on a combination of factors, including income and household size. Eligible applicants can receive a maximum of $202,000 in financing assistance and an additional $4,000 in closing cost assistance.

Qualifications:

  • Must be a first-time homebuyer
    • No residential ownership within three years prior to applying 
  • Must have a very low to moderate income, based on the Department’s standards
  • Purchased home must be the primary residence and must be located within the District of Columbia
  • Must have a good credit score (lenders set guidelines)          

How to get help: 

Washington, D.C., down payment assistance

The D.C. Housing Authority offers a variety of programs to help residents purchase a home, including the DC Open Doors program, which makes homeownership in the District affordable by offering qualified buyers home purchase loans, plus down payment and closing cost assistance through deferred repayable loans. 

The program also offers below-market interest rates for first trust mortgages. Both first-time and repeat homebuyers are eligible for the program.

You can learn more about the Open Doors program at an informational seminar. 

Qualifications: 

  • Minimum credit score of 640
  • Maximum income of $199,200
    • Income is based on borrower’s income only (not household)
  • Maximum debt-to-income (DTI) ratio of 50% 
  • $726,200 maximum first trust loan
    • No maximum sales price limit

How to get help: 

DC Homeowner Assistance Fund

The DC Homeowner Assistance Fund Program uses funding from the American Rescue Plan to help District homeowners who are struggling with their mortgage payments and other property or housing expenses because of the pandemic.

How to get help: 

Register online to see if you qualify.

Check today’s mortgage loan rates >>


Homeless assistance in Washington, D.C., 

If you are homeless or at risk of homelessness, you may be able to get help from the following program: 

Coalition for the Homeless 

The main goal of the Coalition for the Homeless is to provide support for D.C. residents experiencing homelessness. 

Services include:

  • Temporary housing
  • Food case management
  • Substance abuse counseling, 
  • Employment assistance 
  • Housing placement assistance

Qualifications: 

Eligibility varies depending on each program and service. 

How to get help: 

Homeless Prevention Program 

The Homeless Prevention Program (HPP) helps families avoid homelessness through case management, mediation, financial assistance (including up to four months of rent arrears), and connection to housing resources.

Qualifications: 

  • 30% of AMI or below
  • Families are assessed for HPP eligibility when completing intake at the Virginia Williams Family Resource Center (VWFRC), the central intake for DC’s coordinated homelessness assistance system for families with children  

How to get help: 

Call the D.C. shelter hotline at 202-399-7093. 

More housing help: 

Electric bill assistance in Washington, D.C.

If you are struggling to pay your utility bills in Washington, D.C., check out the following programs:

Utility Discount Programs (UDP)

The Utility Discount Programs helps low-income District residents reduce their utility costs. 

If you’re eligible, you could receive discounts of:

  • Up to $475 per year on your electric bills ($300 per year if you don’t have electric heat)
  • Up to $276 during the winter season on your gas bills
  • Over $962 annually on your water and sewer bills

Qualifications:

  • U.S citizen or a qualified alien
  • Resident of Washington, D.C.
  • Must have utility bills in applicant’s name 
  • Meet annual household income guidelines

How to get help:

  • Apply online 
  • Print and complete this application and send via mail with required documents to:
    • Attn: Utility Affordability Administration 1200 First Street NE, 5th Floor Washington DC, 20002 

Low-Income Home Energy Assistance (LIHEAP) in Washington, D.C.

LIHEAP helps qualifying households with home heating and cooling costs, paid directly to utility companies. The agency does not assist with water, sewer, or telephone services. 

Qualifications:       

  • Meet income guidelines 
  • Responsible for paying your home heating or cooling bills
  • Resident of Washington, D.C.
  • U.S. Citizen, qualified alien, or permanent resident of the U.S.

How to get help:

Department of Energy & Environment

DOEE is not currently accepting appointments for utility assistance but may in the future. Visit the DOEE website for future availability. 

Weatherization Assistance Program (WAP)

WAP helps low-income families lower their monthly energy bills by making their homes more energy efficient. Types of assistance include:

  • Installing carbon monoxide detectors
  • Removing mold
  • Replacing inefficient or unsafe heating units 
  • Insulating a single family home for energy efficiency

Qualifications:

  • U.S citizen or a qualified alien
  • Resident of Washington, D.C.
  • Meet annual household income guidelines
  • Automatically eligible if you are receiving SSI, TANF or Aid to Families with Dependent Children benefits

How to get help:

More electric bill help: 

Free money to help pay bills

Medical and dental help for single moms in Washington, D.C.

The following medical and dental services are available to qualifying individuals and families:        

District of Columbia Dental Society 

The District of Columbia Dental Society (DCDS) connects residents with free and low-cost dental clinics. 

Qualifications: 

Each individual clinic sets its own eligibility requirements. 

How to get help: 

Office of Disability Rights 

The Office of Disability Rights (ODR) connects residents with free medical clinics. 

Qualifications: 

Each individual clinic sets its own eligibility requirements. 

How to get help: 

Health Resources & Services Administration (HRSA) in Washington, D.C.

HRSA, an agency of the United States Department of Health and Human Services, funds health centers that provide free or subsidized health and dental care to low-income people and those otherwise unable to access quality health care, like people living in rural areas.

HRSA also offers a 24/7 free and confidential mental health hotline for pregnant and new moms. Dial 833-943-5746 (833-9-HELP4MOMS) if you are struggling.

Qualifications: 

Each health center sets its own eligibility criteria for free or reduced cost care. 

How to get help:

Find an HRSA health center in Washington, D.C., by typing in your address on HRSA’s search tool.

Washington, D.C., Medicaid

D.C. Healthy Families, the District’s name for its Medicaid program, provides medical coverage for low-income individuals and families. In Washington, D.C., most Medicaid recipients are enrolled in the Statewide Medicaid Managed Care program, which includes:

  • Managed Medical Assistance (MMA) – Covers medical services like doctor visits, hospital care, prescription drugs, mental health care, and transportation for medical needs
  • Long-term Care (LTC) – Covers care in a nursing facility, assisted living, or at home (must be at least 18 years old and require nursing home-level care or hospital-level care if you have cystic fibrosis)
  • Dental – Covers all dental services for children and adults

Qualifications:

  • Resident of Washington, D.C.
  • U.S. national citizen, permanent resident, or legal alien
  • Meet income requirements

Plus, you must meet at least one of the following requirements:

  • Pregnant, or
  • Caretaker for a child 21 or younger
  • Member of the household has a disability, including blindness
  • 65 or older

How to get help:

Washington, D.C., CHIP

District of Columbia Medicaid for Infants and Children provides medical coverage for children up to age 21 whose families do not qualify for Medicaid. Covered services include: 

  • Doctor visits
  • Surgeries
  • Vaccines
  • Vision and hearing 
  • Hospital stays

Qualifications: 

  • Washington D.C. resident
  • U.S. national citizen, permanent resident, or legal alien 
  • Under age 21
  • Meet income guidelines 

How to get help: 

Washington, D.C., Healthy Start

DC Healthy Start is a program for residents of Wards 5, 7 and 8 that provides services, referrals, and support for all women, parents, and infants up to 18 months. 

Education services cover:

  • Prenatal care and parenting 
  • Conception 
  • Wellness screenings 
  • Stress management
  • Local resources and assistance
  • Free transportation to attend perinatal care appointments

Qualifications: 

Pregnant women and parents of children under 18 months old who live in Wards 5,7 and 8 are eligible for D.C. Healthy Start services. 

How to get help: 

  • Call 800-MOM-BABY (1-800-666-2229)
  • Email: dchealthystart@dc.gov

More medical/dental help: 

Food help for low-income families in Washington, D.C.

A number of federal and state food and nutrition programs are available across the state:

Washington, D.C., Food Assistance Program (SNAP)

USDA’s Supplemental Nutrition Assistance Program (formerly known as the Food Stamp program) provides food benefits and nutrition education to low-income households. 

SNAP recipients are issued an EBT card that can be used like an ATM card in retail food stores to purchase food, including:

  • Breads
  • Cereals
  • Fruits
  • Vegetables
  • Meats
  • Fish
  • Poultry
  • Dairy
  • Plants and seeds to grow food 

Qualifications:

  • Washington, D.C., resident
  • Current bank balance (savings and checking combined) under $2,750 or under $4,250 and share your household with one of the following:
    • Person or persons age 60 and over
    • Person with a disability (child, spouse, parent, yourself
  • You must also have an annual household income below these amounts.  

How to get help: 

Women, Infants, and Children (WIC)

The Special Supplemental Nutrition Program for Women, Infants, and Children is a nutrition program that provides free baby formula and nutritional food items to low-income mothers and their babies. 

Qualifications:

How to get help: 

National School Lunch Program (NSLP) and School Breakfast Program

NSLP serves healthy, well-balanced, reduced-price or free meals to children in school. 

An extension of the NSLP, the School Breakfast Program provides free or low-cost breakfast to eligible students. Schools with at least 80% of the students eligible for free or reduced-price meals must provide breakfast at no cost to all students. 

Learn about the DC program here. 

Qualifications: 

Household income must fall at or below the limits of the Federal Income Eligibility Guidelines.

How to get help: 

  • Apply online 
  • Contact your child’s school to enroll
  • Call 202-727-1839
  • Email osse.nutritionprogram@dc.gov  

Washington, D.C.’s Summer Food Service Program

The U.S. Department of Agriculture and Consumer Services serves nutritious meals at no cost to children during summer break. Food is distributed at local schools, nonprofits, l parks and libraries. Learn more about the program in DC here. 

Qualifications: 

Must be under age 18. There is no registration or application required. 

How to get help: 

Washington, D.C., food banks

Food banks in Washington, D.C., provide meals for individuals and families who are struggling to put food on the table. 

Qualifications: 

Each food bank sets its own eligibility and proof of need requirements. 

How to get help: 

To find a food bank near you and for additional information, visit the Capital Area Food Bank website.

More food help: 

Child care help for low-income families in Washington, D.C.

There are multiple federally funded education programs and resources in Washington, D.C.:

Washington, D.C., Head Start and Early Head Start

Head Start is a free federal preschool program for children aged 3 to 5 from low-income families. Early Head Start serves pregnant women and children under age 3. The programs focus on cognitive, social, and emotional development and prepare children for school. 

Qualifications: 

  • Children from birth to 5 
  • Meet federal poverty guidelines 
  • Children in foster care, homeless children, and children from families receiving public assistance (TANF, SSI, etc.) are eligible regardless of income
  • Some programs accept kids with incomes above the Poverty Guidelines
  • Pregnant women can also receive prenatal and postpartum information, education, and services through Early Head Start

How to apply: 

Universal Pre-K

The District of Columbia Public Schools (DCPS) offers a free, universal pre-kindergarten program. This program helps provide free childcare while also ensuring children are ready for kindergarten. Only resident students of the District can attend DC public schools tuition-free.

Tuition rates vary by grade, sector, and the educational services the student receives. These amounts change each school year. You can find the rates for the current school year here. 

Check out the school finder here. 

Here is a list of other pre-K options in the DC area. 

Qualifications: 

For the student to be considered a resident and claim free tuition, they must: 

  • Be physically present in DC
  • Submit valid documentation of DC residence

To be eligible for any school year:

  • Students must be 3 by September 30 to apply to PK3
  • Students must be 4 by September 30 to apply to PK4

How to get help: 

More child care help

Education help for single moms in Washington, D.C.

If you’re a single mom who wants to further her education, here are some helpful resources: 

Get a GED in Washington, D.C.

If you are at least 18 years old in Washington, D.C., you can take the GED test. You may also be able to take the test at 16 or 17 with special permission from the school district where you live. 

You must take the GED Ready practice test and pass before you can take the GED. 

The GED test is broken into four exams on different subjects, which can be spaced out and taken at your own pace (though each individual exam has a time limit): 

  • Mathematical reasoning – 115 minutes
  • Reasoning through language arts – 150 minutes
  • Social studies – 70 minutes
  • Science – 90 minutes

You have two options for taking the test in Washington, D.C.: 

  • Online at-home test – $36 per subject
  • In-person at a test center – $3.75 per subject

How to get help:

Generation Hope

Generation Hope, a non-profit started and run by a teen single mom supports teen moms in completing their college degrees through:

  • Tuition and child-care assistance
  • Mentorship, including being assigned a mentor
  • Mental health support
  • 1-1- career-readiness coaching
  • Training, events and community of other single-parent students

Commitment to Excellence Scholarship Program 

DCHA’s scholarship program awards $40,000 to eligible students each year. Applicants must be attending an accredited college, university, or trade/technical school in the fall and must have a 2.0 GPA or a 225 GED score.

Qualifications:

The head of household and/or applicants must be in DCHA’s Housing Choice Voucher Program (HCVP) or public housing program. 

How to get help: 

Grants and scholarships in Washington, D.C.

The Office of the State Superintendent of Education (OSSE) connects students and prospective students with grants and scholarships available in Washington, D.C.. To find out which scholarships and grants you may be eligible for, create a student profile on the OSSE website. 

Individual schools also offer need-based and academic scholarships for their students. If you’ve been accepted to a higher education institution, contact their office of financial aid to learn how to apply. 

More education help: 

Employment help for single moms in Washington, D.C.

Workforce programs in Washington, D.C., provide training and assist with employment:

Washington, D.C., Reemployment Assistance (Insurance) Program

This program provides unemployment compensation to eligible Washington, D.C., workers who are out of work through no fault of their own.

Qualifications: 

  • Washington, D.C., resident 
  • Unemployed
  • Previously employed for the past 12 months
  • Earned a certain amount of wages
  • Actively looking for another job

How to get help: 

American Job Centers

The American Job Centers offer employment and training services, career counseling, and job search assistance. 

How to get help: 

More employment help: 

Charity organizations in Washington, D.C.

There are a number of charitable organizations throughout Washington, D.C., that offer support to single moms:

The Salvation Army of Washington, D.C.

The Salvation Army wears many hats. Chapters assist with:

  • Food, shelter and clothing
  • Medication costs
  • Education and job training
  • Christmas presents
  • Rent and utility bills
  • Substance abuse rehabilitation
  • Youth services
  • Emergency disaster response

Qualifications: 

Each Salvation Army branch determines its own eligibility criteria for different programs. 

How to get help: 

Visit the Salvation Army website to find your local chapter. 

Catholic Charities of Washington, D.C.

Catholic Charities assists with:

  • Housing
  • Utility assistance
  • Food assistance
  • Health care assistance

Qualifications: 

Each Catholic Charities branch and program determines its own eligibility criteria for different programs. 

How to get help: 

United Way of Washington, D.C.

The United Way of Washington, D.C., connects people in need with local resources like: 

  • Food
  • Shelter
  • Child care services
  • Housing
  • Health care
  • Support groups

How to get help: 


Not your state? Select yours here:

Whether you are a collector, investor, or inheritor of gold coins, now is a great time to sell, with gold prices at all-time highs and many people in need of cash thanks inflation and a lousy job market.

Unlike scrap jewelry, bullion or dental gold, coins are minted and typically stored as an investment or in some cases, a rare collector’s item. Most coins are sold just for their weight and purity, but some collectible coins are worth significant money also for their rarity, collectability, history and other extrinsic qualities. 

Bottom line up front: Best way to sell gold coins

In this post, we’ll explain why we recommend either a local pawn shop (and how to find a good one) or online gold buyer Cash for Gold USA as our most trusted sources for buying most gold coins, jewelry and other precious metals and stones.

If you need more information, read on — we answer common questions about selling gold coins: How do you actually sell a gold coin, anyway? Who buys them, and how much are they worth? We answer these questions and more below:

How to sell gold coins

1. Learn about the value of your gold coins

If you don’t know what you’re selling, it’ll be very easy to be ripped off by the buyer. Is your gold coin simply bullion, worth its weight and purity at today’s value — or is it a rare collectible? These posts can help you understand the value of your coins:

15 common coins worth money
What to do with your coin collection

Start with a Google search, look through listings on ebay and coin collector sites and familiarize yourself with what you have. Understand the markings on your gold to help understand the purity. The 2026 Red Book Handbook of U.S. Coins Paperback and Price Guide is the Bible of coin collecting.

You might want to invest in a digital scale to understand the exact weight of your coin.

2. Check today’s gold price

As of January 16, 2026, gold was near record highs near $4,601.

At a minimum, your gold coins will always be worth at least the value of the gold that they contain. This will depend on the purity of the metal and the weight of the coin. Once you know this information, which you can find with a quick Google search about the coin, you should be able to quickly figure out the rough value of the coin.

An appraisal from a local jeweler or coin dealer can help further, especially if you believe your coin is rare.

These are some common gold coins in the United States and their value based on current gold prices as of January 16, 2026:

Gold CoinApprox. Market Value
American Gold Eagle$4,520
American Buffalo$4,520
Canadian Gold Maple Leaf$4,520
Indian Head Gold Eagle$2,260
South African Krugerrand$4,520

Learn more about the current price for gold and selling gold for cash in this post.

3. Choose a reputable gold buyer

If you need cash immediately, or prefer to deal with local businesses, research local pawnshops or jewelry stores, coin or antique dealers via personal referrals, Yelp and Google reviews. Many communities have quality local business that will offer you a fair price on your gold.

However, if you choose to sell your gold coins to an online gold buyer, you’ll send your coins to them for evaluation and final sale. A reputable gold buyer will pay for insured and trackable shipping with FedEx, UPS or USPS.

4. Get multiple offers

No matter where you sell, be sure to get multiple offers — and do not be shy about negotiating for the highest price.

To get an idea of what is fair, see the melt value of your gold coins based on today’s gold price on CashforGoldUSA:

CashforSilverUSA calculator

This calculator is for information purposes only and is not the amount you should expect to receive. It provides the highest melt value of your gold today, not an offer. Your offer will depend on your appraisal.

Where to sell gold coins for cash

Here are places where you can sell gold coins:

  • Coin collectors 
  • Coin dealers 
  • ebay
  • Antique store / dealer 
  • Auctions
  • Pawnshops
  • Online gold and silver buyers
CashforGoldUSA display ad

Looking to sell silver coins? Find out where to sell them.

What’s the best place to sell coins locally

In some cases when you have an exceedingly rare or otherwise precious coin, it makes sense to sell a coin collection or rare coin to a dealer, at auction or to an individual collector.

A reputable online gold, silver or coin buyer is another option if you prefer a more private sale without leaving your home. These businesses will have a robust online presence you can research and often offer high-price guarantees.

Do banks buy gold coins?

Today’s banks very rarely buy gold coins. In the past, when the United States operated on the gold standard, many banks would accept gold coins and exchange them for paper money when requested. If you want to sell gold coins, you need to find a gold coin buyer.

Best place to sell gold coins online: CashforGoldUSA

When it comes to selling gold coins that don’t have any value as collectors’ items (or any other type of gold) I recommend selling to CashforGoldUSA, for a few reasons:

  • They pay fast: within 24 hours of an accepted offer.
  • 100% free shipping and insurance: Door-to-door free, trackable FedEx or USPS shipping, plus free Jeweler’s Mutual insurance up to $150,000. Lloyds of London insures the CashforGoldUSA facility.
  • Better Business Bureau review of A+
  • Pays by your choice: Paypal, print-at-home check, direct deposit, personal check by Fedex or First Class USPS or Virtual Visa credit card.
  • Buys all quantity and purity of gold, silver, sterling flatware, as well as diamonds and fine watches
  • Trustpilot 4.8 stars with 2,377 reviews

Other online gold coin buyers

Some popular online gold bullion buyers you can consider include the following, but were not included in our recommendation because of online reputations, speed of payment, ease of use of website and other processes, and age of business:

  • Liberty Gold and Silver
  • Luriya
  • Money Metals Exchange
  • SellYourGold.com
  • US Gold Buyers
  • APMEX
  • Kitco
  • JM Bullion
  • American Bullion
  • Goldco Precious Metals
  • Gold Geek
  • Abe Mor
CashforGoldUSA display ad

FAQs about selling gold coins

Gold coins are either gold bullion coins, for investments, or rare coins, which can be made of any precious metal, and are often of historical significance. Here are some common questions you might have:

How much are gold coins worth?

The value of your gold coin will depend on these factors:

  • The purity of the gold (i.e., how much gold the coin contains)
  • The weight of the gold
  • The current spot price for gold
  • Whether or not your coin has any value as a collectible

Whether or not your coin has any value as a collectible, it will always be worth at least its weight in gold.

Gold prices Gold prices keep hitting new record highs, thanks in part to market turmoil amid tariffs and global unrest. Spot gold hit a record in January, 2026 of $4,601.

How much is a gold dollar coin worth?

The retail price for a 1-ounce American Eagle gold dollar coin is $4,520. as of January 16, 2026.

The market price of a gold dollar coin considers several factors, including purity of gold, rarity, weight and condition. Your gold dollar coin’s price may vary from $200 to tens of thousands of dollars for rare, mint-condition gold dollar coins, including American Eagles, Canadian Maple Leafs and Austrian Ducats.

Do gold coins lose value?

Gold coins lose and gain value based on the current spot price of gold.

What gold dollar coins are worth money?

Gold dollar coins that are commonly collected and sold include:

  • Sacagawea gold dollar coins that were minted 2000-2008 and again with different reverse designs starting in 2009
  • Proof Capped Bust $5 Gold Half Eagle
  • O Liberty Head $20 Gold Double Eagle
  • Roman Proof Saint-Gaudens $20 Gold Double Eagle
  • Proof Liberty Head $10 Gold Eagle
  • Indian $10 Gold Eagle
  • Draped Bust $2.50 Gold Quarter Eagle
  • Saint-Gaudens $20 Gold Double Eagle
  • Satin Proof Indian $10 Gold Eagle
  • Proof $4 Stella Coiled Hair

If you’re ever in doubt as to whether or not your coins have any value as collectibles, there are many (many!) numismatist websites and manuals that you can reference to check the value of your coin before selling. Coin dealers in your area can be helpful in offering an appraisal.

Also, read this post on coin collections, and check out the industry standard for grading coins, The Official Red Book.

CashforGoldUSA display ad

Should I get my gold coins graded?

Referred to as certifying, rating, slabbing, or encapsulating, coin grading involves an expert evaluating a coin to determine its condition, authenticity, rarity, and value.

It can cost about $20 to $150 to get a coin graded from either the Professional Coin Grading Service or the Numismatic Guaranty Corporation, plus you have to pay a membership fee to the grading company.

If your goin is not rare, and is simply an investment, or it is a low value, then grading will not add value to your coin. However rare coins should be graded.

Are gold coins easy to sell?

The answer to this question will depend on whether or not your gold coins have any value as collectibles, such as old or rare coins — as well as those in excellent condition. Coins like these have value on top of the value of the amount of gold that they contain. To get the best deal when selling collectible gold coins, you may need to work with a numismatist or sell directly to a collector, which can take time.

On the other hand, there are many gold coins that have absolutely no value as collector’s items. This is particularly true of most modern “investment grade” gold coins, such as:

  • American Eagle
  • American Buffalo
  • Canadian Maple Leaf
  • British Britannia
  • South African Krugerrand
  • Austrian Philharmonic
  • and others

When selling these types of coins, you’re essentially just selling them for the value of the gold that they contain. In these instances, it’s pretty easy to sell your coins for scrap. Pawnshops, jewelry stores, consignment shops and “we buy gold” locations near you will buy these types of coins.

Again, CashforGoldUSA, an online buyer, is our top recommendation for selling gold items.

Is it easier to sell gold coins or bars?

It is typically easier to sell smaller units of gold. As such, gold coins, or smaller gold bars, are usually easier to sell than large gold bars.

Bottom line: Where can I sell my gold coins for the best price?

If you have gold bullion coins, or commonly held gold coins like the American Eagle, a site like CashforGoldUSA, a local jeweler, or gold recycler are fine choices. However, rare coins of any precious metal including silver are best sold through a rare coin buyer or rare coin dealer.

Get a free estimate on your gold coins from CashforGoldUSA.

Have more items or valuables you are looking to sell? Learn more about what to do with inherited coins.


How much are gold coins worth?

The value of your gold coin will depend on these factors: purity, weight, spot price, and whether or not it is collectible.

How much is a gold dollar coin worth?

The market price of a gold dollar coin considers several factors, including purity of gold, rarity, weight and condition. Your gold dollar coin’s price may vary from $200 to tens of thousands of dollars for rare, mint-condition gold dollar coins, including American Eagles, Canadian Maple Leafs and Austrian Ducats.

Should I get my gold coins graded?

If your goin is not rare, and is simply an investment, or it is a low value, then grading will not add value to your coin. However rare coins should be graded.

Are gold coins easy to sell?

The answer to this question will depend on whether or not your gold coins have any value as collectibles, such as old or rare coins — as well as those in excellent condition. Coins like these have value on top of the value of the amount of gold that they contain.

Do banks buy gold coins?

Today’s banks very rarely buy gold coins. In the past, when the United States operated on the gold standard, many banks would accept gold coins and exchange them for paper money when requested. If you want to sell gold coins, you need to find a gold buyer.

Ethos offers term and guaranteed whole life insurance policies with no medical exams ever for people ages 20 to 85.

Like other online insurance providers, Ethos uses a detailed questionnaire to ask questions about your health, finances, and lifestyle to determine whether or not they can offer you coverage. 

I was ultimately not offered an insurance policy based on my BMI and health conditions, though I should note that I also haven’t been approved for any other online provider to date. 

Ethos claims to approve 95% of applicants for policies, which means if you are generally healthy, you should be able to obtain an affordable life insurance policy through Ethos.

Our review of Ethos Life

  1. Yes, it’s real. Ethos is a legit life insurance company.
  2. Ethos is not for everyone.
  3. Ethos has no medical exams ever.

Others’ reviews of Ethos

How much Ethos costs

How Ethos works

Details about Ethos life insurance policies

Pros and cons of Ethos

Ethos vs. other life insurance companies

Bottom line: Ethos is worth considering if you need to buy life insurance

What we found in our review of Ethos: 3 things to know

1. Yes, it’s real. Ethos is a legit life insurance company.

Although it was only founded in 2016, Ethos is a legit life insurance company with an A+ rating from the Better Business Bureau and 4.7/5 stars on Trustpilot. Ethos administers policies from established insurance carriers, including:

  • Legal & General America (est. 1981)
  • Ameritas Life Insurance Corp. (est. 1887)
  • TruStage Financial Group, Inc. (underwriter CMFG Life est. 1935)
  • Senior Life Insurance Company (est. 1970)
  • Mutual of Omaha (est. 1909)

Ethos policies are also reinsured by Munich Rea, which holds an A+ BBB rating.

2. Ethos is not for everyone.

Ethos is licensed in every state except New York, plus the District of Columbia. They offer two types of policies:

Term life insurance: 

  • For people aged 20 to 65
  • Policies can cover you until the age of 80
  • $20,000 to $2 million in coverage
  • 10-, 15-, 20- and 30-year terms
  • Approval is based on your answers to questions about your medical history, finances, and lifestyle (where you work, whether you smoke, if you have kids, etc.)

Ethos claims to have life insurance policies that cover all health conditions and BMIs, but based on my experience, this isn’t true. 

For reference, I am a 32-year-old woman with two children ages 4 and 9. I want term life insurance to be able to replace my income and support my family in the event that I die before my kids are financially independent. 

However, because of my high BMI and health conditions — asthma, PCOS, anxiety, and IIH — I have been unsuccessful in obtaining life insurance coverage, both from Ethos and other providers like Ladder Life Insurance. 

After being rejected, Ethos did suggest I call an agent to talk about other policy options, and an agent named Damon recommended I apply for an accidental death policy from Mutual of Omaha for $500,000, which would cost me $36/month.

While this coverage doesn’t offer everything I’m looking for in a life insurance policy, it is something I may purchase in the meantime while I work to improve my health until I can be covered. 

Guaranteed issue whole life insurance: 

  • For people aged 66 to 85 
  • Policies cover you for life, with no payments after you turn 100
  • $1,000 to $30,000 in coverage
  • Guaranteed approval after you answer health questions to determine your rate
  • Secure rate that never increases

While Ethos does guarantee approval for its whole life insurance policies, depending on your answers to its health questionnaire, you may not qualify for the full $30,000 in coverage.

3. Ethos has no medical exams ever.

Sounds too good to be true, right? 

Well, it is true that Ethos will never require a medical exam, but that doesn’t mean everyone will be automatically approved for term life coverage. Ethos’ whole life policies, on the other hand, have guaranteed approval. 

Ethos use an online questionnaire to weed out people who wouldn’t otherwise qualify for term life coverage — for example, if you have a high BMI, serious health conditions, or you work in a risky career. 

For whole life insurance coverage, a set of health-related questions determine how much coverage you can receive and at what rate. 

We evaluated Ethos in comparison to other online life insurance companies based on:

  • Coverage – Amount of coverage available, variety of coverage options
  • Ease of application – Online questionnaire, medical exams, overall user experience
  • Price – Cost of coverage
  • Customer service – BBB reviews/my personal experience with customer service
  • Customer reviews – Customer ratings across major review sites

[wp-review id=”32458″]

What kind of insurance is Ethos?

Ethos offers term life insurance and guaranteed issue whole life insurance coverage. 

Term life insurance provides coverage for a set period of time at a fixed rate, with a specific sum paid to your beneficiaries at the time of your death. 

Whole life insurance provides permanent coverage with a guaranteed payout that builds cash value over time.

What others say about Ethos

Reviews for Ethos life insurance are overwhelmingly positive: 

BBB rating and reviews

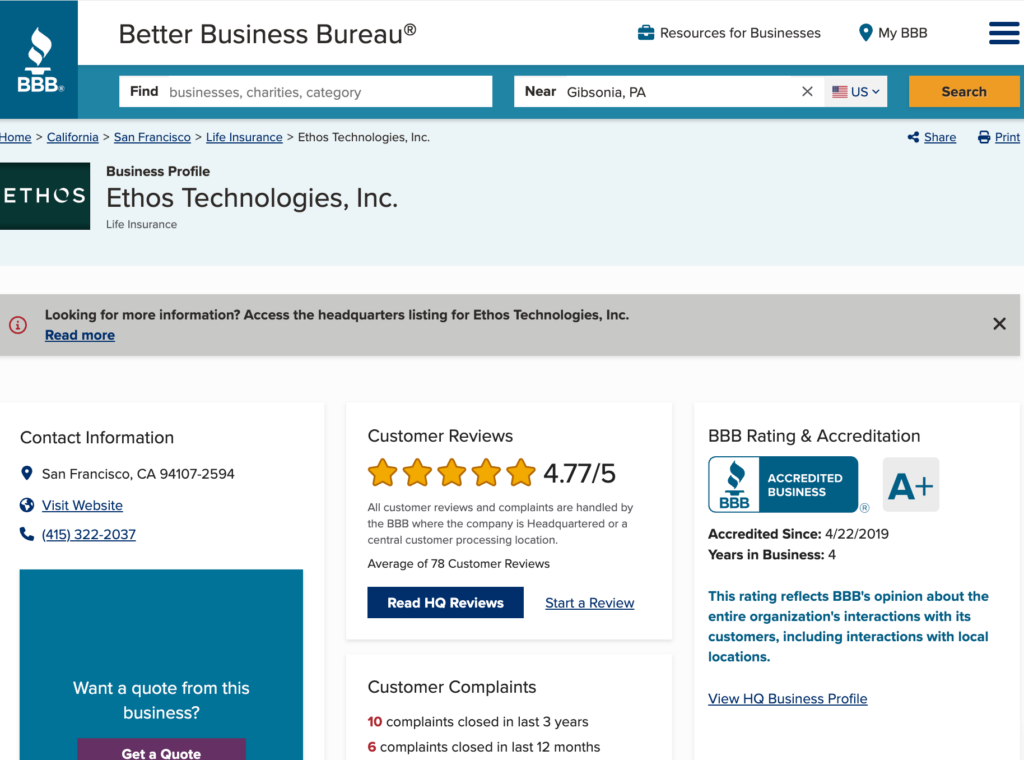
Ethos Technologies, Inc., has an A+ rating with the Better Business Bureau and 4.77/5 stars based on more than 75 customer reviews.

Ethos life insurance review Better Business Bureau page.
5-star Ethos life insurance review posted on the Better Business Bureau.
5-star Ethos life insurance review on the Better Business Bureau.
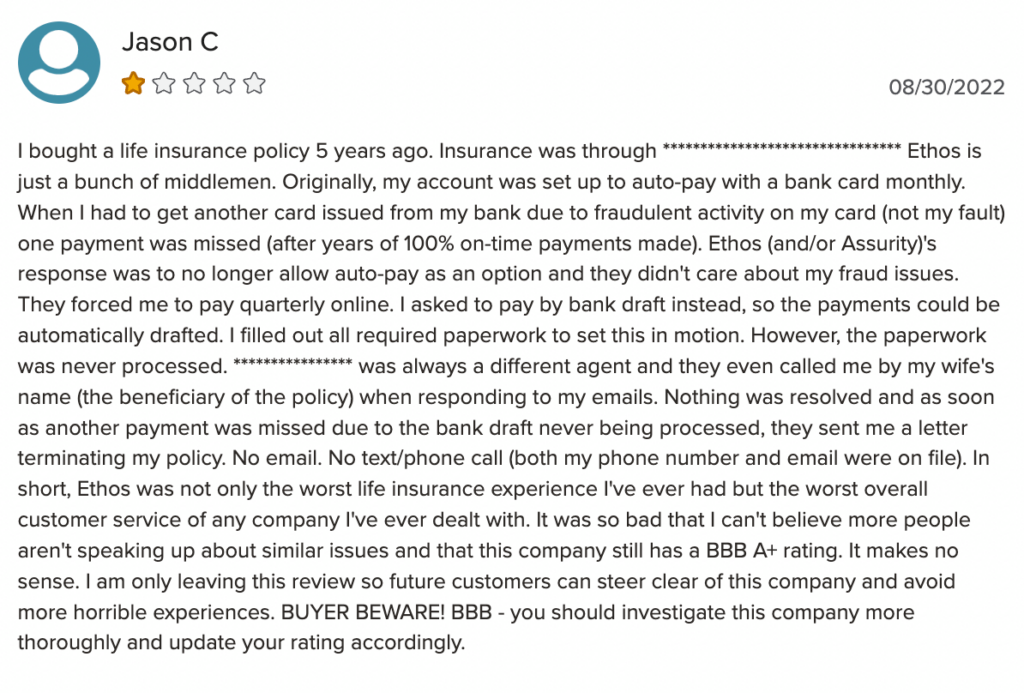
1-star Ethos life insurance review on the Better Business Bureau.

Trustpilot rating and reviews

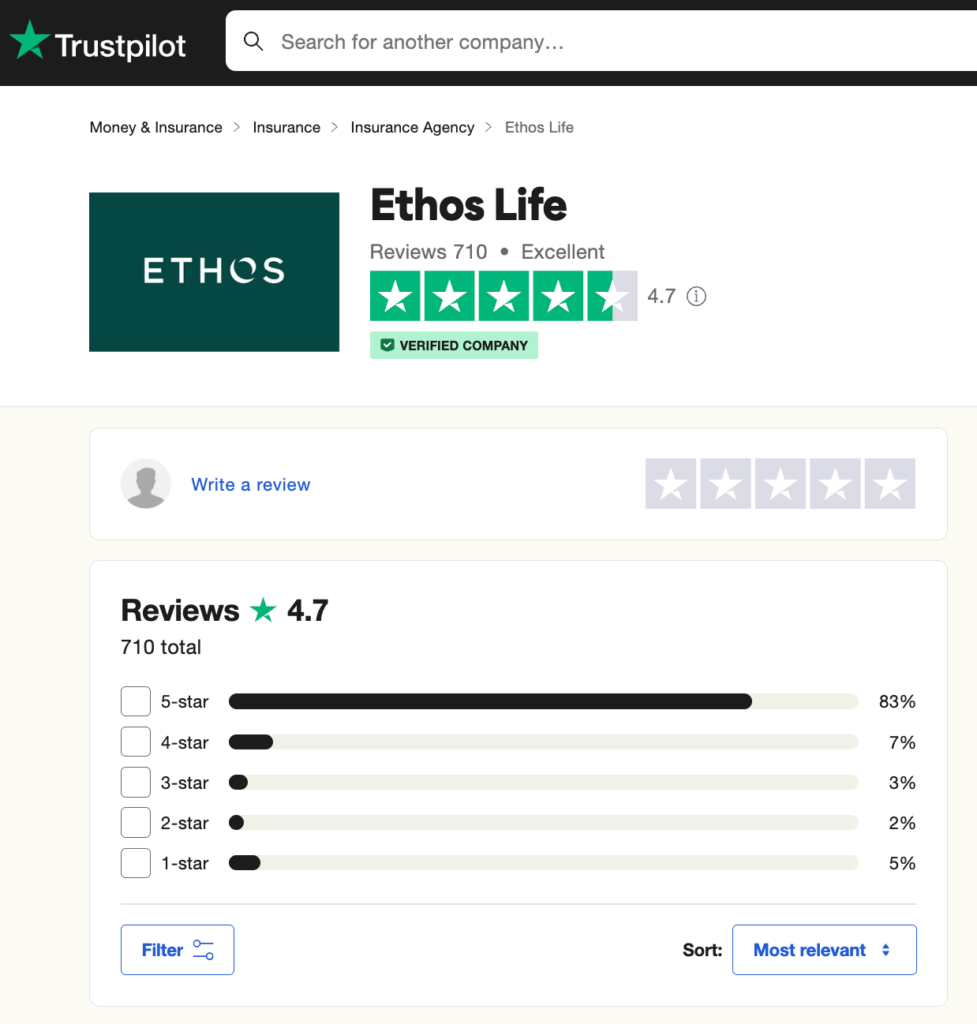
Ethos has 4.7/5 stars based on 740+ reviews on Trustpilot. 

Ethos life insurance review Trustpilot page.
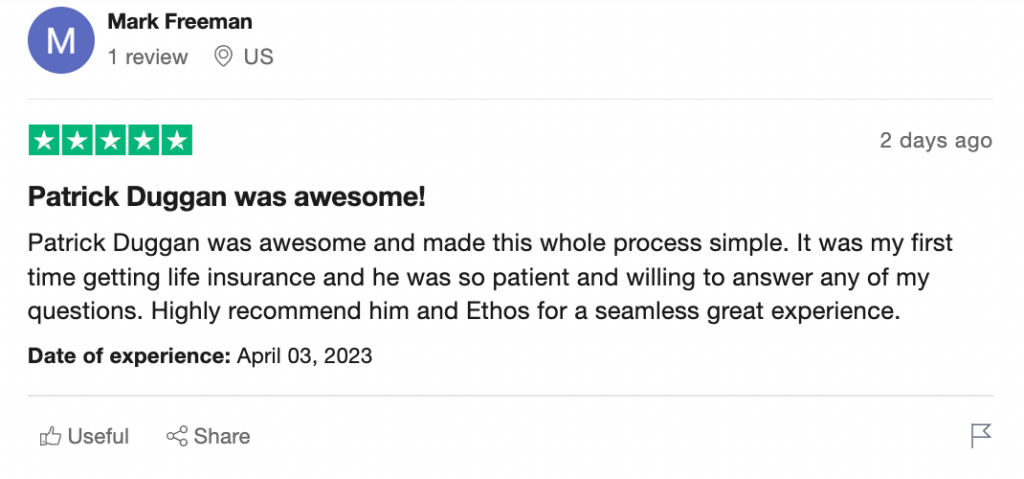
5-star Ethos life insurance review on Trustpilot.
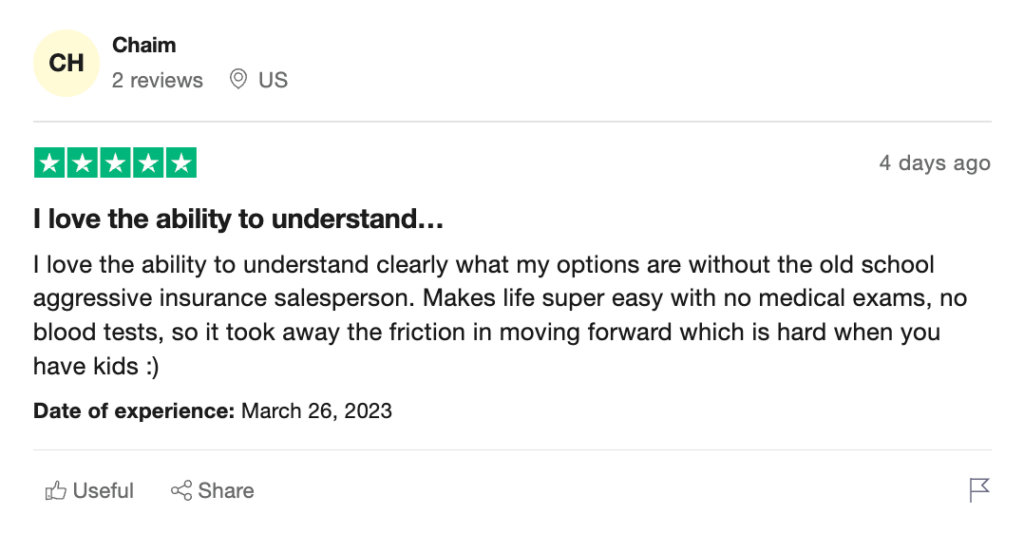
5-star Ethos life insurance review posted on Trustpilot.
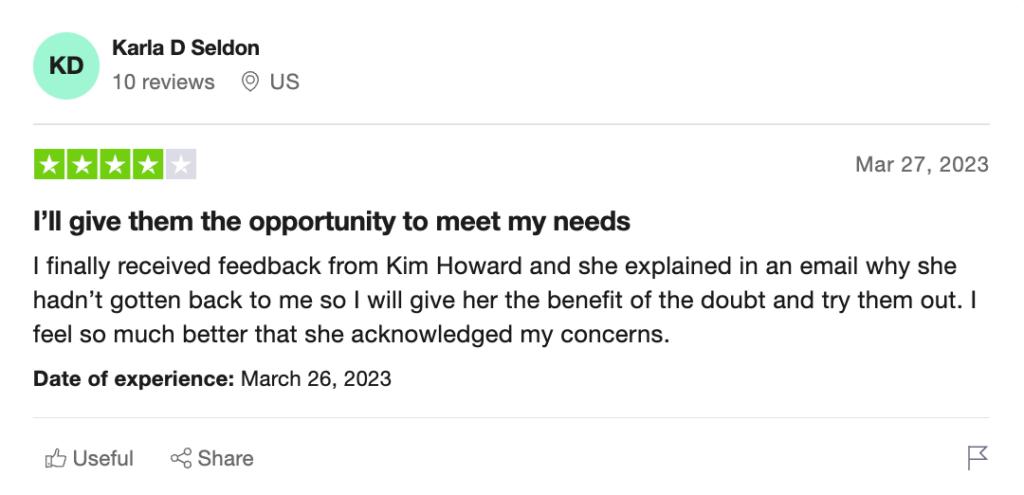
4-star Ethos life insurance review posted on Trustpilot.

What Redditors think about Ethos

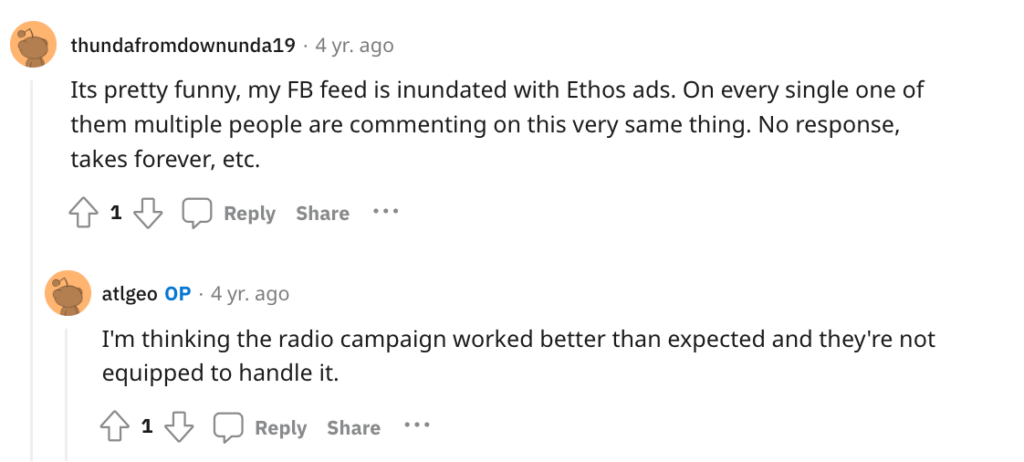
The only posts about Ethos on Reddit are from people thinking about applying for coverage. Responses are limited and are from people who have applied but are still waiting to hear if they’ve been approved for a policy: 

Experience with ethos?
byu/atlgeo inLifeInsurance
Does anyone have any experience with Ethos life insurance?
byu/anonymous-2356 inInsurance
Ethos life insurance review posted on Reddit.

Common complaints

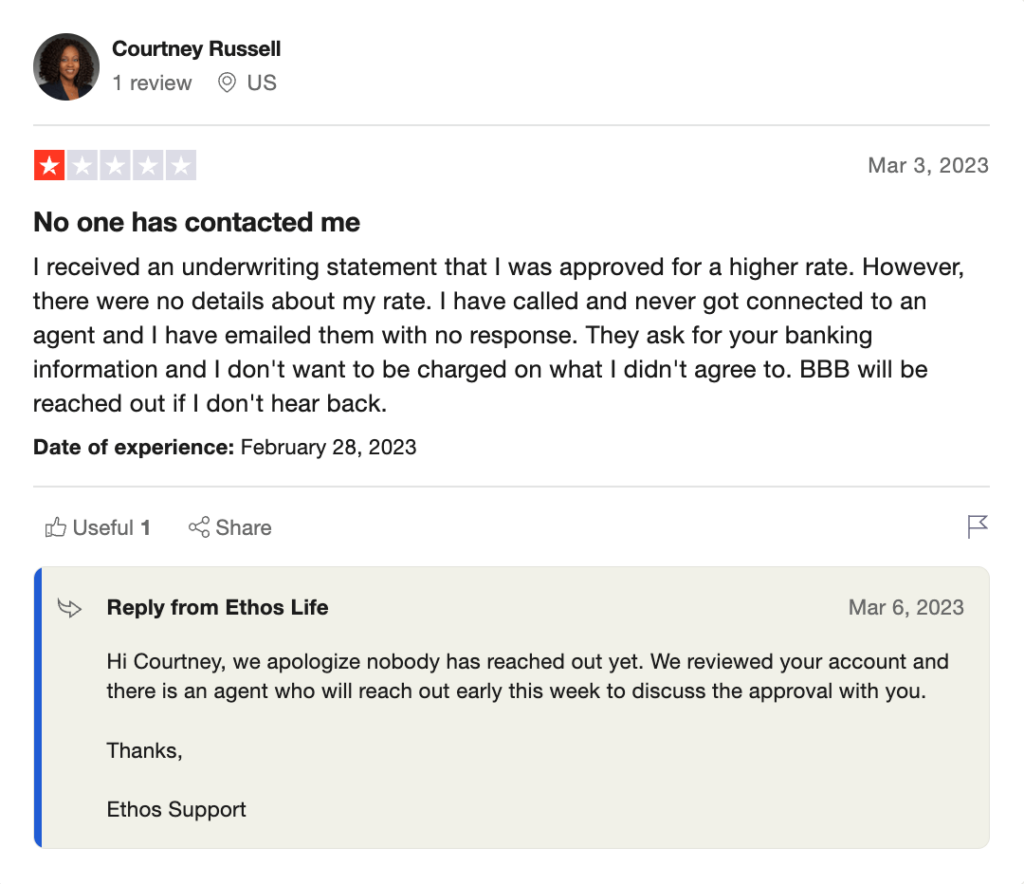
Common Ethos complaints are from people frustrated with the long underwriting process and those who have been unable to reach customer service:

Ethos life insurance review complaint on Trustpilot page.

From my own experience, it was difficult to find Ethos’ contact information on their website. The “Email us” button is at the very bottom of their home page, and there is no publicly listed phone number that I could find. I was only shown a phone number to call once I was rejected for a policy.

For reference, the number they listed was 415-322-1828. I was connected with an agent immediately after selecting the appropriate menu options.

On the other hand, I emailed support@ethoslife.com (which comes up when you click the “Email us button”) with a list of questions and have not gotten a response nearly three weeks later. 

How much does life insurance from Ethos cost?

Ethos term life insurance coverage starts at $7 per month, with policies ranging from $20,000 to $2 million. This rate is based on a 20-year old healthy, non-smoking female for a 10-year term and $100,000 policy.

Whole life insurance policies are for $1,000 to $30,000 in coverage. A 66-year-old healthy, non-smoking female can expect to pay about $27 per month for $5,000 in whole life coverage.

Ethos offers a life insurance calculator to give you a general idea of what you can expect to pay for life insurance coverage from Ethos. This does not take into account your specific answers to its more detailed application questionnaire.

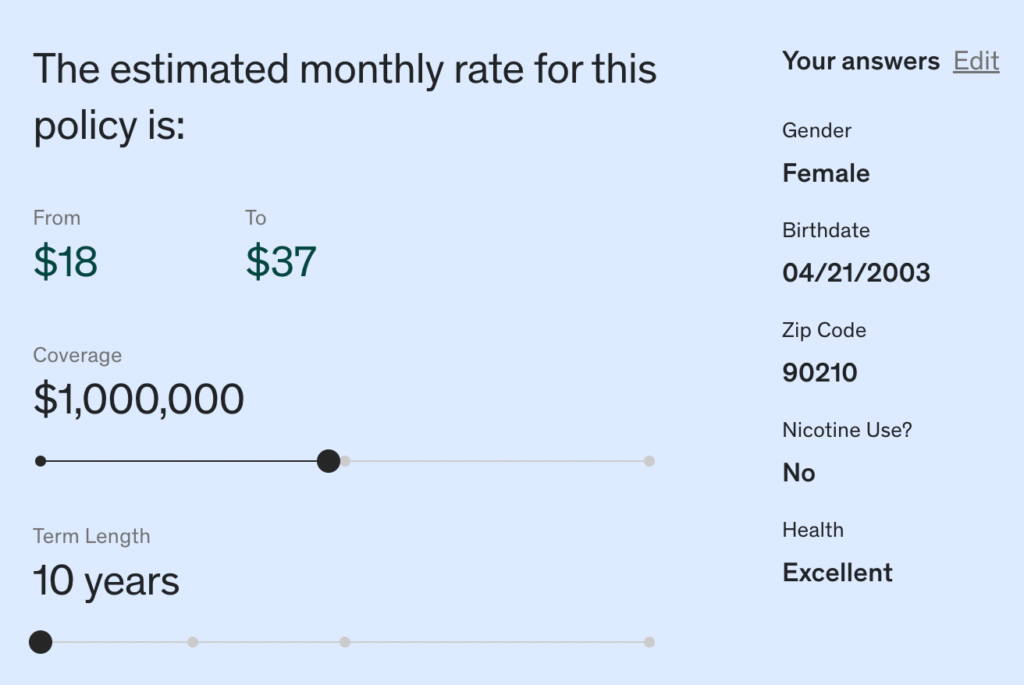
According to Ethos’ calculator, a 20-year-old female with excellent health who doesn’t use nicotine products can expect to pay between $18 and $37 per month for a 10-year policy with $1,000,000 in term life coverage:

Ethos life insurance review estimate for 20-year-old female.

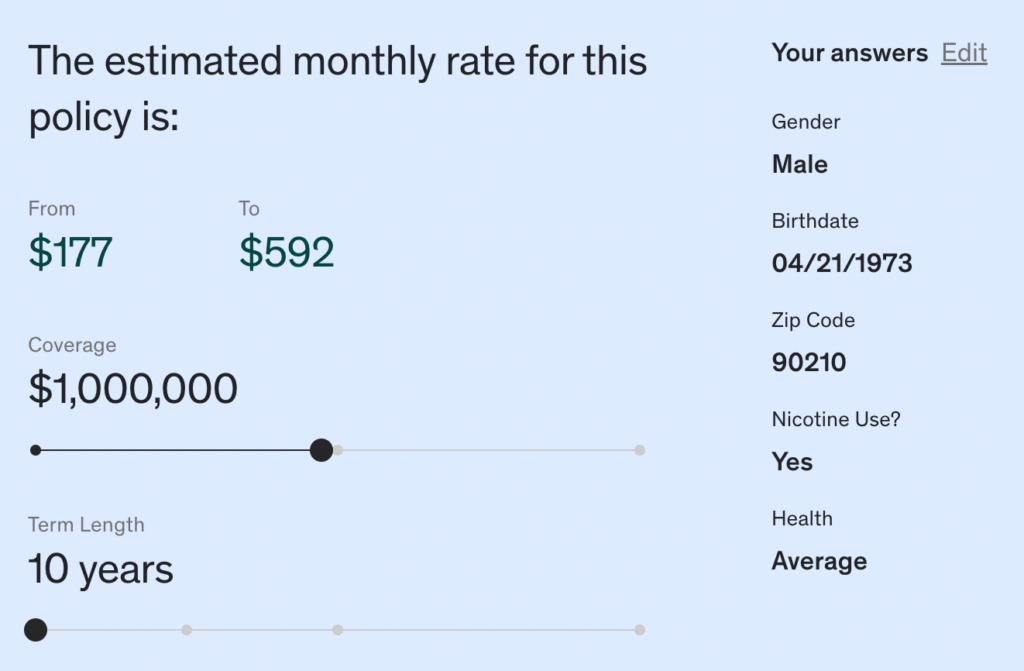
A 50-year-old male with average health who uses nicotine products can expect to pay between $177 and $592 per month for the same policy length and coverage amount:

Ethos life insurance review estimate for 50-year-old male.

Note that this calculator does not tell you whether or not you’d be approved for an Ethos policy but just gives you an estimate of what you can expect to pay if you were. 

How does Ethos life insurance work?

Ethos uses a simple online application process to determine eligibility for term life insurance coverage. Based on your answers to their questionnaire, you’ll either be: 

  1. Instantly denied or approved
  2. Notified via email if you qualify after an underwriting process, which may take anywhere from a few days to several weeks; you may be called to answer more questions about your health and eligibility 

For whole life insurance policies, you are guaranteed approval, but a health questionnaire will determine how much coverage you can receive and how much you’ll pay.

Ethos’ questionnaire requires you to provide your: 

  • Name
  • Contact info
  • Medical history
  • Employment and salary info
  • Mortgage/total debt
  • Beneficiaries 
  • Last four digits of your social security number

If you are approved for a policy, Ethos will pay out your coverage amount — known as a death benefit — to your beneficiaries in the event you die while covered. 

Can’t afford health insurance? 5 health insurance options for single moms

Details about Ethos life insurance policies

If you’re considering an Ethos life insurance policy, here’s what you need to know: 

What policies does Ethos offer?

Ethos’ term life insurance policies are for people ages 20 to 65, with coverage ranging from $20,000 to $2 million. Policies can cover you for 10, 15, 20, or 30 years, though you can’t get a policy that covers you past the age of 80. That means someone who is 65 would only be approved for a maximum 15-year policy. 

Ethos’ whole life insurance policies are for people ages 66 through 85, with coverage that lasts until the end of your life. After you turn 100, your coverage remains in place but you no longer have to pay a monthly premium. 

Who underwrites Ethos insurance?

Ethos administers policies underwritten by major insurance providers: 

  • Legal & General America (est. 1981)
  • Ameritas Life Insurance Corp. (est. 1887)
  • TruStage Financial Group, Inc. (underwriter CMFG Life est. 1935)
  • Senior Life Insurance Company (est. 1970)
  • Mutual of Omaha (est. 1909)

Does Ethos offer riders?

Ethos policies currently only include one rider at no additional cost — an accelerated death benefit, which allows the insured to withdraw a portion of their death benefit upon diagnosis of a terminal illness.

Does Ethos pay out?

Yes. At the time of your passing, your beneficiary will file a claim with your insurance carrier to receive payment in one lump sum, unless Ethos discovers you: 

  • Committed insurance fraud
  • Answered questions within the application dishonestly
  • Died by suicide during the first two years of the policy

Pros and cons of Ethos

These are some of the pros and cons of an Ethos insurance policy: 

Pros

  • A+ BBB rating and 4.7 stars on Trustpilot
  • No medical exams ever
  • Offers both term and whole life insurance
  • Coverage options available for ages 20 to 85
  • Policies underwritten by established insurance providers
  • Life insurance calculator to give you an idea what you might pay before you apply
  • 30-day money-back guarantee. 
  • No cancellation fees or penalties

Cons

  • Difficult to reach customer service — no phone number listed on home page/slow email response time
  • May deny coverage based on your answers to questions about your health, salary, mortgage/debt, and career/lifestyle
  • Underwriting process may take several weeks if you are not instantly approved or denied

Can’t afford health insurance? 5 health insurance options for single moms

Ethos vs. other life insurance companies

Among other online life insurance providers, Ethos stands out because of its: 

  • High customer ratings
  • Term and whole life insurance options
  • Number of available carriers

I compared the estimated cost of an Ethos term life insurance policy for a healthy 20-year-old for a 10-year term at $500,000 in coverage vs. the same policy from competitors Ladder Life. 

Note that each of these calculators did not have the exact same criteria for coverage estimates. For example, Ethos didn’t ask for height/weight like the other calculators, so I chose “excellent” for health status and inputted a weight/height of 5’5” and 110 pounds with no health issues for the other two calculators: 

  • Ethos: $11 to $22 per month
  • Ladder: $33 per month

Bottom line: Ethos is worth considering if you need to buy life insurance

If you are a relatively healthy adult between the ages of 20 and 65 or you are 66 to 85 and want to purchase a whole life insurance policy, Ethos is a reputable insurance provider with affordable coverage options and an easy application process.

Headquartered in New York City and doing business throughout the United States via its website, Abe Mor has one of the largest online presences in the online diamond buyer market.

Founded in 1964 ago by an Israeli diamond cutter of the same name, Abe Mor has 4.8 stars on its Google Business profile and an A+ BBB rating with hundreds of customers praising its easy selling process and fair pricing. Abe Mor buys diamonds of at least .50 carats and competes with Diamonds USA and myGemma, formerly WP Diamonds.

Here’s how Abe Mor stacks up against other top online diamond buyers:

Is Abe Mor legit?

How to sell diamonds to Abe Mor

Pros and cons of Abe Mor

FAQs about Abe Mor

Is Abe Mor legit?

Yes, Abe Mor is a legit diamond buyer that has been in business since 1964. The company has been accredited by the Better Business Bureau since 2016 with an A+ rating and zero customer complaints.

Abe Mor only purchases loose diamonds and diamond jewelry of .50 carats and larger. Abe Mor will also pay you for the gold and platinum content of your ring if it’s set with an eligible diamond or diamonds.

If your jewelry does not contain a diamond — or its diamond is smaller than 0.5 carats — we suggest selling instead to Diamonds USA.

Diamonds USA has an A+ BBB and buys all diamonds, gold, and silver, paying within 24 hours. Diamonds USA buys all diamonds of any size, including diamond earrings, diamond rings, and diamond tennis bracelets.

How to sell your diamonds to Abe Mor

While Abe Mor does give estimates for loose diamonds and diamond jewelry in person and over the phone, the process to sell online works like this: 

  1. On the next page, click “Request an estimate” to fill out a short form, including your name, contact information, and a description of your loose diamond or diamond jewelry. You can also upload images to the site, as well as a grading report, if you have them. Though a grading report, or diamond certification, is not required to sell to Abe Mor, sharing such a report can help the company give a  more accurate initial offer. The Abe Mor site is also mobile-friendly if you want to upload photos and attachments from your phone. 
  2. You will receive an initial offer for your item within 1 to 2 business days via email and text (if you check the box to receive a text offer). 
  3. If you reject the offer, then Abe Mor promises to ship your item back to you immediately for free via FedEx trackable shipping. If there are sufficient details provided with the initial submission, you may be able to negotiate this initial estimate, either via email or over the phone, though what you are ultimately paid will be based on the in-person appraisal. 
  4. If you choose to move forward, Abe Mor will send you a trackable prepaid FedEx shipping kit, which should arrive at your home within 2 to 3 business days. From there, you can schedule a pickup at your home or drop off at a FedEx location. Packages sent to Abe Mor are insured by AIB Express Logistics in transit for up to $50,000 — though more insurance can be requested if needed. Packages are not addressed to Abe Mor but delivered to AIB’s secure location and brought to Abe Mor by armed guards. Once in Abe Mor’s possession, your diamond is insured by AIB, and packages are opened under video surveillance. You’ll be emailed a tracking number to track your shipment. Shipping and insurance is always free.
  5. Within 48 hours of receipt of your item, Abe Mor’s in-house team will conduct a final appraisal and you will receive an official offer via email — or via phone if an explanation is needed. You can negotiate before accepting or rejecting this offer. Upon request, Abe Mor will send items for GIA certification. 
  6. If you accept the offer, you will likely receive payment within 3 business days — either by check (which is mailed via FedEx 3rd day delivery) or via wire transfer. Upon request, Abe Mor will overnight a check for 24-hour delivery.
Abe Mor reviews submission form.

Pros and cons of Abe Mor

These are some of the pros and cons of selling your diamonds and diamond jewelry with Abe Mor.

Pros

  • A+ BBB Rating and zero customer complaints
  • Diamond grading reports are not required, though accepted
  • Shipping and insurance is always free
  • Items insured by AIB Insurance for up to $50,000, with additional insurance available if necessary
  • Modern, clean and easy-to-use website

Cons

  • Appraisals are conducted by in-house Abe Mor staff, though you can request GIA authentication. If GIA gives the same grading determined by Abe Mor and you decide not to sell to Abe Mor, you must pay for the certificate. Otherwise, Abe Mor will absorb the cost. 
  • Only accepts diamond jewelry at least 0.5 carats in size
  • May reject your diamonds if it does not need them in its inventory
  • Typical time from shipment to payment is longer than other sites like DiamondsUSA that promise 24-hour payment, though Abe Mor will overnight a check upon request
  • Pays within 2 to 4 days upon acceptance of an offer

Abe Mor reviews

While Abe Mor doesn’t have any customer reviews on major review sites like the Better Business Bureau and Trustpilot, it does boast 4.9 stars on its Google Business profile based on about 403 reviews: 

Abe Mor review from January 2024.
Abe Mor reviews posted on Google.
1-star Abe Mor reviews posted on Google.
Response to 1-star Abe Mor review posted on Google.

Abe Mor BBB

Abe Mor has an A+ rating from the Better Business Bureau, where it has been accredited since 2016. While the company has no complaints on the BBB site, it also has no customer reviews. This suggests that while an excellent track record, Abe Mor may not have the volume of business that other diamond buyers have.

Abe Mor vs Worthy

Abe Mor purchases diamonds from you outright, based off of a single, in-house appraisal of your jewelry. Worthy, on the other hand, is an online marketplace that does not purchase your item outright (though they do offer an estimate of the value of your item). 

Instead, the final sale price of your item on Worthy is dependent on the bids it receives from the buyers using Worthy’s auction platform.

Abe Mor only buys loose diamonds and diamond jewelry, so any other jewelry or gemstone is not eligible for selling to Abe Mor. Worthy’s marketplace does welcome fine jewelry with or without diamonds, as long as it will sell for $1,000 or more, especially branded jewelry like Tiffany and Cartier.

Worthy has a B+ BBB rating, while Abe Mor has an A+ BBB rating. The whole process of selling your jewelry with Worthy.com takes 10 to 14 days from creating an account to getting paid — and some items do not sell. With Abe Mor, you can expect the process to take about 7 to 10 days from the time you request an online estimate, depending on how quickly you mail in your items.

Abe Mor vs Diamonds USA

If the jewelry you’re selling doesn’t include diamonds or doesn’t meet Abe Mor’s minimum 0.5 carat weight requirement, A+ BBB-rated Diamonds USA (and its sister site CashforGoldUSA) is an excellent alternative, since they do not have a minimum carat weight. 

Diamonds USA also pays exceedingly fast — within 24 hours of accepting their offer — while Abe Mor’s process will take about a week.

Diamonds USA is our go-to recommendation if you are selling gold, any-sized diamond or gemstone jewelry, since they do not have a minimum value and have high customer service. Diamonds USA and its sister sites buy all precious metal, gold, silver and gemstones.

Abe Mor vs local jewelry stores

If you’re looking to quickly sell diamonds or diamond jewelry, a local jewelry store may be your best option, since Abe Mor takes as much as 10 days to ship, evaluate, and submit payment.

That said, you may get more money from Abe Mor. In general, local jewelry stores face less competition than online buyers, and also have higher overhead, and therefore have less incentive to offer as much for your diamond. 

Find local jewelry shops to sell your diamonds: 

google-maps-usa-image

Abe Mor vs pawn shops

Pawn shops typically pay between 25% and 60% of the retail value of your item, but pay immediately and in cash. You can learn here what pawn shops buy, how pawn shops work, and how to pawn jewelry.

Again, Abe Mor will likely pay you more, but it will take longer to receive your money. 

FAQs about Abe Mor

Thinking about selling with Abe Mor? Here’s what you need to know:

How quickly will you get your money if you sell to Abe Mor?

If you accept Abe Mor’s offer, they’ll send you a check via FedEx 3rd day delivery. Wire transfers typically appear within 2 to 4 business days.

Is Abe Mor legit?

Yes — Abe Mor is a legit online diamond buyer and seller, with more than 50 years of industry experience and an A+ rating from the Better Business Bureau. 

Bottom line: Abe Mor is a legit way to sell diamonds

If you have loose diamonds or diamond jewelry with a diamond 0.5 carats or larger, Abe Mor is a reputable buyer with more than 50 years of experience in the industry. 

Based on hundreds of 5-star reviews across Google and Yelp, and an A+ Better Business Bureau rating, Abe Mor offers a safe, easy, and fairly quick process to sell your diamonds without leaving your home (if you schedule a FedEx pickup). Customers also frequently praise Abe Mor’s transparency: 

5-star Abe Mor reviews posted online.
Abe Mor reviews posted online.

However, if you have jewelry without diamonds or with diamonds smaller than 0.5 carats, we recommend selling to Diamonds USA, which offers: 

  • Payment within 24 hours of receipt of item
  • A+ Better Business Bureau rating
  • Simple, straightforward selling process
  • Cash for all gold, silver, platinum, and diamond items
  • Expert appraisals
  • 100% satisfaction guarantee, including price-matching and free, insured returns.
  • Free insurance up to $5,000 — as well as up to $150,000 in some cases
  • 10% bonus above the estimate if you send in your item within 7 days

Get a free quote today from Diamonds USA >>

Is Abe Mor legit?

Yes, Abe Mor is a legit diamond buyer that has been in business since 1964. The company has been accredited by the Better Business Bureau since 2016 with an A+ rating and zero customer complaints.

If you’re a single mom in Alabama struggling to make ends meet, keep reading for resources that help with: 

Statistically, families benefit most with cash assistance (vs through benefits programs).1 Here is our guide to single mom grant programs, including our own.

Every month, I give out $500 cash to one single mom struggling with money, health, stress, child care, illness or loneliness — no strings attached. 

Qualifications are simple:

1. You’re a single mom.

2. You need the money right now.

Fill out this form to apply:

(Note that the figures and information in this post are current as of publication date.)

Number of people in family/householdAnnual income
1$15,960
2$21,640
3$27,320
4$33,000
5$38,680
6$44,360
7$50,040
8$55,720

For families/households with more than 8 people, add $5,680 for each additional person.each additional person.

You can also look up your area median income (AMI) here.

Emergency cash for low-income families in Alabama

If you need cash to pay bills, buy gas, feed your family, or for any other reason, these resources can help: 

The Family Assistance Program in Alabama

The Family Assistance Program in Alabama — also known as Temporary Assistance for Needy Families (TANF) in other states — gives cash to families in need for a maximum of five years. Families must have at least one child under 18 or a full-time student aged 19 or younger. 

The maximum amount a family can earn depends on family size:

Family SizePayment Amounts
1$165
2$190
3$215
4$245
5$275
6$305
7$335
8$365
9$395
10$425
11$455
12$485
13$515
14$545
15$575
16$605

Qualifications:

  • Must be a U.S. citizen 
  • Must live in Alabama
  • Caregivers must be a parent or close relative of eligible children
  • Parents should comply with child support guidelines, if necessary
  • Parents must have a job or be able to look for work
  • Must not have a net monthly income that equals or is more than the benefit amount (table above)

How to get help:

More emergency cash help in Alabama: 

Single moms in Alabama can visit 211.org or dial 2-1-1 to ask for assistance.

Check out these posts for more ways to get emergency cash: 

These are some more tips for getting cash quickly: 

Housing help for single moms in Alabama

If you need help finding a place to live or paying your rent/mortgage, these programs can help: 

Rental assistance in Alabama

There are multiple programs in Alabama to help renters find housing and pay their rent:

Public Housing and Housing Choice Vouchers (Section 8)

The U.S. Department of Housing and Urban Development (HUD) gives vouchers to Alabama individuals and families with low-income so they can pay rent. Maximum rent allowance varies by county.

Qualifications:

HUD determines how much a household gets using their income and family size. Visit the HUD website to find specific income information based on your county.

How to get help: 

Emergency Solutions Grant Program

The Emergency Solutions Grant Program (ESG) in Alabama aims to prevent homelessness by helping families pay their rent or find adequate housing quickly. 

Families may also get financial help for moving, paying utilities, and legal assistance. ESG provides funds directly to community agencies to assist families in need of help.

Qualifications:

Qualifications for rental assistance and other services offered by the program vary by the state agency receiving ESG funds. 

How to get help:

Call ADECA at 334-353-0288.

Mortgage assistance in Alabama

If you need help buying a home in Alabama, these programs can help: 

Alabama Housing Finance Authority Programs

The Alabama Housing Finance Authority (AHFA) helps people in Alabama become homeowners with low-cost mortgages. The loans are fixed for 30 years. Some homebuyers may receive down payment assistance.

AHFA offers the following programs:

  • Step Up: Eligible homeowners can get a low-interest mortgage and down payment assistance through this program. Homebuyers can get 4% of the sale price, up to $10,000 for down payment assistance. 
  • Affordable Income Subsidy Grant: This grant program gives funds to eligible homebuyers to help them pay closing costs on a new home.
  • Mortgage Credit Certificates: This program offers a significant tax break for homebuyers to help them have more cash available to pay their mortgages. 

Qualifications:

Eligibility varies by program:

  • Mortgage Credit Certificate users must be first-time homebuyers or not have owned a home in the last three years
  • Step Up participants can not have income above $130,600, have a credit score of at least 640, and have a debt-to-income ratio of 45% or lower
  • To be eligible for an Affordable Income Subsidy Grant, homebuyers must also qualify for the Step Up program                                         

How to get help: 

Call AHFA at 800-325-2432 or contact homebuyerinquiries@ahfa.com to find a participating lender in your area.

Hope Credit Union Home Loans

Hope Credit Union Enterprise Corporation offers various loan options for first-time homebuyers, those looking to refinance, and those denied lending because of poor credit. Hope has specific loan products that cater to low- to moderate-income families:

  • FHA loan – Ideal for families with low to moderate income who cannot afford a large down payment
  • Hope loan – An affordable housing loan from Hope Credit Union you can apply for even if your credit score is as low as 580

Hope has loan options for any income level and credit standing.

Qualifications:

  • Alabama resident

How to get help:

Check today’s mortgage loan rates >>


Homeless assistance in Alabama

Supportive Housing Program in Alabama

Families needing safe, affordable housing can reach out to the Supportive Housing Program. The program provides funds to community agencies to develop affordable housing projects for in-need families. 

Qualifications: 

Each agency outlines its eligibility criteria to receive assistance. 

How to get help: 

Call AHFA at 800-325-2432 to find a Supportive Housing Program in your area.

Individual and Households Program

The Individuals and Households Program (HP) in Alabama is sponsored by FEMA and provides several housing-related services to Alabama families in need, including:

  • Money for a rental
  • Temporary housing
  • Housing repairs
  • Emergency damage repairs
  • Semi-permanent or permanent house construction. 

Qualifications:

The qualifications for HP vary by specific program. For instance, families seeking temporary housing must currently own a home damaged by disaster. Homeowners may also be required to carry flood insurance if they’re getting their home replaced by the program.

How to get help: 

Contact your county’s Alabama Emergency Management Agency office.

More housing help: 

Electric bill assistance in Alabama

If you are struggling to pay your utility bills in Alabama, check out the following programs:

Low-Income Home Energy Assistance Program (LIHEAP) in Alabama

LIHEAP is a federal program that helps Alabama residents with low incomes pay for their heating and cooling bills. The program is split into 18 regions, each with an agency that oversees the program for its included counties.

Qualifications:       

  • U.S. citizen
  • Alabama resident
  • Income that doesn’t exceed 150% of FPL
  • Each agency may also establish its own eligibility criteria

How to get help:

Contact your region’s LIHEAP agency for assistance.

Weatherization Assistance Program (WAP) in Alabama

WAP helps low-income households pay for repairs or upgrades that could save them money on energy bills long-term. Some services available through the program include:

  • Sealing ductwork
  • Repairing drafty windows
  • Installing insulation
  • Placing LED bulbs in the home

Qualifications:

  • U.S. citizen
  • Resident of Alabama
  • Not exceed 150% of FPL with household income

How to get help:

Call 334-242-4909 or contact your region’s office.

Project SHARE

Project SHARE is a statewide program in Alabama that organizations like the American Red Cross and Salvation Army help facilitate in local communities. Funds from the program go directly to energy companies to assist customers in need of help with electricity bills. 

Qualifications:

Each assisting organization sets its own eligibility requirements for the program. In most cases, the head of household must be legally disabled to receive assistance, but some agencies also provide funds to low-income households.

How to get help:

Contact your nearest Salvation Army or American Red Cross office for more information about Project SHARE.

More electric bill help: 

Free money to help pay bills

Medical insurance and dental help for single moms in Alabama

Single moms in Alabama can apply for the following programs to get help paying for health and dental services.

Health Resources & Services Administration (HRSA) in Alabama

HRSA, an agency of the United States Department of Health and Human Services, gives funds to Alabama to make health care more accessible to people who need it most, such as rural households living far from quality health care services. 

HRSA funds important health-focused programs in the state, like the Small Rural Hospital

Improvement Program and the Rural Health Clinic Vaccine Confidence Program. Funds can also move from each program or agency to patients needing care.

Qualifications: 

Eligibility varies by each program or health center based on community need.

How to get help:

Call the Region 4 HRSA office at 404-562-4140.

Alabama Medicaid

Medicaid in Alabama pays for multiple health and dental-related services for families with low incomes. The state offers separate Medicaid programs for children, pregnant women, disabled individuals, and parents and caretakers.

Depending on the specific Medicaid program, single parent families may get help with the following costs:

  • Hearing and vision screenings and treatments
  • Routine healthcare
  • Prescriptions
  • Family planning and maternity services
  • Hospital services
  • Ambulatory care
  • Mental health services

Qualifications:

Eligibility varies by program. However, all programs require households to meet income guidelines and be U.S. citizens and residents of Alabama:

Family size Monthly income
1$1,654
2$2,228
3$2,802
4$3,377
5$3,951
6$4,525
7$5,100
8$5,674
Each additional personAdd $575

Parents and caretakers must have qualifying children under 19 to receive Medicaid for themselves or their children.

How to get help:

Apply on the Insure Alabama website.

Alabama ALLKids

Alabama ALLKids is the state’s version of the Children’s Health Insurance Program (CHIP), a federal program that provides health care coverage to children whose families don’t qualify for traditional Medicaid because of their income. 

ALLKids allows children to receive Medicaid if their family’s income doesn’t exceed 300% of the FPL. 

The program has two versions:

  • Fee: Families pay an annual premium of $104
  • Low Fee: Families pay an annual premium of $52

Families in either group pay no more than 5% of their annual income for out-of-pocket expenses.

Qualifications: 

  • U.S. citizen or qualified non-citizen
  • Alabama resident
  • Child must be under 19
  • Child must not have or be eligible for other insurance, including Medicaid
  • Meet income guidelines based on family size

How to get help: 

Donated Dental Services in Alabama

Single moms needing medically necessary dental care may receive treatment from dental professional volunteers with the Donated Dental Services program.

Qualifications: 

Eligible recipients must be permanently disabled or have a doctor’s recommendation for medically necessary dental care. Veterans may also qualify.

How to get help: 

Apply on the Dental Lifeline Network website.

Free dental clinics in Alabama

Some dental clinics in Alabama provide charitable services to help families with low incomes get the dental care they need. The Alabama Dental Association hosts a list of dental clinics that provide these services to eligible households.

Qualifications: 

Each individual clinic in Alabama sets its own eligibility requirements. 

How to get help: 

Find a nearby free dental clinic or contact community dental clinics to see if they have low-cost services for your family.

More medical/dental help: 

Food help for low-income families in Alabama

A number of federal and state food and nutrition programs are available across the state:

Supplemental Nutrition Assistance Program (SNAP) in Alabama

SNAP is a federal program that gives eligible households money to buy food, including fresh meat, fruit, vegetables, and pantry items. The program pays families on an EBT card that they can use at local grocery stores. 

Recipients must recertify each year and complete a six-month review to continue receiving benefits. Depending on income, a family of four can receive a maximum monthly benefit of $939.

Qualifications:

  • Family members must be U.S. citizens with valid Social Security numbers
  • Must be a resident of the county in which you apply
  • Have a job or be eligible for and willing to work
  • Not exceed income limits:
Household SizeGross Income LimitsNet Income Limits
1$1,473$1,133
2$1,984$1,526
3$2,495$1,920
4$3,007$2,313
5$3,518$2,706
6$4,029$3,100
7$4,541$3,493
8$5,052$3,886
Each additional person$512$394

How to get help: 

Apply on the MyDHR website or print an application to take to your nearest office, which you can also locate on the MyDHR website.

Women, Infants, and Children (WIC) in Alabama

This federal program extends to pregnant women and women with young children in Alabama to:

  • Provide resources, education, and nutritional support 
  • Help women buy infant formula 
  • Give women breastfeeding supplies and support
  • Support unique dietary needs 

Children are eligible through age 5.

Qualifications:

  • Low-income, pregnant, breastfeeding, and postpartum women, for up to one year postpartum
  • Women up to six months postpartum who are not breastfeeding
  • Infants and children under 5 years old, including foster children
  • Low-income sole provider parents of children under age of 5 who are at nutritional risk and who are below 185% of FPL
  • If you are currently receiving Medicaid, Temporary Assistance, or Food Assistance help, you are also eligible for WIC

How to get help: 

Call your nearest Alabama Department of Public Health office. Applicants must bring the children they’re applying for along with identification, proof of residency, and proof of income.

National School Lunch Program (NSLP) and School Breakfast Program

Schools across the state of Alabama participate in NSLP and School Breakfast programs to help their students get affordable and nutritious meals at school. Students can qualify for free or reduced lunches and breakfasts based on their family income. 

Qualifications: 

Eligible Alabama families must have income within the Federal Income Eligibility Guidelines.

How to get help: 

Contact your child’s school for an application.

Child Nutrition Program in Alabama

Families with school-age children can receive nutritious lunches during summer break from this program, which is a cooperative effort from the U.S. Department of Agriculture and the Alabama State Department of Education.

Qualifications: 

  • Be an Alabama resident
  • Be a parent or primary caregiver of a school-age child

How to get help: 

Complete an online application on the Alabama State Department of Education website. 

Alabama food banks

Single moms can sign up to receive food from food banks, which is usually donated by community members and agencies or federal organizations.

Qualifications: 

Each food bank sets its own eligibility requirements.

How to get help: 

Locate your nearest food bank on the Feeding Alabama website.

More food help: 

Child care help for low-income families in Alabama

If you need help paying for child care so you can work, these Alabama programs can help:

Alabama Head Start and Early Head Start

The national Head Start program gives children ages 3 to 5 the opportunity to attend preschool for free. Early Head Start in Alabama is a bridge program for pregnant women and parents with children under age 3 to receive developmental support, guidance, and services until they’re ready to transition to Head Start. 

Qualifications: 

  • Have children from 0-3 for Early Head Start and 3-5 for Head Start
  • Income within the FPL
  • Families receiving public assistance (TANF, SNAP, etc.) may also qualify without needing to prove income

How to apply: 

Subsidized Child Care Program in Alabama

Single moms who need child care for work can receive low-cost or free child care, depending on their income, through this program. Parents can also use subsidized care to attend job training programs and school.

The Alabama Department of Human Resources pays program subsidies directly to managing agencies to distribute to child care centers for eligible children. Families pay copays between $0-$39 each week, depending on their income.

Qualifications:

  • Be a resident of the Alabama county in which you apply
  • Be the parent or primary caregiver for a qualifying child
  • Meet the income guidelines for an initial application

How to get help:

Download an application from the Alabama Department of Human Resources and bring it to your nearest office, or call 334-242-1425 or 866-528-1694.

More child care help

Education help for single moms in Alabama

If you’re a single mom who wants to further her education, here are some helpful resources: 

Get a GED in Alabama

Single moms in Alabama who have not completed high school can pursue a GED for an equivalent certificate to a high school diploma. The Alabama Community College System offers free GED exams for qualifying individuals who pass its practice exam. Otherwise, the four-part exam costs $120.

Test-takers must be 18 years of age, or 16 or 17 if they have parental permission and permission from the school district where they live. 

Grants and scholarships in Alabama

The Alabama Commission on Higher Education (ACHE) funds scholarships, grants, and other educational assistance programs for Alabama residents:

  • Alabama Student Assistance Program (ASAP) funds grants up to $5,000 for students based on their financial need
  • Alabama Student Grant Program works with state colleges and universities to offer up to $3,000 per year to students needing financial aid
  • Minority Doctoral Program helps doctoral students who are people of color receive financial assistance and career resources

Interested degree-seekers should fill out the FAFSA to determine their financial need and assistance eligibility before contacting the ACHE to apply.

Alabama Possible

Alabama Possible is a nonprofit organization that works around the state to help individuals attend college and avoid economic hardship. It currently offers several programs to increase college education in the state and help residents find cash assistance for college. 

Qualifications: 

Qualifications vary by program.

How to get help: 

More education help: 

Employment help for single moms in Alabama

Workforce programs in Alabama provide training and assist with employment:

Unemployment Benefits from the Alabama Department of Labor

Unemployment benefits help single moms in Alabama receive money for weeks they were unemployed, laid off, or had reduced hours at their jobs. 

Qualifications: 

  • Alabama resident
  • Unemployed, laid off, or had a reduction of hours at a current job
  • Able to look for employment each week
  • Meet minimum earning requirements

How to get help: 

File a claim online through the Alabama Department of Labor.

AlabamaWorks!

AlabamaWorks! provides job-focused resources to students and workers in Alabama. Single moms can use the website to search for jobs, locate nearby training opportunities, or find virtual career fairs and workshops to enhance their skills and employability.

How to get help: 

Visit the AlabamaWorks! website and navigate to the I’m a job seeker or I’m a student section, depending on your situation.

American Job Centers in Alabama

Alabama single moms can use the American Job Center portal to locate suitable jobs, find job training opportunities, and get career counseling to help them continue earning for their families.

How to get help: 

  • Search for a location on the American Job Center website
  • Call 877-872-5627 
  • Email info@careeronestop.org 

More employment help: 

Charity organizations in Alabama

There are a number of charitable organizations throughout Alabama that offer support to single moms:

Women’s Foundation of Alabama

This organization helps Alabama women and mothers meet various needs and break the cycle of poverty. The Women’s Foundation of Alabama invests in community programs that:

  • Advocate and support women
  • Provide financial assistance
  • Research community needs to help women and their families

Qualifications: 

Eligibility for funded programs is determined by the agency or program receiving funds from the Women’s Foundation of Alabama.

How to get help: 

Call 205-326-4454 to ask about funded programs in your area.

The Salvation Army of Alabama

The Salvation Army of Alabama helps local communities across the state get the support they need through:

  • Financial assistance
  • Donations
  • Shelter
  • Emergency help
  • Holiday gift giving
  • Food
  • After-school programs
  • Job search and training
  • Help with domestic abuse situations

Qualifications: 

Salvation Army locations in Alabama can create their own programs based on community need and determine their eligibility requirements for each program.

How to get help: 

Visit the Salvation Army website to find your local chapter. 

United Ways in Alabama

The United Way helps people and communities all over the world access what they need to live healthy, safe, and happy lives. The organization has locations in Alabama to assist local communities with better educational opportunities, financial support, and disaster relief.

How to get help: 

Locate your nearest United Way office in Alabama.

SOURCES

  1. “The Long-Term Impacts of Cash Assistance to Families,” by Kevin Werner, The Urban Institute, Jan. 31, 2024 https://www.urban.org/research/publication/the-long-term-impacts-of-cash-assistance-to-families


Not your state? Select yours here: