scroll top

Somewhere between the VHS tapes nobody owns a player for anymore and the fast food toys still rattling around in a junk drawer, there’s a decent chance you’re holding onto something a Disney collector would pay real money for. The 1990s were Disney’s second golden age, Aladdin, Beauty and the Beast, The Lion King, Toy Story, and a wall of Happy Meal tie-ins that came with almost every animated release. Most of it got thrown out or donated once the kids grew up.

What’s left over has turned into a genuine collector market, and it isn’t limited to sealed grails sitting in a climate-controlled closet. A lot of it is the ordinary stuff: the VHS tape still in the cabinet, the fast food toy still in its bag, the plush animal still on a shelf. Condition and completeness decide almost everything here, so the same toy can be worth three dollars or three hundred depending on whether the box survived and whether a kid ever got their hands on it.

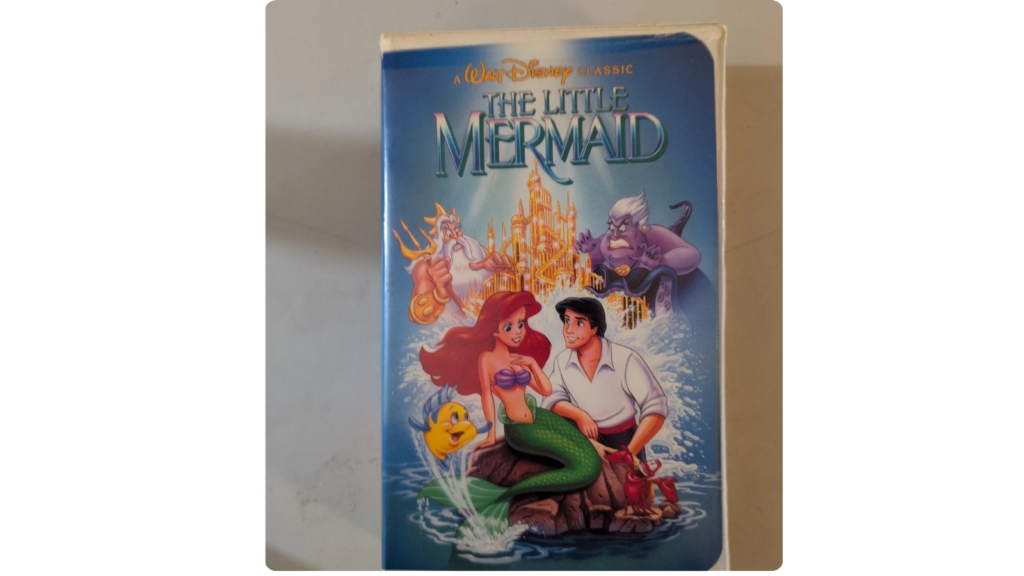
1. The Little Mermaid original “banned” cover VHS
The Little Mermaid VHS
Image Credit: Joe Saint Finds via eBay

Disney’s first Black Diamond release of The Little Mermaid hit shelves in 1990 with cover art showing a golden castle in the background, complete with a spire that a lot of people noticed looked exactly like a certain body part. A single customer complaint was enough to get the tape pulled and reprinted with safer artwork, which means only a narrow window of stock ever went out with the original design.

Clean copies with the uncorrected cover typically bring around $300 in today’s market, and factory sealed examples with the shrink wrap and price sticker intact can push well past that. Opened, played tapes with the same cover are worth far less, usually closer to the low double digits, since the artwork is the entire story here and playback quality doesn’t factor in.

Check the spine for the small black diamond logo before getting excited, since plenty of ordinary Little Mermaid VHS reprints exist with the corrected cover and are worth next to nothing. A few sellers have also been known to print reproduction covers and wrap them around a common tape, so look for the original chipboard clamshell case rather than a loose cardboard sleeve, and be wary of anything without visible wear consistent with thirty-five years of storage.

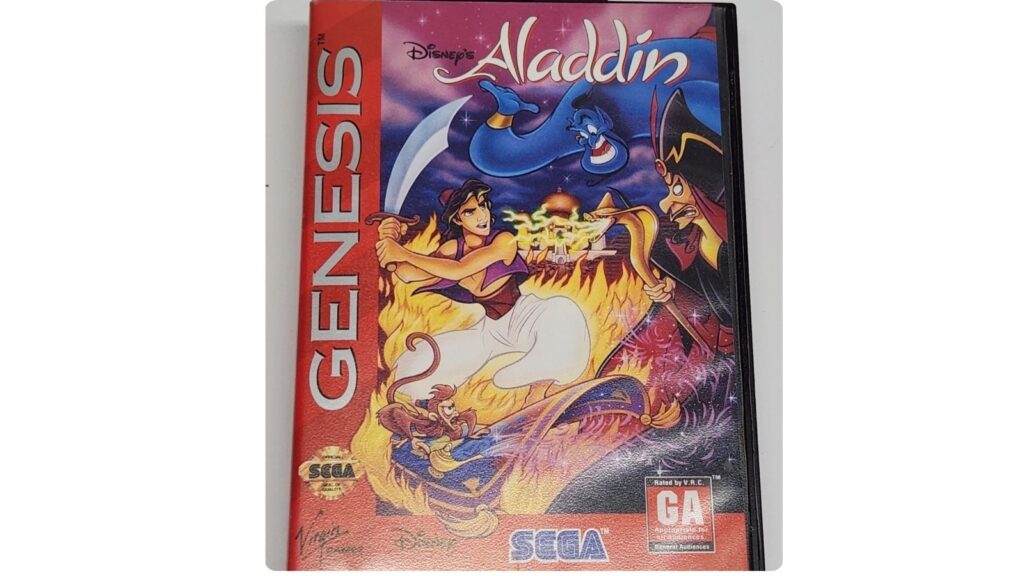
2. Disney’s Aladdin for Sega Genesis
Aladdin Sega Genesis
Image Credit: D&D Bargain Outlet via eBay

Virgin Games and Disney Software built one of the best looking 16-bit platformers of the era around Aladdin’s 1993 release, with hand-animated sprites that borrowed directly from the film’s own animators. It sold well at the time and still turns up regularly in old game collections, which keeps the loose cartridge affordable while rewarding anyone who kept the box.

A loose cartridge alone is only worth a few dollars, but a complete copy with the case and manual typically brings close to $19, and a factory sealed copy climbs toward $94. Professionally graded sealed copies, the kind collectors send off to have authenticated and encased, have reached over $400, though that’s the ceiling for a pristine example rather than a typical result.

The manual and the cardboard box are what separate a complete copy from a loose one, and both are easy to lose after three decades. Check that the cartridge label is the original glossy print rather than a faded or peeling reproduction sticker, which shows up occasionally on resold copies from sellers padding out incomplete lots.

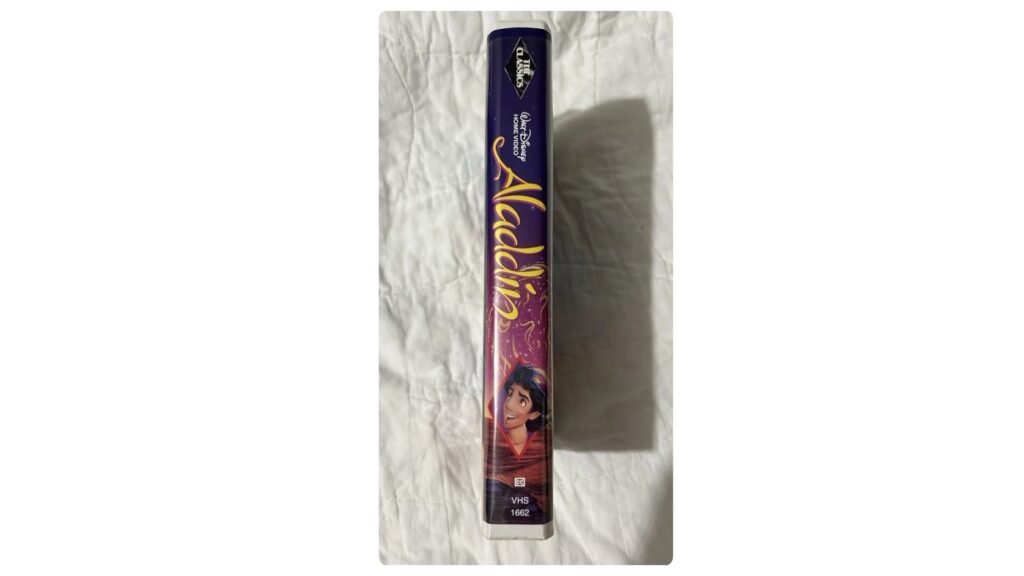
3. Black Diamond Aladdin VHS
Black Diamond Aladdin VHS
Image Credit: michme_6 via eBay

Aladdin’s 1993 Black Diamond release is one of the few titles in Disney’s early home video catalog that holds real value beyond the hype cycle that swept through the Black Diamond category a few years back. Most Black Diamond tapes from this era are worth a few dollars at most, since Disney printed enormous quantities of the popular titles, but Aladdin sits a notch above the pack.

A pristine sealed copy with the shrink wrap and price sticker still attached typically brings up to $200, while an opened copy in good shape is worth a small fraction of that. The black diamond logo printed in the corner of the cover is what identifies the edition, and later reissues without it are common and worth very little.

Look closely at the clamshell case for cracks at the hinge, which is the first place these tapes fail after decades of being stood upright on a shelf. A faded or sun-bleached spine label knocks the price down considerably even on an otherwise complete tape, since collectors buying these want a genuinely clean shelf piece rather than a functional VCR tape.

4. Burger King Aladdin Kids Club toys
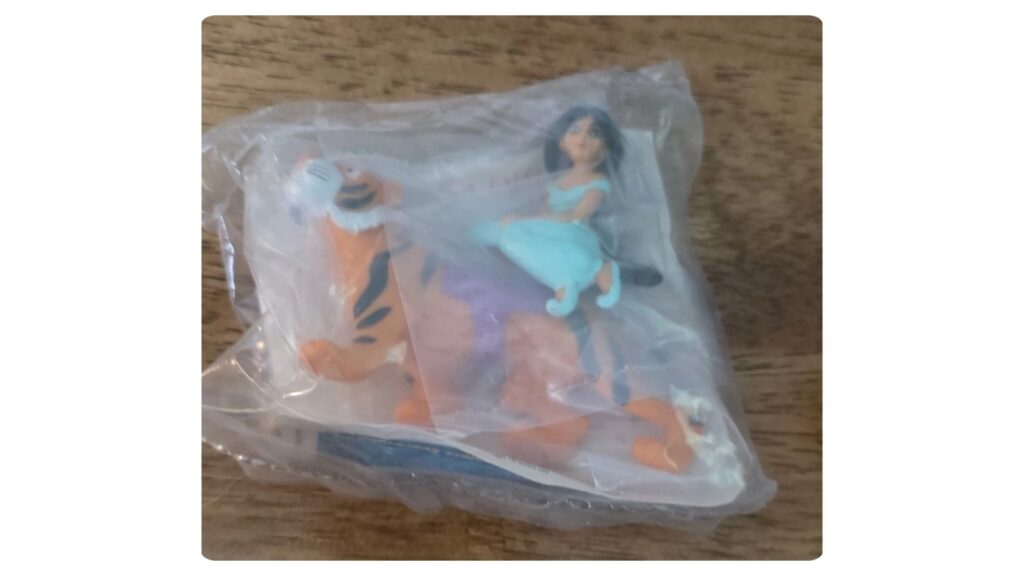
Burger King Aladdin Kids Club toy
Image Credit: Estate Offer via eBay

Burger King ran its own Aladdin promotion in 1992 alongside McDonald’s competing Happy Meal line, releasing a set of small wind-up and pull-back toys featuring Aladdin, Jasmine, the Genie, and Abu. The Henry Ford museum holds one of these toys in its own permanent collection, which says something about how thoroughly this promotion saturated fast food counters that year.

A single loose toy in working condition typically brings a modest few dollars, while a complete set of four still sealed in their original wrappers brings meaningfully more, especially with the cardboard header card that identified each character still attached. Most surviving examples are loose and played with, which is exactly why a sealed one stands out.

These are small, simple toys built for a kid’s meal rather than a toy shelf, so check that the wind-up or pull-back mechanism still works before assuming full value. A stiff or broken mechanism cuts the price substantially even on an otherwise clean example, since function matters as much as appearance on toys this size.

5. Mattel Lion King Pride Rock playset
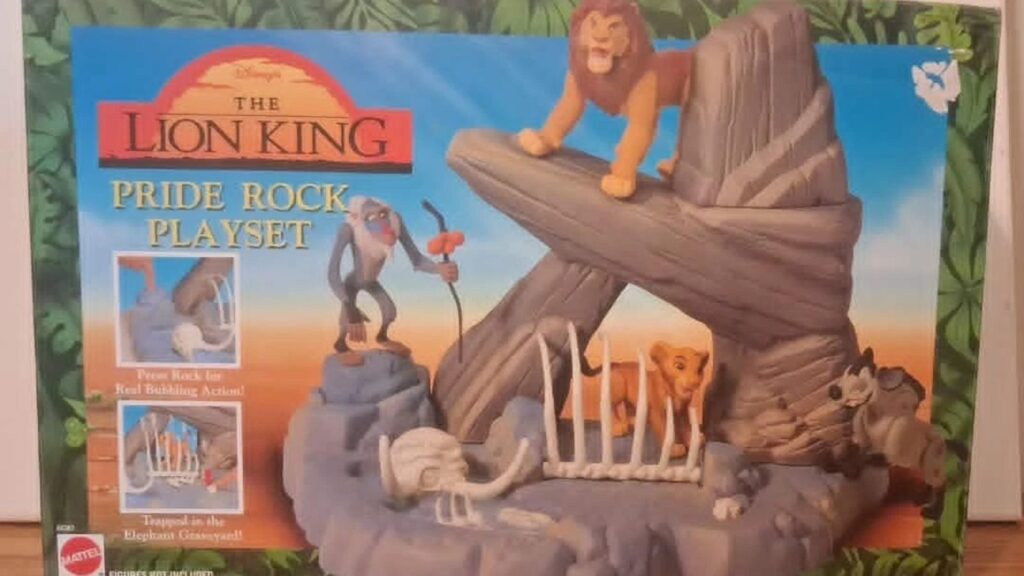
Mattel Lion King Pride Rock playset
Image Credit: Groovy Collectable Things via eBay

The Lion King was 1994’s biggest movie by a wide margin, and Mattel’s Pride Rock playset was the centerpiece of the toy line built around it, a molded rock formation complete with a working presentation ledge for the opening scene everybody remembers. It came bundled with a handful of figures, which is what separates a genuinely complete example from a bare playset.

A complete playset with its original figures typically brings around $135 in today’s market, while an incomplete one missing figures or accessories drops well below that. The rock formation itself is sturdy plastic and tends to survive fine, but the smaller figures and the plastic sun that slots into the top are the pieces most often missing from estate sale finds.

Watch for the difference between this original 1994 line and the toys Disney released for the 2019 live-action remake, since both used similar branding and turn up in the same secondhand bins. The 1994 Mattel packaging says so directly on the box, and the sculpting style on the original figures is noticeably more cartoonish than the photorealistic remake line.

6. Mattel Lion King mane-changing Simba plush
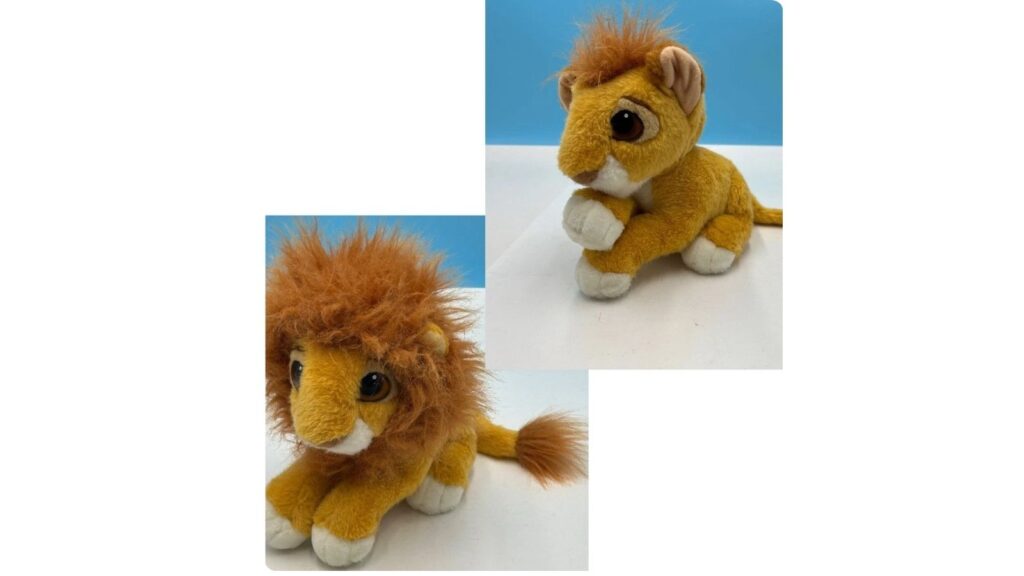
Mattel Lion King mane changing Simba plush
Image Credit: BWE Auction Company via eBay

Among the dozens of Simba plush variations Mattel put out in 1994, the mane-changing “growing up” version stood out for its gimmick: pull on a hidden mechanism and the cub’s small mane extended to simulate him aging into an adult lion. It was a clever bit of engineering for a stuffed toy and sold well enough that plenty survive today, though working examples are scarcer than the concept suggests.

A clean example with a functioning mane mechanism typically brings around $50, while plush toys from the same line without the gimmick, or with a mechanism that no longer extends, sell for a fraction of that. Tag condition matters more than most people expect on plush toys this age, since the printed fabric tag confirms the specific line and year.

Check the fur for matting and the mane mechanism for smooth movement before assuming top value, since three decades of handling tends to gum up the internal mechanism on toys built for repeated play rather than display. A plush that still smells strongly of storage or smoke is a harder sell regardless of how well the mechanism works.

7. 1994 SkyBox Lion King trading card set
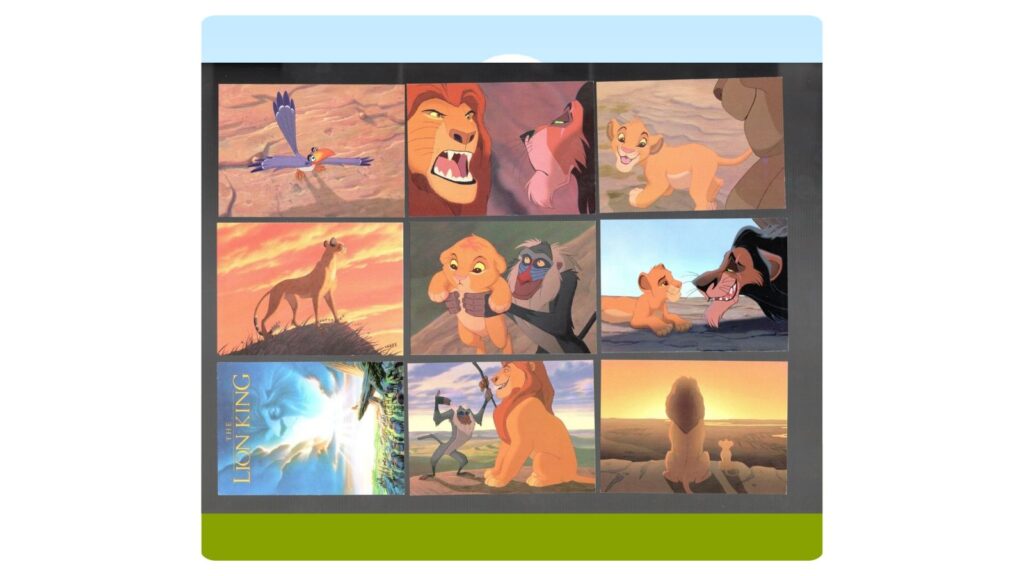
1994 SkyBox Lion King trading card set
Image Credit: LTL SPORTS via eBay

Non-sport trading cards had a real moment in the early 1990s, and SkyBox’s Lion King set capitalized on it with ninety base cards covering the film scene by scene, plus foil chase cards inserted at a lower rate. It was sold in wax packs at grocery store checkouts the same way baseball cards were, which is why complete sets and unopened wax boxes both still turn up with some regularity.

A complete set of the ninety base cards in clean condition typically brings around $20, while the nine-card foil chase subset, numbered separately from the base set, commands more on its own than most people expect for a card printed on foil stock rather than cardboard. Individual base cards are worth pennies apiece outside of a full set.

Corner wear and surface scratches are the main condition issues here, since these cards were handled by kids rather than stored in sleeves from day one. A genuinely mint, unhandled set with sharp corners throughout is uncommon enough to bring a real premium over an average played set, even though the difference isn’t always obvious at a glance.

8. Thinkway Toys talking Woody and Buzz Lightyear figures
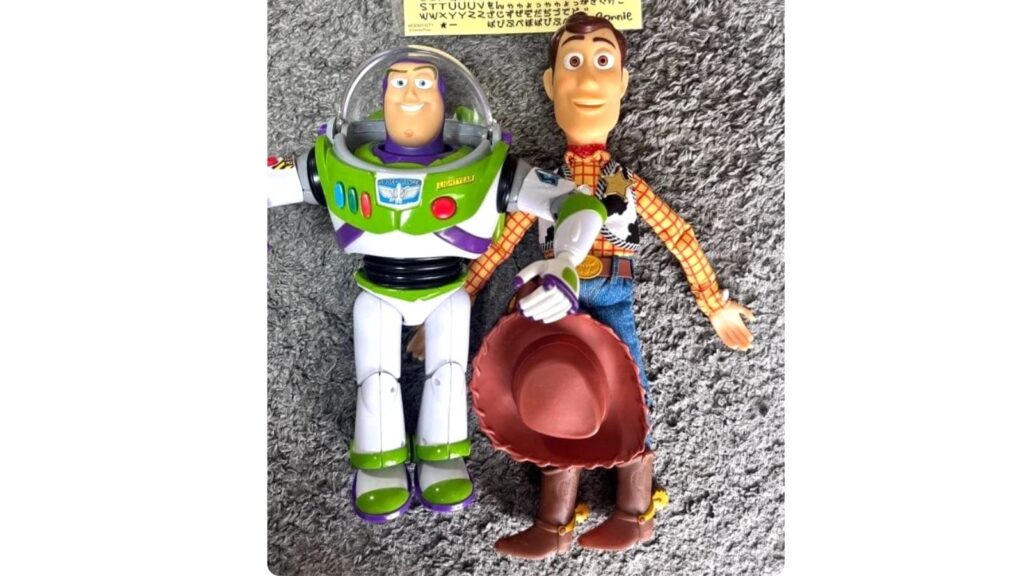
Thinkway Toys talking Woody and Buzz Lightyear figures
Image Credit: kagayaki_jpn via eBay

Thinkway Toys had only eight months to build an entire merchandise line before Toy Story hit theaters in November 1995, after bigger toy companies passed on the project. The result was the first pull-string Woody and the first talking Buzz Lightyear, both produced in far smaller numbers than the sequel toys that followed once the franchise took off.

A loose figure in played-with condition typically brings somewhere in the high teens to twenties, while a complete boxed example with the original graphics intact climbs well past that, and a sealed, unopened figure from this original run brings the most of all. The larger Ultimate Talking Buzz, a full-scale electronic version released the same year, commands a premium over the smaller pull-string figures.

Thinkway kept making Woody and Buzz figures for every sequel that followed, so the packaging is what tells an original 1995 figure apart from a later reissue. The earliest boxes say simply “Toy Story” with no sequel branding, and the figures themselves show more paint wear and simpler tooling than the smoother sculpts that came later.

9. McDonald’s 101 Dalmatians boxed Happy Meal set
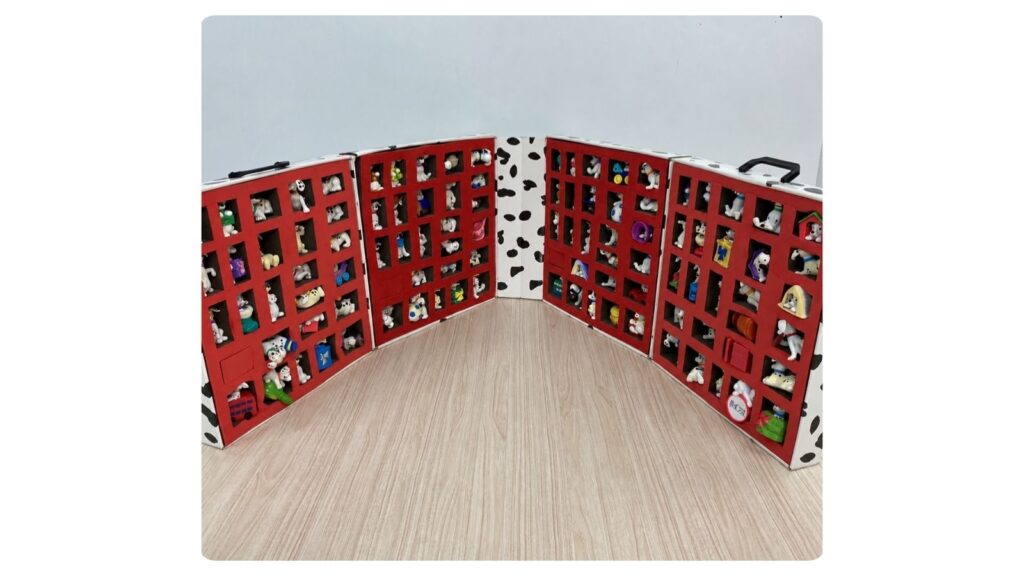
McDonalds 101 Dalmatians boxed Happy Meal set
Image Credit: hiskod_46 via eBay

McDonald’s ran its 101 Dalmatians promotion in 1996 to coincide with the live-action remake, and the puppies came packaged individually in Happy Meals the same way most tie-in toys did. What makes this one different is that McDonald’s also released a complete boxed set of all the figures together for people who didn’t want to buy dozens of meals to collect them.

That boxed set, kept sealed with all figures present, typically brings up to $170 today, while individual loose puppies from the same promotion are worth a dollar or two each outside of a complete grouping. The packaging itself is part of the value, since a loose pile of the same figures brings much less than the same figures still boxed.

Fading is the main issue to check for, since the box art on fast food promotional packaging from this era wasn’t printed to last decades in direct sunlight. A crisp, unfaded box with all the figures still in their original plastic sleeves is worth considerably more than a sun-bleached one, even when every piece is technically present.

10. McDonald’s Pocahontas Happy Meal toys
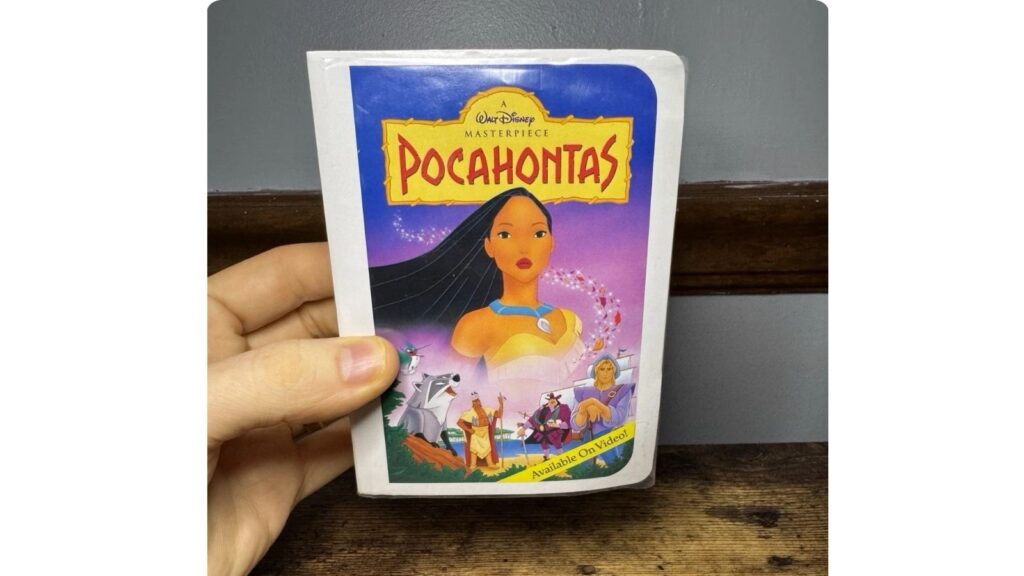
McDonalds Pocahontas Happy Meal toys
Image Credit: ABG Treasures via eBay

Pocahontas arrived in the summer of 1995 with a full Happy Meal lineup covering Pocahontas, John Smith, Meeko, Flit, and several other characters from the film, each figure built around a small mechanical gimmick tied to a scene. It was a fairly ordinary promotion for its time, which is exactly why complete sets are still findable without much effort.

A complete run of the figures together typically brings around $20, while a single loose figure is worth closer to a dollar. It’s a modest number compared to some of Disney’s flashier 90s promotions, but it’s a realistic, findable price point for anyone who kept a full set stashed in a drawer rather than one that made it into rotation as an actual toy.

Completeness is really the only thing driving value here, since none of the individual figures are especially rare on their own. Check that the small moving parts, like Meeko’s spinning acorn or Flit’s flapping wings, still function, since a broken mechanism on an otherwise common figure makes it worth even less than the going rate for loose pieces.

11. Beauty and the Beast Mrs. Potts and Chip china tea set
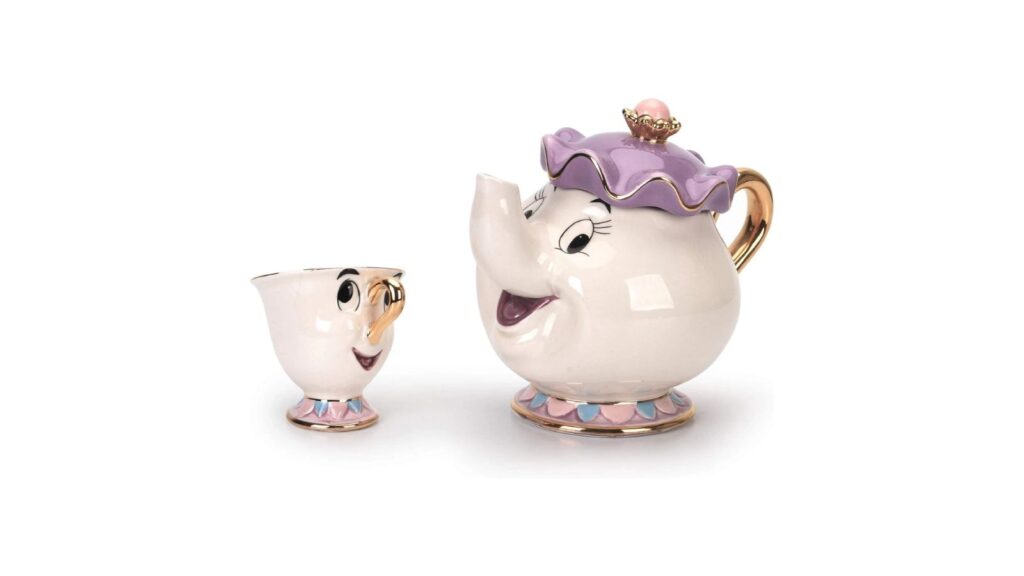
Beauty and the Beast Mrs Potts and Chip china tea set
Image Credit: guisiisod003 via eBay

Beauty and the Beast’s 1991 release turned Mrs. Potts and her son Chip into one of Disney’s most merchandised character pairings, and one of the more charming pieces to come out of it was a genuine child’s china tea set modeled after the pair, sold in a boxed set rather than as a single figurine.

A complete boxed set from the film’s original release window typically brings up to $150 today, while a set missing pieces or its original box sells for considerably less. These were made as functional tea sets for kids rather than display pieces, so complete, unchipped examples are less common than the production numbers would suggest.

Check every piece against the original box art before assuming a set is complete, since teapots, cups, and saucers from this line frequently got separated or broken over years of actual play. Hairline cracks in the ceramic are common and reduce value sharply even when they don’t affect how a piece looks from a normal viewing distance.

12. Polly Pocket Beauty and the Beast Magical Castle
Polly Pocket Beauty and the Beast Magical Castle
Image Credit: pollypocketpalace via eBay

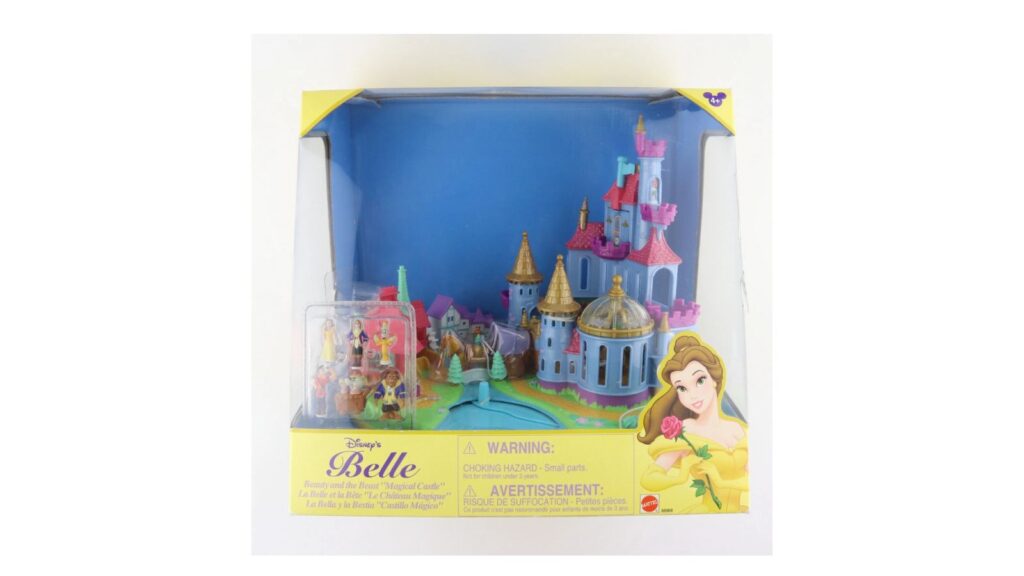
British toy maker Bluebird built an entire Beauty and the Beast themed compact into its Polly Pocket line in 1997, shaping the outer shell like the Beast’s castle and packing a working ballroom scene into the miniature interior most Polly Pocket sets were known for. It wasn’t a huge seller at the time, which is part of why it’s harder to find complete today than the more common Polly Pocket houses from the same years.

A complete example with all its tiny figures and accessories intact typically brings up to $600, while one missing even a single piece drops sharply in value, since the entire appeal of vintage Polly Pocket is built around miniature completeness. The figures themselves are barely bigger than a fingernail and are the first thing to go missing in a toy box.

Bluebird’s original compacts are noticeably smaller and more delicately hinged than the larger Polly Pocket relaunch that arrived years later under new ownership, so check the hinge and clasp closely for the thin, snap-shut mechanism of the originals rather than the chunkier modern version. A working clasp that snaps shut cleanly is worth checking before assuming top value, since decades of hinge wear are common.

13. Playmates Darkwing Duck action figures
Playmates Darkwing Duck action figures
Image Credit: gestrog33 via eBay

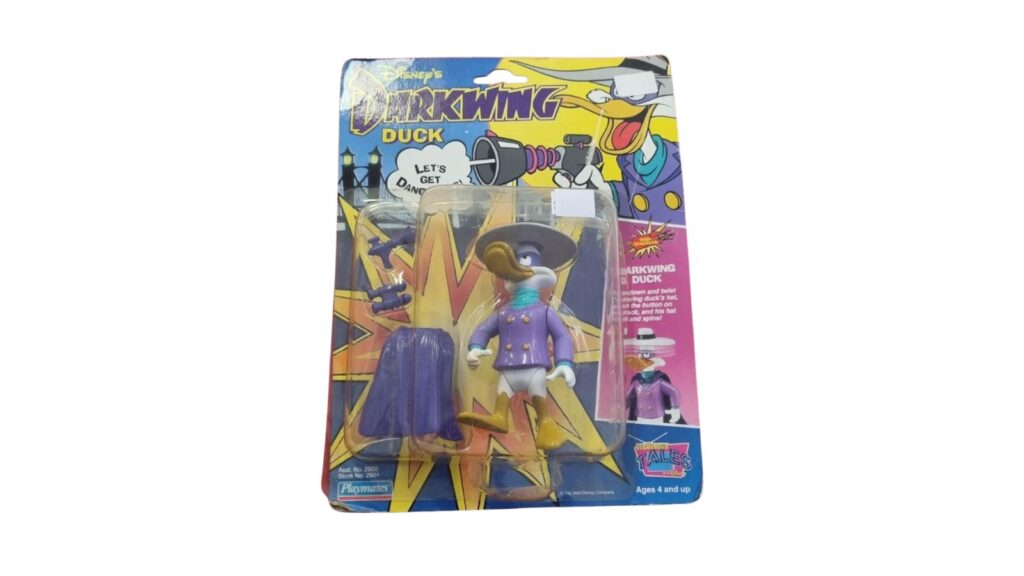
Darkwing Duck debuted in 1991 as part of Disney’s afternoon cartoon lineup, and Playmates built a small line of action figures around the masked mallard and his rogues’ gallery, including Megavolt and Tuskernini. The figures were solidly made for their size but never sold in the volume that bigger 90s toy lines did, which keeps the loose secondary market modest but steady.

A single loose figure in decent condition typically brings somewhere in the $10 to $25 range depending on the character, while a complete carded figure still on its original packaging brings considerably more. Complete sets with the rarer villains included command a real premium over a partial collection built around just the main hero figure.

Paint wear on the beak and cape is the most common condition issue, along with a missing cape entirely on figures that saw real play. Darkwing’s signature hat, which spins on some versions, should still turn freely, since a jammed spinning mechanism is a common and noticeable flaw that collectors specifically check for.

14. Disney’s Dinosaurs Baby Sinclair talking doll
Disneys Dinosaurs Baby Sinclair talking doll
Image Credit: admiralflipper via eBay

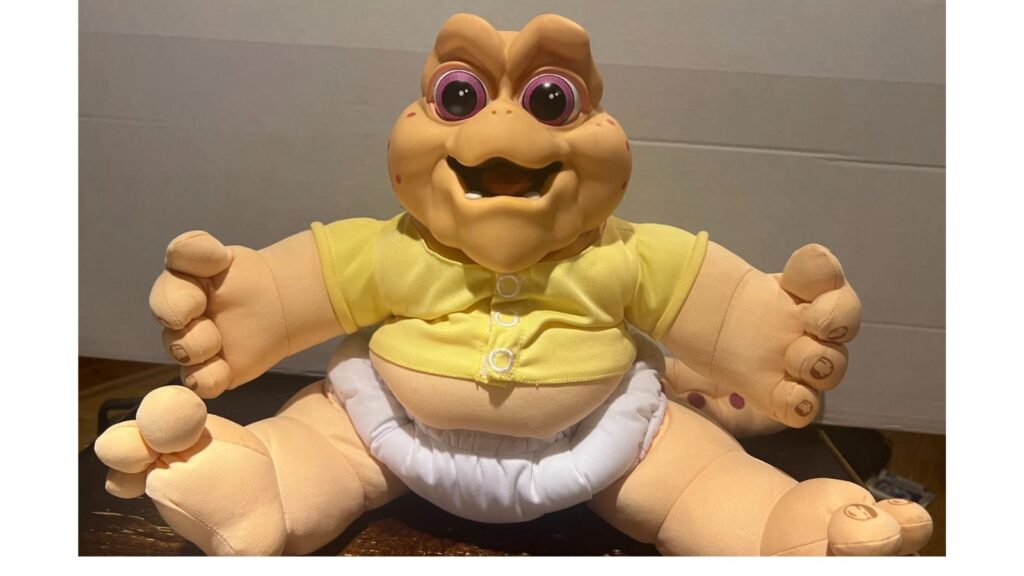
Disney’s live-action puppet sitcom Dinosaurs ran from 1991 to 1994 and turned its wisecracking infant character, Baby Sinclair, into an unlikely merchandising hit. Hasbro’s talking plush version hit stores in time for the 1992 holiday season, repeating a handful of the character’s catchphrases when squeezed, and it sold well enough to become one of the more recognizable toys of that particular Christmas.

A boxed example that still works typically brings up to $250 today, while a loose, unboxed doll sells for a fraction of that even if the electronics still function. The show itself has never had a full streaming release, which keeps a certain nostalgia premium attached to physical merchandise like this one.

Battery corrosion is the most common problem on any electronic plush this age, so check the battery compartment for leakage before assuming the voice function still works. A doll that no longer talks isn’t worthless, since the character and box art still carry appeal, but it sells for meaningfully less than a working example.

15. DuckTales 2 for NES
DuckTales 2 for NES
Image Credit: phatrump via eBay

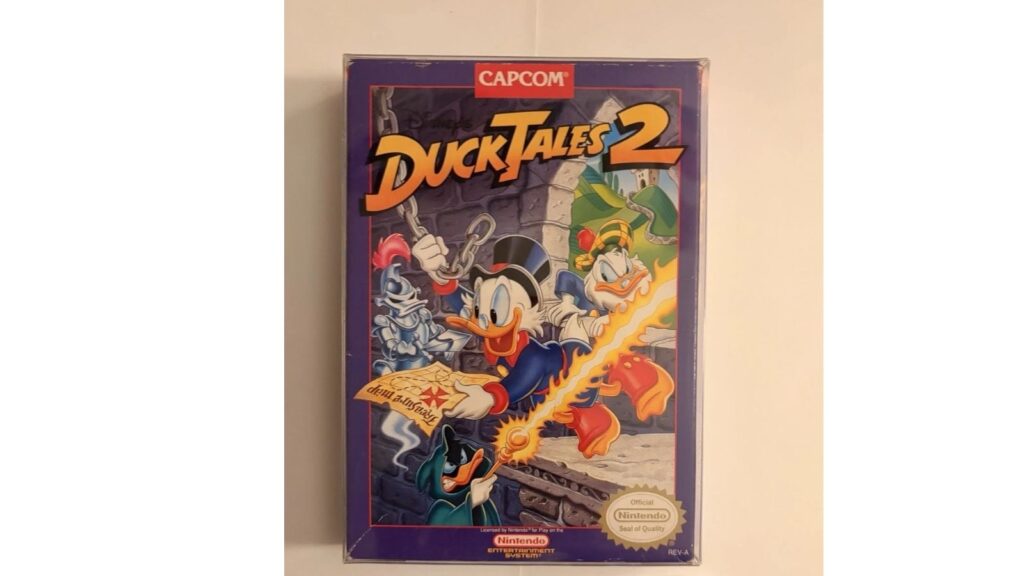
Capcom’s original DuckTales was already a well regarded NES platformer built around Scrooge McDuck’s pogo-cane bouncing mechanic, and its 1993 sequel refined the formula late in the NES’s commercial life, which limited its print run compared to the original game. That smaller print run is exactly why it’s become one of the more expensive standard-release NES cartridges from Disney’s catalog.

A complete copy with the box and manual typically brings up to $600, while a loose cartridge alone sells for a small fraction of that price. Because it arrived so late in the NES’s lifespan, retailers ordered smaller quantities than they had for earlier, more established titles, which is the main driver behind the gap in value.

Reproduction cartridges are a real concern in the retro NES market generally, so check that the label print quality and the cartridge’s pin connector match known authentic examples before paying a premium price. A game that boots but displays glitchy graphics or corrupted saves is a common sign of a repro board rather than an original cartridge.
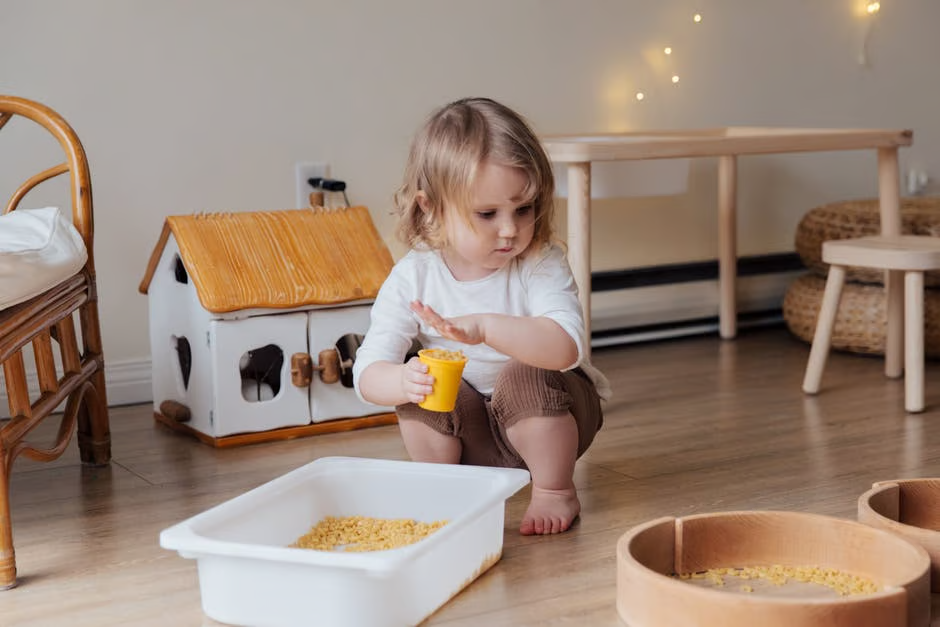
A room packed wall-to-wall with toys can still leave a child complaining, “There’s nothing to do.” The culprit isn’t a lack of playthings—it’s an overwhelming layout. 

This guide shows you how to use reachable storage, defined zones, and adaptable furniture to build a practical playroom your kids will actually use (without turning your home into a permanent showroom).

Start with how your child plays

Before moving heavy furniture, take time to watch where your child naturally plays and what toys they reach for most often during daily activities. Do they build on the open floor, draw at a table, or make up stories with stuffed animals? A few minutes of quiet observation can help you shape the room around their real routines rather than an idealized design.

Leave room to move

Keep a clear, open patch of floor for building, dancing, crawling, or spreading out a large board game. You don’t need an entirely empty room, just enough space for active bodies to move without bumping into furniture edges. Secure heavy shelves to the walls and leave a clear, unobstructed path between play areas.

Make favorite toys easy to reach

Children can choose activities more independently when toys are visible and within reach. In a 2024 study of young children’s play, researchers used four toy sets and observed play in 7- to 8-minute segments across 30 minutes. That was the study’s observation setup, not a recommended toy limit for every home.

Start with a few simple storage choices:

  • Put everyday favorites on low shelves
  • Use picture labels on bins
  • Store small pieces in containers

Give popular toys a clear home, then keep extras in a closet or higher cabinet. Open bins make cleanup easier, while a few closed containers can hide supplies that might otherwise make the room feel busy.

Choose pieces that adapt

Furniture doesn’t have to serve only one purpose. A low table can work for drawing, puzzles, and pretend play, while basic floor cushions can easily be repurposed as stepping stones or target markers during active play.

Modular seating design allows room elements to shift fluidly between passive rest and active, imaginative builds throughout the day. For instance, incorporating a cushy couch play couch provides a comfortable baseline for reading or relaxing, but because the individual foam blocks are modular, they can quickly be pulled apart to construct makeshift playhouses, crawling tunnels, or low climbing steps. Brands like Epic Kidz specialize in this multi-use furniture approach, offering pieces engineered specifically to transition from a living room or playroom lounger into an active engineering tool for kids.

Before bringing in a large piece of baby playmats for play corners, consider how your child might use it in more than one way. Check that it fits comfortably without blocking the room’s main floor area, ensuring it earns its spot by actively supporting daily play rather than just taking up space.

Create simple play zones

A playroom feels far easier for children to navigate and clean up when they can immediately tell where each activity belongs. You can clearly mark distinct areas with a small table, a soft rug, or a low open shelf rather than adding physical walls or bulky dividers. Keep the overall layout flexible, ensuring a game or building project can naturally spill over into adjacent spaces when your child gets a bigger idea.

Try grouping activities in a way that fits your room’s natural layout:

  • Set art supplies near a child-sized table
  • Place books and soft seating in a quiet corner
  • Keep open floor space for building and active play

Simple setup tweaks for lasting play

A functional playroom doesn’t require perfection—just a setup that makes starting and ending play effortless for your child. Keeping favorite toys within reach, preserving open floor space, and choosing versatile furniture creates an environment where independent play happens naturally.

When the room adapts to your child’s changing routines, cleanup stays manageable for everyone. Small, thoughtful adjustments along the way will keep the space engaging and easy to use for years to come.

Learn how to protect your child’s routine when a co-parent faces a legal emergency, including custody, schedules, school, and communication.
Image Credit: User #301539971 via ShutterStock

True, co-parenting requires a delicate balance under normal circumstances. But a sudden legal situation involving an ex you raise a kid with can completely destabilize the household. When police involvement or unexpected custody issues arise, panic sets in quickly for everyone involved.

A child’s world relies on predictable patterns, so keeping their needs centered during adult turmoil prevents long-term distress.

Verifying the facts before changing plans

When a legal issue arises, instant clarity prevents unnecessary panic. Checking the facts before altering standard pickup times or daily schedules keeps children from absorbing false alarms.

There are over hundreds of unexpected legal emergencies impacting co-parenting households every day, ranging from traffic warrants to sudden arrests. A parent who takes a breath and gathers verified details can handle the disruption without letting the chaos spill over to the kids.

Focusing on physical safety, immediate caretaking logistics, and clear facts helps keep the peace at home.

Managing practical handoffs and local bail arrangements

Unexpected detentions mean scheduled custody exchanges will not happen as planned. Arranging safe transportation and immediate coverage without dragging the child into operational details preserves their sense of security.

When an arrest occurs in Central Florida, families often need to coordinate with local professionals like Orlando bail bond services to handle paperwork swiftly while keeping the child safe at home. Handling these administrative tasks in the background allows everyday life to continue with minimal disruption. 

Taking care of business quietly helps children feel that their parents have everything under control.

Maintaining daily rhythms to build resilience

Consistency acts as an emotional safety net when family structures shake. Keeping wake-up times, school routes, meal choices, and bedtime rituals identical to their normal pattern gives kids something solid to hold onto.

Predictable routines reassure a child’s nervous system that their personal world remains safe despite outside problems. The American Psychological Association notes that maintaining familiar daily structures acts as a primary buffer against acute stress during family crises. Sticking to normal discipline and ordinary family rules works much better than overcompensating with special treats or altered boundaries.

Communicating with age-appropriate honesty

Children pick up on adult anxiety instantly, so complete silence often leads to active overthinking. Offering honest, simplified explanations without oversharing adult legal details keeps their trust intact.

Younger kids usually need simple reassurance that their daily needs and safety are fully covered. Older kids require basic factual updates without hearing negative opinions about the other parent.

Coordinating with trusted support networks

Managing a legal crisis alone can quickly lead to exhaustion. Reaching out to pre-established emergency contacts, relatives, or school staff helps keep the daily schedule moving without extra stress on the household.

Alerting teachers or counselors that a temporary family situation is happening allows them to offer extra support without treating the child differently. According to HelpGuide, maintaining non-adversarial communication and consistent routines is key to protecting young ones from unnecessary emotional strain. Relying on close family for carpools or dinner help frees up time to handle emergency details quietly.

Respecting communication limits and co-parenting boundaries

A child’s relationship with the other parent should not become collateral damage during a legal emergency. Keeping personal frustration entirely separate from parenting duties protects the child’s emotional well-being.

Refraining from discussing court dates, legal fees, or potential penalties within earshot of young listeners preserves their peace of mind. Parents who focus on keeping co-parenting boundaries intact remain a comforting, non-judgmental presence when kids have questions. Children adapt much better when they see a calm, respectful adult keeping the home safe and stable.

Preserving stability beyond the initial crisis

Once the immediate legal emergency subsides, transitioning smoothly back into standard routines keeps life moving forward. Legal matters may take months to resolve in court, but everyday life needs to stay dependable. Documenting temporary schedule changes clearly helps if formal custody arrangements require updates down the line.

Putting the child first

Everyone in a co-parenting arrangement is prone to facing legal issues, but they should not put a kid’s routine or well-being in disarray. Keeping the primary focus on emotional stability turns a stressful event into a story of resilience. It takes effort, respect, communication, and good coordination.

Explore more of our family stability resources to keep your household running smoothly through unexpected challenges if you found this guide helpful.

Sarah is 66, single, and living on Social Security and a small pension that puts her reported income at about $95,000 a year. She pulls $60,000 out of her traditional IRA to replace a roof and help her son with a down payment, then doesn’t think about it again.

Two years later, a letter from Social Security tells her that her Medicare Part B premium is jumping from the standard $202.90 a month to $405.80. That’s an extra $2,434.80 a year, and it has nothing to do with anything she did this year. Medicare looked at her tax return from two years back, saw $155,000 in reported income, and moved her into a higher bracket.

If Sarah had pulled that same $60,000 from a Roth IRA instead of a traditional one, her reported income wouldn’t have moved at all. Same roof, same gift to her son, same $60,000, and a completely different outcome on her Medicare bill.

That’s the part almost nobody explains clearly. Medicare doesn’t care how much money touches your bank account in a given year. It only cares about a specific number called your modified adjusted gross income, and some of the biggest checks you’ll ever write yourself never show up in that number at all.

Money that comes out of a Roth IRA or Roth 401(k)

Roth IRA new
Image Credit: Shutterstock

Once you’ve paid tax on money going into a Roth account, and the account has been open long enough to qualify, withdrawals come out completely free of federal income tax. That’s true of Roth IRAs, which never require withdrawals during your lifetime, and it’s true of Roth 401(k)s once you meet the age and holding period rules. Because that money never touches your adjusted gross income, qualified Roth withdrawals are excluded from both AGI and the income figure Medicare uses to set your premium.

This is why financial planners so often push clients to convert part of a traditional IRA to a Roth in the years before Medicare eligibility. The conversion itself is taxable in the year you do it, so it can raise your premium two years later, but every dollar you convert becomes a dollar you can pull out tax-free and surcharge-free for the rest of your life. If you’re already on Medicare and drawing down retirement accounts, the order matters. Pulling from a Roth bucket instead of a traditional one, in a year when you’re close to a bracket line, can be the difference between paying the standard premium and paying hundreds more a month.

None of this changes what counted as taxable when you originally funded the Roth. You already paid that tax once. This is simply the payoff for having paid it early.

Money you pull from a health savings account for medical bills

final notice on a medical bill
Image Credit: Shutterstock

A health savings account is one of the few places in the tax code where money goes in before tax, grows without being taxed, and comes back out without being taxed either, as long as you spend it on a qualifying expense. Withdrawals used for qualified medical expenses, from doctor visits to prescriptions to dental work, are tax-free and never enter your adjusted gross income, which means they can’t push you into a higher Medicare bracket either.

Here’s the detail most people miss. Once you’re on Medicare, you can’t put new money into an HSA, but you can keep spending down whatever is already sitting in the account. HSA money can also be used tax-free to pay Medicare Part B, Part C, and Part D premiums themselves, along with qualified long-term care insurance premiums. That means an HSA can quietly cover the very premiums IRMAA threatens to raise, without adding a cent to the number that sets those premiums in the first place.

If you built up an HSA balance while you were working, treat it as a separate bucket in retirement. Spending it down on medical costs, Medicare premiums included, is one of the cleanest ways to cover healthcare bills without nudging your income anywhere near a bracket line.

Money you send straight from your IRA to a charity

donating to charity
Image Credit: Shutterstock

If you’re 70½ or older, you can send money directly from your IRA to a qualified charity through a qualified charitable distribution, and that money is excluded from your income entirely. The limit for 2026 is $111,000 per person, adjusted for inflation each year, and it counts toward your required minimum distribution once you’re at an age where RMDs apply.

The distinction matters because of how an ordinary charitable gift works. Take $20,000 out of a traditional IRA and write a check to your church or a local food bank, and the $20,000 shows up in your income first, with a deduction only available later if you itemize. Most retirees take the standard deduction now, so that donation often provides no tax benefit at all, and it still raises your income for Medicare purposes. Route the same $20,000 straight from the IRA custodian to the charity instead, and it never touches your income to begin with.

This is one of the few strategies where doing something generous and doing something smart for your Medicare premium are the same action. The money has to move directly from the IRA to the charity, never through your own hands first, or it doesn’t qualify.

Money you borrow against your house or your life insurance

life insurance written on computer
Image Credit: Shutterstock

A loan is not income, no matter how large it is or what you spend it on. A home equity line of credit, a reverse mortgage, or a loan against the cash value of a permanent life insurance policy all put cash in your pocket without appearing on a tax return, because loan proceeds are money you’ll eventually repay, not income, and they don’t affect your Medicare income calculation.

This is why some retirees who are house-rich and cash-poor use a reverse mortgage to cover living expenses instead of pulling larger amounts from a traditional IRA. The reverse mortgage proceeds don’t count as income at all, while an equivalent IRA withdrawal would be fully taxable and would count toward Medicare’s income test. The tradeoff is real. A reverse mortgage carries fees and reduces the equity left in the house, and a policy loan reduces the death benefit your beneficiaries eventually receive if it isn’t repaid. Borrowing isn’t free money.

Still, if the choice is between an IRA withdrawal that could tip you into a higher bracket and a loan that costs interest but doesn’t touch your income, it’s worth running both numbers before you decide. A lot of retirees don’t realize borrowing is even on the table as an alternative to a taxable withdrawal.

A life insurance payout

Life Insurance Policy
Image Credit: Shutterstock

When someone names you as a beneficiary on a life insurance policy, the death benefit you receive isn’t taxable income under federal law. Life insurance proceeds paid because of the insured person’s death generally aren’t taxable, with limited exceptions for policies that were sold or transferred to you for a price. That means a $250,000 payout, or a $2 million one, adds nothing at all to your adjusted gross income the year you receive it.

The one wrinkle is interest. If the insurance company holds the payout and pays it out over time instead of in a lump sum, the interest portion of those payments is taxable, even though the underlying death benefit isn’t. Most beneficiaries take the money as a lump sum specifically to sidestep this.

This matters for Medicare because a life insurance payout is often the single largest check a retiree ever receives, and it’s natural to assume something that large must carry tax consequences. It doesn’t, at least not on the federal income side, and it won’t move your Medicare bracket the following year no matter how much money is involved. If you’re settling an estate and distributing policy proceeds to beneficiaries, it’s worth telling them plainly that the money is theirs free and clear, because grieving family members rarely think to ask.

A gift or an inheritance

inheritance
Image Credit: Shuttertock

Receiving a gift, whether it’s $500 from a parent or a six-figure inheritance after someone dies, is not income to you under federal tax law. Cash or property received as a gift or an inheritance isn’t taxable income to the person receiving it, and it doesn’t appear anywhere on your tax return as income, which means it can’t touch your Medicare premium.

What does count is what you do with the money afterward. Inherit a traditional IRA and have to take distributions from it, and those distributions are taxable income, the same as if you’d built up the account yourself. Inherit a rental property and it generates rent, and that rent is taxable. Inherit stock and later sell it for a gain above its stepped-up basis, and that gain is taxable. The inheritance itself isn’t the taxable event. What the inherited asset produces afterward can be.

This trips people up because a large inheritance often arrives alongside a stack of assets that will generate taxable income going forward. It helps to separate the two in your head. The inheritance is free money, but managing what it turns into is where the Medicare exposure actually starts.

Getting your own money back

dollars
Image Credit: Shutterstock

A lot of income that looks large is really just your own money coming back to you, and none of that counts toward Medicare’s income test. Sell an investment and only the gain is taxable. The portion that represents what you originally paid, your cost basis, comes back with no tax owed. Cash out a non-qualified annuity and the same principle applies. The amount you contributed comes back tax-free, and only the growth on top of it is taxed.

The clearest example most people will actually use is selling a house. Single filers can exclude up to $250,000 of profit from selling their primary home, and married couples filing jointly can exclude up to $500,000, as long as they’ve owned and lived in the home for at least two of the last five years. For most people selling a longtime home, the entire profit falls under that exclusion and never touches their tax return at all, let alone their Medicare premium.

None of this requires special paperwork or an election. It’s simply how cost basis and gain work. The mistake to avoid is assuming every dollar that comes out of an account or off a sale counts as income. Often, a chunk of it is just your own money, returned to you.

None of this means you should reorganize your retirement around dodging a Medicare surcharge. It just means that before you assume a big withdrawal or a big sale is going to cost you at the doctor’s office, it’s worth checking which bucket the money actually came from.

The labor market gets strange at the specialist end. An employer may have hundreds of people who can do the ordinary work, but only a handful who can interpret a questionable mineral-rights record, sign off on a protection study, defend an insurance reserve, or decide whether aging industrial equipment can safely stay in service.

That scarcity is where some surprisingly dull $85-an-hour careers come from.

These are not usually jobs with glamorous titles or obvious career paths. Many sit deep inside industries such as energy, utilities, insurance, pharmaceuticals, mining, manufacturing, aviation, and infrastructure. The work might revolve around contracts, technical reports, regulatory submissions, maintenance data, supplier records, engineering calculations, or decades-old documentation that has to be understood before anyone can make a multimillion-dollar decision.

Employers are not paying that kind of money because the tasks themselves look exciting. They are paying for judgment that takes years to build, and because having the wrong person make the call can mean a shutdown, failed inspection, legal dispute, safety problem, or very expensive mistake.

That is also why many of these roles are hard to fill. You cannot quickly manufacture a senior corrosion specialist, actuarial fellow, reservoir engineer, patent attorney, or experienced plant manager when one walks out the door.

Landman

Landman
Image Credit: Shutterstock

A senior landman can earn around $87 an hour for spending an impressive amount of time figuring out exactly who owns what.

The job is common in energy and natural-resource businesses, where landmen research property records, mineral rights, leases, deeds, easements, and ownership histories. At this level, that can mean untangling decades of transactions before a company can legally drill, build, acquire land, or sign a new agreement.

It is detailed, document-heavy work where a tiny mistake can become an expensive legal problem. Digital tools can search records, but somebody still has to interpret conflicting documents, negotiate agreements, deal with landowners, and decide whether the title history actually adds up.

Actuarial fellow

Actuarial fellow
Image Credit: Shutterstock

If spending your working life thinking about mortality tables, insurance reserves, claim probabilities, and long-term financial risk sounds wonderfully uneventful, becoming an actuarial fellow can pay about $88 an hour.

Reaching fellowship status takes years of exams, which is one reason employers cannot simply replace experienced actuaries overnight. Once there, the work can involve pricing insurance products, reviewing assumptions, modeling losses, calculating reserves, and making sure a company has enough money set aside for liabilities that may not materialize for decades.

The wider actuarial field also has a strong employment outlook. BLS projections show actuaries growing much faster than the overall labor market. AI can crunch numbers faster, but insurers still need credentialed professionals to choose assumptions, assess unusual risks, explain models, and stand behind those decisions.

Senior reservoir engineer

Reservoir engineer
Image Credit: Shutterstock

Senior reservoir engineers can earn around $88 an hour to answer a question that sounds simple but involves an awful lot of spreadsheets: how much oil or gas is actually underground, and how much of it can realistically be recovered?

The work includes production forecasts, reserve estimates, pressure data, decline curves, simulation models, and repeated analysis of how a reservoir is behaving over time. Much of it takes place behind a computer rather than dramatically standing beside an oil derrick.

Reservoir engineering sits within the petroleum-engineering field, where employers continue to need specialists to evaluate deposits, improve extraction, and manage existing wells. BLS still projects about 1,000 petroleum-engineering openings per year, despite relatively modest overall employment growth.

Regulatory affairs senior manager

Regulatory affairs senior manager
Image Credit: Shutterstock

Around $86 an hour can buy an employer somebody willing to spend their career making sure every required document, label, submission, test result, and regulatory response is exactly where it should be.

Regulatory affairs senior managers are particularly important in pharmaceuticals, medical devices, chemicals, and other tightly controlled industries. A large part of the job is preparing submissions, reviewing documentation, tracking rule changes, coordinating specialists, and answering questions from regulators.

This is controlled, methodical work where consistency matters enormously. AI can make searching and document preparation faster, but companies still need experienced people to interpret requirements, deal with ambiguous cases, communicate with regulators, and take responsibility for whether a product actually meets the rules.

Geophysicist

Geophysicist
Image Credit: Shutterstock

A very senior geophysicist can make about $92 an hour, although the day-to-day work can involve far more staring at datasets than scrambling over dramatic mountain ranges.

Geophysicists analyze seismic surveys, subsurface measurements, geological models, and other information to work out what lies beneath the ground. Depending on the employer, that might involve energy resources, mining, underground storage, infrastructure, or environmental projects.

The broader geoscience field is expected to keep growing, with BLS projecting about 1,800 geoscientist openings per year. Computers have been processing geological data for decades, but experienced humans are still needed to decide what incomplete or contradictory subsurface data actually means.

Pharmacy manager

Pharmacy operations manager
Image Credit: Shutterstock

Pharmacy managers average around $87 an hour, and much of that paycheck is compensation for handling a relentless stream of routine responsibility correctly.

Beyond dispensing medication, managers deal with pharmacist and technician schedules, inventory, controlled-drug records, insurance problems, audits, regulatory requirements, expired stock, workflow issues, and prescriptions that need professional review.

There should be plenty of replacement demand. BLS projects roughly 14,000 pharmacist openings each year, with particularly strong need in hospitals and other clinical settings. Automated dispensing may remove some manual tasks, but professional review, medication management, and legal responsibility remain firmly human jobs.

Mechanical Engineer

Mechanical engineer
Image Credit: Shutterstock

At the most experienced individual-contributor level, mechanical engineers can earn roughly $91 an hour without becoming department directors.

The work is not necessarily inventing exciting new machines. Senior engineers can spend days reviewing specifications, checking tolerances, approving drawings, investigating equipment failures, validating design changes, analyzing vibration, or deciding whether a component will survive another operating cycle.

This is one field where automation may actually create more work. BLS expects mechanical-engineering employment to grow 11% through 2035, with about 17,800 openings a year, partly because increasingly complicated automated machinery needs engineers to design, integrate, test, and maintain it.

Insurance risk senior manager

Insurance risk senior manager
Image Credit: Shutterstock

Insurance risk senior managers earn around $87 an hour to worry professionally about unlikely events and then document exactly what the company plans to do about them.

The job can involve reviewing insurance policies, analyzing loss histories, checking coverage limits, negotiating renewals, maintaining risk registers, working with brokers, examining claims trends, and making sure expensive gaps in coverage do not go unnoticed.

There is plenty here for software to assist with, but the final decisions are not simple data-processing exercises. A company still needs experienced people to judge how much risk it can carry, determine which insurance terms are acceptable, negotiate with insurers, and respond when a complicated claim lands on somebody’s desk.

Electrical Engineer

Electrical engineer
Image Credit: Shutterstock

Experienced electrical engineers at the highest individual-contributor levels can earn about $97 an hour.

Some work on genuinely cutting-edge technology. Plenty do something much less glamorous: load calculations, equipment specifications, protection studies, wiring diagrams, grounding systems, code compliance, testing procedures, fault analysis, and endless design reviews.

Demand is strong. Electrical-engineer employment is projected to grow 10% through 2035, with the combined electrical and electronics field producing around 16,300 openings each year. Power infrastructure, semiconductors, communications systems, solar installations, and electrification all need experienced engineers.

Plant manager

Plant manager
Image Credit: Shutterstock

A plant manager can earn around $92 an hour for obsessing over numbers such as throughput, downtime, scrap, labor hours, maintenance backlog, yield, and how many units actually made it out of the building yesterday.

It is the sort of job where a good day can be remarkably uneventful. Machines ran. Workers showed up. Orders shipped. Nothing broke.

Plants still need people who can coordinate production, maintenance, staffing, quality, safety, inventory, and contractors when reality refuses to follow the production plan. BLS projects around 17,000 industrial-production-management openings every year, largely as experienced workers retire or move into other positions.

Civil Engineer

Civil Engineer
Image Credit: Shutterstock

At senior specialist level, civil engineers can earn roughly $93 an hour, often for dealing with infrastructure most people actively avoid thinking about.

Drainage calculations, utility plans, pavement specifications, grading, foundations, permit comments, inspection reports, technical submittals, and revisions can occupy far more of the day than dramatic bridge-building.

The work is also difficult to make disappear. Roads deteriorate. Pipes leak. Stormwater has to go somewhere. Bridges need repairs. New buildings need foundations and utility connections. BLS continues to project growth and thousands of annual openings for civil engineers, while licensed engineers remain responsible for decisions affecting public safety.

Enterprise fleet senior manager

Enterprise fleet senior manager
Image Credit: Shutterstock

At a very large employer, senior fleet-management pay can reach roughly $91 an hour, based on compensation for enterprise-scale organizations.

The work can include replacement cycles, mileage, fuel spending, maintenance intervals, telematics, insurance, registration, breakdowns, driver policies, tire costs, repair vendors, and deciding whether keeping an aging vehicle for another year will save money or create a maintenance nightmare.

Software has made fleet tracking much easier, but fleets remain stubbornly physical. Vans still break down, trucks still need inspections, drivers still damage vehicles, parts still go on back order, and somebody still has to decide when an expensive asset should be repaired or replaced.

Chemical Engineer

Chemical Engineer
Image Credit: Shutterstock

Senior chemical engineers at the highest individual-contributor level earn around $91 an hour.

The glamorous mental picture involves laboratories and new discoveries. The reality can involve process-flow diagrams, material balances, operating limits, equipment specifications, change-control paperwork, safety reviews, process data, and investigating why yesterday’s production batch behaved differently from the previous 200.

Employment should remain solid too. BLS expects chemical-engineering employment to grow 5% through 2035, with demand linked to manufacturing, new processes, environmental concerns, and changing regulations.

Mine manager

Mine manager
Image Credit: Shutterstock

Mine managers average about $93 an hour, but they are not spending every shift dramatically searching for treasure underground.

A lot of the job is operational grind: production targets, equipment availability, maintenance schedules, safety systems, staffing, contractor performance, environmental requirements, permits, costs, and reports.

Mining remains a highly physical business where expensive equipment, safety regulations, geological conditions, and production targets all have to be managed in the real world. Related mining and geological engineering occupations are expected to continue generating openings as workers leave the field, while demand for minerals keeps extraction operations running.

Aerospace supply chain senior manager

Aerospace supply chain senior manager
Image Credit: Shutterstock

In aerospace and defense, senior supply-chain managers can make roughly $97 an hour without designing a single rocket or flying anywhere interesting.

Instead, they get to worry about whether a certified component from an approved supplier will arrive three weeks from Thursday.

The job is full of supplier scorecards, lead times, purchase commitments, shortages, quality problems, production schedules, inventory levels, contract terms, and parts that cannot simply be swapped for whatever happens to be available. The underlying logistics field is expanding rapidly, with BLS projecting 17% employment growth and more than 26,000 openings per year.

Biotech strategic sourcing senior manager

Biotech strategic sourcing senior manager
Image Credit: Shutterstock

Strategic sourcing may be procurement with a grander title, but in biotechnology it can pay about $101 an hour.

The job involves finding suppliers, running bids, comparing contracts, checking vendor performance, negotiating prices, managing renewals, and determining whether a supplier is reliable enough to become part of an important production or research process.

Procurement is not disappearing either. BLS projects more than 53,000 annual openings across purchasing managers, buyers, and purchasing agents. AI can automate some purchasing tasks, but BLS still expects organizations to need people to manage complicated supply chains, negotiate contracts, and oversee suppliers.

Reliability engineering manager

Reliability engineering manager
Image Credit: Shutterstock

Reliability engineering managers in industries such as aerospace, biotechnology, chemicals, and construction can earn about $86 an hour for making sure boring equipment remains boring.

They study failures, maintenance records, downtime, inspection results, component life, and recurring faults. Then they develop preventive-maintenance plans and engineering changes intended to stop the same expensive breakdown happening again.

The work can mean hours of failure-mode analysis, root-cause meetings, maintenance histories, and performance metrics. Modern sensors and predictive analytics help identify problems earlier, but somebody still has to determine what the data means, whether equipment can stay in service, and what corrective work is actually required.

Patent Attorney

Patent attorney
Image Credit: Shutterstock

Senior patent attorneys average about $96 an hour, and a surprising amount of the work is painstaking rather than dramatic.

They review technical inventions, search existing patents, draft claims, respond to patent-office objections, compare precise wording, study prior art, and argue over whether a small technical distinction is legally significant. A single application may go through multiple rounds of revisions and responses.

Routine legal research is becoming easier to automate, but patent work combines law with technical subject knowledge, professional licensing, and legal judgment. BLS projects around 28,700 lawyer openings annually through 2035 and notes that automation is expected to change some routine work rather than eliminate overall demand.

If you just opened your home insurance renewal and the number was higher again for a house that hasn’t changed at all, no new roof, no claim, no addition, nothing, you’re one of a lot of homeowners watching this bill climb every single year for reasons that have nothing to do with anything you did.

The average homeowner is now paying $2,872 a year for coverage, which is up nearly 46% since 2021, and if you’re in Florida the average has climbed to $8,471 a year, nearly three times the national number. Even people who’ve never seen a hurricane are getting hit, because insurers spread the cost of storms and rebuilding across every policyholder they cover, not just the ones near the coast.

None of that is something you can argue your way out of with your current insurer. But it doesn’t mean you’re stuck paying whatever they decided to charge either. Most people just pay the renewal without checking whether anyone else would charge less for the exact same coverage, and that’s really the only thing worth doing before you sign off on this year’s bill.

Why your bill went up even though nothing changed

home insurance
Image Credit: Shutterstock

Home insurance has been rising for five years running now, and most of it traces back to the cost of putting a house back together rather than anything about how you’ve lived in yours. Lumber, labor and building materials have all gotten more expensive, and insurers price that in across the board whether or not your specific house has ever filed a claim. Severe weather adds another layer on top of that. Hail, wind, wildfire and hurricanes have driven losses up nationwide, and because insurers spread those losses across everyone they cover, a bad storm season in Texas or Nebraska can nudge your premium up even if you live in Ohio.

Where you live still matters more than almost anything else. Nebraska, Colorado, Oklahoma and Kansas all average more than $5,000 a year now on top of Florida’s $8,471, and even a state as unassuming as Massachusetts saw its premiums jump 42.9% in a single year. Your credit score plays a bigger part than most people expect too. A homeowner with poor credit pays nearly $2,000 more a year than one with strong credit, for the exact same house and coverage.

None of that is something you caused. But it does mean the number on your renewal was worked out using a formula that looks different at every single insurance company, which is exactly why it’s worth putting somebody else’s numbers up against your current insurer’s before you renew.

The check that catches the padding built into your renewal

Here’s what actually works: pull out your current declarations page, the one or two page summary your insurer sends every year listing your dwelling coverage, liability limit and deductible, and take those exact numbers to two or three other insurers for a quote. Not a cheaper policy with the coverage quietly stripped down. The same coverage, priced by somebody who isn’t your current company.

The difference in pricing between insurers is bigger than most people assume. Two neighbors with identical houses, identical coverage and identical deductibles can end up paying premiums that differ by 50% to 100%, simply because one insurer weighs your roof’s age heavily and another cares more about your credit tier or your claims history. Homeowners who run this comparison typically save somewhere between $400 and $800 a year, and some find a difference wide enough to save $2,000 or more, especially if they haven’t shopped around in years and their current insurer has been quietly raising the renewal price on the assumption that nobody would check.

It also helps that comparing prices has gotten a lot easier than it used to be. The average person requesting a home insurance quote now collects 3.5 quotes, the highest number on record since that particular study started tracking it, mostly because you can get several prices back online in the time it used to take to make one phone call.

How to run it without shortchanging your coverage

home insurance bill
Image Credit: Shutterstock

The place people go wrong with this is chasing the lowest number and letting the coverage quietly slide along with it. A quote that comes in $600 cheaper is very often $600 cheaper because it dropped your dwelling coverage or raised your deductible without saying so plainly, not because that insurer found you some special deal nobody else offers.

Get your dwelling coverage right before you even start comparing. It should reflect what it would actually cost to rebuild your house today, not your mortgage balance and not what your house would sell for, since a chunk of a home’s sale price is just the land underneath it, and land doesn’t burn down or blow away. This isn’t a small distinction. After the Marshall Fire tore through Colorado, researchers looking at the claims that came in afterward found that 74% of the policyholders were underinsured, and more than a third of them were short by 25% or more of what it actually cost to rebuild.

Keep your liability limit and your deductible identical across every quote you collect too. A policy with a $5,000 deductible will always beat one with a $500 deductible on price alone, but that isn’t really a comparison of two insurers. It’s just a comparison of how much risk you’re willing to carry yourself before anyone else has to step in.

The extra moves worth stacking while you’re at it

Once you’ve got a few real quotes sitting in front of you, there are still a couple of adjustments that can push the number down further. Raising your deductible from $1,000 to $2,500 can cut your premium by about 9%, as long as you’d actually have $2,500 sitting somewhere you could get to fast if something happened. Bundling your home and auto insurance with one company can save up to 25%, though it’s worth checking that the bundled price still beats the best standalone quote you found, since a bundling discount doesn’t always beat a truly competitive rate sitting somewhere else.

Your credit is worth a look before you request any quotes too. Since credit-based pricing alone can tack on close to $2,000 a year, paying down a card balance or disputing an error on your report before you start collecting quotes can lower every number that comes back, not just whichever one you end up picking.

When the cheaper quote is actually the worse deal

home under umbrella
Image Credit: Shutterstock

A lower number isn’t automatically the better deal, and it’s worth slowing down before you switch. Check the insurer’s financial strength rating through a group like AM Best first, because a company that can’t pay claims after a rough storm season isn’t saving you anything. It’s just putting off the bill until a worse possible moment to get hit with it. Read through the exclusions while you’re at it. Plenty of insurers cap water damage payouts or leave wind coverage out entirely in coastal areas, and those details only tend to surface once you’re the one filing a claim.

How a company actually handles claims matters as much as how it prices a policy. Reviews and your state insurance department’s complaint records will tell you more about what happens after a loss than any quote page ever could. A policy that’s $300 cheaper a year and takes four months to pay out after your roof caves in during a storm isn’t the win it looked like when you were just comparing numbers on a screen.

A brand-new carrier undercutting everyone else on price is worth a second look for the same reason. Some of them are simply well capitalized and pricing aggressively on purpose. Others are chasing volume in a way that goes badly for their policyholders the first time a bad season of claims rolls in. Ten extra minutes checking reviews and a rating is a small price for knowing the company will actually be there.