If you’re thinking about proposing to your partner and one or both of you have been married before, you might have a lot of questions about second marriage “etiquette.”
Do you give an engagement ring for a second marriage? How much should you spend? What should a second engagement ring look like? How should you propose? The answers to these questions largely depend on the person you’re proposing to and their feelings about second marriage.
“The answer as to whether to propose or give an engagement ring for a second wedding is completely dependent on the couple,” says Jodi RR Smith, president of Mannersmith Etiquette Consulting, a consulting firm based in Marblehead, Mass., that offers etiquette education and training.
Do you give an engagement ring for a second marriage?
Deciding to get married a second time signifies that the tradition of marriage is meaningful to both parties involved. For this reason, Charleston, S.C.-based etiquette and event expert Emilie Dulles says an engagement ring is an appropriate and recommended way to celebrate your union.
“A serious commitment between two adults to spend their lives together in marriage is something precious that should be celebrated from the very first moment they decide to become engaged,” she says.
Allison Williams, founder of the Everlasting Occasion wedding resource site, echoes this advice, especially if you’re planning to celebrate your union by having a second wedding celebration.
“The ring is still a special part of the process and as such, is something that is generally advised,” Williams says.
She does note that a second engagement ring is often more subtle than the first and is sometimes used as the wedding ring instead of purchasing a second band.
While the general consensus is that giving an engagement ring for a second marriage is appropriate and even advised, it’s important to know how your partner feels about a second engagement ring.
If you haven’t broached the topic directly, asking your partner’s close friend or family member can be a great starting place for planning a second engagement. But it also doesn’t hurt to have an open discussion with your partner to find out what they want.
Can I reuse an engagement ring?
While there are certain cases where it may be appropriate to reuse an engagement ring for a second wedding, an engagement ring from a previous relationship should not be used.
“Even if it saves money, and even if the new partner is unaware it was previously owned by another person, this ring will still have meaning to the former partner,” Williams explains.
She says it can adversely serve as a reminder of the former, failed relationship. Your new partner deserves something “unique and chosen for them,” Williams says.
“It should be symbolic. Purchasing a new ring is part of the commitment to the new marriage.”
One exception for reusing an engagement ring for a second wedding is to give a ring that’s been passed down in your family, perhaps estate jewelry from your grandmother.
“The love and longevity associated with the ring acts as an added blessing for the union,” Smith says. How much should you spend on an engagement ring for a second marriage?
However, most experts agree that a second engagement ring is largely dependent on the couple’s feelings toward the second marriage, as well as their financial situation.
“Don’t go crazy on a second marriage engagement ring to spite a previous spouse,” Dulles advises. “Keep in mind that many second marriages include children whose feelings and future needs should be factored into the financial implications of a second marriage, including the engagement ring cost.”
Additionally, purchasing a second engagement ring shouldn’t create financial hardship.
Dulles’ advice?
“If $200,000 is an easy sum to spend, go ahead. If $2,000 is more your speed, stay in that lane.”
She says you can find beautiful engagement rings at all price points, and diamond rings are no longer a must (unless of course your partner specifically wants one).
“Other stones can be selected to create a significant ring that is meaningful and appropriate for a second marriage,” Dulle says.
A proposal for a second marriage can come with more complications than a first-time proposal.
Dulle says there are a few considerations when you’re deciding how intimate vs. elaborate the proposal should be:
“Are there children involved? Are there former spouses with tricky relationships? Is the engagement going to receive public attention?”
But regardless of how you choose to propose, you should still try to make it memorable and special.
“The key is to not repeat any previous engagement location, theme, music or other design element and also to make sure you personalize the event to your soon-to-be fiancé(e),” Smith says.
She notes that the proposal should also match the couple’s personalities:
“An outdoor, adventurous couple might hike a mountain and get engaged at the summit. A city-centered couple might have dinner at a trendy restaurant with a proposal during intermission at a jazz club performance.”
The nature of the proposal should match what makes the couple tick, Smith says.
Unique engagement rings for a second marriage
Engagement ring trends for a second marriage tend to skew less traditional – particularly where diamonds are concerned. Dulles notes that colored gemstones are in.
Aquamarines, tourmalines, topaz, peridot — particularly bezel sets — are all eye-catching statement rings for the creative bride,” she says. Pink sapphire engagement rings are another standout choice in this category, offering a romantic colour with excellent durability and a distinctly non-traditional feel that resonates with many second-time brides.
Ben Affleck recently proposed to Jennifer Lopez for a second time with a rare 8.5-carat natural green diamond. He initially proposed in 2002 with a 6.10-carat pink Harry Winston diamond.
However, for more traditional couples, a more subtle diamond may be the right choice.
“There are some beautiful modern pavé diamond bands that make for great second marriage engagement rings for a more minimalist bride, like this one from Tiffany & Co.,” Dulles says.
If you’re looking for a second diamond engagement ring on a budget, sites like Gemma.com allow you to browse preowned rings at a lower cost. You can also find rings made by independent artists (or have a custom ring designed) on a site like Etsy.
Brilliant Earth also allows you to design your own ring, choosing a gemstone and setting of your choice.
Some less traditional couples may forego a traditional engagement ring altogether.
“Some couples feel like they have ‘been there done that’ and opt for new traditions the second time around like matching ring tattoos,” Smith says.
There are also more casual ring options like these silicon designs available on Amazon:
Communication is key in any relationship. When you’re planning a second engagement, make sure you’re in tune with your partner’s tastes and considerations before you start shopping for a second engagement ring—or planning a second proposal. Many couples also choose to take a pre marriage course before remarriage to strengthen communication, align expectations, and build a stronger foundation for their future together.
Do you give an engagement ring for a second marriage?
Deciding to get married a second time signifies that the tradition of marriage is meaningful to both parties involved. For this reason, Charleston, S.C.-based etiquette and event expert Emilie Dulles says an engagement ring is an appropriate and recommended way to celebrate your union.
Can I reuse an engagement ring?
While there are certain cases where it may be appropriate to reuse an engagement ring for a second wedding, an engagement ring from a previous relationship should not be used.
How do you propose for a second marriage?
The nature of the proposal should match what makes the couple tick, Jodi RR Smith says.
If you are a single mom, you don’t want to get to the end of the month and wonder where all your money went. Single moms have unique financial challenges, since they often operate a household on one income and must pay for expensive necessities like child care. This makes budgeting and tracking expenses important.
Emma’s quick take on how to set up a budget
To start budgeting, you need to list all your income and expenses, as well as identify spending weaknesses. The next steps involve making a spending plan that lets you have money in the bank at the end of the month.
Whether you are tired of reaching the end of the month, wondering where in the world all your money went, or you have some big financial goals you want to reach, here are some effective budgeting tips for single moms:
1. Track how much money you spend for a few months
The first step to creating a budget that works is figuring out where all your money has been going each month. To do this, you’ll want to break out your last few months of bank statements and credit card bills.
Devote a few hours to adding up all your spending in categories like food, entertainment, transportation, clothing, and regular bills on a per-month basis for the last few months.
If it’s currently August, for example, figure out exactly how much you spent on food and dining out in June and July. And do the same thing when it comes to what you spent in other categories that tend to hit your budget hard.
Tally those numbers up to get an idea of how much you’re spending each month! You’ll need this information once you get to the point where you’re creating your budget for future months.
If you prefer using apps, options like YNAB can help you create and follow a budget right from your smartphone. However, if you like to write things down, buy a budgeting planner. They come in different sizes and you can look for them on sites like Amazon or Walmart.
2. Figure out exactly how much money you earn
The next budgeting tip I have for single moms is to figure out exactly how much money you bring home each month. This should be easy if you earn a salary but may prove more difficult if you’re paid hourly or rely on a lot of overtime. Income includes:
If you can’t figure out exactly how much you earn, try to come up with a minimum amount of money you earn in any given month. If you sometimes have 5 weekly paychecks in a month but usually just 4, for example, create your budget based on four pay periods. Or, if you sometimes earn extra commissions but not always, plan your budget based on your lowest income months.
If you happen to earn more in any given month, you can treat it as “extra” money and allocate it toward debt repayment or savings this month or next.
3. Figure out exactly how much money you owe
I suggest using a nice third-party app like Mint or YNAB that will pull in all your accounts, including credit cards, saving and checking accounts, car notes, student loans, mortgages and even personal loans into one place.
Be honest with yourself and add ALL your accounts! No cheating! These apps will give you a snapshot of what is coming in, what is going out and the real figure of your debt.
4. Cut spending
Now that you know how much you earn (or approximately how much you earn) and how much you’re spending each month, it’s crucial to look for areas to cut, especially during times of economic uncertainty, rising household debt, or a recession.
Maybe you found out you’re spending $500 or more on dining out each month and know you could easily cut that in half with a little meal planning. Or perhaps tracking your spending helped you realize you’re spending way too much on clothes for the kids or yourself.
5. Use bill negotiation services to manage your bills
Bill negotiation services are a quick, free way to identify and cancel recurring subscriptions you no longer need or want, and lower your monthly utility bills.
For example, Truebill will negotiate better deals for more than two dozen kinds of services, including Amazon, Netflix, Hulu, Time Warner cable, Audible, Spotify, gym memberships, insurance policies and internet. Truebill saved me $16 off my AT&T bill and got me a better plan, to boot. The app also saved me $23.20 per month on my TimeWarner/Spectrum Internet plan.
You can also compare rates among different companies for auto insurance, life insurance, homeowner’s insurance, and other insurance products you buy. This can also help you lower your bills and free up room in your budget.
6. Allocate all the money you earn on paper at the beginning of the month
At this point, you should be fully aware of your income, your spending weaknesses, and how your current spending might be impeding your ability to save. With those details in mind, it’s time to sit down and create a monthly budget for the following month.
How to make a budget
On a sheet of paper, create two different columns — one for each bill or estimated expense and another for how much it costs.
At the top of the page, list your monthly take-home pay so you can reference it when you need to.
At the top of the page, list all of your regular recurring bills — like rent/mortgage, utilities, car payments, and insurance. (Later on, we’ll talk about ways you can reduce the cost of those recurring bills, with help from apps like Truebill.)
Create a list of estimated expenses you’ll need to cover for the month — for example, how much you plan to spend on food and dining out, gas to get to work, and entertainment for the month.
Keep an ongoing tally of how much these add up to, then see what’s left. At this point, you’ll want to allocate any additional funds to savings, investments, and debt repayment.
If you’re unsure how much money to save, that’s totally normal. Keep in mind that, if you have high-interest credit card debt, you’ll want to allocate as much of your income as you can toward debt while also saving for the future. Considering the average credit card interest rate is well over 17%, any credit card debt you have should probably be tackled first.
For many single moms, this also includes setting up an emergency fund to handle those inevitable unexpected expenses without derailing the entire month’s budget.
Single mom budget example
Here’s how a monthly zero-sum budget might look for a single mom with a take-home pay of $7,000 per month after taxes and 401(k) contributions:
Bills
Amount budgeted
Mortgage or rent payment
$1,550
Car Payment
$480
Groceries and dining out
$700 (estimated)
Car Insurance
$150
Utility bills (electric, gas, and water bill)
$400 (estimated)
Dance lessons
$250
Piano lessons
$140
Clothing
$200
Credit Card #1
$400
Credit Card #2
$250
Credit Card #3
$1,000
Savings
$1,480
Total budget amount
$7,000
Keep in mind that the example budget above is just that — an example. Your budget may look totally different depending on how much you earn, how many kids you have, and other variables.
7. On paper, pay all your bills and expenses until your income is gone
Keep in mind that the example budget above is just that — an example. Your budget may look totally different depending on how much you earn, how many kids you have, and other variables.
The key is making sure you list all your bills and fluctuating expenses along with savings and investments each month. Spend every dollar you earn “on paper.”
As the month goes on and you get paid, pay bills and expenses according to your budget and check each of them off as you go. When it comes to estimated expenses like food and transportation, you’ll need to track those categories throughout the month to ensure you’re staying on track with your spending goals.
At the end of the month, you’ll see how you did, and have the opportunity to tweak your monthly budget so it works a little better the following month.
Remember: This is an art and a science, and no one is perfect. Bills fluctuate, expenses come up unexpectedly, and income can go up and down. Be kind to yourself, but also realize that the stricter you are with your budget, the more joy and freedom it will ultimately afford you.
8. Pay yourself first
“Pay yourself first” means that you prioritize your financial security and long-term goals before your whims and short-term goals.
But the importance of paying yourself first, prioritizing your financial wellbeing above new clothes, a home reno or fancy car, is really about establishing good habits and a foundation of security from which you can build any life you can dream of.
FAQs about budgeting for single moms
What does a budget do for single moms like me?
A budget is an important part of understanding how much money you make, and where that money goes. A budget can help you find ways to spend less money, save and invest your money, and enjoy your money on things that are important to you.
Senator Elizabeth Warren popularized the so-called 50/20/30 budget rule in her book, All Your Worth: The Ultimate Lifetime Money Plan. The 50/20/30 budget rule is to divide up after-tax income:
50% on needs
30% on wants
20% to savings
Using this method makes budgeting less complex since it only uses three categories. These categories also tell you exactly where the money goes. Taking care of your needs, treating yourself to some things you want, and saving for the future is a great start.
How can I budget on a low income?
Budgets are especially important if your income is low — an outline of where your money goes, and where you want it to go, can help you stretch all your cash. This helps you feel in control and make decisions each day to make the most out of your income. We created this guide for single moms looking for low-income resources.
The bottom line: My best budgeting tips for single moms
Here are my top 3 budgeting tips for single moms:
1. Track your spending
If you’re tired of wondering where your money goes every month, the time to give budgeting a try is now. Maybe a budget is exactly what you need to start paying down debt and reaching your financial goals.
2. Consolidate your debt
Whether it means refinancing your student loans, paying off or transferring your cards into a 0% credit card, refinancing your home to pay off debt, or otherwise managing your balances and interest rates to streamline what you owe, making it simple often also saves you money. Here is my step-by-step guide to paying off debt — for good.
3. Have a goal
Humans are more productive when they are working towards something. Instead of just focusing on a zero debt balance — which is a wonderful goal — focus on the next step. What does that achievement get you? Does it mean you can qualify to buy a home? Help pay for your child’s college? Go on a much needed vacation?
Or, maybe now that you have extra cash flow, it is time to save for and invest in retirement? Want to get your finances in order? Earn more, pay off debt and stop stressing? Join my 52-Week Money Challenge now! 100% free!
What does a budget do for single moms like me?
A budget is an important part of understanding how much money you make, and where that money goes. A budget can help you find ways to spend less money, save and invest your money, and enjoy your money on things that are important to you.
How can I budget on a low income?
Budgets are especially important if your income is low — an outline of where your money goes, and where you want it to go, can help you stretch all your cash. This helps you feel in control and make decisions each day to make the most out of your income.
A doula is someone who provides emotional and physical comfort and support to parents during—and after—pregnancy and childbirth.
Researchers at the University of Toronto1 found that women who have continuous support during labor are more likely to be happy with their overall birth experience. Babies and happy parents — what could be a more meaningful career?!
As a doula, you can help moms have less-stressful labor and save money, but you also get to run your own business. That means you can have control over how much you work, and when.
To gain the skills you need to be a doula, it’s best to get certified through a credible organization. Getting certified can help you gain valuable skills, make you more desirable to clients, and could even land you higher pay.
There are many online doula certification programs out there to help you get started on this career path.
Birth doulas are non-clinical professionals. Unlike obstetricians and midwives, you don’t need a medical degree or state license to practice. In fact, there is currently little oversight over the profession in the United States—because of that, there aren’t any universally accepted credentials required to become a doula.
According to the National Health Law Program2:
16 states or U.S. territories are currently reimbursing doula services through Medicaid
13 states or U.S. territories are in the midst of implementing reimbursement
18 states or U.S. territories addressed Medicaid doula benefits in a different way (such as a pilot program or doula registry)
2 states or U.S. territories proposed action (such as introducing a bill) but have not made progress
No data was found for 9 states or U.S. territories
These bills also aim to help establish training and certification requirements in those states.
In Oregon, for example, you must complete an approved training program3 to become a state-certified doula. However, you can still operate as a doula even if you’re not state-certified.
While you don’t need a certification to become a doula, getting certified through a credible organization like Doulas of North America (DONA) International or the International Doula Institute (IDI) can help you gain valuable skills, increase your marketability, and help you earn more money.
Most online doula certification programs don’t have any professional prerequisites, but you’ll have to satisfy certain requirements to receive your certification. That may include reading course material, writing papers, taking tests, and attending live births.
Can Doulas be Legally Accountable For Birth-Related Injuries?
Doctors and midwives are clinical staff and provide clinical care and because of that, they can be held accountable for medical mistakes (malpractice) that cause injuries during childbirth.
Also, keep in mind that depending on the state, the statute of limitations is different for malpractice during birth and for the child born, in case it suffered an injury because of the malpractice. For example, in the state of Illinois, if someone from Chicago was trying to sue the hospital on their own behalf they’d look for a Chicago attorney for birth-related injuries, they could sue the hospital for malpractice up to 2 years after they found out about the injury, but no more than 4 years after the act (‘statute of repose’). As for a minor, if he/she was injured during birth, it’s 8 years or until they turn 22 (Illinois law, 735 ILCS 5-13/212(b)); this leaves the hospital exposed to lawsuits for a long period.
Since doulas don’t provide clinical care, they can’t be held accountable for these types of injuries.
Doulas can, however, be sued for other types of negligence (e.g., giving ‘medical’ advice outside their scope, abandoning a client, breach of contract, etc.).
How much does a doula make?
Your salary as a doula will depend on where you live, whether you decide to work full-time or part-time, and what kind of certification you hold.
Most full-time doulas average four births per month and charge flat fees ranging anywhere from $500 to $2,500 per birth depending on their location and experience.
According to Ziprecruiter,4 birth doulas in the United States make about $65,000 a year on the high end, with a national average salary of $49,220. Assuming this number is based on four births per month, that works out to about $1,025 per birth.
Holding a doula certification may also bump up your salary. According to DONA International, their doulas make 25% more than non-certified doulas and 7% more than doulas with certifications from other organizations.
How to become a certified birth doula
The first step to becoming a certified doula is determining which program is right for you. There are in-person programs, online programs, and hybrid programs that combine the two.
During the certification process, you’ll learn all about childbirth and breastfeeding, as well as techniques for supporting and comforting clients during labor.
You’ll also learn the basics of starting your own doula business.
Attend births in-person, regardless of which program type you choose, to satisfy certification requirements.
Receive an evaluation from your clients and a healthcare provider about their experience with you.
Program Length
The time it takes to become a doula can vary depending on the certification or organization. Usually, you’ll spend 10 to 48 hours attending a course or workshop in-person or online. On top of that, you’ll have to satisfy other certification requirements including reading books, writing papers, and taking quizzes. And, you’ll have to attend three births for a minimum of 15 hours total.
Most programs can be completed in three to six months, though some can be taken in just a few weeks.
Many organizations give you up to a year to finish the program, while others have no time limit for completion.
Re-certification
Most doula certifications are valid for three years. Once that time is up, you must apply for recertification.
Recertification usually involves obtaining continuing education credits. This can range anywhere from 15-30 hours. Examples of continuing education include: attending in-person workshops and reading a book or research articles pertaining to childbirth or parenting and writing a 500-word paper about it.
You may also be asked to pay a recertification fee as part of this process. The recertification fee varies by organization, but you can generally expect to pay anywhere from $80 to $250.
Certifying organizations for doulas
Per the Maternal Health Task Force out of Harvard T.H. Chan School of Public Health,5 there are more than 80 organizations and programs in the U.S. that train and certify doulas. Each organization has its own curriculum and guidelines for what makes a certified doula.
Some of the most widely-recognized organizations offering doula training and certification include:
Childbirth and Postpartum Professional Association (CAPPA)
Childbirth International (CBI)
Doulas of North America International (DONA)
ExpertRating
International Childbirth Education Association (ICEA)
International Doula Institute (IDI)
Postpartum Care Foundation (PCF)
Here’s a quick comparison of these programs:
CAPPA
CBI
DONA
ExpertRating
ICEA
IDI
Postpartum Care Foundation
Online classes
Yes
Yes
Yes
Yes
Yes
Yes
Yes
In-person classes
Yes
No
Yes
No
Yes
No
No
Certification exam cost
No exam fees
No exam fees
No exam fees
No exam fees
$390 initial exam, $230 for recertification
No exam fees
No exam fees
Enrollment/training fees
Starts at $775
$785 (birth doula)$755 (postpartum doula)
Starts at $68 for a one-year membership, certification packets start at $45 for members and $55 for non-members, $110 certification packet submission fee
$99.99
$230 and $450-$650 (in-person training) $750 (online training)
Starting at $790 for doula and postpartum doula certifications
$555
Birth doula training
Yes
Yes
Yes
Yes
Yes
Yes
No
Postpartum doula training
Yes
Yes
Yes
Yes
Yes
Yes
Yes
Financial aid
Perez Scholarship Fund
CBI scholarship program
Spirit Fund fee waiver for low-income applicants
Not available
ICEA scholarship program
Payment plans available
Not available
Labor experience requirements
Proof of observing two labors or births for a total of 10 hours
Proof of support for two clients for a total of 20 hours
Proof of three labor support experiences
Not required
Proof of three, six-hour labor support experiences
Not required
Must work with three postpartum clients as part of earning your certification
Childbirth education requirements
Complete CAPPA childbirth education course
Not required
Audit a childbirth education class/lactation class
Not required
Observe one childbirth education series (unless you are a certified childbirth educator)
Not required
Must work with three postpartum clients as part of earning your certification
How long certification lasts
Three years
Lifetime
Three years
One year
Three years
Three years
Free online resources
Yes
Yes
Yes
No
Yes
Yes
Yes
These certifications are not recognized by state or federal governments, but there are benefits to getting certified by one of these organizations.
You’ll receive hands-on training during the process, which can help you feel prepared and confident as you launch your own doula business.
Doula certification can also make you more desirable to prospective clients, as it shows you have a solid educational foundation and understanding of the job.
You may even earn 10%-20% more money if you are certified by one of these organizations.
If you decide to sign up for certification through an organization, here’s what you need to know.
There are a number of reputable organizations offering online doula certification. Here’s how to become a doula online.
How much does doula training online cost?
Doula certification costs vary widely depending on the program. Costs range from as little as $100 for a basic online certification course on becoming a doula, all the way up to $1,100 for a more comprehensive online certification course from DONA International, a leading doula training organization.
Is there a free online doula certification program?
You’ll have to pay tuition for most online doula training. However, some organizations offer complimentary introductory courses or scholarships.
IDI, for example, has a free intro course you can access when you sign up for their mailing list.
DONA International also has a limited number of fee waivers for people who need financial assistance. You can apply for a scholarship directly through their website.
Doula training online programs
Here’s a look at the most popular online doula certification programs and what to expect from each one.
Childbirth and Postpartum Professional Association (CAPPA)
CAPPA provides certifications for doulas specializing in both labor and postpartum care, as well as programs for birth educators, lactation consultants, and new parents. Classes are offered online, as well as in person at locations across the U.S., Canada, and abroad.
The CAPPA training course starts at $550 for virtual, hybrid and in-person options with an approved faculty member. To pass the course, you must:
Pass a pretest and final exam
View required video lessons
Attend at least three births as a doula and receive evaluations from parents and health care providers
Create a resource list for local parents
After the first year, you’ll have to pay $75 per year to maintain your A CAPPA membership status.
Childbirth International (CBI)
Childbirth International offers training for birth and postpartum doulas, as well as lactation consultants and childbirth education. The birth doula course costs $835 (or five payments of $162), and the postpartum doula course costs $790 (or five payments of $156). You can pay less if you choose to receive digital vs. printed reading materials ($760 and $730 respectively).
CBI’s certifications are for life and do not require you to pay an annual membership or renewal fee. They also offer a 15-25% discount if you purchase more than one course at a time and offer 15% of all future course purchases. You can also receive a full course refund within 48 hours of registering if you decide the course isn’t right for you.
CBI training includes video and written lessons, as well as online, open-book exams (between 10-20 multiple choice questions each). You must also work with two clients for a total of 20 hours.
DONA International online training program
DONA International is one of the leading organizations for doula training, certification, and continued education. They’ve been around for over 25 years and have certified more than 13,000 doulas across the globe.
DONA International’s online doula certification program costs between $700 and $1,100. This includes:
$100 fee to become a DONA International member
$45 fee to purchase the DONA International Birth Doula Certification Packet
$110 certification processing fee
$75 fee to buy the required books
$20 fee to attend a required doula business webinar
$400 to $700 fee to attend a required DONA-approved birth doula workshop
To maintain annual DONA membership, which costs $100 per year, and pay a fee of $80 every three years to renew your certification
DONA’s online doula training is incredibly comprehensive. It covers all aspects of doula care and includes training on breastfeeding, basic childbirth education, client support, networking, and business practices. You’ll also get hands-on experience assisting a few clients during childbirth as part of your training.
The program is self-paced. After attending one of their in-person birth doula workshops, you’ll have four years to finish the rest of the program.
As a member of DONA International, you’ll get discounts on continuing education, access to mentoring and professional networking, and a subscription to DONA’s quarterly trade publication.
You’ll need to attend an in-person course about the basics of childbirth that may be 12 or more hours in total and attend an in-person workshop that goes for 16 to 24 hours over the course of two or three days. Additionally, you’ll need to provide primary doula care for three clients, for a total of at least 15 hours and provide documentation of the experiences.
ExpertRating
ExpertRating is an ISO-certified certification and testing business that offers online certifications in over 800 different skill areas, including doula care.
The ExpertRating Doula Certification costs $99.99 and covers the basics of being a doula. During this online course, you’ll learn about the birthing process, how to provide emotional and physical support to mothers during pregnancy and birth, and what’s involved with prenatal and postpartum doula care.
It takes two to four weeks to complete and includes an exam after you finish the coursework. You can renew your certification for $30 after one year and retake the exam up to three times for $10.
International Childbirth Education Association (ICEA)
ICEA offers birth and postpartum doula certifications in person and online and offers discounted certifications to experienced doulas who already hold certifications with other established doula organizations.
Course costs are broken up into three sections — $230 enrollment fee, plus $520 self-paced workshop pricing, and $290 exam pricing. These fees are for U.S.-based course enrollees. ICEA has a country-based pricing structure with lower fees for countries with lower income levels. They also have fees for course extensions ($75), certification reinstatements after expiration ($115), and for exam retakes ($200).
As part of birth doula training, enrollees must verify three labor support experiences of at least six hours each.
International Doula Institute
IDI is a comprehensive doula training organization. IDI’s Birth Doula Certification Program costs $790. You’ll receive a discount of $150 if you’ve already been certified by another organization.
You also have the option of signing up for a package that includes multiple online certification programs. IDI’s other certifications include postpartum doula, childbirth educator, breastfeeding counselor, advanced lactation and counseling, and perinatal nutrition. Tuition costs $4,740 for all six certification programs.
IDI’s certification programs are done completely online and are self-study so you can go at your own pace. You have a full year to complete a program after signing up.
The birth doula course includes daily and weekly lesson plans taught by doulas, doctors, nurses, midwives, and dietitians. You’ll need to complete assignments, tests, quizzes, and projects throughout the program and pass an exam at the end.
Tuition also gives you access to a doula trainer via phone or email for one year, membership in a private Facebook support group, doula mentorship, an online doula workshop, and the certification exam.
IDI says most people complete their online doula certification program in six to 12 weeks, working about an hour a day.
Certification is valid for three years. To renew, you’ll need to pay $100, complete three continuing education classes, and submit three surveys from clients you’ve worked with.
Postpartum doula training
Doulas aren’t just there to help guide moms through labor and delivery. Another type of doula is a postpartum doula, who is there to help women through postpartum recovery.
What does a postpartum doula do?
A postpartum doula offers a woman and her family physical and emotional support after she gives birth.
Postpartum doula services include helping families navigate newborn care, caring for an older child while parents tend to the baby, and preparing healthy meals for families.
Postpartum doulas can’t provide medical care, but they can share resources and help clients find a healthcare provider if needed.
How to become a postpartum doula
Like birth doulas, you don’t need a degree or state license to become a postpartum doula. That said, there are many organizations that offer postpartum doula certification if you choose to go that route.
Complete postpartum doula certification in person, online, or a mix of both.
Learn about lactation, nutrition and exercise during the postpartum period, infant health problems, and changes that a woman may experience physically and mentally during the postpartum period.
Complete any required reading or in-person training during the certification.
Complete hands-on training. You’ll likely have to work with three families, spending at least 15 hours on in-person support total, to satisfy the certification requirements.
Postpartum Care Foundation online training program
Postpartum Care Foundation’s online training program costs $555. Tuition covers access to lessons in the program, including postpartum nutrition and lactation support.
PCF offers two other options. For $555, you can take the online postpartum doula certification course and get a starter herb kit that includes postpartum teas, baths, and a belly binding.
For $977, you can take the course, get the starter herb kit, and receive three one-hour career support sessions with Zoe Weston, an international leader in women’s health.
Textbooks and other required reading materials aren’t included in the tuition cost.
Pros of the Postpartum Care Foundation online program
Postpartum Care Foundation’s online program includes comprehensive training for becoming a postpartum doula at a lower cost than other comparable programs. (DONA International’s postpartum doula training certification is more than double the cost, for example.)
Postpartum Care Foundation’s online program includes an introduction to the postpartum period and lessons on postpartum nutrition, belly binding, emotional support, lactation support, and baby bonding. You’ll also get in-person experience working with three postpartum clients as part of earning your certification.
Another benefit is that this program is self-paced so you can complete it on your own time from anywhere in the world.
Cons of the Postpartum Care Foundation online program
While the tuition for Postpartum Care Foundation’s online program is affordable, one downside is it doesn’t cover everything.
The required reading materials for the course aren’t included in the cost, so you’ll need to factor that in when you sign up. Expect to spend between $50 and $75 on books.
You may also need to buy supplies to work with clients during the program since these aren’t covered by the tuition either. Supplies include things like crates to transport your healing tools, mason jars for teas and broths, and small bowls for herbs and oils.
How to get doula clients
There are a variety of ways to get your first doula client:
Set up a website advertising your services. Make sure the website is easy to navigate and optimized for search results so potential clients in your area can find you.
Join local pregnancy and parenting groups on social media to find prospective clients.
Go to community events where potential clients could be in attendance. Have business cards ready to hand out in case you meet someone who’s interested in your services.
Network with pediatricians, midwives, obstetricians, breastfeeding consultants and others in the birthing industry who can refer you and your services.
Ask to be a guest speaker at a birth class, or volunteer at a birth class, so you can introduce yourself to expecting parents.
Frequently asked questions about becoming a doula:
How long does it take to become a trained doula?
Most doulas are able to get certified within three to six months of starting the program, regardless of the type of doula that they become.
Many doula certification programs allow you to go at your own pace, so you can complete your training and certification when you have time, which can be great if you have family or other responsibilities.
Some doula certification programs give you a full year to complete your work, and others have no time limit on when you have to finish.
Expect to spend 16-24 hours taking an in-person or online workshop and at least 15 hours supporting parents during labor to satisfy certification requirements. You’ll also typically have to read at least seven books, complete written assignments, and take quizzes to satisfy certification requirements.
What are the services a doula can provide?
According to the Mayo Clinic, a birth doula can provide many services and benefits:
Provide ongoing support before, during, and after labor and delivery
Explain the birth process, including any procedures that may occur
Act as a communicator between the parents and hospital staff
Educate parents about birth options and teach them ways to be more comfortable during labor, like breathing and massage techniques
WebMD lists the following services a postpartum doula can provide:
Education, support and assistance with breastfeeding
Share strategies for taking care of a newborn, such as how to soothe, feed, change and properly lay the baby down for a nap
Help with post-birth comfort and ensure the mother is adjusting to motherhood and healing from childbirth
Provide child care so parents can rest or run errands
How much does a doula make on average?
How much money you’ll make as a doula depends on where you live, how much you decide to work, and what sort of certification you have. Doulas who are certified by a reputable organization, like DONA International, can charge 10%-20% more than doulas who aren’t.
According to career site Indeed, in large cities like New York, Los Angeles, and San Francisco, doulas usually charge between $1,600 to $2,000 per birth. If you’re able to attend four births a month that could earn you up to, you could make up to $8,000 per month—or up to $96,000 per year.
In mid-size cities, like Cincinnati, Atlanta, and Austin, doulas usually charge $900 to $1,400 per birth. This can net you up to $5,600 per month if you assist in four births or up to $67,200 per year.
In smaller cities, expect to make anywhere from $600 to $1,200 per birth. This means you can make up to $4,800 per month for four births or up to $57,600 per year.
In the case of postpartum doulas, most charge by the hour. Average salaries range from $20 to $50 per hour, depending on your location and the services you offer. If you work 40 hours a week as a postpartum doula, you could make up to $2,000 a week, which would work out to more than $90,000 annually.
What does a doula’s schedule look like?
As a doula, your schedule will vary depending on the role you take. According to the American Pregnancy Association6:
A birth doula may schedule time (maybe an hour or more) to talk with a mom-to-be about what to expect during labor
An antepartum doula may block out time to offer emotional support for a mom who is on bedrest because of a high-risk pregnancy
A postpartum doula may offer to watch the baby while the mom takes a nap or help with the breastfeeding process
Your day will begin based on the needs of the client, so it may start in the morning, afternoon, or evening. If you are planning to work as a part-time doula, there is flexibility to take on clients while still respecting the needs of your own family and job.
You have the choice of seeing one or multiple clients in a day, and you can also choose to offer video chats to provide support when you can’t be there in person but want to answer client questions.
Darcy Sauers, owner of The Doula Darcy, is a doula business coach, certified postpartum doula, and certified lactation counselor.
“I truly view my work and time with a new family as sacred,” Sauers says.
As a postpartum doula, she says she tends to work in four to five-hour shifts. According to Sauers, a typical shift can include:
Discussion with the new mom to answer questions and find out how the night went
Preparing a beverage, meal, or snack while mom cuddles with the baby
Asking the mom what she needs the most that day
Assisting with breastfeeding by assessing the baby’s latch or addressing concerns
Performing light household chores such as laundry or washing dishes
Watch the baby and older sibling so mom can take a nap or bathe
Provide non-judgmental support and offer gentle tips and suggestions
Bottom line: Is becoming a doula worth it?
Becoming a trained doula can definitely be worth it for many people. The work is certainly meaningful—research shows women who have the support of a doula have more positive birth experiences and pay less for medical expenses, and being part of such a meaningful moment in a family’s life can be rewarding for many doulas.
Plus, as a doula, you get to run your own business and have flexibility over how much you work. Depending on your location and credentials, you can earn anywhere from $500 to $2,500 per birth.
But while being a doula can be rewarding—and you can make good money doing it—it’s hard work. Because labor is often unpredictable, expect to put in long hours from time to time.
The bottom line: If you’re someone who thrives at comforting, nurturing, and supporting others—and you don’t mind the occasional long hours—then becoming a doula could be a worthwhile career move.
“Not Just Another Delivery: Women’s Maternity Care Experiences of Provider Client Relationships,” by Megan Aston, Dalhousie; Christine Saulnier, Midwifery Coalition of Nova Scotia; and Karen Robb, Midwife Practitioner. University of Toronto. https://tspace.library.utoronto.ca/bitstream/1807/24420/1/9.1_aston_etal.pdf
“About the Doula Medicaid Project,” National Health Law Program. https://healthlaw.org/doulamedicaidproject/
“Welcome to the Equity and Inclusion Division,” Oregon Health Authority. https://www.oregon.gov/oha/ei/Pages/index.aspx
“Expanding Access to Doula Care: State of the Union,” Maternal Health Task Force at the Harvard Chan School. Jan. 8, 2020. https://www.mhtf.org/2020/01/08/expanding-access-to-doula-care/
“Having a Doula – What are the Benefits?” American Pregnancy Association. https://americanpregnancy.org/healthy-pregnancy/labor-and-birth/having-a-doula/
What qualifications do I need to be a doula?
While you don’t need a degree or state license to be a doula, many doulas decide to become certified through an organization like Doulas of North America (DONA) International or the International Doula Institute (IDI). Certification programs can help you learn valuable skills, become a more desirable job candidate, and earn you more money.
How much does a doula make?
Most full-time doulas average four births per month and charge flat fees ranging anywhere from $500 to $2,500 per birth depending on their location and experience.
Can you receive an online doula certification?
There are a number of reputable organizations offering online doula certification.
How long does it take to become a doula?
How long it takes to become a doula depends on which online doula certification you choose. Most programs can be completed within three to six months, though some take less time.
How much does doula training online cost?
Doula certification costs vary widely depending on the program. Costs range from as little as $100 for a basic online certification course on becoming a doula, all the way up to $1,100 for a more comprehensive online certification course from DONA International, a leading doula training organization.
Co-parenting apps are designed to be an ecosystem in which divorced or separated co-parents communicate, schedule on a shared calendar, and in some apps, track and share expenses, access documents and contacts and otherwise manage your kids’ lives.
Often, courts require moms and dads use co-parenting apps, sometimes attorneys or therapists recommend it, and more and more, parents decide on their own to use co-parenting apps.
OurFamilyWizard (sometimes mistakenly called, ‘My Family Wizard’) is a co-parenting app used by tens of thousands of parents to make it easier to share a calendar and schedule, text, share documents and information and other features for better communication — that can be used in court if needed.
OFW is a quality co-parenting app, that is the most widely used and most-recognized by courts — and most often ordered by judges and court mediators, and recommended by attorneys and family therapists.
There are many, many co-parenting apps on the market, and I feel confident that Our Family Wizard is the top choice. After years of complaints of poor technology and customer service, OFW has seen dramatic improvements after being acquired by private equity firm Spectrum Equity in 2020.
I personally do not use Our Family Wizard, as my kids’ dad and I rely on regular text, Google Calendar, email occasionally Zelle to manage our two teenagers.
However, if you are required or are considering a co-parenting app to keep all your calendars, finances, documents like health insurance and medical info, babysitters and school contacts, birth certificates and the like in one place, as well as a secure way to document and share finances, Our Family Wizard is worth the investment for many families.
Keep reading for more details about exactly how this app works, and its pros and cons.
Our Family Wizard reviews from the App Store
OFW has a 4.5/5 star review on the Apple App Store, based on more than 32,500 ratings. As of this writing, the app has most recently been updated May 14, 2025.
User reviews generally report the app is useful and the best of the co-parenting apps, but negative reviews report too many bugs.
Our Family Wizard reviews from Google Play
On Google Play, where OFW has been downloaded more than 100,000 times, the app has 3.9/5 stars based on more than 10,680 reviews. It was most recently updated June 26, 2024.
How does Our Family Wizard work?
Here is how Our Family Wizard works:
Each parent creates their own account
You can then connect OFW accounts by inviting the other parent (or vice versa!)
You can then immediately synch calendars, exchange messages inside the app, document and send requests for reimbursement for expenses, and more. Other features include:
OFW Tone Meter that flags any inflammatory language that could start an argument — or get you in trouble in family court
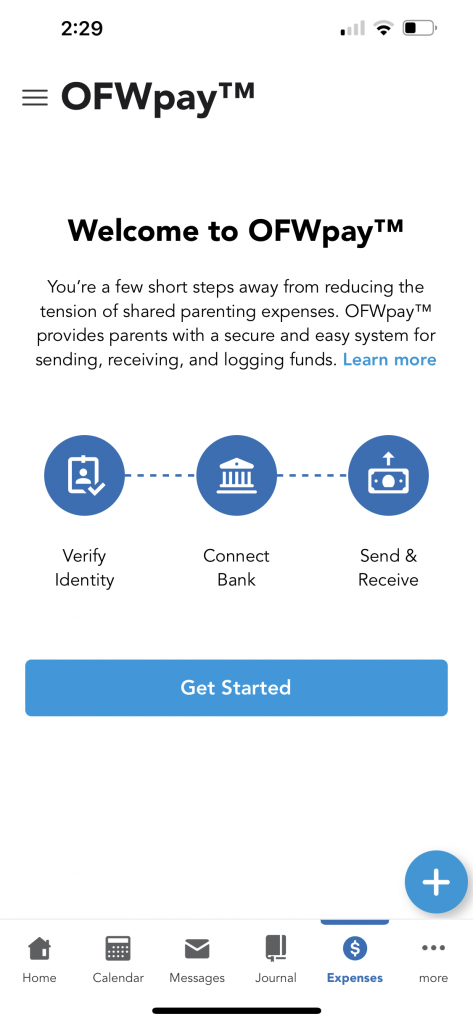
OFW money app, OFWPay, allowing you to connect your bank and send and receive money through the app
Our Family Wizard app features
Of all the co-parenting apps we tried, the Our Family Wizard app has the most features, and all in one, easy-to-use parenting portal. The overall goal of Our Family Wizard is to help separated and divorced parents improve co-parent communication and better facilitate coparent and shared parenting schedules.
You can grant your family lawyer or mediator access to Our Family Wizard, which can help in any disputes and facilitate parallel parenting, whether or not a court and judge are involved.
Our Family Wizard features include:
Our Family Wizard app calendar
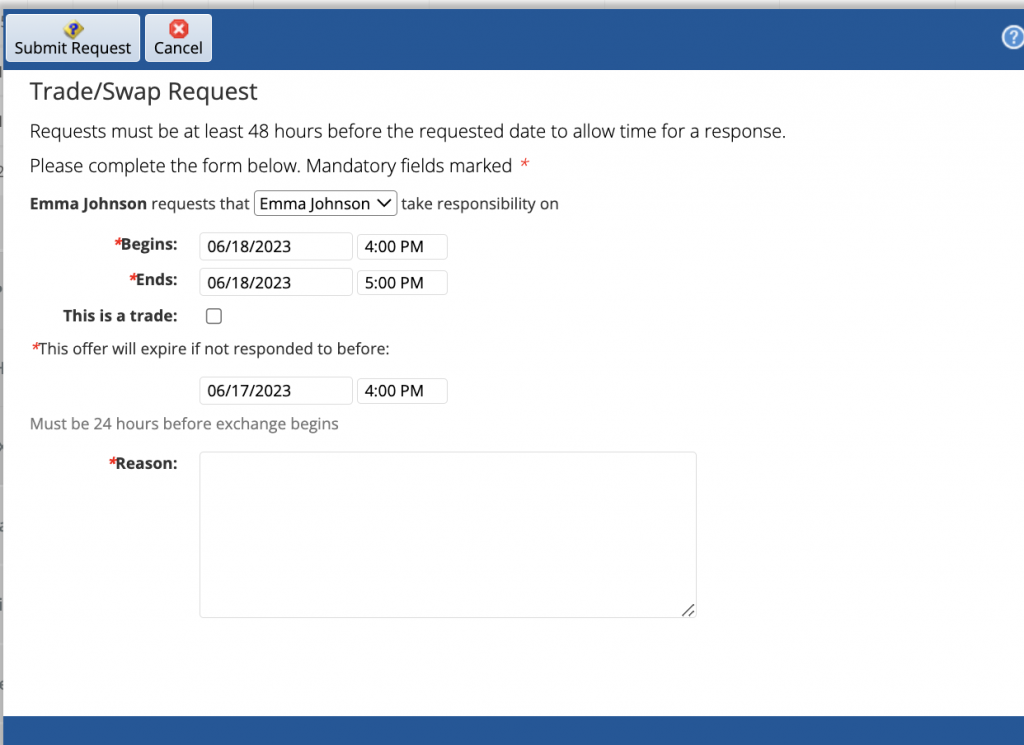
While a shared calendar is the most obvious, and most widely used coparenting app feature, Our Family Wizard’s calendar is easy to use to set a co-parenting schedule, as well as request, agree to, and reject schedule trades, keep track of custody for holidays, kids’ activities, and manage first rights of refusal.
The swap feature is especially handy and a LOT easier and less stressful than using text or verbal communication for many of us:
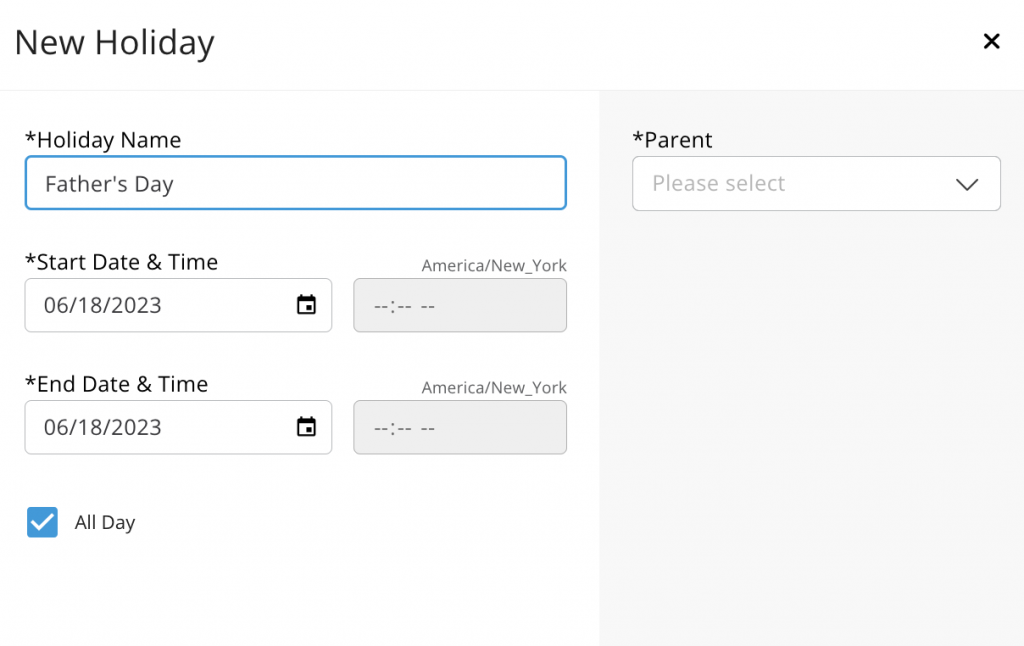
A new feature includes the Holiday Schedule Builder to help families navigate what is often the most stressful and emotionally charged part of co-parenting. This feature is simple to use as it allows you to select one of dozens of national holidays, auto-populates the date, and allows you to choose which parent has the kids that day — and at what time.
Unlike texting or email, OFW messages cannot be deleted or altered. Similar to iPhone messages, these messages are time-stamped, and it is recorded if and when the other party reads them.
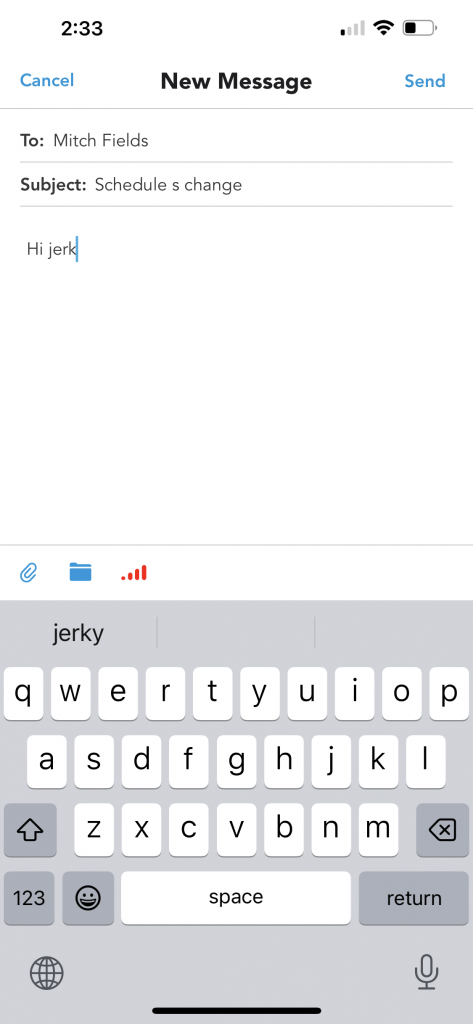
Interesting (and fun / funny feature, if you ask me) is the Tone Meter, which you can pay an extra $10 for in the build-your-own model, or is included in the standard package. This little icon goes from grey to red when the message you are typing has language that you should really, seriously reconsider. He is what it looks like when I was playing around with it in a message to my boyfriend who is 100% a REALLY NICE GUY:
Like other information recorded inside of Our Family Wizard these messages can be downloaded and submitted for court records for an additional fee, but only by a legal professional with an OFW account.
Our Family Wizard app expense sharing
Often, parents who have shared custody also must manage shared, out-of-pocket expenses for the kids, including medical and dental bills, school fees and expenses for extracurricular activities.
Our Family Wizard’s expense log makes it easy to document expenses as they occur, share screenshots of receipts, automatically split the bill between parents based on an agreed-upon percentage (for example, if one parent is required to pay 30% of medical expenses, the actual sum owed by each parent would be calculated automatically) — as well as whether the cost-sharing has been paid.
Recently, the app introduced its OFWPay — an in-app payment tool that connects your bank accounts, more or less like Zelle or Venmo. Unless you are doubling down on documenting all your interactions with your ex for legal reasons, I’d suggest just relying on Paypal, Venmo, Zelle, cash, checks, bank transfers or other ways of paying, but that is up to you.
Our Family Wizard app check-in feature
Whether you are on friendly terms with your co-parent and want to let them know you arrived at your brothers’ house safely, or need to document that you arrived on time for your parenting time, the Our Family Wizard time-stamped geo-tracking check-in feature allows a parent to document exactly where they are at any given time.
Does Our Family Wizard record phone calls?
No. Our Family Wizard only records text and email communications through the app using the following tools:
Shared family calendar
Journal for location check-ins and recording memories
Expense log for shared parenting costs
Message board for secure messaging between co-parents.
These tools are designed to decrease the number of emails and text messages needed between co-parents, which can lead to confusion and conflict.
Can you FaceTime or make phone calls on Our Family Wizard?
Video and phone calling is not currently available on Our Family Wizard, though you can use the app to plan and schedule times for phone and video chats on third-party platforms like Facetime and Zoom.
Our Family Wizard ToneMeter
For an additional $10, the ToneMeter is a unique tool that helps reduce conflict between co-parents. As you write a text, ToneMeter flags any inflammatory language that could make your life a lot more difficult (even if you feel better in the moment! No judgment — I’ve been there!):
Option for attorney access — keeps everyone honest! Plus, you can communicate with your attorney within the Our Family Wizard app.
Notifications — get alerts to new messages, schedule change requests, and document uploads
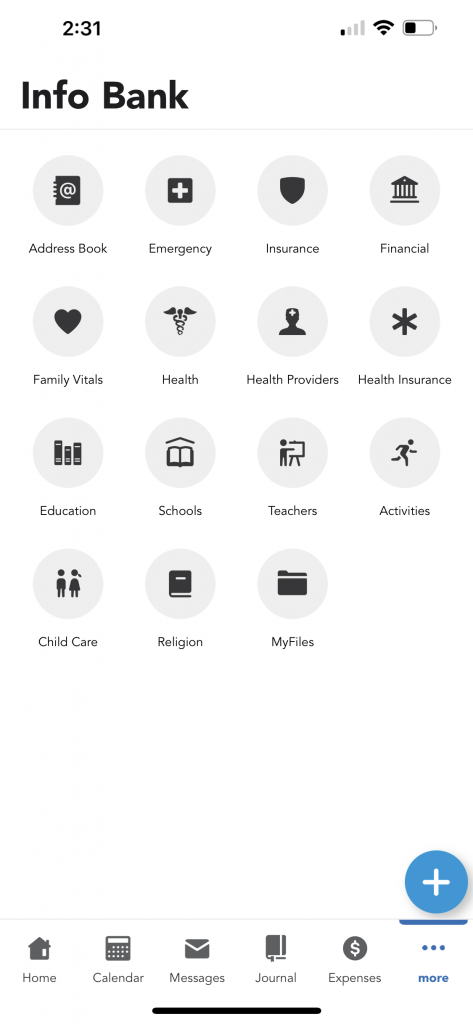
Info Bank, so you can keep track of important information and contacts like:
Passport info
Social security numbers
Insurance cards
Doctors’ contacts
Medical and prescription info
Phone numbers and addresses of family members, babysitters and nannies, school, daycare and friends.
Upload documents like a parenting plan, separation or divorce agreement, or school documents like an IEP or report card.
Military discount
Fee waivers for families in need
30-day free trial, with 100% money-back guarantee
Our Family Wizard cost: Pricing questions answered
Is Our Family Wizard free?
No, both parents have to pay for Our Family Wizard, except for military families, who get a BOGO offer. But, there is a free 30-day money-back guarantee for everyone:
Our Family Wizard offers financial aid to families who qualify, and the app has granted more than 8,000 families free or reduced use of the app as of November 2024.
How much does the Our Family Wizard app cost?
Below is a breakdown of Our Family Wizard’s pricing:
Choose your own plan, or
Essentials annual price: $149.99, or
$216 annually for a premium account
Discount for military families (see the site for info — no promo code needed)
Fee waiver for families in need
You can add all other people for FREE: children, attorneys, step-parents, grandparents, babysitters.
Our Family Wizard discount code: Is there a promo code or discount available?
OFW does not work with coupons or discount codes. However, the app will provide 100% financial aid to those who qualify, as well as military discounts.
Our Family Wizard fee waiver program: Who is eligible?
OFW does have a military discount, as well as a fee waiver program for families who fill out their applications and qualify. With each membership, there are an unlimited number of people who can be added on to the account for free.
You qualify for an Our Family Wizard fee waiver and will get the app for free, if you receive certain public benefits including housing or utility assistance, Medicaid, or food assistance.
To qualify for the fee waiver, each co-parent must apply.
Do both parents have to pay for the Our Family Wizard app?
Yes. You have to use OurFamilyWizard with your co-parent. Each parent has to create their own account, and each account requires a membership fee.
Then, each of those parents can add unlimited numbers of other people: Children, babysitters, grandparents, friends, step-parents, lawyers, nannies.
Is Our Family Wizard monitored?
You can give access to professionals involved in your co-parenting case to monitor your account.
Does OurFamilyWizard track you?
OFW does not track your location. However, there is a “check-in” tool that allows you to share your location, or prove your whereabouts. The check-in is recorded in real-time in the app.
Who can access OurFamilyWizard?
In addition to the parents themselves, judges, attorneys, and mediators can be given access to Our Family Wizard free of charge. Judges and attorneys can subpoena OFW records.
Professionals can monitor multiple accounts and keep track of the families they’re working with.
If you are working with an attorney, mediator, therapist or other professional, you can grant them all access to your whole account. A judge may order this professional to have access.
Is Our Family Wizard admissible in court?
Yes, this communication can be subponeaed, or otherwise downloaded — for a fee, and only by someone with a professional Our Family Wizard — and used as evidence in court.
Parents whose lawyers suggest they use a co-parenting app
Divorced parents
Separated parents
Parents who were never a couple
Parents who frequent family court and need documentation of visits, communication and expense payment
Parents who share equal, 50/50 custody or joint custody parenting plans
Parents who have sole custody, or are working together to co-parent in a variety of visitation schedules
High-conflict parents who communicate exclusively through OurFamilyWizard, which can help with interpersonal conflict management
Parents who co-parent amicably, but like the convenience of keeping all information and communication about the children inside of one app
Parents who need help to manage right to first refusal custody
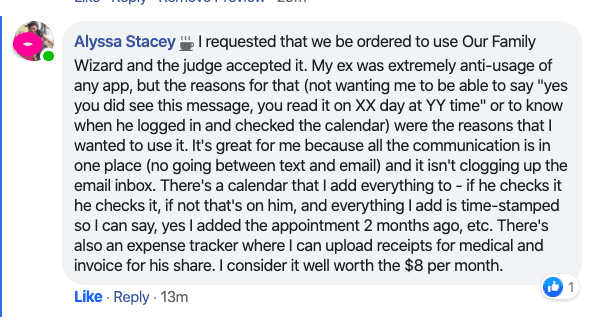
Alyssa Stacey, a divorced mom of one, says this:
I requested that we be ordered to use Our Family Wizard and the judge accepted it. My ex was extremely anti-usage of any app, but the reasons for that (not wanting me to be able to say “yes you did see this message, you read it on XX day at YY time” or to know when he logged in and checked the calendar) were the reasons that I wanted to use it.
It’s great for me because all the communication is in one place (no going between text and email) and it isn’t clogging up the email inbox. There’s a calendar that I add everything to – if he checks it he checks it, if not that’s on him, and everything I add is time-stamped so I can say, yes I added the appointment 2 months ago, etc. There’s also an expense tracker where I can upload receipts for medical and invoice for his share. I consider it well worth the $8 per month.
Tips for how to use OurFamilyWizard co-parenting app:
Be consistent. Always use the messaging feature within the app — never your personal text or email
Always stick to your agreement for how you will use the app, even if the other parent does not
Keep in mind how all the features help you, as well as the co-parent. For example, it is really helpful to have all the kids’ documents in one place — whether or not your kids other parent accesses them.
Our Family Wizard app pros
OurFamilyWizard has been in business since 2001 and is by far the most widely used co-parenting app.
The tool has dozens of features, and for the most part, is very easy to use with intuitive user experience.
The app records activity and conversation for easy court reporting (messages can’t be deleted).
You can give your attorney or mediator access to your account.
OurFamilyWizard’s parent company, Avirat, has an A+ Better Business Bureau rating, which BBB attributes to one unresolved customer complaint.
OurFamilyWizard is working to improve its ratings across all reporting agencies, resolving individual issues and making the app better for all users. It previously had 3.3 stars on Google Play and now has 3.9 stars.
Our Family Wizard app cons
The TrustPilot score is 1.4 stars based on 44 reviews.
Each parent must buy a subscription.
You cannot use OurFamilyWizard solo — just like with conception, you need two people (however, it is free to add other people … more info below).
Is there an Our Family Wizard alternative?
While there are other parenting apps available, there really are none comparable to Our Family Wizard. Realistically, without Our Family Wizard, you could rely on text or email communication and Google calendar to co-parent with an ex.
Bottom line: Is OurFamilyWizard worth it? Is OurFamilyWizard a good app?
Yes, Our Family Wizard is worth it, especially if you are required to use it, or if you have real legal issues that benefit from documenting all your co-parenting inside of a single app. OFW streamlines co-parenting with an ex, reducing the need for communication and allowing you to share essential information about your children.
You can share a calendar and schedule, text, share documents and utilize other tools for better communication. Plus, you can use the app to document communications for court if needed.
That said, many parents would be best-served to just rely on regular text, email, sharing the calendar you normally use (Google Calendar, iCal). Adding another app to your phone — especially if it is devoted to someone you really dislike or even have negative feelings about means you are unlikely to use it effectively.
If you do use OFW, here are our tips for making the most of it:
Be consistent. Always use the messaging feature within the app — never your personal text or email
Always stick to your agreement for how you will use the app, even if the other parent does not
Keep in mind how all the features help you, as well as the co-parent. For example, it is really helpful to have all the kids’ documents in one place — whether or not your kids other parent accesses them.
No, both parents have to pay for Our Family Wizard, except for military families, who get a BOGO offer.
How much does the Our Family Wizard app cost?
One year of Our Family Wizard starts at $149.99.
Is there a promo code or discount available?
OFW does not work with coupons or discount codes. However, the app will provide 100% financial aid to those who qualify, as well as military discounts.
Do both parents have to pay for the Our Family Wizard app?
Yes. You have to use OurFamilyWizard with your co-parent. Each parent has to create their own account, and each account requires a membership fee.
Is OurFamilyWizard worth it?
Yes, Our Family Wizard is worth it, especially if you are required to use it, or if you have real legal issues that benefit from documenting all your co-parenting inside of a single app. OFW streamlines co-parenting with an ex, reducing the need for communication and allowing you to share essential information about your children.
Medical billers and coders handle health care claims and payments for health care providers, insurance companies, and patients. They do so by using universal medical codes, which describe the treatments and services a patient receives, as well as what the provider charges so insurance companies can provide reimbursement.
Medical billers and coders work for hospitals, doctor’s offices, and other medical facilities. They ensure these facilities continue to run smoothly by securing payer reimbursements, adhering to regulatory compliance, and enabling continuity of care.
With the rising need for health care services across the U.S., medical billing and coding is a rapidly growing field. It’s also a great choice if you’re looking for a rewarding career change.
“Medical coding and billing are excellent career choices because there is so much room for growth,” says Kaitlyn Brack, a medical coding quality analyst and approved instructor for the American Academy of Professional Coders (AAPC).
Though many medical billing and coding jobs require you to be onsite in a physician’s office, hospital, or clinic, a number of flexible, work-from-home opportunities also exist.
Coders and billers can specialize in different types of health care or learn specific skill sets like auditing, compliance, practice management, medical transcription, revenue cycle, and health informatics.
You do not need a degree to become a medical coder, though most employers prefer candidates who have a certificate from a certified medical coding program (plus certified medical billers and coders make more money). According to the AAPC, medical coders, on average, make $47,200 per year without certification and $60,097 with certification.
Here’s what you need to know about becoming a medical biller and coder:
If you’re interested in becoming a medical biller and coder, these are some steps you should take:
Step 1: Take an online course
While a certificate is not necessary to become a medical coder, having one will make you stand out in an applicant pool. And if you are making a career change, having some training will certainly be beneficial when you seek employment.
To become a certified medical coder, you will need to pass one of several standardized exams. Training programs for these exams are offered at vocational and technical schools throughout the country. You will need a high school diploma or equivalent to apply.
These programs provide training for national certification exams and entry-level positions in medical billing and coding. Most coding programs can be completed in a year or less, and many are offered online.
After you complete a program in medical billing and coding, the next step is to get certified. To do this, you will need to receive a passing score on specific exams.
There isn’t one single accreditation agency for medical coding in the United States, but there are several organizations that offer certifications for aspiring medical coders. The AAPC and the American Health Information Management Association (AHIMA) offer some of the most commonly recognized medical coding certificates.
Step 3: Search for jobs with ZipRecruiter and other online job boards
Once you’ve obtained certification, it’s time to start seeking employment. Be sure to update your resume so it includes all relevant training, certifications, and skills potential employers will be looking for in a successful candidate. Include any internships and relevant work experience in your applications.
Brack also has a set of criteria she looks for in the hiring process.
“I looked for individuals who are detail-oriented, eager to learn, who have a strong affinity for compliance, are invested in their education, and who display professionalism,” she says.
Companies hiring for positions in medical billing and coding often post on job sites like ZipRecruiter, Indeed, and LinkedIn. You may also be able to find remote medical billing and coding jobs on FlexJobs.com.
Many schools that offer certification programs have a career services department that can assist you with your resume, interview prep, and job search.
Medical coding certifications
If you are interested in a career in medical coding, it’s a good idea to become credentialed. While it is not a requirement for every company, many employers do require or prefer to hire credentialed employees.
“If you look at medical coding job postings, you will see verbiage like, ‘CPC (Certified Professional Coder) Required,’” Brack says. You might consider the following courses in your journey to get certified:
The course, which can be completed in 4 to 6 months, teaches fundamental coding skills for professional services. Students will leave the course with a broad knowledge in reviewing and assigning the correct procedure and diagnosis code for physician services.
The CPC Preparation Course is available online and can be done at your own pace for $2,595 or live with virtual instruction at set times for $3,395.
Certified Coding Associate (CCA®)
The Certified Coding Associate (CCA) credential from the AHIMA is another great option to help you begin a career in medical coding. Candidates who pass the CCA exam will have successfully demonstrated coding competencies across hospital and physician practices.
You can prepare for the exam at your own pace with an online medical coding course or if you prefer an academic setting, the AHIMA has partnered with a number of accredited schools throughout the country where you can take a course in person. Many of these schools also offer online programs. On the AHIMA’s website, there is a directory of 27 Professional Certificate Approval Programs. Inquire with each school for the format and cost of the course.
To learn more in general about a career in medical billing or coding, consider taking this introductory tutorial from Udemy. The 60-minute mini course covers an overview of medical billing and coding tasks, teaches students how to assign medical codes in a family practice setting, and offers insight into education and experience options to become a medical biller and coder.
Many students across the U.S. are eligible for financial aid, which can cover some or all of the tuition for a course in medical coding, such as the University of Cincinnati’s Online Medical Coder Certificate Program. The curriculum prepares students for both the CPC and CCA exams. The course can be completed in a year and can be done either full or part-time. Students can see if they’re eligible for financial aid by completing the FAFSA (the Free Application for Federal Student Aid) form. Various scholarships are also available from the school.
FAQs about medical billing and coding certifications
Which medical billing and coding certification is best?
For people starting out in medical coding, a CPC or CCA certification is best. “Additional specialty certifications are going to be dependent on the direction your career takes or the place you want it to go,” Brack says.
Which medical coding certification pays the most?
CPC or CPA certification are considered core credentials. According to the AAPC, passing the CPC exam elevates your earning potential by more than $25,000 above annual salaries as those without the medical coding certification. In 2022, CPC salaries average $58,055 per year, the AAPC reports. After obtaining core credentials, you can then go on to achieve additional specialty certifications that can increase your salary.
Brack offers her career path as an example of salary potential as a medical coder: “When I became certified with my CPC, my pay increased $12,000 per year; when I was promoted and passed the Certified Family Practice Coder (CFPC) certification, my pay increased by an additional $6,000 per year; my next career move came after passing the Certified Evaluation and Management Coder (CEMC) certification, and that increased my pay by an additional $9K. There are four core coding certifications, 18 specialty coding certifications, and limitless opportunities.”
FAQs about medical billing and coding as a job
Is medical billing and coding hard?
Medical billing and coding may not be for everyone, Brack says. However, as with most things, persistence pays off.
“I was one of those people that did not excel in the typical subjects, but medical coding clicked for me almost instantly,” Brack says. “The more I invested in my education, the easier those aspects of coding came to me. Thiscareer field is one that you get out of it what you put into it.”
Check out this video that shows a day in the life of a medical biller and coder:
Is medical coding a stressful job?
Every profession has its stresses, and medical coding is no different.
“The most stressful pieces of this profession derive from frequent guideline and coding updates, education, among other things, but that is also what entices so many of us that have a true appreciation for the field,” Brack says.
Does medical coding require math?
Medical coding requires some math, but not extensively, Brack notes. She says most of the time basic addition is involved in billing units of medication, procedures, and other services.
“The services that are billed based on time, like anesthesia, it’s being able to translate minutes into units,” she says.
What is medical billing and coding salary?
Brack says pay is highly dependent on whether a person is credentialed, the number of credentials they hold, years of experience, and their employer.
The AAPC has a salary checker that can help you assess your salary potential. The organization reports that on average, medical coders make $54,797 annually ($47,200 per year without certification and $60,097 with certification).
Ziprecruiter lists the national average salary for medical coders at $44,772 per year ($67,500 at the high end).
Bottom line: Is medical billing and coding worth it?
Medical billing and coding can be a rewarding career choice with room for growth and good earning potential. Get started with a core certification to get a broad knowledge of the medical coding field, then you can move on to additional certifications and specialities if desired.
Which medical billing and coding certification is best?
For people starting out in medical coding, a CPC or CCA certification is best. “Additional specialty certifications are going to be dependent on the direction your career takes or the place you want it to go,” says Kaitlyn Brack, a medical coding quality analyst and approved instructor for the American Academy of Professional Coders.
Which medical coding certification pays the most?
CPC or CPA certification are considered core credentials. According to the AAPC, passing the CPC exam elevates your earning potential by more than $25,000 above annual salaries as those without the medical coding certification. In 2022, CPC salaries average $58,055 per year, the AAPC reports. After obtaining core credentials, you can then go on to achieve additional specialty certifications that can increase your salary.
Is medical coding a stressful job?
Every profession has its stresses, and medical coding is no different.
Does medical coding require math?
Medical coding requires some math, but not extensively, says Kaitlyn Brack, a medical coding quality analyst and approved instructor for the American Academy of Professional Coders. She says most of the time basic addition is involved in billing units of medication, procedures, and other services.
What is medical billing and coding salary?
The American Academy of Professional Coders has a salary checker that can help you assess your salary potential. The organization reports that on average, medical coders make $54,797 annually ($47,200 per year without certification and $60,097 with certification).
Is medical billing and coding worth it?
Medical billing and coding can be a rewarding career choice with room for growth and good earning potential. Get started with a core certification to get a broad knowledge of the medical coding field, then you can move on to additional certifications and specialities if desired.
Are all single moms destined for poverty, loneliness and effed-up kids?
Quick answer: NO.
But being a single mom does not mean you’re destined for the welfare line, free school lunches for your kids, or living in your parents’ basement.
The first step is to convince yourself that your new life will be one that is full, joyous and financially rich.
How do single moms survive financially? Emma’s quick take
Love it or hate it, your finances are one of the biggest parts of your life.
Unfortunately, there are millions and millions of single moms out there that are not giving their finances the attention that the moms deserve. They tell themselves things like:
“Money isn’t that important.”
Everything is harder when you’re broke, and that includes being a single mom. The good news is that there are things you can do to get control over your finances, stop living paycheck to paycheck, and build wealth — and stop stressing over money.
Some of these steps are about logistics: Open a bank account, simplify your budget, check your credit score, consolidate your debt, buy life insurance, and make more money.
Some are about changing your mindset and embrace your new reality as a single mom, let go of past assumptions, set goals to earn more.
And others are about learning how to take care of everything you’re working to build by practicing financial self-care. But all of them will bring you one step closer to living the life that you want for yourself and your family.
Here are my steps for how to survive financially as a single mom after divorce, but living a rich life:
Life insurance can be insanely affordable, easy to get, and just plain smart.
Protecting your family with life insurance is one of the most important decisions you’ll ever make for your loved ones, especially as a single mom.
Nobody wants to think about tragedy striking their family, but not planning for the worst could leave your children without financial security in the event of your passing.
One reason people don’t buy life insurance is because they assume it’s going to be too expensive, but opting for flexible term insurance proves that in most cases, that couldn’t be further from the truth.
If you don’t have a bank account of your own, your very first step should be to open one. Why? Because it makes pretty much everything else in this list a whole lot easier to accomplish.
It also just makes the logistics of life a lot easier, giving you somewhere to cash your checks, transfer money, and get a money order—while making it less likely that you’ll need to rely on a payday loan or check cashing service.
If you are stressed about money, chances are that you are also financially unorganized. Do you fail to stick to a budget (or maybe you don’t have a budget? You’re not alone!)? Don’t reach your saving or investing goals? Are your debt and credit scores a mess?
If you’re not clear on your money situation, chances are you’re avoiding it.
This may include failing to open bills, ignoring due dates, missing payments and looking the other way, or humming and tapping your foot when friends bring up investing.
First things first: Get real with yourself. This means opening all your bills as they arrive. No ignoring them. This is adulthood!
Second, plug all your accounts into a third-party app like You Need A Budget.
YNAB is an app and website that helps you create budgets and meet your financial goals — including paying off debt, saving for an emergency, car, house or education.
The point is to get a single, clear picture of all your money, in one spot.
If you need help to secure or pay for housing, there are a number of programs that can help:
The U.S. Department of Housing and Urban Development (HUD) works with landlords to offer affordable rent to low-income individuals and families. Learn how to qualify for HUD housing, and search for an HUD apartment.
Low-income renters can apply for HUD Section 8 vouchers to pay part of their rent to participating landlords.
There are numerous charities, like the Salvation Army and Catholic charities, that provide rental assistance to low-income families.
Once you understand where your money is going, time to cut the dead wood. You know the usuals: gym memberships you don’t use (get real with yourself, sister! Plus: plenty of free ways to work out.), Hulu, restaurant meals, etc.
No more retail therapy.
No more “treating yourself” to meals out you can’t afford, clothes that break your budget, or gifts for your kids that are outside of your financial goals.
If you are broke, shopping is not a hobby you can afford! Financial stress is not a treat — it is self-punishment!
Use up all the shampoo, soap, toothpaste and mascara in your house before you buy more.
Use up all the cleaning supplies and paper products in lieu of picking some up, blindly, at the market.
Make a strict list before stepping foot in Target and do not stray into the cosmetics departments for a “treat” – and I don’t care how great of a deal you find!
By making each purchase a conscious one, you will feel empowered and confident about your money.
You can cut costs like Netflix and restaurants, raise the thermostat, cut coupons, and negotiate your insurance, and other tasks that do help your bottom line, but keep you focused on surviving financially as a single mom, and how to afford to live.
But there is only so much you can slash.
And super-budget thinking is small thinking.
However, if you focus on earning more, growing wealth, and thriving, the sky is the limit!
Decide today to increase your income, your credit, your bottom line. Recalibrate your energy into a wealth zone.
What can a single mother do to make money? Here are some ideas for making more money:
Take a mentor out for lunch to learn about opportunities in your profession.
Research going back to school.
Consider starting your own business.
Join a local or national networking group.
Hell, attend just one networking event!
Talk to your boss about telecommuting and other life-balance arrangements.
Thanks to the Internet, it’s never been easier to make some extra money on the side.
There are hundreds of ways single moms can make money from home, in your spare time without having to wait tables on the weekend.
You need to have this emergency fund in place to cover expenses in case things go wrong. You never know what is coming around the corner, you could lose your job, something in your home could break down, you may need to consult legal help like that of a family immigration lawyer or something entirely different. Having this fund helps to keep your peace.
10. Check your credit score for free—regularly
Your credit score is probably something that you don’t think about.
I go into the reasons why in my post here.
Let’s be honest, most people don’t spend a lot of time thinking about their score, but that could be a huge mistake.
Your credit score plays a huge role in several areas of your life. It can be the difference in getting approved for a loan or mortgage.
If you’re a renter, there is a chance that a bad credit score will get you declined for an apartment.
Also, when you apply for a job, your employer might check your credit score when you apply.
Having a poor credit score could keep you from getting the dream job or that new apartment.
Are you struggling with debt, or otherwise balancing different credit cards and other bills? Have a lousy credit score? This is a complicated, time-consuming juggle that you need to deal with ASAP!
An important first step is to apply for a 0% balance transfer credit card — which can dramatically speed up your debt payoff process by saving you thousands of dollars in interest and fees.
The answer likely includes a combination of a strict budget, debt pay-off plan, and credit repair.
According to think tank Demos, The poverty rate for single parents is 46 percent for single parents with a young child, compared to 27 percent for single parents with a child older than 5. Black and Latino parents confront still higher poverty rates. For families of children under 18 of any age:
The median two-parent black family had $16,000 in wealth.
The median two-parent Latino family had $18,800 in wealth.
The median single-parent white family had $35,800 in wealth (two-parent white families had $161,300).
Compare this to the 64 percent of successful retirees (those who claimed to be comfortable in their retirement) who saved and invested during their 20s and 30s — prime baby-making and raising years! A recent Allianz survey of professional families found that the average traditional, two-parent family has saved $264,000 for retirement while single-parent families had just $171,000 in savings.
To learn actionable strategies and create your own financial independence roadmap, visit thinksaveretire.
This disparity does not have to be your story.
But you must set some goals to buck the single-mom trap.
Short-term goals might be to pay off a credit card bill, build an emergency savings account, or save up for a vacation.
Long-term goals include buying a home, starting a business, remodeling the kitchen, saving for your kids’ college, or investing for retirement.
One of the simplest ways to get started is by opening a Roth IRA account, which allows for tax-deferred investments of up to $7,000 per year for individual filers. Making regular Roth IRA contributions allows your money to grow with flexible withdrawal options.
It is also critical to view and manage your mental health in tandem with your money — the two are deeply connected. Finally, read this wonderful guide to Self Care Sunday from psychologist Elizabeth Cohen – lots of really unusual advice I had not heard elsewhere.
How can a single mother survive with no income?
Temporary Assistance for Needy Families (TANF) is a government program that helps qualifying low-income individuals and families pay for things like food, housing, and child care. Eligibility requirements vary by state.
However, there are limits to how long you can receive TANF benefits — in Pennsylvania, for example, a person qualifies for a total of 60 months in a lifetime.
Fortunately, there are lots of work-from-home jobs for single moms that allow you to work a flexible schedule.
If you are struggling financially, these are some resources to help:
Yes! There are no limits to how much income you can earn as a single mom. If you want to be a wealthy single mom, check out my advice for obtaining financial success:
How can you get over your fear of being a poor single mom?
It is completely human to assume your life will conform to stereotypes or other ideas that informed your concept of what your life would be like in this stage.
Take time right now to dig into your own limiting money beliefs
What are you, as a single mom, capable of when it comes to your career and money? What is the first thing that comes to mind?
Where did you get that idea? Was it something you were taught growing up? A message from the media or your family? What money messages did you receive from you parents when it came to finances and career?
Write these ideas down. Share them in the comments below. Own them. Your assumptions about what you are capable of are not good or bad. This is just information. You are understanding where you are on your single mom journey, and where you want to go (because really, you can go anywhere you want. Anywhere!).
Focus on how your own career and financial opportunities are so much better than for women in generations past
Today, you and I have unprecedented access to education, jobs, legal rights — opportunities that were unheard of for women even one generation ago, and are still but a dream in most of the world.
Things like get a credit card in your own name, access birth control, keep your job while pregnant, and get into top universities. While we have so far to go in achieving gender equality, solely focusing on the gender gap, and not on your opportunities, is in of itself a limiting habit.
Gratitude is the answer.
I have long practiced daily gratitude, and teach my kids the same. There are many studies that prove that by focusing on what you do have, developing an attitude of abundance, and not focusing on your lack, you physiology actually changes, and your attitude and happiness factors increase.
Anecdotally, I will tell you: The more you focus on the positive, the more you attract the positive. The more positive people you surround yourself with, the more success you will have.
Start your own gratitude practice.
Share in the comments here, or in your journal, or on the back of some announcement from your kids’ school exactly all the things you are grateful for. Your health. Being alive as a woman today. That you can open a bank account in your own name. That you are no longer dragged down by him.
So, here you are in single motherhood. It feels overwhelming, daunting. All around you, it seems, are happily married, two-parent homes where everyone has more.
But even though your life doesn’t look exactly like those two-parent homes, your potential to live a full and successful life is exactly the same.
Bottom line: How do low-income single moms survive financially? With a lot of help
If you are struggling financially as a single mom, there are numerous resources available, including housing assistance, free child care programs, and help for expenses like formula, food, diapers, utilities, and more.
Just pop in your email and immediately get your free guide.
No B.S. I will never sell your contact info.
How can a single mother survive with no income?
Temporary Assistance for Needy Families (TANF) is a government program that helps qualifying low-income individuals and families pay for things like food, housing, and child care. Eligibility requirements vary by state.
How do low-income single moms survive financially?
If you are struggling financially as a single mom, there are numerous resources available, including housing assistance, free child care programs, and help for expenses like formula, food, diapers, utilities, and more.
Can I be wealthy as a single mom?
Yes! There are no limits to how much income you can earn as a single mom. If you want to be a wealthy single mom, check out my advice for obtaining financial success: