One of the most common questions people ask before starting orthodontic treatment is simple: how long is this going to take? Whether you’re considering braces for yourself or your child, understanding the timeline helps you plan, stay motivated, and set realistic expectations. The truth is, treatment length varies widely from person to person — but there are key factors that determine how quickly you’ll reach that confident, straight smile.
No two mouths are the same. The duration of orthodontic treatment depends on a combination of biological, behavioral, and clinical factors. While some patients complete treatment in as little as six months, others may need two to three years or more. Understanding what drives these differences can help you become a more informed patient.
The complexity of your case
The most significant factor in determining how long you’ll wear braces or aligners is the severity of your orthodontic issues. Minor crowding or slight spacing problems are typically resolved much faster than complex cases involving significant misalignment, overbites, underbites, or crossbites. A patient with mild crowding might finish treatment in 12 months, while someone with a severe skeletal discrepancy could require 24 to 36 months — sometimes in combination with other dental treatments.
Age and bone density
Age plays a meaningful role in how quickly teeth move. Children and teenagers benefit from still-developing jaw bones, which makes teeth easier to shift into new positions. Adults, whose bones are denser and more set, often experience slightly slower tooth movement. That said, many adults achieve excellent results with modern orthodontic techniques, and the difference in treatment time is often minimal for straightforward cases.
Common treatment options and their typical timeframes
The type of orthodontic appliance you use also influences how long treatment takes. Here’s a breakdown of the most popular options:
Traditional metal braces
Traditional metal braces remain one of the most effective and reliable orthodontic solutions available. They use brackets, wires, and elastic bands to gradually move teeth into alignment. Most patients wearing traditional braces complete treatment in 18 to 24 months, though complex cases may take longer. Regular adjustment appointments — typically every four to six weeks — are essential to keep treatment on track.
Ceramic braces
Ceramic braces function similarly to metal braces but use tooth-colored or clear brackets for a more discreet appearance. Treatment times are comparable to traditional braces, usually falling in the 18 to 24 month range. They’re a popular option for teens and adults who want effective treatment without the noticeable look of metal.
Clear aligners
Clear aligner systems like Invisalign have grown enormously in popularity due to their removability and aesthetic appeal. For mild to moderate cases, treatment can often be completed in 12 to 18 months. However, compliance is crucial — aligners must be worn 20 to 22 hours per day to be effective. Patients who remove them too frequently can significantly extend their treatment timeline.
Retainers and post-treatment phase
It’s important to remember that active treatment is only part of the journey. After braces or aligners come off, patients enter the retention phase. Retainers are worn to hold teeth in their new positions while the surrounding bone stabilizes. Initially, retainers may need to be worn full-time, then transitioning to nighttime wear. Many orthodontists recommend wearing retainers indefinitely to prevent relapse. Skipping this phase is one of the most common reasons teeth shift back after treatment.
Factors that can extend your treatment time
Several avoidable factors can add weeks or even months to your orthodontic treatment. Being aware of these can help you stay on schedule:
Broken brackets or wires: Damaged appliances slow treatment progress and require emergency appointments to repair.
Poor oral hygiene: Gum disease or tooth decay may require treatment to pause while dental health is restored.
Missed appointments: Regular adjustments are critical. Skipping or delaying appointments puts your timeline behind.
Not wearing aligners as directed: For clear aligner patients, inconsistent wear is the number one reason treatment runs long.
Dietary non-compliance: Eating hard, sticky, or crunchy foods with braces can damage your appliances and set back your progress.
How your orthodontist sets and tracks your timeline
At your initial consultation, your orthodontist will conduct a thorough examination — including X-rays, digital scans or impressions, and photographs — to assess the full scope of your orthodontic needs. From this evaluation, they’ll develop a customized treatment plan with an estimated timeline.
Throughout treatment, your orthodontist monitors your progress at each visit, making adjustments as needed. Modern digital tools and 3D imaging have made treatment planning more precise than ever, giving patients a clearer picture of expected outcomes from the very beginning.
If you’re searching for an orthodontist in Chamblee who takes a thorough, patient-centered approach to treatment planning, it’s worth exploring practices that prioritize both clinical excellence and open communication with patients.
Tips to keep your treatment on schedule
Patients who actively participate in their treatment tend to finish faster and with better results. Here are some practical ways to support your own progress:
Keep every appointment — adjustments are what keep your treatment moving forward.
Practice excellent oral hygiene — brush and floss thoroughly around brackets and wires, or clean your aligners daily.
Follow your orthodontist’s instructions — whether it’s wearing rubber bands, using a palate expander, or keeping your aligners in, compliance matters.
Protect your appliances — wear a mouthguard during sports and avoid foods that can damage braces.
Communicate with your care team — if something feels off or breaks, contact your office promptly rather than waiting for your next scheduled visit.
Finding the right orthodontist for your needs
Choosing the right provider is just as important as choosing the right treatment. A skilled orthodontist in Chamblee will not only develop an accurate treatment plan but will also keep you informed and engaged throughout the entire process. Look for a practice that combines modern technology, personalized care, and transparent communication.
For families and individuals in the area, accessing local orthodontic care in Chamblee means convenient appointments, a familiar community-oriented practice, and the kind of attentive care that makes a real difference in your treatment experience and outcome.
Conclusion
Orthodontic treatment is a journey, not a quick fix — but it’s one that delivers lasting, life-changing results. The timeline depends on your unique situation, the treatment option you choose, and how well you follow your orthodontist’s guidance. Most patients complete treatment somewhere between 12 and 24 months, with retention continuing beyond that to preserve their results.
The best way to get an accurate estimate is to schedule a consultation with a qualified orthodontist in Chamblee. A professional evaluation will give you a realistic timeline, a clear treatment roadmap, and the confidence to take that first step toward a healthier, more beautiful smile.
Planning post-work living requires a realistic assessment of current household expenditures. Future retirees often struggle to pinpoint the exact monthly income needed to cover recurring bills and maintain comfort. Navigating inflation, changing healthcare fees, and shifting daily priorities creates uncertainty for long-term budget planning. Establishing clear target figures allows you to build a secure cushion for your post-career years.
Image Credit: Unsplash
Setting your baseline monthly budget
Effective retirement planning begins with identifying core living expenses. Fixed expenditures like housing costs, property taxes, utility bills, and groceries form the primary foundation of monthly cash requirements. Many financial planners suggest targeting roughly 70 to 80 percent of pre-retirement earnings to maintain standard comfort levels.
Discretionary spending patterns often shift dramatically once full-time employment ends. Travel plans, entertainment choices, and personal hobbies can boost monthly expenses during early years of freedom. Tracking current daily spending habits provides a realistic baseline for projecting future financial needs.
Setting realistic targets involves looking closely at recurring family expenses. Subscriptions, vehicle maintenance, and household goods require steady cash flow throughout the year. Categorizing these line items keeps monthly projections organized and accurate.
Evaluating potential social security benefits
Social Security payments serve as a key foundation for millions of older Americans each year. When testing numbers using an annuity calculator in your planning spreadsheet, seeing how guaranteed cash flows fit into a monthly balance sheet becomes far clearer. Having a predictable income baseline reduces financial stress during volatile market cycles.
Personal retirement accounts work alongside guaranteed government benefits to fill income gaps. Combining personal investments with federal monthly payments creates a reliable financial structure. Balancing these sources protects long-term portfolio stability.
Understanding claim timing remains a crucial component of benefit maximization. Filing at age 62 results in lower monthly checks compared to delaying until full retirement age. Taking time to map out claiming strategies yields higher lifetime payouts.
Understanding federal benefit guidelines
Federal announcements confirm that Social Security and Supplemental Security Income payouts for 75 million recipients will rise by 2.8 percent in 2026. This regular cost-of-living adjustment helps offset price increases across daily household items. Reviewing personal benefit statements gives a clear picture of expected monthly income.
Maximizing monthly government checks depends heavily on lifetime earnings history and claim age. Official agency figures indicate that individuals reaching full retirement age in 2026 can receive a maximum benefit of $4,152 per month. Workers with lower lifetime earnings or earlier filing dates receive smaller monthly distributions.
Delaying claims past full retirement age increases payouts by 8 percent annually until age 70. This automatic increase provides strong motivation for individuals remaining employed longer. Coordinating claim dates with a spouse helps optimize total household cash flow across decades.
Factoring medical costs into your plan
Image Credit: Unsplash
Healthcare expenses represent one of the largest variables in any post-career financial plan. Premium payments for Medicare coverage, supplemental policies, and out-of-pocket prescription costs add up quickly. Planning for medical expenses avoids sudden drains on long-term investment accounts.
A thorough medical budget ought to include space for several recurring categories:
Medicare premiums and supplemental coverage policy fees
Prescription medications and routine pharmacy expenses
Out-of-pocket dental, vision, and hearing care costs
Emergency health funds for unexpected treatments
Long-term care insurance offers another layer of financial protection against extended medical stays. Comparing coverage options early prevents unexpected care costs from eroding personal savings. Dedicating specific funds to healthcare maintains budget stability.
Managing housing expenses and mortgages
Housing remains the largest single line item for most households entering retirement. Paying off a primary mortgage before leaving employment eliminates a major monthly cash obligation. Property taxes, home insurance, and routine upkeep continue regardless of mortgage status.
Downsizing to a smaller property or relocating to an area with lower property taxes offers substantial financial relief. Some retirees choose renting to eliminate property maintenance responsibilities and unexpected repair bills. Weighing physical upkeep against potential rental adjustments helps clarify long-term residential choices.
Location plays a huge role in determining total housing expenses throughout retirement. Utility costs, regional tax rates, and home maintenance prices vary widely by region. Choosing a low-cost region stretches monthly retirement dollars significantly.
Navigating inflation and purchasing power
Rising costs for goods and services steadily erode purchasing power across long retirement spans. A comfortable monthly allowance today will purchase less ten or twenty years down the road. Factoring steady inflation rates into annual withdrawal calculations safeguards personal living standards.
Growth-oriented investments help portfolio balances keep pace with rising consumer prices. Maintaining modest exposure to broad market equities balances short-term stability with long-term capital preservation. Fixed-income assets alone struggle to match compounding cost increases.
Diversifying portfolios across asset classes mitigates inflation risks effectively. Real estate holdings, equities, and inflation-indexed bonds provide steady inflation protection. Adjusting asset allocations periodically keeps purchasing power intact.
Building alternative income streams
Relying solely on savings withdrawals can expose portfolios to market downturns early in retirement. Diversifying income channels creates extra safety buffers for monthly household budgets. Alternative cash flows provide peace of mind during extended market dips.
Consider these common income channels to supplement monthly savings:
Dividend-paying stock portfolios or indexed funds
Rental property cash flows or real estate investment trusts
Part-time consulting work or flexible project roles
Immediate or deferred payout structured investments
Side projects and consulting provide both financial rewards and social engagement. Working a few hours per week generates extra monthly spending money. Supplemental cash flow reduces reliance on portfolio withdrawals.
Creating a flexible withdrawal strategy
A structured withdrawal strategy ensures personal savings endure throughout retirement years. The classic 4 percent withdrawal guideline provides a simple starting point for annual portfolio draws. Adjusting withdrawal rates based on annual market performance preserves core portfolio capital.
Holding 12 to 24 months of living expenses in cash reserves prevents selling assets during market slumps. Cash buffers allow investment portfolios time to recover without disrupting regular income needs. Reviewing withdrawal amounts periodically keeps financial strategies on solid footing.
Dynamic withdrawal rules allow retirees to spend more during market upturns and trim back during down years. Staying flexible protects long-term wealth and maintains financial comfort. Working with financial advisors refines withdrawal calculations effectively.
Finding appropriate monthly retirement income numbers requires balancing personal lifestyle preferences with sound mathematical reality. Evaluating expected Social Security distributions, medical expenses, and housing obligations establishes clear financial targets. Adjusting savings habits today creates enduring financial independence tomorrow. Careful planning and periodic budget reviews help you enter retirement years with complete confidence in your financial future.
That electronic memory game with the four colored buttons is probably still sitting in a box somewhere, batteries long dead, buried under board games nobody plays anymore. The same goes for the drum machine your uncle swore he was going to start a band with, the little black box with the swiveling antenna that used to catch three channels on a good day, and the computer that weighed as much as a car battery and somehow passed for portable.
The 1980s produced an enormous amount of electronics, and not all of it aged the same way. Some of it is landfill. Some of it is quietly worth hundreds, or in a few cases thousands, of dollars to people who know exactly what they’re looking at. The difference usually comes down to which specific model you have, whether it still works, and how much of the original packaging survived.
These are 14 pieces of 1980s electronics worth a closer look before any of it ends up in a donation pile.
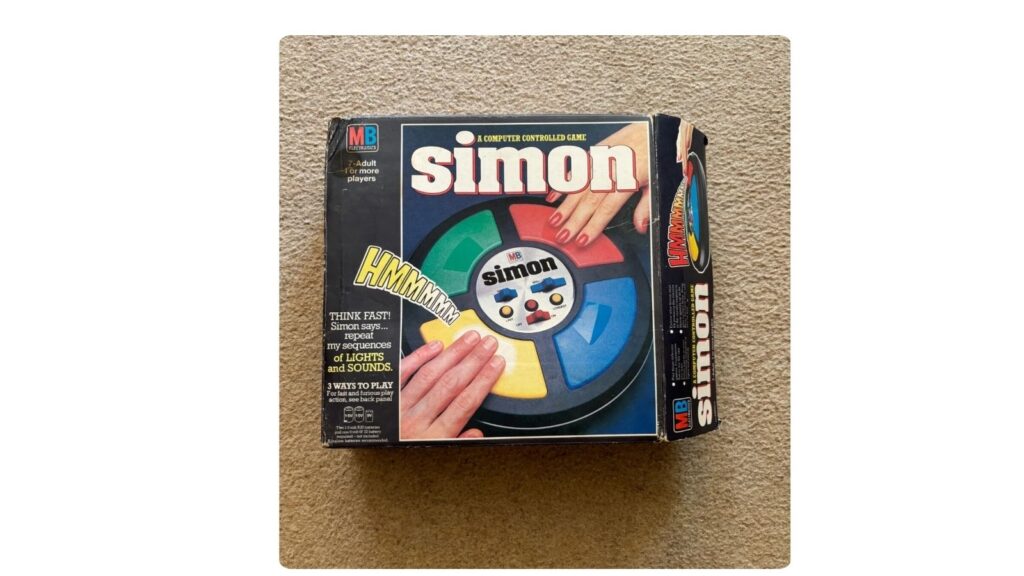
Simon is the electronic memory game with four colored buttons, each one lighting up and beeping in a sequence you have to repeat back, longer each round. Milton Bradleylaunched it at a midnight party at Studio 54 in 1978, and it went on to sell more than 10 million units within a few years. Nearly every household had one at some point, which is exactly why most surviving examples aren’t worth much.
A loose, working Simon in decent cosmetic shape typically brings $15 to $30, and one with its original box and instructions reaches $40 to $70. The appeal holds steady because the four-button design and chirpy sound effects are instantly recognizable even to people who never played it.
Check that all four buttons register reliably and that the volume switch works, since a sticky button or dead speaker is the most common fault. The clear “See-Thru” Simon variant and the smaller Pocket Simon from 1980 turn up less often and carry a modest premium over the standard black model. This isn’t a retirement fund, but it’s a genuinely easy, low-stakes find if one turns up for a dollar at a yard sale.
2. JVC GR-C1 camcorder (1984)
Image Credit: nostalgic_camera_tokyo via eBay
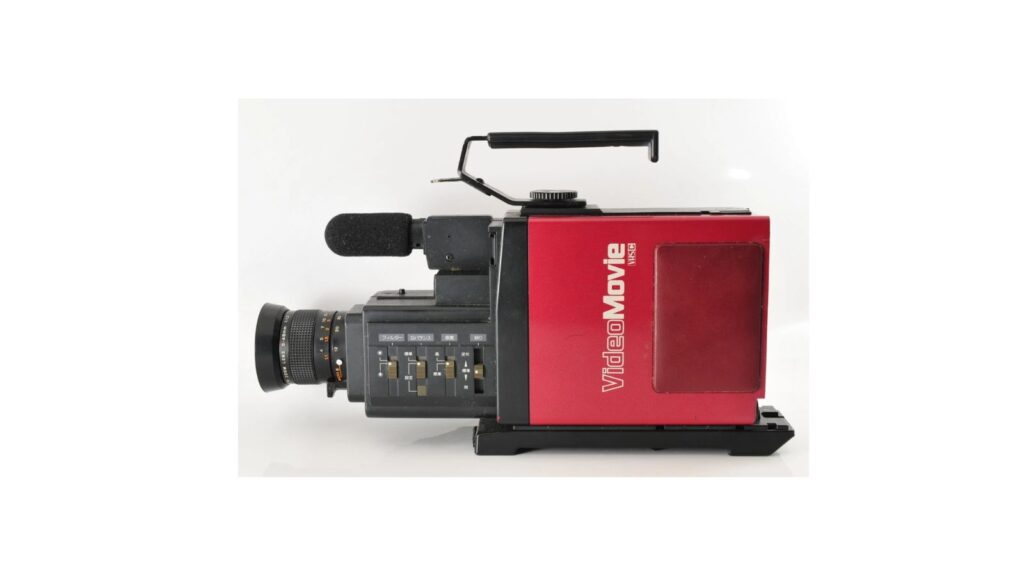
Doc Brown handed Marty McFly a boxy red camera in the opening scene of Back to the Future and called it a “portable television studio.” That was the JVC GR-C1, the first camcorder to combine the camera and the recorder into one handheld unit instead of a shoulder-slung deck wired to a separate camera. It used compact VHS-C tapes that played in any home VCR with a simple adapter shell, which made it genuinely useful rather than just a novelty.
A working GR-C1 with its original battery charger and RF unit typically commands $400 to $900, with the movie connection pushing clean examples toward the higher end. That cameo keeps demand steady among prop collectors even outside the usual camcorder crowd.
These units are old enough that failing capacitors and hardened drive belts are common, and a camera that won’t power on or eject a tape usually needs a repair technician rather than fresh batteries. Streaking across the viewfinder in bright light is a known quirk of the original tube sensor, not necessarily a fault. Confirm the unit actually records and plays back before paying serious money, since a display-only shell is worth a fraction of a working one.
3. Texas Instruments TI-99/4A (1981)
Image Credit: top-of-the-world-ma via eBay
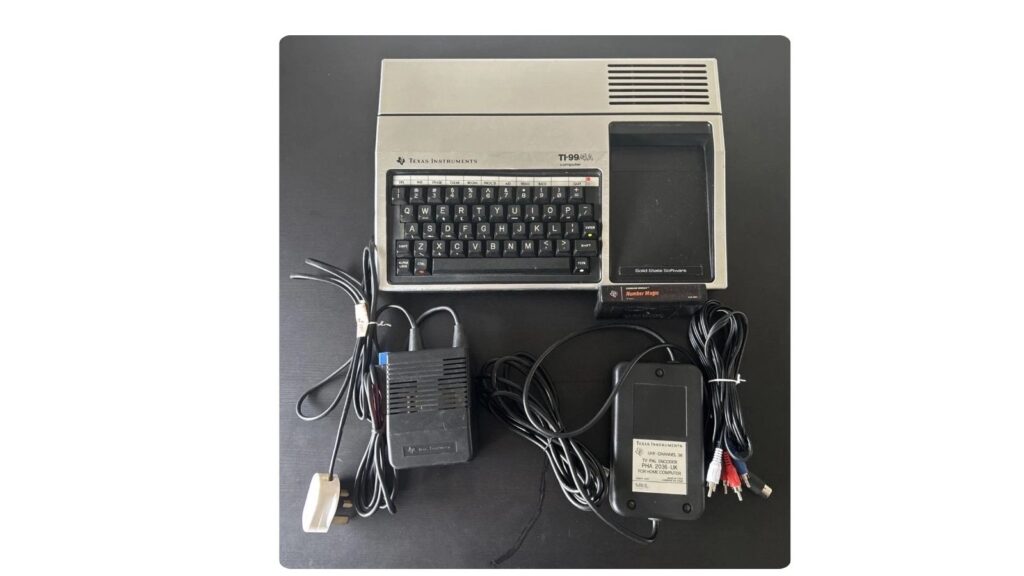
The TI-99/4A was Texas Instruments’ home computer, built around the same chip technology the company used in its calculators, and it briefly undercut Commodore and Atari on price during the early-80s home computer wars. TI sold millions of them before pulling out of the computer business entirely in 1984, which means working units still surface regularly in basements and storage units.
That volume keeps prices modest. A loose, working TI-99/4A typically brings $30 to $60, and a complete example with the original box, power supply, and manuals reaches $100 to $180. The Speech Synthesizer module and cartridge games add a little more when they’re included and tested.
The most common failure is a dead or corroded power supply, so test before assuming the computer itself is broken. Keyboard keys can stick or stop registering after decades of dust, and the membrane underneath isn’t always repairable. Original retail price was $525, which makes even a modest resale a reasonable return, but this is a volume item rather than a rarity. Clean, boxed examples with working cartridges are what actually move for real money.
4. Technics SL-1200MK2 turntable (1979)
Image Credit: Fs-JAPANstore via eBay
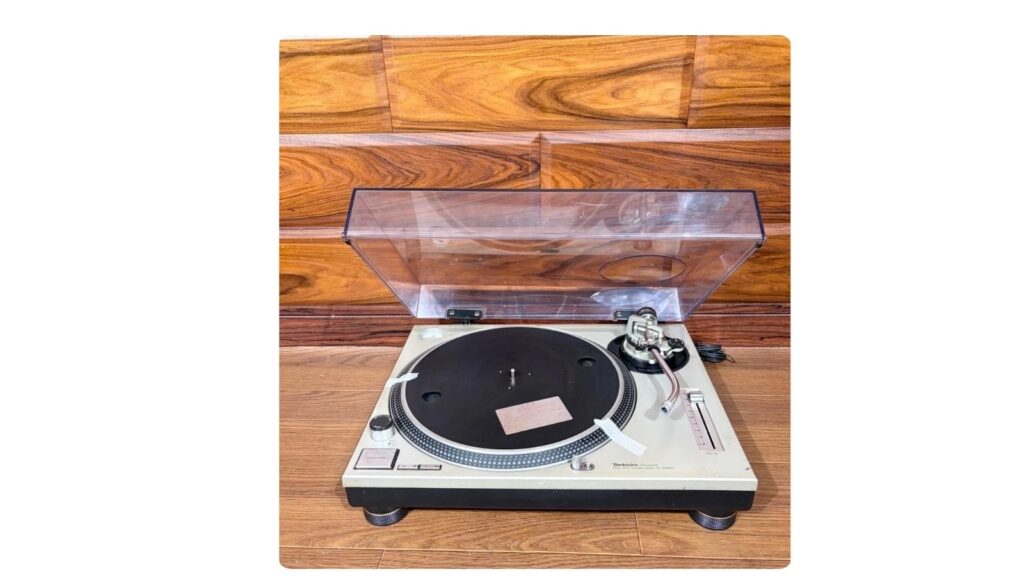
The SL-1200MK2 is the turntable that built hip-hop DJ culture, prized for a direct-drive motor strong enough to handle scratching and a pitch control that let DJs beatmatch two records by ear. Technics kept the design in production for decades with only minor changes, which means a clean MK2 still performs exactly like one would have in 1985.
A well-maintained, working deck without a cartridge typically sells in the $400 to $900 range, depending on cosmetic condition and whether the original dust cover survived. Factory-sealed, never-opened units from the original production run are a different category entirely and have reached well into four figures.
Check that the platter spins at a true, steady speed using the built-in strobe light, since motor wear shows up as pitch drift before anything else fails. The tonearm counterweight and anti-skate dial should move smoothly without grinding. A missing headshell or cartridge isn’t a dealbreaker since both are easy to replace, but a cracked plinth or water damage to the internals is much harder to fix and drops the value sharply.
5. Sony Watchman FD-210 (1982)
Image Credit: Gadget Goodies For Less via eBay
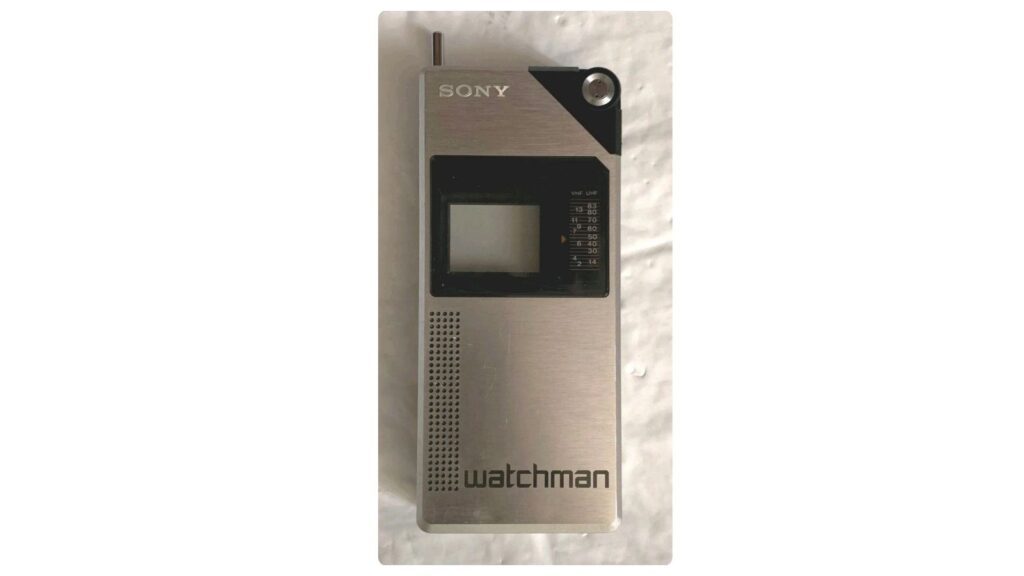
The FD-210 was the first television small enough to fit in a coat pocket, built around a genuinely clever flat cathode-ray tube that let Sony shrink a living room appliance down to the size of a paperback book. It launched in Japan in 1982 and reached the US and Europe in 1984, selling for roughly $300 at the time.
Since over-the-air analog broadcasting ended, a Watchman can no longer pull in live television without a separate digital converter box, which keeps most examples in the hands of collectors rather than actual viewers. Working original silver FD-210 units with their carrying case typically bring $60 to $100, while later plastic-bodied models in the same line usually sell for less.
Test the screen for a stable picture rather than just a powered-on glow, since the flat tube is the one component that can’t be easily replaced if it fails. Battery compartment corrosion is extremely common on anything this age and is usually fixable with a careful cleaning. This isn’t a big payday, but it’s a genuinely distinctive piece of design history for not much money.
6. ColecoVision (1982)
Image Credit: cameron-closet via eBay
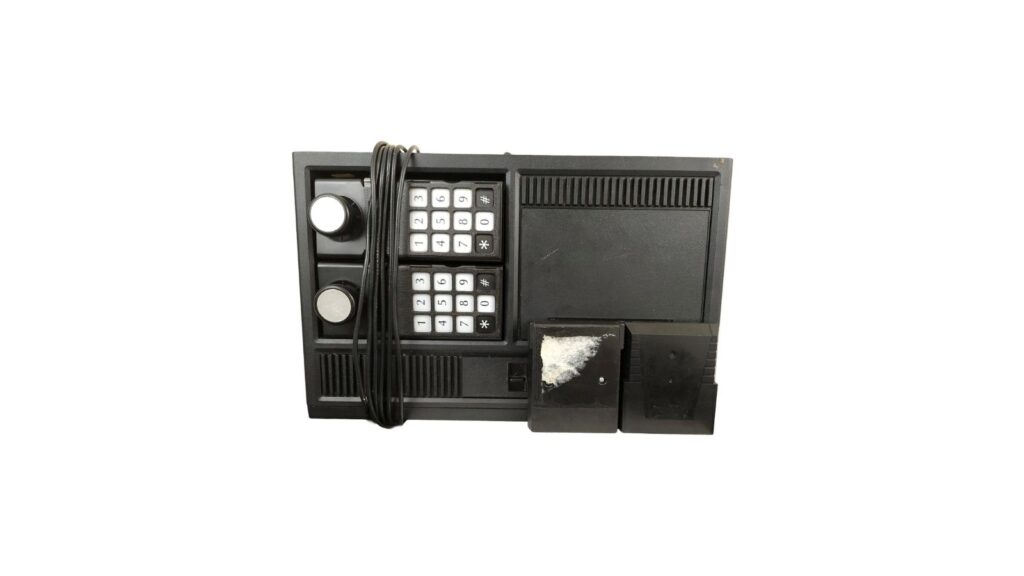
Coleco’s console briefly outmuscled Atari on graphics quality, thanks to a built-in adapter that let it run genuine arcade conversions of games like Donkey Kong at a level the 2600 couldn’t match. It sold well for two years before the video game crash of 1983 ended Coleco’s run in the console business.
A clean, working ColecoVision on its own typically brings $80 to $150, and a complete example with the original box, controllers, and overlays reaches $200 to $300. The Expansion Module that let it play Atari 2600 cartridges adds real value when it’s included and functional.
The controller wires are prone to breaking at the connector after decades of flexing, so test both controllers rather than assuming they work because the console powers on. The numeric overlay panels that slot over each controller’s keypad are commonly missing and worth tracking down separately, since a controller without its overlay looks incomplete even when it technically works. Yellowing on the light grey plastic case is normal and doesn’t hurt value much on its own.
7. Casio VL-Tone VL-1 (1981)
Image Credit: Shop Keepers Pawn via eBay
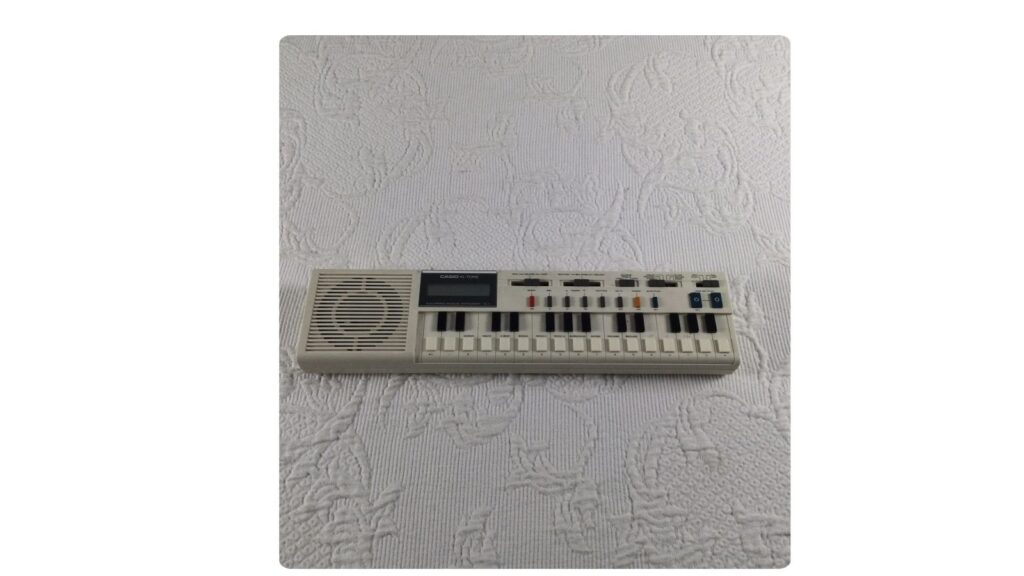
The VL-1 is a calculator, a drum machine, and a monophonic synthesizer crammed into one battery-powered unit small enough to carry in a bag. Casio marketed it as a novelty, but its tinny, instantly recognizable sound ended up on records by the Human League and the Cars, and most famously anchors the French duo Trio’s 1982 hit “Da Da Da.”
A working VL-1 in good cosmetic condition typically brings $70 to $150, with boxed examples including the manual pushing toward the higher end. The calculator mode still works on most surviving units, which is a quick way to confirm the logic board hasn’t failed.
Check that all 29 keys register and that the small built-in speaker produces clean sound without crackling, since a blown speaker is a common and sometimes tricky repair on a unit this small. The soft carrying case Casio included is often missing and adds a little to the price when present. This is an easy, cheap way into vintage synth collecting, and genuinely useful for anyone who wants that specific lo-fi sound rather than just a shelf piece.
8. Osborne 1 (1981)
Image Credit: YellowChoo via eBay
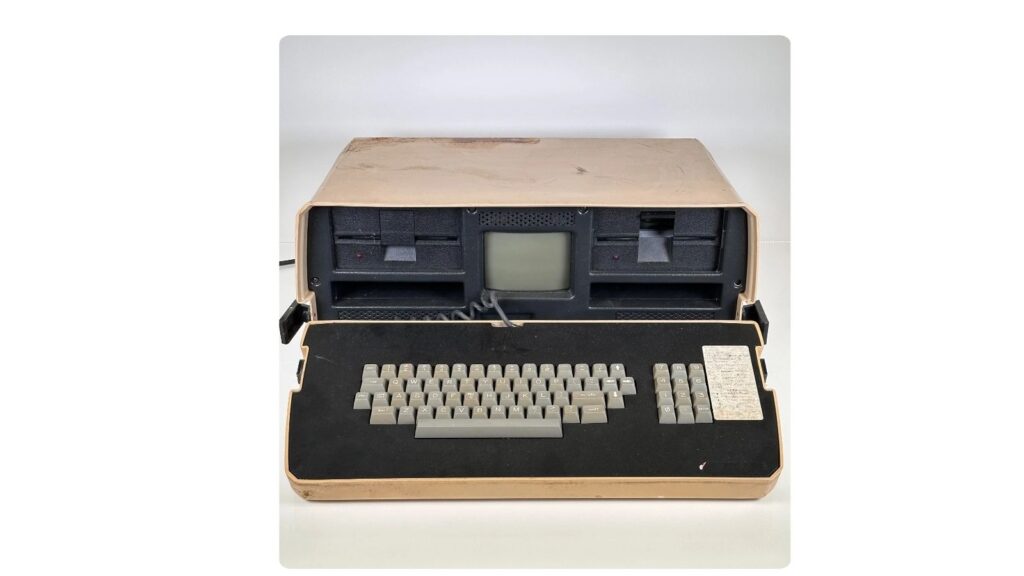
The Osborne 1 was the first portable computer to actually sell in meaningful numbers, a 24-pound case with a built-in 5-inch screen and two floppy drives that Osborne marketed as something that would fit under an airline seat. It shipped with word processing and spreadsheet software worth almost as much as the hardware itself, which was unheard of at the time.
Working examples typically bring $200 to $400, and upgraded or boxed survivors with their accessories have reached $800 or more. The company’s rapid rise and 1983 bankruptcy are part of what makes an intact example appealing to computing history collectors specifically, not just general vintage tech buyers.
The floppy drives are the weak point. Decades of sitting unused lets the internal lubricant solidify, so a drive that grinds or fails to read a disk usually just needs cleaning and relubrication rather than full replacement. Test that the small built-in screen displays text clearly, since a dim or flickering display points to a failing component that’s harder to source than most other parts. This is heavy and awkward to ship, which keeps some buyers away and holds prices more reasonable than the history might suggest.
9. Nintendo Game & Watch Donkey Kong (1982)
Image Credit: RetroXElectro via Etsy
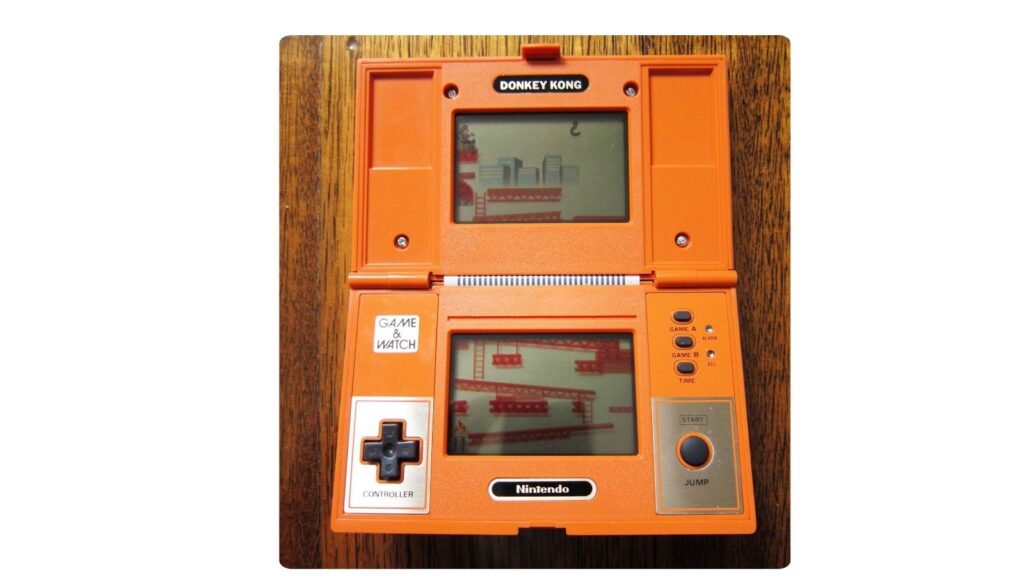
Nintendo’s Game & Watch line put a single game and a working clock into a flat plastic case small enough for a shirt pocket, years before the company made a home console people actually remember. The Donkey Kong model used a dual-screen “multi screen” design, a hinge-opened case with one screen for the ladders Mario climbs and another for the barrels Donkey Kong throws, and it was one of the best-selling entries in the whole series.
A loose, working Donkey Kong Game & Watch typically brings $80 to $110, and a complete example with the original box and manual reaches $220 to $300. Other multi-screen titles in the series follow a similar pattern, with scarcer titles commanding noticeably more.
LCD segments can fade or die with age, so check that every digit and figure on both screens displays fully before buying. The hinge is a common failure point on multi-screen models, since repeated opening and closing over forty years wears down the plastic pins. A unit that won’t stay open on its own, or that pops shut mid-game, has a worn hinge that’s difficult to repair properly.
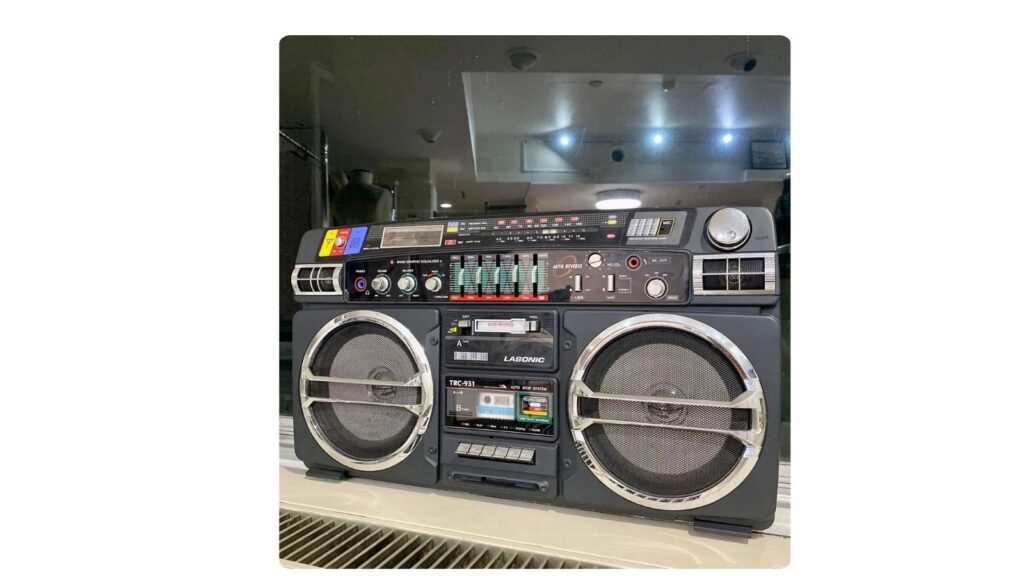
10. Lasonic TRC-931 boombox (1981)
Image Credit: MEKKEMON_JPN via eBay
The TRC-931 is one of the most recognized boomboxes of the hip-hop era, with a squared-off silver and black body, chrome detailing, and a sound that made it a fixture in early rap videos and street photography. Lasonic built later versions of the 931 with updated features, but collectors specifically want the original first-generation cassette model.
Clean, working first-generation units typically sell for $350 to $600, with originality mattering more than almost anything else in that range. Later reissues and the CD-equipped CDX-931 variant that followed the same body style are considered less desirable by serious collectors even though they share the same look.
The cassette mechanism’s rubber belts degrade on nearly every surviving unit, so don’t assume a boombox that won’t play tape is beyond saving. Chrome trim pieces scratch easily and are hard to source as replacements, so cosmetic condition on the metal accents matters more than on the plastic body. A unit missing its original speaker grilles or with mismatched screws is a sign it’s been repaired with non-original parts, which brings the price down.
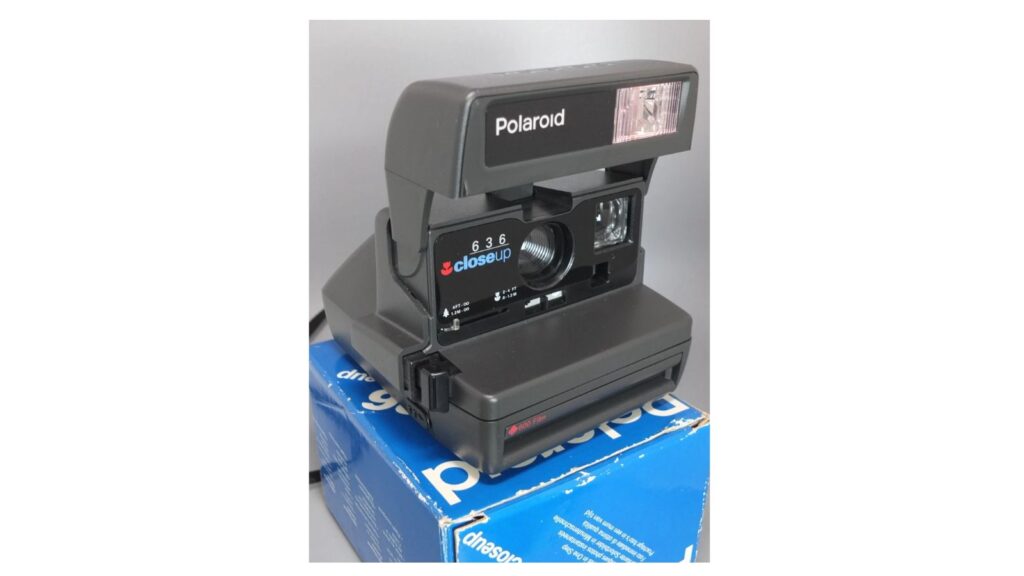
11. Polaroid 600 series camera (1981)
Image Credit: Yesterdays Pieces via eBay
Polaroid’s 600 series brought the OneStep design into the 80s with a faster, more forgiving film speed that made instant photography genuinely easy for casual use. It was wildly popular, which means most surviving examples turn up constantly at thrift stores and estate sales for next to nothing.
Standard working 600-series box cameras typically bring $60 to $180, with complete, boxed examples at the top of that range. The premium Sun 660, which added Polaroid’s Sonar autofocus system to the 600 body, tends to sell for more than the base OneStep models because of that added feature.
Test the camera with actual film before assuming it works, since many units power on and sound functional but have a failed motor or shutter that only shows up mid-shot. The battery that powers the camera is built into each film pack, so a camera with no obvious power switch isn’t broken, it’s just waiting on film. Cosmetic cracks around the film door are common and usually cosmetic only, but a camera with visible mold or water damage inside the body is rarely worth restoring.
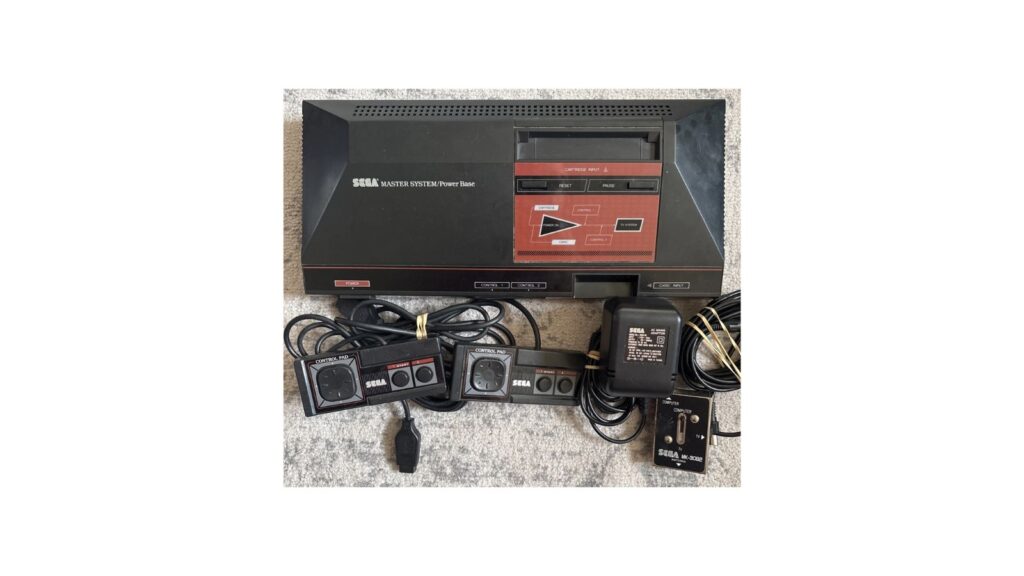
12. Sega Master System (1986)
Image Credit: insertcoinretrogaming via eBay
Sega’s first serious console launch in the US arrived a year after the NES and never caught up in sales, which makes it the quieter sibling in most collections today. It had genuinely strong graphics for the era and a library that leaned on arcade conversions, and its relative rarity in the US has made it more interesting to collectors than its sales numbers would suggest.
A working console on its own typically brings around $120, a complete example with the original box and hookup cables reaches $300 to $350, and factory-sealed units have climbed close to $800. The light gun game that shipped with many bundles adds a little value when the gun itself is present and functional.
Check the RF switch box and AV cables, since these are the parts most often missing from an otherwise complete set and are harder to source than the console itself. The cartridge slot’s pins can corrode from decades of cartridges being swapped, so test that the console reads a game reliably rather than flickering on boot. The card slot built into some models for Sega’s card-based games is a distinguishing feature worth checking for.
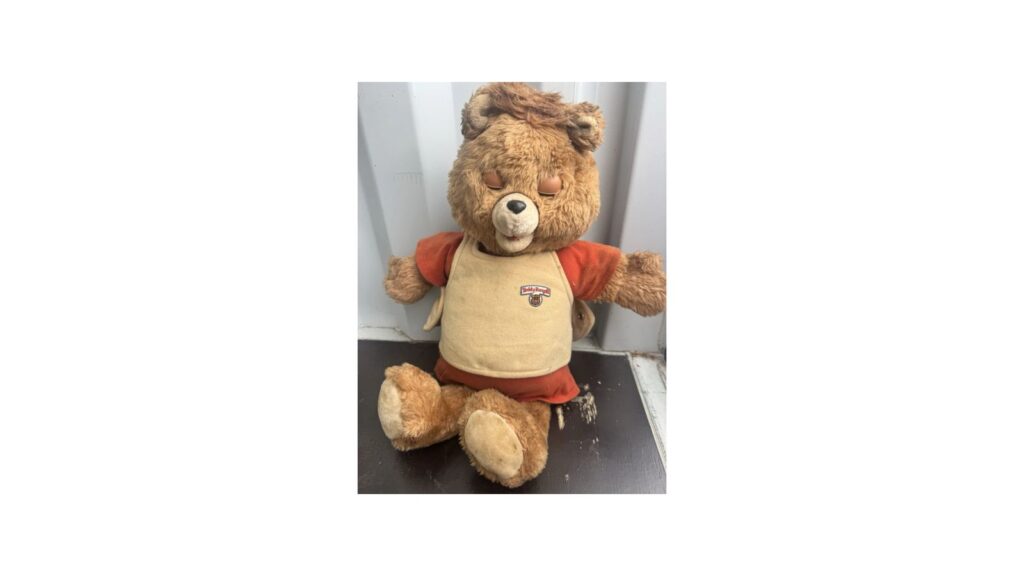
13. Teddy Ruxpin (1985)
Image Credit: new8391 via eBay
Teddy Ruxpin was the animatronic storytelling bear with a built-in cassette player that synced his mouth and eyes to a cassette tape, reading along with an accompanying storybook. He cost $70 at launch, a steep price for a toy at the time, and sold well enough to become one of the defining gifts of the mid-80s before the company behind him went bankrupt in 1987.
Working original 1985 bears with their original box typically bring $100 to $150, with the figure’s internal cassette mechanism being intact the single biggest factor in price. A bear without the original storybook and cassette still has value, but noticeably less, since a non-working or silent Teddy is really just a plush toy at that point.
Battery corrosion inside the compartment is extremely common and can damage the wiring if it’s been left unattended for years, so check that area closely before assuming a silent bear is simply dead. The fabric itself fades and mats with age, and a well-preserved coat adds real value since most surviving bears show decades of handling. Test the mouth and eye movement specifically, not just whether the cassette plays sound, since the motor mechanism can fail independently of the audio.
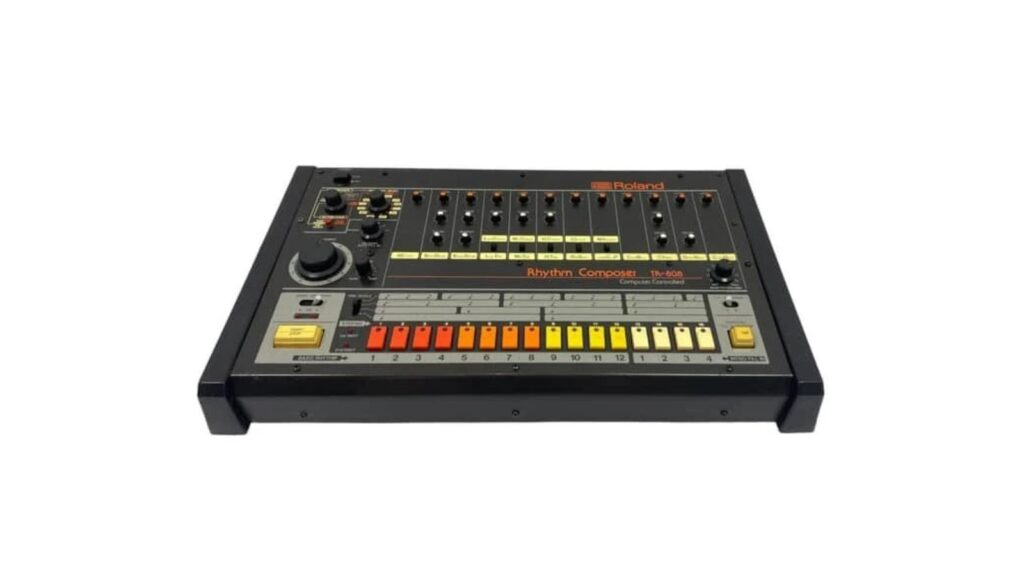
14. Roland TR-808 Rhythm Composer (1980)
Image Credit: ucheboyz via eBay
The 808 is the single most influential drum machine ever made, its analog kick, snare, and cowbell sounds built into the foundation of hip-hop, house, and electro music since the early 80s. Roland made only around 12,000 units before discontinuing it in 1983 over weak initial sales, a decision the company has surely reconsidered given what original units go for now.
A working original 808 in good condition typically sells for $4,500 to $8,000, with fully serviced units from reputable sellers commanding the top of that range. This isn’t a thrift store find the way most of this list is, but original units genuinely do surface in estate sales belonging to former musicians, which is exactly how many of the best-documented finds have turned up.
Originality matters enormously here. A unit with replacement capacitors is still desirable if the work was done properly, but modified circuit boards or non-factory MIDI additions can hurt value with purist buyers even when they add functionality. Every drum voice should trigger cleanly without crackling, and a unit missing its original box of patch cords or manual is still fully desirable, since those were often lost decades ago. If you inherit one of these from a relative who played music, get it appraised by someone who actually works with vintage synths first.
A faller in the Oregon Coast Range drops a 150-foot Douglas fir for a living, and the chainsaw in his hands is the easy part. The hard part comes after the cut, when nobody, not him, not his crew, not forty years on the job, can say for certain which way an old-growth tree is actually going to fall.
Logging workers die on the job at a rate of 110.4 per 100,000 full-time workers, the highest of any occupation the federal government tracks. That is not the kind of tough most people mean when they complain about a bad day at the office. These are tough lives, built around real odds of not making it home.
Some of the jobs on this list pay well, like flying or working underground ore. Some pay almost nothing, like pulling a dead oil tanker apart by hand on a beach in Bangladesh. What they all share is that somebody still has to do them, and the people who do rarely get asked how hard it actually is.
Fifty one loggers died on the job in 2024, in an industry that employs a tiny fraction of the national workforce. A tree that looks stable can still be holding enough tension to snap back and crush whoever is standing in what felt like a safe spot. Branches break off high in the canopy and fall without warning, loggers call them widowmakers, and the nearest hospital is often an hour down an unpaved logging road.
The median pay for loggers was $49,540 a year in 2024, decent by rural standards, nowhere close to hazard pay for a job this dangerous. The industry has gotten safer over the decades, better chainsaw brakes, mandatory hard hats and chaps, required safety training, but the fatality rate has stayed stubbornly ahead of every other job on the books. A faller makes dozens of life or death calls a day about wind, wood grain, and the exact angle of a cut, and gets it right almost every time. Almost every time is the part that should give anyone pause.
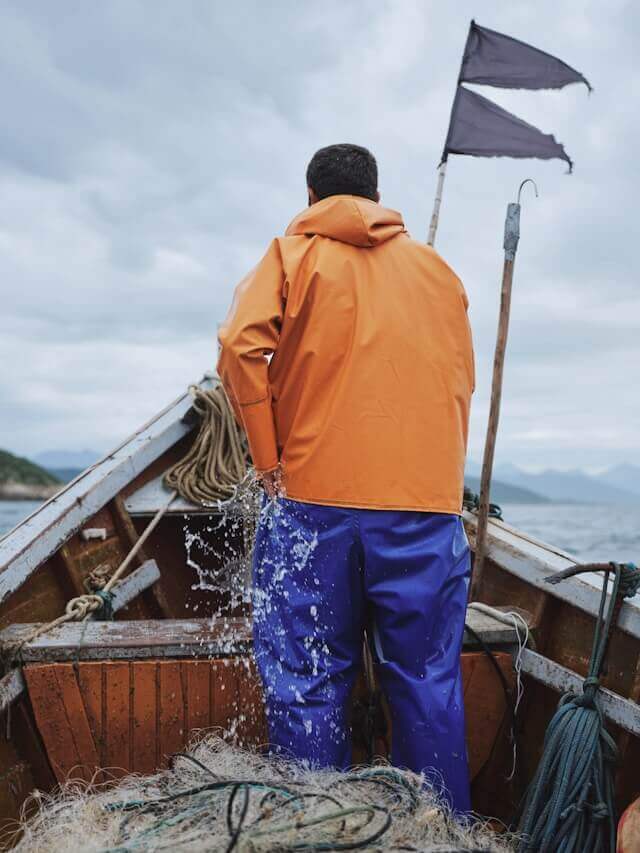
Commercial fisherman on Alaska’s crab boats
Image Credit: Roberta Sant’Anna via Unsplash
The Bering Sea crab fleet that inspired the TV show Deadliest Catch earned its name honestly. In the late 1990s, crab boats in that fishery were losing workers at a rate of 770 per 100,000 full-time workers a year, with boats capsizing under the weight of overloaded, ice-coated crab pots during seasons that sometimes lasted only four days.
That rate has come down hard since the Coast Guard started checking boats for stability before they left the dock, and since the fishery moved away from the derby-style free-for-all that used to send every boat racing out at once. Commercial fishing fatalities across Alaska have dropped 70 percent over the past three decades, and fishing and hunting workers nationally still die at a rate of 88.8 per 100,000, second only to logging. The work itself has not changed much: hauling steel pots that weigh hundreds of pounds across a pitching deck, in freezing spray, often in the dark, hundreds of miles from anywhere a helicopter can reach quickly. Pay is hard to pin down because 57 percent of fishing and hunting workers are self-employed, numbers the government’s own wage survey mostly excludes. The boats are safer. The ocean is not.
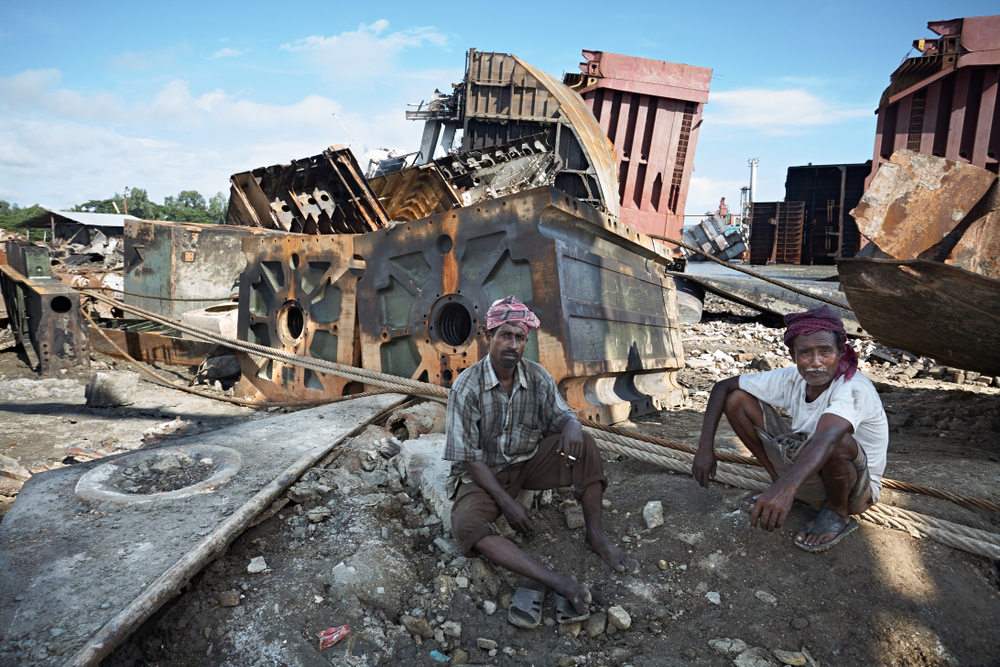
Shipbreaker in Bangladesh
Image Credit: Shutterstock
When an oil tanker or container ship reaches the end of its life, someone has to take it apart, and in Bangladesh that someone usually does it by hand on an open beach, with a cutting torch and no dry dock underneath them. At least 137 workers have been killed and 239 injured in accidents at the shipbreaking yards in Sitakunda since 2015.
The ships beach themselves at high tide and crews strip them down as the tide goes out, cutting through steel plate that can still hold trapped gas, oil, or asbestos from decades at sea. Bangladesh, India, and Pakistan together dismantled more than 85 percent of the world’s scrapped ship tonnage in 2025, work that wealthier countries have largely priced themselves out of doing. Deaths in the industry have fallen as yards face more scrutiny, but gas leaks, falls into empty tanks, and collapsing cables still kill and injure workers with grim regularity. The pay is a fraction of what the same work would cost in a regulated shipyard, which is the entire reason the industry exists where it does.
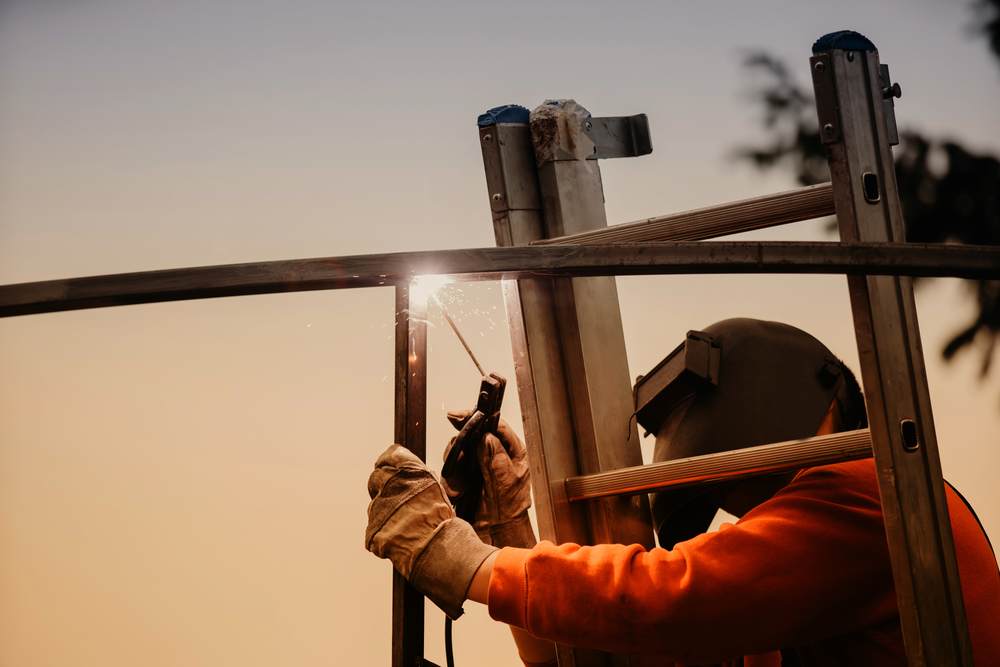
Roofer
Image Credit: Victor Meza via Unsplash
Roofers died at a rate of 48.7 per 100,000 workers in 2024, with 104 fatal injuries recorded that year alone. Almost all of those deaths came from falls, off ladders, off scaffolding, off the edge of a roof that looked solid until a worker’s weight hit a weak spot.
The physical demands alone would wear most people down fast: bending, kneeling, and carrying heavy bundles of shingles up a ladder in direct summer heat, with a dark roof surface baking hotter than the air around it. Add a steep pitch, a wet morning, or a rushed deadline, and the margin for error gets thin. Roofing pays a median of $50,970 a year, reasonably well for a trade that does not require a college degree, and among the better paying options in residential construction. Most roofing companies now require harnesses on steep-slope work, and OSHA has tightened its fall protection rules over the past decade, but the job still comes down to a person’s balance and judgment, thirty feet up, with nothing but a rope between a mistake and a hospital bed.
Structural ironworker
Image Credit: Shutterstock
The workers who bolt a skyscraper’s steel skeleton together walk across beams a few inches wide, hundreds of feet in the air, long before any walls or safety nets go up around them. Structural iron and steel workers died at a rate of 37.8 per 100,000 in 2024, more than ten times the rate for all workers combined.
Connectors, the ironworkers who guide a steel beam into place and bolt it down while it still dangles from a crane cable, do some of the most exposed work on any job site. A gust of wind, a misjudged step, or a beam that swings wrong can be fatal in seconds, and there is rarely a second chance to correct a mistake at that height. The trade pays a median of $62,700 a year, well by construction standards, which is part of why it still draws people despite the obvious risk. Ironworkers tend to talk about the job with a kind of matter-of-fact pride that outsiders find hard to understand. Spend a morning watching them work thirty stories up and it starts to make sense.
Refuse and recycling collector
Image Credit: Shutterstock
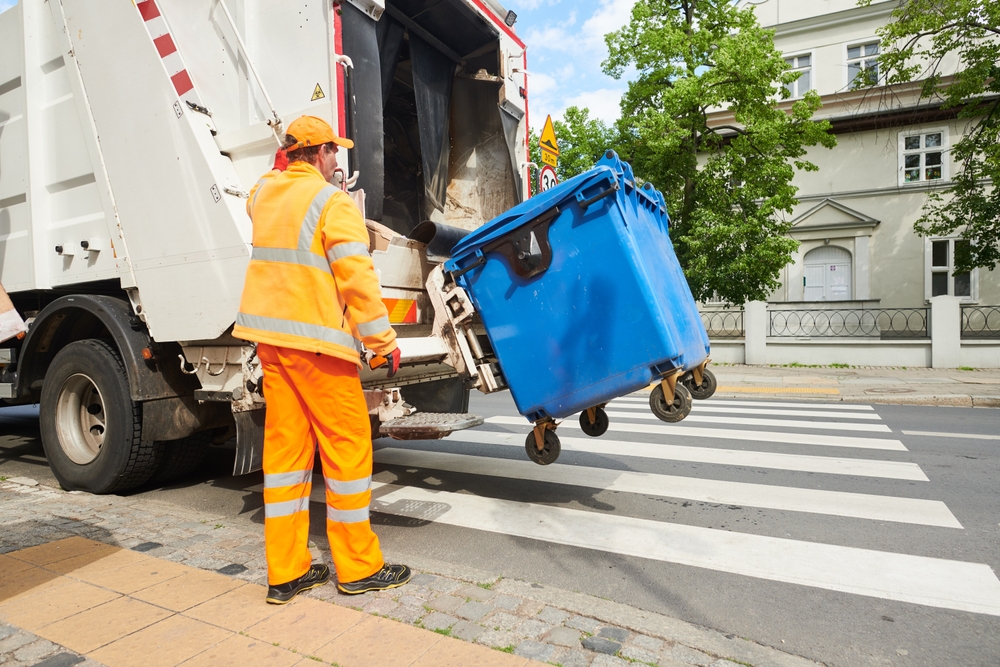
Garbage collection does not sound like a dangerous job, which is part of why its fatality rate of 37.4 per 100,000 workers, with 36 deaths in 2024, catches people off guard. Most of those deaths come from being struck by vehicles, either the collection truck itself or passing traffic while a worker is on foot beside a busy road before sunrise.
The job is repetitive and physically brutal in its own right, climbing on and off a truck hundreds of times a shift, hauling bins that can weigh far more than they look when packed with wet leaves or construction debris. Collectors work in all weather, handle broken glass, needles, and rotting food without much say in what ends up in a bin, and do it for a median of $49,690 a year, pay that rarely reflects the physical toll outside of a handful of strong union contracts. It is essential work that every household relies on and almost nobody thinks about, which is roughly the definition of a thankless job. The traffic risk alone puts it ahead of most office hazards by a wide margin.
Regional and bush pilot
Image Credit: Shutterstock
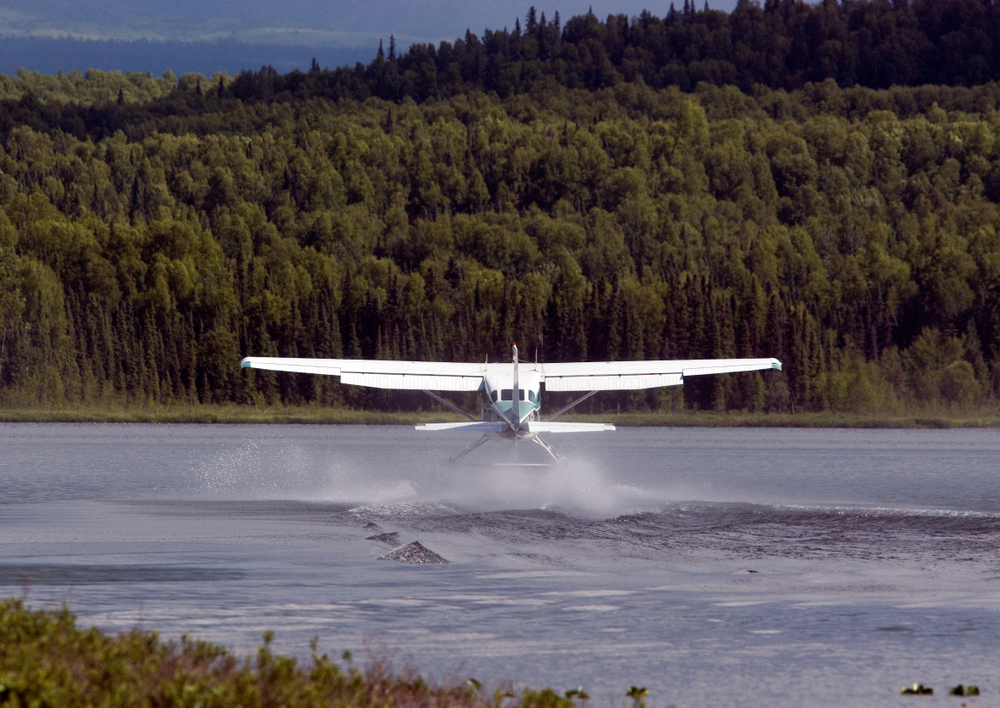
Not every pilot flies a widebody jet out of a major airport with full instrument support and a long runway. Aircraft pilots and flight engineers died at a rate of 36.7 per 100,000 workers in 2024, with 73 fatalities, a number driven heavily by crop dusters, bush pilots, and small charter operators flying into remote strips in bad weather.
Alaska alone accounts for a disproportionate share of small-aircraft crashes nationally, thanks to mountainous terrain, fast-changing weather, and a transportation system that depends on float planes and gravel runways to reach villages with no roads at all. Crop dusting carries its own particular hazards: flying low and fast over power lines and trees, banking hard at the end of every pass. Commercial pilots, the broader category that includes crop dusters and charter work, earn a median of $122,670 a year, well below the $226,600 median for airline pilots, copilots, and flight engineers. Major airline pilots, by contrast, fly one of the statistically safest jobs in the country. The danger in this profession sits almost entirely at the edges, where the aircraft are smaller, the runways are shorter, and the margin for a bad decision all but disappears.
Underground miner
Image Credit: Shutterstock
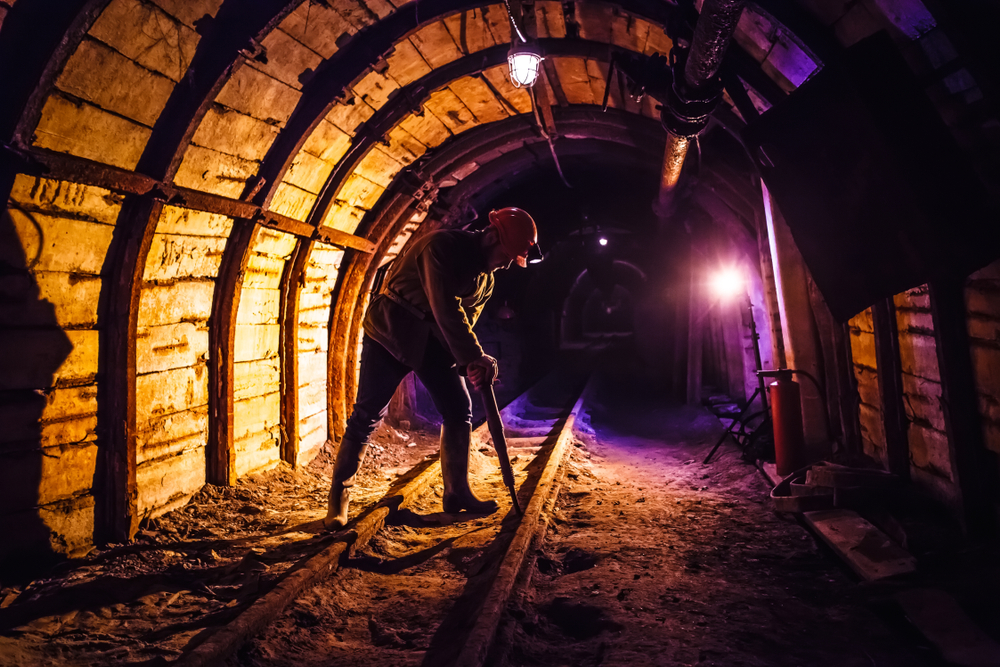
Underground mining machine operators died at a rate of 35.6 per 100,000 workers in 2024, a job that means spending a full shift hundreds or thousands of feet below the surface, where a roof collapse, a methane pocket, or an equipment failure can turn deadly before anyone on the surface even knows something went wrong.
American mining has gotten dramatically safer since the days of regular large-scale disasters, thanks to decades of federal regulation following the Mine Safety and Health Act. Mining, quarrying, and oil and gas extraction combined recorded 92 fatal work injuries in 2024, down from a peak during the shale boom a decade earlier. The work itself has not gotten any less demanding: miners still breathe coal and rock dust that causes black lung and silicosis decades later, work in heat and humidity that surface crews never experience, and rely entirely on ventilation systems and roof supports engineered by someone else to keep them alive. Mining machine operators earn a median of $58,410 a year, well by rural standards, which is part of why people keep doing it despite everything underground that can go wrong.
Artisanal cobalt miner in Congo
Image Credit: Shutterstock
The battery in a smartphone or an electric car almost certainly contains cobalt dug out of the ground in the Democratic Republic of Congo, which produces the large majority of the world’s supply. Much of that digging is not done by machine. Researchers estimate roughly 110,000 to 150,000 artisanal miners work the cobalt-rich copper belt in the country’s south, scraping ore out of hand-dug tunnels and pits with little more than shovels and headlamps, for pay that one analysis put at around $2.70 to $3.30 a day.
In November 2025, a makeshift bridge at a cobalt and copper mine in Lualaba province collapsed under the weight of a stampeding crowd of diggers, killing at least 32 people. The miners had forced their way onto a site that had been closed for safety reasons after heavy rain, a decision that made sense only against the alternative of earning nothing that day. Tunnels collapse, mines flood, and child labor remains a documented problem across the sector despite years of pressure from international electronics and automotive buyers. The ventilation, structural supports, and safety equipment a licensed industrial mine would be required to provide rarely exist on the artisanal side of the business.
Long-haul truck driver
Image Credit: Shutterstock
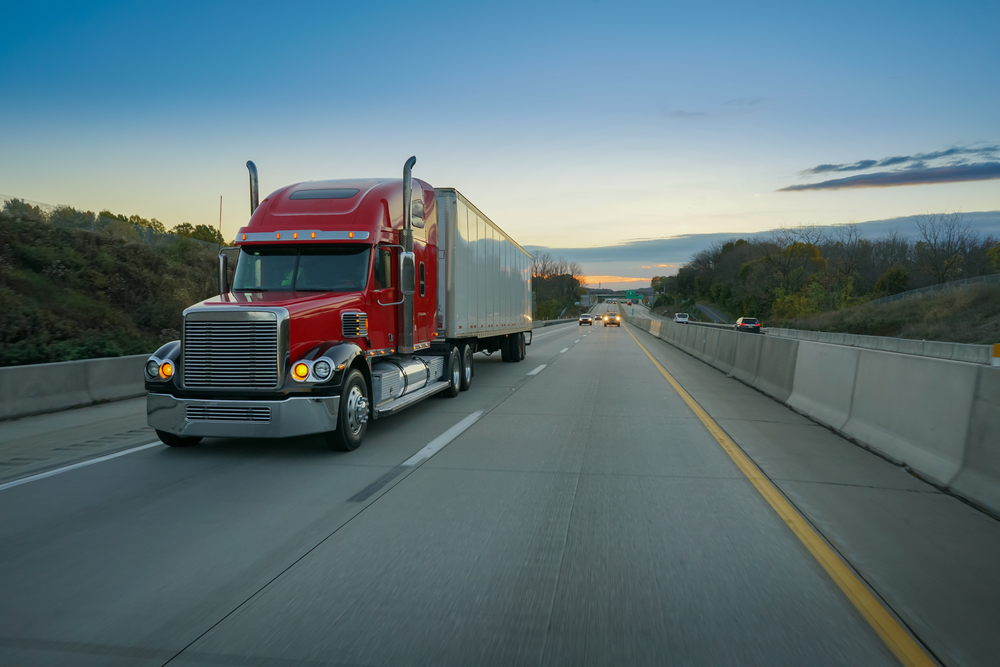
No occupation in America lost more workers in 2024 than driving a truck. Driver and sales workers and truck drivers recorded 950 fatal work injuries that year, more than any other single job category, at a rate of 25.7 per 100,000.
Most of those deaths are traffic crashes, the predictable result of spending ten or eleven hours a day behind the wheel of an 80,000 pound vehicle, often on overnight schedules that work against the body’s natural sleep cycle. Long-haul drivers eat most meals at truck stops, sleep in a cab rather than a bed, and can go days without a real conversation that is not over a CB radio or a phone. Pay has improved over the past several years as the industry has struggled to recruit and keep drivers, with the median now at $57,440 a year. The isolation wears on people as much as the physical risk does. It is one thing to drive for a living. It is another to do it alone, at night, for weeks at a stretch, with a family’s schedule running on a completely different clock than the driver’s own.
Farmer and rancher
Image Credit: Shutterstock
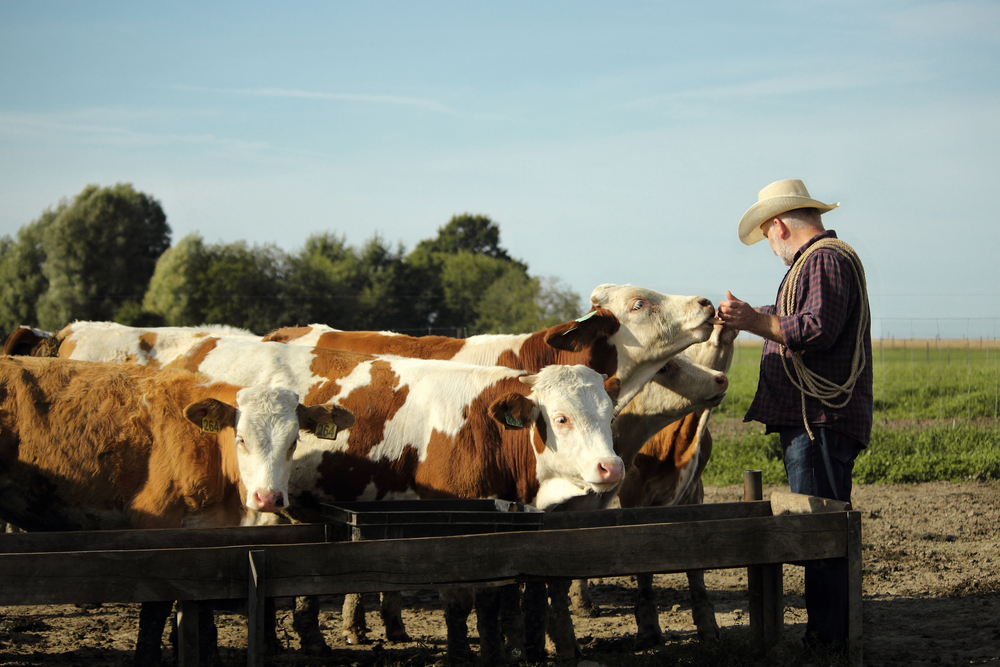
Farmers, ranchers, and other agricultural managers died at a rate of 19.4 per 100,000 workers in 2024, with 175 fatalities. Tractors roll over on uneven ground, grain bins swallow workers who get caught in shifting grain, and livestock, especially bulls and spooked horses, injure and kill handlers who have worked around animals their whole lives. Farmers, ranchers, and other agricultural managers earn a median of $87,980 a year, though that figure leaves out the many farmers who are self-employed and not captured in the government’s wage survey.
Farming is also one of the few jobs on this list where the danger comes bundled with real financial precarity. A bad growing season, a sudden drop in commodity prices, or an equipment breakdown at the wrong moment can threaten an entire year’s income in a way that has no equivalent in most other dangerous trades. Farmers tend to work alone or with a small family crew, often far from the nearest hospital, which turns injuries that would be manageable with fast treatment into something far more serious. The hours are long, dictated entirely by weather and the needs of the land rather than any schedule a person gets to choose, and the work does not stop for holidays, illness, or a bad knee.
Construction laborer
Image Credit: Shutterstock
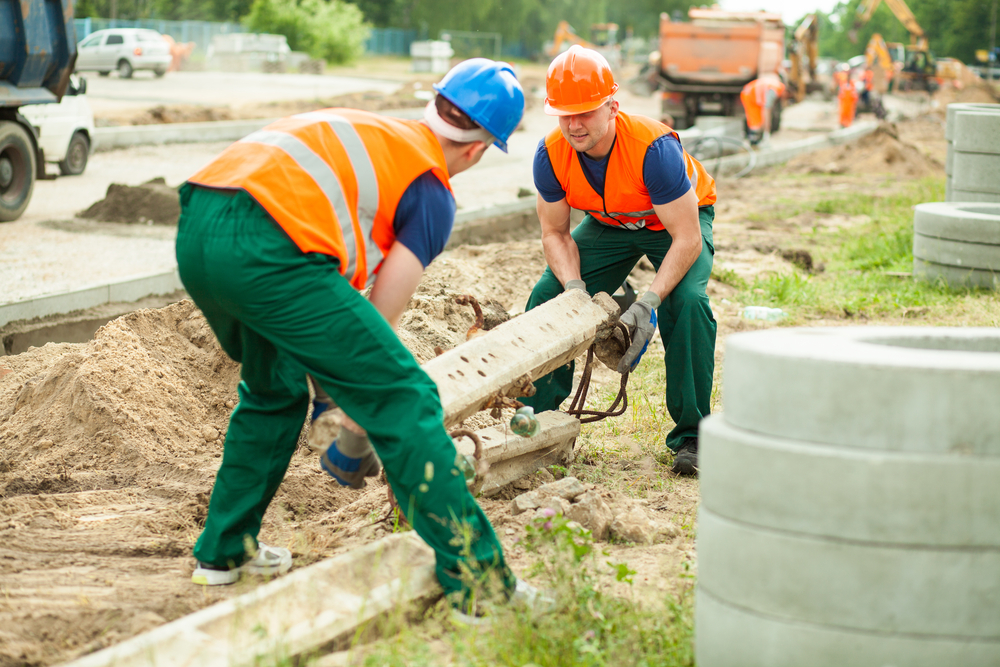
Every job site needs people doing the general hauling, digging, and setup work that keeps the specialized trades moving, and that work carries real risk of its own. Construction laborers died at a rate of 15.8 per 100,000 workers in 2024, with 334 fatalities, more total deaths than any other construction occupation the government tracks.
Laborers get hit by falling tools and materials, caught in trench collapses when soil walls give way without warning, and struck by heavy equipment backing up on a crowded site. The job demands near constant physical labor, digging, lifting, carrying, operating hand tools, often in direct sun or freezing cold with limited shelter nearby. It typically pays less than the skilled trades it supports, a median of $46,050 a year, even though laborers are frequently the ones exposed to the widest range of hazards on any given site, since their work rotates across every part of a project rather than staying confined to one specialty. Experience matters enormously here. A laborer who has learned to read a site’s hazards tends to last. One who has not usually does not stay long.
Electrical lineman
Image Credit: Shutterstock
Electrical power-line installers and repairers died at a rate of 13.8 per 100,000 workers in 2024, a job that means climbing utility poles and working inside substations carrying tens of thousands of volts, often during the exact storms that knocked the power out in the first place.
Linemen get called out in hurricanes, ice storms, and wildfires, when most people are being told to stay indoors, because restoring power is considered essential work that cannot wait for better conditions. A single mistake around high voltage equipment can be instantly fatal, and the work frequently happens forty or fifty feet in the air, on a pole slick with rain or coated in ice. The median pay is $92,560 a year, reflecting the risk and the skill required, particularly for crews who travel for storm response work during hurricane season. The training pipeline is long, often four years of apprenticeship before a lineman works independently on energized lines, and for good reason. There is very little room between doing the job correctly and not surviving a shift.
Sherpa guide on Everest
Image Credit: Shutterstock
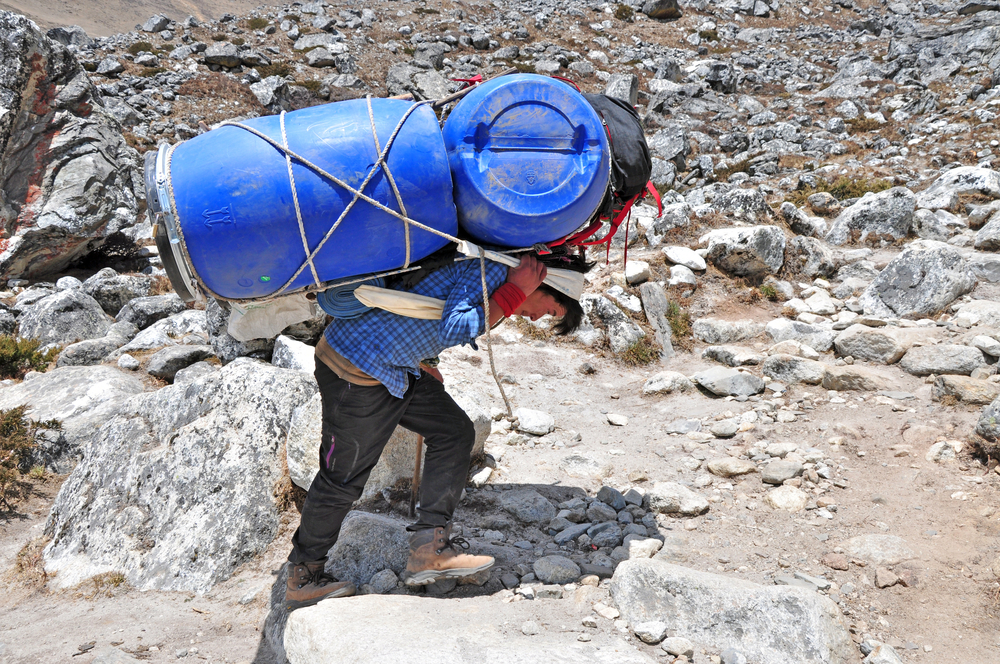
Climbers who pay for an Everest summit attempt typically cross the Khumbu Icefall, one of the most dangerous sections of the entire route, only a handful of times during an expedition. The Sherpa guides who fix ropes, carry oxygen bottles, and haul camp supplies cross it far more often, through a maze of shifting ice towers that can collapse without warning.
The 2025 spring climbing season saw five deaths on Everest, down sharply from nine in 2024 and a record eighteen in 2023. Nepali mountain workers have historically made up a disproportionate share of fatalities on the mountain, a reflection of how much more time they spend on its most hazardous terrain compared to paying clients, who usually make a single push for the summit with a full support team around them. Everest has also gotten more expensive to climb: Nepal’s government is raising the permit fee for climbing the mountain from $11,000 to $15,000 per person starting this fall. The job has made some Sherpas well known within mountaineering circles, including Kami Rita Sherpa, who broke his own record this year with his 31st summit of the mountain.
Oil and gas rig worker
Image Credit: Shutterstock
Oil and gas extraction recorded 65 fatal work injuries in 2024, and a federal database built specifically to track these deaths found the industry’s fatality rate has historically run several times higher than the rate for all US workers, driven heavily by vehicle crashes on the long drives between remote well sites.
Rig work itself brings its own hazards on top of the driving: hydrogen sulfide gas that can incapacitate a worker in seconds if a well kicks unexpectedly, falls from elevated platforms, and equipment under enormous pressure that can fail catastrophically with almost no warning. Roughnecks and roustabouts often work twelve hour shifts on a rotating schedule, two or three weeks on location followed by a week or two off, with little control over conditions once a shift starts. Oil and gas workers earn a median of $52,610 a year, pay that draws people in fast during boom periods, which is exactly why oil field work has always moved in cycles with the price of crude. Workers who have been in the business for years describe a culture that prizes toughness and getting the job done, sometimes at the expense of slowing down when something looks off.
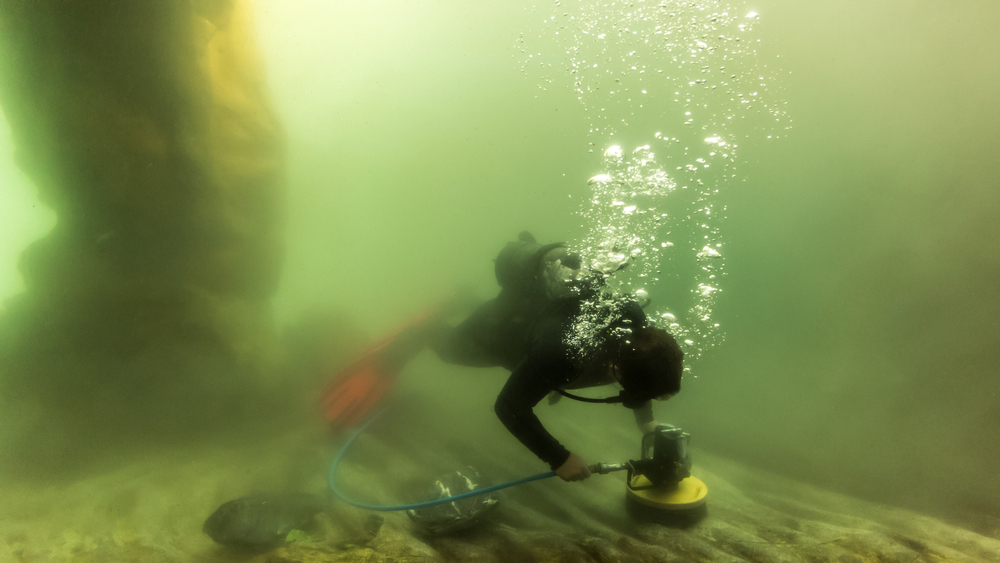
Commercial diver
Image Credit: Shutterstock
Underwater welders, pipeline inspectors, and divers who maintain bridges, dams, and oil platforms do their jobs in conditions that would panic most people within minutes: zero visibility, strong currents, and the constant physics of working under enormous water pressure. A federal analysis of occupational diving deaths found that commercial divers die at a rate of 180 per 100,000 workers a year, forty times the national average for all occupations.
The specific hazards are unlike almost anything else on this list. Decompression sickness, known as the bends, can cripple or kill a diver who surfaces too fast after working at depth. A diver’s air supply runs through an umbilical cord to the surface that can snag on wreckage or get severed outright, and cold water can bring on hypothermia fast enough to impair judgment before a diver even realizes something is wrong. Saturation divers working offshore oil platforms live inside pressurized chambers for weeks at a stretch, breathing a custom gas mixture, to avoid the days of decompression a single trip to the surface would otherwise require. It is a small, highly specialized trade, with an estimated 3,380 commercial divers working in the United States, earning a median of $72,990 a year, pay that reflects both the skill and the risk involved in diving for a living rather than for sport.
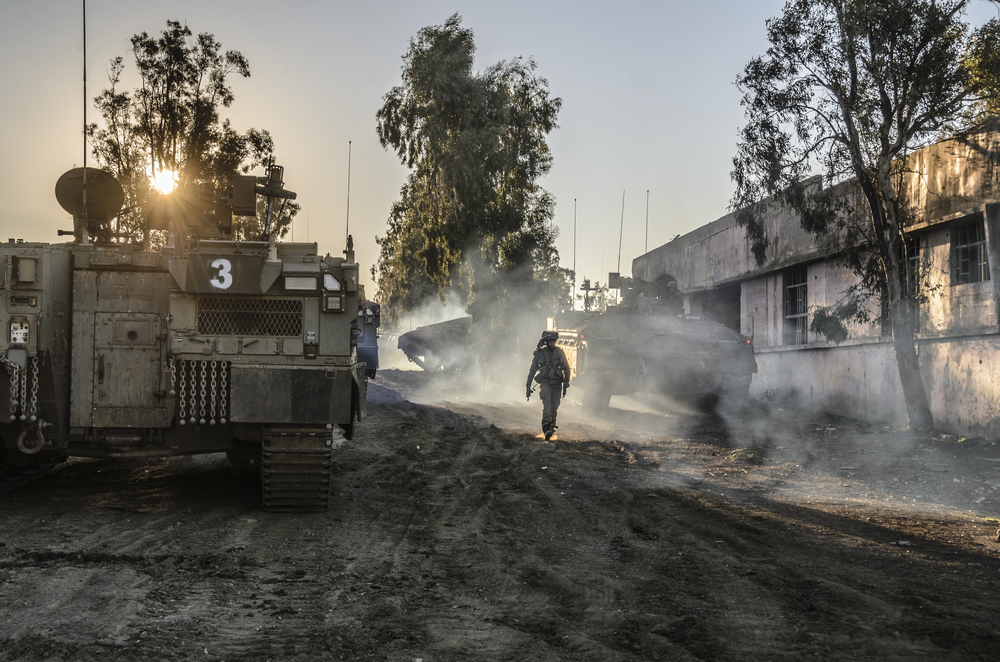
Combat soldier
Image Credit: Shutterstock
Actual combat accounts for a smaller share of military deaths than most people assume. A congressional report found that of more than 16,000 active-duty deaths since 2006, only about 16 percent came from being killed in action, while nearly a third came from training accidents.
The Army alone lost 31 soldiers to training accidents in 2025, split between aircraft crashes and ground incidents like vehicle rollovers during live exercises designed to simulate real combat conditions as closely as possible. A private’s base pay starts at about $28,880 a year before allowances, climbing to somewhere between roughly $37,700 and $45,800 for a specialist or corporal with a few years in. Training for war turns out to carry much of the same risk as fighting one: soldiers handle live ammunition, operate heavy armored vehicles over rough terrain, and jump from aircraft, all while learning skills that have to be practiced at full intensity to be worth anything in an actual deployment. Add to that the psychological weight of the job, long separations from family, the expectation of following orders into real danger, and the risk of injuries that do not show up until years later, and it becomes clear why service members describe the job as demanding in ways that go well beyond the physical.
ICU and ER nurse
Image Credit: Shutterstock
Nursing looks nothing like construction or logging on paper, and yet more workers are injured in the healthcare and social assistance industry than in any other sector in the country, year after year. Nursing assistants rank among the occupations with the highest rates of musculoskeletal injury of any job tracked by the government, largely from lifting and repositioning patients who cannot move themselves.
Registered nurses specifically face nonfatal injury and illness rates of 104.2 cases per 10,000 full-time workers, noticeably higher than the 91.7 rate across all occupations combined, and nurses experience violent incidents on the job at close to three times the rate of the average worker, mostly from combative or disoriented patients in emergency departments and psychiatric units. ICU and ER nurses in particular absorb twelve hour shifts on their feet, codes that require sprinting into a room and performing chest compressions without warning, and the quieter toll of watching patients die despite everything the team did right. The median pay for registered nurses was $93,600 a year in 2024, and it has climbed further in high demand specialties and expensive cities, but burnout and turnover remain severe enough that hospital staffing shortages have become a near constant feature of American healthcare.
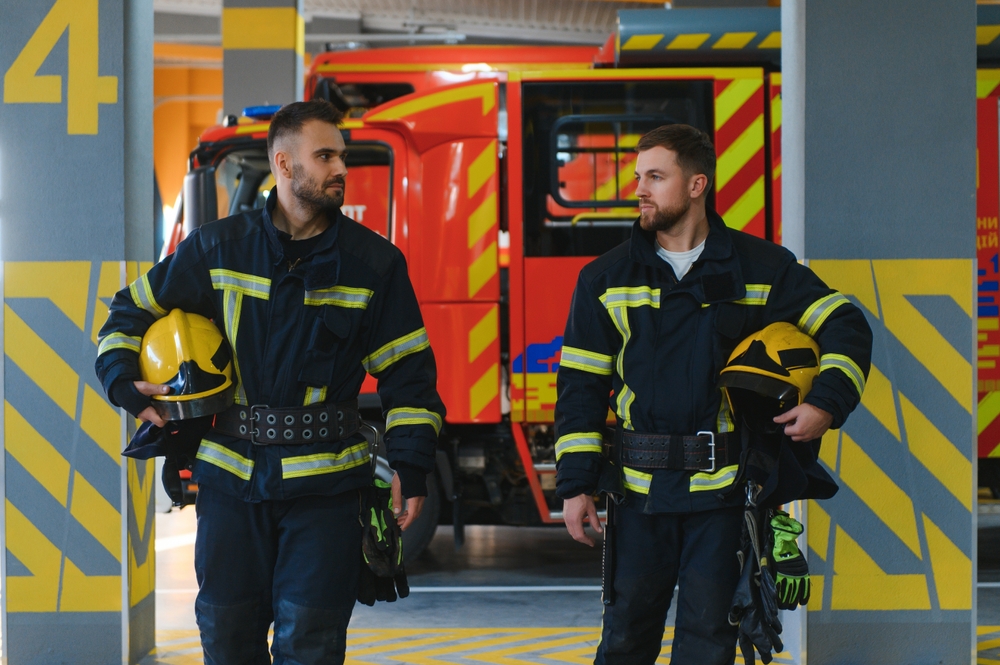
Firefighter
Image Credit: Shutterstock
Structure fires kill and injure firefighters directly, but the job’s biggest long-term threat turns out to be slower and less visible. A National Institute for Occupational Safety and Health study of nearly 30,000 career firefighters found a 9 percent higher rate of cancer diagnosis and a 14 percent higher rate of cancer death compared to the general population, with a mesothelioma rate twice as high as the average American.
Burning buildings release a cocktail of carcinogens, from the synthetic materials in modern furniture to the diesel exhaust firefighters breathe back at the station, and turnout gear only blocks so much of it. Firefighters died in the line of duty at a rate of 4.0 per 100,000 in 2024, a lower number than many jobs on this list, which is part of why the long-term cancer risk tends to surprise people who assume the danger ends when the fire goes out. Departments across the country have started requiring firefighters to shower and change gear immediately after a fire rather than riding back to the station covered in soot, a small change driven directly by the cancer research. Median pay for firefighters was $59,530 a year in 2024, a number that says nothing about what departments spend decades later on the medical bills. It has not eliminated the risk. It has just made departments take it seriously.
Police officer
Image Credit: Shutterstock
Fifty three law enforcement officers were feloniously killed in the line of duty in 2025. Total line of duty deaths for the year, a broader count that also includes accidents and illness on the job, fell to the lowest level since 1943. That decline is good news, but it sits alongside a very different trend: assaults on officers reached their highest rate in a decade in 2025, at 13.8 per 100 officers.
Policing combines several distinct kinds of risk that rarely show up together in one job: the possibility of a fatal encounter with an armed suspect, the much higher likelihood of a car crash during a high speed pursuit or a late night traffic stop, and a daily, grinding exposure to other people’s worst moments that takes a toll few other professions match. Officers respond to domestic violence calls, mental health crises, and fatal accidents as a routine part of a shift, then go home and are expected to function normally. Median pay for police and detectives was $77,270 a year in 2024, though it varies enormously by department and region, and the risk profile of the job does not track neatly with the paycheck.
A personalized comic book can turn a child’s funniest family stories into a birthday gift that feels completely their own. Instead of choosing another toy or gift card, a mom can take the jokes, adventures, embarrassing moments, and memorable characters her child already loves and turn them into a story they can actually hold onto.
Family stories are often built from ordinary moments. Maybe a child once made a hilarious comment at dinner, the family dog caused chaos during a holiday, or a simple road trip became an unforgettable adventure. Those little stories can become even more meaningful when they are transformed into something creative.
For a single mom, a personalized gift can also be a way to celebrate the family they have built together. With a little creativity and some favorite memories, she can create a birthday surprise that feels thoughtful without requiring an enormous budget or complicated planning.
Start with the stories everyone remembers
The best material may already be hiding in family conversations, old photos, and years of inside jokes. Rather than trying to invent an elaborate plot, start with the moments that still make everyone laugh.
Think about the stories your child tells repeatedly or the family moments that have become part of your shared vocabulary. A few good starting points include:
Funny childhood comments
Vacation mishaps
Pet adventures
Holiday disasters
Sibling rivalries
Embarrassing moments
A collection of smaller stories can work just as well as one major event. The goal is to capture the personality and humor that make your family’s memories unique.
Turn real memories into a custom adventure
A custom AI comic book can provide a fun format for turning those memories into a birthday keepsake. Kindred Press’s custom comic book is designed around a personalized character and can include up to five family members, friends, or pets, while allowing the creator to preview and edit the book before printing.
The format also gives you room to exaggerate the original stories. A disastrous family camping trip can become an epic survival mission, while a mischievous pet can be transformed into the secret mastermind behind the household’s chaos.
Keeping recognizable details makes the finished story even more fun. Your child may immediately recognize the setting, family members, or event that inspired a particular scene.
Let your child be the main character
Birthday gifts feel especially exciting when children can see themselves at the center of the story. A personalized comic can take that idea a step further by turning ordinary family memories into an adventure where the birthday child is the hero.
The story does not need to make them perfect. In fact, some of the funniest moments may come from incorporating their real quirks, favorite sayings, or memorable mistakes.
A little exaggeration can make the finished comic feel more like a superhero adventure while still keeping its emotional connection to real life.
Include the people and pets they love
Family stories rarely belong to one person. Parents, siblings, grandparents, cousins, friends, and pets often play important roles in the memories children treasure most.
Including those familiar characters can make the comic feel like a snapshot of the child’s world. A family dog might become the sidekick, a sibling could play the comic relief, and Mom might appear as the person who saves the day.
Adding multiple people also gives the birthday child a reason to share the finished book. Instead of being a gift they quietly enjoy alone, it can become something the whole family reads together.
Make the humor personal
Generic jokes are easy to forget, but family-specific humor has a different kind of staying power. A funny nickname, recurring phrase, or ridiculous family tradition can instantly make a story feel authentic.
The trick is to focus on humor that everyone involved will enjoy. The funniest family memory may not be the best choice if it could embarrass or upset someone, particularly when the gift is intended to celebrate a child.
A good rule is to ask whether the story will make the birthday child laugh when they read it again years later. If the answer is yes, it probably belongs in the book.
Create a keepsake beyond the birthday
The birthday celebration may be the reason for creating the comic, but the finished book can have a much longer life. Children can reread it, share it with friends, or pull it off the shelf years later when they want to revisit a particular stage of childhood.
For a single mom, the keepsake can also represent something larger than a birthday. It captures the humor, relationships, and everyday experiences that make a family feel like a family.
Personalized gifts do not have to be extravagant to be meaningful. Sometimes the strongest present is simply a familiar collection of memories transformed into something new.
Give ordinary memories a second life
The funniest family stories often begin as moments nobody planned. Turning those memories into a personalized comic gives them another life and creates something a child can keep long after the birthday cake is gone.
A thoughtful birthday gift does not necessarily require finding something completely new. Taking the stories your family already loves and giving them a creative format can make the finished present feel both surprising and deeply personal.
For a single mom looking for a meaningful way to celebrate her child, a custom family comic can capture something store-bought gifts cannot: the unique history, humor, and personality they share.
Understanding personal injury compensation rights helps single parents protect household stability and recover unexpected medical expenses effectively.
When you manage a household on your own, a sudden injury can disrupt your family’s routine and financial security. Balancing caretaking duties while managing physical recovery creates immediate stress, especially when medical bills begin arriving.
Taking control of your legal rights and financial recovery options brings stability back to your daily life. Clear action steps can protect your household while you focus on healing.
What steps protect your household assets during recovery?
Protecting your savings requires active communication with healthcare providers and lenders. Contacting medical billing departments early allows you to negotiate payment plans or apply for financial assistance programs before bills enter collections. Securing fair third-party compensation helps offset these mounting costs without draining your family emergency fund. Working with a local attorney helps ensure insurance carriers treat your claim fairly. Retaining experienced counsel in San Antonio helps protect your rights within regional court jurisdictions when pursuing compensation for your family.
How do injury expenses impact single-parent households?
Running a home on a single income means unexpected costs hit much harder. A recent study published by PMC Public Health notes that single-parent families face an elevated risk of financial hardship that directly affects overall well-being. Sudden medical charges create an immediate burden when there is no second income to rely on.
Physical injuries often result in missed workdays and lost income. Combining lost wages with emergency room fees or ongoing therapy costs can quickly stretch a tight family budget to its limits.
Balancing immediate domestic responsibilities alongside an unexpected recovery journey creates severe compound pressures. Covering routine household obligations like monthly rent, utility bills, and childcare services becomes exceedingly difficult when medical bills take priority. Paying for outpatient care, prescription medications, and specialized physical therapy sessions frequently forces parents to exhaust modest cash reserves, leaving zero cushion for unexpected daily emergencies.
Losing regular weekly wages while recovering from harm compounds these financial strains rapidly. Taking unpaid leave or reducing working hours to attend necessary rehabilitation appointments directly reduces household resources when funds are needed most. Facing persistent debt collection attempts while trying to maintain stable living conditions for children creates tremendous physical and emotional stress, making systematic financial planning a top priority.
How do you assess lost earning capacity and medical bills?
Calculating the true cost of an injury requires looking beyond initial hospital visits. Long-term recovery often involves physical therapy, specialized equipment, and prescription medications that add up over time.
Evaluating lost earning capacity is equally important if your injury prevents you from working at full capacity. Calculating these future losses ensures your claim reflects the real financial impact on your child’s future.
How can strategic planning assist your long-term recovery?
Building a structured recovery plan allows you to address immediate financial demands while securing long-term stability. Managing bills systematically keeps your focus on family and personal healing.
Organize all medical documentation: Keep detailed records of doctor visits, receipts, and treatment plans in one central folder.
Track missed work hours: Log every hour or day away from work, including time taken for follow-up appointments.
Communicate with insurance adjusters carefully: Provide factual updates without agreeing to quick settlement offers before understanding full medical costs.
Seek local community resources: Look into regional non-profit support services that offer temporary aid for single-parent families.
Why does local legal representation matter for insurance settlements?
Insurance companies frequently attempt to settle claims quickly for less than their true value. Having regional trial counsel on your side ensures your case accounts for full future care needs and ongoing living costs.
Local lawyers understand regional court procedures and know how to negotiate effectively with insurance carriers. Their guidance removes the burden of legal negotiations, letting you dedicate your energy to your children and physical recovery.
Standing up to large insurance firms requires a deep understanding of regional statutes and venue-specific strategies. Area attorneys bring established relationships with local medical experts, economic analysts, and accident reconstructionists who help build compelling cases. These local specialists accurately evaluate how your recovery timeline affects your long-term earnings, ensuring settlement demands reflect reality rather than generic formulas.
Filing claims within specific municipal and county jurisdictions involves strict filing deadlines, motion requirements, and procedural nuances. Experienced local advocates anticipate defense strategies common to area insurers, shielding single-parent households from high-pressure settlement tactics. Securing knowledgeable regional representation levels the playing field, ensuring your family receives every dollar necessary to safeguard your shared future.
A sudden injury creates temporary hurdles, but proactive financial and legal steps safeguard your home. Partnering with the right support system ensures your family remains secure throughout every stage of recovery.