scroll top
These 5 ideas can help make hosting easier and more manageable.
Image Credit: Pavel Danilyuk via Pexels

Planning a corporate party takes time on its own. Add school schedules, family routines, and everyday parenting responsibilities, and even a relatively straightforward event can create a crowded calendar.

The answer is not necessarily to make the celebration smaller or less memorable. A few practical choices can reduce repetitive planning tasks while leaving enough room to create an event that colleagues and guests genuinely enjoy.

1. Bring invitations and guest management together

Invitations often create more administrative work than expected. Beyond choosing a design and sharing event details, organizers have to monitor responses, answer questions, send reminders, and keep track of changing attendance numbers.

Keeping those tasks within one digital platform can make the process more manageable. For parents looking to send Christmas party invitations online, Greenvelope’s business Christmas invitation collection provides a polished starting point specifically for workplace celebrations. Greenvelope is a premium, design-led online invitation and RSVP platform designed for teams and companies running corporate events. Hosts can customize the invitation to reflect company branding or the tone of the event while keeping the guest experience professional and ad-free.

The same platform can also handle the practical work that follows. RSVP tracking gives organizers a current view of attendance, while custom questions can collect meal choices, dietary requirements, or other guest details. Messaging and reminders make it easier to follow up or share updates without moving communication into separate channels.

For parents balancing work and family commitments, fewer disconnected tasks can mean less repeated follow-up and a clearer path from the first invitation to the event itself.

2. Choose a format that does not require constant coordination

A corporate party does not need a complicated schedule to feel thoughtfully planned. Choosing a format with fewer moving parts can reduce the amount of coordination required in the weeks before the event.

A seated dinner, afternoon reception, or cocktail-style gathering, for example, can create a clear structure without requiring an extensive program of activities. The right format depends on the company culture, guest list, venue, and purpose of the event.

Parents can also look closely at timing. An event that starts and finishes at predictable hours makes childcare and family schedules easier to arrange while giving colleagues clear expectations.

Before committing to a format, it helps to consider:

  • How much setup will be required?
  • Does the event need a detailed running order?
  • How many vendors need coordination?
  • Will guests need transportation information?
  • How much work will remain on the day itself?

3. Share responsibilities before the planning gets busy

Trying to personally manage every element of a corporate party quickly becomes difficult, particularly when work and family responsibilities are already competing for attention. Dividing responsibilities early prevents small tasks from accumulating close to the event.

The key is to assign complete areas rather than individual errands. One colleague might handle the venue, another could coordinate catering, and someone else could manage entertainment or decorations. Clear ownership reduces repeated questions and gives each person enough time to manage their part of the event.

A shared planning document can provide visibility without requiring constant meetings. It also gives everyone one place to check deadlines, responsibilities, vendor information, and decisions as the event develops.

Once the team agrees on the budget, event style, and essential requirements, smaller decisions can stay with the person responsible for each area. For parents balancing professional commitments with family schedules, this keeps planning time more focused and predictable.

4. Make vendors do more of the heavy lifting

A lower price is not always the only consideration when choosing corporate party vendors. For a busy parent, a supplier that handles setup, delivery, coordination, and cleanup can save hours of additional work.

Venues with established catering packages are one example. Instead of coordinating a space, caterer, furniture provider, and service staff independently, an organizer can work through a more centralized arrangement.

The same principle applies to entertainment, décor, photography, and transportation. Asking exactly what is included before booking reveals how much work will remain with the organizer.

It is also useful to establish one contact person for each supplier. When questions or changes arise, knowing exactly whom to contact keeps communication from becoming another administrative burden.

Convenience does not mean sacrificing quality. In many cases, choosing experienced vendors with broader service packages simply shifts logistical tasks to professionals who already have systems for handling them.

5. Protect time on the day of the party

A corporate party should not require the organizer to spend the entire event solving logistical problems. Building breathing room into the schedule makes it easier to handle unexpected changes while still participating in the celebration.

Confirm major details with vendors ahead of time, including arrival windows, setup responsibilities, final guest numbers, and payment arrangements. Preparing a simple event timeline can also give colleagues and suppliers a shared reference point.

Delegation remains important once the party begins. Another team member can serve as the contact for venue questions, while someone else handles entertainment or guest arrivals. That prevents every decision from returning to the same person.

For parents, this preparation has another benefit. A clearly defined end time and cleanup plan make the transition back to family responsibilities more predictable.

The goal is not to control every minute. It is to remove enough uncertainty that the organizer can actually be present for the event they worked to create.

Making corporate party planning more manageable

Hosting a corporate party while raising a family requires thoughtful use of time rather than an elaborate planning system. Centralized invitations, simpler event formats, shared responsibilities, full-service vendors, and preparation can all reduce unnecessary coordination.

A successful corporate celebration still needs personality and attention to detail. The difference is that those details do not all need to demand the organizer’s personal attention. 

With the right structure in place, parents can create a polished, professional event without allowing the planning process to take over the rest of their schedule. That structure helps preserve the energy for the parts of the event where the organizer’s attention matters most, rather than spending it on avoidable admin.

Frequently asked questions about hosting a corporate party

How far in advance should you start planning a corporate party?

Start with the venue, date, budget, and approximate guest count several weeks or months ahead, depending on event size. Early decisions create more flexibility around vendors and reduce pressure as the event date approaches.

What should be included in a corporate party planning timeline?

Include booking deadlines, RSVP dates, menu confirmations, payment dates, vendor arrival times, setup windows, and final guest numbers. A single timeline helps everyone understand what needs to happen and when.

Should corporate parties include partners or family members?

That depends on the event’s purpose, company culture, budget, and venue capacity. If guests are included, make that clear on the invitation so employees know who is welcome and organizers can plan accurate numbers.
Fifteen and a half percent of Americans 65 and older were living in poverty in 2025, and that is not a one-year spike. It is the fifth year in a row senior poverty has climbed, the only age group moving in that direction while poverty across the rest of the country fell to one of its lowest points in years.

Women over 65 have it worse, at nearly 17%. That gap holds up across almost every number in this story: housing, income, and how exposed someone ends up being to whatever Congress decides to do next.

None of this happened by accident or all at once. Rising housing costs, a shrinking food assistance program, and a Social Security trust fund that is already six years from running short all landed on the same generation, in the same stretch of time.

The poverty rate for older Americans just hit a level we have not seen in years

The Census Bureau’s Supplemental Poverty Measure, which accounts for taxes, government benefits, and real living costs instead of just pretax income, put the rate for people 65 and older at 15.4% for 2025. That is the highest it has been in years, and it has risen every year since 2020.

What makes the climb stand out is the contrast sitting right next to it. Overall poverty in the United States fell to a record low in 2025, even as poverty among seniors kept rising. Adults aged 50 to 64 are struggling too, with one in eight now living in poverty. People in that age bracket who lose a job are less likely to find one that pays the same and more likely to stay unemployed longer, which pushes some of them into poverty years before they ever collect a Social Security check.

This is not a one-year blip tied to a single bad quarter. It is a five-year trend that started well before most of the current political fights over Social Security began, which means whatever Congress decides to do next will land on a population that was already losing ground.

Women are carrying most of the weight

pensioner living in poverty
Image Credit: Shutterstock

Nearly 17% of women 65 and older are living in poverty, and the housing numbers explain a good part of why. The majority of older renters, about 60% of them, are women, and half of female renters 65 and older are cost burdened, meaning they spend more than 30% of their income on housing alone. That rate runs nine points higher than it does for older men who rent.

Income explains the rest. The median income for a woman 65 or older who rents is $27,000 a year, a number shaped by decades of lower lifetime earnings, time out of the workforce for caregiving, and a pay gap that followed many of these women straight into retirement. Lower lifetime earnings mean a lower Social Security benefit, since the formula is built on what someone paid in. Women who worked fewer years, or earned less in the years they did work, collect smaller checks for the rest of their lives because of it.

None of this is unique to one background, but it compounds for women who are also older, living alone, or renting rather than owning. Each factor on its own raises the odds of ending up cost burdened. Stacked together, they turn a tight budget into an impossible one.

The safety net under seniors got thinner this year

Food assistance is where the squeeze shows up first for a lot of older households. SNAP participation nationwide fell by roughly 5 million people, about 12%, between the law’s enactment in July 2025 and this spring, driven largely by expanded work requirements and new eligibility rules. Those requirements now reach older adults who were previously exempt, and paperwork alone has knocked eligible people off the program.

Housing instability is following the same pattern. Adults 55 and older now make up nearly 20% of everyone experiencing homelessness in the most recent federal count, and that share has grown even as overall homelessness fell. Older adults are also overrepresented among people experiencing chronic, long-term homelessness, which hit its highest recorded level this year.

Put those two things next to the poverty numbers and the picture gets clearer. Fewer people qualifying for food assistance and more older adults losing stable housing are not separate stories from the poverty rate climbing. They are the same story, told through different programs.

Social Security is already doing more work than most people realize

Social Security Card
Image Credit: Shutterstock

For all the attention on what might change, the program already in place is the only thing keeping senior poverty from being dramatically worse. Census data shows Social Security kept nearly 29 million people out of poverty last year, more than any other government program, by a wide margin.

That number matters because of how little room it leaves for cuts. Social Security is not a supplement sitting on top of a comfortable retirement for most of the people who rely on it. For a large share of seniors, it is close to the entire income, and how many people it keeps above the poverty line is the clearest evidence of that.

This is the backdrop every proposed change to the program has to be measured against. A benefit cut that sounds modest on paper, a percentage point here or a few months of delayed eligibility there, lands directly on income that is already doing the job of an entire retirement plan for millions of people.

The cut already built into current law

Even if Congress does nothing at all, a cut is already scheduled. The Social Security Trustees’ 2026 report found the retirement trust fund will be depleted in the fourth quarter of 2032, after which incoming payroll taxes would cover only 78% of scheduled benefits. That is an automatic, across-the-board cut of about 22% for everyone collecting retirement benefits at that point, including everyone already collecting them today.

If Congress combines that fund with the smaller disability trust fund, which lawmakers have the legal authority to do, the combined depletion date moves out to 2034, with a smaller automatic cut. Either way, the default outcome if nobody acts is a real reduction in monthly checks within the next six to eight years, not a hypothetical one decades out.

This is the baseline every other proposal gets measured against. A plan that only slows the cut is still a cut. A plan that avoids it entirely by raising revenue or restructuring benefits is a different conversation, and Washington has not settled on either path yet.

What’s actually being proposed in Washington

retirement age rising
Image Credit: Shutterstock

Three Senate Democrats, Elizabeth Warren, Tammy Duckworth, and Richard Blumenthal, sent a letter to President Trump pressing for answers on whether his administration would raise the retirement age, after Social Security Commissioner Frank Bisignano suggested in an interview that the idea was under consideration before walking the comment back. The senators argue raising the retirement age by two years would cut the median retiree’s monthly benefit by $345 to $741, a reduction of 17% to 35%, depending on when someone claims.

A separate estimate measures the same idea a different way and lands on a smaller number. An analysis of raising the full retirement age from 67 to 69 found an average lifetime benefit reduction of about 13% for people affected by the change, spread across every claiming age rather than concentrated at one. The two figures are not really contradicting each other, they are measuring different things: one is the hit to a single year’s check, the other is the hit averaged over an entire retirement.

On the House side, a budget proposal has already called for raising the full retirement age from 67 to 69, phased in starting in 2026, as part of a plan that would cut $718 billion from Social Security over ten years. Whatever else happens, that proposal is already sitting in writing, not just floated in a hallway conversation.

Not every proposal on the table cuts benefits for everyone

It is worth saying plainly that raising the retirement age is not the only idea in circulation, and not every one of them targets the same people. One proposal floats a cap on total benefits of $100,000 a year for married couples and $50,000 for single retirees, aimed only at the highest earners collecting Social Security at full retirement age. That cap would affect roughly the top 0.05% of recipients and close about a fifth of the program’s long-term shortfall on its own.

That is a meaningfully different approach than raising the retirement age, which reduces benefits for every future retiree regardless of income, including the people already living closest to the poverty line. A cap on the highest checks and a universal reduction applied across the board solve the same funding problem in very different ways, and they land on completely different groups of people.

Neither proposal has passed anything yet. Both exist right now as ideas lawmakers are circulating, not as law. The direction Congress eventually picks will say a lot about who is expected to absorb the cost of fixing the program.

What a higher retirement age would mean for someone already struggling

elderly woman with no money
Image Credit: Shutterstock

Raising the retirement age does not shrink the number of years someone needs income. It shrinks the number of years Social Security is willing to provide it, and whatever is left over has to come from savings, a part-time job, family help, or nothing at all.

For someone already working past 62 because they have no other income, a higher retirement age does not create new jobs or better health. It extends the number of years they have to make do on less, right as housing costs and shrinking food assistance are already pushing more seniors toward poverty. That is the part of this debate that tends to get lost in percentages and depletion dates: the people most exposed to a higher retirement age are frequently the same people already showing up in the rising poverty numbers.

Lower-income workers are also more likely to be in physically demanding jobs they cannot simply stretch by two more years, and more likely to claim Social Security early out of necessity rather than choice. That means a higher retirement age tends to hit them with the full early-claiming penalty on top of everything else.

What you can actually do about your own numbers right now

None of this changes what is true for your own situation today. Current retirees are not facing a cut under existing law, and nothing Congress has proposed has passed. What you can control is how clearly you understand your own benefit and your own options while the debate plays out.

Start by pulling your actual numbers from a free my Social Security account at ssa.gov, which shows your estimated benefit at 62, at full retirement age, and at 70, based on your real earnings record rather than a rough estimate. If your income is tight, it is worth checking whether you qualify for Supplemental Security Income, a Medicare Savings Program that covers your Part B premium, or the Extra Help program that lowers prescription drug costs, since all three exist specifically for people in exactly this income range.

Your local Area Agency on Aging can run a full benefits check for free and often finds programs people did not know they qualified for, from utility assistance to property tax relief. If the fight over Social Security concerns you directly, contacting your own member of Congress costs nothing and takes a few minutes, and it is one of the only forms of input that actually gets counted.

Senior poverty did not spike overnight, and it will not get fixed overnight either. What happens to it next depends less on any single number in a trustees report and more on which of these proposals Congress actually decides to pass.

Halloween spending has a way of multiplying. A bag of candy becomes three bags, someone needs a costume, the porch looks bare, and suddenly you are buying party plates and dessert too. Costco’s current Halloween lineup is strongest where buying in bulk actually helps, especially treats, party supplies, reusable decor, and a few seasonal foods that can feed a crowd without much work.

There are also plenty of oversized decorations that cost real money, so those only earn a spot when the size, features, or repeat-use value make the price easier to justify. Costco SameDay prices can run higher than warehouse prices, which is worth remembering before you check out online.

Prices are accurate at the time of publishing but may vary by warehouse or delivery ZIP code, and seasonal items can sell out quickly.

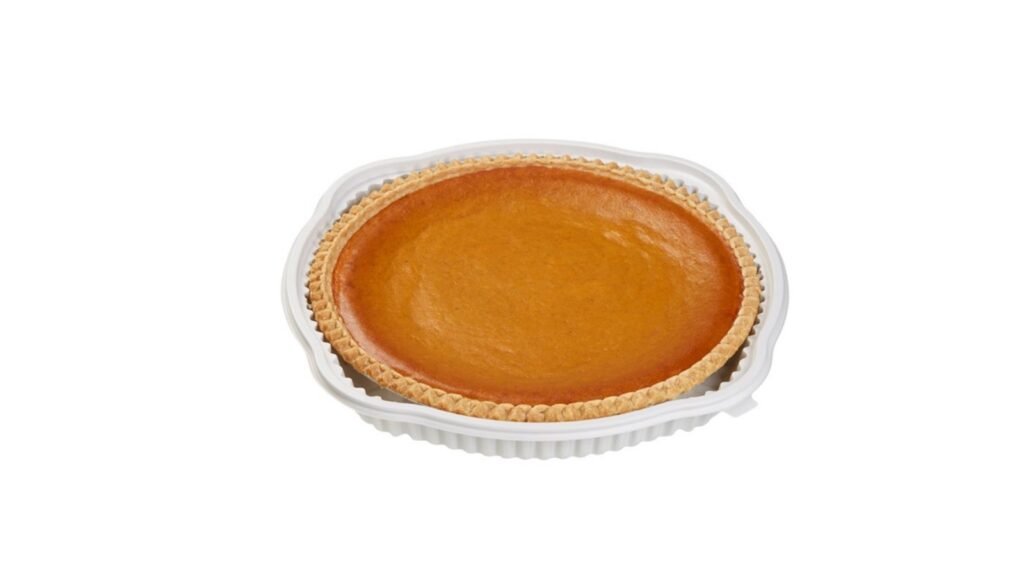
Kirkland Signature pumpkin pie

Kirkland Signature pumpkin pie
Image Credit: Costco

Costco’s nearly four-pound pumpkin pie remains one of the easiest ways to put dessert in front of a crowd without spending bakery-shop money. The 58-ounce pie is $5.99 in the warehouse, although the SameDay price can be higher.

It is not covered in plastic spiders or orange frosting, but that is part of the appeal. Serve it at a Halloween party, bring it to a school or neighborhood gathering, or keep dessert off your already-long party prep list. At this size, even a generous 10 servings works out to about 60 cents each.

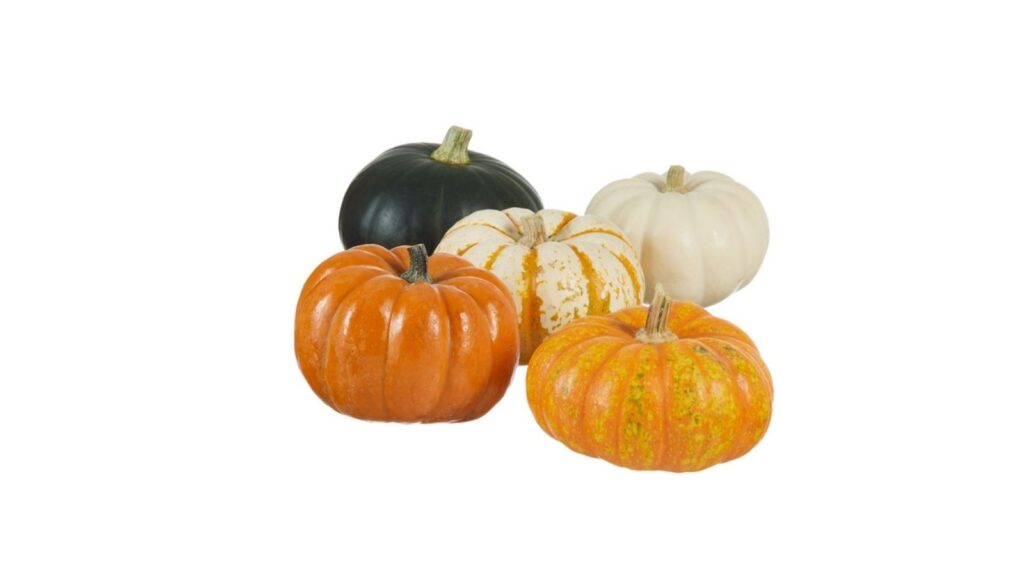
Mini pumpkin variety

mini pumpkins
Image Credit: Costco

Real pumpkins can be cheaper than buying a box of disposable Halloween decorations, especially when you want something small enough for a dining table, mantel, desk, or apartment. Costco’s five-count mini pumpkin variety is $6.80, or about $1.36 per pumpkin.

They work as table decorations without taking up serving space, and you can spread the five pumpkins around the house rather than buying several separate decor pieces. This is also a sensible option if giant carving pumpkins are more mess and expense than you want this year.

Kirkland Signature caramel apple strudel bites

Kirkland Signature caramel apple strudel bites
Image Credit: Costco

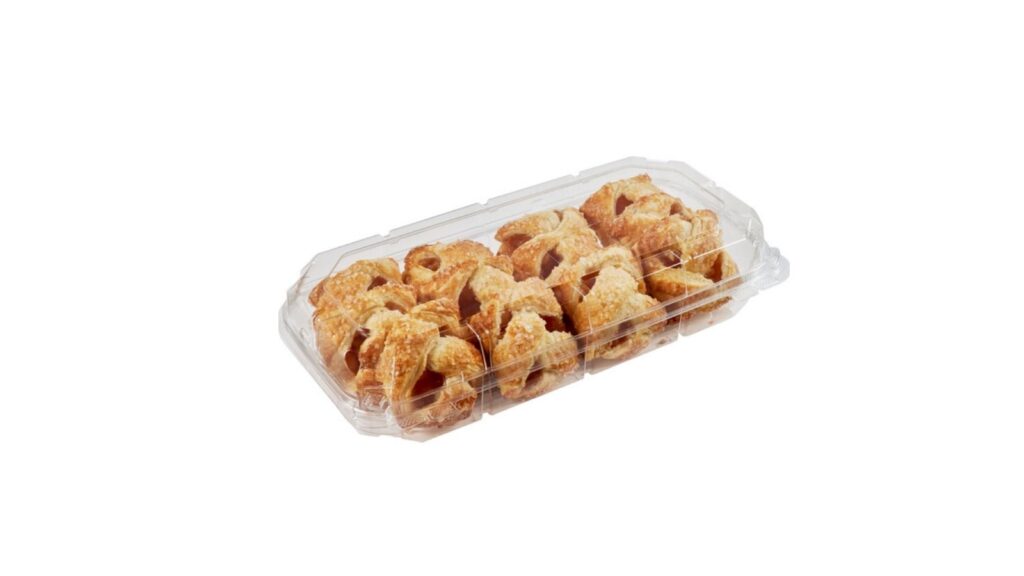
If a Halloween get-together calls for something more substantial than a bowl of wrapped candy, Costco’s 12-count caramel apple strudel bites are $9.07. They use all-butter pastry with caramel apple filling and come out to roughly 76 cents each.

That is useful party math. A dozen individual bakery desserts can get expensive quickly, while these are already portioned and need no decorating. Add them to a dessert table with the pumpkin pie and you have two crowd-friendly choices for well under what a custom Halloween cake can cost.

Kellogg’s Rice Krispies Treats

Kelloggs Rice Krispies Treats
Image Credit: Costco

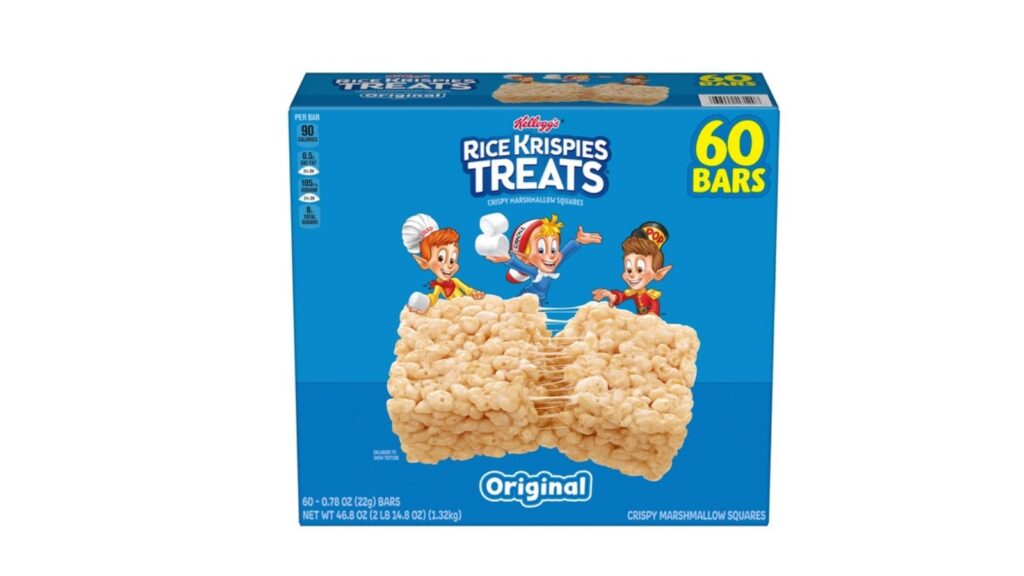
Individually wrapped treats are handy when you need something for trick-or-treaters, classroom bags, sports teams, or a Halloween party without handling loose food. Costco has the 60-count box of Rice Krispies Treats for $10.54 through October 18, after $4 off.

That works out to about 18 cents per bar. They are smaller than a full-size snack bar, which makes them better suited to treat bags than lunch boxes, but the price per piece is hard to argue with if you need dozens of sealed snacks at once.

Welch’s fruit snacks

Welchs Mixed Fruit Snacks
Image Credit: Costco

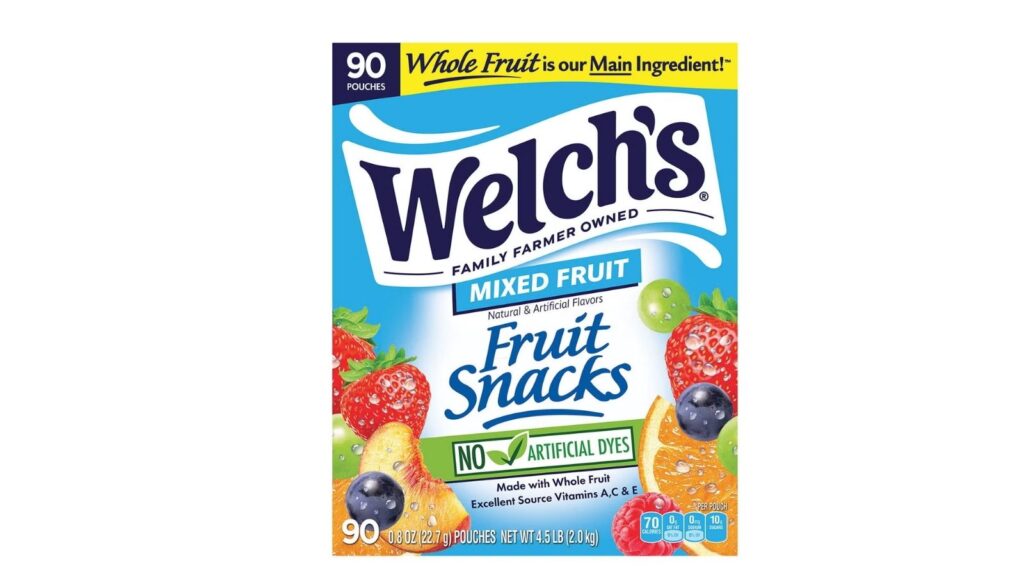
A 90-count box for $15.77 puts these Welch’s fruit snack pouches at roughly 18 cents each. They are individually packaged, made with real fruit, and contain no artificial dyes.

They make sense for more than October 31. Use some for trick-or-treat bags or a classroom party, then send whatever survives Halloween in school lunches. That second use matters with Costco quantities because a bargain stops looking like one when half the box is still sitting in the pantry next spring.

Tootsie Pops

tootsie pops
Image Credit: Costco

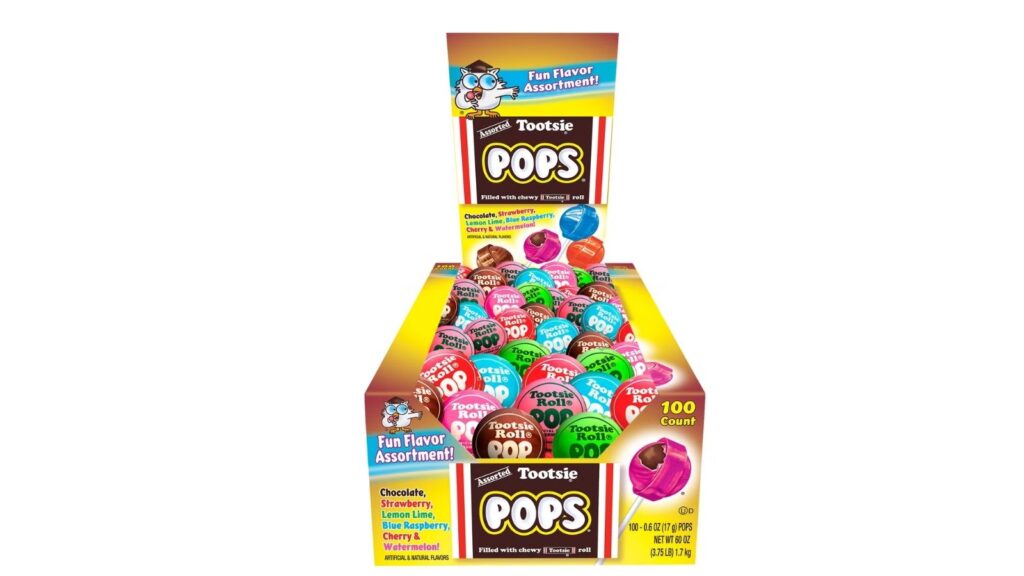
There is something financially convenient about candy that takes a while to eat. Costco’s 100-count assortment of Tootsie Pops is $15.99, bringing the cost down to about 16 cents per pop.

A hundred pieces is enough for many households to cover the entire trick-or-treat window with one box rather than stacking multiple supermarket bags in the cart. They are individually wrapped, easy to hand out, and substantial enough that one per child does not feel particularly stingy.

Sour Punch Twists

sour punch twists
Image Credit: Costco

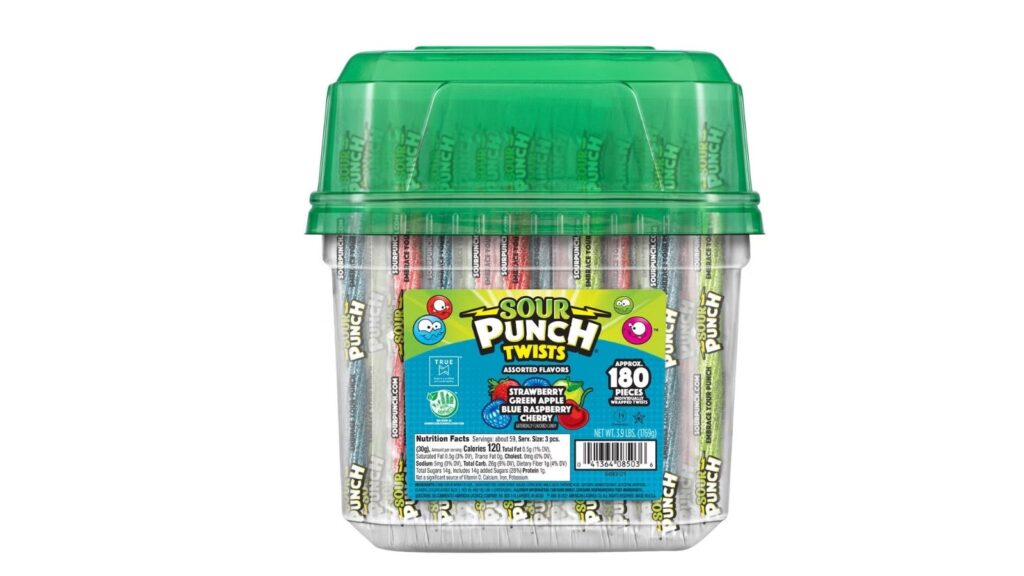
If your candy bowl is usually overwhelmed by chocolate, this 180-count tub of individually wrapped Sour Punch Twists adds a sour option for $16.99. That is under 10 cents per piece.

The tub is resealable, which is more useful than it sounds. You can set out only what you expect to use and keep the rest sealed rather than leaving an open bag of candy around for weeks. With 180 pieces, this also suits larger neighborhood events, school carnivals, and office candy bowls where smaller grocery-store packages disappear fast.

Popcornopolis Halloween Monster mini cones

Popcornopolis Halloween Monster mini cones
Image Credit: Costco

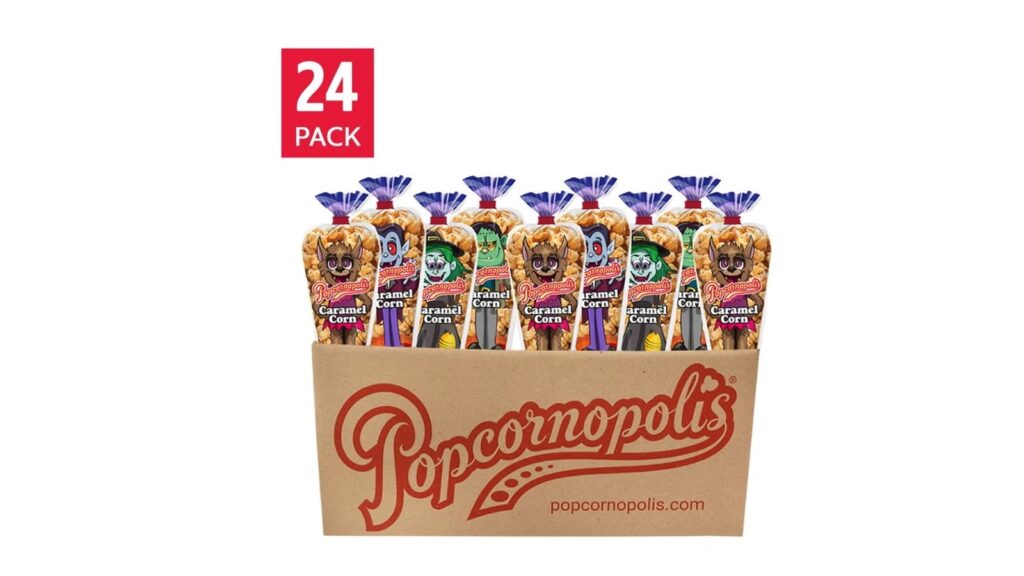
These Popcornopolis caramel corn cones land somewhere between candy and a small party favor. Costco has the 24-count Halloween Monster box for $29.99 after $10 off.

Each cone contains 2.2 ounces of caramel corn and is individually packaged, so these make more sense for a classroom, party, office handout, or a smaller group of trick-or-treaters than a high-volume front porch. At about $1.25 each, they cost more than fun-size candy but less than assembling 24 separate favor bags with multiple fillers.

Halloween and harvest kitchen towels

Halloween and harvest kitchen towels
Image Credit: Costco

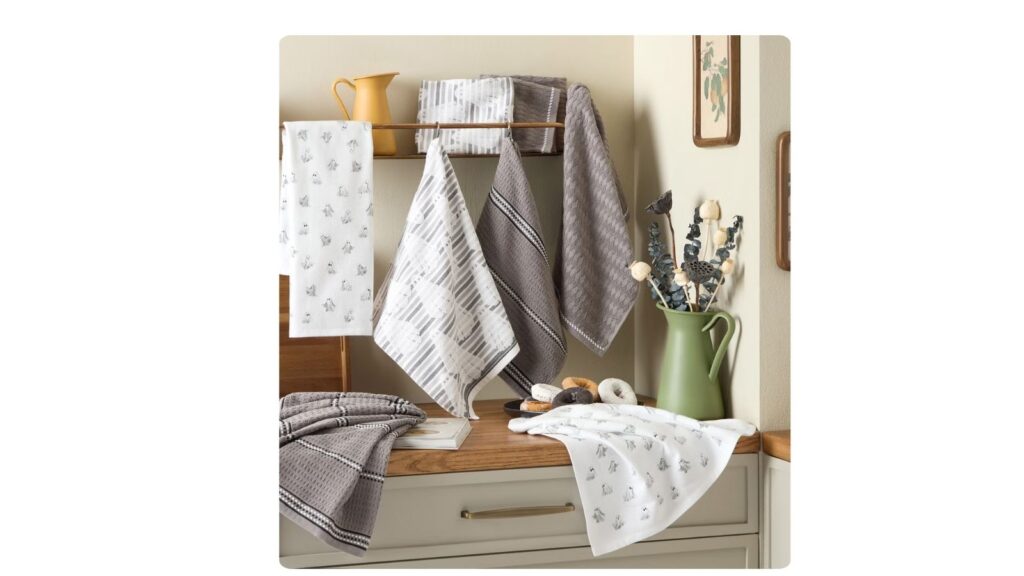
Seasonal decor earns its storage space more easily when it can also dry dishes. Costco’s eight-pack of Halloween and harvest kitchen towels is $19.99, which works out to about $2.50 per towel.

The 18-by-28-inch towels use a cotton-rich blend, are machine washable, and include a mix of festive designs rather than eight copies of the same print. If your kitchen towels are already worn thin, this is a more practical seasonal refresh than another countertop decoration that does nothing for the other 11 months of the year.

Halloween decorative pillows

decorative pillow
Image Credit: Costco

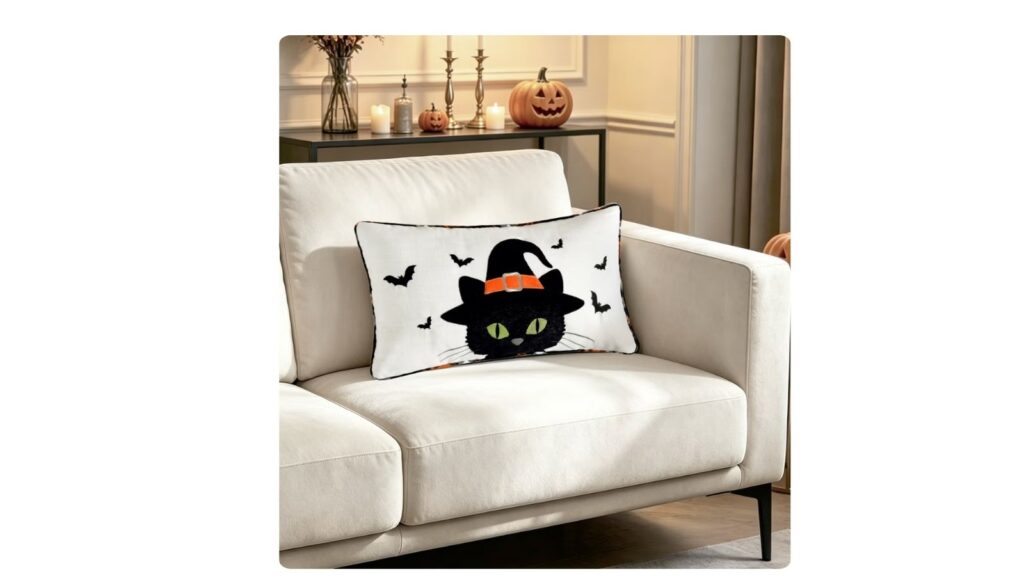
A whole room does not need a seasonal makeover to look like Halloween. Costco’s Halloween decorative pillows are $14.97, with designs that include options such as pumpkins, black cats, and skeletons depending on stock.

This is one of the cheaper decor pieces in Costco’s current online Halloween assortment, and one pillow can change a sofa or chair without creating another large storage bin. Pick one design you actually like rather than treating every variation as a separate purchase. October is short, closet space is not.

Jaclyn Halloween pajama set

Jaclyn Halloween pajama set
Image Credit: Costco

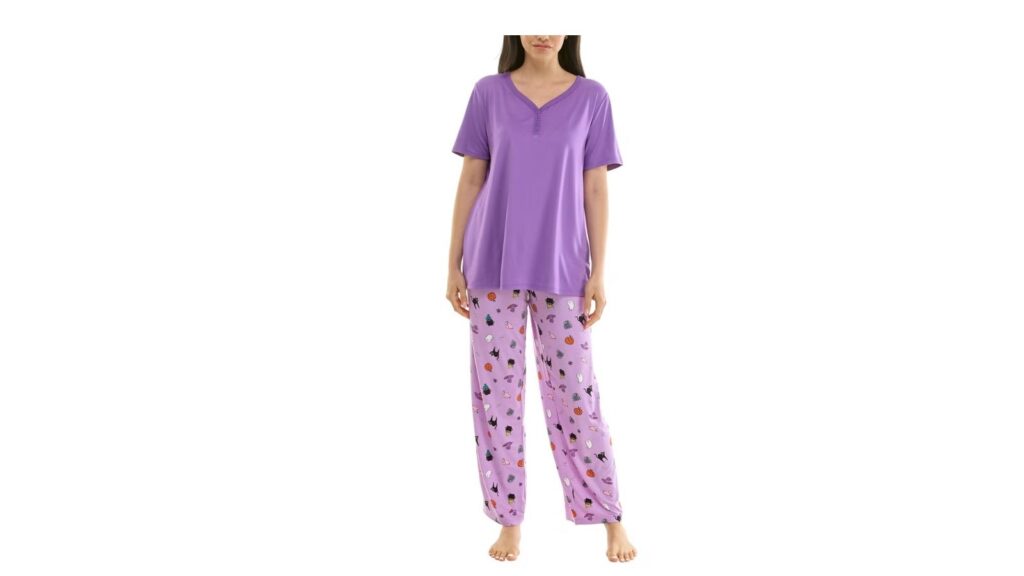
Costumes usually get one night of use. Halloween pajamas have a longer runway. Jaclyn’s three-piece set is $18.99 and includes a short-sleeve Henley top, shorts, and pants.

The black, purple, and orange options have different Halloween prints, but they are all one product, so there is no reason to treat each print as another deal. Getting both shorts and long pants makes the set useful through changing fall temperatures, and $18.99 for three pieces is easier to justify than a novelty outfit that never leaves the house after October 31.

Halloween embroidered faux fur throw

Halloween embroidered faux fur throw
Image Credit: Costco

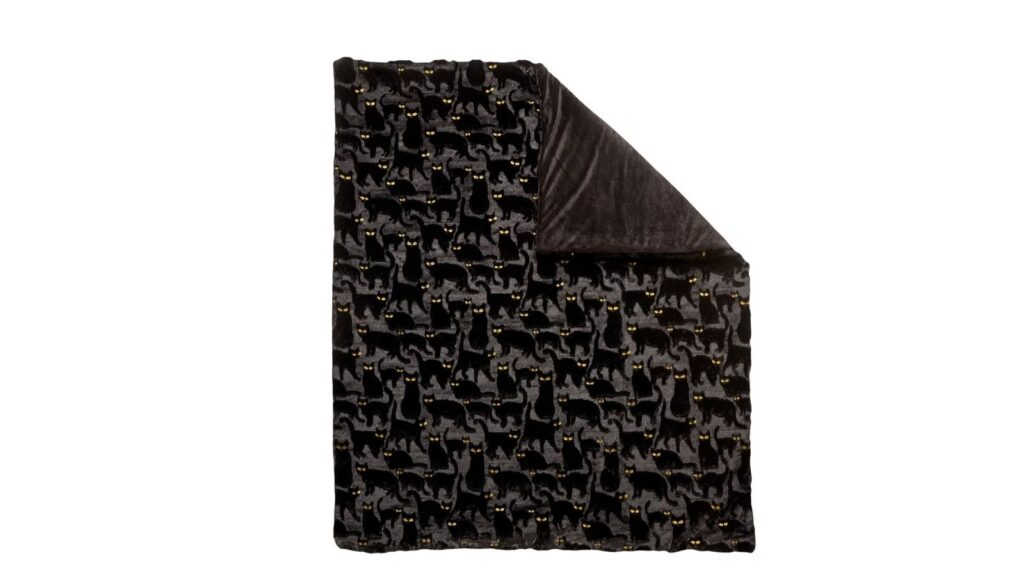
If you want Halloween decor that earns a job beyond sitting on a shelf, Costco’s embroidered faux fur throw is $23.99. Designs include seasonal cat, ghost, and pumpkin options, depending on availability.

A washable throw is easy to use for movie nights, a chilly porch, or the sofa long after the candy bowl is empty. Twenty-four dollars is still a discretionary purchase, but it is easier to defend than similarly priced decor that gets packed away untouched after four weeks.

Peanuts VelvetLoft throw two-pack

Peanuts Printed VelvetLoft Throw
Image Credit: Costco

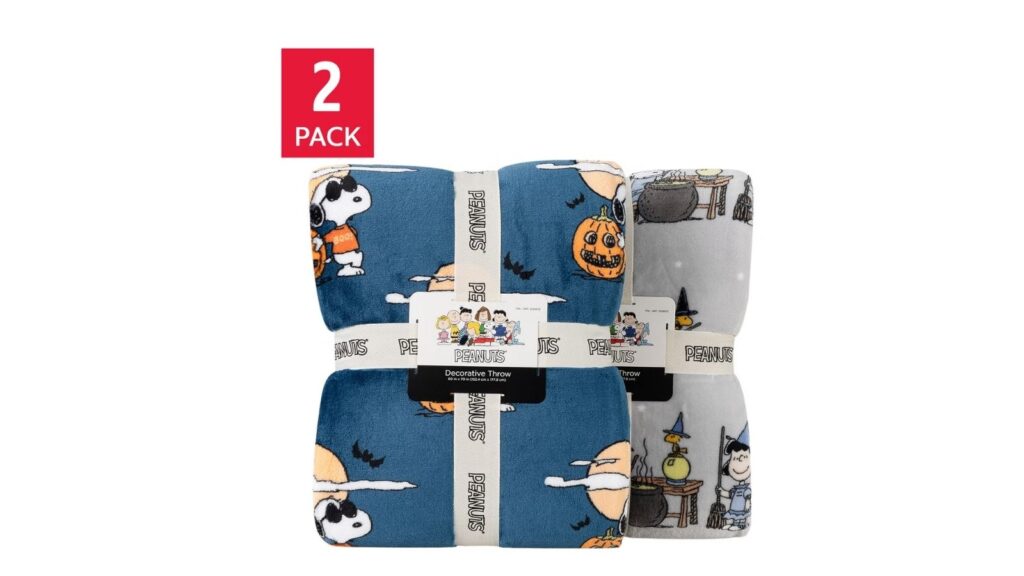
Two 60-by-70-inch Peanuts VelvetLoft throws cost $24.99, putting each blanket at roughly $12.50. The throws are machine washable and use 350 GSM fabric.

The two-pack is the value angle here. Keep one for fall movie nights and use the second in a kid’s room, guest room, or as an inexpensive seasonal gift. If you only need one blanket, buying two merely because the unit price is low makes less sense, so this one is best for households that can genuinely use both.

Harvest hooked accent rug

Accent Rug
Image Credit: Costco

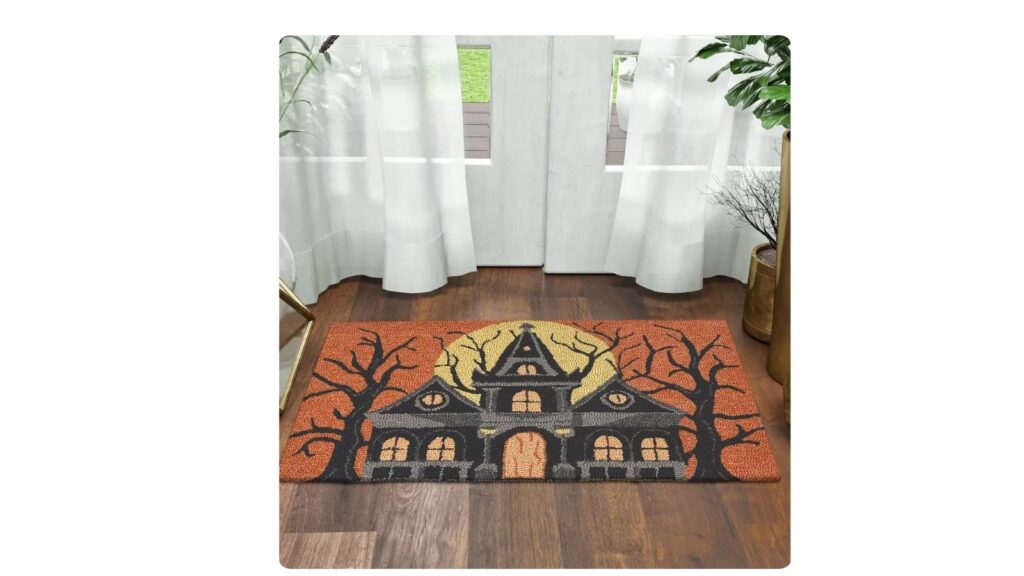
Seasonal doormats can easily creep past $30 at home decor stores, so Costco’s 22-by-38-inch harvest hooked accent rug at $26.99 is worth a look if your entryway needs replacing anyway.

The polypropylene rug has memory foam padding and a fall design that can stay out beyond Halloween, which gives it a longer useful season than something covered entirely in skulls. This is not a reason to replace a perfectly good rug. It is a reasonable way to combine a needed household purchase with seasonal decorating if yours is already headed for the trash.

Artstyle Moonlit Manor Halloween tableware

Moonlit Manor Halloween tableware
Image Credit: Costco

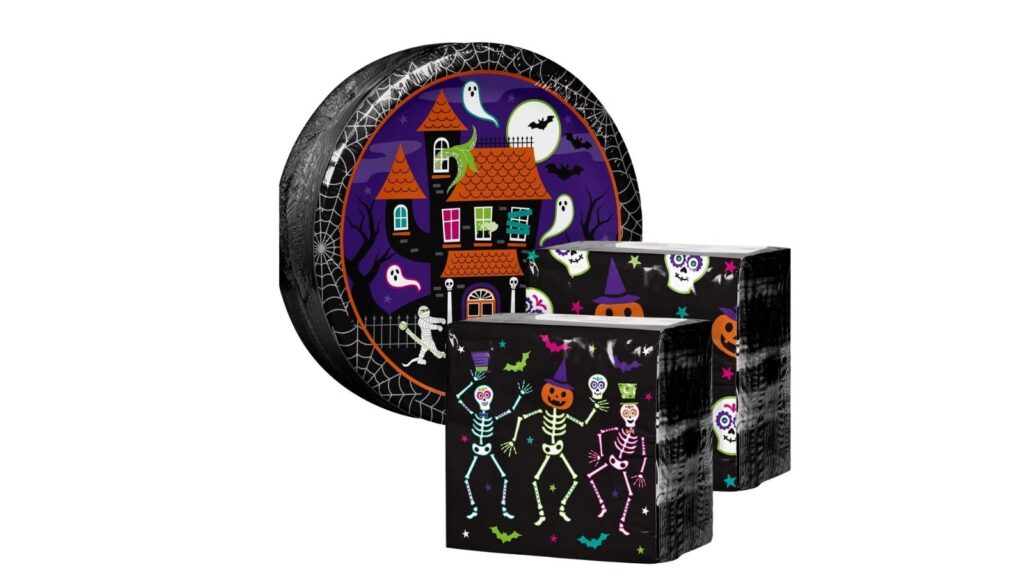
Hosting a large Halloween party can turn disposable tableware into a surprisingly expensive line item. Costco’s Moonlit Manor bundle includes 100 10-inch paper plates and 100 napkins for $29.99.

That is enough place settings for a genuinely big gathering, not a dinner for six disguised as a bulk pack. The plates are microwave safe and designed to resist cuts, so they can handle more than cupcakes. If you are only hosting a handful of people, skip the warehouse quantity. For a school, block party, church event, or packed house, the per-guest cost makes much more sense.

Teetot kids’ Halloween costumes

Halloween costume
Image Credit: Costco

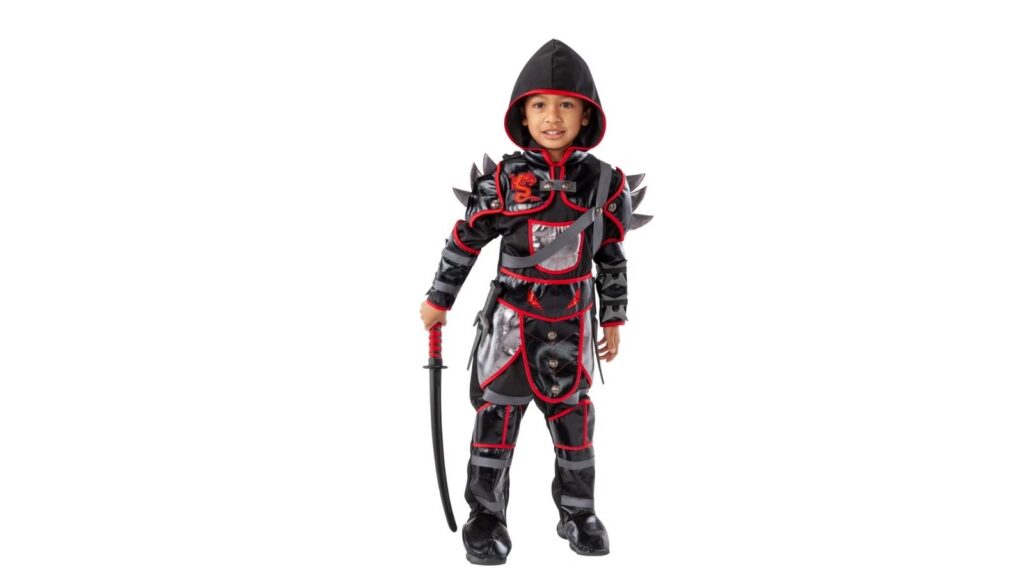
Costco currently has a broad group of Teetot children’s costumes at $39.99 each, with styles including ninjas, princesses, firefighters, astronauts, witches, and dinosaurs depending on size and availability.

Costume shopping gets expensive when the advertised price covers only the main outfit and every recognizable accessory costs extra. These are fuller costume sets, which is the important value point. Keeping all the styles in one entry also makes sense because a red ninja and a different-colored ninja are choices, not two separate deals.

Halloween tabletop dogs

Halloween tabletop dogs
Image Credit: Costco

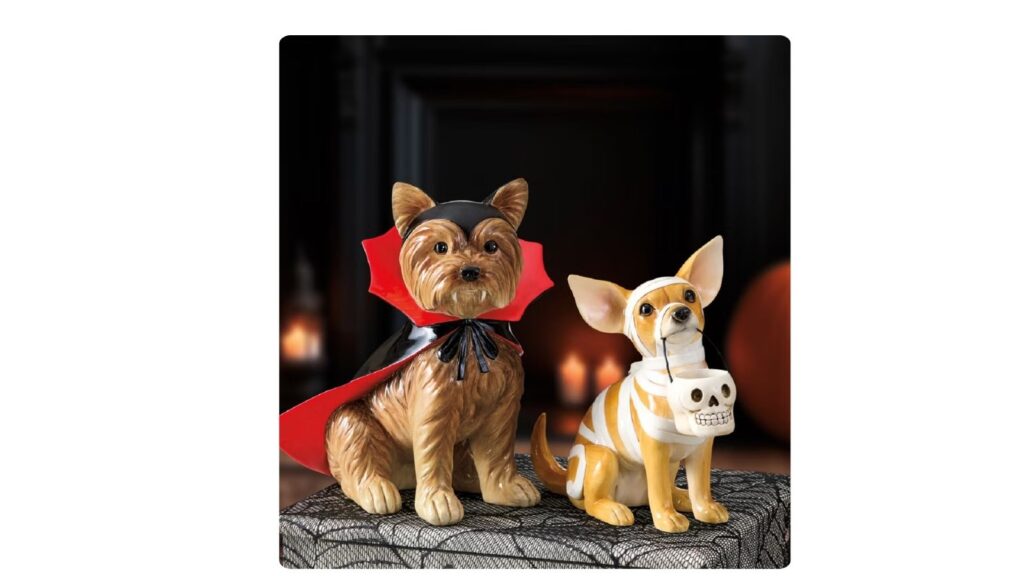
This one is firmly for people whose Halloween decorating philosophy includes tiny dogs in costumes. Costco’s set of two resin tabletop figures is $39.97 and includes a vampire Yorkie and mummy Chihuahua.

It is not the practical pick of the bunch, but the price covers two substantial reusable figures rather than one small novelty item. If you already collect dog-themed decor, the pair makes more sense than buying similar pieces separately. If that sentence does not describe you, your $40 has plenty of better jobs elsewhere on this list.

Animated rise-up reaper

Animated rise-up reaper
Image Credit: Costco

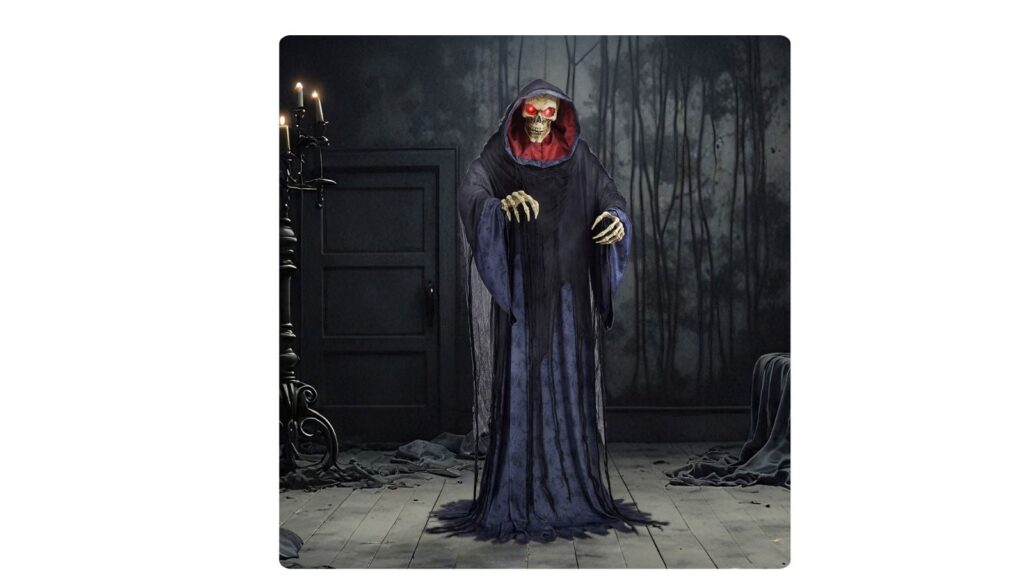
A large Halloween prop can cost as much as several years of candy, so size and mechanics need to justify the bill. Costco’s animated Rise Up Reaper is $79.97 and grows from about five feet to nearly seven feet during its animation.

That movement gives it more impact than a static figure taking up the same storage space. It is still best for households that decorate outdoors every year, not someone trying Halloween yard decor for the first time. Reusing it for several Octobers is what gets the per-season cost down to a reasonable level.

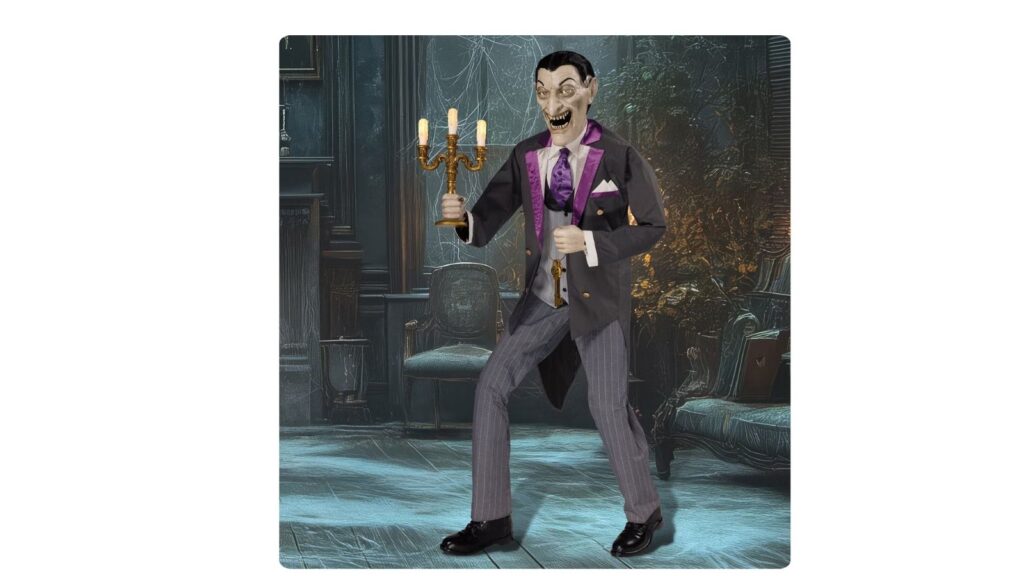
Animated vampire butler

Vampire butler
Image Credit: Costco

At six feet tall, Costco’s animated vampire butler is meant to be a focal decoration rather than another piece squeezed onto the porch. It is $69.97 and adds LED eyes, sound, a lighted candelabra, motion activation, and a timer.

Those built-in effects matter because recreating the same setup with a static figure, separate lighting, and sound equipment can quickly erase any savings. It works indoors or outside and makes the most financial sense for someone who already knows oversized Halloween decorating is an annual event at their house.

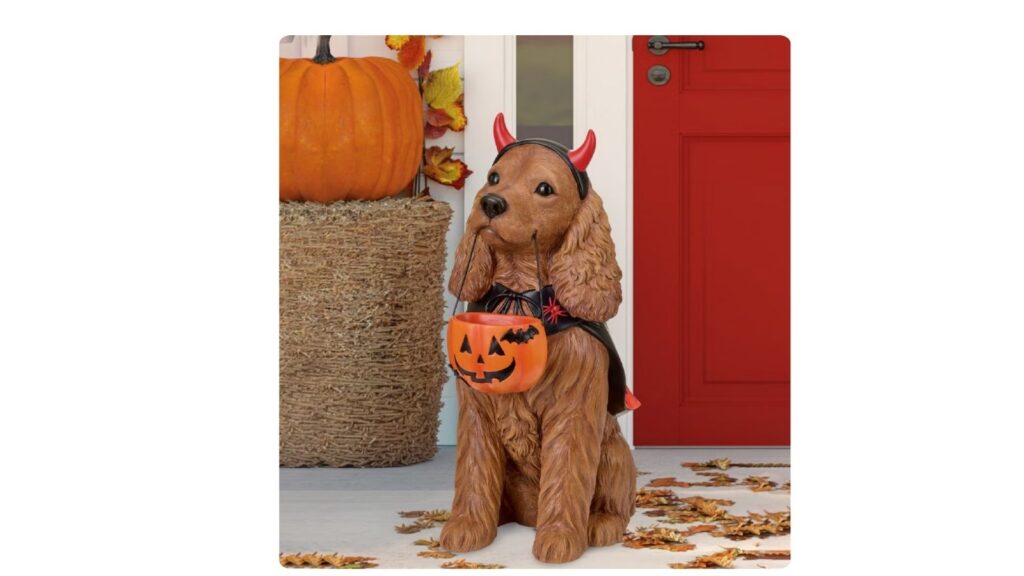
Halloween dog greeter

Halloween dog greeter
Image Credit: Costco

Costco’s 26-inch Halloween dog greeter costs $74.99 and comes in different dog designs, including breeds such as a doodle, French bulldog, and cocker spaniel depending on stock.

The hand-painted resin figure can be used indoors or in a covered outdoor area. Seventy-five dollars is not an impulse-buy price, so this only earns its keep if you genuinely want a substantial porch decoration and will store it for future years. The different breeds are variations of the same item, not three separate reasons to spend another $75.

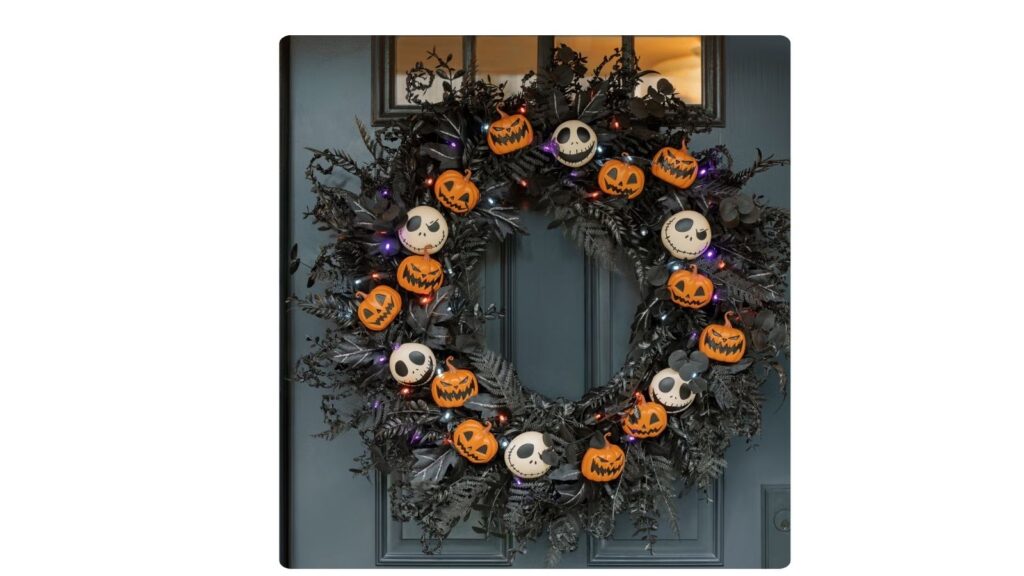
The Nightmare Before Christmas LED wreath

Nightmare Before Christmas LED wreath
Image Credit: Costco

A licensed Disney decoration can get expensive fast, particularly once lighting is involved. Costco’s 30-inch Nightmare Before Christmas wreath is $84.99 and comes pre-lit with 50 multicolor LEDs.

It includes a timer and batteries and is suitable for indoor or covered outdoor use. The useful part is that the wreath combines the licensed decoration and lighting in one piece rather than requiring another string of lights. Nightmare Before Christmas fans can also plausibly stretch its use into the holiday season, which is more mileage than most Halloween wreaths get.

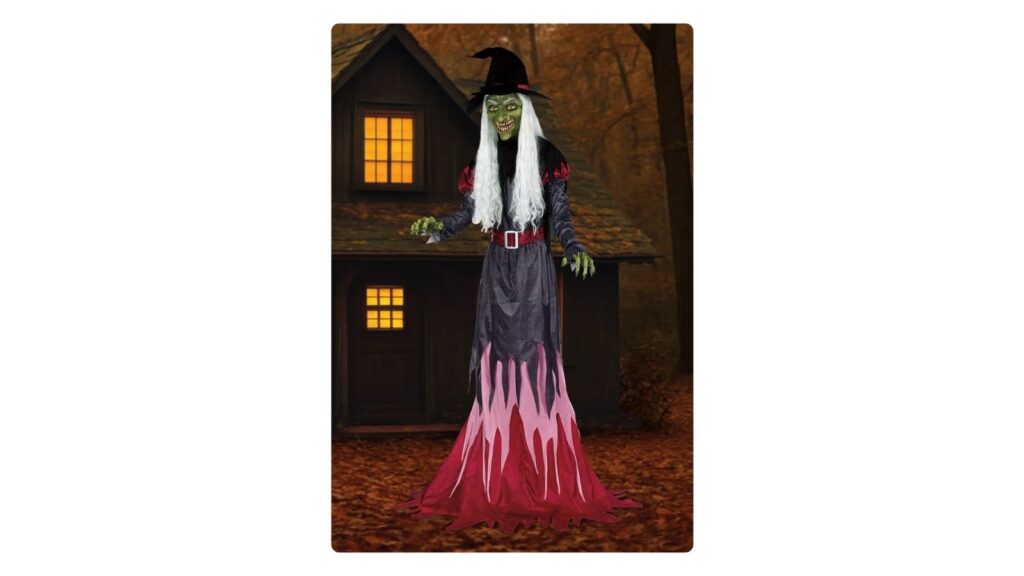
Animated witch

animated witch
Image Credit: Costco

Twelve-foot Halloween decorations are ridiculous in a very specific, intentional way. Costco’s 12-foot animated witch is $99.97 and includes LED eyes, motion activation, sound, volume control, and a timer.

Keeping an animated prop of this size below $100 is the value argument, but only if you have the yard and storage space for it. Apartment dwellers and casual decorators can stop reading at “12 feet.” For households that already spend each October building a large outdoor display, one oversized centerpiece can do more visual work than several smaller decorations bought separately.

As household separations become more complex, parents are organizing financial disclosures early to ensure fair custody and property outcomes.

Navigating marital dissolution involves significant financial, administrative, and legal hurdles, particularly when dividing shared real estate, retirement accounts, and establishing child custody arrangements. Tackling these hurdles requires a clear roadmap right from the start. Preparing your personal records helps protect your future stability while keeping proceedings grounded in practical reality. Taking control of these early steps sets a calm tone for everything that follows.

Learn practical steps for organizing finances, real estate, retirement accounts, records, and child custody matters.
Image Credit:congerdesign via Pixabay

Why is early preparation crucial for asset division?

Splitting a household changes every part of your daily routine. Taking control of your documents early stops chaotic surprises from derailing your negotiations. Financial planners emphasize that organizing retirement accounts and real estate valuations before filing helps parents secure more stable custody and property outcomes. 

Taking this proactive route reduces emotional strain. Clear facts replace guesswork when both sides sit down to negotiate terms. Building a solid informational foundation early prevents unnecessary stress down the road.

How do you gather key financial records?

Tracking down every bank statement, tax return, and debt record takes patience. Begin by creating a dedicated digital folder for all joint and individual accounts. Missing a single investment portfolio or credit card liability creates major headaches later. 

Collect at least three years of tax filings to establish a complete financial baseline. Thoroughness during this phase prevents hidden surprises from emerging during formal proceedings.

  • Download bank statements: Gather checking, savings, and investment records for all active accounts to trace cash flow accurately.
  • Locate tax returns: Pull federal and state filings from the past 3 years to verify reported income and deductions.
  • List debt obligations: Document mortgages, car loans, and credit card balances clearly to map out shared liabilities.

What steps protect parental rights and stability?

Children need consistency while family dynamics shift around them. Maintaining predictable daily routines minimizes the emotional impact of household separation. Courts look closely at who historically managed daily caregiving tasks. 

Documenting your active involvement in school events, medical appointments, and homework helps demonstrate your ongoing dedication. Showing consistent parenting builds credibility with evaluators and judges alike.

How can you establish sustainable custody schedules?

Designing a parenting plan requires flexibility paired with firm boundaries. A workable schedule respects both parents’ work hours while prioritizing school stability for the kids. Practical communication channels keep co-parenting discussions productive. 

Dedicated apps prevent miscommunications and create a reliable record of scheduling requests. Establishing predictable routines helps children adapt smoothly to their new living arrangements.

Finding an experienced advocate makes a massive difference in how smoothly your case proceeds. Working alongside family law attorneys in Fairfax, VA, or your area gives you localized insight into regional court expectations. Local professionals understand how judges interpret property laws and custody guidelines in your specific county. 

Building this relationship early keeps your legal strategy targeted and effective. Choosing the right guide streamlines every subsequent negotiation step.

Why do regional court rules shape outcomes?

Every county operates under specific procedural guidelines that influence court timelines and document requirements. Ignoring local nuances can stall your paperwork for months. Judges apply state statutes through local administrative rules. 

Knowing these unwritten expectations prevents costly delays during hearings. Familiarity with local court customs gives your case a distinct tactical advantage.

Local rules often dictate everything from font size to filing deadlines, so a single oversight can trigger rejection. Some courts require mandatory mediation before a hearing, while others demand specific financial disclosures upfront. Understanding these distinctions helps you anticipate the opposing party’s procedural moves.

Image Credit: ManuelaJaeger via Pixabay

What strategies minimize conflict moving forward?

Keeping communications focused on facts rather than past grievances speeds up negotiations. Direct discussions save thousands of dollars in legal fees and emotional energy. Remaining open to compromise allows both parties to move forward constructively. 

Reaching an amicable agreement benefits everyone involved, especially growing children. Cultivating a cooperative mindset preserves valuable resources for your family’s future. Using a shared calendar or co-parenting app reduces misunderstandings about schedules and expenses. 

Agreeing on a neutral third party for disputes can prevent minor issues from escalating. Written summaries of verbal agreements keep both sides accountable without hostility. Prioritizing long-term stability over short-term victories creates a foundation for lasting peace.

Taking charge of your financial and legal preparation transforms an overwhelming transition into a manageable process. Early planning creates the stability you need for a fresh start. Lean on trusted advisors, stay organized, and take each step with confidence. Your future begins with the proactive choices you make today.

When you’re a single mom, your car often feels less like a convenience and more like a necessity. At that time, the last thing you need is another unexpected bill. Unfortunately, tires have a way of needing replacement at exactly the wrong time. 

If you use your car regularly, like getting to work, taking your kids to school, and running everyday errands, you can’t afford to wait to replace your tires until you save enough money. But paying the entire cost upfront can put a lot of pressure on your budget, especially with rent, groceries, childcare, and other necessities. 

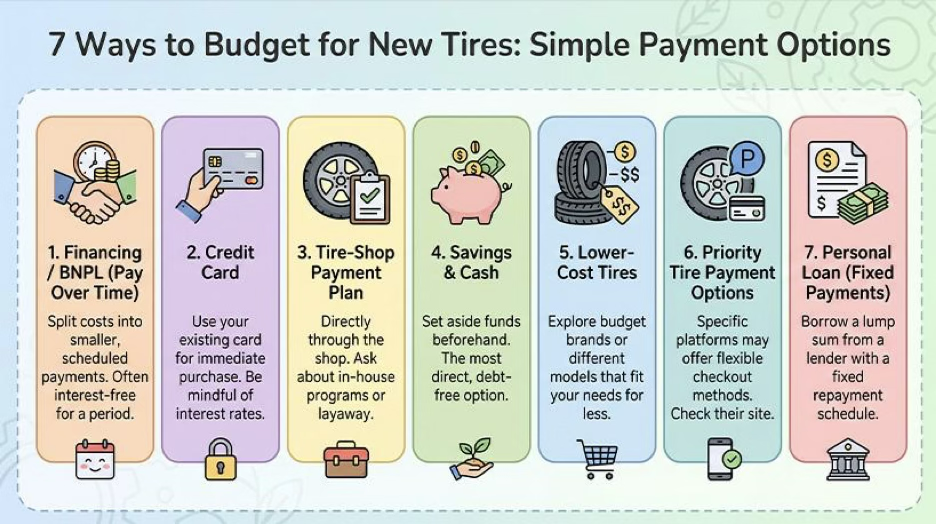
The good news is that you have plenty of options. Tire financing and buy now, pay later methods can help you to replace your tires now while giving you more flexibility with your cash flow. Here are the top seven options to consider when choosing the best payment option. 

Buy tires with a buy now, pay later plan

A buy now, pay later plan can let you purchase tires without paying the full cost upfront. Instead, you can make several installments over time. Depending on the provider and plan, you may be able to split the purchase into a few scheduled payments; some plans also offer interest-free financing. 

However, not all buy now, pay later options work the same way. Some charge interest or fees, while the terms and eligibility requirements can vary. Before choosing a plan, look at the total amount you’re repaying, not just the size of individual payments. 

When you’re budgeting as a single mom, consider whether the required payment fits comfortably into your monthly budget. Don’t choose a payment that only works if nothing unexpected happens. Keep enough room for essentials and the occasional financial surprise. 

Use a tire financing program

Tire financing can help you spread the cost of a new set of tires over several months instead of paying the full amount upfront. Depending on the lender, purchase, and applicant, financing terms may vary, including the repayment period, interest rate, and any required down payment. 

When comparing financing offers, don’t judge them by the monthly payment alone. A longer repayment period may lower your monthly bill but increase the total amount you repay. 

Before signing for a financing program, include a checklist to compare your options: 

  • APR or interest rate
  • Monthly payment 
  • Total amount repaid
  • Fees 
  • Down payment 
  • Length of financing 
  • Late payment terms

For a single mom working with a limited budget, the goal isn’t simply to find the lowest monthly payment. It’s to find financing that you can easily manage from start to finish without putting other household expenses at risk. 

Put the purchase on a credit card

A credit card can be a convenient way to pay for tires, especially when you need them unexpectedly and don’t have enough cash on hand. But whether it’s a good fit depends on how quickly you can pay it off and your card’s terms. 

Before choosing this option, consider:

  • Current APR
  • Available credit
  • How long it will take to pay off 
  • Whether the purchase could include credit utilization 
  • Total interest paid

The credit card option makes sense if you pay the balance off quickly or have a legitimate promotional offer, such as a temporary 0% APR period. On the other hand, carrying a balance at a high interest rate can make a $700 tire purchase considerably more expensive over time. 

The issue isn’t that credit cards are inherently bad. The cost of carrying the balance matters. Before using one, make sure you understand how the purchase fits into your overall budget and repayment plan. Building healthy credit habits can make it easier to use credit wisely and improve your financial independence. 

Ask the tire shop about payment plans

Before assuming you have to pay for your tires all at once, ask the tire shop whether it offers financing or payment plans. Some retailers and installers may offer options that let you spread the purchase over several payments. 

Be especially careful with promotional financing. A special rate may only apply for a limited period or come with specific conditions. Ask when the promotional period ends, what happens to any remaining balance afterward, and whether there are fees or other requirements you need to know.

Understanding the full cost upfront can help you choose a payment plan that fits your budget without creating an unexpected expense later. 

Use savings but don’t empty your emergency fund

If you have enough money in savings to cover a new set of tires, paying in cash can be a smart way to avoid interest charges and financing fees. But it doesn’t mean you should automatically drain your savings account just to avoid taking on debt. 

An emergency fund protects you when an unexpected expense comes up. For a single-income household, that safety net can be especially valuable. A medical expense, childcare issue, or additional vehicle repair could quickly turn a tire purchase into a bigger financial strain. 

Before paying for tires outright, calculate how much you’ll have left in savings. If the purchase would reduce your emergency savings, borrowing a manageable amount may be better than leaving yourself without a financial cushion. 

Paying cash isn’t the best option if it leaves you vulnerable. In some cases, preserving a reasonable emergency cushion and using a low-cost financing option for part of the purchase may make more sense. 

How to decide if tire financing fits your budget

Before you agree to tire financing, take a few moments to ensure the payment fits your budget. Ask yourself these three questions before you finance a new set of tires: 

1. Do I need the tires now?

      If you have worn and unsafe tires, delaying the purchase could put you and your family at risk. In that case, financing may be preferable to driving on tires that need to be replaced. 

      2. Can I afford the payment?

        Look at your payment in the context of your entire monthly budget. Add it to your existing expenses, including rent, groceries, childcare, utilities, gas, and debt payments. Make sure there’s enough room in your budget without relying on every dollar of your income. If your budget feels tight, these money management tips for single moms can help you find a little more breathing room. 

        3. What will the tires actually cost me? 

          A monthly payment may sound manageable, but what will you pay altogether? Compare the total repayment amount, including interest and fees, rather than choosing an option based only on the monthly payment. 

          The best financing option is one you can comfortably afford and understand from start to finish. 

          Conclusion: Financing tires doesn’t have to mean financial failure

          Buying new tires when you don’t have the cash to pay upfront doesn’t mean you’ve failed financially. Sometimes, an unexpected car expense simply arrives at a difficult time. 

          Choose a payment option that works with your budget, not against it. 

          Whether you use a buy now, pay later option, tire financing, a credit card, a payment plan, or some combination of savings and financing, take the time to understand the interest, fees, monthly payment, and total cost. 

          Protecting your emergency savings can be just as important as avoiding debt. You don’t have to make the perfect financial decision; you just need to make one that keeps your car safe, your family moving, and your finances manageable. 

          Say your yard gate was latched some time ago, but your dog is somehow gone with no warning and no sound. Your first reaction is panic. Then you find yourself thinking, “How much will finding him cost when you have no spare money set aside for something like this?”

          Printing flyers and the petrol for driving around to local shelters cost money. You have to take a day off work to keep looking on top of it. It adds to expenses you were not expecting in your monthly budget.

          The obvious next steps all cost money

          A missing pet search starts with putting flyers on telephone poles and shop windows. You post it on social media and have to pay someone to push the post for more reach. Then comes the drive to nearby shelters, as you are hoping somebody has already brought your dog in.

          Your dog going missing can turn a completely ordinary month into a month with an unexpected bill, as you need to spend money and take time away from work. But the effort is not always wasted. People who pass by where you posted flyers, and those who saw your social media post, might have seen your dog and can let you know.

          A boosted post increases the chances of finding your dog faster by reaching more people who wouldn’t have seen the post without the boost. The problem is, what if people aren’t in the right place at the right time, and you need to spend more and put in more effort.

          The free option is the one that reaches furthest

          Here is why PawBoost is the better option. A PawBoost alert costs you nothing to post. A report is sent as a local alert to the Facebook page for your zip code and to email subscribers in the area. Nearby app members also get the alert, so the message isn’t limited to people who follow you.

          According to PawBoost’s own reported data, 45% of people who post a pet on PawBoost eventually mark the post as reunited. It definitely looks good when the alternative is paying for flyers and promoted posts.

          A flyer you pasted will only be useful if enough people walk by and see it. A boosted post can also turn out to be useless if people just scroll past without seeing it. But the PawBoost alert goes out to everyone in the local area at no extra charge.

          If an emergency like a missing dog comes up when you are waiting for payday and are low on budget, you start to panic even more. Getting the alert out with PawBoost for free means your search starts before you even think of spending money on other things.

          Posting an alert costs nothing, but boosting a post does

          Posting the alert on many pet platforms is free, but they usually also have an optional boosting service that they charge for. All boosted social posts cost you money to reach more people. The PawBoost alert goes beyond the person’s own followers and puts the missing pet in front of people nearby.

          Keeping a recent photo of the dog on the phone makes the process easier and faster. The alert can go out as the search is getting underway, and you dont have to wait for flyers to be printed or a paid post to be approved.

          You don’t need to spend your money just because a pet has gone missing. You can paste flyers and use other paid options later if they are needed after the alert is out and the search has started.

          It costs nothing but may be the first thing worth trying

          There are some nights when the last thing you want to think about is another unexpected expense. The list of emergency expenses no one prepares for has ‘a missing pet’ as one of the unexpected expenses. But when your pet is missing, you have one option that does not require you to spend any money.

          45% of people who post a missing pet alert through PawBoost eventually mark the post as reunited with the pet. The search can start in minutes with a photo and a free PawBoost alert while there is still time to get the word out locally. As the alert costs nothing, you don’t have a financial decision to make before the search begins.