scroll top

If you’ve reached a point where divorce feels less like a fleeting thought and more like a decision you need to seriously consider, the first piece of advice we’d like to give you is this: don’t announce it immediately. Second, get informed.

Divorce is very rarely easy and simple, especially when kids are involved. So, before making your next move, you need a clear, objective picture of your reality. You don’t need to have a five-year plan. But you do need to know what you own, what you owe, what your kids need, and what the law in your state actually says.

Get a clear picture of the family finances

First, get a clear picture of your finances. The only way to do that properly is by finding copies of recent tax returns, pay stubs, bank and investment statements, retirement accounts, credit card bills, mortgage documents, insurance policies, loan records, and anything else that shows where money comes from or where it goes.

Don’t assume you know the whole picture because you pay the grocery bill. You might discover a retirement account you rarely think about, a business interest, a line of credit, or debts you did not realize were still outstanding (it happens surprisingly often).

Also, make your own budget. Figure out what housing, childcare, groceries, insurance, transportation, school expenses, and everything else will realistically cost if you are running one household instead of two.

Protect your access to your own information

If your spouse has always handled things like banking, taxes, investments, or insurance, now is the time to learn how those things work. And make sure you can access your own email, financial accounts, phone account, and important documents.

If you share a computer or tablet, think about what information may be stored there. Likewise, change passwords where appropriate and use two-factor authentication.

Keep in mind, we’re not saying to empty joint accounts or hide money, because that can create serious legal problems. What we are saying is this: make sure you are not completely dependent on someone else for access to information you may soon need.

And yes, hiding wealth and assets is actually pretty common. But that doesn’t make it legal.

Start thinking about custody early

You will eventually need to think about where your children live, how parenting time works, who makes medical and educational decisions, how holidays are divided, who handles transportation, and what happens when school breaks collide with work schedules. It’s much better to do that on time than wait for a complicated custody battle.

Start keeping ordinary records, like:

  • Who takes the kids to appointments?
  • Who handles school communication?
  • What activities do they attend?
  • What does childcare cost?

Likewise, make sure you keep relevant receipts, calendars, school records, and medical information. You want to have accurate information when lawyers, mediators, or courts need to understand how your family actually operates.

And try not to make promises to your children about what will happen. You may have a pretty good idea of what you want, but the legal process may have other ideas.

Talk to a lawyer before you make big moves

You don’t need to file for divorce tomorrow simply because you scheduled a consultation. In fact, an early consultation can be useful precisely because you have not filed yet.

A family law attorney can explain how your state handles property division, custody, child support, spousal support, and the timing of the process. If you are looking for comprehensive legal services for families, look for firms with experience. You want someone who can help you understand the legal issues specific to your circumstances.

Bring your financial documents and questions. Ask what you should do now, what you should avoid doing, and what could change once you file. Those answers can be more valuable than a stack of generic divorce articles.

Deal with the mundane stuff now

There is a long list of things that have nothing to do with courtroom arguments but can make your life much easier later. Childcare, housing, health insurance, and school logistics are some of the things you can think about and plan for before divorce.

First, check your health insurance and understand what happens if you are currently covered through your spouse. Then, make sure you know where the children’s birth certificates, passports, medical records, school records, and insurance information are. Also think about childcare for legal appointments and court dates. If you may need to move, research housing costs before you make promises to yourself about what you can afford.

Yes, divorce can be difficult and chaotic, but you don’t have to solve everything at once. You just need enough information to stop making decisions in the dark.
Your child is getting married, and amid the family photographs, emotional speeches, and countless little moments leading up to the ceremony, it is easy to put your own outfit at the bottom of the list. But this is your special day to celebrate, too. As a single mother, you have your own place in this milestone, and you deserve to feel confident, comfortable, and beautifully dressed as you watch your child begin this new chapter.

Explore a practical afternoon wedding style guide for the mother of the bride, including outfit and accessory tips.
Image Credit: Letícia Fracalossi via unsplash

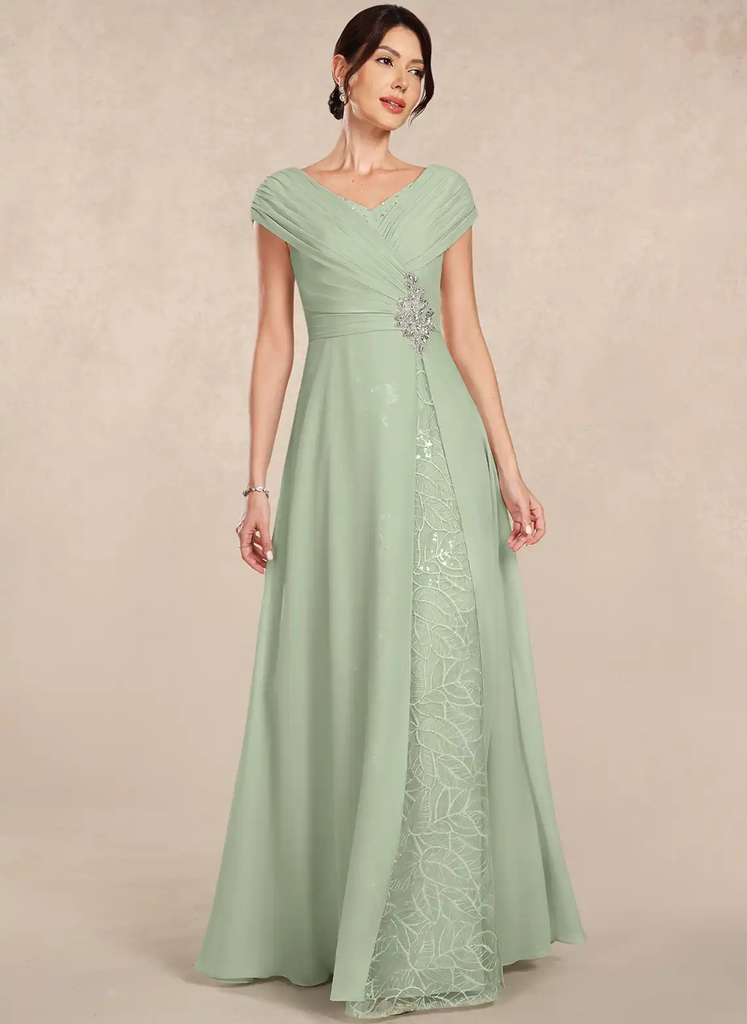
An afternoon wedding has a charm of its own. The atmosphere is often lighter and more relaxed than an evening reception, with natural daylight, softer colors, and less need for dramatic formalwear. Choosing the right type of elegant mother of the bride dresses for afternoon wedding celebrations means finding something that feels elegant without being excessive, suits the setting and season, and allows you to enjoy every meaningful moment of the day.

How afternoon weddings differ from evening celebrations

Afternoon weddings generally allow for a lighter and more natural approach to dressing. This does not mean the outfit should look casual, but it can be less dramatic than what you might choose for an evening reception.

Daytime ceremonies often work well with:

  • Softer colors instead of very dark or heavily metallic shades
  • Lighter fabrics with movement
  • Elegant midi, tea-length, or understated floor-length silhouettes
  • Subtle embellishment rather than intense sparkle
  • Comfortable shoes that suit outdoor photographs or garden paths

The invitation still matters. An afternoon wedding at a formal estate may require a more refined look than a casual garden ceremony, so the time of day should be considered alongside the venue and dress code.

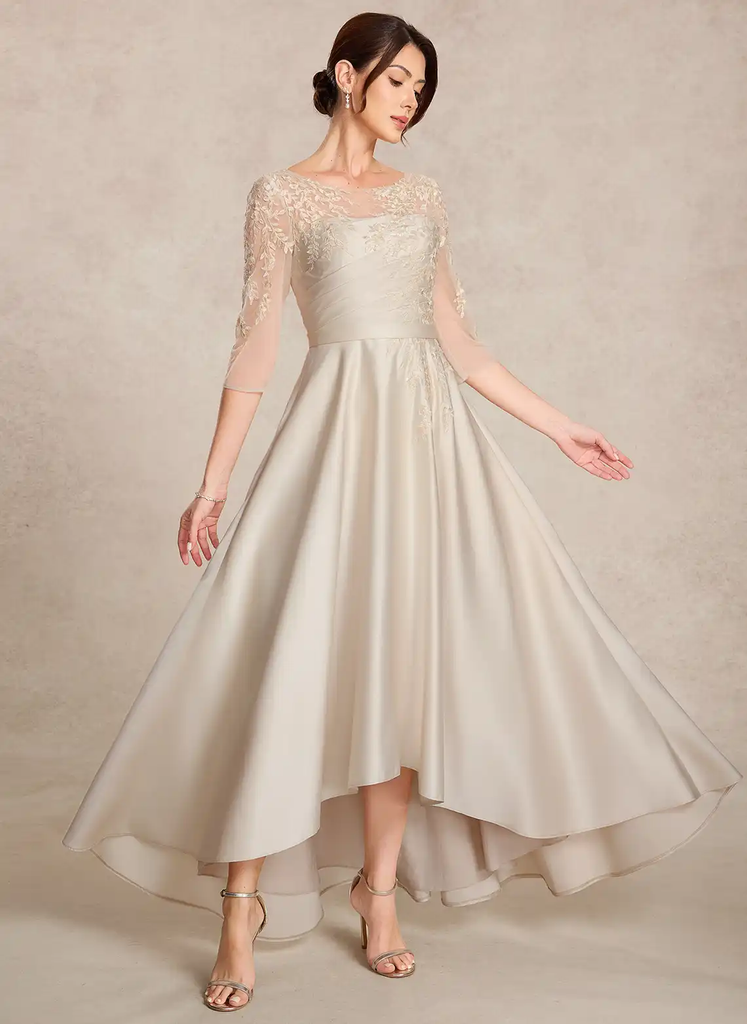
Image source: JJ’s House

Types of mother of the bride dresses for an afternoon wedding

There is no single style that suits every afternoon wedding. Some mothers prefer a traditional long dress, while others feel more confident in a shorter silhouette that is easier to move in.

A few options are particularly suitable for daytime celebrations:

  • Tea-length dresses: Falling between the knee and ankle, this length feels elegant without being too formal. It works especially well for garden, church, and countryside weddings.
  • Midi dresses: A sophisticated choice for a modern afternoon ceremony, especially when paired with a defined waist or softly tailored shape.
  • A-line dresses: Comfortable and flattering, with enough movement for sitting, walking, and greeting guests.
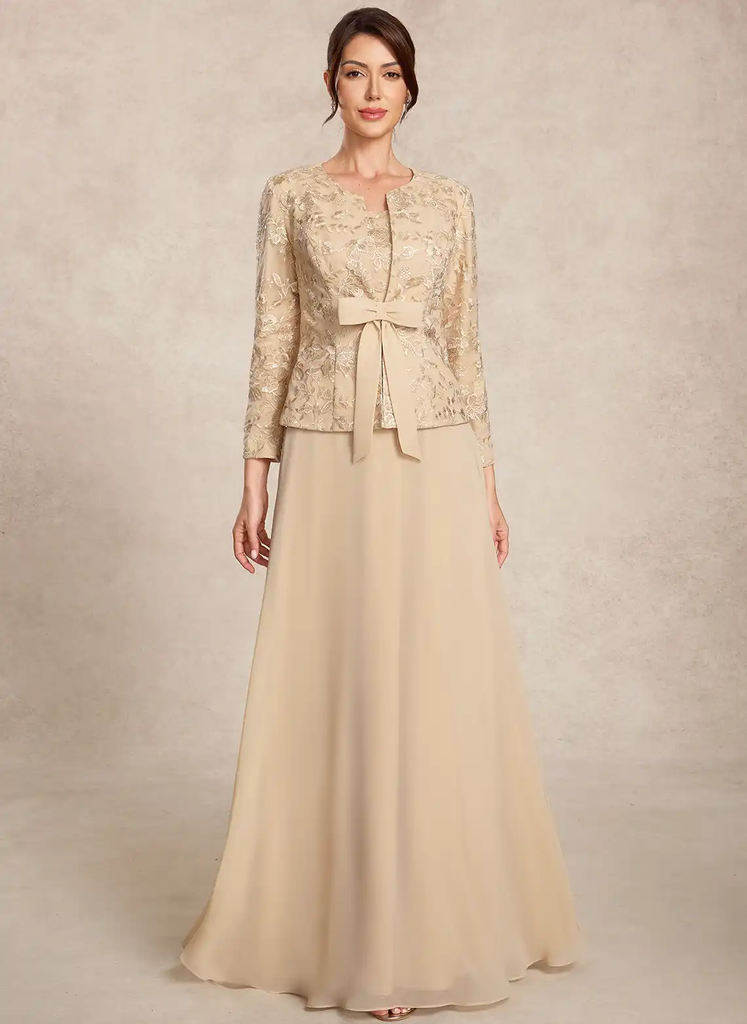
  • Chiffon dresses: Ideal for a softer, flowing appearance and especially lovely in outdoor settings.
  • Simple floor-length gowns: Appropriate when the wedding is more formal, particularly if the design is clean rather than heavily embellished.
  • Lace dresses: A timeless option that adds texture and detail without relying on excessive decoration.

The best type of mother of the bride dress for afternoon wedding events is one that looks special in daylight and still feels comfortable several hours later.

Image source: JJ’s House

Match the dress to the wedding’s formality

The ceremony’s dress code should guide how elaborate the outfit needs to be. A relaxed dress at a formal wedding may feel underdressed, while a heavily beaded gown at a casual afternoon gathering can seem out of place.

For a casual or outdoor wedding, consider a flowing midi, floral lace dress, or softly printed design. A semi-formal celebration may call for a polished cocktail-length dress, elegant jumpsuit, or refined tea-length style. For a formal afternoon wedding, a floor-length gown with tasteful draping, subtle beading, or a structured silhouette can still feel appropriate without looking like eveningwear.

It is also worth considering the role you will play throughout the day. If you expect to move between photographs, conversations, and different parts of the venue, a dress that allows easy movement may be more useful than one that requires constant adjustment.

Fabrics that work well in daylight

Fabric can change the entire impression of a dress. In the afternoon, materials with softness and movement often look more natural than very heavy or highly reflective finishes.

Good options include:

  • Chiffon: Light, fluid, and well suited to outdoor or warm-weather weddings.
  • Crepe: Smooth and elegant, with enough structure to create a polished silhouette.
  • Lace: Adds visual interest and works beautifully for romantic or traditional ceremonies.
  • Satin: Suitable for a more formal event, particularly when the finish is soft rather than excessively shiny.
  • Jacquard: Offers texture and depth without requiring lots of embellishment.
  • Lightweight velvet: Better for cooler seasons or afternoon weddings that continue into the evening.

Think about how the fabric will feel while sitting, walking, and standing for photographs. A beautiful material is not much help if it wrinkles easily, feels restrictive, or becomes uncomfortable as the day progresses.

Image source: JJ’s House

Let the season influence your choice

The season should affect more than just the color of the dress. It can also help determine the fabric, sleeve length, and whether you need an additional layer. 

For spring, lightweight lace, chiffon, and three-quarter sleeves can provide a balance between coverage and freshness, with shades like dusty blue, sage green, blush and champagne working particularly well. Summer weddings usually call for breathable fabrics, sleeveless or short-sleeve styles, and lighter colors such as soft pink, light blue, coral, or mint. 

In autumn, crepe, jacquard, velvet accents, and richer shades like burgundy, emerald green, gold, and chocolate brown can give the outfit more depth. Winter afternoon weddings may require long sleeves, heavier fabrics, or a coordinated jacket, wrap, or elegant coat, with deep red, forest green, navy and charcoal offering a polished seasonal look. 

What should you avoid wearing to an afternoon wedding?

Choosing the right outfit is not only about finding something beautiful. A few choices may feel less suitable for the time of day or the wedding setting.

Try to avoid:

  • Extremely heavy embellishment that looks more suited to a late-night reception
  • Fabrics that are too warm for the season
  • Uncomfortable shoes that make walking across the venue difficult
  • Overly casual materials such as beachwear-style linen unless the dress code allows it
  • White or bridal-looking shades that may compete with the bride’s outfit
  • Dresses that require constant pulling, adjusting, or rearranging

The goal is to look elegant without appearing overdressed or uncomfortable. A well-fitted dress in the right fabric and color will usually make a stronger impression than a more elaborate outfit that does not suit the occasion.

Find a look that feels right for the day

For a single mother, the wedding may bring a mixture of pride, happiness, and a few emotional moments that are difficult to put into words. Choose an outfit that allows you to move comfortably, greet guests with ease, and stay present rather than worrying about your clothes. Years from now, you are likely to remember the laughter, the photographs, and the way your child looked at you—not whether your sleeves or hemline followed every traditional rule.

Starting a business as a single mom does not have to mean investing thousands of dollars or leaving your family with no financial safety net. Many businesses can begin small, use skills you already have, and grow gradually as your income increases. The key is to choose an idea that fits your schedule, budget, and personal strengths.

Explore 10 low-cost business ideas for single moms, including flexible options that can fit around family responsibilities.
Image Credit: Jonathan Borba via Unsplash

Start a small supplement brand

You do not necessarily have to manufacture supplements yourself to start a supplement business. A contract manufacturer such as Sawgrass Nutra Labs can produce supplements for your brand, allowing you to focus on product selection, marketing, and sales. For a single mom, this approach can make a product-based business more practical to explore as a side hustle without building a manufacturing facility from scratch.

A flexible business can also become a useful side hustle while you continue working another job. Wealthysinglemommy.com regularly highlights flexible ways for mothers to increase their income without giving up control of their schedules.

Here are 10 low-cost business ideas worth considering.

1. Freelance writing

If you enjoy writing, freelance content creation can be started with little more than a computer and an internet connection. Businesses need blog posts, website copy, product descriptions, newsletters, and social media content.

You can begin by offering one service instead of trying to do everything. As you build a portfolio and gain clients, you can increase your rates and turn occasional assignments into regular income.

2. Virtual assistant services

Many small businesses need help with emails, scheduling, customer support, data entry, research, and social media management.

A virtual assistant business can be particularly flexible because much of the work can be completed remotely. You can start with one or two clients and increase your workload as your schedule allows.

3. Online tutoring

If you have strong knowledge of a school subject, language, music, or another skill, tutoring can become a simple home-based business.

Online tutoring lets you choose your available hours and work with students through video platforms. You can start independently or use an established tutoring marketplace to find your first clients.

4. Reselling products online

You do not necessarily need to manufacture products to start selling them. Begin by selling unused items from your home through online marketplaces. Once you understand what sells, you can move into buying products specifically for resale.

Clothing, books, home goods, collectibles, and certain electronics can all be potential categories. Start with a small budget and carefully track your purchase costs, selling fees, shipping, and profit.

5. Handmade products

If you enjoy crafting, consider selling products such as personalized gifts, artwork, candles, accessories, or home decorations.

The advantage of starting small is that you do not need a large inventory. You can make products after receiving orders instead of spending a lot of money on items that may not sell.

Social media, local markets, and online marketplaces can help you find customers. A small handmade business can also grow through repeat buyers and referrals.

6. Cleaning or home-organization services

Cleaning and home organization are practical businesses that can be started without expensive equipment. Your initial investment may simply involve basic cleaning supplies, transportation, and simple marketing.

You could offer regular home cleaning, deep cleaning, decluttering, or organization services. The business can begin with local customers and grow through recommendations.

This type of work can also be scheduled around school hours or other family commitments, making it easier to control your working time.

7. Pet care services

If you enjoy working with animals, pet sitting, dog walking, or basic pet-care services can provide another flexible income stream.

You can start with customers in your local area and build a client base through referrals. Depending on your schedule, you could accept weekday walks, weekend visits, or occasional overnight care.

Before starting, check local requirements and make sure you understand the responsibilities involved in caring for someone else’s pet.

8. Start a small Supplement brand

A supplement business may sound expensive, but you do not necessarily have to build your own manufacturing facility. A small brand can work with an established manufacturer to develop and produce products.

For example, companies such as Sawgrass Nutra Labs provide supplement manufacturing services that can help entrepreneurs explore product-based businesses without handling the entire manufacturing process themselves.

The industry also includes areas classified under medicinal and botanical manufacturing and the broader chemical manufacturing sector.

However, this is not a business to enter casually. Product quality, labeling, regulations, testing, insurance, and customer safety all matter. A better approach is to research the market first, understand your costs, and begin with a focused product idea rather than ordering a large inventory.

9. Social media management

Small businesses often know they need social media but do not have enough time to manage it consistently. If you already understand platforms such as Instagram, Facebook, TikTok, or LinkedIn, you could turn that knowledge into a service.

You might create posts, schedule content, respond to basic comments, or prepare simple monthly content calendars.

Start with one niche, such as local restaurants, beauty businesses, coaches, or small online stores. Specializing can make it easier to explain your service and find potential customers.

10. Digital products

Digital products can be attractive because you create them once and can potentially sell them repeatedly. Examples include printable planners, budgeting templates, checklists, worksheets, simple guides, and educational resources.

Think about problems you already know how to solve. A useful product does not have to be complicated. A well-designed budget tracker or family organization planner may be more valuable to a specific audience than a large, generic product.

The initial costs can be relatively low, especially if you already have a computer and basic design software.

How to choose the right business

The cheapest business is not automatically the right one. Start by looking at three things: your skills, your available time, and your budget.

If you have very little money available, begin with a service business rather than purchasing inventory. Writing, tutoring, virtual assistance, cleaning, pet care, and social media management can often be tested before making a large investment.

If you want to sell physical products, calculate the full cost before spending money. Include materials, manufacturing, packaging, shipping, platform fees, advertising, and possible returns.

It is also worth considering how much time you can realistically give the business. A business that requires constant customer support may be difficult to manage if your schedule changes frequently. Flexible work is one reason many moms explore entrepreneurship in the first place.

Start small and track the numbers

You do not need to build a full-time company on day one. Start with a small test. Find a few customers, make a few sales, or offer your service to a limited audience.

Keep separate records of what you earn and what you spend. Your revenue is not the same as your profit. Tracking expenses will help you understand whether the business is actually worth your time.

Wealthysinglemommy.com also emphasizes practical income-building approaches rather than assuming every side hustle will become a full-time salary.

Most importantly, avoid putting essential household money into an untested business idea. Use a manageable starting budget, learn from your first customers, and reinvest only when the numbers make sense.

The bottom line

A low-cost business can give a single mom another way to earn money while maintaining greater control over her schedule. Whether you choose freelance writing, tutoring, reselling, pet care, social media management, or a product-based business, the goal is to start at a level that fits your current life.

You do not need a perfect business plan or a huge investment to begin. Start with what you know, test the idea, watch your expenses, and give yourself room to grow.

Cancelling used to be as simple as calling a number during business hours, but today many companies build obstacle courses around the exit button. Friction keeps revenue flowing, yet it costs consumers time, energy, and, in some cases, big late-payment fees. 

The Federal Trade Commission’s 2024 “Click to Cancel” proposal under the Restore Online Shoppers’ Confidence Act underscored that frustration, pointing out that one in four complaints about recurring charges involved cancellation roadblocks. A growing group of customers therefore rely on third-party tools such as SubDelete to send formal, trackable cancellation notices. For people looking for a SubDelete cancellation service, this approach can provide a more structured way to document the cancellation process.

1. Streaming video and music services

Streaming brands pioneered the ultra-easy free trial, but they also perfected the “where is the cancel link?” maze. Interface designs hide the option behind multiple secondary menus, and some companies require you to finish a multi-page survey before the cancellation button appears. Others insist that cancellations started in the mobile app be completed on a desktop site, complicating matters further.

Those design choices lead to accidental renewals, especially when a household juggles several platforms. By instructing SubDelete to generate a formal notice, you bypass UI games entirely. The service logs account details, drafts the correct language for each provider, and produces delivery evidence – exactly the sort of documentation that credit-card issuers expect if you later dispute an unwanted charge.

2. Gym and fitness club memberships

Health-club contracts are notorious for notice periods, certified-mail rules, and staff incentives to “save” departing members. Although to the Health Club Consumer Protection Act added clear language on electronic cancellation, many brick-and-mortar chains still direct customers to visit the original branch in person. Work schedules, relocations, or lingering pandemic-era hybrid lifestyles can make that requirement impossible.

SubDelete’s workflow eliminates the need to return to a location you may no longer live near. Once the user supplies membership ID, start date, and the last payment amount, the platform prepares a letter that satisfies the club’s written-notice clause and sends it via a trackable channel. Because the delivery record includes the club’s signature on receipt, members hold powerful proof should billing continue past the required thirty-day cutoff.

3. Software-as-a-service and cloud tools

Monthly licensing models for design, productivity, or developer software frequently involve tiered seats, promotional bundles, and automatic upgrades. A common scenario happens when a small business scales back: the owner downgrades seat counts, but the billing system ignores the change because one user still appears “active.” Resolving that glitch often demands opening a support ticket and navigating business-hours chat queues.

SubDelete’s database contains the exact contractual language for more than 200 major SaaS vendors, so it can reference the clause that obligates the company to end service on receipt of written notice. Users receive a PDF copy suitable for accounting records – useful when a finance team must show an auditor that the organization attempted to terminate unused software before the fiscal year closed.

4. Meal-kit and grocery delivery plans

Meal-kit brands rely on predictable weekly shipments, and their business depends on locking in as many recurring orders as possible. The fine print typically states you must cancel four to seven days before the next delivery window. Because reminders arrive by email, they can end up filtered into promotions folders, leaving customers to discover late orders and charges – only when a courier knocks.

A SubDelete cancellation triggers an immediate time-stamped request rather than waiting for a scheduled support callback. That date matters if you need to argue that a shipment sent two days later violated the vendor’s own policy. In addition, the platform’s template cites the FTC’s cooling-off provisions, reinforcing that the consumer gave timely notice. Deliveries that still arrive can then be challenged with both the carrier receipt and the policy citation in hand.

5. Add-on insurance and protection plans

Many consumers sign up for supplemental travel, device, or identity-theft policies without realizing the program auto-renews annually. The insurer often requires advance notice sent to a specific postal address, and cancellers must include policy numbers, last four digits of their Social Security number, and sometimes notarized signatures. Miss one element, and the company rejects the request as “incomplete,” effectively resetting the sixty-day clock.

SubDelete’s guided form ensures no data field is skipped. The generated notice includes all identifiers in the format accepted by the insurer, and the downloadable affidavit satisfies notary requirements in most states. Because add-on policies often appear as a line item on a credit-card statement under a brand name different from the one on marketing materials, the platform’s subscription directory is especially handy for locating the true billing entity.

6. Dating apps and premium social platforms

Dating platforms use emotional momentum to keep members paying. Some lock cancellation behind direct conversations with “relationship advisers,” which drags users into retention scripts. Others only allow cancellation on the device used for the original sign-up, leading to confusion when operating systems or app stores change.

With SubDelete, users sidestep persuasion tactics. The service cites the Electronic Fund Transfer Act’s right to withdraw authorization and simultaneously instructs the payment processor to block future charges. That dual approach – notice to the merchant and directive to the bank – closes the loophole wherein a platform claims it never received the first request. 

Final thoughts

Recurring subscriptions power everything from entertainment to essential productivity, yet ending them can still feel like navigating an escape room. Streaming platforms bury the cancel button, gyms cling to in-person forms, and insurers hide behind notarized letters. When these tactics waste your time or lead to surprise charges, a specialized service such as SubDelete offers a direct route out. 

By matching each company’s stated policy, issuing verifiable notices, and handing you airtight records, the tool relieves consumers of the administrative burden that should never have existed in the first place. For anyone tired of jumping through hoops just to stop paying, documented, third-party cancellation is no longer a luxury. It is common sense.

Turn 45, and money comparisons start showing up whether you want them or not, in retirement account apps, in year-end recaps, in headlines about what everyone else supposedly has saved. One number gets repeated more than any other: the average net worth for a household headed by someone 45 to 54 is $971,270. Read that cold, and it’s easy to think you’re the only one behind.

Look one column over on the same table and the story changes. The median net worth for that same age group, the number that actually sits in the middle of the pack rather than getting dragged upward by a handful of very wealthy households, is $246,700. That’s the number worth trusting, because it describes a real household instead of an accounting quirk.

Feeling behind at 45 is common, and for a lot of people it has more to do with which number they were shown than what they’ve actually managed to save.

What the average 45-year-old is actually worth

45 year old
Image Credit: Shutterstock

Net worth is everything you own minus everything you owe. A house minus the mortgage, retirement accounts, cash, and a car, minus credit card balances, student loans, and other debt. This comes from a large government survey of household finances that runs every three years, and the most recent full round was conducted in 2022 and released the following year. A new round is already underway, with results expected by late 2026, so these are still the freshest official numbers available.

The average and the median tell different stories on purpose. Average net worth adds up every dollar in the age group and divides by the number of households, so a small number of households worth eight or nine figures pull that number sky-high. Median net worth lines every household up from poorest to richest and picks the one standing exactly in the middle. For households 35 to 44, that median is $135,300. By 55 to 64, it climbs to $364,270. A net worth well under a million dollars at 45 isn’t a warning sign. It’s the middle of the pack.

How much money is really sitting in a 401(k) at 45

401K
Image Credit: Shutterstock

Net worth folds in home equity, cars, and other assets. Retirement accounts alone tell a narrower story, and the most detailed annual data on that comes from an industry report tracking 4.6 million retirement plan accounts. For workers 45 to 54, the average 401(k) balance is $214,991. The median for the same group is $78,730, less than half the average.

The same distortion shows up across every age group tracked in that data. The overall average 401(k) balance across all participants is $167,970, a figure that sits close to the 75th percentile, meaning roughly three out of four savers have less than that in their account. A 401(k) balance well below six figures at 45 puts someone closer to the typical saver than the exception, especially once you remember this number only counts what’s inside a workplace plan. It leaves out IRAs, pensions, home equity, and Social Security entirely.

What financial planners say you should have banked by now

talking to financial planner
Image Credit: Shutterstock

One of the most cited sets of retirement savings milestones is built around saving 15% of income every year starting at 25 and retiring at 67. The milestones are three times your salary by 40, six times by 50, eight times by 60, and ten times by the time you retire. Forty-five doesn’t get its own checkpoint. It falls in the climb between the 40 and 50 milestones, which puts a realistic target for most 45-year-olds somewhere around four to four and a half times their salary, not the full six.

These milestones assume a specific and fairly demanding path: saving continuously for two decades, investing more than half of that money in stocks the whole time, and never taking a break from contributing. Job changes, kids, a layoff, or a few lean years throw that path off for almost everyone. The milestones are explicitly framed as aspirational rather than mandatory, which is a useful thing to remember before treating a missed one as a verdict on your finances.

How to close the distance if you’re behind

saving in 401K
Image Credit: Shutterstock

The first move costs nothing extra: contribute enough to get a full employer match if one is offered. Turning down free money is the single most common way people leave retirement savings on the table.

After that, the contribution limits themselves got more generous for 2026. Workers under 50 can put $24,500 into a 401(k) this year. At 45, that catch-up window is still five years away, since it opens at 50, when workers can add a catch-up contribution of $8,000 on top of the regular limit for a total of $32,500. Workers 60 through 63 get an even larger catch-up, bringing their total to $35,750. Anyone without a workplace plan, or who wants to save past it, can put up to $7,500 into an IRA in 2026, plus a $1,100 catch-up once they turn 50.

Short of those limits, the moves that actually shift the numbers are less exciting: raising the contribution rate by a percentage point or two a year instead of waiting for a raise to feel big enough, and rolling old 401(k)s from past employers into one account to stop losing money to duplicate fees. None of it happens in a single afternoon.

Discover how long-term financial planning can help you build savings, manage expenses, and prepare for a more secure financial future.

Financial security rarely comes from a single investment decision or a short-term savings target. It usually results from coordinated decisions made over many years.

Long-range financial planning connects current finances with future objectives such as building wealth, preparing for wealth, managing investment risk, protecting investment risk and assets, planning for major expenses, creating financial flexibility, and preparing for business ownership or succession.

What is long-range financial planning?

Long-range financial planning involves looking beyond the next few months or years and creating a financial strategy designed around longer-term objectives.

A long-range plan may bring together:

  • Income and cash flow
  • Savings
  • Investments
  • Retirement accounts
  • Insurance and risk management
  • Taxes
  • Estate considerations
  • Business interests
  • Major future expenses

Certified Financial Planner Board of Standards, Inc. states that financial planning covers areas including investment planning, retirement savings and income planning, tax and estate planning, and risk management.

A coordinated approach to financial planning can help ensure that individual financial decisions support broader long-term objectives.

Start With Clear Financial Goals

Planning should begin with goals rather than investments.

Three types of financial goals are:

Short-term goals

Examples:

  • Emergency savings
  • Debt reduction
  • Major purchases

Medium-term goals

Examples:

  • Buying property
  • Funding education
  • Starting a business

Long-term goals

Examples:

  • Financial independence
  • Retirement
  • Legacy planning
  • Business succession

Goals should be specific enough to measure and revisit.

Financial priorities change as income, family circumstances, markets, and business conditions evolve.

Build a complete picture of your current finances

Effective planning requires an accurate starting point.

Start with having a complete picture of current finances:

  • Current income
  • Monthly expenses
  • Cash reserves
  • Debt
  • Investment accounts
  • Retirement assets
  • Insurance coverage
  • Real estate
  • Business interests
  • Expected future income

Comprehensive financial planning looks at how different parts of a financial life interact rather than treating investments, taxes, retirement, and insurance as completely separate decisions.

Create an investment strategy for the long term

Long-range planning should include an investment strategy aligned with:

  • Time horizon
  • Financial goals
  • Risk tolerance
  • Liquidity requirements
  • Diversification
  • Changing life circumstances

The importance of reviewing asset allocation as goals and time horizons change. Investor.gov notes that asset allocation may need to change as investors approach their goals or as their risk tolerance and financial circumstances change.

Avoid short-term reactions to market volatility when the underlying financial plan has a much longer horizon.

Make retirement planning part of the strategy

Retirement planning should consider more than simply accumulating a target balance.

Consider:

  • Desired retirement lifestyle
  • Expected retirement age
  • Retirement savings
  • Investment growth
  • Social Security or pension income
  • Healthcare expenses
  • Inflation
  • Longevity
  • Withdrawal strategy

Effective retirement planning considers both how much wealth needs to be accumulated and how those assets may eventually be converted into sustainable income.

Plan for retirement income, not just retirement savings

Retirement savings:
How much has been accumulated.

Retirement income planning:
How assets and other income sources may be used to fund expenses throughout retirement.

Also, potential considerations such as:

  • Timing of withdrawals
  • Income needs
  • Portfolio allocation
  • Taxes
  • Longevity risk
  • Market volatility
  • Required distributions

Retirement income planning can help turn accumulated assets into a strategy for meeting ongoing expenses during retirement.

Connect personal wealth with a long-term business plan

For business owners, personal wealth and business finances can be interconnected. So, it’s important to look into the following:

  • Business cash flow
  • Reinvestment
  • Owner compensation
  • Business valuation
  • Succession planning
  • Exit strategies
  • Tax considerations
  • Personal retirement objectives

The SBA describes a business plan as a roadmap for structuring, managing, and growing a company, and recommends financial projections as part of a comprehensive business plan.

A long term business plan should not exist in isolation from the owner’s personal financial objectives.

Protect the plan against financial risks

Accumulating wealth is only one side of financial security.

Potential risks include:

  • Unexpected expenses
  • Loss of income
  • Market downturns
  • Healthcare costs
  • Disability
  • Premature death
  • Liability
  • Business disruption

There is a need to have appropriate insurance, emergency reserves, diversification, and contingency planning.

Review and update the plan regularly

A financial plan should not be treated as a document created once and then forgotten.

Reviews may be appropriate when there are major changes involving:

  • Income
  • Marriage or divorce
  • Children
  • Career
  • Business ownership
  • Retirement timing
  • Investment objectives
  • Tax circumstances
  • Major purchases

Conclusion — Turn long-term goals into a financial strategy

Long-range financial planning is about creating a connected strategy rather than making isolated financial decisions.

So, it is important to:

  1. Define financial goals.
  2. Understand your current position.
  3. Build an investment strategy.
  4. Prepare for retirement.
  5. Develop a retirement income strategy.
  6. Coordinate business and personal objectives.
  7. Protect against financial risks.
  8. Review the strategy as circumstances change.

Do explore how professional guidance can help bring different parts of their financial life together.