Hosting an annual corporate gala requires an atmosphere that reflects prestige and professional standards. Events fall short when presentations rely on cheap plastic trophies that feel disposable. Honourees invest months of effort into their roles, and their physical awards should reflect that level of dedication.
Presenting substantial crystal-clear accolades commands attention, setting a dignified standard across the room. Check out this guide to see how contemporary glass designs transform your formal corporate event into a premier celebration.
Clear materials catch venue spotlights, creating visual appeal when presenters hand awards to recipients on stage. Ordering pieces through glass awards suppliers ensures you receive heavyweight glass with hand-finished bevelled facets. The clarity of crystal glass awards shows guests that leadership takes employee appreciation seriously.
A substantial glass trophy feels significant in an honouree’s hands, matching the scale of their business milestone. Attendees associate clean glass geometry with modern design, transparent leadership, and corporate success. This positive impression extends to business partners, clients, and industry stakeholders attending the presentation dinner.
2. Delivers clean precision laser engraving
Glass surfaces provide an ideal medium for crisp laser engraving and detailed sandblasting methods. Unlike stamped metals, laser-etched glass retains its legibility permanently without tarnishing, peeling, or fading over time.
Precision engraving techniques produce these distinct decorative features:
Crisp Typography: Fine laser lines keep small script fonts and date stamps easy to read
Detailed Emblems: Multi-depth sandblasting captures fine details of official corporate logos and crests
Frosted Text Contrast: Opaque frosted etching stands out clearly against polished crystal backgrounds
Metallic Colour Fills: Gold, silver, or corporate Pantone fills add striking colour accents to the glass
Corporate awards sit on office display shelves, conference tables, or executive desks for years. Bulky wooden trophies or traditional metal cups often clash with modern office architecture. Clean glass geometry blends into contemporary professional settings, serving as a tasteful decorative piece.
Recipients display transparent glass awards without cluttering their desks with outdated trophy designs. Natural daylight catches the polished edges, drawing attention from visiting clients and colleagues. The award remains a professional talking point that highlights company capability and personal success.
4. Accommodates diverse recognition categories
Glass suits varied geometric shapes and sizes, from clean rectangular towers to flame shapes. This flexibility allows event organisers to create a clear hierarchy of achievement across award tiers.
Consider these popular glass profiles to distinguish your annual gala categories:
Faceted Star Shapes: Star profiles reward rising talent and creative workplace innovators
A formal awards gala offers a prime opportunity to produce compelling social media content for employer branding. Polished glass awards reflect stage lighting, creating striking photographs when honourees pose with executives. Staff members share these high-definition celebration images across professional platforms like LinkedIn.
Organic social shares highlight your company culture to industry peers, potential clients, and job applicants. Seeing real employees celebrated with high-calibre awards positions your business as an employer of choice. This external visibility reinforces internal pride while boosting your corporate reputation across your sector.
Celebrate executive achievement in style
A successful awards gala should leave your workforce unified and proud of their daily contributions. Upgrading from cheap materials to heavy cut glass awards turns routine ceremonies into unforgettable milestones. Your top performers receive a tangible symbol of achievement that honours their dedication with genuine elegance.
Set a high standard for your company’s formal presentations by choosing tailored crystal glass pieces. Rewarding success with quality materials shows your organisation values excellence across all its operations.
If you are 65 and a coworker tells you the average Social Security check is more than $2,000 a month, you can stop worrying when yours comes in lower. The national average for retired workers is $2,088.79 a month, but that number blends everyone from 62-year-olds to people well past 90, so it says very little about what a 65-year-old actually receives.
For retired workers who are exactly 65, the latest published average is $1,607.27 a month. Men at that age average $1,772.00 and women average $1,457.40, which means even the single figure for 65-year-olds blends two quite different groups.
Among retired workers aged 65 to 69, about 12% receive less than $1,000 a month while 8.4% receive $3,300 or more, so two people the same age can be separated by well over $2,000 every month.
What the $1,607 average covers and what it leaves out
Image Credit: Shutterstock
That $1,607.27 describes retired workers, meaning people who collect Social Security on their own work records. It leaves out spouses who collect on a partner’s record, who average $771.38 a month at 65, and it leaves out survivors. Disabled workers are counted separately too, and the average at 65 for that group is $1,802.90.
The figure also counts only people who have already filed. Someone who is 65 and plans to wait until 67 or 70 is not in the number yet, which is one reason the averages climb to $1,807.28 at 66, $2,016.48 at 67 and $2,274.68 at 70 as more of the people who waited join the rolls.
The age-specific figures all come from December 2025, so none of them include the 2.8% cost-of-living increase that took effect in January 2026 or the 3.6% increase arriving in January 2027. A $1,607 check would be about $1,652 after the first of those increases.
Why people the same age get such different checks
Image Credit: Shutterstock
Social Security starts with your highest 35 years of earnings, adjusts the older years upward to reflect wage growth, and averages the result into a monthly figure. Anyone with fewer than 35 years of work gets zeros filled in for the missing years, which pulls the average down. A person who spent a decade out of the workforce raising kids or caring for a parent can end up with a smaller check than a coworker who earned the same salary for longer.
The formula then applies three different percentages to three slices of that average, so a worker who earned half as much over a career does not receive half as much in benefits, although the higher earner still collects the larger check.
The second big factor is the age you start. About 61.3% of retired workers had their checks permanently reduced for claiming before full retirement age, which is 67 for anyone born in 1960 or later. Those retirees average $1,790.63 a month compared with $2,515.93 for retirees whose checks were not reduced. The two groups also differ in how much they earned, so claiming age explains only part of the difference, but together timing and work history can move a check by hundreds of dollars a month.
What claiming at 65 does to your monthly amount
Image Credit: Shutterstock
With a full retirement age of 67, a claim at 65 is two years early, and each of those 24 months costs 5/9 of 1% of the benefit, which leaves the check permanently about 13% smaller than it would have been at 67. A worker whose benefit at 67 would be $2,000 receives roughly $1,733 by claiming at 65, compared with $1,400 at 62, where the reduction is 30%.
Waiting works the other way, because each year of delay past full retirement age adds 8% until you turn 70, which would lift the same $2,000 benefit to $2,480.
Working while collecting adds a wrinkle for anyone who claims before 67. In 2026, $1 is withheld for every $2 earned above $24,480, and the limit rises to $25,560 in 2027. The withheld money is not lost, because the benefit is recalculated at full retirement age to credit those months back.
Medicare at 65 and the premium that comes out first
Image Credit: Shutterstock
Medicare opens at 65 whether or not you have claimed Social Security. People who started collecting at least four months before turning 65 are enrolled automatically, and everyone else signs up during a seven-month window that opens three months before the month of the 65th birthday. Even people who delay their retirement checks should apply for Medicare within three months of turning 65.
Workers who are still covered by an employer plan can delay Part B, and they generally avoid a penalty if they qualify for a Special Enrollment Period. Everyone else who misses the window pays an extra 10% for each year they could have signed up for Part B, and for most people that penalty lasts as long as they have the coverage.
The standard Part B premium is $202.90 a month in 2026, and for people who collect Social Security it is usually deducted straight from the payment. The premium is projected to top $209 a month in 2027.
How much of the check actually lands in your account
Image Credit: Shutterstock
Every average in this article is a gross figure, meaning the amount before deductions. The SSA-1099 tax form that arrives each January shows benefits with Medicare premiums added back in, so the deposit in your account is lower than the benefit on paper.
Take the $1,607 average at 65 and add the 2.8% increase from January 2026, which brings it to about $1,652. Subtract the $202.90 Part B premium and the deposit comes to about $1,449, before any tax is withheld. That is the number rent and groceries actually get paid from, so it is worth working out before you pick a claiming date rather than after the first deposit lands.
Income tax can take more. If half of your benefits plus your other income is more than $25,000 for a single filer or $32,000 for a married couple filing jointly, part of the benefit becomes taxable, and above $34,000 or $44,000 up to 85% of it can be. Federal tax is not withheld automatically, and Form W-4V lets you choose to have 7%, 10%, 12% or 22% of each payment withheld.
What changes at 70
Image Credit: Shutterstock
Delayed retirement credits stop when you reach 70, so a check does not grow from waiting past that birthday, and anyone who has not filed by then earns no extra credit for holding off longer. The credits do add up before that point, since retirees aged 70 who earned them average $3,156.59 a month compared with $2,654.85 without the credits, a difference of roughly $500.
That is part of the reason age 70 shows the highest average of any single age, at $2,274.68. After 70 the check changes through cost-of-living increases and through a yearly review of work records, because Social Security checks whether new earnings raise your monthly benefit. A 70-year-old who is still working has no earnings limit, since the limit does not apply once you reach full retirement age.
Anyone who reaches 70 without having filed gains nothing by holding off another month, and every month of waiting after that is a month of payments given up for no increase. That makes 70 the point where the claiming question is finally settled, and the only decisions left are which spousal or survivor options apply and how Medicare premiums fit around the check.
Cost-of-living increases and work at 75 and 80
Image Credit: Shutterstock
At 75 the average retired worker receives $2,144.88 a month and at 80 the figure is $2,106.29, both lower than at 70. The averages slide mostly because newer retirees start from a higher base, since their earnings are adjusted for wage growth, while people who retired years ago have mostly kept pace through cost-of-living increases alone.
Those increases arrive in uneven amounts, from 8.7% in 2023 to 3.2% in 2024, 2.5% in 2025, 2.8% in 2026 and 3.6% in 2027. The 2027 increase will add about $75 a month to the average retirement benefit, and because every check rises by the same percentage, the dollar increase is larger for a person with a bigger benefit.
Working at 75 or 80 carries no earnings limit, and because of the yearly review of earnings, a recent year of wages that beats one of your old 35 best years can raise the check. Part-time pay in your late seventies rarely changes the amount much, but it costs nothing to let the review run.
Survivor benefits when a spouse has died
Image Credit: Shutterstock
A widow or widower can claim survivor benefits as early as 60, and the payment starts at 71.5% of the late spouse’s benefit, rises to over 90% at age 65 and reaches 100% at the full retirement age for survivors, which falls between 66 and 67. The average nondisabled widow or widower receives $1,935.32 a month.
Someone who qualifies for both a survivor benefit and a retirement benefit does not receive the two added together and instead chooses the one that pays more. The choice can be changed later, so a person might start with survivor benefits and switch to retirement benefits at 70 when that amount is highest. For widowed readers who are 75 or 80, the first thing to confirm is that the check being paid is the larger of the two.
The survivor average covers widows and widowers of every age, so an individual amount depends on what the late spouse was receiving or was entitled to, and on how old the survivor was at claiming. Someone who took the reduced early amount years ago and has a retirement record worth more should find out whether switching would raise the monthly payment.
How to check your own number
Image Credit: Shutterstock
A my Social Security account takes a Login.gov sign-in, a photo ID and a phone number, and once it is set up you can review your earnings history and estimate benefits at different ages.
The earnings record deserves the first look, because each year listed there should match what you actually earned. A missing or understated year can pull your average down, and the most recent year or two may not have posted yet. Then look at the estimates for 62, full retirement age and 70, which show how your own claiming age changes the amount.
Comparing your number with the $1,607.27 average is easier once you know which factors apply to you. A smaller check usually traces back to fewer than 35 working years, lower pay or a claim made before 67, and a larger one tends to come from long careers at higher pay or from waiting past full retirement age.
A 35-year-old who checks their credit score and sees 689 is sitting right on the average for Millennials, the generation group that covers ages 29 to 44. The national average is 713, and 689 lands in the “good” range of 670 to 739 on the FICO scale.
Credit scores are not reported by exact age. The figures come in generation groups, so 689 is an average for everyone from 29 to 44, and a 30-year-old and a 43-year-old are counted together. Gen X, the next group up at ages 45 to 60, averages 709, and the numbers reflect a snapshot taken in September 2025.
A score also says nothing about how much money someone has. Income, savings and checking balances, and investments are not part of a credit report, so a 689 can belong to someone with a healthy emergency fund or someone with none.
Each generation group has its own average. Gen Z, ages 18 to 28, averages 678, Millennials average 689, Gen X averages 709, baby boomers aged 61 to 79 average 747, and the Silent Generation, 80 and older, averages 760. Anyone in their 70s falls inside the baby boomer group, which means the number for that decade is blended with people in their early 60s.
The averages moved only slightly in the past year. Gen Z slipped from 681 to 678 and Millennials from 691 to 689, while Gen X stayed at 709 and boomers rose a point. Lines between groups also shift depending on who is counting, since another recent report places Millennials at ages 30 to 45.
None of the five categories that make up a FICO score is age. Older groups likely score higher because they have had more years to build long histories and pay down balances, which is a different thing from being older.
Why a credit score is not a wealth measure
Image Credit: Shutterstock
A credit report lists accounts, balances owed, payment history, collections, bankruptcies, and who has requested the report. It leaves out income, bank balances, and investments, and since income is not part of your credit report, it is never a factor in calculating your credit scores. Someone earning a high salary can have a mediocre score because of late payments, and someone living on a modest income can have an excellent one after years of paying every bill on time.
What the number measures is how reliably borrowed money has been repaid and how much of the available credit is in use. Lenders use credit reports to decide whether to lend and what interest rate to offer, which is the job a score does. It says nothing about retirement savings, an emergency fund, or whether the monthly budget works, so a 760 is not proof that someone is financially secure and a 650 is not proof that they are not.
Payment history and balances do most of the work
Image Credit: Shutterstock
Payment history makes up 35% of a FICO score and amounts owed make up 30%, which puts nearly two-thirds of the score in those two categories. A few late payments are not an automatic score-killer, though a late payment stays on credit reports for seven years. A recent report found that about 3.2 million consumers with a recent student loan delinquency saw an average 38-point drop, while consistent payers gained 6 points.
Balances are measured as a utilization ratio, which divides what is owed on credit cards by the credit limits. A ratio under 10% is generally best, 30% is a common target but not a hard cutoff, and the average was 28.3% in March 2026. Issuers usually report the balance near the end of the statement period, so a card paid in full on the due date can still show a high ratio if the balance was large when the statement closed.
Account age, new applications and credit mix
Image Credit: Shutterstock
The length of credit history is 15% of a FICO score, and a longer history is a plus, though a good score does not require one. New credit counts for 10%, and opening several new accounts in a short period represents greater risk. FICO scores only consider inquiries from the last 12 months, even though a hard inquiry stays on a report for two years.
Shopping for one loan is treated differently from applying for many cards. Older versions of FICO allow a 14-day span for rate shopping, and newer versions allow 45 days, with the inquiries for a mortgage, auto loan, or student loan counted as one. Credit mix, meaning the types of accounts someone holds, is the last 10%, and it is not necessary to have one of each. Because a good score does not require a long history or a perfect mix, a person with a handful of well-managed accounts can still score well. Rate-shopping inquiries less than 30 days old are ignored when the score is calculated, which leaves time to compare offers.
What matters at 35 with a mortgage, a car loan and other debt
Image Credit: Shutterstock
People around 35 often carry a mortgage, a car payment, student loans, and a couple of credit cards at once, and each one reports to the bureaus every month. Since payment history is the biggest category, setting every loan to autopay for at least the minimum is the most effective single habit, student loans included given the 38-point drops among borrowers who fell behind.
Large loans call for a different approach to shopping. Gathering quotes for a mortgage or car loan within a short window, ideally 14 days since some lenders still use older scoring versions, keeps the inquiries from piling up. Opening a store card for a one-time discount in the weeks before applying for a mortgage adds an inquiry and a new account at exactly the wrong time. Utilization is calculated from revolving balances, so keeping credit card balances low matters even when the mortgage and car loan are still large.
Why a long history helps but does not protect anyone
Image Credit: Shutterstock
Older borrowers get a real advantage from the 15% that goes to the length of credit history, but payment history and amounts owed count for much more. One stretch of missed payments, a maxed-out card, or a bankruptcy can undo years of progress, since a Chapter 7 bankruptcy stays on reports for 10 years. Late payments and collections each stay for seven years from the original delinquency, so a rough patch at 40 can still be showing at 47.
Closing accounts is another way to lose ground. FICO scores still count historically missed payments reported on a closed account, and closing a card removes its limit from the total, which can push utilization up. Identity theft can damage a score without any mistake by the account holder, because a thief can open accounts in someone’s name and leave them unpaid. A credit freeze is free, does not affect the score, and keeps anyone from opening a new credit account in your name.
When the mortgage is paid off and the cards sit in a drawer
Image Credit: Shutterstock
Paying off a mortgage ends the monthly payment, but the account does not vanish from the report. Closed accounts in good standing stay on credit reports for 10 years after the payoff date, and they keep contributing to the length of history in the meantime. After that, the oldest accounts that remain open carry the history, which makes the oldest card the one most worth keeping. A person whose only long-running accounts were a mortgage and a card that was later closed could have little left to show once those 10 years pass.
Issuers are allowed to close unused cards. Card issuers can close inactive accounts with no warning, and there is no industry-wide policy on when a card counts as inactive. In one example, a closed card pushed utilization from 26% to 37.5%. A small purchase every few months paid off in full keeps the account active, and a missed payment on that card would cause more damage than closing it would have.
Why credit still matters at 70 and beyond
Image Credit: Shutterstock
Averages for people in their 70s and 80s are high, at 747 for boomers and 760 for the Silent Generation, but the score keeps doing work after the last big loan is gone. Insurance is one example, since an estimated 95% of auto insurers and 85% of homeowners insurers use credit-based insurance scores in states where the practice is allowed, and in most states insurers cannot use the score as the sole reason to raise rates.
Housing is another, because landlords and utility providers may check credit reports, which matters for someone who sells a house and rents. A roof replacement, a car that dies, or a medical bill that needs financing can show up at any age, and lenders use the same reports to set terms. Fraud is the third reason. A freeze lasts until it is lifted, and an extended fraud alert, available after identity theft, lasts seven years.
How to check your credit reports
Image Credit: Shutterstock
AnnualCreditReport.com is the only website authorized to fill free credit report orders, and the bureaus have permanently extended a program that allows a free report from each one once a week. Equifax, Experian, and TransUnion are separate files, and creditors are not required to report to every credit reporting company, so the three reports can differ. Online orders are available immediately, while phone and mail orders are processed within 15 days, and imitation sites exist, so the address is worth typing in directly.
Each report is worth reading line by line. The pieces to check are the names and addresses, every account and its balance, limit, and status, the payment history on each, any collections, and the list of companies that have accessed the report. An account that was never opened, a payment marked late that was paid on time, or an address where the person never lived are all worth a dispute.
How to dispute an error
Image Credit: Shutterstock
A dispute goes to each bureau that has the mistake, and a copy of the same dispute goes to the business that reported it. The bureau has 30 days to investigate, whether the dispute was filed online, by phone, or by mail. A mailed letter should include a full name and address, each error and why it is wrong, copies, not originals, of supporting documents, and a copy of the report with the errors circled, sent by certified mail with a return receipt.
The bureau forwards the evidence to the business that reported the information, and the results come back in writing. When the report changes, there is a free copy that does not count as the free annual report. If the dispute is not resolved, a statement of the dispute can be added to the file, and a follow-up check confirms that the error was removed or that a dispute notice appears.
How to raise a score without taking on new debt
Image Credit: Shutterstock
The cheapest improvements involve accounts that already exist. Paying every bill on time covers the 35% category, and paying credit card balances down before the statement closes lowers the ratio that gets reported, with under 10% generally best. Keeping old cards open protects the age of the history, and a small recurring charge paid in full each month keeps them from being closed for inactivity.
Experian Boost is a free way to add on-time payments such as phone, utilities, and streaming to an Experian credit report, and late payments are ignored, so they cannot hurt the score. Users whose scores improve see an average increase of 13 points, though it is not guaranteed and only lenders that use that Experian data will see it. Skipping applications for accounts that are not needed avoids inquiries, and a dispute that removes a wrong late payment or collection can do more than any other step here.
Separation changes more than your relationship status. It can affect your home, income, savings, debts, retirement plans and the financial arrangements you have relied on for years. If children are involved, decisions about parenting time and support add another layer of complexity.
The decisions made during the early stages of separation can influence your financial position long after the divorce is finalized. Moving out, closing a joint account or agreeing to cover certain expenses may seem like straightforward steps, but each can have legal and financial consequences.
A little preparation can help you avoid unnecessary disputes, keep important records within reach and approach negotiations with a clearer picture of your financial position.
If you are preparing to separate in Alberta, here are the financial and legal matters worth addressing before making major decisions.
Before discussing property division or support payments, establish what you and your spouse own, owe and earn. You cannot make informed decisions about a settlement without knowing the full financial picture.
Start by collecting copies of:
Recent bank statements for individual and joint accounts.
Three years of personal and business tax returns, if applicable.
Recent pay stubs, employment contracts and records of other income.
Mortgage statements and property tax assessments.
Investment, RRSP, TFSA and pension statements.
Credit card statements, personal loans and lines of credit.
Vehicle ownership documents and outstanding auto loans.
Life, home, disability and health insurance policies.
Records of significant purchases, inheritances or gifts.
Make digital copies and store them somewhere secure that you can access independently. If you have difficulty obtaining certain records, make a note of what is missing and discuss your options with MM Family & Divorce Lawyers, who can help you understand what financial information may be needed during property division.
Pay particular attention to assets and debts that are easy to overlook. Business interests, cryptocurrency, private investments, outstanding tax obligations and loans between family members can all affect the financial picture. An incomplete inventory can create problems during property division.
2. Understand what happens to your property and debts
A common misconception is that everything acquired during marriage is automatically divided equally, or that everything in one person’s name belongs exclusively to them.
Alberta’s Family Property Act governs property division for married spouses, while different rules can apply to unmarried partners. Courts generally start from the principle of an equitable division of family property, but the circumstances of the relationship and the nature of particular assets can affect the outcome.
Before agreeing to a division, identify:
The family home and any additional real estate.
Savings and investment accounts.
Registered retirement savings and pension entitlements.
Vehicles, recreational equipment and valuable personal property.
Business ownership and professional interests.
Mortgages, credit cards, loans and tax liabilities.
Also distinguish between the current value of an asset and the amount of equity you actually own. For example, a home valued at $650,000 with a $400,000 outstanding mortgage has approximately $250,000 in equity before selling costs and other adjustments.
If one spouse intends to keep the property, consider the cost of refinancing, ongoing maintenance, property taxes and insurance. Keeping the family home may sound like the simplest arrangement, but the mortgage payments could become difficult to manage on a single income.
Avoid transferring, selling or giving away significant assets before receiving legal advice. A decision made in haste can complicate negotiations and potentially affect your property claim.
3. Review joint accounts, credit and outstanding debts
Joint financial arrangements can become a source of conflict shortly after separation. Both account holders may have access to shared funds and credit facilities, and missed payments can affect your financial standing.
Start by reviewing every account, credit card and loan connected to both of you. Pay particular attention to joint bank accounts, as both holders may be able to withdraw funds and make transactions. The Financial Consumer Agency of Canada’s guide to joint bank accounts explains how shared account access works and what account holders should know about their responsibilities.
Consider taking these steps:
Open an individual bank account if you do not already have one.
Review automatic payments and identify which household expenses they cover.
Check outstanding balances on joint credit cards and lines of credit.
Monitor your credit report for unfamiliar transactions or changes.
Discuss how shared bills and debt payments will be handled during the transition.
Do not automatically empty joint accounts or stop paying shared obligations without understanding the consequences. Closing accounts may also require both account holders’ consent or agreement from the financial institution.
Remember that separating your finances does not automatically release you from joint debt. If both names appear on a mortgage or loan, the lender may continue to hold both borrowers responsible until the debt is refinanced, paid off or otherwise formally changed.
4. Calculate your post-separation budget
Your household finances will probably look different once you are living separately. Expenses that were previously shared may become individual responsibilities, and some costs may increase simply because you are maintaining two households.
Build a realistic monthly budget before deciding what financial arrangements you can accept.
Include:
Expense
What to account for
Housing
Rent or mortgage, property taxes, utilities and maintenance
Transportation
Vehicle payments, fuel, insurance and repairs
Household costs
Groceries, clothing and everyday essentials
Children
Childcare, school expenses, activities and medical costs
Debt
Credit cards, loans and other monthly repayments
Savings
Emergency funds and retirement contributions
Calculate your income after taxes and compare it with your expected expenses. Leave room for irregular costs such as vehicle repairs, legal fees and annual insurance payments.
This exercise can also help you assess potential support arrangements. An agreement that looks reasonable on paper may be difficult to maintain once your actual living costs are accounted for.
5. Account for child and spousal support
If you have children, child support will likely form an important part of your financial arrangements. In Canada, child support is generally calculated using the Federal Child Support Guidelines, with the amount influenced by factors such as parental income, the number of children and the parenting arrangement.
Shared parenting does not automatically mean neither parent pays support. The applicable calculation can account for both parents’ incomes and the additional costs associated with shared parenting.
Spousal support is assessed separately. Factors may include the length of the relationship, each person’s financial circumstances, roles during the marriage and the economic consequences of separation.
Before entering negotiations, gather:
Recent income documentation for both spouses, where available.
Records of childcare and special expenses.
Information about existing support obligations.
Details of any significant income changes.
A realistic estimate of your monthly living expenses.
Do not rely on informal promises about future payments. Have support arrangements reviewed and properly documented so the amount, payment schedule and responsibility for additional expenses are clear.
6. Review insurance, beneficiaries and tax obligations
Some financial details are easy to overlook during separation because they do not require immediate attention. However, leaving outdated arrangements in place can create complications later.
Review the following:
Life insurance: Check existing policies, coverage amounts and beneficiary designations. Some policies may be subject to existing court orders or support obligations, so obtain legal advice before making changes.
Health and dental insurance: Find out how long coverage through your spouse’s employer will continue and investigate alternative options.
Retirement accounts: Review pension entitlements, RRSPs and other registered investments as part of the property division process.
Wills and estate documents: Review your will, powers of attorney and personal directives with a lawyer.
Tax obligations: Ask an accountant about the tax treatment of property transfers, investments and support payments.
In Canada, child support is generally neither taxable income for the recipient nor tax-deductible for the payer. Spousal support payments made under qualifying arrangements are generally taxable for the recipient and deductible for the payer. The distinction can affect your monthly budget, so account for it before agreeing to support terms.
7. Get legal advice before signing a separation Agreement
Once you have gathered your financial information, assessed your expenses and considered your priorities, you can begin working toward a formal separation agreement.
In Alberta, a separation agreement can address:
Division of property and debts.
Responsibility for the family home and mortgage.
Child and spousal support.
Parenting schedules and decision-making responsibilities.
Division of pensions and other financial assets.
Responsibility for ongoing household and child-related expenses.
You and your spouse can negotiate an agreement privately, through lawyers or with the assistance of a mediator. However, both parties should receive independent legal advice before signing.
A lawyer can also identify provisions that may create problems later, such as unclear payment terms, incomplete property disclosure or arrangements that do not account for future expenses.
Do not rush into signing an agreement simply to bring the separation to an end. Once signed, a separation agreement can have significant legal consequences, and challenging it later may be difficult.
Give yourself time to make informed decisions
Financial preparation before separation is about knowing your position before making commitments that could affect your future. Having complete financial records, a realistic budget and a clear picture of your legal obligations can make negotiations more productive and help prevent avoidable disputes.
You do not need to resolve every issue before separating. However, you should understand the financial consequences of major decisions before agreeing to them, particularly those involving property, debt, support and parenting arrangements.
If you are considering separation in Alberta, speaking with an experienced family lawyer early can help you identify potential risks, understand your rights and work toward an agreement that reflects your circumstances.
Your phone lights up with a trade-in offer the morning a new model launches, and for about ten seconds the number looks almost too good to pass up. It isn’t. An iPhone 15 lost roughly 48 percent of its resale value within a year of release, and a Samsung Galaxy S22 lost closer to 68 percent in that same stretch.
Most people have already caught on to this. Nearly nine in ten Americans say phones are priced too high, and the average person is now holding onto one for well over three years instead of trading up every time a new box shows up on shelves.
Trading in every single year means eating the steepest part of the depreciation curve on repeat. An iPhone 15 lost 48 percent of its resale value within a year of release, and a Samsung Galaxy S22 lost closer to 68 percent in that same stretch. Apple’s lineup tends to hold value better than Android flagships as a whole, with first-year depreciation across the brand averaging around 41 percent, against roughly 64 percent for Samsung and 69 percent for OnePlus, but none of those numbers reward anyone selling every twelve months.
Real-world habits back this up. The average phone upgrade cycle is now longer than 42 months, and a recent poll of flagship owners found that barely one in ten people upgrade annually, while more than half hang onto a phone for two to three years or longer.
None of this means a new phone is a bad purchase. It means skipping a cycle or two and buying a model that’s already a generation old saves more money than most people assume. A budget option like the Pixel 10a costs $500 and does almost everything its pricier sibling does for a fraction of the price.
The latest smartwatch the day it drops
Image Credit: Shutterstock
Smartwatches depreciate on the same schedule as phones, just with less fanfare. Garmin’s older models get discounted hard once a new generation ships: the Forerunner 265 dropped from $450 to around $300, the Instinct 2 Solar fell from $400 to roughly $224, a 44 percent cut, and the Venu Sq 2 slid from $300 to about $180.
The feature difference between generations is usually smaller than the marketing suggests. Samsung’s Galaxy Watch 7 launched with the same battery capacity and the same price as the Watch 6, with most of the advertised improvement coming from chip efficiency and software extras rather than new hardware.
Buying one generation behind gets you nearly the same watch for a quarter to half off, and the battery complaint that actually drives most upgrades usually has more to do with age and battery wear than with which model year you own. A well-maintained two-year-old smartwatch still tracks a run just as accurately as a brand-new one.
A 4K or 8K TV to replace one that still works
Image Credit: Costco
An 8K television sounds like the obvious next step until you notice there’s almost nothing to watch in 8K. Samsung is now the only major manufacturer still making new 8K sets, its flagship 65-inch model runs $5,499, and there just isn’t that much 8K content out there to justify the jump.
Your existing 4K set probably has years of life left in it regardless. Panel makers estimate OLED screens last somewhere between 50,000 and 100,000 hours of use, which works out to roughly ten to thirty years at normal viewing habits, and even the more conservative manufacturer estimates put it at eight to ten years.
Prices on new sets also fall hard once a model has been out for a few months. Last Black Friday, a 65-inch TCL dropped from $1,499 to $899, and a 77-inch LG OLED that launched at over $3,000 was down to $1,600 by spring. Replacing a TV that still looks fine mostly buys bragging rights, not a better picture.
A brand-new game console in launch week
Image Credit: Shutterstock
Launch week is the worst time to buy a console on every metric that matters. Sony cut prices across the entire PS5 lineup by $100 per model last Black Friday, dropping the Digital Edition to $399 and the Pro model to $649, proof that waiting even a year closes a meaningful chunk of the difference in price.
Scalpers make the launch window worse. When the Nintendo Switch 2 arrived, resellers were flipping units for $90 to $150 over the $449.99 retail price, and bundles that should have cost $500 were going for upward of $600 on secondhand marketplaces.
Game libraries are also thinnest at launch, when most of what’s available is ports of titles already playable on the previous generation. Waiting a year gets you a bigger library, a season or two of price cuts already baked in, and none of the scalper markup that defines the first few months on shelves.
A first-generation VR or AR headset
Image Credit: Shutterstock
First-generation headsets have a rough habit of getting discounted the moment sales disappoint. Meta’s Quest Pro launched at $1,500 and was cut to $999 within months, a 33 percent markdown, and the original Quest 2 saw price cuts of up to 33 percent around the same time for the same reason.
Apple’s Vision Pro tells a similar story at a much higher price point. The headset launched at $3,499, sales came in weak, and reports suggest the price itself is the problem, with a cheaper second-generation model not expected until later this year at the earliest.
Buying the first version of any headset means paying full price for hardware that’s least refined and most likely to get a markdown within a year. Letting someone else absorb that first-generation premium, then buying once the price settles and the software library has actually caught up, is the better financial move almost every time.
A fancier streaming stick for a 4K set you already own
Image Credit: Walmart
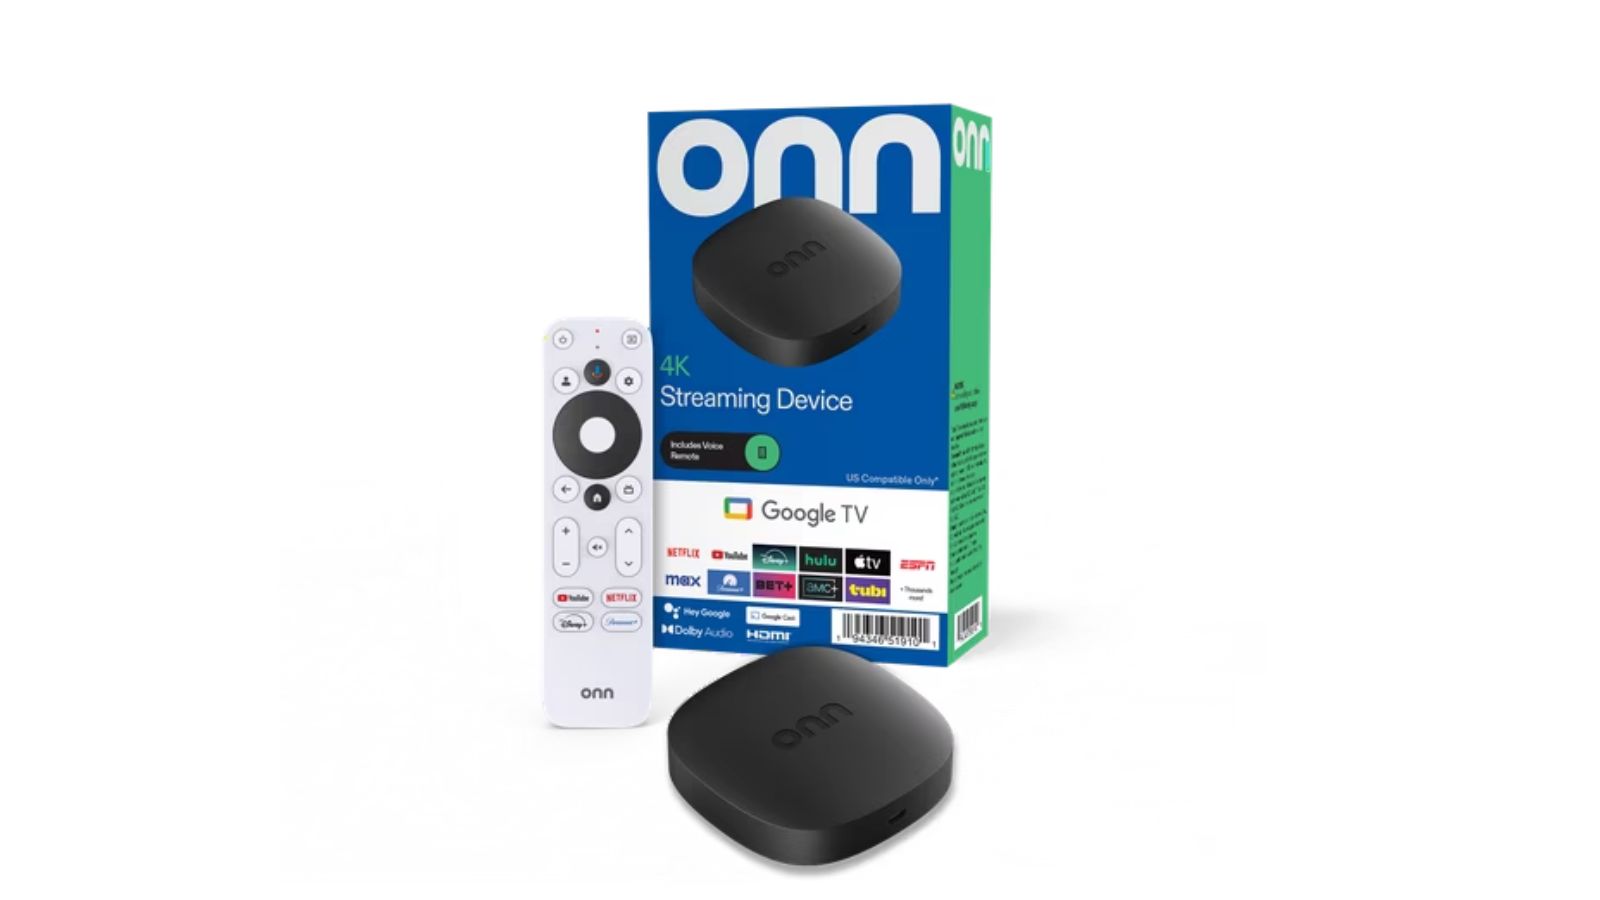
A fully capable 4K streaming stick costs less than a nice dinner out right now. Roku’s Streaming Stick 4K runs $44.99, and Amazon’s Fire TV Stick 4K is $29.99, which means the price difference between a basic and a premium streaming device has almost disappeared.
Upgrading to chase 8K streaming solves a problem that doesn’t exist yet. The same lack of 8K content that makes 8K televisions a hard sell applies just as much to the box plugging into one, since there’s effectively nothing to stream in that resolution regardless of what device is doing the streaming.
If your current stick plays Netflix and Disney Plus without buffering, a new one mostly buys faster menu animations. That’s a real improvement, just not one worth paying $50 or more for on something that was never the bottleneck in your setup to begin with.
The newest robot vacuum with all the extra sensors
Image Credit: Shutterstock
Previous-generation robot vacuums get marked down hard the moment a new flagship ships. The Roborock Qrevo CurvX dropped from $1,499.99 to $849.99, and the Dreame L40 Ultra fell from $649.99 to $399.99 once a newer model took its spot on the shelf.
The feature that drives most of the price difference, a self-emptying base, is mostly a convenience upgrade rather than a cleaning one. Reviewers who have tested the self-emptying models point out that the base itself does nothing to improve how well the vacuum actually cleans, it just means emptying the bin less often.
A previous-generation robot vacuum with the self-emptying feature already does the job for several hundred dollars less than whatever just launched. Unless mapping precision on the newest model is solving an actual problem in your home, like a maze of furniture the old one kept getting stuck on, the extra money buys convenience you were probably fine living without.
A Wifi 7 router before your gear can use it
Image Credit: Shutterstock
Wifi 7 routers carry a steep premium for a standard almost nothing in your house can actually use yet. The cheapest Wifi 7 routers start around $599, compared to roughly $135 for an entry-level Wifi 6E router, and high-end Wifi 7 mesh systems run as high as $2,299 for a multi-unit setup.
Adoption is still tiny. Wifi 7 connections made up only 7.2 percent of U.S. traffic by early this year, and device support is mostly limited to the newest flagship phones and a handful of high-end laptops and gaming devices. Your smart TV, your security cameras, your older phone, and most of your smart home gear are likely still running on Wifi 6E or older standards that can’t take advantage of Wifi 7 at all.
Paying four or five times more for a router that nothing in the house can fully use is money spent on a number on the box, not a number in your actual internet speed. That premium will shrink considerably once more of your devices are built for the standard.
A full smart home system overhaul
Image Credit: Shutterstock
Switching brands or hubs all at once, usually to chase a new standard like Matter, means re-buying an entire house’s worth of gear that was already working. Smart lighting alone runs $15 to $60 per fixture, smart thermostats run $100 to $300 before installation, and a basic smart security package starts at $199.99 in equipment plus $24.99 a month in monitoring.
Multiply any of those numbers by the number of rooms in a house and the total climbs into the thousands fast, all to replace devices that weren’t broken, just built on an older standard. None of that spending is wasted exactly, but spending it all in one weekend instead of spreading it out means absorbing the full cost of early adoption on every category at once.
A gradual swap, replacing each device only once it actually fails or once a clearly better version shows up at a reasonable price, spreads that same total cost over years instead of one expensive month, and it leaves room for prices on newer standard-compliant gear to keep dropping before you commit to all of it.
The newest smart thermostat on the shelf
Image Credit: Shutterstock
Installing a smart thermostat is worth the money. Installing the newest smart thermostat, when an older one is already working, usually isn’t. A professionally installed smart thermostat runs about $420 on average, with the hardware itself closer to $150 to $250 of that total.
The savings that make a smart thermostat worthwhile come from simply having one that can learn a schedule and adjust automatically, not from which specific model is doing the learning. Federal estimates put the savings from a smart thermostat at up to 10 percent of heating and cooling costs, and with the average household spending more than $900 a year on heating and cooling, that ceiling works out to roughly $90 a year regardless of which generation of device is doing the work.
An older working Nest or Ecobee is already capturing that same $90-a-year ceiling. Replacing it with this year’s model mostly buys a nicer app and maybe a slightly better screen, while resetting the payback clock on a purchase that already paid for itself once.
An entire security camera system replacement
Image Credit: Walmart
A full security camera setup, installed, runs a national average of about $1,298, with per-camera costs landing between $125 and $450 depending on the hardware. Labor alone eats 50 to 70 percent of that total, which means swapping out a working system costs almost as much the second time as it did the first.
Subscription fees stack on top of the hardware and rarely get mentioned until the first bill arrives. Ring’s basic plan now runs $4.99 a month for one camera, or $10 a month for a multi-camera plan, and Arlo’s unlimited-camera plan runs as high as $29.99 a month before an annual discount.
Resale value on used security hardware is close to nonexistent, so a full-system swap means paying installation costs again on new cameras while getting little to nothing back for the old ones. Replacing individual cameras as they fail, instead of tearing out a working system to chase a new brand or a marginally sharper lens, keeps both the labor bill and the subscription stacking under control.
A brand-new laptop instead of a repair
Image Credit: Shutterstock
A new laptop battery costs about $100 installed in most cases, and that single repair often adds years of usable life to a machine that otherwise works fine. A new budget laptop starts under $500, but it rarely matches the build quality of the $1,000-plus laptop it’s meant to replace, and a repair bill a tenth the size of a new purchase is hard to beat on value alone.
This year makes the repair case even stronger. Memory and storage chip shortages have pushed component prices up sharply in 2026, with 16GB DDR4 memory modules jumping 51 percent in a single quarter and some storage and memory components rising by more than 100 percent in the same stretch. That same shortage is pushing up the price of brand-new laptops too, since every new machine needs the same memory and storage chips that just got more expensive.
A battery swap or a storage upgrade sidesteps that price spike entirely, since it uses one small, specific part rather than an entire machine’s worth of now-pricier components. If the screen, hinges, and processor are still solid, a repair is the better buy this year specifically.
The newest graphics card at launch pricing
Image Credit: Shutterstock
Launch pricing on a new flagship graphics card almost never matches what’s printed on the box. The RTX 5090 carried a $1,999 list price but sold for a street median closer to 41 percent above that number for months after release, and the RTX 5080 ran roughly 24 percent over its listed price in the same window.
Resale listings tell the same story from a different angle. Completed sales for the RTX 5090 averaged around $6,000 right after launch before settling closer to $4,000 a few weeks later, a drop of about a third, and both figures still sat well above the official list price the entire time.
Waiting even a few months lets street prices drift back toward what the card is actually supposed to cost, and the previous generation’s equivalent cards typically get a real discount the moment a new flagship ships. Buying at launch means paying a scarcity tax on top of an already expensive piece of hardware, for a performance gain that will cost less to get in a matter of months.
A new camera body for a small spec bump
Image Credit: Shutterstock
Camera bodies hold their value worse than almost anything else in a hobbyist’s gear bag, and the jump from one generation to the next is usually smaller than the price difference suggests. A used Canon EOS R6 sells for a median of around $1,315, while the R6 Mark II goes for closer to $1,693 used, a difference of a few hundred dollars for a camera that shares the same sensor foundation, the same image stabilization, and the same weather sealing as the one it replaced.
The actual differences, a few more megapixels and slightly faster autofocus, matter for a narrow slice of shooters doing fast-action or large-print work. For most hobbyists photographing kids, trips, and everyday life, the older body produces images that are functionally indistinguishable from the newer one.
Buying a camera body one generation behind the newest release gets nearly the same image quality for meaningfully less money, and the savings only grow once that older body has been out long enough for prices to settle further.
A brand-new printer instead of fixing the ink problem
Image Credit: Shutterstock
Printer companies make their real money on ink, not on the printer itself, and a new machine almost never fixes that underlying cost. A basic new inkjet runs $60 to $150, but a standard cartridge from a major brand costs somewhere around 10 to 20 cents per page, while ink-tank and high-yield toner models run under a penny per page for the exact same job.
A heavily used printer can cost more in ink over a single year than the printer itself cost to buy, which is why a brand-new discounted printer so often turns out to be the more expensive option over time. Subscription plans don’t fully solve this either. HP’s Instant Ink plans currently run $1.99 a month for 10 pages up to $32.99 a month for 700 pages, which only pencils out if your actual printing volume lines up closely with the plan you pick.
Before replacing a printer that’s jamming or running dry, it’s worth pricing out an ink-tank refill kit or switching ink strategy instead. The printer is rarely the expensive part, the ink almost always is.
An electric vehicle bought in a hurry
Image Credit: Shutterstock
Buying an EV right now isn’t necessarily a bad move, but buying one in a rush usually is, because prices are still falling. The average new EV sold for $56,238 in June 2026, down 4.5 percent from a year earlier and the sixth straight month of year-over-year declines, with Tesla’s own average transaction price falling to $53,107 in the same stretch.
The federal incentive that used to reward buying sooner is gone. The $7,500 federal tax credit for new electric vehicles stopped applying to vehicles bought after September 30, 2025, which removes a meaningful chunk of the financial case for rushing a purchase before some deadline, since that deadline already passed and prices kept falling anyway.
Depreciation on EVs is also unusually steep right now. Some models have lost up to 50 percent of their value within twelve months, well beyond what a comparable gas car typically loses, and used EV prices overall have dropped close to 30 percent since 2023. If an EV purchase can wait another few months without creating a real problem, the numbers say it probably should.
Home battery storage added to solar panels
Image Credit: Shutterstock
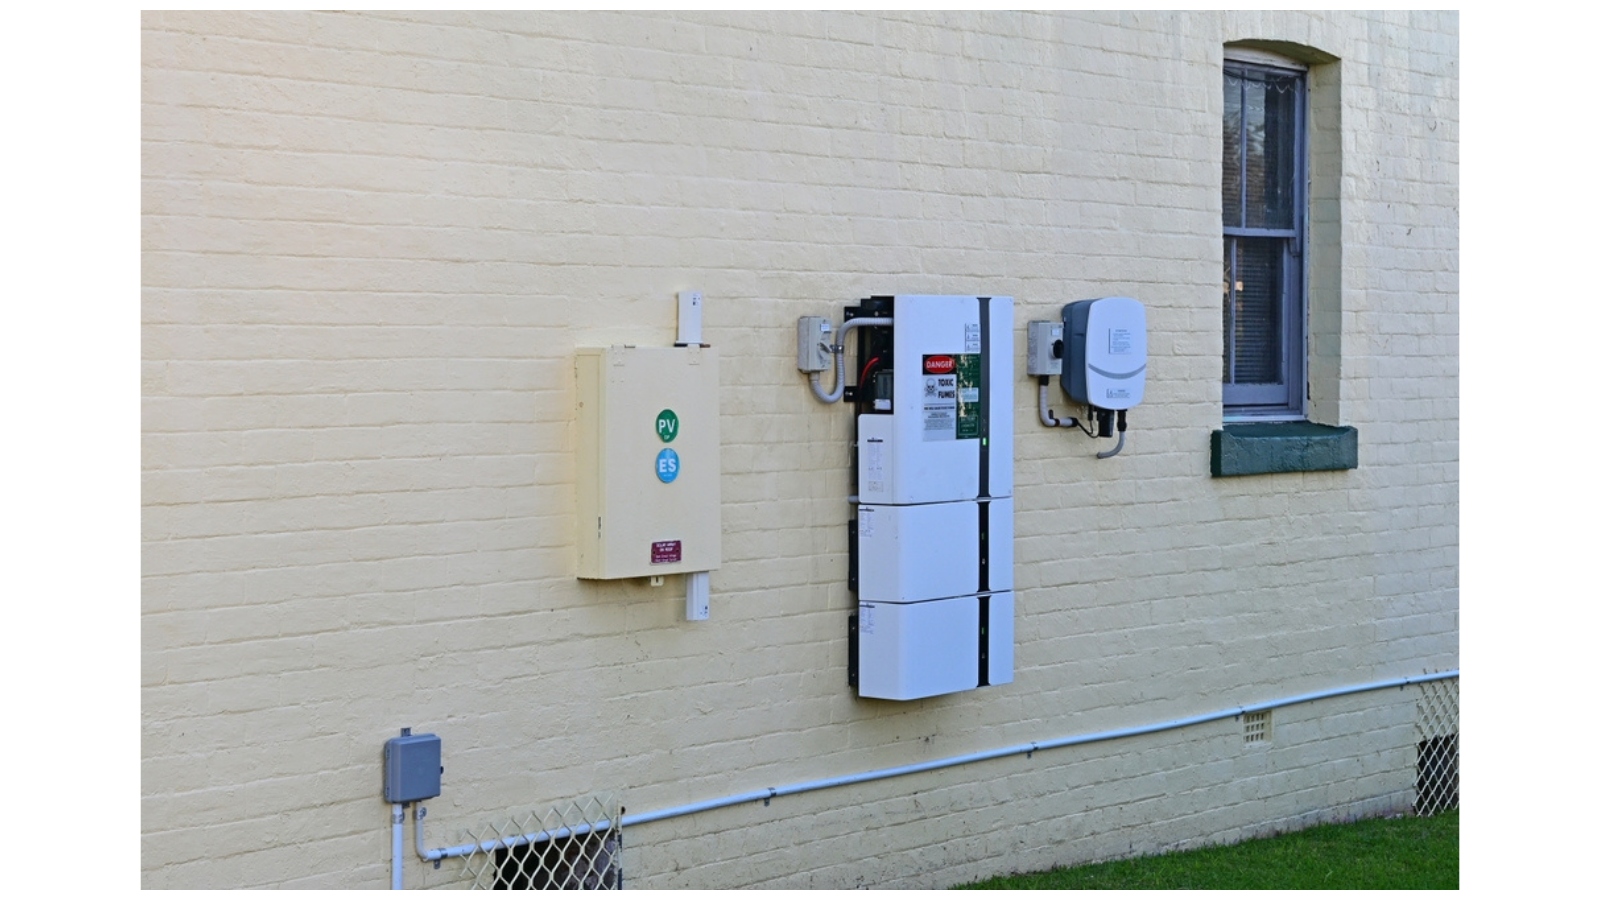
A home battery system like a Tesla Powerwall costs $13,000 to $16,500 installed, and the federal tax credit that used to cover 30 percent of that cost for home batteries has expired, which means homeowners adding one now are paying full price for something that used to come with a meaningful discount.
Battery hardware itself is also getting cheaper on a predictable curve, just not fast enough to have caught up yet. Lithium-ion battery pack prices dropped from $153 per kilowatt-hour in 2022 toward a projected $80 per kilowatt-hour by 2026, roughly half in four years, and that trend is expected to continue as production scales up.
Put together, a battery bought today costs more upfront than it will in a year or two, with no federal credit left to soften the blow, on top of savings that typically take well over a decade to pay back the installation cost. Unless frequent power outages make backup power a necessity rather than a nice-to-have, waiting lets both the price and the payback period improve at the same time.
Extended warranties on things that depreciate fast
Image Credit: Shutterstock
Extended warranties and protection plans are priced to make money for the company selling them, not for the person buying them. AppleCare+ on a top-end iPhone runs roughly $10 a month, or $199 for two years, and a retailer protection plan on a $1,300 TV can run $129 to $175, prices that add up fast across multiple devices in one household.
The market itself is projected to grow from $55.3 billion in 2022 to $81.3 billion by 2028, which says a lot about how profitable these plans are for the companies selling them, and most manufacturer warranties already cover the repairs most people actually end up needing in the first year or two anyway.
On fast-depreciating gadgets especially, a phone, a laptop, a pair of earbuds, the odds rarely favor the warranty. A device worth half its original price within a year isn’t worth insuring at a premium built for a company’s profit margin rather than an honest estimate of what repairs actually cost. Setting aside the price of the warranty in a savings account instead covers most real repair bills with money left over.
A few hundred dollars saved on a phone, a TV, or a camera body adds up fast across a full household’s worth of gadgets. That money is worth more sitting in a bank account than funding someone else’s launch-week markup.
You spend half of every workday bracing for the next interruption. Someone swings by your desk to talk about their weekend, a meeting gets added that could have been an email, and by 3 p.m. you’ve used up every ounce of small talk you had in you. None of that means you’re bad at your job. It usually means your job was built for someone who recharges by talking to people, and you’re not that person.
Plenty of the best-paying work in the country barely asks for any small talk at all. A patent examiner spends the day reading applications and writing decisions with almost no client contact. A nuclear reactor operator spends a shift monitoring instruments, mostly alone, in a control room. These aren’t consolation-prize jobs for people who can’t handle an office. Several of them pay noticeably more than careers built entirely around being likeable.
Most require specific training, licensing, or a degree, and none of them are a shortcut. What they have in common is that the hard part is the skill itself, not performing friendliness while you use it.
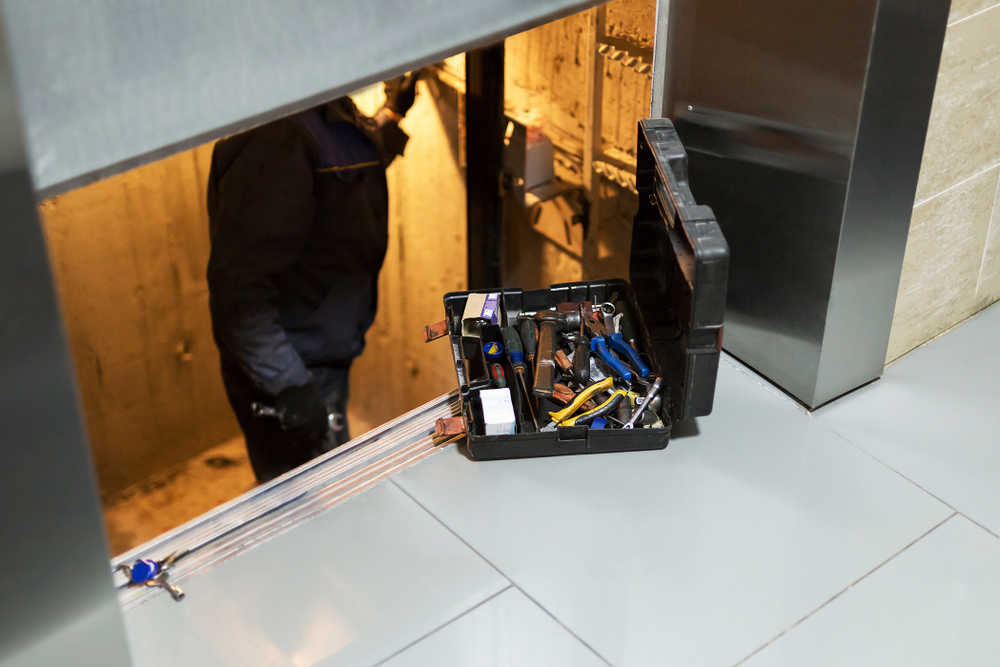
Most elevator and escalator mechanics spend their shift inside a machine room, a shaft, or an equipment closet, not behind a reception desk. The work is mechanical and electrical troubleshooting: tracing a wiring fault, swapping a worn cable, running diagnostics on a control panel. Building staff might ask how long a repair will take, but the actual job happens alone or with one other mechanic, and the conversation that does happen stays practical. Nationally, these mechanics bring home a median $52.84 an hour.
Getting in usually means a multi-year union apprenticeship rather than a four-year degree, with most of the training happening on the job rather than in a classroom. Elevators also fall under strict local and state safety codes, so mechanics typically need to pass licensing exams on top of their apprenticeship. It’s physically demanding work in tight, enclosed spaces, which keeps the field smaller than it would otherwise be, and that scarcity is a big part of why the pay holds up this well.
Nuclear power reactor operator
Image Credit: Shutterstock
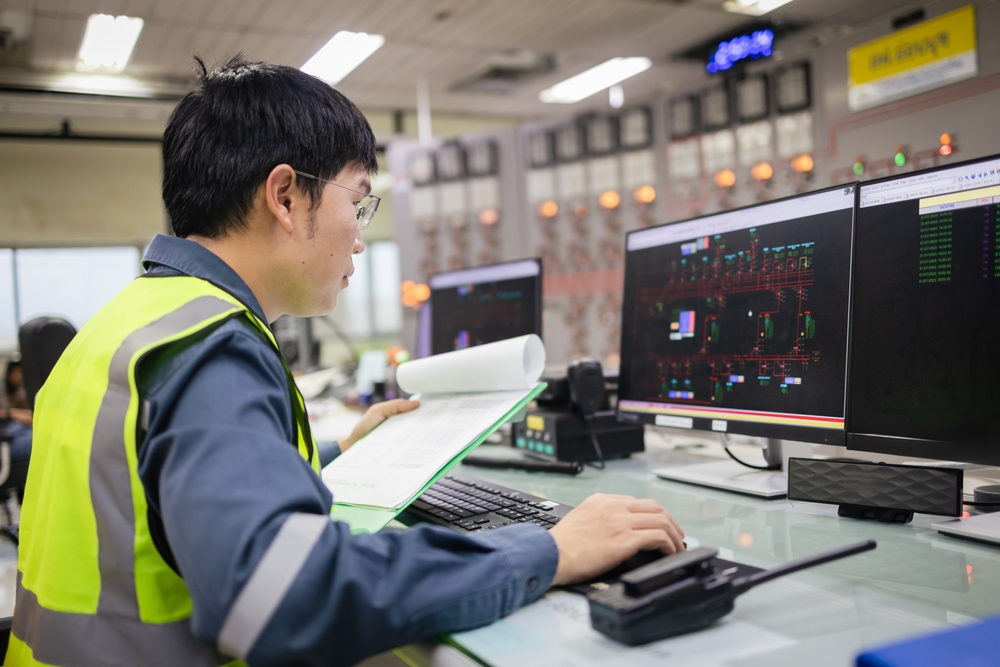
Nuclear power reactor operators monitor a control room, watching instruments and gauges through long, highly procedural shifts. The job is licensed and tightly regulated by the Nuclear Regulatory Commission, and most of a shift is spent alone or with a small, fixed crew rather than in front of the public. Nationally, reactor operators earn a median $59.08 an hour.
Getting licensed typically means years of plant-specific training and passing federal exams, often starting from a related technical role rather than a traditional degree path. Shifts run around the clock in rotating blocks, including nights and weekends, and new operators work under close supervision from senior licensed staff until they’ve logged enough hours to work independently. The job also comes with strict testing and ongoing retraining requirements, since a lapse in attention carries real consequences. It’s exacting, safety-critical work, and the isolation of the control room is treated as a feature of the job, not a flaw, since consistency matters more than charisma when you’re responsible for a reactor core.
Power plant distributor and dispatcher
Image Credit: Shutterstock
Power distributors and dispatchers work from a control room, rerouting electricity across the grid and responding to outages or demand spikes in real time. Most of the job is monitoring systems and making fast technical calls, with coordination handled over radio or phone rather than face to face. Nationally, distributors and dispatchers earn a median $51.31 an hour.
Most employers hire for this role without requiring a four-year degree, relying instead on extensive on-the-job and simulator training before someone works a shift unsupervised. During a storm or equipment failure, a dispatcher might be rerouting power to tens of thousands of customers at once, making fast judgment calls under pressure with little time for anything beyond short, clipped updates to field crews. The role sits at the center of keeping the lights on for an entire region, but almost nobody outside the utility ever interacts with the person doing it. It involves more real-time coordination than some of the other control-room jobs on this list, but it’s still fundamentally a job built around monitoring a system rather than managing people.
Court reporter and realtime captioner
Image Credit: Shutterstock
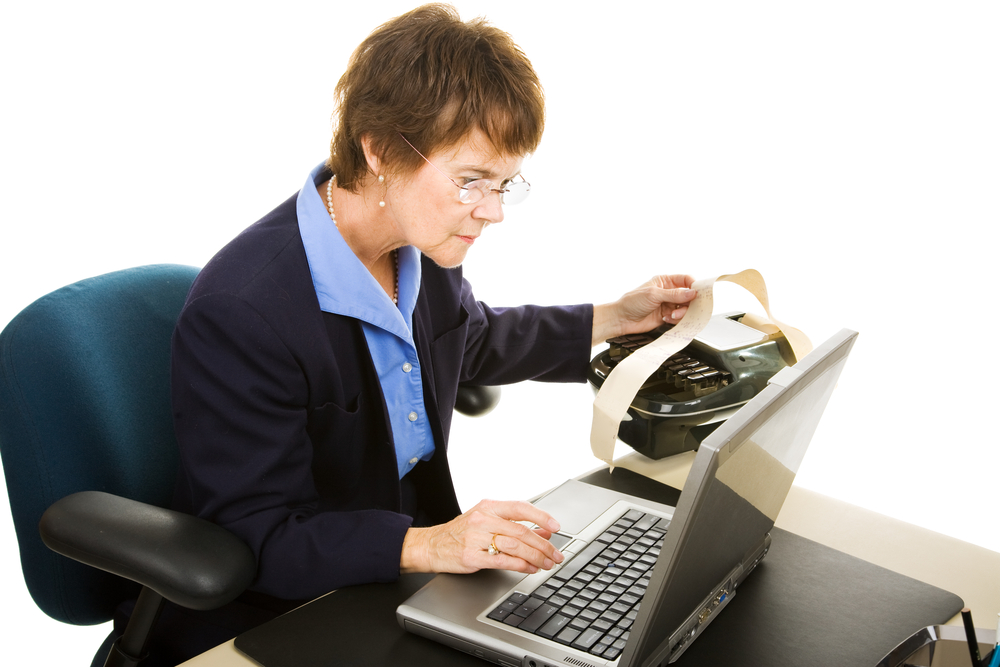
Courtroom and broadcast captioning work rewards accuracy over conversation. A realtime stenographer sits at a keyboard translating spoken words into text as fast as people can talk, which leaves essentially no room for chit-chat during the job itself. Outside of depositions or live broadcasts, plenty of freelance realtime reporters work independently, picking up assignments rather than reporting to an office every day. The national median for court reporters and captioners sits well under $50 an hour, but the best-paid realtime reporters and captioners nationally earn $60.79 an hour, and that top tier is where the specialized, certified realtime skill actually lives.
Getting there means finishing a stenography program and passing speed and accuracy certification exams, often at 225 words per minute or faster. It’s a demanding skill to build, which is exactly why so few people have it, and why the ones who do get paid well for sitting quietly and typing.
Patent examiner
Image Credit: Shutterstock
Patent examiners read, not pitch. The job is deep solo research: reading a patent application, searching prior art, and determining whether an invention is truly new and non-obvious, all from a desk, often working from home for at least part of the week. Contact with the outside world happens mostly in writing, through formal office actions, with the occasional scheduled call or interview with an applicant’s attorney rather than open-ended conversation. Senior examiners in the Washington, D.C., pay zone start around $58 an hour under the federal government’s current pay tables, and the number climbs from there with further promotions.
Most examiners need a four-year degree in a technical or scientific field, since the job involves assessing the technical merits of an invention, but a law degree isn’t required at the entry level. The role also comes with production quotas rather than open-ended deadlines, so the work is self-paced within clear boundaries, which suits someone who’d rather manage their own time than sit through status meetings. It’s about as introvert-friendly as federal work gets: structured, deadline-driven, and almost entirely independent.
Orthotist and prosthetist
Image Credit: Shutterstock
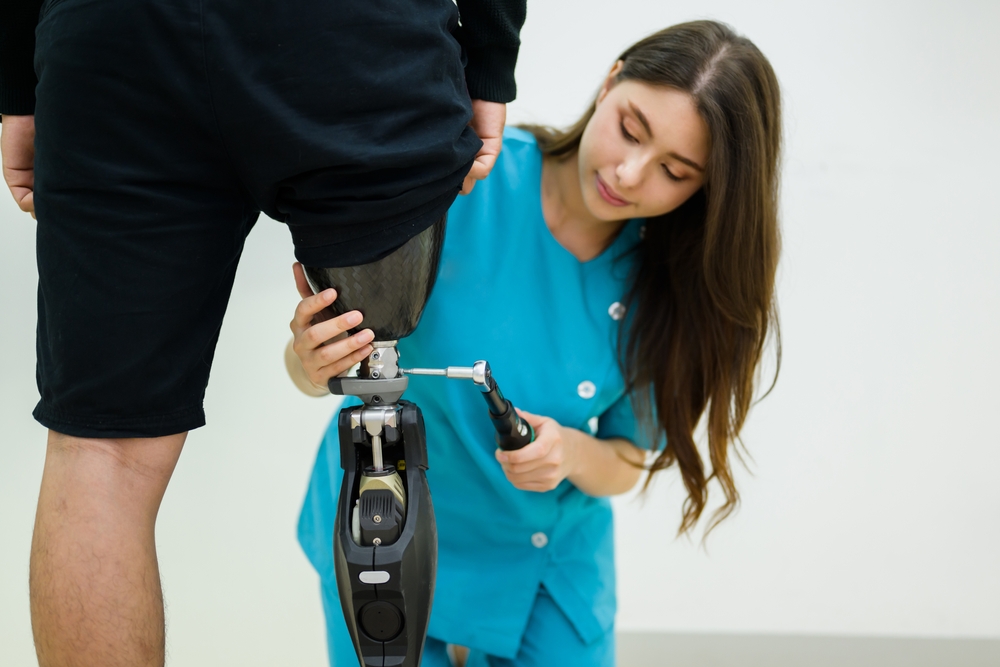
Fitting someone for a prosthetic limb or a custom brace is intimate, one-on-one work, but it isn’t chatty. Appointments are scheduled and focused on measurements, fit, and function, and a meaningful part of the job happens afterward in a workshop, fabricating and adjusting the device alone. Nationally, orthotists and prosthetists earn a median under $50 an hour, but experienced practitioners nationally earn $56.37 an hour and above.
The field requires a master’s degree in orthotics and prosthetics plus a residency and board certification, a longer runway than most of the jobs on this list. Follow-up visits happen on a schedule of weeks or months rather than daily, so the relationship with each patient builds slowly across a handful of focused appointments instead of constant contact, and much of the actual craftsmanship, carving a socket, adjusting alignment, testing load-bearing points, happens solo in the lab with no one else in the room. For someone who wants meaningful, skilled work without a packed schedule of small talk, it’s a strong trade-off: fewer, deeper appointments instead of a constant stream of short ones.
Landscape architect
Image Credit: Shutterstock
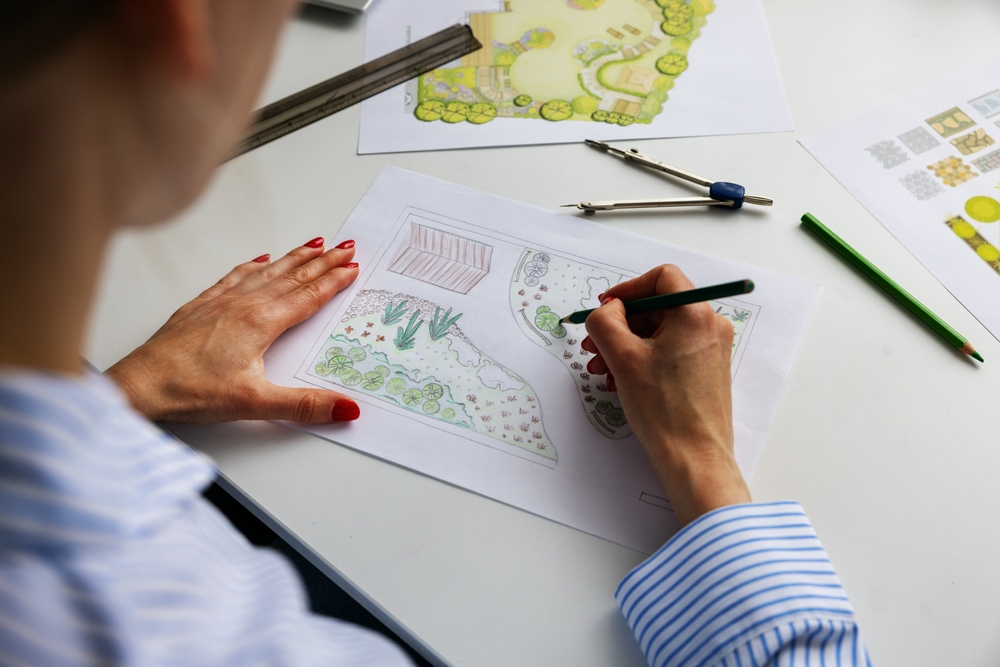
A landscape architect’s best hours happen alone at a drafting table or in CAD software, working out drainage, plant placement, and how a space will actually be used once it’s built. Client meetings and site visits are part of the job, but they’re scheduled check-ins rather than constant interruptions, and a lot of the real work is independent design and technical drawing. Nationally, landscape architects earn a median under $50 an hour, but experienced architects nationally reach $60.38 an hour.
Licensure requires a professional degree in landscape architecture and passing a national exam, which takes several years to complete. Permitting and code research add another layer of solo deskwork, since much of the job involves making sure a design will actually satisfy a municipality’s stormwater and zoning rules before it ever gets built. It’s a creative field with a technical backbone, better suited to someone who wants to solve a problem quietly and present a finished plan than someone who wants to brainstorm out loud in a group all day.
Diagnostic medical sonographer
Image Credit: Shutterstock
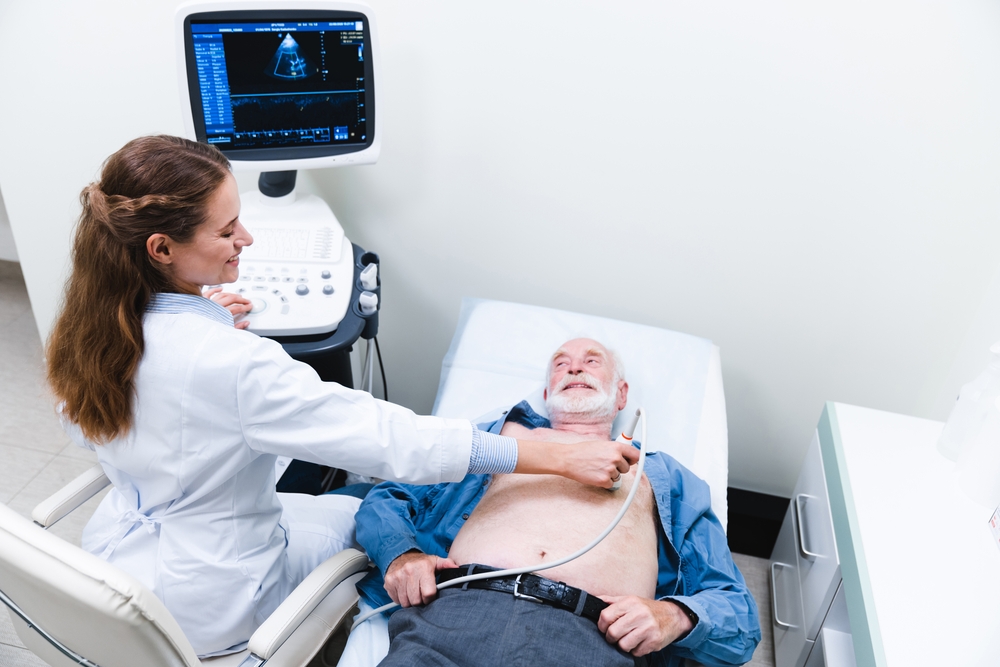
An ultrasound room is quiet by design, lights dimmed, most of the appointment spent watching a screen rather than talking. Sonographers position the probe, capture the images a radiologist needs to make a diagnosis, and give patients short, practical instructions along the way. It’s hands-on, technical work that rewards precision over chattiness. Nationally, sonographers earn a median $46.44 an hour, and experienced sonographers, especially those certified in a cardiac or vascular specialty, regularly cross into the $56 an hour range.
The standard path is an associate or bachelor’s degree in sonography followed by national certification. Appointments are typically 30 to 60 minutes apiece, which keeps the day structured around focused, one-task-at-a-time work rather than an open floor full of distractions. Most sonographers work a defined shift in a hospital imaging department or outpatient clinic, moving from one scheduled appointment to the next rather than fielding walk-ins or phone calls. The job also rewards people who like puzzles: reading subtle differences in grainy black-and-white images takes real pattern recognition, and that skill, not sociability, is what gets someone promoted or specialized.
Dental hygienist
Image Credit: Shutterstock
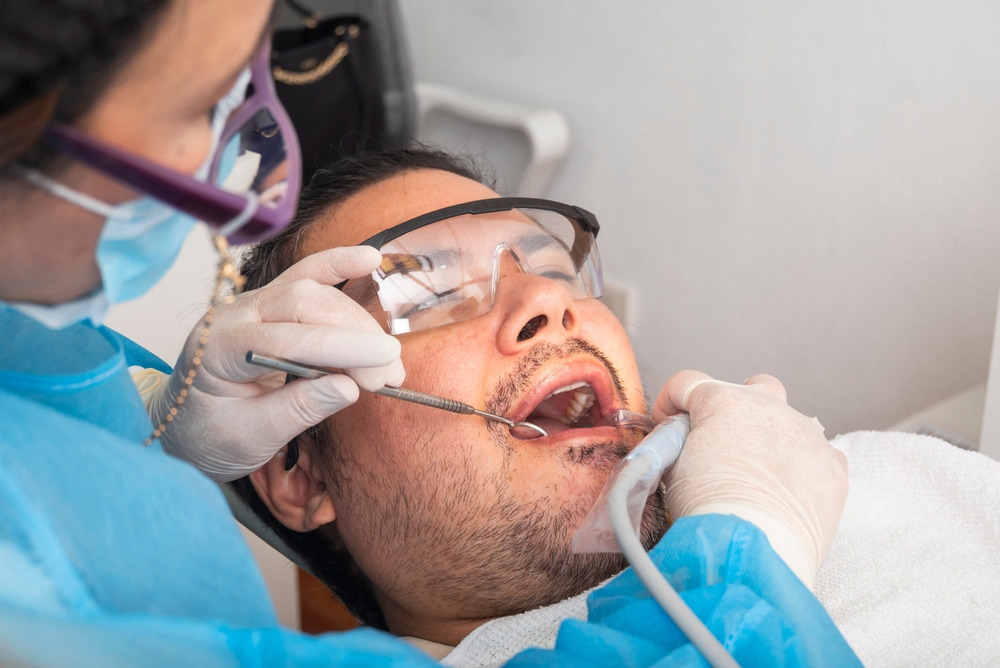
Dental hygienists talk to patients who, for fairly obvious reasons, can’t talk back for most of the appointment. Cleanings follow a set routine of scaling, polishing, and checking for problems, and the conversation that does happen is short and professional rather than a running back-and-forth. Hygienists typically see a new patient every 45 minutes to an hour, which keeps the day structured and predictable rather than open-ended. Nationally, hygienists earn a median $47.16 an hour, and experienced hygienists in busy practices often earn closer to $57 an hour.
The path in is a two-year associate degree in dental hygiene plus a licensing exam, shorter and cheaper than most of the other careers on this list, which makes it one of the more accessible entries here. In several states, hygienists can now work with expanded authority, treating patients in community clinics or nursing homes with less direct dentist oversight, which only adds to the independence of the role.
Nuclear medicine technologist
Image Credit: Shutterstock
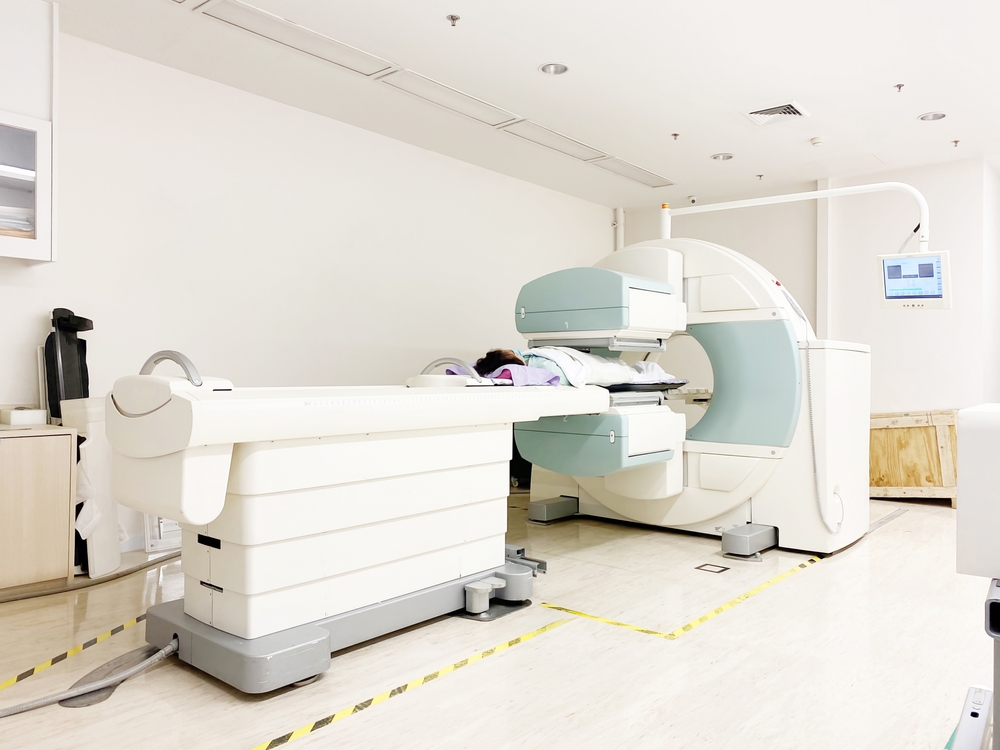
Nuclear medicine technologists spend most of a shift preparing radioactive tracers and running a scanner, not making conversation. A patient gets an injection, waits for the tracer to circulate, then holds still while the scanner does its work. The technologist is mostly occupied with equipment, dosing, and radiation safety protocols rather than chit-chat. Nationally, these technologists earn a median $48.74 an hour, and experienced technologists reach $59.57 an hour and above.
It typically takes a two-year associate degree plus certification to get licensed, and the radiation-safety training that comes with the job isn’t something most employers are willing to skip. Hospitals and imaging centers hire for this role with structured shift schedules, so the day rarely turns into an open-ended string of unplanned interactions the way some healthcare jobs do. Most of a technologist’s time is spent calibrating equipment, calculating doses, and documenting results, tasks that depend on precision and record-keeping rather than bedside manner.
MRI technologist
Image Credit: Shutterstock
MRI technologists work from a control console, communicating with patients mostly through an intercom while they run the scan. The job is procedural rather than conversational: position the patient, start the sequence, watch the images come through, adjust, repeat. Nationally, MRI technologists earn a median $95,480 a year, and technologists with a few years of specialized MRI experience push into the $54 an hour range and above.
Most technologists start with an associate degree in radiologic technology, then add MRI-specific certification once they’re working, since MRI pays noticeably better than general X-ray work. Hospitals typically schedule MRI appointments in fixed blocks throughout the day, so technologists know their caseload before a shift even starts rather than reacting to a constant stream of walk-ins. Some move into research imaging or specialized functional MRI work later in their career, which comes with even less routine patient turnover and more protocol-driven, solitary work. It’s a good fit for someone who likes machines and protocols more than open-ended patient conversation.
Radiation therapist
Image Credit: Shutterstock
A radiation therapist’s time with each patient is short by design: position them precisely on the treatment table, run the linear accelerator for a few minutes, check in, and move to the next appointment. The real skill is in the setup and the planning behind it, making sure the radiation hits the tumor and nothing else, not in extended conversation. Nationally, radiation therapists earn a median $50.63 an hour, clearing $50 without needing to cherry-pick the best-paid slice of the field.
The job usually requires an associate or bachelor’s degree in radiation therapy and a national certification exam. Much of the supporting work, calculating doses and mapping treatment plans, happens beforehand with a dosimetrist and radiation oncologist rather than the patient, so the treatment room itself stays focused and efficient rather than conversational. It’s emotionally heavier work than some of the other entries here, since most patients are undergoing cancer treatment, but the day-to-day interaction stays brief and procedural rather than open-ended.
Actuary
Image Credit: Shutterstock
Actuaries get paid to sit with spreadsheets and worst-case scenarios: how likely is this event, what would it cost, how should a company price around that risk. Much of the job is independent modeling and report writing, with meetings scheduled rather than constant, and plenty of actuaries work in-house for an insurer or pension fund rather than consulting across a rotating cast of clients. Nationally, actuaries earn a median $62.50 an hour.
Breaking in means passing a series of professional exams, usually while already working entry-level, and most actuaries are still sitting for exams years into the job. A lot of actuarial work can also be done remotely or hybrid, since the output is a model, a report, or a set of assumptions rather than anything that requires being physically present with a team. It’s a slow, exam-heavy path that rewards people who’d rather study alone in the evening than go network at a happy hour, which is a big part of why it pays as well as it does.
Mathematician
Image Credit: Shutterstock
Pure and applied mathematics is still, somehow, a paying job outside a university lecture hall. Mathematicians working for government agencies, research labs, and finance and tech firms spend their days on abstract problem-solving, building and testing models, largely without a client-facing component at all. Nationally, mathematicians earn a median $126,710 a year, which works out to a bit over $60 an hour across a standard work year.
Most roles require at least a master’s degree, and plenty require a PhD, so this isn’t a fast path in. Government research labs, universities, and tech companies doing cryptography or algorithm research are among the most common employers outside pure academia, and the work tends to be project-based and deeply individual: one person wrestling with one hard problem for weeks, checking in periodically rather than collaborating constantly. For someone who already loves the subject and dreads open-plan offices, it’s one of the purest desk jobs on this list.
Petroleum engineer
Image Credit: Shutterstock
Petroleum engineers spend real time modeling how oil and gas move through underground reservoirs, running simulations to figure out where and how to drill most efficiently. Office-based reservoir and production engineers do plenty of that work from a desk, with site visits and field rotations layered in rather than constant, though the field does skew more collaborative than some of the other jobs here, with regular coordination across geology, drilling, and operations teams. Nationally, petroleum engineers earn a median $69.67 an hour, near the top of what’s realistic to expect from any job on this list.
A four-year engineering degree is the standard entry point, and starting pay in this field already runs well above most other engineering disciplines. Rotational field assignments are common early in a career, which can mean remote sites with small crews rather than a crowded corporate office, before engineers move into steadier desk-based reservoir or production roles. If constant client contact is the dealbreaker rather than teamwork itself, this is worth a look. If it’s coworkers in general, it probably isn’t the best fit here.
Nuclear engineer
Image Credit: Shutterstock
Nuclear engineering runs on documentation, simulation, and double-checking, the kind of exacting technical work that doesn’t leave much room for improvisation or, frankly, small talk. Engineers in this field design and troubleshoot reactor systems, run safety analyses, and work through regulatory requirements that are about as unforgiving as paperwork gets. Nationally, nuclear engineers earn a median $64.41 an hour.
It takes a four-year engineering degree at minimum, often followed by additional certification depending on the employer, and the field is small enough that specialists are hard to replace. A lot of the job happens at national laboratories, utility companies, or federal agencies, running simulations and writing technical reports that go through multiple rounds of internal review before anything gets implemented, which adds structure and predictability to the week rather than requiring constant real-time collaboration. Teams tend to be tight-knit rather than sprawling, which suits someone who wants depth with a handful of people rather than breadth across a big department.
Biomedical engineer
Image Credit: Shutterstock
Biomedical engineers design the devices that keep other people alive, usually from a lab bench or a CAD workstation rather than a sales floor. The work involves prototyping, testing, and documenting medical devices against strict regulatory standards, with plenty of solitary design and testing time between the meetings. Cross-functional check-ins with clinicians or regulatory staff happen, but they’re scheduled and purposeful rather than the constant drop-by interruptions common in a lot of office jobs. Nationally, biomedical engineers earn a median $52.58 an hour.
Most biomedical engineers come in with a four-year engineering degree, sometimes paired with a graduate degree for more specialized roles in areas like prosthetics or implantable devices. A single device can take months or years to move from prototype to approval, and most of that time is spent running tests, documenting results, and refining a design based on data rather than meeting with people. It’s one of the more stable, least client-facing engineering paths available, and it rewards patience with detail over comfort in a room full of strangers.
Materials scientist
Image Credit: Shutterstock
Materials scientists spend their careers testing how things break: stress-testing metals, polymers, and composites to figure out why a part failed or how to make the next version hold up better. Most of that happens in a lab, running tests and analyzing results, with writeups going to an engineering team rather than a client. Nationally, materials scientists earn a median $117,790 a year, or a little over $56 an hour across a standard work year.
The role typically requires a bachelor’s degree in materials science, chemistry, or a related engineering field, with a master’s or PhD opening up more senior research positions. It’s methodical, repetitive-in-a-good-way work, better suited to someone who likes running the same test forty different ways than someone who needs constant variety in who they talk to.
None of these jobs ask you to fake enthusiasm for people you just met. They ask you to be very good at something specific, and the pay reflects that.