scroll top

Your badge stops working on a Tuesday morning, or the recruiter who called last week stops answering, or your manager asks you to hop on a call with no agenda attached. However it happens, a layoff rearranges your week before it rearranges anything else. The calendar empties out, the direct deposit stops, and everyone around you still expects you to have a plan by dinner.

That shock lands differently depending on where you are in your life. A 26-year-old with six months of rent saved has one kind of problem. A 46-year-old with a mortgage, two kids and braces to pay for has another. A 61-year-old three years from a pension has a third. None of those problems get solved by panic, and none of them get solved by jumping straight to the resume either.

The order you handle things in matters more than how fast you move. Fix the money first, protect the legal ground you’re standing on second, and only then turn to the job search itself.

File for unemployment the same week you lose your job
unemployment claim
Image Credit: Shutterstock

Don’t wait to see if another offer shows up first, and don’t assume a severance check disqualifies you right away. Most states still let you file the week your job ends, and weekly unemployment checks that average around $532 nationally and typically run about 24 weeks depend entirely on when your claim starts, not when your severance runs out. The amount varies enormously by state, since each one sets its own minimum and maximum payment and its own rules about how severance pay interacts with eligibility. Some states count a lump-sum severance against your benefits for a number of weeks; others don’t touch it at all. Call your state unemployment office or check its website before you assume either way, because guessing wrong in either direction costs you money.

Filing is also not a one-time event. Most states require a weekly or biweekly certification confirming you’re still looking for work, and missing even one can stall your payments for weeks while a caseworker sorts it out. Set a recurring reminder the same day you file your initial claim. If your state’s online system rejects your application because of a technicality, such as a mismatched employer name or a severance payout showing up as wages, don’t give up and assume you’re ineligible. Call and ask a person to walk you through it. The system is clumsy, but the money is real, and it’s yours whether or not you feel like you need it yet.

Make sure your final paycheck is actually final
Hand holding a smartphone with online banking account options
Image Credit: Shutterstock

Federal law doesn’t set a deadline for when a last paycheck has to arrive. The Department of Labor’s own guidance says an employer isn’t required by federal law to pay a departing employee immediately, which surprises most people who assume there’s a national rule. What actually controls the timing, and often whether unused vacation or PTO gets cashed out at all, is state law, and state rules on this vary widely: some require payment on your last day, some allow until the next scheduled payday, and some treat accrued vacation as wages that must be paid out while others don’t.

Pull up your state labor department’s page on final wages before you assume either way. If your regular payday comes and goes with nothing in your account, that’s the point to contact your state labor agency or the federal Wage and Hour Division, not three paydays later once the amount feels too awkward to chase. Keep your final pay stub and any written severance or PTO payout terms somewhere you can find them, since a claim for unpaid wages moves a lot faster with paperwork attached than with a memory of what HR said in the exit meeting.

Decide on COBRA or a marketplace plan before your coverage lapses
Health insurance form on a clipboard with a pen and stethoscope
Image Credit: Shutterstock

The average employer health plan now costs $9,325 a year for a single person, with the worker covering only about 16 percent of that out of pocket. COBRA lets you keep the exact same plan after a layoff, but you pick up the full premium yourself, plus a 2 percent administration fee, which for most people runs somewhere between $400 and $900 a month depending on the plan and the state.

A marketplace plan bought through a special enrollment period is usually cheaper, sometimes dramatically so once your lower income qualifies you for a premium tax credit. The trade-off is a different network and possibly a different deductible you’re starting over on. If you’re mid-treatment for something, or your spouse or kids have specialists tied to your current plan, that continuity might be worth the higher COBRA bill. If you’re healthy and just need a safety net, price out a marketplace bronze or silver plan before you default to COBRA out of habit. You have 60 days after your coverage ends to elect COBRA retroactively, so you don’t have to decide on day one, but don’t let that deadline sneak up on you while you’re busy with everything else on this list.

Check whether the WARN Act owes you 60 days of pay
Manufacturing engineer reviewing a tablet beside factory tanks and control equipment
Image Credit: Shutterstock

If your layoff was part of something bigger than just you, a plant closing, a round of mass layoffs, a division shut down, federal law may already be on your side. Companies with 100 or more employees are generally required to give 60 calendar days of written notice before a mass layoff affecting 50 or more people at one location, and the notice has to go to workers directly, not just to a union representative or a state office.

If your employer skipped that notice and didn’t qualify for one of the law’s narrow exceptions, such as an unforeseeable business circumstance or a natural disaster, it owes affected workers back pay and benefits for the days of notice they didn’t get, up to the full 60. This isn’t something that gets applied automatically. The Department of Labor enforces the notice requirement but doesn’t pursue damages on your behalf, so the burden falls on you or a lawyer to raise it, often through a wage claim or a lawsuit. Several states, including California, New York, Illinois and New Jersey, have their own WARN laws with lower thresholds, so a smaller layoff that wouldn’t trigger the federal version might still qualify under your state’s rules. It costs you nothing to check before you assume there’s no case here.

Don’t sign a severance agreement before the clock runs out
Woman reviewing paperwork with a calculator beside her laptop
Image Credit: Shutterstock

A severance offer usually comes with a release, a document where you agree not to sue your employer in exchange for the payout. If you’re 40 or older, federal law gives you real time to think it over before that release becomes binding, and the company isn’t allowed to rush you past it. You get 21 days to consider the offer on your own, 45 days if you’re part of a group layoff, and seven more days to change your mind after you’ve already signed.

The release also has to spell out, by name, that you’re giving up your right to bring an age discrimination claim under that specific law, not just a vague waiver of “all claims.” If your employer changes the offer in any meaningful way during that window, the clock is supposed to restart from the new offer, not the original one. None of this means you shouldn’t sign. Most severance agreements are fine, and most layoffs aren’t discriminatory. It means you shouldn’t sign on the day it lands in your inbox just because the email makes it sound urgent, and it’s worth a one-time conversation with an employment lawyer if the number seems low for your years of service or if you were one of several older employees let go in the same round.

Ask if outplacement is already sitting in your severance package
Worried older couple reading a letter beside an open laptop
Image Credit: Shutterstock

Outplacement, paid career coaching and job-search support funded by your old employer, is common enough now that most people who are eligible for it never find out it exists. Career transition help has become standard practice, to the point that 82 percent of U.S. companies now build some form of it into their severance packages, yet it’s rarely mentioned out loud in the termination meeting. It usually shows up as one line in the paperwork, or not at all until you ask.

Before you sign anything, ask HR directly whether outplacement is included and what it covers: a resume rewrite, interview coaching, LinkedIn help, a job-search portal, access to a recruiter network. If it’s not offered, it’s often one of the easier things to negotiate into a severance package, since it comes out of a different budget than cash severance and costs the company far less than another month of pay. A company that has already decided no to more money will frequently say yes to this instead, mainly because it looks better to everyone who’s still watching. Get the specifics in writing, including how long the service lasts, since some outplacement contracts quietly expire after three or six months whether you’ve used them or not.

Roll over your 401(k) without triggering a tax bill
Wooden 401k letters on financial paperwork beside a calculator and glasses
Image Credit: Shutterstock

Leaving an old 401(k) behind isn’t dangerous on its own, but cashing it out by accident is one of the more expensive mistakes people make after a layoff. The IRS gives you 60 days from the date you receive a distribution to deposit the full amount into another retirement account before the whole balance becomes taxable income for the year, plus a 10 percent penalty if you’re under 59 and a half.

A direct, trustee-to-trustee transfer sidesteps that deadline entirely, since the money moves straight from your old plan to an IRA or your new employer’s plan without ever passing through your hands. An indirect rollover, where your old plan cuts you a check, automatically withholds 20 percent for taxes, which means you have to come up with that missing 20 percent from somewhere else just to roll over the full original balance within the 60 days. Call your old plan’s administrator and ask specifically for a direct rollover, not a distribution. It’s one phone call that can be the difference between keeping your retirement savings intact and losing a chunk of it to the IRS over paperwork.

Reconnect with former managers and colleagues while they still remember you
Smiling woman talking on a phone beside her laptop
Image Credit: Shutterstock

The people most likely to help you land your next role are the ones who already know what you’re good at, and that window closes faster than people expect. A manager who left the company eight months ago still remembers your work clearly. The same manager five years from now barely remembers your name. Reach out within the first few weeks, not after you’ve exhausted every job board and finally decided to network as a last resort.

Keep the message specific and short: what happened, what you’re looking for next, and one clear ask, whether that’s an introduction, a reference, or just advice on a particular company. A vague “let me know if you hear of anything” rarely produces results, because it gives the other person nothing concrete to act on. If a former colleague landed somewhere interesting, ask them directly what the hiring process is actually like there rather than applying cold through the careers page. People are far more willing to help in the first month after a layoff than the sixth, partly because the situation still feels urgent to them too, so don’t save this step for when you’re already discouraged.

Stop blaming a robot for your resume getting ignored

Hands reviewing a printed resume beside a laptop displaying a resume
Image Credit: Shutterstock

The idea that an applicant tracking system automatically rejects three out of four resumes before a human ever looks at them is one of the most repeated numbers in job searching, and it isn’t true. A recent survey of recruiters using more than ten different hiring systems found that 92 percent said their software doesn’t automatically reject resumes over formatting, missing keywords, or a low match score. Most tracking systems just rank and organize applications; a human still decides who moves forward.

That’s actually better news than the myth, because it means a resume that gets ignored usually has a content problem, not a software problem. If you’re not hearing back, the likely culprits are a resume that lists duties instead of results, a title that doesn’t match what the job posting calls the role, or an objective statement nobody reads anymore sitting at the top where your strongest accomplishment should be. Fix those before you spend an evening trying to reverse-engineer an algorithm that the recruiters who actually run it say isn’t doing the rejecting you’ve been blaming it for. Save the real anxiety for the parts of the process you can actually control.

Rewrite your LinkedIn headline for keyword search, not vibes

Hands typing on a laptop with an email-envelope notification overlay
Image Credit: Shutterstock

Recruiters searching LinkedIn aren’t scrolling through profiles the way you’d browse a magazine. They’re running the same kind of search you’d run on any database, by typing in job titles and skills and filtering by what’s listed in your profile, not by reading your summary top to bottom and forming an impression. A clever, vague headline like “problem solver and connector of dots” is invisible to that kind of search, because it doesn’t match anything a recruiter would ever type in.

Put your actual target job title in your headline, along with two or three of the specific skills or tools that show up in the postings you want to apply to. Do the same in your skills section, since recruiters filter searches by those tags directly. This isn’t about writing for a machine instead of a person. It’s about understanding that the first step in getting noticed is showing up in a search result at all, and a profile full of personality with no searchable substance never gets that far. Update your current title the day you’re laid off, too. A LinkedIn profile that still lists you at your old job six weeks after you’ve left raises more questions than it answers.

Get retraining paid for through your state’s workforce program
Adults attending a class with an instructor
Image Credit: Shutterstock

Most people have no idea that free, federally funded job training exists specifically for workers who’ve been laid off, and that it’s run out of a physical office they’ve probably driven past dozens of times. Nearly 2,400 of these exist nationwide, and American Job Centers offer free resume help, job search assistance and a direct line to Workforce Innovation and Opportunity Act training funding, all paid for by the Department of Labor.

Walk in, or make an appointment, and ask specifically about WIOA-funded training for dislocated workers. If you qualify, the program can cover tuition for a short-term certificate or trade program in a field with real local demand, not just hand you a stack of job listings and wish you luck. Eligibility and funding amounts vary by state and by how the money has been allocated that year, so what one caseworker tells you in one county might differ from what another tells you two counties over. Ask directly whether you qualify as a “dislocated worker,” since that status often unlocks a different, better-funded bucket of money than the general training programs offered to everyone else.

Train for a trade that’s short on workers, not long on competition
Mechanic checking the oil dipstick under a car hood
Image Credit: Shutterstock

While plenty of office roles have more applicants than openings right now, the skilled trades have the opposite problem. The Bureau of Labor Statistics expects the country to need 77,400 more electricians by 2034, a 9 percent jump from current levels, with a 2024 median pay of $62,350. That’s a career most people enter through a paid apprenticeship rather than a degree, which means you earn while you train instead of taking on debt to get there.

An apprenticeship typically runs four to five years and combines on-the-job hours with classroom instruction, usually through a union, a trade school, or a contractor association. Pay starts well below that median but climbs steadily as you log hours, and the work itself, residential, commercial or industrial wiring, is largely insulated from the kind of software automation that’s reshaping a lot of white-collar jobs right now. If you’re coming from a field where the demand has dried up, the career change is bigger than most on this list, but it’s one of the few paths where age and steady hands are an asset rather than a liability, and where the retraining period comes with a paycheck attached from day one.

Train for a healthcare role that doesn’t take years of school
Smiling woman in green medical scrubs carrying a backpack and coffee outside
Image Credit: Shutterstock

The aging of the U.S. population is creating demand for in-home care faster than almost any other part of the economy, and it’s one of the few growth areas that doesn’t require a four-year degree to get started. Home health and personal care aide jobs are projected to grow 18 percent by 2035, with about 760,500 openings a year and a median pay of $35,800, and most positions ask for nothing more than a high school diploma, with training completed on the job or through a short certificate program.

The pay at entry level won’t replace a mid-career office salary, and the work is physically and emotionally demanding in ways a desk job isn’t, so this isn’t a fit for everyone who’s between jobs. But it’s a real, fast entry point if you need income now while you figure out your next move, or if you’re drawn to caregiving work specifically and want a sense of what full-time home health work is actually like before committing to something bigger, such as nursing school. Some states require a license or a competency exam for aides working through certified agencies, so check your state’s health department before you assume the job is open-and-apply.

Industrial machinery mechanic repairing an automated conveyor belt on a factory production line
Image Credit: Shutterstock

Temporary and contract work has a reputation as a last resort, but for a lot of people it’s a deliberate bridge rather than a backup plan. America’s staffing companies kept close to 2.2 million people working in temporary and contract roles in a typical week, and most of them took the work specifically to keep income coming in between one job and the next, not because they couldn’t find anything permanent.

A staffing agency can usually place you faster than a direct application, because the agency already has relationships with the companies doing the hiring and gets paid for filling the role quickly. Register with more than one agency in your field, since each one has different client relationships, and be specific with your recruiter about pay floor and how long an assignment needs to run to be worth your time. Plenty of temp-to-hire placements turn permanent once the employer sees your work firsthand, which can be an easier way in the door than competing against two hundred other applications for the same posted job. It also keeps a paycheck coming while you hold out for the right permanent offer instead of taking the first one out of desperation.

Turn your expertise into consulting with free help from SCORE

Older woman discussing paperwork with colleagues at a desk
Image Credit: Shutterstock

If you’ve spent fifteen or twenty years getting good at something specific, a layoff is one of the few moments where turning that into independent consulting actually makes sense, because you already have the track record and the industry contacts that take most people years to build. You don’t have to figure out how to structure it alone. SCORE, a nonprofit resource partner of the Small Business Administration with more than 10,000 volunteer mentors, offers free, one-on-one mentoring for as long as your business exists, not just for a single session.

A SCORE mentor can walk you through the unglamorous parts that stop most people before they start: setting rates, writing a simple contract, handling quarterly estimated taxes, and deciding whether to form an LLC. This path isn’t for everyone, and it works best in fields where companies already hire outside consultants, like finance, engineering, project management or specialized operations work, rather than fields that depend on a steady salary and benefits. But if former colleagues have already said some version of “I wish we could just hire you back for this one project,” that’s usually a sign the market for your expertise exists before you’ve even gone looking for it.

Use the job boards built for workers over 50
Older woman talking on a phone while using a laptop at home
Image Credit: Shutterstock

Age bias in hiring is common enough that most older job seekers have already felt it, whether or not anyone ever said it out loud. Research on the subject backs that up directly: two in three adults over 50 believe older workers face discrimination on the job, and 93 percent think age discrimination is common in hiring today. That’s exactly why a handful of job boards exist specifically to route you toward employers that have already said, in writing, that they want experienced workers.

AARP’s own job board matches you with companies that have signed a pledge committing to a multigenerational workforce, and it lets you filter by title, keyword and location the same way any other job board does. Other sites built around the same idea, such as RetirementJobs.com and the National Older Worker Career Center, skew toward companies that have gone out of their way to say age isn’t a mark against you there. None of this replaces a strong resume or a sharp interview, but it does mean you’re spending your energy applying to employers who’ve already shown they’re not going to quietly screen you out the moment they see your graduation year.

Check if you qualify for paid training through SCSEP
Older warehouse worker wearing a hard hat and scanning inventory beside a box
Image Credit: Shutterstock

If you’re 55 or older and your household income is tight, there’s a federal program built specifically for this situation that most people have never heard of. The Senior Community Service Employment Program pays the highest of the federal, state or local minimum wage for about 20 hours a week while you train at a nonprofit or government agency, as long as you’re unemployed and your family income sits at or under 125 percent of the federal poverty line.

The placements themselves run through schools, hospitals, day-care centers and senior centers, and they’re designed as a bridge into unsubsidized employment rather than a permanent arrangement, so you come out the other side with recent, verifiable experience and a reference instead of a resume gap. You can find a local SCSEP provider through your state’s aging services office or through CareerOneStop’s older worker program finder. It won’t replace a full-time salary, but it’s real paid work while you retrain, and it’s aimed at exactly the group that often gets the least attention in general job-search advice: workers over 55 who need both income and a credible answer to “what have you been doing since the layoff.”

Revisit your Social Security claiming age if this changes your timeline
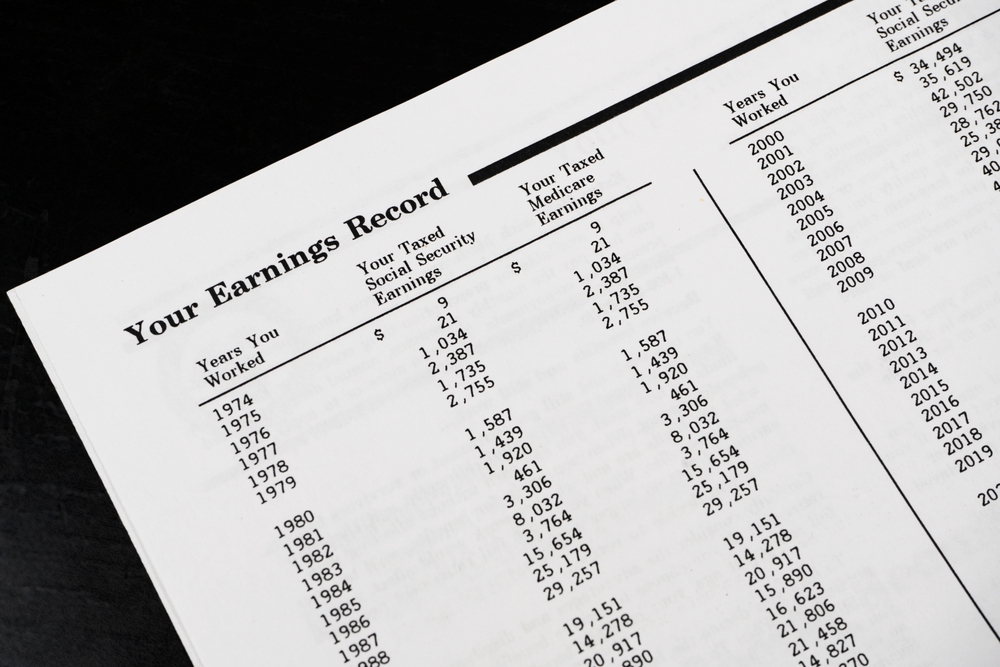
Close-up of a Social Security earnings record
Image Credit: Shutterstock

For anyone within a decade of retirement, a layoff forces a decision that usually would have waited: do you claim Social Security earlier than planned, or find a way to hold off? Every year you delay past your full retirement age adds a permanent increase to your monthly benefit, up until you turn 70, when the increase stops. Claiming early, as soon as 62, locks in a permanently smaller check instead.

There’s no universal right answer here, since it depends on your health, your other savings, whether you have a spouse whose benefit is tied to timing decisions, and how long you expect this gap in employment to last. What matters is not defaulting into either choice out of panic. If you can bridge the next few years with unemployment, part-time work, or savings, delaying even a couple of years can meaningfully raise your income for the rest of your life. If claiming now is what keeps you afloat, that’s a legitimate decision too, not a failure. Either way, run the numbers with the Social Security Administration’s own calculators before you decide, rather than guessing at what delay is actually worth in your specific case.

A layoff is a specific financial and legal situation with its own deadlines, not a verdict on your career. Work through it in the order it hits your bank account, and the rest of it gets a lot easier to plan.
The retirement paperwork arrives in a stack. A pension election form, a 401(k) rollover packet, and a Social Security application usually show up in the same week, often while you’re still packing up your desk. Most people sign all three the same afternoon, treating the Social Security form exactly like the other two: one more piece of paper to clear before the next chapter starts.

That habit is the first expensive one. Filing the day you’re eligible instead of waiting even a few years locks in a smaller check for the rest of your life, and there’s no later form that fixes it.

The first twelve months of retirement come loaded with decisions like that one: Medicare enrollment windows, a portfolio that still has to last thirty years, a budget built on guesses instead of a real paycheck. Get a handful of them wrong early and the cost compounds quietly for decades.

The exact size of that first cut is public information, calculated down to the month you file.

Filing for Social Security the moment you’re eligible

Close-up of a Social Security earnings record
Image Credit: Shutterstock

File at 62, the earliest age allowed, and your monthly benefit is reduced by as much as 30% compared with waiting for full retirement age, which is 67 for anyone born in 1960 or later. That reduction isn’t temporary. It’s built into every check for the rest of your life, and it carries over to what a surviving spouse collects after you’re gone.

Wait past full retirement age instead, and the benefit grows by 8% for every year you hold off, up to age 70. Someone whose full benefit would have been $2,000 a month gets roughly $2,480 by waiting the extra three years, and that increase is also permanent.

62 isn’t automatically the wrong call. Health, other income, and family longevity all factor in. But filing the week you retire, before running the numbers against your own expected lifespan and spending needs, is how people end up locked into a benefit that’s 30% smaller than it had to be, for decades they didn’t plan on living.

Assuming Medicare will cover more than it does

Woman taking US dollar bills from a wallet beside prescription medication
Image Credit: Shutterstock

A 65-year-old retiring this year should expect to spend an average of $185,500 on healthcare and medical costs over the rest of retirement, and that figure is per person, not per household, and doesn’t include a cent of long-term care.

More than half of people approaching retirement believe Medicare will cover all of their healthcare costs, and it won’t. Original Medicare still comes with premiums for Part B and Part D, a deductible, 20% coinsurance on most outpatient care, and no cap on what you can pay out of pocket in a bad year. Dental, vision, hearing aids, and most long-term care aren’t covered at all.

A health savings account, if you had access to one while you were still working, is one of the few ways to get ahead of this. Money goes in before taxes, grows tax-free, and comes back out tax-free for qualified medical costs, including Medicare premiums once you’re enrolled. The account has to be built before retirement, though, since contributing to one stops the moment you sign up for Medicare. Budget for a real number either way, not just the premium, and build in room for a bad year.

Missing your window to sign up for Medicare

Medicare enrollment form on a clipboard with a pen and stethoscope
Image Credit: Shutterstock

Medicare’s initial enrollment window runs seven months: three before the month you turn 65, that month, and three after. Wait two full years past that window without other qualifying coverage, and the Part B premium goes up by about $40 a month on top of the standard $202.90 2026 premium, a 20% late enrollment penalty that sticks around for as long as you have Part B.

The people who get caught out are usually still working past 65, assuming their job’s health plan keeps them covered. It does, but only if the employer has 20 or more employees. Retire from a smaller company, or retire at all, and that assumption can turn into years of penalty before anyone catches the mistake.

Mark the date your coverage actually changes, not the date you think you’ll decide, and sign up inside that seven-month window even if you’re unsure which parts you’ll use.

Getting hit with a Medicare surcharge you didn’t see coming

Medicare premiums chalkboard with prescription paperwork, medicine packs and a stethoscope
Image Credit: Shutterstock

The standard Medicare Part B premium is $202.90 a month in 2026, but that’s only what you pay if your income falls below the first threshold. Cross it, and the premium climbs in tiers, up to $689.90 a month for the highest earners, an extra $487 every month for the same Part B coverage everyone else gets.

The surcharge is based on your tax return from two years earlier, which is exactly what makes it a first-year trap. Your final full-time salary, a lump-sum payout, or a large capital gain from the year before you retired can trigger a higher premium in the first year or two you’re actually living on a fixed income, with no job income left to show for it.

If a one-time event like a retirement payout or a home sale pushed your income up temporarily, you can ask Social Security to use a more current income estimate instead of waiting for the surcharge to catch up with your real situation.

Blowing up your portfolio the first time the market drops

Stacks of coins with a globe and stock market chart overlay
Image Credit: Shutterstock

About half of people who’ve retired in the last five years have already changed their retirement portfolio because of market swings, and nearly as many say volatility has changed how they’re managing withdrawals altogether. New retirees make these moves at roughly double the rate of people who’ve been retired longer.

The reason the first few years matter more than any other stretch of retirement is something planners call sequence of returns risk. A downturn hits hardest right when the portfolio is at its largest and the most withdrawal years still lie ahead, because every dollar sold at a loss during that stretch is a dollar that can’t recover when the market eventually turns around. The same drop ten years into retirement, after the portfolio has already funded a decade of spending, does far less damage.

Keeping one to two years of expenses in cash or short-term bonds before you retire means a bad first year doesn’t force you to sell anything at the bottom. Overreacting to a single rough quarter by moving everything to cash usually does more long-term damage than the downturn itself.

Spending like the paycheck never stopped

Worried older couple reading a letter beside an open laptop
Image Credit: Shutterstock

Only 40% of recent retirees say they’re actually on track with the budget they set before retiring, and about one in five have already had to cut spending below what they’d planned, usually within the first couple of years.

The overspending usually isn’t reckless. It’s a kitchen renovation that got put off for a decade, a long-promised trip, help for an adult kid. Each one seems like a single, isolated decision, but run the numbers on what a modest overspend actually costs: go 20% over a $4,000 monthly budget for two years, about $800 extra a month, and that’s close to $19,200 pulled out of a portfolio before it’s had a single year to grow back. Stacked together before there’s a real sense of what a sustainable number looks like, decisions like that can eat years off a retirement meant to last three decades.

Treat the first twelve months as a trial budget instead of a victory lap. Track actual spending against a real withdrawal rate before committing to a renovation or a second home, not after.

Pulling money from the wrong accounts first

401K
Image Credit: Shutterstock

The common advice is to spend taxable brokerage accounts first, then traditional 401(k)s and IRAs, and leave Roth accounts untouched until last. It’s a reasonable starting point, but following it without exception can mean years of unnecessarily high taxes once required minimum distributions kick in and force large withdrawals all at once.

Every dollar pulled from a traditional IRA counts as ordinary income, and that income can also make more of your Social Security benefit taxable, a cost that doesn’t show up on the account statement itself. Wait too long to touch traditional accounts at all, and the bill arrives all at once: required minimum distributions start at age 73, and missing one brings a 25% penalty on the amount that didn’t come out.

A blended approach, pulling a bit from each type of account every year instead of draining one bucket completely before touching the next, tends to keep you in a lower bracket for longer and leaves more flexibility for the years RMDs actually arrive.

Every mistake on this list is fixable with enough lead time, which is exactly why the first year matters more than any other. Get the timing right once, on Social Security, Medicare, and your own withdrawals, and it keeps paying off for the next thirty years.

Learning a new skill as a single mom means choosing flexible, affordable, time-efficient education options. Perhaps you’re looking to earn more for your family, change careers, or finally finish your education. Whatever your motivation is, it’s possible to secure an education while juggling work and parenting on your own.

Most single mothers prefer online learning programs that are self-paced, as they can fit coursework into their busy schedules without feeling overwhelmed.

What online courses are best for single moms?

Online courses that combine remote-friendly careers, decent pay, and strong demand are ideal for single mothers. Some of the short courses or full degrees you can pursue to enrich yourself include the following.

Coding

Coding courses help single moms learn at their own pace. Employers in different fields are looking for experts who are knowledgeable about various programming languages and can create websites and software. Whether you’re a newcomer or have some experience in the coding field, you can take an online course to learn new languages and keep up with the latest technology.

Additionally, consider enrolling your child in an online coding class to help them gain the skills early. Coco Coders offers interactive coding classes for children every week. Kids from nine years old get a strong foundation in the field of computer science that they can use to create digital projects.

Digital marketing

For creative single moms and those who are comfortable navigating online, digital marketing is a great course to consider. With skills learned from digital marketing, you can write content, manage social media accounts, and build campaigns. Most of these tasks are done on a freelance basis, so single moms don’t have to stick to a fixed shift schedule.

IT and Cybersecurity

Information security, database administration, and cybersecurity are some of the tech-adjacent skills that not only pay well but also lean more towards hybrid or remote roles. According to the United States Bureau of Labor Statistics, the employment rate of information security analysts from 2025 to 2035 is expected to grow at 21%. This growth rate is much higher compared to other occupations.

Accounting

As a single mom, if you find yourself hunting down every deal and tracking every dollar, you can try delving into a career in accounting. Roles such as tax prep and virtual bookkeeping can be done in the comfort of your home. As an entry-level accountant, you’re assured of a solid median wage to sustain you and your kids.

How can you choose the right online course that suits you?

Finding the ideal online class depends on your long-term career objectives and schedule. Consider the following factors before enrolling:

Time commitment and flexibility

Go for self-paced online programs that allow you to work and cater to your children without disruption.

Employer recognition

If you’re looking to grow in your career or are in search of a job, pursue certifications recommended by companies in your area.

Funding of financial options

You can opt for online learning programs that offer payment assistance or scholarships.

Total cost

Before you start an online course, inquire whether they charge additional fees for extended access, exams, and certificates.

Career goals

If your major goal is finding employment, find courses that offer in-demand skills.

Why is it important for single moms to pursue education?

Pursuing new skills as a single mom not only benefits you but also the future of your children. Kids tend to follow in the footsteps of their parents, and teaching them to pursue their dreams is a good way to model their behavior.

  • Other benefits of enrolling in an online enrichment class include:
  • Improving your self-esteem and confidence, especially after a divorce
  • Growing your organizational skills and discipline
  • Better health insurance benefits for your family
  • Increasing your potential to earn more and afford the needs of yourself and your children
  • Long-term job security
  • Saving you money compared to joining a physical school

To ensure your success in online education, set up a plan that works for you and isn’t overwhelming. Start by dedicating a specific study time and area to prevent procrastination and build a routine. You can choose to study either early in the morning before your children get up or late at night when the house is quiet.

Also, set aside time to recharge to prevent burnout. Take a walk, engage in your favorite hobby, or read a book to maintain motivation as you juggle motherhood, work, and school.

Realize your dreams as a single mom with online enrichment classes

Pursuing an education when juggling motherhood by yourself is challenging but possible with the right support systems. Online learning fits into your busy schedule and can help you gain high-paying skills that can be done remotely. Set a specific time when your household is less busy to learn coding and other courses online.

Check out our page for more helpful articles for single mommies.

Being a single mom often means putting everyone else’s needs before your own. Between work, childcare, household expenses, and everyday responsibilities, celebrating your personal milestones can easily fall to the bottom of the list.

But recognizing your accomplishments doesn’t have to mean spending hundreds of dollars. From creating family traditions to preserving meaningful memories, there are plenty of affordable ways to celebrate your motherhood journey.

Here are six thoughtful ideas that can help you appreciate how far you’ve come while keeping your financial priorities in mind.

Create a memory box for your family’s milestones

A memory box is an affordable way to preserve important moments from your child’s early years.

Start with a container you already have at home. Add meaningful items such as your baby’s hospital bracelet, first outfit, birthday cards, or favorite photographs.

You can also include handwritten notes about important family milestones. Describe your child’s first words, a memorable birthday, or a funny moment you don’t want to forget.

Consider writing a letter about your own experience as a mother. Include the challenges you’ve overcome, the lessons you’ve learned, and the moments that made you proud.

As your child grows, the box becomes a collection of stories you can revisit together.

The best part is that creating one doesn’t require expensive supplies. A few carefully chosen keepsakes can be more meaningful than an elaborate scrapbook.

Build family traditions that don’t cost much

Family traditions create a sense of connection and give children something to look forward to.

For single moms, they can also be an opportunity to create routines that reflect your family’s unique personality.

You might plan a monthly movie night, cook a special breakfast on birthdays, or take a family photograph in the same location every year.

Outdoor activities are another affordable option. Visiting a local park, exploring a nature trail, or packing a picnic can become a memorable family experience.

Consistency matters more than cost.

Children often remember the time spent together rather than how much money was involved.

Over the years, these simple traditions can become some of your family’s most treasured memories.

Preserve meaningful memories of early motherhood

The first months with a baby can be exciting, exhausting, and emotionally intense.

For some mothers, breastfeeding is an especially meaningful part of that experience. It may represent moments of closeness, personal determination, or an important chapter in their relationship with their child.

Some moms preserve these memories through photographs, journals, or keepsakes.

Another option is personalized breast milk jewelry, which incorporates a small amount of preserved breast milk into a piece of jewelry.

For example, Mama Jewels offers breast milk jewelry designed to commemorate this period of motherhood.

Depending on personal preferences, a ring, necklace, or pendant can become a reminder of those early months.

Of course, every mother’s experience is different. Breastfeeding isn’t part of everyone’s journey, and meaningful memories can be preserved in many other ways.

The important thing is choosing something that reflects your own experience rather than feeling pressured to follow a particular tradition.

If you’re considering personalized jewelry, make sure the purchase fits comfortably within your budget. A sentimental keepsake should bring joy, not financial stress.

Celebrate personal achievements beyond parenting

Single motherhood involves responsibilities that aren’t always visible to others.

Managing household finances, balancing work and childcare, or successfully navigating a major life change can require considerable effort.

These accomplishments deserve recognition.

Start by keeping a list of personal milestones, including achievements that might seem small at first.

Maybe you’ve paid off a credit card, built an emergency fund, completed a professional course, or established a more manageable daily routine.

Writing these accomplishments down helps you recognize progress over time.

When you reach an important goal, choose an affordable way to celebrate. Enjoy your favorite meal, schedule a relaxing afternoon, or spend time doing something you love.

Celebrating yourself doesn’t have to involve buying something.

Sometimes acknowledging your progress is enough to make a milestone feel meaningful.

Choose thoughtful keepsakes instead of impulse purchases

Managing a household budget often requires making careful spending decisions.

That doesn’t mean personal purchases are off-limits. It simply means choosing items that offer lasting value to you.

Rather than purchasing several accessories you rarely wear, you might prefer saving for one meaningful piece.

A necklace featuring your child’s initials, a bracelet engraved with an important date, or a personalized photograph can all represent significant moments.

For mothers who want to commemorate their breastfeeding experience, personalized breast milk keepsakes from Mama Jewels are another option to consider.

Before purchasing any personalized item, think about how often you’ll use it, whether it suits your preferences, and whether the cost fits your financial situation.

It’s also worth reviewing customization details, care instructions, and return policies before ordering.

A meaningful purchase should be something you genuinely want, not something you feel obligated to buy.

And if a keepsake isn’t in your budget right now, there’s nothing wrong with waiting or choosing a free alternative.

Make time for your own interests and goals

Motherhood is an important part of your identity, but it doesn’t have to define every aspect of your life.

Maintaining personal interests can help you feel connected to the person you are outside your parenting responsibilities.

You might enjoy reading, exercising, learning a new skill, or spending time with friends.

Many of these activities can be adapted to a limited budget.

Local libraries offer free books and resources. Community organizations may provide affordable classes, while online learning platforms offer opportunities to explore new interests from home.

Even setting aside a short period each week for something you enjoy can make a difference.

It’s also worth thinking about your longer-term goals.

Whether you’re working toward financial independence, professional growth, or a personal ambition, taking small steps can help you build a future you’re excited about.

Meaningful celebrations don’t require a big budget

Single motherhood comes with challenges, responsibilities, and achievements that deserve recognition.

Whether you’re preserving family memories, creating traditions, celebrating financial progress, or choosing a personal keepsake, the most meaningful gestures don’t have to be expensive.

What matters is finding ways to acknowledge your experiences while staying true to your priorities.

A handwritten letter, a family photograph, or a simple afternoon spent together can hold just as much meaning as an expensive gift.

Celebrating motherhood isn’t about how much you spend. It’s about recognizing the life you’re building and the moments that make it yours.

California divorce has one fixed rule everyone learns fast: no matter how cooperative both spouses are, the process takes at least six months. That mandatory waiting period is set by California Family Code section 2339 and begins the day your spouse receives formal service of the divorce petition. But six months is the floor, not the ceiling. Many divorces take a year, two years, or longer, and if you’re currently in the process, you deserve a clear picture of why your timeline looks the way it does. Courts are busy, the financial disclosure requirements are real, and any disputed issue between you and your spouse adds procedural steps that compound over time. Whether you’re just starting out or already well into things, knowing what drives a California divorce timeline helps you plan your finances, your co-parenting schedule, and your legal approach with far more accuracy and a lot less frustration.

California’s 6-month waiting period and what it actually covers

California law requires a mandatory six-month waiting period before a divorce can be finalized, and this rule affects the overall timeline of the case. When researching the divorce process, couples may come across firms such as Duncan Family Law divorce lawyers alongside other family law practices that help people understand the legal requirements involved. The waiting period generally begins when the respondent is served with the divorce petition or makes their first appearance in court, whichever happens first. Delays in service can push back the earliest possible finalization date. Courts cannot waive this requirement, even if both spouses agree on all terms and complete their paperwork within the first two months. Understanding the rule early helps couples set realistic expectations and avoid unnecessary delays and expenses. 

What the disclosure requirements add to your timeline

The six-month period doesn’t just give spouses time to reconsider; it also gives both sides time to complete California’s mandatory financial disclosures. Each spouse must prepare and serve a Preliminary Declaration of Disclosure: a sworn statement covering income, assets, debts, and monthly expenses. These documents take real effort to get right, and errors or omissions can trigger objections from the other side, adding weeks or months to the process. A Final Declaration of Disclosure is also required unless both parties waive it in writing as part of a settlement.

In an uncontested divorce where both parties agree on everything, a couple might finish all the paperwork within the first two or three months and simply wait for the six-month mark before submitting a judgment package to the court. But even then, administrative delays at the courthouse often push the final judgment to seven or eight months from the service date. Honestly, that’s the best-case scenario for most people.

Uncontested vs. contested divorce timelines

Contested divorces – cases where spouses disagree on major issues like property division, spousal support, or child custody – take far longer than six months. California courts are overloaded, especially in large counties like Los Angeles, and contested cases require multiple hearings, formal discovery, and sometimes court-ordered mediation or evaluations before any trial date is even set. A contested divorce in Los Angeles County might not reach trial for 18 to 24 months after filing; complex cases can stretch past 36 months.

Every unresolved dispute adds at least one procedural step. And each step adds time. Even a single contested asset can trigger formal discovery requests, third-party appraisals, and expert depositions that push the case well past the one-year mark. The more issues left unresolved at the outset, the longer your case will run, and the more you’ll spend on legal fees before the court enters your final judgment.

Factors that commonly push your final judgment further out

Several specific circumstances extend California divorce timelines well beyond the six-month baseline, and most of them are predictable once you know what to look for. Some delays come from the court’s own scheduling constraints, but many are the direct result of contested issues, missing documentation, or incomplete financial disclosures from one or both spouses. Here’s the thing: even procedurally complete cases sometimes wait months for a judge to review and sign a judgment package, because California courts carry enormous caseloads. Knowing which factors apply to your situation lets you set realistic expectations, and in some cases, take targeted steps to address the delay directly rather than just waiting it out.

Complex assets and high-net-worth divorce cases

Property division is one of the most common reasons a California divorce blows past the six-month minimum. California is a community property state, which means assets and debts acquired during the marriage generally belong equally to both spouses – but identifying, valuing, and dividing those assets takes time, especially in high-asset cases. A family business requires a formal valuation by a certified financial expert. Stock options, restricted stock units, and deferred compensation packages need careful analysis under California’s time-rule apportionment formula. Retirement accounts require a Qualified Domestic Relations Order – commonly called a QDRO, to divide without triggering immediate tax penalties.

Each of these steps involves third-party professionals whose schedules don’t align neatly with court deadlines. And if one spouse is suspected of hiding assets, the discovery process – subpoenas, forensic accounting, expert depositions – can add six months or more on its own. The truth is, high-net-worth divorces in California routinely run two to three years from filing to final judgment. That’s not an outlier; it’s the norm for genuinely complex estates.

Child custody disputes and their ripple effect

Custody disagreements are another major driver of delay. If parents can’t agree on a parenting plan, a California family court judge may order a child custody evaluation, a formal investigation carried out by a licensed mental health professional who interviews both parents, the children, teachers, and others in the child’s life. These evaluations take three to six months to complete, and court scheduling piles even more time on top of that. After the evaluator files a report, each parent has the right to challenge its findings, which can trigger additional hearings before the court resolves the custody question.

Child support in California is calculated directly from the custody arrangement, so an open custody dispute keeps the support issue open too. Temporary orders can address day-to-day arrangements while the case moves forward, but they aren’t the final judgment. Until the court permanently resolves both custody and support, your divorce can’t close; a custody fight therefore has an outsized effect on how long a divorce takes in California overall.

Conclusion

A California divorce takes at least six months from the date your spouse is served, and contested cases involving property disputes, business valuations, or custody disagreements routinely take one to three years. The factors that delay a final judgment are almost always tied to unresolved disputes, incomplete financial disclosures, or court scheduling backlogs that no individual controls entirely. If you want to understand how long a divorce takes in California given your specific circumstances, the most direct step is a conversation with a licensed family law attorney in your county, someone who knows the local court’s pace and can assess your actual risk factors. General timelines give you a useful framework, but your assets, your co-parenting situation, and your spouse’s willingness to cooperate are what determine how long your case actually runs. This article provides general information only, not legal advice, and doesn’t create an attorney-client relationship. Always consult a qualified attorney licensed in California for guidance on your situation.

Managing home upkeep on a single income requires deliberate prioritization and sharp vigilance. When you manage a property alone, roofing vulnerabilities stay hidden out of sight until discoloration spots spread across your living room ceiling. Neglecting small wear today leaves you vulnerable to sudden four-figure emergency invoices that strain your personal finances.

Developing a consistent inspection routine preserves your living space and guards your largest financial investment. By identifying small exterior issues before water reaches your interior framing, you protect your monthly cash flow and command full control over maintenance costs.

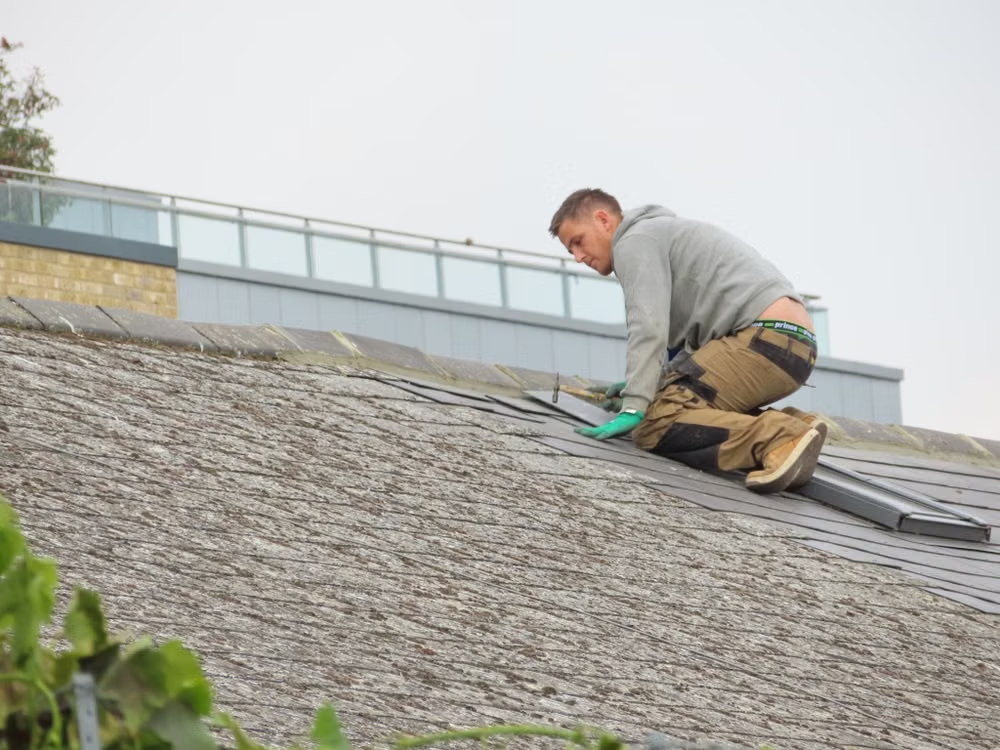
Discover how routine inspections and preventive roof maintenance can help solo homeowners save money.
Image Credit: Keith via Pexels

Why should you prioritize targeted repairs over costly replacements?

National roofing franchises frequently push full tear-offs because their sales models favor high-volume replacements over small maintenance orders. Partnering with a reliable, locally owned roofer handling repairs gives you transparent evaluations and pinpoint fixes tailored to your home’s immediate condition. Regional professionals value long-term neighborhood relationships and understand local climate patterns far better than transient commission-driven sales teams.

That community focus keeps your repair bills fair and prevents unnecessary construction on an otherwise healthy structure. Honest trade professionals identify whether your shingles possess remaining functional life.

If an isolated windstorm ripped off a ridge cap or lifted two perimeter shingles, a focused restoration protects your home without forcing you to finance a complete reroof. Preserving sound materials keeps money in your pocket while maintaining complete weather resistance against seasonal storms.

What makes subtle roof damage a serious financial threat?

Water follows the path of least resistance, slipping under lifted asphalt shingles and pooling along structural rafters long before dripping onto drywall. Since attic crawl spaces rarely receive weekly visits, damp insulation quietly loses thermal resistance while mold colonies take root. You end up paying higher heating bills while moisture rots your plywood sub-decking silently above your head.

Minor deterioration never cures itself under blistering sun and freezing winter rains. An ignored plumbing vent boot or warped flashing piece creates an open pathway for persistent seepage. When rafters soften, standard spot patching no longer solves the problem, forcing you into extensive structural repairs that overwhelm an individual salary.

How do minor flaws escalate into massive invoices?

Catching exterior flaws during early stages keeps your maintenance budget predictable. Data compiled by Gigngo indicates that fixing isolated leaks runs between $150 and $500, while repairing damaged shingles costs $200 to $600. Complete roof replacements require steep commitments between $5,000 and $15,000 or more. Addressing individual shingles keeps your existing roof deck sound and protects your hard-earned bank balance.

Replacing a cracked neoprene collar on a plumbing vent stack costs a fraction of extensive remediation. Neglecting that broken rubber seal allows driving rain to bypass the shingle surface and saturate the surrounding wood decking.

Once moisture compromises the roof deck, crews must tear away large sections, remove wet insulation, and install fresh framing lumber. A task that requires a modest service call transforms into a multi-day construction headache that commands thousands of dollars.

How can you screen contractors without pressure?

Talking to contractors alone can sometimes feel intimidating when representatives push limited-time discounts or demand immediate signatures. Guard your authority by establishing clear communication rules before anyone climbs onto your roof. Reputable specialists welcome questions, present clear diagnostic photos, and give you space to review paperwork on your own schedule.

Walk through these verification benchmarks before approving any exterior repair contract:

  • Verify general liability: Demand a current certificate of insurance naming your address to guard against accidental property damage.
  • Examine state licensure: Check your state licensing board website to confirm active status without pending disciplinary actions.
  • Request itemized proposals: Insist on detailed estimates that separate individual labor fees, material expenses, and cleanup provisions.
  • Check independent reviews: Read multi-year feedback across community forums and local consumer bureaus to measure reliability.

How should you budget for exterior upkeep on one income?

Building a dedicated maintenance reserve provides financial peace when seasonal weather strikes. Homeownership advisors frequently recommend stashing 1% to 2% of your property value each year in a high-yield savings account designated solely for home systems. Automating small monthly transfers into this exterior fund transforms looming repairs from panic-inducing emergencies into planned operating expenses.

Knowing how your insurance policy handles exterior damage helps you avoid sudden out-of-pocket shocks.

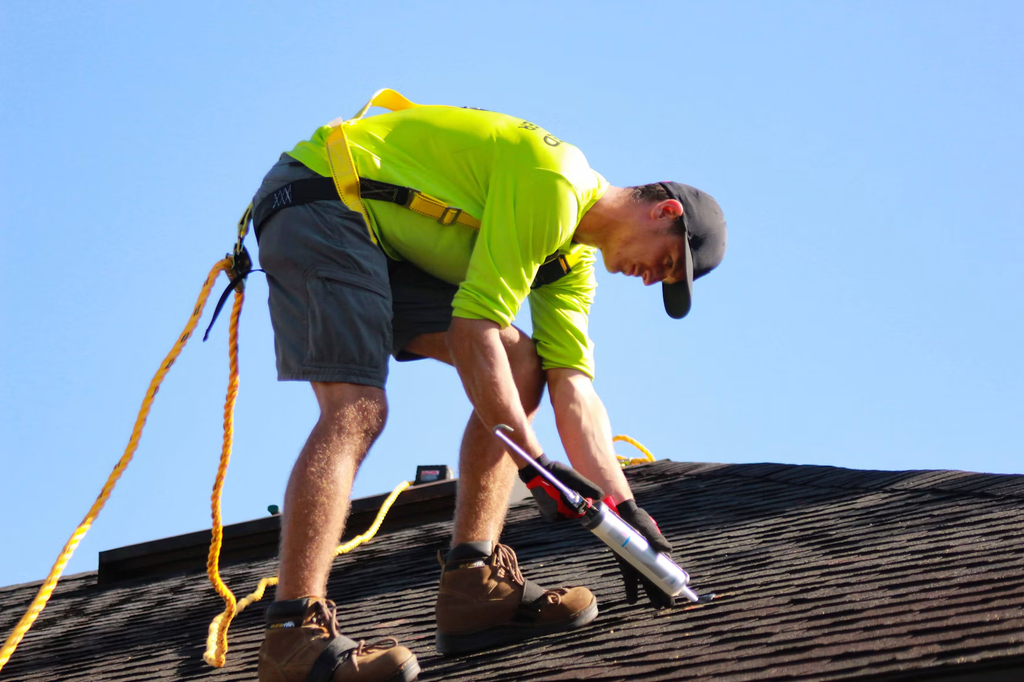
Consumer bulletins from the Maryland Insurance Administration remind homeowners that policies may cover repairs for damaged roof sections alone rather than total surface replacements.

Image Credit: Raze Solar via Unsplash

What preventative habits protect your home year-round?

Simple ground-level inspections give you valuable warning signs before water breaches your living areas. Grab a pair of binoculars twice each year to scan shingle lines, focusing closely on chimney flashing, valley intersections, and eave edges. Spotting curling tabs, moss buildup, or granule bald spots early gives you ample time to arrange affordable localized maintenance.

Educating yourself on roofing components gives you the power to protect your home equity with complete certainty. When you understand your exterior structure, you make knowledgeable maintenance decisions and hire honest specialists without intimidation.

Consistent preventative habits eliminate costly surprises, preserving your hard-earned financial independence and keeping your shelter sound through every coming season.