Your Medicare mail is starting to show up, and this year it comes with an unusually good headline. The average Medicare Advantage premium is projected to fall from $14.37 a month in 2026 to $12 in 2027, a drop of 16.5%.
That’s the kind of number that shows up in headlines everywhere this time of year, and for good reason. It’s also not the number that will land on your own statement, because it isn’t describing any one plan. It’s an average across every Medicare Advantage plan in the country, weighted by how many people are expected to sign up for each one.
Open enrollment for Medicare runs from October 15 through December 7 this year, and the premium number is the easiest thing to compare and the one most likely to mislead you if you stop there. Here’s what it actually measures, where your own costs could move in a different direction, and what’s worth checking instead before you pick a plan.
The weighted average covers every Medicare Advantage plan in the country, including plans that bundle in prescription drug coverage and Special Needs Plans built for people with specific chronic conditions. Each plan’s premium gets weighted by how many people are expected to enroll in it, so a popular plan with a $0 premium pulls the national number down a lot further than a small, expensive plan pulls it up.
That makes the average a decent way to describe Medicare Advantage as a whole. It says plans are staying competitive on price across the country. It says nothing about the plan sitting in your mailbox right now, because your plan is one line in a spreadsheet with thousands of other lines, not the average of all of them.
The projection also includes rebates insurers use to buy down prescription drug costs within a plan, which can shrink a plan’s advertised premium without changing what you actually pay for care. Two plans with the same $12 sticker price can still charge very different amounts once you add up deductibles, copays, and the drugs you actually take.
Why your own premium could move in the opposite direction
Image Credit: Shutterstock
About 8 in 10 Medicare Advantage beneficiaries will be able to keep their current plan at the same premium or lower in 2027. Flip that statistic around and roughly two in 10 won’t, and the difference shows up clearly once you look state by state instead of nationally.
In Wyoming, the average Medicare Advantage premium is set to climb from $45.91 to $69.23 a month. Idaho’s average is rising from $27.81 to $37.93, and Connecticut’s is going from $16.89 to $25.31. On the other side, some of the steepest drops are expected in Minnesota, where the average is falling from $69.11 to $59.40, in the District of Columbia, where it’s dropping from $26.28 to $16.91, and in Mississippi, where it’s falling from $11.18 to $4.08. A national average smooths all of that into a single headline number. Your own premium depends on your state, your county, and the specific plan you choose, not the country as a whole.
The bigger drop is in prescription drug coverage, not the plan premium
Image Credit: Shutterstock
The number with real money behind it this year belongs to prescription drug coverage bundled into Medicare Advantage plans. For plans that include drug benefits, the average monthly drug premium after rebates is projected to fall from $11.32 to $7, a 38% decrease. That’s the change doing most of the work behind this year’s good headlines, and it matters more to most people’s wallets than the plan premium itself.
Stand-alone Part D plans, the kind people on Original Medicare buy separately, are moving the other way, rising less than a dollar, from $35.09 to $36. A bigger number sits past the premium altogether. The standard Part D deductible is climbing from $615 to $700, and the annual cap on what you pay out of pocket for covered drugs is rising from $2,100 to $2,400, the largest increase either figure has seen since Part D began. A lower premium doesn’t do much for you if you’re someone who reaches that deductible by February.
Plan access remains wide, but hundreds of thousands are losing their current plan
Image Credit: Shutterstock
On paper, choice looks steady. More than 99% of Medicare beneficiaries will have at least one Medicare Advantage plan available to them, and 97% will have 10 or more to pick from. The total number of plans offered nationally is barely moving, from 5,553 down to around 5,532.
Underneath that, Humana is exiting plans that cover around 600,000 of its own members for 2027, mostly plans rated 3.5 stars or lower, and other large insurers are trimming their Medicare Advantage lineups too. Nearly 3 million seniors had to find a new Medicare Advantage plan last year even while premiums stayed low. A plan getting cheaper and a plan getting discontinued are different problems, and this fall both are landing in mailboxes at the same time. If your plan is one of the ones leaving your area, you’ll get a non-renewal notice directly from your insurer, and you’ll need to pick new coverage before the window closes on December 7.
What actually matters beyond the premium this open enrollment
Image Credit: Shutterstock
The premium is the number plans lead with because it’s the easiest one to compare at a glance, and it’s also one of the smallest pieces of what most people spend on health care in a year. Before renewing anything or switching anything, pull out your plan’s Annual Notice of Change letter and check four things specifically: your out-of-pocket maximum, whether your actual prescriptions are still covered at the tier you’re used to, whether your doctors and hospital are still in network, and whether supplemental benefits like dental, vision, and hearing have changed.
Medicare’s Plan Finder tool lets you compare those details for your own ZIP code instead of the national average, and 1-800-MEDICARE has people who will walk through the comparison with you for free. A plan with a smaller premium attached to a dropped doctor or a higher drug bill isn’t actually the better deal. It just moves the cost to a part of the year you’ll notice less right away.
Retirees got a 2.8% cost of living raise on their Social Security checks for 2026, and it still isn’t keeping up with grocery and heating bills that climbed faster than that. If your fixed income buys less every month than it used to, you’re not imagining it.
The frustrating part is how much money retirees leave unclaimed simply because nobody mentioned it was available. Nearly 9 million older adults who qualify for food assistance never apply for it, missing out on more than $2,000 a year on average. Millions more are paying full Medicare premiums they could be getting covered, or letting a tax credit built specifically for their age group go unused.
Some of what follows is a one time move. Some of it is worth thousands of dollars spread out over several years. None of it requires a financial advisor, just a phone call or a form most people never got around to looking up.
Waiting even one extra year to claim Social Security can make a real difference to your monthly check, permanently. Social Security adds 8% to your benefit for every year you delay claiming past your full retirement age, up to age 70. For most people retiring now, full retirement age is 67, which means someone who waits from 67 to 70 ends up with a noticeably bigger check for the rest of their life.
That’s not realistic for everyone. If you need the income now, or your health makes waiting risky, claiming early is still the right call for you. But if you have savings or part time work that can cover your expenses for a few more years, running the numbers on a delay is worth the time. A few hundred extra dollars a month, for the rest of your life, adds up fast.
Call Social Security directly, or use the agency’s online estimator, to see what your benefit looks like at different claiming ages before you decide anything. Whatever number you lock in follows you for the rest of your life, so it’s worth the extra half hour now.
Know your 2026 earnings limit before you go back to work
Image Credit: Shutterstock
If you claimed Social Security early and you’re thinking about picking up part time work, there’s a number you need to know first. For 2026, if you won’t reach full retirement age at any point during the year, Social Security withholds $1 in benefits for every $2 you earn above $24,480. In the calendar year you actually reach full retirement age, the limit jumps to $65,160, and the penalty eases to $1 withheld for every $3 earned above that, counting only the months before you hit the milestone.
This isn’t a tax. It’s money Social Security holds back and eventually pays you back, spread out after you reach full retirement age, through a higher monthly benefit. But in the moment, it can feel like a serious pay cut if you didn’t see it coming, especially if you take a seasonal job expecting a certain paycheck and the withholding shows up instead.
Once you reach full retirement age, the limit disappears completely. You can earn any amount from work without losing a cent of your Social Security check. Knowing where that line falls before you accept a new job, or decide how many hours to take, saves you from an unpleasant surprise the following spring.
Factor in this year’s cost of living bump
Image Credit: Shutterstock
Social Security benefits went up 2.8% for 2026, pushing the average retiree’s monthly check to roughly $2,071. That’s an extra amount most months won’t even notice, but it does change a few things worth paying attention to.
First, if you’re on a Medicare Savings Program or Extra Help, a higher benefit could nudge your income closer to the eligibility limit for those programs. It’s worth checking where you land after the increase, not before. Second, if you have a Medicare Advantage or Part D plan with a premium deducted straight from your Social Security check, you may have noticed your deposit didn’t rise as much as expected. Premiums and the cost of living adjustment often land in the same month, which can make the raise look smaller than it actually was.
The adjustment is calculated every year based on inflation data, and it rarely keeps pace with real cost increases for the things retirees actually spend money on, especially health care and housing. Treat it as a small cushion, not a solution, and keep checking whether you still qualify for the programs below that have their own income cutoffs.
Get Extra Help paying for your prescriptions
Image Credit: Shutterstock
Extra Help is a federal program that pays most of the cost of Medicare’s prescription drug coverage for people with modest income and savings, and a lot of retirees who qualify never apply because they assume it’s only for people on full Medicaid. It isn’t. For 2026, you can qualify with an annual income under $23,940 if you’re single, or $32,460 if you’re married, along with resources under $18,090 for an individual or $36,100 for a couple. Resources means money in the bank and investments, not your home or car.
If you qualify, Extra Help covers most or all of your Part D premium and deductible, and it caps what you pay for each prescription at a low, fixed amount instead of the percentage based costs most people face. For someone taking several maintenance medications, that can mean the difference between a drug bill that eats into groceries and one that barely registers.
You apply through Social Security, not through your drug plan, and the application takes most people under half an hour. Even if you’re not sure you qualify, apply anyway. Being turned down costs you nothing, and plenty of people who assumed they’d earn too much find out they were wrong.
Ask about a Medicare Savings Program for your Part B premium
Image Credit: Shutterstock
Every month, $202.90 comes out of most retirees’ Social Security checks automatically to cover the standard Medicare Part B premium, whether they notice it or not. A Medicare Savings Program can cover that premium for you, and depending on which tier you qualify for, it can cover your deductibles and coinsurance too.
There are three tiers based on monthly income. The Qualified Medicare Beneficiary program, for individuals earning up to $1,350 a month or couples up to $1,824, pays your Part B premium plus most other Medicare costs. The Specified Low-Income Medicare Beneficiary program, for individuals up to $1,616 or couples up to $2,184, covers just the Part B premium. The Qualifying Individual program, for individuals up to $1,816 or couples up to $2,455, also covers only the Part B premium, but funding is limited and you have to reapply every year. Resource limits for all three sit around $9,950 for an individual and $14,910 for a couple, not counting your home.
These programs run through your state’s Medicaid office, not Social Security or Medicare directly, which is part of why so many eligible people never sign up. Contact your state Medicaid office or your local State Health Insurance Assistance Program to apply. Getting $202.90 back every month is real money, and it’s the kind of application most people regret not filing sooner.
Mark your calendar for Medicare’s fall shopping window
Image Credit: Shutterstock
Between October 15 and December 7 each year, you can switch Medicare Advantage plans, switch Part D drug plans, or drop Medicare Advantage and go back to Original Medicare, no questions asked and no medical underwriting required. Most retirees let this window close without doing anything, either because the renewal letter from their plan went straight into a drawer, or because switching plans seems like more trouble than it’s worth.
It’s worth the trouble more often than people think. Drug formularies change every year, meaning a medication that was cheap last year can suddenly cost hundreds more under the same plan, while a competing plan covers it at a fraction of the price. Premiums, networks, and extra benefits like dental or vision coverage shift too, sometimes dramatically, and the only way to know if you’re still on the best plan is to actually compare.
Medicare’s plan finder tool lets you enter your specific medications and preferred pharmacy, then ranks plans by your actual expected annual cost, not just the premium. Spend thirty minutes with it every October before the window closes on December 7. If your current plan still wins, you’ve lost nothing. If it doesn’t, you’ve likely just saved yourself hundreds of dollars for the coming year.
Check whether your Medicare Advantage plan comes with a grocery or utility card
Image Credit: Shutterstock
A growing number of Medicare Advantage plans load a prepaid debit card with a set amount of money every month or every quarter that you can spend on groceries, over the counter items like pain relievers and vitamins, or in some cases utility bills. These are usually called flex cards or OTC cards, and plenty of people who have one don’t realize what it covers, or that unused funds often don’t roll over to the next period.
Not every Medicare Advantage plan offers one, and the ones that do vary enormously in how much they load and what you’re allowed to buy with it. Some restrict spending to specific pharmacy chains or a narrow list of approved items. Others are far more flexible and work at any major grocery store. If you’re not sure whether your plan includes this benefit, check your plan’s evidence of coverage document or call the member services number on the back of your card.
If your current plan doesn’t offer a flex card and a competitor does, that’s worth weighing during open enrollment alongside premiums and drug coverage. A few hundred dollars a year in groceries is easy to overlook next to bigger numbers like premiums and deductibles, but it’s real spending money that otherwise comes straight out of your pocket.
Apply for help with your heating and cooling bill
Image Credit: Shutterstock
The Low Income Home Energy Assistance Program, known as LIHEAP, helps cover the cost of heating in the winter and cooling in the summer for households that qualify, and older adults are named as one of the groups the program specifically prioritizes. It can pay toward your utility bill directly, help in a heating or cooling emergency, and in some cases fund weatherization work like insulation or a furnace repair that lowers your bills going forward.
There’s no cost to apply, and the program explicitly warns that anyone asking for a fee to help you apply is running a scam. Funding comes through your state, so how much is available and exactly who qualifies varies depending on where you live, but income limits are usually set well above the poverty line specifically so that more people qualify than you’d expect.
You can find your state’s LIHEAP office and application through the national energy assistance referral line, or by searching your state name along with LIHEAP. If your heating bill has been creeping toward the top of your monthly budget, or you’ve been putting off running the air conditioner because of what it costs, this is the kind of help that exists for exactly that situation. Apply before the coldest or hottest months hit, since some states run out of funds.
Find out if you’re one of the millions skipping free food money
Image Credit: Shutterstock
Close to 9 million older adults who qualify for SNAP never apply for it, missing an average of $2,256 a year in grocery help that could cover a meaningful chunk of a retiree’s food budget every single month.
A lot of the people skipping this benefit assume their Social Security check puts them over the income limit, or that applying means a complicated process better suited to younger families with kids. Neither is necessarily true. SNAP eligibility depends on your household size and income, and many retirees living on Social Security alone, or Social Security plus a small pension, fall well within the limits in their state. The application also allows deductions for medical expenses and housing costs that can push someone who looks over the limit back under it once those are factored in.
Benefits load onto an EBT card you use like a debit card at most grocery stores, and the amount depends on your specific household finances. If you’ve never applied because you assumed you wouldn’t qualify, or because you didn’t want to deal with the paperwork, it’s worth a second look. The application takes under an hour, and the downside of applying and being denied is exactly nothing.
Buy the senior pass that pays for itself on one road trip
Image Credit: Shutterstock
If you’re 62 or older, the National Park Service sells a lifetime pass for $80 that covers entrance fees at more than 2,000 federal recreation sites, including every national park, for the rest of your life. There’s also an annual version for $20 if you’d rather test it out before committing, though at that price the lifetime pass pays for itself after just two or three visits to parks that typically charge $20 to $35 per carload.
The pass covers the pass holder and everyone in their vehicle at sites that charge per vehicle, or the pass holder plus three adults at sites that charge per person. It also gets you a discount on some camping fees and tours run by the Park Service itself, though not on fees charged by outside concessionaires running things like boat tours or lodges inside the parks.
You can buy it online, by mail, or in person at any staffed federal recreation site, and you’ll need some proof of age and residency or citizenship. For retirees who like to travel, or who are finally getting around to visiting parks they’ve been meaning to see for decades, this is one of the cheapest forms of entertainment the federal government sells, and it never expires.
Call your local Area Agency on Aging
Image Credit: Shutterstock
Every region of the country has an Area Agency on Aging, a local office funded to help older adults stay independent in their own homes for longer. What they offer varies by location, but it commonly includes home delivered meals through programs like Meals on Wheels, help with light housework through homemaker assistance programs, and connections to whatever other local resources exist in your specific area.
Most people have never heard of their Area Agency on Aging because nothing prompts you to look for it. There’s no single national ad campaign, no letter that arrives automatically, and the name itself sounds bureaucratic enough that people assume it’s only for someone in worse shape than they are. In practice, these offices exist precisely so that retirees don’t have to wait for a crisis before getting support.
The easiest way to find yours is the Eldercare Locator, a free national service that connects you to the agency covering your specific address with one phone call or a quick search. If you’re managing a long list of small, draining tasks on a fixed income and a limited amount of energy, a single call to find out what’s available locally is worth the ten minutes it takes.
Dial 211 or run a BenefitsCheckUp
Image Credit: Shutterstock
Two free tools exist specifically to cut through the confusion of figuring out what you qualify for, and most retirees have never used either one. Dialing 211 connects you to a local, confidential helpline that can point you toward help with bills, food, housing costs, utility costs, and health care costs in your specific area, run by people who know what’s actually available where you live rather than a generic national list.
BenefitsCheckUp, a free online tool from the National Council on Aging, checks your answers about income, location, and situation against close to 2,000 federal, state, and local benefit programs to show you which ones you likely qualify for, covering everything from food and medicine to utilities and health care. No registration is required, and it’s available in English and Spanish.
Neither of these costs anything, and neither one tries to sell you anything afterward. If you’ve read through several items on this list and found yourself unsure whether you’d actually qualify for Extra Help, a Medicare Savings Program, or LIHEAP, running your situation through BenefitsCheckUp once is faster than researching each program’s rules separately. It will tell you where to apply once it finds a match.
Claim the tax credit built for people your age
Image Credit: Shutterstock
There’s a federal tax credit built specifically for people 65 and older, or for people who are permanently and totally disabled, and most eligible filers have never heard of it because tax software doesn’t always flag it automatically. It’s called the Credit for the Elderly or the Disabled, and you claim it on Schedule R when you file your return.
The credit phases out based on income, so it’s aimed at retirees with modest earnings rather than anyone with a large pension or significant investment income. Single filers lose eligibility once their adjusted gross income passes $17,500, married couples filing jointly lose it at $20,000 if only one spouse qualifies or $25,000 if both do, and the threshold is lower for married people filing separately. There’s also a separate limit on how much nontaxable Social Security or pension income you can receive and still qualify.
The credit itself works out to 15% of a base amount after those income limits are applied, which can mean a few hundred dollars off your tax bill depending on your specific numbers. It won’t change anyone’s life on its own, but it’s money the IRS makes available precisely for people in your situation, and skipping it because you assumed you wouldn’t qualify is the only way to guarantee you get nothing from it.
Use a qualified charitable distribution to shrink your tax bill
Image Credit: Shutterstock
If you’re 70 and a half or older, charitably inclined, and sitting on a traditional IRA, a qualified charitable distribution lets you send money straight from your IRA to a qualifying charity without it ever counting as taxable income. For 2026, you can give up to $111,000 this way, or up to $222,000 combined if you’re married and both spouses have IRAs and make their own qualified charitable distributions.
The real advantage shows up once you’re required to take minimum distributions from your IRA, usually starting at 73. A qualified charitable distribution counts toward satisfying that year’s required minimum distribution, but because the money goes directly to the charity rather than into your bank account first, it never shows up as income on your tax return. That matters more than it sounds like it should, because a lower adjusted gross income can also help keep you under the thresholds that trigger higher Medicare premiums or taxation of your Social Security benefits.
The money has to move directly from your IRA custodian to the charity, not through your own hands first, or it loses the tax benefit entirely. Most custodians can set this up with a simple request, often by mailing a check directly to the charity on your behalf. If you were planning to donate money this year anyway, routing it this way instead of writing a personal check can save you real money in taxes you’d otherwise owe.
Grab the bigger retirement catch-up if you’re 60 to 63
Image Credit: Shutterstock
If you’re still working and contributing to a 401(k) or similar workplace retirement plan, 2026 comes with a specific advantage for anyone turning 60, 61, 62, or 63 this year. The standard contribution limit is $24,500, and most people 50 and older can add a catch-up contribution of $8,000 on top of that, for a total of $32,500. But workers who are 60 to 63 specifically get a bigger catch-up of $11,250 instead, bringing their total possible contribution to $35,750 for the year.
This window closes the year you turn 64, when the catch-up amount drops back down to the standard $8,000 level available to everyone else 50 and older. If you’re in your early sixties, still earning a paycheck, and have the cash flow to contribute more without hurting your current budget, these four years are the single biggest opportunity you’ll get to pack extra money into a tax advantaged account before retirement.
Not every employer’s plan is set up to accept the higher amount automatically, so check with your HR department or plan administrator before assuming it’s happening on its own. For anyone behind on retirement savings and still earning an income, this is one of the most direct ways the tax code currently rewards catching up late, and it’s only available for a few specific years of your life.
Consider a move to a state that leaves your Social Security alone
Image Credit: Shutterstock
Most states don’t touch your Social Security benefit at all once it hits your bank account. As of 2026, only eight states still tax it to any degree: Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah, and Vermont, and most of those offer exemptions based on income or age that let many retirees avoid the tax anyway.
That leaves 42 states plus the District of Columbia where your Social Security check is simply yours, with no state level tax taken off the top. If you’re already weighing a move for other reasons, cost of living, proximity to family, climate, it’s worth checking whether your destination state is one of the eight before you commit. Even within states that do tax Social Security, the actual bite is often small once exemptions are applied, so it shouldn’t be the only factor in a decision this big.
State income tax on Social Security is also just one piece of the full picture. Some states with no tax on Social Security make up for it with higher property taxes or sales taxes, so a state that looks ideal on this one measure alone can still end up more expensive overall. Treat this as one factor to check, not a reason by itself to pack up and move somewhere new.
Sell the silver and gold sitting in a drawer
Image Credit: Shutterstock
Silver is trading at roughly $57 an ounce right now, and gold is sitting above $4,160 an ounce, both near record territory. If you’ve got old silverware, jewelry you don’t wear, a few inherited coins, or anything else that might contain real silver or gold sitting in a drawer, prices like these make it one of the better times in years to actually sell.
A full set of sterling silver flatware can be worth several hundred dollars to well over a thousand once you weigh it against today’s prices, and that’s before accounting for any added value from a desirable pattern or maker. Gold jewelry gets weighed and valued the same way, based on its purity and weight rather than what you originally paid for it or what it might be worth to a collector. Reputable buyers will tell you upfront that they’re paying based on melt value unless a piece has genuine collectible worth beyond its metal content.
Before you sell anything, confirm what you actually have. Sterling silver is stamped 925, and anything silver plated is worth far less than true sterling, so check for a hallmark before you get your hopes up about a full set’s value. Prices on precious metals move daily, so get a current quote rather than relying on a number you saw months ago, and compare at least two buyers before accepting an offer.
Stack a few senior discounts into your regular routine
Image Credit: Shutterstock
A handful of senior discounts are easy to forget about simply because claiming them takes a specific action, like showing up on the right day or signing up for a free membership you didn’t know existed. Kohl’s takes 15% off in store purchases for customers 60 and older, but only on Wednesdays. Walgreens offers 20% off eligible items on the first Tuesday of every month for anyone 55 and older who joins its free myWalgreens rewards program, which takes about two minutes to set up.
Restaurant and travel discounts work similarly. Denny’s gives AARP members 55 and older 15% off, up to a $10 discount, simply for showing a membership card. Amtrak knocks 10% off most fares for riders 65 and older, or 60 and older on routes crossing into Canada, and the discount applies automatically once you select the senior fare when booking.
None of these individually changes your monthly budget. But stacked together over a year, routine discounts like these on groceries, prescriptions, meals out, and travel add up to real savings for essentially no effort beyond asking or showing an ID. Check with specific locations before you go, since participation and exact terms can vary by store, and it’s worth a quick search every so often for what’s currently available near you.
Most of this money and these programs already exist for people in exactly your situation. The only real step left is picking one from this list and making the call.
World of Warcraft can be an affordable hobby or a surprisingly expensive part of a household budget. The real cost depends on how often you play, whether you buy every expansion, and how much you spend on optional extras. For families managing several subscriptions and entertainment expenses, understanding the yearly total is the first step toward keeping gaming costs under control.
Players who want to save time may also consider options such as buy wow forever gold cheap, especially when in-game gold is needed for repairs, consumables, crafting, or other expenses. However, buying gold or other paid services is not necessary to enjoy the game, and players should check Blizzard’s current policies and stick to permitted ways of acquiring in-game currency. For some players, paying for convenience is a personal budgeting decision; for others, spending a little more time earning gold in-game is the better choice.
The main expenses are straightforward: a game subscription, major expansion purchases, and any optional extras. The subscription provides access to the main game, while expansions introduce new zones, storylines, dungeons, raids, and other content. Optional spending can include cosmetics, in-game currency, character services, and third-party gaming assistance.
World of Warcraft: Annual budget breakdown
The following table provides an illustrative budget for one player over 12 months. Prices vary by region, edition, and purchase date, so check the official Blizzard store before setting your final budget.
Expense
Estimated yearly cost
Required?
Game subscription
Approximately 156–180 at 13–15 per month
Yes, for regular subscription-based play
Expansion purchase
Approximately 50–90, depending on edition
For access to new expansion content
WoW Token purchases
0–200 or more
No
Shop cosmetics and mounts
0–100 or more
No
Character services
0–60 or more
No
Optional boosting services
0–300 or more
No
Estimated total
About206–930+
Depends on spending habits
These figures are planning estimates, not verified current prices or official annual averages. The expansion cost is shown as a purchase in the year it is bought, rather than an expense that necessarily recurs every year. Optional spending can also be zero, making a budget-conscious year substantially cheaper.
Subscription: The expense you should plan first
A subscription is the most predictable recurring cost for an active World of Warcraft player. Paying monthly is convenient, but longer subscription plans may offer a lower effective monthly price. Before choosing a plan, consider how consistently you play. If you regularly take breaks between seasons or expansions, a monthly plan may be more economical than paying for months you barely use.
Players should also check whether a subscription bundle or longer-term option offers better value in their region. Avoid paying for overlapping subscriptions or leaving an account active during an extended break.
Expansion purchases: A cost that comes and goes
Major expansions are usually purchased separately from the recurring subscription. The price depends on the edition, with premium editions typically including extras such as cosmetics, mounts, or additional bonuses.
For most players, the standard edition is enough to access the new expansion content. Deluxe editions make sense only when the included extras are worth the additional cost to you. If you mainly care about quests, dungeons, raids, and character progression, compare the standard edition carefully before spending more.
WoW tokens: Can you really play for free?
WoW Tokens create an alternative way to cover eligible game time. Players can purchase a Token through the in-game system using gold and redeem it for game time or another supported Blizzard balance option, depending on the region and current rules.
This means experienced players with enough gold can potentially cover their subscription without paying additional cash each month. However, the gold must come from somewhere: farming, crafting, gathering, auction-house trading, or other permitted in-game activities all require time and effort.
A useful way to measure the real cost is to compare the gold needed for a Token with the gold you can reliably earn during a typical play session. If farming enough gold takes many hours, paying for a subscription may be the better value for someone with a busy schedule.
Optional spending: Cosmetics, services, and convenience
Cosmetic purchases can be enjoyable, but they are among the easiest expenses to underestimate. A mount or appearance may seem inexpensive on its own, yet several purchases throughout the year can add up to the price of another game or even a full expansion.
Paid character services, where available, should also be treated as occasional expenses rather than necessities. Before purchasing a transfer, name change, or similar service, check whether it solves a genuine problem and review the current price.
Boosting services are another optional expense. Some players choose to pay for help with difficult content or progression because they have more money than free time. If you are considering a wow boost, compare the price with the time it would take to achieve the same goal yourself, and verify that the service complies with Blizzard’s current rules. Never share your account password or risk your account for an uncertain shortcut.
How to spend less on World of Warcraft
1. Set a yearly spending limit
Choose a total budget before a new expansion or season begins. Separate essential expenses, such as the subscription, from optional purchases. This makes it easier to see how much room remains for cosmetics or services.
2. Choose the right subscription plan
Compare monthly and longer-term options using their effective monthly costs. Choose a longer plan only if you expect to keep playing for most of its duration.
3. Earn gold through gameplay
Gathering, crafting, completing activities, and selling items through the Auction House can help fund in-game expenses. Learn which activities suit your character and play schedule rather than chasing every gold-making trend.
4. Buy only the expansion edition you need
Compare the standard and premium editions based on the extras you genuinely want. Do not pay more simply because a bundle appears to offer better overall value.
5. Track optional purchases
Keep a simple list of Token purchases, cosmetics, character services, and any boosting expenses. Reviewing the total every few months can reveal patterns that are easy to miss when purchases are spread throughout the year.
6. Avoid spending when you are frustrated
A difficult dungeon, a missed achievement, or a slow progression week can make paid shortcuts look more appealing. Give yourself time to decide whether the purchase is genuinely worthwhile before committing money.
What does a typical player really spend?
A player who subscribes, buys an expansion when needed, and avoids optional purchases can keep costs relatively predictable. Someone who frequently buys Tokens, shop items, character services, or boosting may spend several times as much.
The key distinction is between the cost of accessing the game and the cost of convenience. Subscription and expansion purchases provide the foundation, while nearly everything else depends on personal preferences and available time.
Final thoughts
World of Warcraft does not have to be an expensive hobby. By budgeting for the subscription and expansion first, earning gold through permitted gameplay, and treating cosmetics and paid services as optional extras, players can enjoy the game without letting small purchases accumulate into a large annual bill.
The best budget is one that reflects how you actually play. If you have plenty of time, in-game gold-making can reduce cash expenses. If your schedule is limited, paying for selected conveniences may feel worthwhile—but it should always be a deliberate choice rather than an automatic part of every season.
If you’re struggling to pay bills this month, you can still keep the lights on and a roof over your head. The way through is to work out exactly how short you are, protect your most important bills first, and talk to the companies you owe before a payment is late. After that, you look for help and fill whatever gap is left. Below are five steps that work even when the numbers look scary.
Step 1. Figure out exactly how much money you’re short
Most people searching for what to do when you can’t pay your bills skip this part, but it matters most. You need a real number before you can tell whether cutting a few expenses will be enough or whether you’ll need a short-term cash advance app, like this one, to get you to payday. Often, the actual shortfall is smaller than the fear.
Get a sheet of paper or open the notes app on your phone; then write down every dollar coming in before your next paycheck, like wages, child support, benefits, side income. Then specify each bill due in that same stretch, with its amount and due date. Subtract one total from the other.
Now you know where you stand. Maybe it’s $85, maybe it’s $600. Either way, you can’t make a plan without it, so this is your starting point.
Step 2. Prioritize the bills that matter most
When you can’t pay bills in full, decide which ones come first. Pay for the things that keep your family safe, housed, and able to get to work:
Rent or mortgage
Utilities (electricity, heat, water)
Food
Car payment and insurance, if you need the car for work
Childcare, if it lets you keep working
Credit cards, streaming services, and most medical bills can usually wait a little. A late credit card payment hurts your credit score, but it won’t leave you without heat in January. This CNBC Select guide on handling bills backs up what most financial counselors say: housing and utilities come first.
Also look at your bank statement for small charges you’ve forgotten. A $12 app subscription you don’t use is $12 you can put toward the electric bill.
Step 3. Contact bill providers before you miss a payment
Calling your landlord or utility company and saying “I can’t afford my bills right now” feels awful. Do it anyway, and do it before the due date. Companies have a lot more room to help you before your account goes past due.
Be honest and specific with your providers. Many utilities offer hardship programs, payment plans, or due-date changes, and it’s no big deal; just ask.
Look for utility bill assistance too. The federal LIHEAP program helps low-income households with heating and cooling costs, and you can even apply for heating bill help each season. If rent is the problem, call 211 or search your county’s website for rent assistance programs. Many of them can pay part of a month’s rent straight to your landlord.
Write down who you talked to, the date, and what they agreed to. If someone later says there was no deal, you’ll have your notes.
Step 4. Find ways to get extra cash before your bills are due
If you’ve cut what you can and still need to figure out how to pay bills with no money left over, here are some realistic options:
Sell things you don’t need. Kids outgrow clothes, toys, and gear fast. Local Facebook groups and resale apps turn them into cash within a few days.
Pick up quick side work. Babysitting, pet sitting, cleaning, or a few delivery shifts can bring in a couple hundred dollars.
Look for financial assistance for single mothers. Churches, community action agencies, and food banks can free up money in your budget. If a food pantry covers groceries this week, that grocery money goes to the power bill.
Ask about paycheck advances. Some employers will give you part of your earned pay early if you ask.
If you need money before payday and none of that covers it, a cash advance app like Credit Genie can help you get through a short gap without the triple-digit interest rates of a payday loan. Use it for one specific shortfall, not as a regular part of your budget. Before you borrow anything, know exactly when and how you’ll pay it back.
Avoid payday lenders and title loans if you can. The fees pile up fast, and one bad month can turn into a year of catching up.
Step 5. Make a simple plan to stay ahead of future bills
Once you handle this month, take an hour to make next month easier. You don’t need a complicated budget. A few habits help a lot:
Line up due dates with paydays. Ask providers to move due dates so big bills don’t all hit the same week.
Start a tiny buffer. Put even $10 or $20 from each paycheck into a separate savings account. A $200 cushion can keep a car repair from turning into a crisis.
Set calendar reminders three days before each due date.
Check your spending weekly, not monthly. Small leaks are easier to handle early.
If you keep finding there’s not enough money to pay bills, look at other options you have. Free nonprofit credit counseling, a conversation about a raise, or a check on whether you qualify for benefits like SNAP or the Earned Income Tax Credit could change your numbers for good.
The bottom line
Finding out you have no money to pay bills is a sick-to-your-stomach kind of feeling, especially when kids are counting on you. But a short month doesn’t have to become a long-term problem. Most of the damage comes from waiting, as you ignore the electric company’s letters, skip the call to the landlord, or hope the numbers somehow fix themselves.
So pick one thing from this list and do it today. Even a single phone call can buy you a couple of weeks. Then do the next thing tomorrow. It won’t feel like much at first, but by the time your next paycheck lands, you’ll be in a better spot than you are right now.
Today’s parents are replacing traditional, bulky bags with modular carry systems designed for rapid access, durability, and daily versatility.
Your active routine rarely pauses when you step out the front door with your family. Modern life blurs the boundary between your personal daily carry and family gear, leaving you little patience for bulky, oversized duffels that slip off your shoulders.
You need streamlined gear that moves with you through work, weekend commutes, and playground trips. Modern carry systems now borrow smart engineering from outdoor expedition packs to keep your days efficient, balanced, and organized.
How do ergonomic packs support your daily family mobility?
Traditional baby bags place heavy loads on one shoulder, pulling your spine out of alignment while you navigate a stroller or hold a toddler’s hand. Modern ergonomic packs distribute that weight evenly across your back and hips through contoured straps and structured back panels. You move through transit stations or park trails without neck strain or fatigue.
Balanced weight distribution keeps your hands free to handle active parenting tasks. Breathable mesh padding and reinforced sternum clips stabilize your pack when you bend down to tie shoelaces or lift a child into a car seat. Smart load geometry lets you carry water, spare clothes, and tech gear without feeling weighed down.
What makes modular systems adapt to your shifting routines?
You rarely pack the same supplies for a 20-minute coffee run that you take on an all-day excursion. Modular carry systems let you build a setup tailored to your exact destination instead of forcing you to haul dead weight.
Detachable pouches and clip-on organizers transform a standard pack into an adaptable family hub. Pairing dedicated diaper bag accessories with your daily bag lets you separate clean snacks, wipes, and personal items into distinct modules. You snap off what you need for a quick stop without digging through main compartments. Everything stays right where you expect it, keeping your daily pace smooth and predictable.
Which design features speed up access on the move?
Speed matters when you need a wipe or a snack right away. Deep clamshell openings fold completely flat so you can see every item inside without rummaging in the dark. Magnetic buckles and self-locating zippers let you open compartments with 1 hand while holding your child with the other.
Exterior pockets give you rapid entry points for items you grab 10 times a day. Dedicated slip pockets protect your phone and transit passes, while side sleeves hold water bottles upright. Water-resistant fabrics wipe clean in seconds after accidental spills, protecting internal electronics from unexpected messes.
Why should your pack outlast the toddler years?
Parenting gear represents an investment in your daily comfort, so choosing a pack with long-term utility pays off for years. Good Housekeeping points out that while features like wipe-clean surfaces and insulated pockets serve baby needs early on, versatile backpacks stay useful well into the school years for water bottles, snacks, and sports gear.
Neutral styling and rugged fabrics blend into office settings just as smoothly as playground outings. When your child outgrows diapers, your pack transitions into a dependable gym bag, work commuter, or carry-on travel pack. You keep using high-performance equipment rather than retiring a short-lived novelty bag to the closet.
Image Credit: Unsplash
Investing in adaptable organizers and rugged daily packs gives you the freedom to move through parenthood with confidence. You gain a versatile system that supports your active routine, keeps your belongings within arm’s reach, and handles every sudden change in your daily schedule.
Holiday dinners leave behind more than leftovers. There are roasting pans to scrub, guest towels to wash, and floors that somehow collect the entire outdoors. Running out of dish soap halfway through that stretch is a particularly dull reason to make another shopping trip.
With about ten weeks left in the year, a well-priced bulk pack can carry a lot of that work into January. The useful buys are the ones you’ll actually get through, or keep using long after the packaging is gone. Prices vary by location and whether you shop in-store or online, and availability can change.
The dishes after a holiday meal are bad enough without discovering that the soap bottle contains mostly air. Palmolive Ultra Strength comes in a 102-fluid-ounce bottle for $6.49, roughly 6 cents an ounce. That is a useful price for something that gets used every day, whether you have a dishwasher or wash everything in the sink.
Even at an ounce a day, the bottle would cover 102 days, comfortably past December. Refill a smaller bottle by the sink instead of wrestling with the big one over a greasy pan. The value is in the refill volume, especially for households that cook regularly and already know they like Palmolive.
Cascade Complete Shine Boost dishwasher pacs
Image Credit: Costco
A dishwasher that runs every evening needs more than a little bag of detergent to get through the holidays. This 92-count tub of Cascade Complete Shine Boost ActionPacs costs $13.99, about 15 cents per cycle. At one load a day, that’s three months of dishwasher duty.
The pacs contain detergent for automatic dishwashers, so there’s no measuring a scoop while you’re clearing dinner. Keep the tub closed and dry so moisture doesn’t spoil the unused supply. For a household that uses the machine most days, buying enough for 92 cycles is practical stocking up: the quantity matches a chore you already pay for throughout the week.
Finish Jet-Dry Ultra rinse aid
Image Credit: Costco
Water spots on glasses can make a clean dishwasher load look unfinished. Finish Jet-Dry Ultra goes in the machine’s rinse-aid dispenser to help with drying and spotting. The 38-fluid-ounce bottle is $12.99, and the package lists up to 374 washes. That’s roughly 3.5 cents a wash at the stated yield.
Your dispenser setting affects how quickly you use it, but there is plenty of room between that advertised capacity and the weeks remaining in the year. This is a worthwhile refill if you already use rinse aid, particularly with hard water. It also takes up much less cupboard space than several small replacement bottles waiting for their turn.
Scotch-Brite Zero Scratch sponges
Image Credit: Costco
At $11.99 for 24, these Scotch-Brite sponges cost about 50 cents each. The individually wrapped supply lets you replace a worn sponge without making it limp through another week just because there’s no spare under the sink. Even replacing one every week leaves more than enough to finish the year.
The Zero Scratch version is intended for everyday washing, including compatible nonstick cookware. That’s the useful distinction when your pans cost far more than the sponge touching them. Keep separate sponges for kitchen and bathroom work, and follow the care instructions for the surface you’re cleaning. The compact pack is easier to store than an equivalent stash of bottled cleaners.
Scotch-Brite heavy-duty scour pads
Image Credit: Costco
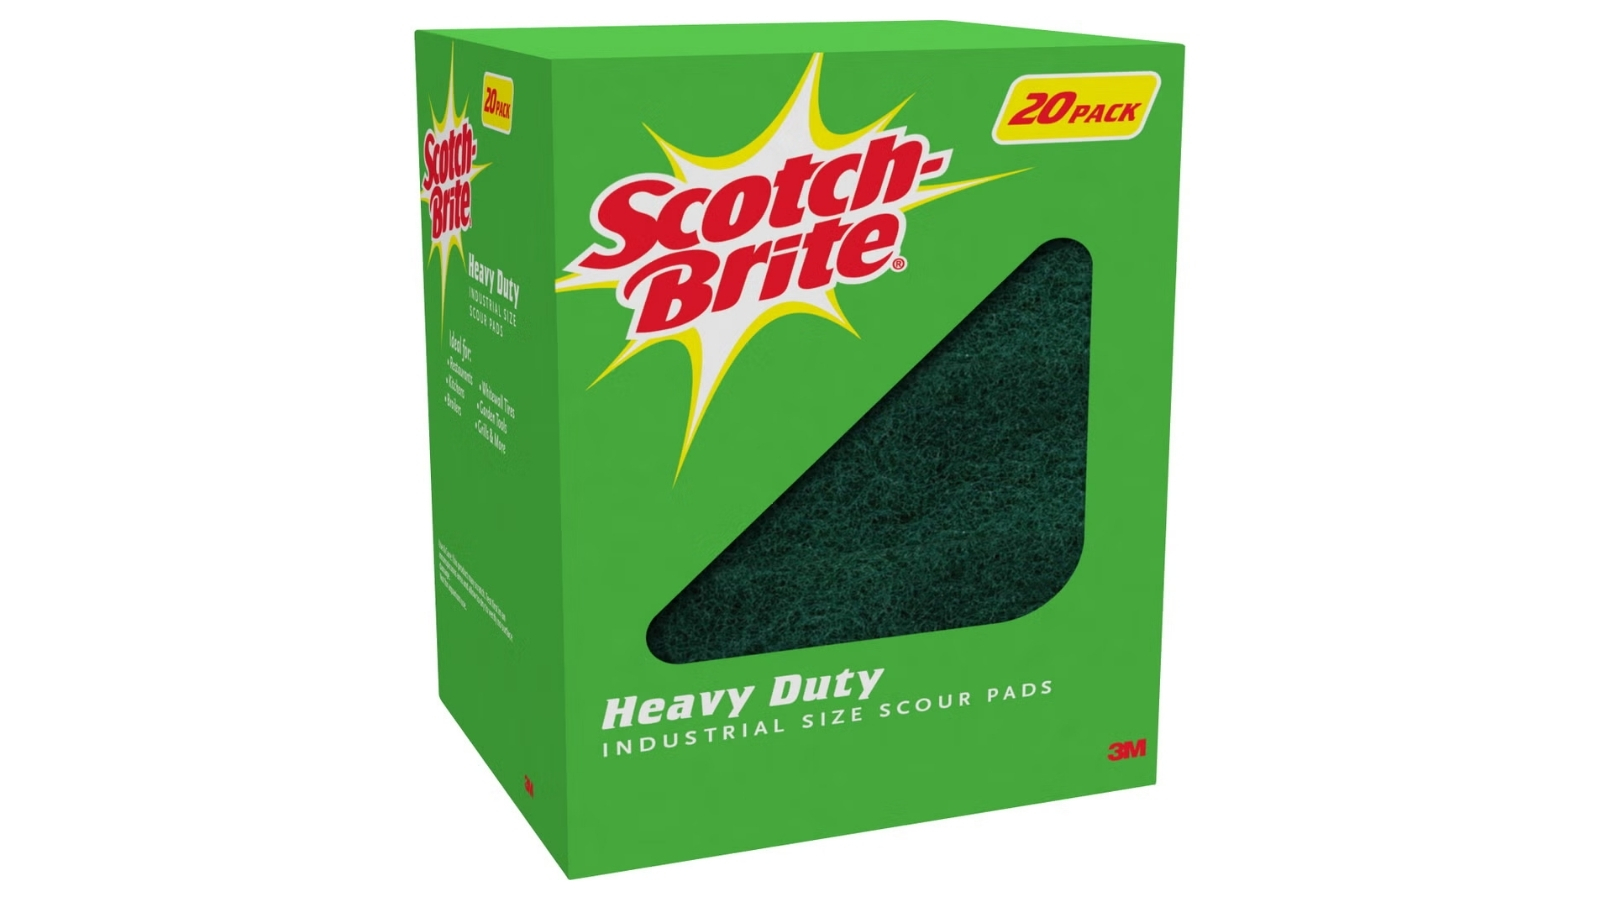
A roasting rack with baked-on residue needs a different tool from the soft sponge used on your nonstick skillet. Scotch-Brite’s heavy-duty scour pads are $9.99 for 20 large, 6-by-9-inch pads. That is about 50 cents per full pad, with considerably more scrubbing area than a small kitchen scrubber.
Use them for tough jobs on surfaces that can tolerate abrasion, including suitable uncoated cookware and utility cleaning. They aren’t the choice for delicate finishes. Twenty pads give an occasional heavy-scrubbing household ample backup through the end of the year. Their size also makes them useful for larger surfaces, where a tiny scrubber means more time spent working the same patch.
Mr. Clean Magic Eraser pads
Image Credit: Costco
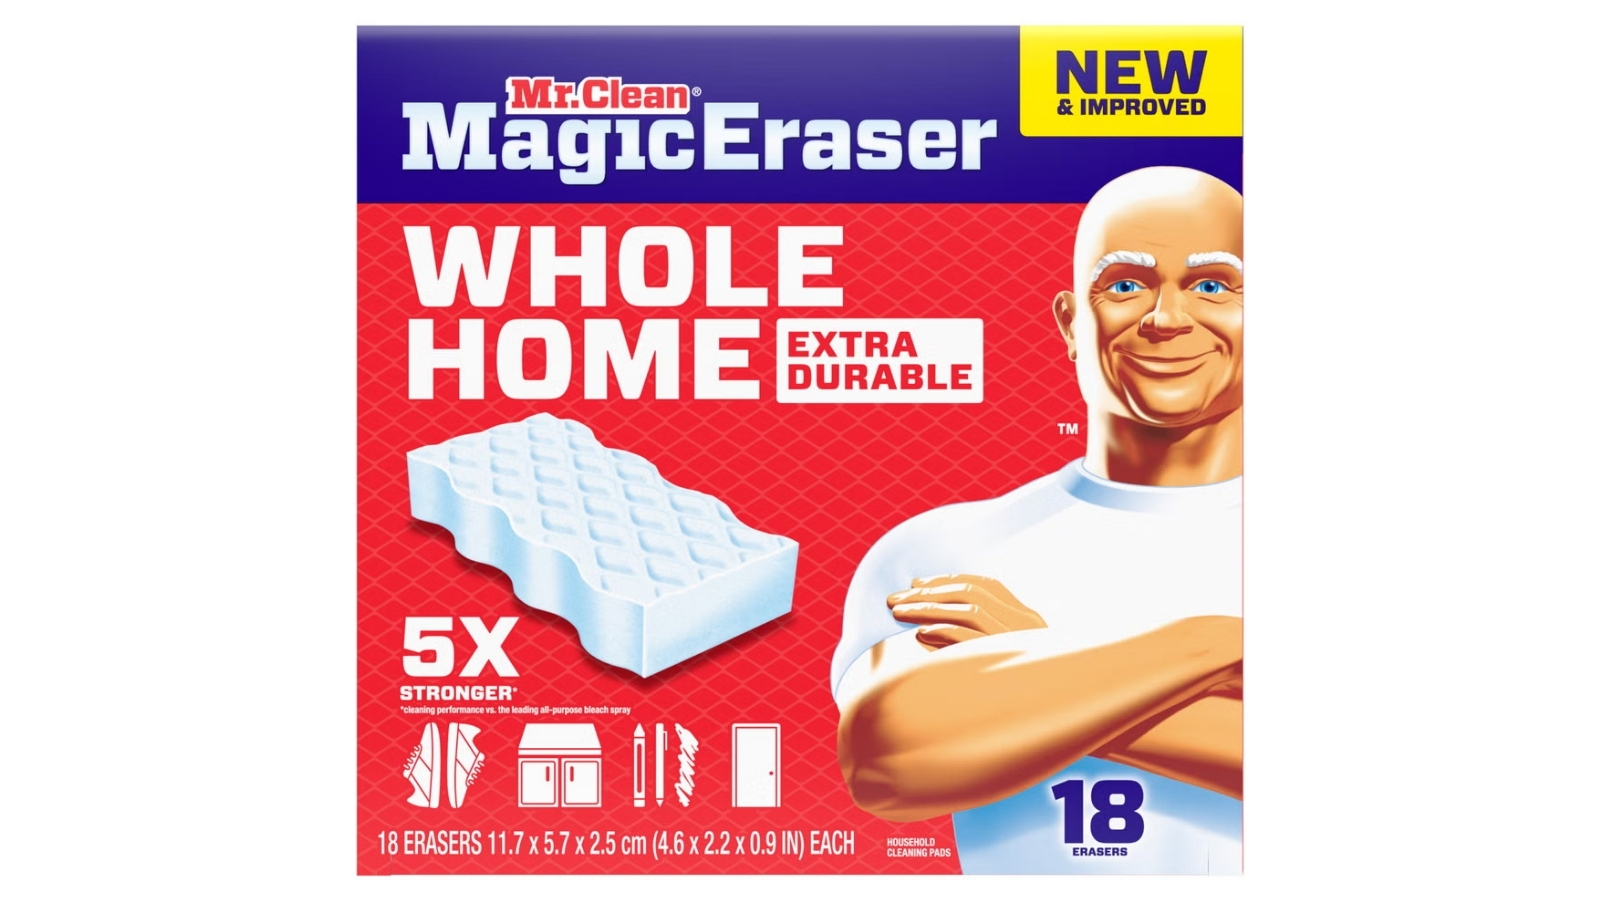
Shoe marks on baseboards and stubborn smudges on doors don’t always need another bottle of spray. Mr. Clean’s Whole Home Extra Durable Magic Erasers use water-activated scrubbing material to tackle marks on compatible surfaces. The 18-count box is $9.97, about 55 cents per pad.
At one pad a week, that quantity stretches well beyond New Year’s. Treat these as occasional spot-cleaning tools, rather than disposable cloths for every countertop. They are abrasive, so test a hidden area and follow the surface restrictions before tackling paint or a shiny finish. For small scuffs that make a room look grubby, the cost per cleanup is modest compared with replacing or repainting something prematurely.
Kirkland Signature microfiber towels
Image Credit: Costco
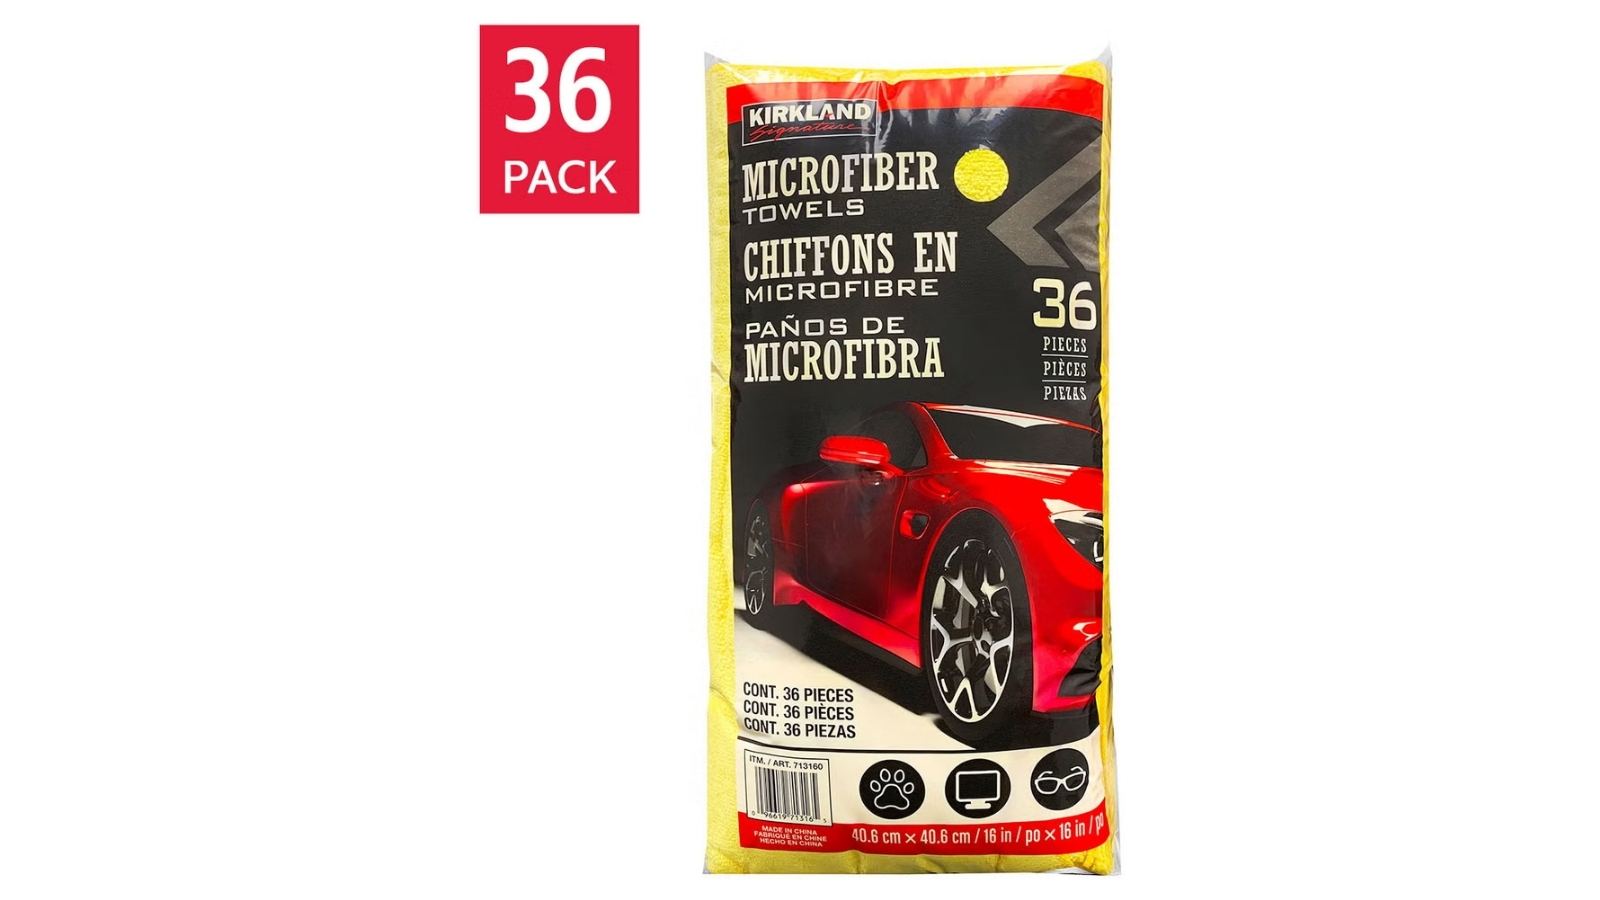
Thirty-six washable microfiber towels for $16.99 works out to about 47 cents each before a single reuse. The 16-inch-square cloths are useful for dusting, wiping, and drying, with enough in the pack to keep clean ones available while the used ones are in the laundry.
Divide them by job so the cloth used on a car never becomes the cloth used on a kitchen counter. This is a durable supply, rather than something you’re likely to exhaust by December. The savings come from using a washable cloth for routine jobs that would otherwise eat through paper towels. A large pack makes the switch easier because you can rotate cloths instead of repeatedly rinsing one dirty rag.
Unitex cotton terry cleaning towels
Image Credit: Costco
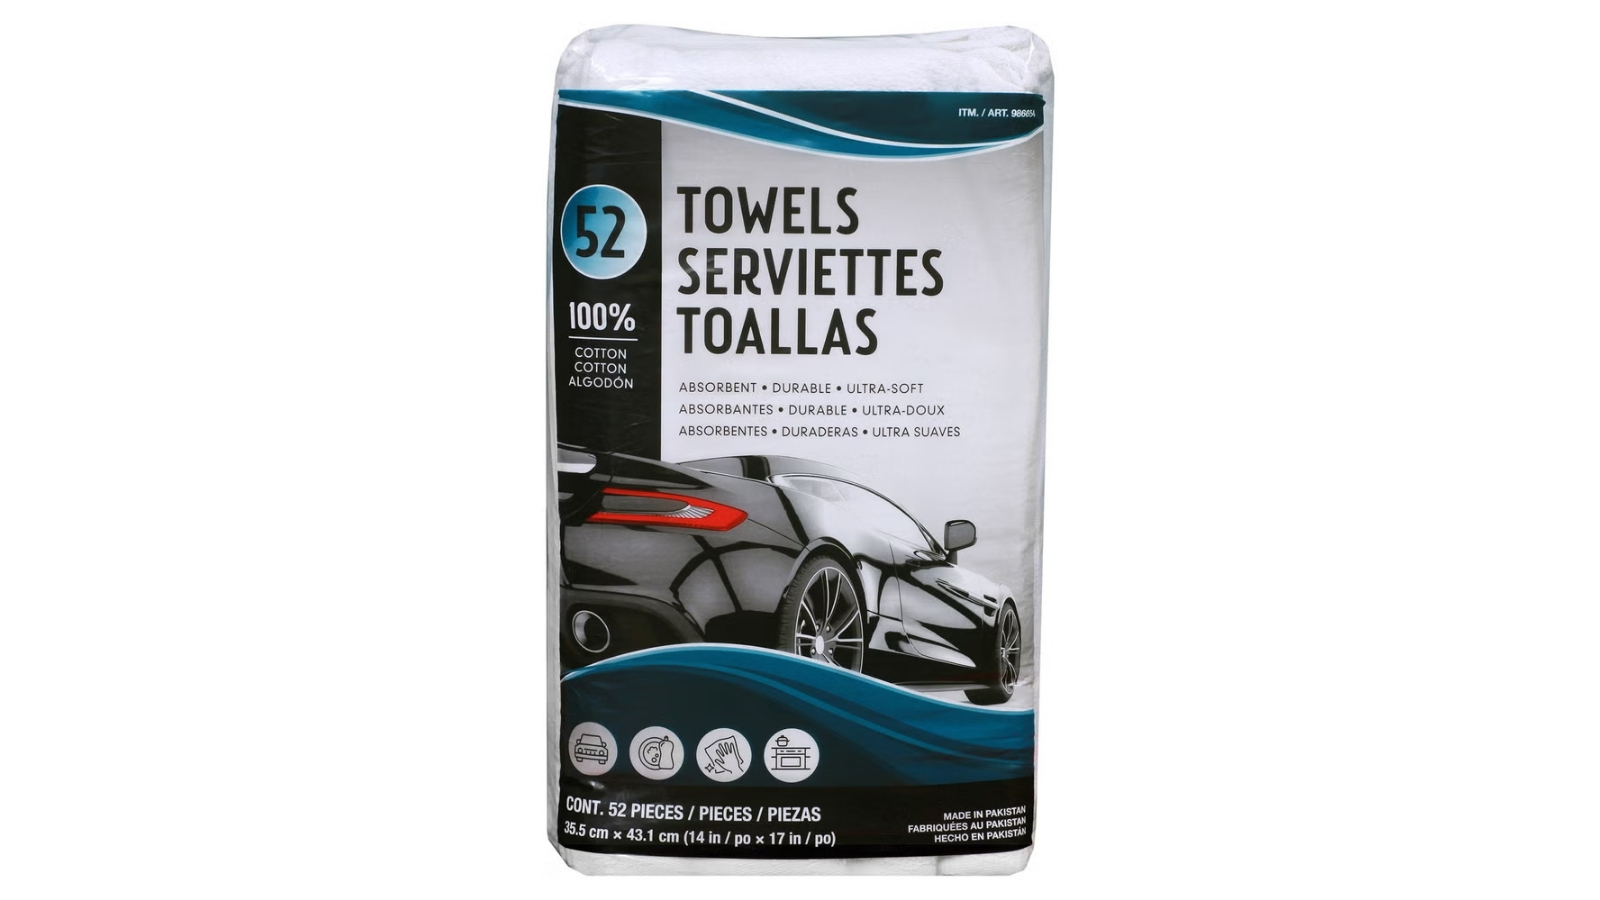
Spilled coffee, a wet countertop, and the puddle beside the dish rack call for absorbency more than polishing. Unitex’s heavyweight cotton terry towels cost $19.99 for 52, or about 38 cents apiece. Each measures 14 by 17 inches, a useful size for everyday kitchen wiping.
Unlike microfiber used for dusting and finishing surfaces, these are workhorse cotton rags for soaking up routine messes. You can set aside a small stack for each day and wash them together, keeping the remainder stored. Fifty-two reusable towels should comfortably outlast the holiday stretch. They make particular sense in a busy kitchen where grabbing paper towels has become the answer to every small spill.
Scott shop towels
Image Credit: Costco
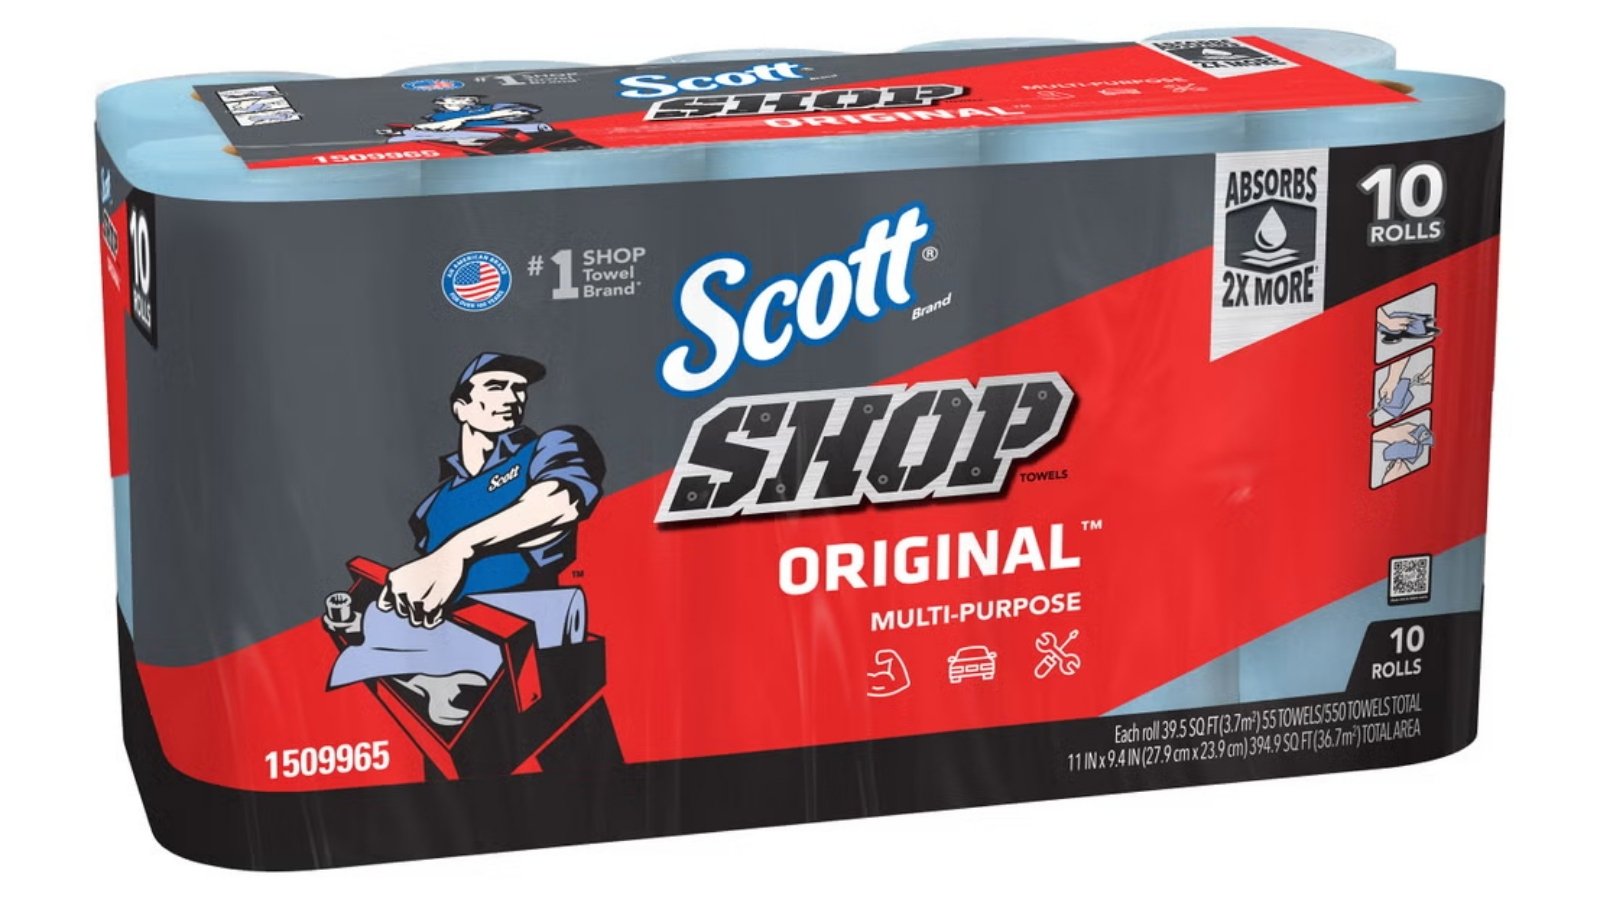
Greasy utility jobs can ruin a perfectly good kitchen towel. Scott’s blue shop towels are built to absorb oil and grease and hold together when wet. The ten-roll pack is $17.79, about $1.78 per roll. With 55 towels per roll, the pack contains 550 sheets.
That is a substantial reserve for occasional garage, bicycle, and workshop cleanup through December and beyond. Keep a roll where the grubby work happens, rather than carrying oily cloths through the house. These earn their place if you actually maintain tools or do messy repairs; ordinary household wiping doesn’t require a tougher towel. Having the right disposable material can also spare the washable rags you want to keep for cleaner jobs.
Kirkland Signature paper towels
Image Credit: Costco
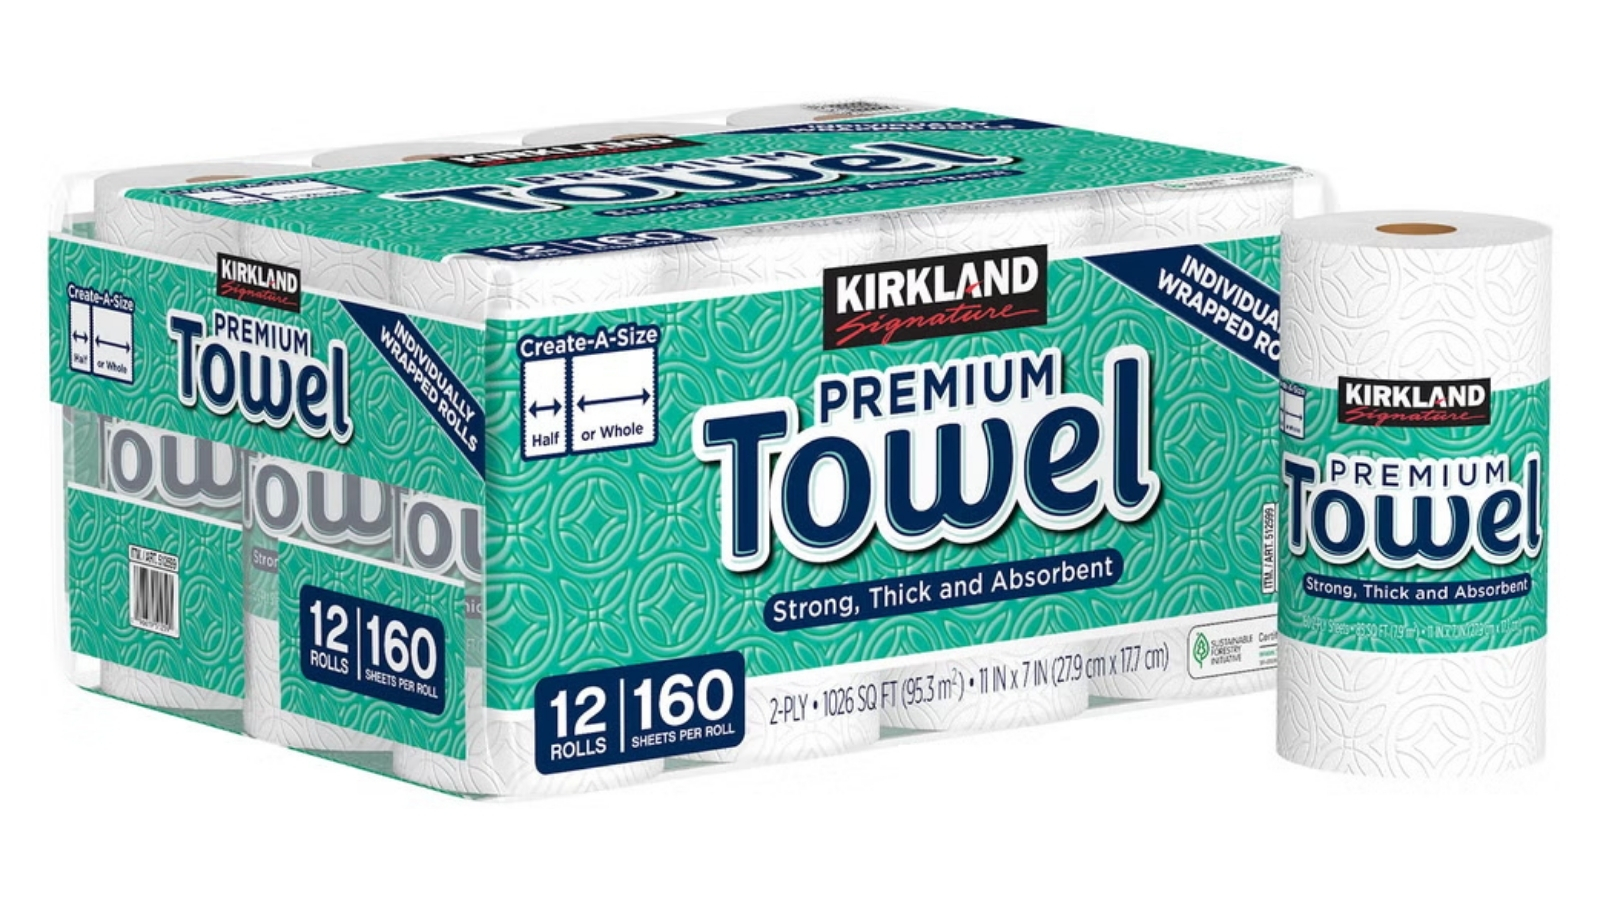
Costco’s paper towel pack contains 12 rolls with 160 sheets each, for 1,920 sheets altogether. At $20.99, that comes to roughly $1.09 per 100 sheets. The Create-a-Size format lets you tear off less for a small spill instead of using a large sheet every time.
A household averaging 20 sheets a day would get about 96 days from the pack. Using washable cloths for routine wiping makes that reserve stretch further, leaving paper towels for messes you’d rather throw away. This is a bulky purchase, so the storage space matters. Twelve individually wrapped rolls can be split between a kitchen cupboard and another dry storage spot rather than occupying the entire pantry.
Kirkland Signature kitchen trash bags
Image Credit: Costco
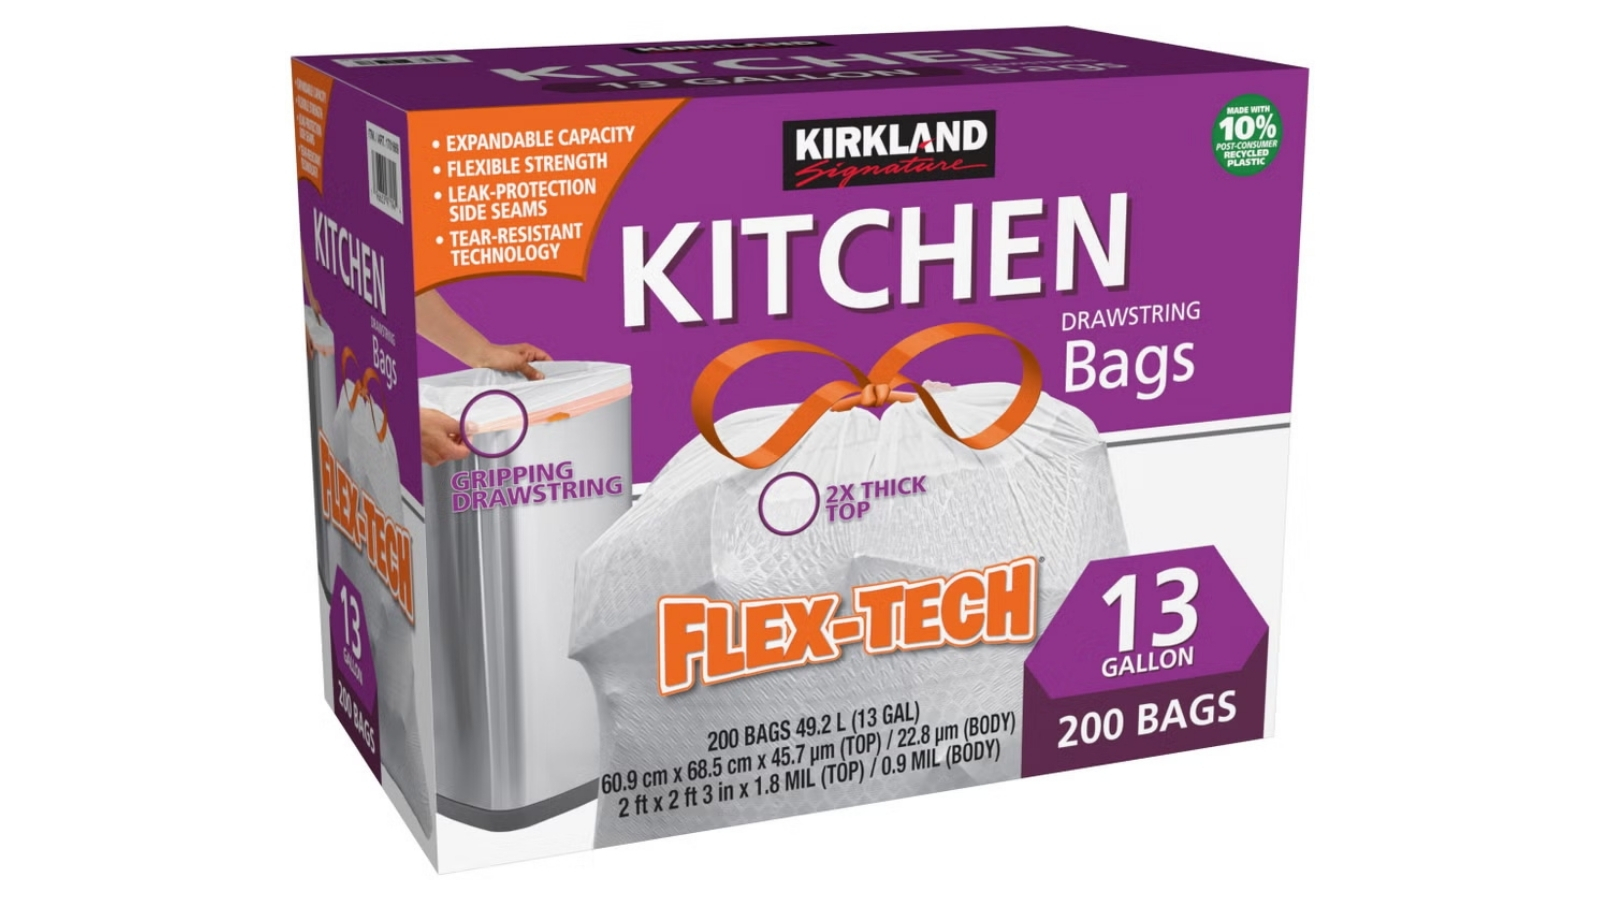
Kitchen trash bags are an unglamorous place to save money, which is precisely why the arithmetic matters. Kirkland Signature’s 200-count box of 13-gallon Flex-Tech drawstring bags costs $19.99, essentially 10 cents a bag. At one bag a day, that’s more than six months of kitchen trash.
The bags have reinforced tops and flexible plastic designed to expand around the contents. Check that 13 gallons suits your can before buying the box; a cheap bag that keeps slipping inside the bin is a daily annoyance. For a standard kitchen setup, 200 is a useful quantity with a long runway past December, even when extra cooking and visitors increase the amount you’re throwing out.
Arm & Hammer Plus OxiClean laundry detergent
Image Credit: Costco
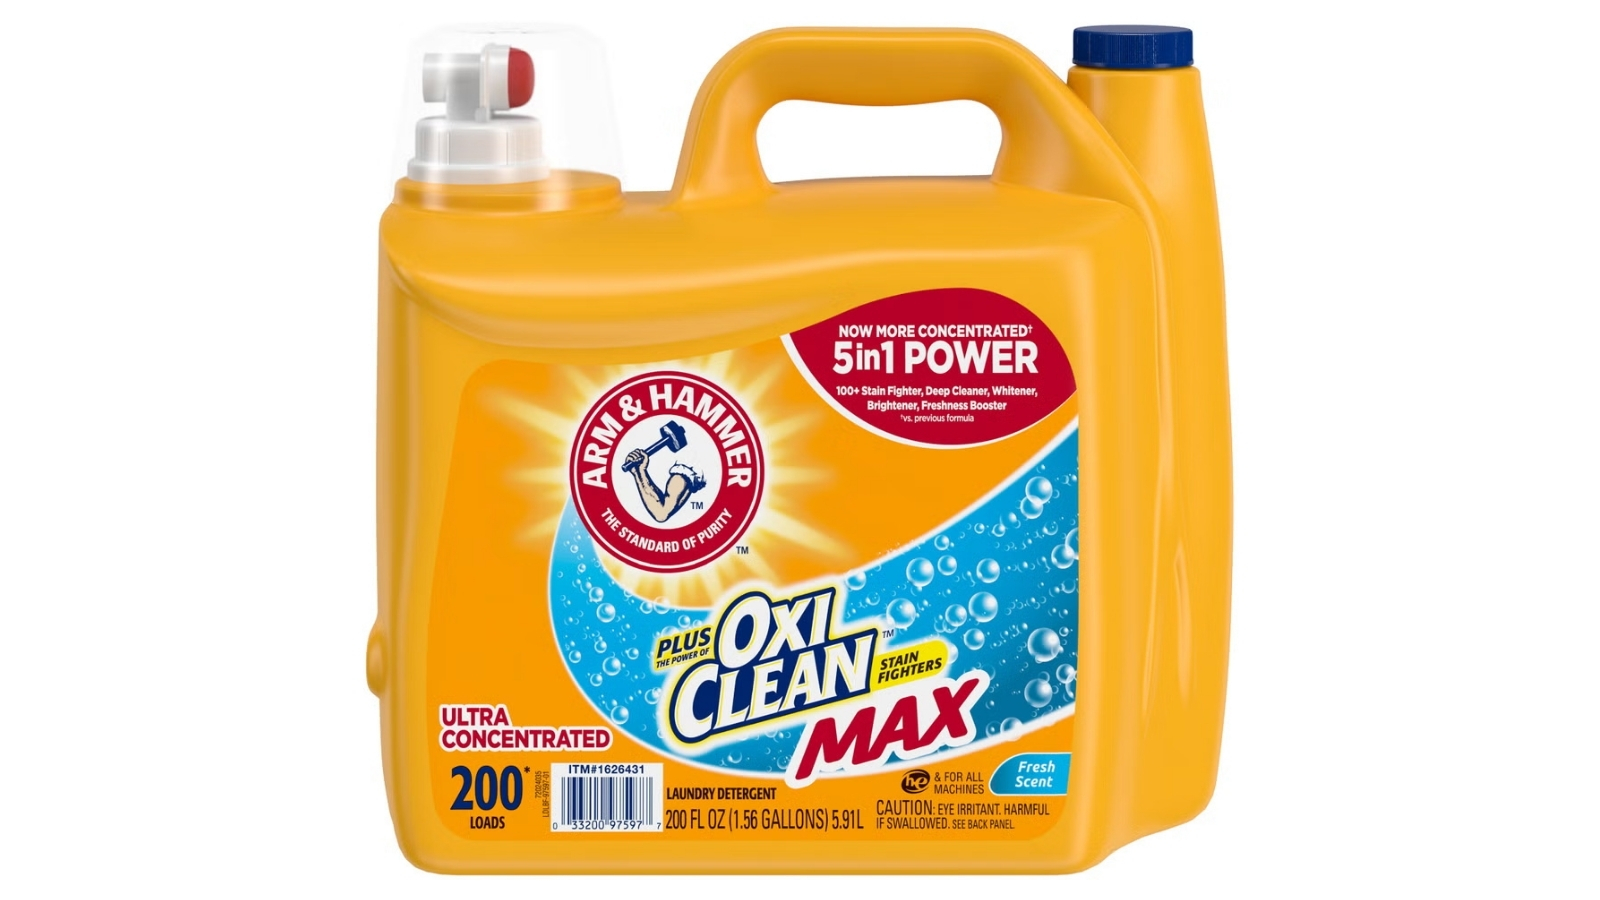
Extra bedding and guest towels can turn a normal laundry week into a small production line. Arm & Hammer Plus OxiClean Max HE liquid detergent is $14.89 for a 200-fluid-ounce bottle rated for 200 loads. That is about 7 cents per labeled load, a low running cost for a regular household chore.
At five loads a week, the stated capacity represents 40 weeks, far beyond the remaining holiday season. Larger or dirtier loads can need more detergent, so use the package’s dosing guide rather than treating 200 as a promise for every machine. The formula is HE compatible and works in cold water, useful for households trying to keep everyday laundry costs under control.
Kirkland Signature Oxi Powder
Image Credit: Costco
A laundry booster can be more useful than reaching for a stronger dose of detergent every time something is stained. Kirkland Signature Oxi Powder is a chlorine-free booster and multipurpose stain remover, priced at $13.99 for an 11-pound tub. The labeled capacity is 328 loads, putting the lowest-dose cost at roughly 4 cents a load.
Heavier stain treatment uses more, but an occasional booster has a long runway in a tub this size. It suits households washing grubby work clothes, kitchen linens, or frequently stained everyday items. Follow the fabric and product directions for soaking or washing. Keep the powder dry between uses so the supply remains usable well past the end of the year.
Nellie’s Wow Stick stain remover
Image Credit: Costco
A small stain shouldn’t automatically turn a usable shirt into a replacement purchase. Nellie’s Wow Stick lets you apply cleaner directly to a stained patch before laundering. The four-pack of 2.7-ounce sticks costs $29.99, about $7.50 per stick, with shipping included.
This makes the most sense if you already use solid stain treatment regularly. You’re buying four substantial sticks for small, targeted applications, rather than adding another product to every full wash. Wet the stick and fabric, rub it onto the stain, and work the area under water as directed. One can stay by the washer while the others remain stored, providing a realistic reserve for the year’s remaining clothing and table-linen mishaps.
FurMe washing machine cleaner tablets
Image Credit: Costco
The machine washing your towels also needs cleaning. FurMe’s Washing Machine Cleaner Max tablets target residue and odor-causing buildup, including the mess left by pet bedding. A 48-tablet pack is $24.99, about 52 cents per treatment. At the twice-monthly schedule in the product directions, that’s a two-year supply.
The tablets go in an empty washer for a cleaning cycle, rather than into a load of clothes. That distinction makes this a maintenance supply with a measurable job, not another fragrance added to laundry. Only a few treatments are needed between now and January. For households already buying small packs of washer cleaner, the larger quantity cuts the frequency of replacing that maintenance supply.
Lysol laundry sanitizer
Image Credit: Costco
Some laundry needs a separate sanitizing step, especially when the care label calls for a cooler wash. Lysol Laundry Sanitizer is a bleach-free additive for use alongside detergent, not a replacement for it. The 150-fluid-ounce bottle costs $16.99, roughly 11 cents per fluid ounce.
The useful budget approach is to reserve it for the loads where you want that extra treatment, such as suitable sportswear or bedding. Occasional use gives a bottle this size a much better chance of carrying you past December than pouring it into every wash. Follow the bottle’s dosing, rinse-cycle, and contact-time directions for your washer. That avoids paying for an extra laundry product without getting its intended benefit.
Bona hardwood spray mop
Image Credit: Costco
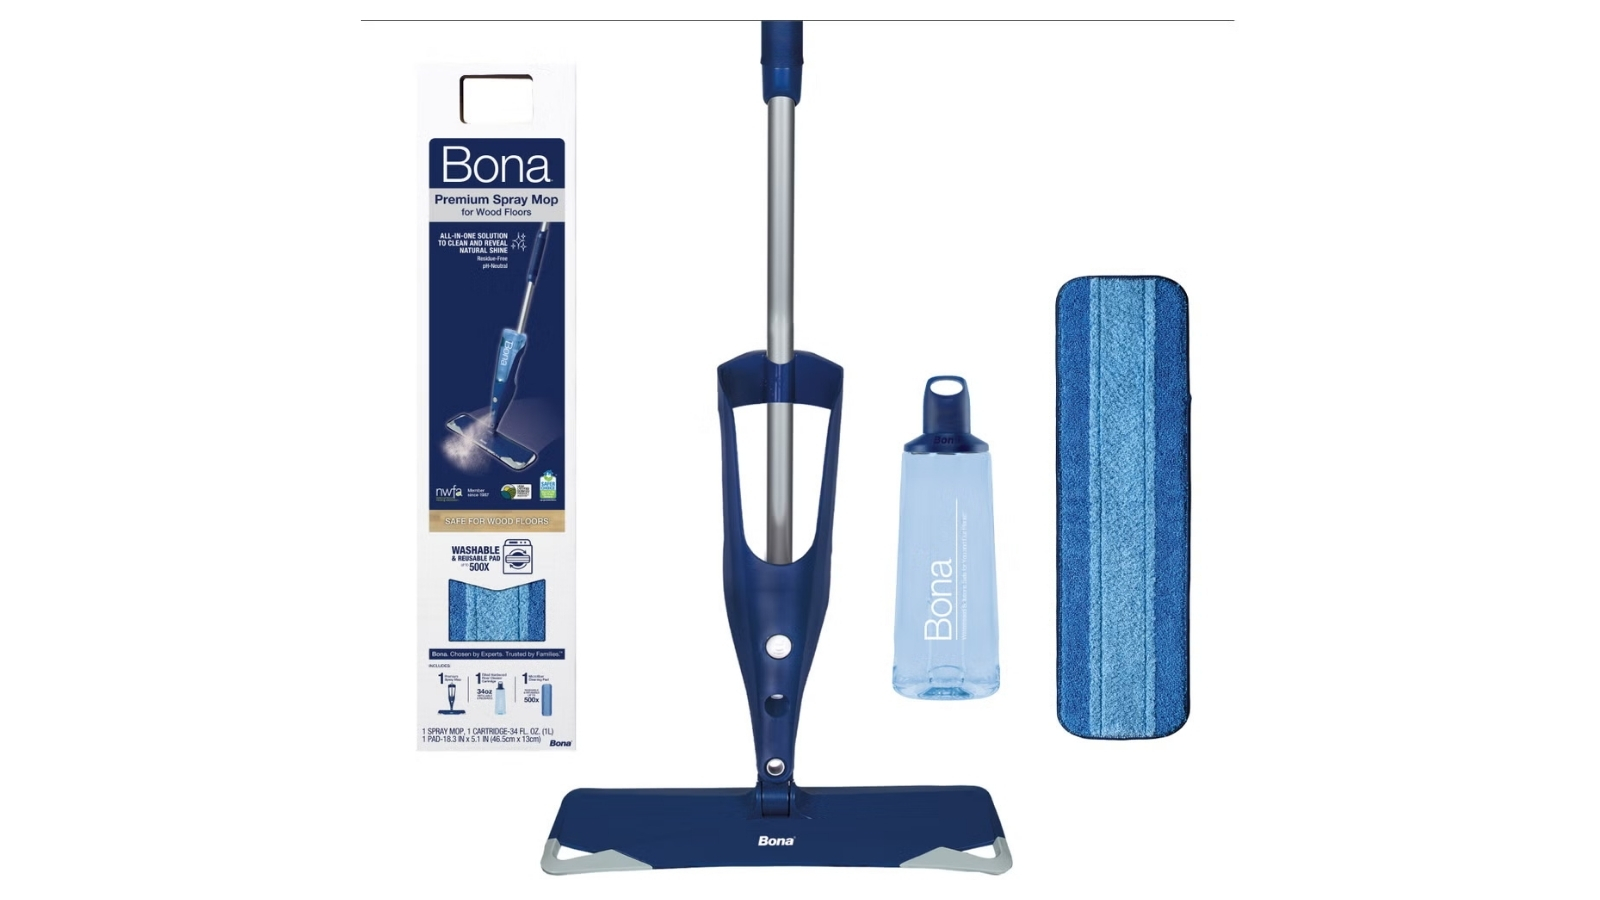
Disposable floor pads create a small recurring bill every time you mop. Bona’s Hardwood Premium Spray Mop costs $39.99 and comes with a refillable 28.75-ounce cartridge, prefilled cleaner, and a washable microfiber pad. The pad is listed as washable up to 500 times, giving this purchase a much longer life than the remaining weeks of the year.
This is for suitable finished hardwood floors, so match it to your flooring before buying. The money-saving features are the refillable container and reusable pad, which let you replace the cleaning liquid without replacing the whole setup. It’s a sensible replacement for a worn mop if you want quick spray-and-wipe cleaning without committing to disposable pads for every pass.
Swiffer heavy-duty dry sweeping cloths
Image Credit: Costco
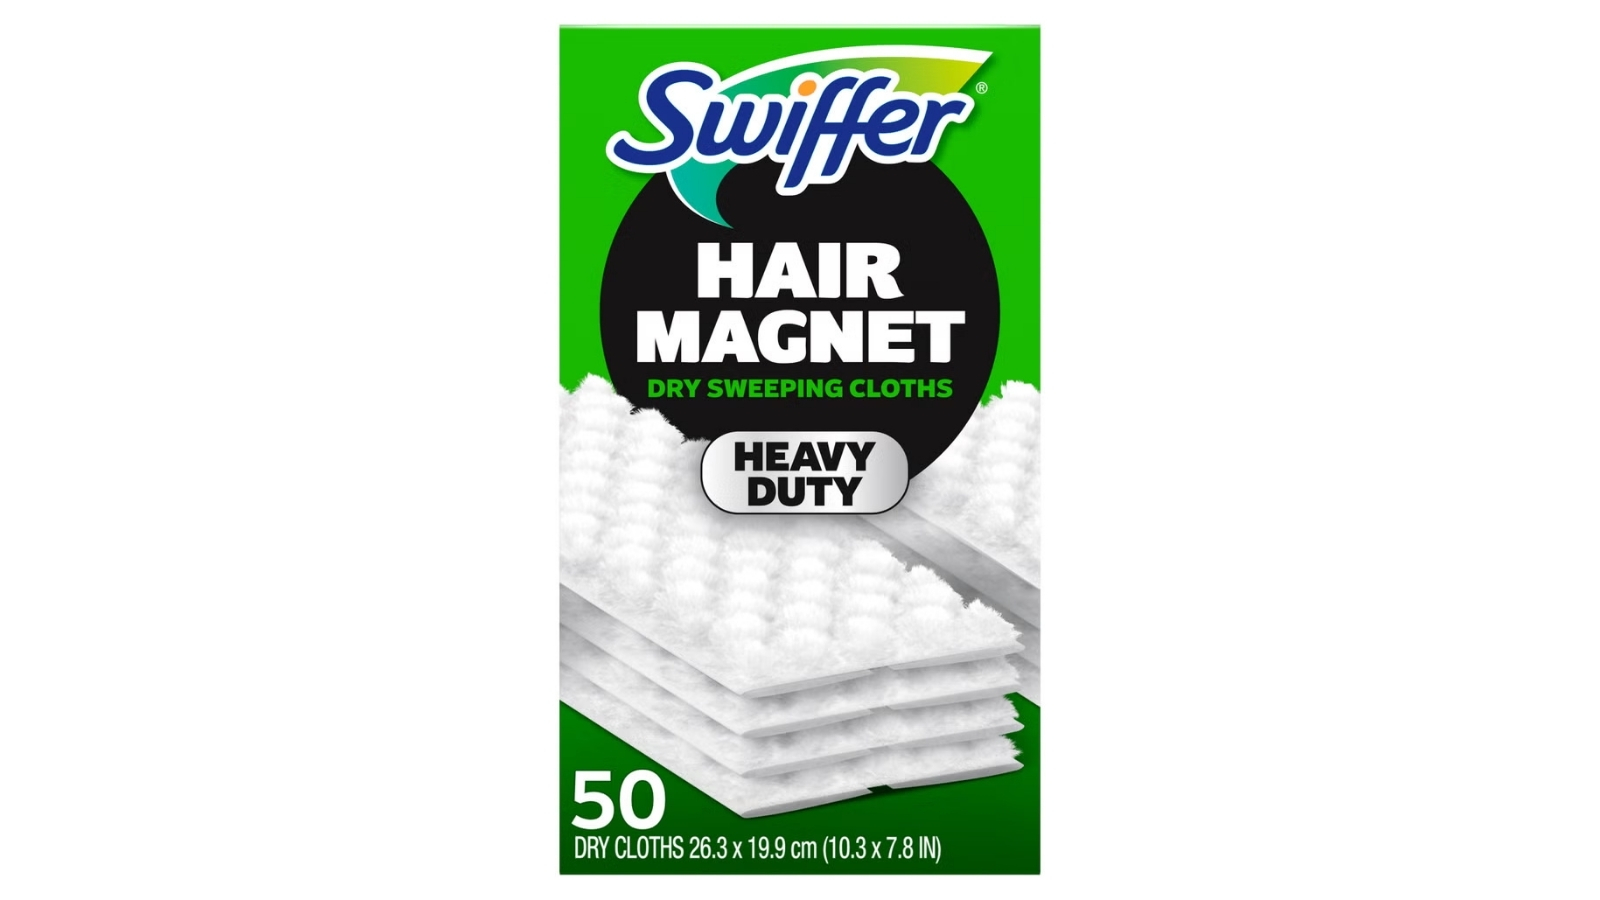
Pet hair and dust often need picking up before a floor needs washing. These Swiffer heavy-duty dry cloths fit compatible Swiffer Sweeper devices and cost $15.99 for 50, about 32 cents each. They’re dry dust-catching refills, rather than wet mopping pads, so they serve a different part of floor cleanup.
At four cloths a week, the box lasts about twelve weeks. That’s a workable end-of-year supply for a smaller home, though a large house with several shedding pets may use more. This purchase makes sense if you already own the handle and use it routinely. Otherwise, the refill price leaves out the cost of buying a tool just to make the cloths usable.
Swiffer heavy-duty duster kit
Image Credit: Costco
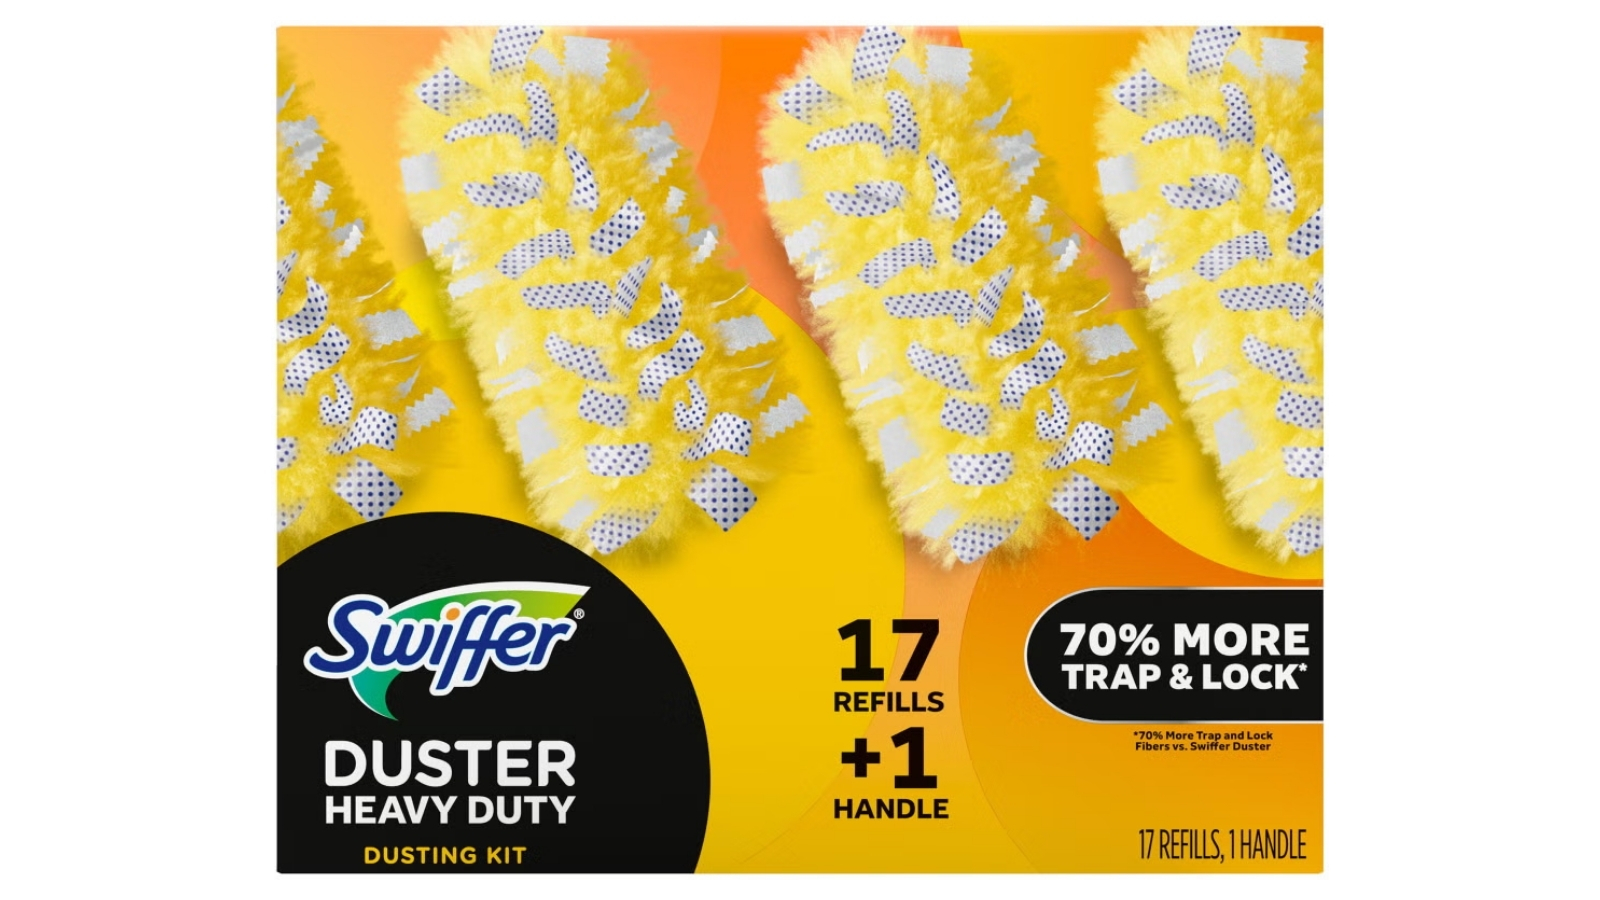
Blinds, vents, and the spaces around ornaments are awkward places to push a flat cleaning cloth. Swiffer’s heavy-duty duster kit includes one handle and 17 double-sided refills for $18.59. That’s roughly $1.09 per refill, with the reusable handle included in the purchase.
The fibers bend around objects and into narrow spaces, useful when you’re cleaning shelves before decorations go up or after they come down. At one refill a week, the kit covers seventeen weeks, although a particularly dusty room may use a refill sooner. Keep it for those awkward dusting jobs where its shape helps. Broad, easy-to-reach surfaces can still be handled with your washable cloths.
Scotch-Brite lint rollers
Image Credit: Costco
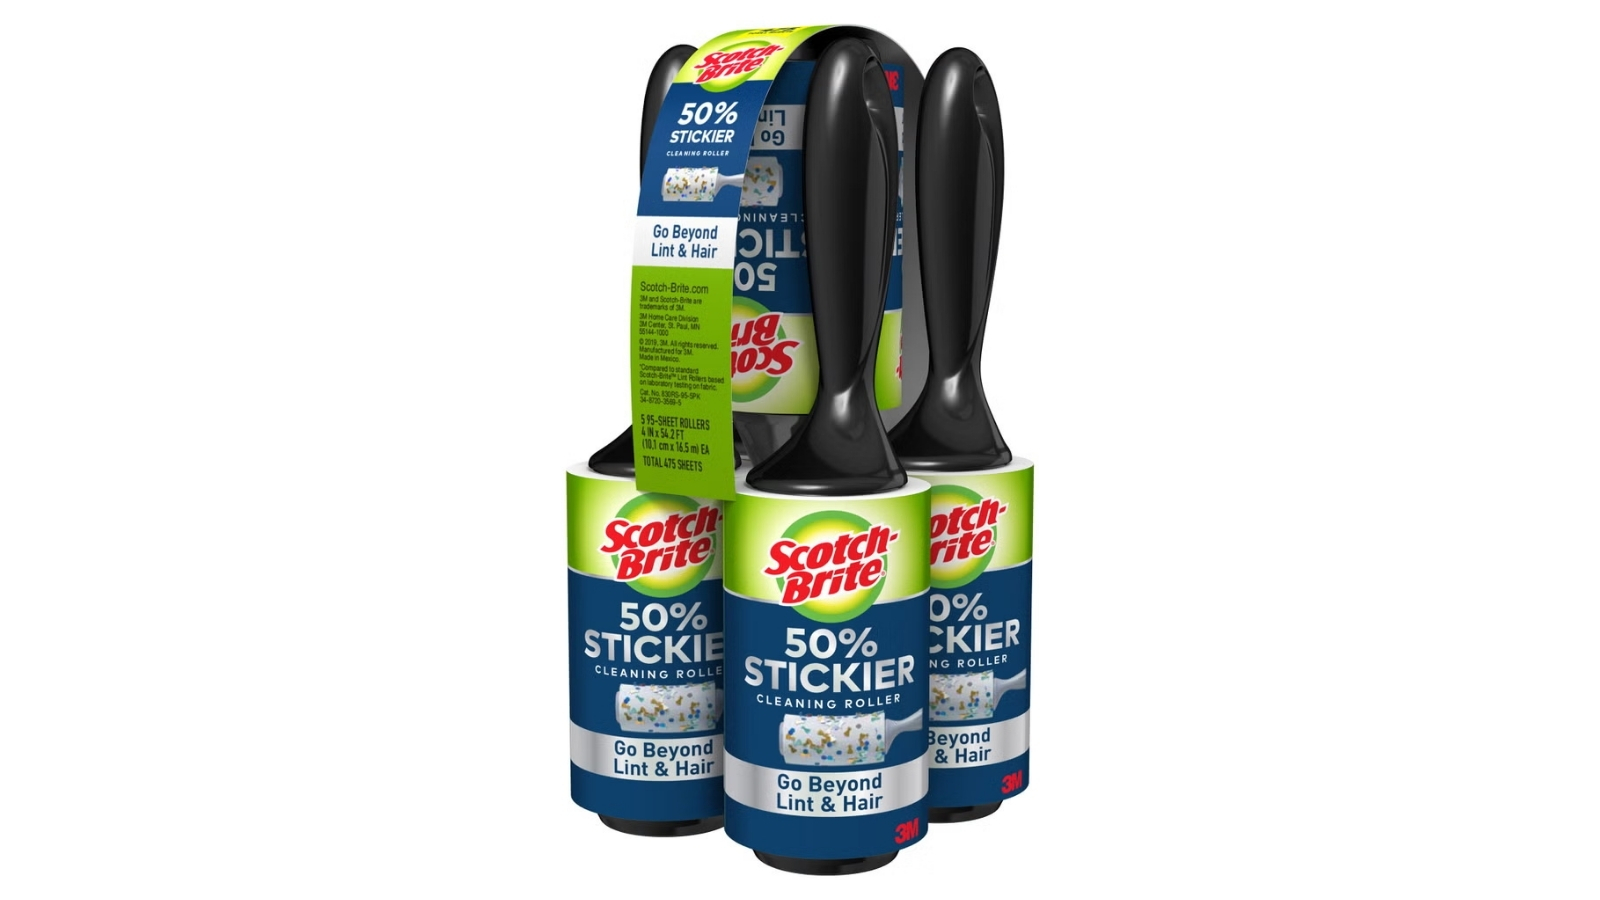
Dark coats and pet hair seem to find each other before every trip out of the house. Scotch-Brite’s five-pack of lint rollers is $20.99, with 95 sheets on each roller. That gives you 475 adhesive sheets for about 4 cents apiece, rather than a small roller that runs out after a few serious coat cleanups.
Even using five sheets a day would stretch the pack for 95 days. Keep one near the door and another with the laundry so clean clothes can be finished before they’re put away. The rollers also pick up loose hair and crumbs from suitable fabric surfaces. They’re particularly useful when a quick surface cleanup is all an otherwise clean garment needs.
Clorox Clean-Up spray and refill
Image Credit: Costco
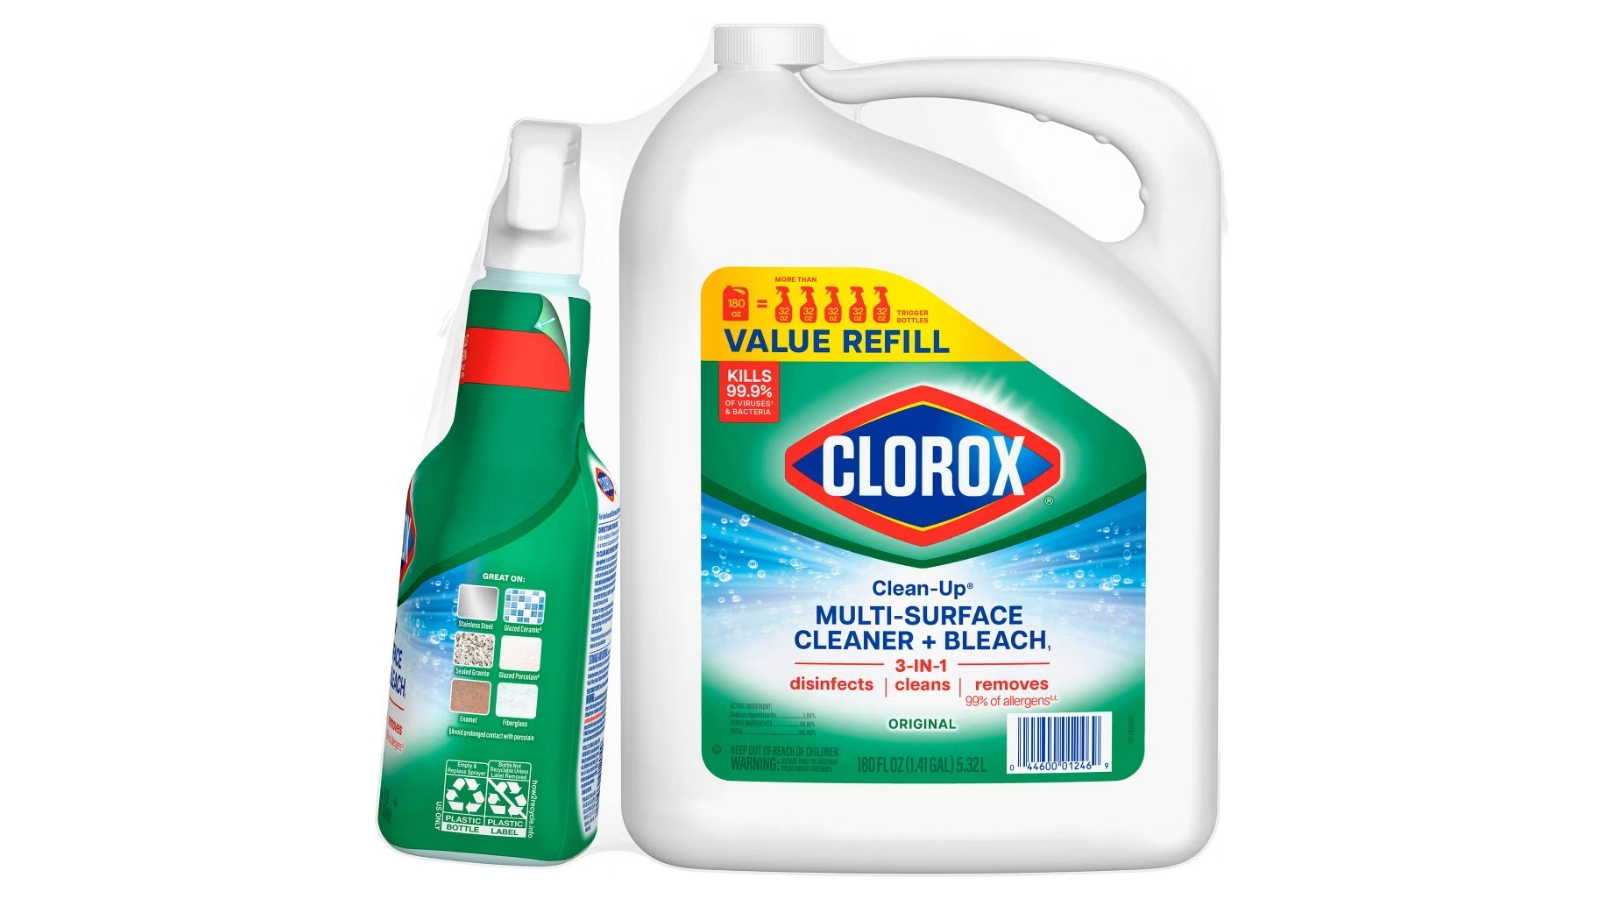
Bathroom mildew stains are a reason to buy a cleaner suited to the job, rather than another pleasant-smelling general spray. This Clorox Clean-Up bundle contains a 32-fluid-ounce spray bottle and a 180-ounce refill for $22.99. The 212-ounce total works out to about 11 cents an ounce.
The refill holds more than five additional spray-bottle fills, giving routine bathroom cleaning plenty of room to run past December. Use it only on compatible surfaces and follow the label’s directions for cleaning and disinfecting. Because it contains bleach, keep it separate from toilet cleaners and other chemicals. The practical value is a reusable trigger bottle backed by a large supply for a recurring bathroom problem.
Lysol disinfecting wipes
Image Credit: Costco
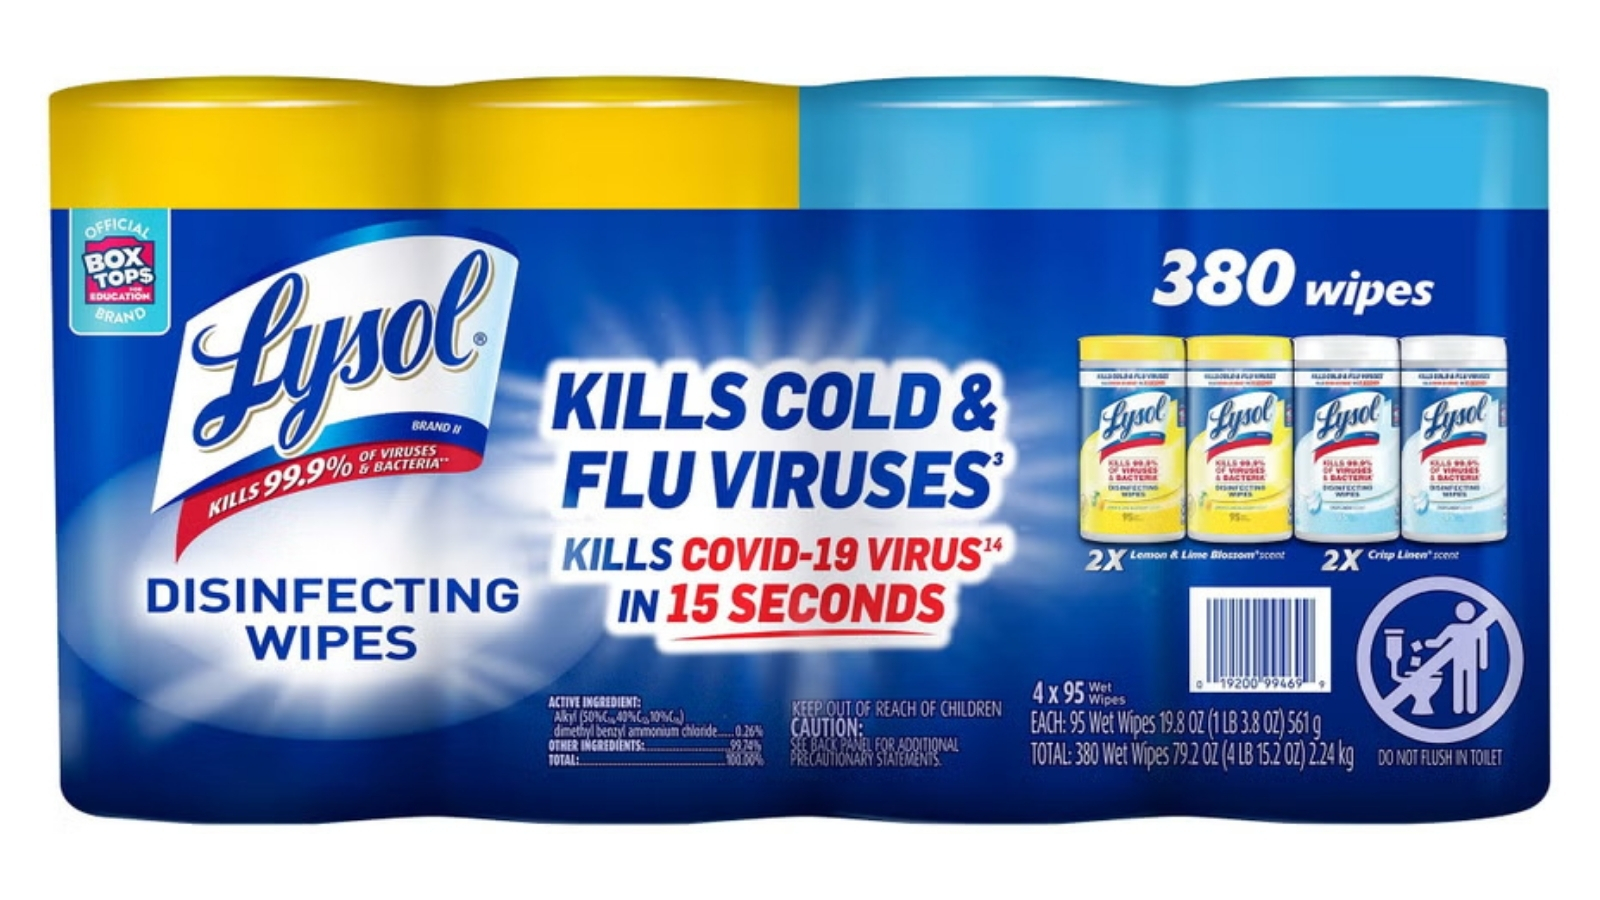
There are moments when a ready-to-use wipe is worth more than assembling a cloth and spray, particularly for small cleanups on shared hard surfaces. Lysol’s four-pack contains 95 wipes per canister, or 380 total, for $14.39. That is just under 4 cents a wipe.
A household using four a day would get about 95 days from the pack. Distribute the canisters where you use them and close the lids properly so the last wipes aren’t dry. They earn their cost for quick, targeted jobs rather than wiping whole floors or large rooms. For disinfection, use enough wipes to keep the surface wet for the time on the label; one hurried swipe isn’t the same thing.
Lysol Advanced toilet bowl cleaner
Image Credit: Costco
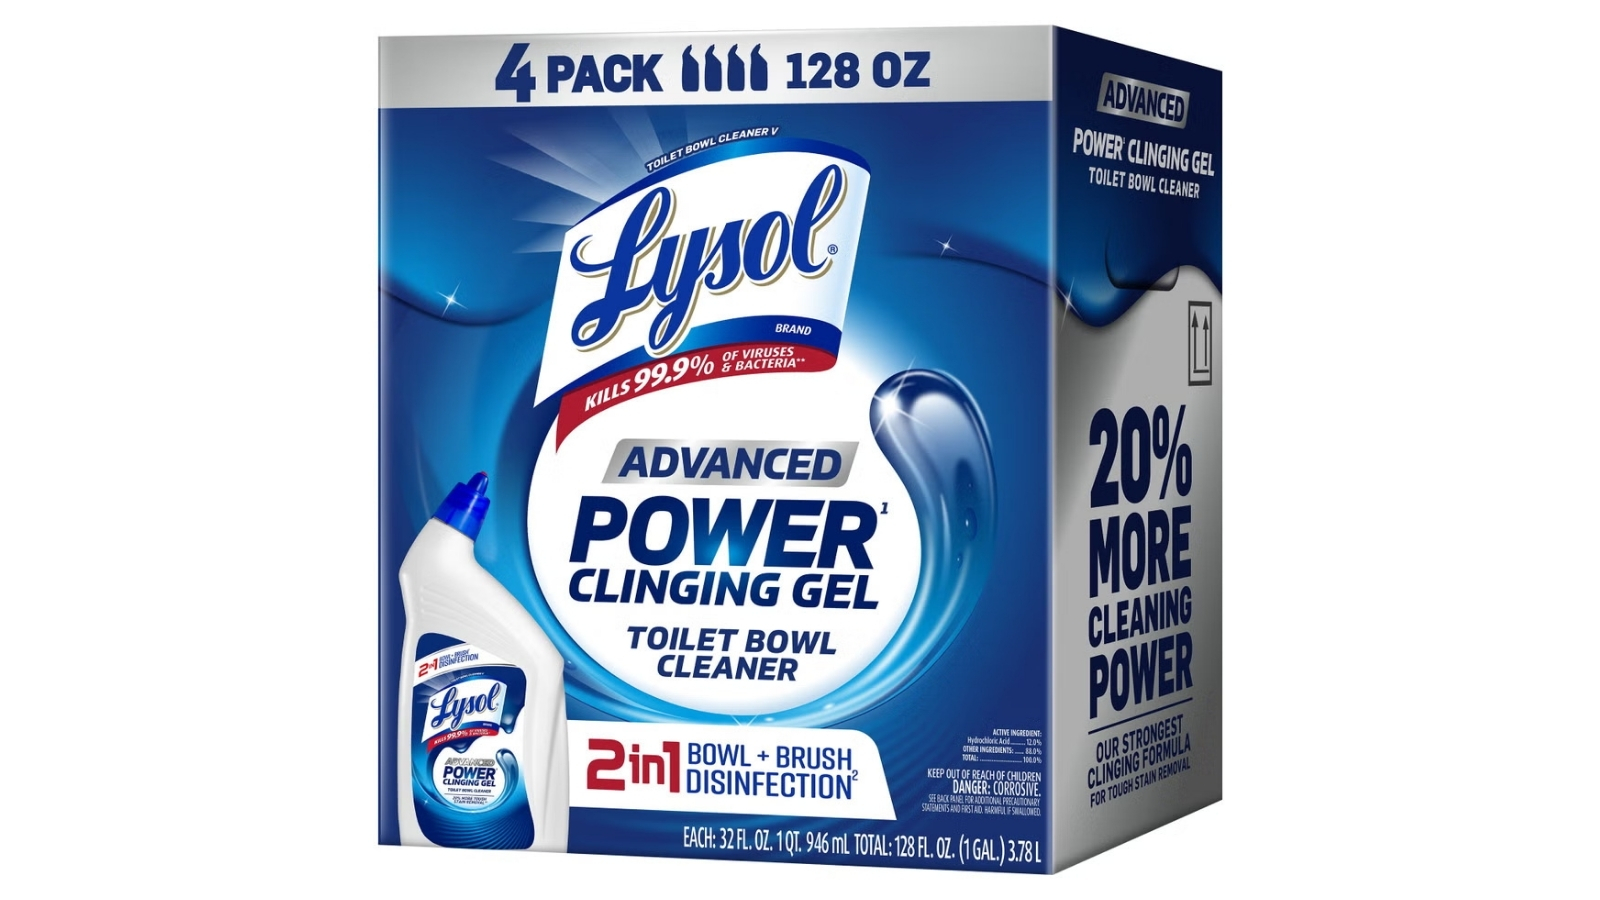
Four 32-fluid-ounce bottles of Lysol Advanced Toilet Bowl Cleaner cost $11.49, about $2.87 per bottle. The thick formula clings inside the bowl, and the angled neck helps direct it beneath the rim. It’s a dedicated cleaner for toilet stains and rings, where a general countertop cleaner isn’t the right tool.
For ordinary household cleaning, four full-size bottles are a reasonable reserve through the end of the year, even with more than one bathroom. Put one by each toilet you clean regularly and store the rest securely. Use it on its own according to the label, never with bleach products. The pack price is low enough that stocking multiple bathrooms doesn’t mean paying convenience-store prices for several separate bottles.
Libman coffee machine descaler
Image Credit: Costco
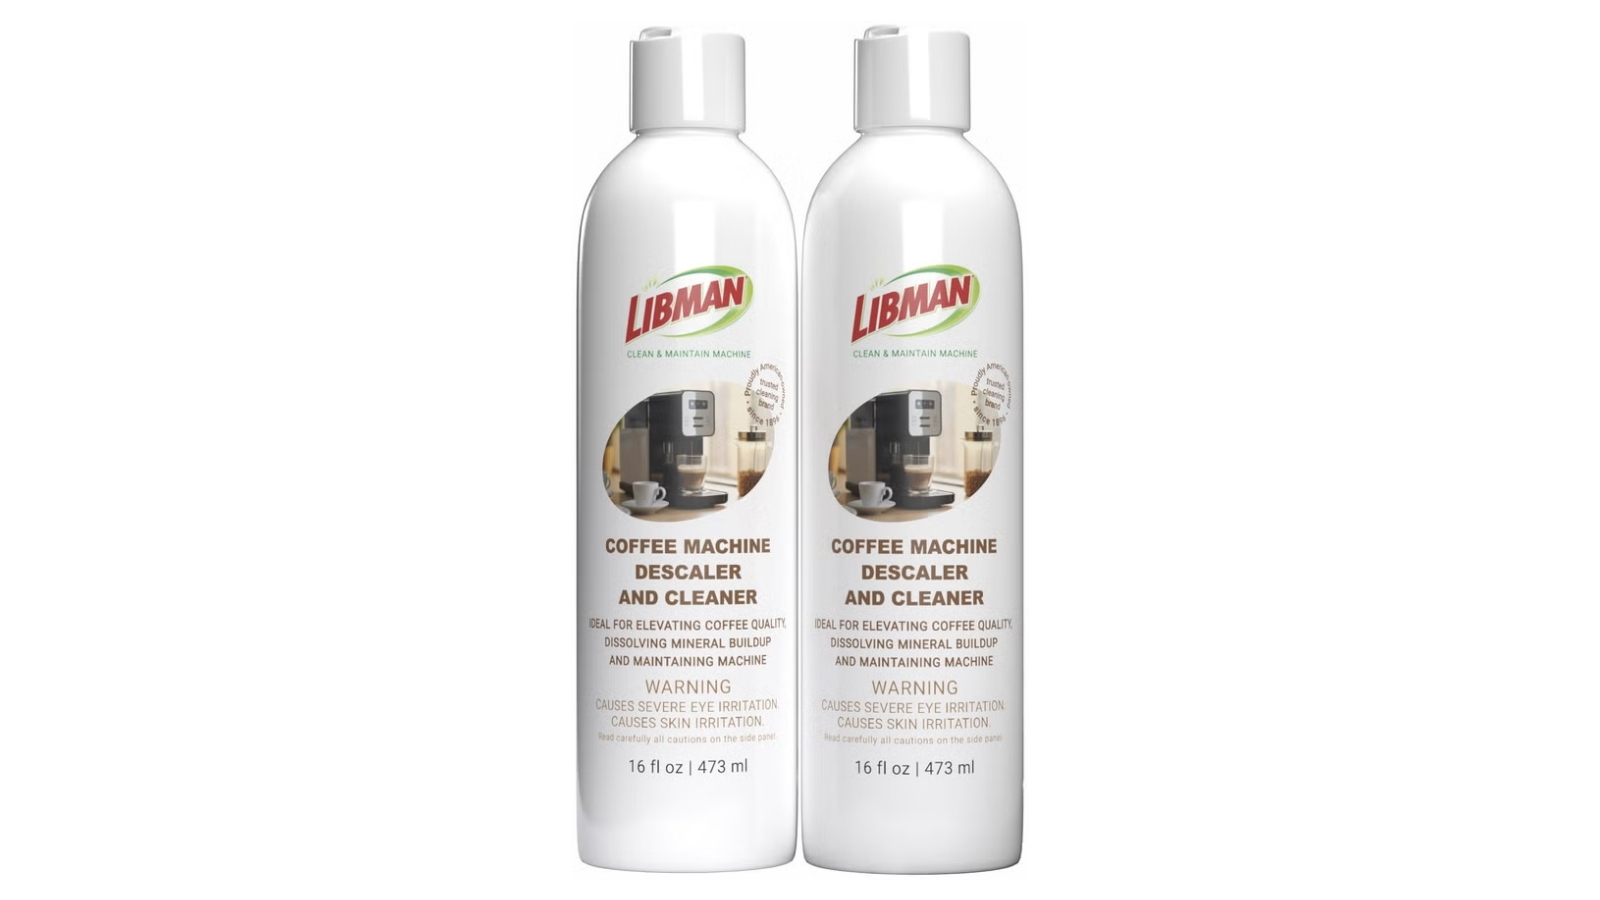
A coffee maker that runs every morning accumulates mineral buildup along with its daily workload. Libman’s descaler and cleaner is $19.99 for two 16-fluid-ounce bottles. With four uses per bottle, the pack supplies eight treatments at about $2.50 each, including shipping.
That’s enough to carry a normal maintenance schedule well beyond December, rather than buying a single treatment each time the machine needs attention. Check your coffee maker’s approved descaling instructions before choosing a product or schedule. Libman’s directions use 4 ounces per cleaning, followed by water-only rinse cycles. For someone who already relies on a home coffee maker, keeping the maintenance supply ready supports an appliance that gets regular use.
Arm & Hammer pure baking soda
Image Credit: Costco
A little cardboard box disappears quickly when baking soda also handles household cleaning. Costco’s resealable 13.5-pound bag costs $9.39, about 70 cents a pound. That gives regular users a much larger reserve for deodorizing and mild scrubbing without paying for a collection of small specialty packages.
Even using a pound a month would leave most of the bag after the year ends. It suits people who already use baking soda for cleaning suitable sinks, utility items, or bins and know where it works in their home. Keep it dry, and separate any portion intended for food from the cleaning supply. Don’t buy it expecting a disinfectant; its value is in inexpensive, familiar cleaning and deodorizing jobs.
Pine-Sol multi-surface cleaner
Image Credit: Costco
Ready-to-use sprays make you pay for a lot of water. Pine-Sol’s two-pack contains two 60-fluid-ounce bottles of concentrated multi-surface cleaner for $17.99. The concentrate can cover routine cleaning of suitable floors, sinks, and other hard surfaces without buying a different bottle for each room.
The labeled 2X-concentrated formula is the reason 120 ounces can stretch further than the same volume of a ready-mixed cleaner. Measure the dilution for the job instead of pouring straight from the bottle, and follow the surface restrictions, including avoiding marble. For a household doing a weekly general clean, two bottles provide a substantial supply for the weeks remaining in the year while keeping the cleaning cupboard manageable.
Type S electric air duster
Image Credit: Costco
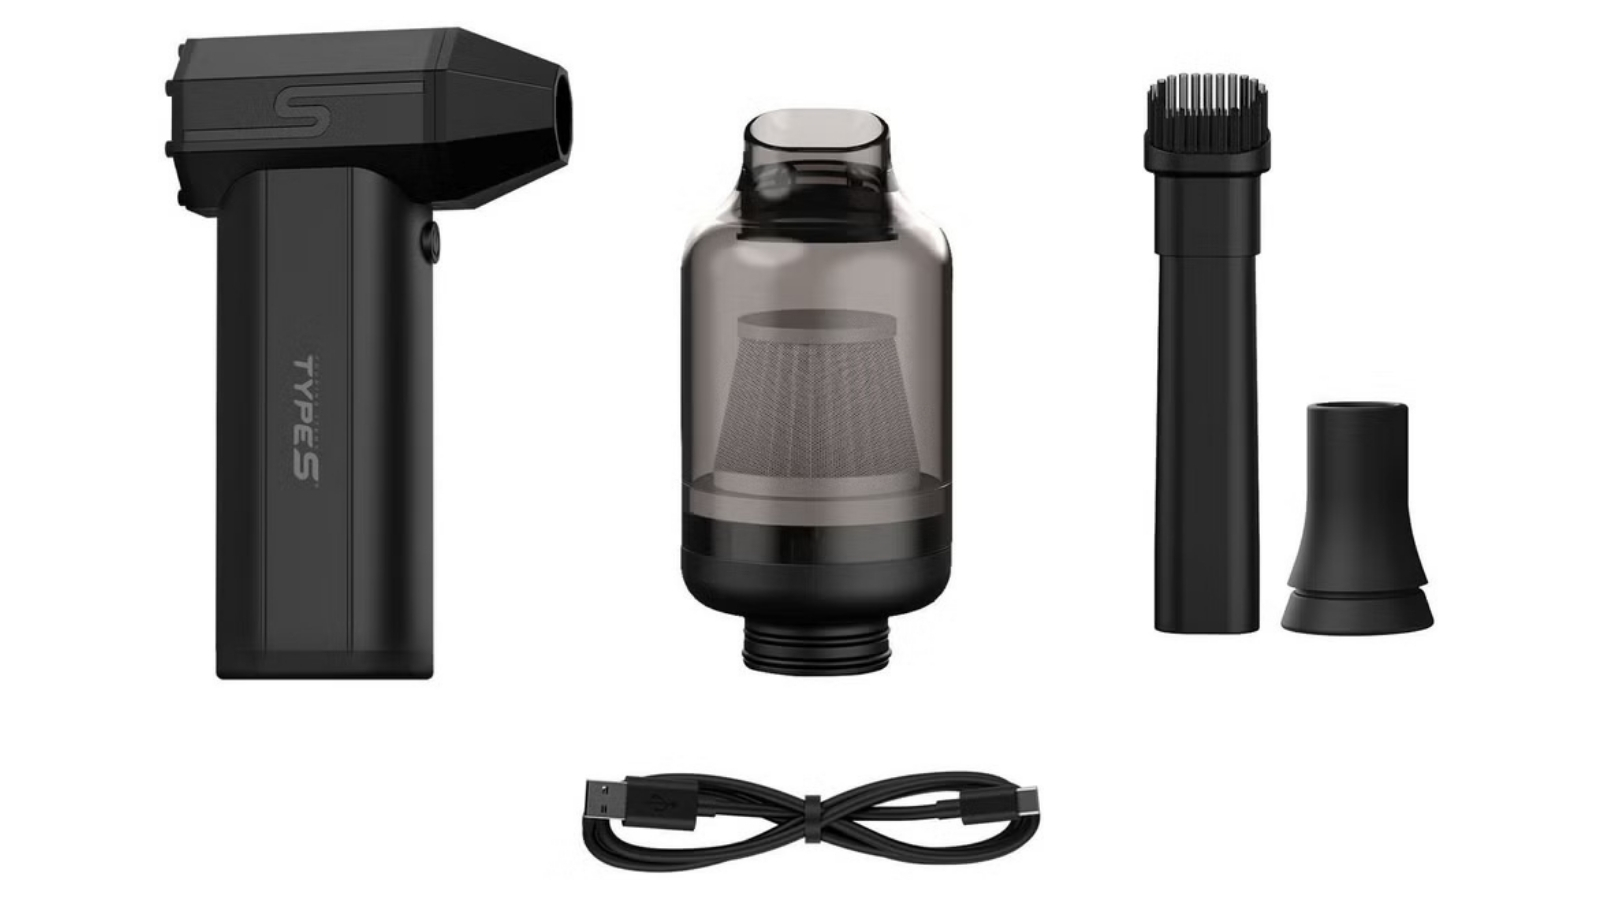
Keyboards, narrow crevices, and dusty car interiors are where an air duster earns its keep. The rechargeable Type S model costs $39.99 and includes a brush, two nozzles, and a vacuum attachment with a washable filter. Four speed settings give it more range than a tool with one fixed blast.
This is a longer-term buy for someone who already uses canned dusters regularly. Charging the device and washing its filter replaces the recurring purchase of disposable cans, with a tool that remains useful after December. It isn’t a necessary purchase for someone who dusts a keyboard twice a year. Frequent home-office or car cleanup gives the upfront price a more realistic chance to pay for itself.
Kirkland Signature nitrile gloves
Image Credit: Costco
For grubby cleanup jobs, Kirkland Signature’s 400-count nitrile glove pack costs $21.99. That’s about 5.5 cents a glove, or 11 cents a pair. The powder-free gloves come in several sizes, so you can choose a fit that lets you handle cloths and small items comfortably.
Four hundred gloves provide 200 pairs, enough for several cleanup sessions a week through the end of the year. They are useful for dirty tasks involving mild cleaners, and the disposable format lets you start the next job with a fresh pair. Check chemical compatibility before using them with a cleaning product; thin exam gloves aren’t universal protection against harsh chemicals. Keep the box away from heat and direct sunlight.
The Pink Stuff cleaning paste bundle
Image Credit: Costco
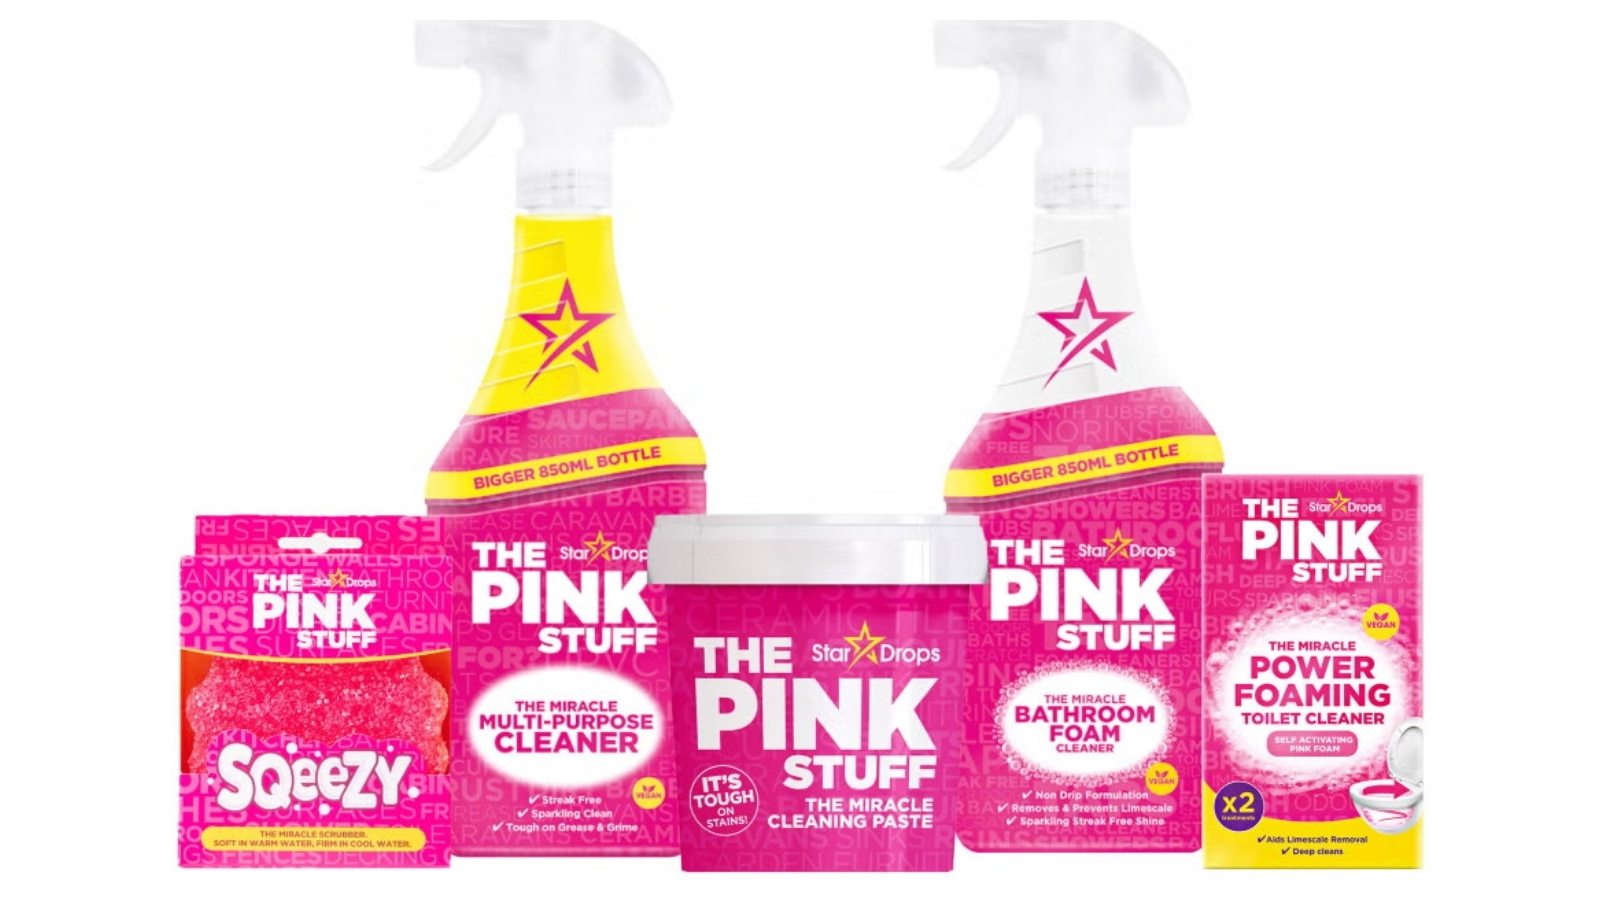
Stubborn grime sometimes needs a paste that stays where you’re scrubbing. The Pink Stuff’s $26.99 bundle includes an 850-gram tub of cleaning paste, multi-purpose and bathroom sprays, a box containing two toilet-foam packets, and a dual-sided sponge. The large paste tub is the main long-lasting supply for occasional tougher jobs.
For someone already using The Pink Stuff, the bundle groups several usable cleaning supplies into one purchase. Small applications of paste on compatible sinks, cookware, or other surfaces should give that tub a long working life through the holiday season. Test an inconspicuous spot first because abrasive cleaners don’t suit every finish. The two toilet packets are extras, rather than the reason to expect the whole set to last.
Windex glass cleaner and refill
Image Credit: Costco
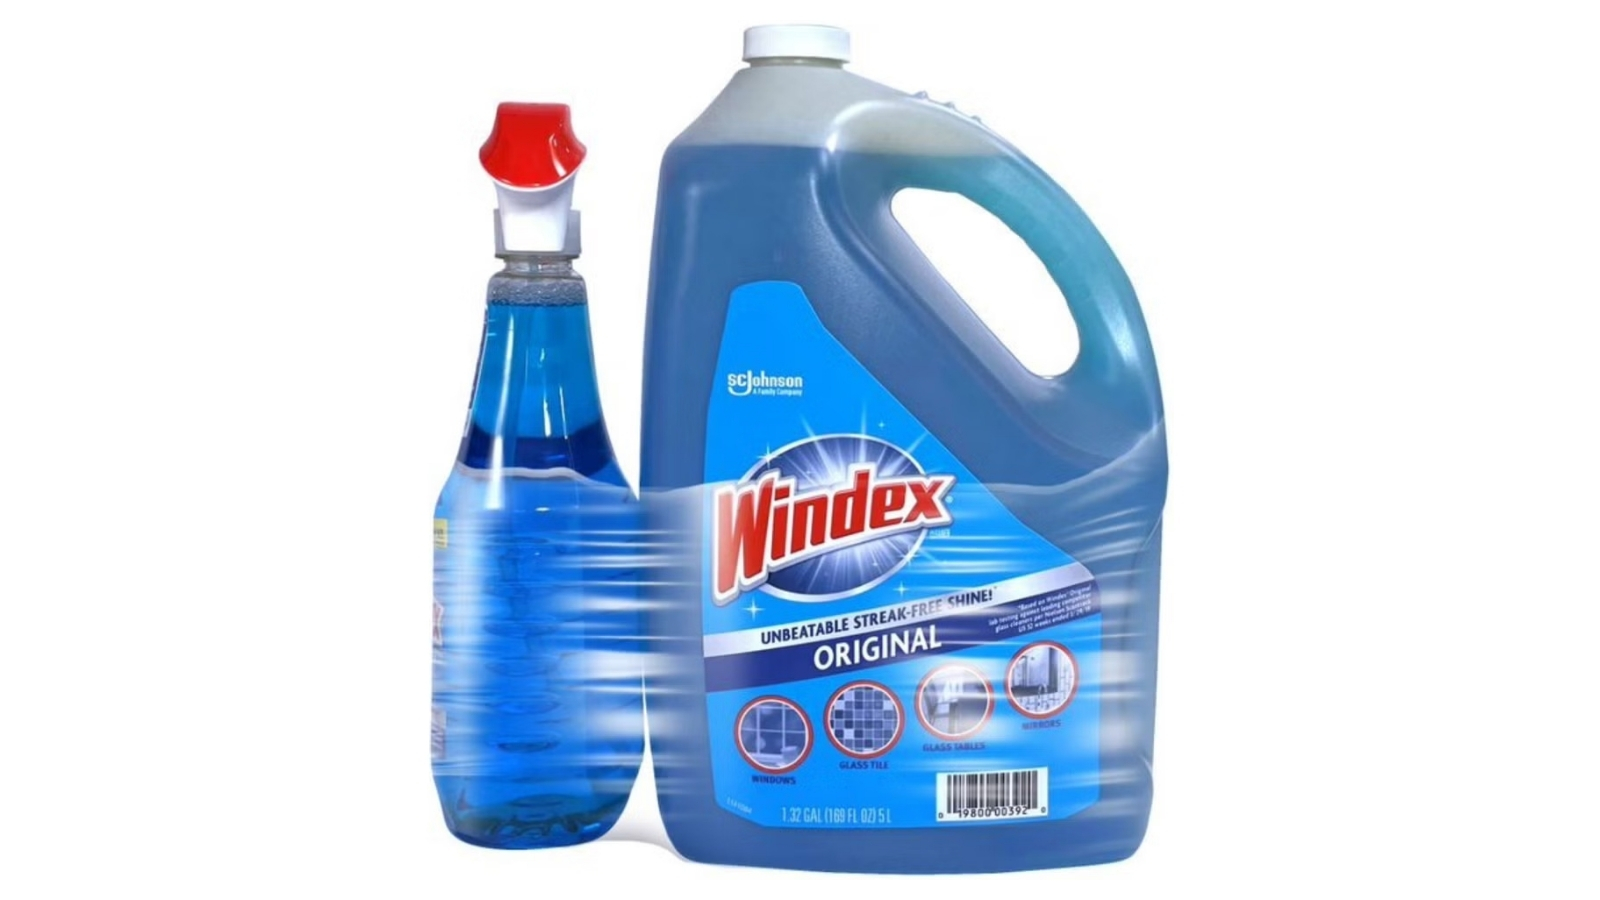
One bottle of glass cleaner can disappear surprisingly fast when you’re cleaning mirrors, windows, and a glass dining table. This Windex bundle pairs a 32-fluid-ounce spray bottle with a 169-ounce refill for $15.99. That’s 201 ounces altogether, or about 8 cents an ounce.
The refill holds more than five additional spray-bottle fills. Even using a full 32-ounce bottle each month would leave plenty after December, making the bundle practical for a home with several glass surfaces. Keep the original trigger bottle and refill it as needed rather than buying a new sprayer each time. Use it on the glass surfaces listed on the label, rather than assuming every screen or coated surface is suitable.