scroll top

Roughly 3.8 million people with Medicare Advantage are getting a version of the same letter this fall: their plan will not exist when January arrives. It isn’t a premium increase or a trimmed network inside a plan that otherwise stays the same. The plan itself is being discontinued, and the explanation on the page is almost always some version of “market changes,” which is corporate shorthand for a number that stopped working for the insurer in that particular county.

That figure is up from 2.9 million last year, which was already the roughest stretch Medicare Advantage had seen. For 2027, Advantage coverage is disappearing entirely in 181 counties, up from just 67 the year before. If you live in one of those counties, there’s no local Advantage plan waiting to take you in. Everyone else whose plan is ending still has options inside their own county, but they have to go find them, because nobody is going to pick one for them.

The part that gets buried in a lot of reporting on this story is a federal protection you’re entitled to specifically because the insurer is the one ending the relationship, not you. It has nothing to do with Medicare itself and everything to do with how private insurers are allowed to underwrite health risk once you try to buy supplemental coverage on your own.

The scope of the 2027 shakeup

Medicare Advantage plans written in a notebook beside a stethoscope
Image Credit: Shutterstock

The 3.8 million figure covers everyone being pushed off a Medicare Advantage plan for 2027, whether their insurer left the county entirely or simply discontinued the specific plan they were enrolled in. Most of those people aren’t stranded. More than 99% of Medicare beneficiaries will still have access to at least one Advantage plan in 2027, and 97% will have ten or more to choose from. For most of the 3.8 million, this is an inconvenience that requires an afternoon of comparison shopping, not a crisis.

The harder situation belongs to the people in the 181 counties where no Advantage plan will be sold at all for 2027. Original Medicare becomes the only Medicare option there, full stop. Rural counties make up a disproportionate share of that list, which tracks with a pattern insurers have followed for years: the places with the fewest providers and the thinnest enrollment tend to be the first dropped when a plan’s margins get tight. Roughly eight in ten Advantage beneficiaries will be able to keep their current plan at the same premium or lower in 2027, which is the detail insurers tend to lead with, and the one that offers zero comfort if you’re in the minority getting the letter instead.

UnitedHealthcare and Humana lead the retreat
Older couple looking at a laptop together on a sofa
Image Credit: Shutterstock

UnitedHealthcare, the country’s largest Medicare Advantage insurer, is exiting Wyoming’s individual market entirely for 2027, and dropping individual Medicare Advantage coverage in about 140 counties nationwide. The company has confirmed that roughly 390,000 of its members are enrolled in plans being discontinued for 2027, with notice letters going out in early October. The cuts are landing hardest on PPOs, the plans that let members see providers outside a set network: the share of UnitedHealthcare members with access to both an HMO and a PPO is falling from 70% in 2026 to 66% in 2027 as the company steers toward narrower, cheaper-to-run HMO networks instead.

Humana is making a smaller geographic retreat but a larger one in sheer membership. The company’s 2027 plan exits will affect about 600,000 members, concentrated in specific markets rather than spread evenly: Humana is leaving the individual Medicare Advantage market in Minnesota, where it had fewer than 10,000 enrollees, while continuing to sell plans in 2,600 counties across 45 states and Washington, D.C., more than 80% of the country. For members in a discontinued plan, the size of Humana’s remaining footprint is beside the point. What matters is whether a comparable plan is still sold at their own address, and that has to be checked county by county, not state by state.

Aetna and Molina make their own cuts
Wooden letter tiles spelling Medicare Advantage beside a stethoscope
Image Credit: Shutterstock

Aetna is pulling standard Medicare Advantage plans from about 123 counties and leaving Maryland and New Hampshire entirely for 2027, two states where forced plan exits already ran unusually high heading into this year. The insurer is cutting 20 PPO plans from its lineup while adding 29 plans aimed at people with chronic conditions, a trade that fits the broader industry shift away from broad-network products and toward plans built around managing specific, expensive diagnoses.

Molina Healthcare’s move is simpler and more complete. The company is exiting the standard individual Medicare Advantage market nationwide for 2027, dropping the prescription-drug-included plans it sells to the general Medicare population entirely. Molina is keeping only its Dual Eligible Special Needs Plans, built for people who qualify for both Medicare and Medicaid, which the company has decided fits its core business better than competing for ordinary Medicare Advantage shoppers. Anyone in a standard Molina MAPD plan loses that coverage outright and has to replace it with something from another carrier, or with Original Medicare.

Why the exits keep happening
Woman reviewing paperwork with a calculator beside her laptop
Image Credit: Shutterstock

The underlying problem is simple to describe and hard for insurers to fix. For years, what Medicare pays private insurers to run these plans hasn’t kept pace with how fast medical costs and care utilization have climbed. CMS initially proposed a nearly flat 0.09% average payment increase for 2027 in January, worth about $700 million industry-wide and far below the 5%-plus bump insurers received heading into 2026. That proposal alone wiped tens of billions of dollars off health insurer stock values in a single day.

CMS reversed course in April and finalized a payment increase of nearly 5% for 2027, worth roughly $26 billion in additional payments nationally, well before insurers locked in the 2027 bids they submitted that June. The healthier number didn’t reverse the plan exits already underway. After a stretch of years in which medical costs climbed faster than government payments, insurers are using 2027 to permanently narrow their networks toward HMOs and special needs plans, which cost less to run than the broad-access PPOs behind much of this year’s cuts. One decent rate year doesn’t undo a strategic shift that’s already in motion, and it doesn’t make a money-losing county profitable again on its own.

Shop the plans still standing in your county

Person using a tablet beneath a Time to Renew message
Image Credit: Shutterstock

If your plan is ending, the first move is also the most obvious one, and it’s the one people skip because the old plan worked fine and shopping for insurance is nobody’s idea of a good afternoon. Medicare’s Plan Finder tool at Medicare.gov lets you search every Advantage plan sold at your address, compare premiums and out-of-pocket maximums side by side, and see which plans include drug coverage without a separate Part D purchase. The regular Annual Enrollment Period runs October 15 through December 7, and anything you choose during that window takes effect January 1.

Don’t assume the replacement plan your insurer nudges you toward, sometimes called a crosswalk plan, is actually your best option. Insurers often default displaced members into whatever plan is closest on paper to the one that’s ending, and it is frequently not the cheapest or most generous choice available in that county. Run the comparison yourself, or call 1-800-MEDICARE and have someone walk you through it, before an automatic reassignment makes the decision for you.

Confirm your doctors and prescriptions actually transfer

Medicare Part D written on a notebook beside a stethoscope
Image Credit: Shutterstock

A plan that looks identical to your old one on a premium comparison chart can still run on a completely different network of doctors and hospitals, and Medicare Advantage plan directories are notoriously unreliable about who’s actually still accepting new patients. Call your doctor’s billing office directly and ask whether they’re in-network for the specific plan you’re considering, not just the insurance company generally. The same caution applies to specialists and to any hospital system you’d use for a planned procedure.

Prescriptions deserve the same scrutiny. Run every medication you currently take through the plan’s formulary before you enroll, because drug tiers and prior authorization rules shift from plan to plan even within the same insurer’s lineup, and a drug that cost you little this year can jump tiers in a new plan without warning. If you’re switching to Original Medicare instead of another Advantage plan, you’ll need a standalone Part D plan to cover prescriptions, since Original Medicare alone doesn’t include drug coverage at all.

The guaranteed-issue window almost nobody mentions

Medicare enrollment form on a clipboard beside a stethoscope
Image Credit: Shutterstock

Here’s the protection buried in the fine print: when a Medicare Advantage plan leaves Medicare or stops covering your area, federal law gives you a guaranteed-issue right to buy a Medigap policy without medical underwriting. Normally, insurers can deny you a Medigap policy or charge you more because of your health history unless you’re inside your one-time, six-month Medigap enrollment window right after turning 65. A plan termination reopens that door, but only if you move to Original Medicare as your replacement rather than enrolling in a different Advantage plan.

The window is narrow and worth marking on a calendar: you can apply as early as 60 days before your old coverage ends and as late as 63 days after it ends, though your new Medigap coverage can’t actually start until the old Advantage plan’s coverage has stopped. For someone with a health condition that would normally get a Medigap application denied or priced out of reach, this is one of the only chances that ever comes along to buy that protection on fair terms. It’s worth pricing out even if you’re currently leaning toward another Advantage plan instead, just to know what you’d be giving up.

What happens if you let the deadline pass

Medicare premiums written on a chalkboard beside a prescription and stethoscope
Image Credit: Shutterstock

Doing nothing is itself a decision, and it’s the worst one available. If your terminated plan’s coverage runs through December 31 and you haven’t chosen anything by then, you’re automatically moved into Original Medicare on January 1, with no prescription drug coverage and no Medigap policy attached. Original Medicare alone has no annual cap on what you could owe out of pocket, a protection your old Advantage plan almost certainly included.

The regular Annual Enrollment Period closes December 7, but losing your plan to a non-renewal buys you extra time most people don’t realize they have: a Special Enrollment Period runs from December 8 through the last day of February, specifically for people whose plan didn’t renew. Use the extra weeks if you need them to compare options properly, but don’t treat them as an excuse to drift into January with no drug coverage in place. Pick a direction, enroll in it, and confirm the effective date before the calendar makes the choice for you.

None of this makes the letter in your mailbox any less annoying to deal with. It does mean you have more room to maneuver than the letter lets on, and a deadline that, used properly, works in your favor instead of against it.
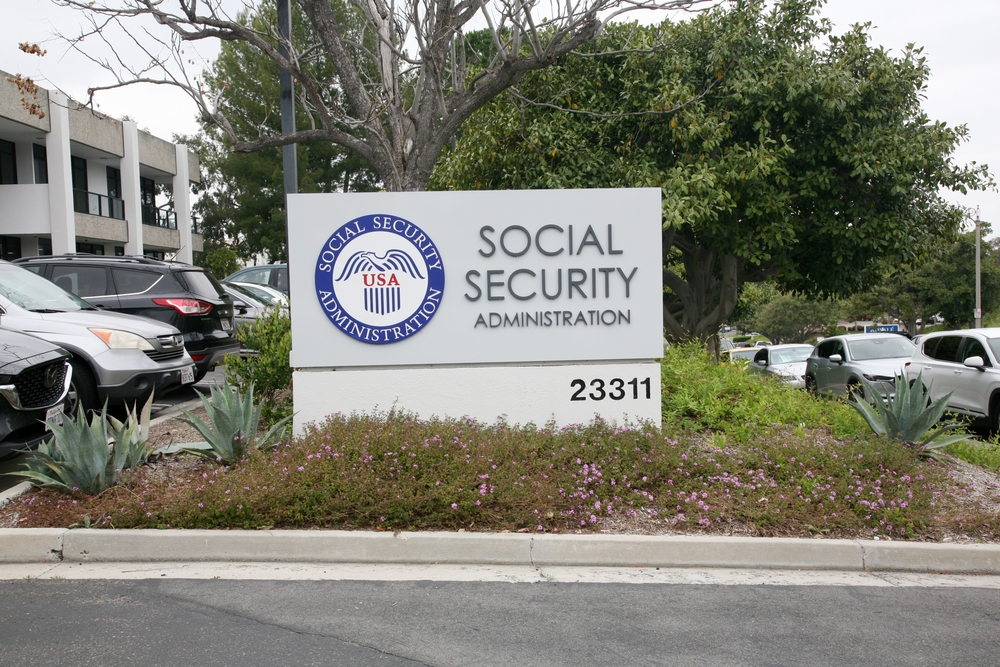
Social Security raised one of its administrative fees to $74 on October 1, and the line item carries a name only a bureaucrat could love: Third Party Manual SSN Verification. If you only caught the headline somewhere between “Social Security” and “new fee,” it’s reasonable to assume your monthly check is about to shrink. It isn’t.

This charge has nothing to do with retirement, disability, or survivor benefits. It applies to businesses and other outside parties who ask the Social Security Administration to manually confirm that someone’s name and number match, usually for a reason that has nothing to do with running a Social Security program in the first place. Think a mortgage application, a background check, or a lawyer sorting out an estate, not your deposit.

The fee itself has climbed by more than 20% since the last update in 2024, and it sits buried inside a longer list of administrative charges most people have never seen.

What the $74 fee actually covers

Social Security Administration sign outside a field office
Image Credit: Shutterstock

Social Security calls this category standard administrative fees for non-program information, and it covers paperwork requests that have nothing to do with someone applying for or managing their own benefits. Section 1106 of the Social Security Act gives the agency authority to charge the full cost of providing information whenever a request falls outside the administration of its own programs, and federal cost-recovery rules require the agency to review this fee table at least every two years to make sure it still matches what the work actually costs.

The update that includes the new charge is a schedule SSA published in the Federal Register, effective for requests received on or after October 1, 2026. It covers ten separate services, everything from copying a case folder to certifying earnings records, and Third Party Manual SSN Verification is just one line in that table.

“Manual” is the operative word. It applies when a request comes in the old-fashioned way, by phone, mail, fax, or a visit to a field office, rather than through one of Social Security’s automated, high-volume verification systems. That distinction matters more than it sounds like it should, because it’s a big part of who actually ends up paying.

Who actually gets the bill

Woman reviewing a folder while working on a laptop at an office desk
Image Credit: Shutterstock

Employers get a pass here, within limits. Social Security’s online Social Security Number Verification Service lets any registered employer check that a worker’s name and number match Social Security’s records at no cost, as long as the reason is wage reporting.

That free tool comes with a hard boundary, though. Social Security specifically warns employers against using it for anything outside payroll, things like a credit check, an identity check, or confirming a number for a mortgage. Those requests fall into fee territory, and if they’re filed manually rather than through one of Social Security’s bulk electronic channels, the $74 charge applies.

In practice, that puts the bill on businesses rather than beneficiaries. The people writing checks for this are mortgage lenders, background-check companies, debt collectors, attorneys handling an estate or a legal dispute, and smaller employers who skip the free online tool and mail in a one-off request instead. Banks and large screening firms running thousands of verifications a month typically use a separate, subscription-based electronic system with its own pricing, so the $74 fee tends to land hardest on smaller or occasional requesters rather than the high-volume players who built automated accounts years ago.

How the price has moved, and not all one direction

Woman reviewing paperwork with a calculator beside her laptop
Image Credit: Shutterstock

Two years ago, the same manual verification request cost $61. The jump to $74 works out to roughly a 21% increase in two years, which Social Security attributes to the gap between what it actually costs to process these requests and what it had been charging.

The rest of the fee table didn’t move in one tidy direction. Copying a paper case folder rose from $122 to $151, and pulling a record extract went from $41 to $46. But copying an electronic folder actually dropped, from $82 down to $75, and a copy of an original Social Security card application fell from $27 to $23. Social Security doesn’t publish a line-by-line explanation for each individual change, only that the whole table gets recalculated against current operating costs on a two-year cycle required by federal user-fee rules.

For a one-off request, the $13 difference between $61 and $74 won’t break anyone. It adds up faster for the businesses and law firms that file these fairly often, which is part of why some of them eventually set up accounts with Social Security’s automated bulk systems instead of paying the manual rate request by request.

What’s still free

Social Security cards beside US dollar bills
Image Credit: Shutterstock

None of this touches the services most people actually rely on. A free my Social Security online account lets anyone check their earnings record, see a benefit estimate, and manage an existing claim without paying a cent.

Replacing a lost or stolen Social Security card is also free, no matter how many times you’ve needed to do it, and Social Security’s inspector general has repeatedly reminded the public not to pay any website that claims otherwise. Applying for retirement, disability, or survivor benefits costs nothing either.

The new $74 charge sits entirely outside that world. It’s a fee for outside parties asking Social Security to do a specific, manual piece of paperwork on someone else’s behalf, not a cost that touches anyone collecting a Social Security check.

If a fee like this ever does land in front of you, it will come from a business asking Social Security to verify your information, not the other way around.

If you take Ozempic, Wegovy, or Rybelsus and you’re on Medicare, your prescription is about to get a lot cheaper. Starting January 1, 2027, the price Medicare pays for those drugs drops from $959 to $274 for a month’s supply, a 71% cut built into the second round of drug price negotiations under federal law.

Part D’s deductible is jumping by more than it ever has at the very same time those drug prices are falling, rising from $615 to $700. Medicare Advantage premiums are dropping too, your plan’s star rating just got recalculated under new rules, and the agents calling you this fall have more room to do it than they did last year.

Open enrollment for 2027 coverage runs from October 15 through December 7, 2026. Some of what follows is already locked into law. A couple of numbers, including the regular Part B premium almost everyone pays, won’t be official until CMS makes its usual November announcement.

Medicare’s second round of negotiated drug prices kicks in

Woman taking US dollar bills from a wallet beside prescription medication
Image Credit: Shutterstock

Starting January 1, 2027, Medicare’s negotiated prices take effect for 15 more brand-name drugs, on top of the 10 that became effective in January 2026. The biggest one by sales is Ozempic, Rybelsus, and Wegovy, which drop from $959 to $274 for a month’s supply, a 71% cut. Xtandi, used for prostate cancer, falls from $13,480 to $7,004, a 48% cut. The other 13 drugs on the list treat conditions ranging from asthma and COPD to multiple myeloma and bipolar disorder, with discounts mostly between 40% and 85% off their 2024 list prices.

Across all 15 drugs, Medicare projects it will save $12 billion, a 44% cut from what it spent on these same drugs in 2024. That number reflects total program spending, not what any one person pays at the pharmacy. The actual benefit to your wallet depends on your plan’s formulary tier and where you land in Part D’s coverage phases, but the negotiated price is now the ceiling. Plans and pharmacies are required to make it available to everyone who qualifies, bringing the total number of Medicare-negotiated drugs to 25.

The Part D premium subsidy ends, but premiums aren’t spiking

Notebook labeled Medicare Part D beside a stethoscope
Image Credit: Shutterstock

For the past two years, Washington has been propping up standalone Part D drug plans with extra federal money through the Part D Premium Stabilization Demonstration. That subsidy disappears after 2026. CMS says insurers have had enough time operating under the Inflation Reduction Act’s redesigned drug benefit that they no longer need the support, so standalone prescription drug plans go back to setting prices under normal market conditions starting in 2027.

The number everyone expected to spike didn’t. CMS projects the average standalone Part D premium will rise by less than $1 a month, from $35.09 to $36. The national base beneficiary premium, the figure used to calculate each plan’s basic premium rather than what you actually pay, is set at $41.33 for 2027, up from $38.99. A provision in the same 2022 law caps how fast that base number can grow each year through 2029, which is a big part of why the subsidy’s end didn’t translate into sticker shock.

Medicare Advantage premiums are falling to their lowest point in years

Medicare premiums chalkboard with prescription paperwork, medicine packs and a stethoscope
Image Credit: Shutterstock

If you’re in a Medicare Advantage plan, 2027 is shaping up to be a good year for your premium. CMS projects the weighted average MA premium, which includes plans with drug coverage and special needs plans, will fall from $14.37 to $12 a month, a drop of more than 16%. Plans that bundle in drug coverage are the bigger story. After rebates, the average Part D premium inside those plans is projected to drop 38%, from $11.32 to $7 a month.

CMS also says roughly eight in 10 Medicare Advantage enrollees will be able to keep their current plan at the same premium or lower in 2027, and supplemental extras like dental, vision, and hearing coverage are expected to hold steady rather than shrink. None of this means every plan gets cheaper. Averages hide a lot, and a plan that raised its premium last year could still do it again. It’s worth pulling up your plan’s actual 2027 numbers rather than assuming the national trend applies to you.

Part D’s deductible and out-of-pocket cap are jumping more than they ever have

Worried older couple reading a letter beside an open laptop
Image Credit: Shutterstock

Here’s the catch to all that savings elsewhere. The standard Part D deductible is rising from $615 to $700, a 13.8% increase, and the annual out-of-pocket cap is climbing from $2,100 to $2,400, up 14.3%. Both are the largest single-year jumps since the current cost-sharing structure took effect. CMS adjusts these numbers every year based on growth in prescription drug spending, and 2027’s growth rate came in higher than usual.

The cap is still the part of this worth remembering. Once your out-of-pocket drug spending hits $2,400, you pay nothing more for covered prescriptions for the rest of the year. And if hitting that number early in the year would wreck your budget, the Medicare Prescription Payment Plan lets you spread your out-of-pocket costs into monthly installments across the calendar year instead of paying it all at the pharmacy counter. It doesn’t lower what you owe, but it changes when you owe it, which matters if your income arrives in a fixed monthly check.

Medicare Advantage and Part D star ratings just got rewired

Medicare enrollment form on a clipboard with a pen and stethoscope
Image Credit: Shutterstock

CMS finalized a significant overhaul of the star rating system that decides how Medicare Advantage and Part D plans get graded, and some of it works in the plans’ favor. The agency is removing 11 of the measures it previously used to calculate ratings, mostly ones tied to administrative paperwork rather than patient outcomes, and it scrapped a planned reward factor called the Health Equity Index before it ever took effect, keeping the older, simpler reward formula instead.

CMS is also adding a new measure for depression screening and follow-up care starting with the 2027 measurement year. Taken together, these changes are expected to push average star ratings higher for a lot of plans once they show up in the 2029 ratings cycle, not because care actually improved but because the scorecard changed. If you pick a plan partly on its star rating, that number is measuring something slightly different than it was before, and a five-star plan in 2029 isn’t automatically providing the same care as a five-star plan today.

Telehealth coverage is secure for the entire year

Older woman talking on a phone while using a laptop at home
Image Credit: Shutterstock

This one’s good news, and it almost didn’t happen. Medicare’s telehealth flexibilities, the rules that let you see a doctor by video or phone from home instead of driving to a clinic, have lapsed and been patched back together by Congress several times since 2023. In February 2026, lawmakers folded a two-year extension into a government funding bill, and those flexibilities now run through December 31, 2027.

In practical terms, that means you can keep getting telehealth visits from home regardless of where you live, audio-only calls still count as a covered visit, and a wide range of providers, not just specialists at hospitals, can bill Medicare for seeing you remotely. The mental health telehealth rules are covered too. You still don’t need an in-person visit before starting virtual therapy or psychiatric care. None of this is permanent. Congress tied it to the next funding deadline again, so it’s worth watching what happens toward the end of 2027.

Weight-loss drug coverage holds steady, but the bigger expansion got pushed back

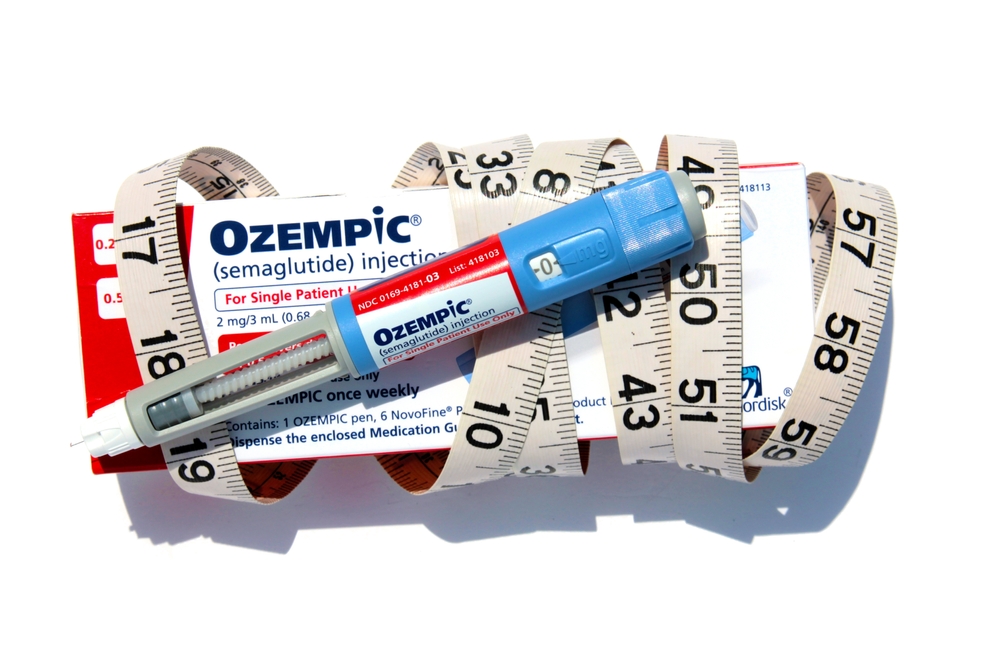
Ozempic injection pen and packaging on a tabletop
Image Credit: Shutterstock

If you’re using a GLP-1 drug like Wegovy or Zepbound for weight loss rather than diabetes, Medicare’s temporary bridge program keeping your copay low is sticking around. The Medicare GLP-1 Bridge caps your copay at a flat $50 a month regardless of dose, and it now runs through December 31, 2027 instead of ending this December as originally planned.

The reason it got extended is that the bigger plan behind it stalled. CMS had intended to launch a broader model called BALANCE on January 1, 2027, which would have let individual Part D plans choose to cover GLP-1s for weight loss as a standard benefit. Not enough insurers signed on, so CMS delayed that rollout indefinitely and kept the bridge program running in its place. One wrinkle worth knowing: the Extra Help low-income subsidy doesn’t apply to the bridge program’s $50 copay, so it isn’t actually free for beneficiaries who normally pay very little for their prescriptions.

Agents and brokers have more room to pitch you this fall

Older woman discussing paperwork with colleagues at a desk
Image Credit: Shutterstock

A few years ago, CMS tightened the rules around how insurance agents and brokers could contact people about Medicare Advantage plans, after complaints about aggressive, repeated sales calls during open enrollment. The same final rule that overhauled star ratings also rolled back restrictions on the timing and manner of those conversations, as part of a broader deregulation push.

What that means in practice: expect more calls, texts, and mailers pushing Medicare Advantage plans this open enrollment season than you got last year. None of this changes your right to say no, hang up, or ask a broker to stop contacting you, and it doesn’t change the fact that a broker gets paid by the insurer, not by you, which can shape what they recommend. Licensed agents still have to follow disclosure rules when they do reach you, including identifying which plans they represent, so the deregulation loosens when and how often they can call, not what they’re required to tell you once they do. If you’d rather compare plans without the sales pressure, Medicare.gov’s plan finder and the 1-800-MEDICARE line work the same as always and don’t push you toward any particular company.

Your Part B premium and deductible are still anyone’s guess

Health insurance form on a clipboard with a pen and stethoscope
Image Credit: Shutterstock

Everything in this article so far is locked in. The regular Part B premium, the one deducted from most people’s Social Security checks every month, is not. CMS typically announces the official Part B premium, deductible, and income-related surcharge brackets in November, and as of this writing, that announcement hasn’t happened yet.

The best available estimate comes from the 2026 Medicare Trustees Report, which projects the standard Part B premium will rise from $202.90 to about $209.50 a month, a 3.25% increase, with the annual deductible climbing from $283 to roughly $292. Those are actuarial projections built on the same assumptions used to forecast the health of the Medicare trust funds, not a finalized number from CMS itself. Last year’s trustees report overshot the actual premium by several dollars, so treat $209.50 as a reasonable planning figure, not the number you’ll see on your Social Security statement come January.

Medicare’s plan finder gets a few new tools, and plenty of competition

Smiling woman talking on a phone beside her laptop
Image Credit: Shutterstock

Open enrollment for 2027 coverage runs from October 15 through December 7, 2026. CMS says access to plan choice stays wide. More than 99% of beneficiaries will have at least one Medicare Advantage plan available, and 97% will have 10 or more to choose from. The agency also added a few things to Medicare.gov and the Plan Finder this year, including more secure sign-in through Login.gov, ID.me, or CLEAR, and a feature that lets you save your doctors so you can compare which plans keep them in network.

You can also jump straight from a plan’s listing to its formulary and Summary of Benefits documents instead of hunting for them separately, and the site now flags more clearly when your current plan is changing for 2027. None of this fixes the actual complexity of comparing drug formularies or provider networks against a dozen plan options. It just makes the comparison slightly less tedious. If your plan auto-renews and you don’t log in during this window, you’ll keep whatever changes it made for 2027, whether or not those changes work for you.

Most of what changes in 2027 will show up quietly, in a monthly bill or a plan document, rather than in a headline. The seven weeks between October 15 and December 7 are the only real chance to do anything about it before those changes take effect.

Planning an international family vacation with children often brings unwanted fatigue. Long flights and crowded airport departure gates quickly drain energy before adventures start. Along the scenic Danube corridor, close geographic borders make multi-city travel relaxing.

Two historic national capitals sit just 60 kilometers apart along this shared river valley. You can introduce your children to distinct traditions and architecture without navigating complex regional rail hubs.

Discover how European capital hopping makes international family trips easier, with nearby cities, scenic routes, and less stressful travel with kids.
Image Credit: Pham Ngoc Anh via Pexels

Why is the Danube corridor ideal for family travel?

Close proximity makes combining Austria and Slovakia one of the easiest journeys in Europe. Your family can admire imperial palaces in the morning and reach a neighboring capital before afternoon snack time. Short travel times keep young children content.

Regional travel connections continue to advance with modern transit projects. Public records from the Austrian Federal Ministry for Climate Action, Environment, Energy, Mobility, Innovation and Technology show that full electrification of the direct rail link has been completed. Coordinated progress makes moving between both cultural centers simple.

Pairing these capitals allows your family to absorb distinct cultures on one trip. Your kids experience fresh languages, architecture, and regional food without losing entire days to transit. You gain rich cultural depth while maintaining a calm daily pace.

How do you navigate cross-border transit without station friction?

Steering tired children through crowded railway terminals brings unwanted stress into your family vacation. Securing a direct taxi from Vienna to Bratislava removes that logistical headache by picking up your group right outside your hotel lobby. You bypass crowded platforms, confusing ticket machines, and steep stairways in one easy step.

Door-to-door transit shields your group from sudden weather shifts and missed connections. A professional driver handles heavy bags while your children relax in comfortable, air-conditioned passenger seats. This calm ride preserves your energy for memorable sightseeing.

Private vehicle transfers give parents complete flexibility around feeding times and bathroom stops. When a toddler requires an unscheduled rest stop, your driver pulls off safely without train schedule pressures.

What makes direct vehicle transfers superior for heavy luggage?

Parenting on vacation demands bulky gear like folding strollers, booster seats, and multiple suitcases. Maneuvering awkward pieces across crowded platforms and narrow carriage doors tests parental patience. Dedicated trunk space lets you bring everything needed without extra anxiety.

Direct travel keeps your bags secure in a single vehicle from pickup to drop-off. You never need to monitor distant overhead racks while watching active children in train aisles. Professional drivers assist with bags, freeing your hands to guide kids safely.

Simplified transit eliminates physical strain before your walking tours begin. Your vehicle drops you right outside your hotel door so check-in proceeds without delay. Minimizing transit friction keeps vacation spirits high.

How can you pair imperial grandeur with walkable old towns?

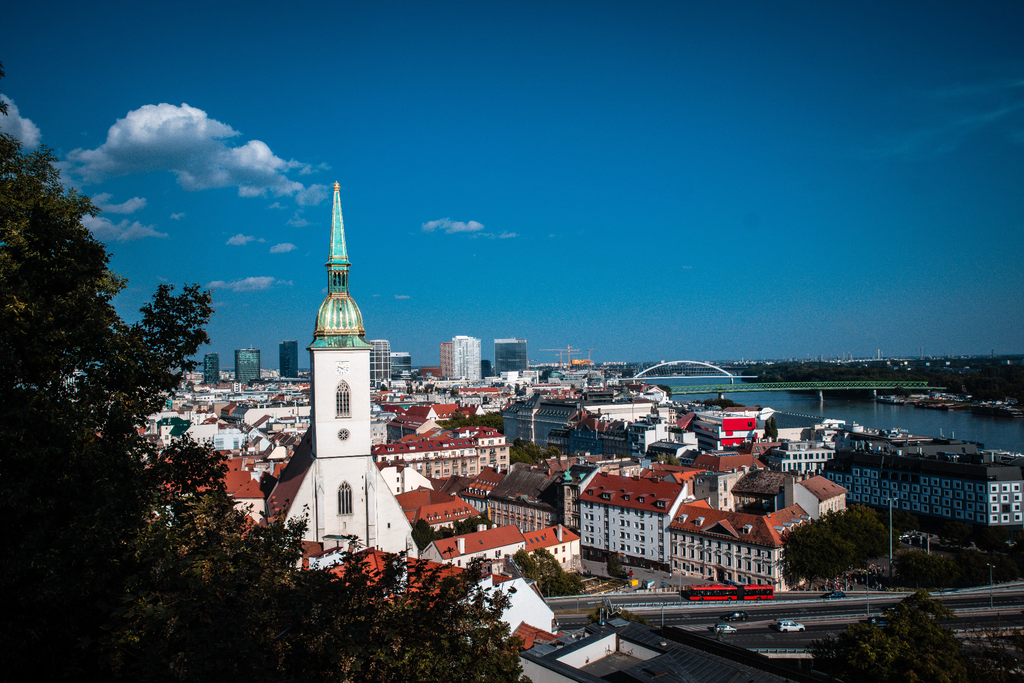
Vienna welcomes your family with grand boulevards, world-class museums, and monumental imperial architecture. You can walk through the palace grounds of Schönbrunn or listen to classical street musicians near Saint Stephen’s Cathedral. 

The Austrian capital gives young kids an inspiring glimpse into history. Bratislava provides an intimate contrast that works wonderfully with young explorers. The Slovak capital features an extensive pedestrian zone where kids walk freely without busy car traffic. 

Playful bronze statues scattered across cobblestone lanes turn walks into engaging treasure hunts. On these walks, a parent’s hands are rarely free between small hands to hold, a map, and a daypack, which makes stopping for photos harder than it sounds. Some parents get around this with Meta glasses for everyday wear, which can take a quick photo, handy for the moment a child spots Čumil, the bronze worker peeking out of a manhole in Bratislava’s old town. Either way, it is worth slowing down at the statues, since they are often the part of the day kids remember most.

Visiting both cities back to back shows children how distinct cultures thrive side by side.

Which family attractions keep children entertained?

Thoughtful itineraries balance historic education with active play to keep children cheerful. In Vienna, Tiergarten Schönbrunn ranks among the oldest operating zoos, presenting spacious habitats and shaded walkways. Interactive exhibits at the Zoom Children’s Museum invite hands-on exploration that sparks creativity.

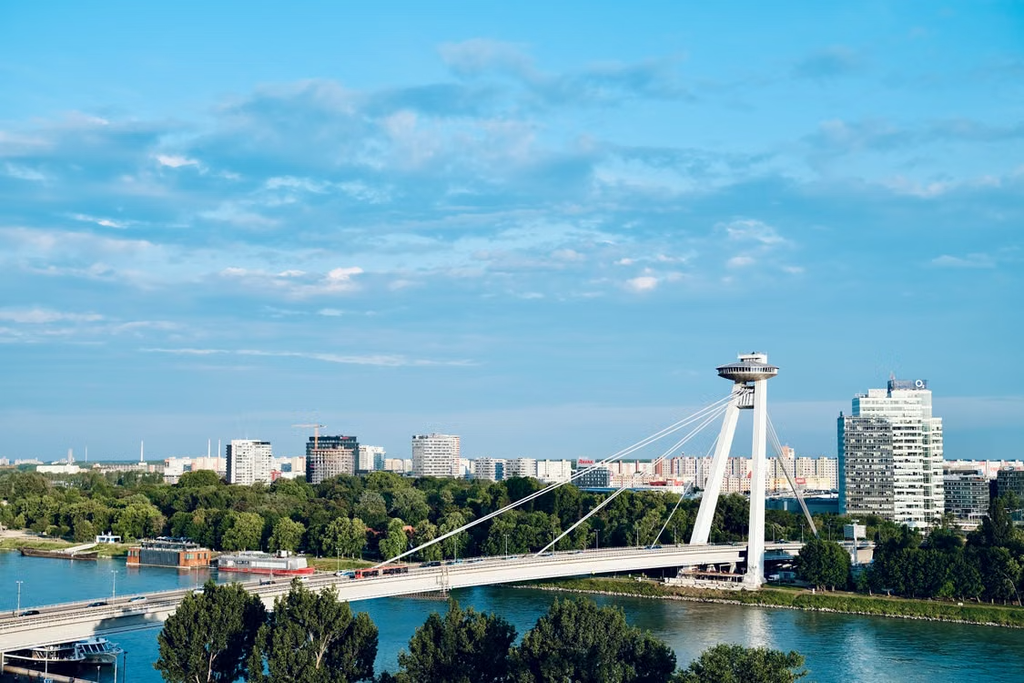
Crossing into Slovakia brings exciting new views high above the river bends. Bratislava Castle features wide stone courtyards where children safely stretch their legs while parents admire panoramic vistas. Across the Danube, the UFO Observation Deck delivers sweeping views stretching across regional borders.

Expanding regional tourism services continue to support international guests. Travel industry data from Passport News confirmed that Bratislava Airport handled over 2.4 million arriving and departing travelers. That steady growth provides visiting families with reliable tourist amenities and welcoming hospitality.

What practical steps keep your dual-city trip smooth?

Smart preparation helps your family hop between two European capitals without missing a beat:

  • Secure travel documents early: Keep passports organized together because cross-border spot checks can occur along regional highways.
  • Request proper safety seats: Confirm infant or booster seats with your transfer provider in advance to match child sizes.
  • Carry light daypacks: Pack water bottles, healthy snacks, and sanitizing wipes to keep everyone comfortable during pedestrian walking tours.

Setting up logistics in advance keeps cross-border journeys predictable and fun. Skipping crowded hubs allows your family vacation to stay relaxed from start to finish. 

Image Credit: Phong Thanh via Pexels

Selecting direct vehicle transit eliminates the logistical fatigue of hauling luggage through multiple train stations. You protect your family’s precious holiday time by replacing frantic platform transfers with effortless comfort.

Thoughtful planning and direct transit transform multi-city European adventures into manageable, joyful experiences. You give your children lifelong memories of two historic capitals while keeping every travel day smooth and peaceful.

A small maintenance problem can become expensive when it damages something beyond the original fault. For example, replacing a loose roof shingle is one job. Repairing water-damaged roof decking, insulation, and ceilings is a much bigger one.

The hidden costs of homeownership often develop out of sight, giving minor problems time to spread before anything looks wrong indoors. Recognizing the warning signs helps you spend money on a manageable repair rather than replacing materials that could have been protected.

Slow leaks beneath sinks

A slow leak beneath a sink can repeatedly wet the cabinet base without leaving a puddle on the floor. Stored cleaning supplies often hide the damage until the panel swells or a musty smell develops.

Household leaks can waste gallons of water annually. And for homeowners, wasted water can be only part of the bill if the leak also damages cabinetry and flooring.

Check connections, cabinet corners, and nearby flooring for dampness or discoloration. Move stored items aside so you can inspect the whole space.

A plumber may be able to resolve an early leak by repairing a connection or replacing a component. Once moisture damages the cabinet and subfloor, the bill can potentially include demolition, carpentry, flooring, and plumbing rather than one straightforward repair.

Pest activity around damp wood

Recurring insects near damaged wood deserve investigation, especially when moisture is also present. Subterranean termites can feed inside wood, allowing damage to progress without being obvious on the surface.

Guidance from NC State Extension identifies moist wood and wood-to-soil contact as favorable conditions for termites. Correcting those conditions matters because treating an infestation does not restore wood that has already been damaged.

The inspection should account for the property’s surroundings, including shaded areas, vegetation, and places where moisture collects. Some places are more prone to pest issues than others due to the local conditions.

For instance, because Greenville, South Carolina, is situated at the foothills of the Blue Ridge Mountains, it creates microclimates that pests like termites, ants, spiders, and mosquitoes thrive in. 

So, expert local knowledge can often matter. Homeowners in the Greenville area should consult Greenville SC Pest Control professionals, as they’ll know how the pests behave and where they hide.

Your aim is to identify the problem before pest treatment becomes only one part of a larger repair bill. Watch for these signs in particular:

  • Mud tubes along foundation walls
  • Discarded wings near windows
  • Damaged wood near damp areas

If termites damage structural framing, repairs may require opening finished surfaces and repairing or reinforcing affected wood. Early investigation helps distinguish a nuisance from a problem capable of creating substantial rebuilding costs.

Clogged gutters and blocked downspouts

Blocked gutters can send water over the edges and onto fascia boards or roof edges. A blocked downspout can also leave runoff collecting beside the house instead of draining away.

The maintenance guide from Lowe’s describes potential damage to roof decking, fascia, interior finishes, and foundations. Keeping gutters clear helps protect those parts of your home, not just the drainage system.

Repeated soaking can rot the wood supporting the gutter, leaving it unable to hold fasteners securely. Repairing that damage may involve removing the gutter, replacing fascia or roof-edge materials, and reinstalling the drainage components.

If water reaches the interior, damaged insulation, drywall, and paint can add further labor and materials. A cleaning job has then become a repair involving several parts of the building.

Watch for overflow, sagging sections, and persistent puddles near downspouts. Arrange safe cleaning and repairs before those conditions become routine.

Dirty HVAC filters that restrict airflow

A clogged HVAC filter can restrict airflow rather than simply leave your home dustier. In a cooling system, reduced airflow can contribute to a frozen evaporator coil and poor cooling.

Continuing to run struggling equipment can turn an inexpensive maintenance task into a service call, with potentially costly component repairs if problems persist. Replacing the filter promptly also avoids paying for an inspection when a neglected filter is the main fault.

Check filters according to the equipment manufacturer’s guidance and use the recommended size and type. Pets, renovation dust, and frequent system use can affect how quickly a filter becomes dirty.

If cooling remains weak or ice appears, arrange professional HVAC service. Repeatedly lowering the thermostat will not resolve the underlying airflow problem.

Loose or missing roof shingles

A loose or missing shingle can leave the roof assembly more vulnerable to rain. Water may reach decking and insulation before a ceiling stain alerts you to the problem.

At an early stage, the work may be limited to repairing a localized roof defect. After repeated leaks, a contractor may need to remove roofing, replace deteriorated decking, and restore the roof covering.

Wet insulation and damaged ceilings create additional work inside the house. Drywall replacement and repainting can make the total bill much larger than the original roof repair.

Inspect from the ground after strong winds, looking for displaced shingles or roofing debris. Arrange an inspection rather than climbing onto the roof yourself.

Catching small problems before repairs multiply

Managing the hidden costs of homeownership means considering what a small fault can damage next. Leaks, pest activity, blocked gutters, dirty filters, and roof defects all deserve attention before surrounding materials or equipment suffer.

Build these checks into a routine you can maintain, and investigate recurring warning signs promptly. And if this article has been helpful, explore some of our related content. 

You’ve been out of work for four months, and you’re applying everywhere. You have the resume, the certifications, and the references who’ll vouch for your work ethic. Then you read the listing again: “We’re looking for a digital native with high energy who thrives in a fast-paced, culture-first environment.” You’re fifty-two. You close the tab.

That reaction isn’t paranoia. Researchers at the National Bureau of Economic Research tested this directly, and job ads carrying subtly age-coded language produced a 12 percentage point drop in applications from workers 40 and older, even when nothing in the posting mentioned age at all. The words alone did the work.

I watched a friend with twenty years in marketing get ghosted by job after job until she dropped the first decade off her resume. The callbacks started within two weeks.

None of this is illegal on its face. Nobody writes “no one over fifty.” They don’t have to.

The phrase “digital native” is doing a lot of quiet work

Desktop computer and tablet on a bright home office desk
Image Credit: Shutterstock

“Digital native” sounds like a skill. It isn’t. It’s a birth year wearing a costume. A German labor court ruled in 2025 that the phrase itself constitutes direct age discrimination, because it describes when someone was born rather than what they can do. U.S. courts haven’t gone that far, but AARP has flagged the phrase as one of the most common code words showing up in job postings, right alongside “recent college graduate.”

The irony is that plenty of people in their fifties and sixties built the internet the posting is asking about. They shipped the software, ran the servers, and wrote the code before “digital native” was a phrase anyone used. If a job actually requires a specific technical skill, from working a CMS to running paid social campaigns, the posting can say so. The second it reaches for “digital native” instead of a named skill, it’s not describing a requirement anymore. It’s describing a demographic, and hoping you won’t notice the difference.

Phrases the government flagged back in 2007 are still everywhere

Printed resumes reviewed with a magnifying glass
Image Credit: Shutterstock

Federal regulation 29 CFR 1625.4 has banned a specific list of job-ad phrases since 2007: “age 25 to 35,” “young,” “college student,” “recent college graduate,” “boy,” and “girl.” Any of them, the rule says, violates the Age Discrimination in Employment Act unless the employer can prove a genuine, narrow exception applies, and almost none can.

Eighteen years later, these phrases still show up constantly, usually at smaller companies without an HR department checking the wording, or in postings written by a hiring manager who has no idea the rule exists. “Recent college graduate” is the most common offender. It sounds friendly and specific. Legally, it’s a flashing sign telling anyone over 40 not to bother.

The same regulation also allows employers to go the other way. Terms like “retirees welcome” or “supplement your pension” are specifically permitted, because they expand the applicant pool instead of narrowing it. If a posting can legally say it wants retirees, it has no real excuse for implying it only wants new grads.

A flat ceiling on years of experience

Recruiter reviewing a printed resume beside a laptop
Image Credit: Shutterstock

A healthcare company once advertised a staff attorney role for someone with “3 to 7 years (no more than 7 years) of relevant legal experience.” A 58-year-old attorney named Dale Kleber, who had thirty years in the field, applied anyway. He didn’t get an interview. The job went to a 29-year-old with far less experience.

Kleber sued, and in 2019 the Seventh Circuit Court of Appeals agreed that a hard cap on years of experience can violate the Age Discrimination in Employment Act, because it disproportionately screens out applicants over 40 even without ever mentioning age. The case is now the standard legal reference for this exact pattern: a minimum experience requirement is fine, but a maximum is a problem, because the only people it excludes are the ones who’ve been working the longest.

Watch the wording closely. “7 to 10 years” is a range. “No more than 10 years” is a ceiling. The first describes a job. The second describes who they’d rather not hear from.

Your graduation year hiding inside a form field

Resume form showing education and experience fields
Image Credit: Shutterstock

Plenty of applications still ask for the year you graduated, framed as routine background information. It isn’t neutral. A survey of 1,000 U.S. hiring managers found that 79% use graduation dates specifically to estimate a candidate’s age, and 46% said they look for a photo to do the same thing.

The federal rule on this is narrower than people expect. Asking your age outright doesn’t automatically break the law, but the regulation says these requests get closely scrutinized precisely because they tend to discourage older applicants from bothering to apply. When a tutoring company’s hiring software was caught auto-rejecting applicants over 55, part of its legal settlement specifically barred the company from ever asking candidates their birth date again.

If a form asks for your graduation year and the job has nothing to do with how recently you were in school, you’re not filling in background information. You’re handing someone the one data point they needed to guess your age and move on.

“High energy” and the vocabulary researchers can map

Woman reviewing paperwork at her office computer
Image Credit: Shutterstock

Researchers at the National Bureau of Economic Research didn’t just guess which words sound ageist. They built a model trained on language that industrial psychologists had already identified as age-stereotyped, then tested it against thousands of real job postings. The language fell into three buckets: stereotypes about health and stamina, personality, and skill, and postings that scored high on any of them predicted real discrimination in a companion hiring experiment.

“High energy” and “high-energy environment” sit squarely in the stamina bucket. So does language implying long hours are a badge of honor rather than a logistics problem. None of these phrases mention age, and that’s exactly why they work. They let an employer signal a preference without writing anything a lawyer would flag.

If a posting describes energy, stamina, or hustle as a personality trait rather than a job function, read it twice. A job that actually requires physical stamina states what the requirements are. A posting that just wants you to sound tired for them is asking something else entirely.

Job titles like rockstar, ninja, and guru

Resume writing tips checklist on a clipboard
Image Credit: Shutterstock

Indeed once analyzed its own listings and found “rockstar” and “guru” were the most common novelty job titles in the U.S., followed closely by “ninja,” “genius,” and “wizard.” Workopolis went further and ran the numbers on actual performance: a posting for “Data Analyst” outperformed an identical one titled “Data Ninja” by 14%.

The titles aren’t neutral marketing flourishes. People who’ve studied them point out that words like “ninja” and “rockstar” skew toward attracting young, white, male applicants, while quietly discouraging women, people from different ethnic backgrounds, and older candidates who read the title and assume the culture wasn’t built with them in mind. A fifty-five-year-old project manager with a flawless track record isn’t likely to picture herself as a “growth hacking ninja,” and that’s roughly the reaction the title unconsciously produces.

If the job is a data analyst, call it a data analyst. The cute title isn’t harmless fun. It’s a filter, and it filters out exactly the people this list is about.

“Culture fit” written in as an actual requirement

Colleagues welcoming a new employee into an office
Image Credit: Shutterstock

“Culture fit” sounds harmless, maybe even reasonable. Nobody wants a miserable office. But when it shows up as a stated qualification rather than a general goal, it becomes a blank check for a hiring manager’s gut reaction, and that reaction rarely gets examined for bias. Organizations that track hiring discrimination describe “culture fit” as one of a handful of codewords that promote exclusion precisely because it has no fixed definition and no objective test.

An older candidate who doesn’t play the company’s foosball table, use its Slack emoji culture fluently, or share references to shows that premiered after they’d already had a decade-long career can get marked down on “fit” without anyone naming age as the reason, including to themselves. It’s one of the few biases that can operate without anyone consciously intending it.

If a job posting lists “strong culture fit” as a requirement with no further explanation, there’s no way to know in advance what that means or how you’d prove you have it. That’s not an accident. That’s the entire function of the phrase.


Perks that are really a demographic pitch

Person reviewing a calendar on a laptop
Image Credit: Shutterstock

Ping pong tables, kegerators, and “unlimited” vacation policies get marketed as culture, but they’re often a recruiting pitch aimed at a specific age bracket. One industry analysis of office perks put it plainly: a pool table in the break room reflects “the young and vibrant nature of the workforce” and works as a recruiting tool for exactly that demographic.

“Unlimited” vacation in particular deserves a second look. Research on the policy has found that employees under it often take less time off than they would under a fixed allotment, because without a clear number, people worry that using “too much” signals a lack of commitment. It’s a perk that sounds generous and often isn’t, and it tends to show up most at workplaces explicitly courting a younger, earlier-career crowd who haven’t yet learned to ask what the policy actually guarantees.

None of this means a company with a ping pong table won’t hire you. It means the posting is speaking a specific dialect, and it’s worth noticing who that dialect was written for.

A careers page where everyone looks twenty-six

Young woman holding a resume in an office
Image Credit: Shutterstock

Scroll past the job description to the “meet the team” photos, and you’ll often learn more than the text tells you. Career coaches who specialize in fighting age bias in hiring specifically tell employers to check their own imagery, asking directly: “Does the language in your job descriptions skew too much toward a young crowd?” and pointing to visuals as part of the answer, right alongside the words.

A careers page stocked entirely with twenty-somethings in a stock-photo office isn’t proof the company won’t hire you. But it’s a reasonable signal about who they picture in the role, and who they expect to feel comfortable applying. Hiring teams rarely curate these photos with age diversity in mind. They tend to reach for whatever images read as “energetic” and “modern,” and those words, again, usually translate to young.

If the “about us” page and the team photos look nothing like the workforce you’d expect for that industry, that’s worth factoring in before you spend an evening tailoring a cover letter to a culture that was never built with you in the room.

Software reading your resume before a person does

Hands reviewing a printed resume beside a laptop showing a resume
Image Credit: Shutterstock

By the end of 2025, roughly 83% of companies planned to use AI to screen resumes, up sharply from under half the year before. The adoption didn’t come with much reassurance about fairness. In one 2025 survey of full-time workers familiar with their employer’s hiring practices, companies reported AI bias most commonly around education, followed by age, and most said AI could reject a candidate without a human ever reviewing the file.

This has already played out publicly. In 2023, a tutoring company settled with the EEOC for $365,000 after its hiring software was programmed to automatically reject female applicants 55 and older and male applicants 60 and older, rejecting more than 200 qualified people before anyone noticed. It was the EEOC’s first settlement of its kind, and almost certainly not the last instance, just the first one caught.

Most job postings don’t mention that a screening algorithm will see your resume before a person does. You’re allowed to assume one will anyway.

A video interview analyzing your face and your voice

Man waving during an online video conversation on a laptop
Image Credit: Shutterstock

Some companies replace a first-round phone screen with a recorded video interview, where software analyzes your facial expressions, speech patterns, and word choice before a human watches it. Illinois took this seriously enough to pass its own law. As of February 2026, employers must get a candidate’s explicit, informed consent before analyzing a video interview with artificial intelligence, and must explain in plain terms what the software is evaluating.

The law exists because the technology has a documented history of reading more into a face than it should. Vocal pitch, speech cadence, and facial movement all shift somewhat with age, and a system trained mostly on younger candidates’ interview footage can easily mistake those differences for a lack of fit or energy, without anyone ever writing the word “age” into a line of code.

If you’re asked to complete a one-way recorded interview with no live person on the other end, you’re entitled to ask, directly, whether AI will be evaluating it and what it’s looking for. Companies using the technology legally have to be able to answer.

The word “overqualified” standing in for something else

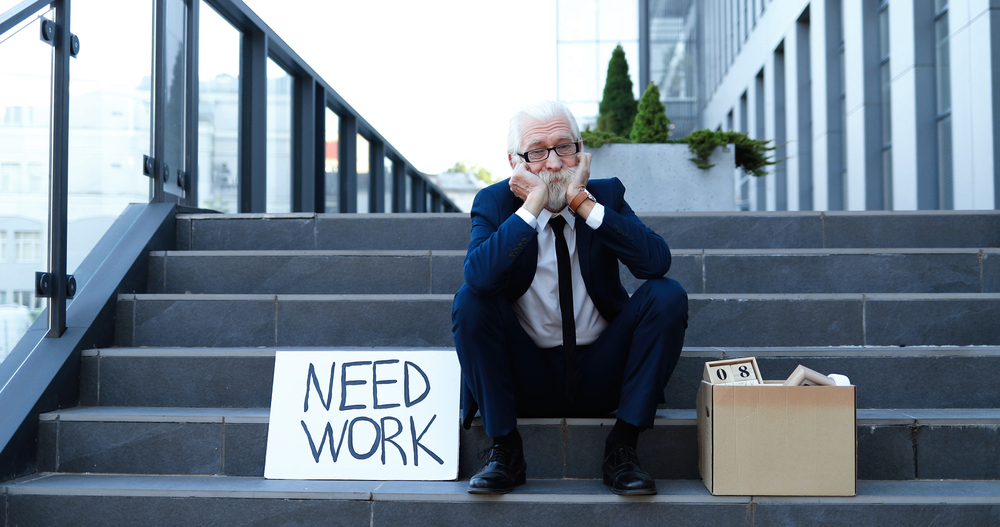
Older job seeker sitting beside a Need Work sign
Image Credit: Shutterstock

Courts have wrestled with “overqualified” for decades, and the consensus is consistent: it’s not automatically illegal, but it’s also not automatically honest. Legal analysts who track these cases note that rejecting a candidate as “overqualified” can function as a proxy for age discrimination when the term isn’t tied to objective criteria, because “too experienced” and “too old” can describe the exact same resume from two different angles.

A thirty-year veteran in a field and a recent graduate can submit wildly different resumes for the same opening, and only one of them will ever hear the word “overqualified.” That’s worth sitting with. The feedback usually isn’t a lie. It’s a real worry, dressed up to sound like a compliment, about whether someone with your experience will stay, accept the salary, or feel bored. Those are legitimate business questions. They’re also, very often, questions a hiring manager wouldn’t think to ask about a candidate twenty years younger with a similar resume.

If “overqualified” comes up in a rejection and nobody can explain what, specifically, disqualified you, ask yourself what the word was standing in for.

Instructions to trim your resume down to ten years

Resume showing profile and employment history beside a keyboard
Image Credit: Shutterstock

Career advice columns routinely tell job seekers to list only their most recent positions and to leave graduation dates off their resume entirely, framing it as smart self-editing. Sometimes a job posting itself asks for it, with a line like “please limit your resume to the last ten years of experience.”

That instruction isn’t really about readability: a resume with thirty years on it doesn’t take longer to scan than one with fifteen, and most hiring managers spend seconds on the first pass either way. What a longer resume does reveal is roughly how old you are, and a request to trim it down is, in practice, a request to hide that information before anyone can act on it.

There’s a real tension here. The same advice that protects you from a biased screener also means you’re the one doing the work of hiding your own experience, which should never have been a liability in the first place. It’s a reasonable short-term move. It’s also a strange thing to have to do for decades of honest work.

A salary that was clearly priced for someone with half your experience

Woman reviewing paperwork with a calculator beside her laptop
Image Credit: Shutterstock

Some job postings describe senior-level responsibilities, then attach a pay range that only makes sense for someone three or four years into their career. The title says “manager.” The salary says someone’s first management job. That mismatch isn’t always intentional age discrimination, but it functions the same way regardless of intent: a candidate with real seniority either turns down the number or negotiates hard enough to raise flags before the interview even happens, while a less experienced applicant takes the number without blinking.

This pattern shows up most in roles that were recently “leveled down,” where a company quietly reduced a position’s seniority on paper without changing what the job actually requires, usually to control payroll costs. The posting keeps language suggesting strategic ownership and independent judgment. The number underneath it suggests they’re hoping nobody with real experience reads that far.

If the responsibilities and the pay range don’t match what you know that kind of seniority is worth in your field, trust the mismatch over the job title. The number is usually the more honest part of the listing.

Recruiters who admit they already factored in your age

Interviewer speaking with an applicant across a desk
Image Credit: Shutterstock

This one isn’t subtle, and it isn’t hidden in the posting. It’s an admission. In the same hiring-manager survey that found widespread use of graduation dates and photos, 42% of hiring managers said they consider an applicant’s age when reviewing a resume, and more than a third said they were specifically biased against older candidates.

That’s more than four in ten hiring managers saying, out loud, to a researcher, that age is part of how they read your resume, before a single interview happens. It happens quietly, in a few extra seconds spent on an application that doesn’t sit right with them for reasons nobody writes down.

You can’t see this one in the posting itself, which is exactly why it’s worth knowing it exists. The listing can be written in flawless, neutral language and the bias can still be sitting on the other side of the screen, unwritten and almost never admitted this plainly outside of an anonymous survey.

The same trick, aimed at Gen Z instead

Applicant handing a printed resume to an interviewer
Image Credit: Shutterstock

Age bias doesn’t only point in one direction, and it’s worth saying plainly. A newer survey of several hundred U.S. hiring managers found that 36% admitted bias against Gen Z candidates, compared with 34% who said the same about applicants over 60. Appearance played a role too: managers said they were put off by both “elderly” and “youthful” looking candidates, though the elderly bias ran more than double.

The reasoning differs by direction. Younger candidates get screened out over assumptions about job-hopping and a lack of real-world experience. Older candidates get screened out over assumptions about retirement timing and health. Both sets of assumptions are guesses dressed up as hiring judgment, and both can be wrong about any individual sitting in front of them.

This doesn’t cancel out the rest of this list. The clues above still skew overwhelmingly toward filtering out workers 40 and older, and that’s the pattern with the deeper legal history behind it. But if you’re mentoring a twenty-four-year-old niece or nephew hunting for their first real job, the same instinct to read between the lines applies to them too.

How rarely any of this gets caught

Magnifying glass over a printed resume on a green desk
Image Credit: Shutterstock

The Equal Employment Opportunity Commission received 16,353 age discrimination charges in fiscal 2025, roughly one in five of everything the agency took in that year. Most of those charges didn’t go anywhere. Over two-thirds ended in a finding of no reasonable cause, and only a small fraction turned into an actual settlement, lawsuit, or payout.

That’s not necessarily because the discrimination wasn’t real; age bias in hiring is famously hard to prove, because a rejection almost never comes with a stated reason, let alone a written one that mentions age. A company can decline to interview you for a dozen plausible-sounding reasons and never have to explain why all of them seemed to land on candidates over 50.

None of this means filing a charge is pointless if you have a strong, well-documented case. It does mean the system catches a small slice of what’s actually happening, and the agency meant to enforce these protections is working through a caseload that’s grown for years running. Recognizing the pattern yourself, before you’ve spent weeks on an application, is often the more useful tool.

Why so many job seekers are already editing their own age out

Older man using a laptop at home
Image Credit: Shutterstock

A 2025 survey of more than 4,200 job seekers found that 42% had altered their resume or LinkedIn profile specifically to look younger, removing graduation dates, trimming their earliest jobs, swapping in a more current headshot, and in some cases updating their titles to sound less senior than they actually were. Among women 45 and older, the figure jumped to 53%.

Career coaches sometimes call this “resume Botox,” and the name fits the discomfort of it. These aren’t people lying about their qualifications. They’re people editing true information about themselves because they’ve learned, often the hard way, that the full and honest version gets filtered out before a human ever reads it.

The real cost of everything on this list isn’t abstract: it’s thousands of qualified people quietly rewriting their own history to get past software and hiring managers who were never going to say, out loud, what the actual objection was. Spotting the clues in a job posting is useful. Knowing you’re not imagining the pattern is probably more useful still.

None of these clues guarantee a company won’t hire you, and none of them are proof on their own. They’re just worth noticing before you spend another evening tailoring a cover letter to a job that was quietly written for somebody else.