scroll top

A full synthetic oil change costs $65 to $125 at most shops, which is exactly the kind of bill that gets pushed back a month when rent, groceries, and the car payment are all due first. An engine replacement typically costs between $2,000 and $10,000, and worn-out oil is one of the ordinary ways an engine ends up needing one.

A timing belt replacement runs $500 to $1,400, while engine repairs after a belt snaps can reach $2,000 to $10,000 or more. A transmission fluid change averages around $100, and replacing a transmission on a mainstream automatic costs $2,500 to $5,000.

Gas matters here too, since regular averaged $4.152 a gallon over the 12 months that ended in May, which makes every lost percentage point of fuel economy cost more than it used to.

Oil changes on the schedule in your owner’s manual
Mechanic checking an engine oil dipstick under an open hood
Image Credit: Shutterstock

Conventional oil is generally changed after 3,000 to 5,000 miles, a synthetic blend can go up to 7,500 miles, and full synthetic can run as long as 10,000 miles, although the owner’s manual has the number for your engine. The prices follow the oil: a conventional change costs $35 to $75, a blend costs $40 to $100, and full synthetic costs $65 to $125. Paying more for synthetic usually means fewer visits, so the yearly total ends up closer than the sticker prices suggest.

Using the oil grade the manufacturer calls for improves gas mileage by 1% to 2%, and putting 5W-30 in an engine designed for 5W-20 can lower it by 1% to 1.5%. Stretching the interval is where the expensive end of the range comes in, since an engine replacement can cost $2,000 to $10,000. A sticker on the windshield from the last shop is a reminder, and the interval in the manual for your engine is the one that counts.

Tire pressure checked once a month
Hands checking a car tire with an analog pressure gauge
Image Credit: Shutterstock

Pressure should be checked on all four tires and the spare at least once a month when the tires are cold, which means the car has sat for at least three hours. The correct number is on the sticker in the driver’s door jamb or in the owner’s manual, and the maximum pressure molded into the sidewall is a limit for the tire, not a target.

Low pressure costs money at the pump and at the tire shop. Gas mileage drops about 0.2% for every 1 psi below the proper average pressure, so four tires that are each 5 psi low waste roughly 1% of the fuel, which is about $50 a year for a car that burns 600 gallons at $4.152 a gallon. The larger cost is tread, because low pressure causes uneven or premature tread wear, and a set of four installed runs $600 to $900 for most people.

Tread depth and rotation
Hand measuring the tread depth of a car tire with a gauge
Image Credit: Shutterstock

A penny works as a tread gauge. Turn Lincoln’s head upside down and slide the coin into a groove, and if the top of his head is visible, the tread has worn to 2/32 of an inch, which is the point where tires are no longer safe. Checking the tread when the monthly pressure check is done takes a minute and shows whether one tire is wearing faster than the others.

Tires should be rotated every 5,000 to 8,000 miles if the vehicle manufacturer recommends it, or sooner if uneven wear appears, and a few vehicles should not be rotated at all, so the manual comes first. Age counts as well, since some manufacturers recommend replacing tires that are six to 10 years old regardless of tread, and the last four digits of the DOT number on the sidewall give the week and year the tire was made. With a set of four costing $600 to $900 installed, getting full life out of each tire is worth the few minutes.

Wheel alignment after impacts and new tires
Mechanic beside a car with alignment sensors mounted to its wheels
Image Credit: Shutterstock

A typical alignment costs $70 to $250 depending on the vehicle, with front-end alignments running about $70 to $130 and four-wheel alignments about $120 to $250. Every 12 to 24 months is common, and sooner after hitting a curb or a pothole, putting on new tires, or having suspension or steering work done.

Toe, the angle at which the tires point slightly inward or outward, is the biggest driver of tire wear, and a bad alignment usually shows up as wear on the inner or outer edge, feathered tread, or one tire wearing out faster than the rest. A car that tracks straight and wears evenly can wait. One that pulls to the side after a pothole is worth checking before the tread shows it, because even the most expensive alignment costs a fraction of a $600 to $900 set of tires. An alignment done right after new tires goes on protects the money that was just spent on them.

Brake pads replaced before they wear down to metal
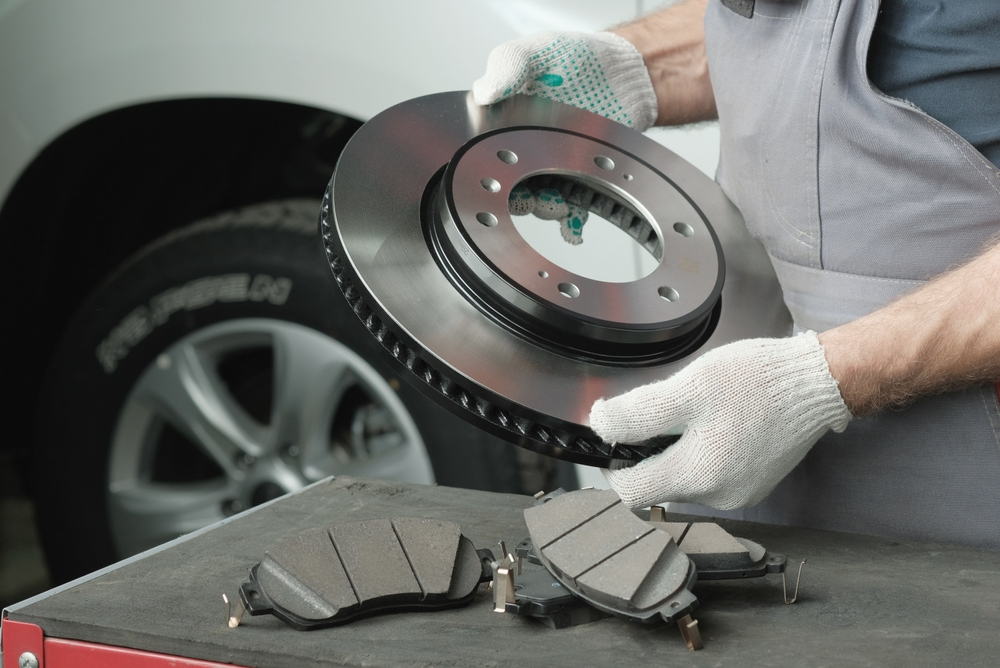
Mechanic holding a new brake rotor above a set of brake pads
Image Credit: Shutterstock

Pads should be replaced when there is only about 3 millimeters of material left. Pads alone run $330 to $390 per axle, while pads plus rotors run $901 to $1,084 per axle, which adds roughly $570 to $700 per axle when the rotors have to come along. Waiting until the grinding starts is how a $330 to $390 job turns into a $901 to $1,084 one, and replacing pads at the 3-millimeter mark lets the work be scheduled instead of forced by a noise on the way to work.

Pads that wear down to the metal backing grind into the rotor, which is how a pad job becomes a pad-and-rotor job. The warning signs are loud screeching or grinding, a pulsing brake pedal, a brake warning light, longer stopping distances, and the car pulling to one side when braking. Brakes should be inspected at least once a year or at the interval in the maintenance schedule, and rotors last roughly 50,000 miles, though they can sometimes be resurfaced instead of replaced.

Brake fluid changed on the automaker’s timeline
Person pouring brake fluid into an under-hood reservoir
Image Credit: Shutterstock

Brake fluid pulls in water over time even in a sealed system, and moisture lowers the boiling point of the fluid, which can reduce pedal effectiveness during repeated hard stops. Water can also corrode the brake system from the inside, and replacing corroded brake lines or a master cylinder costs far more than replacing the fluid.

Automakers disagree on the timing. Mercedes-Benz says every two years or 20,000 miles, Volkswagen says every two years regardless of mileage, Subaru says every 30,000 miles, and Chevrolet allows up to 150,000 miles or 10 years. The spread is wide enough that the owner’s manual is the only number worth following, and a shop that recommends a flush at every oil change is worth questioning. Someone who bought a used car with no service records has no way to know when the fluid was last changed, which makes the first year of ownership a reasonable time to have it tested.

Coolant flushed before it turns to sludge
Person pouring pink coolant into a car cooling-system reservoir
Image Credit: Shutterstock

A coolant flush typically costs between $200 and $250 at a dealership, and independent shops are often cheaper, especially when the flush is paired with an oil change. Every two years or 30,000 miles is a good rule of thumb, though the schedule in the owner’s manual takes priority because it varies by model.

Old coolant lets rust, sediment, and scale build up, which can block coolant flow and cause the engine to overheat, and neglect can end in a blown head gasket or a cracked engine block, repairs that cost considerably more than the flush. The hoses and radiator cap deserve a look during the same appointment, and hoses more than five years old are worth replacing. A low reservoir between services is worth checking too, since topping off a leak without finding it only delays the same repair. At $200 to $250 every two years, the flush works out to about $100 to $125 a year.

Transmission fluid changed before the shifts get rough
Two mechanics working beneath a raised car hood in a repair shop
Image Credit: Shutterstock

A transmission fluid change on an automatic averages around $100 and can range from $80 to $250, and a flush with a new filter runs $230 to $475. The recommended interval is every two to five years or 30,000 to 50,000 miles depending on the type of transmission, so the owner’s manual decides which end of that range applies to your car.

Replacing a transmission on a mainstream automatic costs $2,500 to $5,000, a manual runs $1,500 to $3,000, and luxury or high-performance vehicles can top $6,000. Replacing the filter and cleaning the pan with each fluid change helps avoid costly damage, and fluid that is low or breaking down should be changed right away. If the car starts shifting differently, checking the fluid is the first and cheapest thing to do. Spread over a five-year interval, a $100 fluid change costs about $20 a year, against a replacement that starts at $2,500.

Battery tested every year after the third
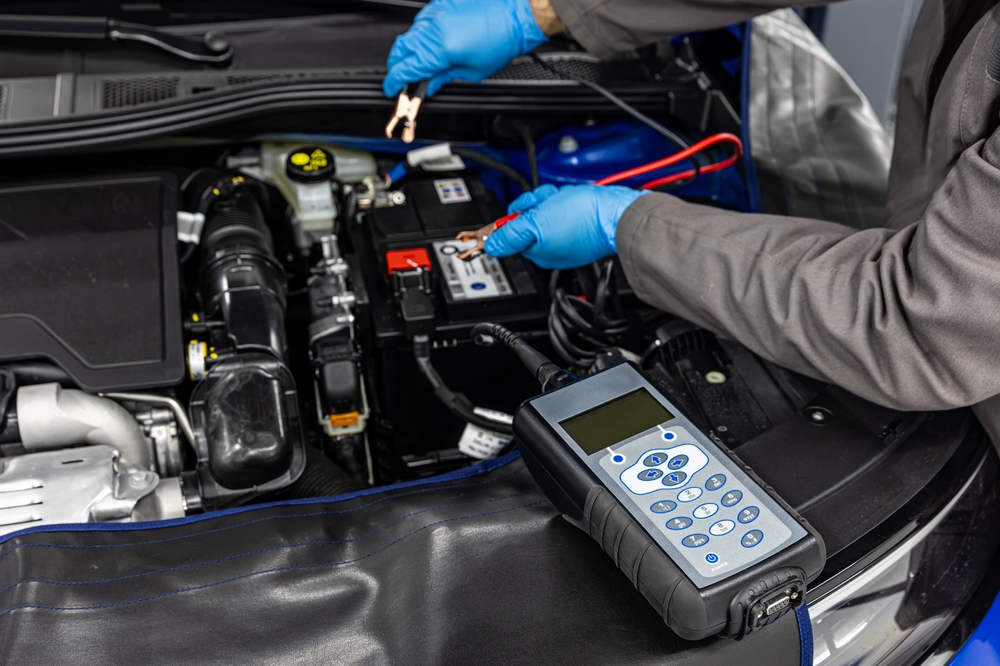
Technician connecting an electronic battery tester to a car battery
Image Credit: Shutterstock

Car batteries last about three to five years, and heat shortens that. Batteries in hot southern climates typically last about three years, while those in cooler northern climates can reach five years or longer, because under-hood temperatures can easily exceed 200 degrees Fahrenheit in hot weather and speed up the wear.

Some failing batteries show no obvious symptoms, so the battery should be inspected at every oil change and tested annually once it reaches its third year. Slow cranking, a battery or charging warning light, and dim headlights at idle in older cars are the signs that usually show up first. A free diagnostic test of the battery and the starting and charging systems is available to AAA members in most areas, and a technician can install a new battery on the spot if the test says it’s needed. Writing the install date on the battery with a marker makes the testing schedule easy to keep.

Timing belt replaced on the manual’s schedule
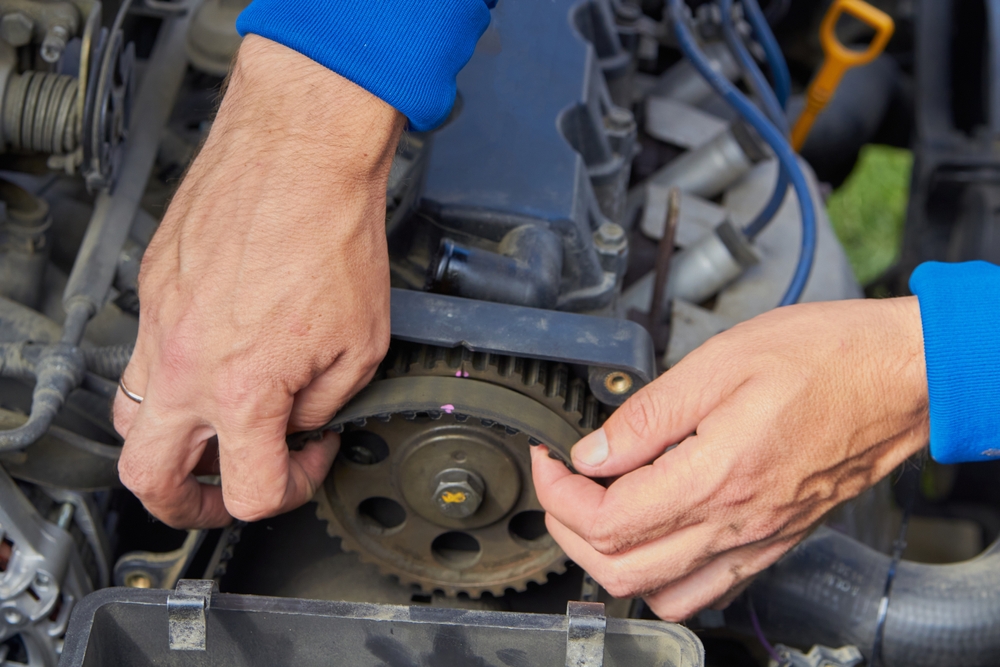
Hands fitting a toothed timing belt around an engine pulley
Image Credit: Shutterstock

A scheduled timing belt replacement typically costs $500 to $1,400 for parts and labor. When a belt breaks, engine repairs or a full replacement run $2,000 to $10,000 or more, and on interference engines the repair bill can reach $2,000 to $5,000.

Many belts fail without any symptoms, so there is no noise or warning light to wait for. The owner’s manual lists the replacement interval, and some engines use a timing chain instead, which has no scheduled replacement. A used car with no record of when the belt was last replaced should have the job done right away. Whether a snapped belt damages the engine depends on the design, so a mechanic or the manual can say whether yours is an interference engine, and that answer sets how much risk each postponed month carries. The scheduled job is one of the more expensive ones, which is why it tends to get postponed, but even the top of that range at $1,400 costs $600 less than the cheapest engine repair after a failure.

A check engine light that gets read quickly
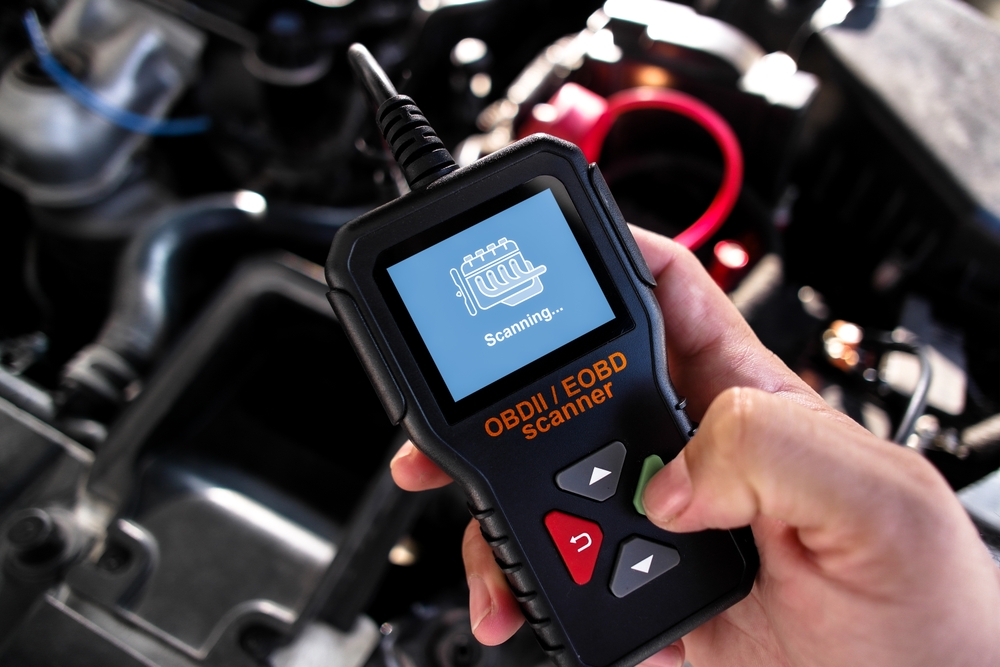
Hand holding an OBD diagnostic scanner over a car engine
Image Credit: Shutterstock

The check engine light could signal a more serious issue that could reduce your fuel economy, and some of the faults behind it are expensive when left alone. A faulty oxygen sensor that goes unfixed can cause as much as 40% lower fuel efficiency, and a lit light can also mean the car may not pass emissions testing in states that require it for registration.

Oxygen sensors sit in the exhaust system, where they monitor the catalytic converter and the oxygen level, and neglected sensor problems can lead to catalytic converter replacement, which is also costly. The code behind the light identifies which system is reporting a fault, and reading it is the cheapest first step because it turns a vague warning into a specific repair estimate. A light that comes on and goes off again still counts as a warning. A repair that could have waited a month can turn into one with a deadline once registration renewal requires a passing test.

An engine air filter you change yourself
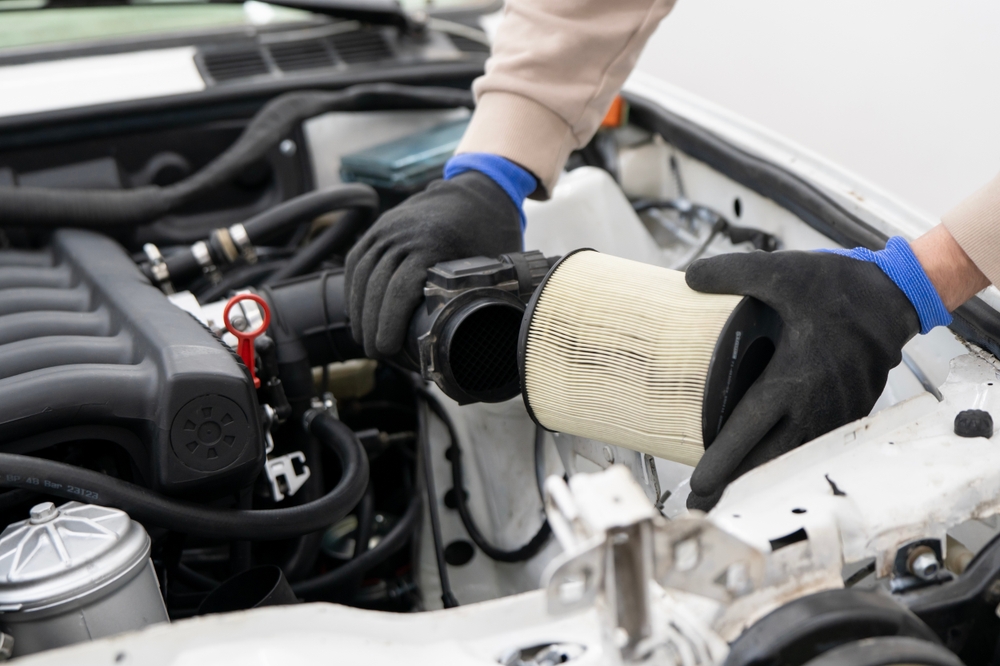
Gloved hands fitting a cylindrical air filter into an engine intake housing
Image Credit: Shutterstock

Most drivers pay $73 to $142 for an engine air filter replacement at a shop, while the filter alone costs $15 to $84. Replacement is typically recommended every 15,000 to 30,000 miles, or sooner in dusty areas, and the owner’s manual has the interval for your car.

On a modern fuel-injected engine, replacing a clogged filter does not improve fuel economy, but it can improve acceleration, so the savings come from doing the job yourself and not from gas mileage. On older carbureted engines a new filter can improve both by a few percent. Labor on the job can cost $30 at an independent shop and $60 or more at a dealer, for work that on many cars means opening a plastic housing and swapping one part. Over 90,000 miles, a filter changed every 30,000 miles is three jobs, which comes to about $219 to $426 at a shop and $45 to $252 in parts alone.

Windshield chips repaired while they are small
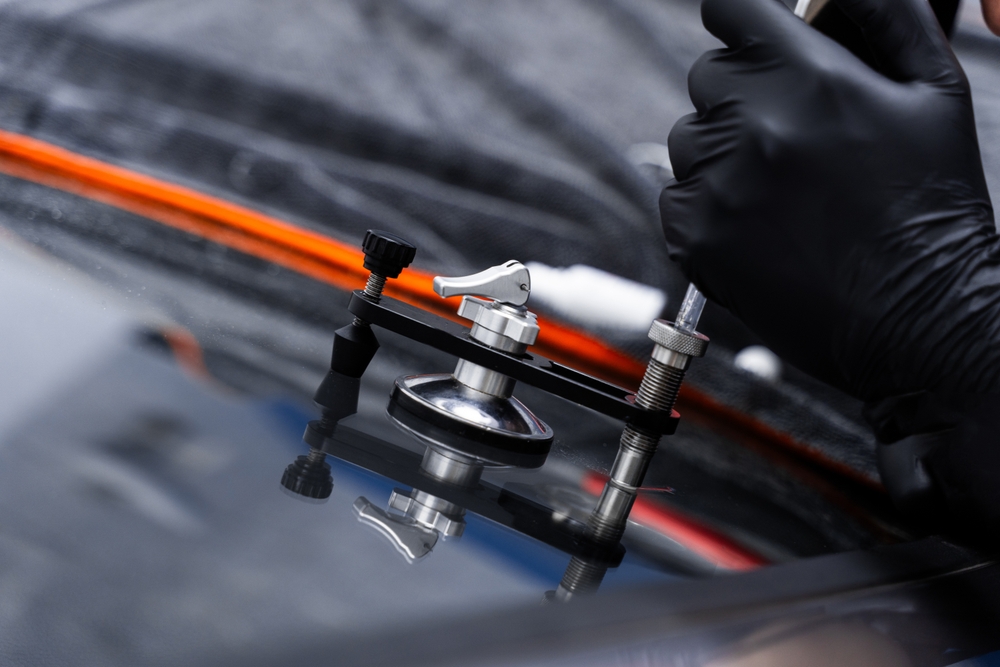
Gloved hand using a resin-injection tool on a car windshield
Image Credit: Shutterstock

A chip roughly the size of a quarter or smaller, or a crack typically under about six inches, can usually be repaired as long as the damage is shallow, recent, and outside the driver’s direct line of sight. Repair is often under a couple hundred dollars, while replacement runs several hundred dollars or more.

A chip left alone can spread with bumps and temperature swings, and once a crack grows or reaches the edge of the glass, repair may no longer work. Slamming doors and sudden temperature changes make spreading more likely. Replacement also costs more on newer vehicles with driver-assistance sensors that need recalibration. Glass damage is commonly covered under comprehensive coverage where it is included, and some policies waive the deductible for repairs while replacements may carry one, so a call to the insurer before the chip grows can cost nothing. The line-of-sight rule is the reason to act early, since a chip that sits outside the driver’s direct view today can spread into it.

The fuel grade your manual calls for
Row of fuel nozzles at a gas station beside a car
Image Credit: Shutterstock

Premium costs more per gallon, and under normal driving conditions a car designed for regular gets little to no benefit from it. Even in severe duty such as towing, where higher octane can gain a few percent, the cost increase is typically higher than the fuel savings.

The wording in the manual decides what to buy. Regular is 87 octane, midgrade is 88 to 90, and premium is 91 to 94. A car that requires premium needs it, while a car that only recommends premium will run better on higher octane but the choice is yours. The fuel door or the owner’s manual says which wording applies, and buying the lowest grade the manual allows is the cheapest way to keep a fuel budget intact. Say premium costs 70 cents more per gallon than regular, a hypothetical difference: a 15-gallon fill-up is $10.50 extra, and 25 fill-ups a year is more than $260.

Smoother driving that spares the gas and the brakes
Seat-belted driver holding the steering wheel with his family in the car
Image Credit: Shutterstock

Speeding, rapid acceleration, and hard braking can lower gas mileage by roughly 15% to 30% at highway speeds and 10% to 40% in stop-and-go traffic. On a car that burns 600 gallons a year at $4.152 a gallon, a 15% hit costs about $370. At the top of the highway range, a 30% loss on the same car is about $750 a year. The range is wide because the damage depends on how much of each trip is spent accelerating hard, which comes down to how early the foot comes off the gas.

Speed has its own price. Each 5 mph over 50 mph is like paying an additional $0.21 per gallon, so driving 70 mph instead of 55 mph adds about $0.63 per gallon in effect. Easing onto the brakes instead of stopping hard also leaves pads thicker for longer, which pushes the $330 to $390 per axle pad job further down the road.

For cross-country moves or long-distance relocations, booking an auto transport company like RoadRunner Auto Transport can also spare your vehicle thousands of highway miles and extra wear.

Extra weight and roof boxes removed
Older man loading a backpack into the cargo area of an SUV
Image Credit: Shutterstock

An extra 100 pounds in a vehicle could reduce mpg by about 1%, so a trunk holding tools, sports gear, bags of salt, and boxes meant for a donation drop-off that never happened costs fuel on every trip, and 300 pounds of it costs about 3%, or roughly $75 a year on 600 gallons at $4.152 a gallon. A rooftop cargo box can reduce fuel economy by around 2% to 8% in city driving and 6% to 17% on the highway, and by 10% to 25% at interstate speeds of 65 to 75 mph.

Rear-mounted cargo boxes and trays have a much smaller effect than a box on the roof. A 10% loss on a car that burns 600 gallons a year at $4.152 a gallon costs about $250. Racks and boxes that stay on through the off-season are paying for nothing, and taking them off takes less time than the trip to the gas station.

Idling kept to a minimum
Lines of cars waiting at traffic lights in the morning sunlight
Image Credit: Shutterstock

Idling can use a quarter to a half gallon of fuel per hour, depending on engine size and air conditioner use. Twenty minutes a day on 250 days adds up to about 83 hours a year, which comes to 21 to 42 gallons, or roughly $86 to $173 at $4.152 a gallon.

Warming up the car in the driveway, waiting in a pickup line with the A/C running, and sitting in a parking lot before an appointment are the usual sources. Cutting that in half still saves $43 to $86 a year at $4.152 a gallon. Turning the engine off for longer waits costs nothing, and it keeps hours off an engine that is not moving the car. Anyone who idles for a full hour a day, such as a delivery or rideshare driver waiting between jobs, burns about 91 to 183 gallons over 365 days, or roughly $380 to $760 at $4.152 a gallon.

Receipts kept and the shop you choose
Customer signing paperwork on a clipboard beside a mechanic in a repair shop
Image Credit: Shutterstock

A company can’t void a warranty or deny coverage solely because you used another company’s part or an independent shop, so routine maintenance does not have to happen at the dealer to protect the warranty. Coverage can still be denied for damage or defects caused by third-party parts or services, which is why records of what was done and when are worth keeping.

Invoices should list parts, labor, mileage, and service details, and DIY work should be logged with the date, mileage, and product used. Inspection reports are worth saving even when the work was declined, and a phone photo of each paper invoice keeps them from getting lost. Records do not guarantee a higher offer when the car is sold, though they support a stronger case for its condition. Anyone told that a warranty is void for using an independent shop can file a report with federal regulators.
Half of all electricians in the country made more than $63,190 last year, which works out to a little over $30 an hour, and most of them never sat in a four-year classroom to get there. They apprenticed, got paid while they learned, and walked out with a skill that keeps a steady paycheck coming in for decades.

That same pattern holds across every trade on this list. Pipefitters, millwrights, wind turbine technicians, and the line workers who keep the power grid running all share the same basic deal: real, physical, skilled work that pays comfortably more than minimum wage almost everywhere in the country, with plenty of room to climb past $40 or even $50 an hour once you have a few years in.

None of them require a bachelor’s degree. Most of them pay you to train. And from utility companies to aircraft hangars to wind farms, the people hiring for these jobs cannot find enough qualified workers to fill the openings.

Electricians

Electrician checking a solar installation electrical panel with a tablet
Image Credit: Shutterstock

Half of the country’s electricians earn more than $63,190 a year, and the top earners clear considerably more once they have a journeyman license and a specialty, like industrial controls, low-voltage systems, or solar hookups. The work covers new construction, renovation, and the steady, unglamorous business of fixing what breaks: a tripped panel, a dead outlet, wiring a previous owner ran wrong twenty years ago.

Apprenticeships typically run four to five years and pay a rising wage the entire time, so there is no unpaid stretch spent living on noodles while you learn. By the time an apprentice is licensed, they are already earning close to what the job pays long term. About 72,700 openings a year are projected through 2035, mostly because electricians are retiring faster than new ones are coming up through apprenticeship programs.

Demand is not limited to new housing, either. Data centers, EV charging networks, and aging grid infrastructure all need electricians, and none of that work can be done from a laptop.

Plumbers, pipefitters, and steamfitters

Plumber repairing the pipes under a kitchen sink
Image Credit: Shutterstock

A licensed plumber brings in a median of $63,800 a year, a little under $31 an hour, and the ceiling is higher for anyone who moves into pipefitting or steamfitting work on industrial and commercial jobs. Pipefitters and steamfitters assemble and repair the high-pressure piping systems that keep factories, refineries, and power plants running, and that work tends to pay better than residential plumbing once someone has the certifications for it.

Every one of these trades runs on an apprenticeship, usually four to five years of paid, supervised work combined with classroom instruction in blueprint reading, welding, and local plumbing codes. Nobody is handing a journeyman card to someone who watched a few online videos, which keeps the field from getting flooded and keeps wages where they are.

About 42,000 openings a year are projected through 2035. A good chunk of that comes from construction growth, but most of it comes from retirements in a workforce that is older, on average, than most skilled trades.

Heavy vehicle and mobile equipment service technicians

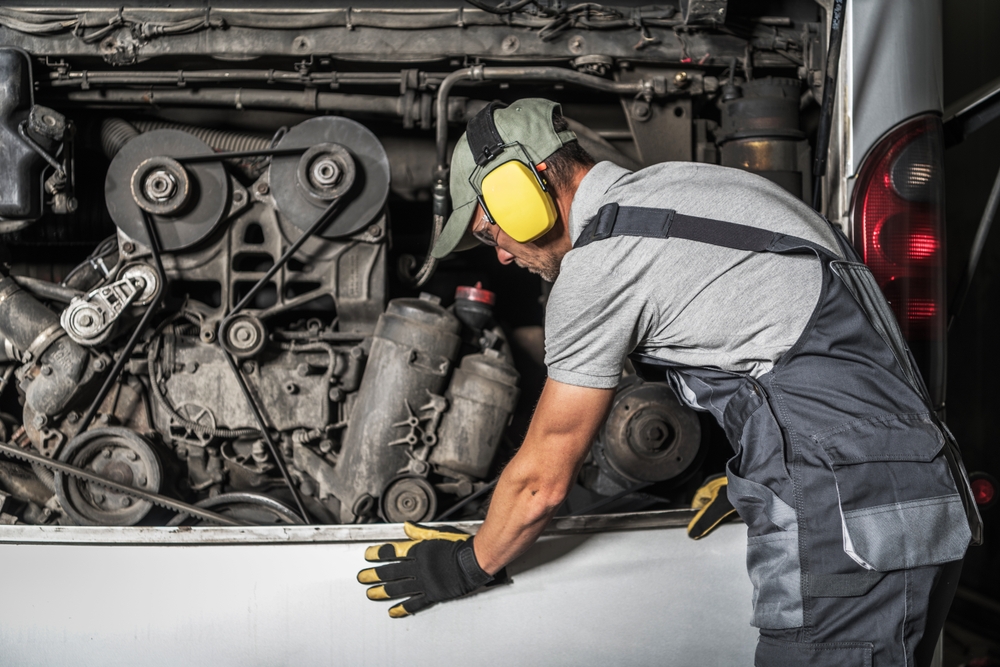
Mechanic repairing the diesel engine of a bus
Image Credit: Shutterstock

Keeping a fleet of delivery trucks, farm equipment, or construction machinery running is a full-time job on its own, and the people who do it earn a median of $63,850 a year, just over $30 an hour. These technicians work on hydraulic systems, diesel engines, electrical systems, and increasingly the computer diagnostics built into modern equipment, which makes the job closer to systems troubleshooting than simple wrench turning.

Training runs through a mix of employer apprenticeships and community college programs, usually one to two years, and most shops will hire someone with the right aptitude and finish training them on the job. Farm equipment dealers, construction companies, and trucking fleets all compete for the same small pool of qualified technicians, which keeps pay moving upward.

Employment is projected to grow 7 percent through 2035, adding roughly 17,100 jobs on top of about 20,300 openings projected every year from turnover alone. None of that equipment fixes itself, and none of it will anytime soon.

Industrial machinery mechanics

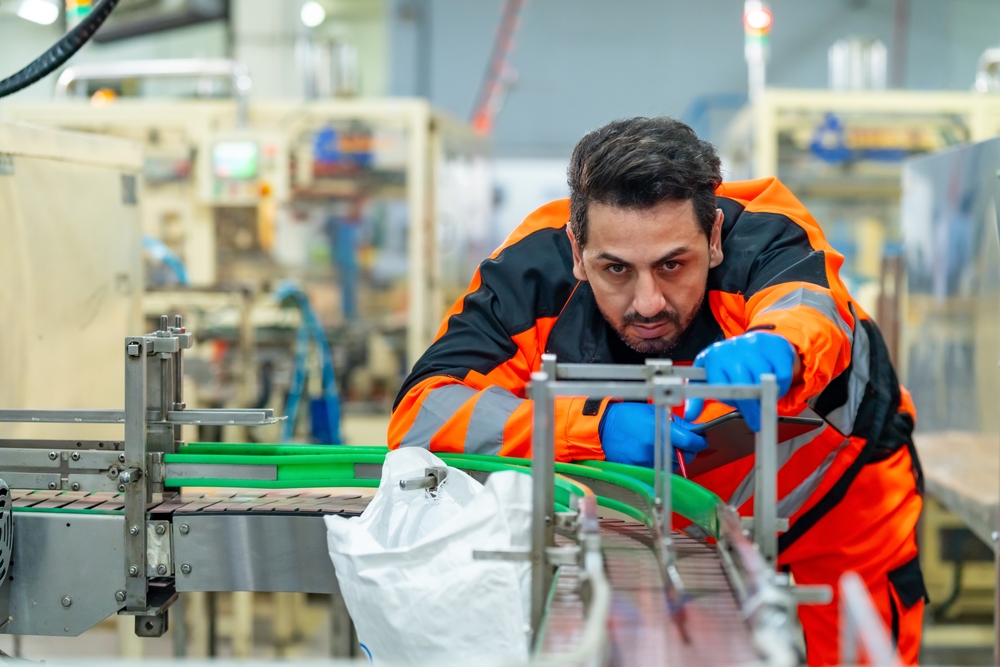
Industrial machinery mechanic repairing a factory conveyor belt
Image Credit: Shutterstock

Factories, warehouses, and processing plants run on conveyor systems, hydraulic presses, and robotics that all eventually break, and industrial machinery mechanics are the ones who get them running again. The median pay is $64,520 a year, a little over $31 an hour, and plants that run around the clock often pay a shift differential on top of that for nights and weekends.

Ironically, the more automated a factory gets, the more it needs this trade, since robotics and automated systems require mechanics who understand both the mechanical and electronic sides of the equipment. Most employers train on the job or through a technical college program, and some manufacturers run their own in-house apprenticeships specifically to build a pipeline of qualified mechanics.

Employment in this occupation is projected to grow 18 percent from 2025 to 2035, among the faster growth rates of any trade on this list, as more plants automate and need skilled people to keep that automation running.

Millwrights

Millwright working on heavy industrial machinery
Image Credit: Shutterstock

Millwrights install and align the heavy industrial machinery that other trades later maintain, which makes the two occupations close cousins but distinct jobs. A millwright might spend a week setting a turbine onto its foundation with laser alignment tools accurate to a few thousandths of an inch, then move to the next plant and do it again. Median pay sits at $65,700 a year, close to $31.60 an hour.

Precision is the whole job. A turbine or compressor that is off by a hair can vibrate itself apart within months, so millwrights train for years, often through a four-year apprenticeship run by a trade union, before they are trusted with the most critical installations. That training bottleneck is part of why experienced millwrights are in steady demand at manufacturing plants, power stations, and paper mills nationwide.

Growth in the occupation itself is modest, projected at just 1 percent through 2035, but that number undersells the demand. Most of the hiring comes from replacing millwrights who retire after decades in plants that cannot run without someone in that role.

Structural iron and steel workers

Structural ironworker working with a steel building frame
Image Credit: Shutterstock

Ironworkers raise the steel skeletons of bridges, stadiums, and high-rise buildings, often hundreds of feet in the air with nothing but a harness and a lot of trust in their own footing. It is one of the more physically demanding trades on this list, and the pay reflects it: a median of $62,780 a year, a little over $30 an hour, with higher scale pay on union jobs in major cities.

Most ironworkers come up through a three to four-year apprenticeship that combines paid fieldwork with classroom instruction in rigging, welding, and blueprint reading. The trade has a reputation for weeding people out fast. The ones who stay tend to stay for decades, which creates a steady stream of retirements that newer workers step into.

Employment is projected to grow a modest 3 percent through 2035, but infrastructure spending on bridges and public buildings, combined with those retirements, keeps crews hiring in most major markets.

Wind turbine service technicians

Wind turbine service technician checking equipment at a wind farm
Image Credit: Shutterstock

Climbing a turbine tower that can run 300 feet tall and troubleshooting the gearbox, blades, and electrical systems at the top is not a job for everyone, but it is one of the fastest-growing trades in the country. Median pay is $64,120 a year, close to $31 an hour, often with per diem pay added on top for techs who travel between wind farms.

Most technicians train through a one to two-year community college program built specifically around wind energy, sometimes in partnership with the turbine manufacturers themselves, and several of those programs place the large majority of their graduates directly into jobs. The work is physically demanding and the climbing is non-negotiable, but it does not require a four-year degree or years of unpaid apprenticeship before the real pay kicks in.

This occupation is projected to grow 30 percent from 2025 to 2035, among the fastest growth rates of any skilled trade in the country.

Boilermakers

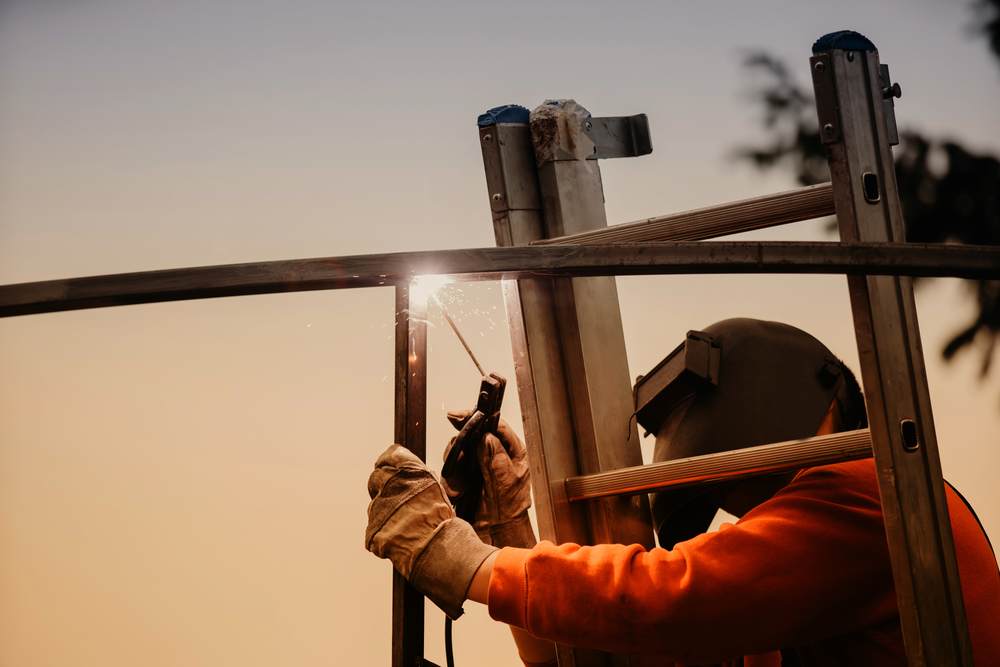
Welder wearing a protective helmet while welding a metal assembly
Image Credit: Shutterstock

Boilermakers build and repair the massive pressure vessels, tanks, and boilers that power plants, refineries, and large industrial facilities depend on, work that involves heavy steel, precision welding, and often confined spaces inside the vessel itself. It is a small trade, with only about 10,200 boilermakers working nationwide, and it pays like one: a median of $76,410 a year, close to $37 an hour.

The path in runs through a four to five-year apprenticeship, usually sponsored by a trade union, that combines paid fieldwork with welding certifications most other trades do not require. Because the work is so specialized, boilermakers often travel between job sites, following outages and maintenance shutdowns at power plants and refineries across several states.

The occupation itself is shrinking slightly, projected to decline 2 percent through 2035 as some older plants close. Even so, around 700 openings are projected every year, almost entirely from boilermakers retiring out of a trade that still needs someone to do this exact work wherever a pressure vessel needs fixing.

Stationary engineers and boiler operators

Maintenance engineer checking a boiler-house control panel
Image Credit: Shutterstock

Large buildings, hospitals, and manufacturing plants all run on mechanical systems that someone has to monitor and keep operating safely around the clock: boilers, chillers, generators, and HVAC systems that cannot simply be left alone. Stationary engineers and boiler operators are the ones watching those systems, and median pay for the role is $78,620 a year, close to $38 an hour.

Licensing requirements vary significantly by city and state, with some jurisdictions requiring a boiler operator’s license earned through a formal apprenticeship or union training program, while others accept documented work experience. Either way, the role carries real responsibility, since a poorly maintained boiler or pressure system is a genuine safety hazard, and that responsibility is part of why the pay runs higher than many other trades on this list.

Growth is projected at 3 percent through 2035, with roughly 3,200 openings a year, mostly in hospitals, universities, and manufacturing facilities that need someone on-site at all hours.
Aircraft mechanics and service technicians

Aircraft maintenance crew working on a helicopter rotor assembly
Image Credit: Shutterstock

Every commercial flight that takes off has been inspected, maintained, or repaired by a certified aircraft mechanic, and the Federal Aviation Administration does not let that work slide. Median pay for aircraft mechanics and service technicians is $79,870 a year, a little over $38 an hour, and mechanics working on larger commercial aircraft for major airlines typically earn toward the higher end of that range.

Getting certified means completing an FAA-approved aviation maintenance program, usually around two years, and passing a battery of written, oral, and practical exams. It is a slower, more regulated path into a trade than most, but it leads to a license that transfers across the country and a job that physically cannot be automated away, since every repair has to be signed off by a certified human mechanic.
Employment is projected to grow 5 percent through 2035, and the combined aircraft and avionics occupation group accounts for about 13,100 openings a year as an aging mechanic workforce retires faster than training programs are replacing it.

Avionics technicians

Avionics technician working on aircraft electronic systems
Image Credit: Shutterstock

Avionics technicians work on the electronic guts of an aircraft: navigation systems, radar, autopilot, and the increasingly complex computer systems that fly modern planes. It is close cousin work to aircraft mechanics but a distinct specialty, closer to electronics troubleshooting than mechanical repair, and it pays accordingly. Median pay is $82,280 a year, close to $39.50 an hour, among the higher-paying trades on this list.

Training follows a similar FAA-regulated path to aircraft mechanics, through an approved aviation maintenance program and certification exams, though avionics-specific coursework leans harder into electrical systems and avionics software. Airlines, defense contractors, and private aviation companies all compete for a limited supply of certified technicians.

The occupation is projected to grow 9 percent through 2035, faster than aircraft mechanics generally, as aircraft electronics grow more complex and need more specialized people to maintain them. Roughly 19,800 avionics technicians work nationwide, a small, tight-knit field where qualified people rarely stay out of work for long once they are certified.

Pile driver operators

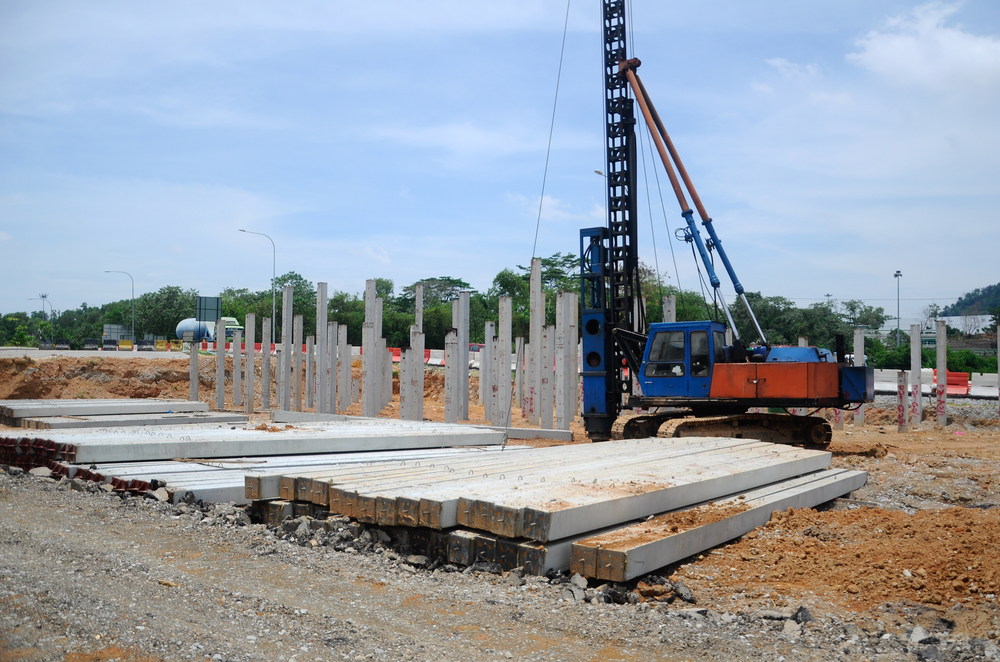
Tracked piling machine beside concrete foundation piles at a construction site in Melaka, Malaysia
Image Credit: Shutterstock; Aisyaqilumaranas / Shutterstock.com

Before a bridge, high-rise, or pier can go up, something has to drive the foundation piles deep into the ground to support it, and that is a pile driver operator’s job. It is one of the smaller and more specialized trades in construction, with only about 2,300 operators working nationwide, and it pays well for a reason: median pay runs $73,300 a year, north of $35 an hour.

Most operators come up through a heavy equipment operator apprenticeship or union training program, often after spending time on other construction equipment first, since pile driving requires a feel for the machinery that takes real experience to develop. It is precise, high-stakes work. A pile set at the wrong depth or angle can compromise an entire foundation.

Employment in this specific role is projected to decline 6 percent through 2035 as some pile driving work shifts to newer equipment that requires fewer operators per crew, but that has not pushed wages down. Skilled operators are still hard to find, and large infrastructure and commercial projects still need them.

Commercial and industrial electrical and electronics repairers

Technician using a tablet beside an open industrial electrical control cabinet
Image Credit: Shutterstock

Factories and large commercial facilities run on electrical and electronic control systems that require a different skill set than residential electrical work: programmable logic controllers, industrial sensors, and the automated systems that keep a production line moving. The people who repair this equipment earn a median of $74,090 a year, close to $35.60 an hour.

Most repairers train through a two-year electronics or industrial technology program, and many employers provide additional on-the-job training specific to the equipment running in their facility. The work sits at the intersection of electrical theory and computer logic, which keeps it out of reach for anyone without real technical training, and keeps it harder to automate away than more repetitive manufacturing roles.

Overall employment in this occupation is projected to hold roughly flat through 2035, but that stability is itself part of the appeal: a steady, well-paid trade with a manageable training path and consistent demand from any facility that runs industrial equipment.

Electrical power-line installers and repairers

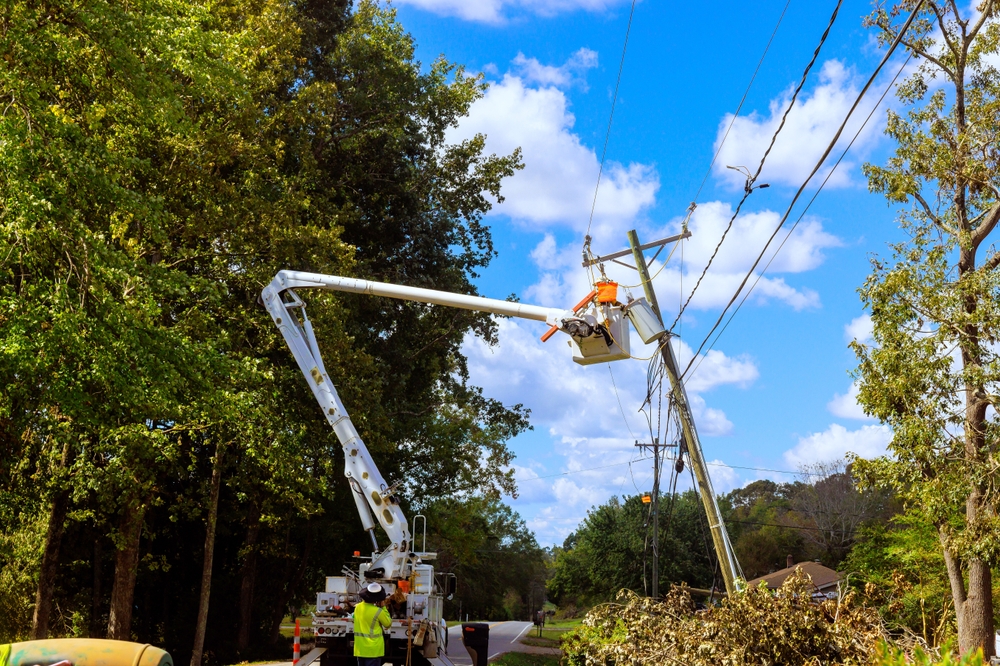
Utility crew repairing overhead power lines with a bucket truck
Image Credit: Shutterstock

Climbing a utility pole or working from a bucket truck on a high-voltage transmission line is not a trade for the faint of heart, and the pay reflects both the risk and the skill involved. Median pay for electrical power-line installers and repairers is $95,320 a year, close to $46 an hour, among the highest-paying trades that do not require a college degree.

Most line workers come up through a utility-sponsored apprenticeship, typically three to four years, that combines paid fieldwork with safety training around high-voltage equipment. Utilities take that safety training seriously, since the margin for error around live power lines is essentially zero, and that rigor is part of why the trade pays as well as it does.

Growth is projected at 10 percent through 2035, adding an estimated 13,600 jobs, with roughly 10,900 openings projected every year as the grid gets upgraded for EV charging demand, renewable energy, and basic storm resilience that keeps getting more urgent.

Powerhouse, substation, and relay electrical repairers

Electrical technicians inspecting equipment at a power substation
Image Credit: Shutterstock

The highest-paid trade on this list maintains the equipment that keeps the electrical grid itself running: the transformers, circuit breakers, and relay systems inside power plants and substations that most people never see and never think about until the power goes out. Median pay is $103,020 a year, close to $49.50 an hour.

Utilities train almost all of these repairers in-house, through multi-year apprenticeships that combine classroom instruction in electrical theory with hands-on work inside live substations under close supervision. It is some of the most consequential electrical work there is. A mistake inside a substation can black out a whole section of a city, and the training reflects that.

Employment is projected to grow 10 percent through 2035, adding about 2,000 jobs to a workforce of just under 21,000 nationwide, as aging grid infrastructure gets modernized and utilities compete hard for a small pool of qualified repairers.

None of these trades require sitting through four years of lecture halls, and all of them pay a working wage from the day training starts. The people doing them are not worried about a chatbot showing up to take their spot on the crew.

A box of cufflinks at the back of a dresser drawer looks like an afterthought, something kept out of sentiment and never sorted through. Most of what’s in there is exactly what it looks like: cheap, mass-produced, and worth closing the drawer on. But cufflinks are a strange category of men’s jewelry. The same small shirt-cuff accessory could be a department-store boxed set, or it could be a signed Tiffany, Cartier, or Georg Jensen piece that got tossed in with everything else because nobody bothered to turn it over.

Here are 18 specific types worth checking for, from Hickok sets that turn up at nearly every estate sale to solid gold pieces by the houses that made cufflinks a serious category of jewelry in the first place. Flip them over before deciding what they’re worth.

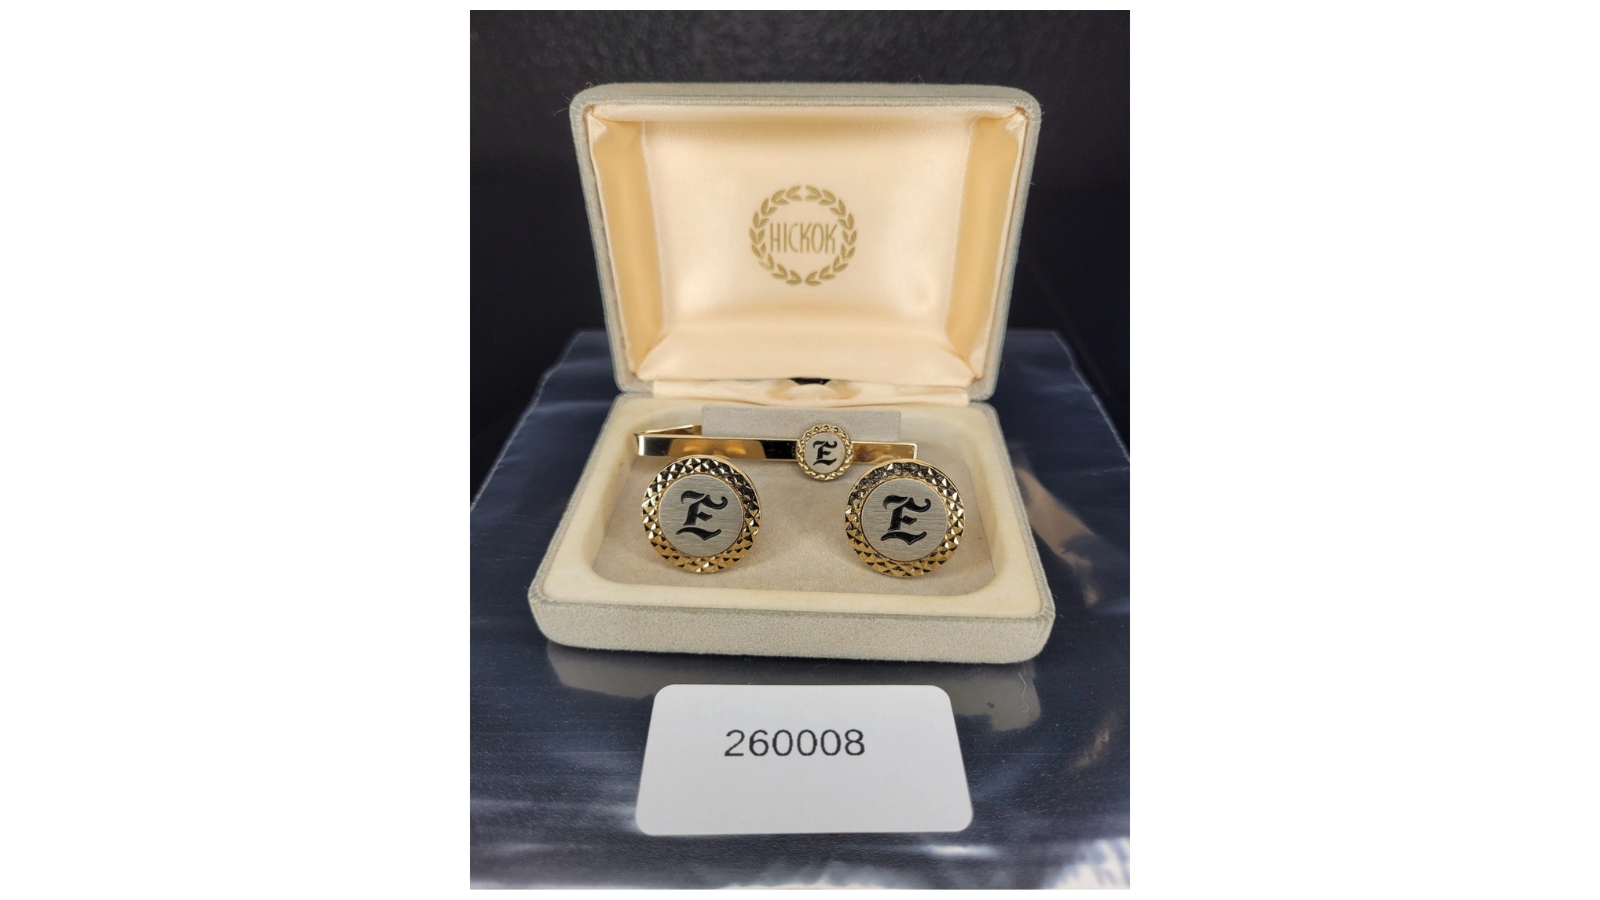
Hickok monogram E cufflinks and matching tie bar in their fitted box
image credit: smokitd_and_lulu via eBay

A Hickok box turning up in a father’s or grandfather’s dresser is one of the most common men’s jewelry finds there is, and most of what’s inside won’t make anyone rich. But matched sets with the original monogrammed cufflinks and tie bar, especially from Hickok’s postwar boxed-set era, sell steadily to buyers who collect the brand or want a specific initial. Clean, complete sets with their velvet-lined box typically bring $15 to $40, with unusual motifs or sterling-marked pieces pushing toward the top of that range.

Condition carries most of the value here. Look for the Hickok USA stamp on the back, check that the swivel backs still move freely, and make sure the finish isn’t pitted or peeling, since gold-tone plating wears unevenly with age. A set that still has its original fitted box, even a shabby one, is worth more than a loose pair rattling around in a drawer, and a monogram that happens to match a buyer’s own initial can add a small premium on top.

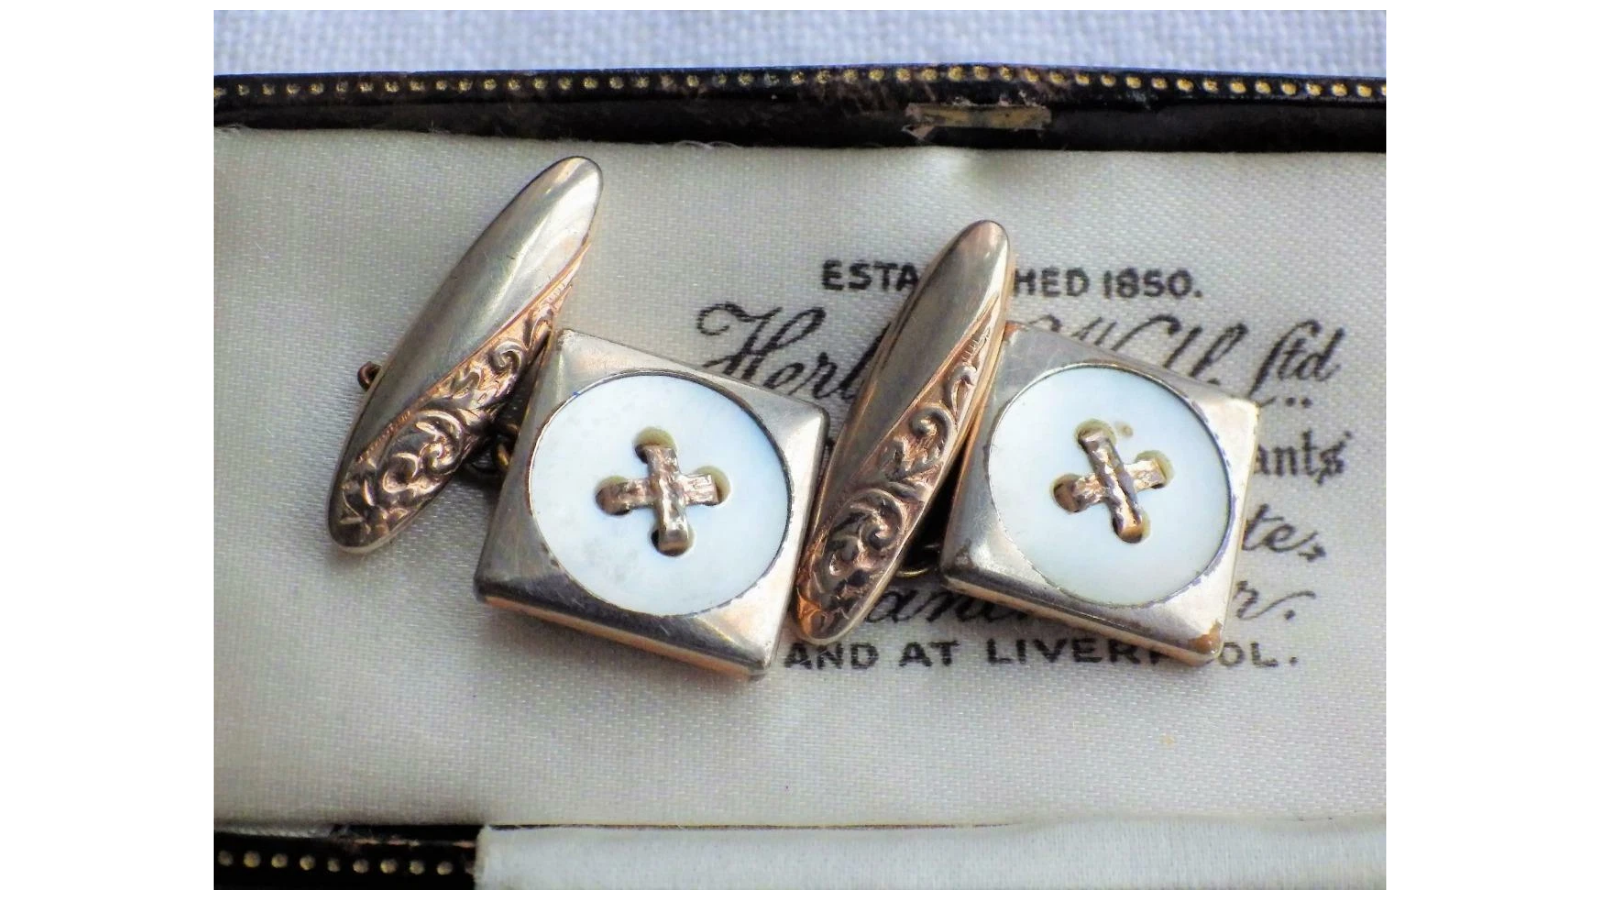
Mother-of-pearl cufflinks with small cross-shaped details in a jewelry box
image credit: jools7758 via eBay

Mother-of-pearl cufflinks were a staple of formal menswear from the 1920s through the 1950s, and plain silver-mounted pairs show up often in old jewelry boxes without anyone realizing what they’re holding. A basic pair with iridescent shell discs set in sterling or silver plate typically brings $35 to $90 in good condition, with unusually large or perfectly matched discs toward the top of that range.

What separates a forgettable pair from a better one is the shell itself. Genuine mother-of-pearl has a soft, shifting sheen when it catches the light, while plastic imitations look flat and uniform by comparison. Small chips around the edge of a disc are common and generally acceptable, but a cracked or discolored disc drops the value sharply. A matched set, where the grain and color of both discs line up closely, is worth more than a mismatched pair that was assembled from spare parts over the years. Gold-mounted examples, especially ones with a diamond or seed pearl center, belong in a different and considerably higher price bracket entirely.

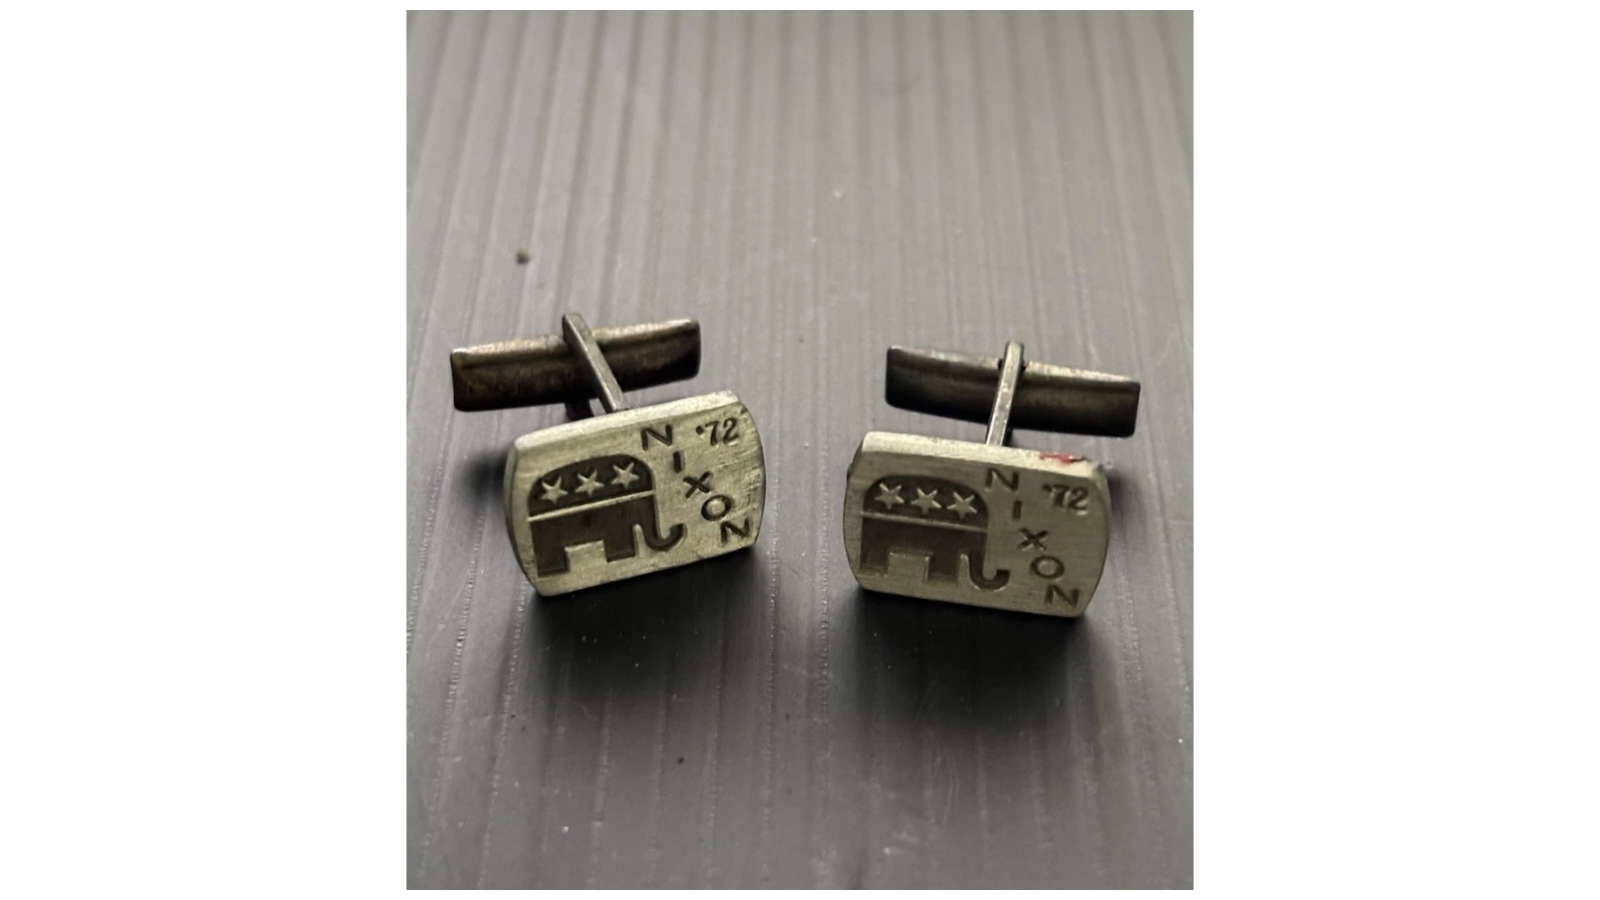
Gold-tone Nixon 1972 campaign cufflinks with elephant designs
image credit: todayisanawesomeday via eBay

Presidential campaigns have handed out cufflinks to donors and staff for decades, and the ones that survive tend to turn up in the same box as old tie clips and lapel pins. A pair tied to a specific, named campaign, especially one with the candidate’s portrait or running mate worked into the design, typically brings $20 to $60, with inauguration sets and earlier or less common campaigns bringing more.

Condition and completeness both matter. Gold-tone plating on these pieces wears thin with handling, so a crisp, unworn finish is worth paying attention to. A pair still on its original presentation card, or paired with a matching tie bar, sells for noticeably more than loose cufflinks alone. Campaigns that lost, or candidates who never made it past the primary, sometimes bring more than a winning campaign simply because fewer of those items were ever produced or kept. Because reproduction and modern novelty versions exist for nearly every well-known election, compare the lettering style and metal finish against known genuine examples before assuming a rare year automatically means real value.

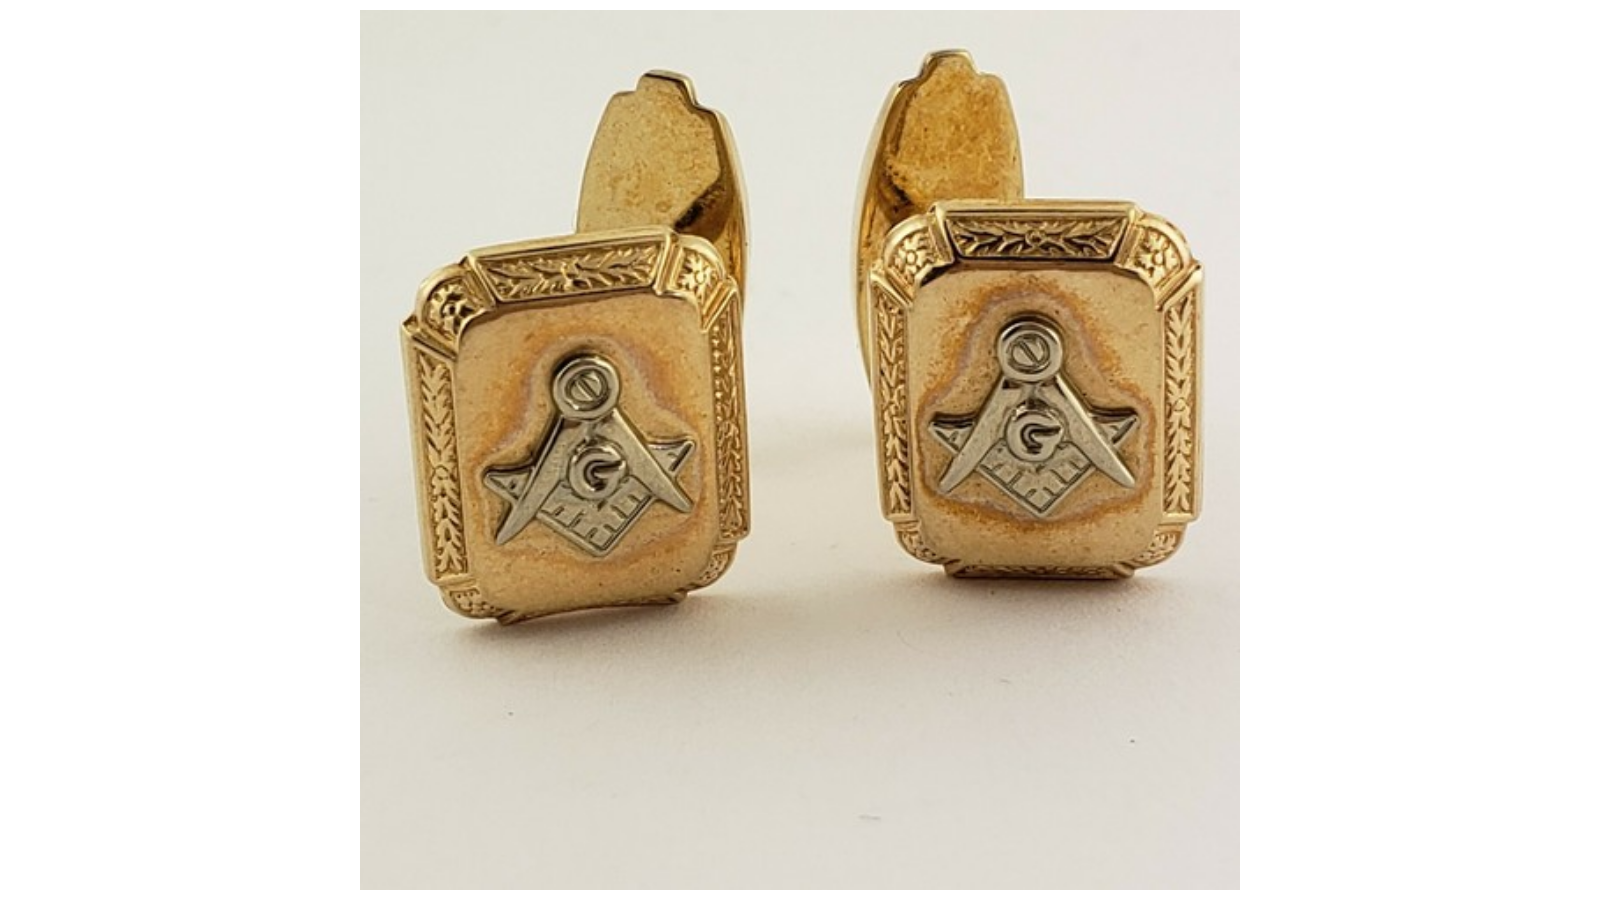
Gold-tone Masonic cufflinks with square and compass emblems
image credit: bergig28 via eBay

Masonic cufflinks show up constantly at estate sales, since so many lodge members owned at least one pair, and most of what surfaces is gold-tone base metal with the square and compass stamped or enameled on the face. Those common sets are modest, typically bringing $20 to $50. What changes the math entirely is the metal underneath the symbol: a pair genuinely struck in 10 karat or 14 karat gold, rather than gold-plated brass, typically brings $150 to $400, with the cleanest hallmarked examples toward the top of that range.

A metal test or a close look at the hallmark is the only reliable way to tell the two apart, since plated and solid gold Masonic cufflinks can look nearly identical. Check inside the cufflink post for a karat stamp, and weigh the pair if you have a scale, since solid gold feels noticeably heavier than its plated equivalent. Chipped enamel or a mechanism that no longer swivels both reduce value, even on an otherwise genuine gold pair.

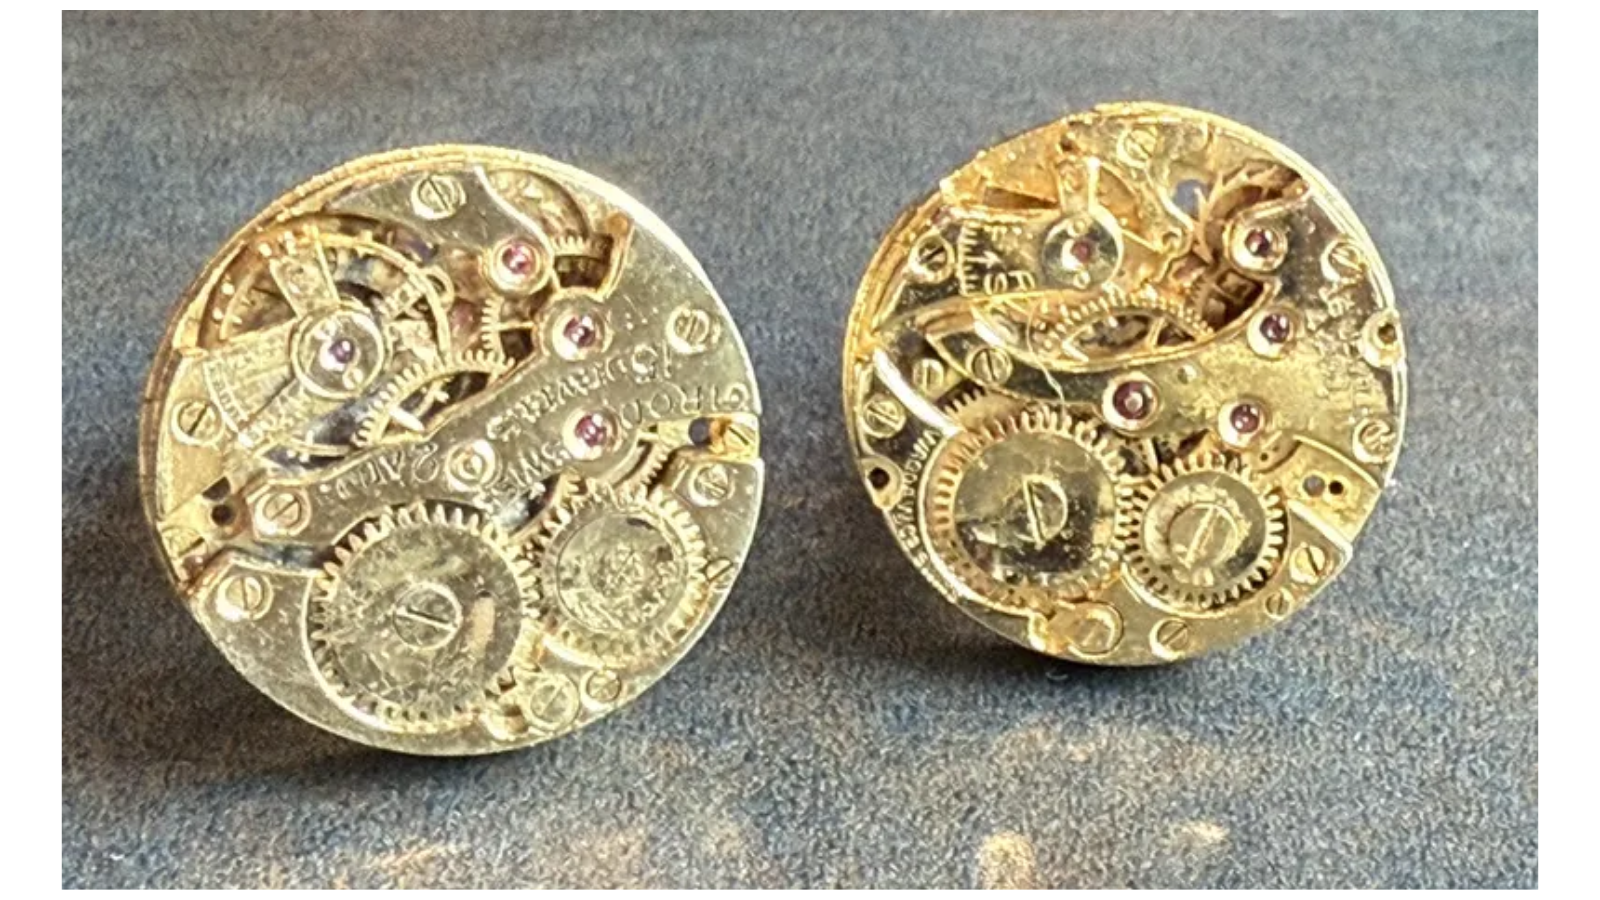
Gold-tone vintage watch-movement cufflinks with exposed gears and jewels
image credit: FickleThistle via Etsy

Early in the twentieth century, jewelers started repurposing worn-out pocket watch movements into cufflinks, mounting the gears and jeweled works behind a glass face. Genuinely old examples, often stamped with a defunct American watch company’s name, carry real collector interest decades later. A clean, period pair in working gold-filled or gold-plated mounts typically brings $35 to $90 for the set.

The name on the movement matters more than most buyers expect, since a recognizable but now-defunct watchmaker adds a layer of history that a generic or unmarked movement doesn’t have. These were never solid gold, since the appeal was always the ingenuity of the piece rather than the metal, so scrap value was never really the point. A pair where the gears are still visible and undamaged under the crystal is worth more than one where moisture has gotten in and clouded or rusted the works. Running movements are rare and mostly beside the point, since almost nobody buys these to keep time, but a face that’s cracked or badly fogged still counts against the pair.

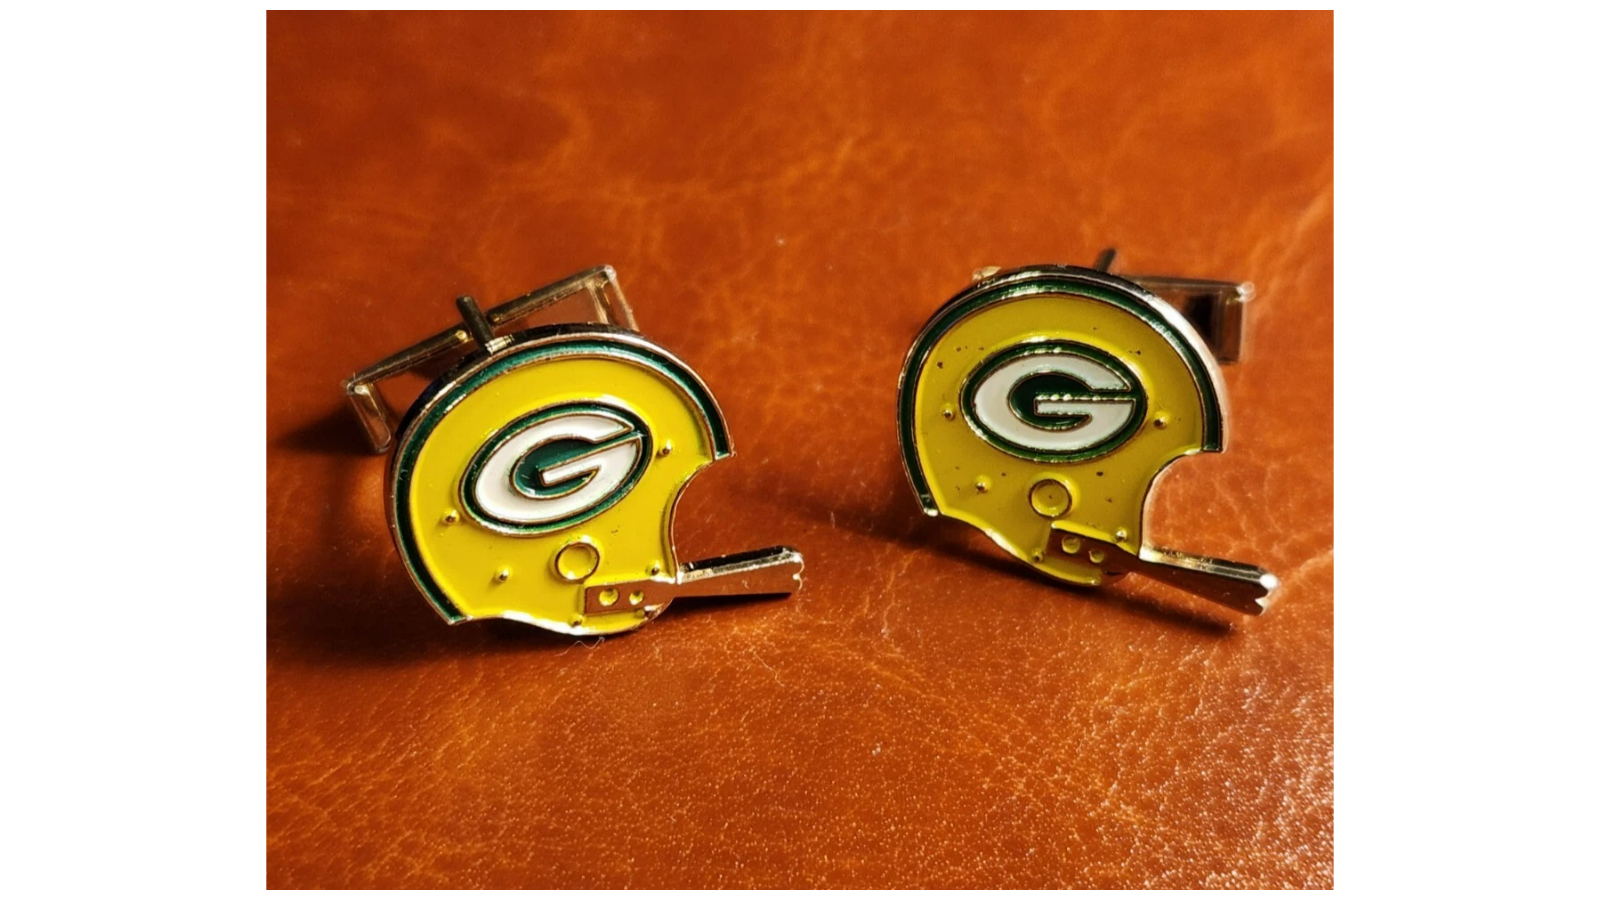
Vintage Green Bay Packers helmet cufflinks in green and gold enamel
image credit: packerwackomark via eBay

Team-branded cufflinks were standard corporate and booster-club gifts through the 1960s and 70s, usually gold-tone metal with the team’s logo worked in colored enamel. A common pair in good condition, for almost any NFL franchise, typically brings $25 to $75, with older teams, discontinued logos, and clean enamel work toward the top end.

These were mass-produced promotional items, so completeness and condition do most of the work in setting the price. Enamel that’s chipped, faded, or shows a logo that doesn’t quite match the team’s known vintage branding should lower expectations, since reproduction team merchandise exists for every popular franchise. A matching tie bar in the same set adds to the value, as does any paperwork tying the pair to a specific event or season, such as a booster-club dinner or an anniversary season. Older, discontinued logos tend to outperform current ones, since fewer of them were kept once a team rebranded. Pieces connected to a specific player or a championship season belong in an entirely different bracket.

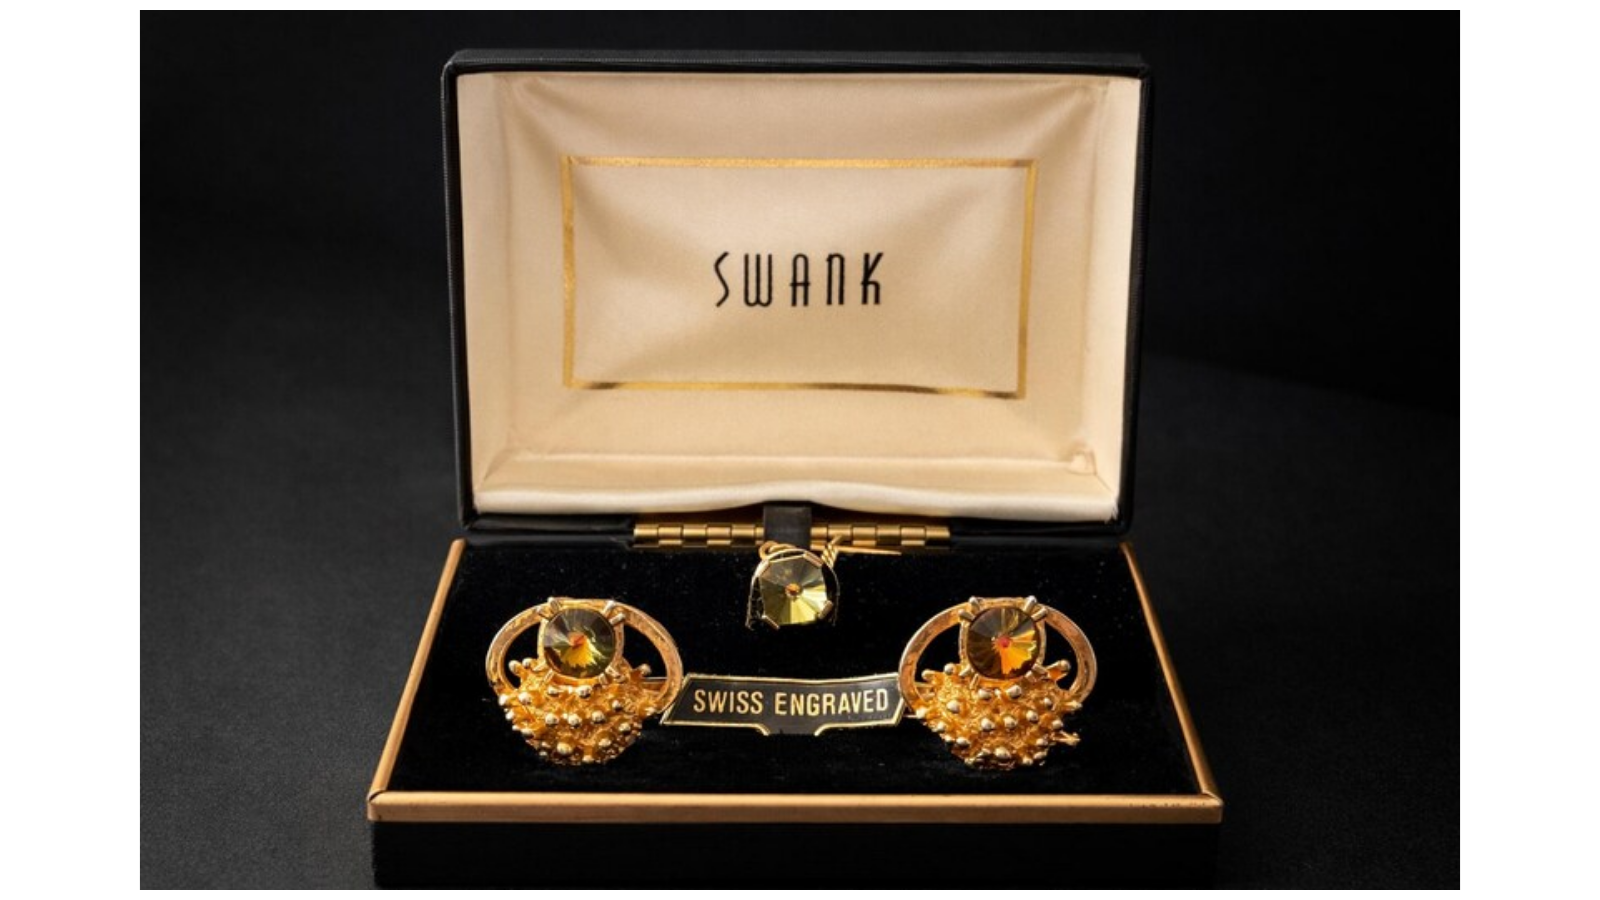
Swank gold-tone cufflinks with amber rhinestones in their original box
image credit: pleasurefortreasure via Etsy

Swank was one of the biggest American names in men’s jewelry through the mid-twentieth century, and its boxed cufflink and tie clip sets, often set with clear or colored rhinestones in a tuxedo-ready design, are some of the most commonly found vintage cufflinks around. Most complete sets in their original presentation box typically bring $20 to $75, with unusual stone colors or sculptural, modernist designs pushing toward the higher end.

Because Swank made these by the millions, rarity comes down to the specific design rather than the brand name alone. Simple round rhinestone pairs are common and modest; cubist, figural, or colored gemstone designs still carrying the Swank name are scarcer and worth more. Missing stones are a frequent problem and an easy one to spot, and a set that still has its original box adds a real premium over the same cufflinks found loose. Cloudy or yellowed rhinestones, from decades sitting in a damp drawer, are harder to sell than clean, bright ones, even when the metal underneath is in good shape.

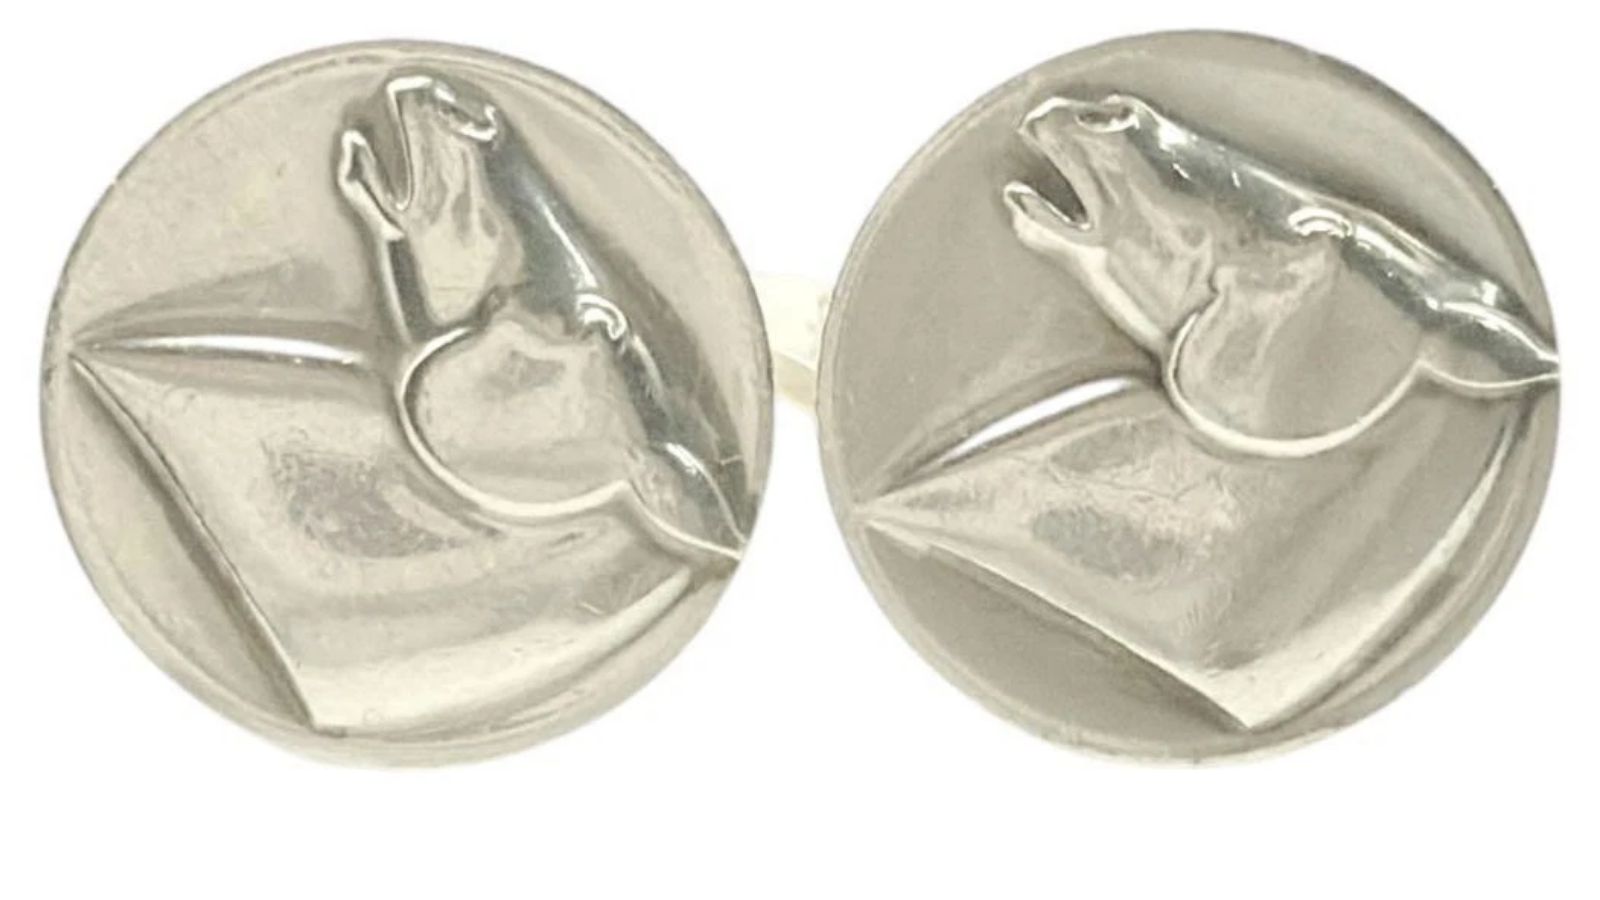
Georg Jensen silver cufflinks with raised horse designs
image credit: ann-pain via eBay

Georg Jensen’s Copenhagen workshop has produced sterling silver cufflinks since the early twentieth century, and because the house issued numbered patterns for decades, even an unassuming pair found in a drawer can often be traced to a specific design and designer. A plain, period-correct pair in good condition typically brings $80 to $150, while cufflinks tied to a named in-house designer and a documented pattern number bring considerably more, often $300 to $500.

Every genuine piece is marked, usually with the Jensen name in a dotted oval alongside a pattern number and a sterling hallmark, so the back of the cufflink matters more than the front when authenticating one. Tarnish is normal and polishes out without hurting value, but a mark that looks filed down, blurred, or machine-stamped rather than hand-struck is a reason for caution. Naturalistic and geometric Scandinavian modernist designs from the 1930s through the 1960s are the ones serious collectors chase hardest.

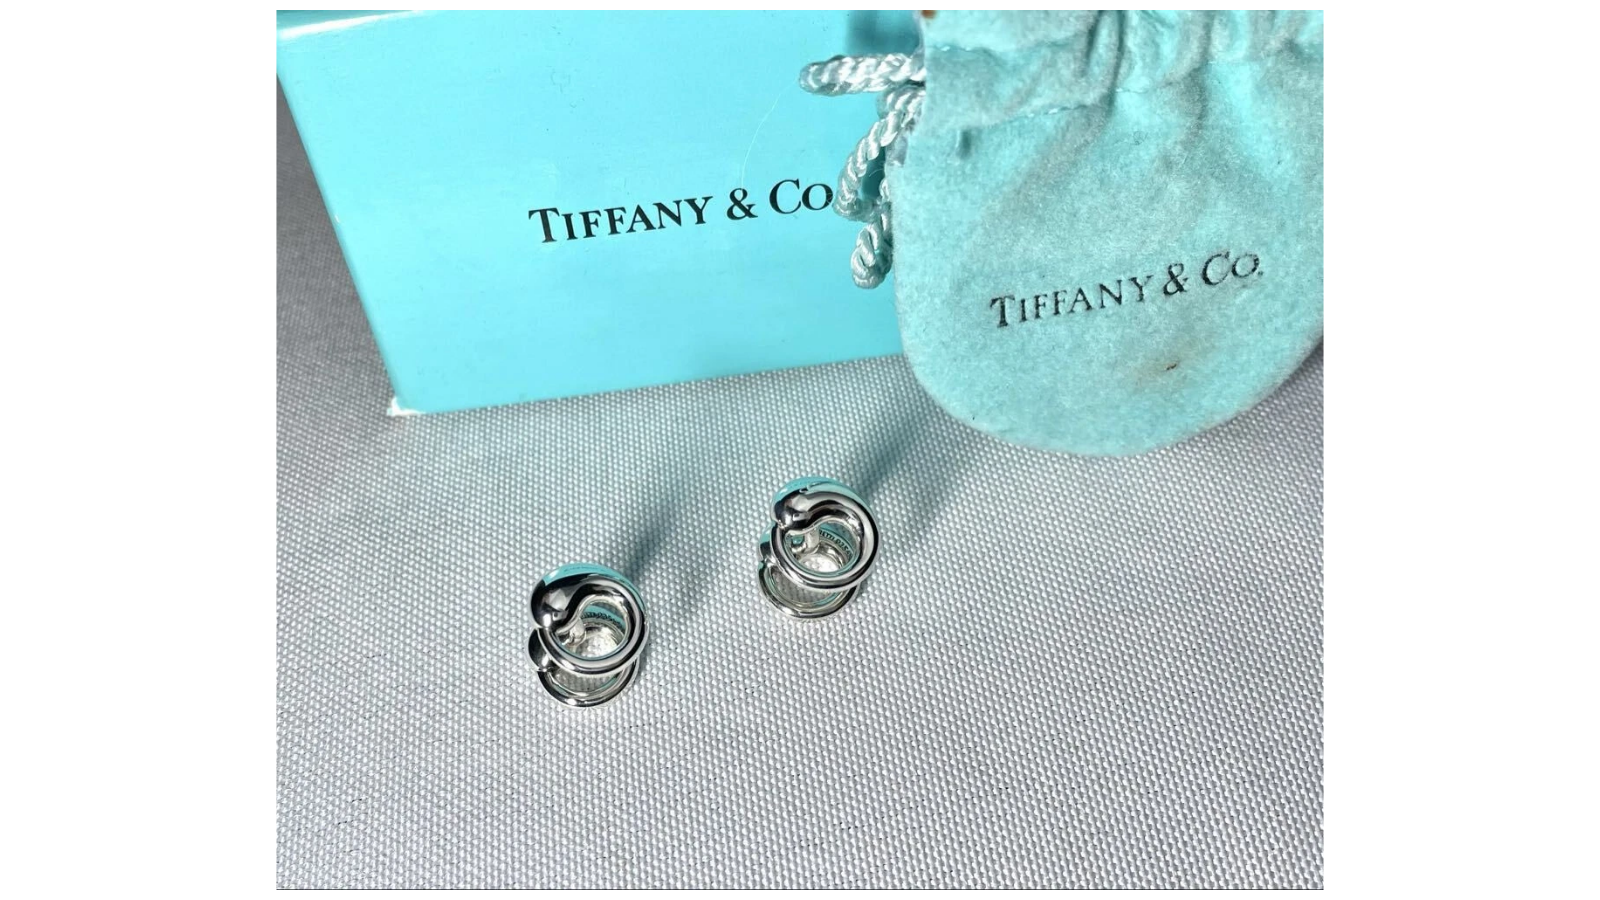
Tiffany sterling silver cufflinks beside a blue box and pouch
image credit: atsuki1860 via eBay

Tiffany & Co. has sold men’s cufflinks in its blue box for generations, and sterling silver examples, rather than gold ones, are the ones most likely to turn up in an inherited jewelry box at a price ordinary buyers can still reach. A genuine, hallmarked pair in a classic shape, oval, knot, or bar, typically brings $150 to $400, with heavier pieces and more distinctive shapes toward the top of that range.

The TIFFANY & CO. stamp, along with a sterling or 925 mark, should be clear and evenly struck; a soft, shallow, or oddly placed mark is worth a second look. Weight matters too, since Tiffany’s sterling cufflinks tend to be substantial rather than thin and light. Pairs tied to a well-known in-house designer, rather than an unsigned house pattern, carry a further premium once that connection is confirmed. Gold or gold-and-silver combination pieces from the same house sell in an entirely different, much higher bracket, so the name alone doesn’t put every Tiffany cufflink in the same range.

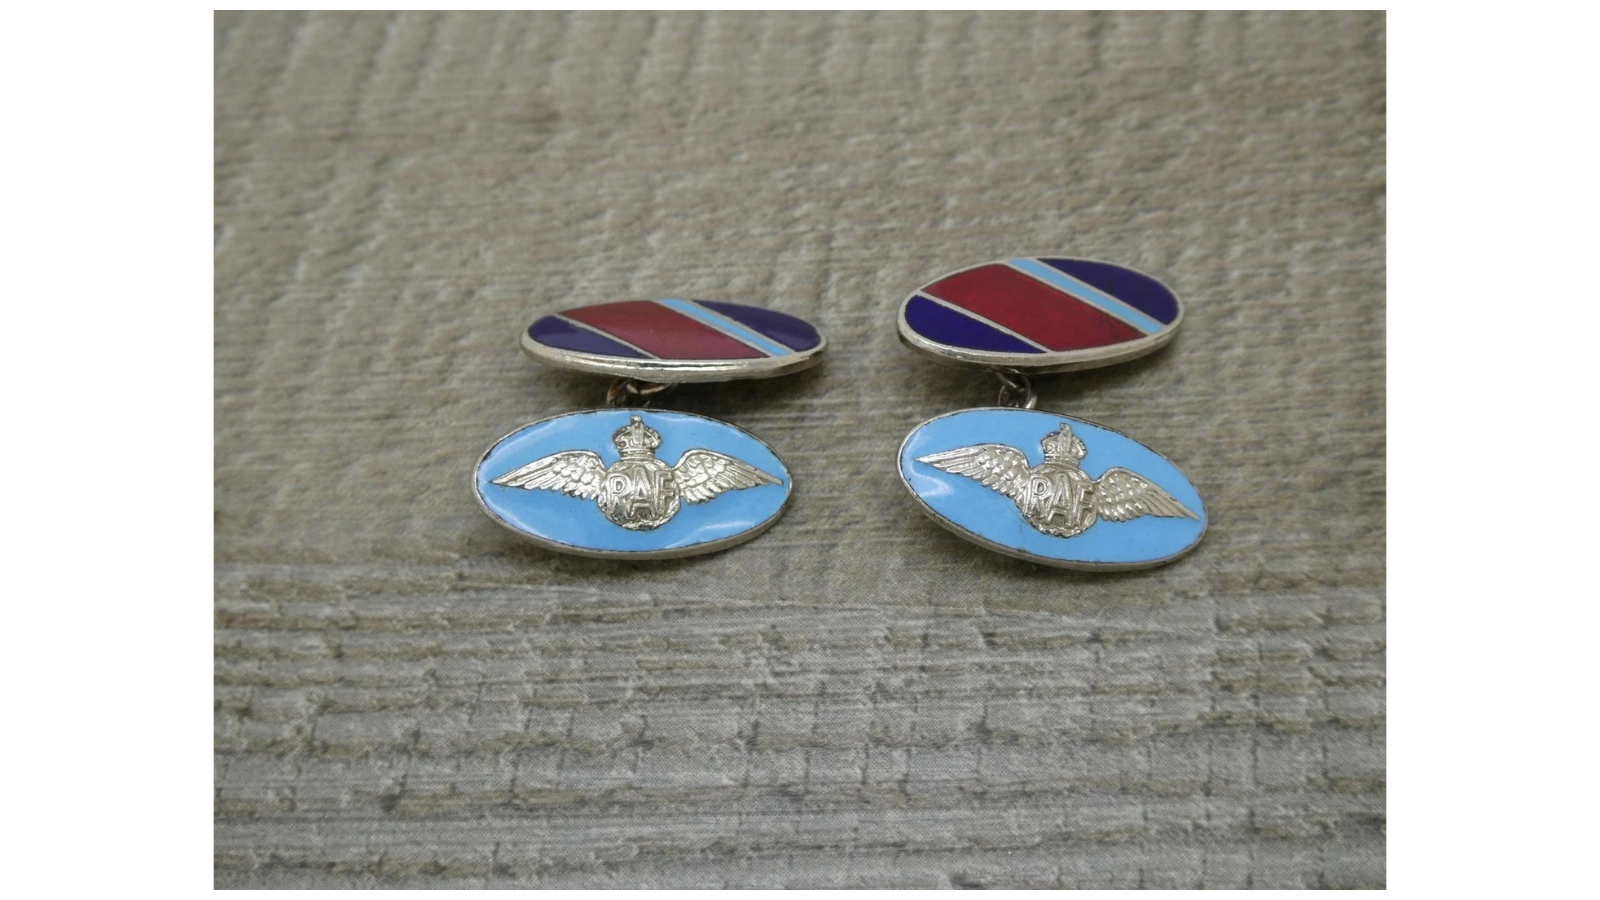
Vintage RAF enamel cufflinks with winged emblems and striped backs
image credit: jewelleryemporium via eBay

British and Commonwealth air force cufflinks, enameled in red, white, and blue with the winged crown-and-wreath emblem, are a specific and collectible corner of military jewelry that turns up regularly in estate sales on both sides of the Atlantic. A genuine period pair in brass or chrome with intact enamel typically brings $35 to $90, with examples in solid gold or tied to a specific, named squadron reaching considerably more.

Enamel condition drives most of the price here, since the roundel colors are prone to chipping and fading after decades of handling. Hold the piece up to good light and check each color field for hairline cracks before assuming it’s pristine. Reproduction and costume-jewelry versions of air force insignia are common and usually have a flatter, more uniform enamel finish than genuine wartime pieces, so comparing weight and the crispness of the stamped detail against a known original is worth the extra minute.

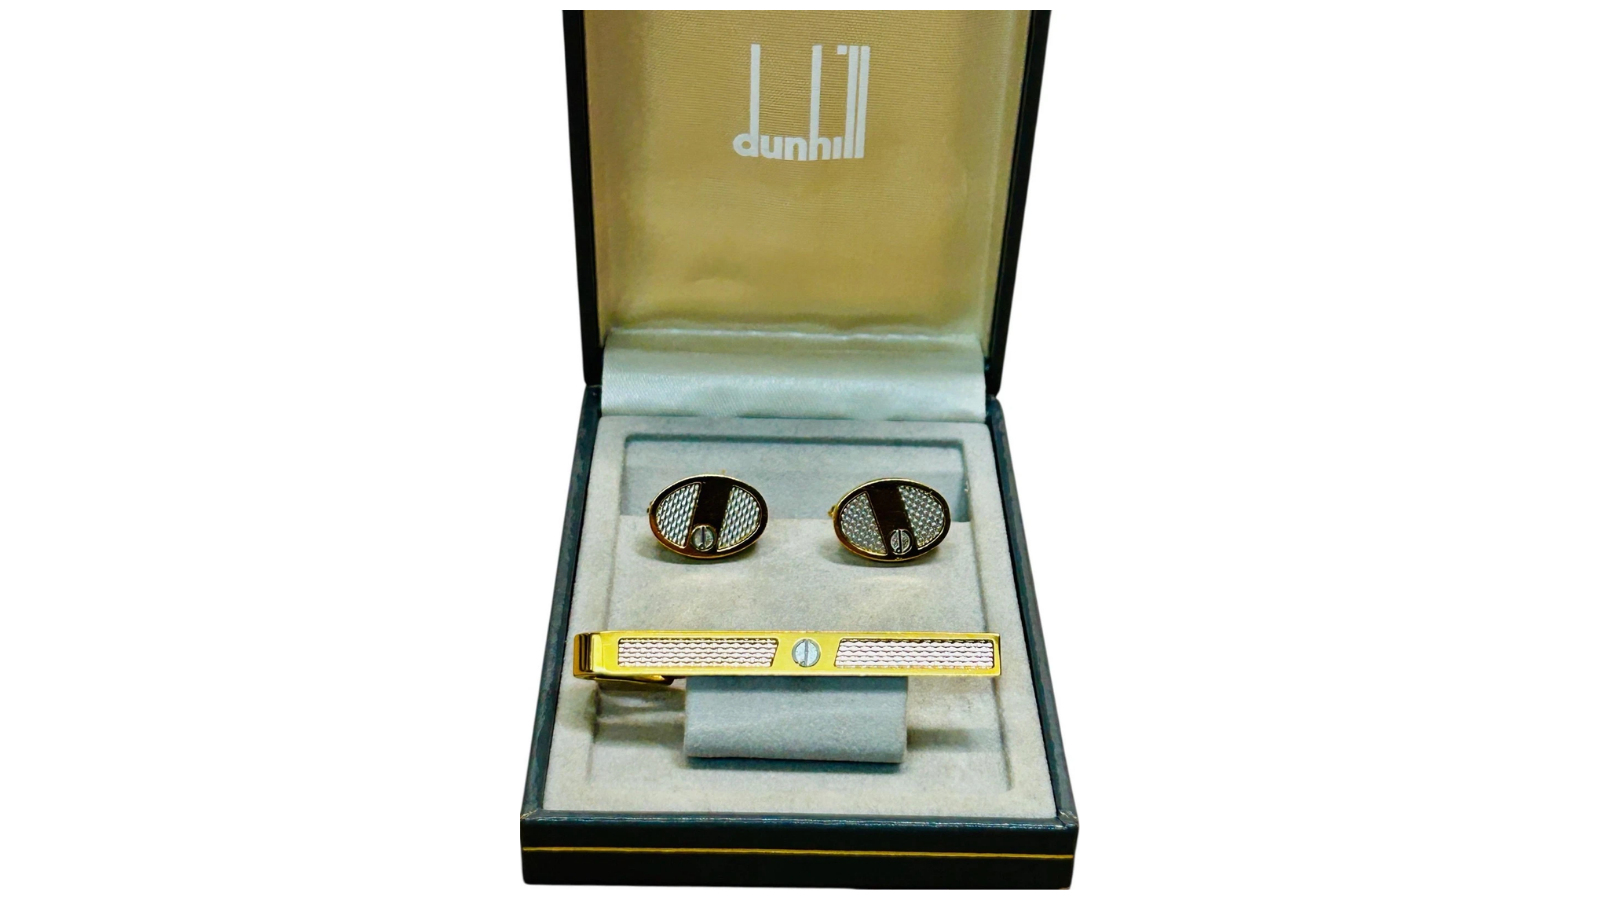
Dunhill cufflinks and matching tie clip in a fitted presentation case
image credit: thegroovymagpieshop via eBay

Alfred Dunhill built its reputation on menswear and smoking accessories, and its vintage gold-plated cufflinks, often set with onyx or lapis and sold in a fitted Dunhill case, are a genuine step up from ordinary mid-century cufflinks without reaching Cartier-level prices. A clean, cased pair with the Dunhill signature typically brings $275 to $375, with onyx or lapis-set examples toward the top of that range.

The original case matters more with this brand than with most, since Dunhill’s fitted boxes are instantly recognizable and buyers pay a real premium for a matched set. Check that the gold plating hasn’t worn through to a brassy base layer at the edges, a common problem on pieces that saw regular use, and look for the Dunhill name stamped clearly on the cufflink itself rather than just on the case, since the two occasionally get separated and reunited by sellers. A genuinely engine-turned surface, with fine, machine-cut parallel lines, marks the better examples.

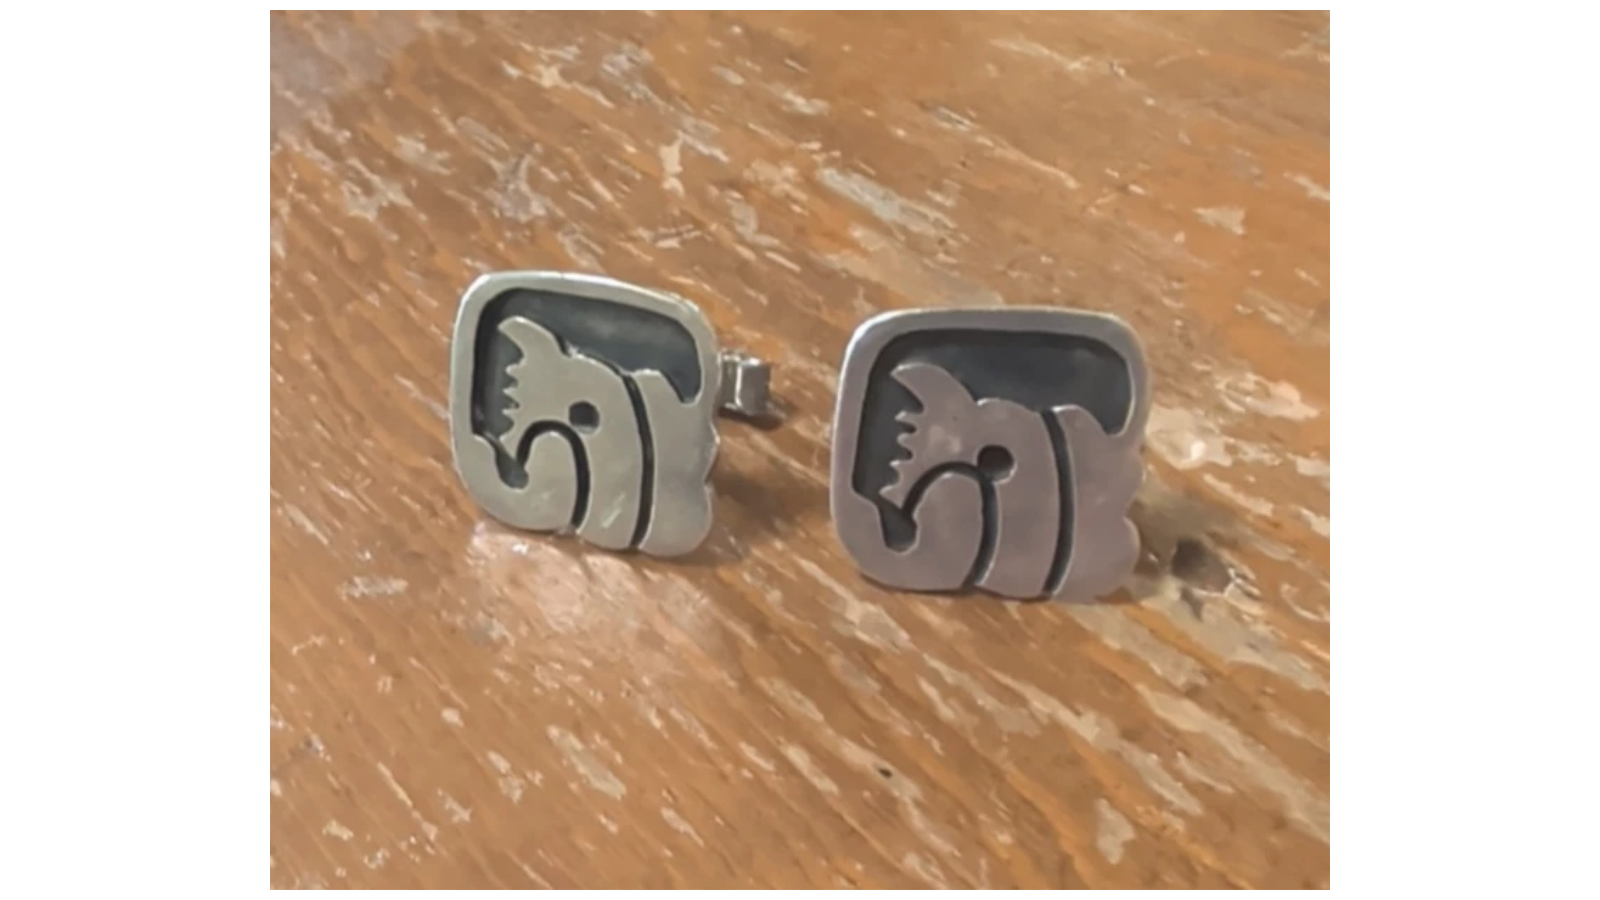
Taxco silver cufflinks with geometric horse-head designs
image credit: livingmodesign via eBay

Taxco, Mexico, has been a center of sterling silver jewelry production since William Spratling set up his workshop there in the 1930s, training generations of silversmiths who went on to run their own studios. Most Taxco cufflinks that surface today are unsigned or marked only “Mexico” and “925,” and these modest, well-made pairs typically bring $40 to $90 in good condition.

A piece stamped with a named workshop’s mark rather than a generic Mexico 925 stamp is worth researching before selling, since work tied to Spratling’s own workshop or one of his trained successors commands real premiums across the wider Taxco silver market. Oxidation and tarnish are normal and polish away without harming value, but a seam that looks soldered rather than cast in one piece, or a stone that’s clearly glued rather than set, suggests a later, lower-quality piece rather than an original mid-century design. Weight is a decent rough guide too, since heavier, substantial castings tend to be earlier work than the thinner, lighter pieces made for the tourist trade in later decades.

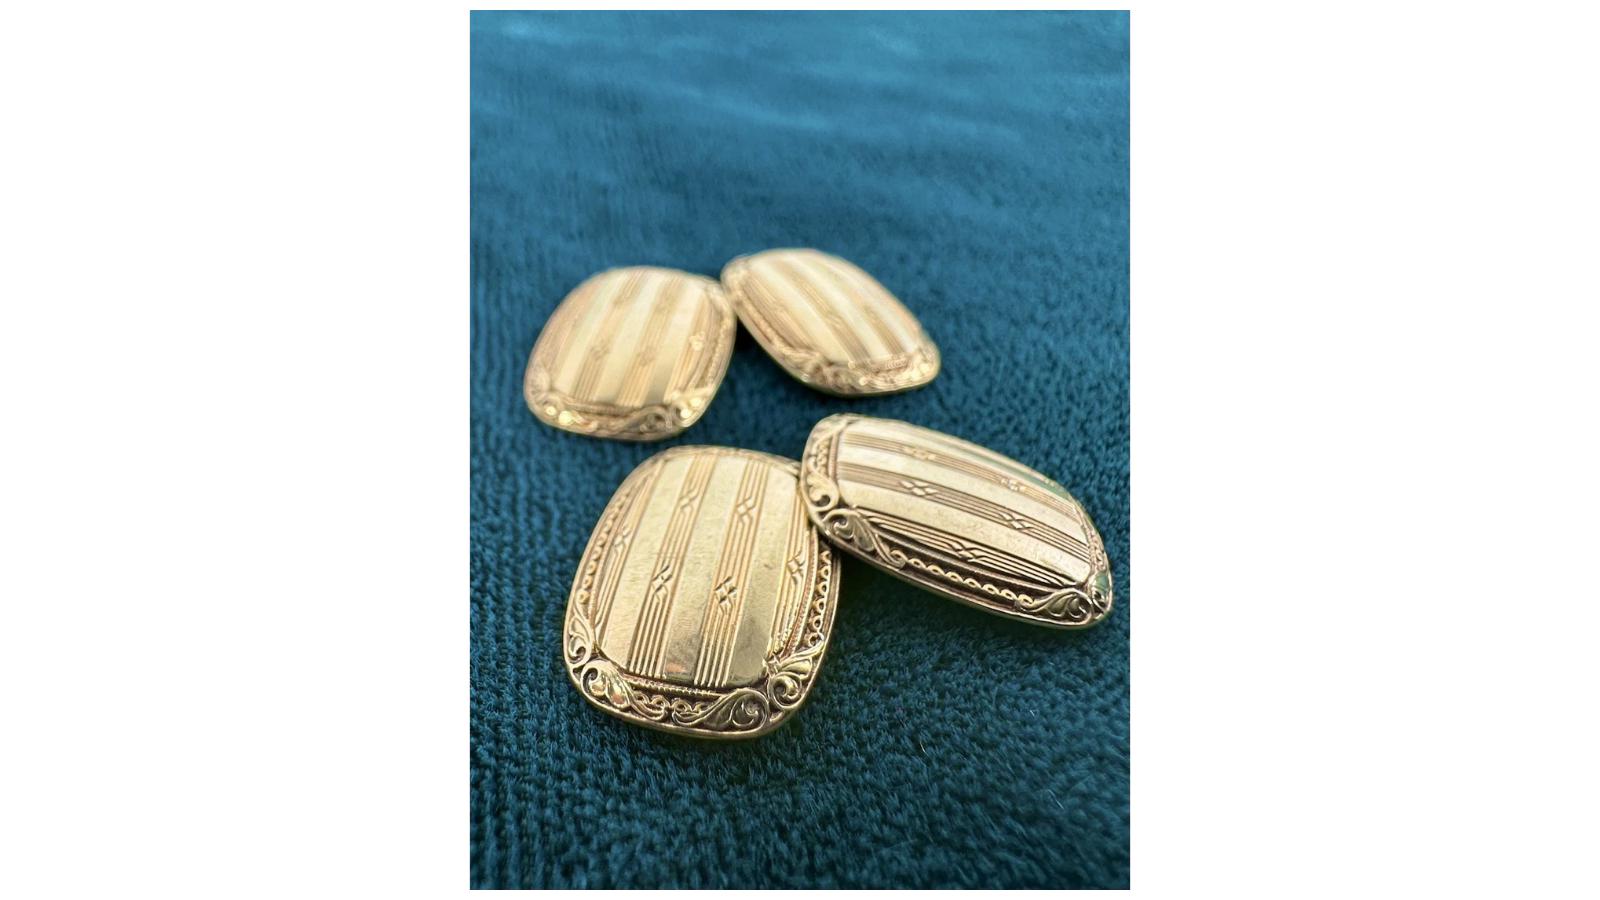
Larter and Sons gold cufflinks with engraved Art Deco faces
image credit: pickergrinnerloversinner via eBay

Larter & Sons, a Newark, New Jersey jeweler active from the 1860s through the mid-twentieth century, specialized almost entirely in men’s gold jewelry, and its Art Deco cufflinks are some of the most consistently well-made pieces from that era to show up in estate jewelry today. A signed, 14 karat gold pair in a geometric or enamel design typically brings $300 to $600, while carved figural or gemstone-set examples command significantly more, with the rarest designs valued well into four figures.

The Larter & Sons mark, usually a small stamped signature alongside the 14K fineness mark, is the key thing to look for on the bar fitting or the back of the cufflink face. Because the firm worked almost exclusively in solid gold rather than gold-filled or plated metal, a genuine pair carries real melt value before the maker’s name even enters the picture. Carnelian, onyx, and enamel were common accent materials; chips in a carved stone or enamel loss both reduce value, but a clean, crisply marked pair in any of the house’s signature motifs is a reliable find.

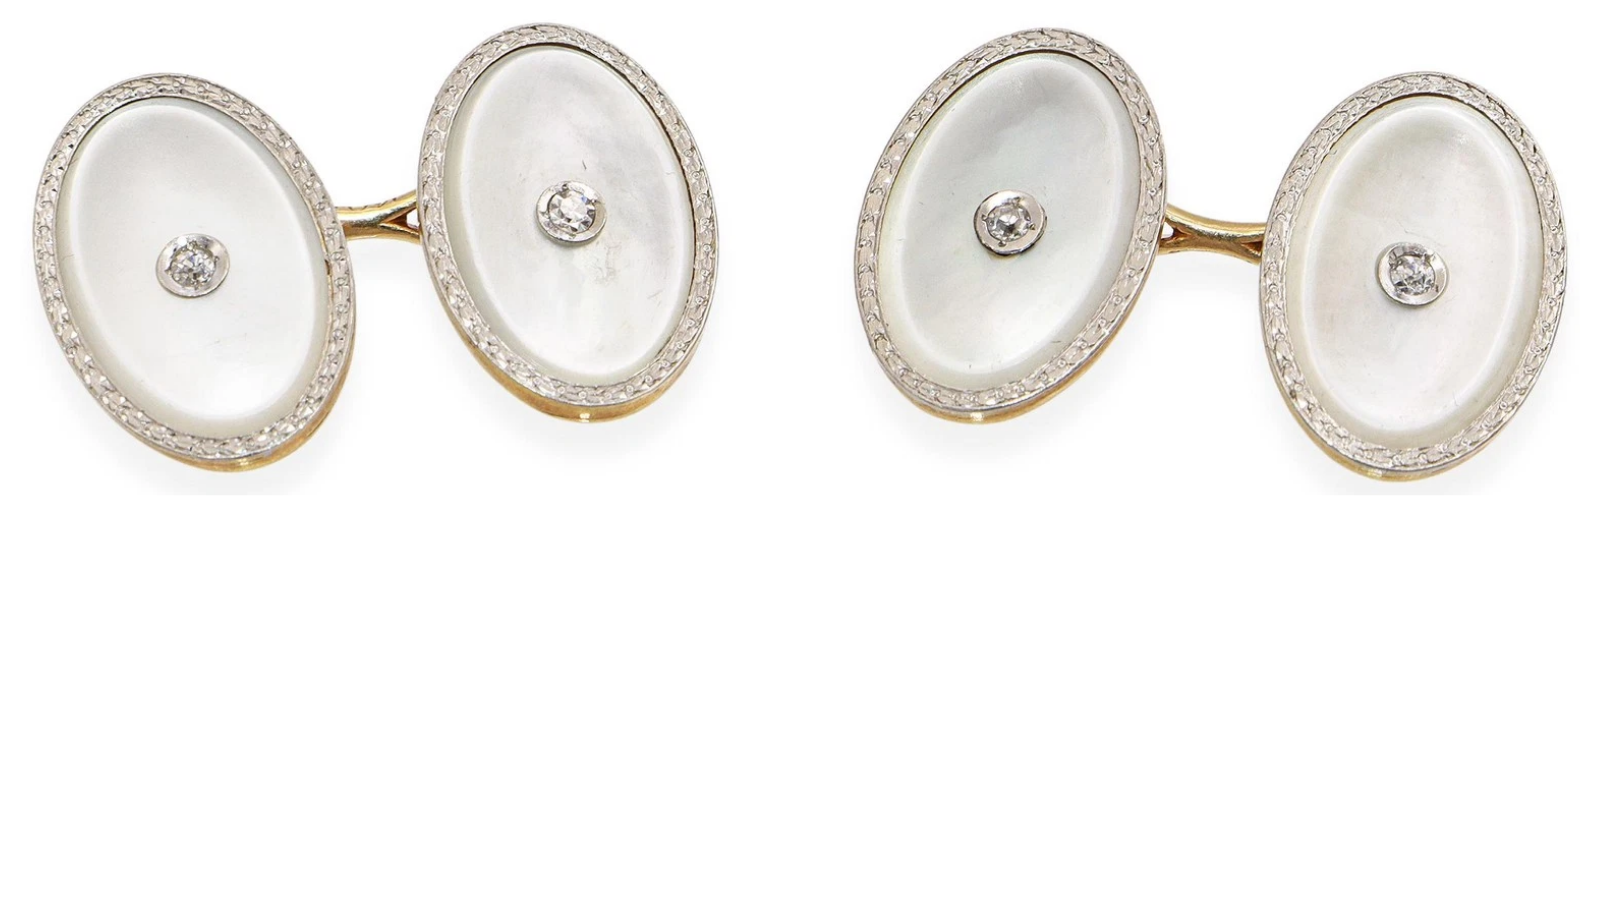
Mother-of-pearl and diamond cufflinks with gold links and oval faces
image credit: blueribbonnumismatics via eBay

Mother-of-pearl paired with gold and a small diamond accent was one of the signature combinations in 1920s and 1930s men’s jewelry, and complete pairs that survived the century in good condition are a genuine step above the plainer silver-mounted versions. A 14 karat gold pair with mother-of-pearl discs and a modest diamond center typically brings $300 to $600, while finer examples with a larger diamond set in a millegrain border bring considerably more, with standout pairs reaching toward $2,000.

Because the shell itself is fragile, condition inspection should start there: hairline cracks across a mother-of-pearl disc are common and reduce value more than most buyers expect, while small edge chips are more tolerable. The gold mounting should show a clear karat stamp, and any diamonds should be checked for looseness in their setting, since a century of wear can gradually open up prongs. A matched set that includes shirt studs alongside the cufflinks is worth noticeably more than the cufflinks on their own.

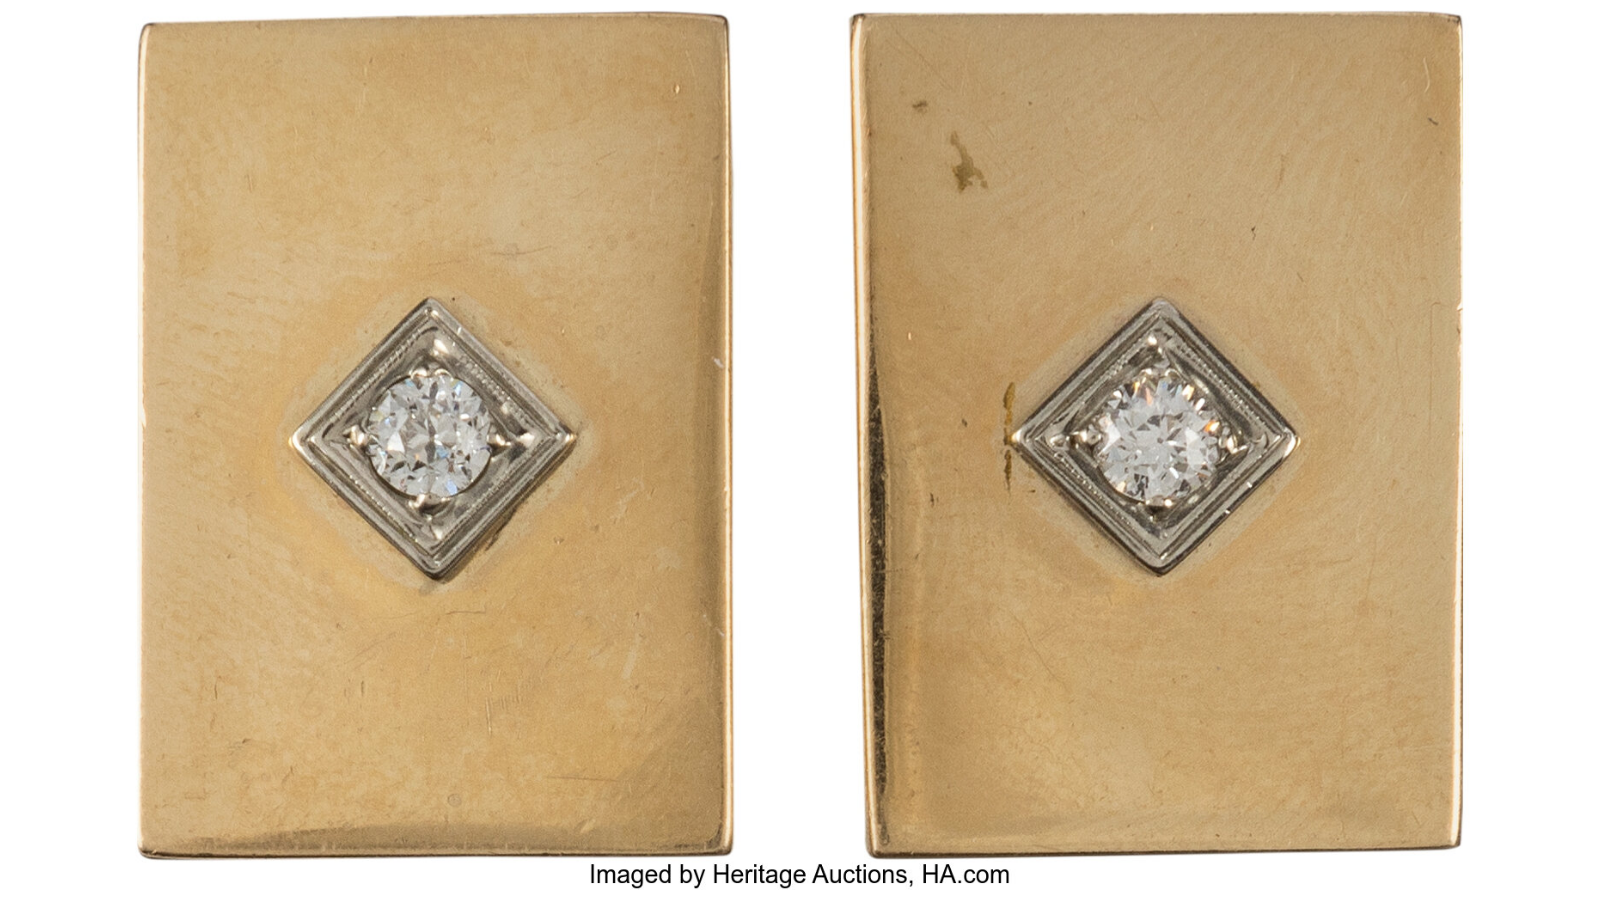
Sid Luckman’s gold cufflinks with square diamond settings
image credit: Heritage Auctions

Separate from ordinary promotional team cufflinks, pieces made for players, coaches, and front-office staff around a specific championship season were often struck in solid gold rather than gold-tone base metal, and they carry a different kind of value entirely. A documented pair with a confirmed tie to a specific championship season or a named player’s career typically brings $250 to $750, depending on the team, the year, and how well the history behind the piece can be confirmed.

These were never retail items, so provenance does almost all the work here: a name engraved inside, a presentation inscription, or a family history tying the piece to a specific player or staff member turns an otherwise unremarkable gold cufflink into something genuinely valuable. Without that kind of documentation, a plain gold football-shaped cufflink is worth closer to its gold weight than its sports history. A stamp reading “1/10 10KGF” or similar means gold-filled rather than solid gold, so check the stamp carefully before assuming a presentation-style piece carries the full premium.

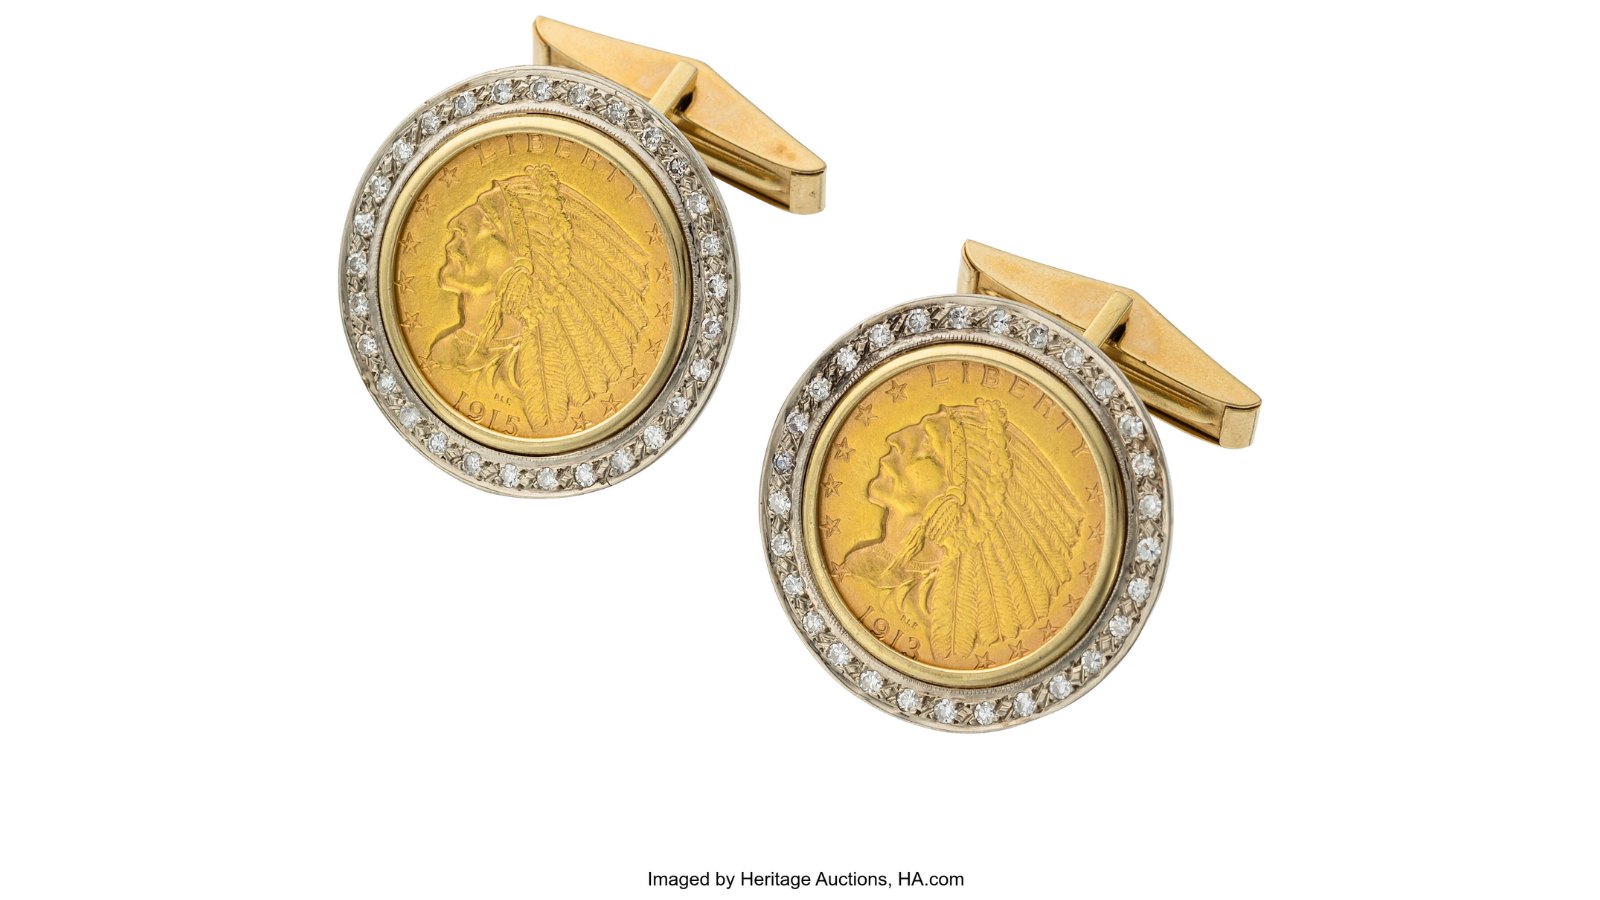
Indian Head quarter-eagle gold coin cufflinks with diamond surrounds
image credit: Heritage Auctions

Mounting an old gold coin in a simple frame and turning it into cufflinks was a popular way to wear family gold discreetly through much of the twentieth century, and $2.50 Indian Head or Liberty Head gold pieces, each worth roughly a quarter ounce of gold, were a favorite size for the format. A 14 karat gold-mounted pair set with two genuine $2.50 gold coins typically brings $600 to $1,200, reflecting demand from both coin collectors and jewelry buyers.

The coins themselves, not just the mounting, carry most of the value, so the date and condition of each coin matter as much as the gold frame around it. A coin soldered directly to the mount, rather than held in a prong or bezel setting that could be removed without damage, is less desirable to coin collectors even though the gold content is unaffected. Scratches and solder marks on a coin’s surface, common on pieces that were worn regularly, reduce numismatic value without touching melt value.

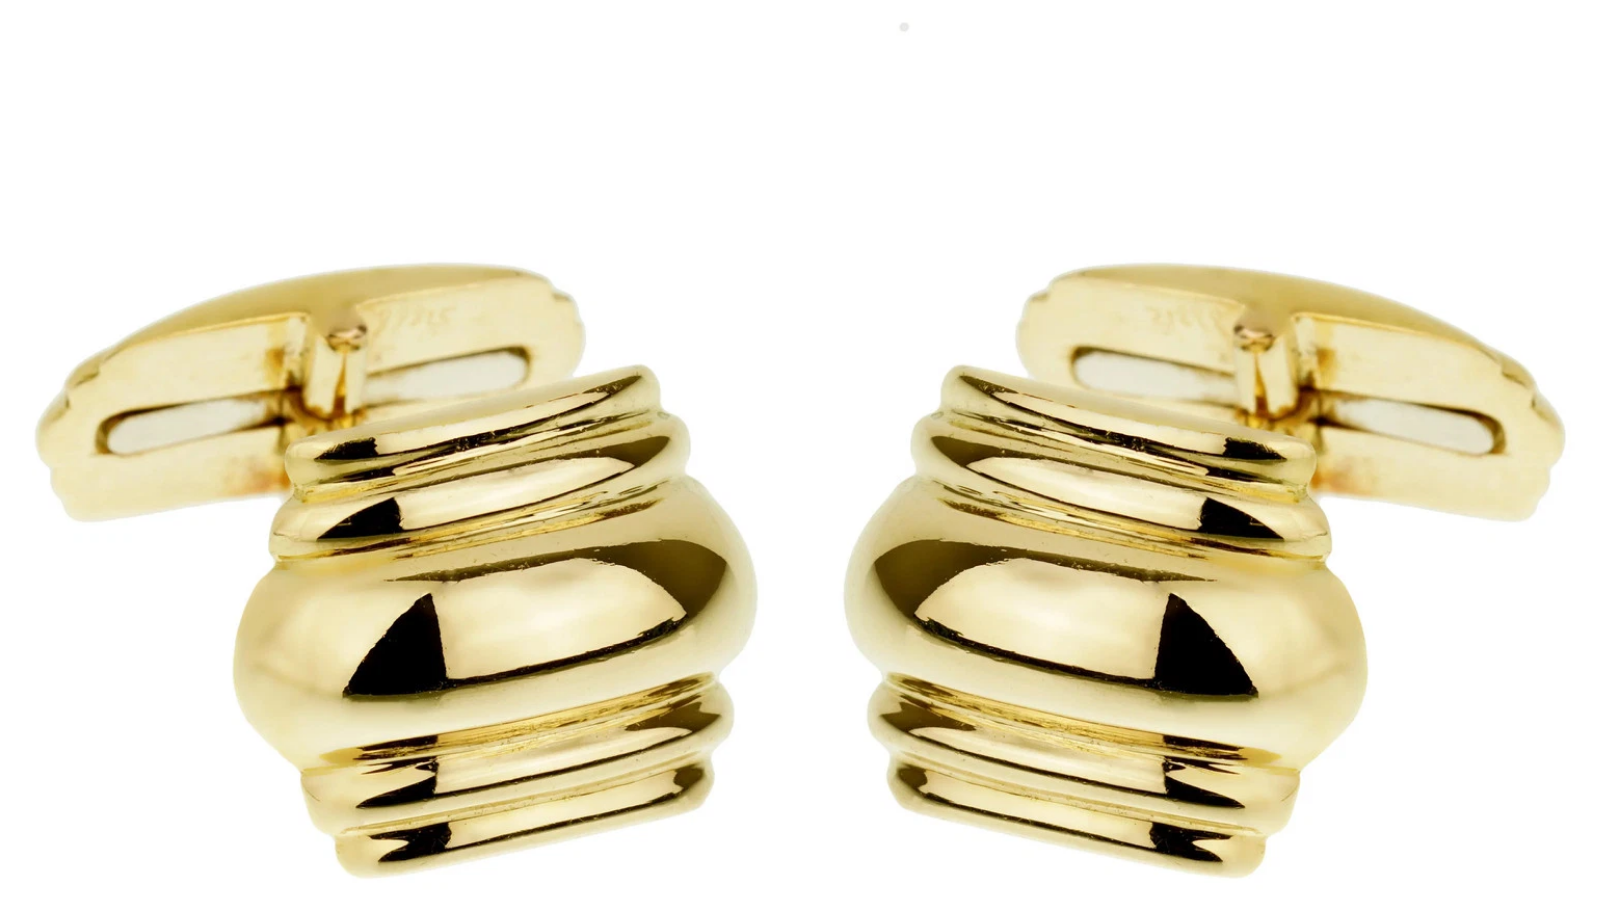
Sculptural ribbed gold Hermès cufflinks on a white background
image credit: opulentjewelers via eBay

Hermès has quietly produced fine jewelry alongside its leather goods and silk scarves for decades, and its vintage 18 karat gold cufflinks, many drawing on the house’s signature equestrian motifs like the Chaîne d’Ancre link or a saddle-stud design, trade at a real but genuinely more attainable level than equivalent pieces from Cartier or Van Cleef & Arpels. A solid gold pair in a recognizable Hermès motif typically brings $600 to $2,500, with larger, more sculptural designs toward the top of that range.

Genuine Hermès gold is solid rather than plated, so the weight should feel substantial for the size, and the piece should carry a clear “750” or “18K” stamp alongside the Hermès signature. Equestrian and nautical motifs, drawn from the house’s core design language, are the most consistently collectible; generic geometric designs without a recognizable house motif tend to sell for less. Sterling silver examples from the same house exist too and sell for considerably less than the solid gold versions, so material matters as much as the name on the back.

Gold Cartier barbell cufflinks in a red presentation box
image credit: tangibledealer via eBay

Cartier’s vintage cufflinks span everything from simple gold bar-bell designs to elaborate gem-set presentation pieces, and the gap between the two is enormous, which is exactly why a pair found in an inherited jewelry box is always worth a close look. A plain, signed 18 karat gold pair without stones typically brings $800 to $2,500, while examples set with rubies, sapphires, or diamonds bring several times that, with the finest gem-set pairs reaching well into five figures.

The Cartier signature, along with a serial number and French or American assay marks, should be clearly and evenly struck; weight is another good indicator, since Cartier’s gold cufflinks were never thin or hollow-feeling. Stirrup, barrel, and double-baton shapes from the 1950s through 1970s are among the most commonly found vintage designs. A piece that’s been resized, re-plated, or had a stone reset should be disclosed and priced accordingly, since any alteration affects both authenticity and value to serious buyers.

A loupe, a small scale, and a few minutes checking hallmarks against the backs of these eighteen designs is usually enough to tell a $20 pair from a $2,000 one.

Two renewal notices have probably turned up in your mailbox this month. One is from your Part D drug plan, spelling out what coverage will cost starting January 1. The other is from your Medigap insurer, and the number on it is rarely small this year.

Open enrollment started October 15 and runs through December 7, and this is the year both of those bills are moving at once. The base figure used to calculate standalone Part D premiums is rising 6 percent, to $41.33 a month, the fastest increase federal law allows through 2029. Medigap premiums, which nobody caps at all, are coming in higher still in plenty of states.

The Part D numbers are already locked in. The Medigap numbers depend on where you live and which company insures you, but the rate filings already sitting with state regulators show plenty of policyholders are looking at double-digit jumps, some well into the twenties.

The federal numbers behind your 2027 drug plan bill

Medicare Part D written on a notebook beside a stethoscope
Image Credit: Shutterstock

The national base beneficiary premium, the starting point used to calculate what standalone drug plans can charge, is rising from $38.99 to $41.33 a month for 2027, a 6 percent increase and the maximum allowed under the Inflation Reduction Act’s premium stabilization cap. That figure isn’t necessarily what you’ll pay, since actual premiums vary by plan, but it sets the floor insurers build from.

The averages insurers are actually filing look calmer on paper. The projected average premium for standalone Part D plans is rising by less than a dollar, from $35.09 to $36 a month, and for Medicare Advantage plans that bundle in drug coverage, the average premium is dropping 38 percent, from $11.32 to $7, once rebates are applied.

The part that stings shows up once you’re actually filling prescriptions. The standard deductible is jumping from $615 to $700, an $85 increase of nearly 14 percent, and your annual out-of-pocket cap for covered drugs is rising from $2,100 to $2,400. Both are the largest single-year increases since the standard Part D benefit was created in 2006.

Why the subsidy that was keeping premiums down just ended

Medicare premiums written on a chalkboard beside a prescription and stethoscope
Image Credit: Shutterstock

The reason Part D premiums are moving at all traces back to a program most people never heard of. Starting in 2025, a voluntary subsidy called the Part D Premium Stabilization Demonstration gave standalone drug plans extra money to keep their premiums from swinging wildly after the Inflation Reduction Act rewrote how the benefit works. It shaved real dollars off monthly premiums for two years running.

That program is ending a year earlier than planned, with insurers now considered to have enough experience pricing the redesigned benefit on their own starting January 1. What that does to any individual premium depends entirely on the plan and the state. The national averages are holding close to flat, but those averages blend plans getting cheaper with plans getting a lot more expensive, and the safety net is gone either way. There will be no standalone drug plans left with a zero-dollar premium for anyone who doesn’t qualify for Extra Help, after 28 percent of beneficiaries outside that program paid nothing at all in 2026. If your renewal notice shows an increase bigger than the averages above, that’s this subsidy disappearing from your specific plan rather than something the national number predicted.

Medigap premiums are climbing even harder this year

Woman reviewing paperwork with a calculator beside her laptop
Image Credit: Shutterstock

Nothing about Medigap pricing is federally set, which is exactly why it can move faster than Part D. Illinois broker John Jaggi had been selling Medicare insurance for 49 years when more than 80 of his clients on the same supplemental plan got hit with a 45 percent premium increase last August, applied immediately rather than waiting for each person’s renewal date.

That jump was unusual in size, but not in direction. Early 2026 rate filings from six of the largest insurers in the supplemental market show Plan G increases ranging from just over 12 percent to more than 26 percent in a single quarter. In Ohio, carriers that used to raise rates 3 to 5 percent a year are now filing for 10 to 15 percent. In Alaska, one insurer raised Plan G premiums close to 12 percent, pushing a 65-year-old woman’s monthly bill from $172 to $192.

More than 12 million people, about 43 percent of everyone on traditional Medicare, carry a Medigap policy specifically because it’s the only thing standing between them and unlimited out-of-pocket costs. For most of them, this is simply what keeping that protection now costs.

Why nothing is stopping the Medigap increases

Older couple looking at a laptop together on a sofa
Image Credit: Shutterstock

Five years ago, a Medigap rate increase above 10 percent was unusual enough to raise eyebrows. Now, it’s uncommon to see an increase below 10 percent, and increases over 20 percent aren’t rare either.

Several forces are pushing in the same direction at once. Beneficiaries are using more medical care than insurers priced for, the Medicare population keeps getting older and costing more to cover, and labor and medical costs across the health system keep climbing. On top of that, roughly 2.6 million people lost their Medicare Advantage plan this year when insurers pulled out of their markets, and a share of them moved into Medigap coverage without being medically underwritten, adding risk to a pool that carriers eventually price back in.

Traditional Medicare also still has no overall out-of-pocket cap, which is the entire reason Medigap exists and the reason insurers can keep raising prices on a product people feel they can’t drop. Lawmakers have floated adding one, but a change like that would add real cost to the federal budget and isn’t close to happening in the current legislative environment.

What actually helps before December 7

Person using a tablet beneath a Time to Renew message
Image Credit: Shutterstock

For Part D, open enrollment is your real leverage. Formularies and preferred pharmacies change every year, so the plan that was cheapest for your medications in 2026 isn’t guaranteed to be cheapest in 2027. Running your actual drug list through Medicare’s official plan comparison tool before you do anything else usually finds savings that dwarf the headline premium increase.

Medigap works differently, because you generally can’t switch to a cheaper plan without answering health questions once you’re past your original enrollment window. Some states require insurers to let you move to an equivalent plan with a different company around your birthday or policy anniversary without medical underwriting, so it’s worth asking an agent whether your state has that rule before assuming you’re stuck. A smaller number of people genuinely save by switching to a high-deductible Medigap plan, which carries a lower premium in exchange for covering less until you’ve spent close to $3,000 yourself, though that trade-off only makes sense if you can comfortably absorb that deductible in a bad year.

If your income is limited, it’s worth checking whether you qualify for Extra Help with Part D costs or a Medicare Savings Program that can cover premiums and cost-sharing outright. A free counselor through your state’s State Health Insurance Assistance Program can run the numbers with you at no cost before you commit to anything.

Neither letter in your mailbox is exaggerating. Both bills are going up this year, and the only real defense is comparing your actual options before December 7 instead of letting either renewal notice carry over automatically.

Discover smarter payment management tips for Australian mums running small businesses, from automating payments to reducing late invoices and admin work.
Image Credit:
Drazen Zigic via Magnific

Running a small business while raising children comes with its own set of challenges. Between managing clients, chasing invoices and keeping up with family responsibilities, financial administration can easily take up more time than expected. For Australian mums working as freelancers, tutors, consultants or service providers, late payments can also make household budgeting more difficult. One way to ease the workload is by setting up direct debit for customers through a provider such as Pinch Payments, allowing authorised payments to be collected automatically.

A successful small business needs more than a steady stream of customers. Having reliable payment processes, keeping finances organised and finding ways to reduce repetitive work can make a real difference, particularly when business hours need to fit around school runs and family commitments.

Managing the financial challenges of self-employment

Running your own business can offer valuable flexibility, but it also means taking responsibility for irregular income, operating expenses and unpaid invoices. Unlike salaried employment, earnings may fluctuate from month to month, making it harder to plan for both business costs and household expenses.

For mums balancing business ownership with family life, separating personal and business finances is a useful starting point. A dedicated business bank account can make it easier to track transactions, while regularly reviewing income and expenses helps identify how much money is available after business costs.

Setting aside funds for tax obligations and unexpected expenses is equally important. Even a modest financial buffer can help cover quieter periods without placing additional pressure on household finances.

Taking the stress out of payment collection

Following up on overdue invoices is rarely how business owners want to spend their time. Yet for those providing regular services, payment reminders and manual bank transfers can become an ongoing administrative task.

Direct debit offers an alternative by allowing businesses to collect payments from customers’ nominated bank accounts once the appropriate authorisation has been provided. It can be particularly useful for services with predictable billing schedules, such as tutoring, fitness coaching, cleaning or ongoing consulting arrangements.

Automated collection can reduce the need for repeated reminders, although payments can still fail because of insufficient funds or other banking issues. Businesses should also establish clear policies for cancellations, refunds and changes to payment arrangements.

The Australian Government’s guidance on choosing business payment methods outlines the importance of selecting suitable payment options and obtaining customer authorisation for direct debit arrangements.

Finding a work routine that fits family life

One of the biggest attractions of self-employment is the freedom to choose when and where to work. In practice, that flexibility can disappear when client requests, emails and administrative tasks spill into family time.

Creating a realistic weekly routine can help. A mum running a home-based consultancy, for example, might schedule client meetings during school hours, reserve one afternoon for invoicing and use automated appointment reminders to reduce last-minute scheduling issues.

The goal isn’t to fill every available hour with work. It’s to make the time spent working more productive.

For single mothers in particular, building a business around existing responsibilities may require a different approach to traditional entrepreneurship. Practical business advice for single mothers can offer useful perspectives on managing workloads, financial decisions and the demands of self-employment.

Small changes, such as using shared calendars, setting communication boundaries and automating routine customer messages, can free up time without requiring significant investment.

Building more predictable cash flow

Consistent cash flow makes it easier to pay suppliers, cover operating expenses and plan household spending. Even profitable businesses can experience financial pressure when customers take longer than expected to pay.

Clear payment terms are essential. Customers should know when invoices are due, which payment methods are available and what happens if a payment is unsuccessful.

For businesses with regular clients, scheduled payment arrangements can make incoming payments more predictable. Owners should still review outstanding invoices and upcoming expenses rather than assuming automated systems will manage every situation.

A simple monthly cash flow forecast can also be valuable. Estimating expected income alongside fixed costs, seasonal expenses and tax commitments provides a clearer picture of the business’s financial position.

Choosing business tools that actually save time

Small businesses don’t necessarily need expensive or complicated software. The best tools are those that solve recurring problems and fit comfortably into existing workflows.

An accounting platform can simplify expense tracking and invoicing, while scheduling software may reduce appointment clashes. Payment automation is worth considering for businesses that regularly invoice the same customers.

Before adopting any new system, compare transaction fees, settlement times, ease of use and compatibility with existing software. A tool that saves a few minutes but introduces additional costs or administrative steps may not be worthwhile.

It’s also sensible to review business systems as circumstances change. What works for a freelancer with five clients may not be suitable for a growing business managing dozens of recurring payments each month.

Making small business ownership more manageable

Balancing business ownership and family responsibilities isn’t always straightforward, particularly when income depends on maintaining a steady flow of clients and payments.

Organised financial records, clear customer payment arrangements and practical automation can help reduce unnecessary administration. Combined with realistic working hours and thoughtful budgeting, these habits make it easier to manage a business without allowing work to take over family life.

For Australian mums building their own businesses, the aim is not simply to work harder, but to establish reliable processes that support financial stability, flexibility and sustainable growth.

You log into your My Social Security account, click into your estimated benefit, and there it is: a bold dollar figure sitting next to your full retirement age, looking like a promise. Maybe it reads $2,400. Maybe it’s $3,100. Either way, it’s tempting to treat that number as the deal, the exact amount that will land in your account every month once you file.

It isn’t a deal. That figure is built on one thing the Social Security Administration doesn’t actually know: what you’re going to earn between now and the day you stop working. To fill that gap, the agency assumes you’ll keep earning exactly what you earned last year, every year, until you file.

That assumption works out fine if retirement is a year or two away and your paycheck is steady. It works out a lot less fine for people whose income rises, drops, or stops altogether before then. In the agency’s own research, about one in five workers under 45 ended up with a statement that overshot their real benefit, not because Social Security got the math wrong, but because life didn’t follow the script the estimate assumed.

The earnings assumption is the biggest reason your number can drift from what you actually collect, but it’s not the only one. Medicare, taxes, and the age you actually file all take a bite the headline figure doesn’t show.

Your statement assumes your paycheck never changes

Older couple looking at a laptop together on a sofa
Image Credit: Shutterstock

Here’s the mechanic behind it. Social Security’s benefit formula runs on your highest 35 years of wage-indexed earnings, but while you’re still working, the agency doesn’t have 35 years of certainty to work with. So it borrows your most recent year on record and projects it forward, unchanged, for every year left until you retire. If you earned $65,000 last year, the statement assumes you’ll earn $65,000 this year, next year, and the year after that, all the way to your filing date.

For plenty of people, that’s a reasonable stand-in. For a lot of others, it isn’t. A layoff, a shift to part-time work, a career change into something that pays less, a few years out of the workforce to care for a parent or a child: any of these quietly pulls your actual 35-year average below what the statement assumed, and the benefit formula follows your real earnings, not your projected ones. The difference tends to shrink as you get closer to retirement, since there’s less time left for your income to diverge from the number already on file. It’s widest for people still decades out, which is exactly when the figure feels the most concrete.

Medicare takes its premium before you ever see the deposit

Medicare premiums written on a chalkboard beside a prescription and stethoscope
Image Credit: Shutterstock

The figure on your statement is your gross benefit, the amount Social Security calculates before anything comes out of it. For most retirees, something does come out of it. Once you’re enrolled in Medicare, your Part B premium is deducted automatically from your Social Security check rather than billed separately, and for 2026 that standard premium is $202.90 a month, more if your income is high enough to trigger a surcharge.

Set that against the 3.6% cost-of-living raise pushing the average retired worker’s check from $2,095 to $2,170 in January, and what’s actually left after Medicare looks tighter than the headline suggests. The 2026 Part B premium alone rose 9.7%, more than three times the 2.8% cost-of-living raise that took effect the same January. The 2027 Part B premium hasn’t been announced yet, that usually happens in mid-November, but nothing about the last few years suggests Medicare is about to slow down.

Filing before full retirement age locks in a smaller check for life

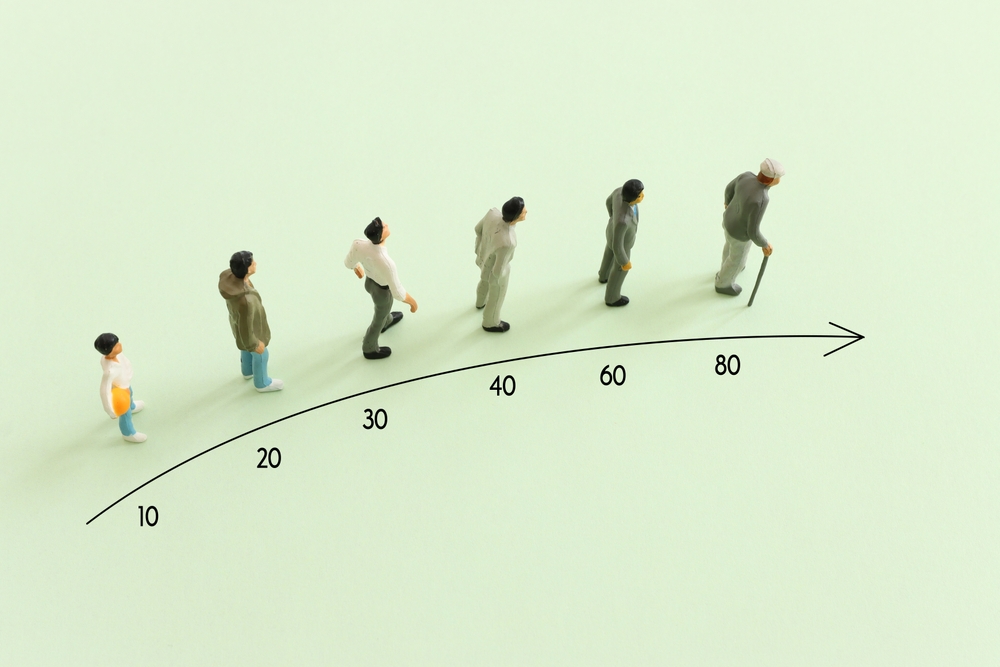
Miniature figures showing stages of life along an age scale
Image Credit: Shutterstock

Your statement usually shows benefit estimates at more than one age: as early as 62, at your full retirement age, and at 70. The full retirement age figure is often the one people remember, in part because it’s usually presented as the main estimate. For anyone born in 1960 or later, that age is 67.

File at 62 instead, and the benefit drops to about 70% of the full retirement age amount, permanently. There’s no making it up later by working extra years or catching up on savings. The reduction is built into the calculation the day you file, and it stays with every payment for the rest of your life, including any cost-of-living raises layered on top of it.

People file early for real reasons: a layoff at 63 with no comparable job in sight, a health problem, a spouse who needs care. None of that is a mistake. But if the only number anyone ever looked at was the full retirement age estimate from a few years back, the difference between that figure and the smaller check that actually shows up can come as a genuine shock, on top of whatever pushed the decision to file early in the first place.

The IRS can tax a slice of what’s left

Wooden blocks spelling IRS surrounded by rolled banknotes
Image Credit: Shutterstock

The number on your statement is also pre-tax. Depending on your other income in retirement, a portion of your Social Security benefit can be subject to federal income tax, and the thresholds that trigger it are lower than most people expect. File as an individual and your combined income tops $25,000, or $32,000 filing jointly, and up to 85% of your benefit can be taxable, where combined income means adjusted gross income plus nontaxable interest plus half of your Social Security benefit.

Those thresholds were set decades ago and have never been adjusted for inflation, so a retiree with a modest pension or a part-time job on top of Social Security can cross them without earning anywhere near what most people would call a high income. None of this shows up on the statement itself. The dollar figure you see is the full benefit before any tax is withheld, which means the amount that actually clears after a tax return is filed can be meaningfully smaller than the one you planned around.

Working while you collect early can shrink the check further

Social Security cards beside US dollar bills
Image Credit: Shutterstock

Filing for Social Security doesn’t require leaving work behind, but doing both before full retirement age comes with a catch called the retirement earnings test. For anyone under full retirement age all year, Social Security withholds $1 in benefits for every $2 you earn above $25,560 in 2027, up from $24,480 in 2026. A higher limit applies in the year you actually reach full retirement age, and the test disappears completely once you get there.

For someone who files at 62 while still working part-time or picking up freelance income, that withholding can take a real bite out of the check the statement promised, sometimes reducing it to nothing for several months if earnings run high enough. The money isn’t gone forever: Social Security recalculates the benefit at full retirement age to credit back the months that were withheld. But that credit arrives years later, and in the meantime, the deposit hitting the account is smaller than the figure that made filing early look appealing.

None of this means the figure on your statement is wrong. It means it’s a starting point, not a guarantee, and the difference between the two is worth planning for before you file, not after.