scroll top

The typical American family headed by someone between 65 and 74 has a net worth of $431,300. The average is $1,897,600, more than four times higher, which says a great deal about how unevenly wealth is spread.

Net worth is everything you own minus everything you owe. The national survey behind these numbers counts families rather than individuals and groups them by the age of the person in charge, so 65 to 74 is the closest bracket to age 65. All of the figures below are from the 2025 survey, in 2025 dollars.

Those totals can mislead in one important way. Most of that wealth is usually a house and retirement accounts, not cash, and the median family in this age group has an income of $69,400 a year to live on.

What the typical family around 65 is worth
Older couple smiling while reading paperwork together
Image Credit: Shutterstock

The most recent survey puts the median net worth of families headed by someone 65 to 74 at $431,300. Half of families in that bracket have more than that and half have less. It is down from $448,600 in 2022 after adjusting for inflation, so the typical family in this age group has not gained ground in three years.

Net worth here means total assets minus total debts. Assets include your home, retirement accounts, bank and investment accounts, vehicles, and other property. Debts include mortgages, credit cards, car loans, student loans, and anything else you owe. Couples who share finances count as one family, so a single 65-year-old and a married couple are measured against the same number even though the couple is usually pooling two incomes and two sets of savings.

If you are exactly 65 and still working, your own situation may look closer to the $411,900 median for ages 55 to 64. If you have already retired, the 65 to 74 figure is the fairer comparison.

Why the average is so far above the median
US fifty-dollar bills spread across a surface
Image Credit: Shutterstock

A small number of very wealthy families pull the average far above where most families sit. For ages 65 to 74, the average of $1,897,600 is about 4.4 times the median. Across all ages, the average of $1,241,500 is more than five times the median of $215,900.

The same pattern shows up in income. Families headed by someone 65 to 74 have a median income of $69,400 and an average of $138,400, which is double. Most families fall below the average, so being under it does not mean you are behind. The median is the number to compare yourself against, because half of all families sit on each side of it.

Headlines that quote an average of nearly $1.9 million for this age group describe a very different set of families from the ones most people know. A family with the median net worth would need to more than quadruple its wealth to match that average.

How net worth shifts from your late 50s to your 70s

Two women reviewing a tablet with an adviser at a table
Image Credit: Shutterstock

The median net worth is $411,900 for families headed by someone 55 to 64, $431,300 for ages 65 to 74, and $504,900 for ages 75 and older. The jump from the late 50s and early 60s to the late 60s and early 70s is only about 5%. Growth tends to slow once people stop adding to savings and start living off them.

Since 2022, the median rose 3% for ages 55 to 64, fell 4% for ages 65 to 74, and climbed 37% for ages 75 and older. The report says families that are nearly or recently retired saw some declines and ties the rise at 75 and older to higher retirement account values. Each bracket holds different families, so these numbers do not follow one family over time. Income looks similar across the two older brackets, at a median of $69,400 for ages 65 to 74 and $66,800 for ages 75 and older, so a larger net worth at 75 does not mean a larger paycheck.

Home equity, usually the largest asset
Woman using a calculator beside paperwork, a model house and a laptop
Image Credit: Shutterstock

A house is typically the biggest single item on a family’s balance sheet. Across all ages, 65.6% of families own a primary residence, and among those owners the median value is $375,000. Subtract the debt secured by the home and the median net housing value for owners is $230,000. Home equity is the part of the value you actually own. The median value among owners has climbed from $353,700 in 2022 to that 2025 figure.

Homeownership is higher among older Americans. In the third quarter of 2026, 79.1% of householders 65 and older owned their home, which leaves roughly one in five without this asset. About 42.0% of all families still carry debt secured by their primary residence, and the median amount among those families is $183,600. For a family heading into retirement with a mortgage balance like that, the house adds to net worth on paper while adding to monthly costs in practice.

Retirement accounts, savings and investments

Pink piggy bank and rolled dollar bills beside a Retirement Fund sign
Image Credit: Shutterstock

Only 54.9% of all families have a retirement account, such as a 401(k) or IRA, and the median balance among those that do is $106,000. The average among account holders is $451,100, which again shows how far a few large balances pull the average up. Counting pensions as well, about 65% of families take part in some kind of retirement plan. The median balance has grown from $95,200 in 2022, which is progress, but it is still a modest sum to fund a retirement that can last decades.

Nearly everyone has some financial asset, whether bank accounts, stocks, bonds, or retirement money, with 98.9% of families holding at least one. The median total among those families is only $44,200, and the average is $637,600. For families aged 55 to 64, average retirement balances reached $670,200. The report does not break these figures out for ages 65 to 74, so the all-family numbers show the general shape rather than your exact peer group.

Vehicles and everything else you own
Older man placing a backpack in the cargo area of an SUV
Image Credit: Shutterstock

Most families own a vehicle, with 84.2% holding at least one, down from 86.6% in 2022. The median value is $26,000, compared with $30,300 in 2022, a drop of about 14% in three years. Vehicles count toward net worth, but nobody can spend a car they need to drive to appointments, and its value falls a little every year, so a reliable older car is worth more to your daily life than its resale price suggests.

The survey groups cars together with homes, land, and businesses as nonfinancial assets. Overall, 90.8% of families hold some kind of nonfinancial asset, with a median value of $326,800, up from $308,100 in 2022. Because the home is usually the largest item in that total, a family with no house has far less in this category. When you add up your own net worth, the same rule applies: count what you could realistically sell and leave out what only has sentimental value.

What families owe
Credit cards resting on US dollar banknotes
Image Credit: Shutterstock

Debt is common. Across all families, 77.0% have some kind of debt, and the median amount among those with debt is $88,100. The smaller debts reach many households, and the amounts below show how different they are in size. Among families with home-secured debt, the average is $239,700, well above the median of that group.

44.7% of families carry a credit card balance, with a median of $3,100 and an average of $8,000. About 32.1% owe on a vehicle loan, with a median of $17,000, and 20.0% have student loans, with a median of $25,600. These are all-age figures, but they show what typically comes off the top when net worth is calculated. The report does not publish debt by age group. Averages run well above the medians, with the average among families that have any debt at $179,100, about double the median, which means a minority of families carry very large balances.

Wealth in a house versus money you can spend
Person reviewing paperwork beside a model house and calculator
Image Credit: Shutterstock

Two families can have the same net worth and very different lives. A family worth $430,000 on paper whose home equity is the typical $230,000 has only about $200,000 left in accounts, investments, and vehicles, and part of that sits in retirement accounts where withdrawals are taxed. The house is real wealth, but it only turns into spending money if you sell it, borrow against it, or take out a reverse mortgage.

Monthly cash flow is what pays the bills. The average retired worker received $2,088.79 a month in Social Security in September 2026, which comes to about $25,000 a year. The median income of $69,400 for ages 65 to 74 includes retirement income, so it is all sources combined. Net worth does not count that income, and it does not count what you will need to spend either. A family with a large net worth and a small monthly income can still feel tight, and a family with a modest net worth and a pension can be comfortable.

Spending down savings after 70
Older couple reading a letter beside an open laptop
Image Credit: Shutterstock

By the mid 70s, many families are living on withdrawals. The median net worth for ages 75 and older is $504,900, and the report credits higher retirement account values for the increase. Whatever the monthly Social Security check does not cover has to come out of savings, so the pace of withdrawals matters more than the size of the balance. Tracking your yearly withdrawals as a percentage of the balance each January shows whether you are drawing down faster than you planned.

Withdrawals also become mandatory. Required minimum withdrawals from most traditional retirement accounts start in your 70s, and missing one can mean a 25% tax on the amount you should have taken, reduced to 10% if you correct it within two years. Those withdrawals count as taxable income whether or not you need the money that year, so they can push you into a higher tax bracket and raise the share of Social Security that is taxed.

Keeping, selling or downsizing the house
Older woman and younger woman reviewing a framed photo among moving boxes
Image Credit: Shutterstock

A paid-off house still costs money. Property taxes, insurance, repairs, and utilities continue after the mortgage ends, and the bills tend to rise while income stays fixed. Staying put can be the right call for a family that wants to age in a familiar place, but it ties up a large share of net worth in something that earns no income.

Selling is often easier on the tax side than people expect. Homeowners can exclude up to $250,000 of gain on the sale of a main home, or $500,000 on a joint return, if they owned and lived in it for at least two of the last five years. That exclusion can cover most or all of the gain for owners who bought decades ago. Downsizing does not automatically free up cash, though, because moving costs, closing costs, and the price of the next home all come out of the proceeds.

Carrying debt into your 70s

Gray-haired woman looking concerned while using a laptop
Image Credit: Shutterstock

Debt gets harder to carry once income stops growing. The share of families with debt payments above 40% of income rose from 6.5% to 8.6% between 2022 and 2025, a level not seen since 2013. That figure covers all ages, but the pressure is sharper for people living on a fixed monthly check.

A mortgage, a car loan, or a credit card balance can be manageable on a paycheck and heavy on a pension plus Social Security. The size of the payment matters more than the total owed, because the payment is what leaves the bank account every month. A family with a net worth near the median and a large monthly debt payment has less breathing room than a family with the same net worth and no debt at all. Of the debts listed earlier, a credit card balance is usually the one worth clearing first, because card interest is typically much higher than the interest on a mortgage or car loan.

A simple way to calculate your own net worth
Woman writing in a budget notebook beside bills, a calculator and coffee
Image Credit: Shutterstock

Start with two lists. On the first, write down everything you own with a current value: your home at a realistic sale price, the balance of every retirement account, bank accounts, investments, vehicles at resale value, and anything else you could sell. On the second, write down everything you owe: the mortgage or home equity loan, credit cards, car loans, student loans, and any other balances. Subtract the second total from the first, and compare the result with the median of $431,300 for ages 65 to 74, not the average.

The number has real limits. It treats a dollar in your home the same as a dollar in your checking account, so it says nothing about how much you can spend. Retirement balances are counted before the tax you will owe on withdrawals, and a home value is an estimate until you sell. It also leaves out Social Security, pensions, and your monthly expenses, which matter more to day-to-day security than the total does. For a more useful read, subtract your home equity and vehicles from your net worth and look at what is left.
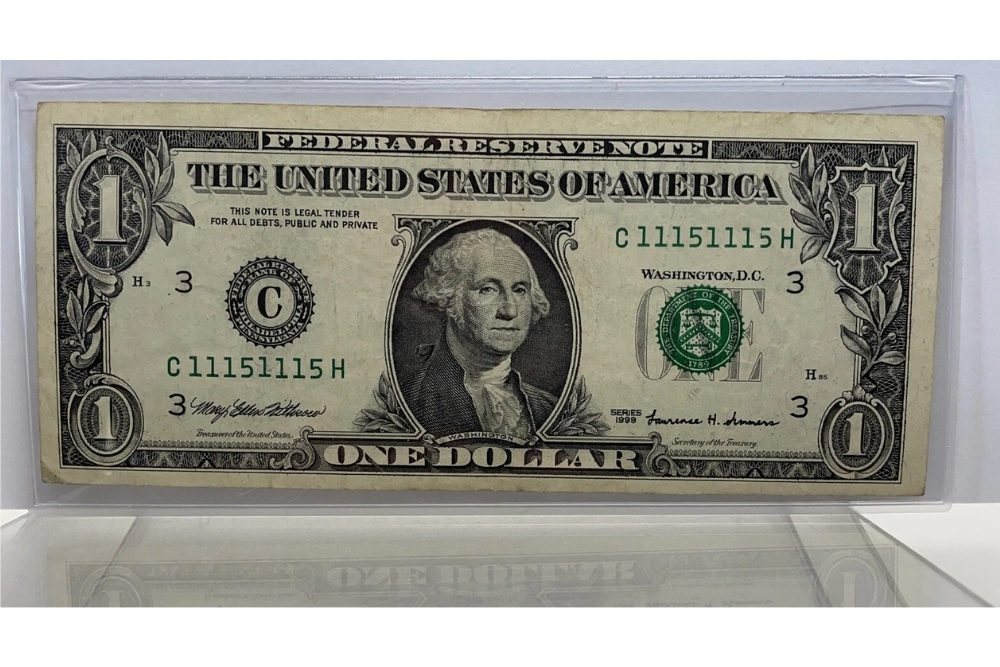
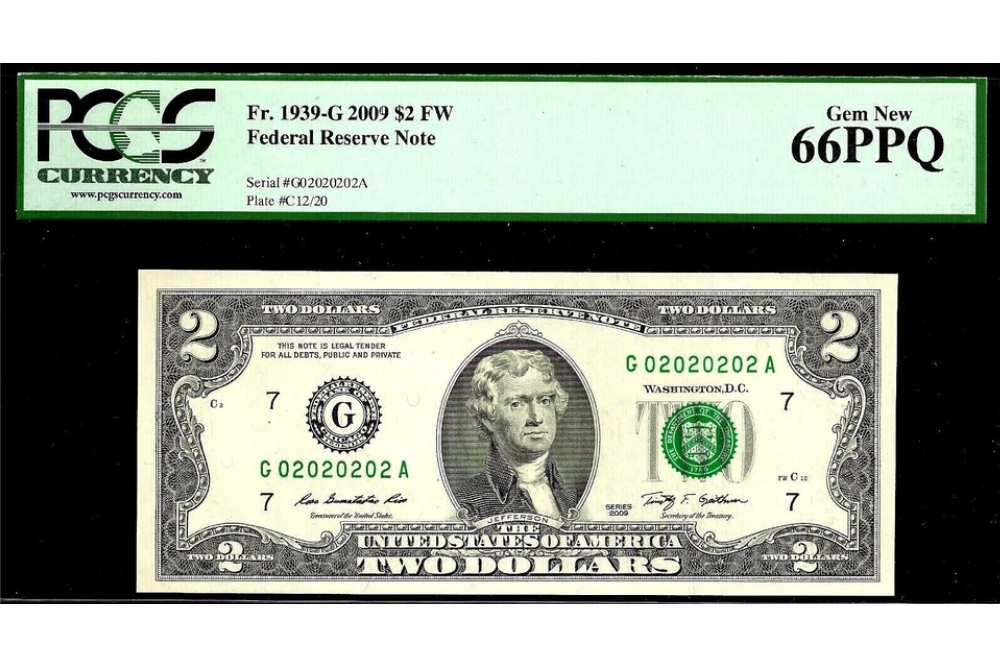
You’re counting out change at a yard sale, or digging through a junk drawer for exact bus fare, and a ten slides past with a run of identical digits staring back at you. Most people fold it into their wallet without a second look. A small, serious niche of currency collectors would tell you to check first.

Every US bill carries an eight-digit serial number, and the patterns those digits form are their own collecting category, separate from rare dates or printing errors. A string of matching numbers, a sequence that climbs in perfect order, a number that reads the same forward and backward: collectors call these fancy serial numbers, and they pay real money for the right ones, sometimes for a bill as ordinary as a one straight from an ATM.
Condition still matters, and so does the exact pattern you’re holding. A worn repeater and a crisp one in gem condition aren’t close to the same bill. Here are 18 specific patterns worth checking your cash for.

1. $1 bill with a repeater serial number

1999 one-dollar note with repeater serial number C11151115H
Image Credit: tennesseecoin via eBay

A repeater is the easiest fancy pattern to spot once you know what you’re looking for. The last four digits of the serial number are an exact copy of the first four, like 53825382 or 61946194. Pull any bill from your wallet and check the eight digits printed twice on the front. If the second half matches the first, you’ve got one.

Repeaters are the most common type of fancy serial number, which keeps the price modest but still real. Clean examples typically bring $20 to $100 depending on how crisp the note is and which digits repeat. A circulated bill with folds and handling marks sits at the bottom of that range or below it, while an uncirculated repeater can push past $100 if the pattern is visually striking, like 90919091, versus something duller like 10021002.

Because repeaters turn up far more often than most other fancy serial number patterns, this is the one worth checking for as a habit rather than hoping for once. It costs nothing but a glance.

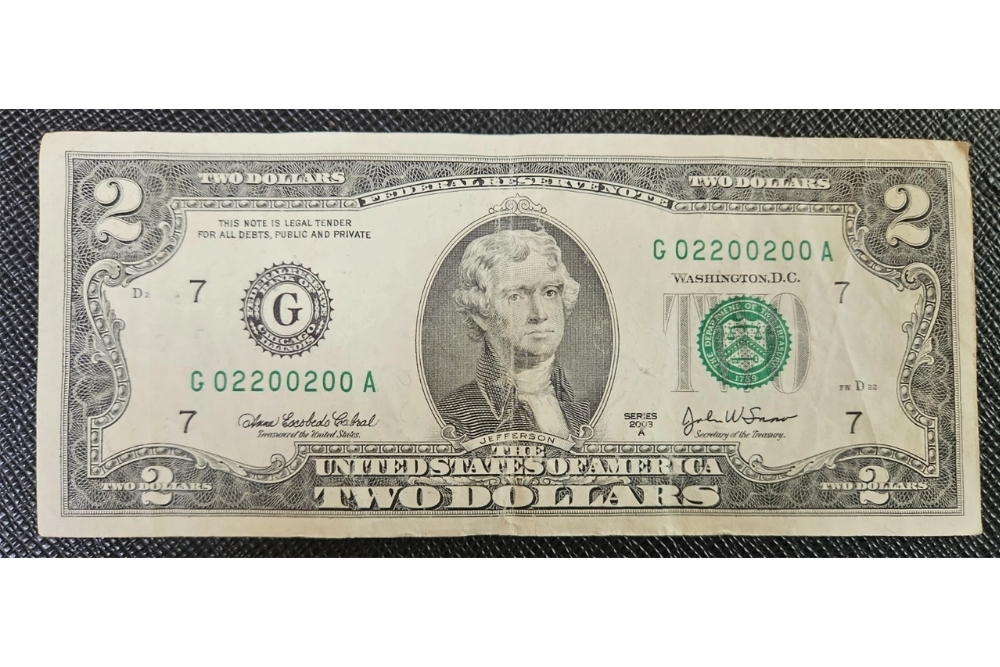
2. $2 bill with a super repeater serial number

Graded two-dollar note with super-repeater serial number G02020202A
Image Credit: mxc1971 via eBay

A super repeater takes the repeater idea one step further. Instead of a four-digit block repeating once, a two-digit block repeats four times straight through the serial number, like 81818181 or 32323232. It reads almost like a heartbeat monitor once you notice it, which is part of why collectors rank it above a standard repeater.

Clean $2 bills with a super repeater typically bring $100 to $400, with the higher end reserved for genuinely crisp notes and patterns built from bolder digits like 90909090 rather than something like 01010101. Because $2 bills already get pulled out of circulation and tucked into drawers more than other denominations, a surprising number of them never get examined for their serial number at all before someone sets them aside.

That’s good news if you’re the one doing the checking. A stack of $2 bills from a relative’s collection is worth running through for super repeaters before anything else, since the pattern is easy to miss on a quick flip-through and genuinely pays off when you catch it.

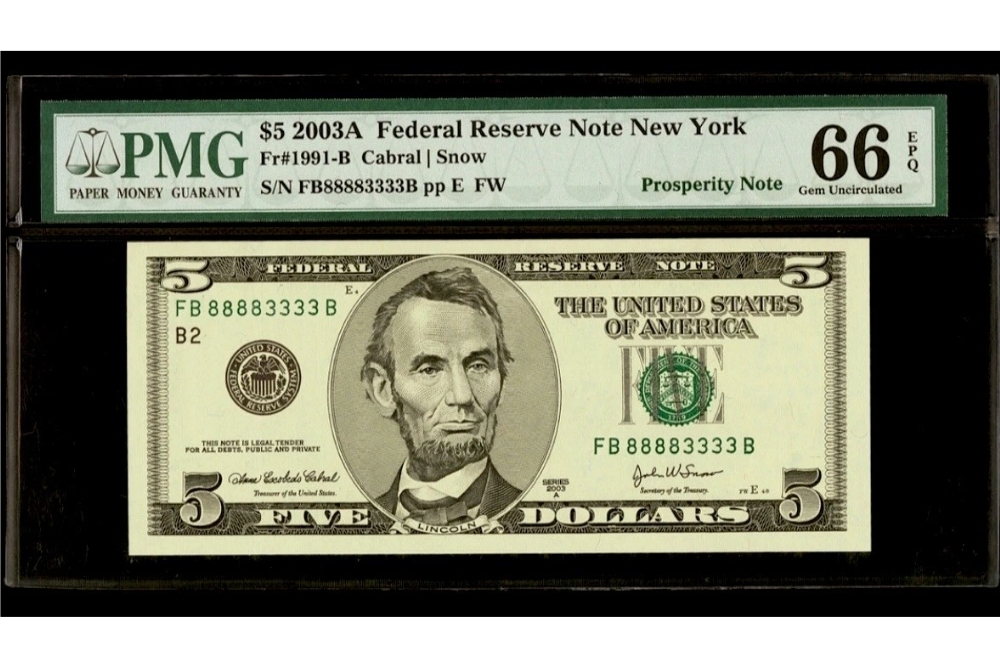
3. $5 bill with a double quad serial number

Five-dollar note with double-quad serial number FB88883333B in a grading holder
Image Credit: sld_collection via eBay

A double quad splits the serial number cleanly in half by digit rather than by sequence. The first four digits are all one number, and the last four are all another, like 77776666 or 22229999. It’s a different animal from a repeater, where the two halves are identical rather than two separate blocks of matching digits.

The pattern is distinctive enough that collectors actively look for it, and clean $5 notes with a true double quad typically add $80 to $180 on top of face value. On a $5 bill that puts a realistic total somewhere around $85 to $185 for a crisp, well-centered example. Worn or heavily creased notes drop toward the bottom of that premium or lose it almost entirely, since a double quad is a visual pattern first, and a worn note makes it harder to appreciate at a glance.

Double quads get confused constantly, even by sellers, with a related but different pattern called a quad double, where the serial number instead contains four separate pairs of matching digits. Read the actual eight digits carefully before assuming you know which one you have.

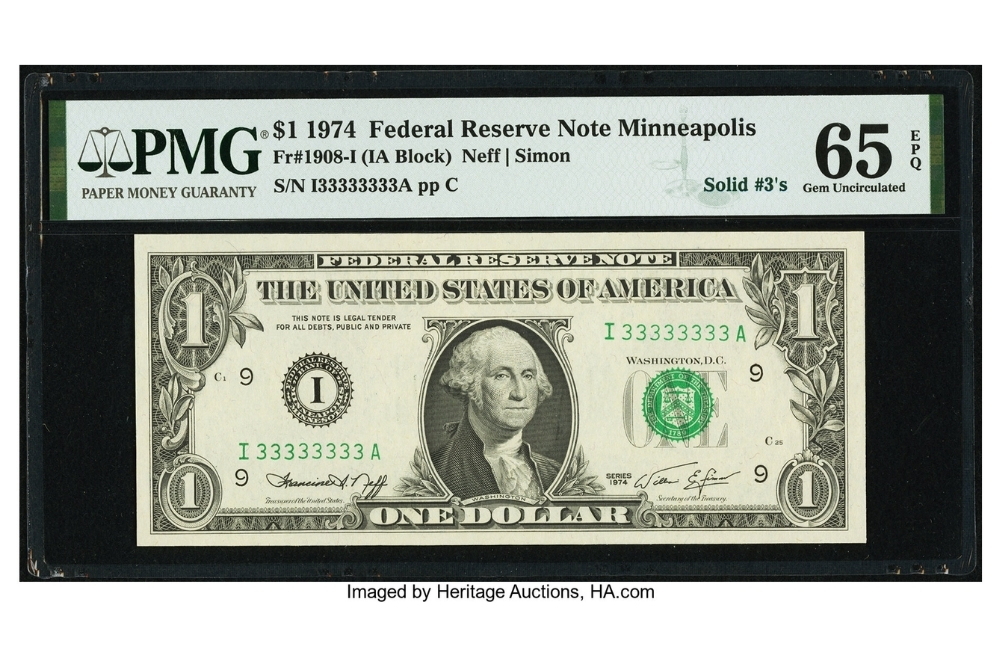
4. $1 bill with a solid serial number

Graded 1974 one-dollar note with solid serial number I33333333A
Image Credit: Heritage Auctions

A solid is exactly what it sounds like. All eight digits are the same number, like 33333333 or 88888888. There are only nine possible solid combinations in any print run, which makes this one of the rarest patterns a casual bill-checker is ever going to find.

Clean solid serial numbers typically bring $1,000 to $4,000, and solids built from a 7, 8, or 9 tend to sell for more than lower digits, since those numbers are considered luckier in some cultures and get chased harder by a wider pool of buyers. Even without professional grading, a solid 3 in ordinary circulated condition is the kind of note that can still bring around $1,600, which shows grading isn’t a prerequisite for finding a buyer at this level.

Condition still moves the number considerably from there. A solid serial on a bill with folds, stains, or tears sells for a fraction of what the same digits would bring crisp and flat, so resist the urge to smooth out a found solid yourself. Let a buyer or a grading service assess it as it is.

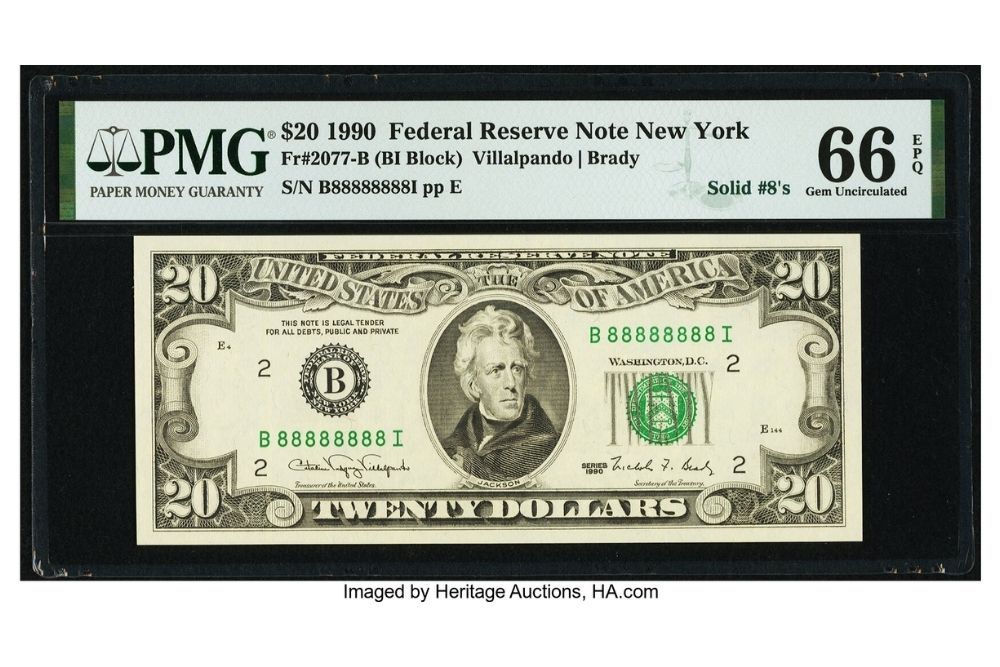
5. $20 bill with a solid serial number

Graded 1990 twenty-dollar note with solid serial number B88888888I
Image Credit: Heritage Auctions

The math behind a solid serial number doesn’t change with denomination, but the odds of actually finding one get longer as the bill gets bigger. Twenties circulate heavily and get folded, stuffed into wallets, and run through ATMs far more than they get examined closely, so a solid twenty that survives in collectible condition is a genuinely uncommon find.

Currency specialists who study print runs point out that higher denominations are produced in smaller total numbers than ones and fives, which means fewer chances for a solid combination to exist in the first place. A collector who found a solid $20 drew genuine excitement from other currency collectors online, several of whom said they had never come across one themselves despite years of looking.

Expect a solid twenty in clean condition to land in the same $1,000 to $4,000 range as a solid on a smaller bill, with real potential to run higher given how seldom they surface. A circulated example with folds or stains is still worth setting aside, just at a steep discount from that range.

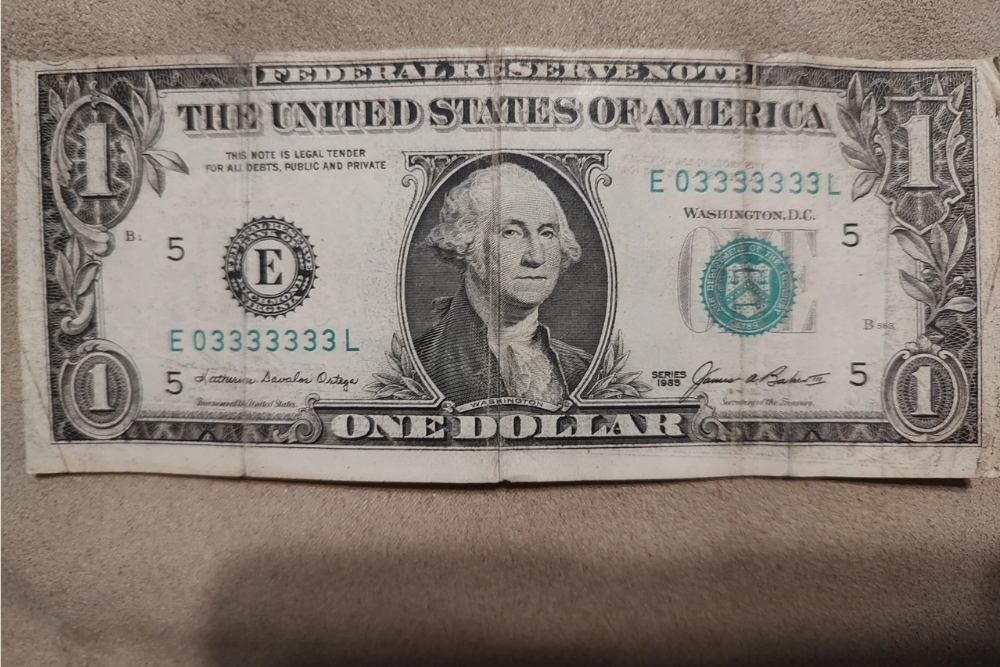
6. $1 bill with a seven-in-a-row serial number

1985 one-dollar note with serial number E03333333L, showing seven consecutive threes
Image Credit: dragracerstan via eBay

Seven-in-a-row notes sit one digit short of a true solid. Seven identical numbers appear with a single different digit breaking the pattern, either at one end or tucked into the middle, like 07777777 or 77177777. Collectors sometimes call this a near solid, and the two terms get used interchangeably.

It misses the top tier of value that a true solid commands, but it’s still a legitimate rarity. Clean examples typically bring $50 to $150, with the price depending on where the odd digit sits and which number repeats seven times. A note where the stray digit interrupts the middle of the run tends to catch a collector’s eye faster than one where it’s tucked at either end, and that visibility can nudge the price toward the top of the range.

A seven-in-a-row is a realistic find for anyone digging through pocket change rather than an inherited collection, since the pattern shows up more often than a true solid by simple math. Check the full eight digits slowly. It’s easy to glance at a run of sevens and miss that the eighth digit doesn’t match.

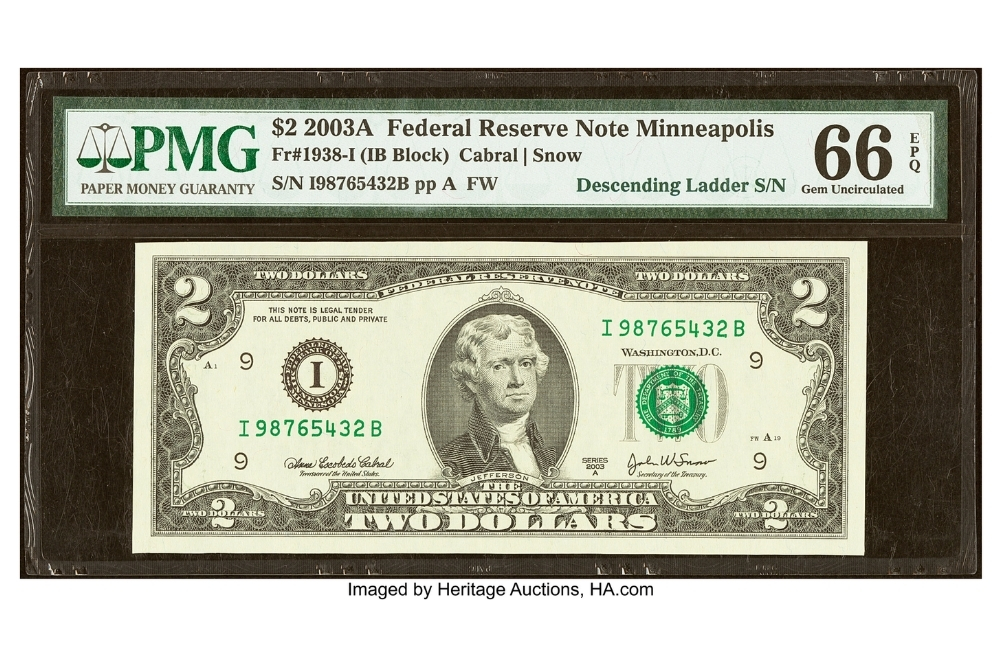
7. $2 bill with a true ladder serial number

Graded two-dollar note with descending ladder serial number I98765432B
Image Credit: Heritage Auctions

A true ladder runs in perfect sequence, either climbing from low to high, like 12345678, or counting down, like 87654321. Every digit has to be exactly one higher or lower than the digit before it, with no gaps and no repeats, which makes this one of the hardest patterns to stumble into by chance.

Clean true ladders typically bring $600 to $2,100, and descending ladders tend to sell for more than ascending ones. Currency print runs don’t always reach their full capacity, so a descending sequence that depends on a run having printed all the way up to a high number is scarcer than an ascending one, which only needs the run to have started low, and it always does.

$2 bills are worth checking for this one specifically because so many people already set them aside as a novelty without ever looking past the denomination. A true ladder tucked inside a stack of twos someone saved decades ago is a realistic find in a way that one on a bill that gets spent and recirculated constantly isn’t. Confirm every digit in order before getting excited. A near-miss where one digit breaks the sequence is a different, much less valuable pattern.

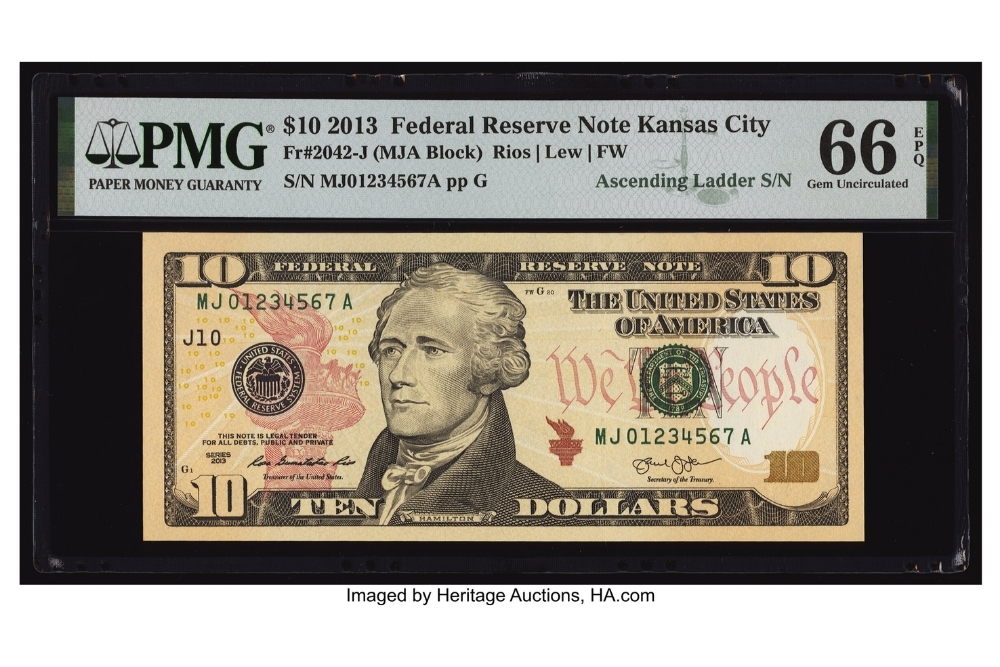
8. $10 bill with a broken ladder serial number

Graded 2013 ten-dollar note with serial number MJ01234567A, a leading zero followed by digits one through seven
Image Credit: Heritage Auctions

A broken ladder keeps the climbing or falling sequence of a true ladder but lets a single zero interrupt it, appearing before, after, or in the middle of the run, like 10234567 or 12345607. It’s a recognized, specific pattern with its own name, not just any serial number that happens to look vaguely sequential.

That specificity matters, because the term gets stretched loosely by casual sellers. A genuine broken ladder, with the zero breaking an otherwise perfect ascending or descending run, typically brings $50 to $200 in clean condition, a real but modest step down from the $1,000 and up that a true, unbroken ladder commands. A serial number that’s merely scattered or jumbled, with no actual sequence underneath it, is not a broken ladder no matter what a listing calls it, and it’s worth face value only.

Ten-dollar bills are a reasonable place to check for this one, since they get handled less than ones and fives but still circulate enough that a genuine find is plausible. Read the full eight digits slowly and confirm the sequence really does run in order apart from that one zero. If it doesn’t, you’re holding an ordinary ten.

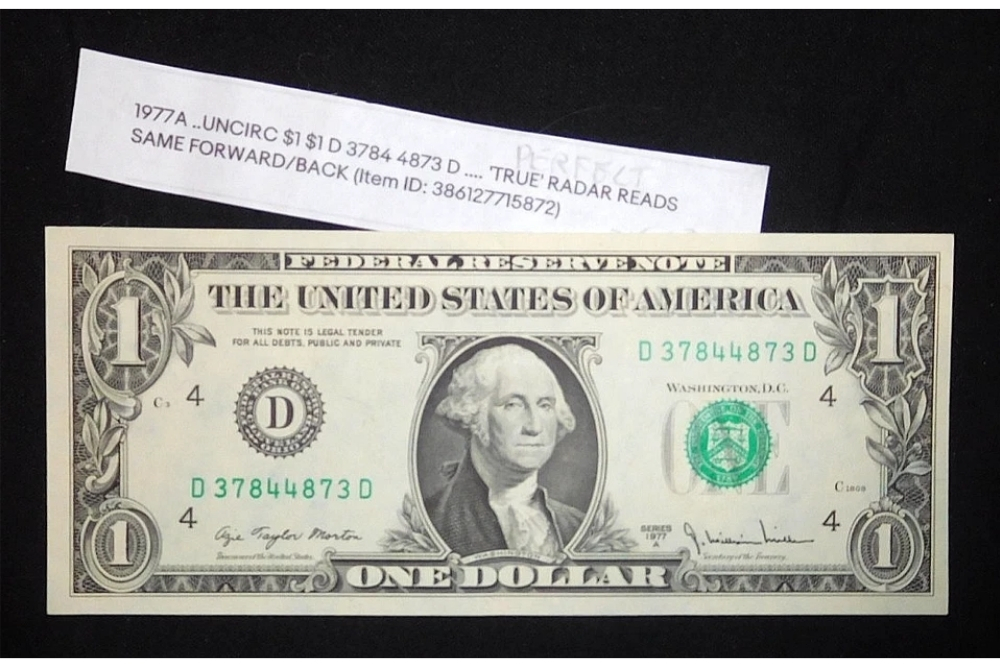
9. $1 bill with a radar serial number

1977A one-dollar note with palindromic radar serial number D37844873D
Image Credit: mrae7 via eBay

A radar reads the same forward and backward, a true palindrome, like 12344321 or 77700777. The name comes from the word itself, which does the same trick. Because the two middle digits always have to match for the whole thing to work, radars have a built-in symmetry that’s easy to spot once you know to look for it.

Real sales back up modest but genuine demand here. A plain radar without any repeating or super pattern typically brings around $70 in circulated condition, honest money for a bill that cost a dollar to begin with. A rarer variation called a repeating radar, where the serial number is effectively two matching four-digit palindromes stacked together, like 12211221 or 54455445, draws more interest from collectors who specialize in the category, since it combines two recognized patterns in one note.

Basic radars are common enough that finding one is a realistic weekend project, not a once-in-a-lifetime find. Check any bill’s serial number both directions before spending it. It takes about three seconds, and the payoff, while modest, is real and well documented.

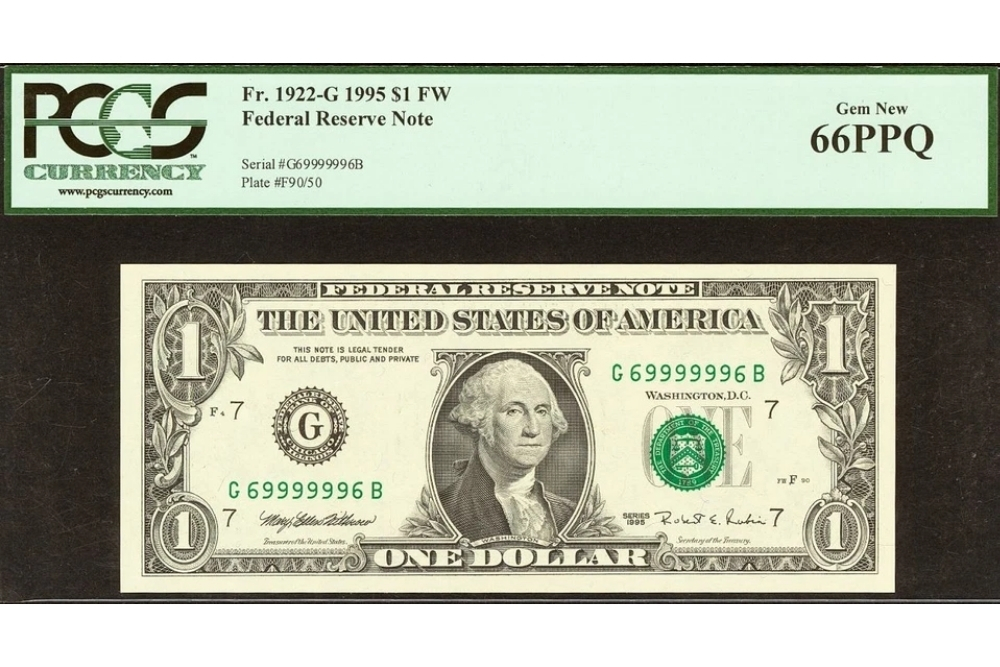
10. $1 bill with a super radar serial number

Graded one-dollar note with super-radar serial number G69999996B
Image Credit: commendablecurrency-oddcurrency via eBay

A super radar tightens the radar pattern considerably. Only the first and last digits differ, with every digit in between identical, like 27777772 or 50000005. It’s technically still a palindrome, but the long run of matching interior digits makes it read as its own distinct, more striking category to collectors.

The jump in rarity shows up in the price. A super radar typically brings close to $170, more than double what an ordinary radar commands, which reflects how much tighter the pattern has to land. Higher denominations carry even more weight here, since fewer fifties and hundreds get produced overall compared to ones, which means a super radar on a bigger bill is a real find rather than a theoretical one.

Super radars are also, by definition, a kind of binary serial number, since the whole thing is built from just two digits. Collectors who specialize in binaries and collectors who specialize in radars both have reason to want one, which keeps demand a little steadier than it is for patterns with a narrower audience. Check the first and last digits against the middle run before assuming an ordinary radar is the more valuable super version.

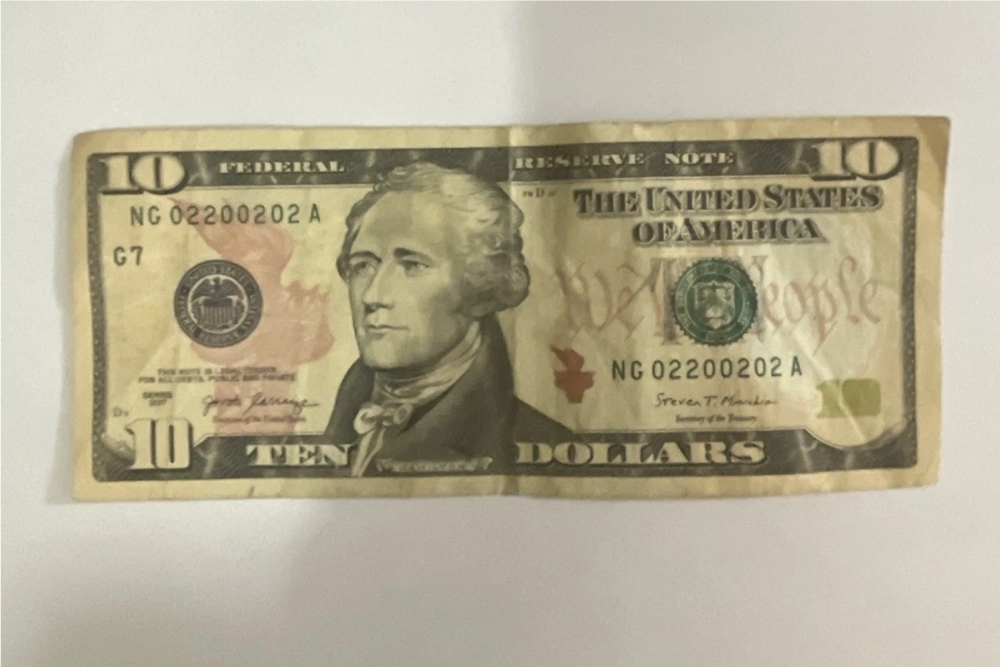
11. $10 bill with a binary serial number

Ten-dollar note with binary serial number NG02200202A, using only zeros and twos
Image Credit: buyselltr51 via eBay

A binary serial number uses only two different digits for the entire eight-digit run, in any order, like 37377337 or 10110100. The digits don’t need to alternate in any particular pattern, which makes binaries more common than radars or ladders but still genuinely uncommon compared to an ordinary serial number built from a random mix of digits.

Clean binaries typically bring $20 to $75, with notes built from only zeros and ones, known as true binaries, pulling a stronger premium of roughly $40 to $150 because that specific combination echoes computer code and draws interest from a slightly different, overlapping group of collectors. A near-solid serial number technically qualifies as a binary too, since it also uses only two digits, which is worth knowing before you assume your bill belongs to a rarer category than it actually does.

Ten-dollar bills are a practical place to check for this pattern since they see regular use without getting folded into oblivion the way ones do. Count the unique digits across all eight positions. If only two numbers show up no matter how many times each repeats, you’ve got a binary worth a second look.

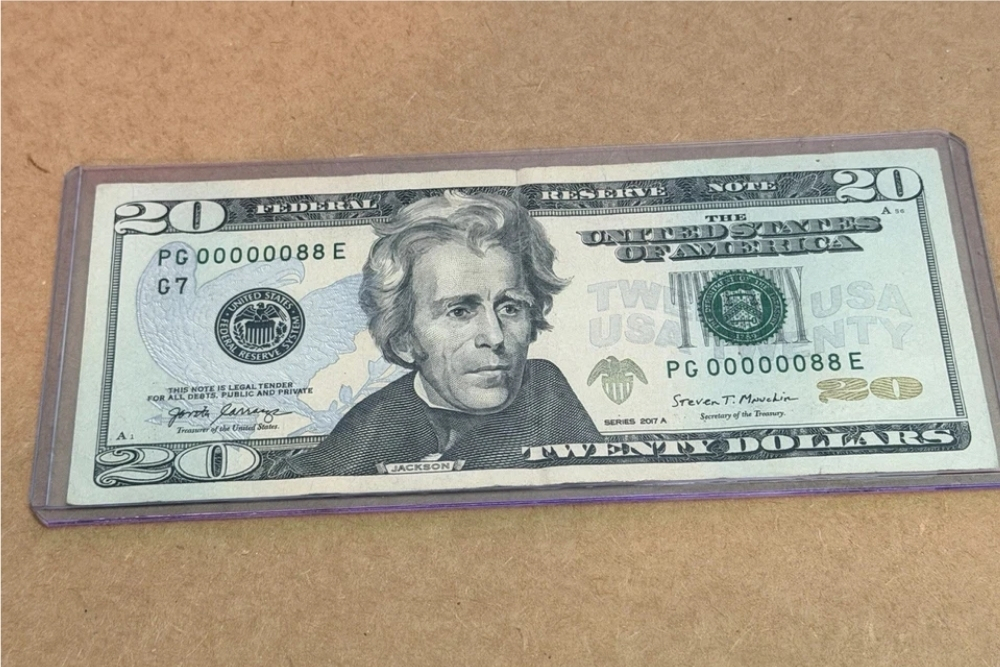
12. $20 bill with a low, repeating serial number

Twenty-dollar note in a sleeve with low serial number PG00000088E
Image Credit: josnic_9734 via eBay

Low serial numbers are their own well-known category, and the lowest ones get steep premiums on their own merit. But a low serial that also happens to repeat a digit, like 00000022 or 00000055, draws interest from two different groups of collectors at once instead of just one, which tends to push the price past what either pattern would bring by itself.

Numbers from 00000010 through 00000099 typically bring $300 to $400 for the lowest of that range and roughly $80 apiece for the rest, with numbers under ten worth considerably more. A doubled digit inside that low range, something a collector can point to and describe in one sentence rather than just “a low number,” tends to sell at or above the top of that baseline, though there’s no fixed extra premium the way there is for a standalone repeater.

Twenty-dollar bills are worth checking here specifically because low serial numbers on larger denominations are scarcer to begin with, and most people only think to check serial numbers on ones. Look at the first few digits before the rest. If you’re staring at several zeros followed by a repeated pair, you’re holding something worth a closer look.

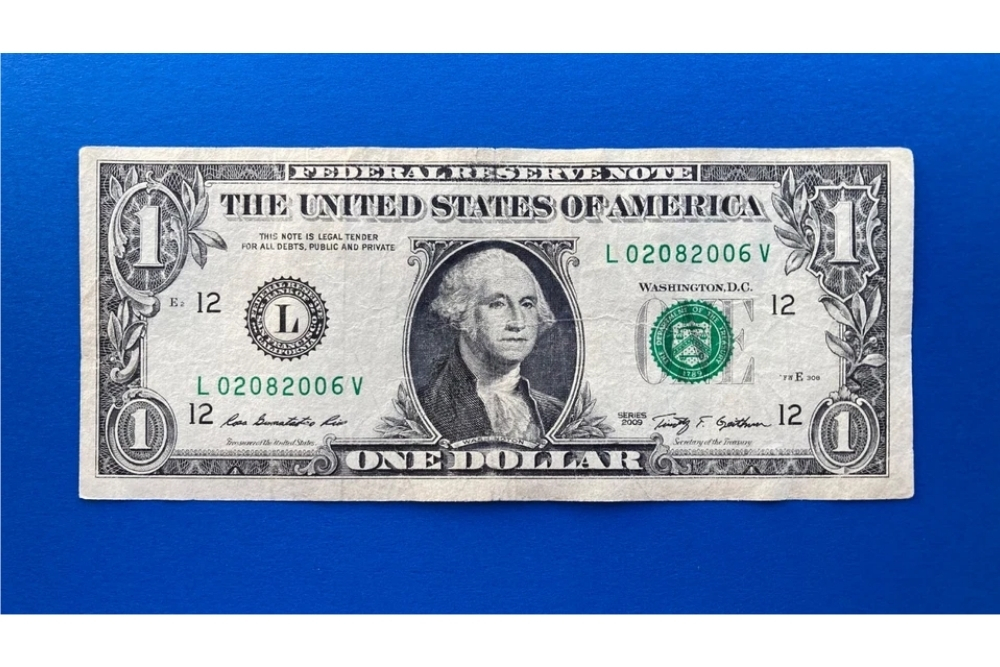
13. $1 bill with a birthday serial number

One-dollar note with birthday serial number L02082006V, reading February 8, 2006
Image Credit: lvthembeagles via eBay

A birthday note is a serial number that reads as an actual calendar date, in month-day-year order, like 07041976 for the Fourth of July, 1976. Collectors and regular buyers alike search for these specifically to match their own birthday, a child’s, or a historically meaningful date, which makes demand highly personal rather than driven by rarity math the way most fancy serial number patterns are.

That personal nature means prices swing widely. An ordinary birthday note with no special cultural weight typically brings around $30, modest money that reflects ordinary personal demand rather than broad collector interest. Dates with wider cultural weight, like a historically significant day or a widely recognized holiday, can bring considerably more when the right buyer is looking. A random date with no personal or cultural pull to anyone browsing is genuinely just a dollar, no matter how neatly it reads as a calendar date.

This is a fun one to check rather than a reliable one. Rearrange the eight digits into month, day, and year order and see if anything clicks. Most of the time, nothing will. Occasionally, it’s worth holding onto.

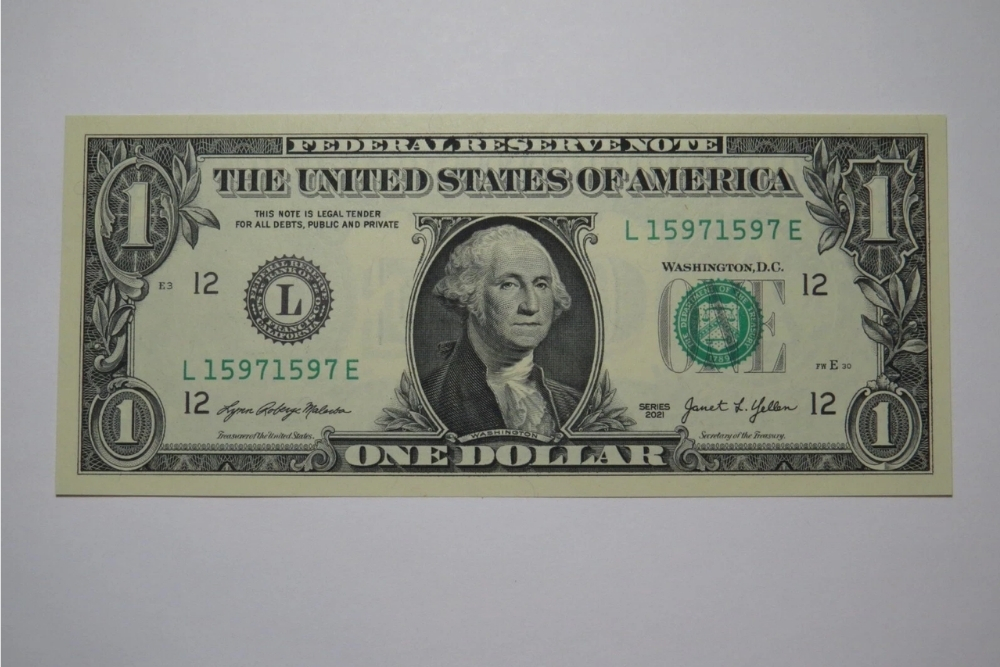
14. Series 2017 or 2021 $1 bill with a fancy serial number

Series 2021 one-dollar note with repeater serial number L15971597E
Image Credit: collectiblenotes via eBay

It’s easy to assume fancy serial numbers only turn up on old currency that’s been sitting in a drawer for decades, but the patterns show up just as often on bills printed in the last few years. A series 2017 one dollar note with a textbook repeater serial number, 77227722, is exactly the kind of fancy serial number that turns up on current bills just as it does on older ones.

The math behind every fancy serial number pattern applies the same way to a brand-new series as it does to one printed decades ago, since the Bureau of Engraving and Printing assigns serial numbers the same way regardless of year. A repeater on a current series bill brings the same $20 to $100 that an older repeater does, condition for condition, pattern for pattern.

That makes a current-series repeater one of the most realistic fancy serial numbers to actually find. You don’t need an inherited collection or a lucky estate sale find. The next stack of ones that comes back as change from a coffee run is exactly as likely to carry a fancy serial number as any bill you’ll ever come across. Check it before it goes back out the door.

15. $2 bill with a binary serial number

Two-dollar note with binary serial number G02200200A, using only zeros and twos
Image Credit: wile.bria via eBay

Binary $2 bills combine two things that work in a collector’s favor at once: the pattern itself, built from only two unique digits across all eight positions, and the simple fact that $2 bills already carry a small built-in premium of collector interest regardless of their serial number.

Clean binary $2 notes typically add $10 to $35 on top of face value, a modest but real bump for a bill that a lot of people already treat as a keepsake rather than cash to spend. Because $2 bills get pulled aside so often before anyone thinks to check the serial number, there’s a reasonable chance that binaries sitting in old wallets and junk drawers have simply never been looked at closely.

Don’t assume a $2 bill is only worth checking for its denomination. Pull the eight digits and count how many unique numbers show up. If it’s only two, no matter the order, you’ve got a binary on your hands, and it’s worth more set aside than spent, even if the premium here is on the modest end of what a fancy serial number can add.

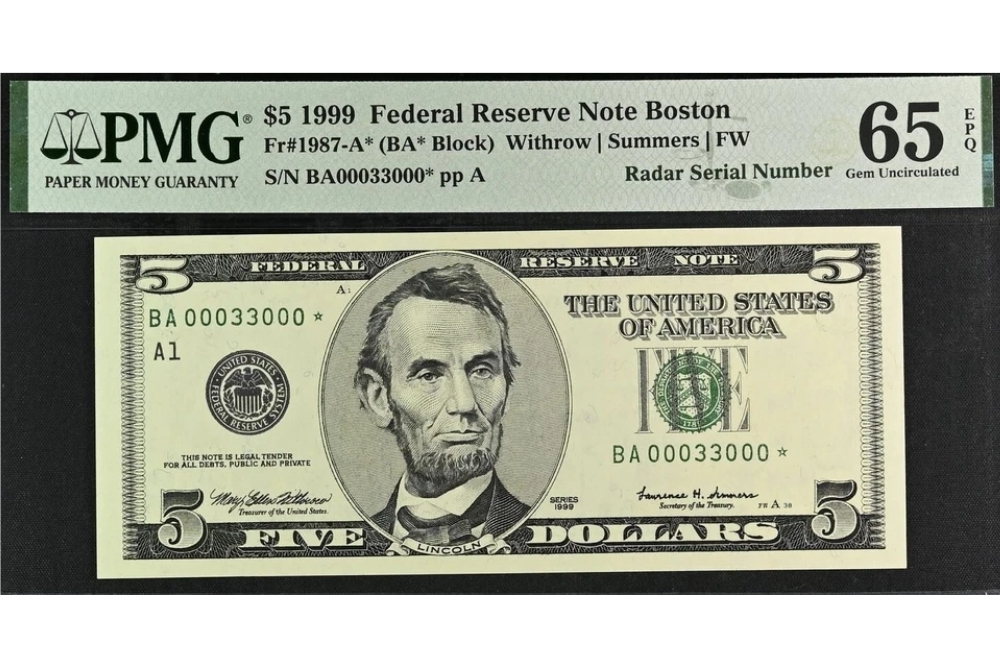
16. $5 bill that’s a star note with a repeater or radar serial number

Graded five-dollar star note with radar serial number BA00033000 followed by a star
Image Credit: commendablecurrency-oddcurrency via eBay

A star note is a replacement bill, printed when the Bureau of Engraving and Printing catches a defective note during production and needs to reissue that spot in the run. You can spot one by the small star symbol printed in place of the final letter in the serial number. On their own, most modern star notes are worth little more than face value, since large print runs mean they’re not especially scarce.

The math changes when a star note also carries a fancy pattern like a repeater or a radar. The two traits stack, and a modern star note with a fancy serial number is explicitly worth more than either trait alone would bring. Layer a repeater’s typical $20 to $100 premium onto a modest star-note bump, and a clean $5 star-and-pattern combination realistically lands somewhere in the $50 to $150 range, more for a genuinely small print run.

Check the end of the serial number for the star first, then check the eight digits for a pattern. Finding both on the same $5 bill is a real, if uncommon, double find, worth setting aside rather than spending on the assumption that one trait alone made it ordinary.

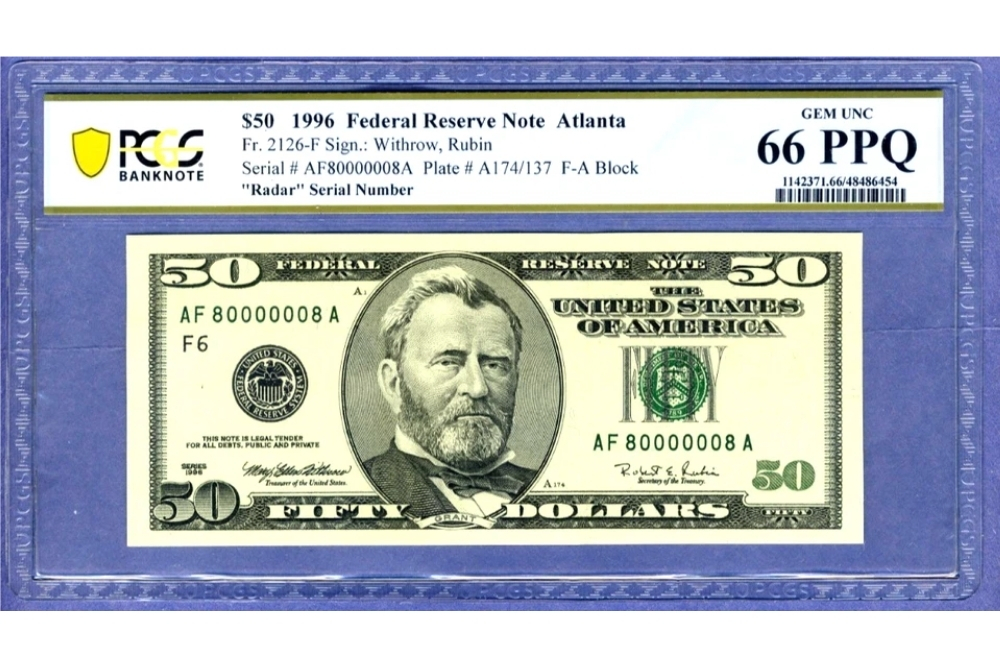
17. $50 bill with a super repeater or super radar serial number

Graded fifty-dollar note with super-radar serial number AF80000008A
Image Credit: mxc1971 via eBay

Fifty-dollar bills don’t circulate the way ones and fives do, which cuts two ways. Fewer people handle them closely enough to notice a fancy serial number, but that also means fewer have been pulled out of circulation and examined already, so a genuine find on a fifty is less picked-over territory than the same pattern on smaller bills.

Super repeaters, where a two-digit block runs through the entire serial number, and super radars, where only the first and last digits break an otherwise identical run, both typically add $80 to $150 on top of face value. On a fifty, that premium stacks onto real money to begin with, putting a clean example comfortably over $100 in total value before accounting for how rarely collectors see these patterns on higher denominations at all.

This is a bill worth examining before you spend it rather than one to go hunting for specifically, since fifties don’t pass through most people’s hands often enough to make searching for one worthwhile. But if one turns up in change from a larger purchase, check the full serial number before it goes back into circulation. The pattern, if it’s there, won’t announce itself.

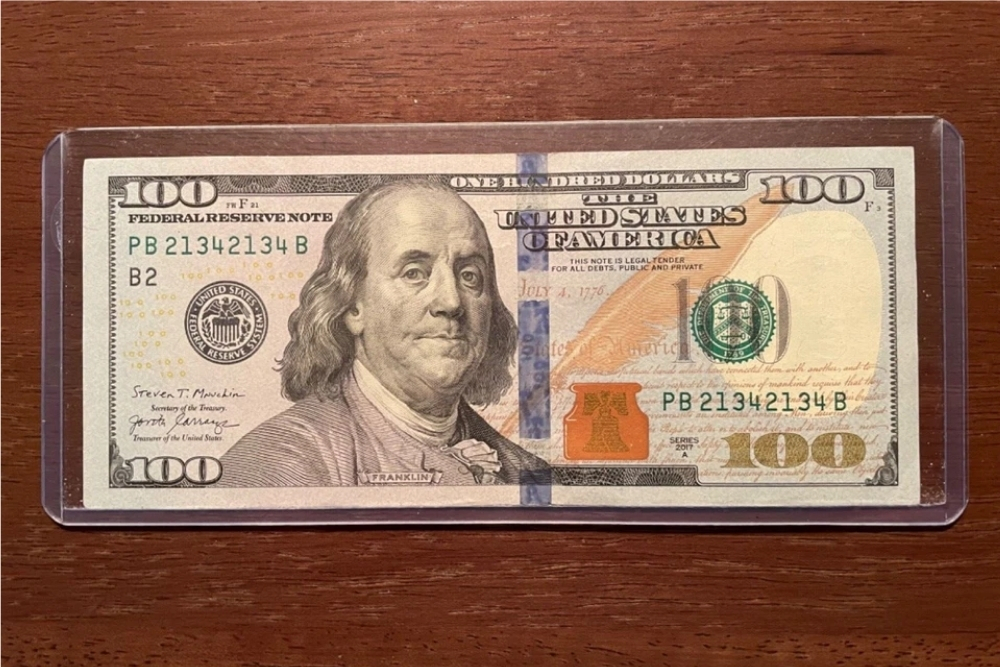
18. $100 bill with a repeater or super repeater serial number

Hundred-dollar note in a sleeve with repeater serial number PB21342134B
Image Credit: yankeefan_mm7 via eBay

The same math that applies to a one-dollar repeater applies just as directly to a hundred. Collectors value the pattern itself more than the bill it happens to be printed on, and identifying a repeater or super repeater costs the same attention whether it’s on a single or a hundred.

Clean repeaters typically bring $20 to $100 and super repeaters $100 to $400, the identical ranges that apply to smaller bills, though real-world prices on hundreds tend to sit toward the higher end of those ranges since fewer people examine hundred-dollar serial numbers closely enough for the fancy ones to surface in the first place. A hundred with a strong pattern and crisp, unfolded condition is a legitimately uncommon combination.

Hundreds don’t pass through daily transactions often, which means most people never get the chance to check one at all. If a hundred does cross your hands, whether as change from a large cash purchase or from a drawer somewhere, it’s worth the ten seconds to read the full serial number before it moves on. The payoff, when it’s there, is proportional to the bill it’s printed on.

Whatever’s in your wallet right now is worth thirty seconds with these patterns in mind. Most of it is ordinary. Some of it, statistically, isn’t.

Your grandmother’s dresser has been holding folded sweaters in the guest room for thirty years, and nobody in the family wants to be the one who finally throws it out. Good instinct. Flip it over, feel for a label, and look at the legs. If it’s a compact walnut chest with tapered dowel legs or a maple dresser with a sunburst of brass pulls, you might be looking at real money instead of a trip to the curb.

Mid-century furniture has had a strange couple of decades. Pieces that sold for $75 at estate sales in the 1990s now regularly bring four figures, and the collector market keeps widening past famous names like Eames and Knoll into smaller American manufacturers that made this style of furniture by the truckload. What separates a thrift store find from real money comes down to the maker, the specific line, and how much of the original finish and hardware survived.

The good news for anyone digging through a basement or an inherited house: almost none of this furniture was a signed, one of a kind piece to begin with. These were production lines, built by the hundreds or thousands in factories across the Midwest and New England, which means a real example could be sitting in your own house right now.

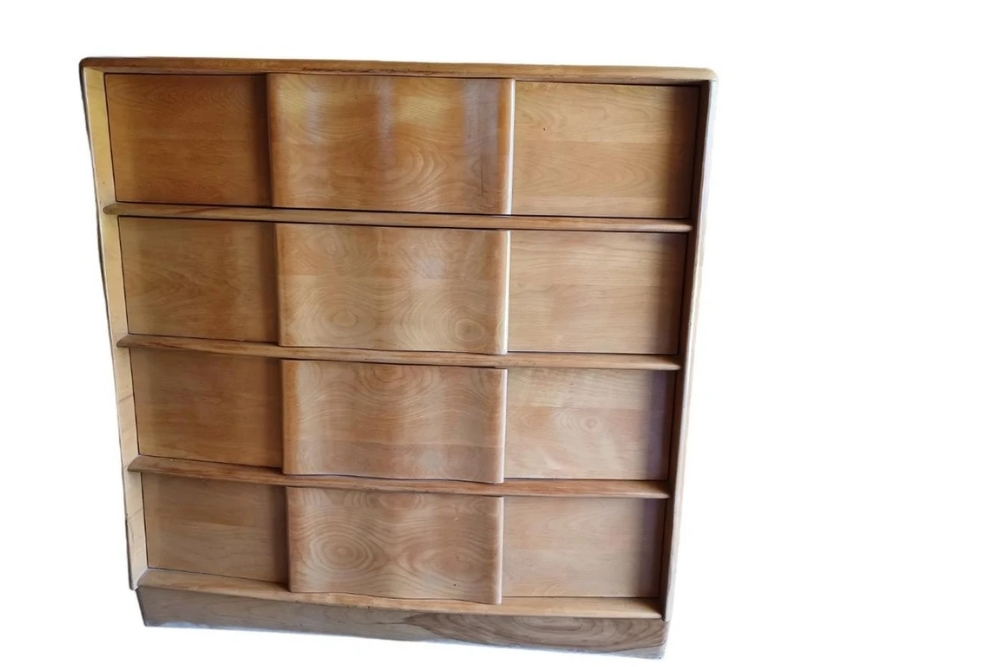
Heywood-Wakefield “Wheat” finish dresser

Heywood-Wakefield Wheat chest with curved drawer fronts
Image Credit: NaomiSuttonInteriors via Etsy

Heywood-Wakefield ran a furniture company out of Gardner, Massachusetts for more than a century, but it’s the blonde maple Modern line the company sold from the mid-1930s through the mid-1960s that collectors actually chase. Wheat was one of the original factory finishes, a warm honey tone applied to solid birch and maple with no veneer anywhere on the piece, which is itself a useful tell against lookalikes.

Clean examples with the original finish intact typically bring $1,200 to $3,000, while smaller or heavily worn pieces fall closer to $600 to $1,000. Flip the piece over or pull a drawer: genuine Heywood-Wakefield from this era carries a burned in “dogbone” logo stamp, usually inside the top left drawer or on the underside, along with penciled model and drawer numbers worth checking closely before you get your hopes up.

The finish is what makes or breaks the price here. A quick nail polish remover test on a hidden spot tells you a lot: original lacquer barely reacts, while a later coat of polyurethane or stain softens almost immediately. Repainted or heavily restained pieces lose a significant chunk of their value, and replacement plastic drawer pulls are a common and easy to spot downgrade from the originals.

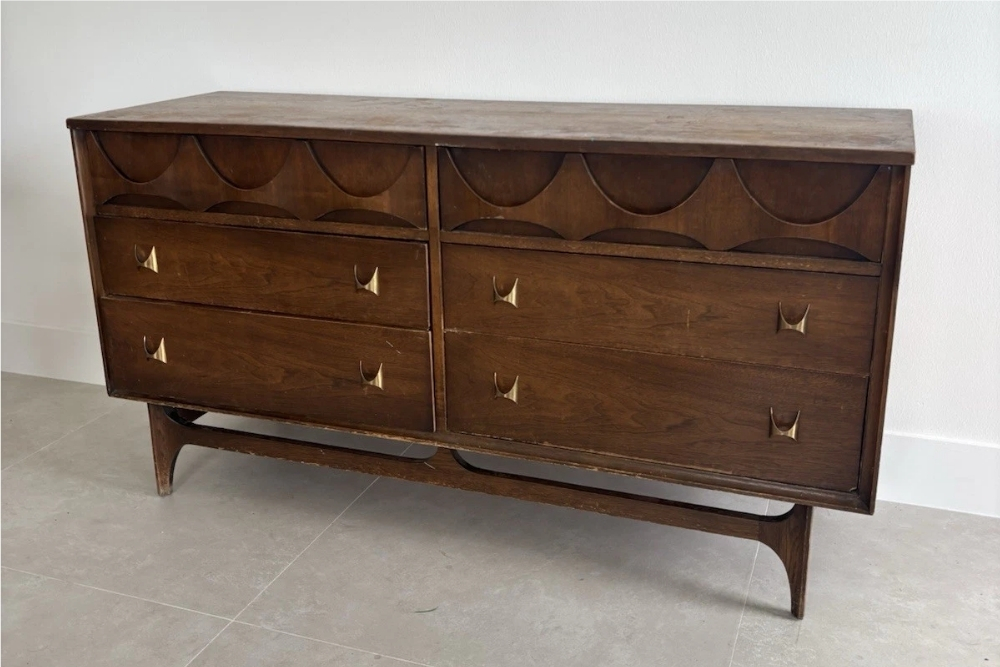
Broyhill Brasilia dresser or credenza

Broyhill Brasilia walnut dresser with sculpted arches above the drawers
Image Credit: abc219 via eBay

Broyhill debuted its Brasilia line at the 1962 Seattle World’s Fair, named for the dramatic new Brazilian capital city architect Oscar Niemeyer was building at the time, and the sculpted walnut case pieces still look strikingly modern six decades later. The line’s defining feature is drawer fronts carved into raised, parabolic curves rather than flat panels, a detail that was genuinely difficult and expensive to mass produce.

A clean dresser or credenza with its original sculpted brass pulls typically brings $1,800 to $3,800, and the large illuminated display credenzas built as room dividers can run higher still. Rougher or incomplete examples fall to $600 to $1,200. Because Brasilia was made in real volume between 1962 and 1970, it shows up often enough at estate sales that patience usually pays off more than urgency.

Check inside a drawer or on the back panel for a Broyhill paper or foil label before paying a premium price, since generic sculpted walnut furniture from other, unbranded makers is routinely sold online as Brasilia on styling alone. Chipped or cracked edges on the raised curves are common and reduce value, as does veneer lifting on the case sides. Replacement hardware is an easy downgrade to spot: original Brasilia pulls are heavier and more deeply sculpted than any generic brass substitute.

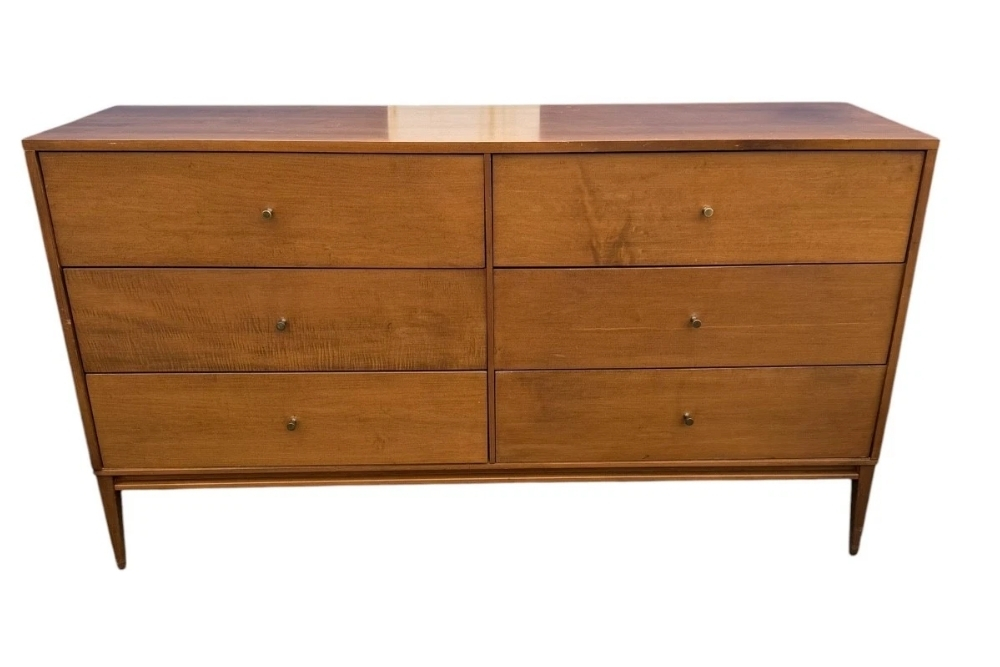
Paul McCobb Planner Group dresser

Paul McCobb Planner Group maple dresser with six drawers and tapered legs
Image Credit: 99limitedv8 via eBay

Paul McCobb designed the Planner Group in 1949 as affordable modular furniture for small postwar homes, and Winchendon Furniture Company in Massachusetts built it by the thousands through the 1950s. The line’s low cost and modularity were the whole point, which is exactly why so much of it survived in attics and basements instead of getting replaced.

A standard six to eight drawer maple dresser in solid original condition typically brings $1,500 to $3,000, with smaller three-drawer chests and nightstands running $400 to $900. Unusual or oversized examples can go well beyond that: an oversized twenty-drawer dresser can reach $9,500, though that’s a genuine outlier rather than anything close to typical. McCobb designed the line in 1949, debuting it at the Chicago furniture market the following January.

Look for the original “Planner Group” paper label, which is often lost but meaningfully helps both authentication and price when it survives. Tapered, canted maple legs on a black iron base are the signature look, along with conical or cylindrical brass pulls. Maple ambers unevenly with age and sun exposure, which is normal rather than a flaw. A missing or replaced iron base, water rings on the top, or non-brass replacement pulls hurt value more than ordinary surface wear does.

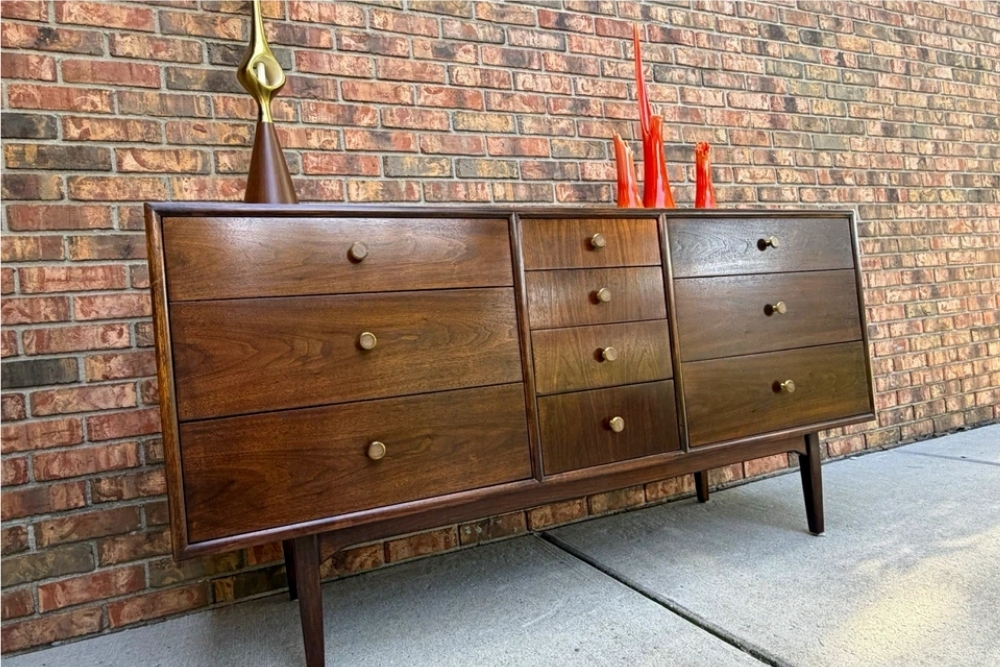
Drexel Declaration dresser or credenza

Drexel Declaration walnut dresser with round pulls against a brick wall
Image Credit: saltheartist via eBay

Drexel’s Declaration collection came out of a late 1950s partnership between designers Kipp Stewart and Stewart MacDougall, and the walnut line was good enough that several pieces were chosen to represent American design at the 1958 Brussels World’s Fair. The look is restrained compared to some of its more sculptural competitors: clean rectangular cases, tapered round legs, and either plain round brass pulls or white porcelain knobs set into brass fittings.

A clean credenza or dresser with its original hardware and an intact Drexel stamp typically brings $2,000 to $4,800, depending on size and form. Matched nightstand pairs typically bring around $3,895 for the set.

Authentication comes down to the stamp, which should appear inside a top drawer or on the case back reading “Declaration by Drexel.” That matters because several other 1960s manufacturers made visually similar sculpted walnut dressers, and sellers sometimes borrow the Declaration name without the piece actually being Drexel’s. A missing or mismatched pull set is the most visible value hit since the hardware is distinctive and hard to replace to match, followed by warped drawer fronts and over-stripped refinishing that flattens the warm walnut tone the line is known for.

American of Martinsville “Dania” dresser

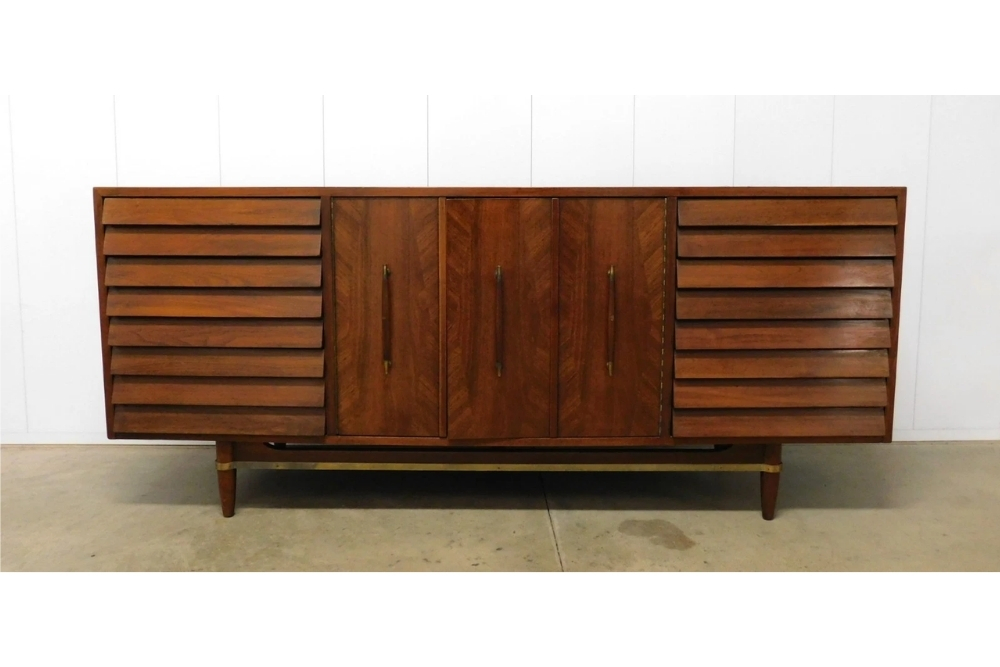
American of Martinsville Dania dresser with louvered drawer fronts, central doors and brass trim
Image Credit: lenedwardsfinefurnishings via eBay

Merton Gershun designed more furniture lines than almost anyone working in American mid-century case goods, and Dania, built by American of Martinsville in Virginia, is generally considered his most successful. The signature detail is immediately recognizable: overlapping, angled louvered slats across the lower drawer fronts with no visible pulls at all, paired with brass capped tapered legs and a brass band running across the base.

A highboy or lowboy dresser with its louvered fronts intact typically brings $1,000 to $2,300, with restored examples landing at the higher end and original finish pieces priced lower. Dania ranks among Gershun’s most internationally successful lines, alongside similar work he produced for Dillingham under different names.

That overlap is worth knowing about if you’re trying to identify a piece: Gershun designed several visually related collections for American of Martinsville alone, including Dilettante, Fortissimo, and Harlequin, so don’t assume a piece is Dania just because it’s walnut with brass trim. The louvered slat fronts are the detail to check for specifically, and they’re also the most fragile part of the piece. Cracked, missing, or replaced slats meaningfully hurt the price, and so does a dresser that’s lost its brass leg caps or base banding. Water rings and dulling refinishing that flattens the walnut to brass contrast are the other common issues.

Kent-Coffey “Tempo” dresser

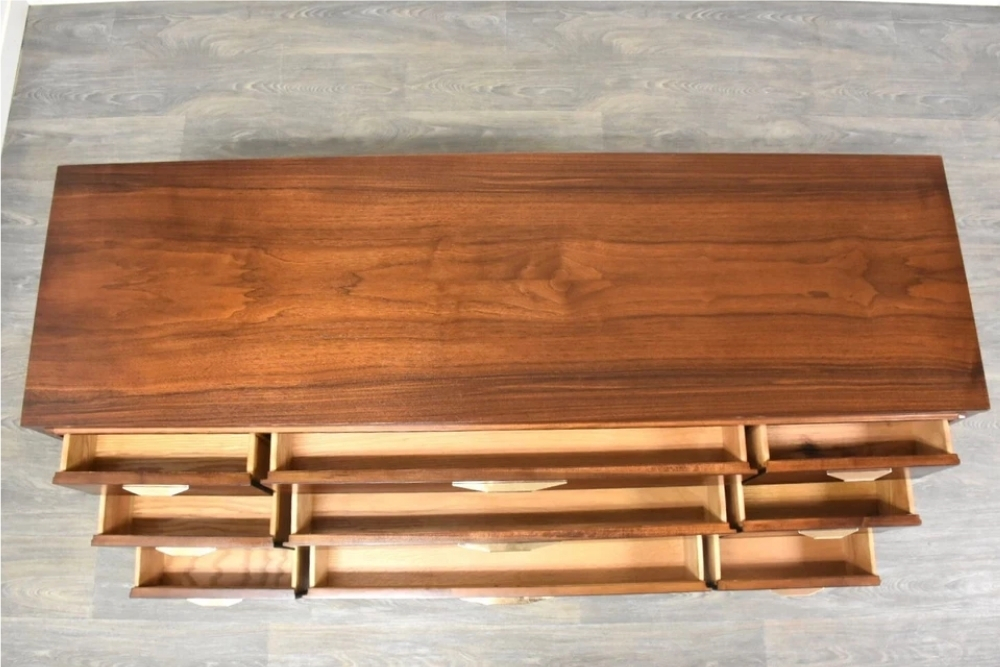
Overhead view of a Kent-Coffey Tempo walnut dresser with drawers open and sculpted pulls visible
Image Credit: mixedmodern via eBay

Kent-Coffey was a North Carolina furniture manufacturer that ran several visually similar walnut lines through the 1960s, and Tempo is one of the more recognizable thanks to its sculpted, arched drawer fronts and substantial brass hardware. The line sold well enough that it still turns up regularly at estate sales across the South and Midwest.

A professionally refinished dresser with its original brass pulls typically brings $1,800 to $3,000, while an unrestored example with visible age sells for less, usually $800 to $1,800 depending on how rough the finish is. Because Kent-Coffey ran so many similar lines side by side, including Perspecta, Tableau, and Townhouse, confirming the line name matters more than it might seem: check the maker’s label on the back or underside rather than assuming from styling alone.

The sculpted brass hardware is both the signature feature and the biggest vulnerability. It’s distinctive enough that generic replacement pulls are an obvious and value-killing downgrade, and original sets that are missing or mismatched should bring the asking price down meaningfully. Veneer chips along the sculpted fronts, water rings and finish crazing on the top, and any structural wobble in the case joinery are the other things worth checking before you commit to a price.

George Nelson “Basic Cabinet Series” credenza

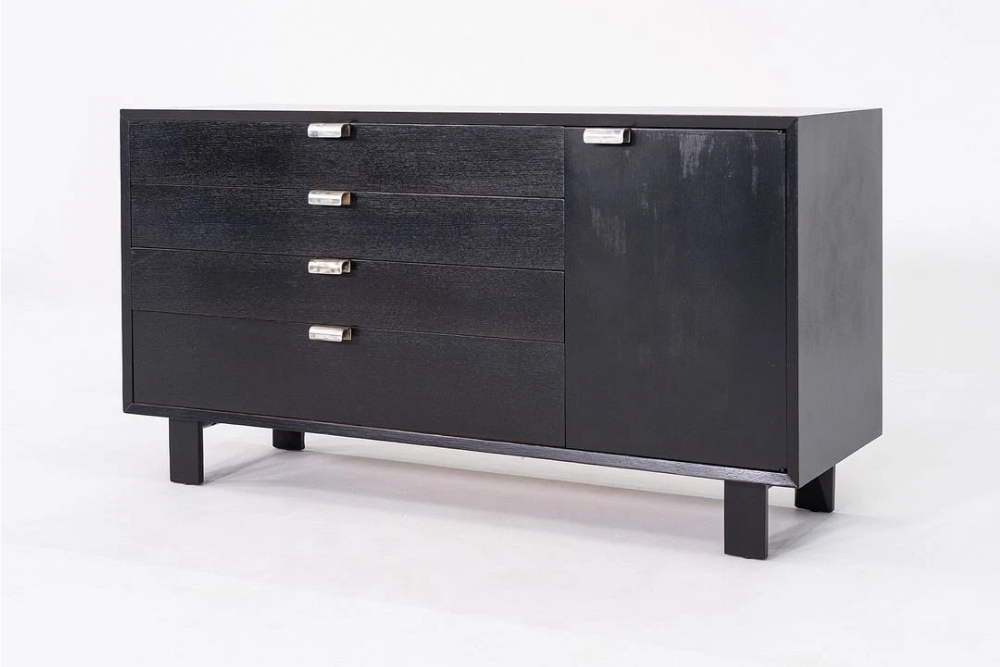
Black George Nelson Basic Cabinet Series credenza with drawers, a cabinet door and metal pulls
Image Credit: d-rose-mod via eBay

George Nelson designed the Basic Cabinet Series for Herman Miller in 1946, building on a modular “Storage Wall” concept he’d developed two years earlier with Henry Wright while the two were editors at Architectural Forum. The modular, interchangeable cabinets were a direct response to postwar Americans owning more belongings and moving more often than earlier generations had, solving a problem fixed furniture suites couldn’t.

An ordinary single-cabinet credenza in walnut with no unusual finish typically brings $1,500 to $2,500 in good condition. Rare finishes or a matched, multi-piece run push well past that, sometimes into the thousands. The catch with this one is that Herman Miller still manufactures the Basic Cabinet Series today as an authorized reissue, and the new version looks remarkably close to the original in photographs.

The real tell is the label and the hardware rather than the overall look. Vintage examples carry an original Herman Miller or George Nelson paper label inside a drawer, with wording and a format distinct from current production’s SKU style labeling. The steel frame legs should show age-appropriate wear on the chrome or brushed finish, not the crisp modern plating of a new piece. Veneer lifting or bubbling, pitted chrome legs, and non-original aluminum pulls are the main things that knock down the price of a genuinely vintage example.

Lane “Acclaim” cedar chest

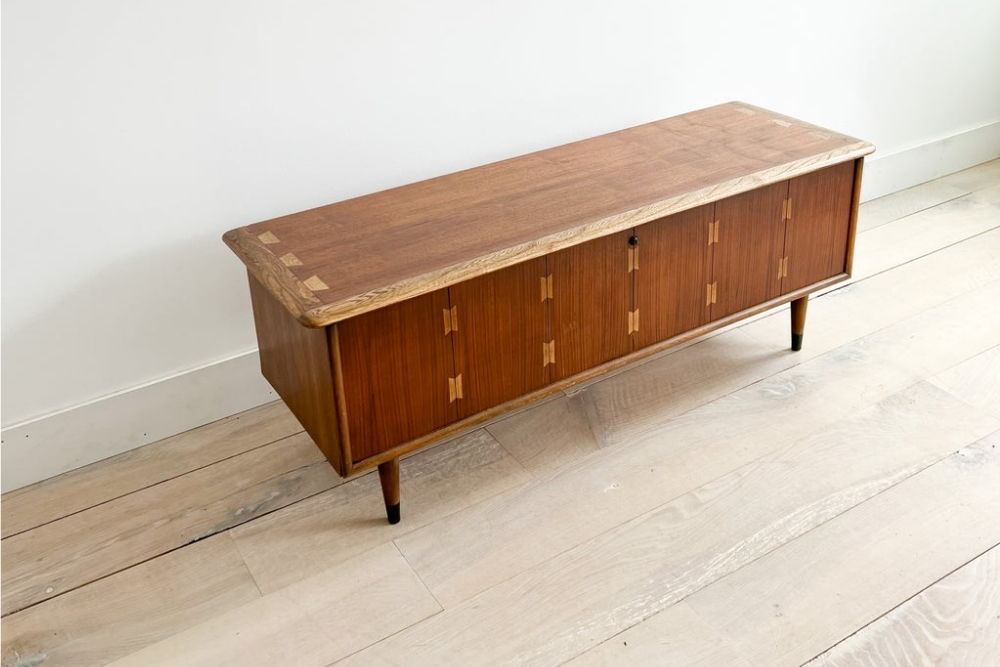
Lane Acclaim cedar chest with contrasting dovetail inlay along its walnut lid
Image Credit: Atomic Furnishing & Design

Lane built cedar hope chests by the millions out of Altavista, Virginia starting in 1912, using mass production methods the company originally developed filling WWI ammunition box contracts. The Acclaim line was one of many Lane cedar chest designs sold through decades of romance themed advertising aimed at young women receiving one as a gift, which is part of why so many ended up in American homes and stayed there.

That same volume is also why most of them aren’t worth much. A plain, ordinary Lane cedar chest with no particular design distinction typically sells for $100 to $300, and damaged or incomplete examples go for even less. Clean, undamaged pieces with original hardware and sharper mid-century styling can reach $700 to $1,500, but that’s the exception rather than the rule for this category.

Check the back or bottom for a stamped serial number and a small brass maker’s plate reading Lane, since several other manufacturers made visually similar cedar chests that get mistaken for Lane online. Cracked cedar lining, a missing or replaced lock, water damage, and replaced legs are the main condition issues to watch for. One safety note worth passing along regardless of value: the automatic push button locks used on pre-1990s Lane chests were the subject of a 1996 recall over child entrapment risk, so that mechanism is worth disabling or replacing if the chest will be around kids.

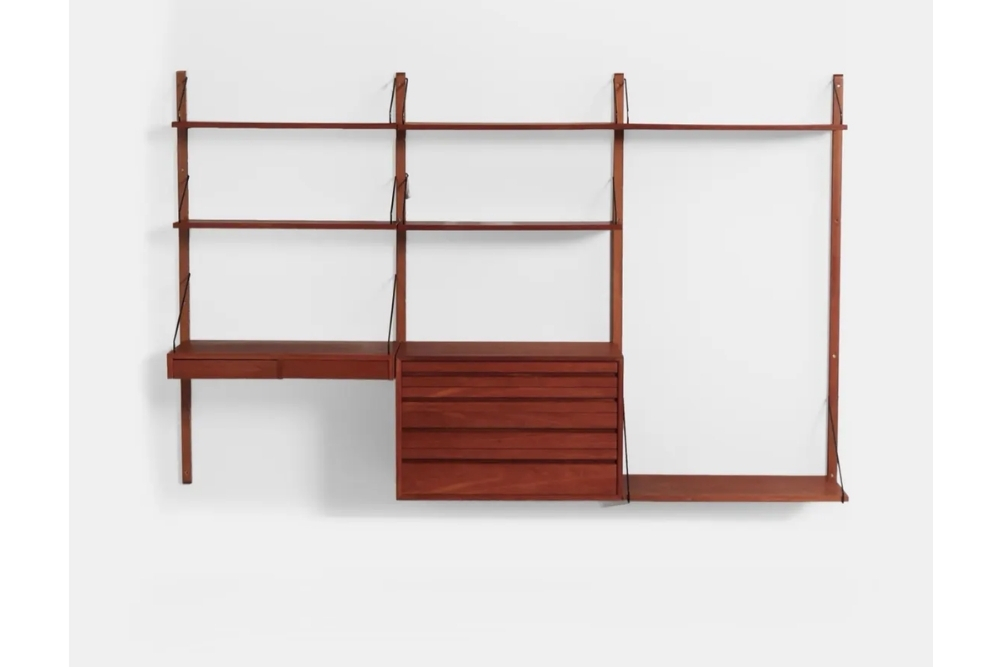
Poul Cadovius “Royal System” wall-mounted shelving

Poul Cadovius Royal System wall-mounted shelving with a desk and drawer cabinet
Image Credit: ZtijlDesign via Etsy

Danish designer Poul Cadovius introduced his Royal System wall-mounted shelving in 1948, growing the idea out of a Venetian blind manufacturing business he already ran. The concept, teak or rosewood shelves and cabinets that hang on slotted steel rails mounted directly to the wall rather than sitting on legs, became one of the most commercially influential pieces of Danish furniture design and popularized wall-hung modular storage well beyond Denmark.

A clean, complete three-bay teak set with its original wall rails and brackets typically brings around $1,500, and larger, complete multi-bay runs in rosewood can reach several times that. The catch is completeness: a single bay or a handful of loose shelves without the matching rails and brackets is worth very little, since the hardware is what makes the shelves reconfigurable in the first place and it’s easy to lose track of over the decades.

Genuine Cadovius pieces hang on vertical, slotted steel rails using angled brackets, a system that’s distinct enough to spot once you know what you’re looking at. Worth knowing before you get attached to a find: “Cado” and “Royal System” get used loosely online for similar Danish wall-rail shelving by other designers that isn’t actually Cadovius’s design. If the rails or brackets don’t match the original hardware pattern, treat the attribution with some skepticism.

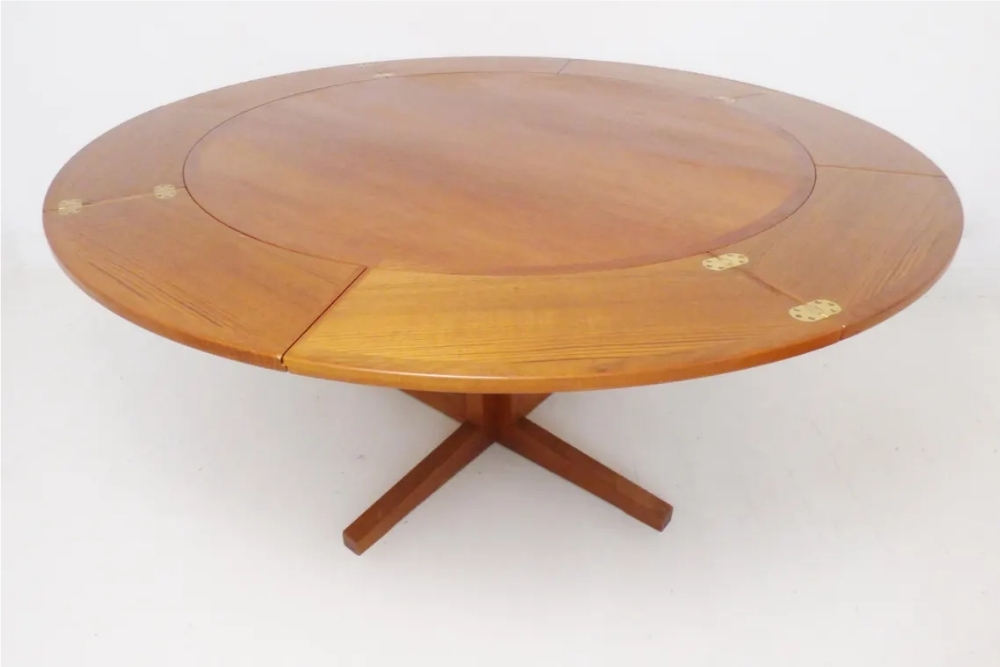
Dyrlund flip-top teak extension dining table

Dyrlund round teak flip-flap table extended with four hinged leaves and visible brass hinges
Image Credit: theeclecticrooms via Etsy

Danish manufacturer Dyrlund built its reputation on the “flip-flap” extension mechanism, where the leaves are hidden folded beneath the main tabletop and flip up and over into place rather than being stored separately and inserted by hand. It’s a clever bit of engineering that solved the real problem of where extension leaves go when nobody’s using them, and several of the company’s best-known tables in this style are attributed to designer Johannes Andersen.

A used teak example with visible scratches and some sun fading typically brings $600 to $900, while a clean rosewood example sold through a specialist dealer can reach $2,500 to $5,000 or more depending on size and condition. Rare, architect-designed Dyrlund tables occasionally go well past that, though that’s not the typical outcome for an ordinary flip-top table someone inherits.

Look for a metal “Dyrlund / Denmark” tag or stamp on the underside of the top or apron, and check that the flip mechanism itself still works smoothly, since that’s the whole point of the design. Sun fading is extremely common and shows up as a color mismatch between the main top and the leaves, which spend most of their life hidden from light. A sticking or loose flip mechanism and veneer chips at the hinge points are the other condition issues worth checking before you buy or sell.

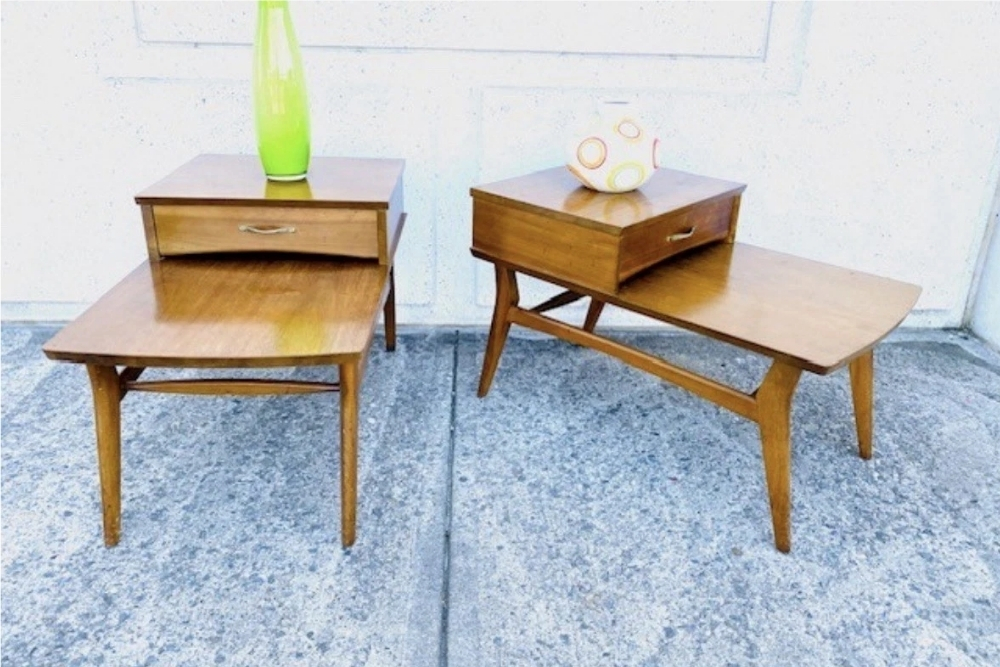
Mersman step and nesting tables

Pair of Mersman two-tier wooden step tables with drawers and tapered legs
Image Credit: yovi_shoppe via eBay

Mersman Bros. Corporation ran an Ohio table factory dating back to 1905 and became one of the most prolific occasional table manufacturers in American history, which means most of what the company made is common enough today to be worth very little. An ordinary Mersman lamp table or step table in typical condition sells for $20 to $75, and that’s the honest outcome for the vast majority of examples still floating around.

The exception is the boomerang-leg, amoeba-top design that shows up occasionally in Mersman’s mid-century output, with a sculptural asymmetrical shape that looks nothing like the company’s more common lyre-base and plain round tables. These genuinely collectible examples are priced well above the typical range by the dealers who specialize in them, though confirmed sold prices for this specific variant are harder to pin down than for the more common forms.

Check the underside or a drawer bottom for a paper or stamped “Mersman” label, often paired with a model number. Because the company produced so much generic furniture, condition matters less to price here than simply having the right, sought-after shape in the first place: a pristine plain Mersman table is still a plain Mersman table, while a boomerang-leg example with some wear is still the one collectors are actually looking for.

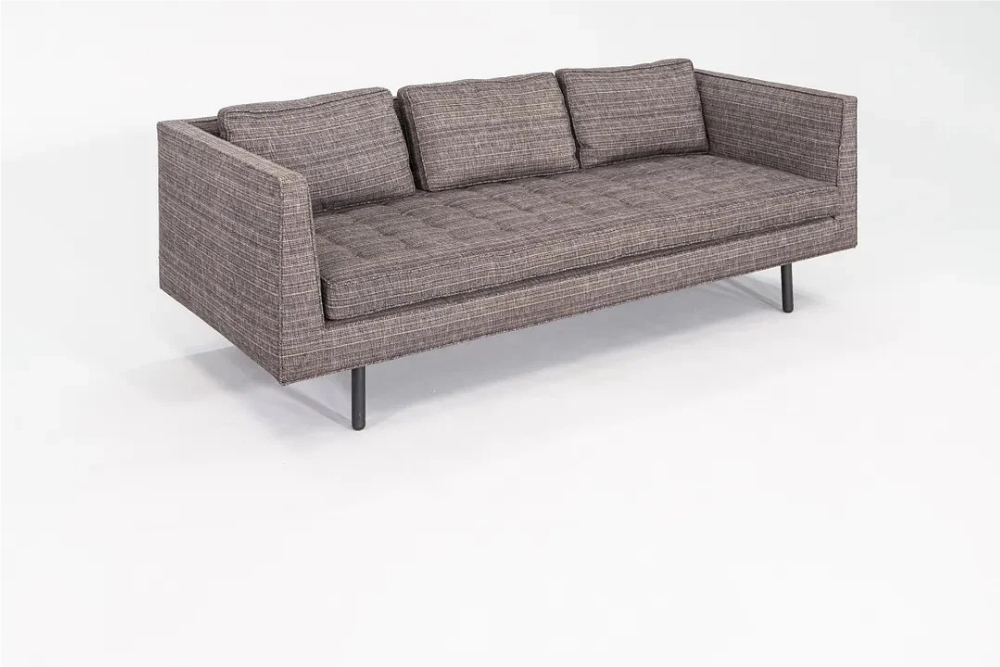
Dunbar sofa by Edward Wormley

Edward Wormley Dunbar three-seat sofa with gray upholstery and slender metal legs
Image Credit: d-rose-mod via eBay

Edward Wormley spent 37 years as Dunbar Furniture’s lead designer out of Berne, Indiana, turning out roughly two small-batch collections a year, each averaging about 100 pieces, with clients able to customize finishes and wood veneers. That low-volume, high-quality approach is exactly why Dunbar furniture holds value today in a way a lot of mass-market mid-century seating doesn’t.

A standard sofa in good original upholstery and a sound lacquered wood base typically brings $2,500 to $4,500, with unusual forms like the tete-a-tete sofa occasionally reaching $8,000 to $10,000. Wormley introduced the Janus collection in 1957, one of several distinct design lines within the Dunbar catalog that collectors use to date and authenticate a piece today.

The manufacturer’s fabric, printed with a repeated “Dunbar” pattern, is usually visible on the underside once you lift a seat cushion, which is the fastest way to confirm you’re looking at a real example rather than a Wormley-style knockoff. Original foam that’s still soft rather than crumbling, intact original pillows, and a lacquered base with no major repairs all matter here. Light scuffing on the legs from normal use is expected and doesn’t hurt value much. Torn or heavily soiled upholstery and a sagging or structurally unsound frame do.

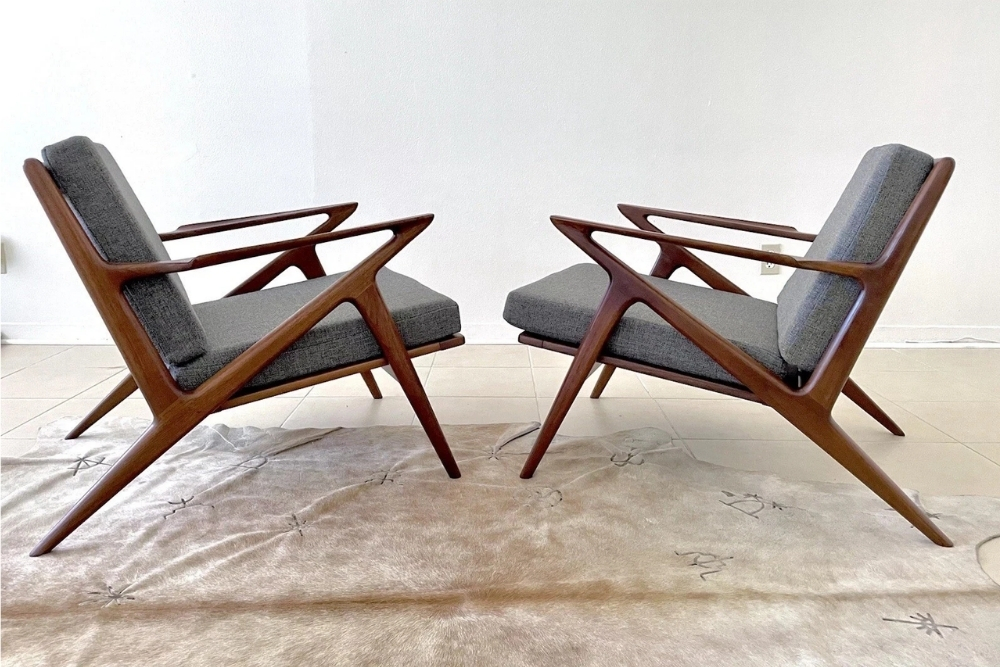
Selig Z-chair

Pair of Selig Z lounge chairs with angular wooden frames and gray cushions
Image Credit: phantomsigna1 via eBay

The Z-chair’s cantilevered seat, floating on a Z-shaped frame with no visible legs at the front, made it an instant visual signature when Selig Manufacturing started importing it from Denmark in the late 1950s. The design is credited to Poul Jensen on a 1957 patent filing, though the attribution has long been disputed among collectors and historians, which is itself a point of genuine debate rather than settled fact.

Pricing on this one swings hard depending on restoration. A single chair with an altered or sandblasted frame and later upholstery sells for as little as $400 to $600, while a professionally restored pair in walnut typically brings around $6,400. Nearly every surviving example has been reupholstered or refinished at some point, so original fabric or leather in good condition is genuinely rare and commands a real premium over a redone chair.

Check for the original “Selig” stamp on the frame before paying a premium price. This is one of the most heavily knocked off mid-century chairs on the market right now, sold new under half a dozen different brand names at a fraction of what an authenticated vintage example brings, and dealers also openly sell “Poul Jensen style” reproductions that look nearly identical but carry a fraction of the resale value. If a listing doesn’t mention the Selig stamp specifically, assume it’s a reproduction until proven otherwise.

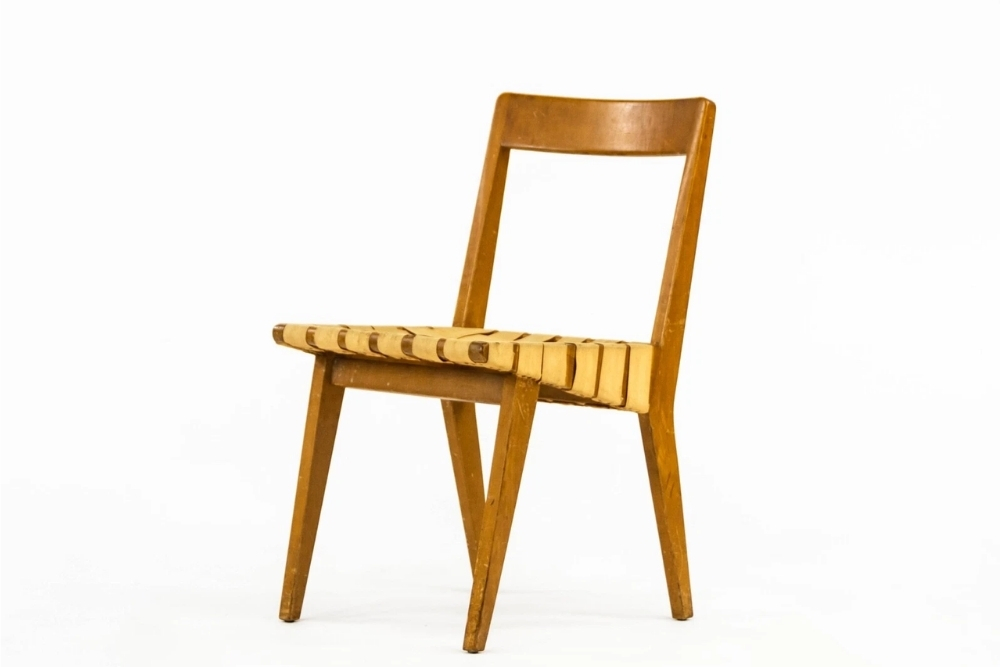
Jens Risom 666 chair for Knoll

Jens Risom Knoll wooden chair with a woven webbing seat
Image Credit: d-rose-mod via eBay

Jens Risom’s 1942 furniture line for Knoll was the company’s first commissioned collection, built out of wartime necessity from scrap wood and rejected parachute nylon webbing that couldn’t be used for its intended purpose. The resulting woven strap seats and backs became Risom’s signature look, and the 666 model, in both dining and lounge forms, is the piece most commonly found today.

A set of four dining chairs in good original condition typically brings around $1,625, while a single chair with some wear and an altered finish sells for considerably less, closer to $400. The low end of that range reflects just how many of these survive: Knoll produced the line for years, and it was popular enough that originals show up regularly at estate sales and smaller regional auctions rather than only at specialist dealers.

Look for the original Knoll Associates fabric label or decal, usually stamped on the frame underside or along the rear selvage of the webbing. The webbing itself is the first thing to fail on these chairs: sagging, staining, or replacement strapping in a non-original material or color all reduce value, as does a refinished or sandblasted birch frame. Knoll still sells a current “Risom Collection” of authorized reissues, clearly marked as new production, so don’t mistake a brand-new Knoll piece for a vintage original just because the Risom name is attached.

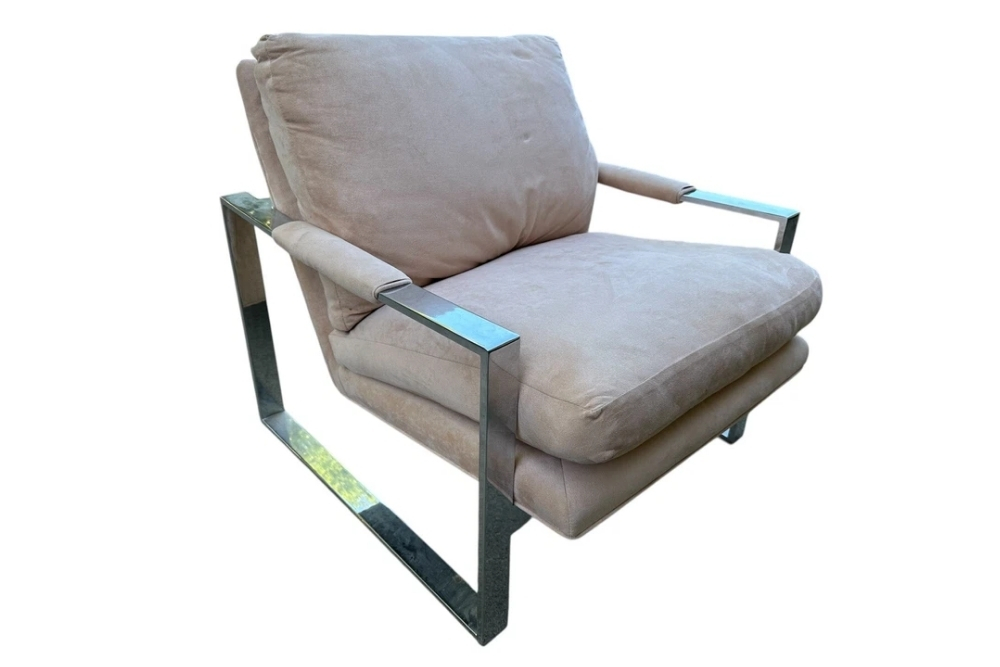
Milo Baughman lounge chair for Thayer Coggin

Milo Baughman lounge chair with a chrome frame and pale upholstered cushions
Image Credit: wfaa8 via eBay

Milo Baughman and furniture manufacturer Thayer Coggin began working together in 1953 on a handshake deal that ran for roughly fifty years, making Baughman’s chrome-framed lounge chairs and sofas some of the most widely produced American mid-century seating around. The partnership’s longevity is part of what makes authentication a little tricky, since Thayer Coggin still builds some of these designs today to the original specifications.

A pair of lounge chairs in good, original condition typically brings $3,000 to $7,000 for the pair, or roughly $1,500 to $3,500 each, with rare documented models occasionally reaching into five figures. A single chair in decent shape but without matching documentation runs closer to $1,200 at retail. Heavily worn or reupholstered examples in unoriginal fabric sell for considerably less than either figure.

Every genuine piece should carry a Thayer Coggin tag stamped or sewn to the frame underside, but because the company still manufactures some of these chairs new, the tag alone doesn’t confirm vintage age. Check the hardware style, the fabric, and the foam type as secondary cues, since older examples tend to have heavier, more age-appropriate chrome plating and foam that’s started to compress or yellow. Chrome pitting and oxidation are common and expected on a genuinely old piece. Sagging or replaced upholstery in clearly modern fabric is the bigger value concern.

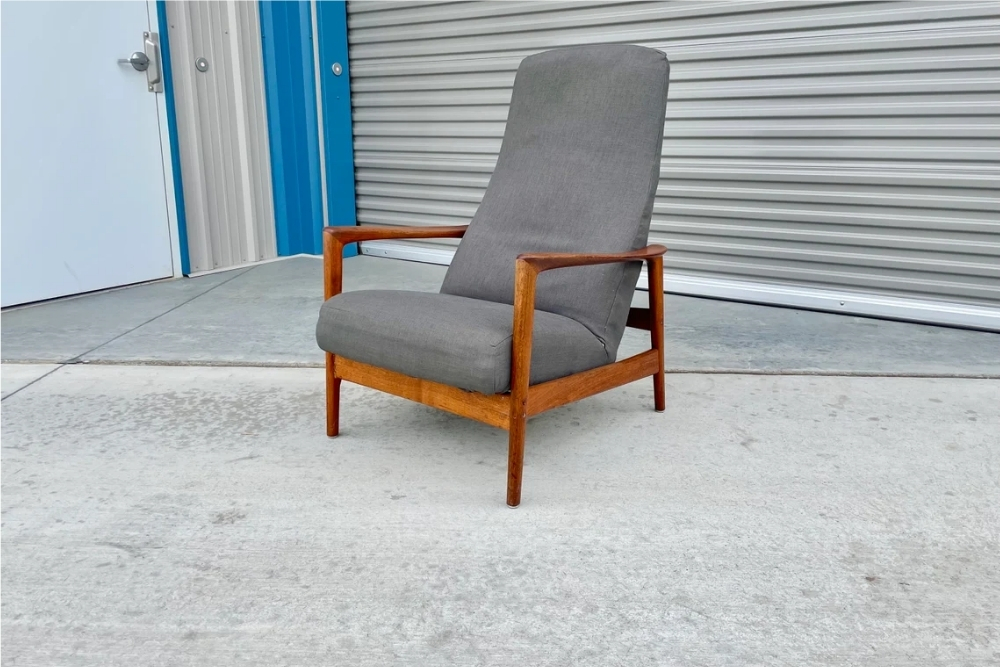
Dux recliner by Folke Ohlsson

Folke Ohlsson Dux recliner with gray upholstery and a walnut frame
Image Credit: MidCenturyNoHo1 via Etsy

Folke Ohlsson designed for Swedish manufacturer Dux starting in the early 1950s and personally moved to the United States in 1950 to pitch American retailers using miniature models of his furniture, a sales approach that worked well enough to make Dux a recognizable household name within a few years. His patented knock down construction, which let the chairs ship and store flat, kept costs down and helped the line spread well beyond the design conscious buyers who usually sought out Scandinavian imports.

A single recliner in teak, walnut, or beech with its original leather or fabric typically brings $1,200 to $1,500 in clean condition. A matched pair with ottomans in good shape typically brings $3,400 or more, and sets with working mechanisms and intact upholstery sell for considerably more than one with a broken recline function.

Look for a manufacturer’s label on the underside identifying the specific recliner model. The recline and rock mechanism matters more to the price than cosmetic wear does: pilling, light staining, or dust on the upholstery are minor and expected, while a mechanism that doesn’t function properly or a misaligned ottoman support knocks the price down more noticeably, even if the wood and upholstery are otherwise in good shape.

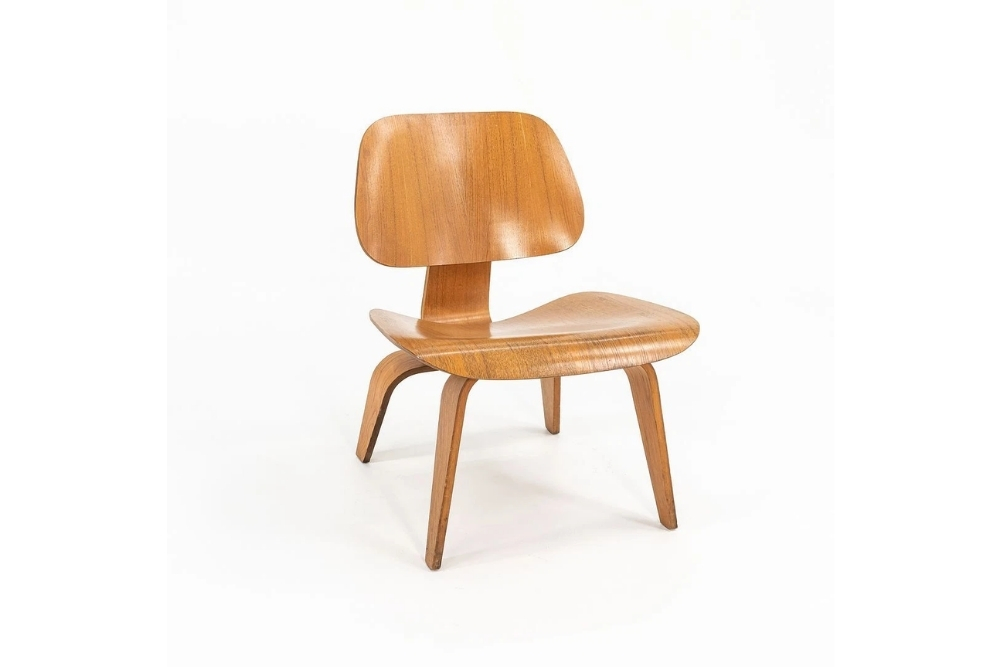
Eames molded plywood lounge chair

Eames LCW molded plywood lounge chair in calico ash
Image Credit: d-rose-mod via eBay

Charles and Ray Eames designed the molded plywood lounge chair in 1945, and it debuted at the Museum of Modern Art the following year to the kind of reception that gets a chair called the best design of the 20th century by Time magazine decades later. Evans Products Company manufactured the earliest examples under license before Herman Miller took over production directly, and the chair has stayed in continuous or near continuous production ever since in one form or another.

That long production run is exactly why price expectations need to be realistic here. Clean, authenticated early examples typically sell for $650 to $850, not the much higher figures sometimes seen on dealer retail markups without a documented sale behind them. Herman Miller and Vitra are currently the only two authorized manufacturers of the design, so a brand new “Eames LCW” sold by anyone else isn’t a legitimate reissue regardless of how it’s marketed.

Early examples carry a specific five screw, two screw, five screw pattern on the back where the shock mounts attach, along with a period label reading “Manufactured by Evans Products Company” rather than a modern Herman Miller tag. Delamination between the plywood layers, cracked veneer at stress points, and loose or sheared shock mounts are the serious value killers. Minor edge nibbles or a small split at the back of the seat are normal wear for a chair this age and don’t meaningfully hurt the price.

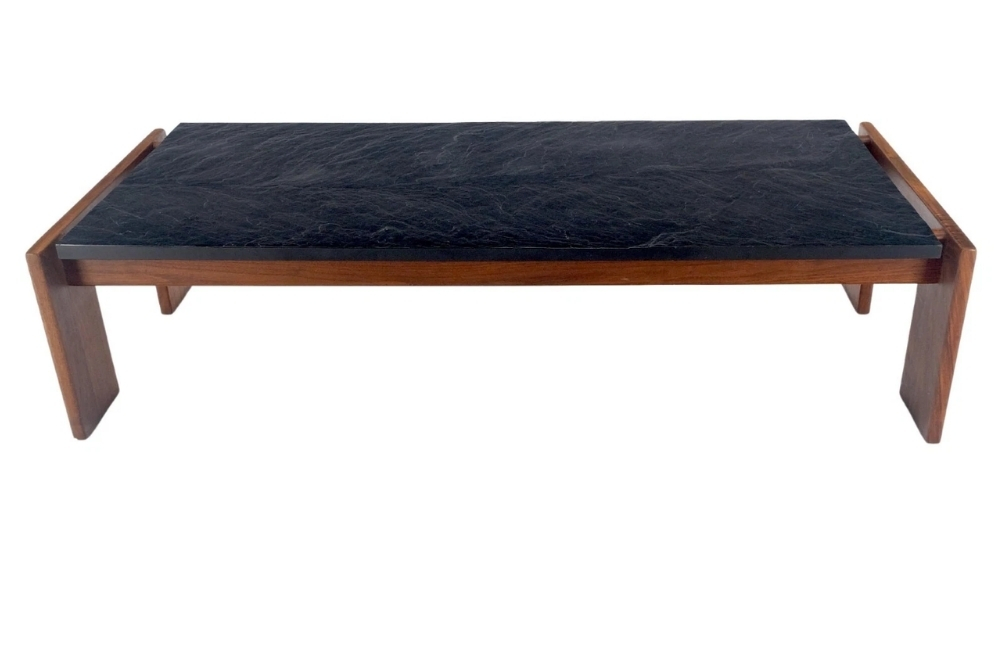
Adrian Pearsall walnut and slate coffee table

Adrian Pearsall rectangular coffee table with a dark slate top and sculpted walnut frame
Image Credit: establishedlines via eBay

Adrian Pearsall trained as an architectural engineer before founding Craft Associates in Kingston, Pennsylvania in 1952, starting out in wrought iron before shifting to the sculptural, biomorphic walnut designs he’s best known for by the late 1950s. His coffee tables, built around a carved walnut base topped with slate or glass, are some of the most recognizable and frequently reproduced pieces of the whole mid-century walnut category.

A clean example in good structural condition typically brings $600 to $1,900, with most well-preserved pieces landing closer to $1,000 to $1,500. The spread depends heavily on the base’s condition and whether the top is genuine slate rather than a cheaper laminate version that circulates under the same model names.

One detail worth knowing before you pay a premium for a “signed” example: Pearsall didn’t sign his own work, so a signature on a table is a red flag for misattribution rather than confirmation of authenticity. Listings hedged with language like “attributed to” or “in the style of” aren’t confirmed originals and should be priced accordingly. Oiled walnut dries out and grays over time, which is normal and fixable with re-oiling rather than a real flaw. Loose joints on the sculptural base need regluing, and chips at the edges where a glass top rests against the walnut are common and worth checking closely before you buy.

Walk into a Home Depot most weekday mornings and the employee walking you to the paint aisle might already be collecting a pension. That isn’t a coincidence or a fluke of local hiring. It’s the result of a hiring strategy specific companies have run for more than two decades, and it’s getting more deliberate, not less.

In 2025, 19.1% of Americans 65 and older were in the labor force, working or actively looking for work, up from 12.9% in 2000. Separate research from AARP found that 7% of retirees 50 and older had un-retired in just the past six months, and 48% of them said the main reason was simple: they needed the money.

Money is the loudest reason, but it isn’t the only one. Plenty of retirees go back for the schedule, the conversation, or the simple fact that thirty years of waking up with somewhere to be doesn’t just switch off because a pension started. None of that requires apologizing for it. It also doesn’t mean taking just any job that will have you.

The employers actually doing the hiring right now cluster in a handful of predictable places, retail and education among them, and a few genuinely unexpected ones. Retail is the easiest place to start, mostly because it’s the one most companies have been doing on purpose the longest.

Retail sales floors want them back

Retail worker using a handheld scanner at a grocery checkout
Image Credit: Shutterstock

Home Depot has spent more than two decades recruiting workers over 50, after partnering with AARP in 2004 to help fill tens of thousands of store positions, and the company still shows up on nearly every list of age-friendly employers. CVS Health runs a similar effort called Talent Is Ageless, built to recruit pharmacy support staff, customer service reps and retail associates who are 50 or older, with flexible scheduling options like telecommuting and job sharing built in.

These aren’t isolated examples. AARP relaunched its corporate outreach in March 2026 as the Employer Alliance, and more than 160 companies signed on in the first several months, each committing to at least one concrete step toward hiring and keeping older employees rather than a symbolic pledge alone.

For a retiree, the appeal of the sales floor is mostly logistical: shifts are short, part-time schedules are normal, and the work doesn’t require relearning a career. Retail associates also get first pick of employee discounts and, at bigger chains, benefits that kick in well before 30 hours a week. It’s not glamorous work, and the pay rarely cracks $20 an hour to start. But for someone who wants structure, a paycheck, and conversation that isn’t with the television, it’s one of the easiest doors back into the workforce.

Classrooms are calling retired teachers back

Mature teacher speaking with students indoors
Image Credit: Shutterstock

School districts have spent the past several years rewriting rules that used to punish retired teachers for coming back. Missouri’s legislature passed a law letting retired educators substitute without forfeiting their pension checks, after state data showed over two-thirds of substitute roles in the state were already filled by people 50 and older. Georgia, Michigan and West Virginia have pushed similar fixes, mostly aimed at the same problem: not enough qualified people willing to run a classroom on short notice.

The pay won’t replace a pension. Missouri substitutes typically earn between $101 and $125 a day, and the lawmakers who pushed the fix openly admitted a retiree drawing an average $3,800 monthly pension could lose money by returning under the old rules. What substitute teaching actually offers is control: pick your days, pick your grade level, and walk away at 3pm without homework to grade.

For a career teacher who retired and immediately missed the classroom, it’s close to the easiest re-entry there is. No new credential is required beyond a background check, and districts are hungry enough that nobody stops to ask why there’s a year or two missing from the resume.

Real estate rewards a second career

older real estate agent handing over keys
Image Credit: Shutterstock

Real estate has become one of the most common landing spots for people who didn’t plan to retire into real estate. The median age among real estate agents nationally is 60, and just 6% say the business was their first career.

Part of the draw is obvious: nobody assigns an agent a schedule. Part of it is less obvious. Buyers and sellers tend to trust an agent who sounds like they’ve lived a full life already, and decades spent in an unrelated career, finance, teaching, construction, whatever it was, often translate directly into credibility with clients navigating the biggest purchase of their lives.

Getting licensed takes 45 to 60 hours of coursework plus a state exam, a real time investment but nothing close to a second degree. The catch is the one every agent eventually learns: income is commission-only, so the first six months to a year can be lean while a new agent builds a client base. For a retiree with savings or a spouse’s income to lean on, that runway is manageable. For someone who needs a paycheck immediately, it’s a harder sell than most jobs on this list.

Bank lobbies still need a human face

Bank teller serving a customer across the counter
Image Credit: Shutterstock

Teller jobs are shrinking nationally as banking moves online, with the Bureau of Labor Statistics projecting a 13% decline in the role through 2034. That sounds like a reason to skip this one, except the decline is slow and the turnover in the meantime is constant, which means branches are hiring more often than the long-term trend suggests.

The median teller salary was $39,340 a year as of May 2024, with plenty of part-time positions that pay by the hour and don’t ask for a finance background. Banks train tellers on the job, typically under a more experienced colleague, and the core skills, patience, basic math, and the ability to stay pleasant with a difficult customer, are exactly what a lot of retirees spent a career building in some other industry.

It’s steady, indoor, air-conditioned work with a schedule that rarely runs past bank hours, which makes it an easy fit for someone who wants structure without standing on their feet all day. The ceiling is low. The floor is reliable.

Home care agencies are desperate for steady hands

older home aide worker
Image Credit: Shutterstock

Home health and personal care aides make up one of the largest occupations in the country, and agencies cannot hire fast enough to keep pace with an aging population that overwhelmingly wants to stay in its own home rather than move into a facility. The median pay was $34,900 a year as of May 2024, which is modest, but the entry bar is low: most states require nothing more than a high school diploma, with training layered on afterward.

Retirees are a natural fit for a job that rewards patience over credentials. Many have already done this work informally, caring for a spouse or an aging parent, and agencies increasingly recruit directly from that experience rather than from a traditional applicant pool. Hours are flexible, assignments range from a few hours a week to full-time live-in care, and pay climbs with certification as a nursing assistant or with specialized training in dementia or hospice care.

It is physically and emotionally demanding work, more so than most jobs on this list, and it is not a fit for everyone. But for a retiree who wants purpose as much as a paycheck, it is one of the most in-demand jobs in the entire economy right now.

Massage therapy pays better than people expect

older Massage therapist
Image Credit: Shutterstock

Massage therapy is one of the better-kept secrets on this list. The median pay was $55,310 a year, with employment projected to grow 18% over the decade, far faster than most occupations, and that’s before counting tips, which many therapists earn on top of their base rate.

Training typically runs through a postsecondary program rather than a full degree, and requirements vary by state but usually involve several hundred hours of coursework and a licensing exam. That’s a real commitment, but it’s measured in months, not years, and many massage schools specifically market toward career-changers in their 50s and 60s.

Many massage therapists are self-employed, which means a retiree can build a client list slowly, work out of a spare room or a shared studio space, and set hours around the rest of life rather than the other way around. It’s physical work that demands strong hands and the stamina to stay on your feet, so it suits a retiree in good health more than one managing chronic pain. For the right person, it’s a second career that pays as well as the first one did.

Notarizing loans pays surprisingly well

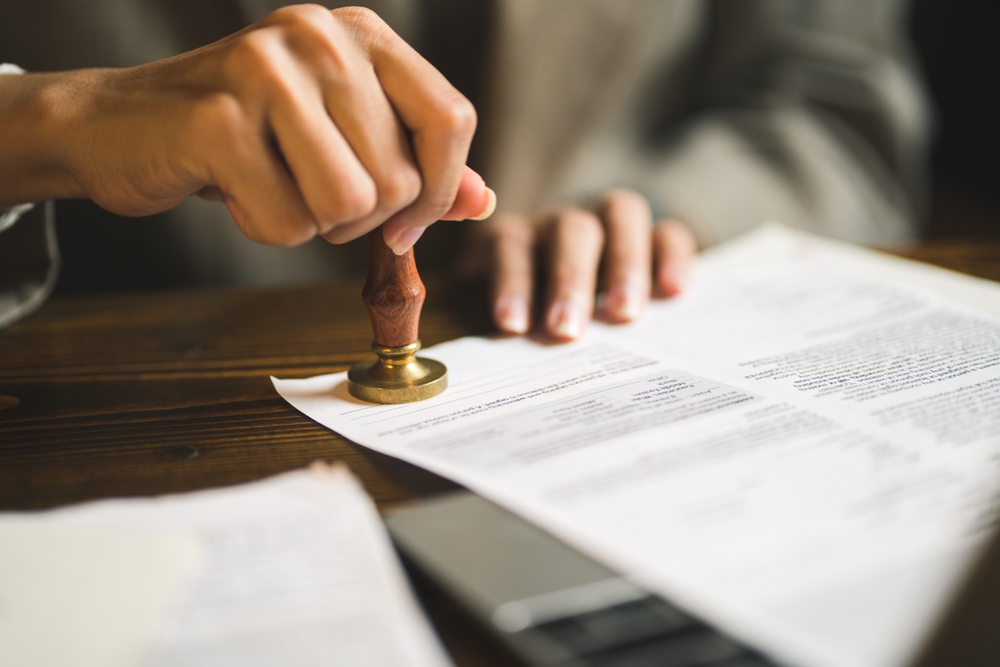
Hands pressing a wooden-handled stamp onto a legal document on a desk
Image Credit: Shutterstock

Barbara Hill wanted something flexible to ease into retirement, and found it by accident: a bank sent a loan signing agent to her New Jersey home to walk her through paperwork on a home equity loan, and the woman mentioned she was supplementing her Social Security doing exactly that job. Hill got curious, got certified, and now makes about $66,000 a year as a notary loan signing agent, a role that requires no college degree at all.

The job itself is simple: a notary public who has taken additional training sits with borrowers while they sign mortgage paperwork, verifying identity and making sure every required signature and initial lands where it should. Getting started means obtaining a state notary commission, then specialized signing agent training, which typically costs a few hundred dollars and takes a few weeks.

Pay runs anywhere from $75 to $200 per appointment, and a well-trained agent can typically complete one in under an hour. It won’t replace a corporate salary overnight, and building a steady pipeline of signings through title companies and signing services takes time. But for a retiree with a car, a printer, and a willingness to hustle a little, it’s one of the highest-paying jobs on this list relative to the barrier to entry.

Airlines want flight attendants with life experience

older flight attendant
Image Credit: Shutterstock

Flight attending might be the least expected entry on this list, but airlines have been actively courting older applicants for years. Instructors who prepare candidates for airline hiring say carriers increasingly ask for what they call golden candidates, prospective flight attendants 40 and older whose life experience makes them better at defusing a difficult passenger or calming a nervous flier than a 22-year-old fresh out of training.

There is no federal mandatory retirement age for flight attendants in the United States, unlike pilots, who must stop flying commercially at 65. Flight attendants earned an average of $63,760 a year as of the most recent government data, and the hiring process, while competitive, does not screen out applicants based on age.

The catch is the schedule. New flight attendants almost always start on reserve, meaning they’re on call to cover whoever else can’t work a given shift, which can mean odd hours and little advance notice. It’s a demanding second act for someone who already raised a family and built a first career, but for a retiree who genuinely wants to travel and doesn’t mind irregular hours, it’s a legitimate path back into full-time work.

School buses need drivers more than ever

School bus driver smiling through the window of a yellow school bus
Image Credit: Shutterstock

School bus driver employment was still 9.5% below 2019 levels as of August 2025, even as districts raised wages to compete for workers, a shortage serious enough that transportation departments nationwide now run recruitment events built specifically around convincing nervous applicants that driving a 40-foot bus isn’t as intimidating as it looks.

Retirees are one of the groups districts lean on hardest to cover open routes, alongside students, caregivers and people with disabilities who want part-time, scheduled hours. A bus contractor in Waukesha, Wisconsin recently offered $25.50 an hour with 25 guaranteed paid hours a week and 40 hours of paid training, no commercial driving experience required going in. “We’ve got students, single moms and dads, we’ve got retirees, people who are in school, this works perfectly for them,” one of the company’s drivers told the local Fox affiliate.

The schedule is the real selling point: morning route, afternoon route, summers off, and nothing to do with the bus in between. For a retiree who already knows how to manage a bus-load of chaos from raising their own kids, or who just wants part-time hours that match a school calendar, it’s one of the more reliably available jobs on this entire list.

Hospitals pay a premium for per diem nurses

mature nurse in a hospital
Image Credit: Shutterstock

Nursing has a staffing shortage that has outlasted the pandemic that made it famous, and one of the main ways hospitals cover open shifts is per diem, or PRN, work: shifts posted as needed and picked up by nurses who want flexibility over a fixed schedule. Retired nurses are an obvious fit, since they already hold a license and need no retraining to walk back onto a unit.

Per diem nurses are typically paid a higher hourly rate than staff nurses doing the same job, since the trade-off is no benefits and no guaranteed hours. Staffing agencies recruit specifically from the pool of retired RNs and LPNs, placing them in hospitals, clinics and home health settings for however many shifts a month they want to work.

It’s not a low-commitment job. Per diem nurses still do the full job, administering medication, monitoring patients, responding to emergencies, with none of the institutional hand-holding a staff nurse gets. For a retired nurse who misses the work itself more than the schedule that came with it, it’s close to a direct return to the career they already had.

Gyms are hiring fitness instructors over 60

Older yoga instructor leading a group of women through a seated side stretch in a bright studio
Image Credit: Shutterstock

SilverSneakers, the fitness program available through many Medicare Advantage plans, actively recruits and certifies instructors well past the age most gyms consider hireable. Several of its own instructors got certified for the first time at 63 and 75, after careers that had nothing to do with fitness: one spent 36 years in academic libraries, another 38 years in retail.

Certification runs through organizations like the American Council on Exercise or the Athletics and Fitness Association of America, typically a self-study program followed by a proctored exam, plus CPR and AED certification. It’s a real time investment, but it doesn’t require a degree, and fitness instructors average around $75,000 a year.

The appeal for an older instructor goes both ways. Class participants, who are often in their 60s, 70s and 80s themselves, tend to trust an instructor who understands joint pain and balance issues firsthand rather than one reciting modifications from a manual. For a retiree who already loves the gym and wants to bring other older adults along with them, teaching is a natural next step, not a stretch.

Dog walking turns into real income

Dog walker holding leashes and waste-bag dispensers while walking five dogs along a city pavement
Image Credit: Shutterstock

Pet ownership keeps climbing, and so does demand for someone to walk the dog while its owner is at work. Pet-sitting platforms like Rover market directly to retirees as an ideal fit, and dog walkers can earn up to $1,000 a month or more, with top earners doing considerably better by adding boarding and overnight sitting to the mix.

There’s no licensing requirement and almost no startup cost beyond a phone and comfortable shoes. The bigger platforms handle the background checks, client matching and payment processing, which removes most of the friction of starting a small business from scratch. Many retirees stack a few services together, daytime walks during the week, weekend boarding, occasional overnight house-sits, to smooth out the income.

It’s low-impact exercise with a built-in social benefit, since regular clients tend to become familiar faces rather than one-off transactions. For a retiree who already has the daytime availability that younger walkers don’t, it’s one of the simplest side incomes on this list to start.

Golf courses hand the keys to retirees

Rows of blue golf carts parked outside a clubhouse among palm trees
Image Credit: Shutterstock

Golf course managers have relied on retirees to fill starter and ranger positions for decades, mostly because the timing works out: golf season typically opens in early spring, before students are available for summer work, leaving a staffing window that retired golfers have filled for years.

The jobs themselves are simple. Starters send groups off the first tee on schedule, and rangers patrol the course in a cart keeping pace of play moving and enforcing basic rules, like no coolers and no sneaking onto the back nine without paying. Pay at public and semi-private courses typically runs $14 to $14.50 an hour, though many positions include free or discounted golf as part of the deal.

For someone who already spent decades playing the game, it’s close to the easiest transition on this list: no training beyond a short orientation, no new skill to learn, and daily proof that showing up pays off in more than just a paycheck. Courses tend to prize these hires specifically because retirees bring stability that teenage summer staff can’t, and fewer seasons spent retraining a revolving door of new hires.

Stadiums are full of retired ushers

older usher
Image Credit: Shutterstock

June Palm is 95 years old and has worked as an usher at Wrigley Field for 27 years, the oldest and longest-serving member of a crew the Chicago Cubs openly describe as mostly retirees. “We have quite a few retirees,” the team’s assistant director of guest services told the station, and Palm is far from the only one wearing the uniform into her 80s and 90s.

Ushers and ticket takers at ballparks and arenas nationwide do the same basic job: scan tickets, point people toward their seats, keep an eye out for trouble, and answer the same ten questions over and over with a straight face. Pay typically runs between $12 and $18 an hour depending on the venue, and shifts are tied to the event calendar rather than a fixed weekly schedule.

It won’t replace full-time income, and the standing, stair-climbing and occasional bad weather rule it out for some retirees. But for a sports fan who wants a reason to be at every home game without paying for a ticket, it’s one of the more enjoyable part-time jobs a retiree can find.

National parks pay seasonal guides to talk

National park ranger
Image Credit: Shutterstock

The National Park Service hires seasonal park guides every year to lead visitors on walks, answer questions and keep groups safe, and the job listing specifically counts volunteer experience, teaching, environmental education and tour leading toward the qualifications, which makes it an unusually accessible federal job for a retiree with the right background.

Seasonal guides typically start in spring and work through the busy summer months, guiding small groups on short walks or larger groups on longer interpretive programs. The positions come with a uniform requirement and, at some parks, access to subsidized government housing, which matters in parks located far from any town.

It’s not a year-round paycheck, and competition for popular parks, think Yellowstone or the Grand Canyon, can be steep. But for a retiree who already spent a career as a teacher, naturalist or tour guide, and who wants to spend a summer somewhere spectacular while getting paid instead of just visiting, it’s one of the more unusual jobs on this list, open application cycles permitting.

Crossing guards earn more than minimum wage

older crossing guard
Image Credit: Shutterstock

School crossing guard postings across the country explicitly list retirees as ideal candidates, right alongside stay-at-home parents, and the pay is better than the job’s reputation suggests. National data puts the median wage at $21.42 an hour, and individual listings bear that out: a district outside Boise pays $18.50 an hour, one in Tiburon, California pays $21 an hour plus bonus pay.

The job itself is exactly what it sounds like: stand at a designated crosswalk before and after school, stop traffic, and get kids across safely. Shifts run two hours a day split between morning and afternoon, which works out to real money for very little time commitment, and the schedule follows the school calendar exactly, meaning summers, snow days and holidays off.

There’s no training beyond a short orientation, no degree, and no experience required, just reliability and the willingness to stand outside in all weather twice a day. For a retiree who wants a few hundred dollars a month and a built-in reason to interact with the neighborhood kids, it’s about as low-stress a job as exists on this list.

Call centers are quietly age-friendly

Mature customer-service representative wearing a headset while using a laptop
Image Credit: Shutterstock

Customer service and call center work has become one of the more age-friendly corners of the job market, mostly because it rewards exactly the traits that come with decades of work experience: patience, clear communication and the ability to stay calm with someone who is furious about their cable bill.

CVS Health’s Talent Is Ageless program specifically routes some of its older recruits into telecommuting customer service roles, letting employees work from home with the kind of schedule flexibility in-person retail can’t offer. Major employers that have signed AARP’s employer pledge, including Google, CVS and Macy’s, list many of their phone-based and remote support roles under the same age-inclusive hiring push.

Most of these jobs require nothing beyond basic computer literacy and a quiet space to take calls, and training is provided on the employer’s own systems and scripts. The pay is modest compared to the jobs above it on this list, but the remote flexibility is hard to beat for a retiree managing health issues, caregiving duties or simply a preference for working in slippers rather than a uniform.

Amazon built a warehouse program around RVers

Warehouse worker wearing a hard hat and high-visibility vest beside stocked storage shelves
Image Credit: Shutterstock

Amazon runs a seasonal hiring program called CamperForce, built specifically around retirees and other RV owners willing to park at a campground near a fulfillment center for a few months and work the holiday rush. The company pays camping fees for the season, which runs from early fall through just before Christmas, and offers the same hourly pay, overtime and completion bonuses as other seasonal warehouse hires.

The program has grown well beyond its original handful of participating warehouses; this year Amazon offered CamperForce positions at 27 facilities across the country. Workers pick, pack, stow and receive packages during 10- to 12-hour shifts, the same physically demanding work as any other fulfillment center associate, just done by people who go home to an RV instead of an apartment.

It’s not easy work, and Amazon doesn’t pretend otherwise: the shifts are long, the pace is set by machines, and the job has drawn real criticism over how physically taxing it is for an older workforce. But for retirees who already live the RV lifestyle and want a few months of steady, well-compensated work with their camping fees covered, it has become one of the more distinctive jobs a retiree can pick up, by design.

None of these eighteen jobs will replace a career salary, and most were never meant to. What they offer instead is the thing a lot of retirees discover they miss most: somewhere to be, and someone who’s glad they showed up.

The first holiday season after a separation can feel like one long negotiation. Who gets Thanksgiving? Where will the kids wake up on Christmas? How do you handle a family gathering when it falls during your ex’s parenting time?

Even years after divorce, holiday co-parenting can stir up sadness, frustration, and pressure to make everything magical.

You don’t have to recreate your old family celebrations or make every relative happy. You can build a holiday season that gives your children stability, connection, and room to enjoy both parents.

In Soberlink’s holiday divorce guide, divorced mom and podcast host Andrea Rappaport and family law attorney Leanne Townsend share practical ways to approach the season. Here’s how to put their advice to work.

Make your holiday parenting plan early

Townsend’s first recommendation: Work out the schedule well before the holidays.

Before booking travel or accepting invitations, review your parenting agreement and confirm the details with your co-parent. Think beyond who has which day. Discuss pickup times, transportation, school breaks, and any special events.

If both parents value the same holiday, Townsend suggests alternating years as one possible approach. Another family might celebrate on different days.

The goal is a clear plan that works for your children. A Christmas celebration on December 26 can still include pancakes, presents, and a movie marathon.

Once plans are settled, explain them to the kids in simple, age-appropriate terms. Knowing what to expect can spare them the uncertainty of wondering where they’ll be.

Let go of everyone else’s expectations

Your mother wants the grandchildren at dinner. Your ex’s family has an annual party. You want to keep a tradition you’ve loved since childhood.

Those wishes matter, but they don’t all have to become obligations.

Rappaport encourages parents to distinguish between what must happen and what someone would like to happen. Missing one gathering doesn’t mean you’re letting your family down.

Give relatives the schedule early, and resist the urge to defend every decision. You can say: “The kids will be with their dad that day. We’d love to celebrate with you the following weekend.”

Address alcohol concerns before celebrations begin

For some families, holiday stress includes concerns about a parent’s drinking during time with the children.

In the guide, Townsend discusses alcohol monitoring as a way to document sobriety when alcohol use is a concern or an accusation in a custody dispute.

Soberlink breathalyzers aren’t your average run-of-the-mill alcohol testing device. These are high-tech devices with built-inuses a handheld breath-testing device, facial recognitionidentity verification and, tamper sensors, so your co-parent can’t manipulate the results. After each scheduled test, the systemand automatically sharesd the results with specified contacts, so they have instant proof of sobriety and peace of mind that their kids are safe under their co-parent’s supervision. to help document sobriety. Those records can give parents concrete information rather than leaving them to rely on reassurance alone.

Concerned about a co-parent’s alcohol misuse during holiday parenting time? Learn how Soberlink’s family law alcohol monitoring program works.

Keep communication brief and focused

Holiday logistics can quickly turn into arguments about your entire relationship. An email about pickup time doesn’t need to revisit last year’s disappointments.

Rappaport recommends keeping communication brief, informative, friendly, and firm.

For example: “The school concert is Thursday at 6 p.m. It falls during your parenting time. I plan to attend and wanted to confirm whether you’re bringing the kids.”

Before sending an angry message, pause. Rappaport uses a ranking exercise to decide which issues deserve attention. Ask yourself how much this disagreement matters and how escalating it might affect your children.

Save your energy for issues that have a meaningful effect on their well-being.

Create traditions that fit your family now

You may miss the holidays you once imagined. Your children might, too. New traditions can make room for joy while you’re adjusting.

Rappaport describes decorating her apartment for Hanukkah with her boys and making charitable giving part of their holiday wish lists.

Your tradition can be inexpensive and easy to repeat:

  • Drive around to see holiday lights with hot chocolate.
  • Cook a favorite breakfast together.
  • Let each child choose a holiday movie.
  • Donate toys or volunteer as a family.

A familiar activity, repeated with love, can become something your children look forward to every year.

Give your kids permission to feel sad

A fun holiday can still include disappointment. Your child may miss their other parent, an old tradition, or having everyone together.

Rappaport recommends acknowledging those feelings instead of trying to talk children out of them.

Try: “I understand why you miss that. What would help this year feel special?”

They don’t need to perform happiness to protect you. Keep adult disagreements out of those conversations, and let them enjoy their other parent without feeling guilty.

Your holidays will evolve as your family does. Planning ahead, making space for feelings, and addressing genuine concerns can help everyone settle into the season.

If alcohol concerns are complicating your co-parenting plans, explore Soberlink’s options for documenting sobriety during parenting time.

The forehead is one of the first parts of the face where repeated movement becomes visible. Every time someone looks surprised, frowns, concentrates, or raises the eyebrows, the skin folds along familiar paths. At first, those marks disappear when the expression stops. With time, however, changes in collagen, elastin, hydration, sun exposure, and genetics can leave lines visible even while the face when relaxed.

Some are mainly movement-related, while others reflect accumulated skin damage and structural aging. The most useful approach begins by identifying what is contributing to the lines rather than trying to fill, relax, or resurface every forehead in the same way.

What causes deep forehead wrinkles?

Deep forehead wrinkles usually develop through a combination of repeated muscle contraction and gradual changes within the skin. The frontalis muscle lifts the eyebrows and creates horizontal forehead lines. Nearby movement in the glabella contributes to vertical creases between the brows, particularly with frowning or concentration.

Several factors can make those lines more pronounced:

  • repeated facial expression and frequent raising of the eyebrows;
  • loss of collagen and elastin with age;
  • ultraviolet exposure and damaged skin;
  • genetics and individual skin type;
  • smoking, stress, dehydration, and other habits.

Dynamic lines become visible mainly during movement, whereas static wrinkles remain when the face is relaxed. A line that once diminished can gradually become permanent as the skin becomes less elastic and less able to recover from repeated folding.

Skin care for forehead lines

A consistent skin care routine cannot stop facial movement or erase every crease, but it can improve moisture balance, texture, and the appearance of early lines. A moisturizer helps retain water in the outer layers of the skin, while selected active ingredients may support smoother texture and collagen-related processes over time.

Products commonly considered in an anti-aging routine include:

  • retinoids or retinol, depending on tolerance;
  • moisturizer selected for the individual type of the skin;
  • antioxidants such as vitamin C;
  • peptides in suitable formulations;
  • broad spectrum sunscreen with SPF 30 or higher.

Introducing too many strong products at once is a common error. Irritation can make the forehead look rougher rather than smoother, so active ingredients are usually added gradually. Anyone with sensitive skin, persistent irritation, pregnancy, or a skin condition should discuss stronger products with a dermatologist before changing the routine.

Learn what causes forehead wrinkles and how to reduce their appearance with skincare, professional treatments, and preventive habits.

Sun protection and prevention

Daily protection is one of the more useful steps for prevention because ultraviolet radiation breaks down collagen and adds to premature aging. Sunscreen should be combined with shade, hats, and an effort to avoid deliberate tanning. Protection is relevant even when wrinkles are already visible because further UV exposure can continue to affect the skin.

Adequate rest, regular exercise, and a balanced diet support the body and general skin health, although none will make established wrinkles fade on their own. Lifestyle factors work best as part of a broader routine rather than as a substitute for treatments aimed at muscle activity or structural skin changes.

The best way to reduce forehead wrinkles

The best way to reduce forehead wrinkles is dependent on whether the problem is mainly muscle movement, surface damage, loss of elasticity, or a combination of these. A dermatologist or qualified aesthetic practitioner can assess the face both at rest and during expression to identify which mechanism is most responsible.

For example, movement-related horizontal lines often respond better to neuromodulators than to a cream. Fine surface lines and uneven skin texture may improve with resurfacing technologies, while deeper static wrinkles sometimes need more than one technique. Cost, recovery time, type of the skin, desired result, and tolerance for repeated procedures also influence the choice. A restrained combination can sometimes improve several causes at once without overcorrecting one feature.

Botox and other neuromodulators

Botulinum toxin treatments are widely used for forehead lines because they temporarily relax the muscles responsible for repeated folding. Small injections into selected points reduce contraction of the frontalis and related muscles, allowing the overlying skin to appear smoother.

Among the neuromodulator options available to clinics, Innotox for sale at Dkdermal is a practical choice for professional use. It fits naturally into aesthetic practice where product quality, reliable sourcing, and consistent handling matter.

Injecting too much or choosing the wrong points can affect the position of the eyebrows, which is why forehead treatment should account for the balance between the frontalis and muscles around the glabella and eyes. Someone who relies strongly on the forehead to raise a low brow may need a different plan from a person with higher resting brows.

Botox and similar products usually provide temporary improvement rather than a permanent change. The effect develops over several days and generally lasts for a few months before muscle activity gradually returns.

Cosmetic procedures for forehead wrinkles

Muscle relaxation is only one option. When skin quality itself is contributing to visible lines, cosmetic procedures designed to stimulate renewal or collagen production may be more appropriate.

Lasers and resurfacing technologies

Laser resurfacing uses controlled energy to create changes in the skin and stimulate new collagen formation. Depending on the technology and intensity, treatment can address fine wrinkles, uneven pigmentation, rough texture, and some forms of sun damage.

Options may include:

  • ablative laser resurfacing;
  • non-ablative lasers;
  • fractional resurfacing;
  • chemical peels;
  • microneedling or other collagen-stimulating devices.

The stronger the resurfacing procedure, the more carefully recovery and risk need to be considered. Some lasers carry a greater chance of pigment changes in darker skin tones, while deeper resurfacing may involve more downtime. A responsible provider should match the technology to the patient’s skin rather than choosing a device simply because it is newer.

Fillers for static wrinkles

Dermal fillers can sometimes be used when a forehead crease remains visible at rest, although this area requires particular caution because of its vascular anatomy. Fillers do not stop the frontalis muscle from contracting; instead, they add material beneath a crease or restore support where appropriate.

For that reason, a filler may occasionally be combined with a neuromodulator rather than used alone. The goal is not to completely fill every line. Careful assessment is especially important on the forehead, where injection-related vascular complications can be serious.

Brow lift and surgical options

A brow lift addresses a different problem from ordinary wrinkle treatment. When low or descending eyebrows, excess upper-face skin, and deeper forehead creases occur together, lifting the brow can change both eyebrow position and forehead tension. Surgery may produce a more substantial structural change than injectable procedures.

A surgical brow lift is generally considered when:

  • eyebrow descent is pronounced;
  • forehead skin has significant laxity;
  • non-surgical treatments cannot address the main concern;
  • the patient is comfortable with recovery and surgical risk.

There are also nonsurgical approaches sometimes described as a chemical brow lift, using botulinum toxin to alter the balance of muscles around the eyebrows. These effects are temporary and much more subtle than surgery.

Preventing forehead wrinkles from becoming more visible

Not every contributing factor can be changed. Genetics, natural aging, facial structure, and the way someone instinctively moves the face all play a role. Still, prevention can slow avoidable damage and help maintain the result of professional procedures.

The practical priorities are straightforward: use reliable sun protection, avoid tanning, moisturize consistently, choose ingredients appropriate for the skin, and limit habits that accelerate skin aging. Trying to consciously stop every facial expression is neither realistic nor necessary.

When lines become deeper despite good daily care, professional assessment can help determine whether the next step should target muscle movement, surface texture, collagen loss, or brow position. The right choice is usually the one that addresses the actual cause while keeping the forehead expressive, balanced, and firm rather than simply making every visible line disappear.