Building an asset portfolio starts with setting clear family priorities. Parents need to decide whether monthly income or future equity matters most. Aligning decisions with long-term plans prevents unnecessary financial stress.
Building an asset portfolio starts with understanding personal capacity. Reading a negatively geared property explained allows families to evaluate standard tax structures before purchasing real estate. Clear targets simplify choosing between capital growth and immediate cash returns.
Every household faces different debt tolerances and time horizons. Short-term wins may look attractive, but steady growth creates lasting security. Written goals keep buyers focused during property searches.
Assessing family budgets and cash flows
Understanding current spending habits protects family stability during property acquisitions. Running real numbers prevents unexpected shortfalls when hidden repair costs pop up. Detailed budget reviews reveal how much extra mortgage payment a household can handle.
Mortgage repayments, maintenance fees, and council rates add up quickly. Keeping a separate emergency fund protects family savings from sudden property expenses. Smart budgeting creates a buffer against rising interest costs.
Tracking core monthly expenses provides clarity before talking with mortgage brokers:
Fixed household bills like utilities and insurance
Discretionary spending on travel and entertainment
Regular contributions to high-yield savings accounts
Evaluating long-term asset growth potential
Purchasing real estate demands a long-term mindset rather than quick speculative trading. Property values move in cycles over multi-year periods. Holding assets through market fluctuations builds meaningful equity for future generations.
A recent financial article reported that family investors prioritizing long-term capital growth saw an average annual asset appreciation rate of 6.3 percent over a ten-year holding window. This steady return highlights why patience pays off when building wealth for children. Parents can leverage steady value growth to fund future education expenses.
Targeting locations with steady growth history protects capital investment. Solid historical performance indicates strong demand from local tenants and buyers. Buying in proven suburbs offers stable returns over decades.
Selecting suitable neighborhoods for suburb value
Location drives demand and overall tenant retention rates. Buying near top-rated schools, parks, and public transport hubs attracts quality long-term renters. Family-friendly areas maintain high demand even during market downturns.
Researching local council infrastructure plans reveals upcoming area upgrades. New shopping centers, road expansions, or school upgrades boost local appeal. Investing near planned amenities helps boost asset growth as years pass.
Visiting neighborhoods at different times of the week shows true local activity. Clean streets, active parks, and low vacancy signs indicate a healthy rental market. Local observations give buyers confidence before submitting purchase offers.
Managing household risk and interest rates
Interest rate changes directly impact monthly rental cash flows. Preparing for rate adjustments keeps mortgage payments manageable under shifting market conditions. Conservative stress-testing prevents budget pressure when rates increase.
Risk mitigation strategies help protect family finances against sudden economic changes:
Choosing fixed-rate mortgage options for predictable payments
Setting up offset accounts to minimize loan interest charges
Diversifying financial assets reduces dependence on a single property market. Maintaining cash reserves provides flexibility during tenant vacancies or unexpected repairs. Proactive risk management keeps investment stress away from family life.
Image Credit: Thirdman via Pexels
Assembling a reliable professional advisory team
Navigating real estate transactions requires expertise across multiple disciplines. Building a team of trusted specialists saves time and prevents expensive mistakes. Qualified advisors guide buyers through complex legal and tax requirements.
Mortgage brokers locate competitive loan terms tailored to family budgets. Property managers handle tenant screening, rent collection, and routine maintenance requests. Skilled accountants streamline tax deductions to maximize net returns.
Working with experienced professionals allows parents to focus on daily family life. Regular check-ins with advisors keep financial plans on track. Good guidance turns complex property ownership into a manageable routine.
Planning exit strategies and asset transfers
Establishing clear exit strategies protects wealth accumulated over decades. Parents must decide when to hold, refinance, or sell assets as retirement approaches. Clear plans keep family wealth aligned with changing lifestyle needs.
Refinancing properties allows owners to access equity without selling assets. Retaining real estate provides ongoing rental income during retirement years. Transferring property ownership to children requires careful estate planning to minimize tax burdens.
Reviewing financial plans annually maintains alignment with personal milestones. Adapting strategies as family needs evolve keeps investments working efficiently. Well-planned wealth transfer creates lasting stability for future generations.
Building a property portfolio requires patience, clear budgeting, and solid research. Parents who take structured steps position their families for lasting financial independence.
Starting with clear goals allows mothers to navigate real estate with confidence. Small, well-planned investments today can secure financial freedom for years to come.
Running a family business means taking care of every digital asset, including your main website address. Moving your web address to a new provider feels overwhelming when daily sales rely on continuous uptime and smooth customer access.
Taking organized steps protects your site revenue and keeps your family brand accessible online. Simple planning makes web address migration smooth and stress-free for your entire team.
Before initiating any transfer request, you must change your domain security status inside your current account settings. Domain registrars keep security locks active on all web addresses to prevent unauthorized transfer attempts by unknown parties.
Log in to your current control panel and locate the domain management tab. Turn off the registrar lock toggle so system requests can move forward to the next step.
Leaving this lock turned on stops the migration process immediately and creates unnecessary technical delays. Disabling the lock opens the path for your new provider to request account control on your behalf.
Obtaining the transfer authorization code
Every registrar requires a unique authorization code to approve a domain relocation request. This special string of letters and numbers acts as a temporary security key for your web address.
Finding this authorization key takes just a few minutes inside your management dashboard. Selecting reliable domain transfer services helps business owners learn how to transfer a domain when retrieving passcodes from account panels. You will copy this passcode directly from your current manager into your new destination portal.
Keep this authorization code private during the entire transition process. Sharing secret security strings publicly creates severe safety risks for your primary business digital assets.
Checking administrative contact information
Transfer verification notices travel directly to the primary administrative email listed on your public account profile. Outdated contact emails prevent you from receiving and approving transfer requests sent by system administrators during the account move.
Review all contact fields before submitting any technical requests:
Primary administrative email address
Technical manager contact details
Organization telephone contact number
Physical company mailing location address
Updating contact records guarantees that system verification messages arrive without unexpected delays. Clean contact files keep your transfer moving forward without administrative holds or lost confirmation emails.
Many account holders forget that domain registrations list separate contacts for technical and billing roles. Checking all four contact entries in your profile makes sure every notification reaches your team without getting filtered into spam folders.
Backing up your complete DNS records
Your online shop relies on precise server records to direct customer visits and handle shopping cart checkout functions. Losing DNS settings during a transition brings your storefront down and stops customer order processing completely.
A domain management checklist recommends backing up every DNS record, including A, CNAME, MX, and TXT entries, prior to initiating any registrar move. Store these numerical IP addresses and text strings in a secure local text file or spreadsheet on your computer.
Having complete record backups allows your team to restore custom settings instantly if default settings reset. Your web pages stay visible and active throughout the administrative transition.
Managing privacy protection settings
Domain privacy services keep personal family details hidden from public registry search directories online. Active privacy shields can block validation emails sent during registrar updates as the privacy system masks the true owner email.
Turn off domain privacy features temporarily before starting your migration request. Turning off privacy allows central registries to verify your official ownership credentials without automatic system rejection.
You can turn privacy protection back on as soon as your web name moves into the new management dashboard. Keeping family details safe remains simple when you follow this proper sequence.
Image Credit: Ivan S via Pexels
Timing your domain transfer wisely
Timing plays a major role in keeping family retail operations running without sales losses. Starting a web name transfer right before high-traffic shopping days creates unnecessary business risks for your store revenue.
Select low-volume periods to initiate your account updates:
Mid-week business days with light customer order volumes
Seasonal lull periods in your regular product catalog sales
Calendar windows with at least 15 days remaining before domain expiration
Workdays when your technical support team stays available online
Avoid starting migration projects during seasonal sales or promotional email campaigns. Choosing quiet days keeps customer shopping experiences smooth and uninterrupted.
Plan your timeline so that technical steps complete long before major marketing campaigns kick off. Extra calendar buffer time protects your business revenue against unexpected registry delays.
Confirming email routing and MX records
Family businesses rely on custom domain emails to answer customer questions and send automated order receipts. Transferring a web address can disrupt mail delivery if mail exchanger records get cleared during server shifts.
Copy your existing MX records into your new host panel before authorizing the final transfer move. Matching mail records across both accounts keeps incoming messages flowing into your inbox without dropping customer correspondence.
Send test messages from external personal accounts right after making configuration updates. Quick verification testing gives your family peace of mind that customer service channels remain open for daily orders.
Store your email server IP addresses in a separate note for quick reference during setup. Having these details ready prevents misconfigured email routing when nameserver records update across global networks.
Reviewing ICANN waiting periods
International internet registry rules enforce specific time limits on web address transfers between service providers. Knowing these regulatory timelines prevents confusion when managing long-term web domains for your business.
Brand new web addresses must stay with their original registrar for 60 full days after initial registration. Names that moved to new hosts within the past 60 days sit under mandatory transfer locks enforced by policy as well.
Checking your original purchase date saves your family time during technical planning sessions. Scheduling transfers around these predefined periods prevents unexpected account freezes and rejected transfer requests.
Review your domain creation date inside your account dashboard before submitting payment to the new provider. Knowing your status helps your team set realistic expectations for project deadlines.
Moving your web address does not need to disrupt your family business operations. Following systematic steps protects your store revenue and keeps customer data safe during every step of the transition.
Proper preparation allows your online shop to shift into new account management seamlessly. Your family can remain focused on growing the business and delivering great service to your customer community.
If you’ve built your family life around spending carefully, the idea of borrowing money can feel like a small defeat. You’ve clipped the coupons, cooked from scratch, and stretched every dollar, and now something has come up that your savings can’t quite cover. It’s easy to treat that moment as a failure. It usually isn’t. Borrowing is a tool, and like any tool it can be used well or badly. The families who regret it are rarely the ones who borrowed. They’re the ones who borrowed without thinking it through.
So this isn’t a lecture about never taking on debt. It’s a practical framework for borrowing deliberately, so that if you do decide to, you make the decision with clear eyes and don’t spend the next two years wishing you’d handled it differently.
Before anything else, get honest about what you’re actually facing. There’s a meaningful difference between a genuine need and a want that has dressed itself up as urgent, and that distinction shapes every decision that follows. A broken-down car you rely on to get to work, an unavoidable medical bill, or a home repair that will get worse and more expensive if ignored are real needs with real costs of delay. A sale that ends Sunday, a vacation everyone’s excited about, or an upgrade that would be nice but not necessary are something else entirely.
This matters because urgency is the emotion that lenders and retailers most love to manufacture. The pressure to decide now is almost always working against your interests, since a genuine emergency is still an emergency after you’ve slept on it, while an impulse usually loses its grip overnight. If you can wait a day or two without real consequence, the thing probably wasn’t an emergency, and borrowing for it deserves a much higher bar. Give yourself that pause every time. It’s free, and it prevents a large share of the borrowing people come to regret.
Know what kind of borrowing you’re considering
Once you’ve decided a cost is genuine and worth borrowing for, the next question is how, because the form the borrowing takes matters enormously. Families typically reach for one of a few options, and they behave very differently. Credit cards are convenient and flexible but carry high interest and a structure that quietly encourages carrying a balance for years. Buy-now-pay-later feels painless but fragments your spending into obligations that are easy to lose track of and quick to add up. A fixed-term loan sits differently, offering a set amount, a set repayment, and a defined end date.
For a specific, one-off cost with a known price, that fixed structure often serves a budget-minded family better than open-ended revolving credit, which is why some households compare quick and easy personal loans against the credit card sitting in their wallet. A defined loan for a defined need means you know exactly what you’ll pay and exactly when it ends, which is far easier to build a budget around than a balance that lingers and compounds. The point isn’t that one product is always right. It’s that matching the borrowing type to the situation, a fixed cost to a fixed loan rather than to open credit, is one of the most important decisions in the whole process.
The numbers that actually matter
Here’s where careful families protect themselves, and it comes down to looking past the headline. The single figure lenders advertise is rarely the one that matters. What you need to understand about any personal loans you’re weighing up is the full picture, which means the interest rate, every fee attached, the total amount you’ll repay over the life of the loan, and the monthly payment measured against your actual budget rather than a hopeful version of it.
Two offers with similar-sounding rates can cost very different amounts once establishment fees, ongoing charges, and the loan term are factored in, because a lower monthly payment often just means a longer term and more interest paid overall. Always ask for the total repayable, the real number you’ll have handed over by the end, and compare offers on that basis. Watch particularly for anything that punishes you for paying early, since the ability to clear a debt ahead of schedule is worth having. None of this requires being good at math. It requires refusing to sign until you can state, in a single sentence, exactly what this will cost you in total and each month. If a lender makes that hard to work out, treat the difficulty itself as a warning.
Borrow only what the budget can absorb
Even a well-chosen loan at a fair rate can become a problem if the repayment doesn’t genuinely fit your life. So stress-test it honestly before committing. Look at your real monthly budget, the one with the grocery overruns and the kid who suddenly needs new shoes, not the tidy spreadsheet version, and ask whether the new repayment fits without squeezing the essentials. If it only fits in a perfect month, it doesn’t fit, because perfect months are rare in a family.
Just as important, leave room for the next surprise. The classic borrowing trap isn’t taking one loan, it’s taking one that consumes all your slack, so that the very next unexpected cost forces you to borrow again to cover it. That’s how a single manageable debt quietly becomes a cycle. A careful family borrows an amount that the budget can absorb with breathing room left over, and if the only way the numbers work is by assuming nothing else ever goes wrong, that’s a clear signal to borrow less, wait longer, or find another way entirely.
Protecting yourself from the regret part
The final layer is guarding against the specific things that turn borrowing into regret. Read the fine print, all of it, because the terms that hurt live in the sections people skip, covering what happens if you miss a payment, whether the rate can change, and what the fees really are. Steer well clear of payday lenders and any product promising money with no questions asked at eye-watering rates, since these are engineered to trap people in exactly the cycle a frugal family is trying to avoid. Have an exit plan before you start, knowing how and when the debt will be cleared, and ideally aiming to beat that timeline.
And hold on to the most frugal option of all, which is sometimes not borrowing at all. Waiting three months to save, buying a cheaper version, borrowing the item instead of the money, or simply going without can quietly beat any loan, however reasonable its terms. Borrowing done thoughtfully is a legitimate financial tool, and there’s no shame in using it when it’s the right call. The goal is simply to make it a decision you’ll still feel good about long after the money is spent.
This article is general information only and doesn’t take your personal circumstances into account. Consider speaking with a qualified financial counsellor or adviser before taking on debt or making borrowing decisions.
You’ve maxed out contributions when you could, paid off debt early, avoided lifestyle creep. On paper, you’ve done everything right. Then you look closely at a few of your biggest financial decisions and realize some of them have been quietly working against you the whole time.
The median 401(k) balance in America is $44,115, while the number most people picture when they hear “average” is closer to $167,970. That gap isn’t only bad luck or low pay. A lot of it comes down to specific, ordinary-sounding choices that feel careful in the moment and cost real money over the next twenty years.
None of the moves below are exotic or reckless. They’re the responsible-looking decisions that quietly drain tens of thousands of dollars from a retirement account, one reasonable choice at a time.
You leave a job, HR hands you paperwork, and one box says you can take your 401(k) balance as cash instead of rolling it into a new account. It looks like found money. It isn’t.
Researchers who tracked more than 162,000 workers leaving 28 different retirement plans found that 41.4% cashed out some or all of their retirement savings at job separation instead of rolling the balance forward. Every dollar cashed out gets hit with ordinary income tax, plus a 10% penalty if you’re under 59 and a half. A $30,000 balance can shrink by a third before it ever reaches your bank account.
The fix costs nothing and takes fifteen minutes: roll the balance into your new employer’s plan or an IRA instead of taking the check. You lose nothing by asking your new plan’s administrator to handle the transfer directly, and you keep every dollar working instead of handing a chunk of it to the IRS on your way out the door.
Claiming Social Security the day you turn 62
Image Credit: Shutterstock
Sixty-two looks like the finish line, and claiming the moment you’re eligible looks like collecting what you’ve earned. It also locks in a permanently smaller check for the rest of your life.
Full retirement age for anyone born in 1960 or later is 67. Claim at 62 instead, and your benefit is reduced for as long as you receive it, not just for a few years. Wait past 67, and you earn delayed retirement credits worth roughly 8% more for every year you hold off, up until age 70. The average retired worker collected $2,071 a month as of January 2026. That 8% a year compounds into a meaningfully larger check for however long you live.
This isn’t a blanket argument for waiting until 70. Health, other income, and family longevity all matter. It’s an argument for running your own numbers before defaulting to the earliest possible date out of habit.
Skipping catch-up contributions once you hit 50
Image Credit: Shutterstock
Turning 50 unlocks extra room in your 401(k) that a lot of people never use, mostly because nobody tells them it exists.
For 2026, workers 50 and older can contribute an extra $8,000 on top of the standard $24,500 limit, bringing the total to $32,500. If you’re between 60 and 63, the IRS lets you go even further with a “super” catch-up of $11,250 instead of the standard $8,000. IRA catch-up contributions rose too, adding $1,100 on top of the $7,500 base limit.
These are your highest-earning, closest-to-retirement years, which makes this room the most valuable stretch of contribution space you’ll ever get. Skipping it isn’t a mistake that shows up immediately. It shows up as a smaller number fifteen years later, after all that unused space has quietly disappeared. Even bumping your contribution rate by a few percentage points the year you turn 50, rather than waiting for a raise or a less busy year, adds up faster than most people expect once compounding has a decade or two to work on it.
Moving your whole portfolio to cash and bonds too early
Image Credit: Shutterstock
Getting nervous about the stock market as retirement approaches is a normal instinct. Acting on it by going almost entirely to cash and bonds in your 50s or early 60s tends to backfire.
New 2026 retirement income research found that portfolios holding 30% to 50% in stocks supported the highest safe withdrawal rates, not portfolios that went heavier into bonds and cash. The baseline safe withdrawal rate for that kind of balanced allocation sits at 3.9% for a fixed-spending retiree in 2026. Go too conservative too soon, and you remove the growth engine that’s supposed to keep your money ahead of decades of inflation and withdrawals.
There’s a middle ground between reckless and overly cautious. A retirement that could last 25 or 30 years still needs some exposure to growth, even if the split shifts gradually as you age rather than dropping to near zero the moment you stop working.
Letting required minimum distributions sneak up on you
Image Credit: Shutterstock
Required minimum distributions read like a future-you problem until future you is standing in front of a tax bill you didn’t see coming.
Under current rules, you generally have to start withdrawing from traditional IRAs and 401(k)s at age 73, a threshold that climbs to 75 by 2033. Miss the deadline or withdraw too little, and the IRS charges a 25% penalty on the amount you should have taken, cut to 10% if you fix the error within two years. Because RMDs count as ordinary income, a large one can also push you into a higher tax bracket or trigger higher Medicare premiums the same year.
The people who avoid this surprise are the ones who mark the calendar the year they turn 73, not the year the IRS sends a notice. A financial advisor or even a plan administrator can calculate the exact figure well ahead of the deadline.
Buying an annuity without reading the surrender schedule
Image Credit: Shutterstock
An annuity salesperson describing guaranteed income for life can sound like exactly what a nervous retiree wants to hear. What often gets skipped is what happens if you need that money back early.
Most fixed and indexed annuities carry surrender charges that start around 10% and shrink to zero over a schedule that can run six to eight years. Pull money out before then, and that percentage comes straight off the top, on top of a 10% IRS penalty if you’re under 59 and a half. Variable annuities add another layer of ongoing fees for mortality, expense, and administrative costs that keep charging every year you hold the contract.
Annuities aren’t automatically a bad product. They’re a bad fit for money you might need access to. Before signing anything, ask specifically how much you’d lose if you needed the funds back in year two, not year ten, and get the answer in writing rather than a verbal estimate from whoever is selling you the contract.
Treating whole life insurance as your investment plan
Image Credit: Shutterstock
An insurance agent pitching a policy that “pays a death benefit and builds cash value” is describing two different products stapled together, and the investment half is the weaker one.
The average annual return on whole life cash value runs between 1% and 3.5%, well below what a low-cost index fund has delivered over most stretches of market history. It also takes 10 to 15 years before the policy builds enough cash value to be worth borrowing against, because early premiums go mostly toward fees and commissions rather than your account balance.
Whole life can make sense for specific estate planning needs or a lifelong dependent who requires ongoing financial support. It rarely makes sense as your main retirement growth vehicle, and premiums that could have gone into a 401(k) or IRA usually would have worked harder there. If an agent frames a policy primarily as a savings or investment tool rather than as insurance, that’s a signal to get a second opinion before you commit to years of premiums.
Draining a retirement account to pay off the mortgage
Image Credit: Shutterstock
Being debt-free looks like the responsible endgame, and pulling a lump sum from a 401(k) to zero out the mortgage balance can look like the fastest route there. The bill for that decision is bigger than most people expect.
Withdraw $50,000 from a 401(k) before age 59 and a half, and you’ll automatically owe a $5,000 penalty before taxes are even calculated. On a $100,000 withdrawal taxed at a 24% federal rate plus the 10% penalty, you could lose $34,000 to the IRS and keep just $66,000 of it. That’s money that also stops compounding for whatever years remain before retirement.
If a mortgage payment actually threatens your monthly budget, refinancing, downsizing, or using non-retirement savings first usually costs less than raiding a tax-advantaged account that’s still supposed to be growing. The emotional relief of a paid-off house is real, but it’s worth pricing out against the tax bill and lost growth before deciding it’s worth the trade.
Forgetting Medicare premiums scale with your income
Image Credit: Shutterstock
Medicare Part B has a standard premium everyone assumes they’ll pay, until a bigger number shows up on the bill because of income from two years earlier.
The 2026 standard Part B premium is $202.90 a month, but income-related monthly adjustments kick in for anyone whose 2024 income topped $109,000 for single filers or $218,000 for joint filers, pushing the monthly premium as high as $689.90. Because Medicare uses a two-year lookback, a big Roth conversion or a large capital gain today can raise your premiums in a year you’re not expecting it.
This is exactly why RMDs, Roth conversions, and capital gains need to be planned with Medicare in mind, not decided in isolation. A withdrawal that looks smart on a tax return can quietly cost you thousands in higher premiums two years down the road, for a full year, since these adjustments reset annually rather than phasing in gradually.
Retiring with a credit card balance still open
Image Credit: Shutterstock
Retirement doesn’t erase existing debt, and a surprising number of retirees find that out the hard way once fixed income meets revolving interest.
A recent analysis found that 92.6% of retirement-age adults carry a credit card balance, with average APRs sitting around 21% in 2026. The 2026 Social Security cost-of-living increase came in at just 2.8%. A fixed benefit growing under 3% a year cannot outrun revolving debt priced at seven times that rate, no matter how disciplined your monthly budget is otherwise.
Paying that balance down before you retire, even if it means working a few extra months, does more for your financial security than almost any investment decision you could make in that same window. Interest at 21% is a guaranteed loss that no market return reliably beats, and treating a payoff plan as part of your retirement timeline, not a separate problem to deal with later, tends to produce a much calmer first year of retirement.
Sending your adult kids more than your own 401(k)
Image Credit: Shutterstock
Helping your kids looks like the obvious right choice, month after month, until you add up how much of your own retirement you’ve quietly redirected to theirs.
Roughly 75% of parents give some form of financial support to at least one adult child, and working parents contribute about 2.3 times more each month to their kids than to their own retirement accounts. Groceries, phone bills, and vacations add up quietly because each individual expense feels small and temporary, even as the combined total quietly outpaces what’s going into your own accounts.
Helping isn’t the problem. Helping without a ceiling is. A monthly dollar limit, tied to what you can afford after your own retirement contributions are funded, keeps generosity from becoming the reason you’re still working at 72. Framing the help as a fixed, temporary amount rather than an open-ended arrangement also tends to protect the relationship, since neither side has to renegotiate the terms every time a new expense comes up.
Never touching Roth conversions before RMDs hit
Image Credit: Shutterstock
A traditional IRA that’s grown for thirty years turns into a tax bill the government eventually forces you to take, whether or not you actually need the income that year.
Converting some of that balance to a Roth IRA during lower-income years, ideally before required minimum distributions start at 73, means paying tax on the conversion now at a rate you control, rather than later at a rate the IRS controls through forced withdrawals. Advisors who work through retirement income planning often flag the years right after you stop working and before Social Security or RMDs begin as the cheapest window to convert, since taxable income tends to dip during that gap.
This isn’t a strategy to run without guidance. Converting too much in one year can itself trigger a higher tax bracket or Medicare surcharge. Converting nothing at all just guarantees the IRS decides your tax bill for you later.
Co-signing your kid’s loan
Image Credit: Shutterstock
Co-signing looks like a formality, a signature that helps your child get approved without really costing you anything as long as they keep paying. That assumption doesn’t hold up well in practice.
About 90% of private student loans require a co-signer, and a survey of 500 parent co-signers found that 56.8% believe their credit score has been hurt by cosigning, while 51.2% said their child’s debt was putting their own retirement in jeopardy. You’re not a backup plan when you co-sign. You’re equally responsible for the full balance from day one, and a lender has no obligation to warn you before your child’s late payment shows up on your credit report.
If you’re financially able to make the payments yourself without hardship, co-signing carries less risk. If you’re not, a smaller amount you’re prepared to give outright is usually safer than a signature obligating you to an amount you can’t control.
Treating the 4% rule like a law of physics
Image Credit: Shutterstock
The 4% rule has been repeated so often it gets treated as settled fact, when the research behind it keeps shifting the number and the assumptions underneath it.
The newest retirement income research sets a baseline safe withdrawal rate at 3.9% for a fixed-spending retiree in 2026, rising to as high as 5.7% for retirees willing to adjust spending based on how markets perform. Even Bill Bengen, the researcher who created the original 4% rule in 1994, has since revised his own worst-case estimate up to 4.7%. Three credible numbers, three different assumptions, and none of them is a fixed rule that applies to every portfolio.
What matters more than memorizing a single percentage is understanding which assumptions apply to your situation, including your asset mix, how flexible your spending can be, and how much guaranteed income you already have from Social Security or a pension. Treat any single number as a starting point for a conversation with an advisor, not a fixed rule you can set and forget for thirty years.
Sitting on a mountain of cash “just in case”
Image credit: Jonathan Borba via Unsplash
An emergency fund is smart. Treating half your net worth like an emergency fund is a different decision entirely, and it has a real cost that doesn’t show up on a bank statement.
A retiree holding $100,000 in cash loses roughly $25,770 in purchasing power over ten years at 3% inflation, even while the account balance itself never drops. The interest a savings account pays rarely makes up the difference once you account for taxes on that interest. The balance on your statement stays the same. What it actually buys keeps shrinking.
Most planners suggest 12 to 24 months of expenses in cash or short-term CDs, with the rest invested in something that has a realistic shot at outpacing inflation over the decades a retirement can last. Safety and stagnation aren’t the same thing, even though they can look identical on a balance sheet, and the retirees who confuse the two often don’t notice until their spending power has already slipped.
Bottom line
Image Credit: Shutterstock
There’s one more detail worth knowing before you write off early withdrawals entirely: if you leave a job the year you turn 55 or later, the IRS’s rule of 55 lets you pull from that specific employer’s 401(k) penalty-free, though income tax still applies. It only covers the plan tied to the job you just left, not old accounts or IRAs, and it’s easy to miss if nobody mentions it.
None of this requires perfection. It just takes a five-minute check before you cash something out, sign a loan, or claim a benefit you can’t take back.
A worker earning $25 an hour who logs 10 hours of overtime a week is paid $37.50 an hour for that time right now. A bill introduced in the Senate this month would push that same hour to $50 instead, worth about $6,500 more a year for that one worker.
Senator Ruben Gallego of Arizona introduced the Double the Wage for Overtime Act on August 5, and if it becomes law, it would be the first change to the federal overtime rate since 1938. A matching bill has already been sitting in the House since June, backed by a long list of labor unions and progressive advocacy groups.
Whether any of that money actually lands in your paycheck depends heavily on your job, your current pay stub, and whether Congress can move a bill with zero Republican support anywhere close to a vote.
Federal law has required employers to pay time and a half for hours worked past 40 in a week since the Fair Labor Standards Act passed in 1938. That’s meant a worker earning $20 an hour gets $30 an hour for overtime, not $40. The Double the Wage for Overtime Act would rewrite that formula, requiring employers to pay double a worker’s regular rate, not one and a half times it, for every hour worked beyond 40 in a week.
The change wouldn’t happen overnight even if the bill passes. Employers would get 180 days to adjust payroll and scheduling before the new rate kicked in. And passing is a long way off. The Senate bill was just introduced and referred to committee, and it still needs to clear the full Senate, the full House, and get a presidential signature before it changes anyone’s paycheck.
Not everyone who works overtime is covered by this
This bill raises how much overtime pays. It doesn’t touch who actually qualifies for overtime in the first place, and that gap matters more than it sounds like it should.
Under current law, salaried workers earning less than $684 a week, or $35,568 a year, are automatically guaranteed overtime pay no matter their job title. Salaried workers earning more than that can be classified as exempt if their job involves enough management, administrative, or professional responsibility, which means they get no overtime at all, doubled rate or not.
Hourly workers are a different story. Manual laborers, including construction workers, mechanics, and factory floor employees, are guaranteed overtime under federal law no matter how much they earn, and so are police officers, firefighters, and paramedics. Their eligibility for overtime was never in question, only the rate is.
Which workers would see the biggest jump
Image Credit: Shutterstock
An estimated 13.4 million workers would benefit if this bill became law. The ones most likely to actually see that money work in jobs where overtime is routine and hard to cut: manufacturing lines, trucking and logistics, hospital floors, warehouses, construction crews, and public safety jobs like firefighting and policing.
A hospital can’t run a night shift two nurses short. A trucking company can’t always pull a second driver out of thin air. Those are the jobs where employers are more likely to keep paying overtime even at double the rate, because running short staffed costs more than the raise does.
Why some workers might not see a raise at all
Not everyone who occasionally works late is going to get a bigger check from this bill, and some workers could end up working less.
Doubling the overtime rate makes overtime a lot more expensive for employers, and businesses tend to respond to higher labor costs by avoiding them. The likeliest response is capping hours at 40 a week and hiring more part time workers to cover what’s left, instead of paying anyone double time. Something similar played out the last time federal regulators tried to expand who qualified for overtime pay in 2016, when many employers responded by capping hours instead of paying more.
Retail, restaurants, and nonprofits running on fixed budgets are the most exposed to this kind of response, since they have the least room to absorb a doubled labor cost without changing anyone’s schedule. The workers who need overtime income the most are often the ones with the least leverage to keep getting it once it costs their employer twice as much.
Where the bill stands in Congress
Image Credit: Shutterstock
The bill has real institutional backing, just not from both parties. It’s endorsed by some of the country’s largest unions, including the AFL-CIO, United Auto Workers, and National Nurses United, along with research and advocacy groups like the Economic Policy Institute and the National Urban League.
A companion bill, H.R. 9216, was introduced in the House back in June by Representatives Greg Casar of Texas, Pramila Jayapal of Washington, and Steven Horsford of Nevada. Every cosponsor on both bills is a Democrat, and the Senate version now sits in a Republican controlled committee. That combination makes quick passage unlikely, and some observers see it as more of a messaging bill meant to force a public vote than a near term path to actually becoming law.
Bottom line
Image Credit: Shutterstock
Overtime pay is already getting attention in Washington from a different angle. A federal tax deduction on overtime pay, worth up to $12,500 a year for a single filer, took effect for the 2025 tax year and runs through 2028. That deduction only shields part of what you already earn. Doubling the rate itself is a separate fight, and right now, it’s a much longer one.
Somebody’s grandmother had a cabinet full of these. Yours probably did too, stacked three deep with mismatched lids, dragged out every Thanksgiving for the green bean casserole and shoved back in a hurry once the dishes were done. CorningWare was never treated as precious. It went through dishwashers, got scraped with metal spoons, sat stacked wet in a drying rack, and did all of that for forty years without complaint. That’s exactly why the pieces that survived clean, with their original lids and their pattern still crisp, are worth real money now.
Corning Glass Works stumbled onto the material by accident in 1953, when a lab furnace overheated and produced a white glass ceramic strong enough to go from a freezer straight into a hot oven without cracking. By 1958 that accident had a name, Pyroceram, and a product line. Over the next forty years Corning ran dozens of patterns through that same durable body, some for three decades, some for a single year before they got pulled. Production length is the single biggest thing separating a fifteen-dollar casserole from a two-hundred-dollar one.
Before anything else, check the bottom of the dish. If it reads “CorningWare” or “Corning Ware” with “Made in USA” and shows a faint glow when held up to a bright light, it’s the real glass-ceramic. If it says “Not for Stovetop Use” or “Made in China,” it’s the later stoneware version, and no pattern name on it will change that.
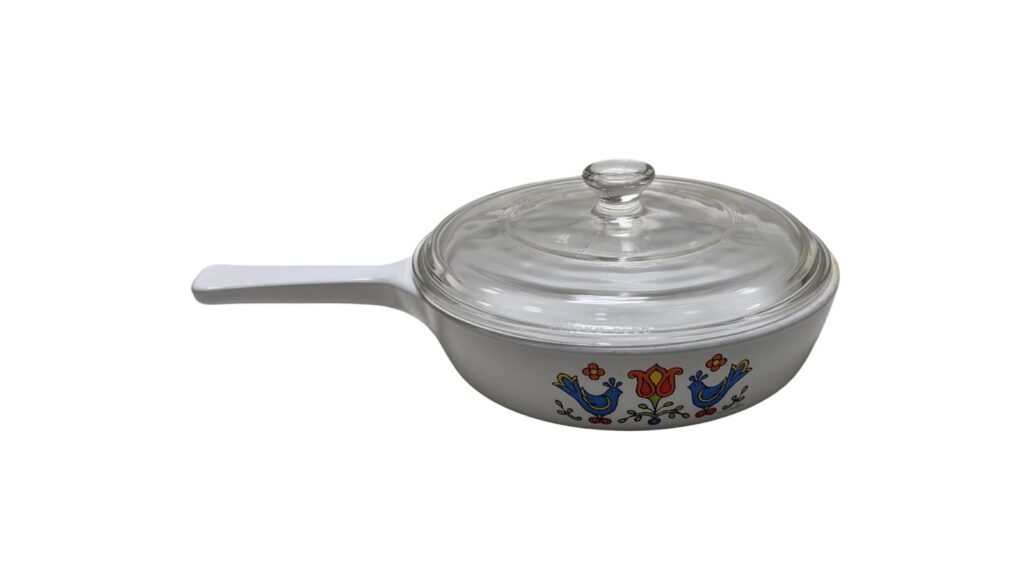
Two blue birds face each other across a spray of red and orange flowers on Country Festival, one of the easiest CorningWare patterns to spot in a box of donated dishes. Corning introduced it around 1975 as a stand-alone folk-art design that never coordinated with a matching dinnerware line, which is part of why it still turns up on its own rather than as part of a set. Collectors sometimes call it “Friendship” or the “Blue Bird” pattern, and the symmetrical, cross-stitch-style layout is unmistakable once you’ve seen it once.
This is one of the more common patterns still circulating, so don’t expect a windfall from a single casserole. Loose pieces without a lid typically bring $5 to $15, with larger sizes and pristine, unfaded print at the top of that range. The real money is in complete matched sets with every lid present, since Country Festival lids crack and go missing at the same rate as any other pattern’s. Check the print closely under good light: the blue on the birds fades fastest, and a piece with dull, grayish birds instead of clean cobalt blue has been through too many dishwasher cycles to command a premium.
French White fluted oval baker
Image Credit: Seaside Treasures Vintage via eBay
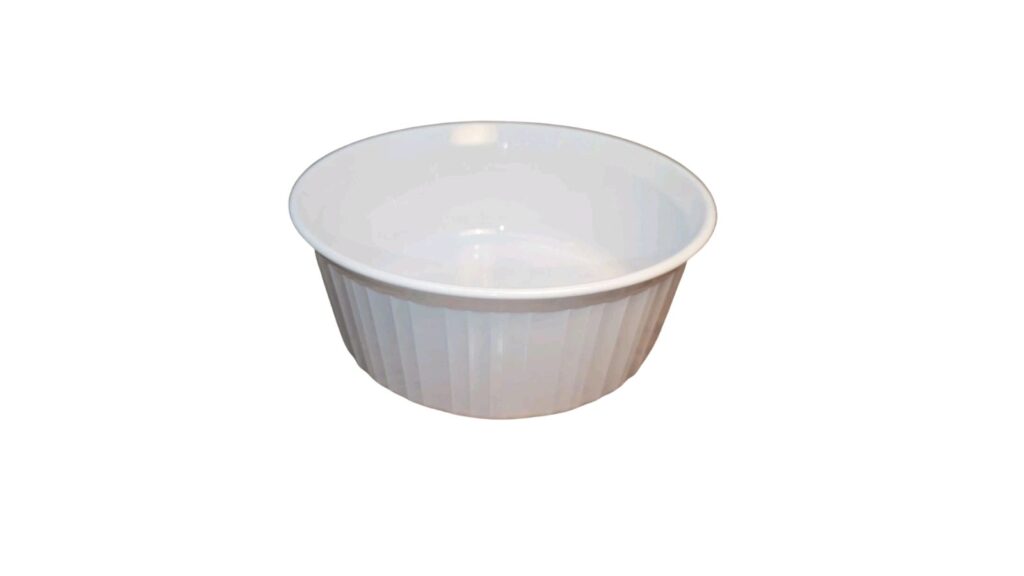
French White has no printed pattern at all, just a plain white body with embossed fluting running around the sides, which is exactly why it gets overlooked in a stack of floral casseroles. Corning introduced it in 1978 and, unlike almost everything else on this list, kept some version of it in production for decades. That means the plain white piece at a thrift store could be genuine 1980s Pyroceram or a much newer stoneware reissue, and the two are not worth the same thing.
That distinction matters more here than with any patterned piece. Vintage Pyroceram French White brings $10 to $40, with unusual shapes like the fluted oval lasagna baker or a quiche dish at the higher end and common round casseroles at the lower end. Hold the piece to a bright light: genuine Pyroceram shows a faint translucent glow, while the later stoneware version is completely opaque and usually stamped “Not for Stovetop Use” on the base. Fluting depth and sharpness matters too, since decades of scrubbing round off the embossed lines on the oldest examples. A crisp flute pattern with no chips along the rim brings more than a worn one in the same size.
Floral Bouquet gift-line casserole
Image Credit: itsgreat via eBay
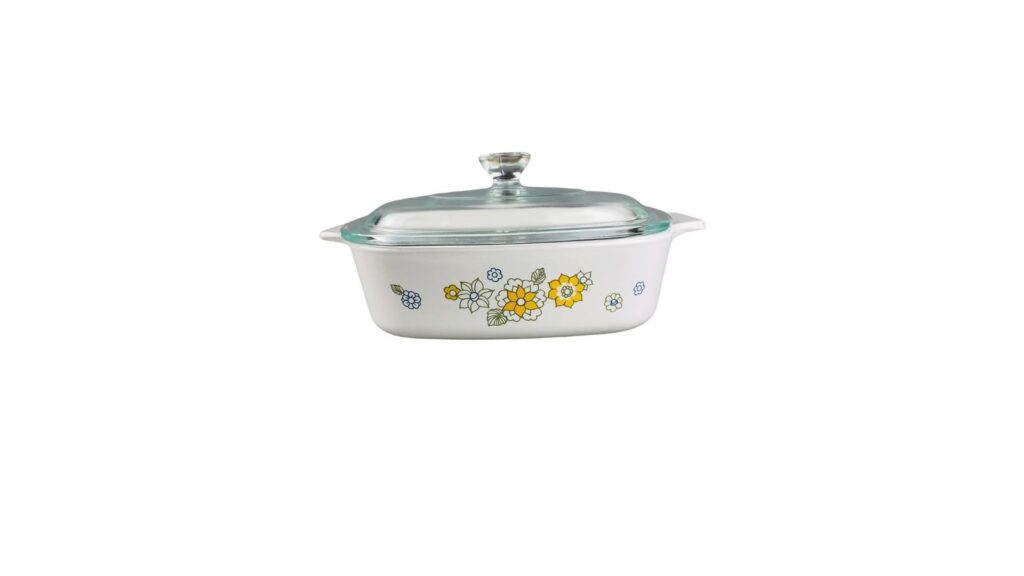
Floral Bouquet showed up first as a gift-line item in 1969 before Corning put it into general production the following year, and it reads as noticeably softer than the bold, graphic patterns that came both before and after it. Loose outlined blooms in blue and gold cluster across the white body in a hand-drawn style that lasted in production only until about 1975, a short enough run that clean examples aren’t as common as the pattern’s gentle look might suggest.
Single pieces typically bring $15 to $80, with the spread driven almost entirely by size and how vivid the gold accents still look. Because the outlines are delicate rather than bold, they show wear faster than a pattern like Blue Cornflower, so a piece with the gold still bright and unrubbed is worth meaningfully more than one where the color has gone flat and gray. Original gift-boxed sets, when they turn up complete, sit at the top of the range. As with any CorningWare from this era, a matching Pyrex lid roughly doubles what the dish alone is worth, and a missing lid is the single biggest thing capping the price.
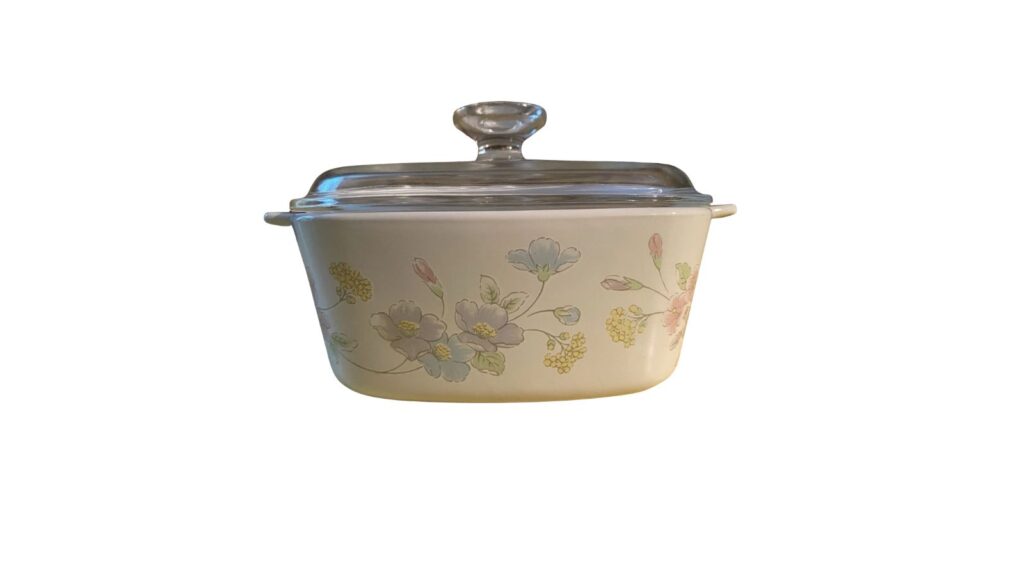
Pastel Bouquet casserole with lid
Image Credit: trainmaster2102 via eBay
By 1985 CorningWare’s florals had gone soft and pastel, and Pastel Bouquet is the clearest example: pink, blue, and lavender blossoms arranged in a lighter, airier cluster than anything from the 1970s. It ran into the early 1990s, long enough that individual pieces are genuinely easy to find, but complete matched sets with every lid intact are not.
A single casserole in clean condition brings $10 to $100 depending on size, and full sets with lids can reach $350. That’s a wide range, and the size of the piece does most of the work: small individual casseroles sit at the bottom, while a large covered roaster or oval baker with its lid intact sits at the top. Ironically, dating to the mid-1980s rather than the 1970s helps this pattern now, since 80s kitchen style has come back into fashion and buyers are actively decorating around it. Look for even, unfaded color across the whole piece and a lid that matches the dish’s exact size, since mismatched replacement lids are common and reduce value.
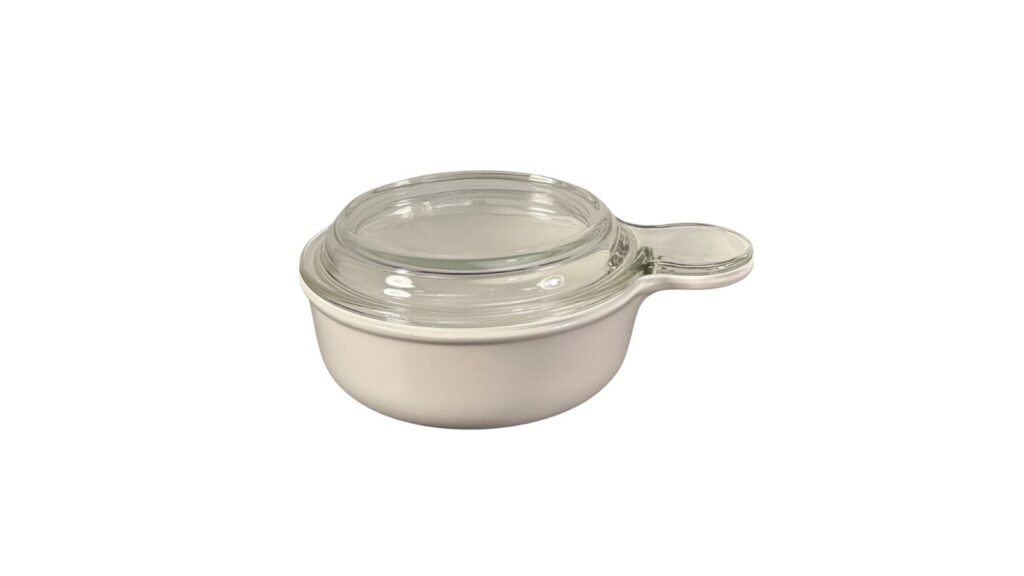
Grab-It individual serving bowl
Image Credit: Curation Collectibles via eBay
The Grab-It is a single-serving bowl with a stubby handle on one side, designed for a quick reheated lunch rather than a family dinner, and it has developed a following completely disproportionate to how humble it looks. Because it was a smaller, secondary item in most patterns rather than the main event, Grab-Its in scarcer patterns are genuinely harder to find than the casseroles that made those patterns famous.
A loose Grab-It bowl typically brings $15 to $40, but that number changes fast once the original lid, plastic or glass depending on the era, is still with it. A complete bowl and lid in a sought-after pattern has brought well over $100. The lids are the weak link: they’re thinner than the bowl itself and were treated as disposable by most households, so they cracked, warped in the dishwasher, or simply got left behind at potlucks. If you find a box of loose CorningWare at an estate sale, it’s worth digging specifically for the handled Grab-It shape, since sellers who don’t recognize it often price it the same as a common saucer.
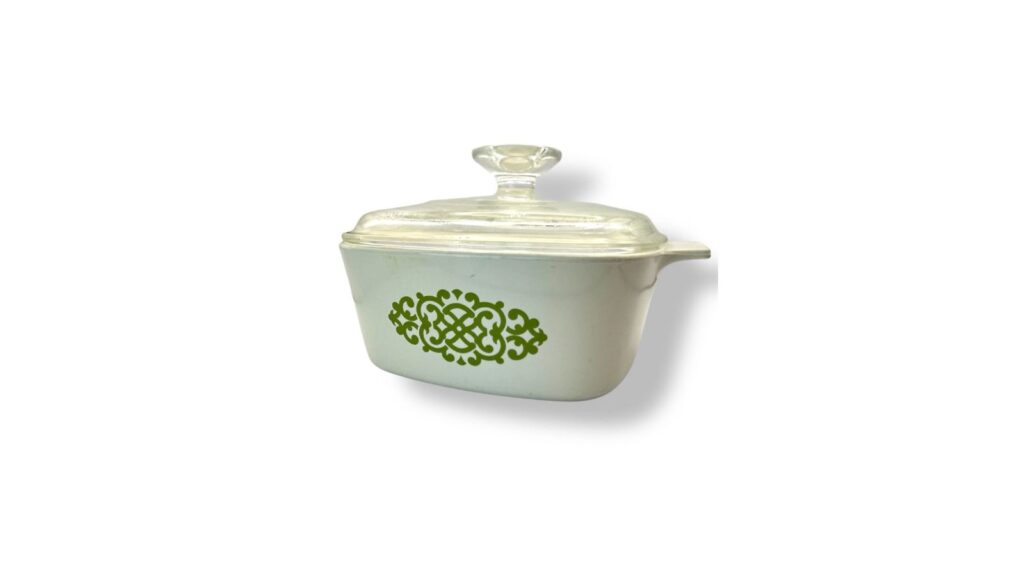
Medallion “Shell Oil” promotional casserole
Image Credit: Thrift List Sell via eBay
Medallion never went near a store shelf. Corning made it exclusively for Shell Oil, and the only way to get a piece was to be a Shell gas credit card holder in the early-to-mid 1970s, when the dishes showed up as a promotional offer tucked into the monthly bill. It came in two colorways, an olive-green stenciled geometric design and a blue version collectors call Blue Macrame, both built around interlocking lines that form the medallion shape giving the pattern its name.
Because it skipped retail distribution entirely, far fewer pieces exist than for any pattern Corning actually sold in stores, and pieces bring $30 to $100 in clean condition, with unusual forms like the open roaster bringing more. What makes Medallion a genuinely findable piece of history rather than a museum-only rarity is that it landed in ordinary households simply because they filled up their gas tank, not because anyone sought it out as a collectible. The full run of known Medallion pieces, including both the blue and green colorways, has been documented by longtime collectors, which makes authenticating a suspected piece fairly straightforward.
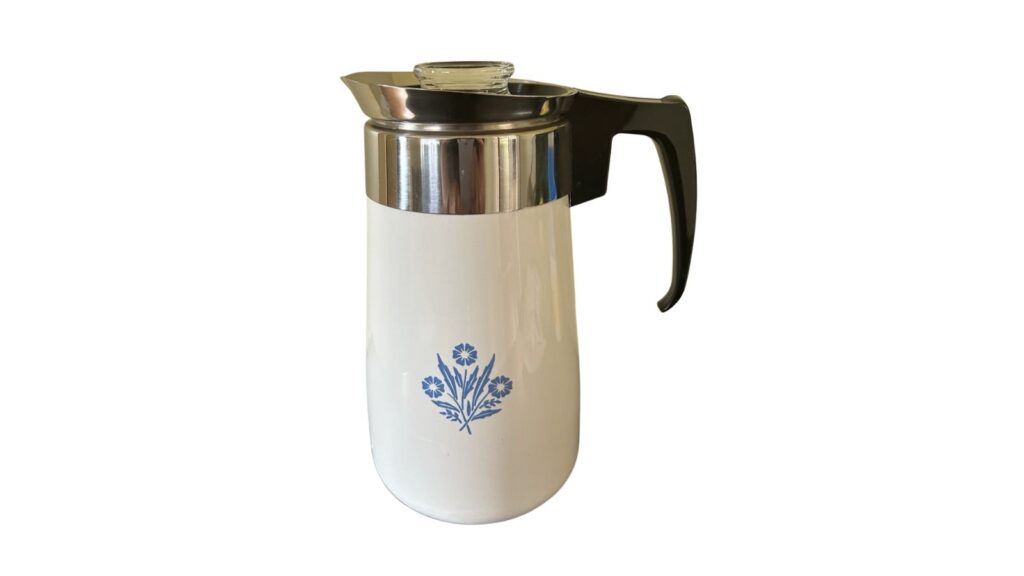
Blue Cornflower stovetop percolator
Image Credit: oldgeszer via eBay
CorningWare made a lot more than casseroles, and the Blue Cornflower stovetop percolator is proof that the flagship pattern extends well past the dish everyone remembers from Thanksgiving. Assembling a complete, working percolator is a genuinely different challenge than finding a casserole with a lid, since the glass basket, the metal stem, and the knob all had to survive together, and most surviving units are missing at least one piece.
A complete percolator brings $30 to $100 or more, with pristine, fully original examples pushing toward the top of that range and beyond. Because the internal parts are what typically go missing first, a percolator with its original glass perk knob, metal filter basket, and stem all present and undamaged is worth substantially more than an incomplete one, even if the Pyroceram body itself looks flawless. These were also functional appliances that saw daily use for years, so check the body carefully for hairline cracks near the base and confirm the cord and heating element are intact before assuming a percolator is display-only. One that still actually works is a genuine rarity at this point and worth noting separately from one that’s decorative only.
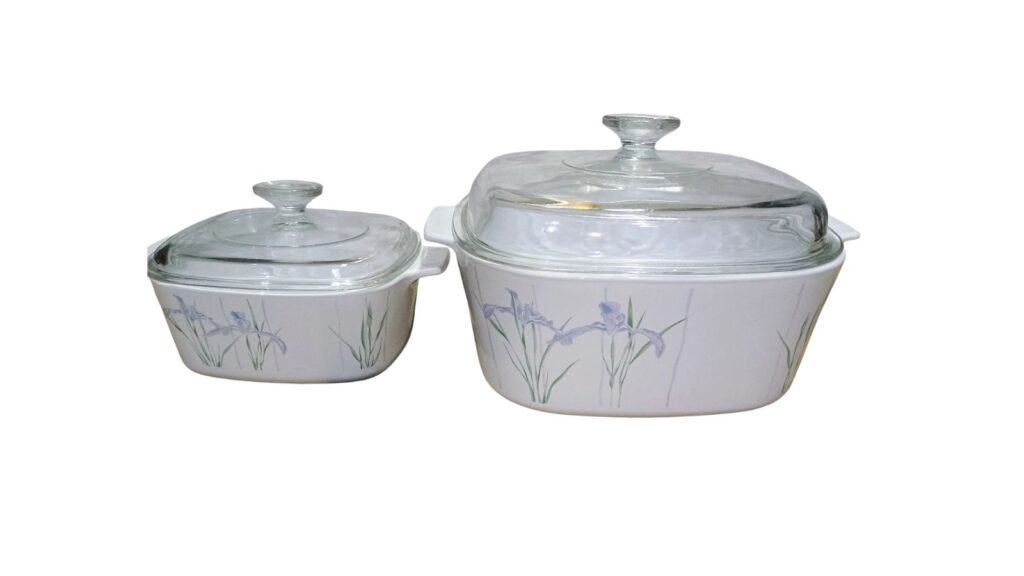
Shadow Iris casserole set
Image Credit: biglrip414ny via eBay
Shadow Iris trades CorningWare’s usual bright florals for something quieter: tall, wispy purple iris stems arching across the white body in a design that reads more graphic than botanical. Corning introduced it around 1985, discontinued it in the early 1990s, then briefly relaunched it years later, which says something about how well it sold the first time around even though it never became a flagship pattern.
Single pieces bring $10 to $135 depending on size and condition, while complete matched sets climb to $150 to $350. The cooler, more monochrome palette has found a specific audience among buyers decorating black-and-white or minimalist kitchens, which keeps demand steady even though the pattern itself isn’t especially old. As with any pattern built around fine linework rather than bold color blocks, the irises show wear faster than you’d expect, so check closely for rubbing along the high points of the stems where a sponge would have made the most contact. A piece with the purple still crisp and unbroken is worth chasing over one where the lines have started to blur into the white.
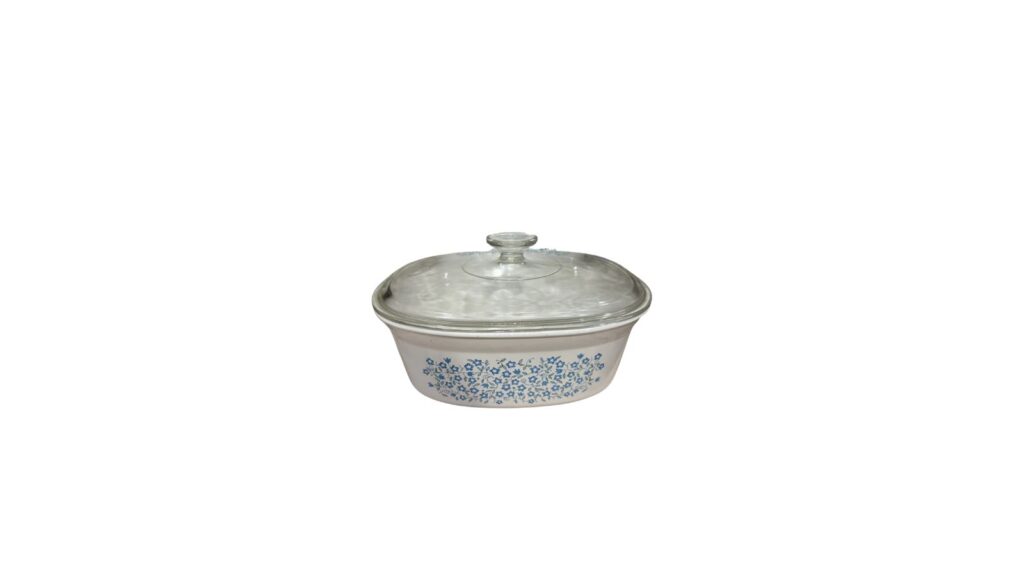
Blue Heather casserole with lid
Image Credit: mystopheles via eBay
Blue Heather ran for barely a year, maybe two depending on the source, making it one of the shortest production windows of any mainstream CorningWare pattern. Small five-petal blue flowers connected by thin vines cover most of the dish’s surface, a busier, more delicate treatment than the original Blue Cornflower it’s often mistaken for at a glance.
That brief run is exactly why it’s worth more than patterns that look similarly floral but stuck around for a decade. Clean pieces bring $30 to $150, with larger casseroles and pieces that still have their original lid toward the top of that range. Because Blue Heather uses a busier, more detailed print than most CorningWare patterns, faded or rubbed examples are common and sell for noticeably less, so pattern clarity is worth checking closely before assuming a piece is worth top dollar. Confirm you actually have Blue Heather and not the far more common Blue Cornflower before getting excited: the flower count and connecting vines are the tell, since Cornflower uses three simple blossoms while Heather scatters many more, smaller ones across the whole surface.
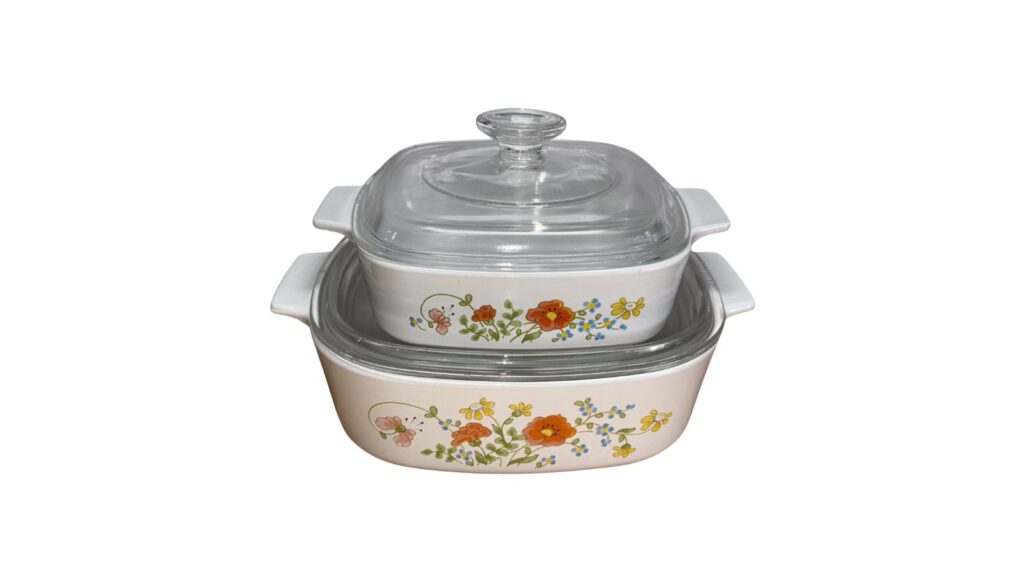
Wildflower large covered casserole
Image Credit: The Tippecanoe Picker via eBay
Wildflower is one of the more intricate patterns CorningWare ever ran, orange-red poppies, yellow daisies, and small blue blossoms scattered across the white body in a design busier than almost anything that came before it. It had a shorter run than Blue Cornflower or Spice of Life, about seven years, and the detailed print shows wear more visibly than simpler patterns, which keeps genuinely clean examples in real demand.
Individual pieces bring $20 to $60 in clean condition, with the large covered casserole or oval roaster at the top of that range and small saucepans at the bottom. Complete sets in excellent condition, all lids present and the floral print still bright rather than rubbed to a blur, can reach into the low hundreds. Because the pattern was originally sold in coordinated sets of around seven pieces, a lone casserole found at a thrift store is only ever going to be worth a fraction of what a complete run would bring, so it’s worth checking whether other Wildflower pieces are sitting nearby on the same shelf before assuming you’ve found everything.
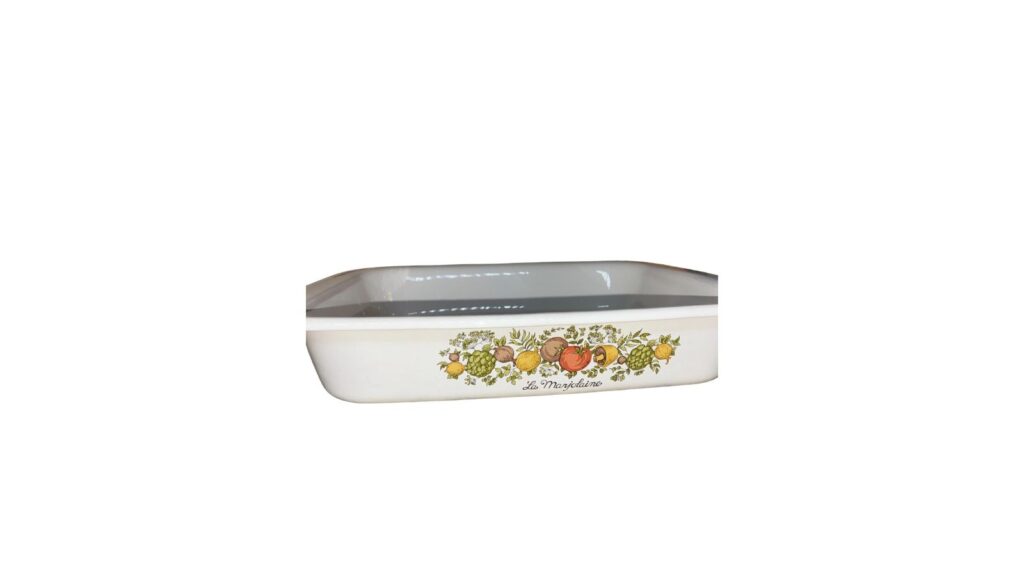
Spice of Life French-inscription roaster
Image Credit: NorthCarolinaClassics via eBay
Spice of Life is the second most produced CorningWare pattern after Blue Cornflower, vegetables and herbs printed in earth tones that were everywhere in 1970s kitchens. What most people miss is that the earliest pieces carry a French word beneath the vegetable band, L’Echalote, La Marjolaine, or Le Romarin among others, and Corning dropped that lettering from later production runs entirely.
Because the pattern ran for fifteen years, common sizes without the French script are genuinely inexpensive, typically $15 to $50 per piece. The pieces worth seeking out are the larger forms from the earliest years: a big oval roaster or Dutch oven still carrying the French inscription and its original lid moves well past that everyday range. Ignore any listing that treats the French words alone as proof of extraordinary value; the internet is full of Spice of Life priced in the thousands that never actually sells at that number. Size, completeness, and the vintage of the backstamp matter far more than the lettering by itself. As always, Pyroceram from this era shows a faint glow against light, while any post-1998 stoneware reissue does not.
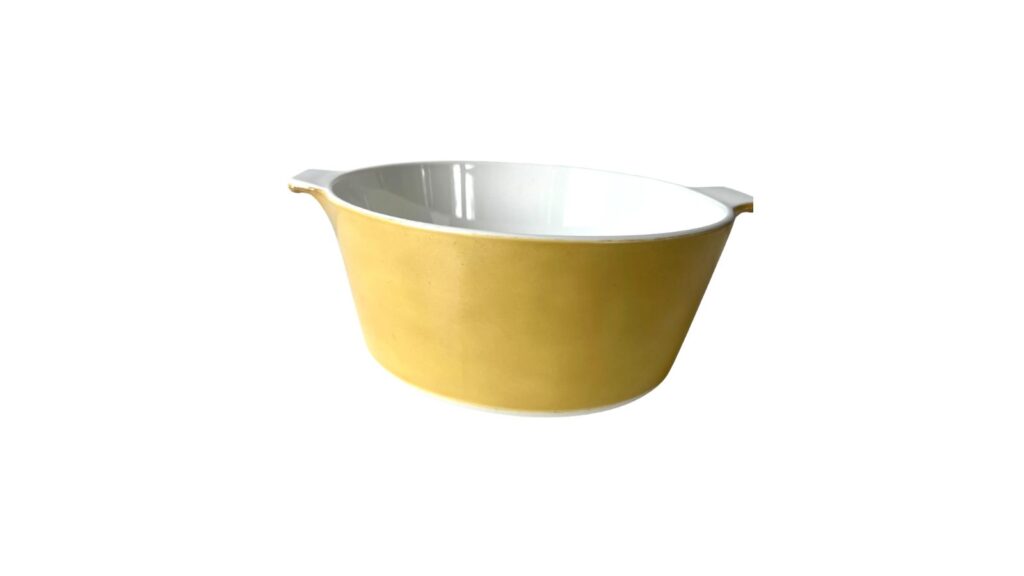
Butterscotch buffet server
Image Credit: artistictouch25 via eBay
Butterscotch skips the printed pattern entirely: the whole Pyroceram body is cast in a warm, solid amber-yellow color instead of the usual white, a striking departure from everything else Corning made that decade. It was part of the short-lived “Corning Ware Round” buffet line, sold for exactly one year in 1969 alongside an avocado-green counterpart, and Corning dropped it after that single season.
That one-year run makes genuine Butterscotch pieces worth $40 to $150, with the larger 4-quart buffet server or Dutch oven at the top of the range and smaller casseroles lower. Because there’s no printed decoration to fade or wear away, condition assessment here mostly comes down to the ceramic knob on the lid, which is prone to loosening or cracking, and the amber glaze itself, which can show heat staining from decades of stovetop use that’s harder to disguise on a solid color than on a busy print. A tight-fitting original lid with an intact knob and a body free of dark staining is what separates a top-of-range Butterscotch piece from an ordinary one.