You turn 70, log into your 401(k), and finally add up what you’ve been avoiding for a decade. The number on the screen either matches what you pictured or it doesn’t come close.
The average 401(k) balance for savers 70 and older is $264,500. Compare that to someone in their early 20s, who has about $7,700 saved on average, and it looks like real progress. Compare it to what that balance actually has to cover for the next 20 or 30 years, and it looks a lot thinner.
Where you land against that number matters less than what it can actually pay you every month, and whether there’s still time to change it.
This gets tracked every quarter across more than 25 million retirement accounts, and the breakdown by age tells you more than the headline figure alone. Someone in their early 20s has about $7,700 saved, which is basically starting from zero, and that’s fine, they’ve got 45 working years ahead of them. By the time savers hit their 50s, the average crosses $215,700, and it keeps climbing through the back half of that decade to $260,800 for ages 55 to 59.
Then the growth basically stalls. Savers 60 to 64 average $257,400, those 65 to 69 sit at $258,800, and by 70 and older, the average is $264,500. That’s roughly $7,000 of growth spread across 15 years, not because people stop saving entirely, but because a lot of them stop working, start pulling money out, or roll it into an IRA instead. If your balance has flattened out around this age, you’re not the exception. You’re the norm.
Averages hide the real story, medians tell it
Image Credit: Shutterstock
Those numbers are useful, but they’re still averages, and averages get pulled upward by a smaller group of savers with very large balances. A separate look at 401(k) plans administered nationwide found the average account balance was $167,970 at the end of 2025, a record high. The median, the point where half of savers have more and half have less, was only $44,115. That’s the figure most people actually match. Narrow it down to older savers and the split gets sharper. For those 65 and older specifically, the average balance was $330,186, while the median was $103,202. A smaller group in that age bracket is sitting on far more money than everyone else, and it’s dragging the average up with it. If your balance looks nothing like $264,500 or $330,186, check yourself against the median instead. It’s the number that actually reflects what a typical saver your age has put away.
What that balance actually pays you every month
A balance only matters once you turn it into income. Using the standard 4% withdrawal rule, the $264,500 average generates about $10,580 a year, or roughly $882 a month, before taxes. Add that to the average Social Security retirement benefit of $2,071 a month, and a 70 year old drawing on both sources is looking at somewhere around $2,950 a month, or just under $35,500 a year.
That’s not nothing, but it’s not comfortable either, especially with housing, health care and everyday costs climbing every year. It works if the mortgage is paid off, your health is decent and you live somewhere affordable. It falls apart fast if any one of those isn’t true, or if a big medical bill or a home repair shows up without warning. This is exactly why the balance by itself was never the full picture. What that money needs to cover matters just as much as what it adds up to, and that’s a personal calculation, not a national average.
Catching up still works, even this late
Image Credit: Shutterstock
None of this is set in stone. If you’re 70 and still working, even part time, the 2026 contribution limit is $24,500, plus an $8,000 catch-up for anyone 50 or older, for a total of $32,500 a year into a 401(k). That’s real money, and it still compounds even with a short runway left.
If you haven’t claimed Social Security yet, waiting matters more than most people realize. Each full year you delay past your full retirement age, up to 70, adds 8% to your monthly benefit. Someone who’d get $2,071 a month at full retirement age could be collecting closer to $2,568 by waiting until 70. Past that age, there’s no more benefit to delaying further, so if you’re already 70 and haven’t filed, there’s no reason left to wait.
Being behind the average at 70 isn’t a verdict. It’s a starting point for the next move.
The bottom line
Image Credit: Shutterstock
One more thing worth knowing if you’re near this age: the required minimum distribution age is 73 for anyone born between 1951 and 1959, and 75 for anyone born in 1960 or later. If you haven’t been forced to withdraw from a traditional 401(k) or IRA yet, you may still have a few years of choice in how and when you draw that money down.
You picked up a package of ground beef at the store this week and did a double take at the price. You’re not imagining things. That single pound now costs more than a fast food combo meal did five years ago.
Prices have moved so far past what people budgeted for that entire categories of everyday spending are shrinking. Movie theaters sit half empty on a Tuesday night. Cable subscribers keep cutting the cord. Coffee drinkers switch to whatever’s on sale or just make a smaller pot.
This isn’t about people losing interest in beef, movies, or coffee. When a price climbs faster than a paycheck, something has to give, and for a lot of households right now, that something is cutting back or walking away entirely.
Here are 21 things that got expensive enough to change how people actually spend.
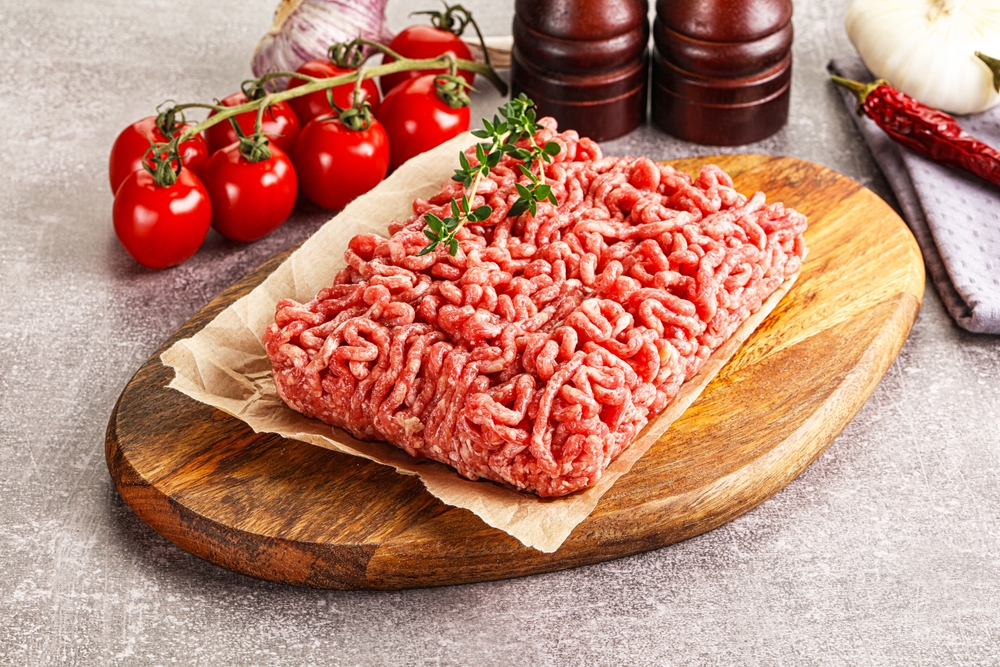
Ground beef hit $6.89 a pound in July 2026, a fresh record, and there’s no relief in sight. The national cattle herd has shrunk to its smallest size in roughly 75 years, the result of years of drought that forced ranchers to sell off breeding stock instead of expanding it. Rebuilding a herd takes three to four years at minimum, since cows need time to grow and calve, so this shortage isn’t fixing itself soon.
Shoppers have noticed. Chicken thighs, pork, and plant based proteins have all picked up sales as families swap out burgers and pot roast for cheaper options. Some households have simply started treating red meat as an occasional splurge instead of a weekly staple, and restaurants are shrinking portions or raising prices to protect their margins.
A family that used to buy two pounds of ground beef a week for tacos and burgers is now spending close to $14 on the meat alone, before buns, cheese, or a single side dish. Multiply that across a month of grocery runs and it’s easy to see why beef is the first thing coming out of a lot of carts.
Home insurance in wildfire and hurricane states
Image Credit: Shutterstock
The average homeowners policy now runs about $3,057 a year, up 46 percent since 2021, roughly three times the pace of overall inflation. Florida homeowners are paying far more than that. The typical policy there runs around $8,292 a year, nearly triple the national average, after repeated hurricane losses pushed reinsurance costs through the roof.
People aren’t quietly absorbing this. Some homeowners in high risk zones are dropping coverage altogether and self insuring, betting they can handle a disaster out of pocket rather than keep paying premiums that rival a car payment. Others are shopping surplus lines carriers that charge more but will actually write a policy, since major insurers have pulled back from entire zip codes in California and the Gulf Coast.
Lenders still require coverage on a mortgaged home, so most owners don’t have the option of simply opting out. What they’re doing instead is raising deductibles to the maximum allowed, stripping out optional coverage, and accepting more risk in exchange for a bill they can actually pay each month.
Concert tickets
Image Credit: Shutterstock
A floor seat at a major stadium tour now runs upward of $200, and the average ticket across the top 100 North American tours sat at $122.15 in mid-2026, with fees adding close to 29 percent more at checkout. Ticket prices have climbed roughly 80 percent between 2021 and 2025, far outpacing wages.
Plenty of fans have simply stopped trying to see the biggest names live. Instead they’re picking smaller venues, local acts, and club shows that still run $10 to $30 before fees, or skipping touring artists entirely in favor of a streaming playlist. Resale markets make the sting worse, since bots and professional resellers scoop up tickets the moment they go on sale and relist them at multiples of face value.
The people getting priced out hardest are the ones who used to treat concerts as a regular, affordable outing rather than a once a year splurge. A single mom’s budget doesn’t stretch to a $435 floor seat, and a lot of longtime fans are quietly becoming former fans of the live show, even if they still love the music.
Coffee
Image Credit: Sam’s Club
Your coffee habit got more expensive without you changing a single thing about it. The average price of ground roast coffee hit about $9.72 a pound in April 2026, up from $7.54 a year earlier, driven by weather damage to Brazilian and Vietnamese crops layered on top of tariffs on imported beans.
Coffee shops have raised prices too, though more cautiously, since chains know customers notice a $6 latte faster than a $2 jump in a bag of beans at the grocery store. That’s pushed a real shift in habits: more people are brewing at home instead of hitting a drive-thru every morning, buying the cheapest store brand instead of a name brand, or stretching a bag of grounds by using less per pot than the label recommends.
Some households have cut back to one cup a day instead of two or three. Others have switched to instant coffee, which costs less per cup even though it jumped in price too. None of this fixes the underlying problem, since the crop damage driving prices higher won’t resolve until future harvests come in, but it’s how people are coping in the meantime.
Extended car warranties
Image Credit: Shutterstock
Buying a car that costs close to $50,000 now often comes with a pitch for extended coverage, and that pitch isn’t cheap. Extended warranties average $139 a month, with plans ranging anywhere from $30 to $250 depending on the vehicle and coverage level.
A lot of buyers are declining. Nearly half of vehicle owners hold an extended warranty, but only about one in 10 ever files a claim on it, and word of that math has spread. More buyers are running the numbers themselves: a warranty that costs $2,000 to $5,000 over its life only pays off if a major repair actually happens, and reliable brands like Toyota and Honda rarely need one.
Instead of paying a warranty company monthly, more people are setting aside their own repair fund in a separate savings account, betting that self insuring beats paying a middleman for a service they may never use. Dealerships still push hard on these add ons at the finance desk, but fewer buyers are signing without at least doing the comparison first.
Wedding videography
Image Credit: Shutterstock
Couples planning weddings in 2026 keep cutting the same line item first. Skipping videography entirely is now the single most common cost cut couples make, saving $1,500 to $4,000, even though it’s the one thing that can never be redone. Photography is getting trimmed too, with couples pulling coverage down from 10 or 12 hours to 7 or 8, which often bumps them into a cheaper package tier entirely.
It’s not that couples don’t want the footage. It’s that a wedding now averages $34,000 to $36,000, and when something has to go, video is the piece that feels most skippable in the moment, even to people who will regret it later.
Some couples are finding a middle ground by hiring a videographer for ceremony coverage only, two or three hours instead of a full day, and using the savings to upgrade photography or florals instead. Others are asking a friend to shoot on a phone and calling it good enough. Either way, the full day, cinematic wedding film that used to be standard is quietly becoming the exception rather than the rule.
Cable TV
Image Credit: Shutterstock
The average cable bill now runs about $147 a month, compared with roughly $30 for a typical streaming bill. Most households only watch a small fraction of the channels they’re paying for, and everyone knows it.
The exodus has been steady rather than sudden. Pay TV subscribers have fallen from a peak of around 100 million a little more than a decade ago to somewhere in the 55 to 60 million range today, as households swap a single bundled bill for a handful of streaming apps they can cancel and restart as needed. A family that keeps two or three streaming services active typically spends $30 to $90 a month, a fraction of what cable costs once fees and equipment rental are added in.
The one thing keeping some households tethered to cable is live sports, since regional sports packages and local news still aren’t fully replicated on streaming. Everyone else has largely already left, or is one price hike away from doing the same.
Pet insurance
Image Credit: Shutterstock
Insuring a dog now costs an average of $62.44 a month, with cat coverage running $32.21, and renewal notices keep arriving with double digit increases attached as vet costs climb right alongside them.
A lot of pet owners are opting out entirely and gambling that they can cover an emergency out of pocket if one comes up. Others who already have a policy are downgrading to accident only coverage instead of full accident and illness plans, or raising their deductible to bring the monthly bill back down to something manageable. The stakes are real either way: 37 percent of pet owners went into debt in a recent year covering an unexpected vet bill, with credit cards and medical financing apps covering the shortfall insurance would have paid.
The tragic version of this trend shows up in shelters, where rising vet costs are now a documented reason some owners cite for giving up a pet they can no longer afford to keep healthy. For most families it’s less dramatic: they’re just deciding, pet by pet, whether the monthly premium is worth it.
Chocolate and candy
Image Credit: ALDI
Cocoa futures have collapsed roughly 70 percent from their late 2024 peak, yet chocolate on the shelf hasn’t gotten any cheaper. US chocolate prices were actually up 14 percent in early 2026 compared with the same period a year earlier, even as the raw ingredient got dramatically cheaper to buy.
Hershey has told investors it sees no reason to change its pricing even with cocoa costs down, and that’s a pattern across the industry. Companies raise prices fast when costs spike and lower them slowly, if at all, once costs ease, because customers rarely notice a price that quietly stays the same.
Shoppers are responding by buying less. Smaller bags and single bars have replaced the big multipacks in a lot of carts, and candy aisle sales volumes have dropped even as dollar sales held steady, which is the classic sign of people paying more for less rather than walking away from chocolate completely. Holiday candy spending has slipped too, as families trim the size of Easter baskets and Halloween buckets to fit a tighter budget.
New cars
Image Credit: Shutterstock
The average new vehicle sold for $49,758 in June 2026, and sticker prices have stayed above $50,000 for eleven straight months, one of the longer stretches on record. Loan terms have stretched out to compensate, with 20 percent of new car buyers now carrying a monthly payment of $1,000 or more.
Plenty of would-be buyers have simply stopped shopping. Instead they’re holding onto an existing car longer, patching it up with an out of pocket repair instead of trading it in, or shifting their search to the used market where prices have held roughly flat. Others are downsizing what they’re willing to buy, skipping the loaded trim level and the extra features that used to feel standard.
Auto loan approval rates have actually loosened, since lenders are competing hard for the buyers who are still in the market, which sounds like good news until you notice it mostly means people are qualifying for bigger loans on more expensive cars rather than smaller loans on cheaper ones. The buyers sitting it out entirely aren’t showing up in any of those numbers at all.
Child care
Image Credit: Shutterstock
Full time infant care at a licensed center now runs about $1,230 a month nationally, up 5 percent from $1,171 just a year earlier, with costs in states like Massachusetts and California pushing past $2,000 a month for the same care.
For a lot of families, that bill now exceeds what one parent brings home after taxes, which turns child care from a budget line into a career decision. One in four parents has already cut work hours or left a job entirely because of child care costs or a lack of available spots, and that number climbs higher for families with more than one child in care at the same time.
Grandparents are stepping in more often as unpaid caregivers, and informal nanny shares between two or three families have become a common workaround in cities where center based care runs highest. None of it fully replaces licensed care, but for households doing the calculation, a $15,000 annual bill for one child often doesn’t pencil out against a second income, especially once commuting and work clothes get factored in too.
Movie theater concessions
Image Credit: Felipe Bustillo via Unsplash
A movie date for two now costs $54.08 on average, with individual tickets running $16.30 nationally, before a single tub of popcorn or box of candy gets added to the total. In expensive markets like New York, that same date night pushes past $73.
Theaters have leaned harder into concessions to make up for softer attendance, and the markups show it. A large popcorn and two drinks can add another $25 to $30 on top of the tickets, which is often more than the tickets themselves cost. Families with kids feel this hardest, since a trip for four people can easily clear $100 once snacks are included.
The response has been predictable: more people are sneaking snacks in, splitting one popcorn between two people instead of buying separately, or simply waiting for a movie to hit streaming instead of paying for opening weekend. Midweek matinee showings have become the budget conscious moviegoer’s workaround, since a lower ticket price at least takes some of the sting out of the concessions bill.
Car insurance
Image Credit: Shutterstock
Full coverage car insurance now averages a little over $2,150 a year nationally, part of a cumulative 46 percent increase since 2022 driven by pricier repair parts, more expensive lawsuits, and back to back years of severe hail and storm damage. Some states have it far worse. Louisiana premiums jumped from $1,535 to $3,438 in a single year, a 124 percent spike tied to litigation costs and high risk driving patterns.
A meaningful number of drivers have responded by dropping coverage they’re not legally required to carry, keeping only the state minimum liability instead of full comprehensive and collision, especially on an older car that isn’t worth much anyway. Others have raised their deductible from $500 to $1,000, which can cut a premium by 8 to 15 percent in exchange for paying more out of pocket if something happens.
Uninsured driving is the risk nobody likes to talk about, but it ticks up right alongside premiums, since some drivers simply stop paying for coverage they can no longer afford rather than downgrade it. That’s a gamble that can turn a fender bender into a financial disaster, but for a stretched household, it’s a gamble some are making anyway.
Checked baggage fees
Image Credit: Shutterstock
Checking a single bag on a domestic flight now costs $45 to $50 prepaid at most major airlines, after a wave of fee increases hit United, Delta, American, and Southwest within days of each other in early 2026. Southwest, which offered two free checked bags for more than 50 years, ended that policy for most passengers back in 2025.
Travelers have gotten aggressive about avoiding the charge. Carry-on-only travel has become the default for anyone taking a short trip, and packing cubes and compression bags exist almost entirely to squeeze a week’s worth of clothes into a bag that fits under the seat. Airline branded credit cards, which often waive the first checked bag fee, have seen a jump in applications from people who fly only a handful of times a year but want to dodge the fee every time.
Airlines collected close to $5.5 billion in baggage fees in 2025 alone, and industry analysts don’t expect that number to shrink even if fuel costs ease, since fees are much easier to raise quietly than a base fare that shows up in comparison searches.
The daily newspaper
Image Credit: Shutterstock
A print newspaper subscription now runs more than $1,000 a year at many major papers, with the Boston Globe charging $1,347 annually for print while its all digital package runs a fraction of that. Circulation at the country’s largest papers has responded accordingly, falling 12.5 percent in a single year across the top 25 US titles.
Longtime subscribers, many of them older readers who grew up with a paper on the doorstep every morning, are the ones canceling in the biggest numbers, priced out of a habit they’d kept for decades. Younger readers who might replace them were never really subscribers to begin with, since most of them get news through social media or a free app instead.
Publishers know exactly what’s happening and are betting on digital subscriptions to make up the difference, but a digital only plan rarely replaces the print revenue it’s meant to replace. The morning paper habit that once felt as automatic as making coffee is quietly becoming something only a shrinking, aging slice of the population still pays for.
ACA marketplace health insurance
Image Credit: Getty Images via Unsplash
Premiums on the ACA marketplace jumped hard in 2026 after enhanced subsidies expired at the end of 2025. Subsidized enrollees who kept the same plan saw payments rise 114 percent on average, from about $888 a year to $1,904, and some households in high cost states faced increases north of $20,000 annually.
People noticed immediately. Marketplace enrollment is expected to fall by roughly 5 million people this year as households decide the coverage simply isn’t affordable anymore, even though going without insurance leaves them exposed to a single bad diagnosis or accident wiping out their savings. Some are switching to bare bones bronze plans that cover almost nothing until a high deductible is met, just to keep some coverage on paper while paying less each month.
Others are gambling on staying uninsured entirely, particularly younger, healthier households who’ve decided the odds favor skipping coverage until something forces the issue. Insurers are also pulling back, with Cigna announcing plans to exit the marketplace next year, which will shrink the options left for whoever’s still buying.
The landline
Image Credit: Shutterstock
Fewer than one in four American households still keep a working landline at home. Seventy eight percent of US adults were wireless only in 2026, up from 71 percent just a year earlier, meaning more than 200 million Americans now rely entirely on a cell phone.
It’s not really about price on its own, since a landline itself is fairly cheap, but it’s almost always bundled with a home internet or cable package that keeps getting more expensive every year. Dropping the landline is one of the easiest, most painless cuts a household can make when a bill needs trimming, since almost nobody actually uses it to make calls anymore.
Seniors remain the biggest holdouts, with 40.7 percent of Americans 65 and older still keeping one, often for the reliability during a power outage or because it’s simply the number everyone in the family has known for 30 years. Everyone under that age bracket has mostly already made the switch, and the phone hanging on the kitchen wall is turning into something that shows up mostly in nostalgic photos rather than actual homes.
Traditional funerals
Image Credit: Shutterstock
A traditional funeral with a casket, viewing, and burial now averages $7,848, and that’s before a burial vault, which can push the total closer to $10,000. Costs have climbed roughly 28 percent over the past decade, well ahead of general inflation.
Families have responded by walking away from tradition entirely. Direct cremation, which skips embalming, a formal service, and a casket in favor of the simplest possible option, now costs as little as $1,000 to $3,000, and more than 63 percent of American families now choose cremation over burial. That’s a complete reversal from a generation ago, when burial was the assumed default and cremation was the exception.
Plenty of families still want a real gathering to grieve together, so they’re splitting the difference: choosing cremation to control the hard costs, then holding a separate memorial service afterward at a church, a park, or someone’s backyard instead of paying funeral home facility fees. It’s a workaround born entirely out of the price gap between what a funeral home charges and what a family can actually afford.
Professional movers
Image Credit: Shutterstock
Hiring movers for a mid distance relocation isn’t cheap. A three bedroom move of 800 to 1,200 miles runs about $9,340 on average, and a cross country move can climb well past $18,000 depending on the size of the home.
Most people have simply stopped hiring anyone. Roughly 62 percent of Americans now handle their own moves, renting a truck and doing the loading, driving, and unloading themselves rather than paying a crew to do it. The savings are real, often several thousand dollars on a longer move, but so is the cost of a week off work, a sore back, and the very real risk of dropping something valuable down a flight of stairs.
A middle option has grown fast as a result: portable moving containers that get dropped off, loaded by the family, and driven by someone else. It splits the difference between full service movers and a fully DIY truck rental, and its growing popularity says a lot about how many people want professional help but simply can’t justify paying full price for it anymore.
Fast food
Image Credit: Shutterstock
Fast food traffic fell 1.6 percent year over year in May 2026, the steepest drop since January, and the decline is concentrated among middle and lower income customers who used to treat a drive-thru run as the cheap, easy option. Menu prices climbed 3.6 percent over the same period, so the industry is technically posting higher sales even while fewer people walk through the door.
Drive-thru lanes that used to back up onto the street at dinnertime now sit noticeably empty at some locations, a shift industry executives are watching play out in real time. A combo meal creeping toward $12 has broken the basic promise fast food used to make: that it would always be cheaper and faster than cooking or a sit down restaurant.
Chains are scrambling with $4 and $5 value menus to win customers back, and some of it is working, but the core habit of grabbing fast food out of pure convenience has weakened. More people are packing a lunch, cooking a quick dinner at home, or picking up a grocery store meal deal instead, treating fast food as an occasional treat rather than the default option it used to be.
College textbooks
New textbooks still run $100 to $300 each, and the sticker shock has pushed students to a breaking point most schools don’t fully account for. Sixty three percent of college students have skipped buying a required textbook because it was too expensive, and 11 percent have skipped meals specifically to afford their course materials instead.
Students aren’t just going without. A quarter have taken on extra work hours to cover the cost of books, and the ones who can’t find extra hours are showing up to class without the material their professor assigned, hoping to get by on lecture notes and whatever they can find online for free. Rental programs and digital editions have pulled the average annual spend down over the past decade, but for students paying out of pocket for a required lab manual or access code, the individual sticker price hasn’t gotten any friendlier.
Professors adopting open educational resources, free digital textbooks with no publisher attached, have made a real dent at some schools. Where that hasn’t caught on, students are left choosing between an outdated used copy, a library reserve copy shared with 40 classmates, or simply going without.
A six-figure paycheck doesn’t always come with exciting projects, flashy meetings, or a job title anyone at a party wants to hear about. Sometimes the money is in checking expiration dates, chasing missing records, reviewing safety rules, or making sure a company filled out the right form before something ships.
That kind of work has an advantage right now. When a task is tied to patient safety, government rules, insurance risk, hazardous materials, the power grid, or a legally required audit, a company can’t simply decide it isn’t worth doing anymore. Many of these jobs also happen mostly through databases, video calls, document systems, and email, which makes working from home practical.
Most aren’t beginner jobs. The higher pay usually comes after you’ve built experience in a related field and learned a pile of rules that most people would rather avoid. That is also a big part of why the jobs can be so valuable.
If verifying hundreds of licenses, board certifications, work histories, malpractice records, and expiration dates sounds mind-numbing, you’ve found the right profession. Medical staff credentialing managers oversee the people who make sure doctors and other clinicians are properly qualified before they can treat patients. They also deal with renewals, missing paperwork, committee approvals, database errors, and audits. Current pay averages about $110,792 per year.
This work fits remote life surprisingly well because most of the evidence being checked is electronic. Hospitals, health systems, physician groups, insurers, and companies that handle credentialing for other organizations all need it. You usually work your way up from credentialing coordinator or specialist rather than jumping straight into management. Professional credentialing certification can help once you have experience. The long-term demand is hard to ignore, too. The broader group of health-services managers is projected to grow 23% over the decade, with tens of thousands of openings each year.
2. Clinical quality assurance specialist
Image Credit: Shutterstock
Clinical quality assurance is built around a thrilling question: Did everyone follow the procedure exactly? You review clinical-trial records, investigate deviations, check training files, track corrective actions, and make sure research teams followed required quality rules. There can be entire meetings about why somebody checked the wrong box three months ago. For people who are unusually patient with details, the average pay of about $98,524 per year makes the paperwork easier to tolerate.
Drug companies, medical-device makers, research organizations, and biotech firms employ these specialists, and much of the checking can be done through secure systems from home. A life-science background is common, but experience with clinical research, regulated manufacturing, or quality systems can matter just as much as the exact degree title. Knowledge of good clinical practices and audit procedures is important. The wider medical-science workforce is projected to grow 9%, faster than average, as research and development continue expanding. Someone still has to decide whether an irregularity is harmless, requires correction, or threatens the integrity of a study.
3. Clinical research associate
Image Credit: Shutterstock
Clinical research associates spend a large chunk of their lives checking whether clinical-trial sites did what the study protocol told them to do. That means reviewing patient records, confirming consent paperwork, checking drug accountability, questioning missing data, tracking protocol deviations, and following up until every loose end has an answer. The work can be repetitive enough to make a spreadsheet look adventurous. Average pay is currently about $100,279 per year.
Many CRAs are home-based, although the job often includes trips to hospitals and research sites. Other employers use more centralized monitoring, which means even more of the checking happens remotely. A common path starts with experience as a clinical research coordinator, trial assistant, nurse, or another research-support role, along with a bachelor’s degree in a health or science field. You also need a working knowledge of clinical research rules. Research employment remains on a solid track, with medical-science jobs projected to grow 9%. Clinical trials may use better monitoring tools, but sponsors still need qualified people to question discrepancies and decide whether a study site is following the rules.
4. Pharmacovigilance specialist
Image Credit: Shutterstock
Pharmacovigilance specialists track what happens when patients have possible side effects from medicines. A typical day can involve opening case files, checking dates and doses, coding medical terms, requesting missing information, deciding whether a case meets reporting rules, and watching regulatory deadlines. It is important work disguised as an endless procession of forms and database fields. Average annual pay is around $96,145.
Because adverse-event information is received and processed electronically, drug manufacturers, biotech companies, consulting firms, and research organizations can run these teams remotely. People commonly enter with backgrounds in pharmacy, nursing, life sciences, clinical research, or drug-safety operations. Experience with safety databases and medical coding systems becomes especially valuable as you move up. The same expansion in drug development that supports medical-science employment also creates ongoing safety work, with the broader field projected to grow 9%. Human judgment still matters when reports are incomplete, contradictory, medically complicated, or serious enough to trigger extra review.
5. Clinical supply associate
Image Credit: Shutterstock
A clinical trial can grind to a halt because the right box of medication didn’t arrive at the right clinic before the old stock expired. Clinical supply associates help prevent that wonderfully boring disaster. They monitor trial-drug inventory, coordinate shipments, track expiration dates, work with depots, investigate missing packages, and make sure study sites have the right quantities without creating piles of wasted product. Average pay is about $95,504 per year.
The physical boxes may sit in warehouses and clinics, but much of the planning happens through inventory systems and calls, so experienced clinical-supply employees can work from home. Employers include pharmaceutical companies, biotech firms, research organizations, and specialist supply vendors. People often arrive from clinical operations, pharmaceutical manufacturing, logistics, or supply-chain jobs and then learn the extra rules governing trial materials. It is a niche sitting between health care and logistics, two areas with plenty of continuing work. Logisticians are projected to grow 17%, far faster than average. A delayed shipment can affect patients and research schedules, so companies still need people who can solve exceptions rather than simply move numbers around a system.
6. Global trade compliance specialist
Image Credit: Shutterstock
There are people whose working day revolves around figuring out which customs classification belongs to a machine part and whether that part is allowed to cross a border. Global trade compliance specialists check product classifications, country-of-origin records, export restrictions, sanctioned-party screenings, customs documents, and broker questions. If you enjoy rules with exceptions followed by more rules, this could be your corner of the job market. Average pay is about $98,648 per year.
Manufacturers, aerospace companies, medical-device firms, retailers, energy businesses, and international distributors all need this work. Much of it can be handled remotely because the job centers on product databases, regulations, shipment records, and communication with internal teams and customs brokers. Experience in logistics, importing, exporting, procurement, or customs operations can lead into the field, and specialized trade training becomes more useful as you advance. Overall compliance employment is projected to remain stable, with roughly 33,000 openings a year from growth and replacement needs. Companies may automate routine screening, but somebody still has to interpret unusual products, conflicting rules, and shipments that don’t fit neatly into a standard category.
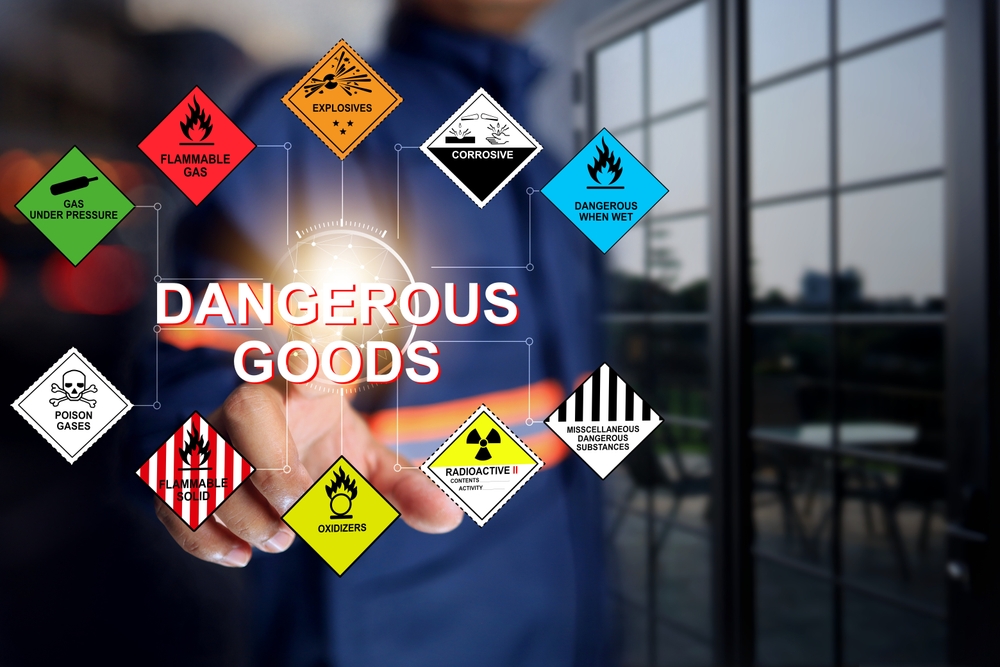
7. Dangerous goods manager
Image Credit: Shutterstock
Shipping perfume, laboratory chemicals, batteries, compressed gases, or other regulated materials can require a surprising amount of rule-following. Dangerous goods managers oversee classifications, packaging requirements, labels, shipping documents, employee training, carrier rules, and investigations when something goes wrong. The role’s current average pay is about $100,450 per year.
A lot of the compliance work can be managed from home, although larger jobs may require occasional trips to warehouses, laboratories, or distribution sites. Remote dangerous-goods roles are currently advertised across the transportation and compliance market. Experienced shipping, logistics, environmental-safety, or hazardous-materials workers are the usual candidates, and recurring training in air, highway, and ocean shipping rules is part of the deal. Transportation, storage, and distribution management jobs are projected to grow 6%, faster than the average for all occupations. Software can flag a missing field, but an incorrectly classified chemical or battery can become a serious safety and legal problem, which keeps experienced humans in the loop.
8. NERC compliance specialist
Image Credit: Shutterstock
NERC compliance specialists work in the electric-power world, but most aren’t climbing utility poles or fixing transformers. Their job is proving that utilities and other grid organizations are following reliability and security standards. That involves control evidence, audit requests, access records, testing calendars, training records, corrective-action plans, and enough documentation to make even a devoted rule follower tired. Average pay is about $109,666 per year.
The role is a particularly good example of obscure work that has moved home. Current searches show hundreds of remote NERC compliance openings and dedicated remote analyst roles. People usually come from electric utilities, grid operations, regulatory compliance, information security, engineering, or auditing and then learn the reliability standards in depth. The overall compliance field is projected to remain steady with about 33,300 openings annually. More important for this niche, electric-grid operators face recurring mandatory requirements and audits. A company cannot simply skip the evidence because nobody feels like assembling it this quarter.
9. Senior environmental compliance specialist
Image Credit: Shutterstock
Senior environmental compliance specialists keep track of permits, emissions records, waste rules, water requirements, inspection findings, reporting calendars, and promises companies have made to regulators. A surprising amount of the job consists of discovering that one facility forgot to record something weeks ago, then figuring out whether that omission matters. Average pay sits around $101,295 per year.
Consulting firms and companies with multiple facilities can base senior specialists at home, with occasional travel when an inspection, audit, or site problem actually requires a person on the ground. Manufacturing, utilities, chemicals, energy, construction, and waste businesses all need this expertise. A degree in environmental science, engineering, chemistry, or a related field is common, but employers also value years spent dealing directly with permits and environmental programs. Environmental scientists and specialists are projected to grow 4%, about as fast as average, with thousands of openings each year. Monitoring tools can collect readings, but messy real-world questions about permits, unusual releases, and corrective actions still require somebody who understands what the rules mean.
10. Product stewardship professional
Image Credit: Shutterstock
Product stewardship is what happens after a company realizes it sells thousands of products into places with different chemical, labeling, recycling, ingredient, and safety requirements. People in this field check restricted substances, answer regulatory questions from customers, maintain product-compliance information, and determine whether a material can legally stay on the market. The average salary is about $114,017 per year.
This work is especially common in chemicals, manufacturing, consumer goods, industrial products, agriculture, electronics, and materials companies. Remote product-stewardship openings are available because much of the job involves regulatory databases, product specifications, supplier information, and internal meetings rather than standing on a factory floor. Chemistry, toxicology, materials science, environmental compliance, or regulatory affairs experience can provide a route in. Employment for chemists and materials scientists is projected to grow 5%, with about 7,000 openings each year. Product rules also keep changing, and the difficult cases involve substances, mixtures, exemptions, and markets that don’t fit into a clean yes-or-no decision.
11. Senior supplier quality engineer
Image Credit: Shutterstock
Senior supplier quality engineers are paid well to ask vendors why a part failed, what they are doing about it, and how they can prove it won’t happen again. Days can disappear into corrective-action records, inspection results, supplier scorecards, process changes, audit findings, and meetings about dimensions that are off by a fraction. Average pay is around $101,441 per year.
Many of these jobs can be home-based when suppliers are spread across the country, although periodic travel for supplier audits and factory problems comes with the territory. Medical devices, aerospace, automotive, industrial manufacturing, electronics, and defense contractors all employ them. Most senior roles expect an engineering or technical background plus several years in manufacturing quality, supplier development, or process control. Quality certifications can strengthen your case. The broader industrial-engineering field is projected to grow 11%, much faster than average, with about 25,000 openings each year. Automated inspection can find defects, but arguing through root causes with a supplier and deciding whether its corrective plan is actually credible remains very human work.
12. Safety compliance manager
Image Credit: Shutterstock
Safety compliance managers spend their days making sure other people aren’t taking shortcuts that could injure somebody. That often means reviewing incidents, tracking corrective actions, maintaining training records, checking required programs, answering questions from supervisors, and preparing locations for inspections. It isn’t glamorous. It can involve an impressive number of conversations about guardrails, ladders, forklifts, labels, and whether somebody completed a form. Average annual pay is about $101,408.
Companies with many locations can centralize much of this work remotely, with managers traveling only when an incident, audit, or high-risk site needs an in-person visit. Manufacturing, warehousing, construction, health care, energy, insurance, and transportation companies all need safety expertise. Experienced safety coordinators and specialists can move into management, often adding professional safety credentials along the way. Occupational health and safety employment is projected to grow 12%, much faster than average, with about 18,300 openings every year. Sensors and checklists help, but deciding why an accident happened and whether a proposed fix will actually protect workers requires context and judgment.
13. Industrial hygienist
Image Credit: Shutterstock
An industrial hygienist spends a lot of time thinking about things most workers would rather never think about: solvent vapors, mold spores, noise exposure, welding fumes, dust, ventilation rates, and whether somebody has been breathing too much of something for too long. They measure workplace exposures, review laboratory results, investigate complaints, and recommend controls. Average pay is around $114,193 per year.
The word “remote” needs a small asterisk here. Senior industrial hygienists and consultants can be based at home, but they travel to workplaces when actual sampling or inspections are needed. Between visits, analysis, planning, client meetings, and follow-up happen remotely. Employers include consulting firms, insurers, manufacturers, government contractors, laboratories, and large corporations. A science or engineering degree is common, and experienced professionals may earn the Certified Industrial Hygienist credential. The wider occupational safety field is projected to grow 12%. Equipment can measure noise or chemicals, but somebody still has to decide where to sample, what the readings mean, and whether workers are actually protected.
14. Loss control consultant
Image Credit: Shutterstock
Insurance companies would rather prevent a warehouse fire than write a giant check afterward. Loss control consultants help them figure out which customers are most likely to have expensive accidents. They examine fire protection, roofs, machinery, storage practices, worker safety, building conditions, and other hazards, then recommend changes that can reduce losses. Average pay is about $113,493 per year.
These are often home-based territory jobs. You handle planning, research, calls, and casework remotely, then visit insured properties when an actual inspection is necessary. Property insurers, commercial insurers, risk-consulting firms, and large self-insured companies employ people with this skill set. Safety professionals, engineers, experienced insurance employees, and people with industrial backgrounds can move into the work, with risk-management or safety credentials helping later. The closely related occupational-safety workforce is projected to grow 12%. Photographs and automated models can flag obvious hazards, but a real building rarely behaves like a tidy database. Insurers still need people who can walk through a complicated operation and notice what doesn’t look right.
15. Business continuity planning analyst IV
Image Credit: Shutterstock
Business continuity analysts spend months planning for days everybody hopes never happen. They keep lists of critical operations, backup locations, recovery priorities, vendor dependencies, emergency contacts, and the maximum amount of downtime each department can tolerate. Then they run tabletop exercises where everyone pretends the building is unavailable or a major supplier has disappeared. Senior-level pay averages about $113,400 per year.
This is naturally remote-friendly because much of the work is interviewing teams, maintaining plans, organizing tests, mapping dependencies, and chasing people who still haven’t updated their emergency contacts. Banks, insurers, hospitals, manufacturers, universities, utilities, and large corporations need continuity staff. Senior analysts usually build experience through risk management, operations, emergency planning, compliance, or disaster recovery before moving up. Continuity certifications can help. Related project-management employment is projected to grow 6%, faster than average. The job also survives budget debates because disasters, outages, cyber incidents, and supplier failures keep forcing companies to prove they have a workable backup plan.
16. Governance, risk and compliance analyst
Image Credit: Shutterstock
Governance, risk and compliance analysts, usually shortened to GRC analysts, live in the world of controls. They check whether employees have the right system access, gather proof that required security steps happened, track exceptions, question vendors, prepare audit evidence, and make sure somebody fixes control failures before the next review. It is steady, methodical work with an average salary of about $100,908 per year.
Because evidence, access records, questionnaires, and meetings are digital, GRC is one of the more natural work-from-home specialties in security and corporate risk. Banks, insurers, health-care companies, government contractors, manufacturers, and technology firms all use these teams. People often enter from information security, internal controls, vendor risk, privacy, or compliance and learn frameworks and audit requirements on the job. Information-security analyst employment is projected to grow 29%, one of the strongest outlooks among office careers. Tools can gather evidence faster, but someone still has to judge whether a control really works, approve exceptions, and explain failures to auditors or executives.
17. Senior employee relations specialist
Image Credit: Shutterstock
Senior employee relations specialists deal with the workplace problems managers don’t want to handle alone. That can mean complaints, misconduct allegations, policy violations, accommodation questions, disciplinary decisions, attendance problems, and arguments over whether two employees were treated consistently. A lot of the job is interviews, case notes, policy checking, and careful conversations nobody is especially excited to have. Average pay is about $100,560 per year.
Large companies can run employee-relations teams remotely because investigations and manager consultations often happen over phone and video. Employers span health care, finance, retail, manufacturing, transportation, universities, and large service companies. Most senior specialists have several years of HR or employee-relations experience and know how to conduct investigations, interpret policies, and handle confidential information. HR specialist employment is projected to grow 6%, with more than 80,000 openings each year. Templates can help organize a case, but interviewing people who disagree about what happened and deciding on a fair response is not a simple checkbox exercise.
18. Senior labor relations specialist
Image Credit: Shutterstock
Labor relations is employee relations with thicker rulebooks. Senior specialists handle union contracts, grievances, discipline disputes, contract interpretation, bargaining preparation, past-practice questions, and meetings where two sides may spend an hour debating three sentences in an agreement. If you like details and have a very high tolerance for procedural arguments, average pay is around $97,920 per year.
Remote labor-relations teams are practical for large employers spread across many facilities, although negotiations, hearings, or serious disputes can still require travel. Transportation companies, hospitals, manufacturers, universities, public contractors, utilities, and other unionized employers need experienced specialists. The usual route is several years in HR, labor relations, operations, or a union environment, followed by increasingly difficult grievance and contract work. Employment in the occupation is projected to remain broadly stable, with about 5,100 openings each year as workers leave or retire. The job depends heavily on negotiation, credibility, precedent, and reading the people across the table, which keeps experienced specialists valuable even when the paperwork itself becomes easier to process.
Athletes, biohackers, and people coming off illness are all asking a version of the same question lately: why does recovery feel so much harder than it used to? Part of the answer lives at the cellular level. NAD+ – short for nicotinamide adenine dinucleotide – is a coenzyme your body depends on to produce energy, repair DNA, and regulate hundreds of metabolic processes. But NAD+ levels drop with age, chronic stress, poor sleep, and intense physical output. The gap between how much your body needs and how much it produces widens; you feel it as fatigue, slow muscle recovery, and mental fog. NAD+ injections offer a direct way to close that gap. Understanding how they help with recovery and performance starts with what this molecule actually does inside your cells, and why the delivery method matters more than most people expect.
When athletes and clinicians talk about cellular recovery, they’re really talking about mitochondrial function – and NAD+ sits at the center of it. NAD+ 1000mg vial sends the coenzyme into the bloodstream rather than through the digestive system, avoiding the breakdown that oral forms go through in the gut. That distinction matters because oral NAD+ precursors – like NMN or NR supplements – still require enzymatic conversion steps before cells can use them. Injections skip those steps and raise circulating NAD+ levels more directly. Some clinicians and patients report noticing changes in energy and mental clarity relatively early into NAD+ therapy, though individual experiences vary and oral supplementation may take a different timeline to show similar effects. For anyone using NAD+ therapy to support recovery and performance goals, understanding the form being used and why can be a useful part of that decision.
How NAD+ powers cellular energy production
NAD+ is the molecule that makes the electron transport chain run. Your mitochondria use it to convert glucose and fatty acids into ATP – the actual currency your muscles, brain, and organs spend to do anything at all. Without adequate NAD+, that conversion slows, and your cells run low on fuel even if you’re eating well and sleeping enough. Honestly, this is why NAD+ depletion feels less like a specific symptom and more like a general dimming across all systems. Research from the National Institutes of Health has documented that NAD+ levels in human tissue decline significantly with age, with some tissues showing a reduction of more than 50% by middle age. For performance-focused individuals, that decline means less ATP output per unit of substrate – your body becomes less able to turn food into usable energy. Restoring NAD+ through injections gives the mitochondria what they need to run the chain at full capacity again.
Why injections deliver results faster
Bioavailability is the factor most supplement marketing glosses over. The oral route for NAD+ precursors involves absorption through the gut wall, conversion in the liver, and then transport to target tissues – each step representing a potential loss. Studies published in journals like Cell Metabolism have shown that intravenous and intramuscular NAD+ administration raises blood NAD+ levels far more sharply than equivalent oral doses. Intramuscular injections, which most at-home and clinic-based protocols use, are practical and less invasive than IV infusions, while still delivering meaningfully higher bioavailability than capsules or powders. And here’s the thing – for people whose goal is measurable recovery support, whether that’s reduced soreness, faster return to baseline after hard training, or improved sleep depth, the speed of delivery matters. You don’t want to wait weeks for a therapeutic level to build when your training schedule doesn’t pause. Injections get NAD+ where it needs to go, at a concentration that actually moves the needle on how you feel and function.
Recovery and performance: Where NAD+ makes a real difference
Recovery and performance aren’t separate goals – they’re two sides of the same process. You perform better because you recover well, and you recover well because your cells have the resources to repair, rebuild, and adapt. NAD+ sits at the intersection of both. Its role in activating sirtuins – a class of proteins tied to cellular repair, inflammation regulation, and longevity pathways, means it does far more than fuel energy production. It also signals your cells to prioritize maintenance over breakdown. For athletes, this matters in the 24 to 72 hours after intense exercise, when muscle protein synthesis is active and inflammation either supports or blocks adaptation. For professionals under cognitive load, it matters across those sustained hours of focus a demanding workday demands. NAD+ injections address both contexts because the underlying biology is identical: cells with adequate NAD+ handle stress better, repair faster, and function at a higher level across the board.
Physical recovery after training
Intense exercise depletes NAD+ because your muscles consume it rapidly during high-output activity. The soreness and fatigue you feel afterward reflect, in part, the cellular repair work your mitochondria need to complete, and they need NAD+ to do it. Research from the journal Science has identified that NAD+-dependent enzymes called PARPs activate immediately after DNA damage, including the micro-tears that resistance training causes in muscle fibers. If your NAD+ pool is already low going into a session, recovery takes longer because the repair machinery runs slow. So restoring NAD+ through injections before or after training gives those repair enzymes the substrate they need to work efficiently. Some sports medicine clinicians also point to NAD+’s role in reducing inflammatory cytokine activity, which means less of the prolonged soreness that keeps you out of the gym or off the field. The practical outcome is a shorter window between hard sessions and a return to full output.
Cognitive performance and mental edge
Your brain accounts for roughly 20% of your body’s total energy consumption, according to data from the National Institute of Neurological Disorders and Stroke. It’s one of the tissues hit hardest by NAD+ decline, and the effects show up as difficulty concentrating, slower processing speed, and the kind of afternoon mental fatigue that no amount of coffee fully fixes. NAD+ supports neuronal function through multiple pathways: it feeds mitochondria in brain cells, activates neuroprotective sirtuins, and supports the production of neurotransmitters that regulate focus and mood. Athletes who train hard know that cognitive performance drops alongside physical fatigue; the two aren’t disconnected. But injections that restore NAD+ levels address both simultaneously, which is why many users report not just physical recovery improvements but also sharper thinking and better emotional regulation. In competitive environments, that mental edge is often the difference between executing under pressure and falling apart in the final stretch.
Conclusion
NAD+ injections help with recovery and performance by restoring a coenzyme your cells can’t function well without. From mitochondrial energy production to DNA repair, inflammation control, and neurological function, NAD+ touches nearly every system involved in how hard you can push and how fast you bounce back. The truth is, the injection form matters because it delivers the molecule at therapeutic concentrations your body can use right away, without the conversion losses that come with oral supplements. If recovery has been taking longer than it should, or your mental sharpness doesn’t match your effort level, a drop in NAD+ is worth taking seriously. Understanding how NAD+ injections help with recovery and performance gives you a clearer picture of what your cells actually need, and why restoring that coenzyme is a practical, biology-backed place to start.
A savings account should protect cash, support daily discipline, and help funds grow without unnecessary friction. The right fit depends on more than a posted rate. Access, fees, balance rules, deposit habits, and insurance coverage all affect results. Families benefit from judging each option against real goals, such as emergency reserves, medical bills, tuition, home repairs, travel, or a future purchase.
Every savings choice should begin with purpose. Emergency money needs quick access and predictable rules. Funds meant for a car, tuition, or property taxes may be subject to stricter limits. Clear labels also reduce impulse spending. When a household separates needs by timeline, each deposit carries a defined role, and progress becomes easier to measure.
Compare local options
Bakersfield residents often weigh convenience, relationship service, and dividend potential before placing cash. Branch access may matter for some families, while others prefer mobile deposits and automatic transfers. Reviewing savings accounts in Bakersfield helps households compare fees, access, rate terms, and balance requirements with fewer assumptions and better control.
Check the rate
The annual percentage yield gives a clearer picture than a headline rate. It includes compounding, which affects long-term growth. A higher yield may require a larger deposit, limited activity, or paired services. Savers should compare the full terms before moving funds. Small rate differences can matter once regular deposits build a meaningful balance.
Review fee rules
Charges can drain gains before a family notices. Monthly maintenance fees, paper statement costs, low balance penalties, and excess withdrawal charges deserve close review. Disclosures should make these items easy to find. A good test is simple: estimate likely costs using normal habits, rather than assuming every rule will be followed perfectly.
Know balance needs
Minimum balance requirements shape how useful an account feels. Some options waive fees after a set amount remains deposited. Others pay better dividends only above certain levels. That structure may suit established savers with stable reserves. Newer savers often need a lower opening requirement, since consistent deposits build strength over time.
Access matters
Access should match daily life, not disrupt it. Mobile transfers, direct deposit, branch help, and electronic statements can make saving easier. Still, instant availability may tempt unnecessary spending. The best setup gives families enough reach for urgent needs while keeping routine purchases away from protected funds.
Look at withdrawal limits
Withdrawal rules deserve attention before funds are deposited. Some savings options limit transfers, electronic payments, or certain account movements. These guardrails can support discipline, yet they may create pressure during irregular months. Savers should confirm allowed activity, fee triggers, and any restrictions tied to statement cycles.
Match tools to habits
Helpful tools turn intention into routine. Automatic transfers, balance alerts, goal labels, and scheduled deposits can support steady growth. Timing matters. A household paid every two weeks may benefit from moving money right after payday. That approach protects savings before bills, subscriptions, and discretionary purchases compete for attention.
Consider safety
Safety should never be treated as a minor detail. Federally insured deposits protect eligible balances within stated limits. Families should confirm coverage, login protections, fraud alerts, and notification settings. Strong safeguards reduce financial stress and help savers focus on building reserves, rather than worrying about basic account security.
Read the fine print
Introductory offers can help, but they may change quickly. A promotional rate might apply only to new money, selected balances, or a limited period. Disclosures explain what happens after the offer ends. Reading those terms early prevents confusion later and shows whether the account remains useful beyond the opening months.
Think about service
Service quality becomes important when questions arise. Joint ownership, beneficiaries, transfer holds, and account changes often need clear answers. Local support can help families resolve issues without feeling rushed. A provider that explains options plainly gives savers more confidence, especially during major life events or income changes.
Build a simple plan
Once an account is chosen, behavior drives the outcome. Families should set a target, choose a deposit amount, and review progress monthly. Increases can follow raises, paid-off debt, or lower expenses. A simple plan works because it removes guesswork and keeps savings connected to real priorities.
Conclusion
The strongest savings choice combines fair returns, transparent fees, practical access, clear limits, and reliable protection. No single feature should control the decision. Families make better choices by comparing the full structure, then matching it to income patterns and near-term needs. With regular deposits and occasional reviews, their savings can grow with less strain and greater confidence.
Life has a way of surprising us. Most days unfold quietly, following familiar rhythms, but every now and then something happens that changes everything in an instant. A road accident can leave more than bruises and broken bones. It can shake your confidence, disrupt your routines, and leave you wondering when life will begin to feel normal again.
Healing takes time, and it is rarely a straight path. Some days you will feel stronger, while others ask you to slow down and simply rest. Like so many things in Nordic living, recovery isn’t about rushing to the finish line. It’s about taking gentle, steady steps forward, trusting that each small choice helps you find your way back.
In the first days and weeks after an accident, your body needs your attention. Even injuries that seem minor can take time to reveal themselves, so following the advice of your doctor and attending any recommended appointments is one of the kindest things you can do for yourself.
If your accident involves insurance claims or legal matters, it can also help to seek professional guidance. As Attorney Matthew Trapani explains, having someone experienced to manage the legal process allows you to spend less energy worrying about paperwork and more energy focusing on your recovery.
Just as importantly, allow yourself to rest. We often underestimate the healing power of sleep, quiet, simple afternoons, and saying no to things that can wait. Your body is doing remarkable work beneath the surface, and it deserves the time and space to recover.
Don’t forget your emotional wellbeing
Physical healing is only one part of recovery.
It’s completely natural to feel anxious, frustrated, or even overwhelmed after an accident. Many people find themselves replaying the event in their minds or feeling nervous about getting back behind the wheel. Rather than pushing those feelings away, try meeting them with the same compassion you would offer a friend.
Research from the Centres for Disease Control and Prevention suggests that emotional wellbeing plays an important role in physical recovery. Looking after your mental health can support your body’s ability to heal while reducing the long-term effects of stress.
Simple conversations with people you trust can make an enormous difference. Sometimes a cup of tea shared with a friend or a quiet walk with someone who listens is exactly what your nervous system needs.
Peace of mind regarding justice is another important emotional aspect that helps people process difficult experiences. Seek credible injury law resources to find a way to navigate complex administrative processes with greater confidence. Gathering clear information allows individuals to make informed decisions without feeling overwhelmed. Having a structured plan in place ultimately offers reassurance during challenging times.
Healing through gentle daily habits
One of the things I love most about Nordic living is the reminder that wellness isn’t built through dramatic changes. It’s created through small, consistent habits that quietly support us every day.
While you’re recovering, try focusing on simple routines that nourish both body and mind:
Spend a few peaceful minutes breathing deeply before your day begins.
Choose wholesome meals filled with nourishing, natural ingredients.
Follow any gentle movement or stretching recommended by your physiotherapist.
Keep a notebook nearby and write down one small improvement each day.
These little moments may not feel significant at first, but together they become part of your healing.
Let life return slowly
It can be really tempting to jump straight back into your normal routine, especially if you’re used to being busy. But recovery always has its own pace.
Instead of trying to do everything at once (or eating the elephant whole as I say), begin with small tasks around the house. Fold some laundry. Water the plants. Sit outside with a blanket and a warm drink. Allow yourself to stop before you become completely exhausted.
Listening to your body isn’t a weakness; it’s wisdom. Pain and fatigue are gentle reminders that healing is still taking place.
Lean on the people around you
We aren’t meant to carry difficult seasons alone.
Whether it’s a neighbour offering to collect groceries, a family member helping with school runs, or a friend checking in with a simple message, accepting support allows you to focus your energy where it’s needed most.
If you’re finding recovery particularly difficult, support groups or counselling can also provide reassurance that what you’re experiencing is both understood and shared by others.
Create evenings that invite rest
One of the simplest gifts you can give yourself is a peaceful evening routine. Even if you are in perfect health, this is a great habit to have.
Turn off bright screens an hour before bed. Dim the lights. Read a few pages of a favourite book. Sip a calming herbal tea. Listen to gentle music or simply sit quietly for a few moments.
These small rituals help calm the nervous system and encourage deeper, more restorative sleep, giving your body the best opportunity to repair itself overnight.
Notice the small victories
Recovery is rarely measured in giant leaps.
Sometimes progress looks like walking a little further than yesterday. Sometimes it’s climbing the stairs in one hit, sleeping through the night, or realising you’ve smiled without thinking about your injuries.
Keeping a simple journal of these moments can be wonderfully encouraging. On difficult days, looking back reminds you just how far you’ve already come. Record ALL the wins however small because they are all worth something.
Healing isn’t about returning to who you were overnight. It’s about gently rebuilding your confidence, your strength, and your trust in yourself.
Like the changing seasons, recovery asks for patience. Give yourself permission to move slowly, accept help when you need it, and celebrate every small step forward. With time, care, and compassion, life gradually begins to find its rhythm again.