scroll top

Your neighbor is 74, sharp as ever, still driving herself to book club and refusing help with anything. Then one week she can’t remember if she paid the electric bill, and her son finds out she’s been sending $200 a month to a “grandson” who calls from a blocked number.

Independence in your 60s, 70s, and 80s doesn’t happen by accident. It’s built years earlier, through decisions most people make quietly and without fanfare: how much goes into a 401(k) before 55, whether the mortgage gets paid off, who’s named on a power of attorney form nobody wants to think about.

The habits below aren’t dramatic. None of them require a windfall or a financial advisor with a corner office. They’re the boring, repeatable choices that keep you in charge of your own life instead of handing that job to your kids, a court, or a stranger on the phone claiming to be from the government.

Delay claiming Social Security if you can afford to wait

Social Security
Image Credit: Shutterstock

If you were born in 1960 or later, your full retirement age is 67. Claim at 62 instead, and Social Security locks in a permanent cut to your monthly check for as long as you live. Wait until 70, and you’ll collect 124 percent of your full retirement age benefit, because the increase stops adding up once you turn 70.

The average retired worker collected $2,071 a month in January 2026, and someone who earned the maximum taxable amount every year for 35 years and claimed at full retirement age gets $4,152 a month. Each year you delay past 67 adds roughly 8 percent more to that number, permanently, up until you turn 70.

Waiting only makes sense if you can afford to. If you need the income now, have health problems that shorten your likely payout window, or you’re the lower earner in a marriage where your spouse already claimed, taking benefits early can be the smarter move. For everyone else with savings to lean on in their 60s, those extra years of patience become the largest guaranteed raise most people will ever see, one that keeps paying out for the rest of their life.

Keep three to six months of expenses in a fund you don’t touch
older lady with savings
Image Credit: Shutterstock

A car repair, a broken furnace, or a week in the hospital shouldn’t be able to unravel your retirement plan, but for a lot of older adults, it still can. Among Americans between 61 and 79, 41 percent have six months of expenses saved, while 16 percent have no emergency savings at all.

Three to six months of essential expenses, in a savings account you don’t touch for anything else, is still the standard financial planners recommend, and for good reason. Once you’re living on a fixed income from Social Security or a pension, there’s no overtime shift or side gig you can pick up on short notice to cover a surprise $4,000 bill. The money either exists already or it doesn’t.

Build it gradually if you have to. Automate a transfer of even $50 or $100 a paycheck into a separate account, and resist the urge to treat it as a second checking account for vacations or holiday gifts. The whole point of this money is that it sits there, boring and untouched, until the day your roof leaks or your car won’t start, and on that day, it’s the difference between an inconvenience and a crisis.

Pay off the mortgage before the paycheck stops
mortgage
Image Credit: Shutterstock

Carrying a mortgage into retirement used to be the exception. Now it’s closer to the rule. 41 percent of homeowners between 65 and 79 still carried mortgage debt in 2022, up from 24 percent in 1989, and the balances have grown along with the share of people carrying them.

A paid-off house changes the numbers on everything else. Once the mortgage is gone, Social Security and any pension or retirement withdrawals only have to cover property taxes, insurance, utilities, and maintenance, not a four-figure monthly loan payment on top of it. That’s often the difference between a retirement that feels manageable and one that requires picking up part-time work just to stay current on the house.

If you’re in your 50s or early 60s and still have 15 or 20 years left on your mortgage, run the numbers on paying extra toward the principal now, while you still have full-time income to work with. Even an extra $200 or $300 a month can shave years off the loan. If refinancing to a shorter term at a lower payment isn’t realistic, prioritize the payoff over goals that can wait, like a bigger vacation fund or a newer car.

Know Medicare’s enrollment deadlines before you turn 65

medicare ahead
Image Credit: Shutterstock

Missing your Medicare enrollment window doesn’t just delay your coverage. It costs you money for the rest of your life. Skip signing up for Part B when you’re first eligible, without qualifying employer coverage bridging the wait, and Medicare adds a 10 percent penalty to your premium for every 12-month period you went without it, permanently.

The standard Part B premium in 2026 is $202.90 a month. Wait two full years past your enrollment window, and that penalty alone adds roughly $40 a month for as long as you have Medicare, on top of whatever the premium itself climbs to in future years. Part D prescription coverage carries its own separate penalty if you go 63 days or more without creditable drug coverage.

Your Initial Enrollment Period runs seven months: three months before the month you turn 65, your birthday month, and three months after. If you’re still working past 65 with coverage through an employer plan, you may be able to delay Medicare without a penalty, but confirm that with your HR department before you assume it. Mark the date on your calendar the year you turn 64, not the week you turn 65, so there’s no scramble.

Push retirement contributions to the max in your 50s and 60s

retirement written on calculator
Image Credit: Shutterstock

The IRS lets people over 50 save more in a 401(k) than younger workers, and the older you get, the bigger that advantage becomes. In 2026, the standard 401(k) contribution limit is $24,500, but workers 50 and older can add a catch-up contribution to reach $32,500 total. If you’re 60, 61, 62, or 63 this year, that catch-up jumps, letting you put away $35,750 total.

IRA limits went up too. You can contribute $7,500 in 2026, or $8,600 if you’re 50 or older, whether that money goes into a traditional or Roth account.

Most people never come close to maxing these accounts out, but the years right before retirement are exactly when it matters most. Compound growth has less time to work its magic this late, so every extra dollar you contribute now is a dollar that isn’t relying on decades of market gains to grow. If a raise, a bonus, or the last of the kids moving out frees up cash in your budget, redirecting that money into retirement accounts before you get used to spending it is one of the most effective moves left on the table in your final working years.

Treat every unexpected call, text, or email as a threat until proven otherwise

landline phone
Image Credit: Shutterstock

Older adults reported more than $7.7 billion in fraud losses in 2025, a 59 percent jump from the year before, with the average victim over 60 losing more than $38,000. More than 12,400 people lost over $100,000 each.

The scams work because they create urgency and secrecy at the same time. Someone calls claiming to be from the Social Security Administration, the IRS, or your own bank, tells you your accounts have been compromised, and insists you can’t tell anyone, including your family, while you “fix” it. Real government agencies and banks don’t operate that way. They don’t ask you to buy gift cards, wire money, or move your savings into a “safe” account to protect it.

Make it a household rule: any unsolicited call, text, or email asking for money, account access, or personal information gets hung up on, deleted, or ignored, even if it sounds legitimate and even if it claims to be urgent. Call the organization back yourself, using a number you already have on file or find independently, never the number the caller gives you. If a family member is the one calling with an emergency, hang up and call them back on their known number before sending a cent.

Put a financial power of attorney in place before you need one
financial power of attorney
Image Credit: Shutterstock

A financial power of attorney lets someone you trust step in and manage your bank accounts, pay your bills, and handle your finances if you’re ever unable to do it yourself, whether that’s from a stroke, an accident, or dementia. Without one, your family has to go to court and ask a judge to appoint a conservator, a process that can take months and cost thousands of dollars in legal fees while your bills go unpaid.

Most people don’t have this document. 56 percent of American adults have none of the core estate planning documents, including a financial power of attorney, and will ownership actually dropped to 26 percent this year.

This isn’t just a document for people with complicated finances or large estates. Anyone with a bank account benefits from naming someone in advance, on their own terms, rather than leaving a judge to pick a stranger or a distant relative later. An estate attorney can draft one in a single meeting for a few hundred dollars, and many states offer simple statutory forms you can fill out yourself. Choose someone you trust completely, name a backup in case your first choice can’t serve, and give them the actual document, not just a vague promise that they’re “in charge” if something happens.

Say no to cosigning loans for your adult kids

co-signed loan
Image Credit: Shutterstock

Cosigning seems like an easy way to help your kid get an apartment, a car, or through college when their own credit isn’t strong enough yet, but it rarely stays that simple. People 55 and older make up 57 percent of student loan cosigners, and cosigning makes you just as responsible for that debt as if it were your own.

A survey of parent cosigners found more than a third had regretted the decision, and roughly a third had watched a missed payment show up on their own credit report when their child fell behind. It happens at exactly the point in life when you’re trying to qualify for your own refinance or protect a credit score you’ve spent decades building.

If your child needs help, there are ways to give it that don’t put your name, and your retirement, on the line: a gift toward the down payment, a shorter-term cosigned lease instead of a mortgage, or simply telling them you can’t cosign but can help another way.

Price out long-term care before you’re the one who needs it
long term care
Image Credit: Shutterstock

Long-term care is expensive enough to derail decades of careful saving, and Medicare doesn’t cover most of it. A private room in a nursing home runs a national median of $355 a day, or roughly $129,575 a year, and even a semi-private room averages $114,975 a year. Assisted living communities cost less but still add up to around $74,400 a year nationally.

Long-term care insurance is one way to cover that risk, and it’s cheapest when you buy it earlier rather than later. A healthy 55-year-old couple pays around $5,010 a year combined for $165,000 in initial benefits, and premiums climb noticeably with every year you wait.

Insurance isn’t the only answer, and it isn’t right for every budget. Some people self-fund by earmarking a portion of savings specifically for care costs, and some rely on a mix of home equity and family support instead. What matters is picking a plan on purpose, in your 50s or early 60s while you’re still insurable and thinking clearly, rather than leaving your children to figure out how to pay for a nursing home the week you’re admitted to one.

Freeze your credit even when nothing’s wrong
credit freeze
Image Credit: Shutterstock

A credit freeze is free, and it blocks anyone, including you, from opening new credit in your name until you lift it. It’s one of the few fraud protections that actually works, because it stops identity theft before it starts instead of asking you to catch it after the damage is done.

Older adults are squarely in the crosshairs. Adults 55 and older get the highest volume of suspicious calls, texts, and emails of any age group, with more than a quarter receiving 11 or more a week, and identity theft reports hit more than 1.3 million in 2025, with total fraud losses topping $15.8 billion.

You don’t need to have been targeted to freeze your credit, and you don’t need to pay a credit monitoring service to do it. Contact all three credit bureaus, Equifax, Experian, and TransUnion, request a freeze on each one separately, and keep the PIN or password they give you somewhere safe so you can lift it temporarily if you actually apply for a loan or credit card. It takes about ten minutes total and closes off the single most common way criminals profit from a stolen Social Security number.

Automate the bills you can’t afford to forget
happy that bills are paid
Image Credit: Shutterstock

Payment history makes up roughly 35 percent of your FICO score, the single largest factor in the formula, and a payment reported 30 days late can sit on your credit report for up to seven years. As you get older, the consequences of a missed payment only get more serious: a lender who won’t approve you for a home equity loan, a card issuer who cuts your credit limit, an insurer who bumps your rate.

Missing a payment is usually about timing, not money: a bill arriving during a hospital stay, a due date that quietly changed, or simply losing track of which of a dozen accounts is due when. Automating the essentials, mortgage or rent, utilities, insurance, and at least the minimum on every credit card, removes that risk from your memory entirely.

Set it up once, then check your bank and credit card statements monthly anyway, since automation isn’t the same as ignoring your accounts. A card that expires, a closed checking account, or a failed transfer can cause a missed payment even when you thought everything was on autopilot. Pair automation with a monthly ten-minute review, and you get the protection without losing track of where your money is going.

Keep some income coming in, even after you stop working full time
Customer service representative
Image Credit: Shutterstock

Retiring completely and working full time aren’t the only two options, and a growing number of older adults are choosing something in between. 38 percent of adults 65 and older worked part time in 2024, whether for the money, the structure, or simply staying connected to other people.

If you haven’t reached your full retirement age and you’re already collecting Social Security, there’s a real limit to watch. In 2026, you can earn up to $24,480 before Social Security withholds $1 in benefits for every $2 you earn above that. Once you reach full retirement age, that limit disappears completely and you can earn as much as you want without any reduction.

A part-time job, consulting work in your old field, or even a few paid hours a week doing something you’re good at accomplishes more than padding your bank account. It keeps a second source of income flowing so a bad year in the market doesn’t force you to sell investments at a loss just to cover groceries, and it gives your days structure that a lot of new retirees find themselves missing more than they expected.

Downsize before your house forces the decision
older couple downsizing
Image Credit: Shutterstock

The house that made sense for raising kids doesn’t always make sense for a fixed income and a body that’s slower to climb stairs. Cost-burdened older households, meaning they spend more than 30 percent of income on housing, hit a record 34 percent in 2023, more than 12.4 million households, and that number keeps climbing as property taxes, insurance, and maintenance costs rise faster than fixed incomes do.

Waiting until a fall, a health scare, or a maintenance emergency forces the issue usually means moving under pressure, at a worse price, with less choice about where you land. Downsizing on your own timeline, while you’re still healthy enough to sort through decades of belongings and handle a move, gives you options that disappear once a crisis makes the decision for you.

That doesn’t necessarily mean leaving the neighborhood or moving into assisted living years before you need it. A smaller home, a condo with no yard work, or a one-story layout that doesn’t depend on stairs can all free up equity and cut ongoing costs while keeping you independent for longer, not less. Talk to a real estate agent and a financial advisor together, not separately, so the sale price and the tax and Medicaid implications get considered at the same time.

Update your beneficiary designations, not just your will
beneficiary designations
Image Credit: Shutterstock

A will doesn’t control who inherits your 401(k), IRA, or life insurance policy. Beneficiary designations on those accounts operate as separate legal contracts, and they override your will completely, even when the two documents say different things. Workers aged 55 to 64 hold an average of $271,320 in their retirement accounts, which makes an outdated form an increasingly expensive mistake.

Someone divorces, remarries, has a grandchild, or loses a spouse, and updates their will to reflect it, but never circles back to the beneficiary form filed with their old employer’s 401(k) years earlier. When they die, the account goes to whoever’s name is still on that form, an ex-spouse or a person who’s no longer part of their life, regardless of what the will says or what anyone intended.

Pull up every retirement account, life insurance policy, and payable-on-death bank account you own, log into each one, and confirm exactly who’s listed as primary and contingent beneficiary. Do this after every major life event, a marriage, a divorce, a death in the family, a new grandchild, and check it again every few years even when nothing’s changed. It takes minutes per account and it’s free.

Put your medical wishes in writing too, not just your money
living will
Image Credit: Shutterstock

A financial power of attorney covers your money. It doesn’t cover a decision about whether you want to be resuscitated, kept on a ventilator, or moved to hospice care if you can’t speak for yourself. That requires a separate document, usually called an advance directive or a healthcare power of attorney, and most older adults don’t have one. Only 46 percent of adults over 50 have documented their advance healthcare preferences in a legally binding way.

Without it, doctors and hospitals default to state law to decide who speaks for you, usually a spouse first, then adult children, which can mean multiple family members disagreeing about your care at the worst possible moment, with no guidance about what you actually wanted.

Two documents do the job: a living will, spelling out the specific treatments you do and don’t want, and a healthcare power of attorney, naming the person who can make calls your living will doesn’t cover. Many hospitals and state bar associations offer free forms, no attorney required, and the conversation with your family about what’s actually in them matters as much as the paperwork itself.
You know the drawer. The one with a hundred jewel cases stacked sideways, half of them cracked, most of them mix CDs you burned in 2004. It feels like the most obsolete clutter in the house. But CD collecting has quietly turned into real money again, and the reason has nothing to do with sound quality or nostalgia playlists. It comes down to which pressing you have, how many were made, and whether yours survived in the condition collectors want.

Most CDs really are worth next to nothing. A regular jewel case copy of an album that sold five million units isn’t scarce just because it’s old. What moves the needle is a small, specific list of things: promotional copies never meant for retail, pressings that got pulled and destroyed before most of the run reached stores, early runs in the tall cardboard “longbox” packaging that disappeared in 1993, and Japanese pressings with the paper obi strip still attached to the spine.

None of the discs below are museum pieces locked away in a vault. These are things that ended up in ordinary collections: a promo a radio DJ brought home, a longbox someone never got around to opening, an import a friend brought back from a trip. A few are genuine long shots. Most are the kind of find that’s actually plausible if you dig through a box in the garage.

Tool “Aenima” original lenticular cover CD (1996)

Tool CD
Image Credit: hyperel via eBay

The first pressing of Tool’s “Aenima” didn’t use a printed cover. It used a lenticular image, the kind that shifts and appears to move depending on the angle you’re holding it at, showing a distorted face that seems to breathe. It was an expensive packaging choice for a mid-90s CD, and later pressings and reissues switched to a flat printed version because the lenticular process was costly to keep running.

Clean original lenticular copies typically bring $200 or more, with sealed examples pushing higher still. The tell is tactile as much as visual: run a finger over the cover and you should feel the ridged, slightly textured surface of a true lenticular print, not a smooth photograph. Reissues use a static image of the same design, which looks similar in a photo but doesn’t shift when you tilt it.

Condition matters more here than on most 90s CDs because the lenticular surface scratches and delaminates more easily than a normal printed cover. Cracked jewel cases are common and expected on a 30-year-old disc, but a scuffed or peeling lenticular front cuts the value noticeably. Check the corners first, since that’s where the coating tends to lift.

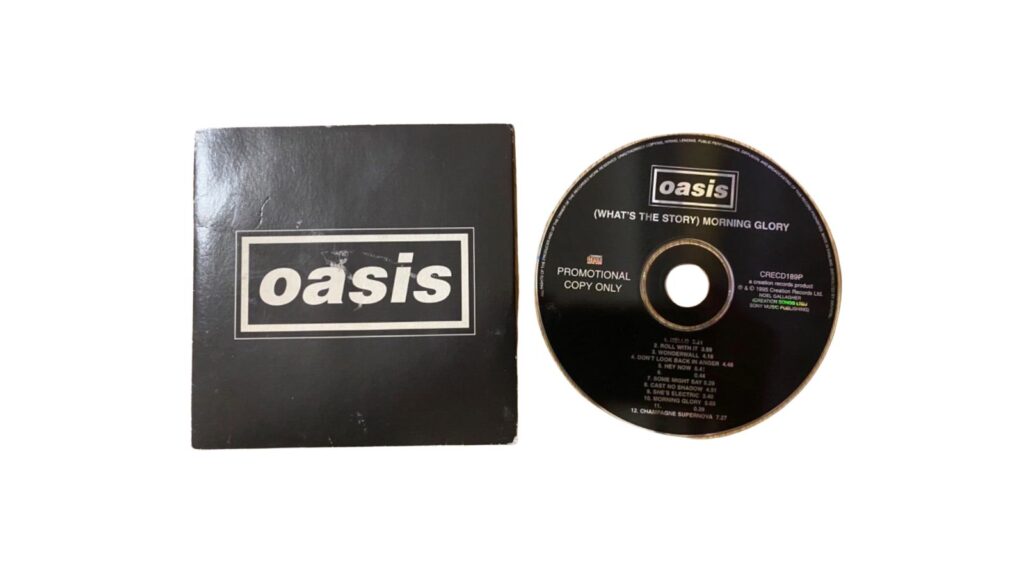
Oasis “(What’s the Story) Morning Glory?” UK promo CD (1995)

Oasis CD
Image Credit:
bbv1531 via eBay

Oasis’s second album is one of the best-selling British records of all time, so the standard retail CD is worth almost nothing. The promotional copies sent to UK press and radio ahead of release are a different story. These were issued in small batches with distinctive artwork and inserts meant for industry use only, not for sale, and most were never meant to survive past a single listen by a reviewer.

Clean examples with the promo-only packaging and inserts intact typically bring $100 or more, with well-preserved copies commanding a real premium over any retail pressing. Look for “promotional copy, not for resale” language printed on the disc face or insert, along with any radio station stamps or handwritten track notes, which are common on genuine promos and don’t hurt the value.

The retail version of this album is everywhere and worth pocket change, so don’t assume any copy with the familiar sleeve is valuable. It’s specifically the promo-only issue, not a standard first pressing, that collectors are after. If your copy doesn’t say “not for sale” anywhere, it’s almost certainly a regular retail disc.

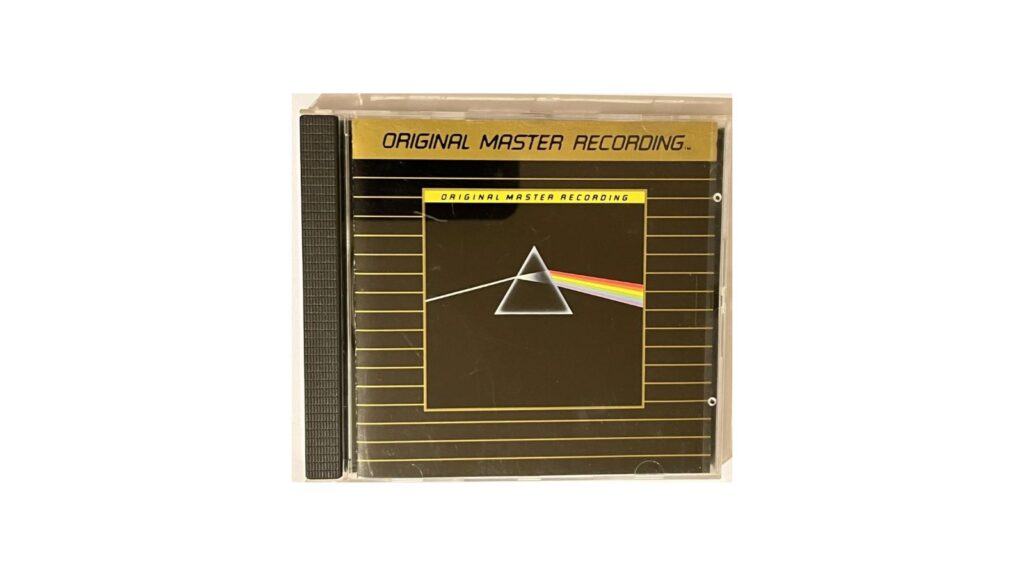
Pink Floyd “Dark Side of the Moon” 24-karat gold CD (Mobile Fidelity, UDCD 517)

pink floyd
Image Credit:
Imhotep’s Emporium via eBay

Mobile Fidelity Sound Lab spent the 1990s remastering classic albums onto 24-karat gold discs under its Original Master Recording banner, sold at a premium over standard CDs when new. The Dark Side of the Moon edition is the best known of the run, remastered from the original tapes and pressed on gold instead of standard aluminum, which was marketed at the time as a more durable, less prone-to-degrade format.

Clean used copies typically bring $40 to $150, and sealed, unopened examples have reached $300 or more. The gold disc itself, the “UDCD 517” catalog number on the spine, and the Mobile Fidelity branding on the booklet are what to check for. A regular black Warner/Capitol pressing of the same album is worth almost nothing by comparison.

Mobile Fidelity pressed gold discs for dozens of other titles too, including Rush’s “Moving Pictures” and various Bob Dylan and Steely Dan albums, and most of those carry similar premiums in the same general range. The booklets are prone to edge wear and yellowing, so a crisp, unmarked booklet adds real value on top of a clean disc.

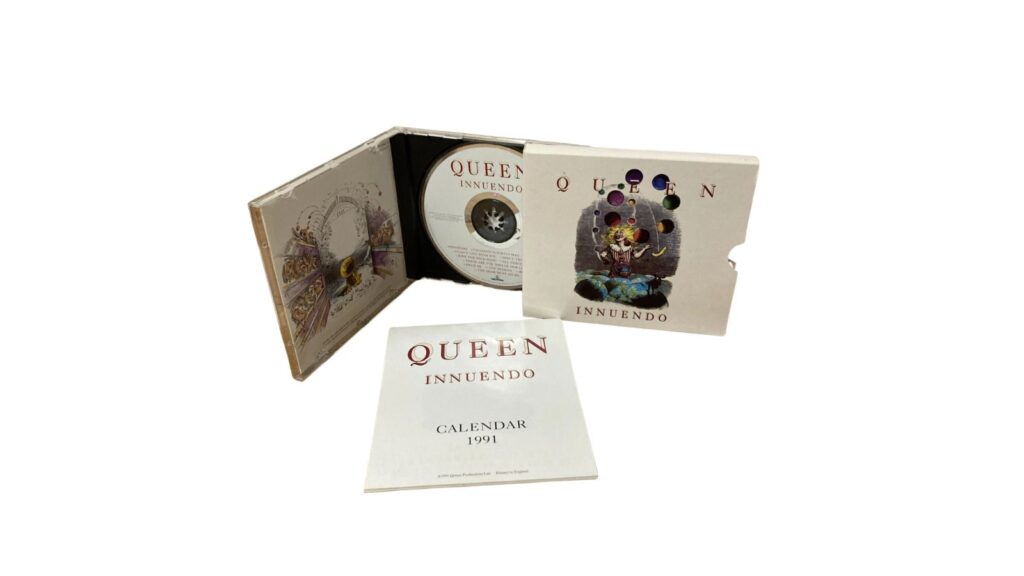
Queen “Innuendo” Hollywood Records promo CD (1991)

Queen CD
Image Credit: darrenp3211 via eBay

Not every Queen collectible involves a hunt through vinyl bins. This promotional pressing of “Innuendo” was distributed by Hollywood Records to radio and industry contacts around the label’s 1991 reissue push for the band’s catalog, marked as promotional stock rather than a standard retail release. The whimsical, art-directed packaging on the promo run is what separates it visually from the plain retail jewel case most fans own.

Clean sealed copies typically sell for around $200, well above what a standard used copy of “Innuendo” brings. A disc that’s been opened and played is worth a fraction of that, since it’s the sealed, unplayed, still-promotional condition that collectors are paying the premium for.

Promo pressings from this label and era are easy to confuse with ordinary reissues at a glance, so check for “promotional use only, not for sale” language on the back cover or spine before assuming a copy is the rarer version. A standard retail “Innuendo” CD, which is common and inexpensive, will lack that language entirely.

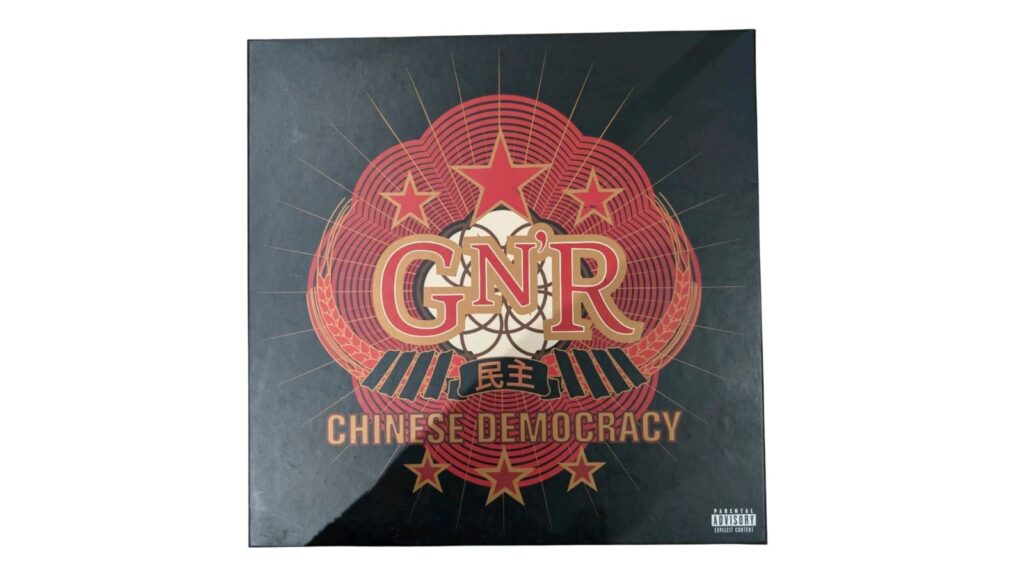
Guns N’ Roses “Chinese Democracy” red hand cover CD (2008)

guns n roses
Image Credit: gasm_6329 via eBay

“Chinese Democracy” took over a decade to make and became one of the more famous “will it ever come out” stories in rock. The standard US retail release used black cover art, but a variant pressing circulated with red hand artwork on the cover instead, tied to a specific retail run rather than the mainstream pressing most stores carried.

Clean sealed copies of the red hand variant typically carry a value of around $350, a real premium over the standard black-cover version, which is common and worth little more than a few dollars. This is a genuinely recent release as collectible CDs go, which makes it a good reminder that scarcity, not age, is what drives value in this hobby.

Because this album came out well into the digital era, most surviving copies are still factory sealed rather than played and worn, so condition differences are usually about the shrinkwrap and spine rather than disc scratches. A torn or missing shrinkwrap on the sealed variant meaningfully reduces what a buyer will pay, since sealed status is a big part of the appeal here.

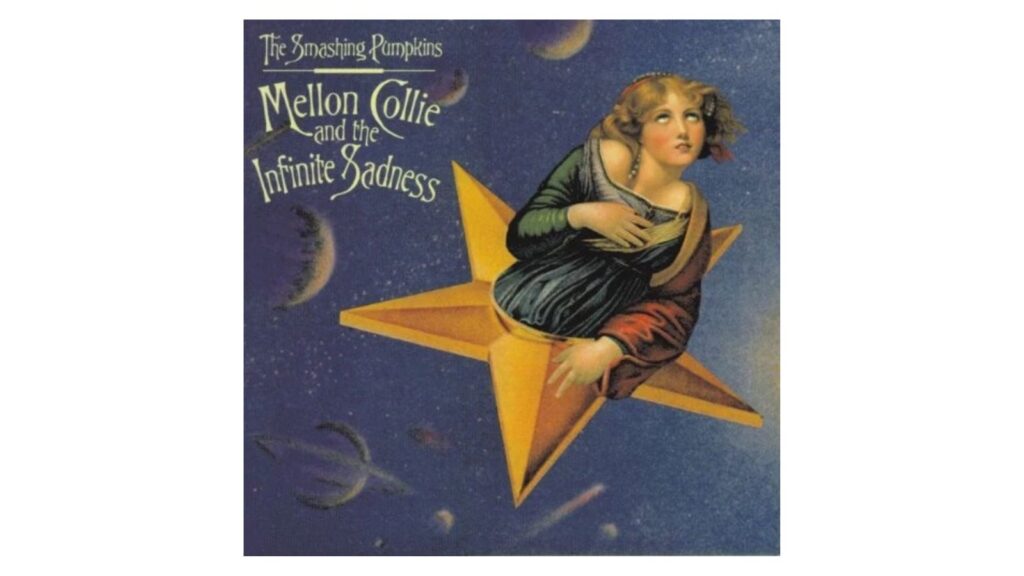
Smashing Pumpkins “Mellon Collie and the Infinite Sadness” original box set CD (1995)

smashing pumpkins
Image Credit: Shutterstock

The double-disc “Mellon Collie” arrived in a deluxe box packaging with exclusive artwork, an expanded lyric booklet, and print inserts not included in the standard two-disc jewel case version most stores sold. It was a genuinely elaborate release for a mid-90s alternative rock album, closer to a small art object than a typical CD package.

Complete original box sets in clean condition sell in a range of roughly $240 to $1,700, with the middle of that range sitting around $640 for a solid, complete example. The gap between the low and high end comes down almost entirely to completeness: every insert, both discs, and the box itself in good shape versus a box missing pieces or showing heavy shelf wear.

The standard double jewel case version of this album is common and worth little, so the box packaging itself is what separates a real find from a regular used CD. Check the corners of the box for crushing, since it’s a lightweight cardboard structure that doesn’t hold up well to being stacked under other things for thirty years.

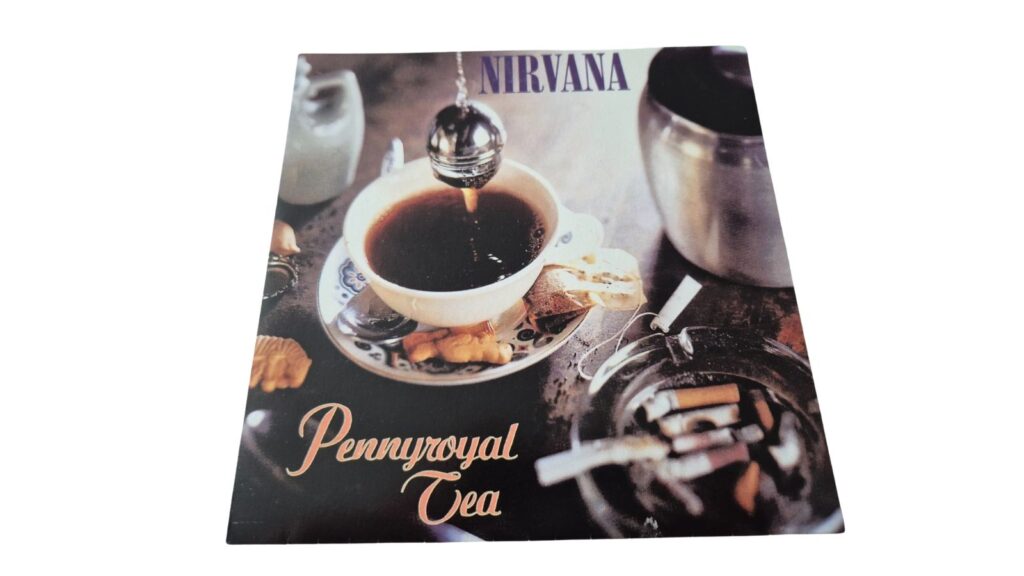
Nirvana “Pennyroyal Tea” German CD single (Geffen, 1994)

Nivarna
Image Credit:
aetherial_practitioner via eBay

This single was scheduled for an April 1994 release to promote “In Utero,” pressed in Germany ahead of the date. Kurt Cobain died on April 5th, days before release, and Geffen pulled the single and destroyed the vast majority of the pressing out of sensitivity to the timing. A small number of copies had already left the pressing plant or reached early distribution points before the recall took effect.

Surviving German copies typically bring $600 to $1,560 depending on condition and completeness of the packaging. This is a case where the music itself was never rare. “Pennyroyal Tea” appears on “In Utero,” which sold millions of copies. It’s specifically this withdrawn single pressing that’s scarce, because almost none of them reached the public.

Given the value, counterfeits and misattributed later reissues circulate. Check the catalog details and German pressing markings carefully against a reliable identification source before assuming a copy is genuine, and be skeptical of any example lacking the correct German label information on the disc and packaging.

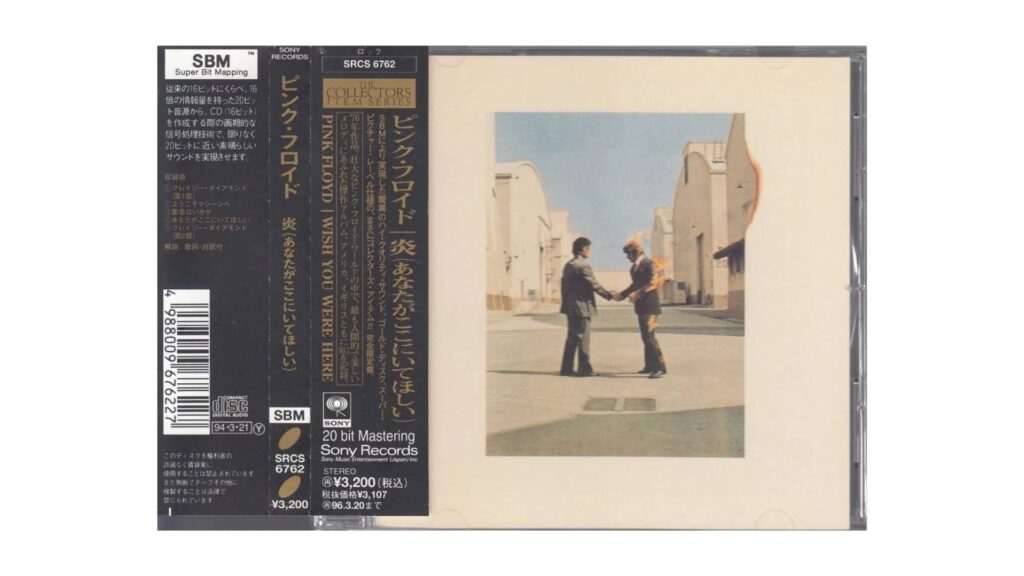
Pink Floyd “Wish You Were Here” Japanese CD (Sony, catalog 35DP-4)

Wish you were here
Image Credit:
tokyo_satoshi_japan via eBay

Japanese CD manufacturing in the 1980s and early 1990s had a reputation for tighter quality control and better disc materials than many Western pressing plants, and Japanese releases typically included a paper obi strip wrapped around the spine with the title and catalog information printed vertically. That strip, more than almost anything else on a Japanese CD, is what collectors are checking for.

Clean examples of this pressing with the obi strip intact typically bring $500 to $1,500. Losing the obi strip can cut the value of a Japanese pressing by roughly a third to half, since it’s a thin paper band that was easy to misplace or discard when the CD was first unwrapped decades ago and is difficult to reproduce convincingly.

If you have any Japanese-pressed CDs from this era sitting in a collection, the obi strip is the first thing worth checking, regardless of the artist. It’s a detail that’s easy to overlook because it isn’t part of the disc or the jewel case itself, just a loose paper wrap that either survived the last thirty years or didn’t.

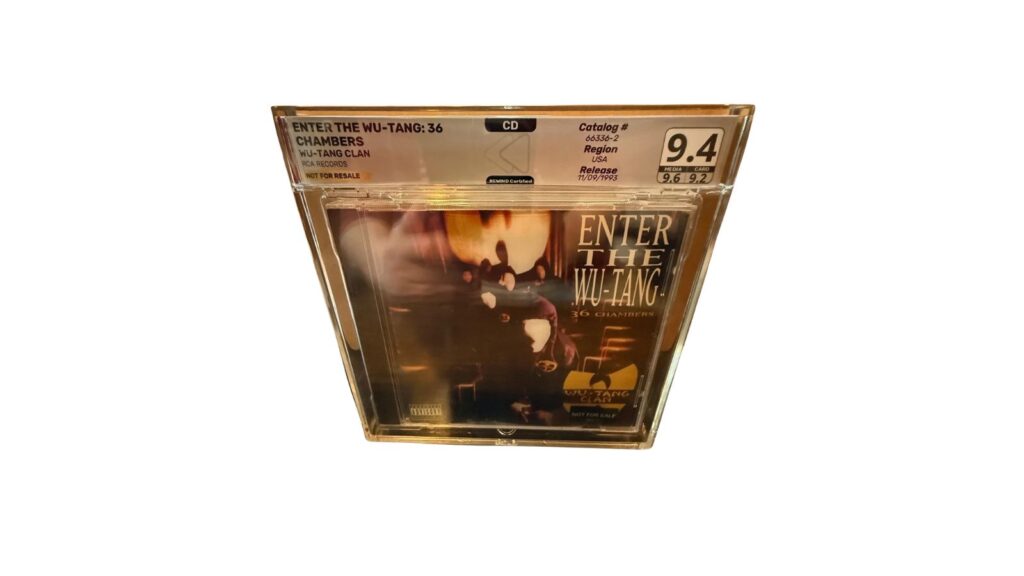
Wu-Tang Clan “Enter the Wu-Tang (36 Chambers)” promotional CD (1993)

wu tang clan
Image Credit:
LE Collectibles Store via eBay

The Wu-Tang Clan’s debut is one of the foundational albums in hip-hop, and the standard retail CD reflects that: it sold well and isn’t scarce. The promotional copies issued to radio programmers and press ahead of release are a different matter, marked “not for sale” directly on the disc face and packaged with a sticker distinguishing them from the retail version.

Clean examples with the promotional markings intact are collectors are willing to pay over $1,000 for a piece of hip-hop history this significant. The retail version, by contrast, is genuinely common and worth a few dollars in used condition, so the promotional stamping is the entire difference in value here.

Because early 90s hip-hop promos are actively sought after, misidentified retail copies sometimes get listed as promos by sellers who either don’t know the difference or hope buyers won’t check. Look specifically for “not for sale” printed directly on the disc, not just on a removable sticker, since stickers can be transferred between discs.

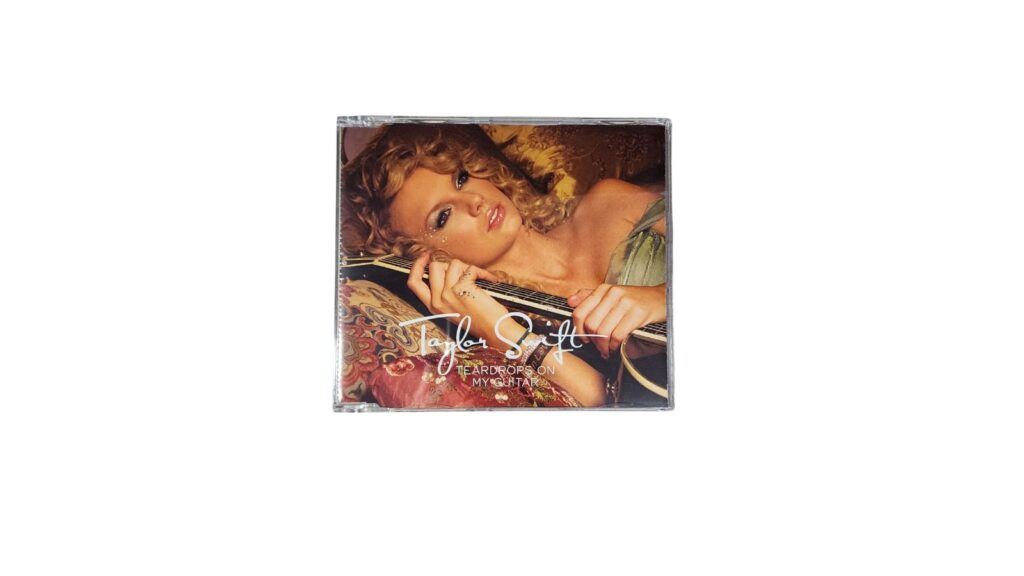
Taylor Swift “Teardrops on My Guitar” promotional CD single

taylor swift
Image Credit: gettshine11 via eBay

Released to promote Taylor Swift’s debut album, this radio promo single was pressed in limited numbers well before Swift became one of the best-selling artists in the world. At the time, it was a routine industry mailer sent to country radio stations, not something anyone treated as a future collectible.

Clean examples now bring more than $1,200, a reflection of how early-career promotional material from major artists tends to appreciate once their catalog and fanbase grow substantially. Fans specifically seeking out pre-fame promotional material have driven demand for this and similar early Swift releases well beyond what a typical country radio promo would normally command.

As with any promo tied to a currently massive artist, verify the pressing details carefully before paying a premium, since counterfeits and misdescribed reissues are more likely to circulate around in-demand names. Genuine promotional copies carry “promotional use only” language and typically lack standard retail barcodes and packaging, which is the quickest way to separate a real promo from a later fan-made or reissued item.

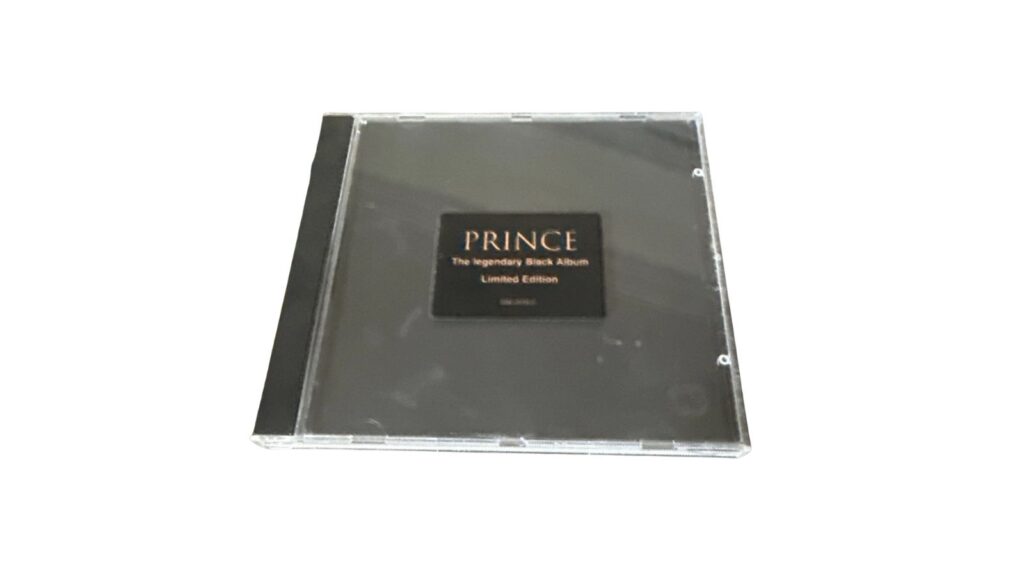
Prince “The Black Album” promotional CD (1987)

prince
Image Credit: vjs01 via eBay

Prince recorded “The Black Album” for release in December 1987, then abruptly ordered the master tapes destroyed and pulled the album days before street date, reportedly telling associates he found its darker themes troubling. A small number of promotional copies had already gone out to industry contacts before the withdrawal, and those are what collectors chase today. The album was eventually given an official retail release in 1994, and that later version is common and inexpensive, worth only a few dollars used.

It’s specifically the surviving 1987 promotional pressings, not the 1994 reissue, that trade for $3,000 to $8,875, with one confirmed example reaching the top of that range. The gap between a worthless reissue and a five-figure promo comes down entirely to correctly identifying which pressing you’re holding.

Given the enormous price difference between the two versions, verifying pressing details before assuming you have something valuable is essential. The 1994 official release carries standard retail packaging and a barcode; the 1987 promotional pressings predate that packaging entirely and carry different, less polished markings consistent with an unfinished, pulled release.

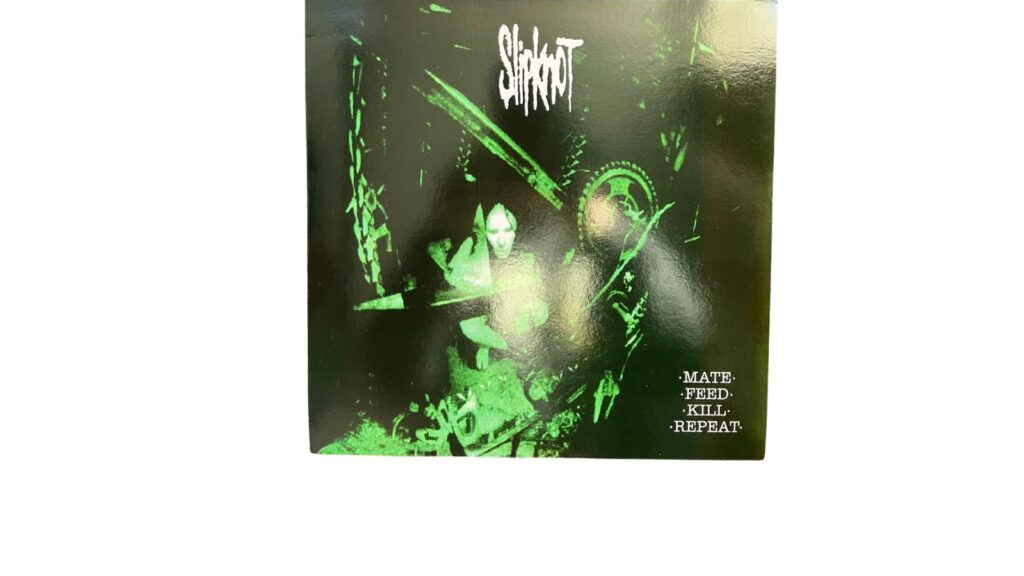
Slipknot “Mate. Feed. Kill. Repeat.” (1996)

slipknot
Image Credit: SMASHYOURCD via eBay

Before signing to a major label, Slipknot self-financed and self-distributed this independent debut, pressed in a run of exactly 1,000 copies with a forest green disc face. The band handed copies out to fans, radio stations, and record labels directly. Two members who later became core to the band’s lineup hadn’t joined yet when it was recorded, and none of its songs appeared in this exact form on any later official release.

Genuine original copies typically carry a value of $1,200 or more, a remarkable figure for a self-released demo from a band nobody outside Iowa had heard of yet at the time. Since Slipknot’s rise to mainstream fame in the late 90s, this original pressing has become one of the most actively sought after items in the nu-metal collector world.

Because of the price this title commands, it’s also one of the most heavily bootlegged CDs in the genre, reproduced on CD, cassette, and even vinyl over the years. Genuine copies have a forest green disc face and specific booklet details that differ from known bootlegs, and any copy should be checked carefully against documented identification points before it’s treated as authentic.

Most of what’s sitting in a CD binder really is worth a dollar or two, and that’s fine. But it only takes one longbox, one promo sticker, or one obi strip to turn a box destined for the donation pile into something worth a genuine second look.

Some of the best-paid jobs are built around work most people would rather not think about: maintenance schedules, inspections, permits, inventory, compliance meetings, equipment logs, benefits paperwork, and the same operational problems showing up every Monday morning.

That routine can be valuable. When the work involves a professional license, a physical facility, a regulated product, expensive machinery, or legal responsibility, companies still need experienced people who can make decisions and take responsibility when something goes wrong.

1. General dentist

happy dentist
Image Credit: Shutterstock

General dentistry is far less glamorous than television makes medicine look. Much of the week is a repeating loop of exams, fillings, crowns, X-rays, numbing injections, treatment plans, and checking the work of hygienists. General dentists have median pay of $172,790 per year. Employment is expected to keep growing at about the pace of the overall job market, with thousands of openings each year as dentists retire or leave practice.

The reason this work has staying power is simple: teeth still have to be examined and repaired by a licensed person working directly inside a patient’s mouth. Older adults are also keeping their natural teeth longer, which means more years of cleanings, restorations, gum care, and other routine treatment. Getting there is not quick. You need undergraduate coursework, a dental degree, clinical training, exams, and a license. But unlike surgical specialties, a general dentist can build a career around scheduled office visits and fairly predictable procedures. Dental groups, private practices, community clinics, and outpatient centers all employ them, and the daily work is repetitive enough that plenty of people decide the paycheck is more interesting than the job itself.
2. Pharmacy operations manager

Pharmacy operations manager
Image Credit: Shutterstock

A pharmacy operations manager lives in a world of prescription queues, controlled-drug counts, staffing schedules, inventory reports, insurance problems, refrigerator temperatures, audits, and procedures that must be followed exactly. Average pay is about $180,060 per year. The job can exist in hospital systems, outpatient pharmacies, specialty pharmacies, large dispensing operations, and other healthcare organizations.

This is not simply an office manager with a pharmacy attached. These managers are usually licensed pharmacists, and they are responsible for keeping medication operations safe and compliant while supervising pharmacists and technicians. That licensing requirement creates a serious barrier to entry, but it also protects the work from being handed off to a cheap outside vendor. Dispensing equipment can count pills and software can flag interactions, yet a licensed professional still has to oversee medications, controlled substances, errors, staffing, and regulatory requirements. The usual route is a PharmD, pharmacist licensure, several years working as a pharmacist, and then supervisory experience. If you can tolerate constant checking, documenting, reconciling, and answering the same operational questions, it is a surprisingly lucrative form of healthcare management.

3. Benefits director

Remote benefits director
Image Credit: Shutterstock

Benefits directors spend their careers thinking about deductibles, enrollment rules, health plans, disability coverage, retirement programs, vendor contracts, eligibility disputes, and federal requirements. It is the kind of work that can make a 70-page plan document seem like an exciting afternoon. Average pay is around $192,292 per year. Large employers, hospital systems, manufacturers, universities, insurers, and other organizations with big workforces need people to run these programs.

The job is durable because employers cannot simply stop administering health and retirement benefits when the paperwork becomes annoying. Someone has to select vendors, monitor costs, handle escalated problems, make sure plans follow the rules, and explain major changes to executives and employees. Routine enrollment work can be streamlined, but responsibility for a multimillion-dollar benefits program still sits with people. Most directors work their way up through benefits administration, human resources, consulting, or employee-benefits management and have many years of experience before reaching this level. A bachelor’s degree is common, along with specialized benefits credentials. This is a good example of a high salary tied less to excitement than to complexity, regulation, and the fact that mistakes can become very expensive very quickly.

4. Pipeline integrity engineering senior manager

Pipeline integrity engineering senior manager
Image Credit: Shutterstock

Pipeline integrity sounds dramatic until you see what much of the job actually involves. Senior managers review inspection results, corrosion readings, maintenance histories, repair schedules, pressure records, contractor work, and long lists of pipe segments that need more attention. Average pay is about $189,000 per year. Employers include pipeline operators, utilities, energy companies, engineering firms, and infrastructure contractors.

The work persists because buried pipe does not stop aging just because nobody wants to think about it. Corrosion, cracking, coating damage, ground movement, and equipment failures all have to be monitored, and pipeline operators face strict inspection and safety obligations. A computer can sort inspection readings, but deciding whether a section can remain in service, needs excavation, or requires immediate repair carries real engineering and safety consequences. Most people reach this level after an engineering degree and many years in pipeline, corrosion, mechanical, or integrity work. Professional engineering credentials and corrosion or inspection certifications can help. It is a niche career, which is part of the appeal. There are fewer qualified people competing for these jobs than for broad corporate management roles, while miles of existing infrastructure continue to require inspection and maintenance.

5. Facilities engineering director

Facilities engineering director
Image Credit: Shutterstock

A facilities engineering director is responsible for everything in a large building that nobody notices until it stops working. Think chillers, boilers, generators, electrical systems, pumps, elevators, fire systems, preventive maintenance, inspections, work orders, and replacement schedules. Average pay is about $185,939 per year. These roles show up in hospitals, research campuses, factories, universities, laboratories, large office complexes, and other buildings that cannot simply close when the air conditioning fails.

Much of the job is repetitive by design. Equipment gets inspected on a schedule. Filters get changed. Generators get tested. Contractors submit bids. Old systems eventually reach the top of the replacement list. That routine is also why the role is hard to eliminate. Physical buildings still need people who understand their mechanical and electrical systems and who can make calls when something leaks, overheats, trips, or fails an inspection. Directors usually come up through facilities engineering, mechanical or electrical engineering, plant operations, or large-building maintenance. A degree is common at this level, and energy-management or professional engineering credentials can help. The paycheck reflects responsibility for expensive assets and uninterrupted operations, not a constant supply of fascinating new problems.

6. Chemical process engineering director

Chemical process engineering director
Image Credit: Shutterstock

Chemical process engineering directors oversee the controlled, repeatable steps used to turn raw materials into finished products. Their calendars fill with process limits, piping changes, equipment reviews, production data, safety studies, permits, shutdown plans, and meetings about why a batch behaved differently than expected. Average pay is about $198,584 per year. You find these jobs in chemical manufacturing, specialty materials, industrial processing, pharmaceuticals, and other plants built around tightly controlled production.

The work has staying power because pumps, tanks, reactors, heat exchangers, and piping exist in the physical world. Plants also operate under safety and environmental rules that require experienced people to approve changes and investigate problems. Most days are not emergency scenes. They are reviews of operating conditions, maintenance needs, process changes, and whether the plant is staying inside approved limits. The usual path starts with a chemical engineering degree followed by years of process, production, or plant engineering work. Leadership experience becomes important as you move toward director level, and a professional engineering license can add credibility. It is highly technical, but often in a painstaking, procedural way. That combination of specialized knowledge and routine responsibility helps explain the pay.

7. Manufacturing process engineering director

Manufacturing process engineering director
Image Credit: Shutterstock

Manufacturing process engineering directors obsess over things such as cycle time, scrap rates, machine settings, line balance, downtime, tool changes, and why one production step suddenly takes 14 seconds longer than it did last month. Average pay is around $183,500 per year. These directors work in aerospace, medical devices, industrial equipment, consumer goods, food production, and other businesses that make physical products.

A lot of the work amounts to making an already functioning process slightly more dependable, less wasteful, and easier to repeat. That may not make for a gripping dinner story, but manufacturers care deeply about it because a small production problem repeated thousands of times can cost a fortune. New equipment also has to be installed, tested, documented, and integrated without wrecking output. People typically reach this job after an engineering degree and years in process, manufacturing, industrial, or production engineering, followed by management experience. Physical production gives the role a useful layer of protection. Someone still has to walk the floor, understand equipment, coordinate maintenance and operators, approve changes, and take responsibility for whether a process can reliably produce acceptable products.

8. Healthcare quality assurance director

Healthcare quality assurance director
Image Credit: Shutterstock

If your idea of excitement is reviewing incident reports, preparing for accreditation surveys, checking quality dashboards, and following up on corrective-action plans, healthcare quality assurance could be your place. Directors earn about $179,089 per year on average. Hospitals, health systems, clinics, long-term-care organizations, insurers, and other healthcare operations use these leaders to keep quality and patient-safety programs functioning.

The job is built around accountability. A questionable patient outcome cannot simply be marked “resolved” by software and forgotten. Someone has to investigate what happened, gather information from clinicians, identify process failures, respond to auditors, and make sure corrective steps actually happen. Regulations and accreditation requirements also create a steady stream of recurring work. Directors commonly come from nursing, healthcare administration, clinical quality, risk management, or compliance. Many have a bachelor’s or graduate degree, substantial healthcare experience, and a quality credential such as CPHQ. The work can feel like an endless cycle of committees, audits, charts, policies, and follow-up meetings, but healthcare organizations cannot decide quality oversight is optional. That makes experienced people valuable even when nobody envies their calendar.

9. Compliance director

Trade compliance director
Image Credit: Shutterstock

A compliance director gets paid well to spend a surprising amount of time asking whether everybody followed the rules. Average salary is around $184,861 per year. The work includes monitoring internal controls, investigating reported problems, reviewing regulatory changes, overseeing training, preparing for audits, and making sure corrective actions do not quietly disappear after a meeting. Healthcare, energy, manufacturing, transportation, insurance, and other heavily regulated businesses all employ compliance leaders.

Routine parts of compliance can be streamlined, but the uncomfortable part of the job is exactly what keeps people in it. A director may have to decide whether a problem is serious, confront senior employees, coordinate an investigation, deal with regulators, and document why the company took a particular action. Those decisions carry legal and reputational consequences. Most compliance directors have a bachelor’s degree and substantial experience in the industry they regulate, often moving up from compliance, audit, legal operations, safety, or regulatory roles. Industry certifications can help because rules differ sharply between fields. It is not a fast-entry career, but it rewards people who are patient enough to read dense requirements, notice small inconsistencies, ask repetitive questions, and keep following up until somebody fixes the problem.

10. Risk management director

Risk management
Image Credit: Shutterstock

Risk management directors spend their days thinking about everything a company hopes will never happen. Fire, injuries, lawsuits, storm damage, equipment losses, vendor failures, insurance claims, and business interruptions all end up on somebody’s spreadsheet. Average pay is about $183,680 per year. Large manufacturers, healthcare systems, property companies, transportation businesses, utilities, universities, and other organizations with substantial physical assets commonly need this function.

The boring part is that preventing trouble means repeatedly reviewing insurance coverage, loss histories, safety controls, contracts, claims, emergency plans, and the same categories of exposure year after year. The valuable part is knowing which risks actually matter and what to do about them. Insurers, executives, lawyers, site managers, and injured people do not always agree, so judgment and negotiation remain central to the role. Directors often come from insurance, claims, safety, operations, or enterprise risk positions and usually have many years of experience. Credentials in risk management or insurance can strengthen the path. Companies may cut plenty of nice-to-have projects during a slow year, but they still insure buildings, respond to claims, manage safety hazards, and prepare for disruptions. That keeps experienced risk people in the conversation.

11. Plant director

Plant director
Image Credit: Shutterstock

A plant director’s world revolves around whether the line is running, whether enough people showed up, what broke overnight, which maintenance jobs are overdue, how much scrap was produced, and whether today’s production target will be met. Average pay is about $193,675 per year. Manufacturers in industries ranging from food and packaging to industrial equipment and materials need senior people who can keep large production sites operating.

Most days follow a familiar rhythm: shift reports, production meetings, staffing problems, maintenance updates, quality issues, safety reviews, inventory concerns, and another round of performance numbers. The job becomes especially valuable when something falls outside that routine. A broken machine or quality failure can stop millions of dollars of production, so someone experienced has to decide what happens next. Plant directors usually work their way up through production, maintenance, engineering, quality, or operations management. A bachelor’s degree is common, but long records of successful plant leadership matter heavily. Even highly automated factories need people to maintain equipment, supervise workers, manage safety, handle suppliers, and decide when a line is safe to restart. The machinery may be sophisticated, but the accountability stays stubbornly human.

12. Utility plant director

Utility plant director
Image Credit: Shutterstock

Utility plant directors oversee the equipment that quietly keeps power, steam, chilled water, or other essential services flowing. The work involves boilers, turbines, generators, pumps, water systems, maintenance outages, operator schedules, inspection requirements, fuel use, and endless operating logs. Average pay is around $194,780 per year. Utilities, large campuses, industrial complexes, hospitals, and facilities with their own central plants are typical employers.

This is a career where boring is the goal. Nobody wants the plant director to have an exciting shift. They want equipment running inside normal limits, operators following procedure, maintenance completed on schedule, and backup systems ready for the day they are needed. Because these facilities involve expensive machinery, safety rules, and continuous service, experienced operators and engineers still have to be present and accountable. Directors generally reach the job after years in utility operations, power generation, facilities engineering, mechanical engineering, or plant maintenance. Education requirements vary with the facility, while operator licenses and technical credentials can matter greatly. Utilities cannot postpone reliable service because hiring is inconvenient, which gives experienced people who understand these systems a durable place in the workforce.

13. Data center operations director

Data center operations director
Image Credit: Shutterstock

A data center operations director is not a software developer. The job is about the physical machinery underneath the internet: electrical feeds, cooling systems, backup generators, batteries, fire suppression, security, maintenance windows, equipment rooms, and technicians who keep it all running. Average salary is about $187,100 per year. Large data-center operators, cloud companies, banks, healthcare companies, telecom firms, and businesses with critical computing facilities employ them.

The routine can be almost comically methodical. Generator tests happen on schedule. Temperatures get watched. Maintenance procedures are checked and double-checked. Every change gets planned because an innocent mistake can knock important systems offline. That physical responsibility is what makes the job durable. Servers still need electricity, cooling, secure buildings, replacement parts, technicians, and emergency procedures regardless of what applications are running on them. Directors often come from data-center facilities, electrical or mechanical systems, critical-environment operations, telecommunications, or military technical work. A bachelor’s degree is common at senior levels, but deep operational experience can be equally important. As more computing capacity gets built, the unglamorous people keeping the buildings powered and cool become increasingly difficult to do without.

14. QA and validation engineering director

QA and validation engineering director
Image Credit: Shutterstock

In regulated manufacturing, a QA and validation engineering director can spend an entire week proving that a machine does the same thing today that it did yesterday. Average pay is about $196,000 per year. The work centers on equipment qualification, process validation, calibration, change controls, deviations, test records, corrective actions, and documentation showing that manufacturing systems work as intended. Pharmaceutical, biotechnology, medical-device, and other tightly controlled plants are common employers.

This is not software testing. These teams deal with real production equipment and processes that may make medicines or regulated products. When a mixer, filling line, sterilizer, clean room, or manufacturing process changes, somebody has to establish that it still works correctly before the company relies on it. That obligation creates a steady supply of painstaking work that cannot simply be skipped to save time. Directors typically have engineering or science degrees and long experience in validation, quality engineering, manufacturing, or regulated operations. Reaching the top usually takes years of learning both technical systems and regulatory expectations. People who enjoy novelty may find the endless protocols painful. People who appreciate repeatable procedures and carefully checked evidence can turn that patience into an unusually well-paid specialty.

15. Property management director

Property management director
Image Credit: Shutterstock

A property management director gets the problems that were too large, expensive, or annoying for an individual property manager. Average pay is around $199,887 per year. The work may cover a large portfolio of office, industrial, medical, residential, or mixed-use buildings. Expect budgets, contractor bids, inspections, preventive maintenance, security issues, capital projects, occupancy problems, broken equipment, and a steady parade of tenant complaints.

Buildings create recurring work because roofs leak, HVAC equipment ages, elevators need inspections, plumbing fails, parking lots deteriorate, and people continue finding creative ways to damage things. Much of the director’s job is coordinating the humans who solve those problems while deciding which expensive project gets funded first. Property software can track tickets and invoices, but it cannot inspect a damaged mechanical room, negotiate with an angry tenant, choose between repair options, or take responsibility for building safety. Directors usually advance from property or facilities management into regional and portfolio roles. A degree is common for larger employers, while professional property-management credentials can help. It is a career built around assets that cannot be moved offshore and problems that keep returning for as long as buildings exist.

16. Procurement director

Procurement director
Image Credit: Shutterstock

Procurement directors spend a lot of time on prices, supplier contracts, delivery dates, purchase terms, shortages, quality problems, and the awkward question of why a critical part still has not arrived. Average pay is about $174,101 per year. The role is especially important in manufacturing, healthcare, utilities, construction, transportation, and other businesses that depend on a constant flow of physical supplies and equipment.

Routine purchasing is increasingly streamlined, but procurement leadership is mostly about the situations that refuse to be routine. A sole supplier raises prices. A shipment fails inspection. A factory shuts down. A hospital needs an alternative product immediately. A new contract transfers too much risk to the buyer. Directors make tradeoffs involving cost, quality, timing, regulation, and supplier relationships, often with millions of dollars at stake. Most work their way up from buyer, sourcing, category-management, or procurement-manager positions, usually with a bachelor’s degree and substantial industry experience. Supply-management credentials can help. The paperwork may be tedious, but companies that make, build, repair, or treat things cannot operate without materials. Somebody still has to make sure the right goods arrive, meet specifications, and do not bankrupt the organization in the process.

17. Regulatory affairs senior manager

Regulatory affairs senior manager
Image Credit: Shutterstock

Regulatory affairs senior managers make careers out of licensing requirements, product filings, certifications, test results, agency questions, labeling changes, operating rules, and deadlines that cannot be missed. Average pay is about $178,243 per year. These roles are especially common in pharmaceuticals, medical devices, biotechnology, chemicals, manufacturing, and other industries where companies need permission to make, market, test, or change certain products.

The work is deliberately cautious. Before a company changes a material, manufacturing step, claim, test method, or product design, regulatory staff may have to determine what filings or approvals are required. Software can organize documents, but an experienced person still has to interpret requirements, deal with regulators, coordinate scientists and engineers, and decide how a change affects the company’s obligations. Senior managers usually have bachelor’s degrees in science, engineering, pharmacy, or another relevant field and many years in regulatory or quality roles. Specialized credentials can help but experience with a particular product category is often more valuable. Regulations rarely get simpler over time, and heavily regulated companies cannot choose to stop complying when budgets tighten. That makes this paperwork-heavy specialty unusually persistent.

18. Director of construction

Director of construction
Image Credit: Shutterstock

Construction directors spend less time swinging hammers than reviewing schedules, change orders, budgets, contractor problems, inspections, delays, safety issues, punch lists, and the latest reason a project milestone moved again. Average pay is about $176,707 per year. Developers, hospital systems, manufacturers, universities, retailers, utilities, contractors, and property companies hire them to oversee multiple projects or major building programs.

A surprising amount of the job is repetitive coordination. Drawings have to be reviewed, permits obtained, contractors scheduled, materials tracked, inspections passed, invoices checked, and unfinished work chased down before anybody can close the project. Yet construction remains stubbornly physical. Every building has a real site, real weather, real crews, real inspectors, and unforeseen conditions that require somebody experienced to make decisions. Construction directors typically move up from project management, field supervision, estimating, engineering, or construction management. Many employers prefer a bachelor’s degree, but extensive field and project experience can carry significant weight. Infrastructure ages, facilities get renovated, and organizations keep needing new or altered space. That means there is continuing demand for people willing to spend years mastering the deeply unglamorous business of getting projects finished correctly.

You turn 70, log into your 401(k), and finally add up what you’ve been avoiding for a decade. The number on the screen either matches what you pictured or it doesn’t come close.

The average 401(k) balance for savers 70 and older is $264,500. Compare that to someone in their early 20s, who has about $7,700 saved on average, and it looks like real progress. Compare it to what that balance actually has to cover for the next 20 or 30 years, and it looks a lot thinner.

Where you land against that number matters less than what it can actually pay you every month, and whether there’s still time to change it.

Where $264,500 falls against every other age

70 year old man
Image Credit: Shutterstock

This gets tracked every quarter across more than 25 million retirement accounts, and the breakdown by age tells you more than the headline figure alone. Someone in their early 20s has about $7,700 saved, which is basically starting from zero, and that’s fine, they’ve got 45 working years ahead of them. By the time savers hit their 50s, the average crosses $215,700, and it keeps climbing through the back half of that decade to $260,800 for ages 55 to 59.

Then the growth basically stalls. Savers 60 to 64 average $257,400, those 65 to 69 sit at $258,800, and by 70 and older, the average is $264,500. That’s roughly $7,000 of growth spread across 15 years, not because people stop saving entirely, but because a lot of them stop working, start pulling money out, or roll it into an IRA instead. If your balance has flattened out around this age, you’re not the exception. You’re the norm.

Averages hide the real story, medians tell it

Those numbers are useful, but they’re still averages, and averages get pulled upward by a smaller group of savers with very large balances. A separate look at 401(k) plans administered nationwide found the average account balance was $167,970 at the end of 2025, a record high. The median, the point where half of savers have more and half have less, was only $44,115. That’s the figure most people actually match. Narrow it down to older savers and the split gets sharper. For those 65 and older specifically, the average balance was $330,186, while the median was $103,202. A smaller group in that age bracket is sitting on far more money than everyone else, and it’s dragging the average up with it. If your balance looks nothing like $264,500 or $330,186, check yourself against the median instead. It’s the number that actually reflects what a typical saver your age has put away.

What that balance actually pays you every month

70 year old with savings
Image Credit: Shutterstock

A balance only matters once you turn it into income. Using the standard 4% withdrawal rule, the $264,500 average generates about $10,580 a year, or roughly $882 a month, before taxes. Add that to the average Social Security retirement benefit of $2,071 a month, and a 70 year old drawing on both sources is looking at somewhere around $2,950 a month, or just under $35,500 a year.

That’s not nothing, but it’s not comfortable either, especially with housing, health care and everyday costs climbing every year. It works if the mortgage is paid off, your health is decent and you live somewhere affordable. It falls apart fast if any one of those isn’t true, or if a big medical bill or a home repair shows up without warning. This is exactly why the balance by itself was never the full picture. What that money needs to cover matters just as much as what it adds up to, and that’s a personal calculation, not a national average.

Catching up still works, even this late

None of this is set in stone. If you’re 70 and still working, even part time, the 2026 contribution limit is $24,500, plus an $8,000 catch-up for anyone 50 or older, for a total of $32,500 a year into a 401(k). That’s real money, and it still compounds even with a short runway left.

If you haven’t claimed Social Security yet, waiting matters more than most people realize. Each full year you delay past your full retirement age, up to 70, adds 8% to your monthly benefit. Someone who’d get $2,071 a month at full retirement age could be collecting closer to $2,568 by waiting until 70. Past that age, there’s no more benefit to delaying further, so if you’re already 70 and haven’t filed, there’s no reason left to wait.

Being behind the average at 70 isn’t a verdict. It’s a starting point for the next move.

The bottom line

bottom line new
Image Credit: Shutterstock

One more thing worth knowing if you’re near this age: the required minimum distribution age is 73 for anyone born between 1951 and 1959, and 75 for anyone born in 1960 or later. If you haven’t been forced to withdraw from a traditional 401(k) or IRA yet, you may still have a few years of choice in how and when you draw that money down.

It’s 2:40 in the afternoon and you haven’t left your chair since lunch, except to sign for a package you don’t remember ordering. Your neck aches, your eyes feel sandy, and you’d be hard pressed to say what you’ve actually gotten done since 9 a.m. Working from home was supposed to give you more control over your day. Instead it just moved the chaos indoors.

You’re not imagining the shift, either. 35 percent of employed people did some or all of their work at home last year, and most of them never got a manual for it. There’s no commute to bookend the day, no coworker walking past to remind you to stand up, and no conference room to escape to when the kitchen table starts to feel like a cage.

Most of what wrecks a work-from-home day has a fix that takes a few minutes, not a life overhaul. Some of these you already know and just haven’t done yet. Do them anyway.

Time-block your calendar before your inbox fills it for you

calendar work from home
Image Credit: Shutterstock

If you don’t put your real work on the calendar first, meetings and messages will eat every open hour without you noticing. Block out two or three chunks a day, ideally 60 to 90 minutes each, for the tasks that actually move your job forward, and treat those blocks the same way you’d treat a meeting with your boss. Nobody else can see an empty afternoon on your calendar and know it’s already spoken for.

This matters more than it sounds like it should. Getting pulled off a task and back onto it costs real time, about 25 minutes on average to fully return to what you were doing before the interruption, and most people naturally drift between projects every 10 or 11 minutes even with nobody interrupting them. A wide-open calendar invites exactly that kind of scattering. A blocked calendar gives you something to point to when someone tries to book over it, and it gives you permission to say no.

Sit near a real window, not just under a bright bulb

working from home near a window
Image Credit: Shutterstock

A windowless corner or a basement is one of the worst spots you can put a desk in, so move it if you possibly can, even if that just means turning your chair to face the nearest window instead of a wall. Daylight does something artificial light can’t fully replace: it keeps your internal clock synced, which affects how well you sleep that night and how sharp you feel the next day.

In one controlled study, office workers exposed to real daylight and outdoor views slept 37 minutes longer per night and scored 42 percent higher on cognitive tests than workers in an identical office with the blinds down. The effect showed up after a single day and got stronger over the course of a week. Face the window rather than sitting with your back to it, since that cuts down on screen glare and gets more light directly on your face instead of just lighting the room behind you. If you can’t relocate your desk, at least take your coffee break by a window instead of scrolling your phone in the same dim spot you’ve been sitting in all morning.

Get up and move for a few minutes every half hour

standing up and stretching
Image Credit: Shutterstock

Sitting at a desk from 9 to 5 with no real breaks is worse for your body than most people realize. Researchers who pooled data on more than a million people found that sitting more than eight hours a day with no physical activity carries a risk of death similar to obesity and smoking, though 60 to 75 minutes of moderate activity spread across the day can offset a lot of that damage.

You don’t need a gym session mid-morning to get the benefit. Stand up, stretch, walk to the mailbox, climb a flight of stairs, or do a lap around the house every 30 minutes. Set a recurring timer if you have to, since it’s easy to lose two hours to a spreadsheet without moving a muscle, and by the time your neck reminds you, the damage is already done for the day. Standing while you’re on a phone call, or during a video meeting where your camera is off, works just as well and costs you nothing but the habit of remembering to do it.

Give your eyes an actual break from the screen

tired eyes from starring at computer screen
Image Credit: Shutterstock

The average American worker now spends seven hours a day looking at a computer screen, and that adds up to real strain: headaches, blurred vision, dry eyes, and neck pain from leaning toward a monitor. Working from home usually makes this worse, not better, since there’s no walk to a colleague’s desk to break up the staring.

Every 20 minutes, look at something at least 20 feet away for 20 seconds. It sounds too small to matter, but it gives your eye muscles an actual chance to relax instead of staying locked at the same focal distance for hours on end. Pair it with blinking more deliberately, since staring at a screen tends to cut how often you blink, and that’s most of what’s behind the dryness by 4 p.m. Position your monitor about an arm’s length away with the top of the screen at or just below eye level, so you’re looking slightly down rather than craning your neck up or forward to see it clearly.

Take a real nap when the afternoon wall hits

taking an afternoon nap
Image Credit: Shutterstock

Hitting a wall around 1 or 2 p.m. is normal, and if your job lets you close the door for 20 minutes, take the nap instead of powering through on caffeine alone. This isn’t slacking off. Pilots given a planned rest break during long flights performed 34 percent better and felt 54 percent more alert after a 26-minute nap, compared to colleagues who didn’t rest at all.
Keep it short and keep it early. Anything past 30 minutes, or anything after about 3 p.m., and you risk waking up groggier than when you started or having trouble falling asleep that night, because you’ve either dropped into deeper sleep stages your body doesn’t want to be pulled out of or eaten into the sleep pressure you need come bedtime. Set an alarm, lie down somewhere dark and quiet if you can manage it, and treat the 20 minutes you lose as an investment in the two hours of actual focus you’ll get back that afternoon instead of pushing through on a fourth cup of coffee.

Give your household a clear signal for do-not-disturb

do not disturb
Image Credit: Shutterstock

If you share your home with a partner, kids, or roommates, the biggest daily disruption usually isn’t your inbox, it’s a knock on the door mid-call. Set up something visual that doesn’t require a conversation every single time: a closed door, a small sign, a colored light, or even just headphones on as a rule everyone in the house already understands.

Talk it through once, out loud, rather than assuming people will figure out your schedule by osmosis. Tell your household when your hard-focus hours are and what actually counts as an emergency versus something that can wait 20 minutes, whether that’s a bleeding knee versus a snack request. Kids especially do better with a concrete rule than a vague one, so something like a red sock on the doorknob during calls tends to stick better than just asking everyone to be quiet. This one conversation, uncomfortable as it might feel to have, saves you from repeating the same interruption argument on a loop for the next five years.

Set a hard stop time and mean it

power off
Image Credit: Shutterstock

Pick an end time for your workday and treat it as a real boundary, not a suggestion. Close the laptop, log out of Slack, and physically leave the room you work in if you can. Without a commute to signal the day is over, work will happily expand to fill every evening hour you let it have.

This isn’t just a personal preference. Several countries have passed laws giving workers the right to ignore work communications outside their scheduled hours without being penalized for it, including France, Ireland, and the Canadian province of Ontario. The U.S. doesn’t have anything like that on the books yet, so the boundary has to come from you. Turn off notifications after your stop time, or better, move your phone into another room entirely. Build a two-minute shutdown ritual to signal you’re actually done, writing tomorrow’s top three tasks on a sticky note, closing every open tab, and shutting the laptop lid, so your brain gets a clear cue instead of just quietly drifting back to email at 8 p.m.

Schedule real human contact into your week

meeting for coffee with friend
Image Credit: Shutterstock

Working from home can quietly erase all the small, unplanned interactions that used to fill an office day, the elevator chat, the hallway wave, the coworker who stops by your desk to ask a question. A recent study found remote workers spend 58 percent more time alone and are 72 percent more likely to go an entire day without any human contact than people who work alongside others.

The fix isn’t complicated, but it does have to be deliberate, since none of it happens by accident the way it used to in a break room. Put a coffee with a friend, a workout class, or a coworking day at a café on your calendar the same way you’d schedule a client call. Even taking an afternoon phone call on a walk through your neighborhood, rather than at your desk, counts. If you live alone, this matters even more, since researchers found the mental health toll was worse for people without others in the house.

Build a dedicated workspace, even a small one

office workspace
Image Credit: Shutterstock

Your brain learns to associate a physical space with a mode of being, and working from your bed or the couch you also relax on blurs that line fast. You don’t need a spare room. A corner of the kitchen table that’s used only for work during work hours, with your laptop and nothing else on it once you’re done for the day, does the job just fine.

Set it up so you’re not rebuilding your workstation from scratch every morning. Keep your charger, notebook, and headphones in that spot, so sitting down there is a signal to your brain that it’s time to focus, and packing them away is a signal that you’re done. If space is tight, a rolling cart you can tuck into a closet at 5 p.m. works almost as well as a whole room would. Pay attention to what’s behind you on video calls too, since a consistent, tidy background is one less small decision to make every morning before your first meeting.

Fix your chair before your back fixes it for you

comfy on computer chair
Image Credit: Shutterstock

A dining chair or a couch cushion might feel fine for an hour, but eight hours a day, five days a week, adds up to real damage in your lower back, hips, and neck. Your feet should rest flat on the floor, your knees at roughly a right angle, and your screen at eye level so you’re not tilting your head down or craning it up for hours at a time.

You don’t need to spend a fortune to fix most of this. A rolled towel behind your lower back, a stack of books under your monitor, and a cheap footrest solve the worst offenders for under $20 combined. Your elbows should sit close to your body at roughly a 90-degree angle when you type, not reaching forward or propped up on armrests that are too high. If you can afford one real upgrade, make it lumbar support, since that’s the piece that’s hardest to improvise well and the one most people go without entirely.

Keep a full glass of water within reach

drinking water
Image Credit: Shutterstock

It’s easy to go four or five hours without drinking anything when you’re heads-down at a desk, and mild dehydration hits your brain before it hits your body in any way you’d notice. Even a small water deficit, around 2 percent of your body weight, is enough to measurably worsen concentration, slow your reaction time, and sour your mood.

Fill a large bottle or glass at the start of your day and keep it on your desk instead of relying on remembering to walk to the kitchen. A simple visual trick works better than tracking ounces: refill a marked bottle a set number of times before you shut down for the day, so drinking enough becomes a matter of counting refills, not doing math mid-meeting. If plain water bores you, add fruit slices or switch to sparkling water rather than reaching for another cup of coffee, since caffeine layered on top of dehydration usually makes the afternoon crash worse, not better, even though it feels like the fix in the moment.

Take a lunch break away from your screen

eating lunch away from screen
Image Credit: Shutterstock

Eating a sandwich one-handed while you answer emails isn’t a lunch break, it’s just working with extra crumbs on your keyboard. Step away from your desk entirely, even if that just means eating at the kitchen table or on the porch for 20 minutes instead of at your laptop. Your brain needs a real stopping point in the middle of the day, not just a change of task.

If you can get outside during that break, even better. A short walk after lunch does double duty: it helps digestion and gives you a second dose of the daylight exposure your body needs to regulate energy through the afternoon slump. Put it on your actual calendar as a recurring block, the same way your meetings are, since an unscheduled break is the first thing that gets skipped when the day runs long. Treat this break as non-negotiable the same way you would if a coworker had asked you to lunch in an actual office.

Walk before and after work like you’re commuting

taking a walk after work
Image Credit: Joshua Tsu via Unsplash

People who work from home lose one of the most useful parts of a commute: the built-in transition between home mode and work mode. Recreate it on purpose. Take a 10 or 15 minute walk before you sit down to work, and another one when you close the laptop for the day, even if it’s just a loop around the block.

It sounds almost too simple to matter, but the walk gives your brain a clear before and after. You show up to your desk already awake instead of rolling out of bed straight into a video call, and you leave work with a clean break instead of just closing a browser tab and drifting into your kitchen still thinking about tomorrow’s deadline. Use the time the way you’d use an actual commute, listening to a podcast, calling a friend, or just letting your mind wander without a screen in front of it, rather than treating it as one more task to check off.

Add a plant or two to your desk

plant on desk
Image Credit: Shutterstock

A living plant on your desk does more than look nice. Greenery in a workspace is widely linked to lower stress and a calmer mood, and it gives your eyes something soft to land on between stretches of staring at a screen. It doesn’t need to be complicated, expensive, or high-maintenance to work.

Pick something close to impossible to kill if you don’t trust yourself with a watering schedule: a pothos, a snake plant, or a small succulent all tolerate neglect and low light just fine, and most only need water every one to two weeks. If you don’t have a green thumb at all, even a small vase of fresh flowers refreshed once a week gives you a similar lift without the pressure of keeping something alive. Position it somewhere you’ll actually see it while you work, not on a shelf behind you, so it’s doing its job instead of just decorating a room you’re facing away from.

Clear your desk before you clear your inbox

clean computer desk
Image Credit: Shutterstock

A pile of mail, dishes, and tangled cables on your desk is a constant low-grade distraction, even when you’re not consciously looking at it. Spend five minutes at the end of each day clearing your workspace down to just what you need for tomorrow morning, the same way a restaurant kitchen resets before the next shift starts.

This is a five-minute habit, not a deep clean, so don’t let it turn into another task you avoid. Put the mail in a tray instead of a stack, coil your charging cables instead of letting them tangle, and take your coffee mug back to the kitchen. Give yourself one small catch-all drawer or basket for the odds and ends you don’t want to deal with right that second, so tidying up doesn’t turn into a decision about where twelve different objects belong. Starting the next morning at a clear desk instead of yesterday’s mess removes one more reason to stall before you even open your laptop.

Batch your errands into one window, not all day

ironing
Image Credit: Shutterstock

One of the traps of working from home is that chores are always within reach, so you end up doing laundry between emails, then unloading the dishwasher during a meeting you’re only half listening to. That scattered approach costs you more focus than it actually saves you in time.

Pick one window, maybe first thing in the morning or right after lunch, and handle your household tasks then instead of letting them interrupt you all day long. Start a running list on your phone or a sticky note by the door, so when you notice you’re low on milk or the trash needs to go out mid-morning, you jot it down and keep working instead of stopping to deal with it on the spot. Outside your errand window, treat chores the way you’d treat them if you worked in an office: they wait until you’re off the clock. This one change alone can reclaim hours of scattered attention over the course of a week.

Cut blue light after dark

on computer at night
Image Credit: Shutterstock

If your workday runs late or you’re still scrolling on your laptop after dinner, the blue-heavy light from your screen is telling your brain it’s still daytime. That delays the release of the hormone that makes you feel sleepy, which makes it harder to fall asleep even after you’ve finally logged off for the night.

Switch your devices to night mode or a warmer color setting once the sun goes down, and dim your overhead lights in the evening instead of leaving them at full daytime brightness. Most phones and laptops have this built in now, so it’s a one-time setting rather than something you have to remember to toggle every night. Working from home makes it tempting to let the workday blur straight into the evening under the exact same lighting, since there’s no office you’re leaving behind to mark the change. Give your evening its own, dimmer atmosphere so your body actually gets the signal that work is over for the day.

Bottom line

bottom line new
Image Credit: Shutterstock

Full-time remote work skews heavily toward people with more education, and 51 percent of workers with a bachelor’s degree or higher did some work from home last year, compared with 19 percent of those with only a high school diploma. Pick two or three of these, actually do them for two weeks, and check back in on how the rest of your day feels.

You have worked in the same office for close to twenty years. Then one quarter your manager starts using the word “efficiency” a lot, and by the following spring your job does not exist anymore. Nobody says the words artificial intelligence out loud. They rarely have to.

A 2026 analysis from the Center for Retirement Research at Boston College found that since ChatGPT launched in November 2022, workers 55 and older in the most AI exposed occupations have become significantly more likely to leave those jobs. Some of that is early retirement. A lot of it is not. The researchers found the increase was driven largely by transitions into unemployment, not by workers choosing to stop working.

That timing could not be worse. More than half of workers over 50 are laid off or pushed out of career jobs before they choose to leave on their own, and once that happens, AI powered hiring tools have been shown to disadvantage applicants over 45 during the first round of resume screening. Lose the job, then lose ground finding the next one, for reasons that have nothing to do with skill.

Here are 15 jobs where that squeeze is showing up first, and why.

Computer programmers

Computer programmer
Image Credit: Shutterstock

Programmer jobs are projected to decline 6 percent through 2034, as companies use AI to automate routine coding tasks and shift the more complex work to software developers instead. That is a shrinking pie for a role that used to be a stable, long career.

The Boston College research on older workers singled programmers out directly. Once ChatGPT became widely available, the rate at which older programmers left their jobs jumped by more than 25 percent compared with the years before, one of the largest increases of any occupation studied. Painters, by comparison, saw almost no change at all. The gap says a lot about which kinds of work AI is actually reaching first, and it is not the physical jobs.

A programmer who has spent two decades writing code for one industry now has to compete for far fewer openings, often against younger candidates willing to work for less and companies eager to test whether an AI coding assistant can do the job for a fraction of the cost.

Accountants and auditors

accountant at work
Image Credit: Shutterstock

On paper, this looks like a growing field. The Bureau of Labor Statistics expects 5 percent employment growth for accountants and auditors through 2034, faster than average, driven by a growing economy and increasingly complex tax rules.

But growth in the field overall does not mean older workers inside it are safe. The same Boston College research found that exits from the workforce among older accountants and auditors climbed by more than 22 percent after ChatGPT’s release, a jump nearly as steep as the one seen among programmers. AI tools are increasingly handling reconciliations, first pass audits, and routine reporting, the kind of work senior accountants used to hand down to junior staff. That leaves fewer places for an experienced accountant to land once their role is restructured, even while the overall job count keeps climbing.

Firms are still hiring accountants. They are just hiring fewer of them at the senior end of the pay scale, and reorganizing teams around a smaller group of people who can oversee what the software produces rather than a larger group who once did that work by hand.

Executive secretaries and administrative assistants

administrative assistant
Image Credit: Shutterstock

Secretaries and administrative assistants are expected to see little or no employment growth through 2034. The Bureau of Labor Statistics points directly at the cause: automated phone systems and AI scheduling assistants are steadily reducing how many people a company needs in this role.

Within that broader group, the specific job of nonmedical secretary and administrative assistant is projected to shrink by about 31,000 positions over the decade, even as medical secretaries, a separate and growing specialty, pull the overall numbers up.

This is a role that has historically rewarded tenure, institutional memory, and the ability to manage a demanding calendar without being asked twice. Those are exactly the skills that do not show up in a job posting anymore, because an AI assistant now handles the scheduling and a chatbot answers the routine questions.

Executives who once relied on a longtime assistant to anticipate their needs are increasingly told the AI tool can do the same thing for a fraction of the cost, even if it cannot actually read the room the way a person who has worked alongside them for a decade can.

Customer service representatives

Customer service representative
Image Credit: Shutterstock

Nearly 154,000 customer service jobs are on track to disappear by 2034, a 5.5 percent decline, even though hundreds of thousands of openings will still appear each year as people retire or move on.

Self-service apps, chatbots, and AI phone systems now resolve a huge share of the simple questions that used to require a live person, which means fewer representatives are needed to handle what is left. The jobs that remain increasingly go to the workers who can manage the hardest, most emotionally charged calls, the ones a bot still cannot defuse.

That is not necessarily an advantage for someone who has spent twenty years handling routine customer service calls. Experience answering routine questions patiently does not automatically translate into handling escalated complaints, and companies restructuring their call centers are not always willing to retrain a longtime employee for the harder version of the same job. Call center veterans who built their whole career on staying calm and following a script now find that the script itself has been automated, leaving only the calls nobody, human or bot, wants to take.

Bookkeeping, accounting, and auditing clerks

Bookkeeping
Image Credit: Shutterstock

This is one of the clearest cases of software directly replacing people. Employment for bookkeeping, accounting, and auditing clerks is projected to decline 6 percent through 2034, a loss of more than 94,000 jobs, as accounting software automates the reconciliation and data entry work these clerks used to do by hand.

Unlike accountants, who need a degree and can pivot into advisory or analysis work, bookkeeping clerks typically do not have an obvious next rung to climb to inside the same company. The tasks that made the job worth having, matching invoices, catching errors, keeping the books balanced, are precisely the tasks a modern accounting platform now does automatically and instantly.

For someone who built a career on being meticulous with numbers, watching that meticulousness get automated out of the job description is its own kind of loss, on top of the practical one. The openings that remain increasingly ask for comfort managing several software platforms at once rather than the manual bookkeeping skills a longtime clerk spent years perfecting.

Data entry keyers

data entry key
Image Credit: Shutterstock

No office occupation on the Bureau of Labor Statistics list of the steepest declines is shrinking faster than this one. Employment for data entry keyers is projected to fall almost 26 percent through 2034, a loss of nearly 37,000 jobs from a workforce of only about 142,000 to begin with.

Optical character recognition and AI powered document processing can now read a scanned form and populate a database faster and more accurately than a person typing it in by hand. There is very little room left for the argument that a human keyer adds something the software cannot.

Data entry has long been an entry point for workers without a college degree, including many older workers who came to office work later in their careers or after a layoff in another field. As the role disappears, that entry point disappears with it, closing off one of the more accessible paths back into steady office work.

Payroll and timekeeping clerks

Payroll clerk
Image Credit: Shutterstock

About 27,000 payroll and timekeeping clerk positions, nearly 17 percent of the field, are projected to vanish by 2034, as payroll software increasingly handles calculations, tax withholding, and time tracking without much human review.

This job used to demand a sharp eye for discrepancies, someone who could catch a miscalculated overtime hour or a benefits deduction that did not look right. Modern payroll platforms flag those discrepancies automatically and route exceptions for approval rather than requiring a clerk to check every entry by hand.

Workers who have spent decades in payroll often built their value around exactly that kind of vigilance. When the software does the checking, the remaining openings tend to go to a much smaller team overseeing the system rather than a full staff running the numbers manually, and there simply are not enough of those oversight roles to absorb everyone the automation displaces. A payroll clerk who spent thirty years learning every exception in a company’s pay structure now competes for one of a handful of remaining spots against people half her age who grew up managing software, not spreadsheets.

Bank tellers

bank teller serving a customer
Image Credit: Shutterstock

Bank teller employment is projected to fall nearly 13 percent through 2034, a loss of about 45,000 jobs, continuing a decline that started with ATMs decades ago and has accelerated as banks add AI powered chat and voice tools for routine transactions.

Mobile deposit, automated fraud alerts, and AI chat assistants now handle a large share of what used to require a trip to the branch and a conversation with a teller. Branches are consolidating as a result, and the tellers who remain are increasingly expected to sell financial products rather than simply process transactions.

That shift favors newer hires trained from day one to pitch credit cards and loans, not necessarily the teller who has spent fifteen years building relationships with regular customers. Loyalty and familiarity, once real assets in this job, do not weigh much against a bank’s push to do more with a smaller branch staff, and branch consolidation often means the surviving positions go to whichever employees are willing to relocate or shift into sales.

Claims adjusters, examiners, and investigators

Claims adjuster
Image Credit: Shutterstock

The Bureau of Labor Statistics is unusually direct about the cause of this one. Insurers now use AI tools to assess photographs of property damage and generate payout estimates automatically, and the agency says that efficiency gain is projected to shrink employment for claims adjusters, examiners, and investigators by 5.1 percent through 2034, a loss of more than 18,000 jobs.

Judgment calls that used to require a trained adjuster physically inspecting a wrecked car or a flooded basement can now be handled, at least in the first pass, by a model trained on thousands of prior claims. The adjusters who remain are increasingly handling the complex or disputed cases the software flags rather than the routine ones.

An experienced adjuster’s real skill, spotting the details that do not add up in a claim, is still valuable. The problem is there is far less routine work left to pair with it, and fewer entry points for that expertise to keep earning a full time salary.

Bill and account collectors

Bill and account collector
Image Credit: Shutterstock

Bill and account collector jobs are projected to shrink by roughly 10.5 percent through 2034. Automated payment reminders, AI powered chat negotiations, and self-service payment portals now handle much of the routine outreach that collectors used to do by phone.

Collections work has always required a particular kind of resilience, the ability to have the same difficult conversation dozens of times a day without losing patience. That skill does not disappear just because a company decides a text message or an automated call can handle the first three attempts to collect a debt before a human ever gets involved.

What is left for human collectors tends to be the accounts that have already resisted automated contact, the hardest cases, with the least predictable outcomes. Fewer of those cases exist per collector than the volume of routine collections work that used to keep a full team employed, which means smaller teams handling a tougher caseload rather than the same number of people doing easier work.

Interviewers

Interviewer
Image Credit: Shutterstock

The workers who conduct surveys, screen applicants, and gather information for research and government programs are facing a nearly 12 percent decline in employment through 2034. AI powered chat and voice tools can now conduct a structured interview and log the responses without a person on the other end of the line.

Government agencies and research firms increasingly deploy automated phone and web surveys for the kind of standardized questioning that used to require a trained interviewer working from a script. The tasks are repetitive enough, and specific enough, that generative AI systems can handle them with minimal oversight.

Workers who built careers on the rapport and consistency needed to get honest answers from strangers over the phone are finding fewer roles that value those specific skills, since a growing share of the interviews themselves are simply not being conducted by a human anymore. The remaining positions increasingly involve designing the survey instrument or reviewing flagged responses rather than doing the interviewing directly.

Paralegal
Image Credit: Shutterstock

The paralegal field is projected to show little or no growth through 2034, a sharp change from the steady expansion it saw for decades. The Bureau of Labor Statistics attributes the flattened outlook directly to AI tools that can now handle legal research and document review far faster than a person can.

Reviewing thousands of pages of discovery documents for relevant facts used to be exactly the kind of labor intensive work that justified hiring a paralegal. AI systems can now scan that same volume of material in minutes and flag the passages that matter, cutting the number of research hours a law firm needs to bill or absorb.

Paralegals with deep experience in a specific area of law still bring judgment that software cannot replace. But with far less routine document review left to divide among a legal team, firms increasingly need fewer paralegals to support the same number of attorneys, and long tenure alone is no longer enough to guarantee a seat at that smaller table.

Editors

Editor
Image Credit: Shutterstock

Editor jobs are projected to grow just 1 percent through 2034, essentially flat, with the Bureau of Labor Statistics noting that editors at traditional print newspapers and magazines specifically face declining employment as those publications lose ground to other formats.

Researchers studying AI’s effect on older workers used an editor as their central example of a job with real automation risk. Correcting spelling and grammar, verifying facts, and evaluating whether an article reads clearly are all tasks generative AI can now do quickly, and the researchers noted the outcome for any individual editor depends heavily on whether that person adopts the new tools early or gets replaced by them later.

An editor who spent a career building judgment about what makes a story worth running is not easily replaced. But a newsroom under financial pressure does not always distinguish between the mechanical parts of the job and the parts that require real editorial instinct when deciding how many editors it can still afford.

Retail supervisors

Retail supervisor
Image Credit: Shutterstock

More than 72,000 retail supervisor positions, first line managers who run the sales floor, are projected to disappear by 2034, a 5 percent decline, as retailers lean on AI powered inventory forecasting and scheduling software to do work that used to require a floor supervisor’s judgment.

Predicting how much staff a store needs on a given day, flagging which products are running low, and building next week’s schedule are all tasks a supervisor used to handle through experience and instinct. AI scheduling and forecasting tools now do a version of that work automatically, based on sales data rather than a manager’s feel for the store.

A supervisor who spent years learning the rhythm of a particular store, the seasonal spikes, the regular customers, the staff who need more oversight than others, built expertise that does not transfer easily to a job posting. Retailers cutting management layers to lean on software tend to keep the newest, cheapest supervisors rather than the most experienced ones.

General office clerks

General office clerk
Image Credit: Shutterstock

Employment for general office clerks, one of the largest office occupations in the country, is projected to fall 6.7 percent through 2034, a loss of nearly 178,000 jobs, the biggest numeric decline of any office and administrative role tracked by the Bureau of Labor Statistics.

This is a catch all role, filing, photocopying, answering phones, routing mail, handling whatever paperwork needs a human hand. AI powered document management and workflow software increasingly handles the routing and filing automatically, and shared inboxes with automated sorting cut into the need for someone to manually direct incoming requests.

Because the job covers so many small tasks rather than one specialized skill, it has long been a flexible landing spot for workers moving between careers or reentering the workforce later in life. As AI absorbs those small tasks one by one, that flexible landing spot keeps getting smaller, right as more experienced workers need somewhere to land.

The real gap shows up in reemployment, not just job counts

mature
Image Credit: Shutterstock

None of these jobs are disappearing overnight, and every one of them will still post real openings each year as people retire or move on. The harder problem is what happens next for the worker who loses one of these roles at 55 or 60. Among workers over 50 who expect their next job search to be difficult, age discrimination is the reason cited most often, ahead of any gap in skills or experience. That is the part a shrinking job count alone will never show.