scroll top

This month, Costco is filled to the brim with fab fall finds, ranging from cozy clothing to kitchen must-haves, and yard essentials to adorable home decor. This wonderfully random selection fits the season perfectly. September is that weird transitional month when it’s sometimes still a little bit summery, but fall is very clearly on the way. Here are the best Costco fall deals we found to help you comfortably on your way to fall.

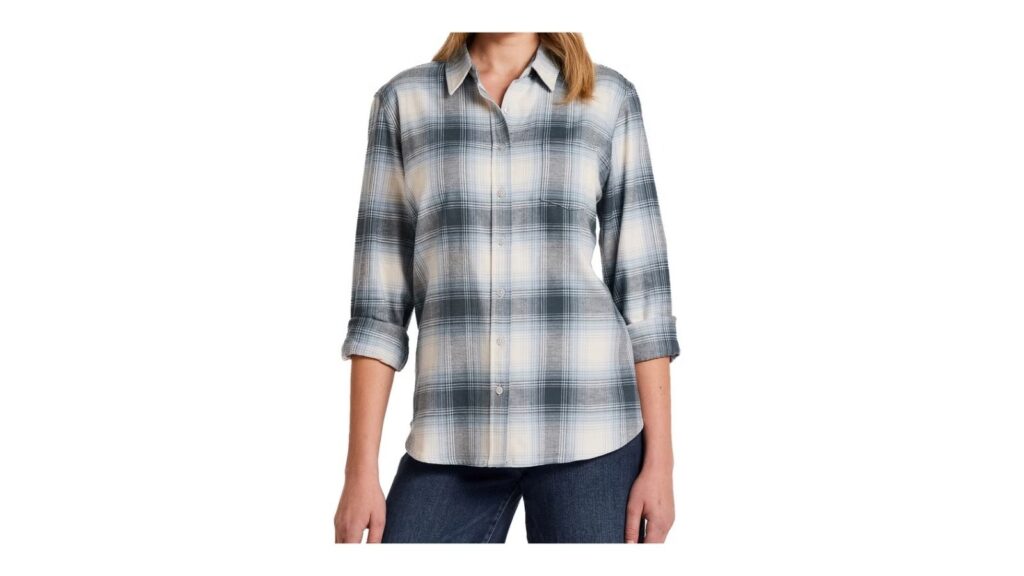
Weatherproof Vintage women’s flannel shirt
Flannel Shirt
Image Credit: Costco

This is the kind of fall clothing deal that makes sense even if you have zero interest in dressing like a pumpkin patch. Weatherproof Vintage’s women’s flannel shirt is currently $9.99 after $3 off, with several colors available.

It is a lightweight cotton-blend flannel with a little stretch, so it can work buttoned up as a shirt or open over a tee when mornings are cool but afternoons are not. Under $10 is a sensible replacement price if last year’s flannel is worn out, and it is versatile enough to keep earning drawer space after October instead of becoming seasonal costume clothing.

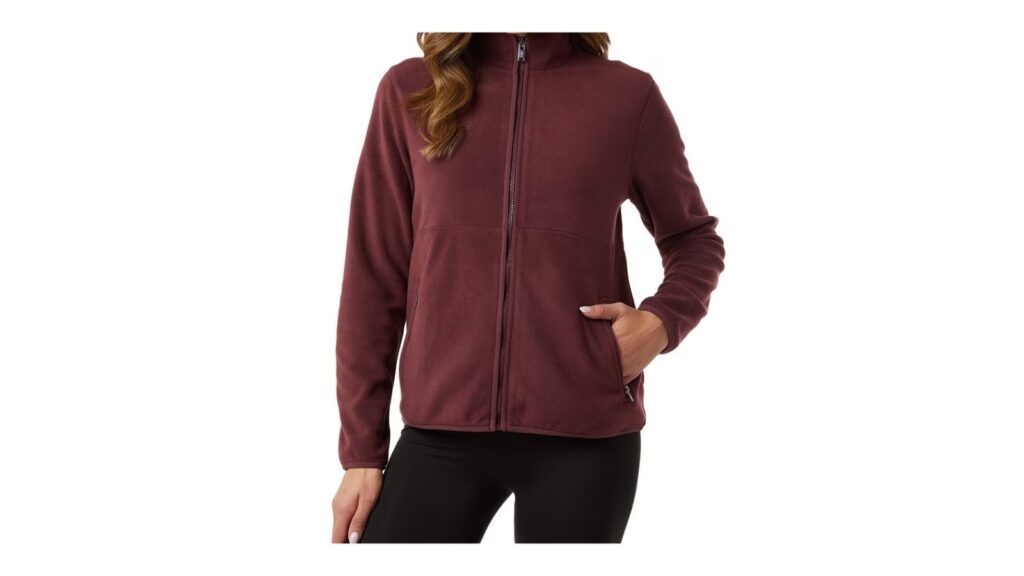
32 Degrees women’s fleece jacket
Fleece jacket
Image Credit: Costco

Those in-between fall days are exactly why fleece jackets exist. The 32 Degrees women’s fleece jacket is $11.99 after $3 off, with Costco listing it for both warehouse and online purchase while supplies last.

The midweight fleece has zippered pockets and is substantial enough for school drop-offs, outdoor games, dog walks, errands, or layering under a heavier coat later. At less than $12, this is also a practical car jacket or backup layer without tying up much money. If you already own several good fleeces, there is no reason to add another. If your current one has a broken zipper or sleeves that have seen better days, this is cheap replacement territory.

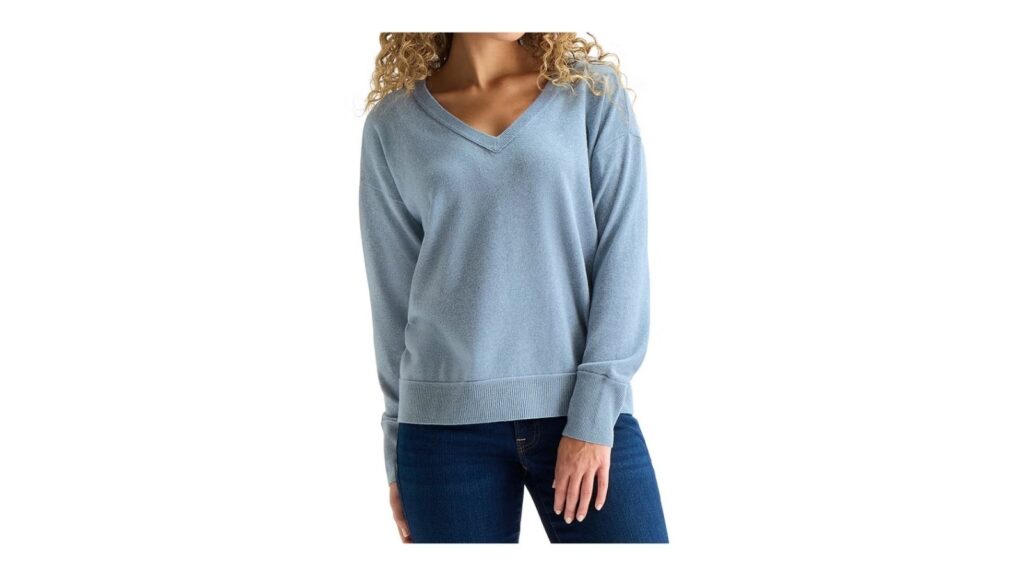
Lucky Brand women’s V-neck sweater
V neck sweater
Image Credit: Costco

A sweater that works with jeans on Saturday and office pants on Monday usually gets more wear than a highly specific fall outfit. Lucky Brand’s V-neck sweater is currently $12.99 after $4 off, with multiple colors and sizes offered.

The relaxed, midweight knit is easy to layer when temperatures bounce around, and the sub-$13 price makes more sense than paying department-store money for a basic seasonal layer. This is particularly useful if you are rebuilding a work wardrobe, replacing something badly pilled, or just need one decent sweater that can handle regular rotation. Costco notes that selection varies by location, so the useful sizes may disappear before the sale does.

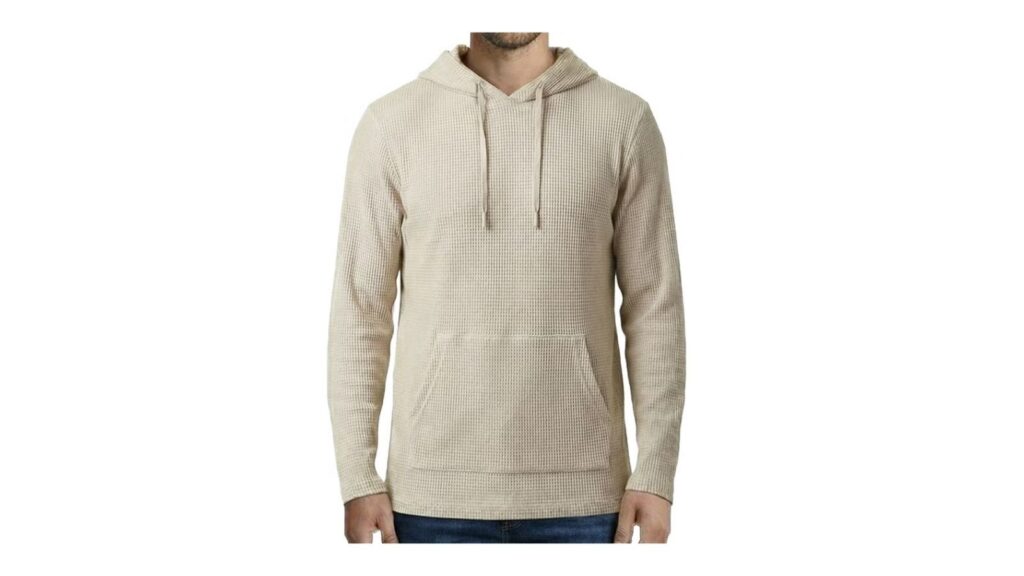
Rainforest men’s textured hoodie
textured hoodie
Image Credit: Costco

For the days when a coat is too much but a T-shirt clearly was a bad decision, Rainforest’s textured men’s hoodie is $12.99 after $3 off. The midweight waffle-textured fabric gives it a little more structure than an old gym sweatshirt.

It has stretch, a kangaroo pocket, and sizing through 3XL, making it useful for errands, yard work, weekend sports, or keeping at work when the building suddenly decides it is January. A fall layer under $13 is good value when it will get used several times a week. This one earns its spot because it solves a seasonal clothing need without costing enough to require a wardrobe budget meeting.

Champion youth hoodie
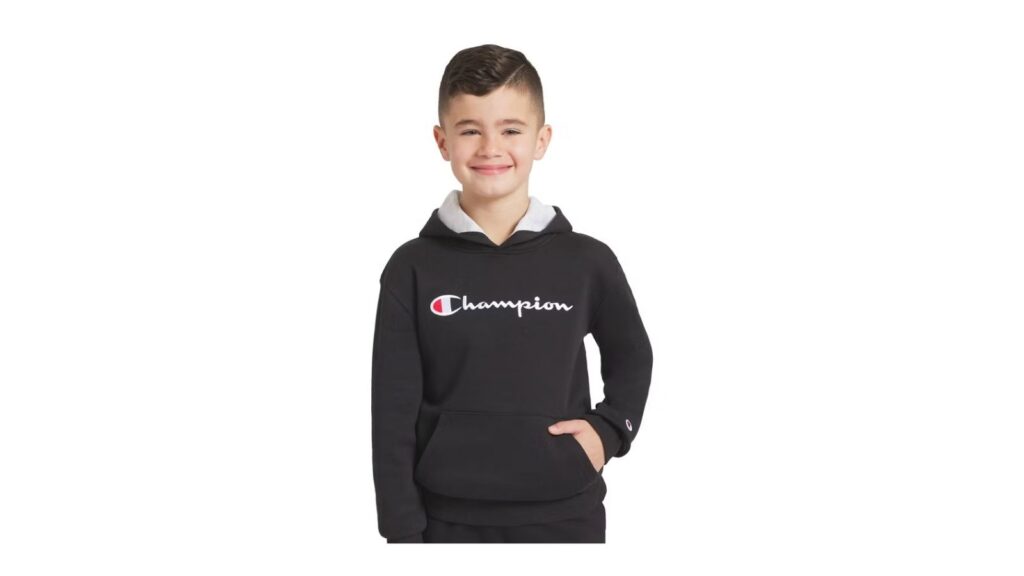
Champion youth hoodie
Image Credit: Costco

Children somehow manage to grow out of hoodies precisely when the first cold school morning arrives. Champion’s youth hoodie is down to $7.99 after $2 off, which is a very manageable price for a fall layer that is likely to see heavy use.

The cotton-blend hoodie has a front pocket and comes in several colors, with sizes running from XS through L. At under $8, it also makes sense as the spare that lives at a grandparent’s house or gets stuffed into a school bag for colder afternoons. There is little benefit in buying several future sizes just because it is cheap, but replacing the hoodie that ends halfway up a child’s forearms is a different matter.

32 Degrees men’s Heat Tee two-pack
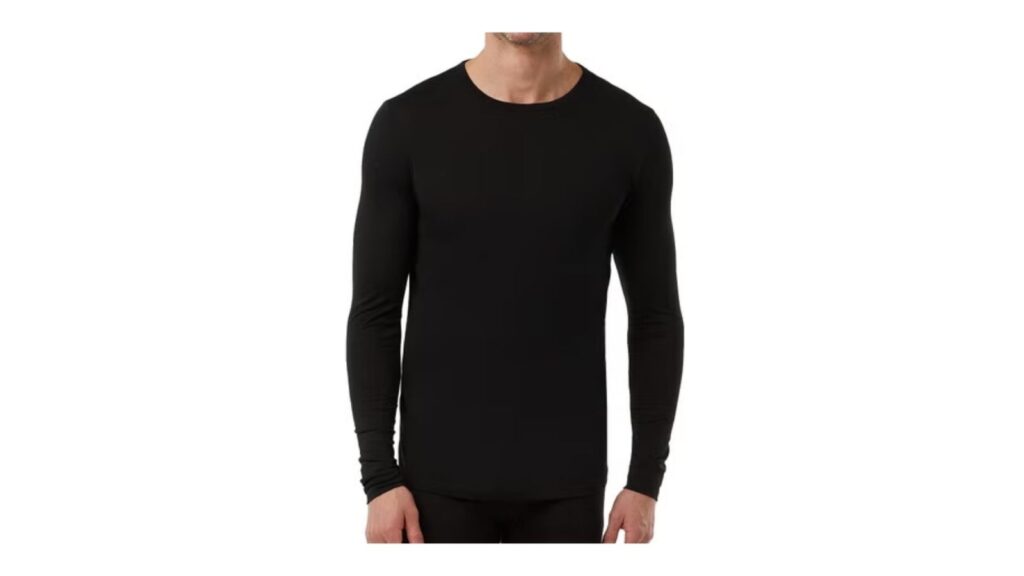
Heat Tee two pack
Image Credit: Costco

Base layers are less noticeable than a new jacket, but they can be much more useful once fall turns genuinely cold. The 32 Degrees men’s Heat Tee comes in a two-pack for $14.99, or about $7.50 per shirt.

These lightweight long-sleeve tees are designed for layering, with moisture-wicking, quick-drying fabric and stretch. They are useful under work clothes, hiking gear, sweatshirts, or heavier winter layers without adding much bulk. This is one of the more practical buys for someone who spends fall weekends outdoors or works in a cold environment, because two basic layers for around $15 can extend the usefulness of clothes you already own rather than requiring a whole new cold-weather wardrobe.

Khombu women’s all-weather boots
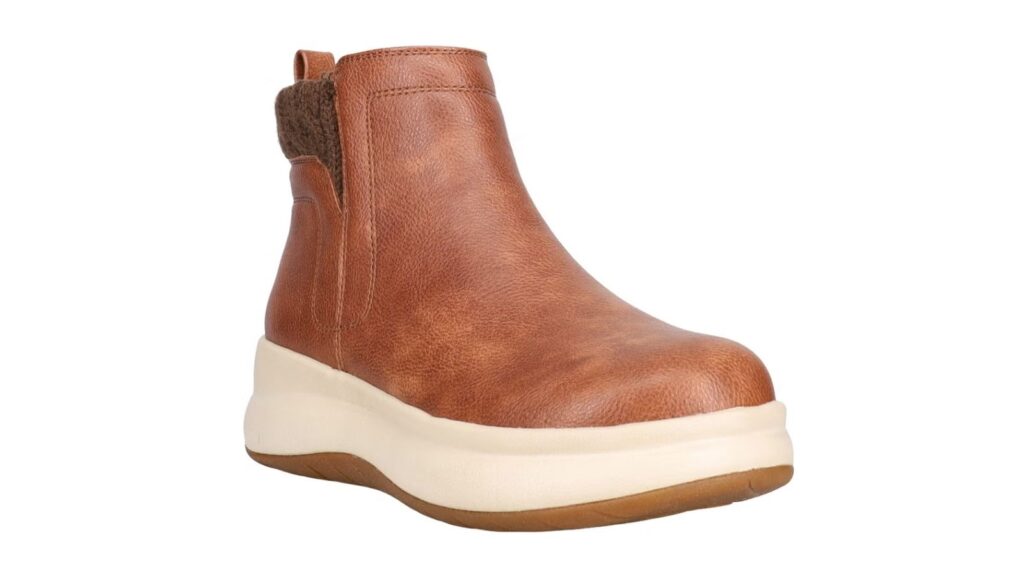
all weather boots
Image Credit: Costco

Wet sidewalks, cold mornings, and muddy sidelines are much easier to deal with in footwear that was designed for them. Khombu’s women’s all-weather boots are currently $33.99. Costco lists them as water repellent, with a warm lining, memory-foam insole, and a cold rating down to minus 4 degrees Fahrenheit.

That makes them more useful than a fashion boot that looks good until the first puddle. They come in black and tan and have a side zipper, so they can cover everyday commuting, school runs, outdoor events, and the early part of winter without requiring separate shoes for every kind of bad weather. Under $35 is a reasonable spend if your existing fall boots leak, have worn-out soles, or simply no longer fit.

Jsport women’s lined slip-on shoes
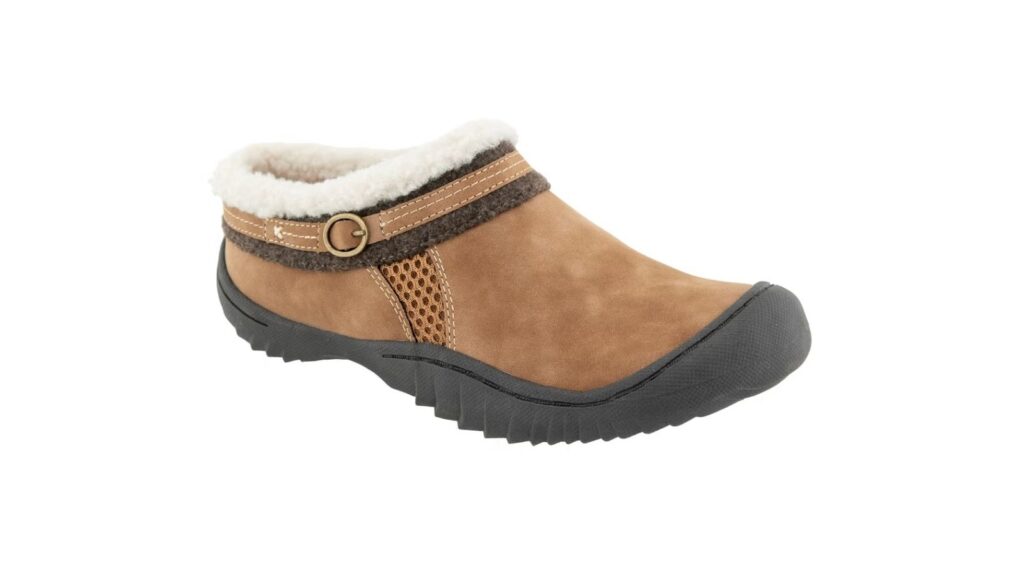
slip on shoes
Image Credit: Costco

Not every cool-weather shoe needs to be a full boot. Jsport’s lined women’s slip-ons are $17.99 after $4 off, with black and tan versions offered in whole sizes.

The cozy lining makes these better suited to chilly fall mornings than an ordinary canvas slip-on, while the memory-foam insole and traction outsole keep them practical for daily errands. They are especially useful for people who want something warmer to keep by the door without dealing with laces or heavier boots every time they leave the house. At under $18, this is also a relatively painless replacement for slippers or casual shoes whose soles have become suspiciously smooth.

HEAD women’s touchscreen running gloves
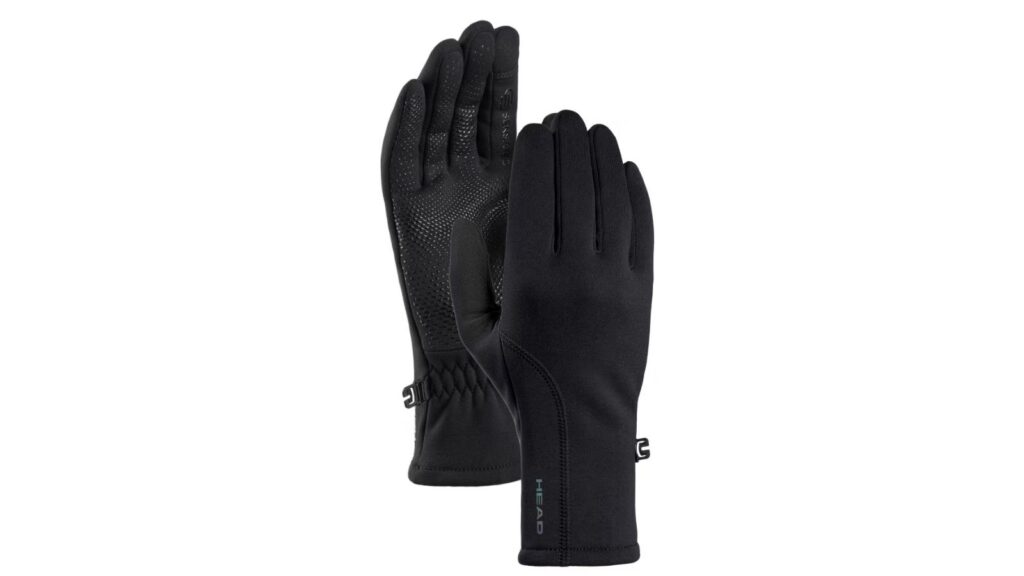
touchscreen running gloves
Image Credit: Costco

Fall walking and running weather is great right up until your hands disagree. HEAD’s touchscreen running gloves are $19.99, with stretch fleece, touchscreen-compatible fingertips, silicone grip, and reflective details.

They are light enough for cool-weather exercise rather than deep-winter shoveling, which makes them useful during exactly the stretch of weather when bare hands are uncomfortable but bulky gloves are annoying. Being able to use a phone without taking them off is also useful on walks, commutes, and school sidelines. Twenty dollars is worthwhile if you will actually use the sport-specific features. Someone who only needs gloves for taking the trash out can spend less.

Berkshire Life heated throw
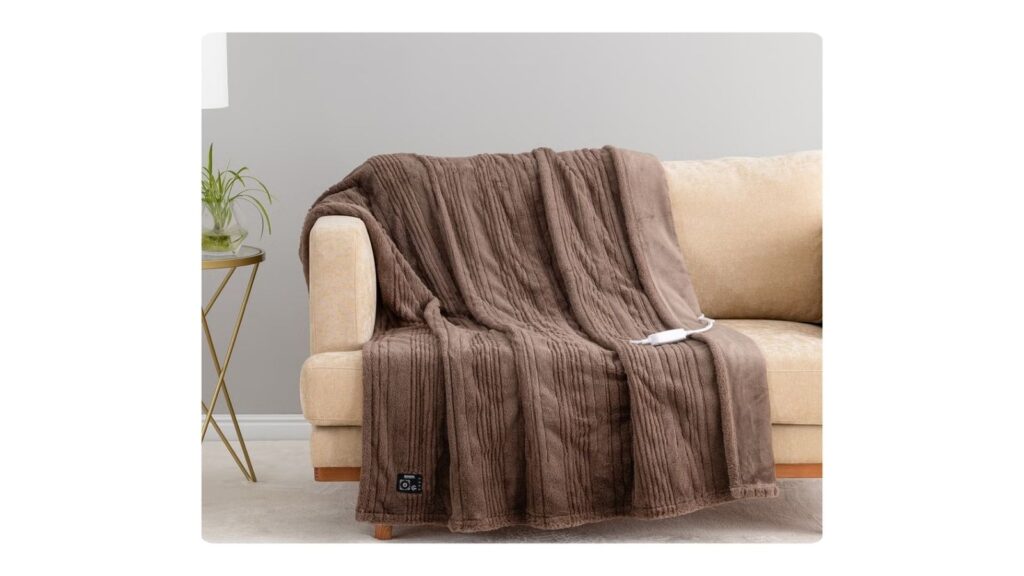
heated throw
Image Credit: Costco

The first chilly evening does not necessarily require heating the whole house like it is mid-January. Berkshire Life’s heated throw is $34.99, with four heat settings and a four-hour automatic shutoff.

The 50-by-60-inch throw has faux fur on one side and a velvety finish on the other, and it is machine washable once the controller is removed. That makes it useful for the couch, a reading chair, or someone whose preferred indoor temperature is several degrees warmer than everyone else’s. At around $35, it is also a far more practical fall comfort purchase than a pile of decorative blankets that look seasonal but do absolutely nothing when the room is cold.

Herringbone down-alternative blanket
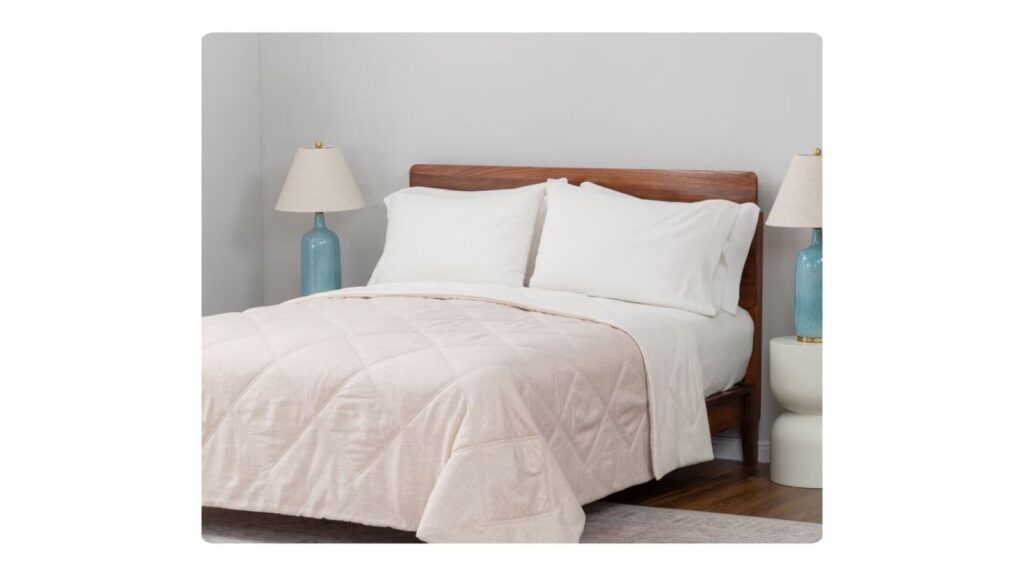
Herringbone down alternative blanket
Image Credit: Costco

If the summer quilt suddenly feels inadequate at 3 a.m., Costco’s herringbone microfiber down-alternative blanket is a straightforward seasonal upgrade. Prices currently start at $26.99, depending on bed size.

The reversible blanket has a 345 GSM weight and down-alternative fill, so it adds warmth without the care requirements of real down. It is also machine washable, which is useful for households with pets, kids, or guest beds that need to be ready for holiday visitors. Around $27 for a full-size bed blanket is reasonable if you genuinely need another layer. It is less convincing as the fifth blanket in a linen closet already threatening to avalanche.

Total blackout velvet curtains
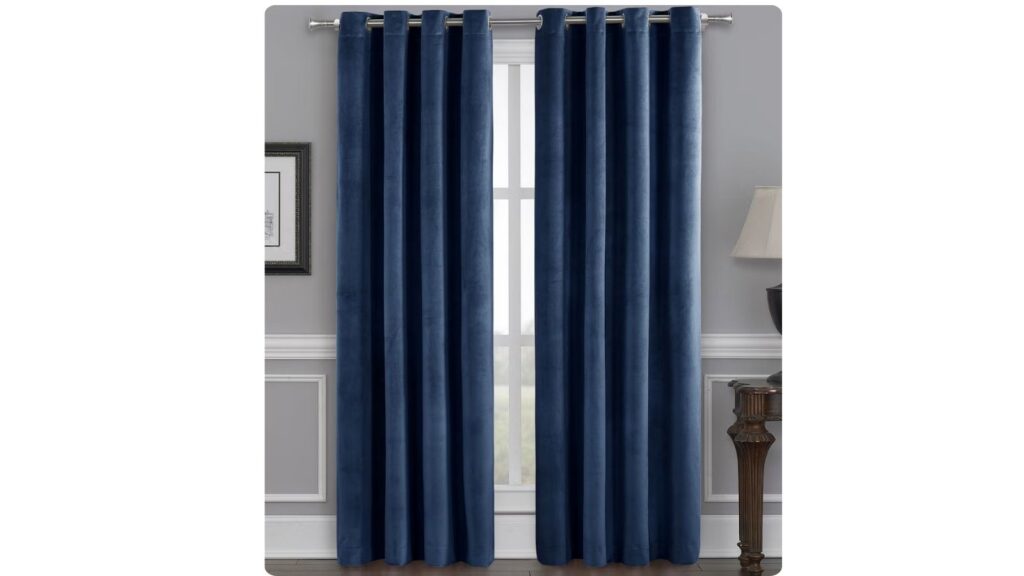
Total blackout velvet curtains
Image Credit: Costco

Fall does not just bring colder evenings. It also finds every drafty window in the house. Costco’s Total Blackout velvet curtains come as a two-panel pack starting at $42.99, with an insulated construction designed to block light and help reduce heat transfer.

They are a particularly useful buy for bedrooms, street-facing rooms, or older windows where cold air becomes noticeable as temperatures drop. Blackout curtains can also make early fall sunsets less disruptive for shift workers and young children. Measure carefully before ordering, because an inexpensive curtain is no bargain when it stops six inches above the floor. For a room that already needs window coverings, getting insulation and blackout coverage in the same purchase is a better use of the budget.

Solo Stove Bonfire fire pit
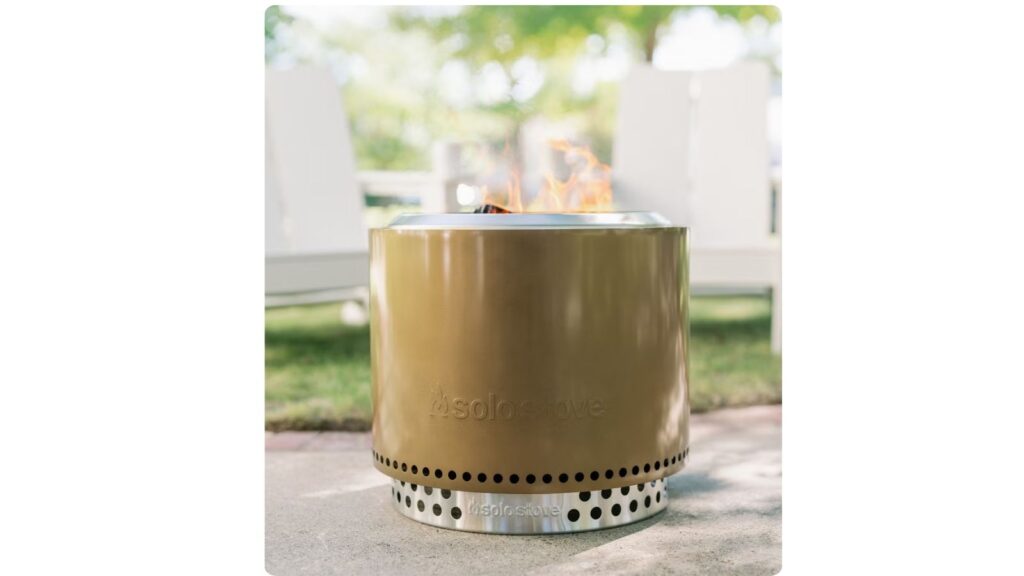
fire pit
Image Credit: Costco

A fire pit has one very obvious fall job: keeping the patio useful after temperatures drop. Costco’s Solo Stove Bonfire 2.0 in metallic bronze is $199.99, including the stand and carry case.

The 19.5-inch wood-burning pit uses Solo Stove’s airflow design to reduce smoke and has a removable ash pan that makes cleanup less miserable. Two hundred dollars is not a casual backyard purchase, but the included accessories improve the value compared with piecing together a pit, stand, and storage solution separately. This is worth considering for households that regularly entertain outside or use a fire pit through fall. If everyone heads indoors the second it gets chilly, your money has other work to do.

Greenworks 80V blower and string trimmer
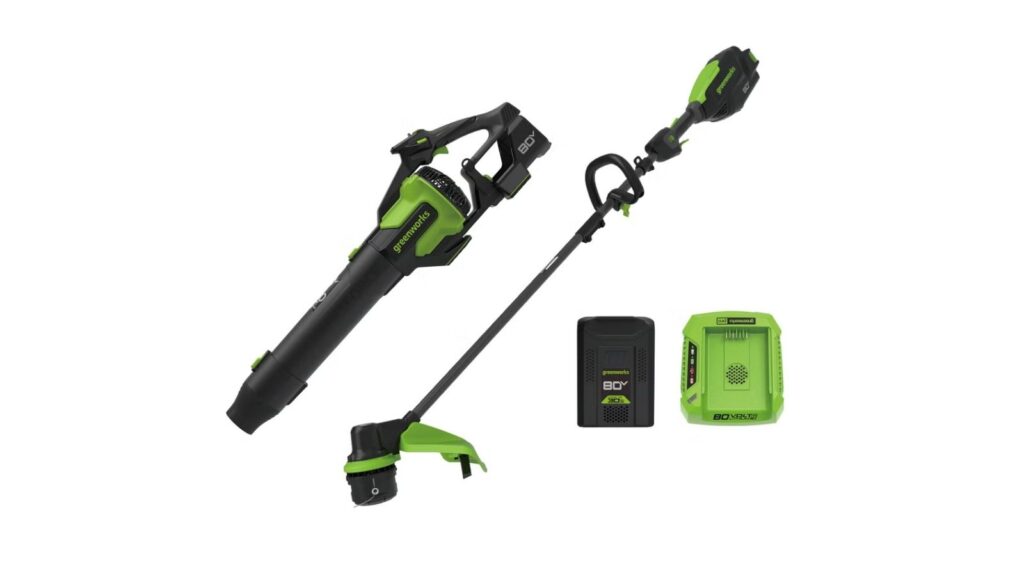
Greenworks 80V blower and string trimmer
Image Credit: Costco

Leaves turn a cordless blower from a nice garage extra into something you may use every weekend. The Greenworks 80V package combines a 730 CFM blower and 17-inch string trimmer for $279.99, currently $50 off. A battery and charger are included.

The blower is specifically designed to clear debris and wet leaves from driveways, patios, and other hard surfaces, while the trimmer can handle the last rounds of yard cleanup before winter. This is only a deal if you need both tools, since buying a bundle to use half of it defeats the point. For someone replacing aging gas equipment or starting a cordless yard-tool setup, getting two 80V tools plus the battery at the discounted price is more compelling.

Wells Lamont HydraHyde work gloves
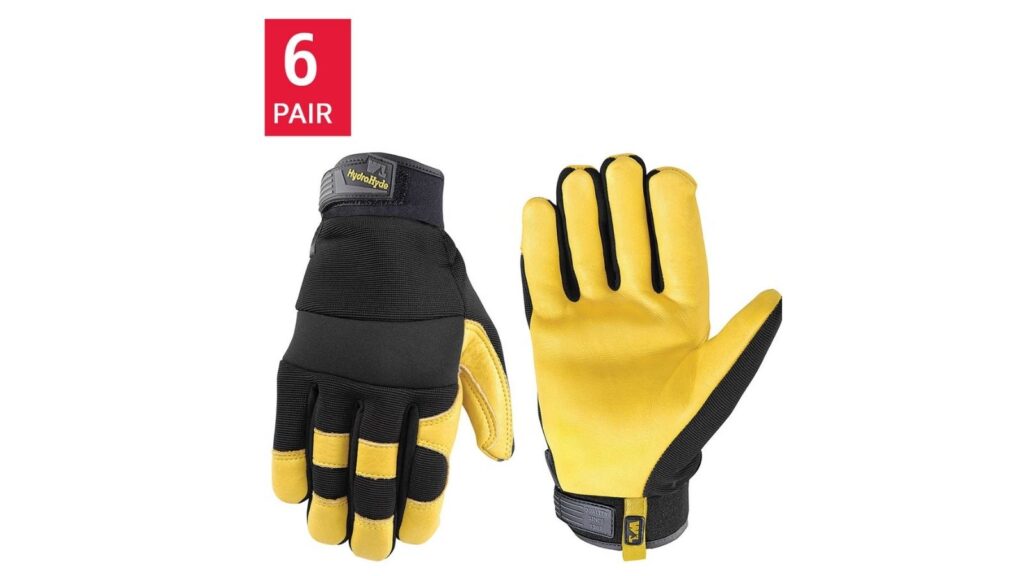
work gloves
Image Credit: Costco

Raking leaves, moving branches, stacking firewood, and cleaning up the garden are all faster when you are not stopping every few minutes to inspect another splinter. Wells Lamont’s HydraHyde leather work gloves come in a six-pair pack for $43.99.

That works out to roughly $7.33 per pair. The goatskin palms are water resistant, while the stretch backs and adjustable wrists make them useful for landscaping, gardening, equipment work, and general fall cleanup. Six pairs are excessive for an apartment dweller with one houseplant. For a household that burns through work gloves, shares them between several people, or keeps spare pairs in the garage and shed, the bulk pack makes much more sense.

Scotts MAX Fall Weed & Feed
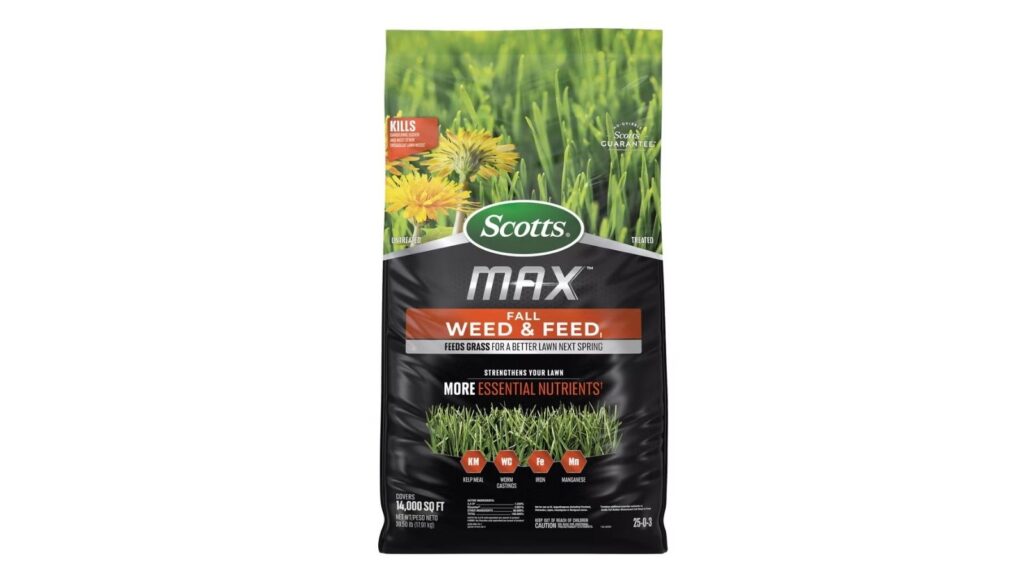
weed and feed
Image Credit: Costco

Fall lawn care is one of those jobs that is easy to remember in April, when the results of skipping it become obvious. Costco’s Scotts MAX Fall Weed & Feed covers up to 14,000 square feet and is listed online at $79.99, with Costco’s current savings event taking $20 off participating fall or southern formulas through September 20.

The 39.5-pound bag is meant to kill listed weeds while feeding grass ahead of next spring. This obviously only makes sense for a fairly large lawn, and it should be used according to the grass type and application conditions on the label. For homeowners already planning a fall lawn treatment, the current $20 discount is worth using rather than paying full price later.

Halloween and harvest kitchen towels
Halloween and harvest kitchen towels
Image Credit: Costco

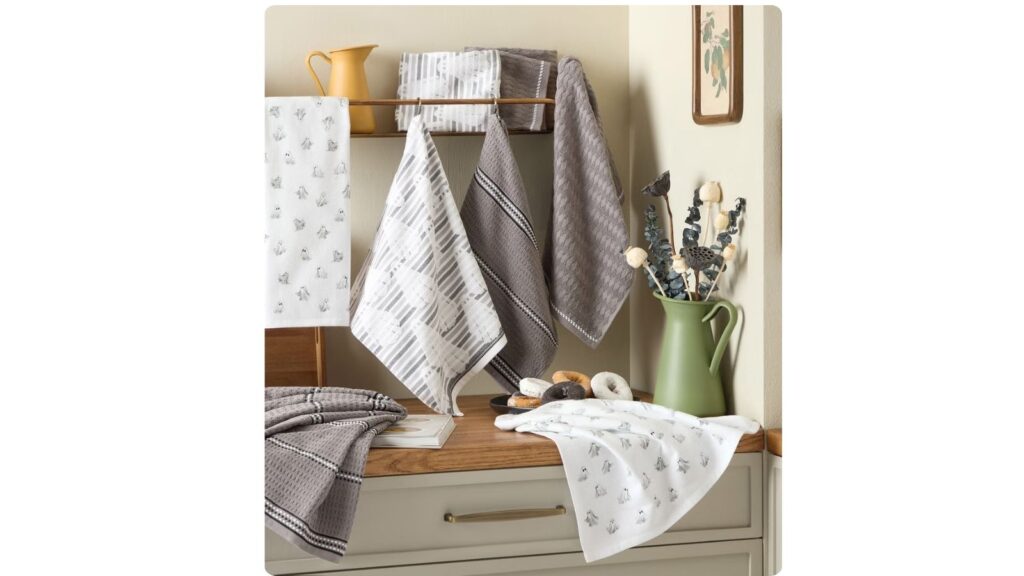
Seasonal decor is easier to justify when it can also wipe up gravy. Costco’s Halloween and Harvest kitchen towels come in an eight-pack priced around $14.99, with multiple autumn and Halloween designs. The current Costco product page remains live, although design selection can vary.

Each towel measures 18 by 28 inches, and the set mixes cotton and cotton-blend styles that are machine washable. At less than $2 per towel, they are inexpensive enough to use rather than treat as untouchable kitchen decoration. This is the sort of fall purchase that works for a tight budget because it can replace worn kitchen towels while still adding a seasonal touch. No storage bin full of ceramic acorns required.

Harvest hooked accent rug
Harvest hooked accent rug
Image Credit: Costco

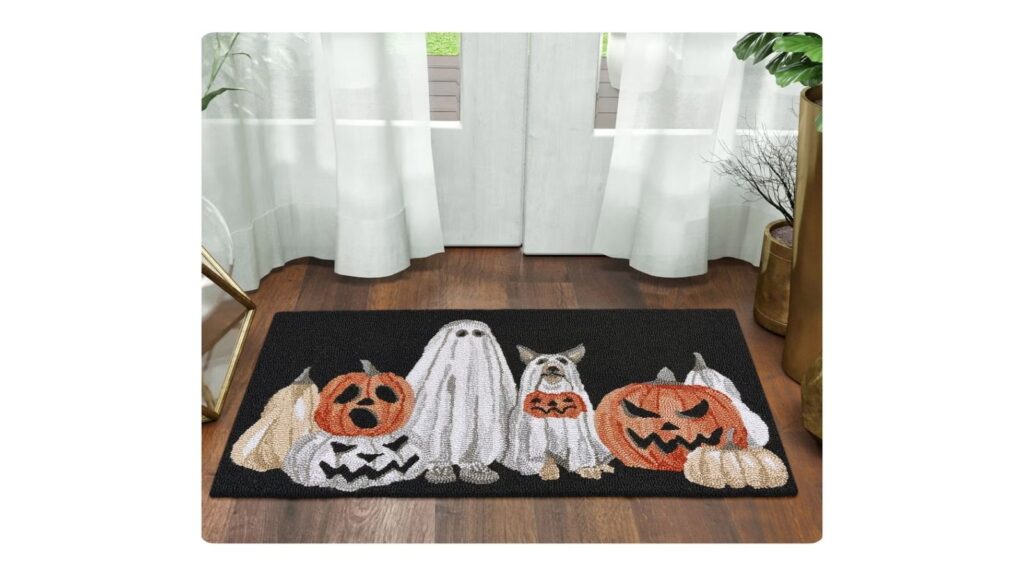
An entry rug is another piece of fall decor that can do actual work. Costco’s 22-by-38-inch Harvest Hooked Accent Rug has been listed at $26.99, with seasonal designs intended for entryways, kitchens, and other high-traffic spots.

The hand-hooked polypropylene pile is more practical around wet fall shoes than a delicate decorative textile, and the memory-foam padding adds some cushioning underfoot. Twenty-seven dollars is not dirt-cheap for a small rug, but it is easier to justify when the rug fills a real spot by the door or sink rather than existing solely because September happened. If you already own a good entry mat, skip it. Seasonal redundancy is still redundancy, even when pumpkins are involved.

Talavera-style ceramic pumpkin
Ceramic pumpkin
Image Credit: Costco

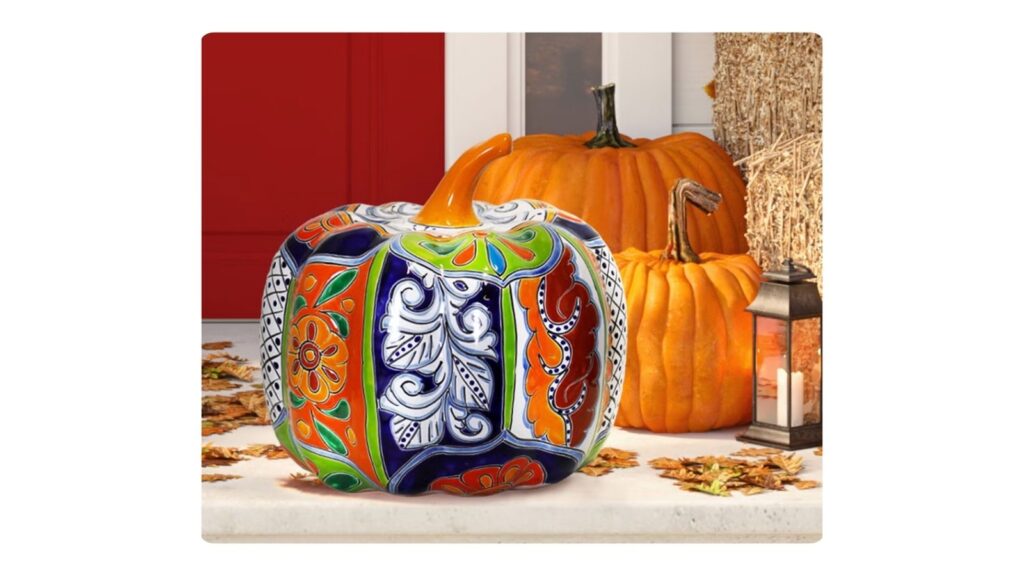
For one genuinely decorative pick, Costco’s 13-inch Talavera-style ceramic pumpkin is $69.99. It is hand-painted in Mexico, double glazed, weighs 15 pounds, and is designed for indoor or outdoor display. Costco still lists it in its current harvest and Halloween collections.

Seventy dollars is too much for throwaway decor, but that is not really what this is. Ceramic construction and a weather-friendly glazed finish give it a much better chance of coming back out every September for years, which matters if you prefer buying one substantial porch piece instead of replacing cheaper decorations annually. The multicolor Talavera pattern also avoids being locked into one narrow Halloween look, so it can stay out through Thanksgiving without looking like somebody forgot to put October away.
A college application plan works better when each month has a limited job. Senior year becomes difficult when college research, essays, recommendations, financial aid, schoolwork, and deadlines are treated as one large project. Common App itself breaks the process into separate stages, including gathering materials, adding colleges, working with supporters, understanding requirements, planning essays, and submitting applications. The calendar below turns those stages into a practical month by month college application plan that can be adjusted to individual school deadlines.

August: Finalize your college list and build one master calendar

August should turn a broad college search into a working application list. Check each college for admission plans, application requirements, essays, testing policies, financial aid requirements, and deadlines. Colleges set their own deadlines, so dates should be taken from each institution rather than assumed from a general admissions calendar. Common App also notes that individual colleges choose their own admission plans and deadlines.

Next, create one document or spreadsheet containing every school and every required task. Include the application deadline, recommendation requirements, supplemental essays, test score policy, financial aid dates, interview information, and application fee. Mark early applications separately from regular applications.

This is also the right point to decide whether outside guidance would make the schedule easier to manage. Transizion works with college selection, application planning, essays, deadlines, and individual mentorship. If that type of structured support fits your situation, check this website while building the calendar rather than waiting until deadlines are close.

Your August checklist can stay short:

  • Confirm the final college list.
  • Record every college deadline.
  • Review application requirements.
  • Create a folder for each college.
  • Identify all required essays.
  • Decide which applications may be submitted early.

September: Get recommendations moving and draft the main essay

September is the month for work that depends on other people. Ask teachers for recommendations early enough for them to prepare thoughtful letters, and make sure the appropriate counselor or school official knows where school forms need to go. Common App allows applicants to invite recommenders and provides a system for recommendations, transcripts, and other school materials.

At the same time, move the main personal essay from brainstorming into drafting. Do not spend the entire month searching for a perfect topic. Choose a subject that gives enough room to explain something important about your experiences, decisions, interests, or growth, then revise it several times. Supplemental essays can begin once the main essay has a clear direction.

October: Finish early applications and start financial aid tasks

October is where the calendar becomes less flexible. If an early action or early decision application is on the list, review every component well before its actual deadline. Check names, dates, activities, course information, essays, uploads, and college specific questions.

Financial aid also deserves its own track. Federal Student Aid explains that FAFSA deadlines can differ at the school, state, and federal levels, with schools often having the earliest dates. The safest approach is to check the financial aid page of every college on the list rather than relying only on the federal deadline.

If another SAT attempt is relevant to your application plan, check current test and score release dates before registering. College Board lists October, November, and December SAT dates during the 2026 fall application season.

Before submitting anything, complete a final review:

  • Read each essay outside the application form.
  • Confirm that the correct essay is attached to the correct college.
  • Review the activities section for missing details.
  • Confirm recommendation status.
  • Check the college’s official deadline again.

November: Submit early applications and build the regular decision queue

Once early applications are submitted, do not treat November as a waiting month. Move directly to regular decision applications. Sort remaining colleges by deadline and amount of work required, then finish the schools with the largest number of supplemental essays first. Common App provides deadline and requirement tracking through the applicant dashboard, but each school’s requirements still need individual review.

December: Reduce the number of unfinished pieces

December should be about completion rather than expansion. Avoid adding colleges without a clear reason because every new school may bring another set of questions, essays, fees, and financial aid requirements.

Complete supplemental essays in batches when prompts address related subjects, but answer each college’s actual question. Reusing an idea can save time. Copying one school specific response into another application usually cannot.

If early admission decisions arrive, read the terms carefully. A result may change the remaining application plan, but it should not cause other deadlines to be ignored until the implications of that decision are clear.

January: Submit regular applications and verify what arrived

January is often less about writing and more about verification. After submitting an application, confirm that the college has received required materials. A submitted application does not automatically mean that every transcript, recommendation, test score, or financial aid item is complete.

Common App explains that colleges determine which school forms they require, and these can include counselor recommendations, teacher evaluations, midyear reports, and final reports. Keep checking applicant portals and respond when a college requests missing information.

February and March: Shift from applications to follow up

By February, most of the work should move into maintenance. Keep grades steady, check applicant portals, watch email carefully, and complete scholarship applications that remain open. If a college requests an additional document, send it according to its instructions rather than assuming the application is already finished.

Financial aid work may also continue. Federal Student Aid advises applicants to follow school and state FAFSA deadlines because those can arrive well before the federal deadline and some aid may be limited.

When admission decisions begin arriving, create a comparison sheet instead of reacting to the first acceptance. Record estimated cost, grants and scholarships, academic options, housing, location, and any conditions attached to the offer.

The useful question now changes. During fall, the question was whether an application was ready to submit. During spring, it becomes whether a college still makes sense after the real cost and admission terms are known.

April and May: Compare offers and make the final decision

The final stage is a comparison project. Read financial aid offers carefully and calculate what each option would require from the student and family. Federal Student Aid recommends comparing aid offers and considering net cost when deciding where to enroll.

Do not let months of effort create pressure to choose a college simply because its application required more work. Application effort is already spent. The final decision should use the information available now.

Review the remaining choices from several angles:

  • Confirm the full expected cost.
  • Compare academic programs connected to your goals.
  • Review housing and campus arrangements.
  • Check enrollment instructions and deadlines.
  • Decline offers you know you will not use.
  • Complete the enrollment steps for the selected college.

A strong college application timeline does something more useful than preventing missed deadlines. It changes the type of decision that needs attention each month. August is about selection, fall is about execution, winter is about completion, and spring is about comparison. When those jobs stay separate, senior year becomes easier to manage and final college decisions can be made from actual offers rather than assumptions made months earlier.

For a single parent, the family car is not a convenience; it is a lifeline. It gets kids to school, gets you to work, and holds the whole schedule together. That makes car insurance one of the most important, and most stressful, line items in the budget.

Find practical car insurance tips for single parents, including coverage options that can fit your budget and family needs.
Image Credit: Frankie Cordoba via Unsplash

The challenge is real: protect your family fully without paying a dollar more than you must. A reliable insurer such as www.5starinsurance.com is one piece of that, but knowing what to buy matters just as much. This guide walks through getting coverage that fits both your family and your finances.

Why does car insurance matter more for single parents?

When you are the only driver and the only earner, the stakes are simply higher. There is no second income to fall back on if an accident brings a large bill or takes the car off the road. The margin for error is thin.

That reality cuts two ways. You need enough coverage to protect the family from a serious financial hit, yet the premium has to fit a single-income budget. Getting that balance right is the whole task. Too little coverage risks everything; too much drains money the family needs elsewhere.

How much coverage does a family really need?

The legal minimum is rarely the right answer for a parent. Liability coverage is the part that pays for injury and damage you cause to others, and the state minimums are often too low to protect a household with assets. A serious crash can exceed them fast.

A sensible single-parent policy usually includes:

  1. Solid liability. Limits high enough to protect your savings.
  2. Uninsured motorist. Cover if an uninsured driver hits you.
  3. Adequate medical. Help with injury costs for you and the kids.
  4. The right deductible. A level you could actually pay in a pinch.

A deductible is the amount you pay toward a claim before insurance covers the rest. Set it where a surprise would not derail you. For families relying on one vehicle, individual coverage choices like these deserve real thought rather than a rushed default. The goal is protection you can count on.

Where can you cut costs safely?

Lowering the premium does not have to mean gutting your protection. The smartest savings come from structure and shopping, not from stripping coverage you genuinely need. A few moves make a real difference.

Image Credit: Vitaly Gariev via Unsplash

Try these to trim the cost:

  • Compare quotes. Prices vary widely between insurers.
  • Bundle policies. Combine auto and renters or home.
  • Adjust the deductible. A higher one lowers the premium.
  • Ask about discounts. Safe driving and low mileage count.

The biggest lever is often simply shopping around each renewal. Government-adjacent consumer guides on how to save on car insurance and nine ways to lower your costs list proven tactics worth trying. Cut the price, not the protection your family depends on.

What mistakes should you avoid?

A few common errors quietly cost single parents money or leave dangerous gaps. Knowing them in advance is half the battle. Most are easy to sidestep.

The frequent traps are predictable. Carrying only the state minimum can expose your assets after a bad accident. Setting a deductible too high risks a bill you cannot pay when the car breaks down or crashes.

Letting a policy lapse to save a month can spike your future rates. It can also leave you uninsured at the worst moment. Avoiding these missteps protects both the budget and the family.

How do you find the right policy?

Finding the right fit is less about luck than about a little organized effort. With a clear picture of your needs, comparing options gets much simpler. A short process gets you there.

Follow these steps to land a good policy:

  1. Know your needs. Match coverage to your family and assets.
  2. Gather quotes. Compare several insurers on the same terms.
  3. Check the insurer. Look for strong service and claims reviews.
  4. Review yearly. Reassess as your life and car change.

The right policy balances real protection with a premium you can sustain. Read what a quote actually includes, not just the headline price, and favor an insurer that treats a claim fairly. A little effort now buys genuine peace of mind for the whole family later.

Protecting your family and your budget

Car insurance is where a single parent protects both the people who depend on them and the budget that keeps everything running. Carry enough coverage to shield the family from a serious hit, then trim the cost through smart shopping rather than thin protection. Avoid the common traps, compare options honestly, and review the policy as life changes. Handled that way, the family car stays a lifeline, not a liability.

Frequently asked questions

How much car insurance does a single parent need?

Enough to protect your family and assets, which usually means more than the state minimum. Solid liability limits, uninsured motorist coverage, and adequate medical protection are wise, along with a deductible you could actually pay. The exact amount depends on your assets and budget, so match the policy to your real situation rather than a generic default.

What is the best way to lower my premium?

Comparing quotes at each renewal is the single most effective step, since prices vary widely between insurers for the same driver. Bundling policies, adjusting your deductible, keeping a clean record, and asking about discounts all help too. The key is trimming the price without cutting the coverage your family genuinely needs.

Should I Only Get the State Minimum to Save Money?

Usually not. State minimums are often too low to cover a serious accident, leaving you personally responsible for the rest, which can threaten your savings and stability. For a single-income household, that exposure is a real risk. Carrying more than the minimum is typically a wiser investment in your family’s financial security.

How often should I review my car insurance?

At least once a year, and after any major change such as a new car, a move, or a teen driver. Your needs and the market both shift over time, so a yearly review keeps your coverage right and your price competitive. Treating it as a regular habit prevents both overpaying and dangerous coverage gaps.

You check your account balance on a random Tuesday and it’s $340 lower than you expected, again. Nothing dramatic happened. No big purchase, no emergency, just the usual mix of coffee, a couple of Amazon orders, and a lunch you didn’t feel like packing that morning. That’s how most people actually lose money. Not in one big hit, but in a hundred small ones that never show up on a receipt worth remembering.

The fix works the same way, in reverse. You don’t need to overhaul your whole life to find an extra couple hundred dollars a month. You need a handful of small changes that don’t ask much of you and quietly add up by December.

Start with the money you already have, sitting in an account that’s barely paying you anything for the privilege.

Open a high-yield savings account for your idle cash

high-yield savings account
Image Credit: Shutterstock

Most people keep their savings in whatever account their bank defaulted them into, which usually means it’s earning next to nothing. The average savings account nationwide currently pays 0.38% APY, while online banks are offering 4% or higher on the same money, with no extra risk and no lockup period.

On $5,000 in savings, that’s the difference between earning about nineteen dollars a year and earning well over two hundred, just for choosing where you park cash you already have. Moving an emergency fund or a slush fund into a high-yield account takes about ten minutes online. Most don’t require a minimum balance, and the money stays FDIC insured and just as easy to access as it was before.

This isn’t a habit you have to keep building. It’s a decision you make once, and the interest keeps stacking up in the background without you doing anything else.

Automate a payday transfer before you can spend it

payday written on calendar
Image Credit: Shutterstock

Most savings plans assume you’ll move whatever’s left over into savings at the end of the month. Almost nobody actually does this, because by the end of the month there usually isn’t anything left over. The version that works runs backwards: money moves the day it lands, before you’ve had a chance to spend it.

Set up an automatic transfer from checking to savings for the same day your paycheck hits, even if you start with fifty dollars a check. That’s $1,300 a year. Bump it to a hundred dollars and you’re at $2,600. You won’t miss money you never see sitting in checking, and you’re not relying on willpower at nine at night when you’re tired and scrolling.

Pair this with a high-yield account and the two habits do the work for each other. Money moves on its own, and it earns real interest the moment it lands instead of sitting idle for weeks.

Audit your subscriptions and cancel what you don’t use

subscription renewed
Image Credit: Shutterstock

The average American now spends $111 a month on subscriptions, with about $252 of that a year going toward services nobody’s actually using. Streaming apps stack up fast, and a free trial for a meal kit or a fitness app quietly converts to a paid plan long after you forgot you signed up.

Pull up your bank or card statement and list every recurring charge you see, not just the obvious ones. Cancel anything you haven’t opened or used in the last month. For the ones you’re not ready to give up, check whether an annual plan is cheaper than paying monthly. Plenty of streaming and software services knock off a month or two of cost if you pay for the year up front.

Do this every few months, not just once. New subscriptions creep back in faster than people expect, especially ones that renewed automatically after a trial.

Swap name-brand groceries for store brands

shock at large grocery bill
Image Credit: Shutterstock

Store-brand groceries typically cost 25% to 30% less than the name-brand version of the same product, and in blind taste tests, most shoppers can’t tell the difference. This isn’t about overhauling your whole cart in one trip. Start with pantry basics: pasta, canned tomatoes, flour, sugar, spices, and frozen vegetables, where the recipe barely changes between brands.

Cereal, condiments, and dairy are usually safe swaps too, and most people can’t tell the difference once it’s poured into a bowl or mixed into a recipe. Baking is one place brand loyalty sometimes still pays off, since the exact ratio of ingredients can change texture in a cake or cookie, along with anything your household is particular about, like a specific coffee or peanut butter.

Do the swap gradually, a few items a trip, so you actually notice which substitutions your family accepts without complaint and which ones aren’t worth the savings. A full cart switch on a family of four’s weekly shop can realistically shave $30 to $50 a week off the total, depending on how much of that cart was name-brand to start with.

Make your coffee at home

coffee maker
Image Credit: Shutterstock

Buying a basic drip coffee from a drive-through every weekday adds up to roughly $766 a year, which is a strange amount of money for something that doesn’t feel expensive in the moment. Order a flavored latte instead of plain drip and that number climbs considerably higher.

You don’t have to give up coffee, just where you buy it. A basic drip machine, a French press, or even good instant coffee gets you the same caffeine for a fraction of the price, and you can still treat yourself to the coffee shop version once a week instead of every day. Even a $150 espresso machine pays for itself within a couple of months compared to buying espresso drinks out daily.

If you’re buying for two people in the household, double every number above. A habit that looks small at $5 a day changes shape once you multiply it by a family, and it changes again once you add in the pastry or breakfast sandwich that often rides along with the coffee order.

Pack lunch a few days a week

make a packed lunch the night before
Image Credit: Shutterstock

Workers who buy lunch out spend an average of $34.82 a week doing it, which works out to somewhere around $1,800 a year for food you could usually make at home for a fraction of that. You don’t need to pack lunch every single day to see the difference. Even bringing lunch three days a week and buying it the other two cuts the total meaningfully.

Leftovers from dinner are the easiest version of this. Cook a little extra the night before and lunch is already handled, no extra prep required. Sandwiches, grain bowls, and soups also hold up well overnight and travel easily to work, and none of them require anything fancier than containers you probably already own.

The savings show up fastest for people who currently buy lunch out most days. If that’s you, even swapping two of those five workdays for something packed from home puts a real dent in a weekly total that’s easy to lose track of when it’s five separate five-to-fifteen-dollar charges instead of one number on a statement.

Shop your car insurance every year

car insurance
Image Credit: Shutterstock

Drivers who never compare rates could be overpaying by an average of $4,914 a year compared to what they’d pay by shopping around. Insurers price you differently depending partly on when you last got a new quote, not just your driving record, which is why staying loyal to one company rarely pays off the way people assume.

Get quotes from at least three insurers once a year, even if you’re happy with your current company. If your current insurer’s renewal price comes in higher than a competitor’s quote, call and ask them to match it before you switch. Many will, since keeping an existing customer usually costs an insurer less than acquiring a new one.

Life changes are also a good trigger to re-shop: a move, a paid-off car, a teen driver aging into their own policy, or simply a birthday that bumps you into a new age bracket for pricing. Bundling home or renters insurance with your auto policy at the same company is worth asking about too, since insurers frequently discount both policies for keeping them together.

Turn the thermostat back a few degrees

smart thermostat
Image Credit: Shutterstock

You can cut up to 10% off your annual heating and cooling costs just by setting your thermostat back seven to ten degrees for eight hours a day, whether that’s while you’re asleep or out of the house at work. The house doesn’t have to work harder to warm back up afterward. It actually loses heat more slowly the colder it gets relative to outside.

A programmable or smart thermostat automates this so you’re not manually adjusting it twice a day, but you don’t need to buy anything new to start. Set it back manually before bed and before you leave for work, and set it back to normal about half an hour before you’re due home or awake so the house is comfortable by the time you need it to be.

The same idea works in reverse for summer cooling: keep the house a little warmer than usual while nobody’s home, and cool it to a comfortable temperature only when someone’s actually there to feel it. This one costs nothing and takes effect the same day you start doing it, which makes it one of the fastest habits on this list to see reflected on an actual bill.

Ditch the bank that charges you fees

bank building
Image Credit: Shutterstock

A monthly maintenance fee of $10 to $15 doesn’t feel like much in the moment, but that’s up to $180 a year for the privilege of keeping your own money in an account. Add an overdraft charge or two and an out-of-network ATM withdrawal, and the yearly total climbs past $300 without a single dramatic charge ever showing up.

Most banks waive the monthly fee if you set up direct deposit or keep a minimum balance, and plenty of people qualify without realizing it because nobody ever pointed it out to them. If yours doesn’t offer an easy waiver, online banks and credit unions routinely offer checking accounts with no monthly fee and no minimum balance at all, often with a better savings rate attached too.

Switching banks sounds like a hassle, but most of it is one afternoon: open the new account, move your direct deposit, update any autopay links, and close the old one once everything’s cleared and any pending transactions have settled. Set a calendar reminder for two weeks out to double check nothing bounced during the switch.

Ask your pharmacist about the generic

pharmacist handing over prescription
Image Credit: Shutterstock

Generic prescription drugs are typically 80% to 85% cheaper than their brand-name equivalents, and they’re held to the same FDA safety and effectiveness standards, not a watered-down substitute. Most pharmacies will fill the generic automatically unless your doctor specifically writes the prescription as dispense-as-written.

If your doctor prescribes something new, it’s worth asking directly whether a generic version exists yet. Some newer medications don’t have one, but plenty of common prescriptions for blood pressure, cholesterol, allergies, and reflux do, and the price difference at the counter can be dramatic, sometimes the difference between a co-pay and a bill that runs well into three figures.

Check your insurance plan’s formulary too, since many plans put generics in the lowest-cost tier specifically to encourage this. This is one of the rare places where the cheaper option isn’t a compromise. It’s the same drug, made to the same standard, with a different label and a smaller price tag.

Switch to a lower-cost cell carrier

paying cell phone bill
Image Credit: Shutterstock

People who switch from one of the big three carriers to a smaller provider like Consumer Cellular or Mint Mobile have reported saving close to $500 a year, while keeping the same phone number and largely the same coverage, since most smaller carriers run on towers owned by the major networks anyway.

Before switching, check how much data you actually use most months. If you’re rarely far from Wi-Fi and don’t stream much video on the go, a lower-data plan from a smaller carrier probably covers you fine. Porting your number over usually takes less than an hour and doesn’t require a new phone, and you can often keep your current phone as long as it’s unlocked.

There’s a real trade-off worth knowing about: smaller carriers can get deprioritized on the network during high-traffic times, so data speeds occasionally slow down in crowded areas even though you’re using the same towers. For most people’s daily use, that trade-off is worth several hundred dollars a year. Multiply the savings by however many lines are on your family plan, since this is one habit that scales with household size.

Borrow instead of buy at the library

student and library card
Image Credit: Shutterstock

A household that regularly checks out books, movies, and museum passes instead of buying or renting them can save around $2,300 a year, using an online calculator built specifically to price out library use against retail cost. Most libraries also lend audiobooks and ebooks digitally, so you don’t even need to visit in person to use the card.

Plenty of library systems have expanded well past books. Some lend out power tools, sewing machines, board games, telescopes, and even museum or state park passes for free, items that would otherwise sit in a closet after one project or one visit. Many also offer free access to streaming services, magazine apps, and online courses that would otherwise cost a separate subscription.

If it’s been years since you used your card, it’s worth checking what your specific library system actually offers now rather than assuming it’s still just a room of books. The catalog has usually grown a lot since the last time you looked, and most of it can be browsed and reserved from your phone before you ever set foot inside the building.

Let a cash-back app work while you shop

ibotta logo
Image Credit: Ibotta, public domain via Unsplash

Roughly 160 million Americans now use cash-back apps like Rakuten and Ibotta, with typical users earning $250 to $300 a year back on purchases they’d have made anyway. The apps work by checking offers before you shop online or scanning a receipt after an in-store purchase, and the cash back deposits straight to your bank account or PayPal.

This only pays off if you’re buying things you already needed. A coupon or cash-back offer on something you weren’t going to buy isn’t a discount, it’s a new expense with a rebate attached, and it’s the one way this habit can quietly work against you instead of for you.

Used on routine purchases, groceries, household basics, gas, it’s free money for spending you were doing anyway. Most apps let you stack their cash-back offer on top of a store’s own sale price or a coupon, which is where the real savings tend to show up rather than on any single offer alone.


Sell what’s been sitting in a closet or garage

garage full of collectibles
Image Credit: Shutterstock

Most households have things they paid real money for and haven’t touched in over a year: clothes that don’t fit anymore, electronics replaced by a newer model, kids’ gear outgrown, tools bought for one project. Facebook Marketplace, eBay, and local consignment or buy-sell-trade groups make it easier than it used to be to turn that stuff back into cash instead of storage clutter.

Start with anything actually worth real money rather than trying to sell everything at once. Name-brand clothing, working electronics, furniture in decent shape, and specialty tools tend to sell fastest and for the most money. Items with almost no resale value, like fast-fashion basics or outdated electronics, are usually better donated than listed, since the time spent photographing and messaging back and forth isn’t worth it for a five-dollar sale.

This is a one-time cash boost rather than a recurring monthly habit, but it’s real money that’s currently doing nothing but taking up space. Put the proceeds straight into the savings account or debt payment you’re working toward instead of letting it blend back into everyday spending, or the whole exercise ends up being a wash.

Buy the generic version of your medicine cabinet basics

lots of medication in a pile with money
Image credit: Çağlar Oskay via Unsplash

The same logic that applies to store-brand groceries applies to the basics in your bathroom cabinet: pain relievers, allergy medicine, antacids, and cold remedies. Store brands are required to match the active ingredient and dosage of the name-brand version to make the same claims on the label, which is why the two usually work identically despite the price difference.

Check the “compare to” or “active ingredient” line on the store-brand box against the name-brand version you’d normally buy. In the vast majority of cases, they match exactly, down to the milligram.

This is a small swap on its own, but it’s one more place where brand loyalty is costing you money for no real benefit.

None of these eighteen habits require a dramatic life overhaul, and you don’t need to adopt all of them at once to notice the difference. Pick three or four that fit your actual life, start there, and add more once the first few feel automatic.

That yellow and blue plastic house in the basement, the one with the doorbell that still rings and the garage door that still rolls up, is not just clutter waiting for a garage sale sticker. Fisher-Price has been making toys since 1930, and a surprising number of the ones that ended up in attics, toy chests, and church rummage sale boxes are worth real money today.

Most of what the company made was built to survive decades of hard play, which means millions of examples still exist and most of them are worth very little. The toys that command real prices are usually older, licensed, or tied to a specific version that only ran for a short time. Condition and completeness decide almost everything else. A toy missing one small plastic horse or one paper sticker can be worth a tenth of the same toy with every original piece intact.

Fisher-Price Pushcart Pete pull toy (1936 to 1937)

Fisher-Price Pushcart Pete pull toy
Image Credit: angelinabella via Etsy

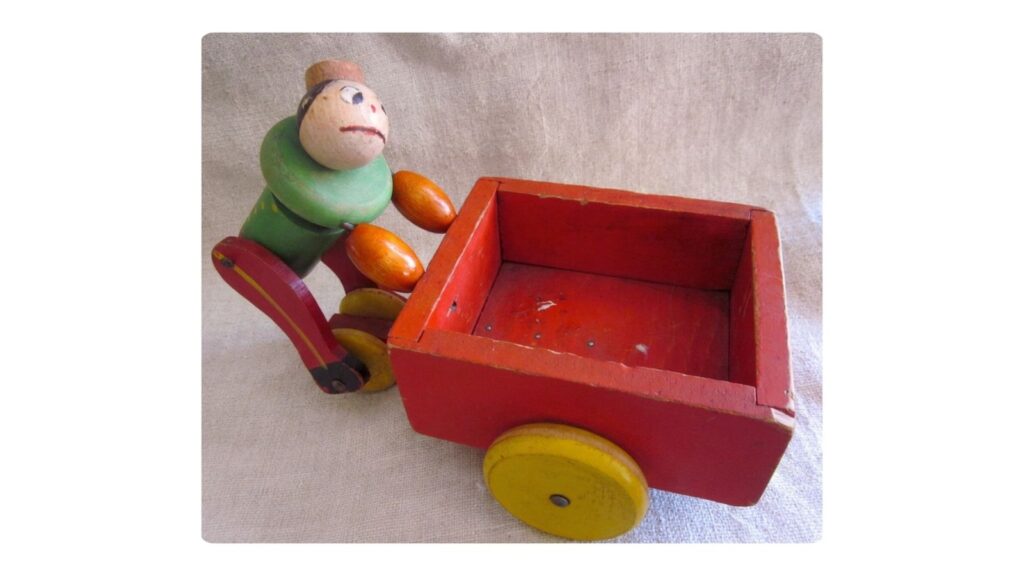
Pushcart Pete was one of Fisher-Price’s earliest toys, a wooden figure about nine inches long with a scowling painted face pushing a small red cart on yellow wheels and topped with a matching red hat. His head and body swivel on a pin joint as he moves forward, which is part of what made him charming enough for parents to buy in the 1930s and rare enough that almost none survived intact into the present.

A pristine, all-original example in excellent condition has reached as much as $9,200, though that figure reflects an exceptional early sale rather than a typical outcome. More realistically, clean examples with original paint and an intact cart bring $1,500 to $2,500 today. Because so few exist, reproductions and heavily restored examples are a real risk, so any wear pattern, paint texture, or joint construction that looks too fresh or too uniform is worth a second look before assuming you have an original. Confirming the swivel mechanism moves the way period examples describe is a good first check.

Fisher-Price Raggedy Ann and Andy pull toy (1941)

Fisher-Price Raggedy Ann and Andy pull toy
Image Credit: SomethingFromSandy via Etsy

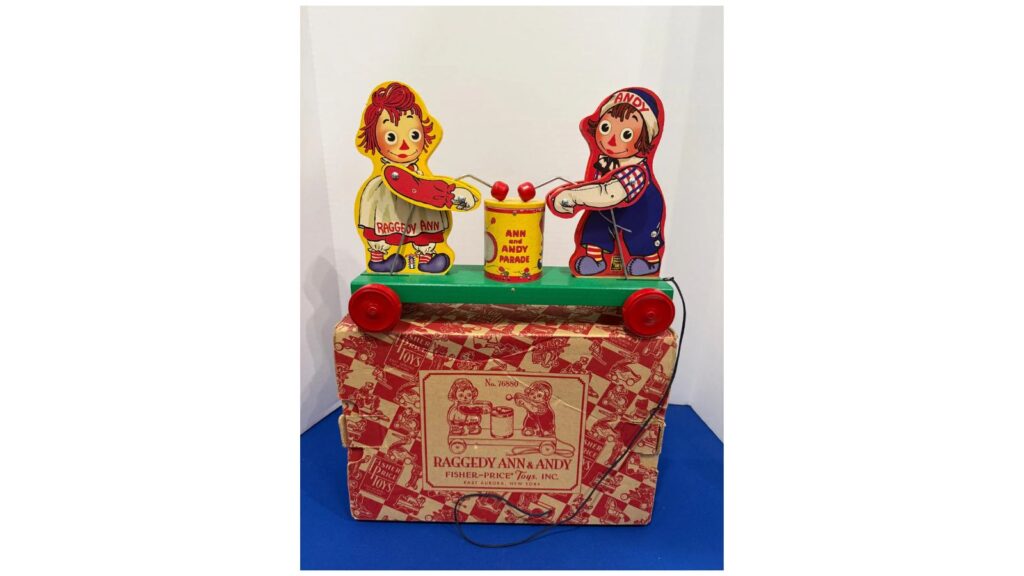
Fisher-Price made this one for a single year: two flat wooden figures of Raggedy Ann and Andy that beat a small drum with their mallets when the toy rolls forward, a mechanism the company reused across several of its character pull toys from this era. That one-year production window is what makes it scarce, regardless of which example you happen to find, since there simply wasn’t much time for the company to build up inventory before moving on to other licenses.

Complete, clean examples typically bring $2,500 to $3,000 today, with an especially strong early sale once reaching over $6,000. The completeness gap here is dramatic: an incomplete example missing Andy’s arms and the drum top still found a buyer, but for only a few hundred dollars. Check that both figures, both mallets, and the full drum assembly are present and that the mallets still strike the drumhead before getting excited about the higher end of that price range.

Fisher-Price Walt Disney’s Easter Parade pull toy (1936 to 1938)

Fisher Price Walt Disney Easter Parade pull toy
Image Credit: Vintage Disney Collectibles via Facebook

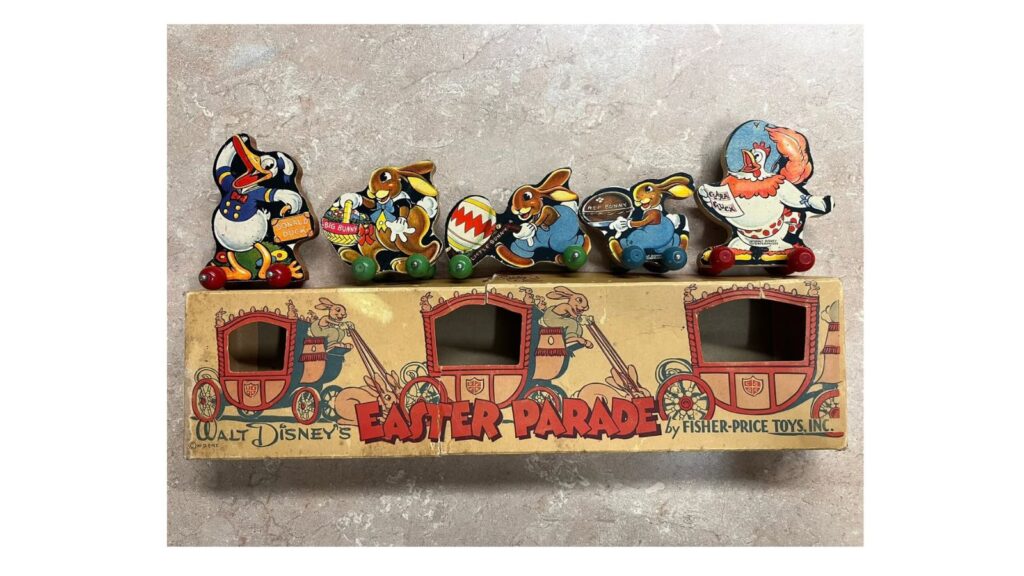
This toy features five separate wooden cutout figures, Donald Duck, Clara Duck, Big Bunny, Wee Bunny, and Little Bunny, each with paper lithograph detailing glued to a flat wooden silhouette and mounted on small wooden bead wheels that let the whole parade roll forward together. It’s one of the more elaborate Disney-licensed pull toys the company made in its earliest years, released during the same wave of Snow White and Mickey Mouse tie-ins that produced several of its most valuable pieces.

Clean examples with the original box typically bring $1,440 to $2,340, and standout examples have climbed considerably higher. The small bead wheels and delicate cutout figures were never built to survive rough handling, so a complete set of all five figures with no cracking, warping, or paint loss is genuinely uncommon. Missing even one figure meaningfully lowers what a buyer will pay, and a box adds a real premium on top of that.

Fisher-Price Doc and Dopey Dwarfs pull toy (1938)

Fisher-Price Doc and Dopey Dwarfs pull toy
Image Credit: bidwell39 via eBay

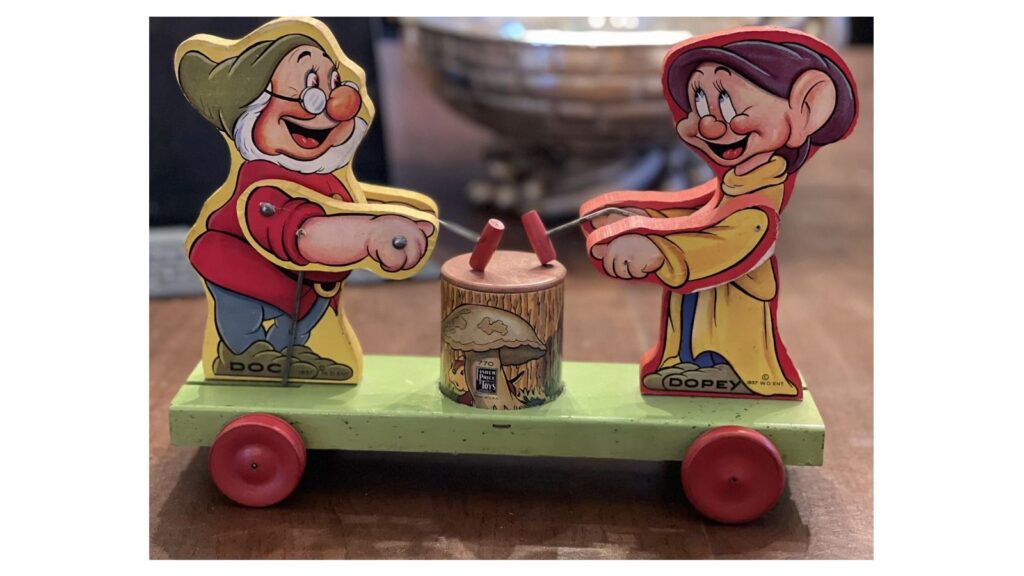
Released right after Snow White hit theaters, this pull toy features flat wooden cutout figures of Doc and Dopey that beat a small drum as it rolls, part of a wider run of Seven Dwarfs-themed toys Fisher-Price produced to capitalize on the film’s popularity. Disney-licensed toys from the company’s first decade sit at the top of most collectors’ lists, and this pairing is a good example of why that licensing era commands such a premium over the company’s unlicensed designs.

Clean, complete examples typically bring $1,200 to $2,000. As with the other Disney pull toys from this era, the paper lithograph work is what drives the price, since the printing detail on the dwarves’ faces and costumes is what collectors are really paying for. A played-with survivor with intact figures can still clear four figures, but cracking, water staining, or a broken drum top will cut that number substantially.

Fisher-Price Big Performing Circus wagon (1962 to 1969)

Big Performing Circus wagon
Image Credit: Hanatime via Etsy

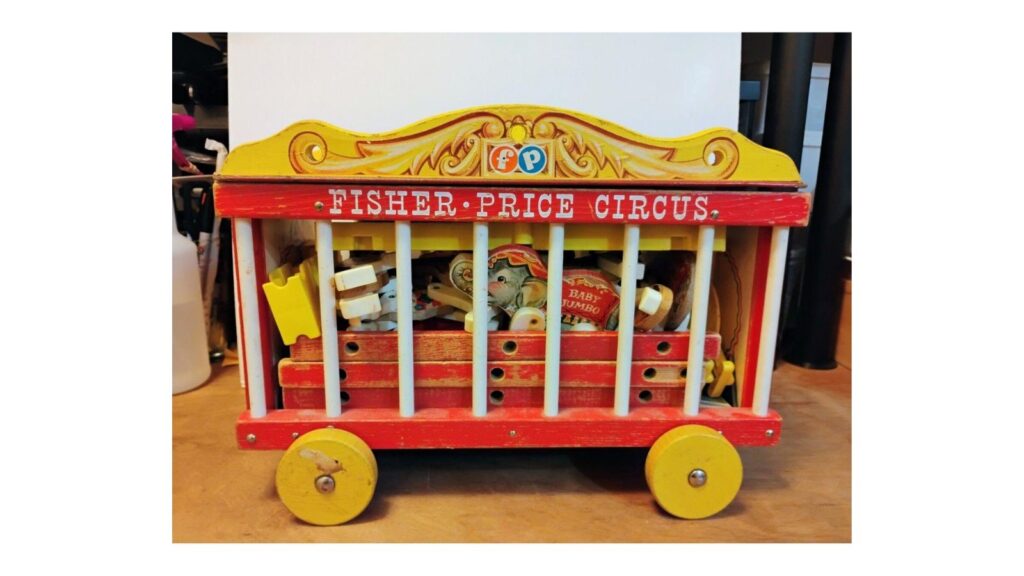
One of the most recognizable Fisher-Price pieces from the 1960s, this wagon came with eleven performer figures and twenty pieces of circus equipment, including ladders, a trapeze, ring sections, and a small ringmaster figure, all designed to be set up and torn down like a real traveling show. It’s a common enough sight loose at flea markets, but a genuinely complete example is a different story.

A bare wagon with a handful of pieces typically brings $50 to $150, while sealed, fully complete boxed examples have cleared as much as $800. The gap between those two numbers comes entirely down to whether every ladder, trapeze bar, and small prop survived four or five decades of play in the hands of a child. Count every piece against a checklist before assuming what you have is complete, since a wagon that looks full at a glance is often missing several of the smallest parts.

Fisher-Price Play Family Airport #996 (1972)

Vintage Fisher Price Play Family Airport
Image Credit: LilPeopleEastAurora via Etsy

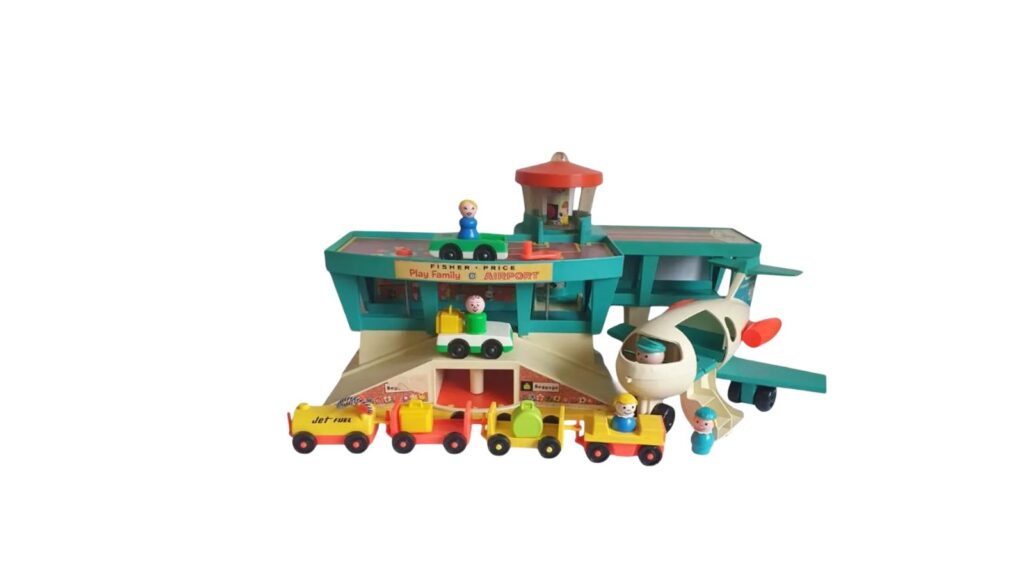
Widely considered one of the best-designed Little People playsets Fisher-Price ever made, the Airport has a swing-out runway and concourse, a control tower on top, a drive-up ramp for cars, and a revolving luggage conveyor that turns by hand crank alongside a helicopter with spinning blades and a rotating landing pad. It stayed in the lineup for years and went through several color and figure updates before being discontinued.

Complete examples with working mechanisms typically bring $200 to $400, and a factory-sealed example has reached as much as $1,000. The conveyor belt and crank mechanism are the first things to check, since they’re mechanical and prone to seizing up after decades in storage. Missing luggage carts, the helicopter itself, or any of the small passenger figures will drop the price noticeably even if the base structure still works fine.

Fisher-Price Play Family House #952 with the cardboard moving van (1969 to 1979)

Fisher Price Play Family House
Image Credit: GardenLuckyParadise via Etsy

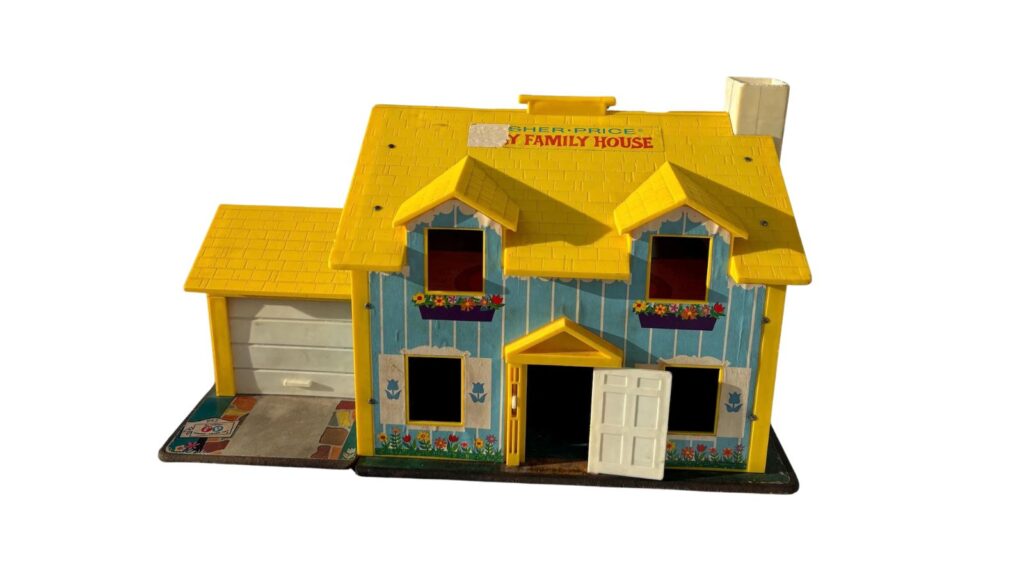
This yellow and blue two-story dollhouse, complete with a working doorbell and a roll-up garage door, is one of the most common Fisher-Price toys still floating around basements and attics, and the furniture colors were updated roughly every two years, so there’s no shortage of variations to sort through. On its own, a complete example with its original wooden and plastic Little People and furniture typically brings modest money, generally $20 to $150 depending on how much furniture and how many figures survived.

The real find here is a small, easily overlooked accessory: a cardboard moving van that shipped with the house for only its first year of production before being discontinued because it simply wasn’t durable enough to survive play. Surviving examples in decent shape have brought over $500 on their own, entirely separate from the house itself. Most people who own this house have never heard of the van, which is exactly why it’s worth digging through any box of loose accessories before donating them.

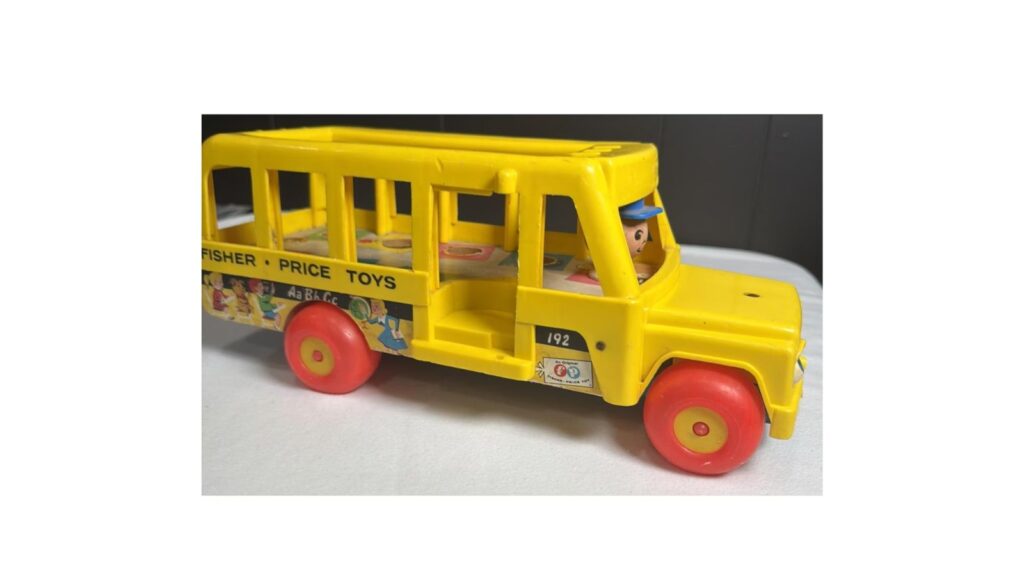
Fisher-Price Safety School Bus #983 (1959)

FisherPrice Safety School Bus 983
Image Credit: ItHasHope via Etsy

This plastic-bodied bus was the first Fisher-Price toy built with removable figures, a design choice that led directly to the entire Little People line the company still sells in a different form today. Six small wooden peg passengers can be lifted out through the clear plastic top, while the driver stays permanently fixed in place behind the wheel, and the bus features a rolling-eyes mechanism on the front grille that was a genuine novelty for the era.

Complete examples with all six original passengers and a functioning eye mechanism typically bring $165 to $700, with the wide range reflecting how much condition and completeness matter on a toy this old. A bus with a cracked windshield, a stuck eye mechanism, or missing passengers sits at the low end regardless of how charming it looks on a shelf, so functionality matters just as much as appearance here.

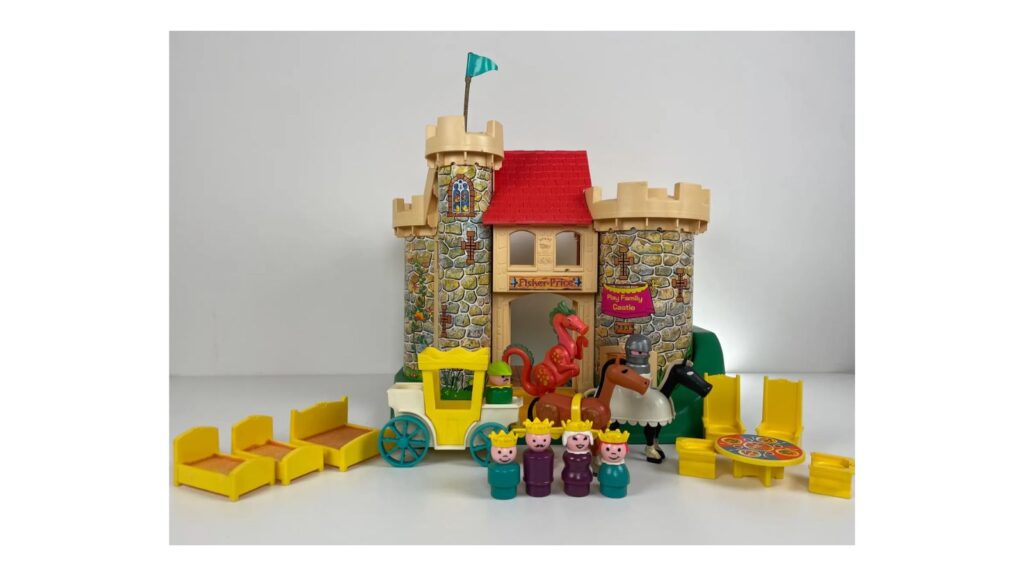
Fisher-Price Play Family Castle #993 (1974)

Fisher Price Play Family Castle 993
Image Credit: RosyTangerines via Etsy

This is one of the heaviest and most detailed Little People sets Fisher-Price ever produced, with a working drawbridge, sliding stairs, trap doors, a dungeon, a horse-drawn carriage, thrones, beds, and a pink dragon among its 21 pieces. It’s also a good example of a set from the transitional era when figures came with wooden bodies and plastic heads, except for the all-plastic knight, which makes the mixed figures themselves a useful dating clue.

A genuinely complete set typically brings $200 to $500, but that number falls off fast with any missing piece. A set missing just one horse, otherwise in nice shape, has sold for as little as $65. Beds usually need replacement foam by now, which buyers generally accept without much penalty, but a missing king, queen, knight, or dragon is a different kind of problem that hits the price much harder.

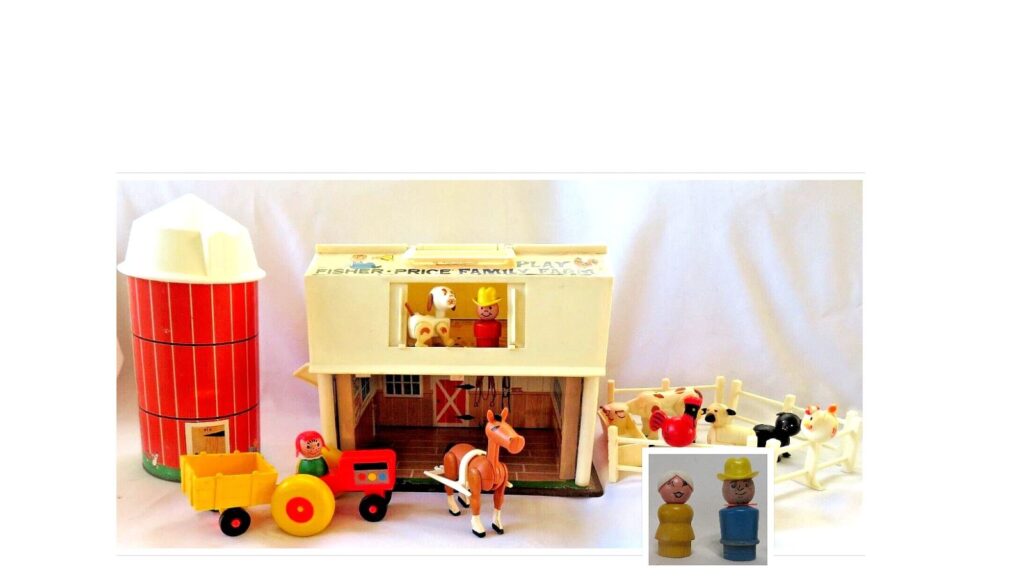
Fisher-Price Play Family Farm #915, wood-base version (1967 to 1968)

Fisher Price Play Family Farm 915
Image Credit: Second Childhood Dolls & Toys via eBay

The Play Family Farm is the toy that turned Little People into Fisher-Price’s flagship line, thanks largely to the satisfying “moo” sound when the barn door swings open and the fact that every piece packs away inside the barn itself for easy carrying. The earliest run, built on a solid wood base rather than the Masonite and later plastic construction that followed, carries the strongest premium among farm collectors today.

Complete sets with the full run of animals, the tractor, cart, silo, and fencing typically bring $100 to $600, with the wood-base 1967 to 1968 examples pushing toward the top of that range when everything is present. A loose barn with a couple of stray animals is worth much less, closer to $20 to $30, so it’s the full roster of small pieces, not the barn itself, that really determines where a given farm lands on that scale.

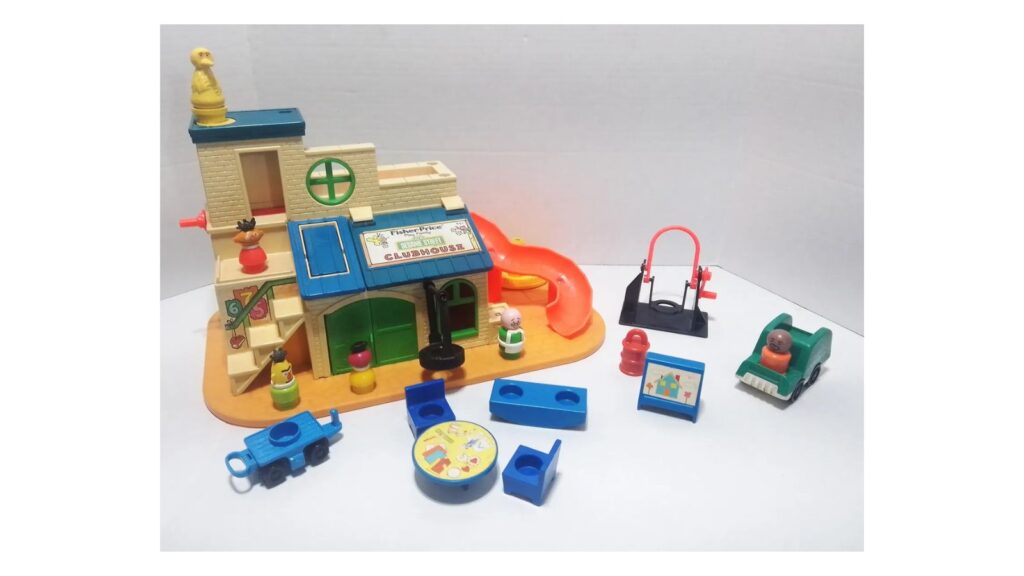
Fisher-Price Play Family Sesame Street Clubhouse #937 (1977 to 1979)

Fisher Price Play Family Sesame Street Clubhouse 937
Image Credit: TreasuresMemories via Etsy

This is a separate set from the more famous Sesame Street brownstone Fisher-Price released a couple of years earlier, and the two get confused constantly because they share a theme and a similar-looking box. The Clubhouse came with Big Bird, Grover, Bert, Ernie, and the Count, plus a slide, a wagon, ramps, and a small tire swing mounted on the front of the structure.

Complete examples typically bring $30 to $155. The Roosevelt Franklin figure is the detail that matters most here: he shipped with the set only briefly before being pulled from the Sesame Street lineup entirely, and a Clubhouse that still has him is genuinely uncommon today. The tire swing is also usually broken or missing altogether, and the paper lithograph tends to peel at the edges over time, so an intact example earns a real premium over the ones that turn up at most estate sales.

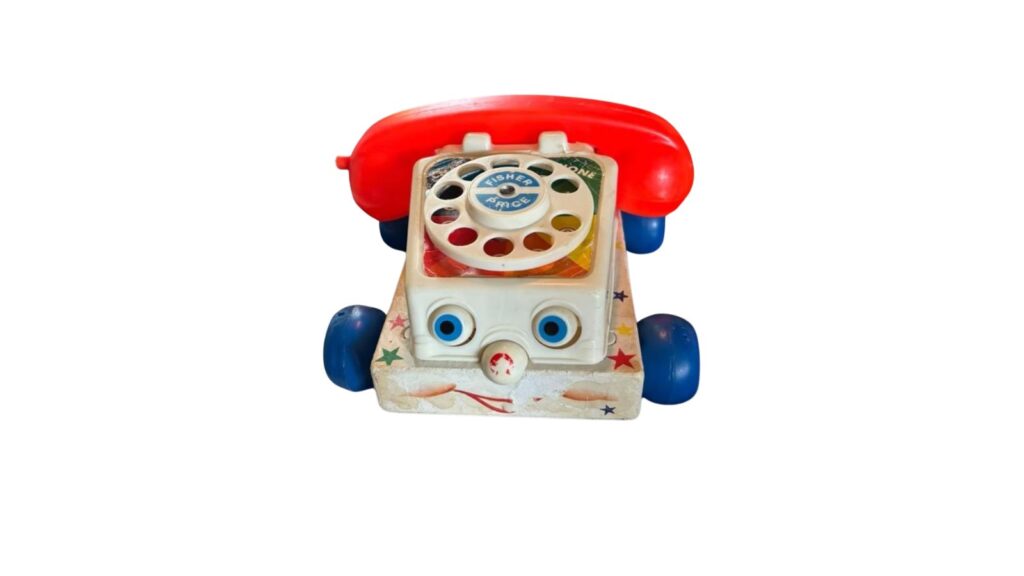
Fisher-Price Chatter Telephone #747, wood-base version (1961 to 1966)

Fisher Price Chatter Telephone 747
Image Credit: Louvintagecloset via Etsy

Most people recognize this toy from its cameo in the Toy Story movies, but the earliest version, with a solid wood base and a black and white twisted cotton pull cord, predates that fame by decades. Later versions through the 1970s and 1980s switched to plastic wheels and a plastic base, which is the easiest way to tell a scarce early example apart from the very common later ones still turning up in nearly every thrift store toy bin.

General examples across all production years bring anywhere from $15 to $150, but boxed examples specifically from the 1961 to 1966 wood-base run bring $80 to $150 on their own even without the box in some cases. Wooden wheels are the single clearest sign of a pre-1967 build worth a closer look. The rotary dial and the moving googly eyes both need to still function properly for a phone to bring anything near the top of that range.

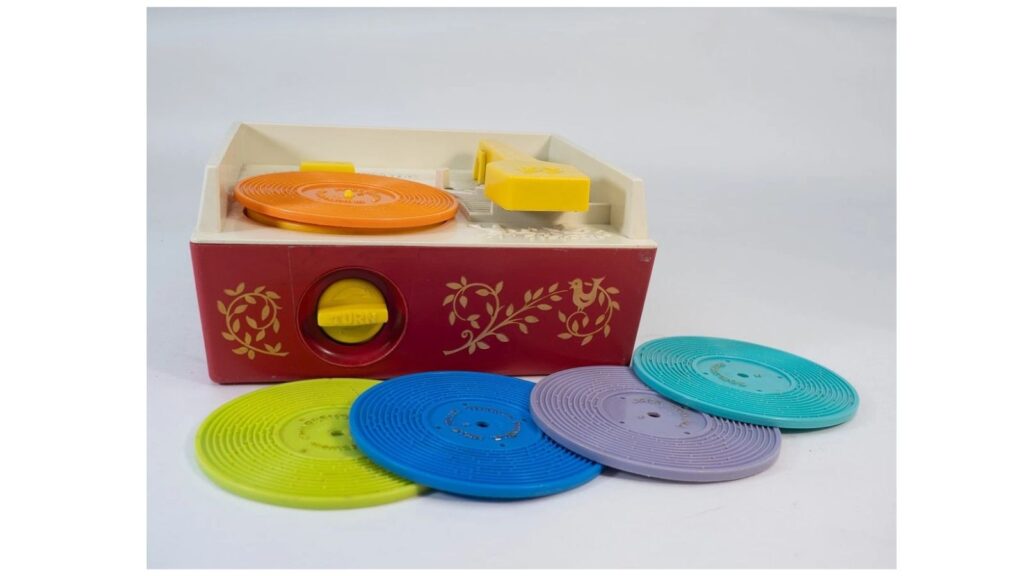
Fisher-Price Music Box Record Player (1971)

Fisher Price Music Box Record Player
Image Credit: St Davidʼs Hospice via eBay

This wind-up toy record player came with five double-sided plastic records that play ten different tunes when cranked, a design meant to mimic real record players kids saw their parents using at home. It’s a genuinely charming design and a common one, distinct from the separate Fisher-Price Phonograph the company introduced later in the decade, which keeps prices modest but still worth checking before it goes in a donation box.

Working examples with all five original records intact typically bring $30 to $150, with boxed sets landing at the higher end of that range. The wind-up spring is the mechanism most likely to have failed after fifty years of storage, and a broken or weak spring cuts the value by more than half even if the records themselves are all present and undamaged. Missing records hurt the price almost as much as a broken spring does.

Running a business alone alongside raising kids takes incredible resilience and strategic planning. Balancing client demands with parental duties requires systems that keep daily chaos under control.

Many women find that building a sustainable enterprise allows them to regain control over their schedules and financial future. With clear boundaries and practical habits, sole parent founders can thrive without burning out.

Discover practical business advice for single moms, from managing time and finances to balancing work and family responsibilities.
Image Credit: Matilda Wormwood via Pexels

Structuring your daily routine

A predictable daily flow forms the backbone of any home business operation. Setting firm work hours prevents client calls from spilling into dinner preparation or bedtime routines. Structured blocks of dedicated focus time keep projects moving forward consistently.

Maintaining precise records and following official guidelines remains a top priority when scaling up operations. Hiring a qualified company auditor in Sydney, for example, can help local business owners maintain compliance with complex financial reporting laws. Regular reviews of financial statements keep cash flow predictable and prevent costly legal mistakes.

Establishing clear routines gives children a sense of order and security throughout the week. Kids quickly learn when parent attention is focused on work tasks versus family activities. Simple visual schedules on the fridge help younger kids understand daily plans.

Streamlining business operations

Managing every operational task solo slows down long-term growth. Automating recurring invoices and client reminders frees up valuable hours every single week. Modern software tools handle routine administrative labor so founders can focus on revenue-generating work.

Utilizing modern digital platforms keeps daily administrative tasks organized and manageable. A published feature highlighted that time management resources help founders maintain weekly schedules divided between family, company duties, and personal care.

Streamlined workflows reduce stress when unexpected family emergencies pop up. Digital file storage allows work from anywhere when a child stays home sick from school. Standardized templates for client emails save precious energy during busy periods.

Managing cash flow and finances

Maintaining separate personal and business bank accounts protects company assets from accidental personal expenses. Clear accounting records make tax season far less stressful for busy mothers. Keeping 3 months of operating expenses in reserve guards against unexpected market drops.

Regular financial checks reveal unnecessary subscription costs that bleed company profits each month. Setting aside funds for tax obligations every month prevents emergency cash crunches later. Clear pricing models reflect true labor costs rather than discounted rates.

Smart financial planning relies on simple rules that keep cash flowing smoothly. Implementing basic financial habits prevents money problems before they start:

  • Track incoming invoices daily to spot delayed payments fast.
  • Reserve $500 monthly for unexpected equipment repairs or tech upgrades.
  • Review profit margins quarterly to adjust service rates when needed.

Balancing family needs with professional goals

Finding balance between household duties and career ambitions remains a primary driver for many parent entrepreneurs. An industry report noted that building a rewarding career alongside maintaining quality family life represents a major goal for women. 

Involving kids in simple, age-appropriate business tasks creates fun learning experiences. Older children can help pack product shipments or organize inventory shelves on weekends. Small paid chores teach valuable money management lessons early in life.

Setting clear expectations with clients prevents unrealistic communication demands during family hours. Automatic email autoresponders state standard response times so clients know when to expect answers.

Building a reliable support system

Working in isolation often leads to creative fatigue and emotional exhaustion. Connecting with local business groups creates valuable networking opportunities and shared problem-solving space. Other parent founders offer realistic advice derived from shared personal experiences.

Trades with other sole parents create low-cost solutions for childcare and errands. Swapping afternoon school pickups with another parent buys dedicated quiet work blocks. Shared community networks provide reliable backup options during heavy work deadlines.

Professional mentors guide founders through difficult scaling decisions without costly trial and error. Regular check-ins with experienced peers keep goals clear and realistic. 

Prioritizing personal well-being

Self-care forms the foundation of sustainable business leadership for sole parents. Neglecting personal physical health leads to severe fatigue and decreased productivity. Short daily walks or brief quiet breaks recharge mental energy for tough tasks ahead.

Protecting personal downtime requires turning off work notifications after business hours. Stepping away from digital screens lets the mind rest and recover from daily decision fatigue. Resting without guilt strengthens mental resilience for home and work duties.

Celebrating small business milestones boosts morale and keeps passion alive. Small victories deserve recognition, whether winning a new client or completing a major project on time.

Image Credit: Vitaly Gariev via Pexels

Building a successful company with children single-handedly requires patience, discipline, and practical strategies. Organizing daily routines, automating administration, and securing professional guidance keep growth steady. Every positive step forward creates lasting stability for your family.

Sole parent founders possess unique strength, adaptability, and determination. Implementing smart operational systems protects business profits and quality family time. Courage and consistency pave the way toward long-term success.