scroll top

You’re 57. The severance ran out months ago, LinkedIn has gone quiet, and the last recruiter who called wanted someone with “energy” for two-thirds of your old salary. Getting rehired after 50 is a rigged game right now. Building your own income on your own schedule is a completely different fight, and it’s one where four or five decades of living stop being a liability and start being the entire selling point.

Seven percent of retirees went back to work in just the past six months, and most of them said the real reason was money, not boredom. That’s not a failure of planning. That’s the cost of everything rising faster than paychecks did, and it’s pushing a lot of capable people back into the workforce on their own terms instead of someone else’s.

Most “side hustles for retirees” lists recycle the same five ideas: start a blog, do virtual assistant work, freelance write, tutor algebra, keep the books for a small business. Half of those jobs are already being quietly handled by the same software writing those lists. Nothing below works that way. Every one of these needs a real person in the room, a driver’s license, a steady pair of hands, or the kind of judgment that only comes from actually living a long time.

Start with the one that pays best per hour of actual work: sitting at a kitchen table while a stranger signs the biggest paperwork of their life.

Notary loan signing agent

Hands pressing a wooden-handled stamp onto a legal document on a desk
Image Credit: Shutterstock

Every mortgage closing, refinance, and home equity loan needs a licensed person in the room to witness the signature and stamp the paperwork, and that person doesn’t need a law degree. A certified loan signing agent typically earns $75 to $200 per appointment, and someone booking five to eight signings a month can pull in several hundred dollars without touching a laptop after 5pm.

A state notary commission usually costs under $150 and a weekend of study. Loan signing certification adds another short course and a background check, both of which title companies expect before handing you paperwork worth someone’s house. Mortgage volume rises and falls with interest rates, but purchases, refinances, and reverse mortgages never fully stop, so the work exists in some form no matter what happens next with rates.

This job rewards exactly what younger workers often lack: patience with paperwork, a calm bedside manner with a nervous first-time buyer, and a schedule flexible enough to drive across town at 4pm on a Tuesday. Title companies also tend to trust an agent who looks like someone’s parent more than one who looks like their teenager, which isn’t fair, but it’s real.

Senior move manager
Older woman and younger woman reviewing a framed photograph among packed moving boxes
Image Credit: Shutterstock

By 2030, one in five Americans will be of retirement age, and most of them are sitting in houses stuffed with fifty years of furniture, holiday dishes, and photo albums nobody else wants. A senior move manager gets paid to walk into that chaos and make the move to a smaller home, or into assisted living, actually happen: sorting belongings, coordinating movers, arranging what’s left behind, and unpacking the new place before anyone arrives.

The certifying body, NASMM, doesn’t require a specific professional background, and most people entering the field come from corporate careers, healthcare, or small business rather than moving trucks. That’s the point. Families hire a move manager for judgment and calm under pressure, not muscle, and they’ll often pay a premium for someone who has personally packed up a parent’s house and knows how heavy that day feels.

Every client’s grief, guilt, and family politics look different, and untangling which sibling gets grandma’s china while the moving truck idles outside takes a kind of steadiness that comes from having lived a while. It’s recession-resistant work too, because people don’t stop aging or downsizing just because the economy wobbles.

Estate sale and cleanout specialist
Man and woman sorting boxes and household belongings in a cluttered garage for a sale
Image Credit: Shutterstock

When a family needs to empty a house fast, whether after a death, a move, or a foreclosure deadline, they usually hire an estate sale company rather than doing it themselves. The average estate sale grosses $18,000 to $20,000, with companies typically keeping 35% to 40% as commission, which means a single well-run weekend can be worth several thousand dollars to whoever’s running it.

Most people break in by working weekends for an existing estate sale company first, learning how to price a set of grandma’s stemware or grandpa’s tool collection without guessing wildly in either direction. Pricing is the actual skill: knowing that a set of 1970s Fostoria glassware sells for real money on the right platform while last year’s Bath and Body Works candles sell for nothing at all.

Shoppers walking through a sale trust someone who clearly knows their Depression glass from their Corelle more than they trust a 24-year-old scrolling behind the register. Decades of accumulated knowledge about furniture, china patterns, tools, and collectibles is the entire product here, and it only builds with time.

Companion care for older adults
Support worker and older woman laughing together while holding mugs of tea on a living-room sofa
Image Credit: Shutterstock

An 84-year-old who can no longer drive, cook safely, or keep track of her own pills doesn’t need a nurse. She needs steady, patient help a few hours a day, and employment in this field is projected to grow 17% between 2024 and 2034, with median pay at $34,900 a year. Working privately for one or two families directly, instead of through an agency, usually pays better per hour since nobody’s skimming a cut in the middle.

The work is mostly non-medical: bathing, meal prep, medication reminders, rides to appointments, and simple company that keeps someone from spending eight hours a day alone. Families hiring privately often specifically want someone closer to their parent’s own age and life stage rather than a 19-year-old CNA student working her way through nursing school.

No medical license is required for non-medical companion care, though some states require a background check and a short course before you can join a local registry. Word of mouth through churches, senior centers, and local Facebook groups fills these positions faster than any job board does, because trust matters more here than a resume.

Non-emergency medical transportation driver
Woman assisting a wheelchair user up a portable vehicle ramp outdoors
Image Credit: Shutterstock

A dialysis patient needs a ride to treatment three times a week for the rest of her life, whether or not she can still drive herself there. The non-emergency medical transportation market is valued at $11.6 billion in 2026 and projected to reach $25.8 billion by 2034, built almost entirely on trips like hers.

Getting into the field usually means driving for a regional company that already holds the insurance and Medicaid contracts, or, with more capital and a wheelchair-accessible van, bidding for those contracts yourself. A clean driving record, a defensive driving course, and patience with frail or anxious passengers matter more here than speed or a shiny vehicle.

This work rewards a driver who won’t rush an elderly passenger getting into the car, who remembers which patient needs help with a walker, and who treats a dialysis run three times a week as a relationship rather than a transaction. Younger gig drivers chasing surge pricing on rideshare apps tend to burn out fast on this kind of unhurried, low-tip work. People who’ve raised kids or cared for aging parents themselves usually don’t.

Handyman and small repair work
Plumber using a hand tool to repair pipes beneath a kitchen sink beside an open toolbox
Image Credit: Shutterstock

Most homes eventually need small repairs like a wobbly deck rail or a faucet that won’t stop dripping, and self-employed handymen typically charge $50 to $80 an hour, with corporate or franchise rates running $75 to $125. None of that requires a general contractor’s license in most states, just tools, insurance, and the ability to actually finish what you start.

The best clients for this work are often other people over 50: homeowners who want a job done right the first time by someone who shows up when promised, doesn’t try to upsell a full renovation, and explains what’s wrong in plain English instead of contractor jargon. A lot of handyman businesses build their entire client list from neighbors and referrals within a five-mile radius.

This field really is wide open. Fewer young people are entering the skilled trades every year, and the demand for basic home repair hasn’t slowed to match. A retired electrician, plumber, or tradesperson can often go from full-time employee to part-time handyman and earn nearly as much working a third of the hours, simply by cutting out a company’s overhead.

Personal chef and in-home meal prep
Private chef wearing gloves while preparing sushi at a home kitchen island
Image Credit: Shutterstock

Cooking dinner every night loses its charm somewhere around year thirty, especially for people managing a health condition or cooking for one for the first time. Personal chefs typically charge $50 to $100 an hour, with a weekly meal-prep visit running $150 to $400 once groceries are included.

This job runs on repeat business rather than one-off gigs. A chef who lands three or four regular weekly clients, each paying for a few hours of cooking and a stocked fridge, can build stable, predictable income without ever working in a restaurant again. Marketing is mostly word of mouth through local Facebook groups, Nextdoor, and referrals from a client’s friends.

Decades of home cooking translate directly into this work in a way culinary school doesn’t always match. Clients managing diabetes, heart disease, or a spouse’s dietary restrictions often want someone who understands real family cooking and real limits, not someone plating foam garnishes for Instagram.

Wedding officiant
Woman in a white suit reading from a folder and speaking into a microphone beside an outdoor wedding arch
Image Credit: Shutterstock

The average couple pays $240 for a wedding officiant, and more than two million couples marry in the U.S. every year, so the market never really closes. Officiants who write a ceremony that actually sounds like the couple, instead of reading a generic script off a phone, can charge toward the top of that range and stay booked most weekends from spring through fall.

Two-thirds of couples now ask a friend to officiate rather than hiring anyone, which sounds like bad news for this business until you talk to the friends who’ve done it. Standing in front of two hundred people, keeping the ceremony moving, and not fumbling the legal paperwork afterward is harder than it looks, and plenty of couples would rather pay a calm, experienced professional than gamble on Uncle Dave.

Getting ordained online takes about ten minutes and often costs nothing, though most states also require registering with the county to make the marriage legally valid, so check local rules before the first booking. A warm, unhurried presence in front of a nervous couple and their families is the entire skill set, and decades of life experience build that far better than a script does.

Mobile car detailing
Small brush cleaning dust from a car dashboard air vent
Image Credit: Shutterstock

A car sitting in a driveway all week doesn’t clean itself, and plenty of owners would rather pay someone to show up with a bucket and a shop vac than lose their Saturday to it. Solo mobile detailers routinely report 60% to 80% gross profit margins, with startup costs as low as $500 to $1,500 since there’s no shop rent to carry.

Most of the work comes to the client’s driveway or office parking lot rather than the other way around, which suits anyone who’d rather not stand in a shop all day. Regulars who book a monthly wash and wax for two or three vehicles provide the steady income, while one-off deep details and ceramic coating jobs bring in the bigger checks.

This work rewards someone who is actually careful with an expensive car and communicates clearly with an anxious owner handing over their keys, both of which come more naturally after decades of owning cars yourself. It’s physical, more knee and back strain than heavy lifting, so it suits someone active who’s simply done with 5am warehouse shifts.

Local tour guide
Tour guide speaking into a microphone and pointing out a city landmark to a small group of visitors
Image Credit: Shutterstock

A lifetime of living in one place is worth more to a curious traveler than any guidebook. Airbnb Experiences has grown to more than 40,000 activities across over 1,000 cities worldwide, and local guides set their own price and keep most of what guests pay. Guides on peer-to-peer tour platforms can earn around $50 an hour leading small groups through the parts of a hometown a guidebook never mentions.

This works especially well for a specific, slightly obsessive kind of local knowledge: the history of a neighborhood’s old speakeasies, a self-taught expertise in a city’s Gilded Age mansions, or forty years of knowing exactly which diner serves the best pie after the football game. Tourists pay for a story, not a script, and a specific angle beats a generic walking tour every time.

A smartphone, comfortable shoes, and the liability coverage most platforms include are usually the entire startup cost. The best reviews go to guides who are natural talkers and truly enjoy strangers, which describes a lot of retirees who spent a career listening to other people’s problems and are finally ready to talk about something they love instead.

Vintage and antique picker
Woman examining a white serving dish among secondhand household items in a thrift shop
Image Credit: Shutterstock

A five-dollar flea market find is worth exactly nothing until someone who knows what they’re looking at spots it. The global secondhand market is projected to reach $393 billion by 2030, with the U.S. market growing about four times faster than the broader retail clothing industry, and that boom covers far more than clothing. Vintage furniture, old tools, sterling silver, coins, and mid-century glassware are all part of the same wave.

A picker’s whole job is knowing what a small find is actually worth to a specific buyer online, and that knowledge takes years to build. Decades spent noticing furniture styles, silver marks, and old toolmakers’ names translate directly into an edge here that a 25-year-old reseller chasing Instagram trends hasn’t had time to develop yet.

This can run as a low-stakes weekend hobby, hitting estate sales and thrift stores before reselling finds on Facebook Marketplace or eBay, or scale into a real business sourcing inventory for other dealers. Either way, the startup cost sits close to zero, and the only real investment is time spent learning what actually sells.

Substitute teaching
Mature teacher sitting with three students around a classroom table during a lesson
Image Credit: Shutterstock

Schools across the country can’t find enough adults willing to walk into a classroom on short notice, and they’re paying more to fix it. Long Beach Unified raised its daily substitute rate from $165 to $190 specifically because it couldn’t fill classrooms otherwise, a pattern repeating in districts nationwide, and the national median annual wage sits around $37,000.

Most states only require a high school diploma or a short certification course, not a full teaching degree, and the schedule is naturally part-time: you work the days you choose to accept, with summers and most holidays already off. Districts specifically like substitutes with real-world work experience, since managing a room of teenagers is closer to running a warehouse floor than babysitting.

This suits someone who wants steady daytime hours without a year-round commitment, and it pairs easily with a second income source since most districts let you accept or decline each assignment. A retired professional walking in with actual career experience to share often earns more respect from students than someone straight out of college.

Vacation rental co-host
Hand retrieving an electronic key fob from an open wall-mounted rental lockbox
Image Credit: Shutterstock

A vacation rental owner who lives three states away can’t personally hand a guest their keys at midnight. Co-hosting agreements typically pay 10% to 30% of a listing’s revenue on top of what the platform itself charges, and demand for local help keeps climbing alongside the platforms.

The job is part hospitality, part project management: coordinating a reliable cleaner, handling the guest who can’t find the wifi password, and knowing when a maintenance issue needs a same-day fix versus a scheduled repair. None of that requires owning property yourself, just a phone that’s always on and a network of local contractors who actually show up.

Retirees who already know their town well, including which plumber shows up and which cleaning service cuts corners, have a real advantage managing rentals for absentee owners who don’t. Someone managing four or five properties at 15% of revenue each can build a solid income without ever buying real estate.

Pet sitting and dog walking
Dog walker holding leashes and waste-bag dispensers while walking five dogs along a city pavement
Image Credit: Shutterstock

Fewer people have a retired parent or a stay-at-home neighbor nearby anymore to ask for a dog-sitting favor, so they pay a stranger instead. Overnight pet sitting through platforms like Rover typically pays $35 to $75 a night, with 30-minute walks running $15 to $25, and someone juggling five or six regular clients can turn that into steady weekly income.

Building a client base usually starts on an app, but the real money comes from graduating those first clients into direct, ongoing arrangements once trust is established, cutting out the platform’s cut. A dog owner who trusts a specific sitter tends to keep booking the same person for years, especially once that sitter has proven she’ll actually follow the feeding instructions.

This work rewards someone calm and reliable who doesn’t need reminding twice about a medication schedule, qualities plenty of pet owners associate more readily with an older, steady sitter than a college student between exams. It’s physical, outdoor work that suits someone who wants to stay moving without a gym membership.

Paid house sitting for absent owners
Woman in gardening gloves misting potted plants with a spray bottle inside a home
Image Credit: Shutterstock

A snowbird who leaves a Florida condo empty from May through October needs more than a neighbor who occasionally checks the mail. Paid house sitting typically runs $50 to $100 a day, or $100 to $150 for an overnight stay, and the market for it is quietly large: absentee owners, families on extended travel, and seasonal residents all need someone trustworthy running the water, collecting packages, and keeping the house looking lived in.

This is a different arrangement than the free home-swap sites built for travelers, where a sitter stays for free in exchange for watching the place. This is paid work, arranged directly with a homeowner or through a local property manager, and it depends entirely on being the kind of person a stranger will hand house keys to without hesitation.

A retiree with solid references, a clean background check, and the flexibility to stay somewhere for a week or two fits this work naturally, especially in areas with a large seasonal population. Word of mouth through a homeowners’ association or a property manager who needs a rotating list of sitters tends to fill these jobs faster than any app does.

Private music or craft lessons
Music teacher playing an acoustic guitar beside a child practicing a ukulele during a lesson
Image Credit: Shutterstock

A kid learning piano and a 60-year-old finally learning guitar for herself both need the same thing: someone patient who actually plays. Self-enrichment teachers earn a median of $21.79 an hour nationally, and private lessons taught from a home studio typically charge more than that once a teacher builds a reputation.

Piano, guitar, and voice remain the most requested lessons, but knitting, woodworking, watercolor painting, and even ham radio all have a small, steady market of adult students willing to pay for real instruction. Decades of playing an instrument or working a craft translate directly into teaching credibility that a diploma doesn’t.

This scales naturally: start with one or two students a week in a spare room, and grow into a full afternoon and evening schedule once word spreads through local parent groups and community centers. It also requires no commute if lessons happen at home, and no competition from AI, since nobody’s toddler is learning piano technique from a chatbot.

Renting out an RV or camper
Motorhome with an open storage compartment, buckets, baskets and cleaning supplies arranged outside
Image Credit: Shutterstock

Most RVs sit parked in a driveway for the majority of the year, quietly losing value while their owners still pay for storage and insurance anyway. RV owners renting through peer-to-peer platforms can earn up to $30,000 a year or more, with larger Class A motorhomes sometimes topping $60,000, turning a depreciating asset into one that actually pays them back.

The rental platform usually handles insurance, payment processing, and roadside assistance for renters, which removes most of the risk that used to make owners nervous about handing over the keys to a stranger. Owners set their own calendar and price, and can block off the exact weeks they want the camper for their own trip.

This suits an over-50 crowd almost perfectly, since RV ownership itself skews older, and a retired couple already comfortable maintaining their own rig has a natural advantage over a first-time shopper trying to learn gray water tanks from a video. It’s close to passive income once the listing and cleaning routine are set up, with none of the driving a rideshare gig demands.

Certified peer recovery support specialist
Woman facilitating a seated group discussion while participants listen with notebooks
Image Credit: Shutterstock

Someone who has actually been through addiction or a mental health crisis and come out stable on the other side has a kind of authority no textbook can replace. The number of certified peer support specialists nationally has grown from about 30,000 to 82,000 over the past decade, and almost every state now runs its own certification program that turns that lived experience into a paid, credentialed job.

Certification typically requires 40 to 60 hours of training plus supervised experience, far less than the years it takes to become a licensed counselor, and demand keeps outpacing supply as more states require insurers to cover the service. The work exists in hospitals, outpatient clinics, community organizations, and increasingly, private practice.

Someone who has personally faced addiction, grief, or a mental health crisis and rebuilt a stable life has a credibility here that no amount of classroom study can substitute for, and that credibility only deepens with age and years of stability. It’s meaningful, steady work for anyone who wants their hardest years to finally count for something.
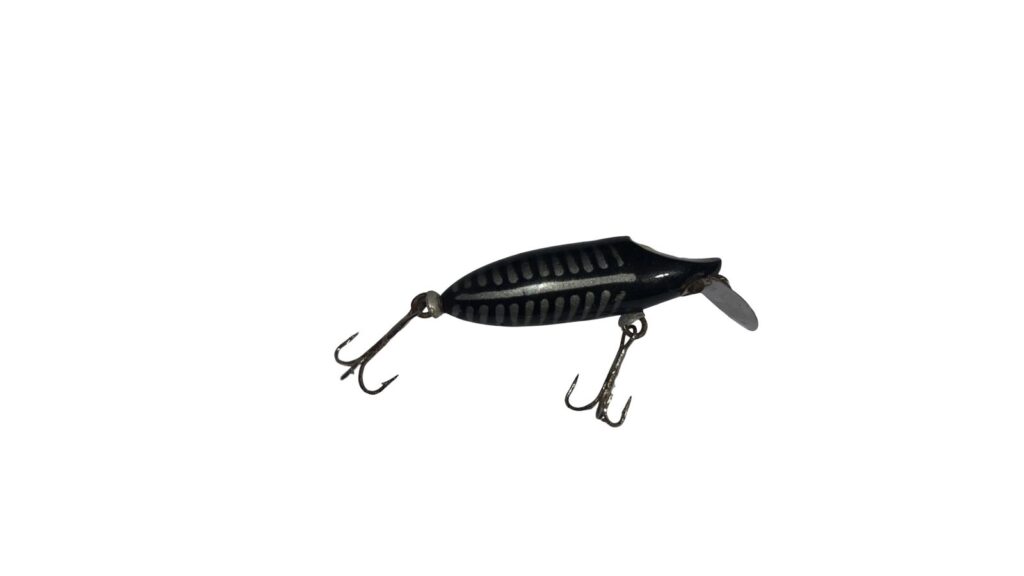
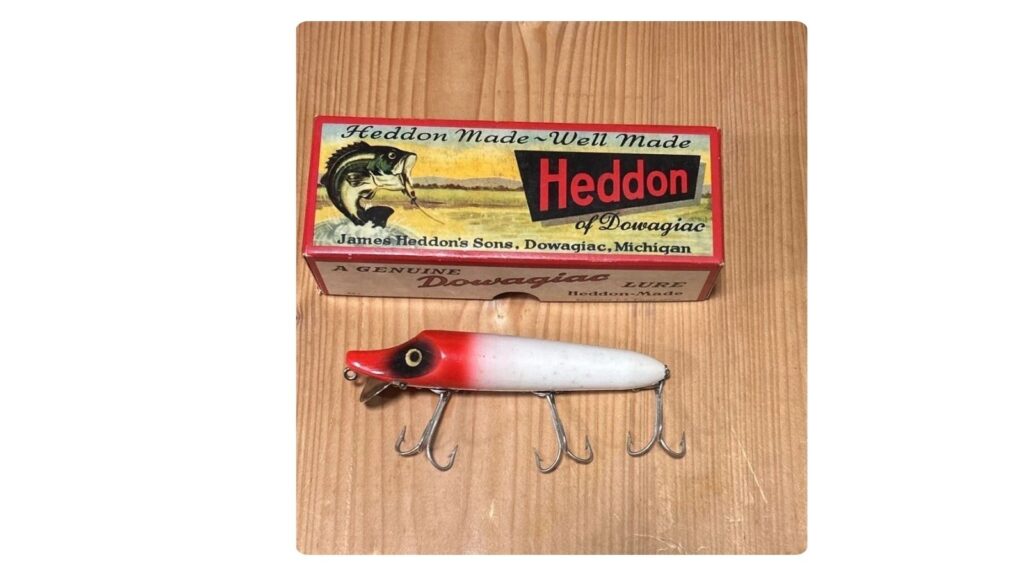
Your dad’s old tackle box has been sitting in the garage since he stopped fishing, full of rusty hooks, tangled line, and a few dozen wooden lures with chipped paint. Before any of it goes in the trash or off to a church sale, dump it out and look closely. Some of those battered old baits are worth more than the rod you’d use to cast them.

American lure collecting is a real market with real money behind it, built mostly around a handful of companies working out of small Midwest towns from roughly 1900 through the 1950s. Heddon of Dowagiac, Michigan sits at the center of it, but Creek Chub, South Bend, Pflueger, Shakespeare, and a string of smaller makers all have serious followings of their own. What separates a junk-drawer bait from a genuine find comes down to maker, model, color, and condition, in that order, and condition usually decides the final number.

The biggest trap in this hobby isn’t fakes, it’s repaints. A worn lure touched up to look mint is common enough that collectors check every example under strong light before they trust the paint.

1. Heddon River Runt Spook

Heddon River Runt Spook
Image Credit: papet_4905 via eBay

Heddon’s River Runt line goes back to 1929, with the plastic “Spook” versions following a few years later, and the company kept making them into the 1980s. That kind of volume, across dozens of colors and body styles, is exactly why most examples you’ll find are not worth much. Common finishes like perch scale or shore minnow in honest, used condition typically bring $5 to $20, which still beats the dollar or so Heddon charged for one new.

The scarcer colors are where it gets interesting. Luminous “Glow Worm” examples are hard to find in good shape because the heavy glow paint tends to bubble and flake with age, and finishes made for only a year or two, or weedless rigs like the No-Snag model, show up far less often at estate sales. Clean examples in those colors climb well past $200.

Check the eye style and line-tie hardware before getting excited. Earlier River Runts have a down-turned eye with a gold iris, and later ones switched to white. Mismatched hardware or an eye that’s clearly been swapped knocks the price down fast, and a glossy repaint erases the fine scale detail that made the original finish worth having.

2. Heddon Vamp

Heddon Vamp
Image Credit: Relite-Trust-Japan Store via eBay

The Vamp is Heddon’s long, slim wood minnow, built with glass eyes and aimed at pike and bass, and it came in a long list of factory colors. Which color you’ve got matters more than almost anything else about the lure. A Vamp in the Allen Stripey finish, a pale scale pattern with a red head and stripe, typically brings around $550 in good, boxed condition, and the oversized Musky and Giant Vamp models built for bigger water go for more still.

Common colors in used condition are a fraction of that, often $20 to $75, so don’t get your hopes up over every Vamp that turns up. What separates the two is mostly paint and eyes: glass eyes that are intact and original, paint with real age rather than a slick repaint, and hardware that matches the lure’s era.

A matching, correctly labeled box roughly doubles what the lure alone brings, and even an empty original Heddon lure box is collectible on its own. Watch for replaced glass eyes especially. They’re a common, often hard-to-spot repair unless you know exactly what the originals look like up close, and they quietly cut the value even when the rest of the lure looks right.

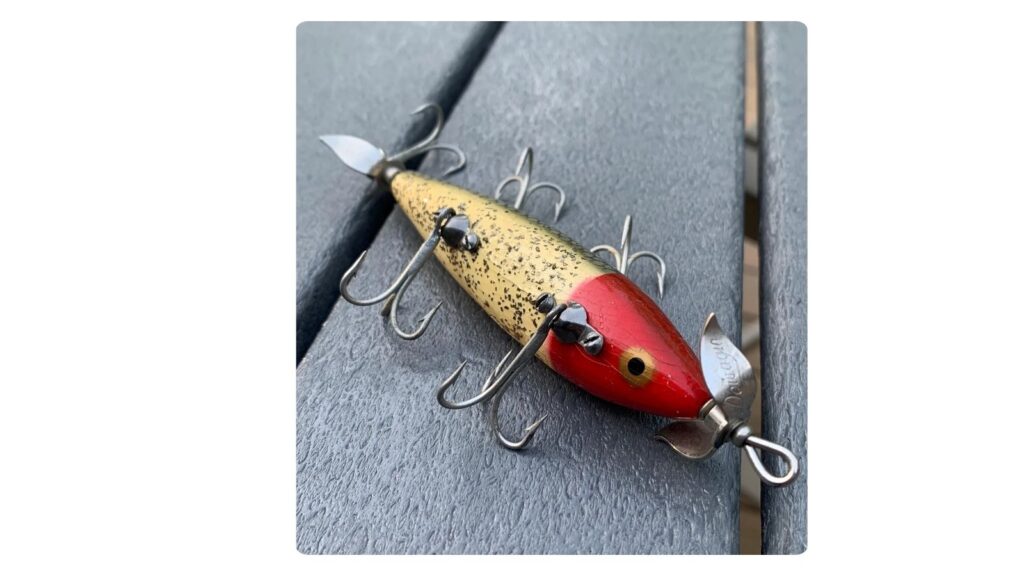
3. Heddon 150 Underwater Minnow

Heddon 150 Underwater Minnow
Image Credit: GulfCoastFieldFinds via Etsy

Before Heddon settled into the simpler lineup most collectors know, its earliest wood minnows carried model numbers like 150, part of the original Dowagiac Minnow family dating to the early 1900s. These are the lures that built the company’s reputation: multi-hook wood bodies with propeller blades front and back, glass eyes, and hand-finished paint that varied by color code.

A boxed 150 in perch scale, one of the more desirable and recognizable finishes, typically brings $700 to $1,000 in clean condition with its correct box. Loose examples with no box bring meaningfully less, often half that or under, and worn paint or a replaced propeller cuts further still.

This isn’t a lure most people stumble across loose in a kitchen drawer. It belongs more to a great-grandfather’s tackle collection than a modern garage, which is exactly why it’s worth knowing what to look for if an old wooden tackle box turns up in an inherited estate. Check the propeller blades for matching wear and era-correct styling, and look on the belly for the stamped model number that confirms what you actually have.

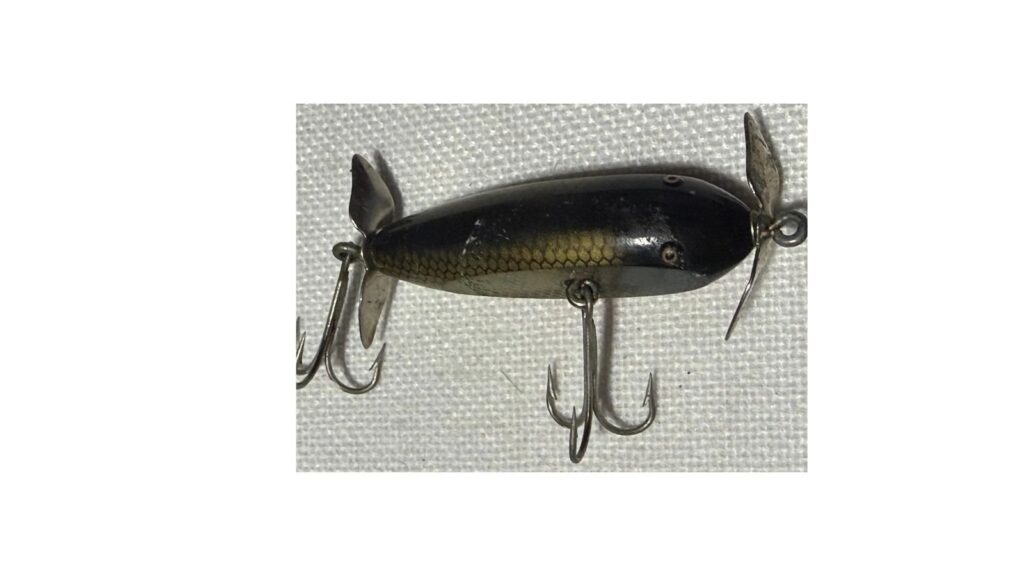
4. Creek Chub Injured Minnow

Creek Chub Injured Minnow
Image Credit: RMECollectibles via Etsy

Creek Chub Bait Company started in Garrett, Indiana in 1906, and the Injured Minnow was one of its earliest standout designs, a wood bait built to wobble like a dying baitfish. Early examples have glass eyes and a lifelike, scaled paint job that was genuinely advanced for the era.

A well-preserved Injured Minnow with its original box typically sells for over $600. Loose, used examples without a box are far more common and far cheaper, often in the $30 to $100 range depending on paint and hardware condition, since this was a working bait that plenty of anglers actually fished rather than put on a shelf.

Glass eyes are the first thing to check. Replaced or modern eyes are common on lures this age and bring the price down even when the body and paint still look sharp. After that, look closely at the belly stamp and hook hardware for signs of mismatched repairs, since a lure assembled from parts of two different Injured Minnows is worth considerably less than a fully original example, however good it looks from a distance.

5. Creek Chub Baby Pikie

Creek Chub Baby Pikie
Image Credit: PineAndSparrow via Etsy

The Pikie Minnow became Creek Chub’s signature lure almost as soon as the company started, and the Baby Pikie is the smaller version, a jointed wood minnow shaped to mimic a wounded baitfish. It was made in huge numbers across several decades, which keeps most surviving examples affordable.

Clean examples with original hardware and decent paint typically bring $20 to $75, more for early glass-eye versions or less common colors, and considerably more with a correct printed box. This isn’t a lure that will fund a vacation on its own, but it’s a genuinely useful one to recognize, since Creek Chub baits turn up constantly in old tackle boxes without anyone realizing what they’re holding.

Check the belly for the Creek Chub stamp and confirm the glass eyes, where present, are original rather than replaced. A jointed Baby Pikie with a cracked or repaired joint is worth a fraction of one that still articulates correctly, and that’s easy enough to test by hand before buying or selling.

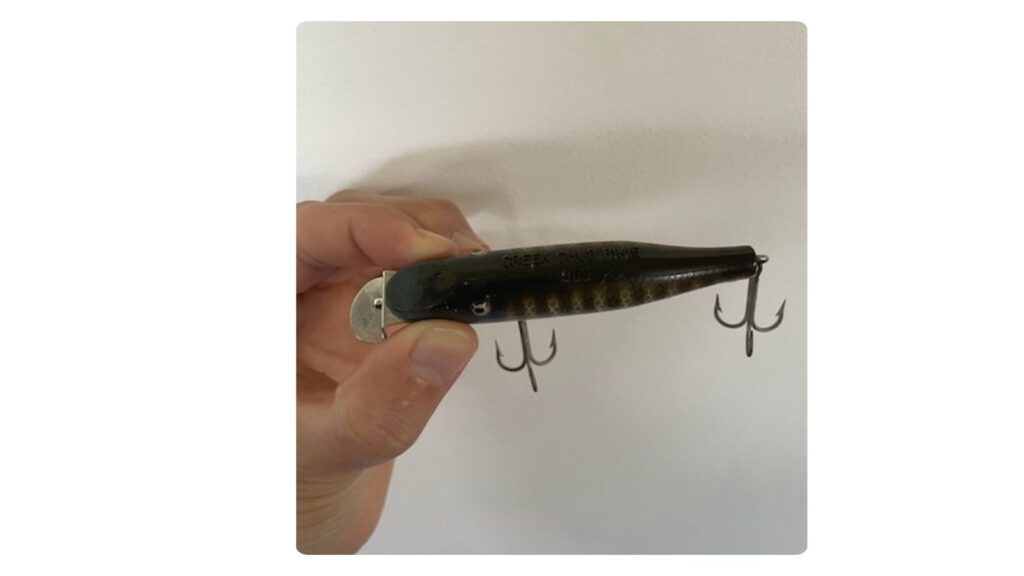
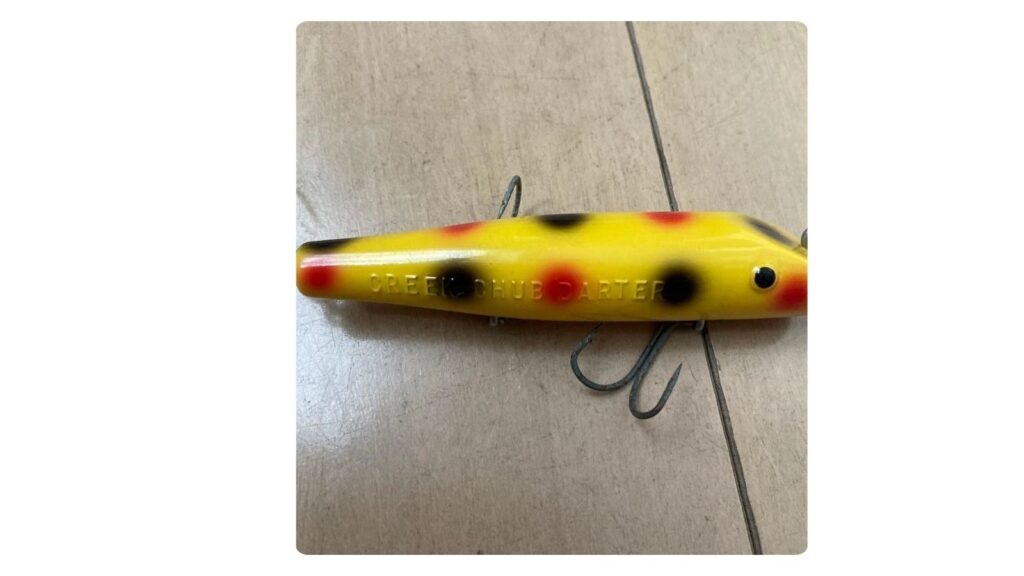
6. Creek Chub Darter

Creek Chub Darter
Image Credit: A Store That Sells【Myasu】from Japan via eBay

The Darter is another of Creek Chub’s signature shapes, built with a cupped face so it darts and dives erratically on a twitched retrieve instead of swimming in a straight line. Like most Creek Chub baits it was made in wood for decades before the company moved to lighter plastic bodies, and the wood versions with glass eyes are what collectors actually want.

Clean wood Darters with original glass eyes and solid paint typically bring $30 to $125, with early examples, boxed lures, and scarcer colors pushing toward the top of that range or past it. The later plastic-bodied versions are common and worth comparatively little.

As with most Creek Chub lures, the belly stamp and hardware style help date a given example, and one with replaced trebles or an obvious repaint should be priced as a well-loved fishing lure rather than a collectible. Pay close attention to the cupped face for chips, since that’s the part that takes the most abuse on the water and the part most often touched up before a sale.

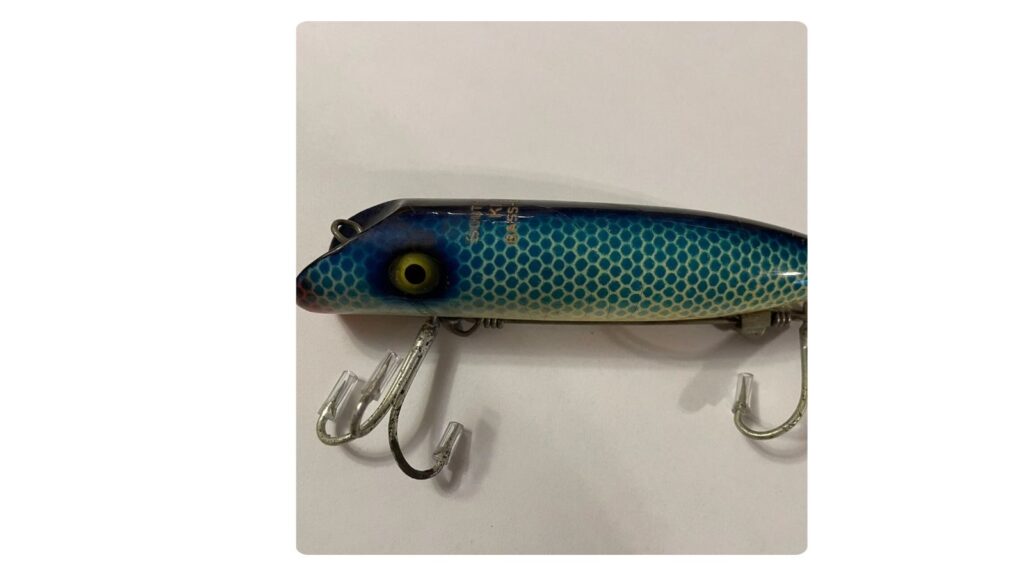
7. South Bend Bass-Oreno

South Bend Bass Oreno
Image Credit: beageneva via eBay

The Bass-Oreno put South Bend Bait Company on the map after it arrived in 1915, and the company kept making it, with small changes, for almost fifty years. Dating one isn’t hard once you know the markers: the earliest examples have no eyes at all, South Bend added glass eyes around 1926, and switched to simpler tack eyes in 1934 after the glass versions turned out to add too much weight to the lure.

Depending on age and condition, original Bass-Orenos typically run from about $6 up to $200 or more, with the earliest no-eye and glass-eye examples toward the top of that range and boxed lures higher still. The Bass-Oreno was made in such enormous numbers, across sixteen original colors and several more added later, that most examples you’ll find are genuinely common. A handful of early or unusual colors are the exception.

Don’t assume every South Bend lure in an old tackle box is cheap just because the standard Bass-Oreno usually is. Check paint and hook hardware carefully, since these were fished hard for half a century, and a repainted example should be treated as a decoration rather than a collectible.

8. South Bend Surf-Oreno

South Bend Surf-Oreno
Image Credit: Happy Hooker’s Bait & Tackle Shop via eBay

Built for saltwater, the Surf-Oreno is a scaled-up member of the Oreno family meant to survive rougher conditions and bigger fish than its freshwater cousins. It arrived in 1916 and kept the same basic shape as the rest of the line, just considerably larger and tougher.

Clean examples, especially in less common color patterns, typically sell for over $100, with exceptional boxed pieces bringing meaningfully more. Saltwater lures as a category get overlooked by some freshwater-focused collectors, which keeps prices a bit more approachable than you’d expect for a lure this size and this old, though interest has been climbing as more people realize these sat in the same tackle boxes as the common Bass-Oreno.

Size and weight meant these lures took a real beating from salt air and hard use, so rust on the hooks and hardware, pitting on any metal fittings, and sun-faded paint are all common and all reduce value. A Surf-Oreno that still has sharp paint and its original hook hardware, with no replacement trebles, is genuinely harder to find than the lure’s production numbers would suggest.

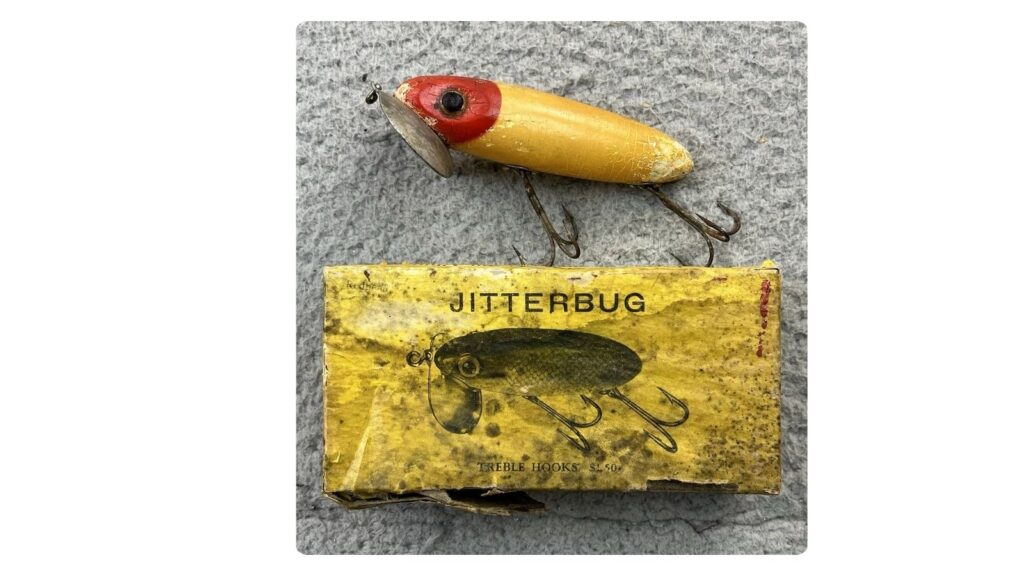
9. Arbogast Jitterbug

Arbogast Jitterbug
Image Credit: Thrift Central 1 via eBay

Fred Arbogast introduced the Jitterbug in 1938 out of Akron, Ohio, and its wide metal lip still makes the same loud, splashing commotion on the retrieve that made it a favorite for night fishing. Early wood-bodied Jitterbugs, made before the company shifted to plastic, are what collectors want most.

Vintage wood examples in their original box, with sharp paint and the correct lip and hook hardware, typically sell for upwards of $200. Loose, used examples without a box are far more common and far cheaper, often $10 to $40, since the Jitterbug has stayed in production in one form or another for over eighty years and plenty of well-worn ones are still floating around in tackle boxes.

Weight and sound are the giveaway for an early wood Jitterbug. Pick it up and tap it, since wood has a different heft and knock than the plastic bodies that came later. Check the metal lip shape too, since Arbogast changed the design more than once over the decades, and a mismatched lip on an otherwise old-looking body usually means a parts lure rather than an original.

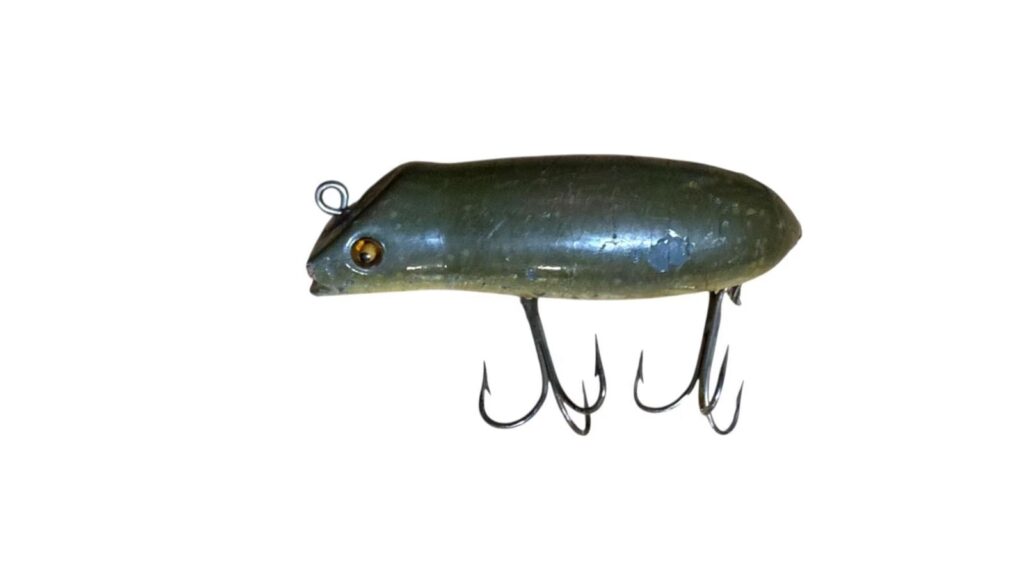
10. Shakespeare Swimming Mouse

Shakespeare Swimming Mouse
Image Credit: CBVintageCollectible via eBay

Shakespeare, the Kalamazoo, Michigan tackle maker, built the Swimming Mouse as a wood topwater lure shaped like a mouse, complete with a leather or fabric tail meant to twitch on the surface. It’s one of several wood baits the company made in the early to mid-1900s before shifting toward plastic lures.

Most surviving examples are common enough that clean ones in decent paint typically bring $15 to $50, with earlier glass-eye versions worth more than later painted-eye models. Shakespeare’s early 1900s “gem clip” rigged lures, a separate and scarcer line from the same company, have sold for several hundred dollars in top condition, which gives a sense of how much more the company’s rarer early wood baits can bring compared with a common Swimming Mouse.

Check the tail first. Original leather or fabric tails are often missing or replaced on Swimming Mice that actually got fished, and a replacement tail knocks the value down even when the body and paint are otherwise solid. After that, look at the glass eyes for cloudiness, cracks, or anything that suggests they’re not original to the lure.

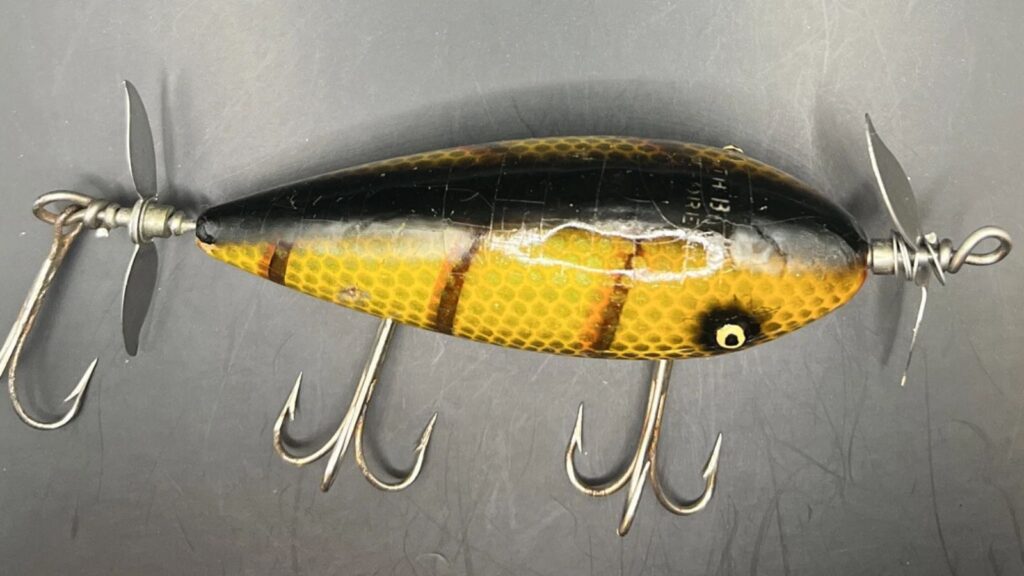
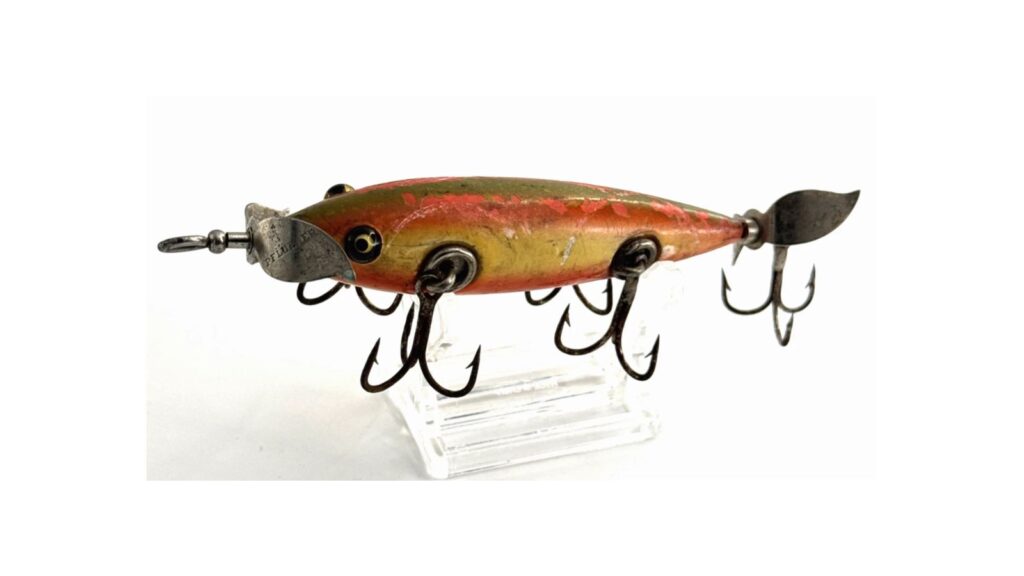
11. Pflueger Never-Fail Minnow

Pflueger Never-Fail Minnow
Image Credit: 1Loves2Shop1 via eBay

Pflueger’s Never-Fail Minnow is an early five-hook wood minnow from a company making fishing tackle in Akron, Ohio before most of its competitors existed. Multi-hook minnows like this one come from the earliest, most collectible era of American lure making, and they don’t turn up often outside established collections.

A Never-Fail Minnow in its original box, sometimes marked as the “Neptune Wooden Minnow,” typically brings around $500 in clean condition. Loose examples without a box, or ones with replaced hooks and hardware, sell for considerably less, often a few hundred dollars for a genuinely clean piece and well under that for a heavily used one.

Five-hook minnows like this got fished hard and lost often, which is part of why clean survivors carry a premium. Check that all five hook hangers and their hardware match in style and patina, since a lure that’s had hooks added or swapped over the decades will usually show it under close inspection, and any mismatch is worth factoring into what you’d pay or expect to get.

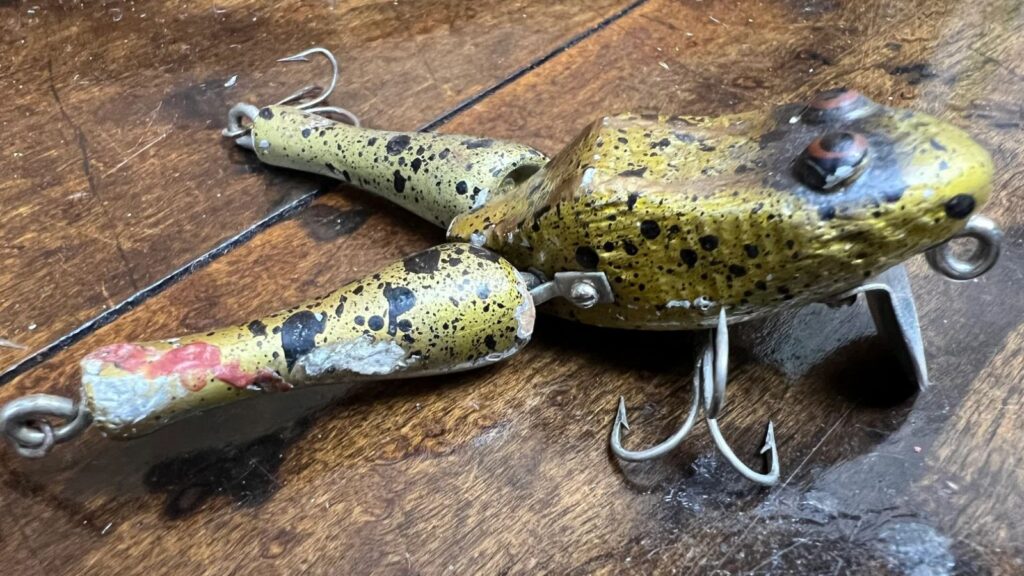
12. Paw Paw Wotta-Frog

Paw Paw Wotta-Frog
Image Credit:
VintageeThings via Etsy

Paw Paw Bait Company, based in Paw Paw, Michigan, built the Wotta-Frog as a jointed, green-painted frog lure with legs that kick on the retrieve. Frog lures like this one are fragile by design, with thin jointed legs and delicate paint, so most surviving examples show real wear.

A Wotta-Frog with its original box and in genuinely pristine condition typically sells for over $100, with exceptional examples bringing more. A used example with chipped paint or a repaired leg joint is worth a fraction of that, sometimes just $15 to $30, since the whole appeal of a frog lure like this rests on its details staying intact.

Check every leg joint individually. A frog lure that’s been glued or pinned back together at a broken joint has lost both its function and most of its value. Paw Paw’s history traces back to the Moonlight Bait Company, which the founders renamed in 1928, so earlier Moonlight-marked frog lures from the same basic mold are a related but separate find worth looking for in the same old tackle box.

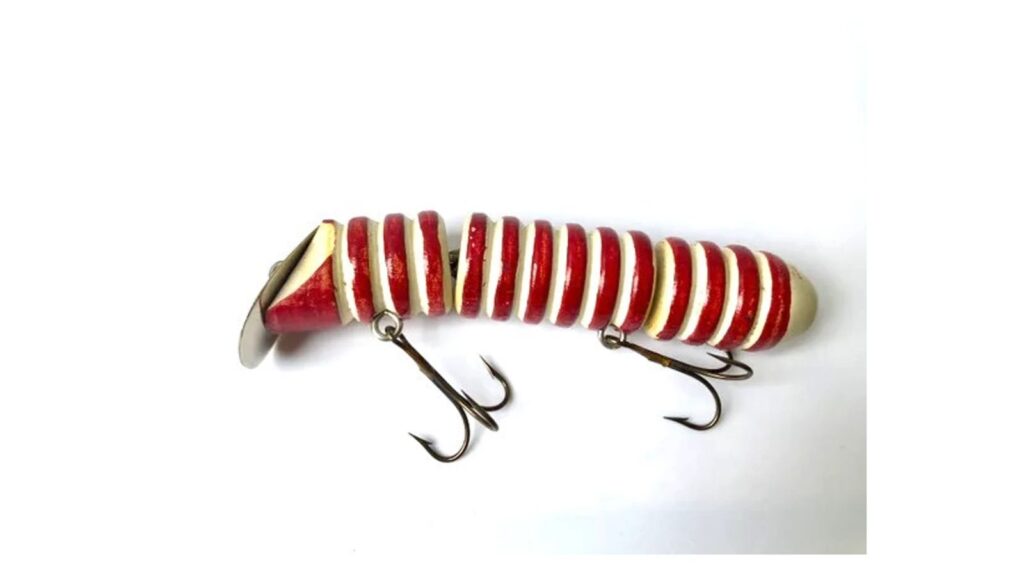
13. Oliver & Gruber Glowurm

Oliver & Gruber Glowurm
Image Credit: HallmarkantiquesShop via Etsy

The Glowurm is a bass lure with a distinctive ridged, painted wood body, made by the short-lived firm of Oliver & Gruber before production stopped in 1924. A company that only made tackle for a handful of years leaves a small pool of survivors to begin with, and the Glowurm’s unusual ribbed shape makes it easy to pick out once you know what you’re looking at.

Lures in good condition, especially with the original box, have sold for $140. That’s a solid number for a lure most people have never heard of, and it reflects how few of these turn up compared with the giants of the era, not any kind of design breakthrough. A rough, heavily painted-over example is worth only a modest fraction of that price.

The ridges are the first thing to check. They’re part of what made the original paint job distinctive, and a repaint tends to fill in or blur that detail in a way a careful eye can spot. Because this brand is obscure enough that most sellers won’t know much about it beyond “old wooden lure,” it pays to look closely at the body shape and paint yourself rather than trust a listing’s description, and a lure in its correctly marked box is worth tracking down over a loose one every time.

14. Comstock Flying Hellgrammite

Comstock Flying Hellgrammite
Image Credit: St. Marks Fishing- Apalachee Bay Inshore/Offshore via Facebook

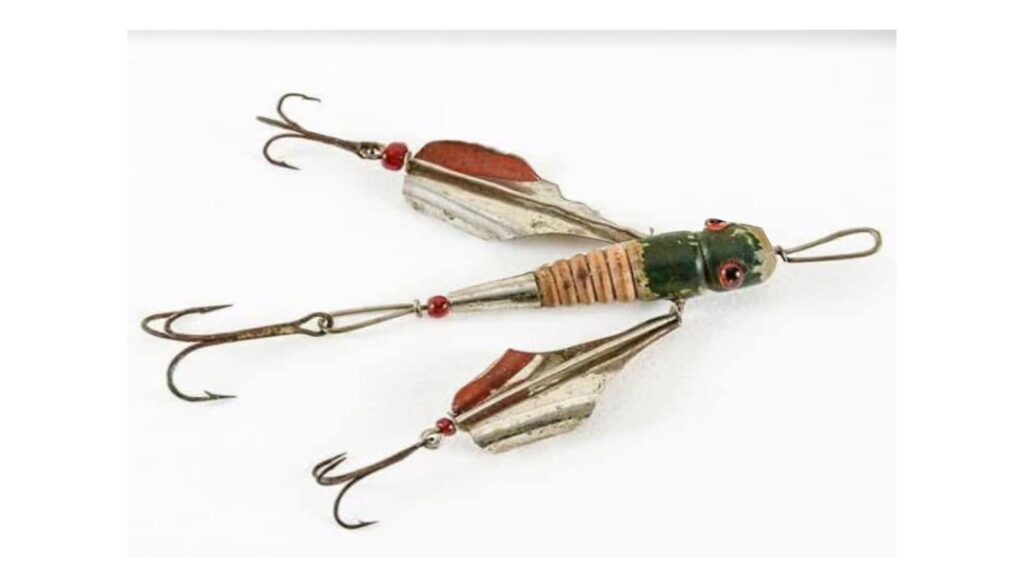
Harry Comstock of Fulton, New York made the Flying Hellgrammite around 1883, and it’s considered one of the very first lures built with glass eyes, a detail that later became standard across the whole industry. Shaped after the hellgrammite, an insect used as live bait, it has a winged, segmented body that was genuinely ahead of its time.

Well-kept original examples have fetched over $10,000 at the high end of the market, reflecting how few survive from a production run this early and this small. Lesser condition examples bring considerably less, but even a rough one with honest age and the right features is worth having checked by someone who specializes in early folk art lures.

The authentication wrinkle here matters. Pflueger’s predecessor company took over production of the same design not long after Comstock introduced it, adding its own luminous paint to the wings, and lures from that later run are a different and less valuable item than an original Comstock-made piece. Telling the two apart comes down to the paint, the eyes, and the overall hand-carved character of the earliest examples, which is exactly the kind of detail worth getting a specialist’s opinion on before assuming you’ve found a five-figure lure in an attic.

A major life change should trigger an insurance checkup right away—not simply at your next renewal. Start with the policies that could have an enrollment deadline or an immediate address, driver, ownership, or beneficiary problem. Then confirm that each policy still protects the people, property, income, and liabilities you have now.

For a single mom, this is less about buying more insurance than preventing a gap. A move, new benefits package, divorce, raise, side business, or teen driver can make yesterday’s coverage a poor fit.

Key takeaways

  • Review insurance promptly after a move, job change, divorce, birth or adoption, home purchase, major income shift, new driver, or business launch.
  • Handle health insurance first when coverage may end. Many Marketplace Special Enrollment Periods are tied to a 60-day window, while job-based plans must provide at least 30 days for special enrollment.
  • Do not cancel an old home, renters, auto, or health policy until the replacement is confirmed and you know its effective date.
  • Recheck life insurance beneficiaries after divorce and other family changes, but coordinate changes with any court order, divorce agreement, trust, or estate plan.
  • Compare like with like: the same limits, deductibles, exclusions, replacement-cost terms, and effective dates—not premiums alone.

Your first-hour insurance checkup

Gather the declarations page or benefits summary for each policy: health, auto, homeowners or renters, flood, life, disability, umbrella, pet, and business coverage. Note:

  1. Policy owner, insured people, drivers, and beneficiaries.
  2. Insured address, vehicles, property, and business activity.
  3. Limits, deductibles, exclusions, riders, premium, and renewal date.
  4. What changed and any enrollment or notification deadline.

Ask the insurer or benefits administrator to confirm changes and effective dates in writing. Keep updated policy pages, receipts, and cancellation notices together. Never end old coverage based only on a quote; confirm the new policy is issued, paid, and effective first.

What to review after a move

Homeowners or renters insurance

Tell the insurer before or promptly after moving. Coverage does not automatically transfer neatly to every new property, and the new home may have different rebuilding costs, security features, hazards, or eligibility requirements. If you rent, remember that the landlord’s policy is not a substitute for coverage on your belongings and personal liability.

Ask whether personal property is covered while in transit or storage and what protection the mover provides. The NAIC’s moving guidance recommends checking your existing policies and understanding the mover’s liability before moving day.

At the new address, update your home inventory with photos and receipts. Check whether belongings are insured at actual cash value, which accounts for depreciation, or replacement cost. Also ask how long additional living expense coverage would help with temporary housing after a covered loss and what limits apply.

Flood risk

Do not assume homeowners or renters insurance covers flooding. FEMA’s National Flood Insurance Program says most such policies do not cover flood damage. NFIP building and contents coverage are separate, with separate deductibles, and an NFIP policy generally takes effect 30 days after purchase, subject to listed exceptions. Review the property’s flood risk and options before a storm is approaching at FloodSmart.gov.

Auto insurance

Update the garaging address, commute, annual mileage, household drivers, and where the car is registered. Rates and required coverages depend partly on location, and a move across state lines may require a new policy. Ask the new state’s motor vehicle agency about registration and license deadlines, and consult its insurance department about local requirements.

Tell the insurer who regularly drives each car and where it stays. If raising a deductible to reduce the premium, choose an amount you could pay tomorrow without missing essentials.

What to review after a new job or job loss

Health insurance comes first

Compare the new employer plan with current coverage. Review the premium, deductible, out-of-pocket maximum, provider network, prescription formulary, and costs for care your family uses. Check whether each child should be on your plan, a co-parent’s plan, Medicaid, or CHIP.

If job-based coverage ends, do not wait. According to HealthCare.gov, losing qualifying coverage can create a Marketplace Special Enrollment Period if the loss happened in the past 60 days or is expected in the next 60 days. Marketplace rules also state that job-based plans must provide a special enrollment period of at least 30 days. Your precise options may include a spouse’s or parent’s plan, COBRA continuation, a Marketplace plan, Medicaid, or CHIP.

Divorce by itself does not create a Marketplace Special Enrollment Period; divorce or legal separation accompanied by loss of health coverage may. Voluntarily ending COBRA before it expires generally does not create one either. Keep proof of the coverage loss because the Marketplace may request documents.

If you already have a Marketplace plan, report income, household, address, and job-based coverage changes promptly. HealthCare.gov says those changes may affect coverage choices and premium savings. When moving to a different state, you generally need to start a new Marketplace application rather than simply update the old one.

Life and disability benefits

Ask whether employer life and disability coverage is portable or convertible, what deadlines apply, and whether supplemental coverage remains affordable. Compare the benefit with your household’s need. Update beneficiaries through the plan’s official process, and verify retirement-plan beneficiaries separately.

What to review after divorce or separation

Insurance details should follow the signed agreement and court orders, not an informal understanding.

Health coverage for you and the children

Confirm the exact date any spouse-sponsored coverage ends. Identify who must insure the children, how premiums and uncovered medical bills are divided, and how each parent receives insurance cards and claim information. If your coverage will end, explore special enrollment, COBRA, and public-program options before the termination date.

Auto, home, and renters coverage

Match policies to actual ownership and residence. Confirm who owns and garages each car, who drives it, and how a licensed child uses vehicles in both households. Verify the home policy’s named insured, lender or landlord, address, and property coverage. Someone moving out may need coverage at the new residence before the shared policy changes. Do not remove a spouse or cancel jointly connected coverage without confirming your authority and replacement protection.

Life insurance and beneficiaries

Review every primary and contingent beneficiary. The NAIC recommends updating policies after a life-changing event such as divorce and checking beneficiary names and contact information each year.

But do not automatically delete an ex-spouse. A divorce decree or support agreement may require one parent to maintain life insurance for the children or former spouse. State law can also affect beneficiary designations. Coordinate the policy with your attorney and estate-planning documents, especially before naming a minor directly. Confirm who owns the policy, who pays it, how long it must stay active, and how compliance will be documented.

Review the less-obvious gaps

  • Side work or a business: Tell your home or renters insurer about business inventory, visitors, equipment, or work from home. Personal policies may limit business coverage.
  • Disability coverage: Check the waiting and benefit periods, definition of disability, benefit amount, and coordination with employer coverage.
  • Umbrella liability: Revisit required underlying auto and home limits, household drivers, and rental properties.
  • Valuable property: Jewelry, art, collectibles, and electronics may have sublimits. Update ownership, appraisals, and scheduled-property coverage.
  • Pet insurance: Review reimbursement, deductibles, waiting periods, exclusions, and address changes.

How to compare coverage without creating a gap

Quote the coverage you need before chasing the lowest price. Give every insurer the same accurate information and compare the same limits, deductibles, policy form, replacement-cost basis, endorsements, and effective date. Ask what is excluded, whether limits are per person or per incident, and what documentation a claim would require.

For home, renters, auto, life, mortgage protection, pet, business, boat, or motorcycle coverage, Quote My Policy can be one place to start a comparison. Its site says the quote request is free and without obligation, and that it connects consumers with a licensed insurance professional who can discuss options from multiple carriers. Availability and suitable products can vary by state and applicant, so verify the professional and insurer with your state insurance department before purchasing.

The NAIC provides a directory of state insurance departments, which can help you check licensing, understand state-specific rules, or find the complaint process. Price matters, but so do the insurer’s financial condition, complaint history, coverage terms, and service.

A final checklist before you finish

  • Confirm all new policies are active before canceling old ones.
  • Replace outdated addresses, names, drivers, household members, property, and contact details.
  • Review primary and contingent beneficiaries on life insurance and retirement accounts.
  • Store current declarations pages, ID cards, inventories, and benefit summaries securely.
  • Tell a trusted person where policies and key contacts are kept.
  • Put a yearly insurance review on the calendar—and repeat this checkup after the next major change.

Frequently asked questions

How soon should I review insurance after a major life change?

Immediately when coverage, ownership, residence, drivers, or beneficiaries could change. Health enrollment rights may be time-limited, and property or auto information can become inaccurate as soon as you move or change who uses an asset. Start before the event when possible.

Does divorce automatically let me enroll in a Marketplace health plan?

No. HealthCare.gov says divorce or legal separation qualifies for a Special Enrollment Period when it also causes a loss of health insurance. Divorce without a coverage loss does not. Other qualifying events may apply, so use the Marketplace screener or contact the appropriate Marketplace.

Can I simply remove my ex from my life insurance beneficiary form?

Not always. First check the divorce decree, support agreement, policy ownership, and applicable state law. If coverage is required for support, changing the beneficiary or allowing the policy to lapse could conflict with that obligation. Ask your attorney and insurer how to complete any permitted change correctly.

Does renters insurance cover a flood at my new apartment?

Most renters policies do not cover flood damage, according to FEMA. Separate flood contents coverage may be available through the NFIP or private insurers. Ask about the effective date and exclusions; NFIP coverage generally has a 30-day waiting period, with exceptions.

Should I cancel the old policy as soon as I receive a cheaper quote?

No. A quote is not proof that coverage is in force. Wait until the insurer confirms issuance, payment, and the effective date. Then coordinate cancellation so there is no lapse, and compare the actual policy with the quote to make sure limits and deductibles match.

Checking a crypto app takes a few minutes and three free lookups. First, FinCEN’s registry: is the company on it? Second, the state money transmitter license. Third, the NYDFS list, when New York is involved. All three match? Good sign. A gap anywhere? The money stays put. Here’s where to click. Then what the results mean.

Why a licensed crypto app is worth checking 

Think of a license as a regulator saying, “we looked.” Nothing more. It isn’t a promise the company will stay solvent. But a licensed app has someone to answer to. It files reports, takes exams and can be fined. No license? Then nobody official is watching the crypto app. Anyone curious about how crypto platforms get licensed in the US will spot the pattern. Owners get vetted. Money laundering controls get tested. Somebody gets named compliance chief. NMLS records show public regulatory actions too, which can surface old trouble fast. Homepages skip all that. Registries don’t.

Four checks do most of the heavy lifting. None covers everything alone.

CheckWhere to lookWhat it showsWhat it does not prove
Federal registrationFinCEN MSB Registrant SearchA filed registration, declared activities and statesApproval, safety or accurate data
State licenseNMLS Consumer Access or the state regulatorLicense type, status, authorized states, public actionsThat the company is financially sound
New York statusNYDFS regulated entities tableHolders of BitLicenses and trust charters, with datesAnything about other states
Company identityThe app’s terms of serviceWhich legal entity runs the serviceThat its claims are true

Step one: search the FinCEN MSB registrant list 

Back in 2013, FinCEN’s guidance put many virtual currency exchangers and administrators in the money transmitter bucket. That’s why they show up on the MSB list. Search by legal name, trading name, state, even registration number. Partial entries work, which helps when a spelling is off.

One trap here. Use the company named in the terms of service. The app store brand is the wrong thing to type. They often differ. Say a parent is comparing two apps with near-identical logos. One belongs to a registered company. The other belongs to a shell with a P.O. box. The brand names alone tell nothing.

The results show declared activities, states, the filing address and two dates, signed and received. Registrations get renewed every two years, so a very old received date may mean a lapse. The address could be a registered agent’s. Plus it’s self-reported. A match proves a filing exists. Period. Save the status page as a PDF. It dates the check.

Step two: check state money transmitter license 

Registration with FinCEN is a federal filing. It is not a license. State licenses live elsewhere. Most show up on NMLS Consumer Access. It’s free. No login. Type the exact legal name first. Then try trade names. If the company lists an NMLS ID, search that. Cleanest hit.

Each record gives the entity, license type, issuing state and current status. Look for the authorized to conduct business flag. Pending? Expired? Suspended, revoked, withdrawn, denied? Same answer every time. No go in that state. States differ, and a few regulate outside NMLS, so a missing record means checking the state regulator’s own site. A Texas resident needs a Texas answer. A California license says nothing about Ohio. 

ResultLikely meaning
Exact match, active statusGood start, keep going
Match with an old received dateRegistration may have lapsed, so ask the company
Different legal nameCheck the terms. A parent company may run it.
No match anywhereDoesn’t prove fraud. Still a reason to pause.

Step three: scan the NYDFS list for New York 

New York plays by its own rules. The Department of Financial Services posts a regulated entities table for virtual currency businesses. It lists companies with a virtual currency license, a combined virtual currency and money transmitter license, or a limited purpose trust charter, plus the date each one was granted. There’s no search box. Scrolling is the method. The same page names firms that gave their licenses back.

Who needs one? Any business whose activity involves New York or its residents, even when the company sits in another state. Individuals who simply buy digital assets as an investment don’t. The requirement lands on the business. So an exchange or wallet that serves New Yorkers and appears nowhere on the table has some explaining to do. And that table is the official roster. Marketing copy isn’t.

Timing matters too. Licenses change hands. A company approved last year can be suspended this month, and a surrendered license stays on the page as a record. That’s why a screenshot from a review site or a friend’s tip counts for little. The lookups take minutes, and they show the regulators’ own data on the day of the check.

Warning signs before you deposit

Lookups catch paperwork problems. Behavior catches the rest. These should slow anyone down:

  • No legal entity named in the terms, or a name that matches nothing in the registries.
  • A “licensed” badge with no license number, regulator name or link.
  • Registration abroad only, with no word on US state rules for US customers.
  • Pressure to deposit fast, or guaranteed returns.
  • Fees or “taxes” demanded before a withdrawal.

Even a licensed app can fail. And a license number can be copied from a real company, so search the number, don’t just trust it. Registration isn’t insurance, either. Crypto balances usually aren’t covered by the deposit insurance behind a bank account. A clean result lowers one risk. The others stay.

A five-minute check before the first deposit 

Do it in this order.

  1. Grab the legal entity name from the terms of service.
  2. Run that exact name through FinCEN’s MSB Registrant Search. Save the status page.
  3. Then NMLS Consumer Access, plus a second look at the home state’s regulator.
  4. New York involved? Open the NYDFS table.
  5. Compare the records. Names? Dates? States? They should agree.
  6. Something off? Email the company. A real one answers in plain English.

A busy parent can run steps one through four on a lunch break. The slow part is usually waiting on an email reply, not the searching.

Step five catches the most. A name that shifts between records? Usually a parent company, a partner firm or a plain typo. A legal name that shifts is worth one email, never a guess.

What a clean result actually means

A pass looks like this. The legal name from the terms sits in FinCEN’s registry, with a recent filing and the right activity. The home state lists an active license with the “authorized” flag, or its regulator confirms one. New York? The company needs a line in the NYDFS table. Only then does a first small deposit make sense. A registry hit says who a company is, not how well it runs. Expired status, missing record, a name that changes between databases? The money waits until the company explains it in writing.

Navigating the automotive market can feel overwhelming for any buyer today. With so many options available, figuring out where to spend your money is tough. You might find yourself torn between local dealerships, online classifieds, and private sellers. Choosing the wrong seller can easily lead to purchasing a mechanical nightmare that drains your wallet.

To help you navigate this market safely, you need solid guidelines. In this article, you will explore the crucial rules dictating where you should spend your money safely today.

1. Always verify dealership reputations online

The very first rule when deciding where to buy used cars Australia is to thoroughly check customer reviews. Before setting foot on any physical lot, research their online reputation and history. A flashy showroom means nothing if previous customers constantly leave critical online feedback. Spend time reading independent review websites to accurately gauge their true honesty.

Look closely for consistent complaints regarding hidden fees, aggressive salespeople, or dodgy mechanical warranties. If multiple Aussies share similar horror stories about a specific location, trust their warnings entirely. You should only give your business to local dealerships that boast positive, verified customer feedback.

2. Prioritise certified pre-owned dealership lots

When you want maximum peace of mind, your best option is visiting certified pre-owned dealerships. These locations specialise in selling high-quality vehicles that trained mechanics have thoroughly inspected. They offer a level of mechanical safety and financial security that shady roadside lots cannot match. 

These certified lots back their stock with extended warranties and roadside assistance packages. This means if anything goes wrong shortly after your purchase, you are not left financially stranded. 

3. Inspect private seller platforms with caution

Browsing online marketplaces and private classifieds can reveal absolute bargains if you look closely. However, dealing directly with private sellers requires you to maintain a much higher level of caution. Without the legal protections offered by licensed dealerships, you are on your own if things fail.

You must implement strict personal safety rules when communicating with unknown private sellers online:

  • Public Meeting Spots: Always arrange to inspect the vehicle in a busy, well-lit public space rather than a secluded home
  • Daylight Inspections: Never view a vehicle at night or in the pouring rain, as this easily hides bodywork damage
  • Independent Mechanic Checks: Insist on having your own trusted mechanic inspect the car thoroughly before handing over cash
  • Proof of Ownership: Demand to see their physical driver’s licence and compare it to official registration papers

4. Understand the risks of public auto auctions

Public auto auctions often advertise low prices to attract eager, budget-conscious bargain hunters. While you might occasionally score a deal, these aggressive environments are risky for average buyers. Vehicles sold at public auctions are almost always sold completely ‘as is’, without standard dealer guarantees.

Before bidding at any public auto auction, you must thoroughly understand the severe risks involved:

  • No Real Test Drives: You are generally not allowed to drive the vehicle on open roads before placing your binding bid
  • Zero Mechanical Warranties: If the engine fails the moment you drive away, you bear the financial burden completely alone
  • High-pressure Bidding: The fast-paced auction environment can easily push you into spending way over your strict budget
  • Ex-fleet Vehicles: Many auction vehicles have been heavily used by multiple drivers during their previous corporate lives

5. Demand transparent pricing and clear contracts

Regardless of whether you choose a large dealership or a small independent lot, demand absolute transparency. The seller must be completely willing to explain every line item on the final invoice. If they try to rush you through paperwork or hide extra fees, walk away immediately. A trustworthy business will always ensure you understand what you are paying for today.

Take the paperwork home and read it thoroughly before signing anything binding or handing over a deposit. Make sure there are no sneaky delivery charges or overpriced paint protection packages added secretly. Choosing a seller who respects your intelligence and budget is the most important part of a successful purchase.

Navigate the automotive market like a pro

Finding the perfect pre-owned vehicle should not feel like navigating a dangerous minefield. By strictly following these essential rules, you can easily identify the most trustworthy sellers in the market. You will protect your hard-earned savings and completely avoid the stress of dealing with dodgy operators.

Take your time, do your extensive research, and never let anyone pressure you into a rushed deal. Now that you know where to look safely, you can start your exciting car-buying journey today.

You pull up the resume that landed your current job to give it a refresh, and the first line stops you cold: “Objective: To obtain a challenging position that allows me to utilize my skills and contribute to organizational growth.”

That sentence was standard advice when you wrote it. Now it’s the fastest way to signal you haven’t touched this document since gas cost two dollars a gallon.

The hiring process itself has changed shape since then. 97.4% of Fortune 500 companies now run a piece of software against every resume before a person ever opens the file, and that software is looking for very different things than the recruiters of 2005 were.

The fifteen habits below are what’s actually holding your resume back. Start with that line at the top, because it’s usually the first thing that needs to go.

Your resume opens with an objective statement

Printed resume with profile and employment-history headings beside a white keyboard
Image Credit: Shutterstock

The objective statement was built to tell an employer what you wanted. The problem is that nobody hiring for a role cares what you want yet, they care whether you can do the job. An objective statement is “a weak way to introduce yourself” that eats valuable space at the very top of the page, and that verdict hasn’t softened with time.

Swap it for a professional summary instead: three to five sentences stating your title, your years of experience, and one or two things you’re known for. If you managed a two-million-dollar budget or cut turnover in half, that goes in the first two lines, not buried in bullet three under job number four.

Drop “seeking a position that allows me to” completely. It says nothing about what you can actually do, and it wastes the single most valuable real estate on the page, the part a recruiter reads before they’ve decided whether to keep going.

There’s a photo of you in the corner

Woman holding a clipboard with her resume in an office
Image Credit: Shutterstock

A headshot might feel like a personal touch, but in the United States it works against you. Plenty of employers across the US, UK, and Canada will screen out an application that includes a photo, simply to keep accusations of bias out of the hiring process entirely. The Equal Employment Opportunity Commission has long advised employers not to request a photo before an offer is made, because a picture opens the door to decisions based on age, race, or appearance instead of qualifications.

This wasn’t always the rule everywhere, and it still isn’t the rule in much of the world. But in the US job market specifically, a photo in the corner reads as either a mistake or a habit picked up somewhere else.

If you want a recruiter to see your face, that’s what LinkedIn is for. Put a clean, current headshot there, link your profile in your contact section, and save the paper for what actually gets you hired.

It still says “references available upon request”

Resume form on a clipboard beside a keyboard, glasses, and a small plant
Image Credit: Shutterstock

This line used to be a courtesy. Now it’s dead weight. Nearly every hiring manager already expects you to hand over references the moment they ask, which means spelling that out on the page just eats space you could use for something that actually helps your case.

Cut it, full stop. Use that line, and the white space it frees up, for a specific accomplishment, certification, or skill relevant to the job instead. If a posting specifically asks you to list references upfront, follow that instruction, since it’s a direct request rather than a formality.

Otherwise, keep a separate reference sheet ready with names, titles, and phone numbers, and give the people on it a heads up before anyone calls. Hand the sheet over only when someone asks for it. This is one of the easiest fixes on this whole list, and it’s an easy way to make a resume look like it was written for 2026 rather than 2006.

Your email address gives away your age

Hands typing on a laptop with an email-envelope notification overlay
Image Credit: Shutterstock

If you’re still applying for jobs from an @aol.com, @hotmail.com, or old @yahoo.com address, it’s worth the ten minutes it takes to fix. An old-school email domain such as AOL or Hotmail can date an entire application before a recruiter ever reads a single line of real experience, and it plants a small, unnecessary seed of doubt about how current your skills are.

It isn’t really about age. It’s about the impression that you haven’t touched your setup, digital or otherwise, in a long time. Create a free Gmail or Outlook address using some version of your first and last name, and use that exclusively for your job search.

Skip anything cutesy or joke-based too. FarmerJoe1987@ might be a fine address for your fantasy football league, but it’s not one you want a hiring manager reading out loud in a meeting. Set up the new address today and use it everywhere you apply from here on.


It reads like your entire career history since your first job

Older couple holding a printed resume beside an open laptop
Image Credit: Shutterstock

If your resume runs three or four pages because you’ve listed every role since you left school, you’re not proving depth. You’re burying it. One resume-writing expert points to two pages covering roughly the last fifteen years of your career as the sweet spot, since trying to pack in everything you’ve ever done tends to produce a resume nobody can actually skim.

The job you had in 2004 doesn’t need its own section anymore, unless it’s directly relevant to the role you’re chasing now. Condense anything older than fifteen years into a single line, or drop it entirely if it isn’t adding useful context.

Use the space you free up to go deeper on your recent, relevant work instead, with real numbers attached wherever you have them. A recruiter isn’t grading you on the length of your career. They’re grading you on whether the last decade and a half makes you the right fit for this specific job.

Every bullet point starts with “responsible for”

Resume Writing Tips checklist on a clipboard with a red pen
Image Credit: Shutterstock

Two words do more damage to a resume than almost anything else on this list. A career coach who has helped hundreds of people land jobs points to “responsible for” as the phrase to cut immediately, since having a responsibility isn’t the same as delivering a result. Everyone had responsibilities. What a hiring manager wants to know is what you actually did with them.

Rewrite every bullet to lead with a verb and end with a result. “Responsible for managing the social media accounts” becomes “Grew Instagram following from 4,000 to 22,000 in eight months.” “Responsible for training new hires” becomes “Trained 14 new hires, cutting onboarding time by two weeks.”

If you don’t have a hard number, use a comparison, a scope, or a before-and-after instead of a duty. This is the single highest-return edit you can make to an old resume. It turns a list of job duties into a list of reasons to hire you.

It’s a beautifully designed document that a computer can’t read

Hands reviewing a printed resume beside a laptop displaying a resume
Image Credit: Shutterstock

That two-column template with the shaded sidebar and the little icons next to each skill might look sharp to your eye. To a piece of hiring software, it can be unreadable. Nearly all Fortune 500 companies now run resumes through an applicant tracking system before a recruiter ever sees them, and graphics, tables, columns, and photos are among the most common reasons that software fails to read a resume correctly.

Your carefully designed sidebar of skills might simply not exist as far as the system is concerned. The fix isn’t to make your resume ugly. It’s to build it in a single column, with standard section headings like Experience and Skills, plain black bullet points, and your contact information in the body of the page rather than a header, since many systems skip headers entirely.

Save the design flourishes for your portfolio or your LinkedIn banner. Your resume’s job is to get through the machine first and impress the human second.

Your work history is one giant paragraph

Several resume layouts on a table with a magnifying glass
Image Credit: Shutterstock

Dense blocks of text under each job title were common twenty years ago, back when a resume was something a person actually sat down and read start to finish. That isn’t how resumes get reviewed anymore. A recruiter’s first pass over a resume typically lasts somewhere around six to eight seconds, scanning rather than reading, before they decide whether it’s worth a second look.

A paragraph doesn’t scan. Bullet points do. Break each role into three to six lines, each one starting with a strong verb and ideally containing a number. Keep every bullet to a single line or two at most.

White space isn’t wasted space on a resume, it’s what makes the important parts visible in those first few seconds. If you’re not sure your resume passes the scan test, read it for exactly seven seconds and then look away. Whatever stuck is what a recruiter actually walks away with.

Your full home address is sitting right under your name

Magnifying glass over a printed resume on a green desk
Image Credit: Shutterstock

Listing a complete street address made sense when interview invitations arrived by mail and employers needed it for identification. Almost none of that applies now. HR leaders increasingly consider a full home address unnecessary on a resume, pointing to privacy concerns and how much of hiring has shifted onto digital and remote channels.

City and state is all a resume needs today, and it’s often all that’s useful. It tells an employer you’re roughly in the right time zone or open to relocating, without handing your exact address to every job board, recruiter, and forwarded email thread your resume ends up in.

If you’re applying to a genuinely local role where proximity matters, city and state does that job just as well as a full street address, minus the risk. Keep your street address for tax paperwork and background checks once you’re actually being hired, not for a document you’re sending to strangers on the internet.

Linkedin logo
Image credit: Alexander Shatov via Unsplash

Skipping a LinkedIn URL used to be normal, because LinkedIn itself barely factored into hiring. That’s no longer true. A recent survey of recruiters found that 73.3% of them always or often check a candidate’s LinkedIn profile as part of evaluating an application, which means for nearly three out of four recruiters, your resume is only half the picture.

If there’s no link to your profile sitting near your email and phone number, you’re making a recruiter go find you themselves, and plenty won’t bother.

Add the URL, and make sure the profile it points to actually matches your resume. A recruiter who reads impressive details on paper, then finds a profile picture from a wedding and a job title that hasn’t been updated in six years, will notice the mismatch. You don’t need thousands of connections. You need a profile that says the same things your resume says, consistently.

Your skills section brags about knowing Microsoft Word

Desktop computer and keyboard with a tablet on a tidy office desk
Image Credit: Shutterstock

Somewhere in your skills section, there’s a good chance you’ve listed Microsoft Word, email, or basic typing as if they set you apart from other candidates. They don’t anymore, and haven’t for a while. Most hiring managers already assume you can handle Word, Excel, and PowerPoint without being told, and calling them out just burns space while hinting you’re not sure what counts as a basic skill these days.

Typing speed belongs on that same discard pile. Unless a role specifically requires fast, accurate transcription, nobody needs to know you can type 65 words a minute. Spell check solved that problem decades ago.

Replace that space with skills that are actually specific to your field and to the posting in front of you. Software you’ve mastered that isn’t universal, certifications, languages, and technical tools relevant to the role all belong there instead. A skills section should tell an employer something they didn’t already assume about every working adult in the country.

It opens with “Dear Hiring Manager” and closes with “Sincerely”

Woman with glasses writing notes on a clipboard against a yellow background
Image Credit: Shutterstock

A resume is not a letter, but plenty of resumes from the early 2000s were formatted like one, complete with a formal salutation at the top and a signature line at the bottom. If yours still has either, it’s borrowing formatting from your cover letter and applying it to the wrong document.

A resume needs your name, your contact information, and then straight into your summary or experience. No greeting, no closing, no “thank you for your consideration” tucked in at the bottom. Save that language for the cover letter, where it belongs and where a hiring manager expects to see it.

This mistake is small, but it’s a tell. It suggests the resume was built from a template designed for correspondence rather than one designed to be scanned quickly for qualifications. If you’re not sure whether a line belongs, ask what it tells a recruiter about your qualifications. If the answer is nothing, it goes.

There’s a fax number in your contact information

Hands feeding a document into an office fax machine and pressing its keypad
Image Credit: Shutterstock

If your contact block still has a line for a fax number, it’s worth asking when you last actually sent or received one. For most people reading this, the honest answer is years, possibly decades. A fax field on a resume is one of the clearest signs that the document was drafted once, a long time ago, and simply carried forward through every update since without a second look.

Your contact information should be short: name, phone number, email, city and state, and a LinkedIn URL. That’s it. Landline numbers can go too, unless a landline is genuinely the only number where someone can reach you.

Every extra line in that block is competing for attention with information that actually matters, in the first few seconds a recruiter is willing to give you. If you find a fax number on your resume today, that’s a decent signal to read through the rest of the document with fresh eyes, because there’s likely more than one thing in there that hasn’t been touched in a while.

The font is doing all the talking about how long you’ve been out of the game

Applicant handing a printed resume to an interviewer
Image Credit: Shutterstock

Times New Roman was the default font in Microsoft Word for years, which is exactly the problem. Everyone used it because nobody had to think about it, and that’s still true for anyone who hasn’t opened their resume in a while. Design professionals asked about resume fonts have compared defaulting to Times New Roman to “like putting on sweatpants”, a choice that signals no thought went into the document at all.

Swap it for something cleaner and built for screens rather than print, since almost every resume today is read on a monitor, not printed on paper. Calibri, Arial, Garamond, and Georgia are all safe, modern, and still compatible with the software scanning your resume before a person sees it.

This is a five-minute fix with an outsized effect. A dated font won’t sink an otherwise strong resume on its own, but paired with an objective statement and a fax number, it completes a fairly dated picture.

You’re sending the exact same resume to every job

Recruiter reviewing a printed resume beside a laptop
Image Credit: Shutterstock

Applying to fifteen jobs a week with one unchanged resume file is efficient. It’s also working against you. Recruiters say they start by filtering candidates on skills 76.4% of the time, and resumes containing the exact job title from a posting see interview rates 10.6 times higher than those that don’t. A generic resume simply doesn’t contain the specific words a recruiter, or the software they’re using, is searching for.

This doesn’t mean rewriting your resume from scratch for every application. It means opening the job posting, pulling out the exact skills, tools, and job title it uses, and making sure those same words appear somewhere on your resume, assuming you actually have that experience.

A twenty-minute edit before you hit submit will do more for your interview rate than almost anything else on this list. Job hunting in 2005 rewarded persistence. Job hunting now rewards precision.

Most of this is an afternoon’s work, not a full rewrite. Fix the fifteen habits above, and your resume will finally sound like it was written by someone applying for a job in 2026, not one who stopped updating it years ago.