The first days after a serious accident usually center on immediate injuries. Broken bones are stabilized, wounds are treated, and doctors look for signs of internal damage. Yet recovery does not always end when someone leaves the hospital. For single mothers managing children, work, and a household, lingering health problems can affect nearly every part of daily life. Knowing what may appear weeks or months later can make follow-up care easier to prioritize.
Persistent pain is one of the most disruptive long-term effects of a major accident. Injuries involving the back, neck, joints, nerves, or soft tissue may continue causing discomfort after the initial healing period.
Pain can also change how someone moves. A mother with an injured knee might place more weight on her other leg, eventually creating soreness elsewhere. Persistent or worsening symptoms deserve medical attention rather than simply becoming part of a new routine.
Brain injuries may have less obvious effects
A traumatic brain injury does not always produce symptoms that are easy to see. Headaches, dizziness, memory problems, sensitivity to light, difficulty concentrating, and sleep changes can persist after an accident.
These symptoms can interfere with parenting and work. Tasks such as following a school schedule, paying bills, driving, or managing several appointments may suddenly require more effort. Anyone experiencing new neurological symptoms after an accident should seek medical evaluation, particularly if symptoms worsen.
Emotional health can change too
A serious collision, workplace incident, or other traumatic event can affect mental health long after physical injuries begin improving. Some people experience anxiety, depression, sleep disturbances, or symptoms associated with post-traumatic stress.
Certain situations can become triggers. Driving past an accident location, hearing tires screech, or returning to the workplace where an injury occurred may cause distress.
Mental healthcare can be an important part of recovery. Therapy, support groups, or other professional care may help when emotional symptoms begin interfering with everyday activities.
Recovery can affect the entire household
A long recovery can change family routines. A parent who cannot lift heavy objects may need help carrying groceries or picking up a young child. Driving restrictions can complicate school transportation. Medical appointments and reduced work hours may add financial pressure.
Documenting medical visits, work restrictions, symptoms, and accident-related expenses can help keep these responsibilities organized. After a serious job-related injury, some families may also speak with work accident lawyers about questions involving compensation or other legal rights.
Follow-up care matters
People sometimes stop medical care once the most severe symptoms improve. However, follow-up appointments give healthcare professionals opportunities to evaluate healing, adjust treatment, and identify problems that were less apparent immediately after the accident.
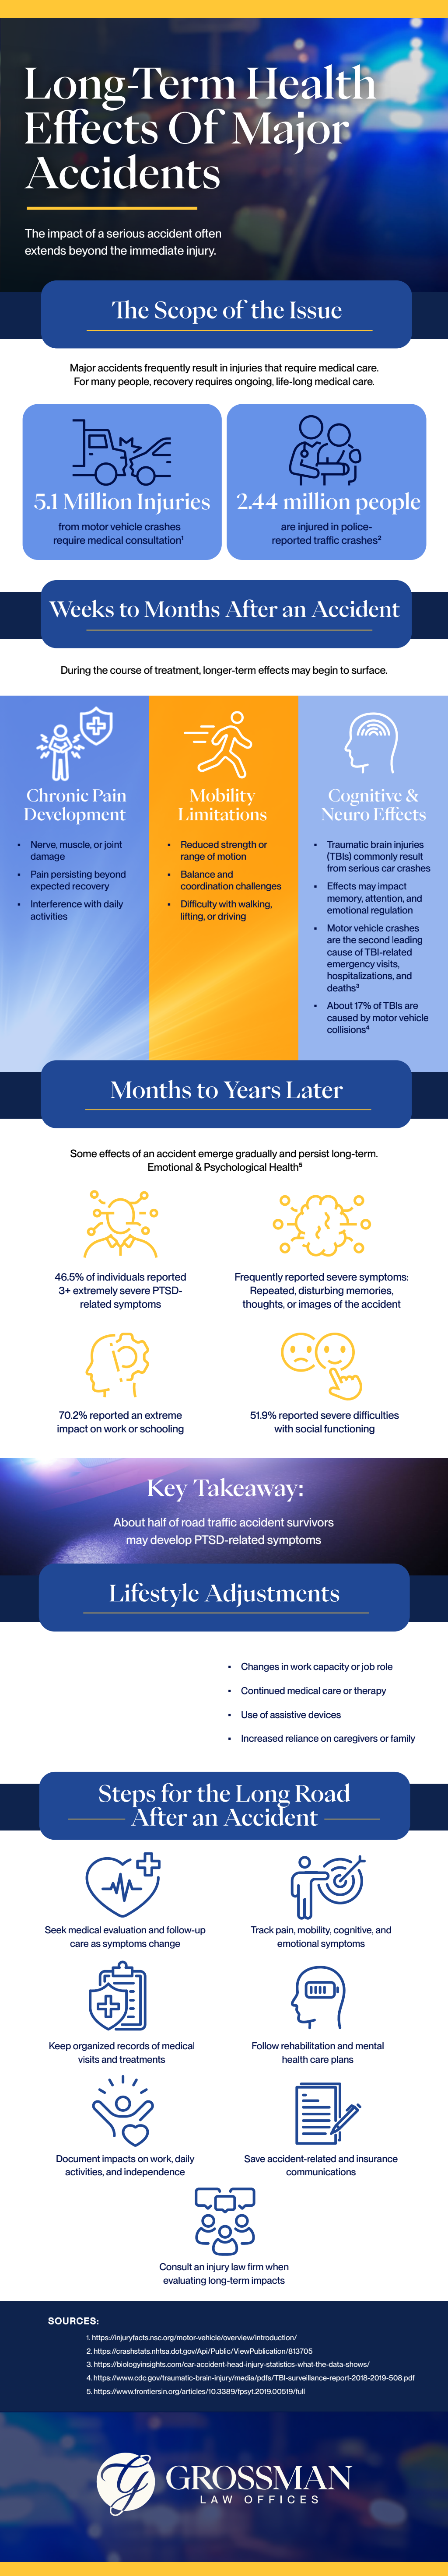
Recovery from a major accident rarely follows a perfect timeline. Physical pain may linger, emotional symptoms can emerge later, and everyday responsibilities may expose limitations that were not obvious at first. For a single mother, paying attention to those changes is especially important because her health affects the routines that keep the household moving. Look over the infographic below to learn more.
On December 19, 2022, the FTC announced that Epic Games, the company behind Fortnite, would pay $245 million in refunds over its billing practices, the largest refund amount the agency had obtained in a gaming case. The billing complaint centered on purchases players never meant to make. One of its allegations went further.
When players disputed unauthorized charges with their credit card companies, the FTC alleged, Epic locked their accounts. A locked account lost everything bought inside it, a sum that could reach thousands of dollars, and players who got back in were warned that one more dispute could mean a lifetime ban.
The case raised questions that reach well past Fortnite, to every digital purchase, a coin package from a sweepstakes gaming site included. What does the money buy? Who can undo the purchase, and how? What has to happen before coins in an account turn into a prize? The answers vary more than most buyers assume.
A digital purchase lives inside an account the seller controls
The lockouts showed what buyers of digital goods really hold. Steam’s subscriber agreement, for one, files the rights to access its games and in-game content under the word “Subscriptions,” a term most people would save for a monthly plan. Its license section is blunter: the content is “licensed, not sold,” and the license ends when the agreement or the subscription that carries it does. Whoever operates the account writes those rules.
That’s why a locked account cost so much more than any single refund could return. A card dispute might recover the price of one item; a lockout took the whole library, every outfit and battle pass bought over the years. The FTC’s order went straight at that, barring Fortnite’s maker from blocking players’ access to their accounts because they disputed unauthorized charges.
That order binds one company, and only for the conduct it names. A budget that counts a game library as something of lasting value is counting an asset that one account decision can erase.
The card you pay with sets your federal protection
When a digital charge goes wrong, the strongest tool most buyers carry is a credit card. Under the Fair Credit Billing Act, as the FTC’s consumer guide explains it, a cardholder can dispute an unauthorized charge, a wrong amount, or an item that wasn’t delivered as agreed. The issuer must receive the written dispute no later than 60 days after it sent the first bill that contained the error.
That letter goes to the address the issuer lists for billing inquiries, not the one for payments, and the guide suggests certified mail with a return receipt as proof of what arrived. The issuer then has 30 days to acknowledge the dispute in writing and two billing cycles, never more than 90 days, to resolve it. The cardholder can hold back payment on the disputed amount while the investigation runs. If a card is used without permission, the same guide notes, federal law caps the cardholder’s share of the unauthorized charges at $50.
Debit cards come with thinner protection. The FTC’s guide to lost and stolen cards puts the maximum loss at $0 when the card is reported before any unauthorized use and $50 when it’s reported within two business days of discovering the problem. After that it rises to $500, and once 60 days have passed since the statement, it can include everything taken from the account and possibly money in linked accounts.
Refund windows close fastest on in-game currency
Refund policies are company choices, and they differ widely. Steam’s refund policy takes back nearly any game, whatever the reason, as long as the buyer asks within two weeks and has logged under two hours of play. PlayStation’s cancellation policy gives 14 days on a game, but only until the buyer begins downloading or streaming it.
Currency gets far less room. Inside games, Steam’s window shrinks to 48 hours and applies to Valve’s own titles, provided the item is still unused and hasn’t been altered or traded; elsewhere it depends on whether each developer chose to allow refunds. PlayStation’s policy files virtual currency under “in-game consumables,” naming “V-bucks or Robux” among them, and once such an item has been delivered the purchase stands unless the item is faulty.
Buy that currency mid-game and it arrives instantly, which closes the window before it opens. The V-Bucks named in the 2022 case sit at the least refundable end of a major store’s policy. The seller’s reasoning isn’t hard to follow: a coin can be spent within seconds, and a spent coin can’t be handed back the way an unplayed game can.
The closer a purchase comes to money inside a game, the closer it is to final the moment it’s paid for. Coin packages on sweepstakes gaming sites can sit in that group too, depending on how each operator writes its terms.
A coin package is final under the terms, and only cards can pay for it
Sweepstakes gaming sites typically run on two coins. On Hello Millions, Gold Coins are for play, and only Sweeps Coins can be redeemed for prizes. Version 2.3 of the operator’s terms says no purchase is required to open an account or play, that any purchase is final, and that the play coins carry no cash value.
As with a game library, the money buys a license rather than property. The terms grant a revocable license to use the coins “solely for Your personal, private entertainment” and say the player has “no right or title” in them.
Buying coins on the Hello Millions sweeps platform runs on cards alone: a LineUps review of the site says packages can be paid for with Visa, Mastercard or Discover and nothing else. The same review says an official ID has to be uploaded in the site’s Redeem menu before any prize is redeemed, and that each Sweeps Coin must first be played at least once. Live chat, it adds, is open only to players who buy a package, while the help center and an email contact form serve every player.
Eligibility comes from the terms as well. They set the minimum age at 21, or the local age of majority if that’s higher, and they list 16 states, plus everywhere outside the US, where the games aren’t offered, leaving each player to confirm that taking part is lawful where they are. The account name also has to match government ID, so a typo at sign-up can hold up a redemption later.
Refunds from FTC cases can take years to arrive
Beyond the card rules, money back for a bad digital charge can also come from an FTC enforcement case, and those cases matter more for subscriptions now that a court has set aside the agency’s cancellation rule. Their refunds run on a far slower clock than any card dispute.
Fortnite players had to file claims, and eligibility reached back to January 2017 for both unwanted in-game charges and accounts locked after a card dispute. According to the FTC’s refund updates, the first round, 629,344 payments totaling more than $72 million, went out in December 2024, two years after the settlement was announced and nearly eight years after the earliest eligible charges. A second round of more than $126 million followed in June 2025, and the deadline for new claims passed the following month.
Amazon’s settlement over allegations that it deceptively enrolled customers in Prime is still paying out. The FTC’s original order of September 2025 required refunds only for members who used fewer than 10 Prime benefits over a year. In September 2026 the FTC raised the maximum payment from $51 to $200 and extended refunds to members who used up to 20 benefits over a year and signed up between June 23, 2019, and June 23, 2025, according to CBS News coverage of the revised order.
Amazon began sending those payments on October 1, CBS reported, and they arrive automatically, with nothing to file; the company had refunded more than $845 million as of September. Someone who joined in mid-2019 and qualifies under the wider terms is getting money back on a sign-up from more than seven years ago.
Coin charges carry the operator’s company name
Each coin purchase leaves a trail in three places. The terms promise two of them: an on-screen confirmation that the transaction went through, and an email that says the same. The third is the card statement, where, the terms say, the charge will appear as a purchase from B-Two Operations Limited, the company that runs the site.
With that name in mind, anyone can total a month’s coin spending straight from the statement and check each line against its confirmation email. For a running tally between statements, a list of money habits that work without a budget recommends switching on transaction alerts for bank accounts and cards.
Disagreements with the operator go through a route of their own. The terms ask for a Notice of Dispute sent through customer support, promise a written acknowledgement within five days, and require 60 days of informal talks before either side can start binding arbitration. A new player who wants to keep the option of going to court has 30 days from accepting the terms to opt out of arbitration.
Who can undo a coin purchase, then, depends on the problem. A charge for the wrong amount, or one never authorized, goes to the card issuer, and a disagreement over the account follows that dispute route. A purchase made exactly as intended, which only later felt like a mistake, fits neither: regret isn’t among the billing errors the FTC’s credit card guide lists, and the terms call every purchase final.
Ending a marriage is rarely simple, but the adversarial courtroom battle depicted in popular media is increasingly becoming an outdated relic. For couples facing separation today, the traditional legal process often introduces unnecessary emotional strain, drawn-out timelines, and staggering legal expenses. Recognizing that mutual agreements yield far more sustainable outcomes than judicial mandates, many spouses are turning toward collaborative alternative dispute resolution. In fact, choosing professional divorce mediation in Boise allows families across the Treasure Valley to resolve sensitive parenting and property divisions outside a contentious courtroom setting. By prioritizing open dialogue over litigation, mediation transforms what could be a destructive conclusion into a structured, forward-looking transition.
Understanding divorce mediation: Process and purpose
At its foundation, divorce mediation is a voluntary, confidential alternative dispute resolution (ADR) process. Rather than having two opposing attorneys argue before a family court judge who knows very little about your personal values, you and your spouse work alongside a neutral third-party mediator.
The mediator does not act as a judge, nor do they represent either party as legal counsel. Instead, their primary role is facilitative:
Guiding productive communication between spouses.
Identifying underlying priorities and areas of consensus.
Uncovering practical options for complex financial and custody disputes.
Ensuring both parties understand the tangible implications of their choices before finalizing agreements.
Because the mediator remains impartial, the dynamic shifts away from “winning versus losing” toward mutual problem-solving. Every decision—from how retirement accounts are divided to who keeps the family home—is reached through consensus.
Why litigated divorces create unintended fallout
To understand the rising preference for mediation, one must look closely at what conventional litigation entails. When spouses hire separate trial lawyers to fight in court, the system inherently pits them against one another as adversaries.
1. The true financial toll
Litigation costs can quickly spiral out of control. Between attorney retainers, formal discovery motions, depositions, expert witness fees, and billable court appearances, contested divorces routinely cost tens of thousands of dollars per spouse. These are funds directly depleted from marital assets that could otherwise support two independent households or fund children’s college savings.
2. Loss of autonomy and privacy
Courts operate on rigid statutory guidelines and judicial discretion. In a contested trial, personal family matters—including financial statements, allegations of misconduct, and parenting evaluations—become part of the public record. Ultimately, a judge who has spent only a few hours reviewing your case issues legally binding orders regarding your life, children, and property.
3. Lingering relational damage
Litigation creates an adversarial posture where each side is incentivized to highlight the other’s shortcomings. For couples with shared children, this dynamic often leaves lasting resentment, making effective co-parenting nearly impossible long after the final decree is signed.
Key benefits of choosing mediation
Mediation offers a stark contrast to courtroom conflict. By fostering a controlled, respectful environment, it yields distinct advantages across financial, emotional, and practical spectrums.
Unlike open court proceedings, mediation takes place behind closed doors. State ADR rules and standard mediation agreements protect all discussions, notes, and settlement proposals from being introduced as evidence in future court proceedings should negotiations stall. This safe container allows spouses to speak transparently, explore creative compromises, and propose unorthodox solutions without fear of legal penalty.
Customized, flexible agreements
Judges must adhere strictly to statutory formulas and standard local schedules. A mediator, however, helps couples craft bespoke agreements tailored to unique circumstances. Whether you manage variable freelance income, run a family-owned business, or need a non-traditional alternating parenting schedule to accommodate shift work, mediation grants the flexibility to construct workable terms that a standard court ruling rarely provides.
Step-by-step: How the mediation process works
While individual situations differ, a standard professional mediation pathway follows a predictable, structured progression designed to reduce anxiety and maintain forward momentum.
Step 1: Initial consultation and intake
The process begins with an intake meeting where the mediator outlines their role, verifies that mediation is appropriate, and establishes ground rules for constructive dialogue.
Step 2: Comprehensive financial disclosure
For any agreement to be legally durable, complete financial transparency is mandatory. Both spouses gather and share documentation, including tax returns, pay stubs, retirement account statements, real estate valuations, and outstanding debts. The mediator helps organize these disclosures into an objective balance sheet.
Step 3: Facilitated negotiation sessions
Working through a series of focused meetings, the couple addresses the core pillars of their divorce. The agenda typically moves methodically through:
Child and Spousal Support: Calculating baseline guidelines while addressing real-world needs and health insurance coverage.
Asset and Debt Division: Deciding the equitable distribution of real property, retirement plans, vehicles, and liabilities.
Step 4: Drafting the settlement agreement
Once full agreement is reached, the mediator drafts a Memorandum of Understanding. This document details every agreed-upon term in clear, unambiguous language.
Step 5: Legal review and court filing
Before signing, each spouse is encouraged to have an independent consulting attorney review the draft. Once finalized and signed, the paperwork is submitted to the court for uncontested judicial approval, finalizing the divorce without courtroom appearances.
Crafting a child-centered parenting plan
For parents, protecting children from the fallout of divorce is almost always the highest priority. Research consistently demonstrates that it is not divorce itself that causes long-term psychological harm to children, but rather prolonged, unmanaged conflict between their parents.
Mediation uniquely supports children by keeping their best interests at the core of negotiations. Instead of arguing over arbitrary percentage splits of parenting time, parents collaborate to address real-world routines:
Academic Continuity: Coordinating transportation, homework support, and school communication across two homes.
Health and Wellness: Clarifying how medical decisions are handled, therapy needs are met, and health expenses are shared.
Milestones and Traditions: Protecting birthdays and major family holidays so children do not feel torn between parents.
Navigating complex financial realities
Modern divorces frequently involve financial arrangements that cannot be resolved with a simple 50/50 division. Real estate market fluctuations, retirement pensions, stock options, and small business operations require nuanced handling.
The marital residence
Deciding what to do with the shared home is often an emotionally charged issue. Mediation allows couples to weigh realistic options rather than forcing an immediate fire sale. Couples can explore whether one spouse can refinance and buy out the other’s equity, or if a delayed sale is mutually beneficial.
Retirement and pension accounts
Dividing 401(k)s, IRAs, and defined-benefit pensions requires strict adherence to federal and state tax codes to avoid triggering steep early-withdrawal penalties. Mediators assist couples in understanding tools like Qualified Domestic Relations Orders (QDROs), ensuring retirement balances are divided cleanly and equitably.
Is mediation right for every couple?
While mediation is an exceptional path for the vast majority of separating couples, it requires certain baseline conditions to succeed. It works best when both parties:
Accept that the marriage is ending and are prepared to negotiate in good faith.
Are willing to disclose all financial assets and debts honestly without concealing information.
Can advocate for their needs without being dominated or intimidated by the other spouse.
Are committed to keeping disagreements focused on problem-solving rather than retribution.
In situations involving active domestic violence, unaddressed substance abuse, or intentional asset hiding, traditional litigation with court oversight remains the appropriate and necessary legal recourse.
Taking the next step toward resolution
Divorce marks the end of one chapter, but it simultaneously establishes the blueprint for your next stage of life. Choosing to navigate this transition through mediation preserves your financial resources, protects your emotional well-being, and provides your family with a predictable, respectful resolution. Engaging in a candid, structured conversation early in the process can save months of unnecessary stress and provide the clarity needed to step confidently into your future.
For many parents, having a grown child move back home starts out as a kindness. Maybe it was a job loss, a breakup, or a plan to save money for a few months. Then the months turn into years, and the arrangement starts to feel less temporary.
Eventually, some parents decide it’s time for their adult child to move out, and not every child agrees. Arguments flare up, deadlines get ignored, and the house that once felt like home starts to feel like a standoff between generations.
The answer often depends on the details of the living situation. If an adult child pays rent, signed a lease, or has an agreement to live in the home, they may be treated much like any other tenant under Texas law.
Even without formal rent, regular payments toward bills or household expenses can blur the lines. Courts may look at what the parties agreed to, whether money changed hands, and how long the child has been living there. Informal arrangements can still carry legal weight.
An adult child who lives at home without paying anything may still have some protections as an occupant. Their exact status depends on the facts and applicable law, which is why parents shouldn’t assume the legal relationship is the same as the family one.
Why parents can’t always just change the locks
Changing the locks, removing someone’s belongings, or shutting off utilities can feel like a quick solution. In many situations, though, these self-help tactics can create legal problems for parents, especially if the adult child is considered a tenant or lawful occupant.
Texas law restricts lockouts and other forms of forced removal from a residence. Parents who skip proper procedures may face claims for damages, and the situation can escalate quickly into police calls and even more family conflict.
The correct approach depends on the adult child’s status and the specific circumstances. Situations involving threats or family violence may involve different legal tools entirely. When in doubt, following an established legal process is far safer than acting alone.
What does the legal removal process actually look like?
The process often starts with written notice. Texas generally requires a notice to vacate before an eviction case can be filed, and the timing and delivery method can depend on any agreement between the parties and current law.
If the adult child doesn’t leave, parents may need to file an eviction case, usually in a justice court. A judge hears the case, and if the parent wins, the court can issue a judgment for possession of the home.
If the adult child still won’t leave after the judgment, a writ of possession may allow a law enforcement officer to oversee the removal. Choosing the correct procedure from the start helps avoid delays, dismissals, and having to start over.
How to handle the situation without making a family conflict worse
Clear written expectations can help prevent misunderstandings. A simple document outlining a move-out date, contributions to expenses, and house rules gives everyone the same reference point and reduces arguments about who said what. Putting it in writing also shows the request is serious.
Reasonable timelines make a difference too. Offering enough time to find housing, save money, or arrange a move can lower tension. Some families find that mediation helps them reach an agreement without the stress of going to court.
Documentation matters throughout the process. Keeping copies of notices, messages, and agreements protects both sides if things escalate. Staying calm and respectful, even when frustration runs high, can preserve the relationship long after the living arrangement ends. That matters more than winning any single argument.
Conclusion
Asking an adult child to move out can be one of the hardest conversations a parent ever has. It’s emotionally complicated, and it can become legally complicated too, especially when rent, agreements, or longtime occupancy are involved.
Owning the home doesn’t automatically allow immediate removal. An adult child’s legal status shapes the process, and skipping steps like proper notice or court proceedings can create new problems instead of solving the old ones. Patience at this stage usually pays off.
Following applicable procedures protects everyone involved. When questions come up about notice requirements, eviction steps, or a particular family situation, a qualified attorney can explain the options that fit, since every household and every outcome is different.
A fifty tucked inside a birthday card, folded into a wallet pocket for months, maybe years, before anyone spends it. Fifty-dollar bills live differently than twenties. People hold onto them longer, tuck them into books and envelopes, pass them down instead of running them through a register every week. That habit alone means more old fifties have survived in good condition than you’d expect.
It also means the denomination carries its own quirks. Fewer fifties get printed each year than tens or twenties, so a fancy serial number or an odd print quirk that’s fairly ordinary on a smaller bill is scarcer here and worth more. Grant’s portrait has looked out from this bill since 1929, through a design that barely changed for most of a century, which makes it easy to miss a bill that’s actually from an earlier, scarcer run.
None of this requires a safe deposit box. Most of what follows is still something you could plausibly find in an inherited envelope of cash, a forgotten gift, or the bottom of a cash box nobody’s opened in years.
1. $50 bill with a radar or repeater serial number
Image Credit: Heritage Auctions
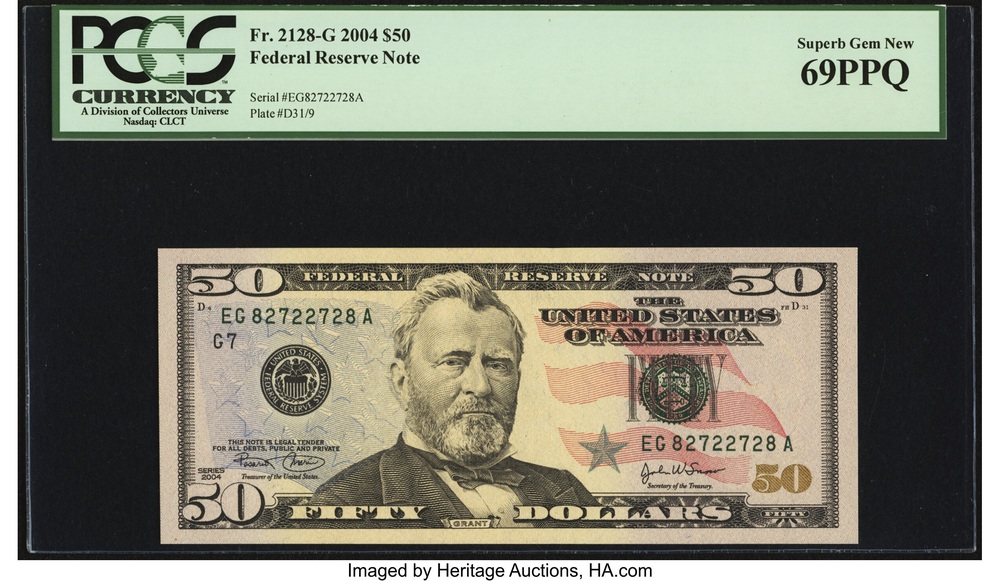
Every bill carries an eight-digit serial number, and collectors sort them into the same handful of categories regardless of denomination. A radar reads the same forward and backward, something like 61455416. A repeater splits into two identical four-digit halves, like 38273827.
What’s different on a fifty is the math behind it. Fewer $50 bills get printed each year than ones, fives, tens, or twenties, so an unusual pattern on a high denomination is mathematically scarcer than the identical pattern on a one, and currency specialists consistently point to higher-denomination notes as the stronger pick when the pattern itself is otherwise equal. Plain radars typically bring $20 to $150, and a super radar, where only the two middle digits differ, can reach $75 to $400 in crisp condition, with repeaters following a similar scale.
Check the eight digits only, ignoring the prefix and suffix letters. Condition matters enormously here, since a folded, well-circulated fifty with a great serial number sells for a fraction of a crisp one pulled straight from a bank strap.
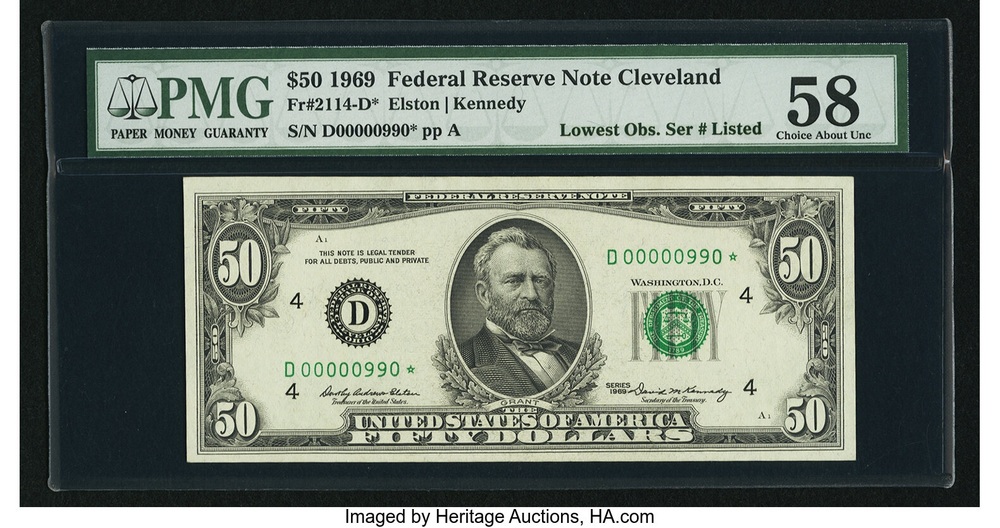
2. $50 bill with a low serial number
Image Credit: Heritage Auctions
Every new series restarts its serial numbers at 00000001, and the very first notes off a given press run rarely make it into general circulation. Most get pulled aside for bank officials, ceremonial purposes, or collectors before they ever reach a cash drawer.
A handful still slip through.Numbers from 00000010 through roughly 00000099 typically bring $50 to $300, and anything under ten is a genuine trophy that can bring several hundred to several thousand dollars depending on series and condition. On a fifty specifically, the premium tends to sit toward the higher end of these ranges compared with a one or a five, since so few low-numbered fifties were saved relative to smaller bills.
The catch is proving which series and district you have, since a low serial number only matters within its own combination of the two. Pair the serial with the series year printed in small type near the portrait before assuming anything. A worn, common series with an unusually low number still won’t bring much if the series itself was printed in huge volume.
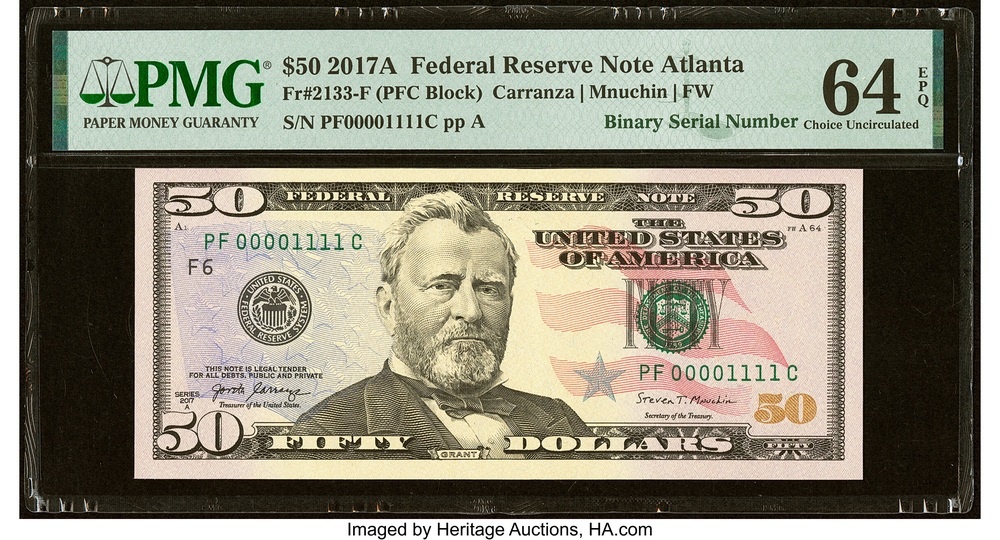
3. $50 bill with a solid, ladder, or binary serial number
Image Credit: Heritage Auctions
Beyond radars and repeaters, serious serial-number collectors chase a smaller group of rarer patterns. A solid repeats one digit eight times, like 33333333. A ladder runs in strict sequence, either direction, like 23456789. A binary uses only two digits throughout the whole number, in any combination.
Solids are the scarcest of the bunch and bring $1,000 to $4,000 in strong condition, since the odds of a press landing on eight identical digits are vanishingly small regardless of denomination. Binaries are more forgiving to find and typically bring $20 to $75, with true ladders falling somewhere in between depending on how clean the sequence is.
These patterns are easy to overlook at a glance, since a number like 23456789 doesn’t announce itself the way a run of eights does. Read all eight digits slowly before spending an unusual fifty, and remember the pattern has to be exact. A near-ladder with one digit out of sequence is just an ordinary bill, no matter how close it looks.
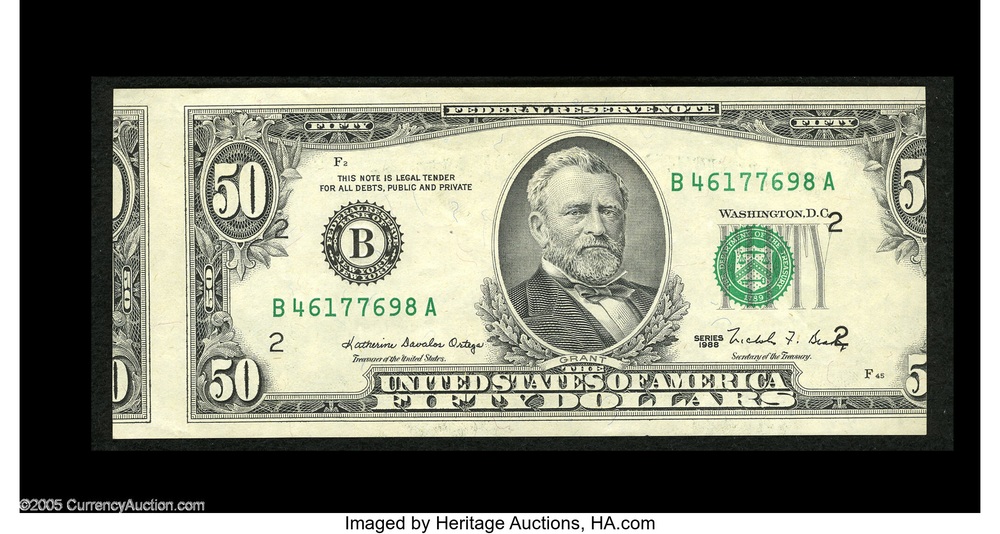
4. $50 bill with an ink smear or off-center printing error
Image Credit: Heritage Auctions
Modern currency is printed with extraordinary consistency, but with billions of notes produced every year, something occasionally goes wrong on the press. The most common results are ink smears, where loose ink transfers onto the paper, and off-center or misaligned overprints, where the seal and serial numbers land noticeably closer to one edge than they should.
Common ink smear and misalignment errors typically trade in the $50 to $300 range on an ordinary note, but dramatic over-inking or a badly shifted overprint on a higher-denomination bill like a fifty tends to command a stronger premium than the identical error on a one or a five, since error collectors weigh face value into what they’re willing to pay.
Genuine errors happen inside the Bureau of Engraving and Printing, not after the bill leaves the building, so anything torn, stained, or altered later is just wear, not an error. Get a promising example certified by a professional grading service before selling it. An authenticated error carries far more weight with serious buyers than an unverified claim, especially at this denomination.
5. $50 star note from a documented low print run
Image Credit: Heritage Auctions
A star at the end of the serial number marks a replacement note, printed when a damaged or misprinted sheet needed to be pulled from the regular run. Replacement notes get their own separate, usually much smaller print run, tracked by series and district.
Fifty-dollar star notes start from a smaller baseline than smaller bills simply because fewer fifties are printed overall, so a documented low run carries real weight here. Pre-1950 Federal Reserve Note stars can bring $50 to $1,500 or more in strong condition, and even a modern star from a genuinely small run can clear a real premium in crisp, uncirculated shape.
The single biggest mistake is assuming any star automatically means value. Look up the specific print run for your series, district letter, and serial block before getting excited, since plenty of stars come from runs in the millions and are worth nothing extra. Condition and print-run size both have to line up before a star note is worth setting aside.
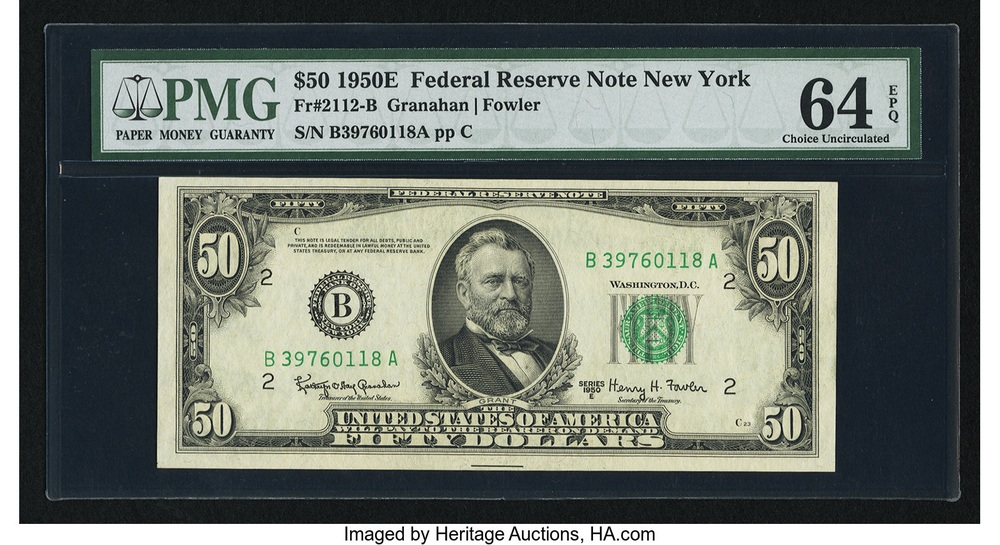
6. 1950E $50 Federal Reserve Note
Image Credit: Heritage Auctions
The 1950E series was the last of the “wide” small-size $50 design before the Federal Reserve moved to the modern layout, and it was printed from only three Federal Reserve districts, New York, Chicago, and San Francisco, in notably smaller numbers than the sub-series that came before it.
That limited distribution shows up clearly in the pricing. New York examples typically bring $135 to $300, Chicago notes run $160 to $700, and San Francisco issues land around $135 to $425, with the scarcer Chicago star-replacement version reaching $1,000 to $1,750 and the New York star climbing even higher in top grade.
Check the series designation printed in small type near the portrait, since 1950E looks nearly identical to the far more common 1950 through 1950D notes that preceded it at a casual glance. Only three districts ever issued this sub-series, so confirming both the series letter and the Federal Reserve Bank seal is the only reliable way to tell an ordinary fifty from one worth real money.
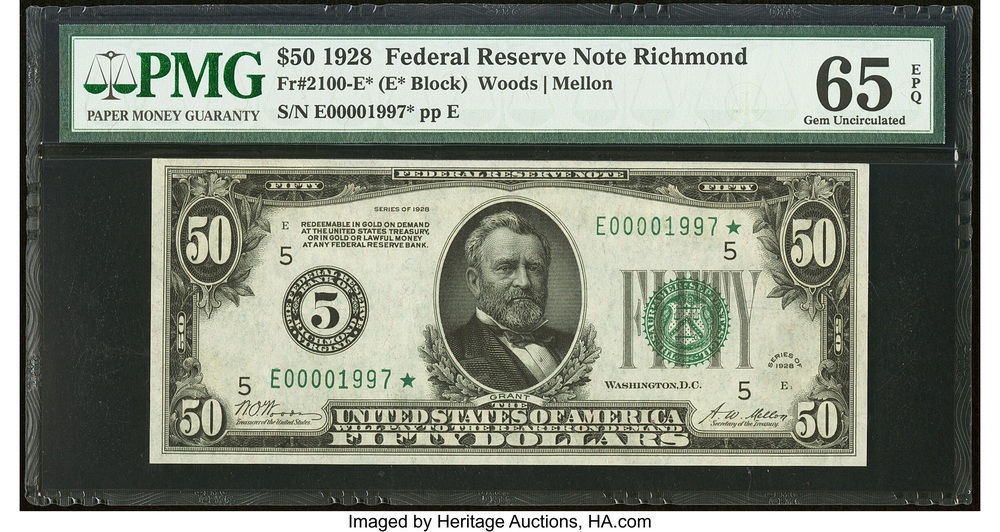
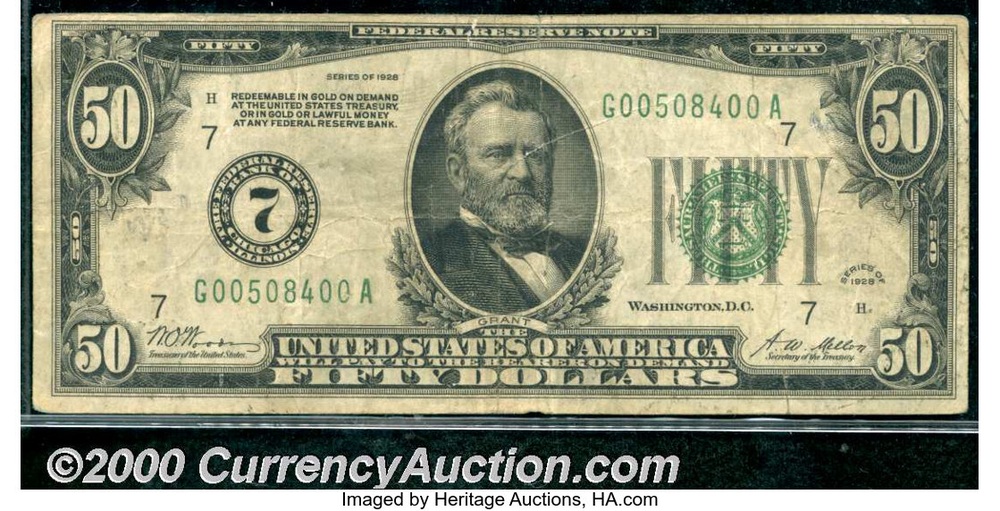
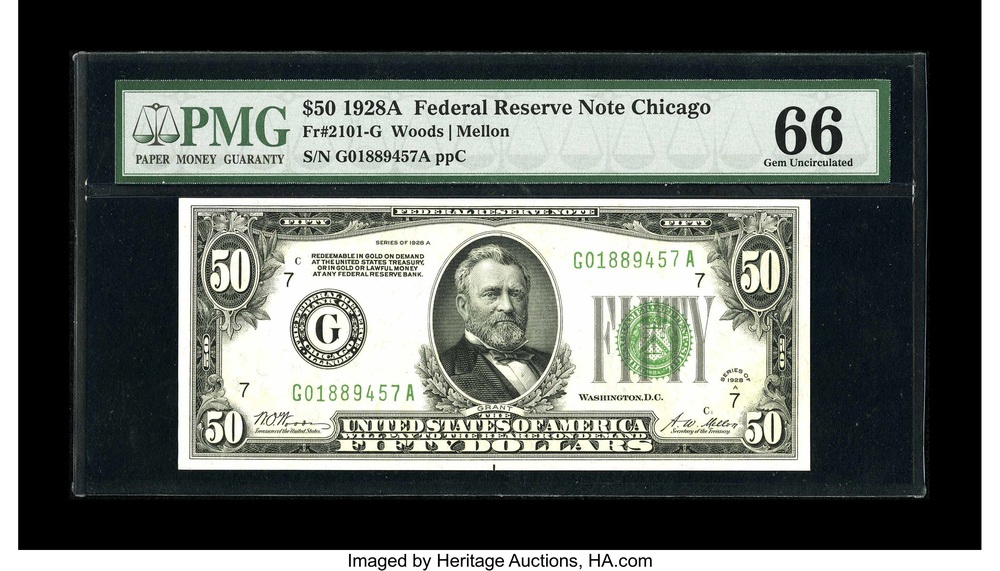
7. 1928 $50 Federal Reserve Note
Image Credit: Heritage Auctions
The 1928 series marked the first small-size $50 bills, shrunk down to the size still used today, and it’s the first series to carry the phrase about redemption in gold printed across the top, a holdover from a monetary policy that didn’t survive the 1930s.
Most circulated examples are genuinely affordable for a note this old.Typical circulated notes bring $70 to $600 depending on district and condition, with crisp uncirculated examples reaching $400 to $600 in the more common districts.
Grant’s portrait and the plain green Treasury seal are the quickest way to confirm you have an ordinary Federal Reserve Note rather than the gold-seal certificate from the same era, which looks similar at a glance but carries a different value entirely. Paper this old is often brittle at the folds, so handle it by the edges and store it flat if you plan to keep it rather than sell it.
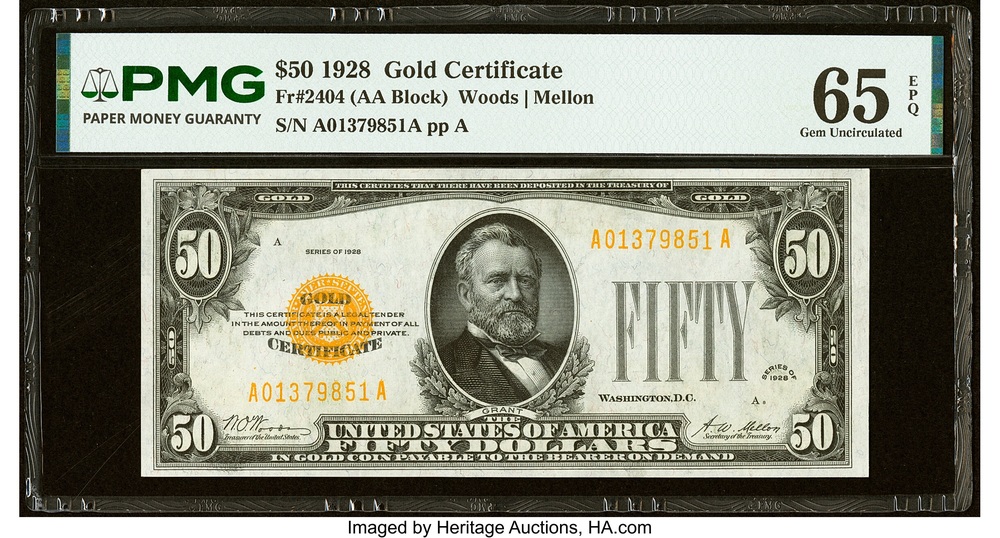
8. 1928 $50 gold certificate
Image Credit: Heritage Auctions
Gold certificates were a different animal entirely: a promise printed on paper that the US Treasury would hand over the bill’s face value in actual gold coin on demand. The 1928 small-size $50 is identified by its bright yellow-gold Treasury seal in place of the familiar green.
Most gold certificates were turned in and destroyed after the government recalled private gold ownership in 1933, part of why even a common series like this one carries a real premium over face value. The full range runs from roughly $185 in worn circulated condition up to $17,000 for an exceptional, high-grade example.
The yellow seal and yellow serial numbers are the fastest way to confirm what you have, since the portrait and layout otherwise look nearly identical to an ordinary Federal Reserve Note. Watch for staining and soft, re-folded corners, both common on notes this age, and don’t confuse an ordinary circulated example with the far scarcer star-replacement version, which commands a dramatically different price on its own.
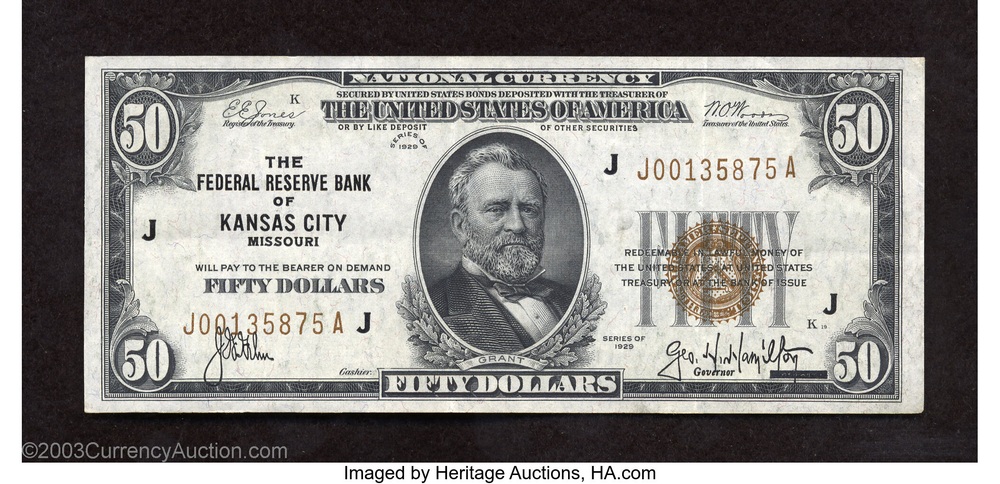
9. 1929 $50 Federal Reserve Bank Note
Image Credit: Heritage Auctions
Not to be confused with the ordinary Federal Reserve Note, this is a separate category issued only in 1929 and backed by a single Federal Reserve Bank rather than the system as a whole. It’s identified by its brown seal and serial numbers, a design holdover from the National Bank Notes it was printed alongside.
These notes were an emergency measure, rushed into circulation during the early banking crisis of the Great Depression, and all small-size $50 Federal Reserve Bank Notes were printed in relatively low numbers to begin with. Circulated examples typically bring $160 to $250 depending on condition and district, with higher grades reaching $650 to $850 or more.
Ulysses S. Grant’s portrait and the brown seal are the fastest way to identify one of these. Watch for soft corners and center folds, which are common on a note this old that circulated hard before most examples were pulled from use. A crisp, well-centered example is worth noticeably more than a worn one with the same district letter.
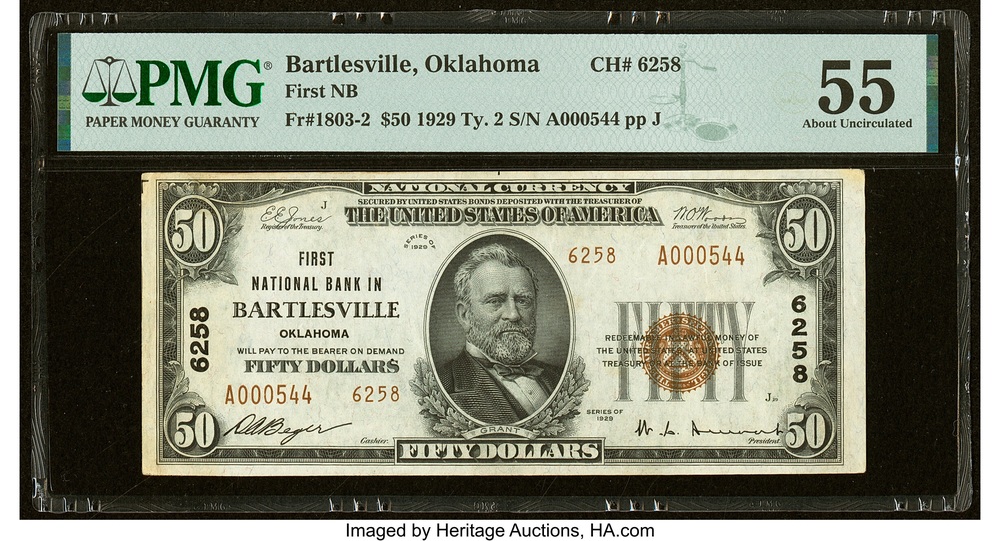
10. Small-size $50 National Bank Note
Image Credit: Heritage Auctions
Until 1935, individual banks across the country could issue their own currency, backed by government bonds and overprinted with the local bank’s name. The small-size versions, issued from 1929 until the program ended, look almost like an ordinary Federal Reserve Note at a glance, with the bank’s name and location printed across the top instead of “Federal Reserve Bank.”
Typical examples bring $30 to $800 depending on condition and issuing bank, and specific National Bank issues, particularly those tied to a small-town or now-defunct bank, can be worth considerably more once a collector who specializes in that state or that bank gets involved.
Check the bank name and charter number printed on the face, then look up how many notes that specific bank issued at that denomination before deciding it’s common. High-denomination notes like fifties were requested far less often than fives and tens by most small-town banks, which makes a surviving $50 National genuinely scarcer within its own bank’s output than the same bank’s smaller bills.
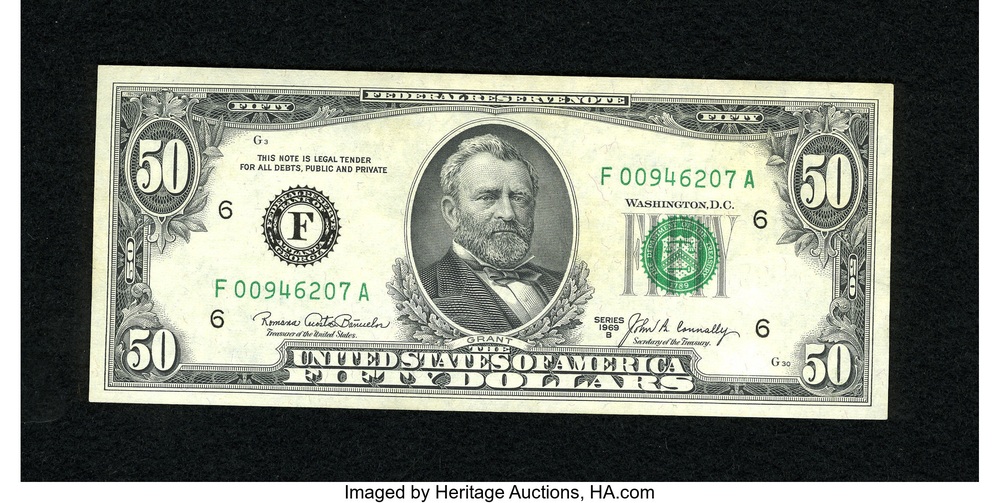
11. 1969B $50 Federal Reserve Note
Image Credit: Heritage Auctions
Most late-twentieth-century $50 bills are common enough to be worth exactly face value, but the 1969B sub-series breaks that pattern. It was printed in notably smaller numbers than the series around it, and the gap shows up clearly once you compare the pricing.
Regular 1969B examples typically bring $225 to $900 depending on district and condition, with the scarcest districts reaching toward $2,500 in top grade, and the star-replacement version of the same sub-series commands $1,250 to $2,500 across the board.
The series designation sits in small type near the portrait, easy to miss if you’re not specifically checking for it, since a 1969B fifty looks identical to an ordinary 1969 series bill at a glance. Most people who find one have no idea they’re holding anything other than face value. A careful look at that series letter is the entire difference between an ordinary fifty and one worth real money.
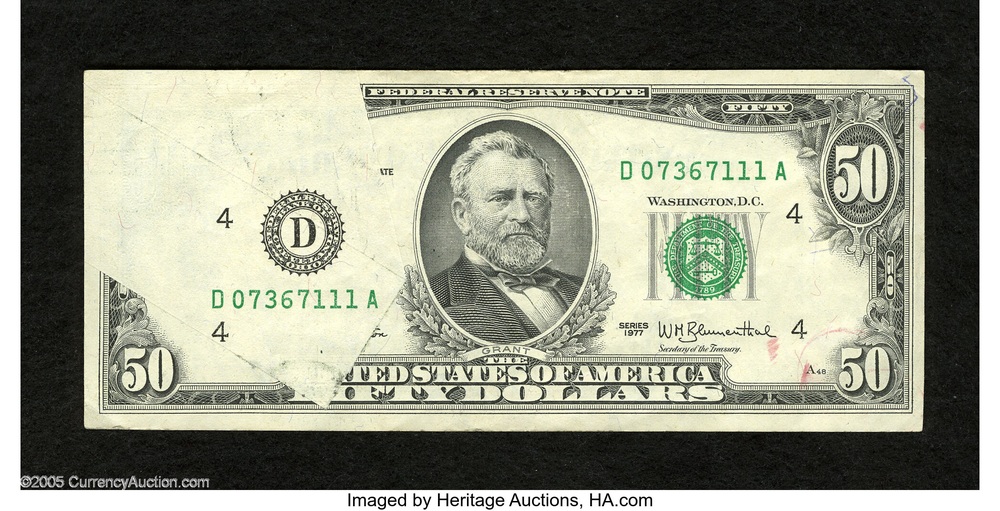
12. $50 bill with an obstructed or foreign-object printing error
Image Credit: Heritage Auctions
This is the rarest and strangest category of currency error: something physical, a scrap of paper, a sticker, a piece of tape, gets caught between the printing plate and the sheet during one of the three production stages. The object blocks ink from reaching that part of the paper, leaving an unprinted void in its exact shape, sometimes with the object itself still stuck to the note.
These are genuinely uncommon finds, but modest examples do surface and trade in the market. Collectors typically start building this category in the $100 to $500 range for a certified example, and a dramatic obstruction on a high-denomination note like a fifty tends to outperform the same error on a smaller bill, since face value factors into what serious buyers will pay.
Authentication matters enormously here, since the premiums involved have made fabricated obstruction errors a real problem in the hobby. A legitimate example should show genuine ink voids with sharp, consistent edges, not something that looks chemically treated or trimmed after the fact. Submit anything promising to a professional grading service before assuming you’ve found something significant.
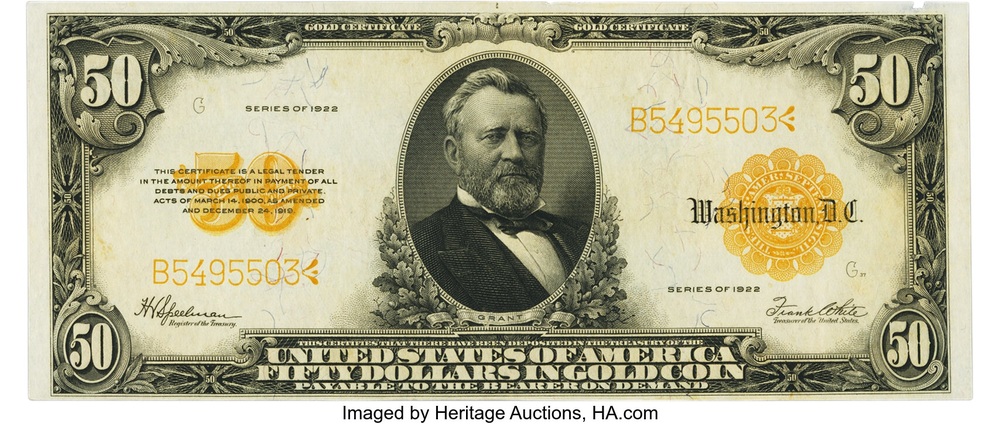
13. 1922 $50 gold certificate
Image Credit: Heritage Auctions
Before small-size notes arrived in 1928, gold certificates came in the larger “horse blanket” format used for all US currency through the 1920s. The 1922 series is the more available of the large-size $50 gold certificates, which makes it the more realistic entry point into the category for anyone without a specialist’s budget.
Even the more available version is still a genuinely scarce note next to an ordinary modern bill, since most large-size gold certificates were destroyed along with their small-size successors. Clean circulated examples typically run $300 to $7,500 depending on condition and specific Friedberg variety, with a scarcer sub-variety reaching considerably higher in top grade.
Look for the gold-colored seal and serial numbers that mark every note in this category, set against the larger physical dimensions common to all large-size currency, nearly an inch bigger in each direction than a modern bill. Fold lines and center wear are common on survivors this old, and a crisp, bright example is worth meaningfully more than a soft, repeatedly handled one.
14. 1928A $50 Federal Reserve Note
Image Credit: Heritage Auctions
Most 1928-series fifties are affordable, but the lettered sub-series that followed tells a different story. The 1928A designation, marked by a small letter next to the series year, was issued in smaller numbers than the plain 1928 series it replaced, and certain districts within it are considerably scarcer than others.
The full range runs from $60 in heavily worn condition up to $2,450 for a crisp uncirculated example, with a handful of specific district and plate combinations reaching higher still in top grade. That’s a dramatically wider spread than the baseline 1928 series covered earlier on this list.
The letter suffix sits directly after “1928” in the small series designation near the portrait, easy to miss if you’re not specifically checking for it. Most people who find one of these have no idea what they’re holding, since the bill looks identical to an ordinary 1928 fifty at a casual glance. A magnifying glass and a careful look at that one small letter makes the entire difference in value.
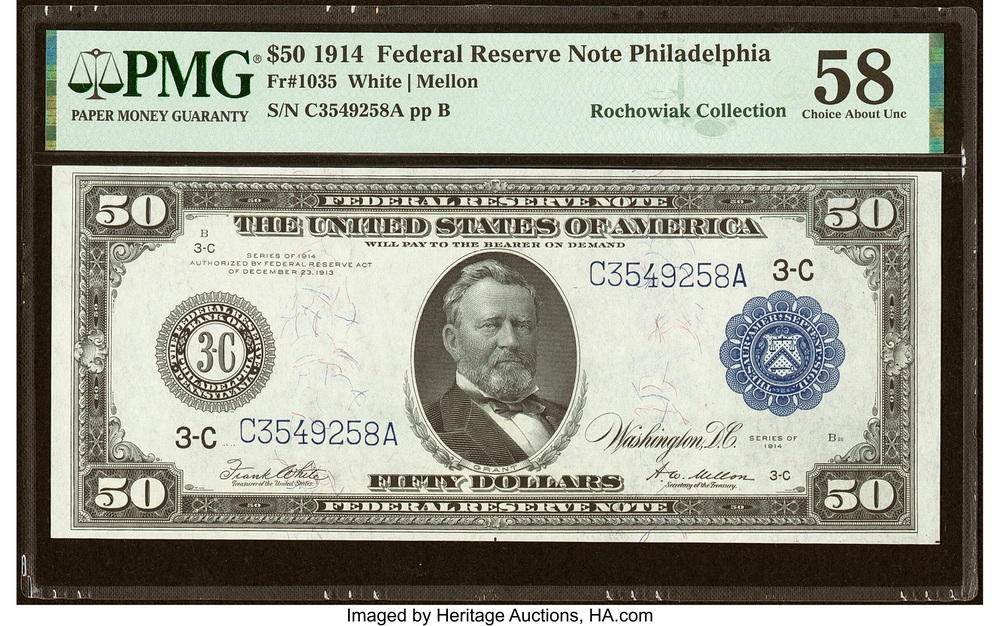
15. 1914 large-size $50 Federal Reserve Note
Image Credit: Heritage Auctions
The 1914 series was the first issue of Federal Reserve Notes, created the year after the Federal Reserve itself was established, and it came in two distinct versions. An early red-seal printing, issued in runs as small as 8,000 to 80,000 notes depending on district, was quickly replaced by the far more common blue-seal version that continued for the rest of the large-size era.
The blue-seal 1914 fifty is genuinely findable and typically brings $500 to $900 in very fine condition depending on district and grade, while the red-seal version, scarce enough that surviving examples are tracked individually by specialists district by district, commands a significant multiple of that at every grade level.
The seal color is the fastest way to sort one from the other. These notes also measure noticeably larger than a modern bill, almost an inch bigger in each dimension, which is often the first clue that you’re holding something older than typical pocket change. Grant’s portrait appears here too, decades before it settled permanently onto the small-size fifty.
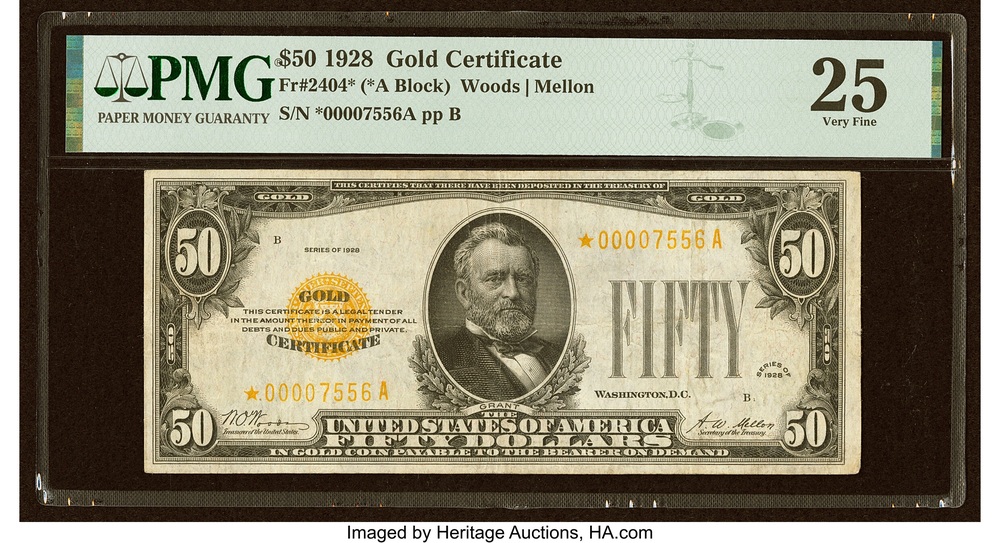
16. 1928 $50 gold certificate star note
Image Credit: Heritage Auctions
Every category of currency has a replacement-note version, printed when a damaged sheet needed to be pulled and swapped out during production, and gold certificates are no exception. A star at the end of the serial number marks these replacements, and on an already-scarce series like the 1928 $50 gold certificate, that star multiplies the rarity considerably.
Replacement gold certificates were printed in far smaller numbers than their regular counterparts to begin with, since fewer defective sheets needed replacing than complete runs required. The full range for a 1928 star-replacement $50 gold certificate runs from roughly $1,200 in heavily circulated condition up to $170,000 for a pristine, high-grade example, a dramatically wider spread than the plain non-star version covered earlier on this list.
The star sits at the very end of the serial number, easy to overlook next to the far more eye-catching yellow seal that already marks the note as a gold certificate. Anyone sorting through inherited currency should check every gold-seal fifty for that symbol specifically, since the difference between an ordinary 1928 gold certificate and its star-replacement counterpart is a single character that completely changes the value math.
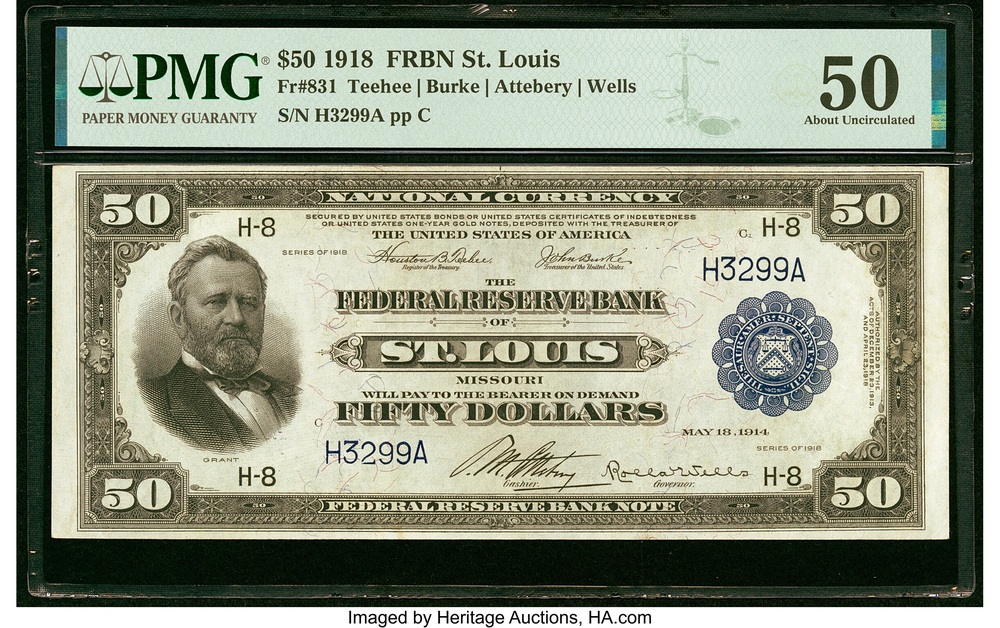
17. 1918 $50 Federal Reserve Bank Note
Image Credit: Heritage Auctions
The 1918 $50 Federal Reserve Bank Note is a large-size issue with an unusually narrow origin: St. Louis was the only Federal Reserve district to issue it, and just 4,000 were produced. That makes it a distinct collecting target rather than simply another old fifty with a different district letter.
A surviving example graded PMG About Uncirculated 50 sold for $31,200 at Heritage Auctions on October 10, 2025. That is a documented result for one particular note, not a promise that every example will bring the same amount. Condition, repairs and the quality of the paper all affect what collectors will pay.
Look for the 1918 series date and the St. Louis Federal Reserve Bank wording on the face. It is different from both the 1914 Federal Reserve Note and the smaller 1929 Federal Reserve Bank Note elsewhere on this list. If one turns up in a family collection, professional authentication is a sensible first step before assigning it a value.
18. Large-size $50 National Bank Note
Image Credit: Heritage Auctions
Before the small-size notes of 1929, individual banks issued their own currency in the larger “horse blanket” format, prominently engraved with the bank’s own name. Fifty-dollar denominations within this category are considerably scarcer than the $5 and $10 notes the same banks issued, because the Treasury printed $50 and $100 notes together on shared sheets, and most banks simply never ordered them.
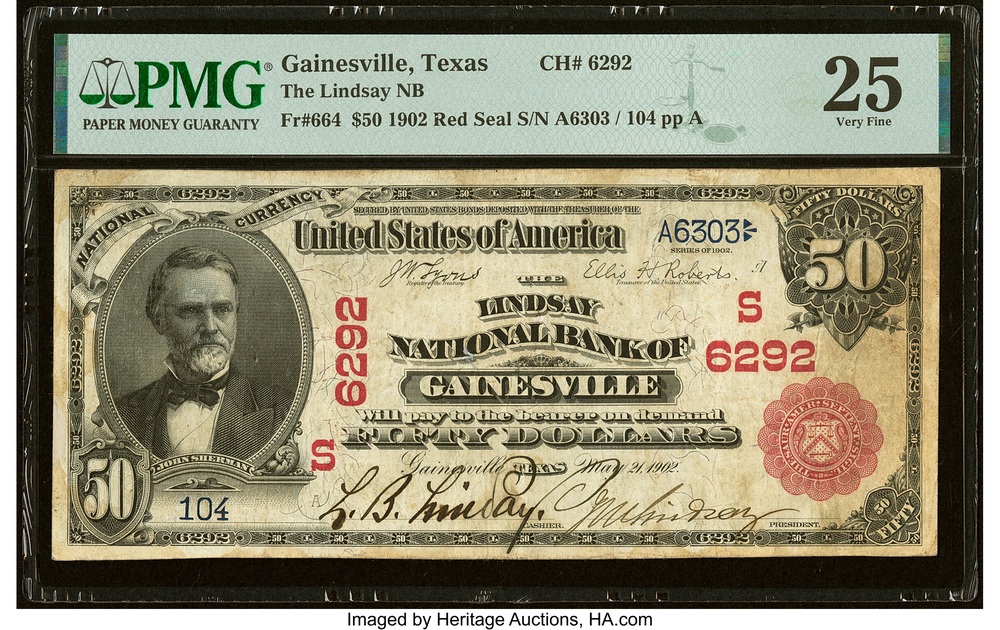
The more available blue-seal 1902 series typically brings $750 to $1,250 in clean circulated condition for a well-known bank. The earlier red-seal version of the same series is dramatically scarcer; specialists estimate only around 100 examples survive across every bank that ever issued one, which pushes value well beyond the blue-seal range for any confirmed example.
Seal color is the fastest way to sort the two apart, with red seals predating blue. As with any National Bank Note, the issuing bank matters as much as the series. A note from a well-documented city bank is a different animal from one tied to a small-town bank that issued only a handful of high-denomination sheets, even when both look similar at a glance.
As user demand surges, digital platforms must modernize backend systems to avoid performance bottlenecks. This transformation protects uninterrupted uptime for enterprise customers.
Rapid growth tests your SaaS platform in ways early prototypes never anticipated. When operational data expands rapidly, customer transactions multiply, and background jobs pile up, database responsiveness drops fast. Enterprise accounts expect seamless reliability, making high availability and peak performance strategic priorities for your leadership team.
Scaling past this inflection point requires more than simply paying for larger server instances. You need a clear look at how your data tier handles pressure and where structural updates yield lasting returns.
Why does early database design break under enterprise scale?
Your initial architecture worked well when your platform served dozens of steady accounts. Back then, simple table relationships and default cluster settings met every latency target without friction. Heavy enterprise usage completely alters that picture with concurrent write bursts, massive reporting queries, and complex tenant filters.
Researchers at the USC Viterbi School of Engineering point out that modern data systems struggle to maintain real-time performance as data volumes and workloads expand exponentially. Memory limits shrink under peak load, while unoptimized cache configurations force disks to handle excess traffic. Once standard queries begin to stall, your entire product experience degrades across user sessions.
Where do latency spikes and storage bottlenecks hide?
Bottlenecks rarely announce themselves with complete system crashes. Instead, subtle delays creep into primary workloads through locking contention, connection pooling starvation, and bloated write-ahead logs. Your engineering team might notice dashboard widgets taking 3 extra seconds to load during morning peak hours.
Identifying hidden storage friction
Write amplification often builds behind the scenes when tables hold millions of records. High write volumes cause indexes to fragment, which forces memory managers to swap pages constantly. Tracking table bloat and connection exhaustion early helps your team isolate trouble spots before customers submit support tickets.
Query execution plans and disk I/O metrics can reveal inefficiencies that standard performance dashboards often overlook. Regularly reviewing these indicators helps engineers detect unnecessary data scans, excessive disk reads, and slow storage operations before they affect application responsiveness.
When should you seek specialized infrastructure support?
Growing SaaS companies often expect internal application developers to manage complex relational clusters. Product engineers excel at shipping user features, but deep database diagnostics require distinct domain expertise.
Your internal developers already juggle aggressive product roadmaps and release cycles. Turning to experienced Postgres consulting services gives your platform direct access to deep performance tuning without pulling staff away from core features. These specialists examine your query planners, connection poolers, and replication topology under live traffic loads. That direct guidance maintains cluster stability during traffic spikes and high-stakes enterprise onboarding.
How can you streamline queries to reclaim system speed?
Query inefficiency wastes valuable CPU cycles and chokes connection pools faster than raw data volume. Many web frameworks produce bloated queries that pull entire rows when your interface only needs 2 columns. You can eliminate massive computational waste by auditing database activity and pruning heavy operations.
Applying structured tuning practices keeps your query engine fast and predictable:
Audit slow log patterns: Review statements taking longer than 100 milliseconds during daily peak hours.
Eliminate redundant joins: Remove unused table relations that burden memory buffers on heavy reporting views.
Build targeted indexes: Add composite indexing on frequently filtered columns to avoid full table scans.
What cloud database approaches reduce engineering strain?
Scaling your storage layer manually requires continuous monitoring of hardware health, failover orchestration, and backup validations. Many engineering leads choose managed database environments so their teams can offload low-level operational overhead.
Research from the University of San Diego shows the managed cloud database market expanding from $17.2 billion in 2023 to $66.46 billion by 2030. This surge reflects how modern SaaS providers rely on automated patching, instant replicas, and elastic provisioning. Shifting routine maintenance to specialized platforms gives your developers more room to build high-value software features.
How do modern teams build long-term architectural resilience?
Sustaining rapid business growth demands proactive architectural choices rather than reactive bug fixes. You should separate analytical reporting workloads from your transactional write paths using read replicas and event streaming. Isolating heavy batch processes prevents background jobs from interrupting real-time customer actions.
Regular load testing and automated alerting establish a safety buffer around your production data tier. When you benchmark clusters against simulated traffic jumps, your team uncovers structural limits on your own terms. Building this level of stability keeps enterprise buyers confident in your software capabilities.
Image Credit: san0198 via Pixabay
Keeping your database healthy is an ongoing discipline, not a one-time project. High-growth software demands active workload tuning, disciplined indexing, and skilled technical partnerships to stay fast. When you invest in your data foundations early, your platform scales smoothly, customer trust remains high, and your engineering team stays focused on product innovation.