scroll top

An extra $100 landed in your lap this month. Maybe it was a tax refund that came in higher than expected, a refund from a cancelled subscription, something you sold on Facebook Marketplace, or just a grocery bill that came in lighter than usual. Whatever it was, you have a little breathing room you didn’t have last month.

A hundred dollars doesn’t feel like much on its own, especially with rent, groceries and gas all costing more than they did a few years back. But where that money goes matters more than how much of it there is. Park it in the wrong place and it quietly disappears into a tank of gas and a couple of takeout orders. Put it somewhere specific and it actually does something for you.

None of the moves below require you to have your whole financial life sorted out first. Some take five minutes online. A few take a phone call. All of them beat leaving the money sitting in checking, where it earns nothing and gets spent on whatever’s convenient.

Pay down the credit card charging you the most interest
Credit cards resting on US dollar banknotes
Image Credit: Shutterstock

If you’re carrying a balance on more than one card, this is almost always the highest-return move on the list. Credit card companies are charging cardholders who carry a balance an average interest rate above 22%, and plenty of store cards and subprime cards run well past 29%. No savings account, CD or index fund is going to beat a guaranteed 22% to 29% return, which is effectively what you get by not paying that interest anymore.

Put the $100 toward whichever card has the highest rate, not the lowest balance. That’s the avalanche method, and it saves more in interest over time than knocking out your smallest debt first for the psychological win. If you only have one card, it’s an easy call. If you have three or four, pull up the actual rates before you decide where the money goes, because a 19% card and a 27% card cost you very different amounts on a balance that sits for months.

If your card is already maxed out and the minimum payment is the real problem, a one-time $100 payment won’t fix that on its own. In that case, it’s worth a call to the card issuer about a hardship plan or a lower rate before the next statement cuts, rather than treating this as the whole solution.

Move it into a savings account that actually pays you
Notebook labeled Best High-Yield Savings Accounts beside a calculator and piggy bank
Image Credit: Shutterstock

The average traditional savings account is paying 0.38% in interest, which on $100 works out to a few cents a year. Meanwhile, the top online high-yield savings accounts are currently paying up to 4.35% APY, more than ten times as much, for the exact same safety and FDIC insurance.

Opening one takes about ten minutes: most online banks just need your ID, your Social Security number and a linked checking account to transfer from. There’s no reason to keep an emergency fund, or the start of one, sitting in a checking account that pays nothing when a high-yield account costs you nothing extra and pays real money. If you don’t have three to six months of expenses saved somewhere accessible, this $100 is a perfectly good start, and it compounds every month after that. Some online banks also run new-account bonuses worth $100 or more just for opening an account and setting up a direct deposit, which stacks on top of the higher rate instead of replacing it.

Buy a few shares of a low-cost index fund
Stacks of coins with a globe and stock market chart overlay
Image Credit: Shutterstock

You don’t need thousands of dollars or a finance degree to start investing. Most major brokerages, including Fidelity, Schwab and Vanguard, let you buy fractional shares, so $100 buys you a real stake in a fund that tracks the S&P 500 or the total U.S. stock market instead of one single, riskier company.

The point of an index fund isn’t to get rich off $100. It’s to get the habit started while the amount is small and the stakes are low. Money in a taxable brokerage account isn’t locked up the way retirement money is, so it stays available if you actually need it, but it also isn’t meant to be touched for at least five years if you want a real shot at riding out the market’s ups and downs. If you already have a workplace 401(k) with an employer match you’re not fully using, that match beats a brokerage account every time, since it’s free money before the investing even starts.

Add it to your Roth IRA
Roth IRA paperwork with a calculator, pen and glasses
Image Credit: Shutterstock

For 2026, Roth IRA contributions are capped at $7,500, or $8,600 if you’re 50 or older, as long as your income falls under the limit for your filing status. That’s $7,500 of room you’re probably not filling, and $100 toward it costs you nothing in taxes now and nothing in taxes later, since qualified withdrawals in retirement come out completely tax-free.

A Roth IRA isn’t a separate investment, it’s a tax wrapper you put investments inside, so once the money lands in the account you still need to choose something to put it in, usually a target-date fund or an index fund. Most major brokerages will open one with no minimum balance. If you’re self-employed or your income is irregular, a Roth is one of the few accounts where contributing a little whenever you have it, rather than on a fixed schedule, works perfectly fine.

Stash it in your HSA if you have one
HSA enrollment form beside a pink piggy bank, dollar bills and a pen
Image Credit: Shutterstock

A health savings account tied to a high-deductible health plan has 2026 contribution limits of $4,400 for individual coverage and $8,750 for family coverage. An HSA is the only account in the entire tax code that’s tax-free going in, tax-free growing, and tax-free coming out, as long as the money goes toward qualified medical expenses.

Most people never come close to maxing it out, so $100 toward this year’s limit is an easy add. Unlike a flexible spending account, HSA money never expires and never has to be spent by December 31, so it can sit and grow for decades if you don’t need it right away. If you’re healthy now and can afford to pay small medical bills out of pocket instead of from the HSA, keeping receipts and reimbursing yourself years later, once the balance has grown, is a legitimate strategy some people use to treat it almost like a second retirement account.

Make a principal-only payment on your mortgage or car loan
making a payment on mortgage
Image Credit: Shutterstock

An extra $100 applied specifically to principal, not the regular payment, shaves interest off the entire remaining life of the loan. On a mortgage, that can mean shaving weeks or months off a 30-year term, since interest is calculated on the balance that’s left. On a car loan, where terms are shorter and rates are often higher, the effect shows up faster.

The important part is telling your lender the extra money is for principal only, not for next month’s payment in advance. Most lenders have a specific field for this on their online payment portal, and if you can’t find it, call and ask, because skipping that step means your $100 just prepays a future bill instead of cutting the balance. This move doesn’t make sense for everyone. If your loan rate is low, say under 5%, you’re usually better off putting the $100 somewhere it can earn more than your loan is costing you.

Buy a CD or an I bond instead of letting it sit
Wooden blocks spelling bonds beside US dollar bills and coins
Image Credit: Shutterstock

If you want a fixed, predictable return and you know you won’t need the money for a while, a certificate of deposit or a Series I savings bond beats a regular savings account. Top 12-month CDs are currently paying up to 4.35% APY, locked in for the full term regardless of what happens to rates afterward.

Series I bonds, bought directly through TreasuryDirect, are currently earning a composite rate of 4.26% on bonds issued through the end of October 2026, with a new rate announced every May and November. I bonds also adjust with inflation and are exempt from state and local income tax, which makes them a decent spot for money you’re saving for something specific, like a wedding or a down payment, that’s still a year or more out. The catch with both is access: a CD charges a penalty for early withdrawal, and I bonds can’t be cashed at all in the first 12 months, so this isn’t the place for your actual emergency fund.

Start a sinking fund for a bill you already know is coming
Hand holding a smartphone with online banking account options
Image Credit: Shutterstock

A sinking fund is just a savings account, or a named pocket inside one, for an expense you can see coming from months away: car registration, the holidays, a kid’s sports fees, your annual Amazon Prime renewal. Instead of that bill feeling like a surprise every single time, you’ve been quietly funding it for months.

Most online banks let you open multiple savings accounts or create labeled “buckets” within one account for free, so this $100 can become the seed money for “Christmas 2026” or “car registration” specifically. The psychological trick is real: money that’s labeled for a specific future bill is much harder to accidentally spend on something else than money that’s just sitting in a general savings account. Come December, or whenever the bill actually lands, you’re pulling from a fund you built on purpose instead of scrambling or reaching for a credit card. Run two or three of these at once, one for the holidays, one for car costs, one for whatever your household always seems to get hit with in the same month every year, and the whole category of “surprise” expenses stops being a surprise.

Get the car maintenance you’ve been putting off
Mechanic checking the oil dipstick under a car hood
Image Credit: Shutterstock

An overdue oil change, worn brake pads or tires that are down to the wear bars are the kind of small problems that turn into expensive ones. A $100 oil change and inspection now is the difference between catching a slow leak early and replacing an engine later, or between a $40 set of brake pads and a $400 rotor replacement because you drove on metal-on-metal too long.

This isn’t about babying a car, it’s about math. Preventive maintenance is cheap specifically because it’s preventive. Once a part fails instead of wearing down gradually, the repair bill usually includes labor for parts that were fine but got damaged by the part that wasn’t. If you don’t know what your car actually needs, most shops will do a basic inspection for free or close to it when you bring it in for something simple like an oil change, and they’ll tell you what’s actually urgent versus what can wait another few months.

Stock the freezer and pantry while staples are on sale
Woman opening a pantry stocked with jars, cartons and other groceries
Image Credit: Shutterstock

Grocery prices move constantly, and the staples you buy every single week, chicken, ground beef, rice, pasta, canned tomatoes, go on real sales on a predictable cycle even if the timing varies by store. An extra $100 spent stocking up when those items are actually cheap, rather than buying them one week at a time at whatever the current price is, functions like a discount on your future grocery bills.

This only works if you actually have freezer space and you buy things you’ll use. A deep discount on 10 pounds of a cut of meat your family won’t eat isn’t savings, it’s waste with extra steps. Focus the $100 on proteins that freeze well, pantry staples with a long shelf life, and anything your household already goes through regularly. Building up a two or three week buffer of staples also means a tight week, a lost shift, or an unexpected expense doesn’t automatically mean a thin grocery budget on top of everything else.

Cover the fee for a certification or license exam that pays off
Adults attending a class with an instructor
Image Credit: Shutterstock

Plenty of better-paying jobs are gated behind a single exam fee that costs less than $100: a forklift certification, an insurance producer license, a Series 65 for financial roles, a notary commission, a food handler’s card for a promotion into management. These aren’t side hustles that AI can replace next year, they’re credentials tied to a physical trade, a regulated license or a specific employer requirement.

Before spending the money, check with your employer or the specific job posting about what’s actually required, since some employers will reimburse the fee once you pass, effectively making it free. If you’re between jobs or job hunting, picking a credential that’s actually in demand in your area, not just the first one you find online, is worth ten minutes of research before you commit the fee. The $100 you’d spend otherwise, say, on a few nights out, disappears either way. Spent on an exam fee, there’s a real chance it comes back to you many times over in a higher hourly rate.

Knock out a payday loan or buy now pay later balance
Hand holding a smartphone with buy now pay later graphics
Image Credit: Shutterstock

If you have an outstanding payday loan, the interest is brutal enough that paying any of it down early is worth doing before almost anything else on this list. A typical payday loan carries an APR of close to 400%, which means a $100 payment toward the principal saves you real money within weeks, not years.

Buy now, pay later balances are usually interest-free if you pay on schedule, but miss a payment and plenty of them convert to a standard interest rate or tack on late fees that function the same way a payday loan does. If you’ve got several of these stacked across different apps, a late payment on one of the smaller ones is an easy thing to lose track of. Use the $100 to clear whichever balance is closest to a due date or carries the steepest penalty for missing it, not necessarily the smallest one.

Get your pet’s preventative care out of the way
Veterinary professional giving a ginger kitten a vaccination
Image Credit: Shutterstock

A routine vet visit, a round of vaccines, or a dental cleaning for a cat or dog costs real money, but it’s a fraction of what treating an advanced dental infection, heartworm, or a preventable illness costs once it’s gone untreated. $100 covers a decent chunk of an annual wellness exam or a vaccine booster at most vet clinics, and plenty of vets will let you put it toward a payment plan if the full visit costs more.

Pet insurance is a different conversation and depends heavily on the animal’s age and breed, but preventative care isn’t optional in the same way insurance is a choice. Skipping a $100 dental cleaning now because the pet “seems fine” is how a lot of owners end up facing a $1,500 extraction later, done as an emergency instead of scheduled in advance. If cost is the only thing standing between your pet and care, many areas have low-cost vet clinics or vet schools that offer the same services for less.

Put the $100 into home upgrades that actually lower your bills
Electrician fitting a thermostat to a wall
Image Credit: Shutterstock

A programmable thermostat, weatherstripping around drafty doors and windows, and swapping incandescent bulbs for LEDs are all upgrades you can buy for $100 or less that pay for themselves. The Department of Energy says setting your thermostat back 7 to 10 degrees for eight hours a day can save up to 10% a year on heating and cooling, and a programmable or smart thermostat does that automatically without you remembering to touch the dial every night.

Weatherstripping is the cheapest fix on this list, usually a few dollars a door, and it directly targets the draft that’s making your furnace or AC work harder than it needs to. LED bulbs cost more upfront than incandescents but use a fraction of the electricity and last years longer, so the $100 spread across a house full of bulbs keeps paying you back on every single electric bill after that, not just once.

Fund a 529 or custodial account for a kid in your life
Piggy bank wearing a graduation cap beside a jar labeled 529 Plan
Image Credit: Shutterstock

There’s no federal limit on 529 contributions, only a gift tax rule that kicks in above $19,000 per beneficiary per year in 2026, which means $100 fits in with plenty of room to spare. Money grows tax-free and comes out tax-free as long as it’s spent on qualified education expenses, and many states offer a state tax deduction on top of that for contributions made by residents.

If the goal is more general than education, like giving a kid a head start on money they can use for anything once they’re an adult, a custodial brokerage account under UTMA or UGMA rules works differently: there’s no tax break, but there’s also no restriction on what the money eventually gets used for. Grandparents, aunts, uncles and family friends can all contribute to either type of account, so this doesn’t have to be a parent’s job alone if you’re the one with the extra $100 and a kid you want to help.

Hands reviewing a printed resume beside a laptop displaying a resume
Image Credit: Shutterstock

If you’re job hunting, $100 covers a solid headshot session or a professional resume rewrite, and both change how fast you move through a hiring process. Recruiters spend seconds on a first pass through a resume, and a document that’s cluttered, outdated or formatted strangely gets skimmed past regardless of the experience underneath it. A blurry selfie as a LinkedIn photo sends a similar signal before anyone reads a word you wrote.

This doesn’t require a studio. Plenty of photographers offer a 15-minute headshot package for well under $100, and some cities have mall kiosks or local photographers who specialize in exactly this at a lower price point than a full portrait session. For the resume, a professional resume writer who understands your specific industry’s keywords and format expectations is usually a better use of $100 than a generic template, especially in fields where applicant tracking software filters resumes before a human ever sees them.

Take the defensive driving course that knocks down your insurance
Man adjusting the rearview mirror before driving
Image Credit: Shutterstock

Most major insurers offer a discount for completing an approved defensive driving course, typically somewhere between 5% and 20% off your premium, and the course itself often costs less than $100, sometimes a fraction of that if you take it online. The discount usually holds for up to three years, so this isn’t a one-time saving, it’s a multi-year discount for a single afternoon’s worth of effort.

Check with your specific insurer before signing up for a course, since not every provider is approved and some states only recognize certain programs for the discount to apply. If you’ve gotten a ticket recently, a defensive driving course sometimes does double duty: it can knock points off your license in some states on top of lowering your premium, which is a better return on $100 than almost anything else that requires an afternoon of your time. Most courses are approved for either the classroom or the online format, so there’s no real excuse to put this off once you know your insurer offers the discount.

Put it toward next quarter’s estimated taxes if you’re self-employed
Wooden blocks spelling IRS surrounded by rolled banknotes
Image Credit: Shutterstock

If you freelance, run a small business, or otherwise owe quarterly estimated taxes, the fourth-quarter payment for 2026 is due January 15, 2027. Chipping $100 toward that payment now, rather than scrambling to cover the whole quarter at once in January, is one of the least exciting but most useful things you can do with extra cash if self-employment income is unpredictable.

Underpayment penalties on estimated taxes are calculated quarter by quarter, so being short in one quarter costs you even if you make up for it later in the year. If you’ve historically underpaid or you had a strong quarter and expect to owe more than usual, setting aside money as you go, even in $100 increments, beats discovering a four-figure tax bill you weren’t expecting when you file. A separate savings account earmarked specifically for taxes keeps this money from quietly blending into your regular spending before January rolls around.

An extra $100 isn’t going to transform your finances on its own. What it can do is nudge one part of your situation, a balance, a bill, a bare-bones emergency fund, slightly closer to where you want it to be, and that’s worth more than letting it disappear into whatever’s easiest to spend it on this week.
Gardenia essential oil has been used spiritually for meditation, heart-centered rituals, and stillness. The flower is often associated with purity and love, and while there’s no sufficient evidence for claims of it producing a spiritual effect, it has been used in several well-being practices.

This guide explains what the oil is, how people use it, what the science supports, and how to use it safely.

What is Gardenia essential oil?

Gardenia comes from Gardenia jasminoides and also goes by cape jasmine. The NC State Extension lists its native range as Japan and southern China, with very fragrant, white flowers that age to yellow. The scent is best described as sweet and floral.

Why Gardenia has spiritual associations

Gardenia has been linked with purity, love, and peace, mainly due to its white blooms. In modern spiritual and folk practice, it is often used for emotional healing and a sense of connection, whether in meditation, prayer, or quiet reflection.

The flower has been prized for its scent for centuries, and women in China wore gardenias in their hair as early as the Song Dynasty. It’s worth noting that these meanings are derived from symbolism and tradition and are not rooted in scientific research.

Gardenia essential oil spiritual Benefits

Gardenia essential oil has a wide range of applications.

Meditation and stillness

A familiar scent can serve as a cue to slow down. Diffuse a few drops, or place a drop on a tissue nearby, and use the scent as an anchor for breathing or silent sitting. Keep the dose small, since strong floral oils can feel heavy in a closed room.

Heart-centered rituals

Gardenia’s link with love makes it a common choice for gratitude practice, journaling, and relationship rituals. Light a candle, apply a diluted blend to the wrists, and spend a few minutes writing what you appreciate. Judge it by whether the ritual helps you focus, not by any promised outcome.

Clearing space and fresh starts

Some people use gardenia for new-moon rituals, home blessings, or marking a transition. Its purity symbolism suits this, but opening a window and tidying the space matter just as much as the scent.

Evening wind-down

A short evening routine can include a diffuser, a warm drink, and a few quiet minutes. Gardenia is only one option here, and you should stop if the scent causes a headache or irritation.

What does the Science say?

There is no evidence that gardenia oil creates spiritual states. Evidence for aromatherapy and mood is also limited. A 2011 review of 16 randomized trials in the Journal of Alternative and Complementary Medicine found most reported reduced anxiety.

The authors noted weak methodology and called for better studies. The NCCIH says it is unclear whether aromatherapy with lavender helps anxiety or stress.

None of these studies tested gardenia. Any calming effect is better described as a possible result of a pleasant scent and a quiet routine.

How to use Gardenia oil safely

If you’re looking to purchase this oil, Wholesale Botanics’ gardenia essential oil is a useful starting point. The official page lists a botanical grade, which is a blend of natural oils and aromatic compounds. This isn’t unusual for floral scents, but it helps to know this beforehand.

Here’s how you can incorporate it safely in your routine:

  1. Dilute it: Dilute properly before skin use.
  2. Patch test first: Apply a small diluted amount to your inner forearm and wait.
  3. Diffuse sparingly: Use a few drops for short sessions in a ventilated room.
  4. Avoid contact with eyes: Keep it away from mucous membranes.
  5. Store it safely: Keep it out of reach of children and pets.

The NCCIH notes that aromatherapy with lavender is considered possibly safe but may cause headache or coughing, and topical lavender products may cause allergic skin reactions. Scented oils can do the same.

The gardenia plant is also flagged as a problem for cats, dogs, and horses, so keep the oil away from animals. Speak to a health professional before use if you are pregnant or have a medical condition.

Gardenia essential oil spiritual benefits: Making it part of your practice

Start with one small ritual, such as three minutes of quiet breathing with a diffused scent. Choose a consistent time, like first thing in the morning or just before bed, so the scent becomes a cue to slow down.

Decide on one intention beforehand, such as peace, gratitude, or clarity, and return to it when your mind wanders.

Try this for a week or two, then adjust the amount, the timing, or the length of the ritual, and keep only what helps. If the scent gives you a headache or irritates your skin, stop and try a different approach.

At a private lunch on Capitol Hill on September 24, someone asked Texas Attorney General Ken Paxton how he would bring down the federal deficit. Paxton, now the Republican nominee for Senate, answered that cuts to mandatory spending are something lawmakers will have to do and added, “We have to suck it up.”

The room held roughly a dozen people, most of them lobbyists, and the public only learned what was said when pieces of a recording began leaking to reporters at the end of September. Mandatory spending covers the programs that pay out under existing law instead of through yearly budget votes, and about three-quarters of it goes to Social Security, Medicare and Medicaid.

Paxton did not say which programs he meant or how deep the cuts would go, and after the audio came out he said he would not vote to cut Social Security benefits. Nearly 5 million Texans collect Social Security retirement, disability or survivor benefits, and early voting in the state begins Monday.

What the recording captures

US Capitol building and dome beneath a cloudy sky in Washington DC
Image Credit: Shutterstock

The clip is a short slice of a longer conversation, and the attendee who recorded it, someone who opposes Paxton’s run, has declined to share the full audio. Two other people at the lunch confirmed details of the exchange, and both said they did not remember Paxton describing specific cuts at any other point during the event.

Paxton laid out a two-part approach to the deficit that paired tax cuts meant to grow the economy with cuts to mandatory spending. He said the numbers do not add up, that presidents from both parties have spent heavily, and that without those cuts there is no solution. At one point a lobbyist said she would like to pay less in personal taxes, the room laughed, and Paxton said he agreed and that tax cuts bring in more revenue. Texas Democrats have pointed to that moment in their response.

The recording does not include a program name, a dollar figure or a percentage. Nothing in the audio shows whether Social Security is part of what he has in mind, which is why both sides have been able to read the clip so differently.

What Paxton says he meant

Close-up of a Social Security earnings record
Image Credit: Shutterstock

After the audio was published, Paxton said he would not vote to cut Social Security benefits if elected, and he pointed to earlier public statements, including August 21 and September 1. He described Social Security as a promise to people who paid into it and said the national debt still has to be solved. He named a crackdown on fraud as a major way to cut the deficit and called the recording cherry-picked audio that took his words out of context.

His campaign took the same position earlier in the year. In August, the campaign’s deputy communications manager told a San Antonio news outlet that Paxton was against any cuts to Social Security. On Social Security alone, his public position has stayed the same, and what remains unclear is what the private remark about mandatory spending was aimed at.

The recording and the public statements can both hold only if the cuts he has in mind land somewhere other than Social Security, and he has not said where.

Why mandatory spending covers more than Social Security

US Capitol building against a background of dollar bills illustrating government spending
Image Credit: Shutterstock

Mandatory spending includes a lot more than retirement checks. Beyond the big three programs, the remainder covers food benefits, unemployment insurance, and retirement and disability benefits for federal workers and veterans, so a candidate who says it needs trimming could be talking about any of them. Federal Medicaid spending is already set to fall by nearly $1 trillion over ten years under the 2025 tax and spending law.

Still, three programs make up about three-quarters of the total, and it is hard to find savings on a scale that matters without touching at least one of them. That helps explain why politicians in both parties have tiptoed around entitlement changes, since the people who depend on those benefits spent years paying in.

Paxton is not the only Republican who has been pressed on this. In June, House Speaker Mike Johnson said entitlement programs need to be adjusted to deal with the debt, then said afterward that Republicans are not talking about reducing benefits and would focus on fraud and inefficiencies instead.

The cut that is already on the calendar

Worried older couple reading a letter beside an open laptop
Image Credit: Shutterstock

Whoever wins in Texas, Social Security has a funding problem that does not depend on any campaign promise. The trust fund that pays retirement and survivor benefits is projected to run out of reserves in the last quarter of 2032, and from that point incoming payroll taxes and other income would cover about 78 percent of scheduled benefits unless Congress acts. If lawmakers allowed the retirement and disability funds to share money, the combined reserves would last until the third quarter of 2034, when 83 percent of benefits would be payable.

More than 62 million people received benefits from the retirement and survivors fund at the end of 2025. The average retirement benefit will be about $2,163 a month in January, and a 22 percent cut applied to that same amount would take away roughly $475 a month, or about $5,700 a year.

The people who oversee the program have urged Congress to act early so that any changes can be phased in gradually.

What your 2027 check looks like right now

Social Security cards beside US dollar bills illustrating benefit payments
Image Credit: Shutterstock

Benefits are going up in January, which is a separate matter from the 2032 date. Social Security announced a 3.6 percent cost-of-living increase for 2027 for 76 million people, and the average retirement benefit rises by about $75 a month. The same announcement raises the amount of earnings subject to Social Security tax from $184,500 to $192,300 for people who are still working.

Part of that raise will go to Medicare. The standard Part B premium is $202.90 a month this year, and the 2027 amount is usually announced in mid-November. People with a my Social Security account can see their personal increase notice starting in late November, and the same account lets them estimate what they would receive at different ages and check their earnings history for errors.

Where the other side of the race stands

Ballot paper entering a white ballot box beside American flags
Image Credit: Shutterstock

Democratic nominee James Talarico has said the way to protect Social Security and lower the deficit is to raise taxes on the wealthy, specifically by eliminating the payroll tax cap for people who earn more than $400,000 a year. Right now the Social Security tax stops applying after the first $184,500 of earnings.

Paxton has criticized Talarico’s economic agenda, which includes higher taxes on billionaires, as a threat to Texans’ paychecks. On the campaign trail, he has promoted tax deductions for health care, housing and family expenses rather than laying out a Social Security plan.

The race is close. A poll of likely voters released October 2 had Talarico at 51 percent and Paxton at 49 percent.

Paxton has not said which programs he would cut or by how much, and Texas voters begin casting early ballots on Monday. The retirement trust fund is still projected to run short in late 2032 no matter who takes the seat.

A marketing coordinator posting comes across your feed. Nice photos of the office, three paragraphs about the company’s mission, a line about “flexible hybrid culture.” You scroll to the bottom looking for the number and there isn’t one. Just “competitive salary” and a button that says apply now.

That’s a choice a company makes, not an accident. Sixteen states and Washington, D.C. now require employers to list a real salary range in job postings, and even outside those states, a company that has already set a budget for the role can put a number on the page in the time it takes to type it.

Pay attention to the wording early, because a company that won’t tell you what it pays usually isn’t being coy about anything else, either. It’s telling you exactly how it plans to handle every other hard conversation once you’re hired.

The salary range is missing or vague

Hands reviewing a printed resume beside a laptop displaying a resume
Image Credit: Shutterstock

More than a dozen states now require companies to post a real number, and the map keeps growing every year. If a company operates in one of those states and still lists “competitive salary” instead of a range, that’s not confusion about the law. It’s a decision, and usually a cheap one, since posting a range costs nothing and takes less time than writing the paragraph about company culture two lines above it.

Even in states with no transparency law, a company that has already set a budget can share it. Refusing doesn’t protect a negotiating position, it just makes sure you walk into that conversation without the information they already have sitting in a spreadsheet. Ask for the range before the first call if it’s missing from the posting, and treat hesitation, or a vague answer like “we pay competitively,” as your actual answer. A recruiter who can’t or won’t name a number in 2026 is telling you the number isn’t good.

The salary range is technically there but tells you nothing

Woman reviewing paperwork with a calculator beside her laptop
Image Credit: Shutterstock

Some companies solve the missing-number problem by posting a range so wide it stops meaning anything, something like $50,000 to $200,000 for the same role. Regulators in several pay transparency states have started flagging ranges that broad as noncompliant, because they don’t reflect a real, good-faith estimate of what the job actually pays. Ranges like that exist to check a legal box while the real number stays hidden from you until an offer is already on the table.

When you see a spread that wide, assume the offer will land toward the bottom of it unless a recruiter tells you otherwise in writing, and ask early what the range looks like for someone with your exact background rather than the posted range as a whole. A narrow, specific range, even a modest one, is a much better sign than an impressive-looking wide one. It usually means someone actually priced the job against the market before posting it, instead of pasting in a placeholder.

“Other duties as assigned” sits next to a thin list

Overloaded worker holding a clock and sticky note beside a laptop covered in tasks
Image Credit: Shutterstock

That phrase by itself isn’t a problem. Almost every job description carries some version of it, because nobody can predict every task a role picks up over a year. The problem shows up when it’s attached to a duties section that only runs four or five bullet points for a role that clearly needs more than that to actually run day to day.

Seventy seven percent of employees say they’re asked to take on work outside their job description at least once a week, and more than a third face it daily. In the same survey, ninety three percent said the extra work leads to burnout, and forty percent said it strained their relationship with their manager. A short duties list paired with an open catch-all usually means the company already knows the role will grow past what’s written and simply hasn’t bothered writing that part down yet. Ask what the last person in the role actually spent their time on.

The title says entry level and the requirements don’t

Adults attending a class with an instructor
Image Credit: Shutterstock

Zippia’s analysis of millions of postings found that nearly 40% of jobs labeled entry level ask for at least three years of experience, and postings that require two or more years while still calling themselves entry level pay about 20% less on average than similar roles without that label attached. The word “entry level” in the title is doing work on your paycheck, not describing your actual workload or how much the company can lean on you.

This is showing up in the applicant pool too. On Indeed, almost two thirds of applications from job seekers with six to nine years of experience are going toward entry-level postings, because there’s nowhere else for that experience to land right now. If a posting calls itself entry level and still lists years of required experience, read it as a mid-level job with an entry-level paycheck attached, and price your ask to the responsibilities in the listing, not the label at the top of it.

The posting leans on fast paced, wear many hats, and self starter

Older warehouse worker wearing a hard hat and scanning inventory beside a box
Image Credit: Shutterstock

These phrases show up so often that they’ve stopped describing a culture and started describing a staffing problem. A role that truly needs “someone who can wear many hats” is usually built to cover work that two or three people used to split before the company decided not to replace one or two of them, and folded their leftover tasks into a single new listing.

None of that means skip the job. It means ask exactly what “many hats” covers on a normal Tuesday, who else touches those tasks, and whether the team’s headcount has grown or shrunk in the last year. Ask how long the role has been open and why the last person left it, since a “fast paced” team that’s been hiring for the same seat every few months is usually fast paced for reasons that have nothing to do with the actual work. A specific, concrete answer is a decent sign. A laugh and “you’ll figure it out” tells you the job is bigger than the title suggests.

The company calls itself a family

Older woman discussing paperwork with colleagues at a desk
Image Credit: Shutterstock

Only about 23% of U.S. employees are actively engaged at work, and workplaces that lean on family language tend to make it harder to raise that kind of concern out loud, since pointing out a problem starts to feel like betraying people instead of giving normal, professional feedback. The same framing tends to normalize working past your hours, because family, at least in theory, doesn’t clock out at five.

A team that’s actually close usually doesn’t need to announce it in the job posting. A 2024 Deloitte survey found nearly 70% of employees report feeling burned out at work at least sometimes, and family language is one of the more common ways that reality gets papered over during hiring. If a posting spends more words on the family metaphor than it does on what the job pays or what a normal week looks like, notice that, and ask directly what turnover on the team has looked like over the last two years.

Unlimited PTO is the headline benefit

Older couple enjoying a holiday beside a canal and traditional buildings
Image Credit: Shutterstock

Only about 10% of U.S. workers currently have access to unlimited PTO, and the people who have it take an average of 13 days off a year, two fewer than employees on a standard, capped policy actually take. The plan sounds generous mostly because there’s no number printed anywhere on the offer letter, not because people actually end up using more time off once they have it.

Nearly 44% of employees with unlimited PTO say they feel like they don’t take enough of it, which is what happens when a benefit has no floor to point to and no manager modeling what normal use looks like. Ask what a typical employee on the team actually took off last year, not what the policy technically allows, and whether new hires get any real guidance on it. If unlimited PTO is the only benefit called out by name in the posting, ask what happens to accrued time when someone leaves, since unused hours under a capped plan are money owed to you, and unused hours under an open-ended one usually aren’t.

You’re asked to do real work before you’re hired

Hands typing on a laptop with an email-envelope notification overlay
Image Credit: Shutterstock

Under the Fair Labor Standards Act, work performed during an interview process generally has to be paid if it provides an actual benefit to the business, real customer data entered into a live system, a finished asset that ends up in a campaign, hours worked on a real schedule alongside paid staff. A short skills test that never leaves the interview room is one thing. A “trial shift” where you’re taking real orders, or a “sample project” that quietly becomes part of the company’s actual materials, is a different situation entirely.

If a posting mentions a working interview, a trial period, or a take-home assignment, ask directly whether it’s paid and how many hours it’s expected to take, and get that answer in writing before you show up. A company that gets vague or defensive about that question is showing you exactly how it handles pay questions once you’re actually on staff and asking about a raise.

The job title and the actual duties don’t match

Manufacturing engineer reviewing a tablet beside factory tanks and control equipment
Image Credit: Shutterstock

Job titles alone don’t determine whether a role is legally exempt from overtime, the actual duties do, and the federal salary floor for that exemption has stayed at $684 a week, about $35,568 a year, all the way through 2026. A company can hand you a title like “coordinator” or “specialist,” pay you just above that floor, and still expect manager-level hours, because the title itself carries no legal weight in either direction.

If a posting pairs a junior-sounding title with senior-level responsibilities, and the salary lands anywhere near that federal floor, work out what your real hourly rate looks like once you count the hours the role actually needs, not the 40 it’s advertised at on paper. A title is marketing, chosen partly to make a lower salary sound more palatable on a resume and easier to justify internally. The duties list and the number on your paycheck are the actual job you’re being offered, regardless of what the business card ends up saying.

The requirements section reads like three jobs stapled together

Older man rubbing his forehead during a discussion across an office desk
Image Credit: Shutterstock

Recruiters have a name for postings that ask for deep experience across several specialties, multiple certifications, and leadership ability, all for one entry- or mid-level salary: unicorn job descriptions. They usually mean the company hasn’t decided what the role actually is yet, or that it’s trying to fund two or three separate jobs out of a single salary line, and hoping one exceptional applicant will solve that budget problem for them.

If the required-skills section reads like a department instead of a single role, ask directly in the interview which items on that list are truly non-negotiable versus nice to have. A recruiter who immediately trims the list down is telling you the posting was aspirational and written to attract attention. One who insists you need all of it is telling you exactly what your actual, day-to-day workload is going to look like once you start, and how thin the team already is if a single new hire is expected to cover that much ground alone.

Nights and weekends are expected and nobody says how that’s paid

working nights
Image Credit: Shutterstock

There’s no federal law in the U.S. requiring an employer to leave you alone outside your scheduled hours, so if a posting mentions being “available after hours” or “responsive on weekends,” that expectation has no built-in ceiling unless the posting or your offer letter sets one itself. For hourly, non-exempt roles, the Fair Labor Standards Act does require pay for time actually spent responding to work messages off the clock, even a few minutes at a time, though in practice most workers in that position never see that pay show up on a check.

Ask specifically what “available” means day to day, a phone check twice a week versus truly on call around the clock, and ask directly whether that time is paid if you’re non-exempt. A posting that names the expectation but skips the boundary is telling you the boundary hasn’t been decided yet, which usually means you’ll be the one setting it, alone, sometime after you’ve already accepted the job.

Nobody can tell you who you’d report to

Smiling woman talking on a phone beside her laptop
Image Credit: Shutterstock

Fifteen percent of employees say they don’t clearly understand what’s expected of them in their role, and 29% describe their workload as unmanageable, and both numbers tend to climb sharply at companies with loose or constantly shifting reporting lines. A posting that’s vague about who manages the role, or that lists it as reporting to “the team” instead of a named position and title, is often vague because the structure hasn’t actually been settled, or because it changes depending on who happens to be interviewing you.

Ask for a specific name and title in the interview, not just a department or a vague “leadership team.” If the answer changes between the first call and the offer letter, ask about that shift directly before you sign anything, since a reporting line that’s still moving before your first day rarely settles down cleanly once you’re actually there, and you’ll be the one absorbing the confusion while it sorts itself out.

The culture section talks about hustle more than the job talks about work

Person working at a laptop in a dimly lit room at night
Image Credit: Shutterstock

People going through the slow-burn kind of burnout researchers now call quiet cracking tend to keep saying yes to extra tasks and after-hours messages even as the stress quietly builds, right up until, all at once, it stops working for them. That’s exactly the behavior a “work hard, play hard” culture section is designed to reward and reinforce. A posting that spends more space on energy, hustle, and ambition than it does on hours, pay, or support is telling you which of those three things the company actually prioritizes once you’re inside it.

Plenty of good jobs are legitimately demanding, so this isn’t a reason to skip an ambitious posting outright. Read the actual job description underneath the culture language and check whether the hours, team size, and support described in the posting match the intensity being promised in the paragraph sitting above it. If the culture section is specific and the job section is vague, the posting has its priorities backward, and so does the team you’d be joining.

Growth is promised and pay isn’t part of the promise

Industrial machinery mechanic repairing an automated conveyor belt on a factory production line
Image Credit: Shutterstock

Workers report feeling far more secure about their job today than about their future at the same company. In one 2025 survey, 82% of employees said they felt secure in their current job, but only 62% felt secure and confident about their future with the company. That 20-point drop usually traces back to vague growth promises that were never actually attached to a number, a review date, or a title path anyone could point to.

If a posting promises “room to grow” or “opportunity for advancement,” ask what that actually looked like for the last two people who held the role, a specific title change, a specific raise amount, a specific timeline for when it happened. A concrete answer means the path is real and has been walked before. A general, vague answer means the promise is quietly doing the work an actual raise or promotion should be doing instead, at no cost to the company that’s making it.

The pay is mostly commission and the base is buried

salary and overtime
Image Credit: Shutterstock

Career advisors flag phrases like “competitive salary” and “uncapped earnings potential” as signals of below-market base pay and limited room to negotiate, especially once a role leans heavily on commission or bonus targets that not everyone on the team actually hits. A wide advertised range on a sales posting, something like $45,000 to $150,000, almost always means most people land near the bottom of it, with the top figure kept around mainly to sell the job to new applicants.

Ask directly what the guaranteed base pay is, separate entirely from commission, and what share of the current team actually hits target in an average quarter, not just the best quarter anyone’s had. If a recruiter can quote the top number instantly but goes quiet or vague on the base, that’s the number that matters more for your actual budget, and it’s the one they’d rather you not focus on.

That little ceramic couple leaning into each other on your grandmother’s windowsill was never just a kitchen afterthought. For most of the twentieth century, salt and pepper shakers were the cheapest souvenir a traveler could bring home and the easiest gift a hostess could receive, which means millions of pairs went into circulation, and a surprising number of them are still sitting in cabinets, junk drawers, and dollar bins today.

Most are worth a few dollars and nothing more. But certain makers, patterns, and figural designs built real collector followings, and a pair that looks like dime-store kitsch can be worth considerably more once you know the name stamped on the bottom. Condition decides almost everything here: these are small, breakable objects that lived on countertops, so chipped ears, replaced cork stoppers, and faded paint are the norm rather than the exception, and they knock a set down fast.

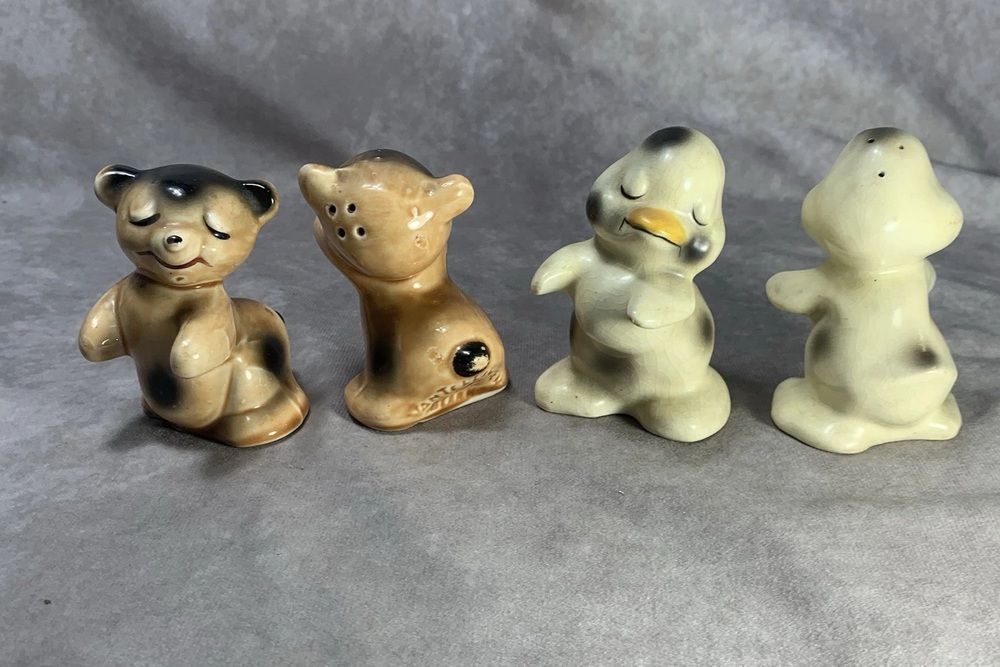
1. Van Tellingen hugging salt and pepper shakers

Van Tellingen bear and duck salt and pepper shakers arranged on gray fabric.
image credit: idioticxposure5 via eBay

The “hugger” format, two figures standing close enough that their shoulders touch and a magnet or notch holds them together, was invented by illustrator Ruth Van Tellingen Bendel, who began producing the design through Regal China in the late 1940s before patenting it in 1949. Her original patent covered the bear version, but the line quickly expanded into bunnies, a Dutch boy and girl, and a sailor embracing a mermaid.

Common pairs like the hugging bears and bunnies are genuinely easy to find and typically bring $15 to $30 in decent shape. The Dutch couple and the sailor and mermaid pairing are scarcer and often run $30 to $50, more for mint examples with their original cork stoppers intact.

Check the base for “Van Tellingen” or “Pat. Pend.” stamped into the glaze, since reproductions exist without it. A missing cork or a hairline crack where the figures join is the most common flaw, and a set with both figures matching in paint tone is worth more than one where the colors have faded unevenly from sun exposure.

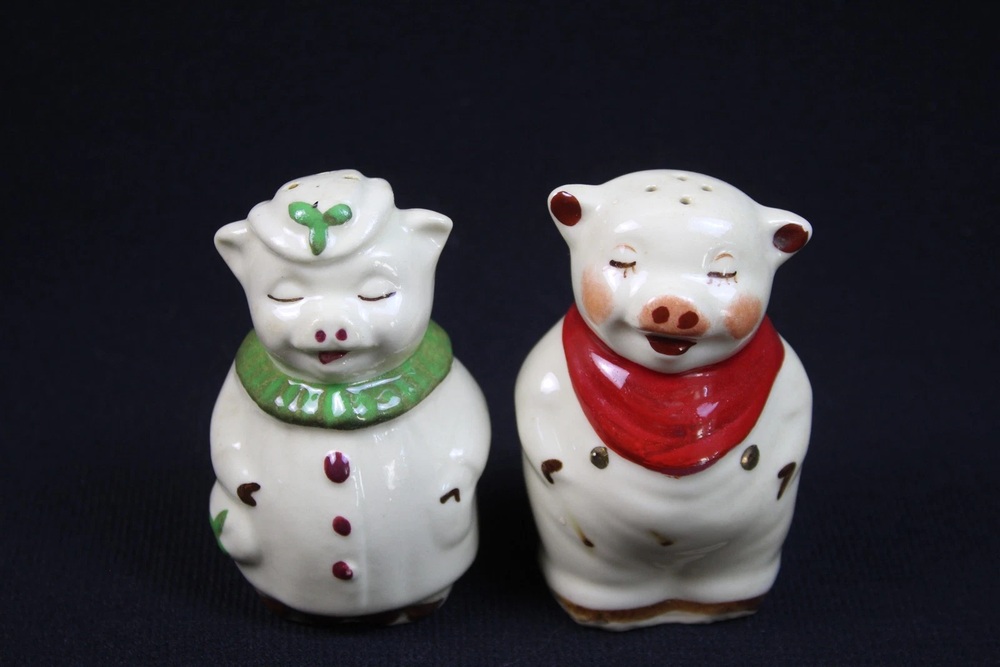
2. Shawnee Winnie and Smiley Pig shakers

White Shawnee pig shakers wearing green and red neckerchiefs.
image credit: livinintheboonies via eBay

Shawnee Pottery of Zanesville, Ohio, introduced these grinning pig shakers around 1942, designed by Rudy Ganz as companions to the brand’s larger Smiley and Winnie cookie jars. The pottery operated from 1937 to 1961 and sold heavily through Sears, Woolworth, and door-to-door coffee premiums, which is why so many pairs survived into family cupboards.

Condition drives the price more than usual on these. A chipped or cracked pair can slip to $15 or less, while a clean pair in a common bib color, blue, green, or gold, typically brings $20 to $50. The scarcer red-bib and peach-bib colorways push toward $75 for pairs with no chips or crazing.

Look closely at the ear tips and the pig’s snout, which chip first, and confirm the impressed Shawnee mark on the underside before assuming a similar unmarked pig is the real thing. Original cork stoppers are frequently missing, and a set without them sells for noticeably less than a complete one.

3. Hull Pottery Little Red Riding Hood shakers

Two Hull Little Red Riding Hood shakers with red hoods and floral dresses.
image credit: moms_collectables-0 via eBay

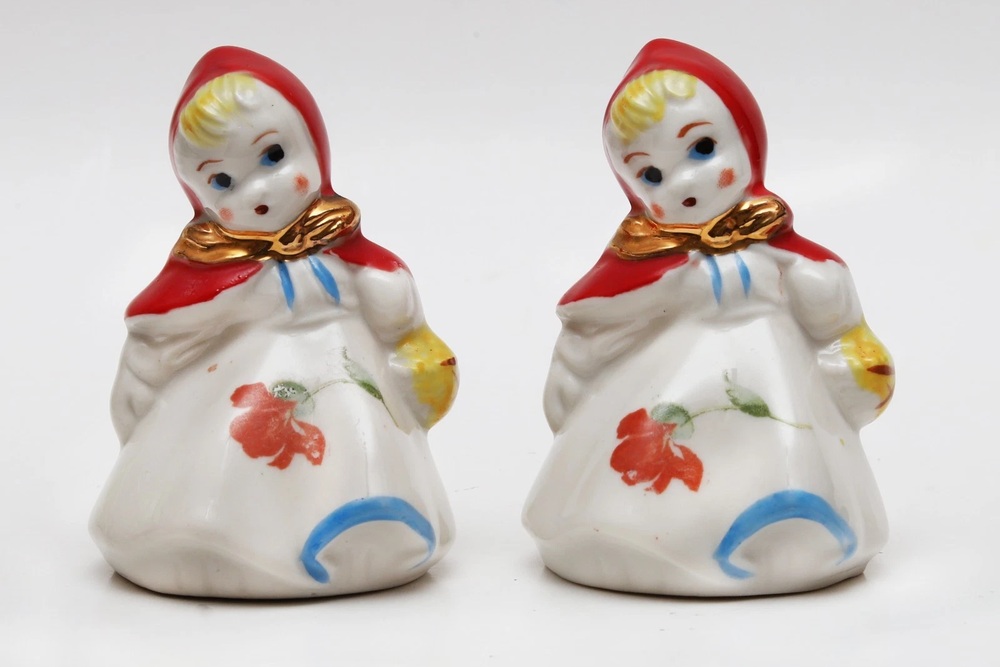
Hull Pottery, founded in Crooksville, Ohio in 1905, built an entire kitchenware line around Little Red Riding Hood between 1943 and 1957, with designer Louise Bauer creating the cookie jars, grease containers, and matching salt and pepper shakers that turn up most often in estate sales today.

The smaller, more common version of the shakers typically sells for $15 to $25 in good condition, considerably less than the cookie jar, which can run into the hundreds depending on the dress pattern. The larger, harder-to-find size brings closer to $45 to $70 even with a missing stopper or minor paint wear, since fewer of them survived.

Paint loss along the red hood and apron trim is the most common issue, along with hairline cracks near the base where decades of handling take their toll. A matched pair with crisp, unfaded paint and original cork stoppers brings more than one with mismatched replacements, and a few reproduction pairs have circulated with softer, less detailed features than the originals.

4. Royal Bayreuth tomato shakers

Royal Bayreuth tomato shakers with ribbed orange-red bodies and green leaf feet.
image credit: thesecondchapter0605 via eBay

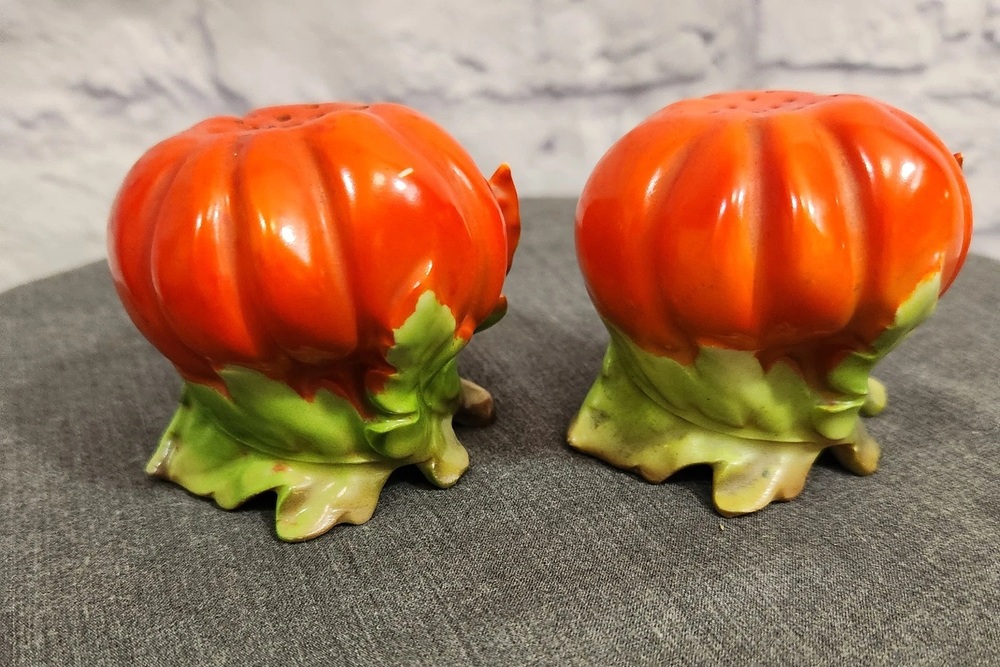
Royal Bayreuth, a German porcelain maker operating out of Tettau since 1794, produced an entire figural “tomato set” line of creamers, sugars, mustard jars, and salt and pepper shakers shaped like ripe red tomatoes with painted green leaves, most dating to the early twentieth century. A shaker pair alone typically brings $20 to $40, while the full set with creamer and sugar can reach $75 per piece.

The company also made lobster and strawberry versions of the same figural format, both scarcer and more valuable than the tomato.

Flip a piece over to check for the blue Royal Bayreuth mark, since the tomato shape has been widely copied by other importers without the mark at all. Paint loss on the raised leaf details and a missing cork stopper are the most common condition issues, and a shaker pair sold with its matching creamer and sugar bowl is worth meaningfully more than the same pieces sold separately.

5. Rosemeade Pottery animal shakers

Two Rosemeade quail-shaped ceramic shakers on pale fabric.
image credit: grandma_stuff90745 via eBay

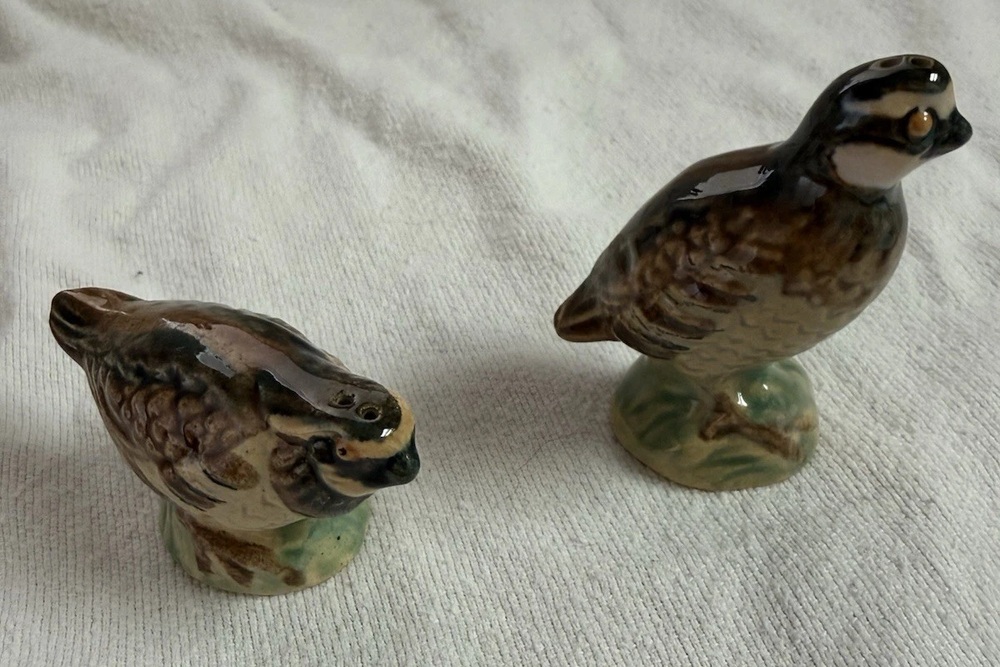
Rosemeade Pottery operated in Wahpeton, North Dakota from 1940 to 1961, founded by Laura Taylor, whose naturalistic animal designs drew on the wildlife of her own North Dakota farm childhood. The pottery turned out an enormous range of small figural salt and pepper shakers shaped like pheasants, quail, skunks, and prairie animals, most of them cast rather than thrown by hand.

Common birds like the pheasant and quail pairs typically sell for $15 to $35, while scarcer, less typical animals like a kangaroo pair bring $35 to $55 or more depending on how unusual the subject is.

The maker’s mark is a small impressed “Rosemeade” or a paper foil label on the base, and pieces missing the label are harder to confirm without comparing the mold details to a reference photo. Chips on the beak or tail tips are common on the bird designs, and foil labels, when present, add to the value since most have worn away over seventy-plus years.

6. Fenton hobnail milk glass shakers

White Fenton hobnail milk glass shakers with perforated metal lids.
image credit: techguy1995 via eBay

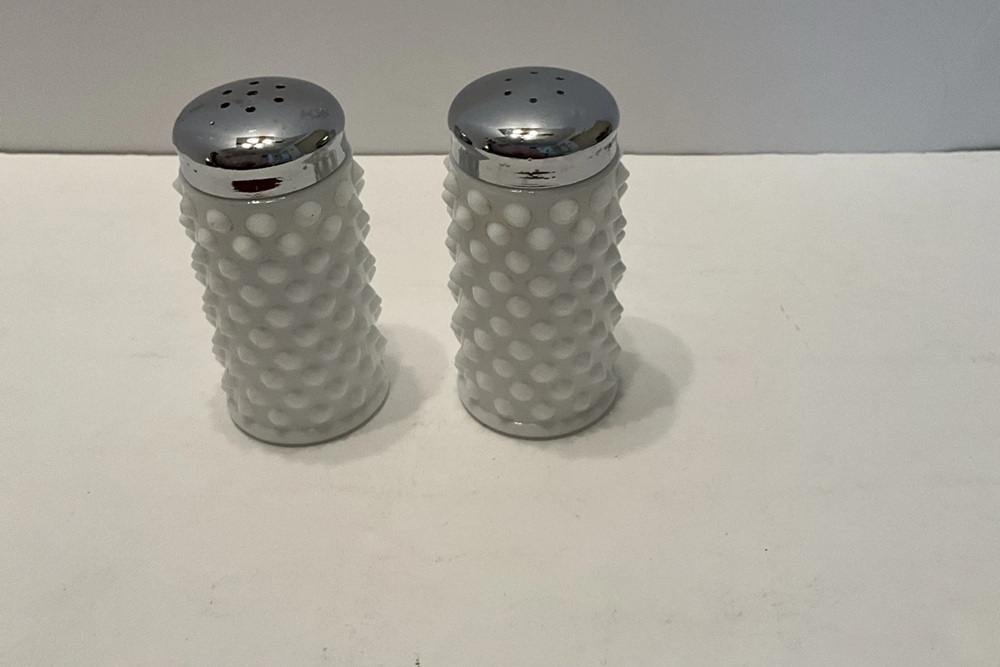
Fenton Art Glass, founded in Williamstown, West Virginia in 1905, made its white hobnail milk glass pattern, rows of small raised glass bumps, into one of the most recognizable American glassware lines of the mid-twentieth century before the company closed in 2011. Plain white hobnail footed shakers with their original metal lids typically sell for $20 to $45 in clean condition.

Colored versions in cranberry or blue opalescent glass are scarcer and bring $35 to $60 for a matched pair, sometimes more for cranberry, which collectors chase hardest.

Check the glass for a tiny oval Fenton sticker, since most pieces left the factory with one, though it rarely survives decades of dishwashing and its absence alone doesn’t mean a piece is fake. A cracked or badly rusted metal lid is the most common flaw and is worth replacing only with a period-correct one, since a mismatched modern lid noticeably lowers the price a buyer will pay. A full matching set with a sugar jar and tray is worth seeking out, since it brings more than the same pieces sold apart.

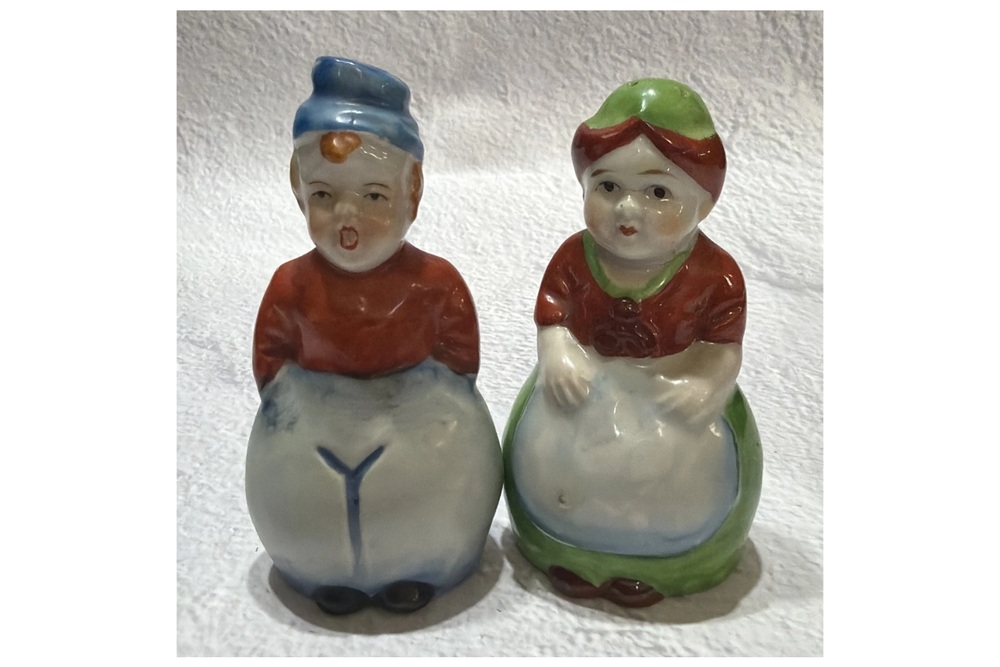
7. Occupied Japan Dutch boy and girl shakers

Occupied Japan Dutch boy and girl shakers with red tops and white clothing.
image credit: blendedvtt via eBay

Between 1945 and 1952, items exported from Japan to the United States carried a “Made in Occupied Japan” mark, and ceramic salt and pepper shakers were one of the most commonly imported souvenir categories of the period. The Dutch boy and girl theme was especially popular, and a pair in that design, while not as valuable as pieces showing a full-length figure, is worth $12 to $20 today.

Other themes from the same era, teapots, chickens, and musicians, turn up regularly at similar prices.

The mark itself is what collectors look for first, stamped or printed on the base in small lettering that’s easy to miss under years of grime. A gentle wash in warm water, never anything abrasive, usually reveals it. Hairline cracks near the arms or hat brim are common on these lightweight pieces, and a set with its original cork stoppers intact is worth a little more than one with replacements.

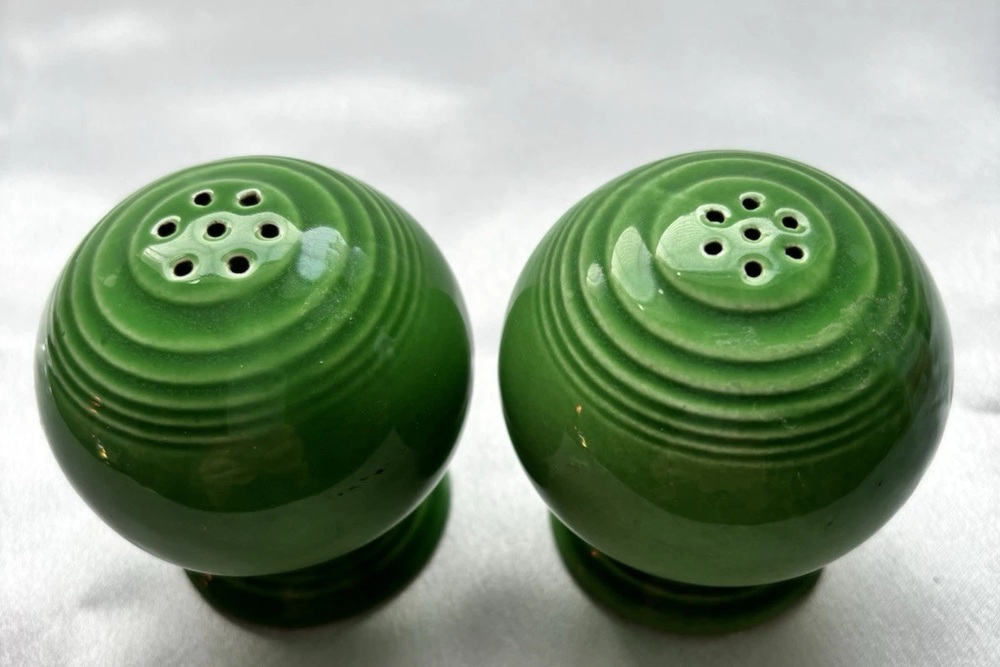
8. Vintage Fiesta dinnerware shakers

Green Fiesta ball-shaped shakers with concentric rings around the holes.
image credit: flaglatin via eBay

Original Fiesta, made by Homer Laughlin from 1936 to 1969, included small bulb-shaped salt and pepper shakers in every glaze color the line ever produced. A single shaker in a common original color, yellow, turquoise, or light green, runs about $25 to $35 through specialty dealers, so a matched pair in good condition typically totals $20 to $45 on the general secondhand market.

Medium green, introduced in 1959 as the line was winding down, is the color collectors chase hardest, and a pair in that glaze often sells in the $150 to $250 range, sometimes more for mint examples.

Because the shakers are small, Homer Laughlin never marked most of them, so color is the main way to identify an original piece rather than a later reissue, which runs in a noticeably different, more uniform palette. Chips on the fill-hole rim and a cork stopper that doesn’t match the original color are the usual condition flags, and a glaze with a slight sheen difference from modern Fiesta is a good sign of age.

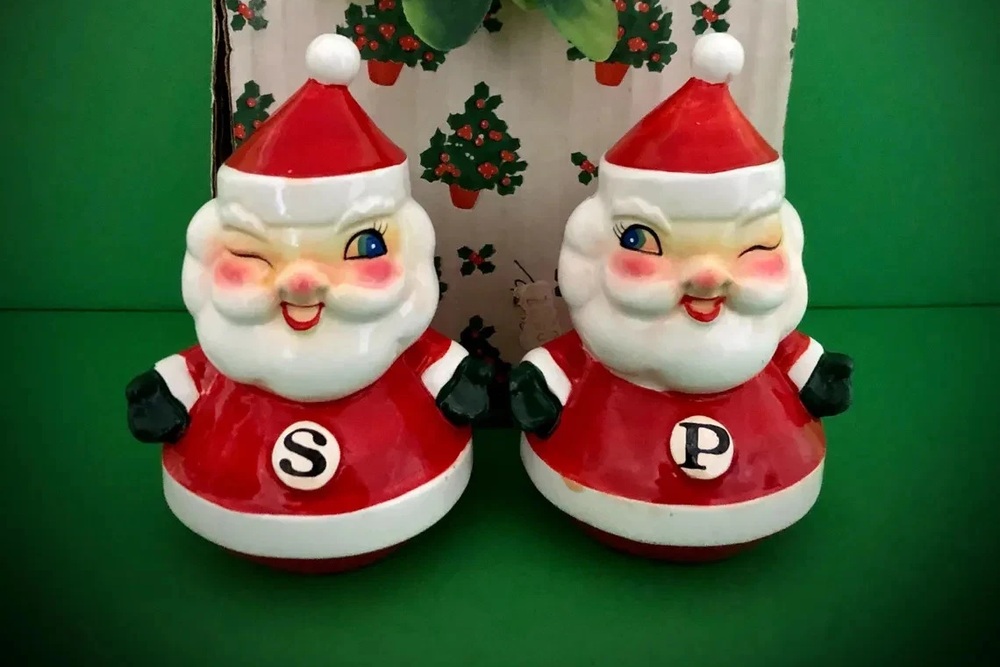
9. Holt-Howard winking Santa shakers

Holt-Howard winking Santa shakers marked S and P.
image credit: home*n*fashion via eBay

Holt-Howard was founded in 1949 by brothers John and Robert Howard along with college friend Grant Holt, who began importing cheerful, cartoon-faced ceramics from Japan and built an entire Christmas line around a winking Santa character through the late 1950s and 1960s. The standard winking Santa salt and pepper pair, often with a spring-loaded hat or stacking design, typically brings $50 to $80 today.

Rarer variations, including the stacking three-piece Santa design, climb considerably higher, with clean examples reaching $150 or more.

Flip a piece over and look for the stamped “HH” or “Holt-Howard” mark, since knockoff winking Santas without the mark are common and worth far less. Crazing in the glaze is typical and doesn’t hurt value much on its own, but a chipped hat point or a replaced cork stopper does, and a set still in its original box commands a real premium. The same winking-face line also made matching mugs, a sugar and creamer set, and an ashtray, so a shaker pair found alongside any of those is worth noting before splitting the lot up.

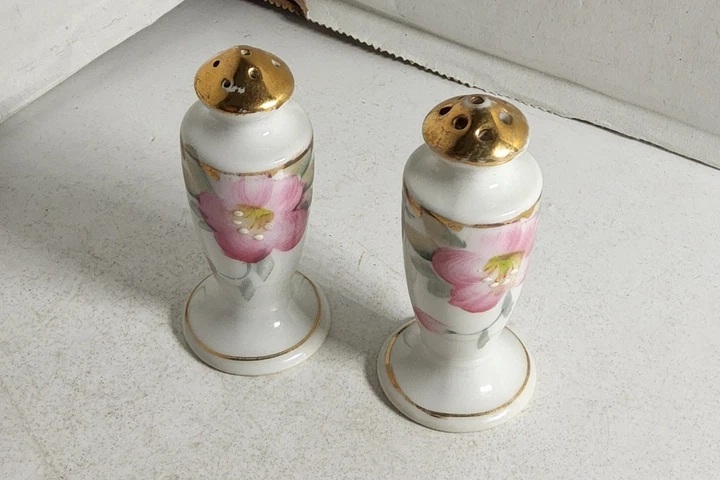
10. Noritake Azalea pattern shakers

Noritake Azalea shakers with pink flowers and gold-colored tops.
image credit: daviddaderholt via eBay

Noritake’s Azalea pattern, pink flowers with gold trim on fine white china, was one of the most widely distributed Japanese export patterns in American homes during the early and mid-twentieth century, often given away as a grocery or soap company premium. A shaker pair in clean condition typically sells for $10 to $25, and a matched six-piece set with the mustard jar, spoon, and tray brings $75 to $100.

The pattern was produced for decades, so pieces vary slightly in gold trim thickness depending on the era.

Worn gold trim is extremely common and expected on a pattern this old, and it only meaningfully hurts value when it’s worn through to bare porcelain on the handle or rim. A chip at the base, where the shaker sat flat on a table for decades, is the more serious flaw to check for, and a set sold with its original tray is worth more than the shakers alone.

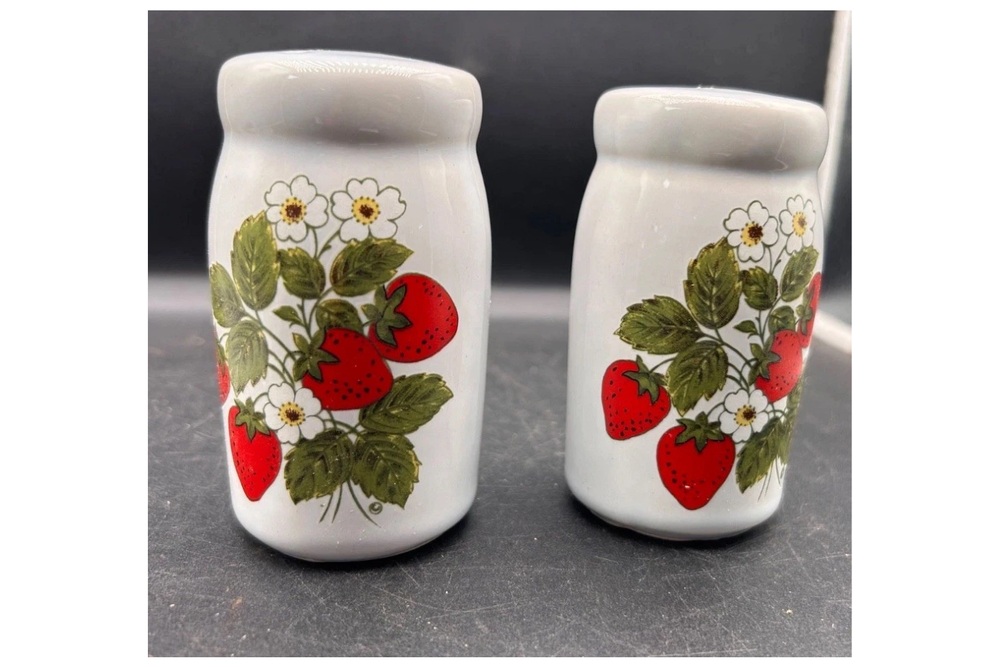
11. McCoy Pottery strawberry shakers

McCoy Strawberry Country shakers with red strawberries, green leaves and white flowers.
image credit: whilo_42 via eBay

The Nelson McCoy Pottery Company, operating in Roseville, Ohio and marking its wares consistently from around 1929 onward, produced a Strawberry Country pattern late in its run, simple white stoneware decorated with painted strawberries, that became one of its most recognizable kitchen lines. A pair of strawberry-pattern shakers in good condition typically sells for $10 to $20, in the same range as McCoy’s other simple figural kitchen shakers from the same decades.

McCoy also made a matching pitcher, canisters, and a cookie jar in the same pattern, and a shaker pair sold alongside other strawberry pieces brings more as part of a grouping than alone.

Look for the “McCoy USA” or “McCoy” impressed mark on the base, since the company’s popularity has made it a frequent target for unmarked imitators. Chips along the raised strawberry details and a cloudy, worn glaze from years of dishwasher use are the most common flaws, and cork stoppers are often missing entirely by now.

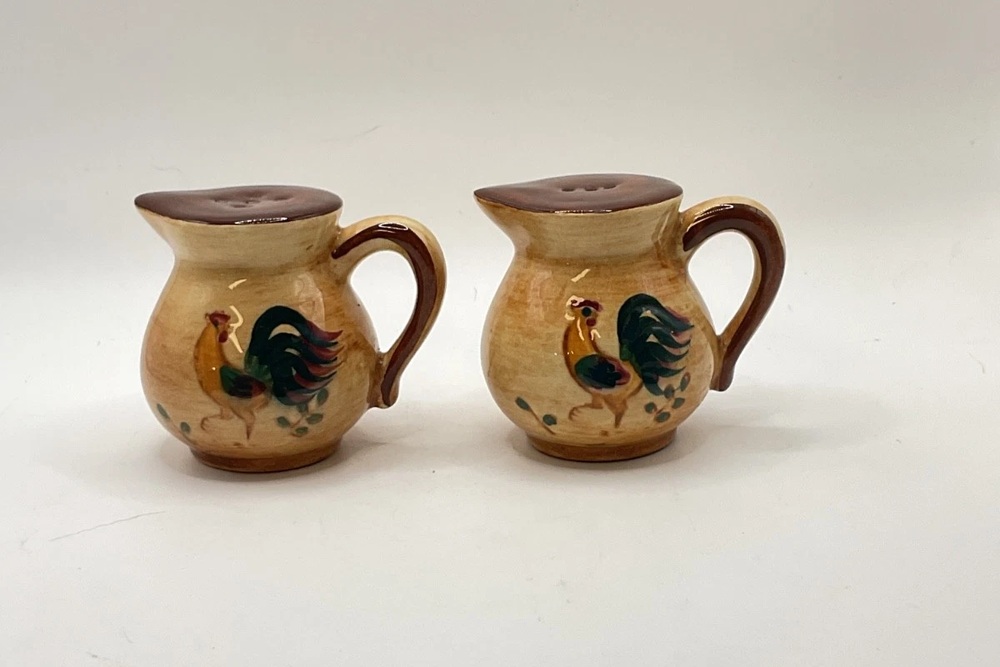
12. Pennsbury Pottery Red Rooster shakers

Pennsbury Red Rooster shakers shaped like small pitchers.
image credit: defrafar via eBay

Pennsbury Pottery, hand-painting folk art designs in Morrisville, Pennsylvania from 1950 until it closed in 1971, built its best-known pattern, Red Rooster, around a strutting brown and red rooster motif that appeared across an entire dinnerware line. A single Red Rooster salt shaker typically runs about $15, so a matched pair usually totals $25 to $35.

The hand-painted nature of the line means no two pieces are perfectly identical, which collectors consider part of the appeal rather than a flaw.

Each piece was hand-decorated rather than transfer-printed, so brushstroke variation is normal and expected, not a sign of a fake. What does hurt value is chipped glaze along the rooster’s comb and tail, the most exposed details on the design, along with a missing or replaced cork stopper, which is common after seventy-plus years of use. Because the pottery closed in 1971 and never resumed production, there’s no reissue to worry about confusing with an original, which makes this one of the easier patterns to buy with confidence.

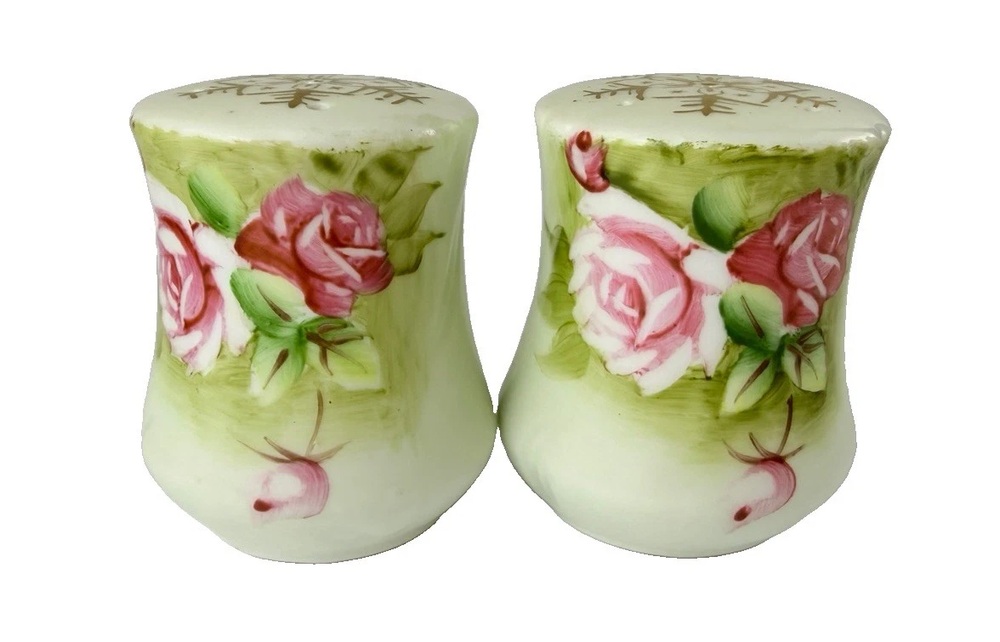
13. Lefton China hand-painted shakers

Lefton ceramic shakers painted with pink roses and green leaves.
image credit: instanti0ocg via eBay

Lefton China, the giftware import business founded by Hungarian immigrant George Zoltan Lefton after World War II, brought enormous quantities of hand-painted Japanese ceramics into American department stores through the 1950s and 1960s, salt and pepper shakers included. A common hand-painted floral pair in good condition typically sells for $15 to $25.

Complete themed Lefton sets with a matching creamer, sugar bowl, or cookie jar bring more than the shakers alone, often $40 to $75 for a grouping in clean condition, since collectors pay a premium for pieces that still go together.

Look for the pink Lefton paper label or the stamped “Lefton” mark on the base, since the label is often the first thing to rub off after repeated hand washing, and plenty of genuine pieces survive with no label at all. Faded hand-painted details and a chipped glaze along the fill hole are the most common flaws on pieces this old, and a set with both pieces still showing crisp color is worth seeking out over a faded match.

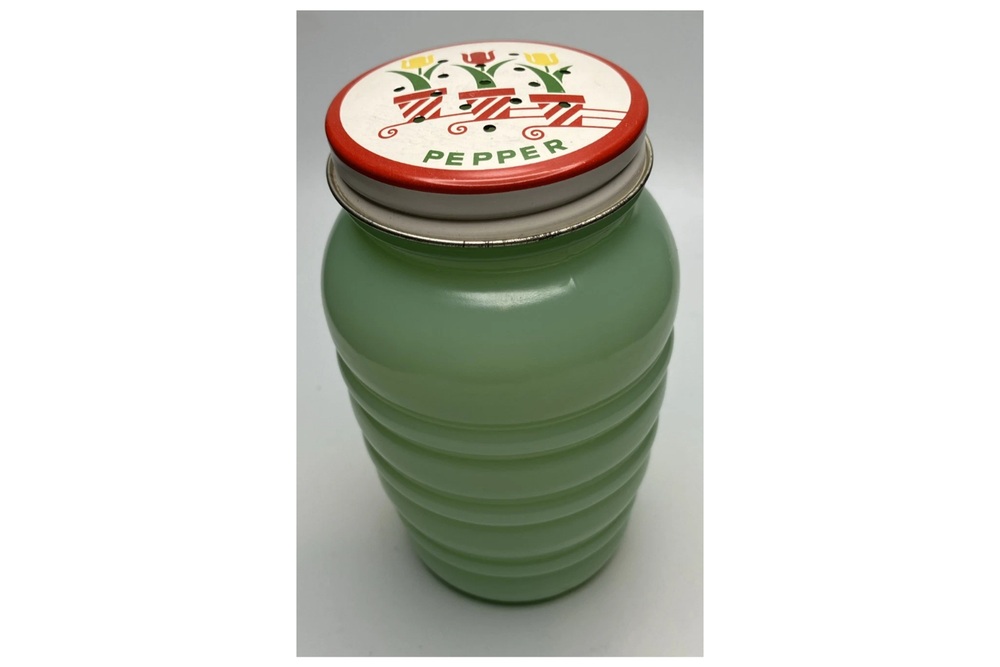
14. Jadeite Fire-King tulip shakers

Green Fire-King jadeite pepper shaker with a tulip-decorated metal lid.
image credit: kayak50 via eBay

Anchor Hocking’s opaque green Jadeite glass, produced under the Fire-King name through the 1940s and into the 1970s, included a line of kitchen range shakers with embossed tulip designs and metal screw lids. A plain swirl or ribbed Jadeite pair typically sells for $20 to $40, while the tulip-pattern pair with its original mint lids has been valued at $90 to $100.

Jadeite without uranium content, which covers nearly all Fire-King production, is the safer and more common version to collect.

Check the metal lid for rust and flaking chrome, which is extremely common and knocks the price down noticeably, since a mismatched replacement lid is an easy substitution to spot. A faded or scuffed label on the lid, when a set still has one, adds a little to the value, and genuine Jadeite has a slightly uneven, cloudy quality that’s hard to fake in modern reproductions. Newer jadeite-look glass from the 1990s onward tends to be heavier and more evenly colored, which is usually enough to tell it apart on sight.

15. Jeannette Glass Doric pattern shakers

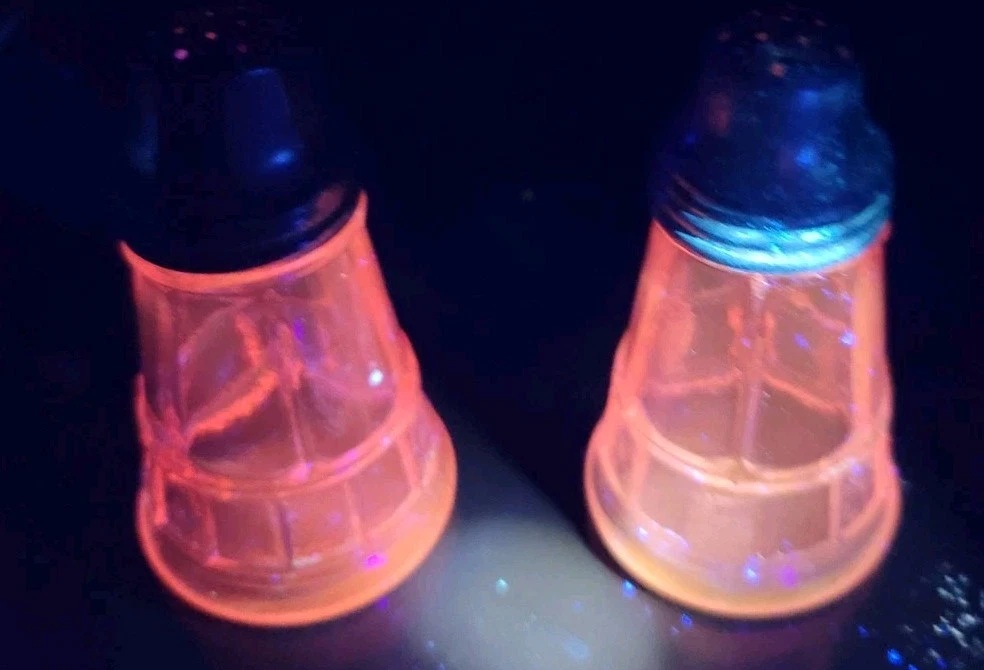
Jeannette Doric glass shakers glowing pink under ultraviolet light.
image credit: teestreasurechest via eBay

Jeannette Glass Company, one of the major Depression-era glass makers operating out of Jeannette, Pennsylvania, produced its Doric pattern in pink and green through the 1930s, including small ribbed salt and pepper shakers with metal screw lids designed for a kitchen range rather than a dining table. A pair in good condition typically sells for $20 to $25, in line with Jeannette’s other floral and ribbed range shakers from the same years.

Scarcer Depression-glass range shakers in black or cobalt blue from other makers of the same era command more, often climbing past $40 for a matched pair.

The metal lid is almost always the weak point, since decades near a stove meant rust and pitting were common even when the glass itself survived in excellent shape. A lid with its original paint intact, rather than bare rusted metal, adds real value, and a chip on the glass rim where the lid screws on is the most common damage to check for under good light.

16. Josef Originals figural shakers

Josef Originals sailor-shaped salt and pepper shakers.
image credit: palefury64 via eBay

Josef Originals, a giftware line created by the George Good Corporation and manufactured in Japan and later Korea from the 1950s through the 1980s, turned out an enormous range of whimsical figural salt and pepper shakers, animals, children, and seasonal characters among them. Everyday figural pairs, like the round pig and rabbit designs, typically sell for $15 to $25, while seasonal Christmas designs like Santa and Mrs. Claus climb higher, often toward $50 for a clean pair, depending on the specific figure and condition.

The snowman and reindeer designs from the 1950s tend to sit at the higher end of that range.

A tiny printed paper label on the base, often a small shield or wafer sticker, is the clearest way to confirm a genuine Josef Originals piece, though it’s frequently missing by now. Chipped facial features and faded cold-paint details, which were brushed on rather than fired into the glaze, are the most common and most value-damaging flaws on these pieces.

17. Goebel Friar Tuck shakers

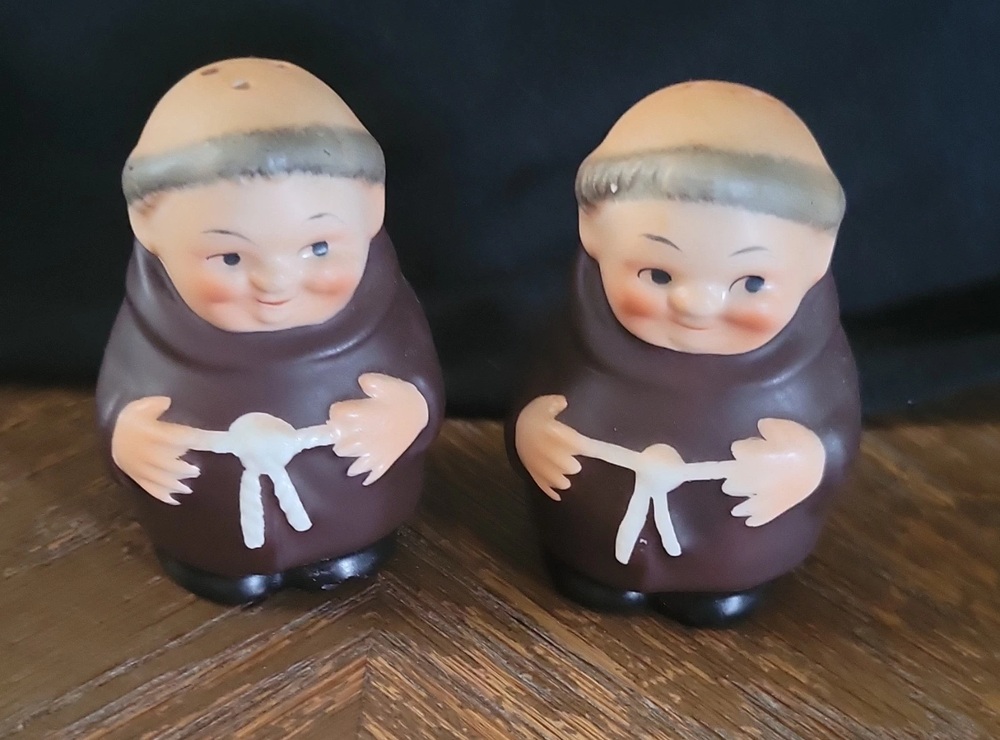
Two Goebel Friar Tuck shakers wearing brown robes.
image credit: judyc98 via eBay

W. Goebel Porzellanfabrik of Germany, better known for its M.I. Hummel figurine line, also produced a separate and more lighthearted series of figural kitchenware featuring a round, grinning Friar Tuck monk, including matching salt and pepper shakers, creamers, and sugar bowls through the 1950s and 1960s. A shaker pair typically sells for $20 to $45, and a complete Friar Tuck set with creamer and sugar has been appraised at $50 to $75.

At the far end of the Goebel market, a Disney-licensed Goebel salt and pepper set has brought as much as $1,500, a separate and much scarcer collaboration line from the standard Friar Tuck pieces.

Every genuine piece carries the stamped Goebel bee-in-a-V trademark on the base, which changed shape slightly over the decades and helps narrow down a production date. Chips on the monk’s tonsure and a cracked or replaced cork stopper are the usual flaws to check for.

18. Antique sterling silver figural shakers

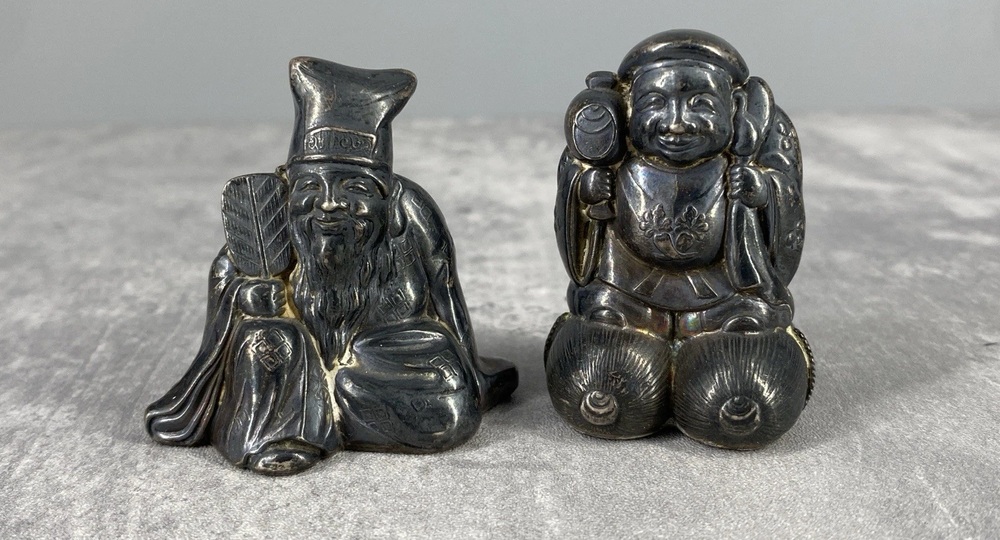
Antique Japanese silver figural shakers depicting two seated figures.
image credit: maywoodantiques via eBay

Sterling silver salt and pepper shakers from American and European makers, Gorham among the most common names found in family silver chests, were a staple wedding and anniversary gift from the Victorian era through the mid-twentieth century, often cast in figural shapes like shells, urns, or novelty animal forms. A signed pair in good condition typically brings $300 to $700, with weight and maker both affecting where in that range a set lands.

Rare Victorian novelty forms from major houses like Tiffany are worth considerably more, often climbing into the thousands, though that reflects an unusual combination of maker, age, and design rather than the typical sterling pair most people inherit.

Check for a full sterling hallmark rather than “silverplate” or “EPNS,” which look similar at a glance but are worth a fraction of the price. Dents, monogram removal scars, and a missing glass liner inside the shaker all reduce value, and tarnish alone is not a problem since it polishes off without damaging the silver underneath.

Selecting the right dock system for your waterfront property comes down to matching your shoreline’s physical conditions with how you intend to use the space daily. With around 30,000 lakes in Florida alone, thousands of waterfront property upgrades are installed across shorelines each year, and choosing the wrong layout or material can lead to early repairs and structural issues. Balancing water movement, seasonal changes, and material performance helps keep your investment safe and functional for decades.

Learn how to select the best dock system for your waterfront property by considering durability, water depth, seasonal changes, and long-term costs.
Image Credit: Google Gemini

Evaluating water conditions and shoreline dynamics

Water depth, fluctuation levels, and wave action serve as the primary engineering factors when choosing between stationary and floating structures. Deep-water setups with significant seasonal height shifts generally benefit from floating frameworks that move naturally with tides or dam-controlled reservoirs. Stationary pipe or piling setups excel in shallow, stable waters where fixed height access remains consistent year-round.

Local bottom conditions also dictate structural support choices. A soft, muddy lakebed requires long pilings driven deep into the substrate, whereas rock-heavy bottoms often require specialized anchoring grids or floating dock configurations.

Ignoring these underwater realities usually results in shifted frames and premature surface warping. And if you’re already well versed in top waterside spots for boating and fishing, making choices appropriate for the region and location is doubly important to make the most out of what nature has to offer.

Selecting framework materials for long-term performance

The supporting frame of your dock takes the brunt of physical stress, submerged moisture, and environmental load changes. Traditional pressure-treated timber frames offer a lower initial investment, but wood naturally absorbs water, warps over time, and requires routine staining and board replacement.

Aluminum framing has emerged as the premier standard for high durability due to its high strength-to-weight ratio and natural resistance to corrosion. Premium marine aluminum engineered to handle severe weather such as Wahoo CAT 5 dock systems provides heavy-duty structural stability without the weight burdens of steel or the rapid decay of timber. Choosing robust marine-grade aluminum eliminates rust risk while maintaining structural integrity against severe wind and wave surges.

Decking options and maintenance demands

Decking surfaces directly impact bare-foot comfort, slip resistance, and ongoing maintenance schedules. While structural frames provide safety, the top decking material defines your daily user experience.

  • Polypropylene panels feature slotted designs that reduce wave uplift pressure while staying cool under intense sun exposure
  • Composite boards offer a polished hardwood aesthetic while eliminating splinter risks and rot
  • Aluminum decking provides superior longevity and maximum heat dissipation for barefoot safety

Maintaining your surface extends the working life of the entire dock installation. Simple routines like sweeping off organic debris and rinsing surfaces prevent mold build-up and preserve traction.

Designing layouts for intended waterfront use

Layout choices depend heavily on the types of watercraft you own and how your family uses the shoreline. Straight single-slip layouts work well for standard powerboats, while wider U-shaped or L-shaped designs create protected swim areas and easy boarding access.

If you enjoy entertaining guests, dedicated seating areas or integrated upper decks double your usable square footage without expanding your footprint into navigation channels. Ensuring proper swim ladders, bumper guards, and cleats are integrated early in the design phase creates an organized and safe dock environment.

Long-term care for waterfront assets

Every dock system requires periodic inspections to maintain structural integrity and safe operation. Checking hardware connections, hinge pins, and anchoring lines prior to heavy boating seasons catches minor wear before it affects the frame. Inspecting underlying structural components following major storm events ensures the anchoring system remains properly aligned.

As with any of the many potential home upgrades available, this investment in care is as must about protecting your initial spend and preserving your property’s value as it is anything else. So if you’re on the fence about sticking to the required maintenance schedule or a dock system, don’t skip over your responsibilities.

Navigating local permitting and environmental regulations

Local zoning ordinances and environmental guidelines play a major role in determining what dock configuration you can legally construct. Many municipal authorities and environmental agencies strictly regulate total square footage, physical distance from neighboring property lines, and overall shoreline coverage.

Building in ecologically sensitive zones often mandates specific construction designs that allow natural sunlight to reach subaquatic vegetation beneath the structure. Getting your plans reviewed by municipal building departments early in the planning process helps prevent project delays, costly fines, and sudden retrofitting demands after installation begins.

Finding the ideal match for your property

Choosing the right dock requires weighing your budget against shoreline geography and long-term maintenance preferences. Investing in durable frame materials and functional layout designs ensures your dock serves as a hassle-free extension of your living space. Exploring specialized dock design options helps tailor your choice to your exact shoreline needs, and for more articles relevant to coastal residents, stick around on our site.