scroll top

Remote work is not dead, but the easy-to-find jobs are packed with applicants. The worst listings offer low pay, vague duties, or an “entry level” label followed by a demand for years of experience.

Better options are there if you know what to look for, but these are job titles most people have never searched for because they don’t know they exist. Companies still need workers who can interpret live conversations, guide families through health decisions, clear shipments through customs, map physical infrastructure, and investigate safety problems.

Some of these careers require a license, certification, or specific degree. Entry level means you can land the job without first spending several years doing that exact work. Remote rules vary by employer, so check location limits, work hours, and travel requirements before applying.

Video relay interpreter

Video relay interpreter
Image Credit: Surface via Unsplash

Video relay interpreters help Deaf and hard-of-hearing people make phone calls through American Sign Language. You watch the caller on video, speak their signed message to the other person, then sign the spoken reply back in real time. Calls can involve a doctor’s office, a bank, a family member, a mechanic, or an emergency. There is no script, and you may switch topics every few minutes. Average pay for an ASL interpreter is about $72,400 per year.

Remote relay companies provide secure platforms, scheduling systems, and technical support. You need strong ASL skills, an interpreter training program, and any certification required by the employer. Some companies offer screening and development programs for newly qualified interpreters. The work depends on tone, facial expression, regional signs, cultural context, and fast judgment. A literal translation can completely change the meaning of a conversation, so employers still need trained people who can understand what both sides are trying to say.

Remote court reporter

court reporter
Image Credit: Shutterstock

Court reporters create the official record during depositions, hearings, arbitrations, and other legal proceedings. In a remote deposition, you join by secure video, identify speakers, mark exhibits, record every word, and read testimony back when an attorney asks. You also prepare a clean transcript that may become evidence in a lawsuit. Median pay is about $67,310 per year, and freelance reporters may earn additional money through transcript fees.

You can enter through a court-reporting certificate or associate program, followed by a speed test or professional credential. Reaching the required accuracy takes serious practice, but you do not need years of legal-office experience before taking your first assignment. Remote deposition firms, courts, government contractors, and reporting agencies hire qualified beginners. Speech software can produce a rough draft, but legal proceedings include interruptions, accents, technical terms, poor audio, and several people talking at once. A human reporter is responsible for identifying errors and certifying that the final record is accurate.

Licensed customs broker

Licensed customs broker
Image Credit: Valeria Strogoteanu via Unsplash

Customs brokers help companies bring goods into the country without getting shipments held, fined, or charged the wrong duty. You review invoices, classify products, calculate fees, submit electronic entries, and answer questions from importers, carriers, and government officials. One shipment might contain clothing. The next could involve industrial machinery, food ingredients, or medical equipment. Remote licensed brokers earn an average of about $75,242 per year.

You do not need to spend years working in a port before becoming licensed. Eligible applicants can study the customs rules, pass the federal broker exam, complete the background process, and apply for a license. The exam is difficult, but prep courses can be completed from home. Freight forwarders, importers, manufacturers, and customs firms use remote brokers because most documents are filed electronically. Product classification still involves judgment. A small difference in materials, intended use, or country of origin can change what a company owes and whether the shipment may legally enter.

Digital accessibility tester

Digital accessibility tester
Image Credit: Getty Images via Unsplash

Digital accessibility testers check whether websites, apps, online forms, and digital documents work for people with disabilities. You may complete a checkout using only a keyboard, test a page with a screen reader, inspect captions, or find buttons that have no useful label. Then you document the problem and show the product team what the user experiences. Average pay is about $62,732 per year.

Many testers start by learning accessibility standards and practicing with free assistive technology. A certificate can help, but a small portfolio of real tests may be more useful than another broad college degree. Banks, colleges, health systems, retailers, government contractors, and software companies employ remote testing teams. Automated scanners catch missing labels and obvious color problems. They often miss whether instructions make sense, whether focus moves in the correct order, or whether a blind user can finish the task without getting trapped. Human testing matters because passing an automated scan does not mean a product is usable.

Cartographer

Cartographer
Image Credit: Shutterstock

Cartographers turn location data into maps used by utilities, insurers, environmental firms, transportation companies, and public agencies. You might map wildfire exposure, underground pipes, broadband coverage, flood risk, delivery territory, or land planned for development. The raw information can come from satellites, surveys, drones, property records, and field crews. Median pay for cartographers and photogrammetrists is about $78,380 per year.

Remote cartographers usually work in geographic information systems, better known as GIS. A geography, planning, geology, environmental science, or surveying degree is one route. A focused GIS certificate and a strong map portfolio can also lead to junior work. You will need to show that you can clean location data, use map layers, and notice when two sources conflict. Mapping tools can draw whatever they are given, including bad information. A person must decide whether a road moved, an address is wrong, or a boundary was entered incorrectly. Those decisions affect construction, insurance, emergency planning, and public safety.

Certified tumor registrar

Certified tumor registrar
Image Credit: Getty images via Unsplash

Tumor registrars read medical records and build detailed histories of cancer diagnoses, treatments, and outcomes. You may review pathology reports, surgery notes, imaging results, and follow-up care, then code the information for a hospital registry. The data helps health systems track survival rates, treatment patterns, and whether patients are receiving recommended care. Certified tumor registrars earn about $62,810 per year.

Hospitals and registry contractors hire remote workers because most of the job takes place inside electronic medical records. Entry usually requires approved coursework and the Oncology Data Specialist credential. Some people enter from medical coding, health information, or another clinical-records role, while others complete a dedicated certificate. The work is not simple data entry. Cancer cases can involve several diagnoses, uncertain dates, changing treatments, and records from more than one hospital. Registrars must understand the full story, follow strict coding rules, and question information that does not line up.

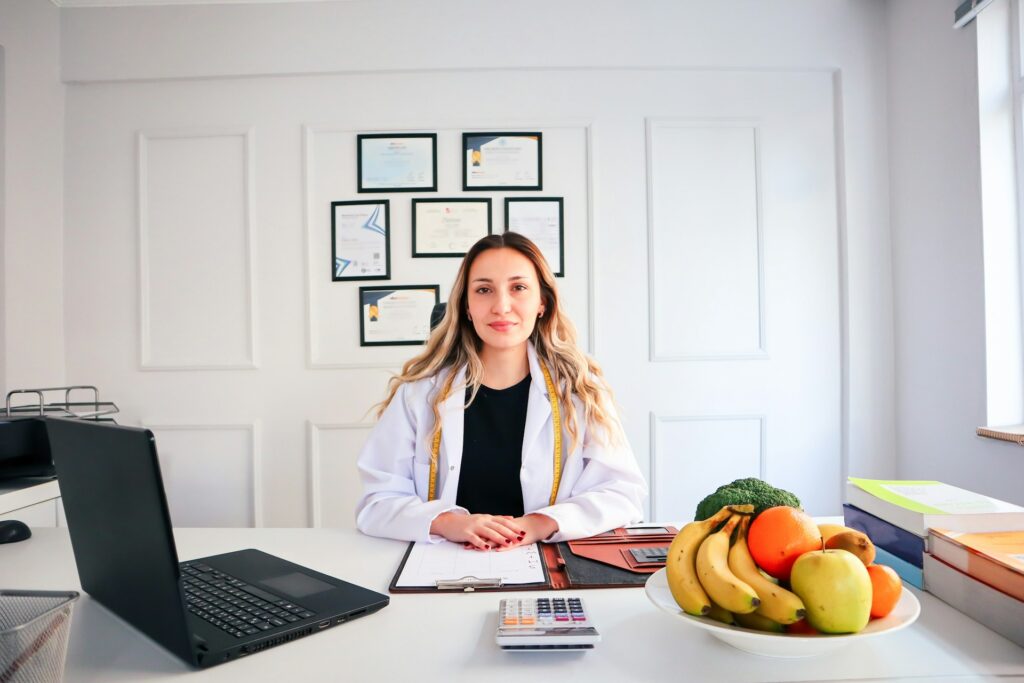
Telehealth registered dietitian
Telehealth registered dietitian
Image Credit: B.Y.G. via Unsplash

Telehealth dietitians meet with patients by video to manage diabetes, kidney disease, digestive problems, high cholesterol, food allergies, and other conditions affected by diet. You review medical history, medications, lab results, eating habits, culture, cooking ability, and budget. Then you help the patient build a realistic plan instead of handing over a generic meal sheet. Median pay is about $73,850 per year.

You must complete the required nutrition education, supervised practice, national exam, and any license required where patients live. Once qualified, you can apply for your first dietitian job with virtual clinics, health plans, hospitals, diabetes programs, and employee wellness providers. Demand is supported by rising rates of chronic illness and wider use of remote care. Food choices are personal and often tied to money, family habits, religion, medical fears, and past dieting experiences. A food-tracking app can count nutrients. It cannot persuade a tired patient to make a workable change or notice when an eating pattern points to a deeper problem.

Virtual school counselor

Virtual school counselor
Image Credit: Getty Images via Unsplash

Virtual school counselors support students enrolled in online public schools, charter schools, and private programs. A normal day may include meeting with a teenager who is falling behind, checking graduation requirements, helping with college forms, talking with a parent, or arranging outside help for a student in crisis. School and career counselors earn a median of about $65,140 per year.

The usual path includes a master’s degree in school counseling, supervised training, and the required education credential. That makes this an entry-level profession after licensing, not a job you can enter through a weekend course. Virtual schools do hire newly credentialed counselors, especially those who completed internships with middle-school or high-school students. Remote counseling is more than sending reminders about missing assignments. You must notice changes in behavior, understand family problems, respond to safety concerns, and work with teachers who may see only one part of the situation. The decisions can affect whether a student graduates or receives urgent help.

Online marriage and family therapist

online family therapist
Image Credit: Look Studio via Unsplash

Marriage and family therapists provide counseling to couples, parents, children, and other family members. Through secure video sessions, you may help clients deal with conflict, divorce, grief, addiction, parenting stress, or a major change in the household. The therapist listens for patterns, asks difficult questions, watches how people react to each other, and checks for safety risks. Median pay is about $63,780 per year.

You need a qualifying master’s degree, supervised clinical hours, and a license. Newly licensed therapists can join telehealth practices, behavioral-health companies, employee assistance programs, or group practices without first building a private client list. Employment is projected to grow much faster than average as more health plans cover mental-health care. Therapy is built on trust, timing, and careful judgment. A family may say one thing while body language shows something else. A therapist must recognize danger, challenge harmful behavior without losing the client, and adjust the session when emotions suddenly change.

Virtual corporate trainer

Virtual corporate trainer
Image Credit: Shutterstock

Virtual corporate trainers teach employees how to perform a job, follow safety rules, handle customers, use internal systems, or understand new policies. You may lead a live class for new insurance representatives one week and coach a smaller group through difficult practice calls the next. Training and development workers earn a median of about $65,850 per year.

Entry-level trainer openings often accept classroom teaching, peer coaching, onboarding, customer service, health care, claims, manufacturing, or other frontline experience. You may not need previous employment with the title “trainer,” but you do need proof that you can explain a process and keep a group engaged. Remote employers include insurers, hospital systems, banks, call-center operators, manufacturers, and government contractors. Recorded lessons cover basic information. A live trainer notices when half the class is lost, answers unusual questions, corrects risky misunderstandings, and changes the explanation when the first version does not work.

Remote procurement buyer

Remote procurement buyer
Image Credit: Shutterstock

Buyers purchase the materials and services an organization needs. Depending on the employer, you could order hospital supplies, machine parts, packaging, laboratory equipment, uniforms, or maintenance contracts. You compare vendors, negotiate prices, check delivery dates, and respond when an important order is delayed. Buyers and purchasing agents earn a median of about $75,650 per year.

Manufacturers, health systems, food companies, universities, utilities, and government contractors use remote purchasing teams. A degree in business or supply chain management can help, but some employers hire from inventory, warehouse, vendor-support, or purchasing-assistant positions. Internships and short procurement certificates can also provide a way in. Buying is not just clicking the cheapest option. A lower bid may come with weak quality, slow delivery, poor payment terms, or a supplier that cannot handle a sudden increase. The buyer must weigh those risks, negotiate with real people, and explain the decision when another department wants a different answer.

Junior production planner

Junior production planner
Image Credit: Shutterstock

Production planners decide what a factory should make, when it should make it, and whether the right materials will arrive in time. You may build a weekly schedule for food, medical supplies, electronics, packaging, or industrial parts. When a machine breaks or a supplier misses a truck, you help rearrange the plan so the most urgent orders still ship. Junior production planners earn about $63,615 per year.

Some companies centralize planning teams and let them work remotely while local supervisors run the factory floor. A business, operations, engineering, or supply chain degree is useful, but employers may also promote people with inventory, scheduling, or manufacturing experience. Entry roles usually require spreadsheet skills and a willingness to learn the company’s planning system. A computer can create a schedule based on normal conditions. Factories rarely stay normal. A delayed material, rush order, quality failure, or staffing shortage can force several bad choices, and a planner must decide which problem will cause the least damage.

Insurance premium auditor

Insurance premium auditor
Image Credit: Getty Images via Unsplash

Premium auditors check whether a business paid the correct amount for workers’ compensation or liability insurance. The original premium may have been based on estimated payroll, sales, and business activity. At the end of the policy period, the auditor reviews actual records, interviews the owner, and decides whether job classifications were accurate. Entry-level premium auditors earn about $69,194 per year.

Look specifically for remote desk-audit positions, which use payroll reports, tax forms, accounting records, and video or phone interviews instead of site visits. Insurance carriers and audit vendors train beginners in classification rules and audit software. A business degree helps, but experience with payroll records, insurance, bookkeeping systems, or business operations may be enough. This is investigative work, not accounting. A landscaping company, staffing agency, and roofing contractor can have completely different risks even when their paperwork looks similar. Auditors must ask follow-up questions and decide what the business actually does.

Remote fundraiser

Remote fundraiser
Image Credit: Vitaly Gariev via Unsplash

Fundraisers build relationships with people who may support a nonprofit, hospital, school, museum, research group, or community organization. You might hold video meetings with donors, organize a small campaign, explain what a gift would fund, and follow up with people who have shown interest. Fundraisers earn a median of about $66,490 per year.

This is not a job where you spend the day producing articles or advertising copy. The valuable part is listening, remembering what a donor cares about, making an appropriate request, and keeping the relationship honest. A bachelor’s degree is common, though volunteer campaign work, event experience, sales, community outreach, or customer relationships can help you enter without previous fundraising employment. Remote fundraisers work by phone, video, email, and donor-management systems, with occasional events depending on the employer. People rarely make a meaningful donation because a system generated the perfect sentence. They give when they trust the organization and the person representing it.

Virtual health educator

Virtual health educator
Image Credit: Getty Images via Unsplash

Health educators teach people how to manage or prevent health problems. You might run online classes for patients with diabetes, coach employees through a wellness program, explain prenatal-care resources, or help a community understand screening and vaccination options. Health education specialists earn a median of about $63,000 per year.

Hospitals, insurers, public-health contractors, universities, nonprofits, and workplace wellness companies employ remote educators. A bachelor’s degree in health education, public health, nursing, nutrition, or a related subject is the normal route. A professional health-education credential can help but may not be required for the first job. The challenge is not finding health facts online. It is helping a real person understand which facts matter, recognize bad information, and make a change that fits daily life. An educator may need to adjust the same lesson for an older adult, a new parent, and a worker who has limited time or internet access.

Grandma’s casserole dish is having a moment. Not because it matches anything in a modern kitchen, but because collectors have figured out that those cheerful turquoise mixing bowls and herb-covered casseroles from the 1960s and ’70s are worth real money, sometimes a lot of it. Every weekend, people are pulling old Pyrex out of thrift store bins for a dollar and flipping it for $200. Others are realizing that the stacked green dishes they were handed down are worth more than the kitchen shelves they’ve been sitting on.

The market for vintage kitchenware has been building for years, driven by people who find these pieces genuinely beautiful and by a growing collector base that knows exactly what it’s looking at. Certain Pyrex patterns, specific CorningWare designs, Scandinavian enamelware from Norway and Denmark, and a handful of American cookware brands have all found serious second-hand audiences. The price spread is enormous, from under $50 for entry-level finds to thousands of dollars for the rarest pieces.

Condition matters more than almost anything else here. A chip on the rim of a Pyrex bowl cuts the value in half. A complete set with its original lids is worth far more than the same pieces sold separately. And a number of the most sought-after pieces have reissues or reproductions that look similar but are worth a fraction of the original. Worth knowing before you find something at a yard sale and have to decide on the spot.

CorningWare Spice of Life with French herb inscription

CorningWare Spice of Life with French herb inscription
Image Credit: Kunamatada via eBay

Every grandma in America had the Spice of Life version of CorningWare: vegetables and herbs in earthy tones, a design most people recognize immediately. What most people miss is the inscription on the early pieces. First-generation Spice of Life casseroles carried one of several French herb names beneath the vegetable design: La Marjolaine (marjoram), L’Échalote (shallot), Le Romarin (rosemary), Le Persil (parsley), or La Sauge (sage). These “French inscription” pieces are from the early 1970s and command more than standard Spice of Life without the text.

A small individual casserole without a lid typically brings $15 to $30. A medium casserole with the original lid in good condition sells for $25 to $50. The 5-quart oval roaster is the piece collectors specifically seek, and it brings $80 to $150 in clean condition with a matching lid. Complete matched sets of four to six pieces with all original lids can reach $120 to $350 depending on number of pieces and pattern wear.

The French inscription alone doesn’t make any piece rare. A small, common casserole size with French words is still a common casserole. What matters is size, shape, and whether lids are present. The internet is full of Spice of Life listed for $500 that never sells; always check completed sales, not listing prices. The original Pyroceram material can go from stovetop to freezer; post-1998 CorningWare is stoneware and cannot. Look at the base: a “World Kitchen” or “Corelle” mark means stoneware and no collector premium regardless of what the pattern looks like.

Fire-King Jade-ite restaurant ware (late 1940s–early 1960s)

Fire King Jade ite restaurant ware
Image Credit: Prudentia Sollertia via eBay

The color stops people cold. Jade-ite is a milky, opaque jade green glass made by Anchor Hocking from the late 1940s through 1974, and the restaurant ware line was its best-selling format. These are the thick, sturdy plates, mugs, and bowls you’d find in a 1950s diner, built to take daily commercial punishment. That’s also why finding clean examples requires hunting: decades of hard use took their toll.

Common restaurant ware pieces like the standard dinner plate or the short tumbler mug bring $5 to $45 in good condition. A complete set of six plates and six mugs in excellent condition can bring $65 to $200 depending on condition quality. The gravy boat is genuinely rare and can exceed $1,000 in excellent shape. The Philbe pattern, with its distinctive molded floral design, is scarcer than standard restaurant ware and commands more across all pieces.

Before buying, check the base. Genuine vintage Fire-King pieces say “Fire-King Oven Ware” in script and may include the Anchor Hocking anchor logo. Pieces stamped with “2000” alongside the Fire-King mark are from a reissue done that year and are not vintage originals; they look similar but carry no collector premium. The color should be a consistent milky jade throughout the piece, with no streaking or patches of clear glass. Heavy scratching from commercial use reduces value significantly, so examine the bottom and interior surface carefully under good light.

Cathrineholm lotus enamel serving bowl

Cathrineholm lotus enamel serving bowl
Image Credit: british-vintage via eBay

Cathrineholm was a Norwegian enamelware factory that ran from 1907 until 1972. Designer Grete Prytz Kittelsen shaped the forms and the palette; Arne Clausen designed the lotus leaf motif that became the line’s signature. The lotus series came out in the 1960s in a range of mid-century colors: tangerine, avocado, royal blue, lemon yellow, butterscotch, and more. The pieces are unmistakable on a thrift store shelf, and the collector base has grown sharply over the past decade.

Single serving bowls in common colors bring $75 to $150 depending on size and condition. Pink lotus is genuinely rare and sells for considerably more. The coffee pot with its original black plastic handle brings $100 and up for common colors. Rare colorways including French blue and the two-tone lemon-lime combination are the hardest to find and command the highest premiums.

Chips in the enamel reduce value sharply, as does rust at the rim where the factory polished the enamel down to bare metal to prevent chipping. Inspect rims closely. To authenticate, look at the lotus petal shape: genuine Cathrineholm petals are wider toward the top and taper at the base, like a real leaf. Knockoffs that exist tend to have the leaf widest in the middle, like a coffee bean shape. The authentic pieces may or may not carry a factory stamp since some came with paper labels, but the petal shape doesn’t lie.

Revere Ware pre-1968 copper-clad saucepan or skillet

Revere Ware saucepan
Image Credit: FlipsandFinds2023 via Etsy

Thrift-flipping social media has written off Revere Ware as not worth picking up. That advice ignores the key distinction. Pre-1968 Revere Ware, before a manufacturing change thinned out both the copper and stainless steel layers to cut costs, is consistently collectible and sells at a real premium. Individual pre-1968 saucepans and skillets average around $44 per piece in the resale market, a number that regularly exceeds what you’d pay at a thrift store by a meaningful margin.

The base stamp tells the story. Pieces made from 1946 through 1968 carry a left-facing Paul Revere silhouette inside a double-line circle, plus the words “Made Under Process Patent” or “Pat. Pending.” That patent language is the essential identifier: no patent reference means post-1968 production with thinner, less valuable copper cladding. A pre-1968 tea kettle in good condition brings around $125. Specialty pieces like the coffee percolator, loaf pan, or measuring cup set are more desirable than basic sauce pans because fewer were made and kept.

Condition matters in two places specifically: the copper bottom and the Bakelite handle. The copper bottom can be polished, which is acceptable and fine for use, but heavy pitting or corrosion hurts value. The Bakelite handle is original to the piece and can’t be replaced without affecting what it’s worth, so look for cracks or crazing in the plastic. A dirty, tarnished pre-1968 piece is not a lost cause; Bar Keepers Friend removes decades of residue without harming the metal. What you can’t restore is a replaced handle or a cracked pot.

Hall China Autumn Leaf Aladdin teapot

Hall China Autumn Leaf Aladdin teapot
Image Credit: SimplyMarvelousMary via Etsy

Hall China made the Autumn Leaf pattern exclusively for the Jewel Tea Company from 1933 to 1978. It was never sold in retail stores; the Jewel Tea salesman brought it to your door as part of a promotional incentive program. That 45-year run created an enormous collecting base and a pattern that almost everyone of a certain age recognizes. The Aladdin teapot, shaped like a stylized Aladdin lamp with the rust-orange Autumn Leaf decal, is the most recognizable single piece in the line.

Clean examples with no chips, no cracks, and a bright unfaded decal typically bring $75 to $200. The early Aladdin shapes from the 1940s are more valuable than later versions. Rarer early production teapots (the Streamline, Philadelphia, or Donut shapes from the 1930s and early 1940s) bring $150 to $700, and the novelty shapes like the Football teapot in Chinese Red (Hall’s name for an orange-red glaze) can push to $1,200 and beyond.

The National Autumn Leaf Collectors Club (NALCC) has commissioned new limited-edition pieces from Hall China since 1984. These reissues carry an NALCC symbol and issue year on the base and sell for $20 to $80, not at vintage prices. Original Jewel Tea production pieces are marked “JEWEL” on early examples and “HALL” on later ones, without the NALCC designation. A complete Autumn Leaf kitchen including canister set, batter bowl with lid, and teapot in matching condition is worth considerably more than any single piece purchased alone.

Pyrex pink Gooseberry 4-piece mixing bowl set

Pyrex Gooseberry
Image Credit: VCPvintagekitchen via Etsy

The Gooseberry pattern, with its stylized berries and curling vines, came in two colorways: turquoise on white and, much rarer, pink on white. Turquoise Gooseberry is common enough that complete sets move at the lower end of the Pyrex market. Pink Gooseberry is a different conversation entirely. The 404 bowl (the largest in the standard 401-404 nesting set) alone brings $80 to $150 in good condition, and a complete four-piece set in the pink colorway typically brings $175 to $400 depending on color intensity and whether all four bowls are chip-free.

Pink Pyrex is more valuable across patterns because the pink production runs were shorter and fewer pieces survive in good condition. The color fades more visibly than turquoise and is more sensitive to dishwasher damage. When evaluating any Pink Gooseberry bowl, hold it up to strong light: the opalescent glass should glow milky white with consistent pink coverage. Fading, splotchiness, or a gray undertone means the piece has been through too many dishwasher cycles and will bring considerably less than excellent-condition pricing.

The standard 401-404 set has straight-sided bowls with a smooth rim. The Cinderella 441-444 set uses the same Gooseberry pattern but on bowls with angled side handles. Both sets exist. The Cinderella format commands a slight premium because the bowls see less heavy mixing use, meaning they’re often in better condition. Matching a complete set with consistent color intensity across all four pieces is what pushes prices to the high end of the range.

Pyrex Snowflake Blue complete refrigerator dish set with lids

Pyrex Snowflake
Image Credit: Kathoula via eBay

Snowflake Blue came out in 1972 as part of Pyrex’s Compatibles line, designed to coordinate with Corelle dinnerware. The pattern is a garland of snowflakes, swags, and dots in alternating blue-on-white and white-on-blue on different pieces in the set. Production ran until 1976, and that short window has kept the supply genuinely limited. The refrigerator dish set, three rectangular stacking containers (501, 502, 503) each with its own fitted lid, is the most pursued format.

A complete refrigerator set with all three lids intact brings $60 to $150. The word “complete” carries enormous weight here. The lids crack easily and are frequently missing, which is why finding a full set in one place is harder than it sounds and worth paying for when you find it. A four-piece Snowflake Blue Cinderella nesting bowl set (441-444) in the original box can start at $189 and go higher depending on condition. Any set missing a lid or a bowl is worth significantly less than a complete one.

Check each lid carefully by running your finger around the entire rim. Chips and hairline cracks are easy to miss under dim lighting and will render a lid worth very little to collectors who care about completeness. The pattern on all pieces should be consistent and vibrant; mismatched color intensity across a set suggests different dishwasher histories for different pieces. Snowflake Blue turns up less often than Butterprint or Gooseberry at estate sales, which is part of why a complete set brings what it does.

CorningWare Wildflower casserole set (1977–1984)

CorningWare Wildflower casserole set
Image Credit: theLORD’santiques via eBay

Wildflower is one of the most visually distinctive CorningWare patterns: small, delicate blue wildflowers on white Pyroceram with a botanical illustration quality that sets it apart from the bolder designs of the earlier production era. The production window was only seven years, making genuine surviving pieces less common than Blue Cornflower or even Spice of Life. Wildflower sat at the center of the 2018 viral CorningWare frenzy, and while prices corrected after the bubble, the underlying collector demand remains strong.

Individual pieces in excellent condition bring $20 to $60 for smaller casseroles, $40 to $100 for mid-size casseroles with their original lids, and $80 to $250 for the large 5-quart oval roaster. A complete matched set of six or more pieces with all lids present brings $150 to $400. What drives Wildflower prices specifically is pattern clarity: the delicate floral detail shows wear more visibly than bold patterns, and a piece where the flowers look crisp and bright is worth 40 to 70 percent more than the same piece with visible rubbing or fading.

Wildflower is genuine Pyroceram and can tolerate stovetop-to-freezer transitions. Post-1998 CorningWare is stoneware and cannot. The base mark tells the story: “World Kitchen” or “Corelle” branding means stoneware and no collector premium regardless of the pattern. Original Pyroceram has “Made in USA” and the Corning oval without any successor corporate branding. Tap the side of the piece with a fingernail; Pyroceram rings clearly, stoneware produces a dull thud.

CorningWare Medallion (1972–1975)

CorningWare Medallion
Image Credit: Redge’s Used Vintage Overstock via eBay

Medallion lasted only three years in production and never made it into most households’ cabinets, which is exactly why collectors light up when it turns up in thrift stores. The pattern is a bold ochre-gold starburst radiating outward on white Pyroceram, graphic and mid-century modern in a way that looks deliberate rather than dated. People who don’t recognize it don’t know what to price it at, which creates the best buying opportunity in the CorningWare category: a genuinely scarce pattern that still regularly appears underpriced because it’s not as well-known as Wildflower or Spice of Life.

Individual Medallion pieces in excellent condition bring $30 to $100, with larger oval roasters and unusual shapes pushing toward $200. Matched sets are rare because the production run was short and pieces have scattered across the years; a set of three or more pieces with lids in excellent condition can bring $200 to $500. Interior design buyers and CorningWare collectors compete for Medallion because the starburst design works as decor independently of its cooking function.

The 3-year production window means Medallion is more consistently underpriced than patterns made for decades. A thrift store staffer who knows that Wildflower and Spice of Life are valuable may never have encountered Medallion. Learn to recognize the gold starburst and you have a real knowledge advantage. Same authentication rules apply as any vintage CorningWare: chip-free rim, vibrant pattern, no crazing, “Made in USA” base mark, and no World Kitchen branding.

Cathrineholm lotus Dutch oven with lid and chrome handles

Cathrineholm lotus Dutch oven with lid and chrome handles
Image Credit: AnniethingUpcycled via Etsy

The Cathrineholm Dutch oven is the most substantial and consistently valuable common piece in the lotus line. These come in sizes from 1-quart up to 8-quart, with short side handles enclosed in a chrome ring assembly and a fitted lid. Larger sizes (3-quart to 5-quart) in excellent condition with original lids and intact chrome handles can bring $150 to $400 and more, with a single blue lotus Dutch oven in clean condition selling around $465. Multi-piece sets in a single color bring considerably more than individual pieces.

The chrome ring handle assembly is a known weak point: rust can develop where it meets the enamel, and the rings can scratch the pot if removed carelessly. A Dutch oven with a clean, rust-free ring and a lid that fits properly without rocking is the target. The lid knob is a small chrome piece that breaks off more often than it should; a missing or cracked knob reduces the lid’s value significantly. A Dutch oven without its original lid sells for much less than a complete piece.

Rare colors command premiums. Orange and avocado green are the most commonly found and still consistently valuable. Pink lotus pieces are much harder to locate. The French blue colorway is among the rarest Cathrineholm produced and commands the highest prices when it surfaces. Every genuine piece is at minimum 50 years old since the factory closed in 1972. Some generic lotus-pattern enamelware from other manufacturers can be confused with Cathrineholm: the authentic pieces have petals that widen toward the top and taper at the base, which knockoffs typically don’t replicate correctly.

Dansk Kobenstyle France-stamped casserole or Dutch oven

Dansk Kobenstyle France stamped casserole
Image Credit: KissaJSales via eBay

The butter warmer is accessible; the casserole is a different category entirely. The Kobenstyle casseroles, Dutch ovens, and covered pots from the original French and Danish production era are what collectors specifically seek. These pots center on a distinctive trivet-lid design: flip the lid over and the X-shaped handle allows it to sit flat as a trivet, with a practical logic built into the form. In excellent original condition with the matching lid, they bring $75 to $200 for a standard 2-quart or 4-quart, with larger and rarer formats going higher. The 6-quart round Dutch oven in chili red in near-mint condition can push toward $300.

The base stamp authenticates the piece: “Dansk Designs Denmark IHQ” or “Dansk Designs France IHQ” marks original Quistgaard-era production. The IHQ initials stand for Jens Harald Quistgaard. French-made pieces carry slightly more collector appeal than later production and tend to feel heavier with more even enamel application. Thailand-made pieces without the IHQ mark are significantly less valuable and should be treated as modern cookware, not collectibles.

Chip-free enamel interior is essential; a single visible chip on the cooking surface cuts the value in half on what would otherwise be a premium piece. The most desirable colors remain the four Quistgaard originally selected: chili red, dark blue (often called midnight blue), goldenrod yellow, and turquoise. Of these, dark blue on a large format piece is consistently the most sought after. The paella pan format, a wide shallow two-handled casserole, is harder to find and commands a premium when clean.

Revere Ware pre-1968 complete set

Revere Ware pre 1968 complete set
Image Credit:
tyler2610 via eBay

Individual pre-1968 pieces are worth knowing; a complete set is where the real money sits. A well-preserved set of 9 to 12 pre-1968 pieces, including sauce pans in two or three sizes, a stock pot, a skillet, and the original lids, sells for $375 to $600 in the current market. A 24-piece set in good original condition has sold at the high end of that range and above.

What makes a set rather than a collection of pieces is matching: same era, same manufacturing plant, consistent condition across all pieces. Mismatched lids from different eras reduce a “set” to a mixed lot worth much less. Original Bakelite handles across all pieces signal the same pre-1968 production era. Check the copper bottoms for consistent thickness relative to the pan wall. A set where some pans have visibly thicker copper than others is a mix of pre- and post-1968 pieces and should be valued and described accordingly.

A dirty, tarnished pre-1968 set found at a barn sale is not a lost cause. Bar Keepers Friend removes decades of cooking residue and tarnish from both the copper and stainless without harming the metal. What doesn’t come back is a replacement handle that’s been glued rather than bolted, or a pot with a crack that’s been disguised by residue. Clean the base stamp of any piece before walking away from it; the patent language confirming pre-1968 production can be buried under decades of accumulated grime.

Hall China Football teapot in Chinese Red

Hall China Football teapot in Chinese Red
Image Credit: SuesVintageAddiction via Etsy

Hall China produced novelty teapots in dozens of shapes: automobiles, Aladdin lamps, basketball balls, and birdcages among them. The Football is exactly what it sounds like, a teapot molded in the shape of an American football, with a spout at one end and a handle above. It was made in 1938, which means surviving examples are close to 90 years old. In common colors it’s a significant collectible. In Hall’s signature Chinese Red glaze, a distinctive orange-red that the company developed and used across its most desirable pieces, it becomes one of the most coveted single items in American kitchen collecting.

A Football teapot in Chinese Red brings $600 to $1,200 depending on condition. The spout tip and the handle attachment points are the most vulnerable areas; any hairline crack or chip at either location reduces value sharply. The lid must be original and from the same glaze batch, meaning the Chinese Red on the pot and lid should match in tone. A lid that reads slightly darker or lighter than the pot suggests a later replacement, which collectors notice and price accordingly.

Hall produced reissue versions of several popular teapot shapes in the modern era, and these carry different base marks than original 1930s production. An original 1938 Football teapot will have a Hall China mark consistent with that era, not a contemporary production stamp. The Football teapot collector community is knowledgeable and active, so authenticated examples with proper marks change hands at strong prices while mis-attributed examples stall. Verify the base mark against known examples before paying significant money.

Pyrex Lucky in Love 1-qt round casserole (1959)

Pyrex “Lucky in Love” casserole
Image Credit: ILoveMinisCanada via Etsy

No other Pyrex piece has the reputation Lucky in Love does. Corning released this pattern on exactly one shape, the 1-quart round casserole (model number 473), in 1959. The design is simple: green grass and clovers along the base with pink hearts in the middle. It was either a test piece or an extremely limited promotional release and disappeared almost immediately. The Corning Museum of Glass holds one example in its permanent collection, the only known version with clovers but no hearts at all. The market has seen pieces regularly bring over $4,000, with at least one competitive auction in 2022 reaching more than $22,000.

The design is the authentication challenge. Because Lucky in Love is so well known among collectors, reproductions and re-decorated pieces exist. Genuine examples have the pattern silk-screened directly onto the opalescent glass with the colors slightly recessed into the surface, which is characteristic of Corning’s process. Any sign of a raised or applied-on-top pattern, rather than slightly recessed silk-screening, is a serious red flag. The glass itself should be the warm, milky opalescent tone consistent with late-1950s Pyrex production, not a cleaner or more modern-looking white.

Most people will never encounter a Lucky in Love casserole at a thrift store. But if you’re working through a kitchen cabinet at an estate sale and find a small 1-quart casserole with hearts and clovers that you don’t recognize from any common pattern, look carefully before setting it back down. The PYREX mark in all capitals on the base, the model number 473, and the right glass tone are the three things to verify. If all three match, you’re not looking at a three-dollar thrift store find.

Pyrex Balloons casserole

Pyrex Balloons casserole
Image Credit: LucysMidCentury via Etsy

Lucky in Love is the most famous rare Pyrex, but Balloons may be the genuinely hardest to find. The production was so limited that complete records of how many pieces were made don’t fully exist. The design is colorful balloons on white opalescent glass, printed on casserole shapes. Clean examples in good condition bring $200 to $600 and above, with condition and the specific casserole format affecting where in that range the price lands.

Because the piece is so scarce, most collectors who have one aren’t selling it. What shows up in the market is usually estate sale material, pieces that came out of a collection whose new owner didn’t realize what they had. The pattern name isn’t printed on the piece and isn’t obvious to someone who hasn’t specifically studied Pyrex patterns. This is the category where collector knowledge creates the most dramatic buying advantage: the person who recognizes it can pay a realistic thrift-store price; the seller often has no idea what they’re holding.

Every standard Pyrex condition check applies here at maximum importance. No chips anywhere on any edge. Full, vibrant pattern without fading. Correct opalescent glass color. All-caps PYREX with MADE IN USA on the base. A Balloons casserole with a chip on the rim is still an interesting and valuable piece, but it’s worth significantly less than a chip-free example. The rarity makes any intact example worth keeping or buying carefully. Paying full prices for a damaged example is a different calculation.

CorningWare Black Starburst (1959–1963)

CorningWare Black Starburst
Image Credit: slamhard112 via eBay

Black Starburst was produced for roughly four years in the very early CorningWare era, when Corning was still working out which designs American kitchens would welcome. The pattern is a bold geometric starburst in black on white Pyroceram, and it was apparently too stark for mass-market appeal: it was discontinued quickly and never returned. That brief window, combined with decades of attrition, makes it genuinely scarce in a category full of pieces that were made by the millions.

Individual Black Starburst pieces in good to excellent condition bring $50 to $200, with larger pieces like the oval roaster pushing toward $400. Complete sets of three or more pieces bring $300 to $800 and above. It surfaces rarely in thrift stores precisely because collectors who find it hold onto it. When it does appear at an estate sale, it’s often mixed in with less valuable CorningWare and priced the same as a standard Blue Cornflower casserole.

The same authentication rules as all vintage CorningWare apply: the Corning oval without World Kitchen or Corelle branding, “Made in USA” on the base, and the “P” prefix in the size code indicating Pyroceram rather than stoneware. The physical test is the clearest: tap the side with a fingernail. Pyroceram produces a clear, bell-like ring. Stoneware produces a dull thud. An original 1959 to 1963 Black Starburst piece will ring clearly. If it doesn’t, walk away.

There is a particular kind of woman who can finish every task on her list, hit every deadline, take care of everyone who needs her, and still sit down afterward unable to actually enjoy the stillness she just earned. Therapists have started calling this rest resistance, the inability to be unproductive without a low hum of guilt running underneath it, even once the circumstances plainly justify a break. It rarely comes from laziness or bad time management. It comes from a nervous system that learned somewhere along the way that being useful was what kept you safe, loved, or worthy of taking up space. A five minute round of Playsolitaire during a break you have every right to take can feel like a strangely good place to practice sitting with that discomfort in small, low stakes doses.

The body learned this long before the to-do list did

Rest resistance rarely starts as an adult problem. It usually traces back to environments, whether a demanding childhood home or a career that rewarded constant output, where stillness was never modeled as safe or deserved. If productivity was the currency that earned attention or approval, the nervous system quietly filed away a rule that has nothing to do with logic. Being still equals risk. Being useful equals safety. Decades later, a person can consciously know they deserve a break and still feel a physical unease the moment they actually take one, because the body is running an old script the calendar cannot override on its own. This is often most visible in women who have already achieved plenty of proof that they are capable and worthy, which is precisely what makes the guilt so confusing from the outside. Logic says the case is closed. The nervous system never got the memo.

Why self-compassion works where willpower doesn’t

Telling a person with rest resistance to simply relax rarely works, in the same way telling someone to stop worrying rarely helps. Research on self-compassion, most notably from psychologist Kristin Neff, points to something more useful than willpower. Her framework rests on three parts working together, treating yourself with the same kindness you would offer a friend, recognizing that struggling with this is a shared human experience rather than a personal failing, and noticing the guilt without being swept away by it. Self-compassion consistently shows up in the research as a genuine buffer against burnout, precisely because it targets the self-criticism that keeps rest resistance running, rather than trying to out-discipline a nervous system that was never the problem to begin with. Self-criticism, by contrast, tends to do the opposite of what it promises. It rarely produces more discipline. It mostly just produces more shame attached to the very rest a person was already struggling to allow.

Starting with something small enough to not feel guilty about

The most workable way through rest resistance is rarely a dramatic gesture like a week off that ends up feeling more stressful to arrange than the work itself. It is closer to letting yourself receive something small before attempting anything large, a genuinely unproductive five minutes that does not need to be justified as self-care, mental health, or anything else with a job to do. A quick, quiet card game asks nothing of you and produces nothing you have to account for afterward, which is exactly what makes it useful as a first rep. Nobody rebuilds their relationship with rest in one sitting, but every small stretch of time spent doing something with absolutely no productive output attached to it is a little evidence, gathered slowly, that stillness will not cost you anything after all.

Many citizens don’t consider estate planning a pressing issue, especially in the USA. A 2025 study undertaken by Trust & Will strengthens this fact. The study shows that fifty-five percent of individuals in the United States possess no documents related to estate planning. Only 31% have a will, and 11% have created a trust.

Making a living trust is one of the most straightforward methods of securing one’s properties, simplifying the issue of transferring them to others, and bypassing the probate process. It plays a key role in the framework of inheritance planning and helps keep control of some assets. It protects properties during distribution and prevents their unwarranted use in case the owner is unable to operate them. 

Like other estate planning tools, state laws directly influence living trusts. Being familiar with them is important. For instance, knowing how to create a living trust in Louisiana does not necessarily mean that this knowledge applies to other states. Slight differences in state laws can restrict how one is able to carry out the establishment of a living trust.

At times, establishing a trust can look too complex, but knowing what happens or is required can also help in making proper decisions that would give due attention to the financial status of your family.

Let’s go through the most important steps one should take in forming a living trust and look at the key points and mistakes that need to be addressed. Obtaining knowledge in these matters allows one to establish an estate plan that adequately caters to the needs of beneficiaries.

What a living trust does and does not do

A living trust, also known as a revocable living trust or an inter vivos trust, is a legal structure that one creates while still living. It entails transferring one’s property, such as real estate or bank cash, to the trust. Normally, the creator of the living trust appoints themselves as trustee (to be in control during their lifetime) and selects an alternate trustee to assume the role in the event of their incapacitation or death.

What it does, in practice:

  • Probate avoidance: If your assets are in the trust when you pass away, they move straight to your beneficiaries without court involvement, which usually results in less time and lower attorney fees.
  • Privacy: Unlike a will, a living trust is not filed with a court, so it doesn’t become a public record. This secure and private feature matters to some people.
  • Incapacity planning: If you can’t manage your money anymore, your successor trustee can step in immediately. You don’t have to go through a court-watched conservatorship-style procedure.
  • Bypassing probate in different territories and centralizing inheritance: If you have immovable property in several states, the establishment of a trust with sufficient funds might solve the issue of holding separate probates in every state.

What it does not do:

  • Creditor protection: a revocable living trust does not really block creditors while you’re still living. Since you keep control and can revoke it, those assets are still basically reachable by creditors.  
  • Estate tax reduction: assets in a revocable trust remain in your taxable estate. The trust by itself does not lower estate taxes; estate tax strategies usually involve irrevocable trust arrangements on top of this  
  • Medicaid liability: assets held in a revocable trust would, in any event, be included in Medicaid calculations, since you still control these assets.

Revocable vs. irrevocable: Which structure applies to your situation

The distinction between a revocable vs. an irrevocable trust is important since it spells out the terms under which any given trust designed as one or the other can operate.

The revocable living trust is an estate planning tool that gives you the ability to amend terms, change your beneficiaries, add assets, remove assets, and even revoke the entire trust during your lifetime. Most people who are making a simple estate plan use a revocable trust.

With an irrevocable trust, assets are permanently removed from your control and from your taxable estate. After it’s set up, the terms usually cannot be changed without court involvement or, often, beneficiary consent. The tradeoff for losing control is that you get things a revocable trust typically cannot deliver: creditor protection, estate tax reduction for higher net worth estates, and Medicaid planning advantages. 

Irrevocable trusts fit particular planning goals, and they need careful review with an estate planning attorney before you go forward.

Before setting up a living trust, it’s important to understand the potential costs involved. For a breakdown of expenses, 299Trust explains how pricing can vary depending on whether you use an online service or hire an estate planning attorney.

Consulting a lawyer would help address these seemingly overwhelming tasks. According to an estate planning and probate lawyer, lawyers will carefully and thoroughly evaluate your situation. They are trained to identify the most appropriate types of trusts that could be beneficial additions to your estate plan.

The three roles in any trust

Every trust document names three different roles, and understanding these roles helps reduce confusion that can lead to disputes later, after death.

The individual who establishes the trust and puts funds in it is known as the ‘grantor’ (occasionally referred to as a ‘settlor’ or ‘trustee’). In the case of a living trust, the grantor is often also the initial trustee.

The trustee manages the trust asset in accordance with what is written in the trust instrument. While you are alive and able to manage things, if the trust is revocable, you will be your own trustee. But if you become incapable of managing things yourself, then the successor trustee will automatically come into action without needing any further court action.

The beneficiaries are the people or organizations that actually receive the trust assets. During your lifetime under a revocable trust, you are the only beneficiary. After you pass, the beneficiaries named in the document will receive what you left for them.

A capable, trustworthy successor trustee will manage your finances if you become incapacitated or suddenly pass away. It is always best to anticipate this scenario and name at least one alternative successor in case the main successor cannot take over the task.

Funding the trust: The step most people get wrong

Funding is the step where you transfer legal ownership of your assets from your name to your name as the trustee of the trust. Until that transfer happens, those assets are still sitting in your individual name, and they stay subject to probate.

How different asset types are funded

  • Real estate: usually means you need to record a brand-new deed that moves the property from your name into your name as trustee. The exact deed type can look different depending on the state. 
  • Bank and investment accounts: you contact the financial institution, then ask for a re-registration into the trust name. In some cases, trust account particulars have to be altered from, say, “Jane Smith” to “Jane Smith, as Trustee of the Jane Smith Revocable Living Trust dated [date]” to accommodate what is stipulated in the trust documentation.
  • Retirement accounts: These things include 401k accounts and Individual Retirement Accounts (IRAs) and should not be transferred to the trust. If you do, it can trigger a taxable distribution. Instead, you can name your trust as the beneficiary designation when appropriate, or you can name individuals directly. An estate planning attorney can help you pick the proper setup that matches your situation and goals.
  • Life insurance: update the beneficiary designations, not ownership. The right beneficiary structure depends on how your overall estate plan is built and what outcomes you care about.
  • Business interests: LLC membership interests, partnership interests, and corporate stock usually need specific assignment paperwork. The exact method varies a lot by entity type and by what your operating agreement says.

After you fund the trust, go back and review the trust asset list any time you acquire something big. 

What belongs in the trust document

The living trust includes relevant provisions for the proper management of the trust while the grantor is alive. It should also include terms that specify the actions to take in case of incapacity. The document should explicitly provide instructions regarding the determination of the next successor trustee and its order, as well as the identity of the beneficiaries of the trust and the trust terms that apply to them.

The purpose of generic templates, which can be found online, is to assist in the creation of legal documents. Be warned that these documents are usually not suitable for immediate use and should be reviewed and modified according to one’s state laws, specific house setup, or personal property. A template that works in one state can be a problem in another, and even one that fits a fairly simple family situation may not cover the added complexities from blended families, disabled beneficiaries, or business ownership. 

Getting an estate planning attorney to review or draft the trust is an investment that can help prevent post-death arguments and distribution breakdowns.

A living trust is a probate avoidance tool, an incapacity planning mechanism, and a privacy protection for your estate. 

The paperwork itself is just the starting point. The funding is the part that really makes it work. A fully funded revocable living trust, paired with refreshed beneficiary designations and a pour-over will to snag any assets that weren’t properly retitled, is what actually allows a probate-free transfer.

An estate planning attorney familiar with your state’s laws can draft the trust, oversee or guide the funding, and integrate it into a comprehensive plan that addresses incapacity planning, tax exposure, and distribution goals.

Several Americans still have no estate planning documents, according to Trust & Will. They have conducted a national survey of 5,000 US adults from January 28 to February 5, 2026, and its result says that 56% of US adults have no will, trust, medical POA, financial POA, or HIPAA authorization. This data remains unchanged from the previous year, with 55% of individuals having no wills or trusts.

Managing assets depends on your overall estate plan. According to a Beaumont probate lawyer, probate is the legal process used to settle the debts of a deceased person and transfer their inheritance to the heirs and named beneficiaries. Understanding how it works can help you determine whether an asset should be placed in trust.

The downside of the probate process is its lengthy delays. A revocable living trust can resolve the issue since it avoids probate and allows assets to go directly to beneficiaries.

It is common knowledge that trusts achieve their full potential only when properly funded. Putting the right kind of assets in a trust helps to avoid the risk of a potential increase in taxes and the loss of legal safeguards. A wrongly placed asset could lead to delays that could compromise the trust’s objectives. That’s why it’s important to know what assets should not be in a trust, not only what to put in. 

Let’s discuss how trust operates and the suitable assets that should be placed in it.

Why the wrong assets in a trust cause problems

Some assets already have their own natural transfer setup, and moving them into a trust can end up overriding those rules in a way that may cost beneficiaries some money or at least slow down access.  

The IRS and state laws often look at certain assets, mainly retirement accounts and other tax-advantaged savings types, as belonging to the individual, not to a legal entity. Once those accounts are titled to a trust, the tax treatment shifts immediately.

Retirement accounts: The highest-stakes mistake

An IRA, 401(k), or 403(b) transfer that goes directly to a trust is treated as a distribution. That means the full account balance is treated as taxable income in the year of transfer. For a $500,000 IRA, that could push a beneficiary into the highest federal tax bracket.

The SECURE Act changed the rules further

Many beneficiaries were able to take withdrawals from their IRA in a controlled manner that was spread throughout their lifetime until the year 2020. After the enactment of the Setting Every Community Up for Retirement Enhancement (SECURE) Act, said option was not possible anymore. The ACT required most non-spouse beneficiaries to have drawn the funds within a ten-year period.

But if a trust is named instead of a person, the rules are stricter. A trust that doesn’t count as a “see-through” trust under IRS guidelines may have to distribute the entire account within five years. Even the see-through trusts aren’t totally safe from a faster timeline. These trusts have their required distribution schedules compressed, which means they reach higher tax rates faster.

What to do instead

The most favorable arrangement is normally to directly include individuals as the beneficiaries. This configuration should be regularly reviewed and updated after marriage, the breakdown of marriage, or the death of any of the named beneficiaries. For those who want to steer how a minor or someone financially vulnerable receives the money, it’s smart to talk to an estate planning attorney about naming the trust as a backup beneficiary with a properly built accumulation trust. 

Assets with no transfer option at all

Certain assets are legally non-transferable into a trust in the first place. Social Security benefits fall into this category, along with cash held outside a bank account. Neither can be assigned to a trust directly under federal rules governing how those benefits and funds are held.

Health savings accounts and medical savings accounts

Health savings accounts and medical savings accounts fall under two pre-existing schemes of tax-beneficial regulations. They function as individual trusts under federal law. Placing one inside another trust is not allowed.

The alternative is to name a beneficiary on the account directly. A surviving spouse is allowed to treat an HSA left to them as their own, which prevents the account from becoming taxable when transferred. An HSA ceases to be such once it has an owner other than a spouse. Usually, the beneficiary of the account must pay tax on the fair market value of the account in the year the account owner died. If the estate of the deceased person is the owner, it is likely that the HSA account’s value will be indicated when the decedent’s final income tax return is filed. That limitation is worth understanding before assuming an HSA belongs in a broader estate plan.

Life insurance policies

A life insurance policy already bypasses probate when it has a named beneficiary. The death benefit goes directly to that person without court involvement. Transferring the insurance policy to a revocable trust does not bring any advantages to an individual’s estate planning process and might actually hinder process time.

Exceptions may include an Irrevocable Life Insurance Trust (ILIT), which is a separate scheme established to help in cutting down on the cumbersome death benefit that could be counted in the taxable estate of a very wealthy person. This is a deliberate structure, not the same as dropping a policy into a general revocable trust. For most people, the simplest approach is naming beneficiaries on the policy directly and reviewing them after major life events.

Motor vehicles

Putting a car, truck, or motorcycle into a trust can create a title issue that many people do not expect. In most states, they will want the vehicle retitled so it shows up in the trust name. That detail can mess with insurance coverage. Some insurers just refuse to cover a vehicle held in trust, or they want extra endorsements that cost more.  

If a trust-owned vehicle is in a crash, the lawsuit could pull in the trust itself and the trust’s assets. Many cars below a certain value level do not have to go through probate in many states, so the original reason for putting them in a trust in the first place is weakened.  

Practically, a transfer-on-death (TOD) vehicle title is often a better route, since it is available in most states. You can also handle this type of asset with a straightforward clause in a will.

Jointly owned accounts and property

When someone has property with another person under joint tenancy with right of survivorship, it passes straight to the remaining owner if one person dies. There’s no probate process and also no trust that’s strictly required. But once you place that kind of property into a trust, it can effectively unravel the joint tenancy, and that’s where you can get some unintended results for the surviving person. It might even set off a property tax reassessment in certain states.

This kind of issue also shows up with joint bank accounts. If the account is created with a right of survivorship, the surviving account holder automatically gets the money. If instead you use a payable on death, or POD, designation for an individual account, you can usually reach a similar outcome without needing the joint ownership setup. Either approach can make trust inclusion unnecessary.

The coordination problem most estate plans miss

One of the issues where many people still make big mistakes in estate planning concerns the role that beneficiary designations and trusts play. It is immaterial how well the trust is constructed but if for instance, a retirement account still holds an ex-spouse’s name as the beneficiary, then the latter will receive the money. In each and every case, the account holder directs who is to receive the money and that decision prevails against the imposed trust designs.

That means the practical work of estate planning extends beyond just funding a trust correctly. It is important to review all beneficiary designations made at the account level, all payable on death (POD) or transfer on death (TOD) forms, all assets held in joint ownership structures, etc.

Putting it together

What makes trusts valuable is the control of the transfer of assets, which people can exercise. That control only holds when the trust is funded with assets that actually belong in it. It is common when establishing a trust that certain types of assets, including retirement accounts, HSAs, life insurance policies, vehicles, and jointly owned assets, have specific transfer mechanisms that are often more effective than using a trust. In that situation, it would only be counterproductive to try to transfer such assets to the trust, as it would simply bring back the very problems that made the settlor want a trust in the first place.

Estate planning research consistently shows that unfunded or improperly funded trusts are among the most common reasons an estate plan fails to work as intended. The document is only as effective as the assets properly titled within it. Reviewing each asset category separately and coordinating beneficiary designations with the broader plan are what make a trust function as intended.

Medicare’s standard Part B premium runs $202.90 a month in 2026. If your income is modest, the government will pay that for you, along with your deductibles and copays on top of it. Seven million people are already enrolled in the program that does this. Millions more qualify and have never applied.

That’s one program. There are a dozen more, ranging from monthly cash payments to prescription savings to property tax breaks that can add up to several thousand dollars a year. Most retirees don’t know these programs exist, or assume their income is too high, or figure the paperwork isn’t worth the trouble.

The income limits are often higher than people expect. The paperwork usually amounts to one form. And the money is real.

Medicare Savings Programs

Medicare sign
Image Credit: Shutterstock

There are three separate programs here, and depending on your income, one of them will pay your monthly Part B premium, stop providers from billing you for copays and deductibles, or both. They’re called the Medicare Savings Programs: Qualified Medicare Beneficiary (QMB), Specified Low-Income Medicare Beneficiary (SLMB), and Qualifying Individual (QI). All three are administered by your state Medicaid office, not by Medicare directly.

QMB is the most comprehensive. It covers Part A and Part B premiums, all deductibles, and all cost-sharing, and providers are legally prohibited from billing you for Medicare cost-sharing while enrolled. That’s a serious benefit for someone managing multiple doctors and prescriptions. The 2026 income limit for QMB is $1,350 a month for a single person, $1,824 for a couple. SLMB and QI have progressively higher income limits and cover the Part B premium only.

Enrolling in any of these programs automatically qualifies you for Extra Help, which cuts prescription drug costs significantly (more on that below). If you think you might be close to the income limits, apply anyway. Some states set more generous thresholds than the federal minimums, and the asset test excludes your home, car, and most personal property. The application takes about 30 minutes and is free.

Extra Help for Part D prescriptions

pharmacist handing over prescription
Image Credit: Shutterstock

Medicare Part D covers prescription drugs, but the premiums, deductibles, and copays can still add up fast depending on your medications. Extra Help, also called the Low Income Subsidy, covers most or all of those costs for people who qualify. The program is worth an estimated average of $5,700 a year per person in prescription savings.

With full Extra Help, you pay no Part D deductible, your plan premium is covered up to a benchmark amount set by Medicare, and copays are capped at $12.65 for brand-name drugs and $5.10 for generics. Once your drug costs reach $2,100 for the year, you pay nothing. For someone on multiple maintenance medications, the math on those caps can be striking.

The income limit for Extra Help in 2026 is $2,015 a month for a single person and $2,725 for a couple. Resource limits are $18,090 for individuals and $36,100 for couples. CMS has estimated that up to 2 million Medicare enrollees who qualify aren’t enrolled. If you’re already in a Medicare Savings Program, you get Extra Help automatically. If not, you can apply through Social Security online or by phone at 1-800-772-1213.

Supplemental Security Income

older people looking at receipts
Image Credit: Shutterstock

SSI is a federal cash benefit program for people with very limited income and resources. Most people think of it as a disability program, but if you’re 65 or older, you qualify based on age alone. No disability determination required. The federal benefit rate for 2026 is $994 a month for an individual and $1,491 for a couple.

The income and asset limits are strict. To qualify, your countable income generally needs to be below $994 a month and your assets below $2,000 for an individual ($3,000 for a couple), not counting your home, one vehicle, or certain burial funds. Most states add a supplemental payment on top of the federal rate, so your actual benefit could be higher. California, New York, and Massachusetts have among the most generous state supplements.

You can receive both SSI and Social Security at the same time. If your Social Security benefit is low, SSI can top it up to the eligible amount. Receiving SSI also qualifies you for Medicaid automatically in most states, covering costs that Medicare doesn’t. Apply through Social Security.

SNAP food benefits

SNAP
Image Credit: United States Department of Agriculture, Public domain, via Wikimedia Commons

SNAP, formerly known as food stamps, helps low-income households buy groceries. It’s a program most people associate with younger families, but close to 9 million older adults who qualify are not enrolled. The average SNAP benefit for a one-person senior household is $188 a month, delivered to an EBT card that works like a debit card at most grocery stores.

Seniors 60 and older get a different set of eligibility rules than younger applicants. There’s no gross income test: only the net income test applies, and that net figure accounts for deductions including excess medical expenses. If you spend more than $35 a month on out-of-pocket medical costs, the amount above $35 reduces your countable income and can meaningfully increase your benefit. Only about 16% of eligible seniors use this deduction.

The net income threshold for a single senior in fiscal year 2026 is roughly $1,255 a month, but deductions can bring a higher gross income down below that. Work requirements for SNAP changed in 2025, with new rules affecting adults in their early 60s. Apply through your state’s SNAP office to find out exactly what you qualify for. If you receive Medicaid or SSI, you may qualify with a simplified process.

LIHEAP energy assistance

home energy bill assistance for the elderly
Image Credit: Shutterstock

The Low Income Home Energy Assistance Program provides grants that help pay heating and cooling bills. Benefits go directly to your utility company or fuel provider, and you don’t have to pay anything back. Depending on your state and income, grants typically range from $150 to over $1,000 for the season. Some states offer additional crisis assistance for households facing a shutoff.


The federal income limit is 150% of the poverty level, which works out to about $23,940 a year for a single person in 2026. But many states set higher thresholds, and if you’re already enrolled in SNAP, Medicaid, or SSI, you may qualify automatically. Both renters and homeowners are eligible. You don’t have to own your home to receive help with energy costs.

The critical thing to know about LIHEAP is that funding is finite. When a state’s allocation runs out for the year, no more grants are available until the next funding cycle. Most states open applications in October or November. Applying early, especially in colder climates, makes a real difference. Find your local LIHEAP office through your state’s human services department or the National Energy Assistance Referral hotline at 1-800-432-4272.

Social Security spousal benefit

older couple working out finances
Image Credit: Shutterstock

If your spouse has a larger Social Security record than yours, you may be entitled to a benefit based on their earnings rather than your own. A spouse at full retirement age can claim up to 50% of the higher earner’s primary insurance amount. Social Security pays whichever benefit is larger: yours or the spousal amount.

This matters most for people who spent years out of the paid workforce raising children or caring for family. If your own retirement benefit would be $600 a month but 50% of your spouse’s primary insurance amount is $900, you’d receive $900. The higher earner has to be actively receiving their own benefit before a spouse can claim on their record.

Divorced spouses can also claim this benefit if the marriage lasted at least 10 years and you’re currently unmarried. Your ex doesn’t need to have filed for benefits yet, as long as you’ve been divorced for more than two years. Claiming on their record doesn’t reduce their payment at all, and it doesn’t affect any current spouse’s benefit either. A surprising number of divorced people don’t know this option exists.

Social Security survivor benefit

lonely widow
Image Credit: Shutterstock

When a spouse dies, the surviving spouse is entitled to a survivor benefit based on the late spouse’s Social Security record. At full retirement age for survivors (66 to 67, depending on birth year), you can collect 100% of what your spouse was receiving. Claiming before that age reduces the benefit, starting at 71.5% if you claim at 60.

If your own Social Security benefit is less than what the survivor benefit would be, Social Security pays you the higher amount. If you were already receiving spousal benefits, the agency typically switches you automatically when the death is reported. It’s worth confirming that switch happened correctly, especially if your benefit was reduced because you claimed early.

Divorced spouses may also qualify for survivor benefits if the marriage lasted at least 10 years and they haven’t remarried before 60. Remarriage after age 60 doesn’t affect eligibility. Some people who were eligible for survivor benefits never applied, either because they assumed they wouldn’t qualify or because a Social Security rep didn’t mention it. You cannot apply online for survivor benefits. Call Social Security at 1-800-772-1213 or visit a local office.

The Social Security Fairness Act

older male teacher
Image Credit: Shutterstock

On January 5, 2025, a law repealed two provisions that had been quietly cutting Social Security benefits for public-sector workers for four decades. The Windfall Elimination Provision and the Government Pension Offset had reduced or eliminated Social Security for about 3.2 million teachers, police officers, firefighters, postal workers, and other government employees whose jobs didn’t pay into the Social Security system.

The average monthly increase for affected workers is $360. Some see considerably more. Over $17 billion in retroactive payments have already gone out covering the period back to January 2024, when the repeal took effect. If you received a pension from a non-covered government job and also worked in Social Security-covered employment at some point, your benefit should have been automatically recalculated.

If it wasn’t, or if you never applied for Social Security because the Government Pension Offset would have eliminated your spousal or survivor benefit entirely, you may still need to contact Social Security to file or update your claim. Log into your my Social Security account at ssa.gov to check your benefit amount. If something looks off, call or visit a local field office. Retroactivity rules limit how far back payments can go, so the sooner you check, the better.

Property tax exemptions and freezes

older couple with house for sale
Image Credit: Shutterstock

Every U.S. state offers some form of property tax relief to homeowners 65 and older, and the majority of eligible homeowners never apply for it. Programs vary widely. Texas stacks a $60,000 school tax exemption on top of the standard homestead exemption, which can eliminate the property tax bill entirely for homes under $200,000. New Jersey’s StayNJ program reimburses up to 50% of property taxes paid, capped at $6,500 a year. Colorado exempts 50% of the first $200,000 in assessed value for seniors who’ve lived in their home for at least 10 years.

Assessment freezes are particularly valuable over time. Once approved, your taxable assessed value stops rising with the market, so your bill stays roughly flat even as your neighbors’ taxes climb year after year. Illinois, New York, Washington, and about 20 other states offer freeze programs for seniors meeting income thresholds.

Income limits vary, and some programs have no income test at all. The place to start is your county assessor’s office or your state’s department of revenue website. Search your state name plus “senior property tax exemption” and you’ll find the relevant program and application. Most require you to file once and renew annually, and most have spring deadlines that many people simply miss because they don’t know the program exists.

VA Aid and Attendance

older veteran
Image Credit: Shutterstock

Veterans who served during wartime and now need help with daily activities may qualify for one of the most valuable and underused benefits in the entire federal system. Aid and Attendance is a VA pension enhancement that pays up to $2,424 a month for a single veteran and up to $2,874 for a married veteran, tax-free. Surviving spouses of qualifying wartime veterans can also receive a version of this benefit, up to $974 a month in 2026.

You don’t need a service-connected disability to qualify. The criteria are financial need, wartime service (World War II, Korea, Vietnam, and the Gulf War, among others), and a demonstrated need for help with daily activities such as bathing, dressing, or eating, or residence in a nursing home or assisted living facility. The benefit is calculated as the difference between countable income and the applicable maximum rate. Medical and care expenses reduce countable income, so many veterans with substantial gross income still qualify once their care costs are factored in.

The net worth limit for 2026 is $163,699. Claims take four to six months to process on average, so apply early. You can file using VA Form 21-2680 through VA.gov, or get free help from a Veterans Service Organization such as the DAV, VFW, or American Legion, whose accredited representatives can help at no charge.

Your free Medicare wellness visit

Medicare wellness visit
Image Credit: National Cancer Institute via Unsplash

Every year you have Medicare Part B, you’re entitled to a free Annual Wellness Visit with your doctor. There’s no cost to you as long as your provider accepts Medicare assignment, and the Part B deductible doesn’t apply. The visit includes a health risk assessment, a cognitive evaluation for signs of dementia, a medication review, and a personalized prevention plan summarizing which screenings and vaccines you’re due for.

Fewer than a third of Medicare beneficiaries use this benefit each year. That’s a lot of people skipping a zero-cost opportunity to catch potential health problems early and make sure their preventive care is current. A colonoscopy, mammogram, or lung cancer screening may also be fully covered under Medicare if you’re due for one, and the wellness visit is the most efficient way to confirm which screenings apply to you and get referrals in place.

One thing to be aware of: if your provider adds treatment or diagnosis to the same appointment, charges may apply. Keep the annual wellness visit focused on prevention and schedule a separate appointment for anything you want treated or evaluated. If you haven’t used this benefit in the past 12 months, call your doctor’s office and schedule it this week.

Medicaid long-term care

medicaid and stethoscope
Image Credit: Shutterstock

Most people know Medicaid as a health coverage program for low-income individuals. Fewer know that it’s also the largest payer of nursing home care in the country, covering about 60% of all nursing home residents. The nationwide average annual cost of a shared nursing home room in 2026 runs about $119,000. For most families, Medicaid coverage represents a savings of that amount every single year, for as long as care is needed.

Medicare doesn’t cover long-term custodial care. It pays for up to 100 days of skilled nursing after a qualifying hospital stay, then stops. Private long-term care insurance covers only a small fraction of people. For most middle- and lower-income seniors, Medicaid is the only program standing between a family and a complete drawdown of their life savings. Unlike home care waivers, which often have waitlists, nursing home Medicaid is an entitlement: anyone who meets the criteria is guaranteed coverage in a certified facility.

The financial eligibility rules are strict and vary significantly by state. Generally, a single applicant needs income below about $2,982 a month and assets under $2,000, not counting the home (in most circumstances), one vehicle, and personal belongings. If you have a spouse who remains at home, the rules protect a significant share of household income and assets. Medicaid also has a five-year look-back period on asset transfers. The rules are complex enough that most families benefit from consulting an elder law attorney before applying.

Bottom line

bottom line on blocks of wood
Image Credit: Shutterstock

Most of these programs have been running for decades, available and quietly underclaimed by the people who need them most. If you’re not sure which ones you qualify for, a free eligibility screening tool lets you check hundreds of federal and state programs at once by entering your zip code. You paid into this system over a working lifetime. The money is there.

What is the most money a retiree can get from these programs combined?

There’s no single ceiling because each program is separate and eligibility varies by income, state, and personal circumstances. A low-income senior who qualifies for the full QMB Medicare Savings Program, Extra Help for Part D, SSI, and SNAP could receive well over $1,000 a month in combined benefits on top of any Social Security payment. VA Aid and Attendance alone can pay up to $2,424 a month for a qualifying single veteran.

Will getting SNAP or SSI reduce my Social Security benefit?

SNAP benefits don’t affect your Social Security at all. SSI is different: if you receive both Social Security and SSI, Social Security counts most of your Social Security income toward the SSI limit. But SSI can still supplement a low Social Security benefit up to the monthly federal rate.

I’m already on Medicare. Can I still get a Medicare Savings Program?

Yes. Medicare Savings Programs are specifically for Medicare enrollees with limited income. Having Medicare is a requirement for enrollment, not a disqualifier. Apply through your state Medicaid office regardless of your current Medicare plan type.

Do I need to reapply for these programs every year?

It depends on the program. SNAP typically requires annual recertification. The QI program under Medicare Savings always requires an annual reapplication. QMB and SLMB may renew automatically in some states but not all. SSI generally continues as long as you remain financially eligible and report changes promptly. LIHEAP requires a new application each program year. VA Aid and Attendance continues without annual renewal once awarded.

If I was never told about the Social Security Fairness Act repeal, do I need to do anything?

If you were already receiving a benefit affected by WEP or GPO, Social Security should have recalculated your payment and sent retroactive funds automatically. Check your benefit amount in your my Social Security account at ssa.gov. If your payment hasn’t changed and you believe it should have, call Social Security. If you previously didn’t apply for a spousal or survivor benefit because GPO would have eliminated it, you may need to file a new application now that the offset is gone.