scroll top

You’re cleaning out your grandfather’s dresser and there’s a cigar box shoved in the back of a drawer. Inside is a rubber-banded stack of old $5 bills, the kind with red or blue ink instead of green, portraits that look slightly different from the one in your wallet. Your first instinct is to count them as five dollars each and move on to the next box.

Don’t, at least not yet. The $5 bill has one of the deepest collector markets in American currency, mostly because so many people quietly kept them. A five was real money for most of the 20th century, worth setting aside instead of spending, which is exactly why so many ended up folded into wallets, tucked into Bibles, or stashed in cigar boxes instead of wearing out in circulation. That habit is the reason $5 bills turn up in family collections far more often than people expect.

What separates a bill worth five dollars from one worth five hundred comes down to a short checklist: the color of the Treasury seal, the series year printed near the signatures, whether there’s a tiny star in the serial number, and whether that serial number does anything unusual. None of it requires special equipment. It just requires actually looking.

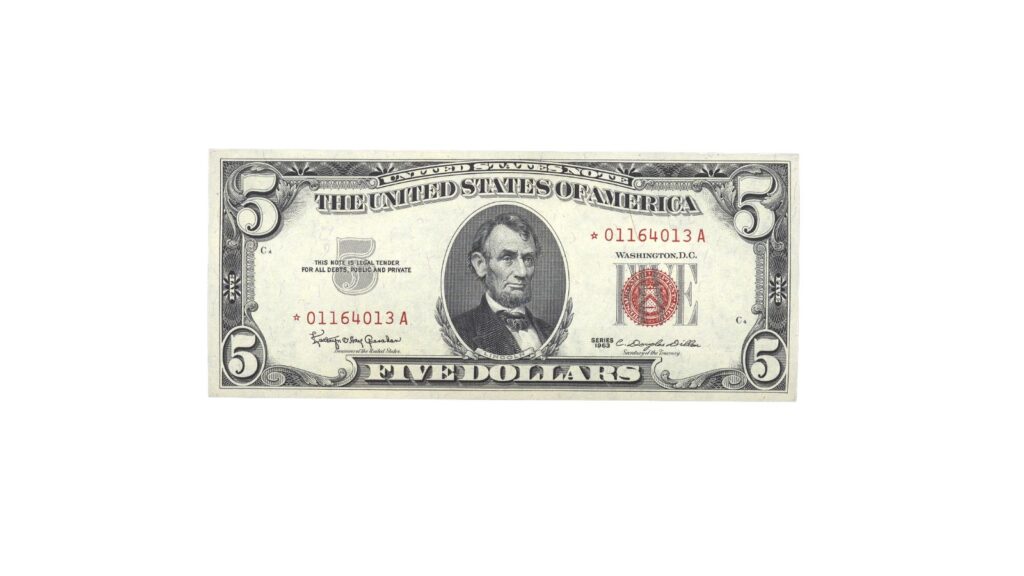
1963 $5 red seal legal tender note
Image Credit: Heritage Auctions

The easiest red seal $5 to find is also the last one the government ever issued. Series 1963 legal tender notes carry a bright red Treasury seal and red serial numbers instead of the green ink used on every $5 bill printed since, along with the words “United States Note” rather than “Federal Reserve Note.” Production stopped in 1966, which gives the series a clean stopping point that collectors like.

Circulated examples are common and only bring a modest premium, typically $6 to $10 over face value. Crisp uncirculated notes with no folds do better, usually landing in the $15 to $25 range. The detail that changes things is a star in place of the first letter of the serial number, which marks a replacement note printed to cover a defective sheet. Star examples run somewhat higher than standard issues in the same grade.

Condition is easy to judge on this series because the paper is still fairly recent by currency standards. Look for hard folds, soft corners, and staining, all of which push a note toward face value fast. A flat, bright, uncirculated example is the one worth setting aside rather than spending.

2. 1953 $5 blue seal silver certificate
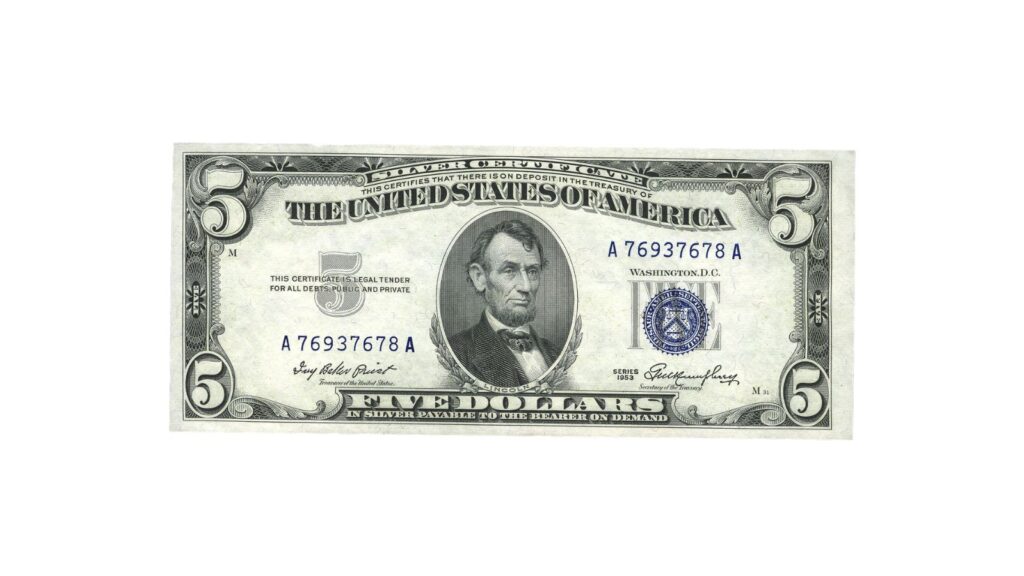
1953 $5 blue seal silver certificate
Image Credit: Heritage Auctions

Before 1968, the government promised to exchange silver certificates for actual silver on demand, and the $5 denomination carried that promise right up until the series ended. A 1953 $5 silver certificate is identified by its blue Treasury seal, blue serial numbers, and the words “Silver Certificate” printed across the top rather than “Federal Reserve Note.”

These are common. A circulated example is worth about $6 to $10, and a crisp uncirculated one brings closer to $20. The series comes in three nearly identical varieties, 1953, 1953A, and 1953B, and none of the three plain versions is scarce. What is scarce is one specific star note buried inside that third variety, covered further down this list, so don’t assume every 1953B silver certificate you find is the rare one. Check for the star symbol before getting excited.

Handling and storage matter more than people expect with these. A bill folded into a wallet for decades loses crispness fast, and crispness is most of what separates the low end of this range from the high end. If you find a stack, look for the notes that still snap when handled rather than fold limply.

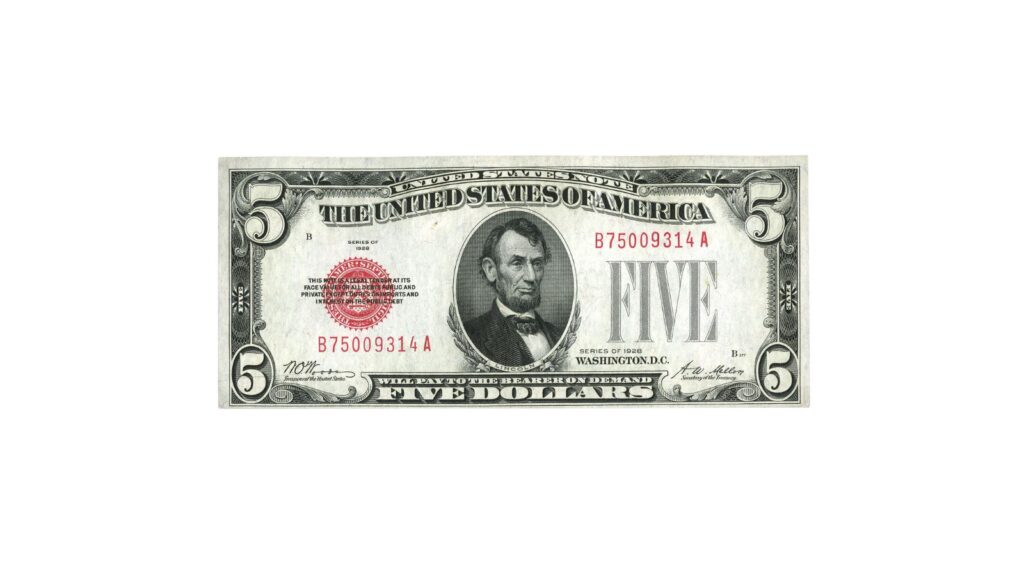
1928 $5 red seal legal tender note
Image Credit: Heritage Auctions

The 1928 series was the first $5 bill printed in the smaller size still used today, and it’s easy to tell apart from its 1953 and 1963 red seal cousins once you know where to look: the red Treasury seal sits to the left of Lincoln’s portrait instead of the right. These were printed across six sub-series, 1928 through 1928F, and heavily circulated for decades before people started setting them aside.

Circulated examples typically bring $7 to $10, not far above face value. The real difference shows up in uncirculated condition, where crisp, unfolded notes with sharp corners can reach $50 to well over $100 depending on the specific sub-series and how well-centered the printing is. Star notes and fancy serial numbers push individual examples higher still.

Because this series predates most family currency habits by a generation, most surviving examples show real wear. A 1928 $5 that’s been kept flat rather than folded is genuinely uncommon, which is exactly why condition drives almost all the value here. If you find one that’s never been through a wallet, it’s worth a second look before you spend it.

4. $5 star notes, any series
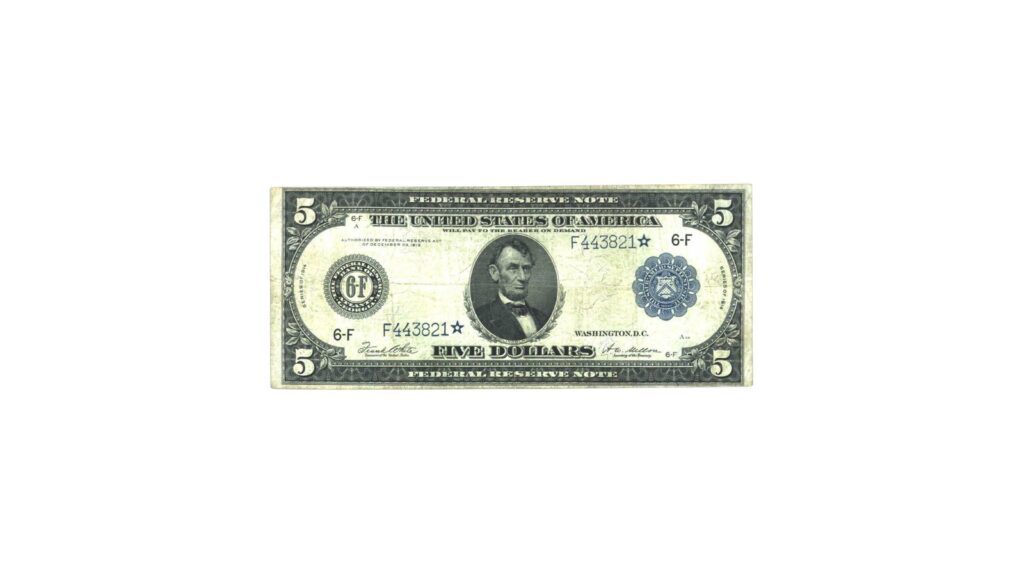
$5 star note
Image Credit: Heritage Auctions

Every series of $5 bill, from the 1928 red seals through the purple-tinted notes in circulation today, includes replacement notes marked with a small star instead of a letter in the serial number. The Bureau of Engraving and Printing uses them whenever a sheet is caught as defective partway through the numbering process, and rather than reprint the same serial number, the replacement gets a star so nothing in the run duplicates.

On red seal legal tender notes the star sits at the front of the serial number. On green seal Federal Reserve Notes it sits at the end. Common modern star notes bring only a small premium, but a 1963 red seal $5 star note runs roughly $10 to $25 depending on condition, and older red and blue seal stars from smaller print runs go considerably higher.

The number that matters most is how many were printed in that particular run. Star notes from small print runs, sometimes well under a million for a given series and district, are genuinely scarce even though nothing about the bill looks unusual at a glance. A quick search of the series and Federal Reserve district printed on the note will tell you whether the run was small enough to matter.

5. Fancy serial number $5 bills
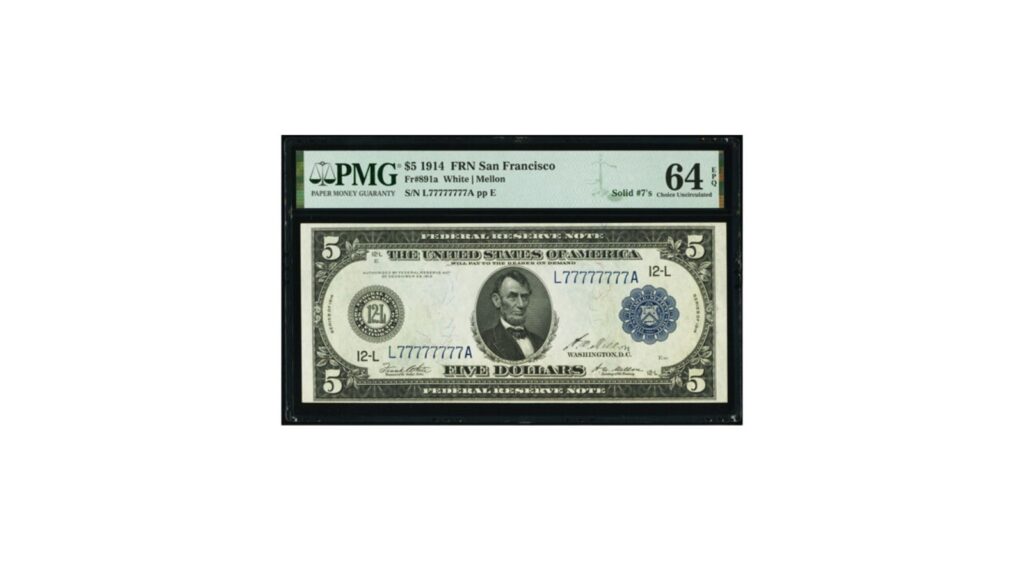
$5 solid number
Image Credit: Heritage Auctions

Every bill carries an eight-digit serial number, and most of them are just random noise. Every so often one isn’t. Solid numbers where all eight digits match, ladders that run in perfect sequence like 12345678, radars that read the same forward and backward, and repeaters where a four-digit block repeats twice, all catch collectors’ attention regardless of the year or series.

The premiums scale with how dramatic the pattern is. Solid numbers bring $500 to $5,000 or more, a true ascending or descending ladder brings $200 to $1,500, and a straightforward radar or repeater typically brings $20 to $100. A $5 bill carries roughly the same premium structure as a $1, so the pattern itself matters more than the denomination it’s printed on.

This is the one item on this list that applies to a bill sitting in your wallet right now, not just old currency. Before you spend any $5 note, glance at the serial number printed twice on the front. It takes five seconds, and it’s the only entry here where a fresh, ordinary bill fresh from an ATM has a real shot at being worth something.

6. Low serial number $5 bills
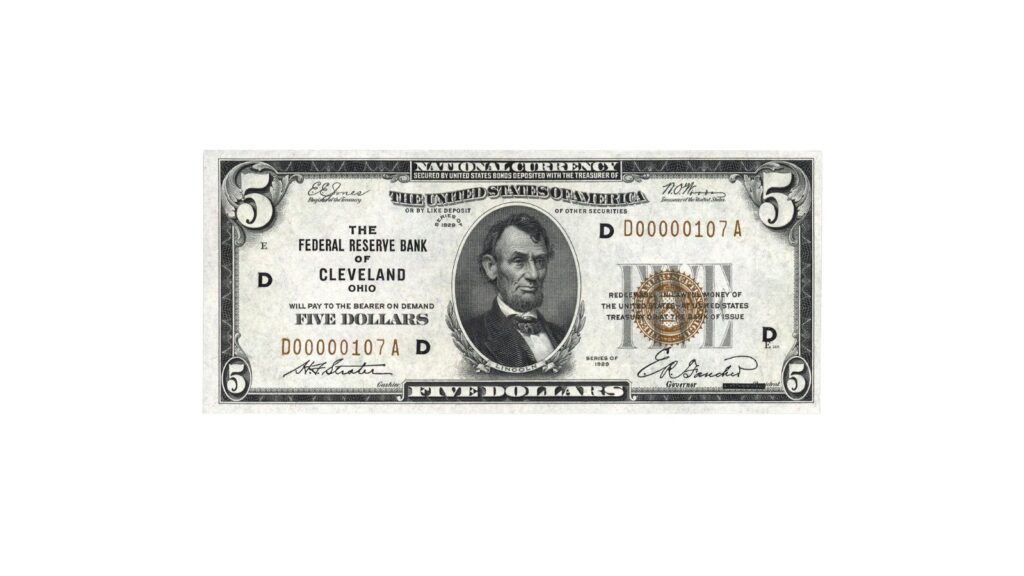
Low serial number $5 bill
Image Credit: Heritage Auctions

Low serial numbers are their own category, separate from the fancy patterns above, because they mark a bill as one of the very first off the press in a given run. A bill numbered under 100 rarely made it into general circulation. Most low numbers were pulled aside by bank officials, government offices, or collectors before they ever reached a cash register.

The scale runs steeply. Serial number 00000001 can bring $2,000 to $15,000 depending on the series and condition, numbers 2 through 9 typically bring $500 to $2,000, and anything under 100 still commands $100 to $500. Once you’re past the first thousand, the premium drops off fast, down to a modest $20 to $50 for numbers in the low thousands.

Condition affects a low serial number bill just as much as any other collectible note, so a crisp, uncirculated example with a low number is worth considerably more than a worn one with the same digits. Because banks sometimes hold back the first straps of a fresh print run for internal use, these do occasionally surface in ordinary circulation decades later, usually already well worn by the time anyone notices.

7. 1934 $5 blue seal silver certificate
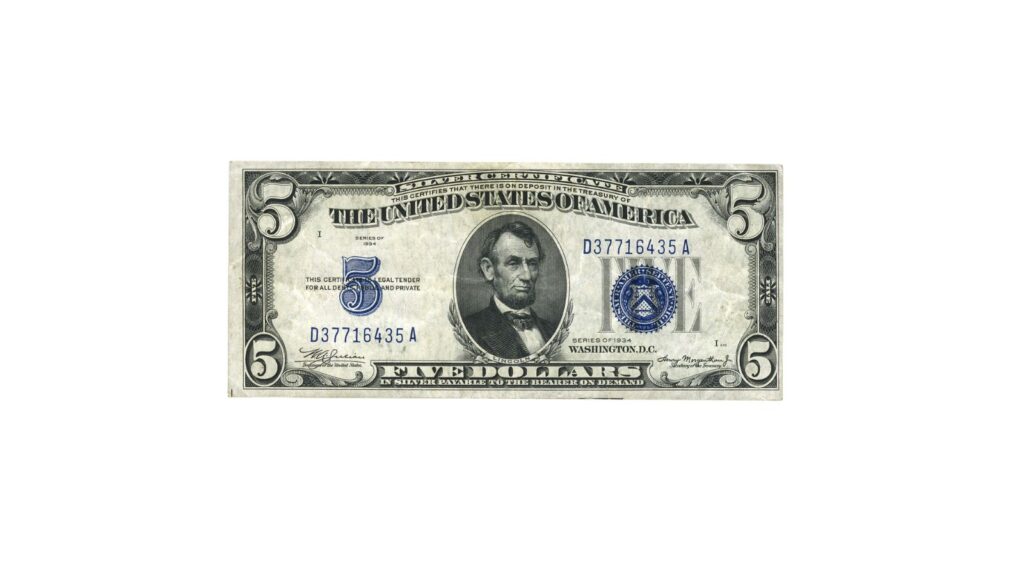
1934 $5 blue seal silver certificate
Image Credit: Heritage Auctions

The 1934 series predates the more familiar 1953 blue seal by two decades and comes with more variety to track. Five sub-series exist, 1934, 1934A, 1934B, 1934C, and 1934D, each marked with a letter near the bottom right of Lincoln’s portrait, and the value swings meaningfully between them.

Circulated examples across the group run about $12 to $30, with the plain 1934 series generally bringing the most since it’s the scarcest of the five. Uncirculated notes tell a bigger story: a gem-quality plain 1934 can reach $800 to $2,500, while the more common 1934A tops out closer to $175 to $275 in the same grade. The 1934D series also comes in “wide” and “narrow” back-plate varieties that collectors track separately.

Star notes exist for every sub-series here too, and the 1934B star is considered the scarcest of the group, commanding real premiums even in circulated grades. Before assuming you have a common 1934A, check the letter suffix carefully. It’s a small detail with an outsized effect on what the note is actually worth.

8. 1953B $5 silver certificate star note
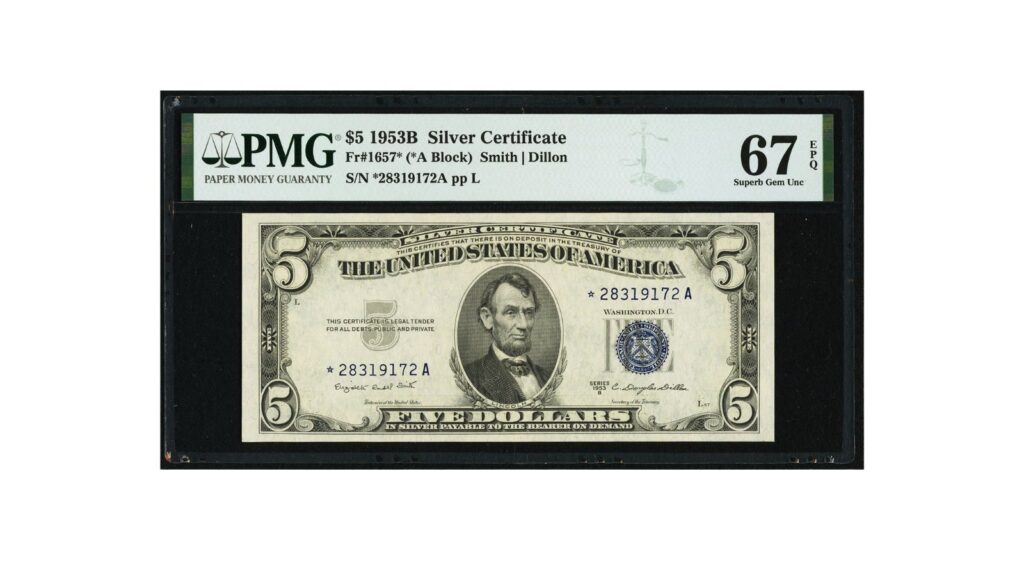
1953B $5 silver certificate star note
Image Credit: Heritage Auctions

This is the trap entry on this list, because it looks nearly identical to the common bill in entry two. Three sub-series of 1953 blue seal silver certificate exist, 1953, 1953A, and 1953B, and the plain versions of all three are equally unremarkable. The exception is the 1953B star note specifically, and it’s genuinely rare: over three million were printed, but fewer than 400,000 were actually released into circulation before the rest were destroyed.

That scarcity shows up in the price. Lightly circulated 1953B star notes sell for over $1,000, and uncirculated examples come up for sale so rarely that dealers simply describe them as worth thousands, without a firm ceiling. Compare that to the common 1953 and 1953A stars, which bring only about $15 to $30 in circulated grades, and the gap is obvious once you know to look for it.

The identification is simple: blue seal, “1953B” printed near the signatures, and a star symbol in the serial number. All three conditions have to be true at once. Miss any one of them and you have an ordinary bill worth a small premium at most, not a four-figure note.

9. 1929 $5 National Bank Note
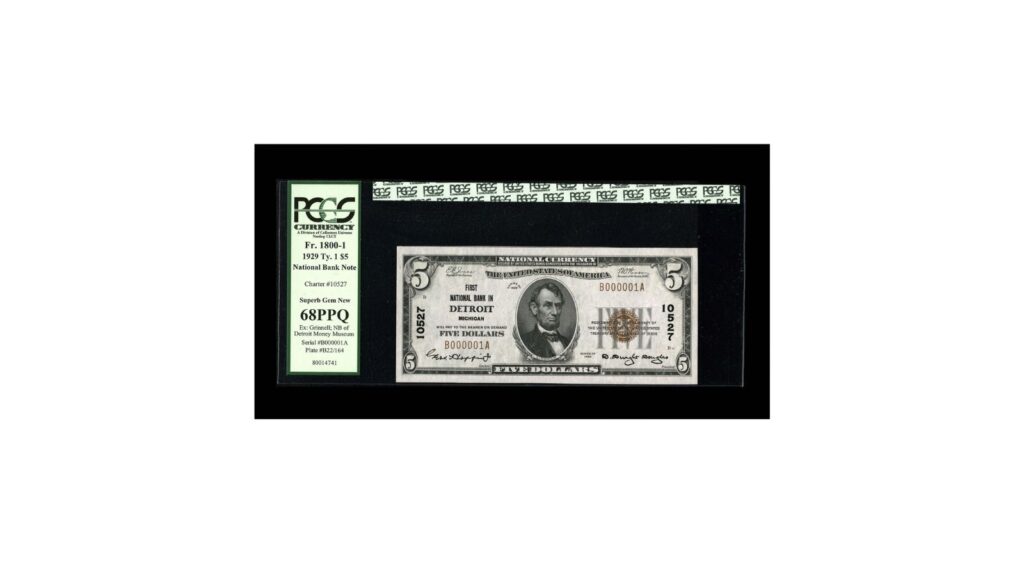
$5 national dollar note
Image Credit: Heritage Auctions

Before the modern Federal Reserve system printed every dollar in circulation, thousands of local banks across the country issued their own $5 bills under federal charter, each one printed with that specific bank’s name across the front instead of “Federal Reserve Note.” A 1929 National Bank Note reading “The First National Bank of” some small town isn’t a novelty item. It’s a real piece of that town’s banking history, and exactly the kind of bill that turns up in collections from families who banked locally for generations.

Common examples from well-known banks bring modest but real premiums, around $80 to $95 in lightly circulated condition and $150 to $225 uncirculated. What changes everything is the issuing bank itself. Some small-town banks issued only a handful of notes before closing or converting to a different charter, and surviving examples from those banks can bring hundreds or thousands of dollars regardless of condition.

The charter number and bank name are printed directly on the note, which makes research straightforward. If you have one, look up the specific charter number before assuming it’s a common example. Rarity here is almost entirely about the bank, not the year.

10. 1929 $5 Federal Reserve Bank Note, brown seal
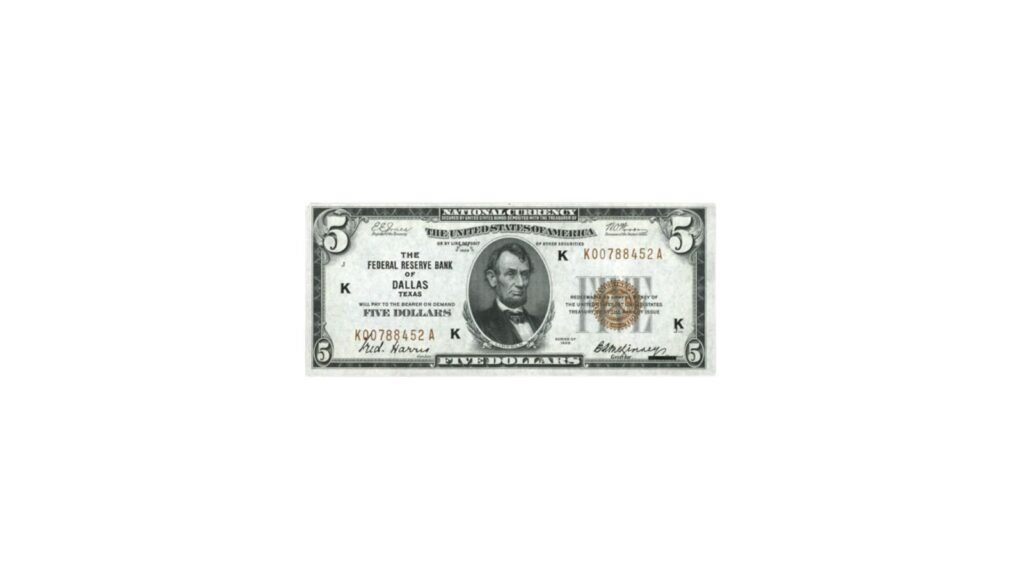
1929 $5 Federal Reserve Bank Note brown seal
Image Credit: Heritage Auctions

Easy to confuse with the National Bank Note above, but genuinely different: a 1929 Federal Reserve Bank Note was issued by one of the twelve regional Federal Reserve Banks rather than a local chartered bank, and it carries a brown Treasury seal instead of the standard green. These were a Depression-era measure, printed using leftover currency paper stock to get more cash into circulation quickly during the 1933 banking crisis.

Standard examples bring around $60 in circulated condition and closer to $185 uncirculated, but the issuing district matters. Notes from the Minneapolis, St. Louis, and San Francisco Federal Reserve Banks are scarcer than the others and bring meaningfully more, and star notes from those same smaller districts can climb into the hundreds or low thousands.

The district is identified by a letter and number printed in the black Federal Reserve seal on the left side of the note. Boston, New York, and Chicago notes are common enough that most examples aren’t worth much beyond the standard premium. It’s worth checking the district before deciding a brown seal $5 isn’t anything special.

11. 1899 $5 silver certificate “Indian Chief”
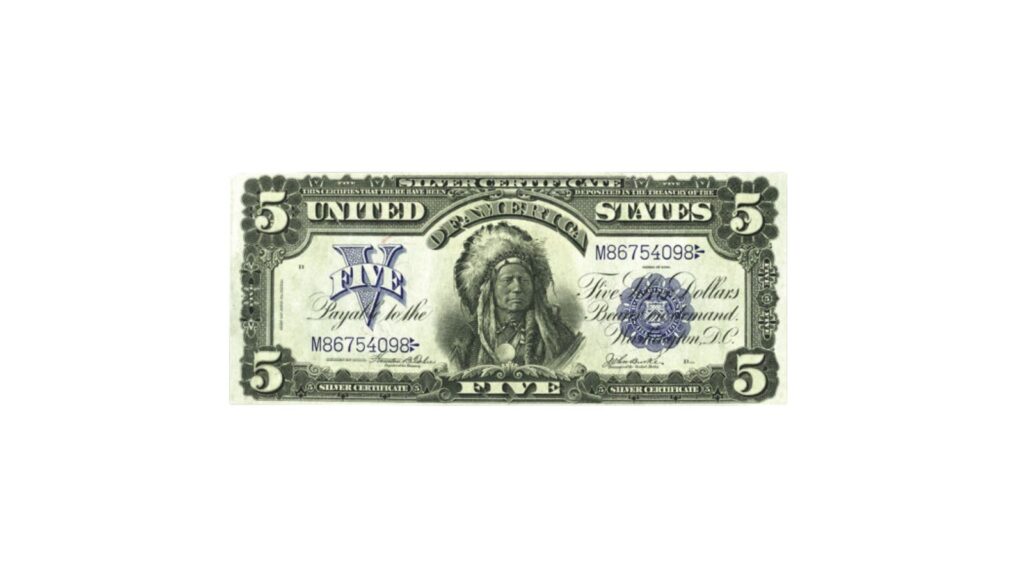
1899 $5 silver certificate Indian Chief
Image Credit: Heritage Auctions

This is the most recognizable large-size $5 bill most people will ever encounter, and it’s a genuinely striking piece of design: a portrait of Running Antelope, chief of the Hunkpapa Lakota, filling most of the front, printed between 1899 and the early 1920s. It was the only time a Native American appeared as the central figure on U.S. paper money, and tens of millions were printed, which means it shows up in old collections more often than its history might suggest.

Value tracks condition closely. Heavily worn examples typically bring under $300, fine to very fine notes run $300 to $1,250, and anything approaching uncirculated jumps to $1,500 and up, with true gem examples reaching $3,000 or more. A serial number under 100, or a star symbol at the start of the serial number, adds a further premium at any grade.

Because millions survive, this isn’t a needle-in-a-haystack find the way some large-size notes are. It’s more a question of condition. If a family collection includes an old, oversized $5 bill with a portrait in full headdress, this is very likely it, and it’s worth an appraisal rather than an assumption.

1907 $5 legal tender Woodchopper note
Image Credit: Heritage Auctions

Nicknamed for its central image of a pioneer with an axe, his wife, their baby, and a dog, the 1907 series was the last large-size $5 bill the government ever printed before currency shrank to its modern dimensions in 1929. At roughly 40 percent bigger than a current bill, it’s obvious in a stack of old currency before you even check the date.

Well-worn examples bring around $50 to $75, fine condition runs $75 to $125, and very fine climbs to around $200 to $235. Extremely fine to about-uncirculated notes bring $300 to $450, and choice or gem uncirculated examples can reach $600 to $900. Tens of millions were printed, and runs of consecutive, uncirculated notes still surface occasionally, so high grades aren’t as impossible to find as the price range suggests.

One quirk worth knowing: a printing plate error nicknamed the “PCBLIC” error, where part of the word “PUBLIC” was misspelled, shows up often enough on this series that it only adds about a 15 percent premium rather than a dramatic one. Fun to check for, even if it won’t make or break what you have.

13. Ink smear error $5 bills
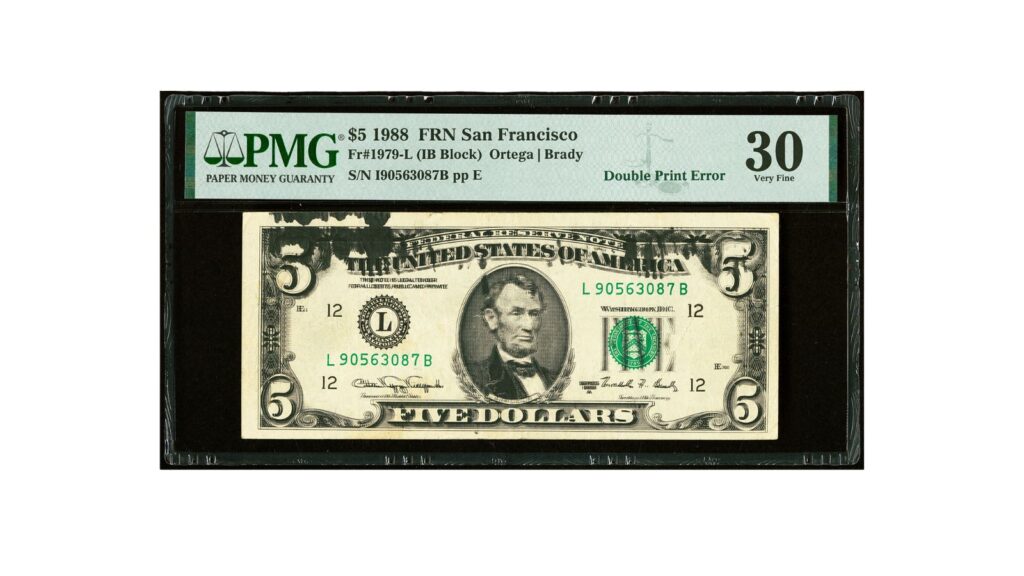
Ink smear error $5 bills
Image Credit: Heritage Auctions

Currency prints in three separate passes, the back, then the face, then the black serial numbers and seals, and excess ink on any one of those passes can transfer onto the sheet as a smear or blotch. The result ranges from a small dark smudge in one corner to a dramatic streak running most of the width of the note.

Size and placement drive the price. Minor smears bring around $50, while a large, dramatic smear crossing a significant portion of the design can reach $1,000 or more. A smear that lands directly over the portrait or the Treasury seal draws more collector interest than one tucked into a plain border area.

The hardest part of this one is telling a genuine press error from ordinary staining picked up over decades in a wallet or drawer. A real ink smear has the same texture as the rest of the intaglio printing since it came from the same press pass, while later staining tends to sit differently on the paper. For anything beyond a minor smear, professional authentication is worth the fee before you try to sell it.

14. Off-center or misaligned print error $5 bills
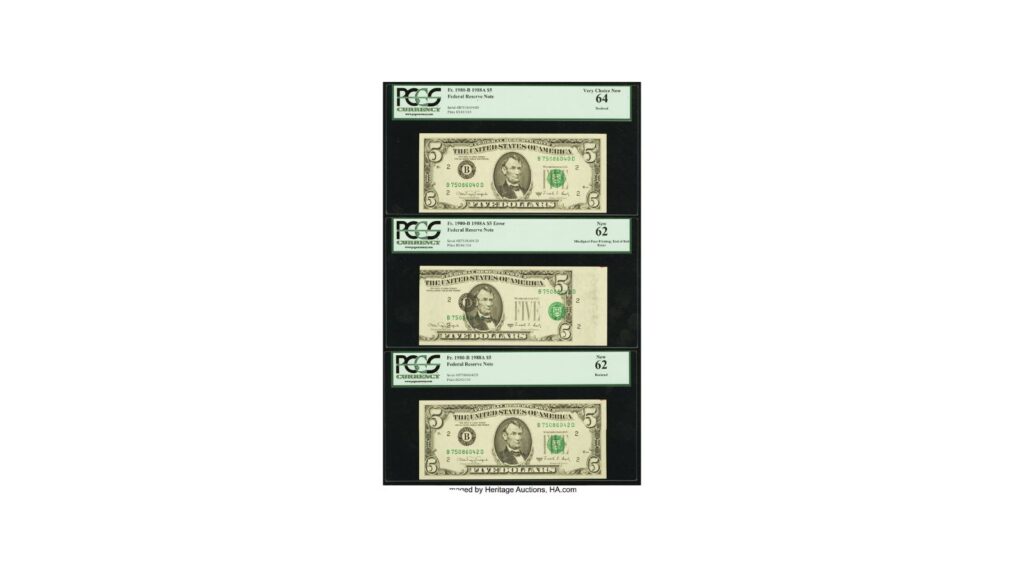
misaligned print error $5 bills
Image Credit: Heritage Auctions

The most common error type by far, and the one most likely to actually turn up in ordinary circulation, is simple misalignment: the printed design shifts off-center during one of the printing passes, leaving uneven margins or a design that runs noticeably close to one edge.

Severity sets the price almost entirely. A barely noticeable shift brings $25 to $50, a clearly crooked note with visibly uneven margins runs $50 to $200, and a dramatic shift where part of the portrait or lettering actually runs off the edge of the paper can bring $200 to $500 or more. The more obvious the mistake is without a ruler, the more collectors will pay for it.

Because this error is common enough to check for on any bill, it’s worth a habit rather than a one-time search: hold new bills up to the light and compare the border width on all four sides. Most notes are perfectly centered, which is exactly what makes an off-center one easy to spot once you know to look. A bill with the portrait or serial number partially cut off by the edge of the paper is worth setting aside rather than spending.

15. Inverted overprint error $5 bills
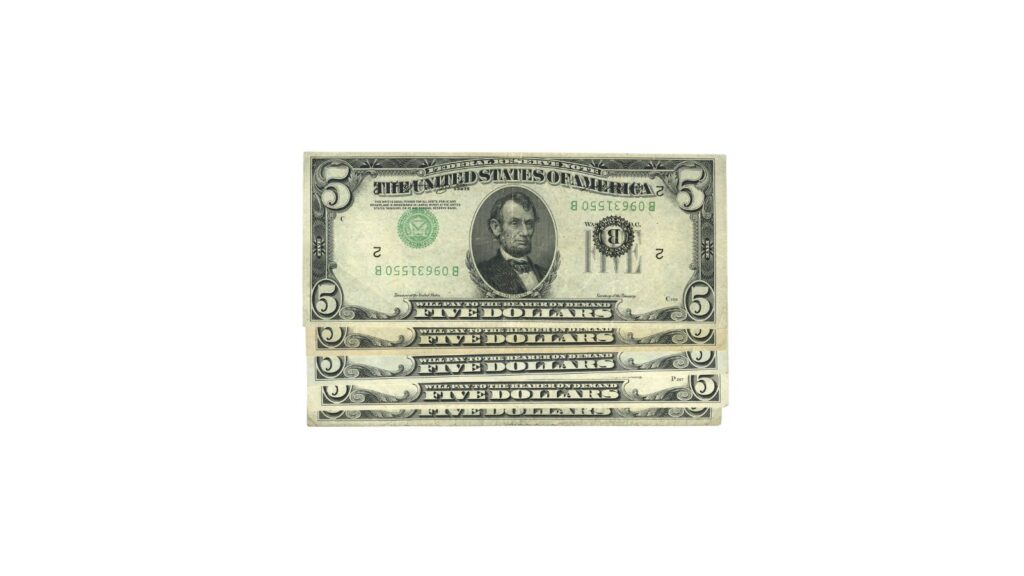
Inverted overprint error $5 bills
Image Credit: Heritage Auctions

The final printing pass on any $5 bill adds the black serial numbers, the Treasury seal, and the Federal Reserve district markings as an overprint layer on top of the already-printed face. On rare occasions that layer gets fed through the press upside down relative to everything underneath it, so the serial numbers and seal appear inverted while the portrait and border sit right side up.

This is a dramatic, immediately obvious error, and it prices accordingly. Inverted overprints typically bring $200 to $2,500, with the higher end reserved for notes where the inversion is complete and unmistakable rather than a partial or minor shift. The more the two layers contradict each other at a glance, the more collectors compete for it.

Authentication matters enormously here because the error is dramatic enough to fake convincingly with a careful alteration. Genuine inverted overprints show ink and pressure consistent with the Bureau’s actual printing process under magnification, which only a professional grading service can confirm with confidence. Given the price gap between a certified and an uncertified example, that step is worth taking before any sale.

16. Fold-over (butterfly) error $5 bills
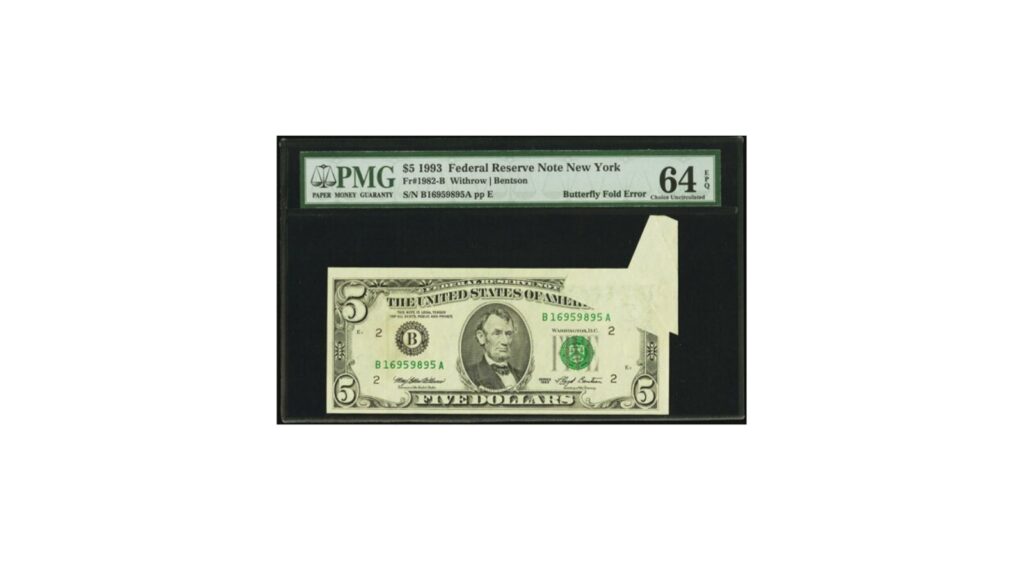
Fold over error $5 bills
Image Credit: Heritage Auctions

When a corner or edge of a currency sheet folds over on itself before it goes through the press, the folded section receives no ink on one side while the flip side of that same section gets printed twice. Once the sheet is unfolded and cut into individual notes, the result is a bill with a startling blank patch on one side and an extra, oddly placed printed section on the other, sometimes called a butterfly note for the shape the fold leaves behind.

The size and position of the fold set the value. Significant fold-over errors bring $500 to $3,000 at the higher end, while smaller folds affecting only a corner bring less. Whether the fold happened during an early or later printing pass also matters, since folds during later passes tend to produce more visually dramatic results.

These are unmistakable even to a non-collector, which is part of why they command strong prices. If a bill in a family collection has an oddly shaped blank section or printing that clearly doesn’t belong where it is, don’t try to flatten it out or explain it away. Get it in front of a currency dealer before doing anything else to it.

17. 1934A $5 Hawaii overprint note
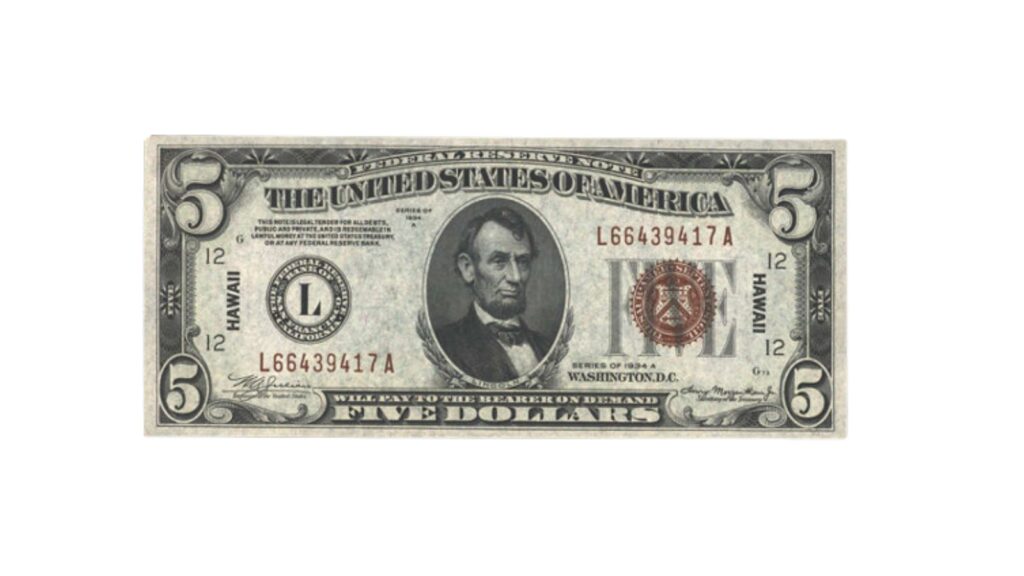
1934A $5 Hawaii overprint note
Image Credit: Heritage Auctions

After the attack on Pearl Harbor, the government printed special emergency currency for use in Hawaii in case the islands were invaded and the currency needed to be declared worthless on short notice. A 1934 or 1934A $5 Hawaii note looks like an ordinary Federal Reserve Note with two changes: a brown Treasury seal instead of green, and the word “HAWAII” printed in large letters across the back with smaller overprints on the front. Around 9.4 million of the $5 denomination were printed, making it the scarcest of the four Hawaii denominations issued.

Circulated examples bring $60 to a few hundred dollars, with uncirculated notes climbing into the thousands depending on centering and paper quality. Star replacement notes are considerably scarcer still, running from roughly $1,500 in circulated grades up toward $8,000 for the best uncirculated examples.

These notes carry a real family-history angle, since so many were kept as souvenirs by service members stationed in the Pacific rather than spent. If a relative served during the war and kept currency as a memento, a Hawaii overprint note is a genuinely plausible find, not a long shot.

18. Mismatched serial number error $5 bills
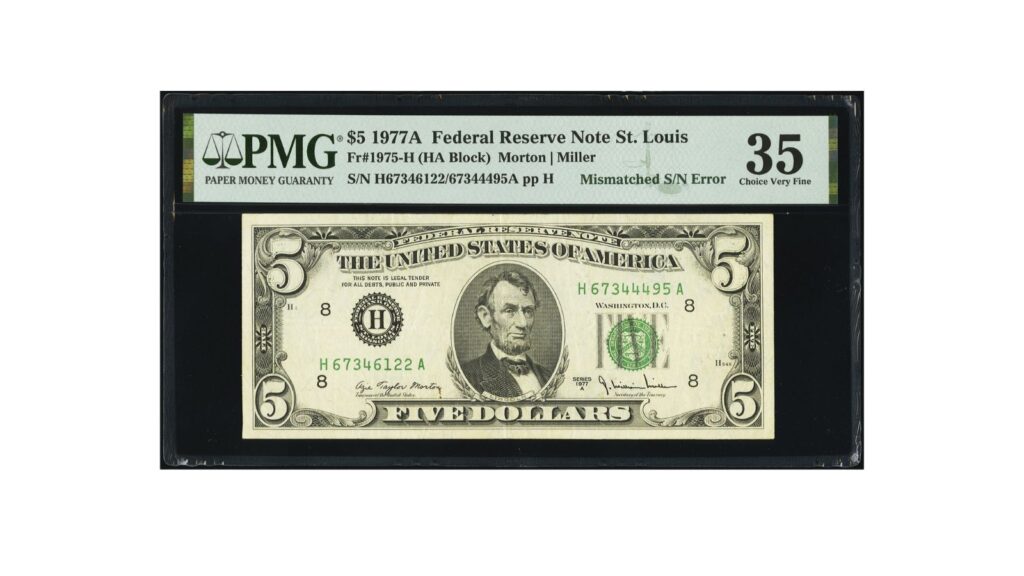
Mismatched serial number error $5 bills
Image Credit: Heritage Auctions

Every U.S. bill carries its serial number printed twice, once in the upper right and once in the lower left of the face, and the two are supposed to be identical down to the last character. When a numbering wheel sticks or fails to advance properly during the overprint pass, the two numbers can end up differing by a digit, or occasionally by more, without anything else about the bill looking unusual.

Because the mistake is subtle, plenty of these go completely unnoticed in circulation. A single mismatched digit brings $300 to $600 circulated and roughly double that uncirculated, while a mismatch affecting multiple digits or the prefix and suffix letters can reach $700 to $2,500. A mismatch found on a star note goes higher still.

This is the one error on this list you genuinely can’t spot at a glance, so it’s worth developing the habit of comparing the two serial numbers character by character rather than assuming they match because they’re supposed to. Because altered serial numbers are also a known forgery method, any note you suspect has a genuine mismatch needs professional certification before it changes hands. Buyers won’t take an uncertified example seriously at this price level.
You’re at checkout with the cart already unloaded, and instead of tapping your debit card, you tap “pay in 4.” The app splits the bill into four payments spread over six weeks. You walk out with the groceries. The bill walks out with you too, just on a schedule.

Twenty-nine percent of buy now, pay later users say they’ve used the loans to buy groceries, more than double the 14 percent who said the same two years ago.

This isn’t the same story as financing a couch or a laptop. Those purchases stick around long after the last payment clears. Groceries don’t. By the time the third payment comes out of your account, the food from the first one is usually gone, and if money is still tight, the obvious next move is financing the next grocery trip too.

What gets left out of that 29 percent number is what happens after someone taps “pay in 4” for groceries the first time. These loans stack fast, almost nobody outside the borrower is tracking how much is owed across every app on their phone at once, and grocery debt is quietly turning into a normal way to eat instead of an occasional stopgap.

The number that keeps climbing

buy now pay later
Image Credit: Shutterstock

Among Gen Z shoppers, that share jumps to 38 percent, and it climbs higher again for parents with young kids. More than half of buy now, pay later users, 54 percent, say they wouldn’t be able to make ends meet without the loans, and that number rises to 62 percent among parents raising kids under 18.

People aren’t choosing these loans because they’re interest free. The single biggest reason users gave for picking buy now, pay later over other options was that it’s easy to get and easy to use, ahead of the fact that many plans charge no interest at all. Groceries aren’t the only necessity riding on that convenience. Large shares of buy now, pay later users also finance other basics with the same apps: 42 percent for medical or dental care, 39 percent for utility bills, 38 percent for gas, and 33 percent for rent or housing costs.

A payment method built for splitting the cost of a new phone is now doing double duty as a way to smooth over a paycheck that runs out before the month does.

Food is spent before the loan is paid off

Buy now, pay later was built around one-time purchases. You buy a couch, split it into four payments, and by the time the last payment clears, you’re still sitting on the couch. Groceries don’t work that way. The food is eaten within a week or two, long before a six-week payment plan is finished, and if money is still tight, the obvious next step is financing the next grocery trip too.

Each purchase through one of these apps opens its own separate loan, so someone financing one grocery trip a week can end up carrying four loans in a single month, each on its own two-week payment schedule, adding up to a dozen separate withdrawals hitting a bank account before that month is over. Miss a paycheck, and there isn’t one payment to catch up on. There are several, on different days, from different lenders, for food that’s already gone.

This is the mechanism that turns a small loan into a bigger problem. It isn’t that any single purchase is unaffordable. It’s that the payments overlap, and overlapping payments are far harder to track than one bill on one due date.

Nobody official is watching how much you owe

buy now pay later and shopping trolley
Image Credit: Shutterstock

Credit cards come with federal rules that let you dispute a charge, get a refund if something goes wrong, and see clear terms before you sign up. Buy now, pay later mostly doesn’t. Federal regulators withdrew the rule that would have applied those same credit card style protections to buy now, pay later loans in 2025, and have since said they don’t plan to bring back a version of it.

That missing protection matters most when someone is carrying several loans at once. Lenders in this industry generally can’t see what a customer owes to a competing app, so nobody outside a borrower’s own bank account has a full picture of how much food debt is actually stacked up. It’s common for people using these loans to have several open at once, sometimes five or more, and keeping that many separate due dates straight is hard even for someone paying close attention.

The result is that several separate obligations go untracked by anyone but the borrower, all coming due around the same time whether or not the paycheck covers them.

Your credit score is only starting to catch up

poor credit score report
Image Credit: Shutterstock

For most of the time buy now, pay later has existed, none of it touched your credit score. Pay every installment on time or miss every one, and your score didn’t move either way. That started changing when new scoring models built specifically to include buy now, pay later activity became available to lenders in the fall of 2025, offered alongside the credit scores lenders already use rather than replacing them outright.

Because the new models are optional and roll out lender by lender, most buy now, pay later activity still isn’t showing up in the score a lender actually pulls when someone applies for a car loan or a credit card. The upside of paying on time, a stronger score for responsible use, is still thin for most people. The downside is catching up faster. Where a lender has adopted the new model and a loan is being reported, a missed buy now, pay later payment can now hurt a score much like a missed credit card payment would, stacked on top of whatever late fee the loan itself already charges.

Anyone leaning on these loans for food should assume that direction is where things are heading, even if it hasn’t reached their specific lender yet.

Free until it isn’t

Pay-in-4 plans are usually marketed as interest free, and for a single on-time purchase, they often are. But the industry has been shifting toward longer loans that do carry interest, and that shift shows up in the numbers. More than a third of all buy now, pay later loans issued now carry interest, not the classic four-payment, no-interest structure most people picture when they hear the term.

Late fees add another layer most people don’t budget for. Missing a single payment can trigger a fee in the range of 7 to 8 dollars, and researchers who modeled what a repeat borrower could end up paying in fees on a small, recurring loan found the effective cost could land somewhere between 139 and 208 percent annual interest once every fee is counted, on a loan that was marketed as free.

None of that shows up at checkout. It shows up later, in the fine print of what a missed payment actually costs.

What actually helps if you’re financing food to get through the week

SNAP
Image Credit: United States Department of Agriculture, Public domain, via Wikimedia Commons

Keep one buy now, pay later loan open at a time instead of layering a new one on top of an unfinished one. If last week’s grocery loan isn’t paid off yet, that’s the signal to pay cash or use a card for this week’s trip, even if it means a smaller cart. Write down every open balance and its due date in one place, since no lender or app is tracking that across platforms for you.

Treat these loans as a stopgap for one rough week, not a standing part of the grocery budget. If income consistently falls short of covering food costs, that’s worth addressing directly instead of financing it every week. SNAP benefits and local food banks exist specifically to cover that kind of shortfall, without interest, late fees, or a repayment schedule attached.

A loan taken out to buy the same groceries as last week doesn’t fix the shortfall. It just moves the due date forward, and doing it every week adds a fee on top of the same bill, again and again. Breaking that pattern sooner means fewer stacked loans to untangle later, and less risk that this month’s grocery bill turns into six weeks of payments instead of one trip to the store.

The bottom line

bottom line new
Image Credit: Shutterstock

Buy now, pay later still adds up to a small slice of how Americans spend money overall. Total BNPL borrowing came to roughly 70 billion dollars in 2025, about 1.1 percent of what Americans put on credit cards, and the amount of BNPL debt outstanding at any given moment runs roughly 400 times smaller than credit card debt outstanding nationwide.

Small in the aggregate doesn’t mean small for the household carrying five of these loans at once with nobody else keeping count. The real risk was never the first loan taken out for a rough week. It’s the fifth one, running quietly in the background while nobody, including the borrower, has a clean total.

August is an odd in-between month. It is still hot enough to want cold desserts and anything labeled “cooling,” but work, school, and fall routines are already creeping back onto the calendar. A few small upgrades can make that transition more pleasant without turning a warehouse run into a major spending event.

Sam’s Club has some genuinely useful indulgences right now, including fresh flowers for less than $8, hotel-style bath linens, inexpensive stoneware, and a couple of café-at-home buys that can earn their keep. Prices are accurate at the time of publishing but may vary by store or sell out quickly.

Member’s Mark Hotel Premier Luxury Bath Towel

Hotel Premier Luxury Bath Towel
Image Credit: Sam’s Club

A good towel is one of the cheapest ways to make an ordinary morning feel slightly less ordinary. The Member’s Mark Hotel Premier Luxury Bath Towel is $6.98 and measures 30 by 58 inches. It is made from 100% cotton with a thick, heavyweight feel, and several colors are offered depending on your club.

The price makes this especially useful if your linen closet needs help but you do not want to replace an entire matching set at once. Buy one or two for the towels you actually reach for every day, then leave the perfectly serviceable guest towels alone. It is a modest upgrade, but one you will notice every time you shower.

Member’s Mark Quick-Dry Memory Foam Bath Mat

foam mat
Image Credit: Sam’s Club

Stepping onto a cushioned bath mat instead of a thin, permanently damp rug qualifies as a small quality-of-life improvement. This 24-by-36-inch Member’s Mark mat costs $12.98. It combines memory foam with quick-dry layers, a skid-resistant backing, and a machine-washable design.

That is a manageable price for refreshing a bathroom without buying new hardware, paint, or a pile of decorative accessories. The larger size also makes more sense in front of a tub or double vanity than the tiny mats that barely catch one wet footprint. If your current rug is curling, stained, or taking a full day to dry, this is a useful indulgence rather than clutter.

DHC Lip Cream two-pack

lip cream
Image Credit: Sam’s Club

Luxury beauty products can get expensive fast, but a good lip balm is something you can enjoy every day without much financial damage. DHC’s Lip Cream comes in a two-pack for $15.98, or $7.99 per tube. The formula uses olive oil, aloe, and ginseng and can be worn alone or underneath lipstick.

This is not the cheapest lip balm in the building, and that is rather the point. It is a small step up from the basic tube rolling around in the bottom of your bag while still staying under $10 apiece. Keep one at home and one in your purse, desk, or car so you are not repeatedly buying replacements after leaving yours somewhere else.

NIGHT satin skincare and haircare pillowcases

pillowcases
Image Credit: Sam’s Club

You do not need a whole new bedding set to make your bed feel nicer. NIGHT’s satin pillowcases come two to a pack for $16.98, which works out to $8.49 each. Queen and king sizes are offered, along with several neutral and soft colors. The slick satin surface is designed to create less friction against hair and skin while you sleep.

For anyone who wakes up with tangled hair or simply likes the feel of satin, this is a much cheaper bedroom refresh than replacing sheets or buying specialty bedding. Two cases also means you can rotate them through the wash instead of treating one fancy pillowcase like precious cargo.

Member’s Mark carnations

carnations
Image Credit: Sam’s Club

Fresh flowers are an actual little luxury, mostly because they serve no purpose other than making a room nicer. Sam’s Club makes the habit easier to justify with Member’s Mark carnations for $7.84. The stems are about 25 inches long, and the bouquet comes in assorted colors and varieties depending on what is available at your club. A vase is not included.

For less than the price of many small décor purchases, you can put something fresh on the kitchen table, desk, or entryway and then move on when the flowers are done. Carnations are also practical for splitting into two smaller containers if one big arrangement feels like overkill. No faux greenery to dust six months from now.

Member’s Mark 3-Wick Scented Candle

scented candle
Image Credit: Sam’s Club

A 24-ounce candle for $14.97 is a reasonable way to get the cozy-home effect without paying boutique candle prices. Member’s Mark uses a soy wax blend, cotton wicks, and scented oils, with different vessels and fragrances available. The candle is currently offered for pickup, delivery, or shipping.

This works best for people who already burn candles regularly, not anyone trying to invent a new hobby involving scented wax. At 24 ounces, it is substantial enough for a living room or kitchen and makes more sense than collecting several tiny candles that each last a few evenings. It can also double as an inexpensive host gift if you keep one unopened.

Member’s Mark Cooling Throw Blanket

cooling blanket
Image Credit: Sam’s Club

August weather does not always cooperate with people who like sleeping under a blanket. This 60-by-70-inch Member’s Mark Cooling Throw starts at $10.52, with the exact price depending on the color or pattern. One side uses cool-to-the-touch fabric, while the reverse is soft microfiber with lightweight filling.

It is a useful compromise for anyone who wants the comfort of a throw without piling on a heavy fleece blanket in late summer. The oversized dimensions are big enough for the couch or the foot of a bed, and the sale price is low enough that you do not need to pretend it is an heirloom purchase. Hot sleepers may get the most use from it well beyond August.

Member’s Mark 5.5-Quart Modern Ceramic Jumbo Cooker

Modern Ceramic Jumbo Cooker
Image Credit: Sam’s Club

If your favorite skillet is scratched, warped, or too small for dinner, replacing it with something nicer can feel surprisingly indulgent. The Member’s Mark 5.5-quart ceramic jumbo cooker is $33.96. It has a ceramic nonstick cooking surface, works with induction cooktops, is oven-safe to 450 degrees, and comes in several colors.

The wide, deep shape is useful for the meals people actually cook on weeknights: pasta, stir-fries, chicken and vegetables, skillet casseroles, and anything that starts out neatly portioned and somehow doubles in volume. It costs more than a basic frying pan, but it can replace several less-useful pans if you are short on cabinet space.

Capresso Automatic Milk Frother

automatic milk frother
Image Credit: Sam’s Club

This is one of the pricier indulgences at $54.98, so it only earns its spot if you already make lattes, cappuccinos, or hot chocolate at home. The Capresso frother makes hot or cold milk foam, and its large-capacity pitcher is dishwasher safe. It is currently available for shipping.

Someone who drinks plain drip coffee every morning can safely keep the $55. For a household that regularly wants foamed milk, though, this gives basic home coffee a café-style finish without requiring an espresso machine that occupies half the counter. It also keeps the upgrade contained to one compact appliance instead of another elaborate coffee system with twelve buttons nobody remembers how to use.

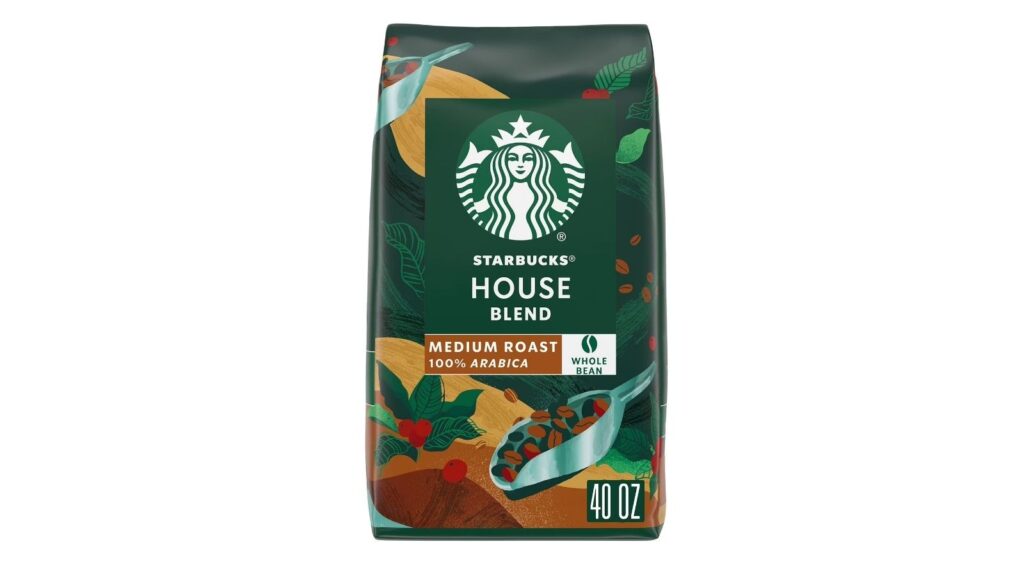
Starbucks House Blend whole bean coffee

whole bean coffee
Image Credit: Sam’s Club

A 40-ounce bag of Starbucks House Blend whole beans costs $24.98, or about 62 cents per ounce. It is a medium roast made with 100% Arabica beans, so it is an easy choice for households that want familiar coffee without buying smaller bags every week.

The value here depends on owning a grinder and actually drinking enough coffee to work through a 2.5-pound bag while it is still fresh. If that describes your household, keeping better beans at home can make the morning pot feel less like a compromise. If you drink one cup every third Tuesday, the giant bag will become expensive pantry décor, so buy accordingly.

Member’s Mark Organic Extra Virgin Olive Oil

extra virgin olive oil
Image Credit: Sam’s Club

Better ingredients can be a more useful luxury than another kitchen gadget. Member’s Mark Organic Extra Virgin Olive Oil is currently $15.91 for 68 fluid ounces, or roughly 23 cents per fluid ounce. The bottle is available through Sam’s Club’s current ordering options.

Use it for salad dressing, roasted vegetables, marinades, dipping bread, or finishing simple pasta, and a basic dinner gets a small upgrade without adding another specialty ingredient. The catch is the bottle size. Olive oil is not a bargain if it sits open forever, so this makes the most sense for households that cook with it frequently or can split a purchase with someone else.

Member’s Mark imported cheese tray

cheese collection
Image Credit: Sam’s Club

Building a cheese board one wedge at a time can turn an innocent snack into a surprisingly expensive grocery trip. Member’s Mark sells a 32-ounce cracker-cut imported cheese tray for $13.88, about 43 cents per ounce. The tray includes Irish cheddar, French Emmental, Belgian Fontina, and Dutch Gouda, already sliced for crackers or sandwiches.

It works for casual guests, packed lunches, an easy Friday-night snack plate, or anyone who likes having several cheeses around without four half-open blocks slowly drying out in the refrigerator. The resealable tray helps on that front. Add fruit and crackers you already have, and it looks considerably more deliberate than the effort involved.

Member’s Mark chocolate croissants

Chocolate Croissants
Image Credit: Sam’s Club

The bakery case has a particularly budget-friendly treat right now: 12 Member’s Mark chocolate croissants for $5.46. That is about 46 cents apiece. They are baked fresh in club and rolled with semi-sweet chocolate, making them an easy breakfast or coffee break that feels a bit more special than toast.

At this price, you can put out pastries for several people without making a separate bakery stop or spending several dollars on each serving. They also make sense for a household with teenagers, visiting family, or anyone else capable of making a dozen pastries disappear with unsettling speed. This is a treat, not a nutritional strategy, but the cost per serving is hard to argue with.

Island Way assorted fruit sorbet

fruit sorbet
Image Credit: Sam’s Club

For a late-summer dessert that feels more interesting than another tub of ice cream, Island Way’s assorted fruit sorbet is currently $11.87 for 10 individual servings. The assortment includes coconut, grapefruit, orange, and lemon sorbets presented in fruit shells.

That comes to about $1.19 per serving, which is reasonable for a dessert you could put straight onto the table for guests without plating, slicing, or pretending you remembered to bake. The individual portions also help if a full-size frozen dessert tends to linger in your freezer until it collects enough frost to qualify as a geological sample.

Member’s Mark by FujiSan sushi roll combo tray

sushi
Image Credit: Sam’s Club

Takeout is one of those small conveniences that can become a large monthly number. The FujiSan Sushi Roll Combo Tray gives you 20 pieces for $15.73, or about 79 cents each. The tray combines several rolls and comes with soy sauce, wasabi, and pickled ginger. It is prepared fresh in club and currently offered for pickup.

For one hungry person or two people sharing a quick meal, it can make an ordinary weeknight feel more like picking up dinner from somewhere without adding delivery fees or a stack of side orders. Sushi quality and selection can vary by club, so this is one to inspect before it goes into the cart rather than ordering blindly for an important occasion.

Ello Pop & Fill stainless steel water bottles

water bottle
Image Credit: Sam’s Club

Two reusable 22-ounce stainless steel bottles are currently $19.10, down from $23.88 through Aug. 16. Each Ello Pop & Fill bottle has a locking lid, straw, and push-button QuickFill opening. They are designed for cold drinks, not hot ones.

At $9.55 per bottle, the pair is useful for two family members or for keeping one at work while the other stays at home. August is also exactly when an insulated bottle earns its cabinet space, whether you are heading to a sports field, commuting, or simply trying to keep water cold in the car. The two-pack is the value here, so skip it if you already own a shelf full of perfectly good bottles.

NatureWell Guava Moisturizing Cream

Guava Moisturizing Cream
Image Credit: Sam’s Club

NatureWell’s Guava Moisturizing Cream comes in two generous 16-ounce tubs for $19.98, or $9.99 each. The cream is made for face and body use and has a rich but fast-absorbing texture. The guava two-pack is currently available for shipping.

Thirty-two ounces is a lot of moisturizer, but that is useful if you actually apply it daily instead of rationing an expensive little jar. Keep one tub in the bathroom and one beside the bed, or split the pack with someone else. This is a sensible way to make an everyday routine feel nicer without drifting into tiny jars with prices that require a financing plan.

Member’s Mark reactive stoneware pasta bowls

pasta bowls
Image Credit: Sam’s Club

Restaurant-style pasta bowls make even leftovers look more considered, and this four-piece Member’s Mark stoneware set costs $14.88. That works out to $3.72 per bowl. The set uses a reactive stoneware finish and is currently available for shipping.

The wide bowl shape is useful well beyond spaghetti. Think grain bowls, big salads, curry, soup, stir-fries, or any meal where a flat dinner plate seems determined to send sauce onto the table. Four nicer everyday bowls for less than $15 is a more practical dining-room refresh than replacing an entire dish set just because your current plates suddenly look boring.

The simple answer is that yes, volunteer tutoring can directly advance your career by turning real-world volunteering into verifiable professional credentials. Unemployed job seekers who log volunteer hours enjoy 27% higher odds of finding a job compared to candidates with identical resumes who do not, according to a Corporation for National and Community Service (CNCS) report. Hiring managers view volunteer leadership as practical proof of core competencies.

Learn how tutoring experience can build transferable skills, strengthen your resume, and expand your network.
Image Credit: Google Gemini

Building marketable skills through structured tutoring

When you tutor, you are running direct project management and managing dynamic client communication. You learn to break complex ideas into actionable steps, track performance metrics, and pivot strategies when standard methods fail.

These exact competencies separate middle managers from individual contributors. Research reports on workforce development indicate that structured volunteer roles improve job prospects for 58% of participants and sharpen communication skills.

There are lots of opportunities out there, many of which are easy to access and deliver niche-specific skills that employers will value. Working with young people who have learning barriers to overcome is a good example of this, as the experience is beneficial and provides transferable skills to those who enter such volunteer programs.

For instance, around 1 in 5 children are dyslexic to some degree, so there are support schemes in place to provide assistance so that they aren’t precluded from the same educational opportunities as their peers. If you decide to become a Dyslexia Tutoring Program volunteer tutor you build specialized expertise in structured learning frameworks, behavioral adaptation, and executive function support. Framing this experience on a resume shows employers you possess patience, structured problem-solving skills, and high emotional intelligence.

Translating specialized volunteer roles to professional resumes

Volunteering should never sit buried at the bottom of your resume as an afterthought. Treat it as legitimate, output-driven employment by highlighting actionable metrics and leadership scope.

For professionals managing packed schedules and looking to get paid well for completing stressful duties, consistency matters far more than total hours worked. You can build a standout professional portfolio by carving out explicit, micro-focused time blocks each week.

  • Dedicate one hour every Tuesday evening to student lesson planning
  • Commit to a two-hour virtual tutoring session every Thursday afternoon
  • Reserve thirty minutes on Friday to document progress metrics and update performance logs

These three focused blocks generate four hours of weekly skill-building without derailing your primary job search or family obligations. If your time management leaves a little to be desired, you will need to make sure you prioritize any training you undergo, as the results will make this investment worthwhile.

On your LinkedIn profile, list your volunteer title under your experience section rather than hiding it in general interests. You can frame the work using high-impact phrases.

For instance, you could say: “I designed customized multi-sensory reading interventions for young learners, boosting literacy assessment scores by 35% over a six-month period.” This language shifts the narrative from casual helper to results-oriented specialist.

Leveraging references and professional networks

Thousands of career changers hit dead ends simply because they lack industry-specific references. Direct supervisors at educational non-profits see your work ethic under pressure, your reliability, and your interpersonal effectiveness.

These directors write glowing, highly detailed letters of recommendation that carry massive weight with corporate recruiters. Furthermore, non-profit boards and fellow volunteers represent an untapped professional network.

The relationships you cultivate while teaching students often lead to internal job referrals, introduced contacts, and unadvertised career opportunities. Exploring other guides across our blog will help you manage your career and motherhood.

Divorce can be a lot to deal with, and deciding whether to go through it alone or get legal advice is a key decision to take. There’s no easy solution to this – the degree of complication in the marriage, how well you can continue to communicate with each other, and the amount of time needed to deal with various documents come into play.

What a DIY divorce looks like

Proceeding with a divorce without a lawyer works well when both parties have already agreed on key issues such as dividing assets, child custody, and financial support. These are known as “uncontested” divorces and center on completing necessary forms rather than contesting issues of fact.

Going the DIY route usually means:

  • Looking up the state’s filing rules and residency requirements
  • Filling out and submitting court paperwork correctly
  • Figuring out child support using state guidelines
  • Putting together a parenting plan or custody agreement
  • Showing up to any required court dates without a lawyer

If you have a straightforward financial situation and an ex-partner willing to work together, this option can help you save a lot of money!

The hardest part of a DIY divorce is usually dealing with the paperwork. Courts have high standards when it comes to layout and language, and a single missing signature can cause delays of weeks. That’s where self-signed legal document forms come in handy. Online services such as YourForms provide templates for this reason: to guide you through completing every part. Using solid legal document templates instead of hiring a lawyer to create all documents from scratch can help save a good amount of money. Keep in mind that legal forms cannot provide legal advice; hence they are useful when the issue involved is quite clear-cut!

When it’s worth hiring a lawyer

Some divorces just aren’t simple, and some situations aren’t safe to handle alone. It’s worth getting a lawyer involved if any of these apply:

  • There are significant assets, retirement accounts, or a business to split
  • One spouse might be hiding money or income
  • There’s a history of abuse or controlling behavior
  • Custody is being contested
  • One spouse knows a lot more about finances or the law than the other
  • Spousal support or tricky tax stuff is on the table

In such cases, an attorney is doing more than just dealing with paperwork – they’re helping to secure a mother’s financial future and provide stability for her children. Attorneys can identify issues self-represented parents might not think to ask about, including what happens to a retirement fund during divorce or how child custody arrangements could affect future moves.

Cost vs. risk

Money is usually the deciding factor, and that’s reasonable. A DIY divorce can cost several hundred dollars in court fees, whereas one involving lawyers can be expensive in the thousands. But cheap does not always mean cheap in the long run – poor financial arrangements or undervalued assets can lead to financial losses far greater than those incurred through paying lawyers.

Some moms seek a middle ground: paying a lawyer a fixed fee to review a self-drafted contract or retaining one solely to handle child custody issues while dealing with other matters alone. It provides access to legal advice without having to pay the entire cost.

Bottom line

It’s all about being truthful about just how complicated the situation is and to what extent the two parties are capable of being able to trust each other. A peaceful, uncomplicated divorce can be managed through suitable legal documents and some patience. A more complex situation, however, almost certainly requires legal advice. Either way, the goal is the same – coming out the other side financially secure and ready to build the next chapter.

There are more than 7 million single mothers nationwide, and many find themselves searching for tuition answers, trying to secure the best educational foundation for their children without bankrupting their households. Balancing a household budget while trying to cover private elementary or high school fees feels like a relentless math problem where the numbers never quite align.

You do not have to rely on a single golden ticket to make private schooling accessible. Bridging the cost gap usually requires combining state-level aid, school resources, strategic savings, and specialized financing options to cover the final balance.

Image Credit: Google Gemini

Tap directly into school-based financial aid

Most parents assume private school financial aid operates like higher education funding, but individual schools set their own institutional rules. You should apply for school-based aid during the initial admissions window, as funds dry up quickly.

Schools evaluate need through third-party processors such as SSS or FACTS, which review tax documentation, assets, and living expenses. Be prepared to present a detailed financial picture that reflects unusual household burdens or single-income realities.

Utilize State Education Savings Accounts (ESAs)

State-funded ESAs are changing how families manage education costs by allowing state dollars to follow the student. Participating states deposit dedicated funds into an account that parents can spend on approved educational expenses.

Unlike basic voucher programs, state ESAs and tax-credit scholarships offer flexible spending options for private tuition, specialized tutoring, and required learning materials. If you live in an eligible state, applying early in the calendar year gives you the best shot at securing a spot before state funding caps are reached.

Leverage tax-credit scholarships

Tax-credit scholarships function as a powerful alternative in states without broad ESA legislation. Corporations and individual taxpayers donate money to private non-profit scholarship organizations in exchange for a state tax credit.

These non-profit organizations then award those funds directly to eligible lower- and middle-income families. Check your state department of education portal to identify registered scholarship organizations operating in your area, as application windows vary widely.

Cover the gap with a dedicated K-12 loan

Even after stacking grants, scholarships, and installment plans, families often face a remaining funding gap. When traditional aid falls short, turning to this K-12 School Loan provider can offer the last-mile financing required to keep your child enrolled without sacrificing daily living essentials. Reputable lenders have products built specifically for borrowers in this situation.

Unlike high-interest credit cards, specialized education loans offer structured repayment plans designed for family budgets. Using a fixed-rate loan to cover the remaining balance helps preserve your cash flow while ensuring your child remains in their optimal learning environment.

Draw strategically from a 529 savings plan

529 savings accounts are no longer strictly reserved for college expenses. Under federal tax guidelines, families can withdraw up to $10,000 annually per beneficiary to pay for qualified elementary or secondary public, private, or religious school tuition.

While federal law permits these tax-free distributions, state tax treatment varies. Some states impose state-level income taxes or penalties on K-12 withdrawals, so verifying local rules with a qualified tax professional is essential before taking a distribution.

Negotiate tuition installment plans

Paying an entire annual tuition bill in one lump sum before September is unrealistic for most single-income households, even if you’re on top of budgeting. Most independent schools partner with tuition management providers to offer spread-out payment schedules.

Instead of facing one massive bill, you can split the costs into monthly payments spread over 10 or 12 months. This predictable monthly cadence makes private school costs manageable within standard working budgets without incurring heavy credit card interest.

Secure community and faith-based grants

Local philanthropic groups, civic organizations, and religious entities frequently manage dedicated education funds for neighborhood families. These grants often go unclaimed simply because parents do not know they exist.

Before looking at commercial financing, explore these neighborhood assets:

  • Local civic clubs like the Rotary or Kiwanis offer targeted youth education grants
  • Regional religious charities provide non-denominational tuition support based on financial need
  • Community foundations distribute localized endowment funds to support neighborhood students

Taking the time to research local community foundations can yield several thousand dollars in non-repayable grant aid.

Crafting your custom tuition strategy

Funding for private K-12 education rarely comes from a single financial source. Successful families mix state aid, school-level assistance, community resources, and responsible financing tools to create a sustainable multi-year plan.

Start by listing every non-repayable dollar available to your family, layer on flexible payment schedules, and use targeted loans only when necessary to bridge the final gap. Explore our blog for more guides on how to handle the ins and outs of parenting and finance.