scroll top

For executive women managing expanding enterprises, travel represents both an engine for growth and a significant strain on calendar control. Female professionals take 25 million business trips every day, reflecting a sharp rise in high-frequency travel among corporate leaders and entrepreneurs. Maximizing the return on these trips requires moving beyond basic survival tactics and treating travel as a strategic variable you can customize for optimal focus.
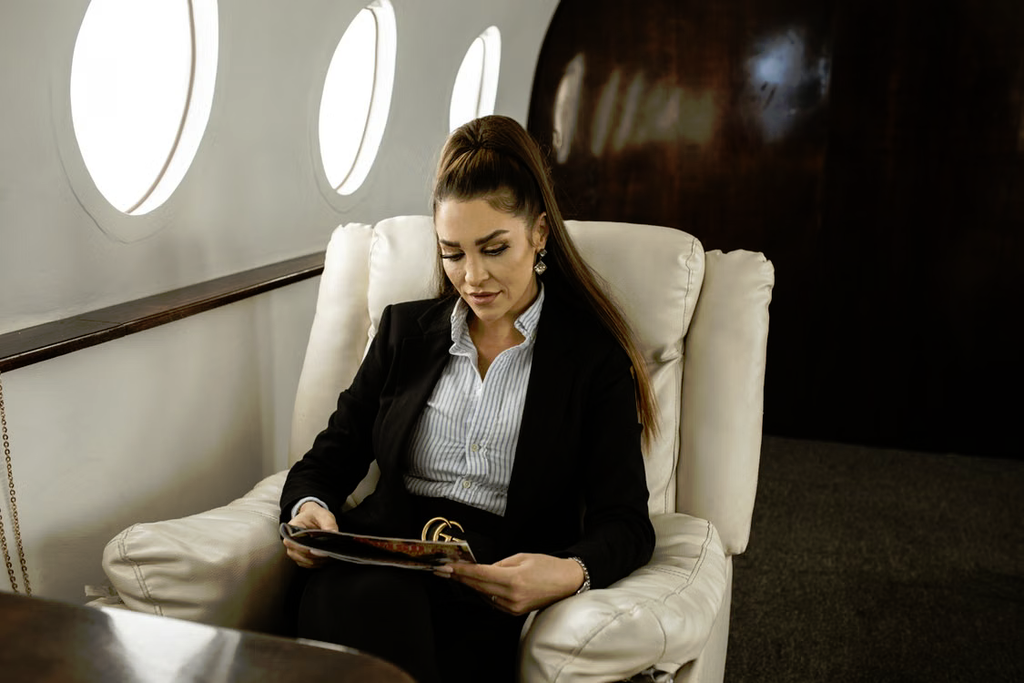
Learn practical business travel tips successful women use to stay productive, organized, and prepared while traveling for work.
Image Credit: RDNE Stock project via Pexels

The flexible approach to flying

Managing demanding schedules starts with radical control over flight times, airport procedures, and ground transport. Losing three hours to security bottlenecks or layovers directly erodes the focus needed for high-stakes dealmaking. Successful leaders treat transit as a high-value window, not passive waiting time, ruthlessly cutting operational friction at every stage.

Smart schedule design protects personal bandwidth while keeping strategic priorities intact. Modern itineraries focus on absolute efficiency, allowing executives to arrive clear-headed and fully prepared.

  • Eliminating multi-leg flights in favor of direct point-to-point routes
  • Prioritizing hotel properties equipped with dedicated quiet workspaces and secure networks
  • Booking flexible transport options that adapt instantly to shifting meeting schedules

When time constraints are particularly severe or access to regional centers is limited, standard commercial flights often fall short. For attending to business in Las Vegas, booking private charters in Nevada gives leaders complete command over departure times and onboard privacy, eliminating the multi-hour delays native to commercial terminals, for example. This combination of flexibility and productivity is available wherever business jet charters are offered nationwide.

Protecting energy and operational focus

Preserving physical resilience on the road requires intentional boundaries around rest, personal time, and mental space. Corporate travel metrics reveal that high-performing executives maintain peak output by structuring downtime with the same discipline as board meetings. Treating wellness as non-negotiable prevents the burnout that often accompanies rapid expansion.

Maintaining high energy levels depends on designing a travel routine that mimics normal daily habits. Protecting a consistent sleep window and keeping early morning hours clear for strategic thinking prevents travel fatigue from compounding over multiple days.

Recent research on high-frequency travel behaviors indicates that scheduling flexibility correlates directly with reduced stress and higher productivity on multi-city trips. Allowing buffer time between back-to-back sessions ensures unexpected schedule shifts don’t derail the entire trip.

Integrating short periods of downtime allows for reflection and mid-trip adjustments. Treating local meals or short walks as essential mental resets keeps creative focus sharp when negotiating complex deals.

You also need to plan for how to handle trips involving the family, regardless of what context they might take place in. So, working out how to stay sane on a road trip with kids is just as important as working to keep your energy and focus on a business-based journey. Preparation is thing that makes a positive impact in both contexts.

Integrating personal flexibility into work travel

Blending professional commitments with personal autonomy creates a sustainable rhythm for frequent trips. Many leaders extend business trips into weekend stays or arrange travel around personal milestones, making heavy travel commitments fit naturally into their lives.

This approach works best when schedules are planned far in advance with clear boundaries. Setting defined work hours while on the road keeps professional responsibilities from spilling into every evening.

Female travel decision-making leans heavily toward hyper-customized itineraries that accommodate both intense work demands and personal well-being. Exercising full autonomy over how, when, and where travel happens transforms mandatory corporate trips into empowering, productive experiences.

Building a flexible, highly efficient travel structure ensures that business trips advance company growth without compromising personal balance. Exploring our other detailed travel guides provides further frameworks for optimizing executive routines and making the most of your leisure trips as well.
There is a particular kind of guilt that shows up when a single mom thinks about spending money on her own face. The kids need shoes. The car needs tires. And here you are pricing out Botox like it is a reasonable line item.

Here is the thing. It is a reasonable line item, or it can be. The problem is not the spending. The problem is spending without a plan, which is how a $150 appointment turns into $2,000 a year you never sat down and added up. Treat it like any other money decision and it stops being a guilty secret and starts being a budget category you control.

These are the seven rules I would hand to a friend before she books anything. While writing them I kept one practice open in another tab, Salt Medical Aesthetics in Bend, Oregon, a two provider medical practice that publishes its prices and its rules in plain sight, so it turns up as the example more than once.

1. Decide what it is for before you decide what it costs

Be specific. “I want to look less tired in meetings” is a goal. “I want to feel better about myself” is not, because no treatment can be measured against it and you will keep spending trying to hit a target that does not exist.

Write down the one thing that bothers you when you look in the mirror. One thing. Then you can price a solution for that thing and judge whether the number is worth it. If you cannot name it, you are not ready to spend on it yet, and that is fine.

2. Learn the unit math before you walk in

Wrinkle relaxers like Botox are priced per unit, and the number of units is where the cost hides. The per unit price sounds small. The units add up.

Here is what good looks like. Salt Medical Aesthetics publishes its per unit pricing, its minimum and its first time patient rate right on the Botox page of its website, which lets you do the math from your couch before you ever call. That is rarer than it should be. Practices generally describe results from wrinkle relaxers as lasting a few months, so a realistic annual cost is several visits, not one. Whatever practice you use, ask for the expected unit count for your specific area in writing, multiply it out for a year, and put that number in your budget before you say yes. If they will not give you a range, that is your answer about the practice.

3. A membership only pays off if you were going anyway

Med spa memberships are everywhere now and most of them are designed to make you feel like you are saving money while you spend more of it. Some are genuinely good. The test is simple: would you have spent this money without the membership?

Salt Medical Aesthetics calls theirs the Salt Fam membership, and it is a useful example of one that is structured honestly. The monthly fee goes into a patient wallet you spend on treatments rather than disappearing, members get a discount on services and retail plus a lower per unit rate on wrinkle relaxers, and after a short minimum term you can cancel with a week’s notice by email and no fee.

Run the numbers on that. If you would spend that money on treatments anyway, the membership just banks it monthly and takes a little off the top. If you would only go once or twice a year, it is a bad deal because the credits are non refundable and you will feel pressure to use them. Memberships reward regulars and punish the occasional visitor. Know which one you are.

4. Ask what is free, because some of it is

Most people never ask and most practices never volunteer it. A free first consultation is standard at any practice worth using, and you should walk out of it with a plan and a price, not a booking. Some places, including the one above, include a free two week follow up with a touch up if you followed the recommended dosing. That is real money, because a touch up elsewhere is a second appointment.

Referral programs are the other one. It is common for a friend to get money off her first visit and for you to get a credit in return. If you and another mom were both going to try it, go together and split the difference.

5. Budget for the whole course, not the first session

Some treatments are one and done. Some are sold as a series, and the first session on its own does very little. Microneedling is the classic example. Practices typically quote it as a course of three or four monthly sessions. Salt Medical Aesthetics lists it both ways, as a single session and as a course, and says plainly on the page that results build over weeks and are not permanent, which is the information you need to budget for it as a recurring cost rather than a one off. Whether a series is right for your skin is a question for a licensed provider. Whether you can afford the whole series is a question for your budget, and that one you can answer today.

If you can only afford the first session, you cannot afford the treatment. Wait until you can afford the series, or pick a different treatment. Half a course is the most expensive way to get no result.

6. Never finance your face

Not on a card, not on a payment plan, not on a buy now pay later button at checkout. If it cannot come out of cash flow this month or a sinking fund you built for it, it waits. Aesthetic treatments are not an emergency, they are not an asset, and they are the first thing that should go when money is tight.

A good practice will not push financing on you. A membership is not a financing agreement, and one that says so in writing is telling you something about how they think. The moment someone starts talking about monthly payments on a $1,500 treatment, you are in a sales conversation, not a medical one.

7. The license matters more than the price

The cheapest injector in town is cheap for a reason. The question that matters is not “how much” but “who,” and the answer should be a licensed medical provider, a nurse practitioner, a physician assistant, an RN under medical direction, whose name and credentials are on the website.

You want a practice where the answer to “should I do this” is sometimes no. Salt Medical Aesthetics goes further than most and publishes it as one of three stated values on its website, under the heading We Say No, with the line that the most powerful word in aesthetics is no. That is the sentence you are looking for. A provider willing to lose a sale today is the one you can trust with your money next year.

Why I keep coming back to the same example

Salt Medical Aesthetics opened in Bend in 2023 and is run by two women who came to aesthetics from hospital nursing. Suzanne Puryear is a board certified nurse practitioner with a doctorate in nursing practice who worked in cardiac transplant nursing and then primary care before founding the practice. Shannon Patterson is a registered nurse who grew up in Bend and spent three years in a cardiac intensive care unit in Seattle. They call their approach The Sisterly Way, and the three values they publish on the site read like a budgeting guide in disguise: less is luxury, we say no, and a minimal menu, mastered.

What caught my attention was not the menu, which is short on purpose. It was the money habits. Every price is on the website, per unit and per syringe, including the first time patient rate and the member rate, so you can do the math from your couch before you ever call. The first consultation is free and ends with a plan, not a needle. A two week follow up is built into every wrinkle relaxer appointment, with a touch up at no charge if you followed the recommended dosing. Refer a friend and she gets a discount on her first visit while a credit lands in your patient wallet.

None of that is medical advice and I am not qualified to give you any. It is a description of a business that treats a single mom’s money with respect, and that is the standard I would hold any practice to, wherever you live.

Spend it like you mean it

None of this is about whether you deserve to spend money on yourself. You do. You are running a household on one income and you are allowed to have a line in the budget that is only for you.

The discipline is in how. Name the goal, learn the math, skip the financing, and pick the practice by the license and not the price. Do that and the guilt goes away, because you are not spending money you cannot account for. You are spending money you planned to.

Stay-at-home moms contribute enormous value to their households, even when that work does not come with a paycheck. But stepping away from paid employment does not mean stepping away from financial growth. With planning, communication, and steady habits, moms and money can be part of the same confident conversation.

Investing for stay-at-home moms is about using the resources available now while protecting future options. That may mean funding retirement accounts, building emergency savings, learning about different asset types, or simply staying engaged in household financial decisions.

Can stay-at-home moms invest without earning a paycheck?

Yes, stay-at-home moms can often continue investing even without a traditional income, especially when the household has shared financial resources and a clear plan. The key is to treat investing as a family priority, not as something reserved only for the person who receives a paycheck.

A stay-at-home parent may not have wages, but they still need financial security, retirement savings, and access to long-term wealth-building tools. If there is a spouse or partner earning income, the household can discuss how much money can be directed toward savings and investments each month. In some cases, a spousal IRA may also be worth exploring with a qualified financial or tax professional.

This is where the phrase “How stay-at-home moms can continue investing and building their financial future” becomes practical rather than theoretical. It starts with ownership, visibility, and consistent action.

Start with a clear household money picture

Before choosing investments, it helps to understand what money is coming in, what is going out, and what is already saved. This step can feel basic, but it gives stay-at-home moms investing confidence because decisions are based on real numbers instead of guesses.

A useful money check-in can include:

  • Monthly income and essential expenses
  • Debt balances, interest rates, and repayment plans
  • Emergency savings and insurance coverage
  • Retirement accounts, brokerage accounts, and college savings
  • Short-term goals, such as home repairs, travel, or childcare costs
  • Long-term goals, such as retirement, education, or returning to work

This conversation should not feel like asking permission. A stay-at-home mom is part of the household’s financial engine, and she should have access to account information, passwords, statements, and planning discussions. Financial transparency helps prevent surprises and makes future decisions easier.

Build the foundation before taking bigger risks

Investing works best when it sits on top of a stable financial base. If the household has no emergency fund, high-interest debt, or unclear monthly cash flow, those issues may need attention before adding more investment risk.

A practical foundation often includes three layers. First, maintain enough cash savings to handle unexpected expenses without relying immediately on credit cards. Second, make a plan for expensive debt, especially debt with high interest. Third, contribute consistently to long-term accounts when the budget allows.

This does not mean everything has to be perfect before investing begins. Small, regular contributions can still matter. The goal is balance: saving for the future without leaving the present vulnerable.

Retirement planning still matters during caregiving years

Time spent at home with children can be deeply meaningful, but it can also create gaps in retirement savings. That is why retirement planning deserves attention even during years when paid work is paused.

Stay-at-home moms may want to review existing retirement accounts from previous jobs and decide whether to leave them, roll them over, or adjust investments. If married and eligible, a spousal IRA may allow contributions based on the working spouse’s income, but rules and limits can change, so professional guidance is helpful.

Retirement planning is not only about account balances. It is also about making sure both partners are protected. Beneficiary designations, life insurance, disability coverage for the earning spouse, and estate planning documents can all affect a stay-at-home parent’s financial future.

What investment habits help stay-at-home moms stay consistent?

The most helpful habit is creating a simple, repeatable system. Investing does not need to be dramatic, complicated, or constantly adjusted. For many families, consistency matters more than trying to time the market.

Helpful habits include:

  1. Automate contributions when possible. Even small scheduled transfers can reduce decision fatigue.
  2. Review accounts regularly. A monthly or quarterly review keeps both partners informed without obsessing over every market move.
  3. Match investments to goals. Money needed soon may belong in safer places, while long-term money may have more room for market ups and downs.
  4. Avoid emotional decisions. Big headlines can create fear or excitement, but a written plan can keep choices grounded.
  5. Keep learning. Reading, listening to finance podcasts, or taking beginner courses can make investing feel less intimidating.

These habits make investing for stay at home moms feel manageable. The point is not to become an expert overnight; it is to stay engaged enough to make informed decisions.

Digital assets: cryptocurrencies, tokenized assets, and digital collectibles

Digital assets can be part of modern financial conversations, and stay-at-home moms may hear about them through social media, friends, or family members. Examples include cryptocurrencies, tokenized assets, and digital collectibles. But what is cryptocurrency? Cryptocurrencies are digital currencies that use blockchain technology to record transactions and generally operate without a central bank. For those interested in crypto investing, this emerging asset category can offer a way to diversify a portfolio and participate in the continued development of blockchain-based finance. These assets can be interesting, but they can also be highly volatile, difficult to value, and vulnerable to scams or poor security practices. A prudent approach starts with education before action. Before buying any digital asset, understand what it is, how it is stored, what risks are involved, and whether it fits the household’s broader financial plan. If the investment cannot be explained in plain language, it may not be ready for your money.

Risk-aware digital asset habits include:

  • Limit exposure to an amount the household can afford to lose.
  • Avoid borrowing money to buy speculative assets.
  • Use reputable platforms and strong security practices.
  • Be cautious of guaranteed returns, celebrity promotions, and pressure to act quickly.
  • Keep records for tax reporting and account access.
  • Discuss digital asset purchases with a spouse, partner, or financial professional before committing significant funds.

Digital assets should not replace emergency savings, retirement contributions, or basic financial protection. For most families, they are better viewed as a higher-risk category that requires extra caution, not as a shortcut to financial independence.

Protect your financial identity and decision-making power

One overlooked part of moms and money is maintaining financial independence inside a shared household. Even in a healthy partnership, both adults should understand the finances and have the ability to act if needed.

That can mean keeping a credit card in your own name, monitoring your credit report, knowing where important documents are stored, and having access to bank and investment accounts. It may also mean discussing how household money is allocated for personal spending, education, childcare support, or future career development.

A stay-at-home mom’s unpaid work supports the family’s earning potential. Financial systems should reflect that value with fairness, respect, and shared control.

Plan for future flexibility

Some stay-at-home moms plan to return to paid work later. Others may start a business, freelance, work part-time, or continue caregiving long term. Financial planning should leave room for any of those possibilities.

Consider setting aside money for future training, certifications, childcare during a job search, or business startup costs. Keeping professional networks warm can also support future earning power. Even small steps, such as updating a resume once a year or tracking volunteer and household management skills, can make re-entry feel less overwhelming.

Flexibility is a financial asset. The more options a family preserves, the easier it is to adapt when children grow, expenses change, or personal goals shift.

A simple starting checklist

If you are not sure where to begin, start with a short list rather than trying to solve everything at once:

  • Schedule a household money meeting.
  • List every account, debt, policy, and major bill.
  • Choose one savings or investing goal for the next three months.
  • Review retirement account options.
  • Build or strengthen emergency savings.
  • Learn the basics before exploring higher-risk investments.
  • Revisit the plan regularly as family needs change.

Small actions create momentum. The first step may be opening a conversation, logging into an account, or setting up a modest automatic transfer.

The takeaway

Stay-at-home moms investing in their future are not doing something extra; they are protecting the financial well-being of the whole household. Whether the focus is retirement, education, digital assets, or everyday money management, the most important tools are clarity, consistency, and shared decision-making.

A career pause does not have to become a financial pause. With a practical plan and an active voice in household finances, stay-at-home moms can continue building confidence, security, and long-term opportunity.

A divorce, a layoff or a drop in your credit score can raise what you pay for car insurance, even when your driving record hasn’t changed at all. Most of the increase comes from a short list of predictable causes, and you can push back on several of them.

You’re rebuilding a budget from scratch, maybe on one income for the first time, and the renewal notice arrives with a bigger number on it. Here’s what drives that number, and how to stay insured without overpaying.

Divorce splits the policy along with everything else

A shared auto policy usually has to be split once you and your ex stop living at the same address. The Insurance Information Institute (III) says that if either spouse changes address, you should get a separate auto policy right away. If you’re buying a car on your own, set up the new policy before you register it.

Expect the split to cost something. III notes that multi-car discounts often disappear once the cars are parked at different homes, and your rate can also shift if you go from being the secondary driver on a car to its primary driver.

Two loose ends are worth tying up early:

  • Take your ex off your policy once they’re out of the household. According to III, that protects you if they cause a crash and get sued.
  • Check whose name is on each title. A change in who owns a car also changes who holds the insurance on it, so a car still titled to your ex needs sorting out.

If you share custody of a teen driver, III says that teen will likely be listed on the policies in both households, which adds cost on both sides.

Your credit score shows up in your premium

In most states, insurers set your price partly with a credit-based insurance score, a rating built from your credit history that predicts how likely you are to file a claim. The National Association of Insurance Commissioners (NAIC) cites a FICO estimate that about 95% of auto insurers use these scores where the law allows it.

The gap between good and poor credit is big. NerdWallet’s September 2026 rate analysis found that drivers with poor credit pay 68% more for full coverage than drivers with good credit, $3,929 a year compared with $2,344. For minimum coverage, the averages were $1,023 and $644.

That means joint debt left over from a divorce, or a few missed payments after a layoff, can push your car insurance up even with a spotless record. A few states are exceptions. Experian reports that California, Hawaii, Massachusetts and Michigan bar insurers from using credit to set auto rates. If your credit took a hit this year, compare quotes for affordable car insurance before your renewal instead of accepting the new number.

Ask for the “extraordinary life circumstances” exception

A model law from the National Council of Insurance Legislators (NCOIL) calls on insurers that use credit to make reasonable exceptions for people whose credit was directly hurt by certain life events. The list includes divorce, an involuntary interruption of alimony or support payments, and an involuntary job loss lasting three months or more.

Some states, New Hampshire among them, have written the same list into their insurance rules. Where it applies, you generally make the request in writing, and the insurer can ask for documents showing the event actually affected your credit. It can also set a deadline tied to your application or renewal date, so ask early. Ask your insurer or your state insurance department whether it applies where you live.

Keep the policy active, even at a lower level

When cash is tight, canceling car insurance for a month can look like an easy way to free up money. It usually costs more later. An Insurify analysis updated in September 2026 says insurers may classify you as a higher-risk driver after a lapse, even if your driving record is good.

Before you let a policy lapse, try these instead:

  • Drop to your state’s minimum liability coverage. It costs less, though it only pays for damage you cause to other people and their property. If you’re financing the car, your lender will likely require full coverage.
  • Raise your deductible on collision and comprehensive, but only if your savings could cover it after a crash.
  • Ask to move your payment due date so it lands after payday.

If your car gets you to work and you couldn’t replace it, bare-minimum coverage can save money now and cost you a paycheck later.

When an SR-22 enters the picture

A rough stretch can also bring an SR-22, a form your insurer files with the state to prove you carry the liability coverage the law requires. Who needs one, and for how long, depends on your state. In Washington, for example, the Department of Licensing requires it from drivers convicted of certain offenses, drivers who didn’t pay a judgment, and drivers tied to certain accidents, in most cases for three years from the date they’re eligible to reinstate their license. Your own state’s DMV has the rules that apply to you.

Where nonstandard insurers fit

Nonstandard auto insurance is the part of the market for drivers whose risk factors make standard rates hard to get. CarInsurance.com lists SR-22 filers, drivers with poor credit, drivers with a coverage lapse and drivers with serious violations among them.

Every company weighs credit, lapses and driving history differently, so one driver can get very different quotes. Get quotes from at least one nonstandard carrier alongside the big names, and compare the same coverage levels side by side.

Then shop again at every renewal. As your credit recovers, the quotes you’re offered can change too. Sorting it out now means fewer surprises at renewal time.


Preparing a child for college is a process that takes years rather than a few months. Academic choices, financial planning, applications and everyday life skills all play a role in helping a student feel ready for the transition.

For single mothers, the process may require balancing college planning with work, household expenses and other family responsibilities. That can make starting early especially useful. There is more time to research options, set financial goals and help a child gradually take responsibility for their future.

College preparation does not have to happen all at once. Small steps taken consistently can make the process much easier to manage.

Start talking about college early

College does not need to be a distant topic reserved for high school.

Parents can introduce the idea naturally by asking children what subjects they enjoy, what careers interest them and what they might want to explore as they get older. These conversations can change over time, and that is perfectly normal.

The goal is not to pressure a child into choosing a specific career. Instead, early conversations help children understand that education can open different possibilities.

As they get older, those discussions can become more specific. Families can talk about different types of schools, potential majors and what students should expect from college.

Help your child build a strong academic foundation

Academic preparation is another area where starting early can help.

Encourage consistent study habits, regular reading and an interest in subjects that challenge your child. Mathematics, science, writing and other core skills can become important depending on the student’s future plans.

Parents do not need to know every answer to support academic progress. Staying in communication with teachers and school counselors can provide useful information about areas where additional support may be needed.

Strong grades matter, but so do good learning habits. A student who knows how to manage assignments and ask for help is developing skills that will remain useful in college.

Encourage interests outside the classroom

College preparation is not limited to academics.

Sports, clubs, volunteering, creative activities and part-time work can help students discover interests and develop useful skills. These experiences can also demonstrate commitment when students eventually apply to colleges.

There is no need to fill every afternoon with activities. Meaningful involvement is often more valuable than joining numerous organizations simply to build a longer list.

Encourage your child to explore things they genuinely enjoy. Those interests may eventually influence their choice of major or career.

Start saving and understanding college costs early

Financial planning is one of the most important parts of preparing for college.

Families should consider tuition, housing, meal plans, books, technology, transportation and personal expenses. The total cost can vary significantly between schools and locations, so it is helpful to research actual costs rather than relying on a general estimate.

Saving does not have to involve large amounts of money. Consistent contributions made over time can help create a financial cushion.

It is also worth discussing how much the family can realistically contribute. Understanding those limits early can make later decisions about schools and funding much clearer.

Research financial aid and scholarships

Scholarships and financial aid can play an important role in making college more manageable.

Students should begin researching opportunities before their senior year whenever possible. Some scholarships have specific eligibility requirements or deadlines that families may not know about until they start looking.

Parents can help by keeping track of deadlines and encouraging their children to complete applications carefully. Students should also learn about grants and other forms of financial assistance that may be available.

Financial aid research should be an ongoing part of college planning rather than a last-minute task.

Teach your child about money

College may be the first time a student manages a budget with significant independence.

Before that happens, parents can teach practical skills such as tracking spending, saving money and making thoughtful purchases. It can also be useful to explain the difference between needs and wants.

As college approaches, families should have honest conversations about financial responsibility. Some parents may consider parent loans as part of their strategy for covering education expenses, but any borrowing decision should be evaluated carefully. Understanding interest costs, repayment terms and the effect on the household budget is important before taking on additional debt.

The goal is to help students understand that education has financial responsibilities as well as academic ones.

Explore college options together

There is no single type of college that works for every student.

Families can explore community colleges, four-year universities, public and private institutions and other education options. Location also matters. An in-state school may have different costs from an out-of-state option, while living at home may reduce housing expenses.

Academic programs should also be considered. A student interested in engineering may need different resources from someone studying art or education.

Comparing schools based on academics, location, student experience and total cost can lead to a more informed decision.

Help your child understand the application process

The college application process can seem complicated when viewed all at once.

Students may need transcripts, essays, recommendation letters, test scores or portfolios depending on the school and program. Creating a timeline can make these requirements easier to manage.

Parents can provide guidance without taking over. The student should remain involved in writing essays, communicating with schools and tracking deadlines.

That involvement matters because applying to college is also an opportunity to develop independence.

Encourage career exploration

Students do not need to know exactly what career they want at age 15 or 16.

However, exploring different possibilities can help them make more informed choices later. Job shadowing, internships, career assessments and conversations with professionals can provide useful insight into different fields.

A student’s interests may change, and that is part of growing up. The purpose of career exploration is to provide information rather than force an early decision.

Prepare your child for independence

College readiness includes practical skills that have nothing to do with grades.

Students should gradually learn how to manage money, organize their schedules, do laundry, prepare simple meals and communicate with adults when they need assistance.

These skills can be taught over time. Giving children more responsibility at home allows them to practice before they are living independently.

Build a support network

Single mothers do not have to manage the entire college preparation process alone.

Teachers, counselors, family members, mentors and community organizations can provide information and practical support. Reaching out for help can also introduce families to resources they may not have discovered themselves.

A strong support network can make difficult decisions easier and give students additional people to turn to as they prepare for college.

Create a college timeline

A simple timeline can help keep everything organized.

During the early high school years, families can focus on academics, interests and financial habits. By junior year, students can begin researching schools, programs and financial aid opportunities more seriously.

Senior year becomes the time to finalize applications, submit financial aid forms, compare offers and make an enrollment decision.

Starting early gives families room to adjust when circumstances change.

Final thoughts

Preparing a child for college is a gradual process. For single mothers balancing multiple responsibilities, starting early can make academic, financial and practical planning feel much more manageable.

The goal is not to create a perfect plan. It is to give a child the knowledge, skills and confidence to make informed decisions about the next stage of their life.

With consistent preparation and open conversations, families can approach the transition to college with a clearer sense of direction.

For a single parent, the whole family rests on one set of shoulders. That makes protecting your income and your loved ones one of the most important financial jobs you have. The right insurance is the foundation of that protection.

Learn about the types of insurance every single parent should understand to help protect their family, finances, and future.
Image Credit: Vitaly Gariev via Unsplash

Insurance can feel complicated, but the essentials are straightforward once explained. This guide covers the cover that matters most to a single-parent household, and how the right guidance makes it simple. A knowledgeable broker such as Morgan Insurance Brokers can turn a confusing task into a clear plan. Understanding the basics is the first step.

Why does insurance matter more for single parents?

When you are the sole earner and carer, the stakes are simply higher. There is no second income to fall back on if illness, injury, or accident strikes. That single point of dependence is exactly what insurance is built to protect.

The goal is to keep your family stable no matter what happens. Good cover means an unexpected event becomes a manageable setback, not a crisis. Alongside a solid savings buffer, it is how you build an emergency fund of real security. Protection and savings work best together.

What types of cover should you consider?

A few core policies do most of the heavy lifting. You do not need everything on the market, only the cover that fits your life. Focus on the essentials first.

Consider these key types of protection:

  1. Life cover. Support for your children if you die.
  2. Income protection. A wage if illness stops you working.
  3. Health cover. Help with medical costs for the family.
  4. Home and car. Protection for your key assets.

Life cover matters most when others depend on you, and term life insurance offers straightforward, affordable protection for a set period. Income protection is just as vital, since your earning ability is your family’s engine. Together these form the backbone of a sensible plan.

How does a broker make it easier?

Insurance is full of jargon and fine print, which is where a broker earns their keep. A broker works for you, not an insurer, comparing options across the market. That independence is genuinely valuable.

Image Credit” Brooke Cagle via Unsplash

A good broker does the hard parts for you:

  • Compares. Weighs many insurers to find real value.
  • Explains. Turns fine print into plain language.
  • Tailors. Matches cover to your actual situation.
  • Supports. Helps if you ever need to claim.

This guidance saves both time and costly mistakes. Rather than guessing which policy fits, you get advice built around your family. For a busy single parent, that peace of mind is worth a great deal.

What if you run a business or side hustle?

Many single parents also earn through a small business or side hustle. If that is you, personal cover is only half the picture. Your work needs protection too.

Business insurance guards your income from claims, accidents, and liability. Government resources explain how to manage business insurance sensibly as you grow. A clear business insurance guide can help you spot the gaps early. A broker can then line up personal and business cover so nothing falls through the cracks.

How do you choose the right cover?

The right plan fits your family and your budget, not a generic template. A little thought now prevents both overpaying and dangerous gaps. A simple process gets you there.

Follow these steps to build your plan:

  1. List your risks. What would hurt the family most?
  2. Cover the big ones. Insure the largest threats first.
  3. Set a budget. Balance protection with affordability.
  4. Review yearly. Update cover as your life changes.

Start with the risks that would do the most damage, then work down. Keeping your car and home premiums in check leaves more for the cover that truly matters. Reassess each year, because a growing family’s needs never stand still.

Protecting what matters most

For a single parent, insurance is not a luxury; it is the safety net beneath everything you build. Cover your income and your family first, lean on a broker to cut through the complexity, and protect any business you run alongside. Choose deliberately, review regularly, and keep the plan matched to your real life. Handled that way, insurance quietly guards the people and the future you work so hard for.

Frequently asked questions

What insurance is most important for a single parent?

Life cover and income protection usually top the list, because your family depends entirely on you. Life insurance supports your children if the worst happens, while income protection replaces your wage if illness or injury stops you working. Health, home, and car cover matter too. A broker can help you rank these against your budget and needs.

Is income protection really necessary?

For a sole earner, it is one of the most valuable policies available. If an illness or injury stopped you working, income protection would replace a portion of your wage and keep the household running. Savings alone rarely stretch far enough for a long absence. It turns a potential financial disaster into a manageable, temporary setback.

Can a broker save me money on insurance?

Often, yes. A broker compares policies across many insurers, so you are far less likely to overpay or buy the wrong cover. They also spot gaps and unnecessary extras you might miss alone. Beyond any savings, the time and stress they remove from the process is a real benefit for a busy single parent.

How often should I review my insurance?

At least once a year, and after any major life change such as a new job, a move, or a growing family. Your needs shift over time, and cover that fit last year may not fit now. A yearly review keeps your protection right and your premiums competitive, preventing both overpaying and dangerous coverage gaps.