Whether you’re already living on Social Security, watching a parent depend on it, or just trying to figure out what retirement even looks like these days, the 2027 raise is worth paying attention to. It’s shaping up to be the fattest one retirees have gotten in three years.
Right now the guesses sit between 3.4% and 3.6%. On the average retired-worker check, about $2,086 a month, that works out to somewhere around $70 to $75 more landing in the account every month starting in January. Not life-changing money, but real money, especially after two years of raises that barely kept up with a carton of eggs.
Nobody gets to call it official yet. That happens October 14, when the last piece of inflation data needed to nail down the real number finally comes out.
The raise is shaping up to be the biggest in three years
Image Credit: Shutterstock
Three groups run these numbers every month just so retirees don’t have to wait until October for a read: AARP, the Senior Citizens League, and the nonpartisan Committee for a Responsible Federal Budget. Right now they’re bunched close together, 3.6% on the high end, 3.5% in the middle, 3.4% on the low end. That’s a tight cluster, considering how wildly the guesses bounced around earlier this year.
Any of those numbers would beat the 2.8% raise from 2026, the 2.5% raise the year before, and the 3.2% raise in 2024. It would be the biggest bump since the 8.7% jump in 2023, itself the largest COLA in four decades. Since 2001, this raise has averaged about 2.6% a year, with nothing at all in 2010, 2011, and 2016. So 2027 would be a good year on paper, if the numbers hold.
How the percentage turns into real dollars
Percentages don’t mean much until you see the dollar signs attached. AARP’s math starts with the average retired-worker check, about $2,086 a month as of July, and a 3.6% raise on that comes out to roughly $75 more every month, close to $900 over the year. TSCL’s version runs off a different base, the average check for all beneficiaries instead of just retired workers, and lands on a $67.90 monthly bump under its 3.5% projection, pushing that average check from $1,940.08 to $2,007.98.
Your own bump depends entirely on what you’re already collecting, since a raise is a cut of your current check, not a flat number handed to everybody. Somebody pulling in $1,600 a month is looking at $54 to $58 extra. Somebody at $3,000 is looking at $102 to $108. Bigger check now, bigger raise later. That’s just how the percentage works.
Why the estimates keep sliding around
Image Credit: Shutterstock
The formula behind all this isn’t complicated on paper. Social Security takes the average Consumer Price Index for Urban Wage Earners and Clerical Workers, CPI-W for short, across July, August and September, compares it to the same three months last year, and rounds to the nearest tenth of a point. Simple enough, except two of those three months don’t exist yet.
That missing month is why the estimates have been all over the map. Back in June, one independent Social Security analyst had the number as high as 4.7%, a spike driven by oil prices after the U.S. and Iran started shooting at each other. Then a ceasefire cooled off gas prices over the summer, and one tracker’s forecast slid down to 3.5% in August. Then August’s inflation report came in hotter than anyone expected, and that same forecast jumped right back up to 3.6% by mid-September. September’s number, the last one anyone needs, lands the same day the government makes it official.
The Medicare premium question everyone forgets to ask
Here’s the part that never makes the headline: most retirees never actually see their whole raise, because Medicare Part B premiums get pulled straight out of the check before it ever hits your bank account. The latest Medicare trustees’ report has the 2027 Part B premium at $209.50 a month, up $6.60 from this year’s $202.90, a bump of a little over 3%. That’s right around the low end of the COLA guesses.
For once, that actually works out okay. The Part B premium jumped almost 10% between 2025 and 2026, from $185 to $202.90, and ate up a big chunk of that year’s 2.8% raise before retirees ever felt it. If 2027 plays out the way the trustees think, the premium and the COLA move at roughly the same speed, which means more of that raise should actually stick around as spending money instead of vanishing into a bigger Medicare deduction.
Take the premium number with a grain of salt too. CMS usually confirms the real figure later in the fall, a few weeks after Social Security makes its own announcement.
When you’ll actually know, and when the money shows up
Image Credit: Shutterstock
Mark your calendar: October 14, 2026, 8:30 a.m. Eastern. That’s when the Social Security Administration drops September’s inflation numbers and the official 2027 COLA at the same time. That single number finishes the calculation and turns every estimate above into an actual fact.
Personalized COLA notices land by mail in early December, spelling out your new benefit amount and, if you’re on Medicare, exactly what’s coming out for Part B. If you don’t want to wait on the mail, the same numbers usually show up sooner in your My Social Security account online.
When the actual deposit shows up depends on your birthday. Born the 1st through the 10th, your first bigger check comes January 13, 2027. Born the 11th through the 20th, that’s January 20. Born after the 20th, you’re getting paid January 27. If you started collecting before May 1997, or you’re on Supplemental Security Income, you see the new amount earlier, on December 31, 2026, since January 3 lands on a Sunday that year.
What to do with an estimate instead of a fact
A range is still useful, even before the SSA makes it official. Plan around the low end, 3.4%, and you won’t be caught off guard if the real number comes in lighter than the headlines are promising right now. If it lands higher, great, that’s a bonus instead of a hole you have to patch somewhere else.
If you’re on Medicare, do the subtraction before you get excited about the headline percentage. A 3.5% COLA minus a roughly 3% Part B increase doesn’t leave much once the premium comes out. The raise looks bigger on paper than it turns out to be in your account.
If you’re still deciding when to file, remember the COLA applies automatically to whatever you’re already drawing, or whatever you’ll be entitled to once you do file. You don’t apply for it separately. Delaying past full retirement age still stacks delayed retirement credits on top of any COLA. The two don’t cancel each other out.
The real number lands October 14. Until then, plan around 3.4% to 3.6%, and check it against your own December notice the second it shows up.
Fall decorating gets expensive fast when every new texture, lamp, blanket, and serving piece comes from a specialty home store. The cheaper route is not covering the house in pumpkins. It is adding warm wood, heavier fabrics, softer lighting, earthy dishes, and a few seasonal pieces that still look good after Halloween.
Costco has a particularly strong mix right now, including hand-painted ceramics, velvet curtains, substantial furniture, Portuguese flannel, and stoneware that looks more like boutique home-store stock. Several pieces also solve practical fall problems, from darker evenings to colder bedrooms and holiday hosting.
Prices are accurate at the time of publishing but may vary by store or sell out quickly.
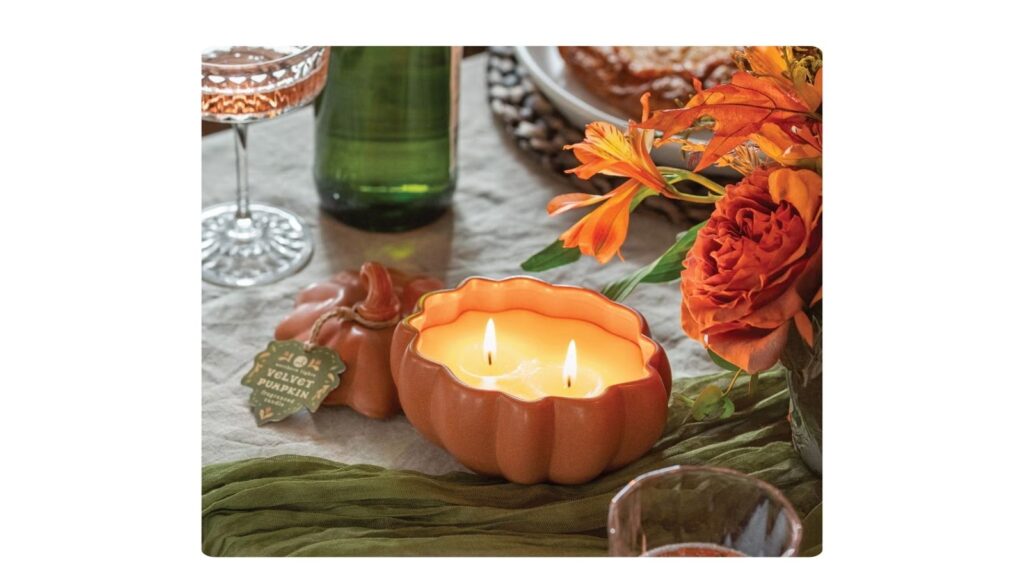
A pumpkin candle can turn cheap-looking quickly, but the ceramic vessel on this Northern Lights version gives it a more finished look. The 9-ounce candle has two lead-free wicks and a scent built around pumpkin, roasted squash, maple butter, cardamom, and pomander. Costco lists a burn time of about 20 hours.
At $23.99, you are also getting a ceramic pumpkin that can stay out after the wax is finished. That makes the price easier to justify than spending the same amount on a candle in a disposable glass jar. It works particularly well on a mantel, kitchen counter, or entry table where one solid fall accent can do the job of several smaller decorations.
Talavera-style ceramic pumpkin
Image Credit: Costco
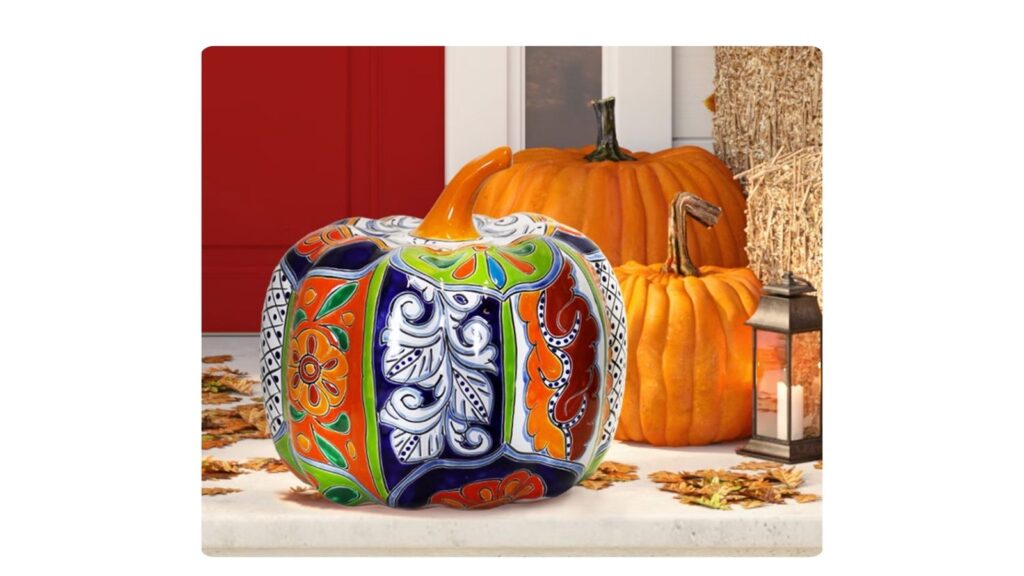
This is the fall decoration for someone who would rather buy one substantial piece than store six bins of seasonal filler. The ceramic pumpkin is individually hand-painted in Mexico, double-glazed, and weighs 15 pounds, so it has the heft and variation you expect from artisan pottery rather than molded seasonal decor. It can also be used indoors or outside.
The $69.99 price is not tiny, but neither is the piece. Hand-painted ceramics of this size can get expensive quickly, and the saturated Talavera-style pattern keeps it from looking like something that only works for three weeks in October. On a covered porch, hearth, or console, it gives you enough color and scale that you can skip buying a pile of smaller decorations.
Harvest hooked accent rug
Image Credit: Costco
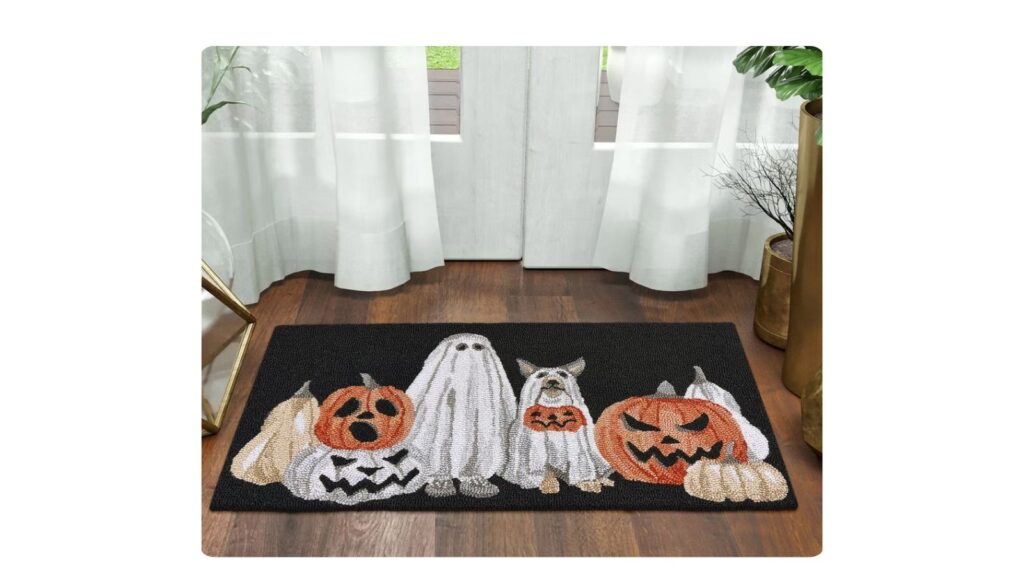
Seasonal rugs are easy to dismiss as decoration, but this one earns its space. The hand-hooked polypropylene surface sits over memory foam cushioning, making it useful in front of the kitchen sink or another spot where you stand for a while. It measures 22 by 38 inches and comes in autumn designs including pumpkins and more Halloween-leaning options.
For $26.99, it is an inexpensive way to make an entry, hallway, or kitchen feel more seasonal without giving up function. The hooked texture also looks noticeably richer than a thin printed mat. Small-space households get an extra advantage here: when fall is over, one compact rug is considerably easier to store than a collection of bulky tabletop decor.
Mikasa electric candle warmer lamp
Image Credit: Costco
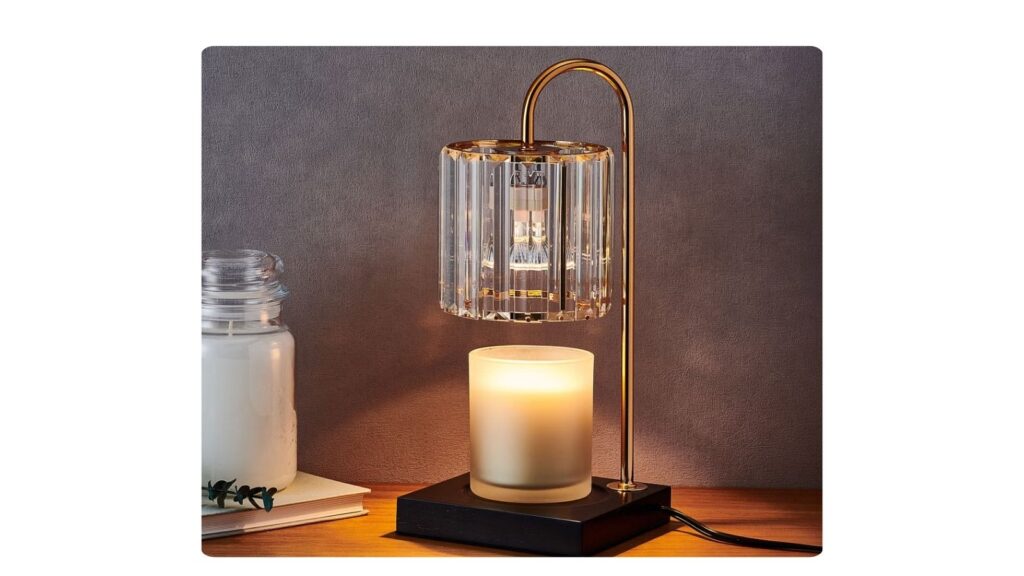
The Mikasa candle warmer is useful even if your fall decorating style contains exactly zero decorative pumpkins. It warms jar candles from above, releasing fragrance without an open flame, smoke, or soot. A cord-mounted dimmer controls both the light and heat, while the wood base, gold details, and small shade make it look more like a decorative lamp than a candle gadget.
It costs $31.99 and fits candles up to 5 inches tall and 4 inches across. That is a sensible buy for homes with pets, kids, or anyone who regularly forgets there is a candle burning in the other room. It can also help prevent wax tunneling, so you have a better shot at using the candle you already paid for.
Marbled chenille decorative pillow covers
Image Credit: Costco
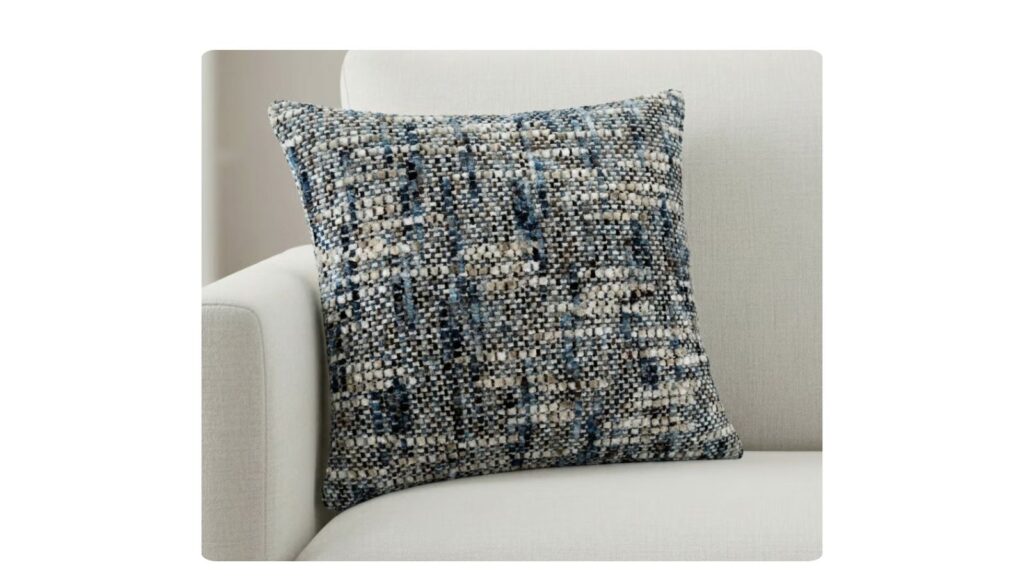
Buying pillow covers instead of whole new pillows is one of the less annoying ways to change a room for fall. These 20-inch covers use variegated chenille with a soft, slightly marbled surface, giving a sofa or bed the depth you normally get from much pricier woven textiles. Brown and green are especially easy fall choices, though blue and ivory are available too. Inserts are not included.
The pair is $32.99. If you already own standard 20-inch inserts, that is a far cheaper refresh than replacing complete decorative pillows every season. The hidden zipper also means the covers can come off when winter decor takes over, leaving you with two flat pieces of fabric to store instead of two more objects fighting for closet space.
Berkshire chenille knit throw
Image Credit: Costco
A good fall throw should look decent folded over the sofa instead of resembling a fleece blanket stolen from the car. Berkshire gives this one a textured chenille knit on the front and a plush reverse, with a generous 60-by-70-inch size. It is machine washable, which matters if the same blanket is going to handle movie nights, kids, pets, and the occasional cup of coffee.
At $18.99 after the current discount, it is one of the cheaper ways to bring heavier texture into a room. Similar chunky-looking throws can cost considerably more once a home-store label gets attached. This one is practical enough to use rather than arrange carefully and tell everyone not to touch, which is generally preferable for something whose main job is keeping you warm.
Evergrace mini-waffle plush comforter set
Image Credit: Costco
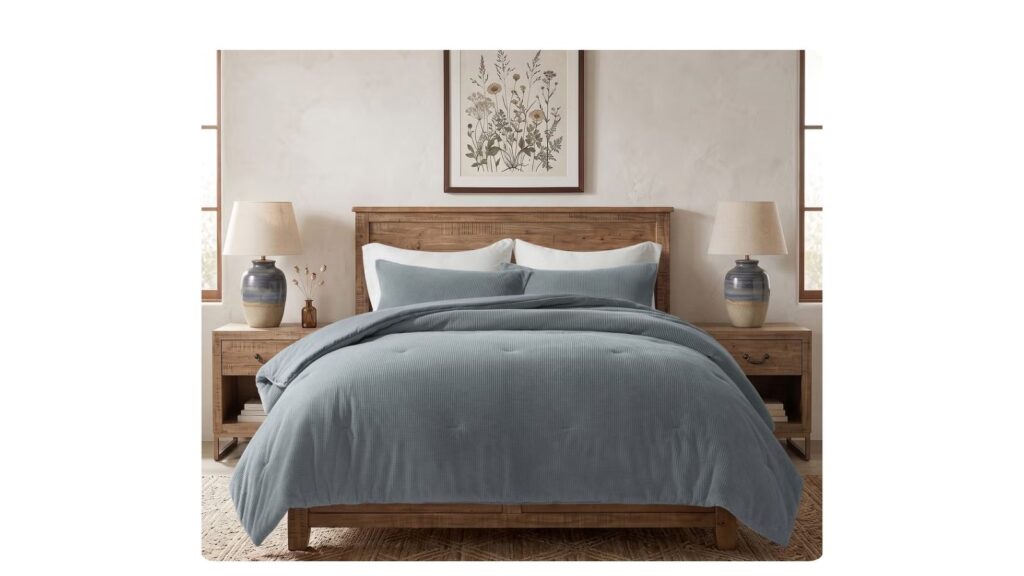
Fall is a good time to reconsider bedding if your current setup requires piling random blankets on top every night. Evergrace’s comforter has a plush mini-waffle texture that gives a bed the layered, hotel-style look people often try to build with several separate pieces. The set includes the comforter and two matching shams, and it is machine washable.
Prices start at $79.99, which is reasonable for a complete three-piece set with this much visual texture. The waffle finish does most of the decorative work, so you do not need another collection of pillows and throws to make the bed look finished. It is particularly useful for anyone wanting a bedroom to feel warmer for fall without committing to obvious seasonal prints that will feel dated by January.
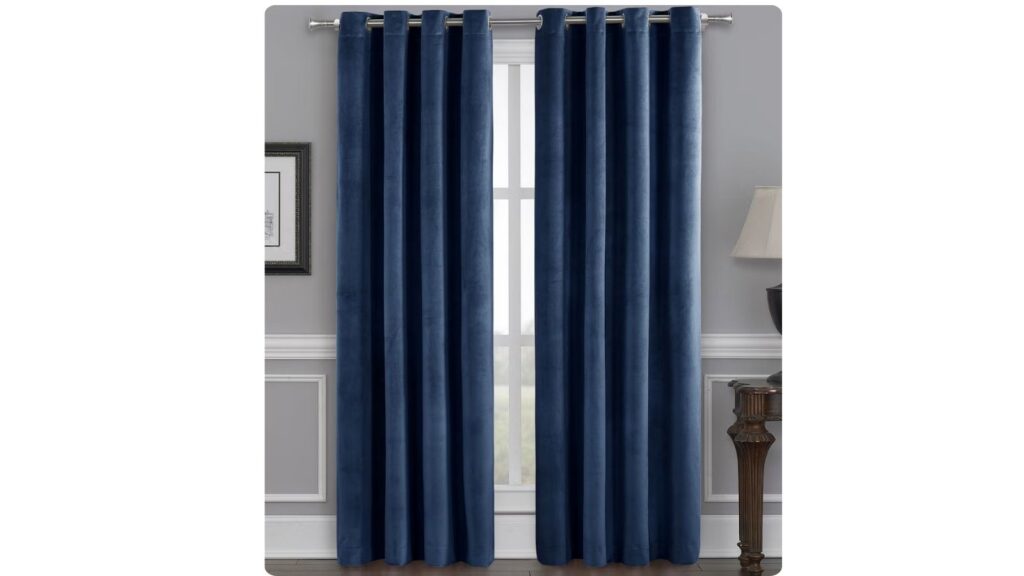
Total blackout velvet curtains
Image Credit: Costco
Velvet does two useful things in fall: it visually warms up a room, and in this case it helps physically insulate one too. These curtains have a soft velvet face with a blackout backing designed to block light, reduce some outside noise, and create a barrier against heat and cold. Each set includes two 52-inch-wide panels, with multiple lengths available.
The two-panel set starts at $42.99. That is a strong price when many retailers sell substantial blackout drapes one panel at a time. They are especially useful in bedrooms, drafty older homes, or living rooms where thin summer curtains start looking a little bleak once the evenings get darker. The slight sheen of the fabric gives them a more tailored appearance than basic thermal curtains.
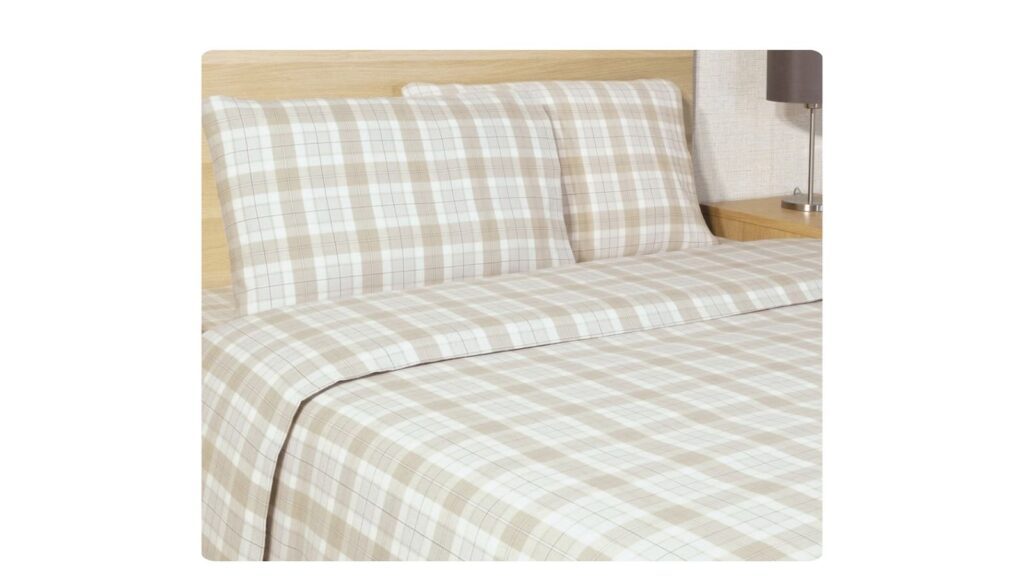
Portuguese cotton flannel sheets
Image Credit: Costco
These are a practical fall purchase disguised as a bedroom upgrade. The sheets are made in Portugal from 100% cotton, brushed on both sides for softness, pre-shrunk, and sold in plaids and other cool-weather patterns. Each set contains a flat sheet, fitted sheet, and two pillowcases.
Prices start at $48.99 for the Full size. For comparison, well-known premium flannel sets can start above $100, so this is not simply a decorative bargain. If you already turn down the thermostat at night, warmer bedding is one of the more useful places to put a fall home budget. The traditional plaids also give the room a seasonal look without requiring separate holiday bedding.
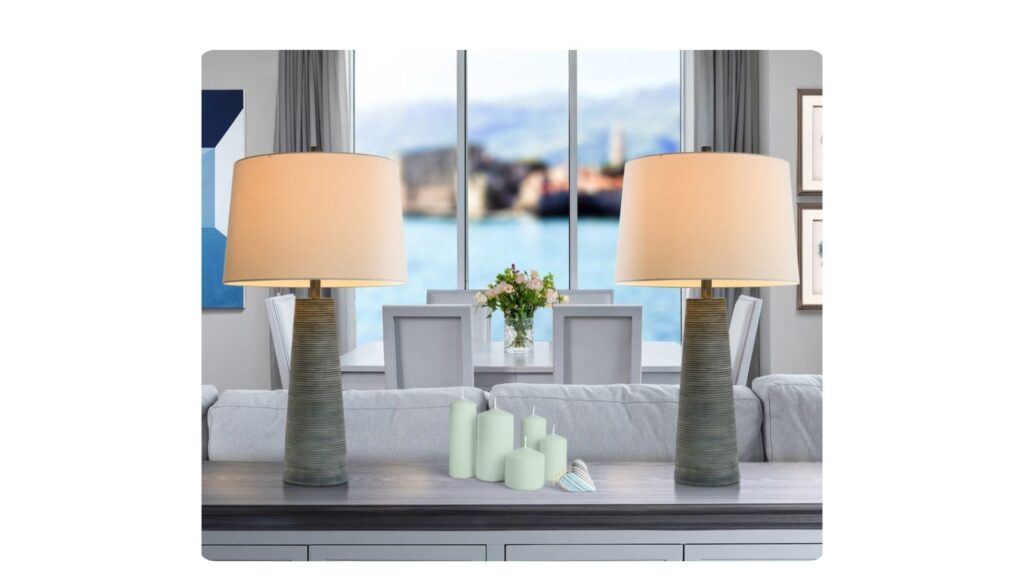
Bentley table lamps
Image Credit: Costco
Lighting makes a bigger difference in fall because suddenly you are using it at 5 p.m. The Bentley lamps have tall ribbed bases, fabric drum shades, and washed denim blue or gray finishes that look more considered than basic bedside lamps. The set includes two matching lamps and two LED bulbs, so there is nothing extra to buy before you can actually use them.
The pair costs $99.99, or roughly $50 per lamp. That is where the value is. Matching substantial lamps from furniture and home stores routinely make a pair surprisingly expensive. Put these on two nightstands or at opposite ends of a living room and the symmetry makes the whole space look more finished, while the softer pools of light are much friendlier on dark fall evenings than one overhead fixture.
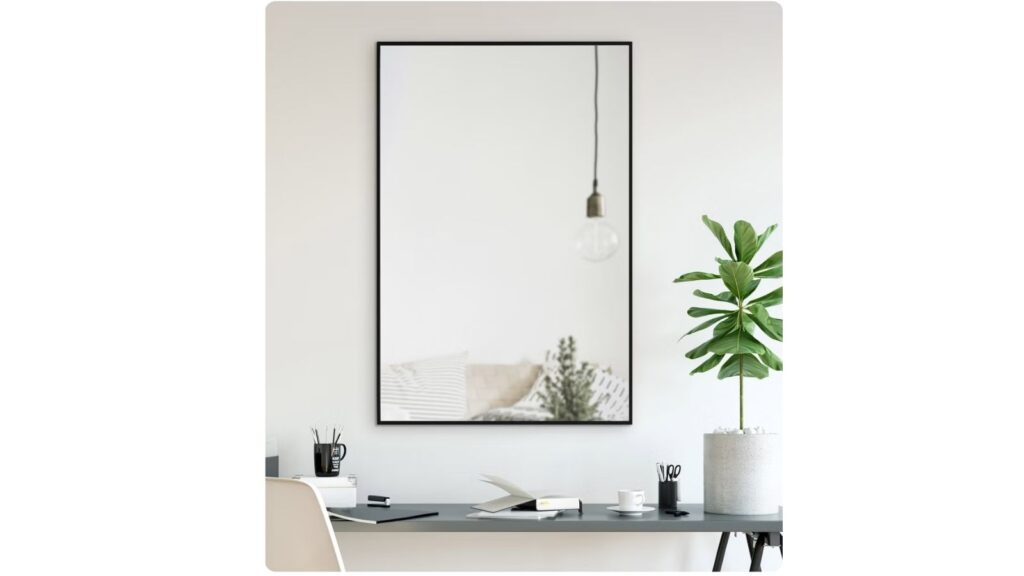
Parker decorative mirror
Image Credit: Costco
The Parker mirror is an easy example of why simple home pieces often give the best expensive-looking effect. It has a slim matte-black iron frame and measures roughly 23.5 by 35.5 inches, with the option to hang it horizontally or vertically. There is no seasonal motif here, just a clean shape that works particularly well with fall’s darker wood, leather, rust, and green tones.
At $99.99, it costs much less than similarly styled black-framed mirrors at several higher-end home retailers. A mirror is also a better use of money than purely seasonal wall art if the room needs more light or visual space. Hang it over an entry console, dresser, or fireplace and it can stay there through every season instead of heading to a storage tote after Thanksgiving.
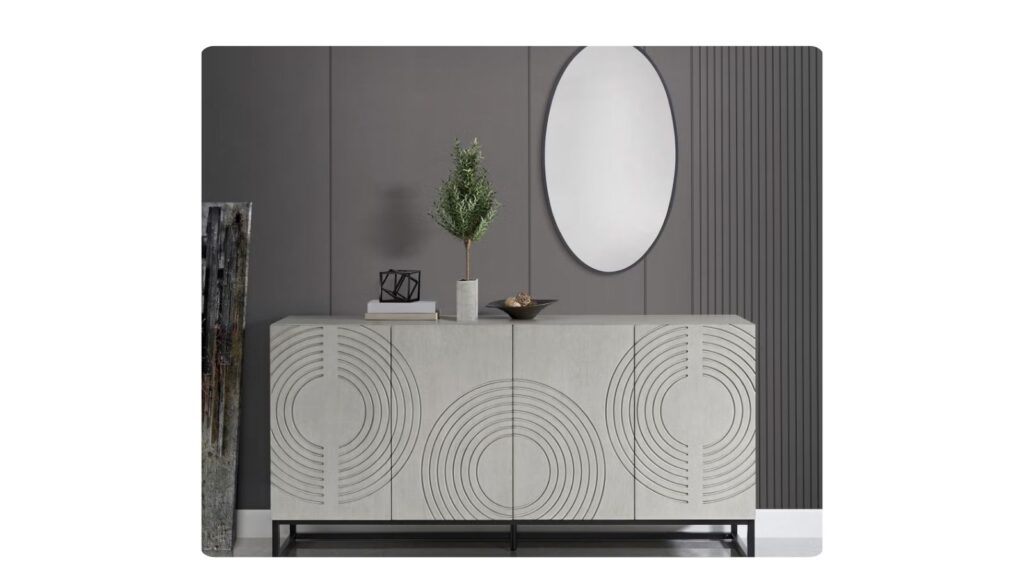
Everly accent cabinet
Image Credit: Costco
Large storage furniture is where a bargain can matter more than saving $4 on a decorative accessory. The 72-inch Everly cabinet uses poplar solids and composite wood with birch veneers, a hand-applied gray finish, a powder-coated metal base, soft-close hinges, and adjustable shelving. The wide, low shape gives it the proportions of a much pricier sideboard.
Costco currently lists it at $299.97. For a six-foot-wide cabinet, that leaves plenty of room between this and the four-figure prices common for large dining-room credenzas. It makes particular sense before fall hosting if you need somewhere to stash serving dishes, table linens, games, or the clutter you would prefer guests not inspect.
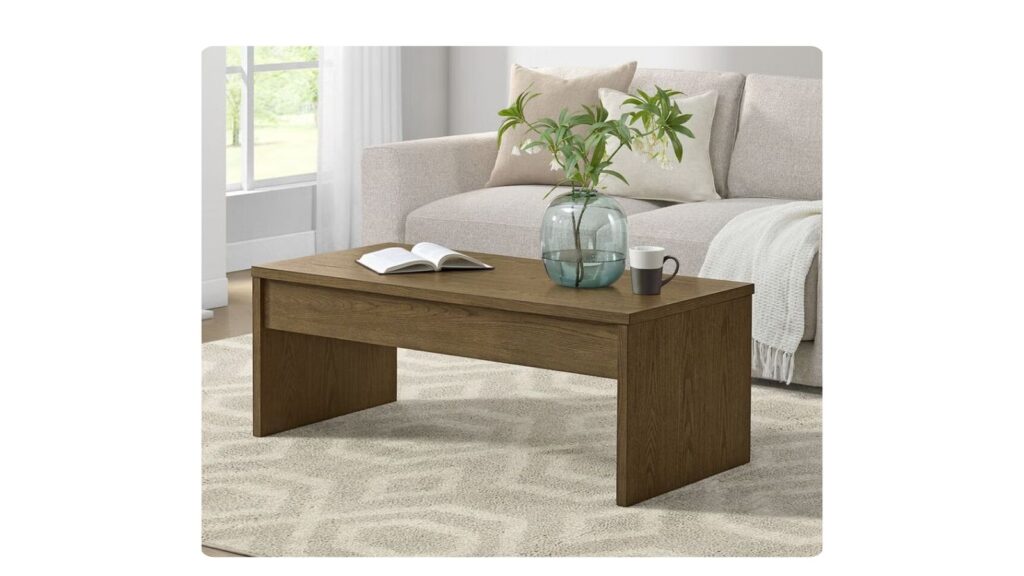
Whitlee lift-top coffee table
Image Credit: Costco
The Whitlee avoids the common lift-top-table problem of looking like office furniture parked in the living room. It uses poplar solids with oak and birch veneers, a warm brown multi-step finish, and a pneumatic slow-close top. Hidden storage sits underneath, so blankets, remotes, chargers, and the rest of the coffee-table mess can disappear when people come over.
At $249.99, it combines two pieces of furniture you might otherwise buy separately: a substantial coffee table and concealed living-room storage. The lifting surface is also useful if fall means more dinners eaten during football, homework on the couch, or laptop time somewhere warmer than a home office. The traditional wood finish is what keeps all that functionality from looking overly utilitarian.
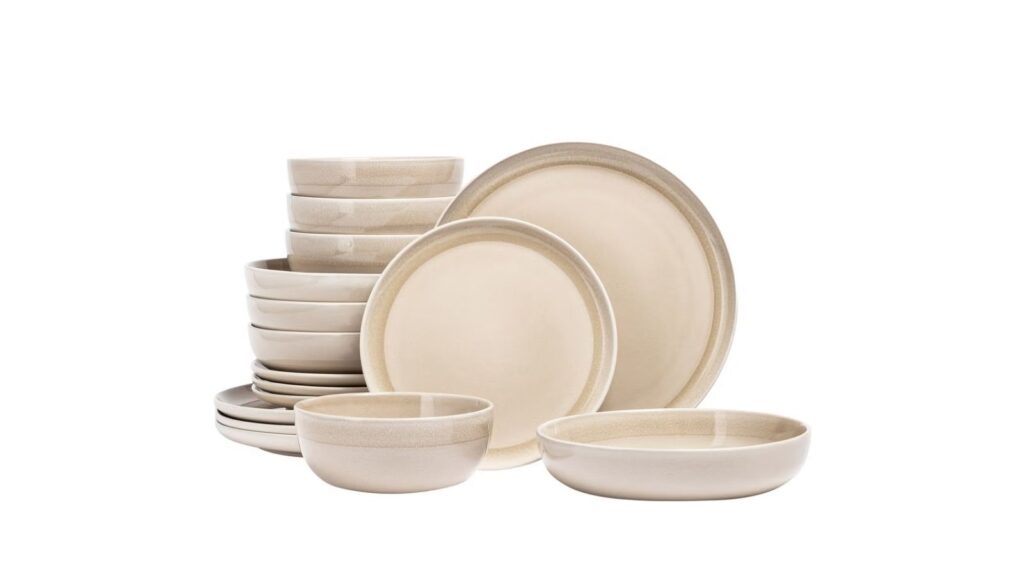
Over & Back Moon dinnerware set
Image Credit: Costco
Reactive glaze is doing the expensive-looking work here. Over & Back’s Moon set is stoneware with natural variations in color and texture, so the dishes have more character than perfectly uniform mass-produced plates. The 16-piece set serves four and includes dinner plates, salad plates, cereal bowls, and wide dinner bowls. Beige and green both work especially well on an autumn table.
The entire set is $44.99, which comes out to less than $3 per piece. That is unusually reasonable for dinnerware with an artisan-style finish, and it is practical enough for daily use because everything is microwave and dishwasher safe. If your existing plates are chipped, mismatched in the accidental rather than charming way, or too formal to use every day, this is a relatively painless reset before the hosting season starts.
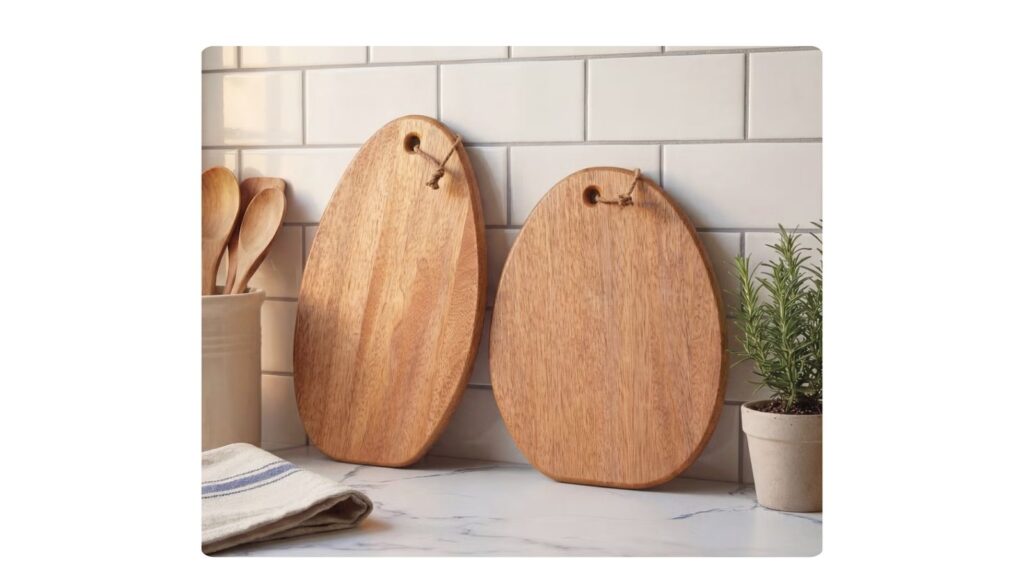
BirdRock Home artisan serving boards
Image Credit: Costco
Warm mango wood is one of those materials that immediately makes a fall table look more pulled together. BirdRock’s set includes two solid mango wood serving boards in different organic shapes, each finished with a jute loop. They can handle cheese, bread, appetizers, or charcuterie, then lean against a backsplash as decor when they are not being used.
The pair is $18.99. That is difficult to beat considering single wood serving boards can easily cost that much or more. This is also a better seasonal buy than novelty Thanksgiving serveware because nothing about the boards limits them to October or November. Hand-wash them and dry them promptly, and they can keep earning their cabinet space through birthdays, holidays, and ordinary snack dinners.
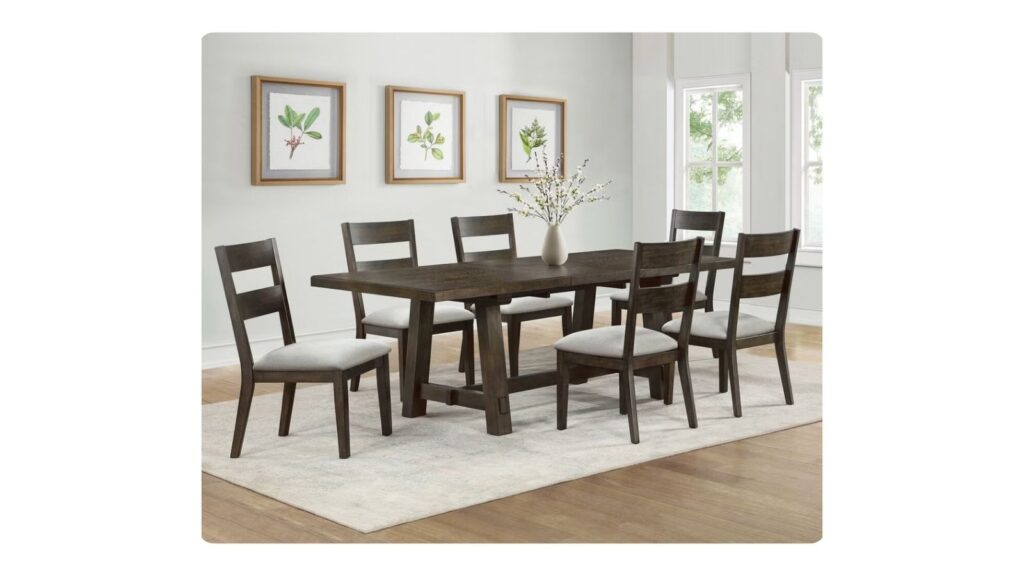
Brinley farmhouse dining set
Image Credit: Costco
This is the big-ticket entry, but the value makes more sense when you count what is included. The Brinley set comes with a dining table, six upholstered chairs, and an 18-inch self-storing leaf that takes the table out to 80 inches. It is made with rubberwood and poplar solids plus ash veneers, finished in a warm farmhouse style that suits the heavier textures and earthier colors people tend to bring out in fall.
The full set is $1,199.99, with delivery, setup, and packaging removal included. That is still serious money, so this only belongs on the list if you already need to replace a dining set. But buying a table and six upholstered chairs separately can push the total much higher. The extendable design also means you are not paying for an oversized table footprint every day just to accommodate holiday dinners a few times a year.
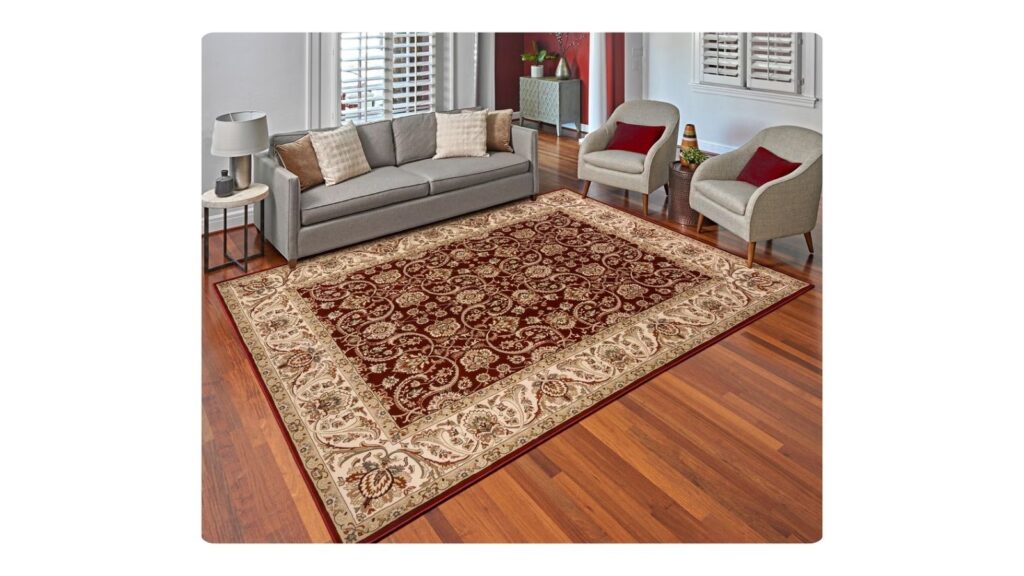
Thomasville Timeless Classic Alden rug
Image Credit: Costco
A traditional rug is an easy way to make a room feel warmer for fall without adding anything that screams seasonal decor. Thomasville’s Alden pattern has the dense, Persian-inspired look that works particularly well with wood furniture, leather, brass, and autumn colors. The polypropylene construction is designed to resist stains and fading, and Costco says it does not shed.
Prices start at $129.99, with larger sizes costing more. That entry price is reasonable for a room-size decorative rug with this much pattern detail, especially if the alternative is trying to warm up a bare room by buying several smaller accessories. A rug also changes the whole visual field at once. If the floors feel cold and the living room looks unfinished, this purchase fixes more than one problem.
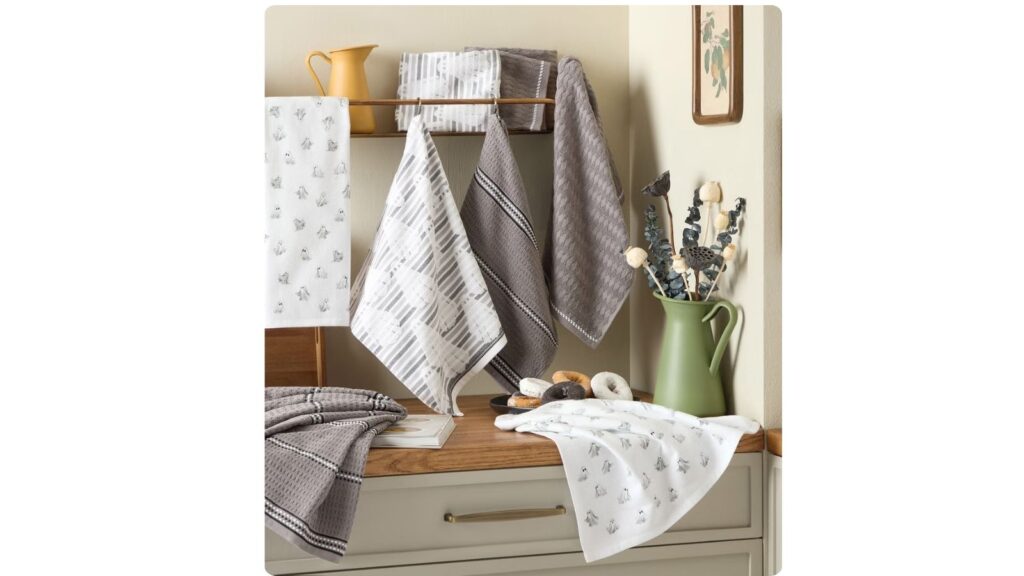
Halloween and harvest kitchen towels
Image Credit: Costco
Seasonal kitchen towels are not exciting, but at least these are built to do an actual job. The eight-piece sets mix prints, yarn-dyed designs, and solids, with themes including pumpkins, ghosts, skeletons, and sunflowers. Each towel measures 18 by 28 inches, and the printed and yarn-dyed versions are 100% cotton. They are machine washable, absorbent, and OEKO-TEX certified.
At $19.99, the set works out to roughly $2.50 a towel. That is a better value than buying decorative towels in pairs from a specialty kitchen store, and you will not feel compelled to keep the pretty one untouched on the oven handle. For anyone who cooks more once soup, baking, and holiday season arrive, having eight fresh towels is considerably more useful than another ceramic sign announcing that it is fall.
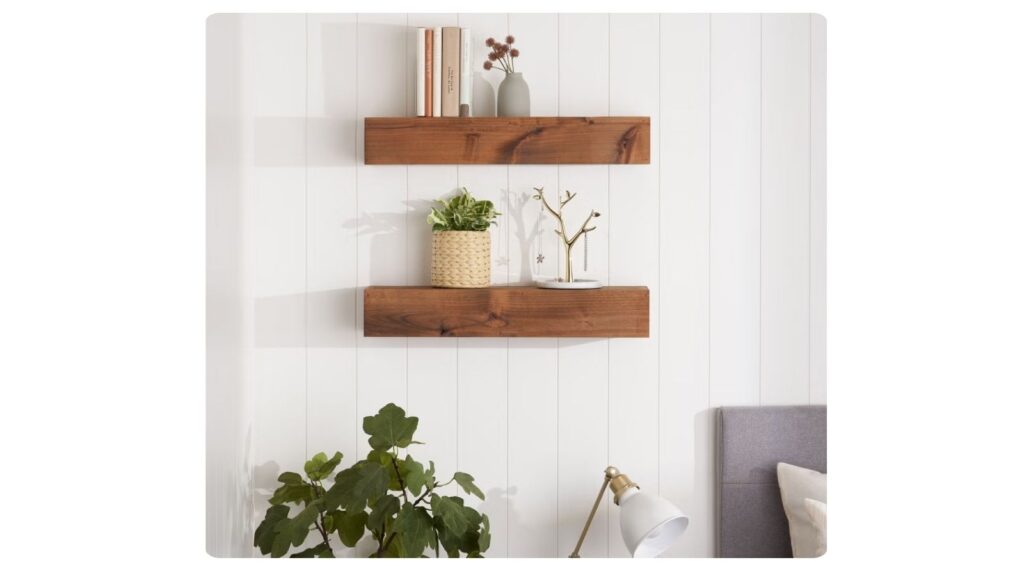
TRINITY farmhouse floating shelves
Image Credit: Costco
Warm wood on the wall can make a plain room feel more layered without taking up any floor space. These TRINITY shelves are handmade in the U.S. from solid knotty alder with a walnut stain. The set includes two 24-inch shelves, concealed mounting braces, and hardware, with each shelf rated to hold up to 15 pounds.
The pair is $57.99. That is particularly good value for solid wood rather than a printed wood-look surface. Use them for framed photos, books, pottery, or a restrained amount of seasonal decor, then swap the pumpkins for something else later. They make the most sense in smaller homes where adding another cabinet or console is not practical but bare walls are going unused.
Tresanti Juliette fireplace console
Image Credit: Costco
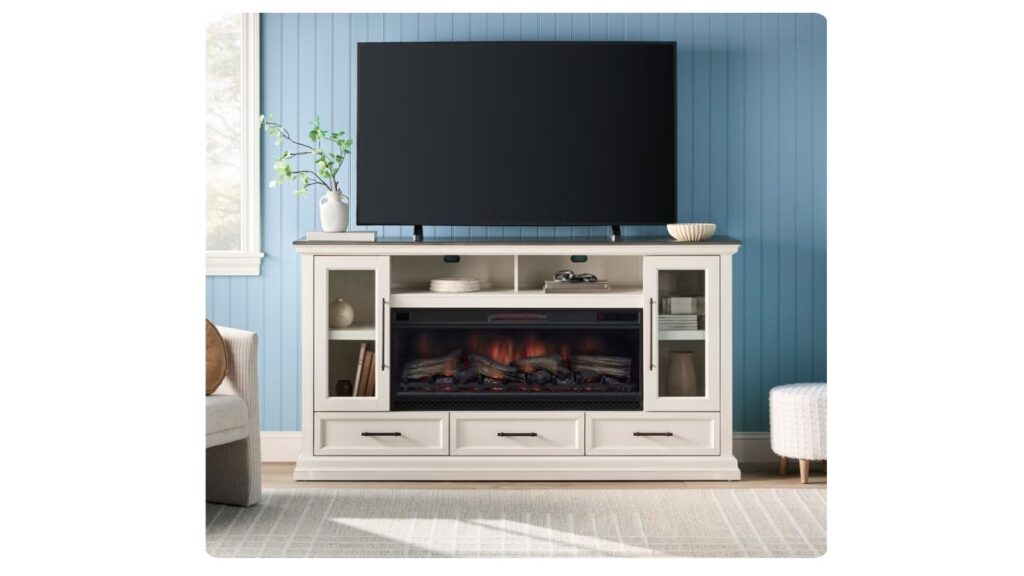
If colder evenings have you considering both a media console and an electric fireplace, combining them is more sensible than finding room and money for two separate pieces. The Tresanti Juliette is nearly 75 inches wide, holds TVs up to 80 inches, and includes an infrared heater rated at 5,200 BTUs. Glass and wood cabinet-door options, drawers, shelving, and a traditional two-tone finish keep it looking like furniture rather than a space heater wearing a disguise.
It is $549.99 where available. That is still a planned purchase, not a casual cart addition, but the combination of storage, TV support, ambient flame effect, and supplemental heat gives the money more than one job. It is particularly useful if you want the look of a fireplace for fall without taking on the cost or construction involved in adding the real thing.
Thomasville Davos swivel chairs
Image Credit: Costco
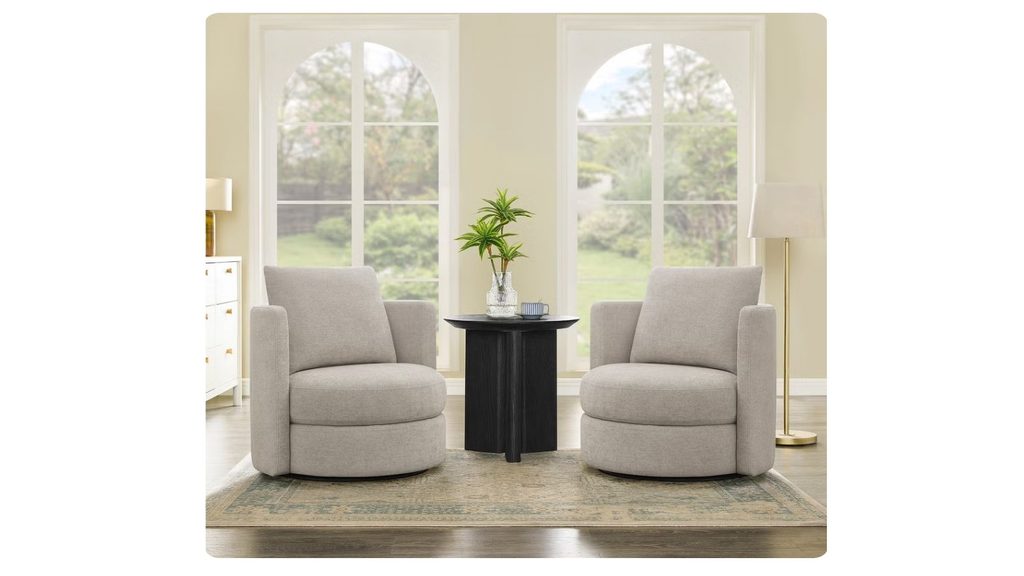
A pair of matching accent chairs can easily become one of the most expensive parts of a living-room refresh, which is why the Davos set stands out. These Thomasville chairs have sculptural barrel backs, 360-degree swivel bases, reversible back cushions, and a compact profile that works for conversation areas or reading corners. The curved shape looks more custom than the usual square armchair.
Costco lists the pair at $299.97, which is about $150 per chair. That is a very different budget from buying two designer-style swivel chairs individually. They also suit fall without being seasonal: add a textured throw or warm-toned pillow now, then change those smaller pieces later. If the living room genuinely needs seating, this is a much stronger use of money than spending several hundred dollars on decor that cannot sit anyone.
You finally book the crown your dentist has been nagging you about for two years, figuring that now you have Medicare, it’s covered. Then the office hands you the bill for the full amount, because Medicare doesn’t pay a cent toward it.
That surprise catches a lot of new retirees off guard, and it isn’t limited to teeth. Original Medicare pays for hospital stays, surgeries, and doctor visits, but it draws a hard line around the everyday care most people over 65 actually need: dental work, glasses, hearing aids, and the custodial help that keeps someone in their own home or a nursing facility.
None of that changes heading into 2027. If anything, the price tags on these services keep climbing, and the fall enrollment window that opens October 15 is the one chance most people get each year to plan around what Medicare leaves out instead of discovering it at the worst possible moment.
Original Medicare treats teeth like they belong to someone else’s body.Cleanings, fillings, tooth extractions, and items like dentures and implants all fall outside Part A and Part B, no matter how badly you need the work. A routinecleaning runs $75 to $200, and a single filling costs $100 to $400. Pulling a tooth can run $150 to $400 for a simple extraction, more if it’s surgical, and a full set of dentures starts around $1,000 and climbs past $3,000 before implants enter the picture.
There is one narrow opening. Medicare will pay for dental work when it’s directly tied to a covered medical treatment, like an oral exam before a heart valve replacement or an organ transplant, or clearing an infection before cancer treatment. Outside those specific circumstances, you’re covering the dentist yourself, and most people over 65 eventually need some kind of dental work.
Routine vision care and eyeglasses
Image Credit: Shutterstock
The same logic applies to your eyes. Medicare doesn’t cover eye exams for eyeglasses or contact lenses, and you pay 100% of the cost yourself. A comprehensive exam runs roughly $50 to $300, with a national median around $150, and that’s before you buy frames and lenses, which run a median of $184 at a warehouse club and closer to $400 at an independent eyewear shop.
Cataract surgery is the exception worth knowing about. It’s one of the most common procedures performed on people over 65, and Medicare covers it along with one pair of eyeglasses with standard frames, or one set of contact lenses, after each cataract surgery that implants an intraocular lens. You still pay 20% of the approved amount after your deductible, but that’s a very different bill than paying for glasses on your own. Medicare Part B also covers an annual diabetic eye exam and glaucoma screening for people at high risk. Everything else, including a new prescription because your eyes have simply changed with age, is on you.
Hearing aids and the exams to fit them
Image Credit: Shutterstock
Medicare doesn’t cover hearing aids or the exams needed to fit them, and you pay all of the cost. That’s a real number to plan around. A recent survey of more than a thousand buyers found the average price paid for a pair of prescription hearing aids was $2,694, with premium technology running as high as $8,500. Over-the-counter models bought without a clinic visit cost far less, but they’re built for milder hearing loss, not the more significant loss that shows up more often with age.
Medicare will pay for a diagnostic hearing or balance exam if your doctor orders one to investigate a medical condition, such as sudden hearing loss or dizziness, and you’ll owe your usual Part B coinsurance for that visit. What Medicare won’t do is pay for the exam that fits you for a device, or for the device itself. If hearing loss runs in your family or you’re already noticing it, that’s a cost worth budgeting for well before you need the aids.
Long-term custodial care
Image Credit: Shutterstock
Long-term custodial care causes more financial damage than any other exclusion on Medicare’s list, and it surprises people because Medicare does pay for some nursing home care, just not the kind most families actually need. Medicare Part A covers up to 100 days in a skilled nursing facility after a qualifying hospital stay: nothing for the first 20 days beyond your Part A deductible, a daily copay of $217 for days 21 through 100, and everything after that is yours. That coverage is for skilled, medically necessary care, not for help with daily living.
Custodial care, help with dressing, bathing, and other everyday tasks, isn’t covered by Medicare at all, whether it happens at home or in a nursing home. And the price of that care keeps rising: the national median cost of a nursing home now runs $9,581 a month for a semi-private room and $10,798 a month for a private one. Most families who end up needing this level of care for any length of time eventually turn to Medicaid, which is now the primary payer for 63% of nursing home residents nationwide, but only after a person’s own savings are largely spent down.
Elective cosmetic procedures
Image Credit: Shutterstock
Medicare doesn’t cover most cosmetic surgery unless it’s needed because of an accidental injury or to improve the function of a malformed body part, and you pay 100% of the cost for anything that doesn’t meet that bar. Breast reconstruction after a mastectomy is a specific, covered exception, treated as reconstructive rather than cosmetic.
Some procedures live in a gray area and require prior authorization before Medicare will consider paying, including eyelid surgery to remove excess tissue, Botox injections for muscle disorders, skin removal surgery on the abdomen, rhinoplasty, and vein ablation. Medicare reviews these case by case to decide whether the procedure is treating a real medical problem or simply changing how you look, and the same operation can land on either side of that line depending on why it’s being done. If your provider recommends something in this category, ask directly whether it needs prior authorization and what happens to the bill if that request gets denied, because the answer changes what you owe by thousands of dollars.
Most alternative therapies
Image Credit: Shutterstock
Medicare’s approach to alternative medicine is narrow and specific rather than broad. The one real exception is acupuncture, and only for one condition:Medicare Part B covers up to 12 acupuncture sessions in 90 days for chronic low back pain, with 8 additional sessions if you’re improving, and only when performed by a qualified provider. The back pain has to meet a specific clinical definition, lasting 12 weeks or longer with no identifiable cause tied to surgery or pregnancy.
Everything else in this category, massage therapy, homeopathy, naturopathy, and most chiropractic care beyond medically necessary spinal manipulation, stays outside Medicare entirely, regardless of how many doctors recommend it or how well it might work for you. That’s a program-wide rule rather than a judgment call your own doctor can override, so appealing a denial for a therapy Medicare has already excluded rarely goes anywhere. If alternative therapies are a regular part of how you manage a chronic condition, that’s a cost to plan for separately rather than an expense you can expect Medicare to absorb.
Care you get outside the U.S.
Image Credit: Shutterstock
Retirement often comes with more travel, and this is where Medicare’s limits catch people by surprise. Medicare usually doesn’t cover health care while you’re traveling outside the U.S., and you pay all costs in most cases. There are three narrow exceptions built around genuine emergencies and geography, such as living so close to the border that a foreign hospital is actually nearer than the closest U.S. facility, but they don’t apply to routine or planned care of any kind.
A Medigap policy can cover part of that cost. Most Medigap plans, lettered C, D, F, G, M, and N, cover 80% of billed charges for certain medically necessary emergency care outside the U.S., subject to a deductible and a lifetime limit of $50,000. Without that kind of policy, or a separate travel medical insurance plan, an emergency hospitalization overseas comes entirely out of your own pocket, and foreign hospitals aren’t required to bill Medicare directly on your behalf, so you may need to pay upfront and file for reimbursement yourself.
How Medicare Advantage bundles some of this back in
Image Credit: Shutterstock
Medicare Advantage plans are where most of these exclusions get patched over, at least on paper. Virtually every plan advertises something in this space: 98% or more of individual Medicare Advantage plans offer some vision, dental, or hearing benefit in 2026, and three quarters of enrollees pay no premium beyond the standard Part B premium. For someone weighing the seven exclusions above, that combination looks appealing on its face: one plan, no extra monthly cost, and a benefit that at least touches every category.
The benefit exists, but the fine print decides how much it actually helps. Annual dental maximums commonly land between $1,000 and $2,000, provider networks can be narrow, and the plan’s overall out-of-pocket limit still matters: the average in-network out-of-pocket limit across Medicare Advantage plans is $5,421. Before you assume a plan solves your dental or hearing needs, pull up its actual benefit summary and check the annual cap and the provider list, not just whether the category is listed on a brochure.
What Medigap actually does here
Image Credit: Shutterstock
Medigap is built to solve a different problem than the one you’re weighing here, and it’s worth being clear-eyed about that before you buy one expecting it to cover dental work or a hearing aid. Medigap policies help cover your copayments, coinsurance, and deductibles for services Original Medicare already covers, which lowers your costs on things like hospital stays and skilled nursing coinsurance.
What it doesn’t do is add coverage Medicare never had in the first place. Medigap plans generally don’t cover long-term care, vision or dental care, hearing aids, glasses, or private-duty nursing. If you’re choosing between a Medigap policy and a Medicare Advantage plan, understand what each one is actually solving: Medigap reduces your share of the medical bills Medicare already pays for, while Medicare Advantage is more likely to include some benefit toward the categories Medicare excludes entirely, with its own trade-offs in network size and annual limits.
Standalone policies, long-term care insurance, and Medicaid
Image Credit: Shutterstock
For the costs neither Original Medicare nor a Medigap policy will touch, a handful of separate options exist, each with its own cost and its own limits. A standalone dental plan for someone over 65 typically runs $20 to $70 a month, and similar standalone policies exist for vision and hearing, usually with their own annual maximums and waiting periods for major work.
Long-term care insurance covers custodial care directly, but the premium climbs steeply the longer you wait to buy it. Annual premiums for a policy bought at 55 run roughly $950 to $1,500, rising to $1,200 to $1,900 by 60 and considerably higher after that, with women generally paying more than men. For people who can’t afford that kind of policy or who need custodial care without having planned for it, Medicaid covers long-term nursing home care once income and assets fall under strict state limits, generally around $2,982 a month in income and $2,000 in countable assets for a single applicant in 2026. Getting there usually means spending down savings first, and Medicaid reviews the prior 60 months of financial records to check for asset transfers.
Deciding what matters most before December 7
Image Credit: Shutterstock
Fall open enrollment isn’t just a chance to shop for a lower premium. It’s the one structured moment each year to look honestly at which of these exclusions actually apply to your situation and choose coverage accordingly. The Annual Enrollment Period runs October 15 through December 7, 2026, and any changes you make take effect January 1, 2027.
If your teeth and eyes are in decent shape but you’re already noticing hearing loss, a plan with a strong hearing benefit and a weak dental one might be the better trade. If long-term custodial care is the bigger worry, given a family history or your own health, that points toward long-term care insurance or an honest look at your Medicaid eligibility timeline rather than anything Medicare Advantage or Medigap will solve. There’s no single plan that covers every exclusion on this list, so the useful question isn’t which plan covers everything. It’s which two or three of these exclusions would actually hurt you the most, and which coverage handles those.
None of these exclusions are new for 2027, and none of them are likely to disappear anytime soon. Knowing exactly where they sit, and what they cost, is what turns a surprise bill into a decision you already made.
People talk about credit as a score to be proud of, when what it really gives you is choices. A good record lets you rent the place you want, borrow at a fair rate, pay a smaller deposit, and leave a bad job or lease without staying up at night doing math.
None of that comes from one smart move; it comes from a few plain habits, kept up long enough that your record starts helping you instead of getting in the way.
Paying on time matters more than anything else in your credit record, and it is also the habit most people break by accident, because a bill comes due in a busy week and quietly slips past. One late payment hurts more than a big balance ever will, and it can stay on your record for years.
Automatic payments handle most of that, so set them up for at least the minimum on every card and loan, then pay more by hand whenever you can. A month when you are not paying attention then costs you a little interest rather than a mark that follows you around for years.
Pay some off before the bill is sent
The next thing that matters is how much of your card limit you have used, and unlike your history, it can change in a single month, which makes it the quickest part to improve. Using most of your limit pulls your score down, even if you pay the bill in full.
Timing is the trick here, because most banks report your balance on the day your statement is made rather than the day the payment is due. The credit bureaus see what you pay off before that date, so keep the balance they see well below the limit and put some of your spending on a second card if you have one.
Read the report, not only the score
The score is only a summary, while the report behind it is what lenders actually read, so it helps to watch both. A credit monitoring service shows you the score and tells you when something changes, and that alert is the useful part. An account you never opened, an address you have never lived at, or a balance that jumps overnight is much easier to deal with in the first week than six months later.
Mistakes turn up often enough to make those twenty minutes worth spending. If you find one, report it to the bureau and to the company that sent the information, keep copies of everything, and expect that company to take about 30 days to look into it and reply. An account that was never yours, or a paid debt still shown as unpaid, is the kind of thing that quietly costs you a better rate.
Let your accounts get old
How long you have had your accounts counts too, and it is the one part nobody can speed up, which is worth knowing before you close the card you have had the longest. Closing it shortens your history and reduces your available limit at the same time.
If that old card is free to keep, leave it open and make one small monthly charge to keep it active. If it charges a yearly fee, ask the bank to move you to a free version of the same account instead of closing it, since that usually keeps the original start date.
Do not apply for too much at once
Every application shows up on your record, and several close together make a lender uneasy, even when each one made sense. New accounts also lower your average account age, right when you want to look steady.
This matters most in the months before something big, so if you are about to apply for a mortgage, a car loan or a rental, leave your credit alone for half a year first. That means no new cards, no store payment plans at the checkout, and nothing closed, because dull is exactly what a lender hopes to see.
Save some cash so credit stays a choice
The strongest credit habit of all isn’t really about credit, since a little money set aside keeps a broken car or a medical bill from turning into a card you cannot pay off. A card that never gets pushed to its limit then keeps your score healthy on its own.
Even a few hundred dollars set aside can change how an ordinary bad week ends, since credit helps you when you choose to use it and costs you when it is the only thing left.
What a good record gets you
It is worth knowing what the payoff actually is, because it is bigger than the rate on one card. A good record can mean a lower rate on a mortgage or car loan, a smaller deposit with the electric company, an easier time renting, and in many states a better price on insurance.
Put it all together, and what it adds up to is independence, because someone with a clean record can take a job in another city, end a lease, replace a car, or handle a surprise without asking anyone for help.
Habits beat quick fixes
Nobody can rebuild a credit record over a weekend, and anyone charging a fee to try is selling you something you can do yourself for free, more slowly and far more safely.
Pay on time, keep the balances low, and read the report a few times a year. Leave your oldest account open, spread out your applications, and keep enough cash that borrowing stays a choice. Keep all of that going for a couple of years and you end up with a record that gives you options, which is the whole point of it.
You made an Indeed account two years ago, uploaded whatever resume you had lying around at the time, and never opened it again. Since then you have applied to dozens of jobs and heard back from almost none of them.
Here is what nobody tells you when you sign up: your Indeed account and your Indeed profile are two different things. Submitting applications does not automatically make you visible to the recruiters searching Indeed’s own database every day, looking for people with your exact title, skills or certifications. A complete, public Indeed profile makes job seekers 3.8 times more likely to turn up in those employer searches and 4.5 times more likely to be contacted directly by someone hiring.
Indeed never spells this out when you first sign up, which is why so many profiles sit half finished while employers search right past them.
Fixing it starts with one setting, tucked near the top of your profile, that most people never touch.
Near the top of your Indeed profile, right after your name, phone number, email and location, sits a toggle called “Employers can find you.” If it is switched off, everything else about your profile can be perfect and it still will not matter, because employers are not applying to find you. They are searching directly, the same way you would search a database, typing in job titles and skill combinations and scrolling through whoever comes up.
The numbers back that up:job seekers with a complete profile set to public are 90 percent more likely to move forward in the hiring process once they apply. That figure matters even if nobody ever discovers you through search, because a complete, visible profile also strengthens every application you submit the normal way.
Your profile and your resume are not interchangeable, either. The profile is the living, editable version of your professional details. Your resume is the document that gets attached or pulled in when you apply. Turning on visibility is the only step that puts your profile to work in the background, whether or not you are actively applying that day.
Fill in every section, not just your last job
Image credit: Glenn Carstens-Peters via Unsplash
Your profile is split into three tabs: Profile, Preferences and Resume. It is common to fill out the first job listed and stop there, but each additional detail changes how Indeed matches you and how a recruiter reading your profile understands your background.
Under Qualifications, add your most recent job title, your education, and any licenses or languages that apply. Skills matter more than most people assume: aim for six to ten skills that actually align with the roles you want, not a generic list copied from an old resume. Under Preferences, set your desired job titles, employment type, working hours, salary range, commute distance, and whether you are open to relocating or want remote, hybrid or on-site work specifically.
This is not busywork. A complete, up-to-date profile makes job seekers 90 percent more likely to move forward in the hiring process after applying, so the difference between a half-filled profile and a finished one is not cosmetic. It decides whether your application lands with context attached or lands blind.
Lead with results, not duties
Image Credit: Shutterstock
Most people write their work experience the way they would describe a job to a friend: what they were responsible for, day to day. Recruiters skimming dozens of profiles do not have time to translate a list of duties into evidence that you were actually good at the job. They need the outcome stated plainly.
Swap task language for outcome language wherever you can. Instead of writing that you handled customer inquiries, write that you resolved a set number of tickets per week while keeping satisfaction scores high. The better move is tophrase it as an outcome, such as “reduced processing time by 22 percent”. The number does the convincing that a job title alone cannot.
This applies to every role on your profile, not just your current one. Go back through older positions and add one measurable result to each, even if you have to estimate. A rough number beats no number, because a blank space next to a job title reads as though nothing happened there worth mentioning.
Mirror the exact wording in the job posting
Image Credit: Shutterstock
Plenty of employers on Indeed use an applicant tracking system to manage applications before a person ever opens one. An ATS scans your resume for keywords, skills and formatting that match the job description, then ranks or filters applications based on how closely they line up. It is reading for overlap, not for personality, so the words you choose matter as much as the experience behind them.
Open the job posting next to your profile and pull out the specific terms it repeats: the software names, the certifications, the exact job title. If those terms actually describe what you have done, use them, in the same form the posting uses. A system built around one exact term is not always smart enough to credit you for a close synonym.
The specific move:repeat your priority keywords two to three times, once in your summary, once in your skills section, and once tied to an actual result in your work experience. Saving your resume as a .docx file rather than a heavily designed PDF also helps, since tables and graphics can scramble how the system reads your information.
Let Career Scout tailor your resume for you
Image Credit: Christin Hume via Unsplash
Indeed built a free AI career coach directly into its mobile app called Career Scout, and it does the tailoring work most people skip because it takes too long by hand. Paste a job link into the chat and it reads the posting, flags the skills you are missing, and suggests specific edits to your summary, your skills section and your work experience bullets.
The results are measurable.Job seekers who use Career Scout are 38 percent more likely to get hired, and they find and apply to jobs seven times faster than people who do not use it. It also runs mock interviews and gives feedback on how you answer, which matters more than it sounds like it should, since most people never practice out loud before the interview that counts. Eighty-four percent of job seekers who use it say the career suggestions are worth acting on, a higher hit rate than most career advice earns.
Career Scout drafts and suggests, not decides. You are still the one who chooses what actually goes on the profile.
Add certifications, projects and work samples as proof
Image Credit: Shutterstock
At the bottom of the Profile tab, there is a dropdown labeled “Add another section.” Most people never open it, which is a mistake, because it is where you can add links to past work, certifications, publications or awards that a plain work history does not capture.
List licenses and certifications with the issuing organization and the date you earned them, include certificate IDs or links when they exist, and remove anything that has expired. For projects, name your role, the specific skills you used, and the actual result, and link to a portfolio or work sample whenever the application allows attachments. If a project is still in progress, label it that way rather than leaving it ambiguous.
Keep this section current the same way you keep the rest of your profile current. Three to five strong, recent examples say more about what you can actually do than a long list of certificates from a decade ago that no longer connects to the work you are applying for now.
Set your preferences so Indeed stops guessing
Image Credit: Shutterstock
The Preferences tab is where you tell Indeed what you will and will not accept, and skipping it means the platform is matching you to roles based on your work history alone, with no sense of what you actually want. Add your desired job titles, employment type, working hours, a realistic salary range, how far you are willing to commute, and whether you are open to relocating.
Also specify whether you want remote, hybrid or on-site work, and turn on “Available immediately” if that is true for you. These details narrow your job recommendations to roles you would actually take, instead of a mix of everything vaguely adjacent to your last title.
Filling this out also speeds up the applying itself. With Apply with Indeed, employers pull information from both your resume and your profile at once, and job seekers can complete an application in as little as 44 seconds. That speed only helps if the information behind it is accurate, so treat your preferences as part of the application, not paperwork you can skip.
Update it like you mean it
Image Credit: Shutterstock
A profile you built once and never opened again slowly stops matching who you actually are. New skills, a finished certification, a promotion, or a change in what you are willing to accept for pay all belong in an update, and none of them happen automatically just because they happened in real life.
The standing advice is to update your profile whenever your experience, skills or preferences change, and to review it weekly if you are actively job searching. That is a higher bar than most people expect, but it matches how often the platform is re-running its matching in the background. Regular updates keep your profile aligned with your current goals and can increase how often employers respond over time.
Set a recurring reminder if that is what it takes. Ten minutes every week is a small trade for staying visible to a system that is quietly rechecking your profile against new job postings whether you remember to log in or not.
An Indeed profile will not get you hired by itself. It just stops a strong candidate from being invisible to the people who are already looking.
September has a way of turning dinner into a scheduling problem. School nights, sports practices, packed lunches, and hungry kids arriving home at different times can make convenience food useful, but feeding a larger household with grocery-store single-serve prices gets expensive fast.
Sam’s Club’s current Instant Savings event runs through September 20, and some of the better food discounts are on family-size packages that cost less than $20. The best values are foods that cover several meals, breakfasts, or lunchboxes instead of disappearing in one sitting. Prices are accurate at the time of publishing but may vary by store or sell out quickly.
A five-pound bag of frozen chicken nuggets for $9.97 works out to $1.99 per pound. That’s a useful freezer price when you have several people to feed and need something that can go from freezer to table without much planning.
The big advantage is flexibility. Serve the nuggets with vegetables and potatoes for dinner, tuck them into wraps, or heat a smaller batch for kids eating before practice. Buying a five-pound bag also avoids paying for several smaller packages that disappear after one meal. They are still convenience food, but at this price the convenience isn’t carrying the usual steep markup.
Tyson grilled sweet teriyaki chicken fillets
Image Credit: Sam’s Club
Teriyaki chicken makes an easy starting point for dinners that would otherwise turn into takeout. This 3.5-pound bag of Tyson grilled sweet teriyaki chicken fillets is $12.98, down from $14.98. That comes to about $3.71 per pound.
Pair it with rice and frozen vegetables, slice it over noodles, or use leftovers in wraps the next day. The seasoning is already handled, which cuts down on both prep time and the temptation to order dinner when the evening gets busy. A family that already keeps rice and vegetables on hand can turn one bag into several inexpensive meals without eating exactly the same plate each time.
Jimmy Dean sausage, egg, and cheese croissant sandwiches
Image Credit: Sam’s Club
Breakfast sandwiches can get pricey when everyone grabs one on the way out the door. This 12-count Jimmy Dean pack costs $11.73, down from $13.98, bringing each sandwich to about 98 cents.
For households with teenagers, early work shifts, or school mornings that rarely go according to plan, that per-serving price is the important part. A dollar breakfast from the freezer is easier on the weekly food budget than repeated coffee-shop or drive-thru stops. Add fruit from home and it becomes a quick breakfast that is still cheaper than buying a prepared sandwich one at a time.
Minh large pork egg rolls
Image Credit: Sam’s Club
A 16-count box of Minh pork egg rolls is $8.38, down from $9.88. That’s roughly 52 cents per egg roll, a much easier number to work with than ordering appetizers for five or six people.
These make the most sense as a side rather than the whole meal. Add them to homemade fried rice, noodles, or a quick stir-fry and a basic dinner feels more substantial without adding another $10 or $15 to the bill. They are also useful when family members eat at different times, since you can cook only what you need instead of preparing the full box.
State Fair classic corn dogs
Image Credit: Sam’s Club
Thirty frozen corn dogs for $11.47 comes to about 38 cents each. The State Fair pack is currently $2 off its regular Sam’s Club price, so it is particularly useful for households that burn through quick lunches and after-school food.
They are not trying to be a fancy dinner, and that’s part of the appeal. A couple of corn dogs with fruit, vegetables, or another simple side can handle a rushed meal for far less than fast food. With 30 in the box, you also have enough to keep some in reserve instead of watching one small package vanish after feeding the whole family once.
CrispUps grilled chicken quesadillas
Image Credit: Sam’s Club
These frozen grilled chicken quesadillas come in a 14-count box for $10.47, down from $12.97. At 75 cents each, they fill the gap between a full meal and an expensive convenience snack.
That is especially handy in a house where someone is always hungry between the official meals. Kids can have one after school, adults can pair a couple with soup or salad for lunch, and you are not opening a large package that has to be finished immediately. The sale knocks $2.50 off the box, which is meaningful on something designed to cover several separate eating occasions.
Totino’s pepperoni pizza rolls
Image Credit: Sam’s Club
The 160-count bag of Totino’s pepperoni pizza rolls is currently $9.47, down from $11.47. That puts each piece at about six cents, which explains why the club-size bag makes more sense for a large household than repeatedly buying smaller boxes.
Pizza rolls are best treated as the emergency food they are. They work for after-school snacks, sleepovers, or those evenings when different family members need to eat at different times. Because the bag holds 160, you can cook a modest batch and leave the rest frozen. The value drops quickly if the whole bag becomes one weekend snack, but portioned out, it can last.
Smucker’s Uncrustables peanut butter and grape jelly sandwiches
Image Credit: Sam’s Club
Making peanut butter and jelly at home is still cheaper, but convenience has a price, and this deal keeps that price fairly controlled. A 24-count box of Uncrustables is $11.87, or about 49 cents per sandwich.
For packed lunches, field-trip days, or afternoons when kids need something they can grab themselves, paying less than 50 cents for the ready-made sandwich can be reasonable. The key is using them where the convenience actually saves you from buying something more expensive. If you have plenty of time to make sandwiches, bread and peanut butter will win on price every time.
Chobani 20G protein Greek yogurt variety pack
Image Credit: Sam’s Club
Individual Greek yogurt cups often look inexpensive until you are buying enough for an entire family. Sam’s Club has this 16-count Chobani variety pack for $16.03, down from $19.78. That is almost exactly $1 per cup.
The 6.7-ounce cups work for breakfast, lunchboxes, or an afternoon snack without requiring anyone to portion yogurt from a larger tub. This is one of the pricier deals on the list, but the $3.75 discount matters if Greek yogurt is already a regular purchase in your house. If it tends to sit untouched in the refrigerator, even a good unit price won’t make the 16-pack a bargain.
Mini Babybel Pro snack cheese
Image Credit: Sam’s Club
This 26-count Babybel pack drops to $7.72, down from $10.72. That puts each wrapped cheese at just under 30 cents, which is a useful price for something that is already portioned for lunches and snacks.
Pre-portioned food usually costs more for the convenience, so getting 26 pieces for under $8 is where this deal stands out. Keep them for packed lunches, pair one with crackers and fruit, or use them when someone wants a snack that is more filling than another bag of chips. Because every piece is individually wrapped, the package also works better for families eating on different schedules.
Kraft original macaroni and cheese
Image Credit: Sam’s Club
An 18-pack of Kraft macaroni and cheese is $10.96, down from $14.96. That works out to about 61 cents per package, and the $4 discount is one of the larger dollar savings among the under-$20 pantry deals.
This is the kind of food that earns its space as a backup. Serve it alongside chicken or vegetables, bulk it up with peas or leftover meat, or use it on a night when cooking from scratch simply is not happening. Eighteen packages also give a large household some breathing room between grocery trips, provided you have the pantry space to store them.
Rao’s Homemade marinara sauce
Image Credit: Sam’s Club
Rao’s is usually positioned as a premium jarred pasta sauce, so getting two 22-ounce jars for $7.76 is a strong pantry buy. The two-pack is currently $2 off, putting each jar at $3.88.
One jar can cover a straightforward spaghetti dinner, while the second can go toward baked pasta, meatball subs, pizza toast, or another meal later in the month. Sauce is also one of the easiest ways to turn inexpensive pasta into dinner for a crowd. If your family already buys Rao’s, the discount is especially useful because it brings a higher-priced brand much closer to everyday pantry territory.
Honey Nut Cheerios
Image Credit: Sam’s Club
A 48-ounce box of Honey Nut Cheerios is $5.64, down from $7.64. At roughly 12 cents per ounce, the large box makes more sense for a cereal-eating family than bringing home a smaller box that barely survives two breakfasts.
Cereal is not complicated, but volume matters when four or five bowls are being poured at once. Pair it with milk and fruit for breakfast, or use it as a dry snack for kids who would otherwise work through pricier individually packaged foods. The $2 discount is enough to make stocking one large box now worthwhile without tying up much of the grocery budget.
Nutri-Grain breakfast bars variety pack
Image Credit: Sam’s Club
Thirty-six individually wrapped Nutri-Grain bars cost $7.98 during the current sale. That is about 22 cents per bar, down from a $9.98 package price.
This is useful less as a full breakfast and more as inexpensive backup food. Put bars in lunchboxes, keep a few in the car for busy mornings, or pair one with yogurt or fruit when there is no time for much else. A 36-count box also reduces the need to buy small multipacks during the month. The deal only makes sense if your family actually eats this type of bar, since pantry clutter at any price is still wasted money.
Hidden Valley original ranch dressing
Image Credit: Sam’s Club
Two 40-ounce bottles of Hidden Valley ranch are $9.98, down from $12.48. That’s 80 ounces total for about 12 cents an ounce, a practical size for households where ranch disappears quickly.
Beyond salads, it can do duty as a dip for vegetables, chicken, and pizza, or as a spread for wraps and sandwiches. Buying two large bottles is not sensible for a household that uses ranch twice a year, but families that go through it regularly can avoid paying the higher unit cost of repeated smaller bottles. The $2.50 instant savings makes the bulk purchase easier to justify.
Member’s Mark taco seasoning
Image Credit: Sam’s Club
Instead of buying taco seasoning one little packet at a time, Sam’s Club has a 23-ounce Member’s Mark jar for $5.98, currently $1 off. That is enough seasoning to handle far more than one taco night.
The bigger value is that it works beyond ground beef. Use it with beans, chicken, sheet-pan vegetables, rice bowls, or taco soup, all inexpensive meals that scale well when several people need dinner. A large seasoning jar also lets you use only what a recipe needs rather than opening another packet each time. For families that make Tex-Mex meals regularly, this is a small purchase that can stretch across months of dinners.
On The Border cafe tortilla chips
Image Credit: Sam’s Club
A 23.5-ounce bag of On The Border cafe-style tortilla chips is $3.98, down from $4.48. At about 17 cents per ounce, it is an inexpensive add-on when chips are part of the meal rather than the entire reason for the shopping trip.
A large bag can stretch taco night, turn leftover chili into nachos, or go with beans, salsa, and shredded cheese for a fast weekend lunch. It is also cheap enough to serve a crowd without opening several smaller bags. This isn’t the biggest discount in dollar terms, but the starting price is low and the package is large enough to be genuinely useful for a family meal.
Mott’s assorted fruit flavored snacks
Image Credit: Sam’s Club
The 90-pack box of Mott’s fruit flavored snacks is $9.98, down from $11.98. Spread across the box, that comes to roughly 11 cents per pouch.
These are a treat, not a substitute for fruit, but the price is useful for families already putting packaged snacks into school lunches. Ninety pouches can cover weeks of lunchboxes without another snack run, and the individual packaging makes portions predictable. This is also one of those bulk buys where knowing your household matters. If the kids do not care for fruit snacks, 90 unwanted pouches are not a deal. If they disappear every week anyway, buying them at about a dime each makes more sense.
Gatorade sports drinks variety pack
Image Credit: Sam’s Club
Families with kids in sports can spend an uncomfortable amount on convenience-store drinks one bottle at a time. This 28-pack of 12-ounce Gatorade bottles is $12.58, down from $15.78, or about 45 cents per bottle.
The deal is only worthwhile if sports drinks are already part of your routine. Water is cheaper, full stop. But for tournament weekends, team practices, or households that regularly buy Gatorade anyway, keeping a case at home can prevent the much more expensive habit of grabbing cold bottles individually at gas stations or concession stands. The current $3.20 discount makes that stock-up noticeably cheaper.
Nescafé Taster’s Choice instant coffee
Image Credit: Sam’s Club
Food spending for a big family includes the adults too. A 14-ounce jar of Nescafé Taster’s Choice House Blend instant coffee is $15.98, down from $21.98. The $6 reduction is one of the deepest dollar discounts in the current under-$20 grocery deals.
This earns its place only if someone in the house already drinks instant coffee. For regular coffee drinkers, a jar that stays in the kitchen can make the morning routine cheaper than turning rushed school drop-offs and commutes into repeated café stops. If instant coffee is not your thing, skip it. A $6 discount is still wasted money when the jar sits untouched.
Hellmann’s real mayonnaise
Image Credit: Sam’s Club
Three 25-ounce bottles of Hellmann’s mayonnaise are currently $11.88, down from $14.88. That works out to $3.96 per bottle and gives you 75 ounces altogether.
For a lunch-heavy household, mayonnaise is more useful than it sounds. It goes into sandwiches, tuna salad, chicken salad, egg salad, pasta salad, and plenty of quick dinners built from leftovers. Buying three bottles at once only pays off if your family uses it steadily, but for larger households that do, the $3 savings and sub-$4 per-bottle cost can trim one more repeat purchase from the grocery list.