scroll top

You tell yourself this is the month you finally get ahead. You open a savings account, maybe even name it something hopeful like “house fund” or “emergency.” Three weeks later you check the balance and it’s forty dollars, because there was never any leftover money to put in it. There rarely is.

You’re not the only one. Forty-seven percent of Americans couldn’t cover a $1,000 emergency expense out of savings this year, and nearly a quarter have no emergency savings at all. Waiting for leftover money to show up, then saving it, rarely works, because there’s rarely any left over.

The fix is getting the money out of your hands before you can spend it, the same way your rent or your phone bill already comes out without you deciding each month to pay it.

Set up the transfer so you never see the money
Hands using a smartphone for online banking with an overlaid bank icon
Image Credit: Shutterstock

The single biggest difference between people who save and people who mean to save is whether the transfer happens automatically or depends on them remembering to do it. Set up a recurring transfer from checking to savings for the same day your paycheck lands, before the money has a chance to get absorbed into groceries, gas, and whatever shows up in your inbox that week. Most banks let you schedule this in under five minutes from their app.

Even better, many employers let you split your direct deposit itself, so a portion of every paycheck routes straight into a separate savings account and never touches your checking balance at all. You never see it, so you never have to decide not to spend it.

Start smaller than seems worth it. Twenty five or fifty dollars a paycheck won’t change your life overnight, but it also won’t get canceled the first time money is tight, which is what happens to the hundred dollar transfer you set up in a burst of optimism. You can always raise the amount once the habit is boring and automatic. That’s the goal: boring and automatic.

Move your savings into an account that actually pays you
High-yield savings account reminder on a notepad beside a calculator, clock, and piggy bank
Image Credit: Shutterstock

A lot of savings accounts barely pay anything. The national average sits at just 0.38 percent, which is close enough to zero that inflation quietly eats your balance faster than interest can grow it. If your money has been sitting in whatever account your bank defaulted you into years ago, it’s probably doing exactly that.

Online high-yield savings accounts pay far more for doing nothing different with your money. The average high-yield account currently pays 1.59 percent, and some of the strongest offers run upwards of 4 percent. On a $5,000 emergency fund, that’s the difference between earning about nineteen dollars a year and earning somewhere closer to two hundred. Same money, same risk, same FDIC protection up to $250,000. The only thing that changes is which bank is holding it.

Switching takes maybe fifteen minutes online: open the new account, link it to your checking, move the balance over, and set your automatic transfer from the first item to land there instead. Watching the balance actually move is its own kind of motivation that a 0.38 percent account never gives you.

Give each savings goal its own named account
Woman putting a dollar bill into a savings jar beside cash and a calculator
Image Credit: Shutterstock

One savings account trying to hold your emergency fund, your vacation money, and your car repair cushion all at once makes it hard to know what you’re actually allowed to spend. Dip into it for a flat tire and you’ve quietly borrowed from your emergency fund without meaning to.

Most online banks now let you split one savings account into several named buckets or vaults, each with its own balance and its own goal, without opening a separate account for each one. Ally calls them buckets. Capital One and SoFi have their own versions. You set a name, maybe a target amount, and your money gets sorted the way a budget categorizes a line item, except you can actually watch each one grow on its own.

The psychological trick here is real. Money labeled “vet bill” is harder to justify spending on a weekend trip than money just sitting in an account labeled “savings.” Giving it a name turns an abstract pile of cash into a commitment you’ve already made to a version of yourself that needed a new transmission.

Let a round-up app handle the spare change for you
A spread of U.S. pennies, nickels, dimes, and quarters
Image Credit: Shutterstock

If rounding up every coffee and grocery run to the next dollar sounds too small to matter, it adds up faster than you’d think when it happens on autopilot. Apps like Acorns link to your card, round every purchase up to the nearest dollar, and sweep that difference into savings or investments without asking you each time.

Acorns says its typical user saves more than $150 in their first four months through round-ups alone, which works out to roughly $37 a month from spare change most people never would have set aside on purpose. That’s not going to fund your retirement by itself, but it’s real money that existed nowhere in your budget a week earlier.

The trade-off worth knowing about is fees. Acorns and similar apps typically charge a flat monthly fee rather than a percentage, which is expensive on a small balance and gets more reasonable as your balance grows. If you’re disciplined enough to move spare change into your own high-yield account manually, you’ll keep more of it. If you know you won’t actually do that, paying a few dollars a month for the automation might be worth it.

Give every dollar a job before you spend any of it
Woman reviewing her household budget with a calculator, notebook, and laptop
Image Credit: Shutterstock

A regular budget tracks what you spent after the fact. A zero-based budget flips that: before the month starts, you assign every dollar of expected income to a category, including savings, until there’s nothing left unassigned. Rent gets a line. Groceries get a line. Savings gets a line too, treated with the same seriousness as your electric bill instead of whatever happens to survive until the end of the month.

This matters because savings treated as “whatever’s left” almost always loses to a dozen small, reasonable-sounding purchases that each seem harmless on their own. A zero-based budget forces the decision earlier, when you’re looking at the whole picture instead of justifying one Target run at a time.

You don’t need special software for this. A notes app, a spreadsheet, or a free budgeting app you already have on your phone works fine. The format matters less than the habit of deciding where every dollar goes before your card decides for you.

Pick a savings challenge with a built-in finish line
Woman and girl smiling while adding a coin to a piggy bank at a kitchen counter
Image Credit: Shutterstock

Open-ended savings goals are easy to abandon because there’s no moment where you’re done. A savings challenge fixes that by giving you a specific end date and a specific number to hit, which makes the whole thing feel more like a project than a lifestyle change you’re supposed to maintain forever.

The classic version is the 52-week challenge: save one dollar the first week, two dollars the second, climbing by a dollar each week until you’re saving fifty-two dollars in the final week of the year. Stick with it and you’ll have banked $1,378, without ever having to find much more than fifty dollars in any single week.

Plenty of variations exist if the escalating version doesn’t fit your paychecks. Some people run it in reverse, saving the big numbers early when motivation is highest. Others pick a round number, like $2,000, and divide it evenly across however many pay periods are left in the year. The specific structure matters less than having one. A finish line gives you something to actually finish.

Cancel one subscription and redirect that exact amount

Hand holding a smartphone that displays a subscription renewal notification
Image Credit: Shutterstock

The average person now spends about $111 a month on subscriptions, and a chunk of that, roughly $252 a year, goes toward services nobody’s actually using anymore. Most people don’t realize this number is that high until they sit down and add up every streaming service, app, and subscription box they forgot they signed up for.

Go through your bank or credit card statement and find one subscription you don’t use enough to justify. Cancel it, and on the same day, set up a recurring transfer into savings for that exact amount, on the same schedule it used to come out. If you were paying $15.99 a month for a streaming service you haven’t opened in three months, that $15.99 now goes to your savings account instead, automatically, every month.

This works better than just canceling and hoping the extra money finds its way into savings on its own, because it almost never does. Money that isn’t assigned somewhere specific tends to get absorbed into whatever you were already spending on, quietly and without you noticing. Giving the freed-up amount a new, specific job keeps it from disappearing the same way the old subscription did.

Put your raise or refund away before you get used to it

bonus
Image Credit: Markus Winkler via Unsplash

Lifestyle creep is the quiet process where every raise, bonus, or windfall gets absorbed into slightly nicer versions of things you were already buying, until your spending has crept up to match your new income and you’re no further ahead than before. It happens gradually enough that most people don’t notice it happening.

Tax refunds are a good example of money that tends to vanish this way. The average refund so far in the 2026 filing season has climbed to around $3,561, which is real money that shows up once a year and is easy to treat as found cash rather than part of your actual income. The same goes for work bonuses and the extra few dollars from a cost-of-living raise.

A simple rule handles this without requiring ongoing discipline: any money that wasn’t part of your regular paycheck a year ago goes straight to savings the day it arrives, before it has a chance to become a new phone, a nicer dinner out, or a dozen smaller purchases that each felt justified. You can decide later whether to spend some of it. Deciding by default, the moment it lands, is what actually protects it.

Get every dollar of your 401(k) match before saving anywhere else
Person reviewing retirement savings paperwork with a pink piggy bank and calculator on the table
Image Credit: Shutterstock

If your employer offers any kind of 401(k) match, that match is the single best return available to you anywhere, better than any high-yield savings account or CD on this list. The average promised employer match is worth 4.6 percent of your pay, and most plans require you to contribute somewhere between 4 and 6 percent of your own salary to unlock the full amount.

Capturing that match on a median income works out to roughly $2,569 a year in money your employer adds on top of what you put in yourself, and compounded over a 35-year career, that stream alone grows to around $355,000. Skip it, and that money simply never exists for you.

About fifteen percent of eligible workers contribute nothing to their plan at all, and many more are auto-enrolled at a default rate low enough to miss part of the match without realizing it. Check what your plan’s exact match formula is, confirm the deferral percentage required to get all of it, and set your contribution to at least that number before you put another dollar toward a savings account. Everything else on this list is worth doing. This one is worth doing first, if it’s available to you.

Give yourself a day before any non-essential purchase
24 hours
Image Credit: Shutterstock

Impulse purchases rarely survive a full day of thinking about them. The twenty-four hour rule is simple: when something catches your eye that isn’t groceries, gas, or a bill, you don’t say no to it and you don’t buy it either. You wait until tomorrow.

Most of the time, the pull fades on its own. You forget about it, or you look at it again the next day and wonder what the appeal was. When that happens, don’t just quietly let the moment pass. Transfer the amount you would have spent into savings instead, so the decision not to buy something actually shows up somewhere rather than just evaporating.

This does two things at once. It cuts down on purchases you’d probably regret anyway, and it turns self-control into a savings deposit instead of an invisible non-event you get no credit for. A rule you can actually follow under pressure, standing in a store aisle talking yourself into something, beats a strict budget you abandon the first time you’re tired or stressed.

Send your cash back to savings instead of your wallet
Woman holding a bank card beside a shopping cart in a grocery store
Image Credit: Shutterstock

Cash back from a credit or debit card is easy to think of as free money you’re entitled to spend, which is exactly why it rarely ends up anywhere useful. A few dollars here, a statement credit there, and it quietly funds small purchases you’d have thought twice about paying for directly.

Most cards let you redeem cash back straight into a linked bank account instead of as a statement credit. If yours does, point it at your savings account instead of checking, and set a reminder to redeem your balance on the same day each month rather than letting it sit and tempt you.

If your card only offers statement credits, you can still get the same effect manually: whenever a cash back credit posts, move that same amount from checking to savings yourself. It takes thirty seconds and it means a reward for spending money quietly becomes a reward for not spending it, which is a better trade than it sounds like at first.

Put your savings number somewhere you’ll actually see it
Actuarial analyst reviewing printed financial charts beside a computer
Image Credit: Shutterstock

A balance buried three taps deep in a banking app is easy to forget about entirely. Money you can’t see doesn’t feel real the way cash in an envelope does, which makes it harder to stay motivated about something that’s working perfectly well in the background.

Pull your savings total somewhere you’ll actually run into it. Some banking apps let you add a balance widget to your phone’s home screen. A printed thermometer chart on the fridge works just as well and costs nothing. Even a recurring note in your calendar with the current total, updated once a week, beats a number that only exists inside an app you rarely open.

Seeing the number climb, even slowly, does something a hidden balance can’t. It turns an abstract goal into visible proof that the automatic transfers from earlier on this list are actually doing something, which makes it easier to leave the account alone the next time you’re tempted to dip into it.

Run a short no-spend stretch to reset your habits
Woman checking a grocery receipt and calculator beside essential food purchases
Image Credit: Shutterstock

A no-spend year sounds impressive and almost nobody finishes one. A no-spend week, or two weeks at the outside, is small enough to actually complete, and completing it matters more than the dollar amount you save during it.

Pick a defined window, two weeks is usually enough, and commit to paying only for true essentials: rent, utilities, groceries, gas, and bills already on autopay. Everything else waits. No takeout, no random online orders, no “just this once” purchases that always seem to show up during these stretches.

At the end of it, total up what you didn’t spend compared to a normal two-week period, and move that difference into savings in one lump transfer. The point isn’t really the money this one time, though it helps. It’s proving to yourself that you can go two weeks without your usual spending and nothing falls apart, which makes the next no-spend stretch, or the next automatic transfer you set up, a lot less intimidating.

Lock part of your savings somewhere you can’t easily touch it
Man holding a glass jar labeled Savings with dollar bills inside
Image Credit: Shutterstock

Money that’s too easy to access is money you’ll eventually dip into for something that isn’t actually an emergency. CDs and Series I savings bonds solve that by trading some flexibility for a better rate and a built-in reason not to touch the balance.

A one-year CD currently pays an average of 2.53 percent, fixed for the full term, and cashing it out early costs you a penalty, which is exactly the friction that keeps the money in place. Series I savings bonds work differently: they’re currently paying a composite rate of 4.26 percent for bonds issued through the end of October 2026, combining a fixed rate with an inflation adjustment that resets every six months, and the interest is exempt from state and local income tax.

Neither one belongs in your emergency fund, since both require you to wait at least twelve months before cashing out at all. They’re a good home for money you’re saving toward something specific a year or more out, like a car down payment or next year’s property tax bill, where the inconvenience of pulling the money early works in your favor instead of against it.

Tell one person your number and let them ask about it
Couple smiling together while holding a pink piggy bank at home
Image Credit: Shutterstock

Keeping a savings goal entirely private makes it easy to quietly let it slide when nobody’s watching. Telling one person, a partner, a sibling, a close friend, your actual target number and a rough timeline changes that, not because they’re checking your bank statement, but because saying a number out loud to someone makes backing off it a conversation you’d have to have rather than a decision you can make silently.

Pick someone who won’t lecture you if you fall behind, and agree on how often they’ll check in. Once a month over coffee or a text thread works better than a daily interrogation, which just makes the whole thing exhausting for both of you.

This isn’t about guilt or shame if the number slips. It’s about adding a small amount of outside accountability to a goal that, left entirely to your own willpower, competes against every other thing you’d rather spend money on today.

Pair your money check-in with something you actually enjoy
Woman checks bills and writes in a budget notebook beside a cup of coffee and calculator
Image Credit: Shutterstock

Budgeting and checking your savings balance are chores for almost everyone, which is exactly why they get skipped. Temptation bundling fixes this by deliberately pairing a task you avoid with something you only let yourself do at the same time.

Make your weekly money check-in happen only while you’re drinking the good coffee you normally save for weekends, or only during the one show you look forward to all week. The task itself doesn’t get more fun, but you stop associating it with dread, because it’s now tied to something you were going to enjoy anyway.

Ten or fifteen minutes is plenty: check your savings balance, confirm your automatic transfers went through, move any cash back or leftover cash, and close the app. Making it short and pleasant, rather than long and serious, is what actually gets it to stick past the first few weeks, when most new money habits quietly fall apart.

Pick one number and one date instead of a vague goal
Project planning concept with hands using a tablet beneath overlaid calendars and schedule charts
Image Credit: Shutterstock

“Save more” isn’t a goal, it’s a mood. It has no finish line, no way to know if you’re on track, and nothing to automate your first transfer around. “Save $3,000 for a used car by next June” is a completely different kind of goal, because it tells you exactly how much to move and how often.

Once you have a real number and a real date, figuring out the monthly amount is simple division: $3,000 by next June, roughly nine months out, works out to a little over $330 a month. That’s the number you plug into the automatic transfer from the first item on this list, not a round figure you picked because it sounded nice.

Vague goals fail quietly, because there’s no moment where you can tell you’ve fallen behind until it’s too late to catch up. Specific goals fail loudly and early, which gives you a chance to actually adjust before the deadline arrives instead of after.

Build in a small, planned reward for hitting a milestone
Two friends enjoying cups of coffee together at a café table
Image Credit: Shutterstock

Saving with zero payoff until some distant goal, months or years away, is a hard habit to sustain. Build in small, planned rewards along the way instead of treating every dollar saved as a dollar you’re not allowed to enjoy until the end.

Pick milestones that make sense for your goal: every $500 saved toward a $5,000 goal, for example, or the end of each successful no-spend stretch from earlier on this list. When you hit one, spend a small, pre-decided amount, somewhere around one to two percent of what you’ve saved, on something you’ll actually enjoy. A nice dinner out, or a small purchase you’ve been putting off, works better than letting the reward stay vague.

The reward has to be planned and capped ahead of time, or it turns into an excuse to spend back whatever you just saved. Done right, it’s the difference between a savings habit built on deprivation and one built on progress you actually get to notice.
High pay does not always come with a dramatic working day. Some careers are built around checking equipment, reviewing production records, maintaining standards, and making sure ordinary processes keep working. The responsibility can be substantial even when the tasks are repetitive. These are established professional roles, generally requiring qualifications and several years of experience. Some salaries below describe higher-paid positions within the occupation, which makes the level of the job an important part of your search.

1. Medical dosimetrist

Medical professional reviewing a clipboard beside a diagnostic imaging scanner
Image Credit: Shutterstock

Medical dosimetrists calculate and help plan the radiation used to treat cancer. Median annual pay is $147,470. Much of the working day is spent reviewing patient information, developing treatment plans, and checking calculations with the clinical team. The routine is technical and closely controlled, with repeated checks before a plan is used. Hospitals and cancer treatment services need these specialists to help deliver the prescribed treatment while limiting radiation exposure to nearby healthy tissue.

You usually need a relevant bachelor’s degree and specialist education in medical dosimetry. Employers commonly expect professional certification. This is detailed planning work with serious consequences, so being comfortable with routine does not remove the need for concentration. You work with radiation oncologists, therapists, and medical physicists rather than making treatment decisions alone. The occupation has positive projected growth. It can suit someone who enjoys precise technical work and can explain why a plan needs further checking, even when the team is under pressure to move a patient’s treatment forward.

2. Pharmacist

Two pharmacy professionals checking medication containers and paperwork at a pharmacy counter
Image Credit: Shutterstock

Pharmacists review prescriptions, check for medication problems, and explain how to take medicines safely. Median annual pay is $140,910. The familiar routine includes reviewing orders, resolving questions, supervising dispensing, and speaking with patients or other clinicians. Work is available in pharmacies, hospitals, and other healthcare services. An established dispensing or medication review role can involve the same processes throughout the day, with careful attention required every time.

You need a Doctor of Pharmacy degree and a professional license. Some specialties require further residency training. Employment is projected to grow, although the outlook differs between practice settings. A community pharmacy can be busy and heavily interrupted, while other roles have a more controlled workflow. Before choosing an employer, ask about staffing, prescription volume, breaks, and expectations outside dispensing. The work is repetitive, but the consequences of a missed interaction or incorrect dose are significant. It suits someone who can maintain accuracy while handling questions and is willing to stop an order when the information is incomplete.

3. Specialist validation engineer

Validation review concept showing a professional presenting a tablet with verification and quality notes
Image Credit: Shutterstock

Specialist validation engineers oversee testing that proves manufacturing equipment and processes work consistently. Average annual pay at the level IV benchmark is $138,515. You might plan a qualification program, review test records, or investigate why a process failed its acceptance requirements. Pharmaceutical and medical device manufacturers need this evidence when introducing equipment or changing production. The work often moves through the same stages of planning, testing, review, and approval.

A science or engineering degree and substantial validation experience are typical foundations for this level. You need enough practical knowledge to recognize when an apparently complete record does not support the conclusion being claimed. Much of the routine involves checking details and resolving questions before signing off the work. Regulated manufacturing gives the specialty a continuing role as processes change. There can be pressure around production shutdowns and deadlines, so ask about the workload. A strong candidate can organize a complicated test program without allowing the schedule to decide whether an unresolved result is acceptable.

4. Specialist product reliability engineer

Engineer in a hard hat and safety vest using a laptop beside industrial electrical equipment
Image Credit: Shutterstock

Specialist reliability engineers examine how products or equipment fail and help reduce recurring problems. Average annual pay at level IV is $137,017. A typical week may include reviewing test results, examining failed parts, and checking whether a proposed change improves performance. Manufacturers need this work for products that must operate reliably over time. The routine can be repetitive because a useful comparison often requires the same tests under carefully controlled conditions.

This is an experienced engineering role, usually reached after working in testing, product development, or manufacturing. You need to understand the physical product and the limitations of the information being collected. Some positions are based in laboratories; others work closely with operating plants. Reliability work remains useful as businesses try to reduce breakdowns, warranty costs, and premature replacement. It helps to enjoy tracing small differences through a long sequence of results. Read the job description carefully because physical product reliability and software infrastructure reliability are different careers, even when employers use similar job titles.

5. Lead materials engineer

Two professionals in hard hats reviewing tablets among wood panels in a manufacturing workshop
Image Credit: Shutterstock

Lead materials engineers help choose, test, and process materials for manufactured products. Average annual pay at the level V benchmark is $152,818. You might review test reports, approve material changes, or investigate why a component performed differently from earlier batches. Manufacturers rely on these decisions when balancing strength, weight, durability, and cost. In an established production environment, much of the routine concerns familiar materials and recurring quality checks rather than entirely new inventions.

A materials science or engineering degree and extensive relevant experience are usual requirements. You may guide other engineers without holding a department management job. The broader occupation is projected to grow, supporting demand for people with practical materials expertise. Expect detailed technical discussions, supplier questions, and records that connect a test result to a production decision. The less visible part of the job is keeping track of small changes that could affect performance later. It suits someone who can stay thorough when the work looks similar from one batch or reporting period to the next.

6. Lead industrial engineer

Professional comparing printed charts with spreadsheet charts on a desktop computer
Image Credit: Shutterstock

Industrial engineers study how production systems use people, equipment, space, and time. Average annual pay at level V is $153,701. In a process improvement role, you might review repeated delays, compare workloads, or check whether a layout change improved performance. Manufacturers, distribution operations, and other large organizations employ industrial engineers. The day can involve observing the same process many times and checking whether the numbers match what is happening on the floor.

A relevant engineering degree and substantial experience are common requirements at this level. You need to understand practical constraints, including maintenance, safety, and the people doing the work. Industrial engineering has a strong projected hiring outlook. The routine often includes measurements, meetings, and follow-up checks after a change is introduced. It can suit someone who likes making a familiar process more reliable without expecting a complete redesign every week. Be prepared for resistance when an apparently small adjustment changes someone’s usual working method, and for results that need more than one explanation.

7. Specialist chemical process engineer

Engineer in protective clothing examining a large pipe in an industrial processing facility
Image Credit: Shutterstock

Chemical process engineers help manufacturing operations run safely and consistently. Average annual pay at level IV is $138,333. An established-site role may involve reviewing operating conditions, checking process changes, and investigating why a batch or production step behaved differently. Employers can make products such as chemicals, fuels, food ingredients, or other processed materials. Much of the routine follows production data and the same equipment, with additional attention when performance starts to drift.

A chemical engineering degree and several years of relevant process experience are typical requirements. You need to understand both the theory and the practical limits of the equipment. Routine work can still carry substantial responsibility, especially where heat, pressure, or hazardous substances are involved. Manufacturers need experienced people to assess changes and resolve recurring problems. Ask whether the position supports daily operations, major projects, or both. Production support can include callouts and shutdown work, while a more office-based technical role may spend longer reviewing records, calculations, and proposed modifications before they reach the plant.

8. Specialist water resources engineer

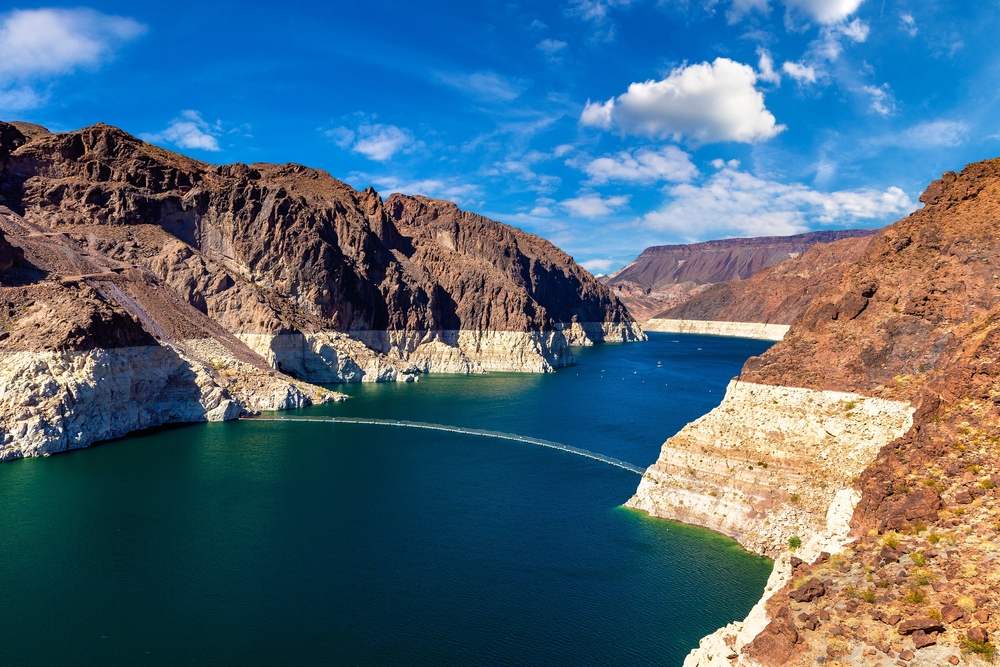
Colorado River water below pale exposed rock bands near Hoover Dam at Lake Mead
Image Credit: Shutterstock

Water resources engineers work on systems that manage water supply, drainage, and flooding. Average annual pay at level IV is $151,630. You might review drainage calculations, check plans, or assess how a proposed development changes water movement. Consulting firms, utilities, and public organizations need these specialists. A review-focused position can involve a familiar sequence of drawings, measurements, design requirements, and corrections across many different projects.

Civil or environmental engineering is a common educational route, followed by substantial water-related experience. Professional engineering licensure is often important at senior levels. The work requires patience with detailed assumptions because a design can look reasonable while depending on incomplete or unsuitable information. Infrastructure maintenance and development support a continuing need for these skills. Some roles include field visits, public meetings, or urgent work after severe weather. If you prefer a more regular schedule, compare ongoing design review and utility planning positions with jobs centered on emergency response or extensive construction-site support.

9. Experienced facilities engineer

Facilities professional in a hard hat reviewing a tablet above a factory production floor
Image Credit: Shutterstock

Facilities engineers look after the technical systems that keep large buildings working. Higher-paid level IV positions reach the national 75th-percentile benchmark of $145,856 per year. You might review maintenance plans, check equipment capacity, or assess modifications to heating, ventilation, and other building systems. Hospitals, laboratories, manufacturers, and other large employers need this work. Much of the routine concerns the same facility, recurring maintenance needs, and planned changes.

A mechanical or electrical engineering degree and substantial building systems experience are common requirements. This salary describes the higher-paid part of the market, so the level and responsibilities of the position matter. You need to understand how systems interact and how to make changes without disrupting the people using the building. The work can be steady, but a breakdown may interrupt the timetable. Ask about on-call arrangements, the age of the equipment, and the maintenance backlog. An established facility with good planning is a different working environment from one where the engineer spends every week dealing with overdue repairs.

10. Experienced environmental compliance engineer

Environmental professional in a hard hat reviewing a tablet beside an industrial facility
Image Credit: Shutterstock

Environmental compliance engineers help operating sites meet their environmental requirements. Higher-paid level IV positions reach a 75th-percentile salary of $136,782 per year. You might review emissions information, check treatment system performance, or assess a proposed process change. Manufacturers, utilities, and consulting firms need this oversight. The routine often follows sampling schedules, permit conditions, inspections, and reporting deadlines rather than a constant stream of unrelated projects.

A relevant engineering degree and extensive experience in the applicable systems are common foundations. This is a higher-paid benchmark, not a typical starting salary. You need to understand the technical information and know when an unusual result requires further investigation. Environmental engineering has positive projected growth. Some positions involve frequent travel between client sites, while others support one established operation. It helps to be comfortable maintaining accurate records and explaining practical changes to production staff. Ask about incident response duties and the size of the compliance workload before assuming that a calendar full of routine checks means a light schedule.

11. Experienced packaging engineer

Professional in a hard hat checking a clipboard beside wrapped pallets of goods in a warehouse
Image Credit: Shutterstock

Experienced packaging engineers oversee the technical details that protect products during manufacturing, storage, and delivery. Higher-paid level IV positions reach a 75th-percentile salary of $143,516 per year. You might review test results, approve changes to materials, or help resolve repeated damage during shipping. Food, healthcare, and consumer goods manufacturers need this work. Established product lines can create a fairly familiar routine of testing, supplier questions, and production support.

Packaging science or engineering education and substantial practical experience are common requirements. The cited figure describes the higher-paid part of this senior market. You need to understand how a package behaves beyond the laboratory, including its handling and performance on the production line. Cost pressure and efforts to reduce waste create regular reasons to revisit existing designs. The job can include trial runs, detailed records, and discussions about changes that appear minor but affect thousands of products. It suits someone who enjoys improving a practical system and can keep track of both the material specifications and the manufacturing conditions.

12. Experienced industrial hygienist

Industrial professional in a hard hat reviewing a tablet beside factory machinery
Image Credit: Shutterstock

Industrial hygienists assess workplace exposures to hazards such as noise, dust, and chemicals. At level IV, the national 75th-percentile annual salary is $137,744. Senior work may include reviewing exposure measurements, planning monitoring programs, and advising on controls. Large employers and consulting firms need people who can handle complicated conditions and explain what should change. Much of the calendar can be organized around repeat sampling, inspections, and reviewing the same control systems.

A relevant science or engineering degree, extensive practical experience, and professional credentials can be important at this level. The pay figure describes a higher-paid position rather than the occupation’s overall average. The wider workplace health and safety field has strong projected growth. You need to judge the quality of a measurement and understand how a recommended control affects actual work. Some positions involve significant travel or industrial-site visits. A good candidate can explain why a gradual exposure still needs attention and can keep monitoring work consistent across different teams, shifts, and facilities without losing important details.

13. Regulatory affairs manager

Letter tiles spelling Regulatory Affairs on a gray background
Image Credit: Shutterstock

Regulatory affairs managers oversee the work needed to keep products compliant with the rules governing their manufacture and sale. Average annual pay is $151,166. In a pharmaceutical or medical device company, you might review product changes, coordinate submissions, and check responses to regulatory questions. Much of the routine involves technical records, deadlines, and confirming that the right people have reviewed a decision. Ongoing products still need oversight after their first approval.

A relevant science or engineering degree and experience in regulatory work are common requirements. Management positions also require organizing other people’s workloads and deciding which issues need urgent attention. You need to understand the product area well enough to spot gaps in the evidence. Compliance work has a stable broader outlook, although specialist management jobs are a smaller market. The day may be predictable in its tasks without being easy in its deadlines. Ask about the number of products, the team’s staffing, and the amount of launch activity. An established portfolio can create a different workload from a business trying to introduce several new products at once.

14. Purchasing manager

Professionals discussing documents and contract terms together at an office table
Image Credit: Shutterstock

Purchasing managers oversee how an organization buys the goods and services it needs. Median annual pay is $148,080. In a large manufacturing or institutional setting, the routine might involve reviewing supplier performance, approving purchases, and negotiating recurring contracts. You also help resolve problems when an order arrives late or does not meet requirements. Much of the work concerns familiar suppliers and repeat purchases rather than finding a new product every day.

A bachelor’s degree and several years of buying or procurement experience are common routes into management. You need to understand the organization’s requirements and be comfortable discussing price, quality, and delivery with suppliers. The broader purchasing field has positive projected growth. This role still carries pressure when a missing part interrupts production or an important contract is approaching renewal. Ask how much of the work involves established purchasing programs and how much involves urgent shortages. It suits someone who can keep detailed agreements straight and make a practical decision when the lowest price comes with an unacceptable delivery or quality risk.

15. Experienced laboratory manager

Laboratory researchers wearing protective suits and goggles examine fluid samples beside a microscope
Image Credit: Shutterstock

Laboratory managers keep testing facilities organized, staffed, and ready to produce reliable results. Higher-paid positions reach a national 75th-percentile salary of $146,359 per year. You might review workloads, check equipment maintenance, manage supplies, and follow up on quality problems. Employers can include manufacturers, testing businesses, and healthcare organizations. In an established laboratory, the day often follows familiar tests, reporting schedules, and recurring checks of staff competency and equipment performance.

A relevant scientific degree and substantial laboratory experience are common requirements. Clinical settings may also expect specific professional credentials. The quoted figure describes higher-paid management work, so the type and size of the laboratory matter. You need to understand the testing well enough to recognize when a result or procedure needs closer review. The routine also includes staffing problems and competing deadlines. Before applying, check whether the job covers one laboratory or several facilities, and whether the manager regularly fills gaps at the bench. Those details can change the working day considerably even when two employers use the same title.

16. Compensation and benefits manager

Two professionals discussing a laptop and paperwork at an office table
Image Credit: Shutterstock

Compensation and benefits managers oversee employee pay structures and benefit programs. Median annual pay is $149,230. The routine can involve reviewing salary arrangements, assessing benefit costs, and coordinating recurring enrollment or renewal periods. Large employers need someone to keep these programs workable and consistent. This is an employee policy and program role, with much of the day spent reviewing information and discussing decisions with human resources colleagues and benefit providers.

A bachelor’s degree and substantial human resources experience are common routes into the job. You need to understand benefit programs, relevant requirements, and the practical effects of changing what employees receive. The occupation has modest positive projected growth, so it is a stable specialist market rather than a rapidly expanding one. Annual review and enrollment cycles make the work repetitive, but busy periods can be demanding. It helps to be comfortable explaining a complicated arrangement in plain language. Ask how much authority the role has and whether a separate team handles routine administration, because those details affect both the workload and the decisions you will make.

17. Experienced supply chain manager

Two professionals reviewing warehouse inventory beside shelves of boxed stock
Image Credit: Shutterstock

Supply chain managers coordinate how materials and products move through a business. Higher-paid positions reach a national 75th-percentile annual salary of $142,958. You might review inventory, check supply plans, and resolve recurring delivery problems. Manufacturers and distribution businesses need reliable flows of goods to keep their operations working. Established operations often have the same planning meetings, performance checks, and replenishment decisions each week.

A relevant degree and practical experience in logistics, purchasing, or operations are common requirements. This salary describes the higher-paid part of the market. You need to understand how a decision in one part of the supply chain affects the rest, including warehouse capacity and production schedules. The routine is familiar, but a supplier failure can create substantial pressure. Ask about the product range, the number of locations, and the frequency of urgent disruptions. A role focused on stable replenishment is different from one rebuilding a troubled supply network. Strong candidates can follow a plan while recognizing when the assumptions behind it have changed.

18. Experienced manufacturing quality assurance manager

Professional in a hard hat checking a folder of records beside boxed products
Image Credit: Shutterstock

Manufacturing quality assurance managers oversee the systems used to keep products consistent and acceptable. Higher-paid positions reach a national 75th-percentile salary of $141,225 per year. You might review audit findings, check corrective actions, and manage quality procedures across a production operation. The routine often revolves around the same measures of performance, recurring inspections, and scheduled reviews. Manufacturers need this work to address defects and maintain the standards their customers require.

A technical degree and extensive quality or manufacturing experience are common requirements. The pay figure describes the higher-paid part of the market rather than the overall average. You need enough knowledge of production to distinguish an isolated mistake from a problem built into the process. The job also involves working with staff who may feel pressure to keep output moving. Ask about the number of sites, the quality team’s size, and the current audit workload. An orderly system creates repetitive oversight work, while a business with unresolved quality problems can make the same title much more demanding.

Follow this parent’s checklist to spot possible vision problems and plan the next steps.
Image Credit: MART PRODUCTION via Pexels

Okay, so your kid said they can’t see the board from their seat. If your first thought is, “Wait, how long has this been happening?” it’s also possible your second one might involve wondering what you missed.

First, don’t panic. A child who struggles to see things far away often needs nothing more dramatic than an eye exam and, possibly, a pair of glasses. Myopia (nearsightedness) is common in childhood, and it can become more noticeable as the eyes grow, particularly between ages 7 and 12.

Still, “I can’t see the board” isn’t something to brush off. So, here’s what to do next.

1. Get the details before you make the appointment

Ask your child what “can’t see” actually means for them.

Here are some questions you can ask:

  • Can they see the board if they move closer?
  • Is everything at the front of the classroom blurry, or only the smaller writing?
  • Does one eye seem worse?
  • Do they squint, close one eye, get headaches, or complain that words look doubled?

Obviously, you don’t need to conduct a home eye exam. What you want to do is collect clues.

And pay attention to when it happens. A child who sees the board clearly in the morning but complains after hours of schoolwork may be dealing with eye strain or focusing problems. A child who consistently can’t make out distant writing may have a refractive error such as myopia. The distinction will be useful information for the eye doctor.

2. Ask the school what they’ve noticed

Your child may not be the first person to spot the problem. A teacher might have noticed squinting, copying from classmates, moving closer to the board, or struggling with work that requires distance vision. So ask whether the school has done a vision screening and, if so, ask for the results.

Just keep one thing straight: a screening is not a full eye examination. A screening can identify children who need further evaluation, but it doesn’t explain why a child has blurry vision. The American Association for Pediatric Ophthalmology and Strabismus (AAPOS) recommends vision screening throughout childhood and referral when a child doesn’t meet age-appropriate visual-acuity standards.

3. Schedule the eye exam

Resist the temptation to diagnose your child through Google! Instead, simply schedule the eye exam.

Depending on the child’s age and the reason for the visit, the doctor may use dilating drops to get a more accurate measurement of the prescription and examine the structures inside the eye. That’s particularly useful with children because they can accommodate, or actively focus, quite strongly.

If you live in Southwest Florida and need an eye doctor in Estero, FL, Florida Vision Centers has a physician-led ophthalmology practice near Coconut Point. The office evaluates a range of eye and vision concerns, with testing and examination tailored to what the patient actually needs.

In other words, you don’t need to show up knowing what’s wrong. “My child says the board is blurry” is a perfectly reasonable place to start.

4. Don’t blame the tablet just yet

Screens get blamed for practically every modern childhood problem, and yes, lots of close-up screen use can contribute to eye strain, headaches, and blurry vision. But that doesn’t mean the iPad literally caused your child’s nearsightedness.

Myopia has several risk factors, including family history, near work, and the amount of time a child spends outdoors. However, spending more time outdoors really is associated with a lower risk of myopia and may help slow its progression.

So there is actually a useful, low-drama thing you can do here: get your child outside more often. AAPOS actually recommends this: at least an hour outdoors each day, along with keeping reading and screens at least 12 inches away and using the 20-20-20 rule for prolonged close work.

5. Bring useful information to the appointment

Write down when the problem started, whether it’s getting worse, whether it happens at home as well as school, and any headaches or other symptoms. Bring your child’s current glasses if they wear them, previous eye records if you have them, and a list of medications.

If you’ve got the school’s screening results, bring those too. For a busy parent, especially a single mom trying to fit a doctor’s appointment between school pickup, work, and approximately 200 other things, this preparation isn’t about being organized for organization’s sake. It can save time and give the doctor a clearer starting point.

6. Ask whether your child needs glasses (and what happens after that)

If the examination shows myopia, the conversation shouldn’t really end with “Here’s your prescription.” Ask whether your child’s nearsightedness is mild and stable or whether it appears to be progressing. This is important to ask because childhood myopia can increase as the eye grows, often through the teenage years.

Depending on your child’s age and individual situation, the eye doctor may discuss ordinary glasses or contact lenses, as well as options intended to slow myopia progression.

And if your child does need glasses? That’s okay. Really, and truly. Kids often adjust faster than parents expect. A much bigger problem is a child who spends months trying to read a blurry board because everyone assumed they were distracted, sitting too far away, or simply not paying attention.

Somebody just told you AI is coming for every job that requires a keyboard. Somebody else told you there are 500,000 unfilled trade jobs and a plumber can out-earn a lawyer. Both of them have a partial version of the truth, and neither one tells you what to actually go learn.

Job postings that ask for AI literacy skills grew by more than 70 percent in a single year. At the same time, the country is short more than 2.1 million skilled trades workers heading into 2030, in fields like electrical work, HVAC repair, and plumbing that have nothing to do with a computer screen. Both of those things are true, in the same economy, sometimes at the same company.

The job market isn’t shrinking. It’s sorting people into two piles: those with a skill somebody is actually short on, and everybody else competing for whatever’s left over. Here’s where the real shortages are.

Practical AI skills, not just AI awareness

Person using a laptop with overlaid AI coding agent graphics and programming code
Image Credit: Shutterstock

Job postings requiring AI literacy jumped by more than 70 percent in a single year. The specific skills employers want are just as telling: prompt engineering, model training, and data annotation are all seeing rising demand. None of that requires a computer science degree. It requires knowing how to get useful output out of the AI tools your company already pays for, and knowing when that output is wrong.

Most companies aren’t hiring people to build AI models from scratch. They’re hiring people who can fold AI tools into ordinary work: writing better prompts, cleaning up a model’s output, catching it when a chatbot gives a customer bad information. You can learn the fundamentals through free courses from the AI companies themselves, a short bootcamp, or just by using the tools at your current job until you’re the person coworkers ask for help.

Two-thirds of executives expect employees to build AI skills on their own within six months, but less than half of U.S. professionals feel supported in doing that. Showing up to an interview able to describe exactly how you’ve used AI tools to solve a real problem puts you ahead of people still describing themselves as “AI-curious.”

Cybersecurity basics

Data privacy concept with hands using a laptop and overlaid padlock, shield, and personal-information icons
Image Credit: Shutterstock

Information security analysts pull a median salary of $124,910 a year, with employment projected to grow 29 percent through 2034, one of the fastest rates for any occupation in the country. About 16,000 openings are expected annually, and that doesn’t count the thousands of other jobs, from IT support to compliance, that now list some level of security knowledge as a requirement.

You don’t need a computer science degree to start. Entry-level certifications like CompTIA Security+ take a few months of study and get you in the door for help desk and junior analyst roles, where you build the experience that leads to the higher-paying jobs. The field also rewards people who came from unrelated careers. Auditors, IT generalists, and former law enforcement officers often move into cybersecurity because they already understand risk and documentation.

The demand isn’t going away. Every company that gets hacked spends the next two years explaining to regulators, customers, and its own board why it didn’t have someone watching the door. That’s a permanent job, not a trend.

Data analysis and data literacy

Professional studying information on a laptop screen in an office
Image Credit: Shutterstock

Data scientists pull a median salary of $112,590 a year, with employment projected to grow 34 percent through 2034, the highest growth rate projected for any occupation in the computer and mathematical field. About 23,400 openings are expected each year, driven by companies that finally have enough data to make decisions with and not enough people who know how to read it.

This isn’t about becoming a data scientist with a graduate degree. Most companies need people who can pull a report out of a spreadsheet, spot the trend that matters, and explain it to a manager who doesn’t want to look at a chart. That skill sits underneath marketing, operations, healthcare, and retail jobs that never mention “data” in the title. Free tools like Excel, Google Sheets, and a basic SQL course will get most people further than a certificate will.

What separates this from data entry, a job AI has genuinely hollowed out, is judgment. A machine can enter data. It takes a person to notice the numbers don’t add up and ask why.

Electrical work

Two electrical professionals in hard hats reviewing plans and equipment at a substation
Image Credit: Shutterstock

Electricians earn a median of $62,350 a year, with 81,000 openings projected annually as employment grows 9 percent through 2034, nearly triple the average for all occupations. Data centers, EV charging networks, and grid upgrades are all competing for the same shrinking pool of licensed electricians, part of a shortfall of 2.1 million skilled trades workers projected by 2030 across electrical, HVAC, and plumbing combined.

An apprenticeship pays you while you train, usually over four to five years, and ends with a state license instead of student debt. Entry requires only a high school diploma. The tradeoff is real: the work is physical, licensing exams are demanding, and it takes years to reach journeyman pay.

What makes this a durable bet rather than a passing shortage is what’s driving it. Every new server farm, every EV charger, every home converting from gas to electric heat needs a licensed electrician to wire it, and none of that work can be done remotely or automated away.

HVAC and refrigeration repair

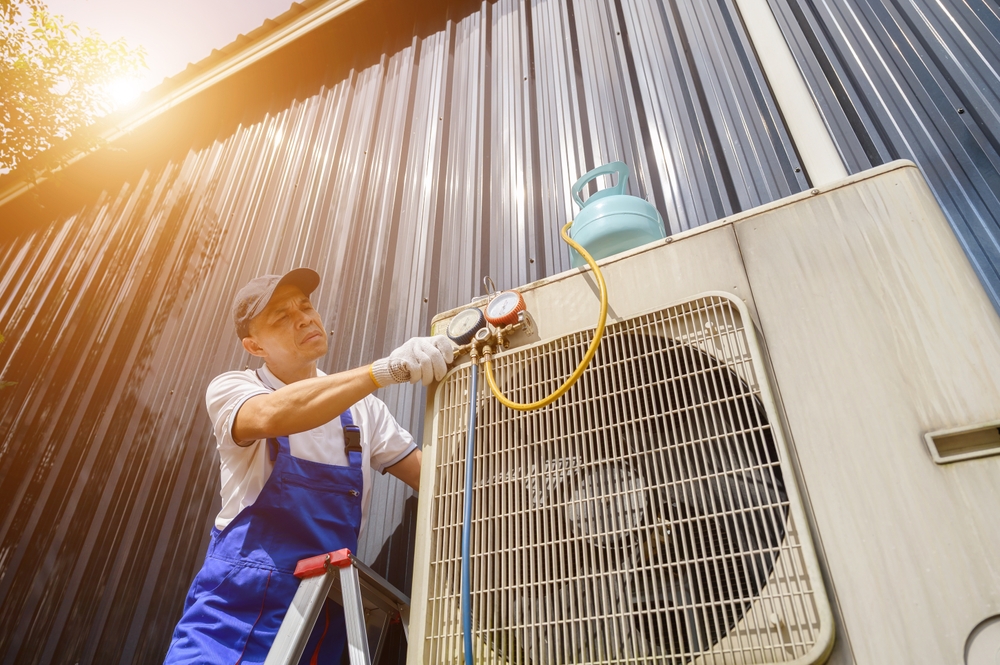
HVAC service technician checking an outdoor air conditioner compressor with refrigerant pressure gauges
Image Credit: Shutterstock

HVAC technicians earn a median of $59,810 a year, with about 40,100 openings projected annually as employment grows 8 percent through 2034. New refrigerant regulations and increasingly extreme summers have made this one of the tightest labor markets in the trades, with contractors reporting months-long waits to fill open technician positions.

Training runs six months to two years through a trade school or community college, followed by an apprenticeship. EPA certification is required to handle refrigerants, which is a one-time exam rather than an ongoing licensing burden in most states. Commercial refrigeration and building automation specialists earn well above the median, often clearing $80,000 to $90,000 once they’re experienced.

This is also one of the few trades where the seasonal nature of the work cuts in the technician’s favor. Emergency calls during a heat wave or cold snap routinely pay overtime rates, and a technician willing to be on call can build a genuinely high income without ever running their own business.

Plumbing

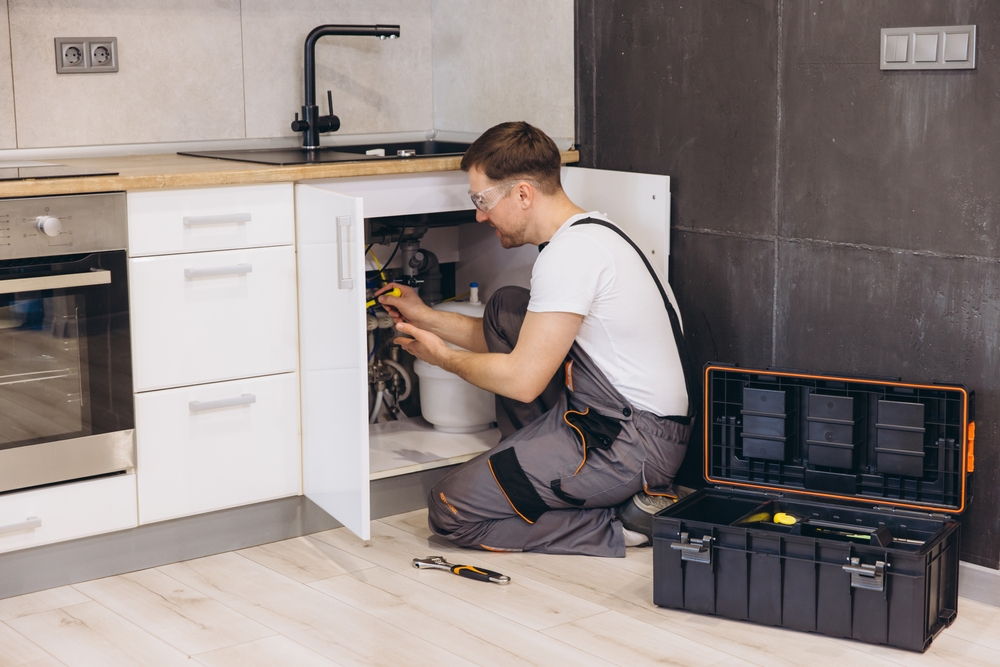
Plumber using hand tools to repair pipework beneath a kitchen sink
Image Credit: Shutterstock

Plumbers, pipefitters, and steamfitters earn a median of $62,970 a year, with about 44,000 openings projected annually. Growth here is slower than electrical or HVAC work, at 4 percent through 2034, but the bottleneck isn’t demand. It’s licensing. Most states require a four to five year apprenticeship before a plumber can work unsupervised, and that long runway keeps new entrants from catching up with retirements.

Plumbers who go on to hold a master license and run their own crew routinely earn well past the median, since licensed plumbers can charge for both labor and the liability they carry. Emergency and commercial work, especially anything involving gas lines or medical gas systems, pays a premium over standard residential jobs.

The apprenticeship itself is paid, which sets plumbing apart from most four-year degree paths. You’re earning a wage from year one while a basic public health requirement, functioning pipes, keeps the work from ever fully disappearing or getting outsourced.

Welding

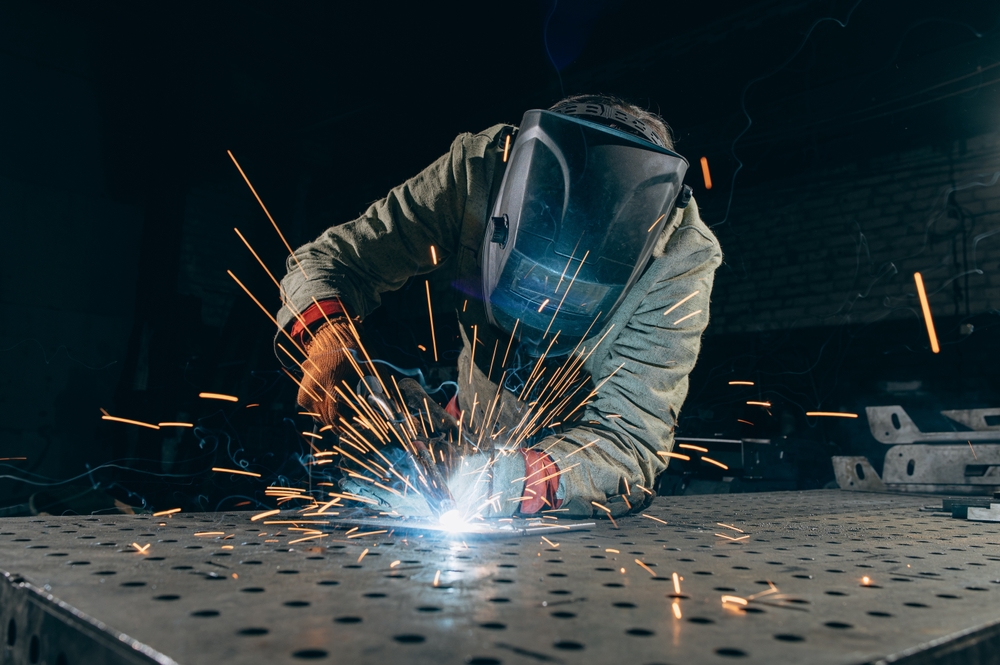
Welder wearing a protective helmet and gloves joins metal with bright welding sparks
Image Credit: Shutterstock

Welders, cutters, solderers, and brazers earn a median of $51,000 a year, and projected job growth sits at only 2 percent through 2034. On paper, that looks unremarkable. In practice, welding is one of the trades hit hardest by worker shortages in 2026, because a large share of the existing workforce is retiring faster than schools are producing replacements.

Low projected growth in a large occupation like this one still means real openings, because most of the demand is replacement demand rather than new job creation. Manufacturing, shipbuilding, pipeline work, and construction all need welders, and specialized certifications in pipe welding, underwater welding, or aerospace welding pay well past the median.

Training can take as little as six months at a technical college for entry-level certification, though the highest-paying specialties take longer and require passing tests through the American Welding Society. This is a trade where the credential, not a degree, is what actually opens doors.

Registered nursing

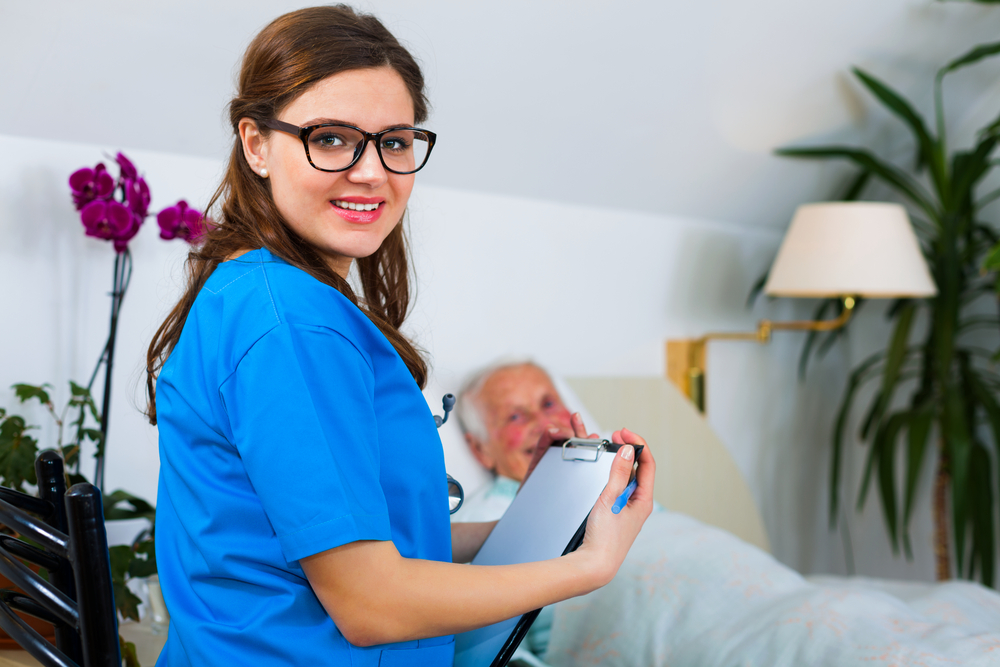
Nurse in blue scrubs holding a clipboard beside an older patient resting in bed
Image Credit: Shutterstock

Registered nurses earn a median of $93,600 a year, with about 189,100 openings projected annually as the aging population drives sustained demand for care. Nursing is one of the largest healthcare occupations in the country, and one of the few where a two-year associate degree can still get you into the field, though a bachelor’s degree opens more doors and typically pays better.

What makes nursing different from a lot of “in-demand” careers is the built-in mobility. A nursing license transfers across states more easily than most professional credentials, hospitals routinely offer sign-on bonuses and tuition assistance, and travel nursing contracts let experienced RNs earn considerably more than a staff position for a few months at a time.

The work is demanding, physically and emotionally, and burnout is a real and well-documented problem in the profession. But the demand isn’t a pandemic-era blip. It’s demographic, tied to a population that’s getting older and living longer with more chronic conditions, and it will keep building for decades.

Home health and personal care work

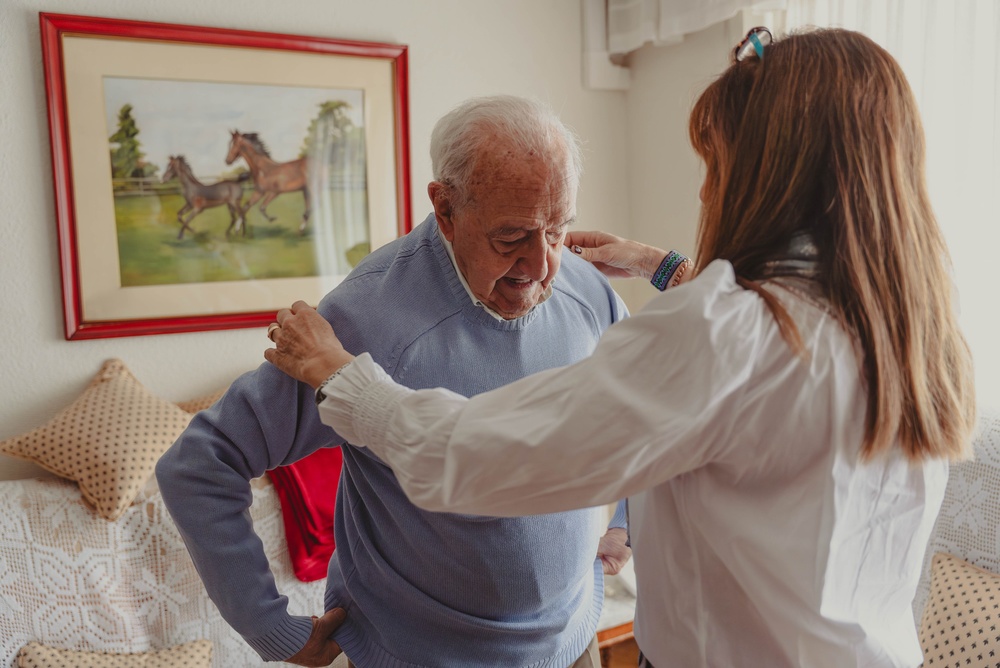
Home care worker supporting an older man as he stands in his living room
Image Credit: Shutterstock

Few jobs add as many new positions as this one: 17 percent growth is projected through 2034, adding more new positions than almost any other occupation in the country. Median pay is $34,900 a year, which is modest, but the barrier to entry is close to nothing. Most positions require only a high school diploma, and some require none at all.

This is real, physical work that involves bathing, dressing, and monitoring people who can no longer fully care for themselves, and it isn’t for everyone. But it’s also one of the only fast-growing fields where someone can start earning money within days of deciding to enter it, with paid training available through many home care agencies and no cost to the worker.

For people building toward a nursing career, this is also a common and practical entry point. It puts you in a medical setting, on a real schedule, earning money, while you figure out whether healthcare is the right long-term fit before committing to years of nursing school.

Solar panel installation

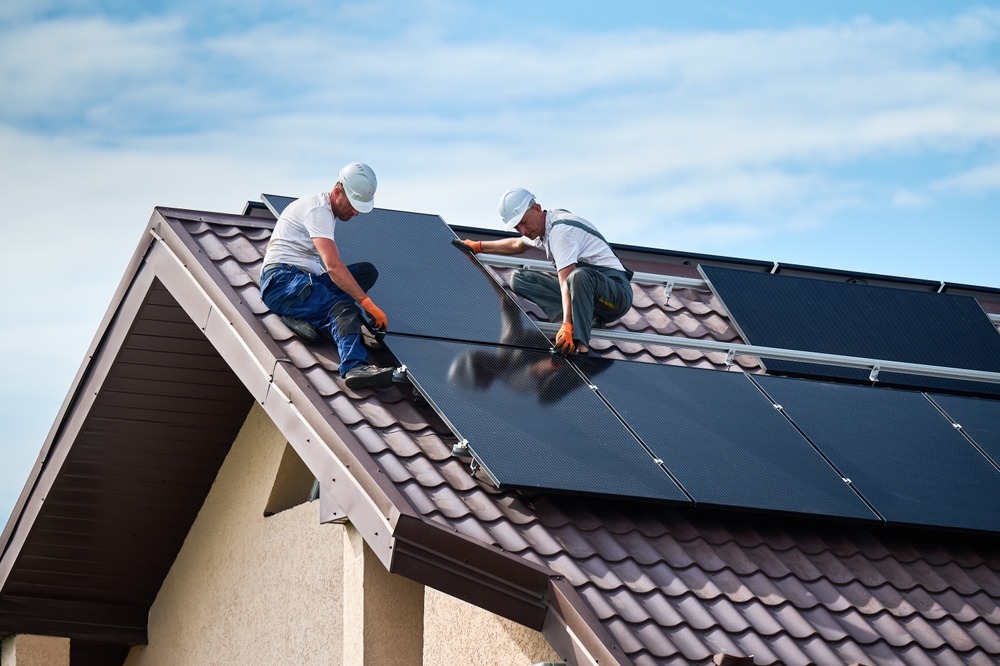
Two installers positioning solar panels on a tiled house roof
Image Credit: Shutterstock

Falling equipment costs and federal tax credits have pushed solar installation into one of the fastest-growing trades in the country: 42 percent projected growth through 2034, with median pay of $51,860 a year. That’s among the fastest rates of any occupation the government tracks.

Most installers train through a technical school program lasting a few months to a year, followed by on-the-job training that typically runs under a year before a worker is fully independent. A high school diploma is the only formal requirement, though electrical knowledge is a real advantage, since installers connect panels to a home’s existing electrical system and, increasingly, to battery storage.

The trade also has an unusually low ceiling for entry cost. Unlike electricians and plumbers, who face years of licensed apprenticeship before working independently, a solar installer can be earning a full wage within a year, with real income growth for anyone who adds electrical licensing or moves into supervising crews.

Wind turbine maintenance

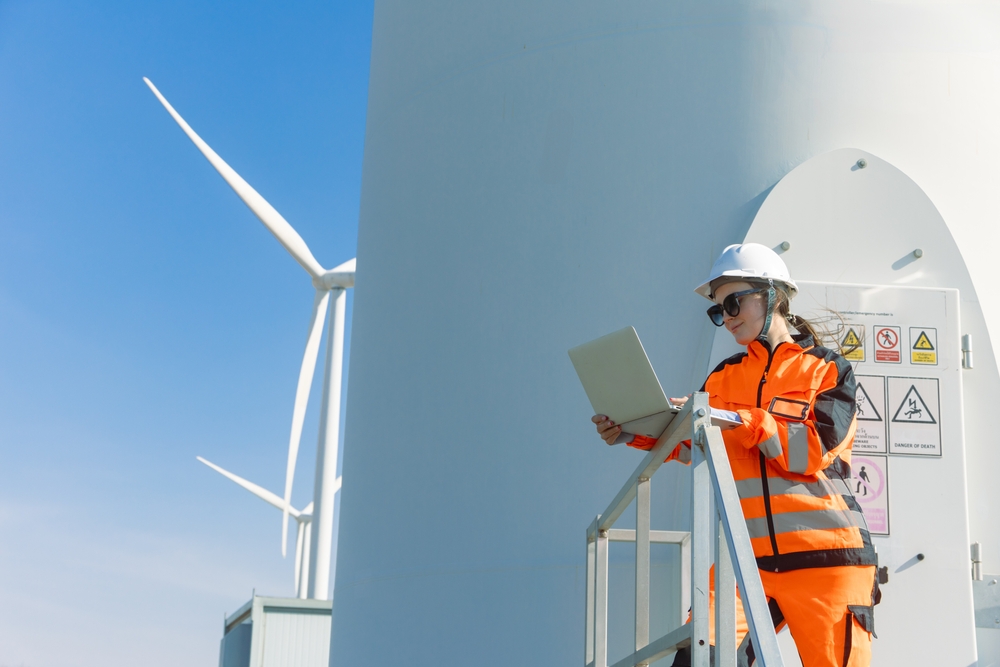
Wind turbine service technician in safety gear checking equipment at a wind farm
Image Credit: Shutterstock

Wind turbine technicians have the fastest projected job growth of any occupation in the country, at 50 percent through 2034, with a median pay of $62,580 a year. It’s a small occupation in absolute terms, adding under 7,000 jobs over the decade, but the percentage reflects how fast the wind industry is scaling.

The job itself is not for anyone afraid of heights. Technicians climb turbines that average over 300 feet tall to diagnose and repair mechanical and electrical components, often in remote locations. Training runs one to two years through a technical program, and most employers also require workers to pass a physical fitness test given the climbing demands.

The tradeoff for the physical demands is pay that starts well above many entry-level trades, plus per diem and travel pay at wind farms located far from population centers. For someone who wants a physically demanding job with a genuinely uncrowded applicant pool, this is about as uncrowded as it gets.

Electric and hybrid vehicle repair

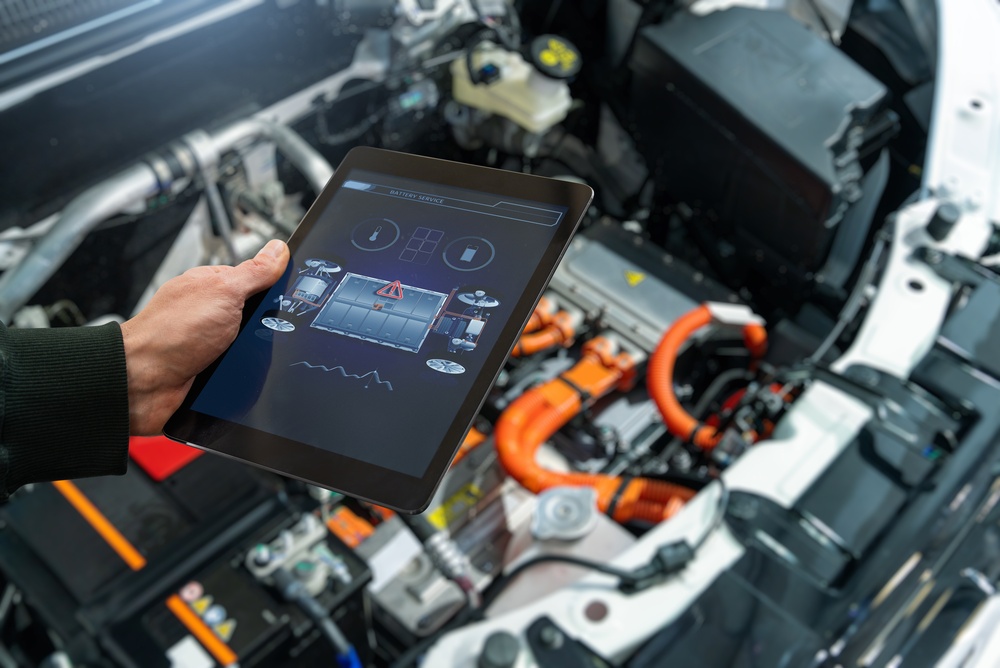
Technician viewing vehicle diagnostics on a tablet beside an electric vehicle’s high-voltage components
Image Credit: Shutterstock

Automotive service technicians earn a median of $49,670 a year, with overall employment growing a modest 4 percent through 2034. But that number hides the real opportunity. Only about 1.4 percent of certified auto technicians hold an EV-specific certification, even as electric vehicles made up more than 8 percent of new car sales in 2024.

Every dealership and independent shop that services EVs needs technicians trained on high-voltage battery systems, and most don’t have enough of them. A technician who already knows how to diagnose a gas engine can typically add EV certification through a manufacturer program or trade school course in a matter of months, not years, since much of the diagnostic and electrical knowledge carries over directly.

This is a rare case where a small, specific credential added to an existing skill set creates a real pay premium. Shops are actively competing for the handful of technicians who can safely work on a battery pack, and that pays more than general automotive work.

Project management

Project planning concept with hands using a tablet beneath overlaid calendars and schedule charts
Image Credit: Shutterstock

Project management specialists earn a median of $100,750 a year, with about 78,200 openings projected annually as employment grows 6 percent through 2034. Nearly every industry, from construction to healthcare to software, needs someone who can keep a budget, a schedule, and a group of people who don’t report to each other all moving toward the same deadline.

A bachelor’s degree is typical, but it doesn’t have to be in a related field. What actually gets people hired and promoted in this line of work is a Project Management Professional certification, which requires documented project experience and a rigorous exam, or a lighter Certified Associate credential for people just starting out.

What makes this skill valuable is how transferable it is. Someone who has run a kitchen, coordinated a nonprofit event, or managed a construction crew already has the underlying skill. Formalizing it with a credential and the right vocabulary is often the only thing standing between that experience and a job title that pays considerably more for the same ability.

Supply chain and logistics coordination

Two professionals reviewing warehouse inventory beside shelves of boxed stock
Image Credit: Shutterstock

The pandemic exposed how fragile supply chains actually were, and companies have spent the years since building teams whose entire job is making sure that doesn’t happen again. Logisticians pull a median salary of $80,880 a year, with employment projected to grow 17 percent through 2034, more than five times the average for all occupations.

Most logistician roles require a bachelor’s degree, often in business or supply chain management, though people move into the field from military logistics backgrounds, warehouse management, and procurement without one. Certifications through organizations like APICS can substitute for some of the formal education requirements employers list.

This field rewards people who are comfortable with software and spreadsheets but don’t need a technical degree to use them well. Inventory systems, shipping schedules, and vendor contracts all generate data that someone has to actually manage, and companies are paying well for people who can do that without a warehouse floor turning into chaos.

Critical thinking and complex problem solving

Actuarial analyst reviewing printed financial charts beside a computer
Image Credit: Shutterstock

Analytical thinking is now the fastest-growing skill on employers’ lists, ahead of every purely technical skill in the survey. Nearly 39 percent of the core skills workers use today are expected to change by 2030.

This isn’t a soft skill in the sense of being vague or hard to prove. Employers want evidence that you can look at a messy, ambiguous problem and work through it methodically instead of guessing or freezing. That’s exactly the kind of work AI tools handle badly, and people, when they practice it, handle well.

You build this by doing it, not by taking a course that promises to teach it. Volunteering for the messiest project at work, working through real case studies in your field, or simply asking one more “why” than feels comfortable in a meeting all count. It shows up on a resume as specific problems you solved, not as a trait you claim to have.

Leadership and people management

Manager discussing work on a laptop with a colleague at an office table
Image Credit: Shutterstock

Leadership and social influence rank among the fastest-growing skills on employers’ lists, alongside talent management, and the reasons are practical. As routine tasks get automated, the value of a job shifts toward the parts that require judgment about people rather than tasks.

You don’t need a management title to build this skill. Training a new hire, running a shift, or coordinating volunteers all count as leadership experience, and the ones that translate best onto a resume have a measurable outcome attached. “Trained three new hires who all passed their ninety-day review” says more than “strong leadership skills” ever will.

Formal options exist too, through a company’s internal leadership program or an outside people-management certificate, but most hiring managers care far more about evidence than credentials here. A specific story about a team you turned around or a conflict you resolved will outperform a certificate every time.

Teamwork and communication

Two pharmacy professionals checking medication containers and paperwork at a pharmacy counter
Image Credit: Shutterstock

When employers reviewed resumes for the graduating class of 2026, teamwork, problem-solving, and communication topped the list of skills that mattered most. Seventy percent of employers now use skills-based hiring, up from 65 percent the year before, meaning they’re evaluating candidates on demonstrated ability rather than just a degree.

This shift matters because it changes what actually gets someone hired. A candidate who can describe a specific time they resolved a disagreement between coworkers, or explain a complicated process to someone who didn’t understand it, is giving an employer something they can evaluate. A resume line that just says “excellent communicator” gives them nothing.

If you’re job hunting, the practical move is to keep a running list of moments where you actually used these skills, with a result attached. That list becomes your interview answers, and it’s a far stronger asset than any personality assessment or soft-skills workshop.

Adaptability under pressure

Professional in a hard hat reviewing plans and working on a laptop in an industrial setting
Image Credit: Shutterstock

Resilience, flexibility, and agility are rising faster in importance than almost any other skill category on employers’ lists, and 85 percent of employers plan to prioritize workforce upskilling by 2030. Employers aren’t asking whether your job will change. They’re asking whether you’ll handle it when it does.

This shows up in hiring in a specific way. Employers increasingly favor candidates who have already changed roles, industries, or tools successfully at least once, over candidates whose resume shows twenty years in one lane doing the same thing the same way. A varied work history that used to read as a liability is starting to read as an asset.

The most practical way to build this is to say yes to the assignments nobody else wants, the ones that involve learning a new system or working with an unfamiliar team. Every one of those becomes proof, later, that you can absorb change without falling apart, which is exactly what employers say they’re short on.

None of these eighteen skills require starting over from nothing. Most of them build on work you’re already doing, or a trade you could learn in less time than it takes to finish a degree fewer employers are actually requiring.

Your mortgage payment is only part of what it costs to own a home. For single parents, the bigger surprise can be how quickly smaller expenses compete with groceries, child care and school supplies.

A broken appliance or higher insurance bill can disrupt a budget with little room to spare. Planning for the less obvious costs below can help you protect your household without treating every unexpected bill as a personal budgeting failure.

Property taxes beyond your mortgage estimate

Property taxes deserve their own place in your budget, even when your lender collects them through escrow. An increase can raise your monthly payment without changing your mortgage’s principal or interest.

According to research by Zillow, maintenance, property taxes and homeowners insurance together averaged $15,979 annually in 2025. So, you should check what your mortgage estimate includes before deciding how much money remains each month.

Review your tax bill and escrow statement rather than assuming last year’s payment will hold. And when comparing homes, ask about the property’s tax history and check which exemptions you may qualify for locally.

Appliance and system repairs

Appliances often need fixing. And those costs are often overlooked by homeowners. 

It’s not always just the cost of the repair that homeowners need to consider. Associated expenses matter, too. For example, a refrigerator failure costs more than just the repair when you also lose groceries and need to get takeouts. 

According to Cinch Home Services, the average home maintenance costs in Michigan are over $1,000 per month but the average home warranty cost in Michigan is only between $60 and $70 per month. Therefore, it can be more than worthwhile taking out a home warranty.

A Michigan home warranty can ensure you’re not left out-of-pocket when appliance repairs are needed. The same applies when you’re based in other states, of course.

Before comparing that expense with your repair budget, review:

  • Service-call fees
  • Coverage limits and exclusions
  • Which appliances and systems qualify

Keep room for routine maintenance, too, since preventing a breakdown and paying for a covered repair are different expenses.

Seasonal utility bills

A home’s utility costs can look manageable during mild weather and climb when temperatures change. Budgeting from one spring electricity bill may leave you short during a hot summer or cold winter.

According to the US Energy Information Administration, the average residential electric bill was $144 per month in 2024. Your own bill may differ, so use the home’s billing history where available rather than treating that national figure as your spending target.

Ask for a full year of utility bills before buying, if the seller can provide them. Compare the seasonal peaks with your available income, not just the annual average.

An older home may also need improvements to make rooms comfortable. Leave space for smaller purchases such as weatherstripping instead of assuming every comfort problem requires a major renovation.

Insurance increases and deductibles

Homeowners insurance involves both the premium you pay regularly and the deductible you may owe after a covered loss. Saving for only one leaves a gap when damage happens.

Check your deductible amounts and understand whether different types of damage have different terms. Keep any money reserved for a deductible separate from funds already committed to school expenses or routine repairs.

Comparing policies means looking beyond the lowest premium. A cheaper policy is not automatically a better fit if its out-of-pocket costs would strain your household.

Paid help when time runs short

Owning a home creates work that does not always fit around parenting and employment. Lawn care, snow removal or a repair appointment may force you to choose between paying someone and rearranging your day.

For a single parent, handling every task yourself may not be realistic. A weekend project can require extra child care, while a weekday appointment can mean missed paid hours.

Price occasional help before you need it urgently. Knowing what a local provider charges makes it easier to decide which jobs you can handle and which deserve a place in the budget.

Include transportation and scheduling costs when comparing options. The lowest repair quote may not be the cheapest overall if it requires several unpaid absences.

Making room for the hidden costs of homeownership

The hidden costs of homeownership are easier to manage when they have a place in your budget before a bill arrives. Start with taxes, repairs, utilities, insurance and occasional paid help. Then, adjust those categories using your own household’s numbers.

With a little planning, single parents can ensure that hidden homeownership costs do not get on top of them and instead remain manageable.

Has this article been helpful? If that is the case, take a moment of your time to explore some of our other interesting and useful posts. 

If you live on an SSDI check, the number everyone’s been revising all summer is finally narrowing down. Forecasters now put the 2027 Social Security cost-of-living adjustment somewhere between 3.4% and 3.6%, depending on which independent estimate you check. That range comes from the Consumer Price Index for Urban Wage Earners and Clerical Workers, known as CPI-W, which is the only inflation measure the Social Security Administration is legally permitted to use for this calculation.

Two of the three months that decide the final number are already locked in. July’s CPI-W came in at 327.104 and August’s at 328.481, both measured against last year’s third-quarter average. September is the only input still outstanding, and the Bureau of Labor Statistics is scheduled to release it on October 14, the same morning the Social Security Administration is expected to make the official 2027 COLA public.

A mid-threes raise would be the largest SSDI recipients have seen in a few years. The adjustment ran 2.8% in 2026 and 2.5% in 2025, after 3.2% in 2024, so even the low end of this year’s range beats anything beneficiaries have gotten since before 2023’s inflation spike cooled off. On a fixed disability check that already gets stretched across rent, groceries and medical bills, that difference is real money.

How the raise actually lands in your check

Social Security cards beside US dollar bills illustrating benefit payments
Image Credit: Shutterstock

The COLA isn’t a flat dollar amount handed out across the board. It’s a percentage applied to your individual benefit, so two people on SSDI with different monthly amounts get different dollar increases even under the exact same percentage. Social Security multiplies your current benefit by the new COLA, then rounds the result down to the nearest whole dollar, which is why your neighbor’s bump might land a few dollars higher or lower than yours even if you both started the year on a similar check.

The increase takes effect with benefits paid in January 2027, not with any payment before that. You won’t have to guess at your new amount, either. The Social Security Administration mails personalized COLA notices in December, and if you’ve set up a my Social Security account, that same notice usually shows up in your online message center before the paper version arrives in your mailbox.

Medicare takes its share before you see the rest

Medicare premiums written on a chalkboard beside a prescription, stethoscope, and medication
Image Credit: Shutterstock

Here’s where the raise shrinks for a lot of SSDI recipients. If you’re enrolled in Medicare, your Part B premium comes straight out of your Social Security check before it ever reaches your bank account, and that premium is set through its own separate process every fall. The current trustees’ projection puts the standard 2027 Part B premium at $209.50 a month, up from $202.90 in 2026, with the Centers for Medicare and Medicaid Services expected to confirm the real figure in November.

Run the numbers on an average SSDI check and you can see how much of the raise that eats. The average disabled worker on SSDI was pulling in $1,630 a month in 2026. A 3.5% COLA on that amount adds roughly $57 a month, and if the Part B premium climbs by its projected $6.60, that’s close to $12 of every $57 gone before you’ve spent a dime of it. It’s not nothing, but it isn’t the full raise either, and anyone enrolled in Medicare should budget off that smaller number rather than the headline percentage.

What changes for the amount you’re allowed to earn

Woman calculating her household finances with a calculator, notebook, and laptop
Image Credit: Shutterstock

The COLA isn’t the only figure that moves every January. Social Security also adjusts the earnings limits tied to SSDI, and those numbers determine how much you can work before your disability status itself comes into question. The substantial gainful activity threshold, or SGA, is the ceiling on what the SSA considers proof you’re capable of full-time work. For 2026 it sits at $1,690 a month for most beneficiaries and $2,830 a month for people who are statutorily blind, and both figures rise most years because they’re tied to growth in the national average wage, not to CPI-W directly.

The trial work period amount moves on the same schedule. In 2026, any month you earn more than $1,210 counts as one of your nine trial work months, the stretch where you can test a return to work and keep your full SSDI check no matter how much you actually bring home. Both figures typically get announced alongside the COLA in October, so the 2027 versions should land the same week as the raise itself. Knowing where they land matters if you’re weighing part-time work, since crossing the SGA line after your trial months are used up can shut your check off entirely.

Why disability advocates don’t trust this number

Woman taking US dollar bills from a wallet beside prescription medication
Image Credit: Shutterstock

CPI-W measures the spending of urban wage earners and clerical workers, which is a reasonable stand-in for a working-age household with a paycheck. It’s a worse stand-in for someone who’s retired or disabled, and advocacy groups have been saying so for decades. People with disabilities and older adults tend to spend a larger share of their income on health care than the working population CPI-W is built around, and health care costs have consistently outpaced general inflation.

The alternative that keeps coming up is the CPI-E, an experimental index built specifically around the spending patterns of people 62 and older. Switching to it would raise the average annual COLA by roughly 0.2 percentage points, which sounds small until you compound it over a decade of benefit checks. Changing the formula isn’t something the Social Security Administration can do on its own. CPI-W is written into federal law as the required measure, so swapping it out would take an act of Congress, and there’s no serious push underway to make that happen soon.

The official 2027 COLA becomes public on October 14, once the September inflation data is in hand. After that, the fastest way to see your own number is through your my Social Security account online, where the notice usually posts before the mailed version arrives.