
scroll top

You get maybe ten minutes between unloading the dishwasher and logging back into work email, and that is not enough time to build a budget or read up on index funds. It is enough time to turn on your full 401(k) match, and roughly one in five workers earning $150,000 or more still isn’t doing that. Lower down the income scale, the share missing out is much higher.

Nobody has the bandwidth to overhaul their entire financial life in a weekend, and most people don’t need to. The 18 things below take anywhere from thirty seconds to about twenty minutes each, and none of them ask you to stop buying coffee or move to a cheaper apartment.

Do even a handful of them and the savings add up fast.

Get the entire 401(k) or 403(b) match your employer offers
Orange egg marked 401k resting on US dollar bills
Image Credit: Shutterstock

Most employer retirement plans match a percentage of what you put in, dollar for dollar or fifty cents on the dollar, up to a cap. If you’re not contributing enough to hit that cap, you are turning down part of your paycheck. Vanguard’s research group found that even among workers earning $150,000 or more, about one in five still don’t save enough to capture their full match, and the rate climbs sharply the lower the income bracket goes. Across the country, employers put roughly $250 billion a year into workers’ retirement accounts, mostly as matching contributions, and a meaningful slice of that sits unclaimed simply because people never checked.

Log into your retirement plan portal or ask HR what percentage of your salary gets you the full match. If you’re contributing less than that number, bump your deferral rate up to it. This is a five-minute fix on a benefits website, and it’s the closest thing to free money most paychecks will ever offer. If cash is genuinely tight and you can’t hit the full match yet, contribute whatever you can manage and raise it the next time you get a raise.

Turn on automatic contribution increases
Wooden 401k letters on financial paperwork beside a calculator and glasses
Image Credit: Shutterstock

A lot of retirement plans have a feature called automatic escalation, which quietly raises your contribution rate by a percentage point or two every year, usually timed to your raise. You set it once and then never have to remember to do it again, which matters because most people don’t go back and manually increase their savings rate on their own.

More than half of employers with retirement plans now automatically enroll new hires, and built-in rate increases are becoming a standard feature of those plans rather than an opt-in extra. If your plan offers it, turn it on and set the annual bump to 1 percent. You likely won’t notice the difference in your paycheck, since it usually lines up with your yearly raise, but you will notice it in your account balance a decade from now. If your plan doesn’t have this feature, set yourself a calendar reminder to raise your contribution by 1 percent every year on your own, ideally right after a raise lands, before you get used to spending it.

Move your emergency fund into a high-yield savings account
Notebook labeled Best High-Yield Savings Accounts beside a calculator and piggy bank
Image Credit: Shutterstock

If your savings account is sitting at the same big bank you’ve used since college, it is probably earning next to nothing. The national average savings rate was 0.37 percent as of the most recent FDIC data, while the top high-yield accounts available right now pay up to roughly 5 percent APY. On a $10,000 emergency fund, that difference comes out to about $37 a year at the national average versus close to $500 a year at the top rate.

Moving your money doesn’t mean closing your old checking account or changing your direct deposit. Open a high-yield savings account online, which usually takes about ten minutes and no in-person visit, and set up a one-time transfer from your old account. Most online banks are FDIC-insured up to $250,000, so you’re not trading safety for a better rate. Leave your checking account where it is for bill paying and keep the high-yield account purely for savings you’re not touching month to month. Rates move with the Federal Reserve, so check back once or twice a year to make sure you’re still getting a competitive one.

Freeze your credit with all three bureaus
Credit cards resting on US dollar banknotes
Image Credit: Shutterstock

A credit freeze blocks lenders from pulling your credit report, which makes it much harder for someone to open a new account in your name. It has no effect on your credit score and doesn’t stop you from using the cards and loans you already have.

Federal law requires credit bureaus to place a freeze within one business day of your request, online or by phone, and free of charge. You have to contact Equifax, Experian, and TransUnion separately, since freezing one does not freeze the others. Each one takes about five minutes through the bureau’s own website. If you need to apply for a loan, a new phone plan, or an apartment later, you can lift the freeze temporarily in about the same amount of time, and the bureaus are required to do it within an hour of your request. There’s no real downside to leaving a freeze in place unless you expect to apply for new credit soon, and lifting it briefly when you do is simple enough that it’s not worth skipping this step in the meantime.

Check your credit reports every week, for free
Blue credit history note beside a calculator and financial paperwork
Image Credit: Shutterstock

Most people still think they’re only entitled to one free credit report a year, which used to be true but isn’t anymore. The pandemic-era policy that let consumers pull reports weekly from all three bureaus was made permanent in 2023, and it’s still in effect.

Go to AnnualCreditReport.com, the only site authorized under federal law to provide these reports, and pull one bureau’s report this week. Rotate through Equifax, Experian, and TransUnion over the following two weeks so you’re covering all three without doing it all at once. You’re looking for accounts you don’t recognize, balances that are wrong, or hard inquiries you didn’t authorize. None of this shows your credit score, just the underlying data that produces it, and reviewing it costs nothing and takes about ten minutes. If something looks off, you have grounds to dispute it directly with the bureau reporting it, and catching an error early is a lot less painful than catching it while you’re trying to close on a house.

Cancel subscriptions you’ve stopped using
Streaming service apps displayed on a smartphone
Image Credit: Shutterstock

The average American now spends $111 a month on subscriptions, or roughly $1,332 a year, and a chunk of that is money nobody is getting value from. The same survey found people waste about $252 a year on subscriptions they’ve forgotten they’re paying for.

Pull up your bank and credit card statements from the last two months and list every recurring charge you see. You will probably find at least one you forgot existed. Cancel anything you haven’t used in the last month, and for anything you’re on the fence about, cancel it anyway. If you miss it, you can resubscribe in under a minute, and most streaming services let you rotate on and off without losing your watch history or saved shows. If a service makes cancellation deliberately difficult, which some still do, check whether your card issuer offers a subscription management tool, since several major banks now let you cancel recurring charges straight from their app without calling anyone.

Search for unclaimed money in your name
Unclaimed money label beside US dollar bills and a blue calculator
Image Credit: Shutterstock

State treasurers are sitting on billions of dollars that belongs to real people who just never came looking for it. Nationally, nearly one in ten Americans has unclaimed property waiting for them, often because an old employer, bank, or insurer lost track of a current address.

Search every state where you’ve lived as an adult, since unclaimed property sits with the state that held it, not the state you currently live in. A free multistate search tool lets you check several states in one place, though some states only let you search their own database directly. Enter your name and any previous names you’ve gone by, including a maiden name if that applies. If something turns up, the claims process usually asks for an ID and proof of address, and payouts can take anywhere from a few weeks to a couple of months. It costs nothing to search and nothing to claim, so there’s no reason not to check, even if you’re fairly sure you don’t have anything waiting.

Automate a transfer for the day you get paid
Hand holding a smartphone with online banking account options
Image Credit: Shutterstock

Waiting until the end of the month to see what’s left over to save is a plan that depends on willpower, and willpower is an unreliable savings strategy. Moving money the day it arrives, before you have a chance to spend it, works better for almost everyone.

Set up an automatic transfer from checking to savings timed to land the same day as your paycheck, even if it’s a small amount like $25 or $50. Most banking apps let you schedule this in a few taps, and you can always adjust the amount later if it turns out to be too aggressive. The trick isn’t the size of the transfer, it’s removing the decision entirely so saving happens whether or not you remembered to think about it that week. If you get paid irregularly, as a lot of freelance and gig workers do, set the transfer as a percentage of each deposit instead of a flat dollar amount, so it scales with whatever actually comes in.

Put every card on autopay for at least the minimum
Hand holding a gold bank card beside a jeans pocket
Image Credit: Shutterstock

A missed credit card payment costs more than most people expect. The average late fee runs around $30 to $32, with some issuers charging as much as $41, and that’s before any damage to your credit score from a payment reported 30 days late.

Log into each card you carry and set up autopay for at least the minimum due, even on cards you plan to pay off in full every month. If your balance ever comes in higher than expected and you can’t cover the whole thing, autopay for the minimum still protects you from a late fee and the credit score hit, and you can pay the rest manually whenever you’re able. This takes about two minutes per card and removes the one financial mistake that’s purely about timing rather than money you don’t have. Set a calendar reminder a few days before each due date too, so you still have a chance to catch and dispute a charge before the payment goes through automatically.

Call your card issuer and ask for a lower rate
Older woman talking on a phone while using a laptop at home
Image Credit: Shutterstock

Credit card interest rates are near record highs. Accounts that carry a balance are paying an average of more than 22 percent, and issuers have more room to negotiate than most cardholders assume.

Call the number on the back of your card and ask directly whether they can lower your interest rate, especially if you’ve paid on time for the last six months to a year. Mention how long you’ve been a customer and, if it’s true, that you’ve gotten offers from other issuers. The worst outcome is a no, and plenty of calls end in a rate cut of a few percentage points with nothing more than a polite ask. If the representative can’t help, ask to be transferred to retention, since that department typically has more authority to adjust terms. This call usually takes ten to fifteen minutes, and if you carry any balance at all, even a modest rate reduction adds up to real savings over a year of interest charges.

Set up overdraft protection instead of paying the fee
Worried man holding a bank card while looking at a laptop
Image Credit: Shutterstock

Overdraft fees average about $35 per transaction, and banks still collect billions of dollars a year from them, concentrated heavily among customers who can least afford it.

Most banks offer free overdraft protection that links your checking account to a savings account or credit card, so a shortfall pulls from that linked account instead of triggering a fee. Call your bank or check your account settings online and ask to set this up, which usually takes a few minutes and no paperwork. Some banks have also started offering a small grace cushion automatically, where you won’t be charged if you’re only overdrawn by $5 or $10, so it’s worth asking what your specific bank’s policy actually is rather than assuming the worst case. If your bank still charges a steep fee with no free protection option, that alone may be a reason to look at a different checking account, since several large banks have dropped or sharply cut overdraft fees in the last few years.

Max out your HSA or FSA before the plan year ends
HSA enrollment form beside a pink piggy bank, dollar bills and a pen
Image Credit: Shutterstock

If your health plan comes with a health savings account or flexible spending account, you’re sitting on a tax break most people don’t use fully. For 2026, you can put up to $4,400 into an HSA as an individual or $8,750 for family coverage, and the health FSA limit is $3,400. Every dollar goes in before taxes, which means real savings on your tax bill.

If your employer’s open enrollment is coming up, check your current contribution rate and bump it closer to the limit if your budget allows, especially for an HSA, since that money rolls over every year and stays yours even if you change jobs. FSA money is different and typically has to be spent within the plan year or a short grace period, so if you’ve got FSA funds sitting unused, check your plan’s deadline and spend down on eligible expenses like contacts, prescriptions, or a dental cleaning before you lose it. This takes about ten minutes during enrollment and can mean hundreds of dollars in tax savings a year.

Put one recurring bill on a cash-back card, then pay it off every month
Woman reviewing paperwork with a calculator beside her laptop
Image Credit: Shutterstock

Rewards cards only help you if you actually use the rewards. Nationally, there’s an estimated $25 billion in unredeemed credit card rewards sitting in accounts, essentially free money nobody has bothered to cash in.

Pick one bill you already pay every month, like your phone, streaming, or insurance, and move it onto a no-annual-fee cash-back card instead of a debit card or bank draft. Set the card to autopay in full every month from your checking account, so you’re never carrying a balance or paying interest on it. You’re not changing how much you spend, just changing which piece of plastic the charge lands on, and the cash back accumulates with zero extra effort. Once a quarter, actually redeem the rewards instead of letting them sit, since points and cash back can expire or lose value depending on the program. This is maybe five minutes of setup and then nothing else to think about, aside from remembering to cash out periodically.

Negotiate your internet or phone bill once a year
Smiling woman talking on a phone beside her laptop
Image Credit: Shutterstock

Internet and phone bills tend to creep up quietly, usually because an introductory rate expired and nobody renegotiated. Callers who ask directly for a lower rate often save $25 to $60 a month.

Before you call, check what your provider charges new customers for the same speed or plan, since that’s your leverage. Call and mention you’re reviewing your bill because the rate has gone up, and ask whether they can match the new-customer price or move you to a better-value tier. Mention a competitor by name if there’s a real one in your area, since providers are more likely to offer a discount when they believe they might actually lose you. This call runs about fifteen to twenty minutes and is worth doing about once a year, since promotional pricing tends to expire on a cycle and your bill will creep back up again if you don’t check in periodically.

Pull your Social Security earnings statement and check it for errors
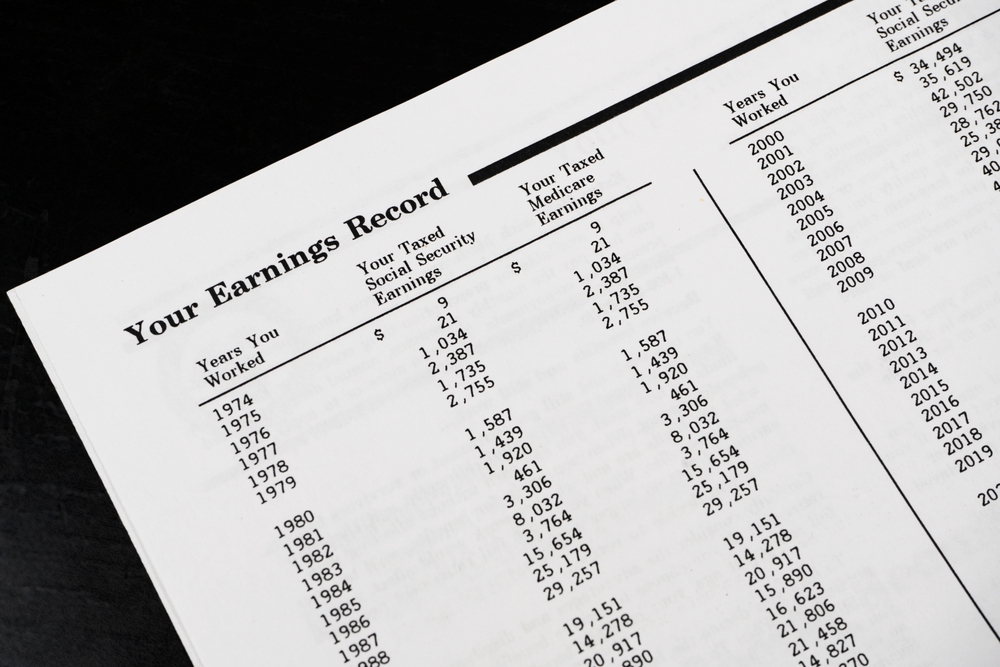
Close-up of a Social Security earnings record
Image Credit: Shutterstock

Social Security benefits rose 2.8 percent starting in January 2026, which sounds small until you remember that your eventual benefit is calculated from your full earnings history, and an error anywhere in that record can lower what you eventually collect.

Create a free account at SSA.gov’s My Social Security portal if you don’t already have one, and pull up your earnings statement. Scroll through the years listed and compare them against old pay stubs or tax returns if you have them handy, especially for years you changed jobs or worked multiple positions at once, since that’s when errors tend to slip in. If you spot a year that’s missing or shows the wrong amount, you can file a correction with documentation like a W-2 or pay stub, and it’s far easier to fix now than it will be decades from now when you’re actually filing for benefits. This takes about fifteen minutes and is worth doing every few years even if you’ve checked before, since a new job or employer error could have introduced a new mistake.

Use open enrollment to recheck what you’re actually paying for coverage
Health insurance form on a clipboard with a pen and stethoscope
Image Credit: Shutterstock

Most employers run open enrollment sometime in the fall, typically in October or November, for coverage that starts the following January, and a lot of people click through it on autopilot because they’re busy and it feels like one more task.

Take the ten minutes to actually compare this year’s plan options instead of defaulting to whatever you picked last year. Premiums, deductibles, and the list of in-network providers all change from year to year, sometimes significantly, and what was the cheapest option last year isn’t guaranteed to still be the cheapest one. If your household had a baby, got married, or had a major medical event this year, it’s worth running the numbers on a higher-premium plan with a lower deductible, since your actual costs might come out lower overall. This is also the window to revisit your HSA or FSA contribution rate and add or drop any voluntary benefits like dental, vision, or life insurance that you meant to sign up for last year and forgot.

Turn on a round-up savings or micro-investing app
Older woman holding a bank card beside her shopping cart in a supermarket
Image Credit: Shutterstock

Round-up apps take whatever change is left over when you round a purchase up to the nearest dollar and automatically move it into savings or a basic investment account. It sounds trivial, but the average user of one popular app rounds up about $43 a month without noticing it.

Link a debit or credit card you use for everyday spending, like groceries or gas, and turn on round-ups. Most apps let you multiply the round-up by two, three, or even ten times if you want to save faster once you see how painless it is. This isn’t a replacement for your emergency fund or retirement account, and the fees on some of these apps can eat into small balances, so check what you’re being charged monthly before committing. But for someone who has tried and failed to stick with manual savings transfers, automating it at the transaction level removes the friction that usually kills the habit within a few weeks.

Check if you qualify for the saver’s credit
Wooden blocks spelling IRS surrounded by rolled banknotes
Image Credit: Shutterstock

If your income falls below a certain threshold and you’re contributing to a retirement account, you may qualify for a tax credit worth up to $1,000 for individuals or $2,000 for married couples filing jointly, on top of whatever tax benefit the contribution itself already gives you.

For 2026, the income limits are $40,250 for single filers, $60,375 for heads of household, and $80,500 for married couples filing jointly. The credit is worth 10, 20, or 50 percent of your contribution depending on where your income falls within those limits, so a lower income actually produces a bigger credit. You claim it on Form 8880 when you file, and most tax software asks about retirement contributions automatically, so there’s a good chance it’s already calculating this for you without your realizing it. If you’re close to one of these income thresholds, it may be worth contributing slightly more to a 401(k) or IRA before year-end to land in a better credit bracket, since the difference in your tax bill can be worth more than the extra contribution itself.

None of this requires a financial advisor, a new budget, or a free weekend. Pick three or four from this list, set them up this week, and let them keep working in the background while you get on with everything else.

Building a great LEGO collection doesn’t require a massive budget. With a few smart strategies, single moms can significantly cut toy expenses while still giving their kids endless hours of high-quality, creative playtime.

This practical guide outlines time-saving tactics to stretch every dollar—from organizing neighborhood set swaps and sourcing cheap individual bricks online to unlocking new playtime potential from the pieces you already own.

Set a LEGO budget before browsing

A LEGO sale isn’t a saving if it pushes you past what you can afford. Set your spending limit before opening shopping apps, then include delivery in that amount. Whether you save a little each month or buy only for birthdays, choose a plan that doesn’t affect essential spending.

Build a wish list with your child and note the full price beside each set. Ask whether they’d rather have a smaller build soon or wait for a bigger favorite. Share the list when relatives ask for gift ideas.

Give new requests a few days before reaching for your wallet. Your child gets time to decide what they really want, and you get breathing room to compare prices without pressure. 

Replace missing pieces first

Before investing in a brand-new set, evaluate whether an unfinished model simply needs a handful of specific parts to be restored. Knowing where to source individual elements makes targeted repairs straightforward; for example, if you are looking to buy LEGO bricks, specialized parts suppliers like DD Bricks allow you to order exact pieces in bulk or individually to complete a build. 

To make the process efficient, write down each required piece’s shape, color, and quantity before placing an order. Start by checking the places where loose parts tend to disappear:

  • Under furniture
  • Inside other models
  • At the bottom of storage tubs

Compare the total order cost with the value of getting the model back into use. Avoid adding unrelated pieces simply to reach a delivery threshold, especially when the extras cost more than the postage.

Shop secondhand without buying more work

Used LEGO can be worth considering without a pristine box. According to research shared by the British Toy & Hobby Association, 79% of surveyed UK parents said their children had received secondhand toys. Focus on what your child will use rather than how impressive a listing looks.

Match the bundle to your builder

A child who invents houses and creatures may prefer loose bricks over a specific set. Someone determined to build a particular spaceship may find an incomplete bundle frustrating. Ask which kind of play matters before choosing.

Request clear photos and ask whether the collection contains non-LEGO pieces. For named sets, check whether figures, instructions, and essential parts are included.

Count your time as a cost

A cheap tub isn’t automatically a good deal. Sorting mixed pieces or tracking down missing parts can turn a bargain into another weekend job. Choose a manageable bundle rather than the biggest one available.

Compare collection arrangements and delivery charges, too. A smaller purchase nearby may suit your schedule better than a distant bargain.

Borrow or swap before buying again

A set your child has finished could be another family’s next rainy-day activity. Ask a trusted friend whether their child would enjoy trading builds for a week or two. Agree on a return date so everyone knows when their favorite pieces are coming home.

Take a quick photo of each set and note any missing parts before swapping. Keep borrowed bricks in a separate container to avoid a treasure hunt through your own collection later.

For building fun outside the house, check your library’s calendar for free LEGO clubs or workshops. Confirm the age range, booking requirements, and whether bricks are provided before heading out. Your child gets a fresh building experience without another purchase to squeeze into the budget.

Stretch playtime with building challenges

Give your child a building challenge instead of another shopping suggestion. A specific mission can make familiar bricks feel interesting again without requiring a new set. Keep the task playful rather than turning it into homework.

Choose challenges around your child’s interests, whether they love animals, vehicles, or imaginary worlds. Let them decide what success looks like. 

Try one of these prompts:

  • Build a bridge that holds a toy car
  • Create a creature using ten pieces
  • Design a bedroom for a favorite character

Take a photo before each creation comes apart so your child can keep a record. They could invent a name or tell you how their model works. Next time, invite them to set the challenge for you instead.

Save money on LEGO without cutting the fun

Saving money on LEGO for kids doesn’t mean saying no to every new build. It means choosing purchases carefully and making better use of the bricks already at home. A replacement piece, a thoughtful swap, or a building challenge can keep play going without another expensive set.

Pick one idea that fits your budget and energy this week. You don’t need the biggest collection to give your child plenty to build, imagine, and enjoy; just a manageable approach that works for your family.

Your newborn isn’t moving one arm normally, and the pediatrician says your baby may have Erb’s palsy. Suddenly, you’re arranging specialist appointments, worrying about recovery, and wondering how you’ll manage everything on one income. For single moms, a birth injury diagnosis brings practical questions about medical care, childcare, work, and financial stability.

The good news is that many children with Erb’s palsy recover significant movement. Others need longer-term treatment, making early medical attention and careful financial planning especially important.

Understand what Erb’s Palsy means for your baby

Erb’s palsy involves damage to nerves in the brachial plexus, which controls movement and sensation in the shoulder and arm. Symptoms can include a weak shoulder, limited arm movement, or difficulty bending the elbow.

An Erb’s palsy diagnosis doesn’t automatically mean your child will have a permanent disability. Recovery depends on the location and severity of the nerve injury.

Ask your pediatrician what movements your baby currently has, which specialists should evaluate the injury, and when recovery should be reassessed. These answers help you plan without assuming the best or worst outcome.

Don’t delay specialist appointments

When you’re the only parent available for appointments, managing medical visits alongside work can become difficult. Still, early follow-up matters because specialists need to monitor nerve recovery.

Clinical guidance recommends referral to a multidisciplinary specialist team when recovery remains incomplete at one month of age.

Ask about pediatric physical therapy, occupational therapy, and specialist evaluation. Follow the treatment team’s instructions rather than attempting exercises found online.

Keep appointment notes and request written home-care instructions. These records make it easier to communicate with childcare providers and anyone helping care for your baby.

Keep the birth records and ask questions

Some brachial plexus injuries occur during complicated deliveries involving shoulder dystocia, when a baby’s shoulder becomes stuck after the head emerges. However, an injury does not automatically establish that the delivery team made a mistake.

Families who suspect preventable harm can consult erb’s palsy lawyers in Little Rock through Birth Injury Lawyers Group to understand their options for reviewing the delivery circumstances.

Start by requesting your labor and delivery records, newborn examination notes, and subsequent specialist reports.

Document what you remember about the delivery, including any complications discussed by medical staff. An attorney and qualified medical experts can evaluate whether the care provided met accepted professional standards.

Explore Arkansas early intervention services

Families don’t necessarily have to pay privately for every developmental support service.

Arkansas operates First Connections, an early intervention program supporting eligible children from birth until their third birthday.

Children with qualifying developmental delays or diagnosed conditions may receive individualized services and family support. Evaluations are available without out-of-pocket costs, and eligible early intervention services are provided at no cost to families.

You can request an evaluation even when you’re uncertain whether your child qualifies.

For a working single mom, services delivered in familiar environments, including the home or childcare setting when appropriate, can make scheduling more manageable.

Build a budget around the real costs

Therapy bills aren’t the only expenses that can strain a single-parent household. Transportation, parking, unpaid time away from work, and specialized childcare can also affect your finances.

Keep receipts and maintain a simple record of missed work hours and medical travel expenses.

Wealthy Single Mommy’s guide to financial assistance for single moms in Arkansas covers resources involving healthcare coverage, childcare, housing, and emergency assistance.

Check your child’s eligibility for Arkansas Medicaid or ARKids First before assuming private insurance is your only option.

If medical expenses become difficult to manage, ask providers about financial assistance and payment arrangements before carrying unpaid balances on high-interest credit cards.

Understand Arkansas birth injury deadlines

Arkansas generally applies a two-year limitation period to medical malpractice claims, but birth injury cases have special rules.

Under Arkansas Code Section 16-114-203, amendments enacted in 2025 establish a fifth-birthday filing deadline for certain medical injuries occurring during childbirth.

Don’t assume you can wait until your child reaches adulthood to investigate a possible claim.

The date of the alleged injury and other circumstances can affect which legal rules apply. Because the childbirth provision is relatively recent, families should obtain case-specific advice about deadlines rather than relying on older online summaries.

Make room for your own well-being

Caring for a baby with additional medical needs can affect employment, relationships, sleep, and personal finances. Those pressures become harder when most daily responsibilities fall on one parent.

Wealthy Single Mommy’s article about raising a child with special needs as a single mom explores the practical and emotional realities families face.

Accepting help with childcare, transportation, or everyday tasks can protect your ability to keep working and care for your baby.

Erb’s palsy affects children differently, so your family’s needs may change as treatment progresses. Focus first on timely medical care, available support programs, and accurate records.

With reliable information and a realistic financial plan, you can make informed decisions about your child’s care while protecting your household’s stability.

This article provides general medical, financial, and legal information and is not individualized professional advice.

Dressing children is expensive for one reason: they grow out of everything so fast. A sweater bought in October is tight by March, shoes last about a season, and none of it wears out before it stops fitting.

The parents who spend the least on it aren’t buying the cheapest clothes, since they buy fewer things, choose what’s worth the money, and get the rest secondhand or passed along.

Here’s how that works in practice, without anybody having to track sales every weekend.

Count what’s already in the drawer

Most kids own far more clothes than they wear, and the quickest way to save money is to find out what’s already there.

Empty the drawers twice a year, at the start of fall and again in spring, and sort everything into three piles: things that fit now, things to keep for next year or a younger sibling, and things to pass on. What’s left tells you exactly what you need, which is usually much less than a shopping trip would suggest.

A rough target helps here as well, and around seven tops, four or five pairs of pants, a week of underwear and socks, two pairs of shoes and one proper coat covers most children, with a little more for anybody still having accidents and a bit less for a teenager who wears the same three things anyway.

Decide where the money should go

Not every item in a child’s wardrobe needs the same investment. Knowing where to spend a little more and where to save can make a noticeable difference to the family budget over time.

It’s generally worth prioritizing quality for items that see the most wear, particularly everyday shoes, winter coats, and clothing designed for harsh weather. A well-made pair of boots, for example, can be more economical than a cheaper alternative that needs replacing halfway through the season. This is why many parents choose kids’ Timberland boots or similarly durable options that can withstand regular use and potentially be passed down or resold once outgrown.

Save on things kids outgrow long before they wear out, like T-shirts, leggings, pajamas, school uniform items, and anything they’ll outgrow by summer; cheaper options are fine, and nobody will notice the difference by week three.

Buy secondhand for the fast-growing years

Children’s clothes are the best thing on the secondhand market, because they’re usually discarded while still in good condition.

Local selling groups, resale apps, charity shops, consignment stores, and school swap events all work, but the trick is to shop out of season. Winter coats are cheapest in April, swimwear in September, and buying a size up then costs a fraction of buying it the week you need it.

It’s also worth telling other parents you’re happy to take hand-me-downs. Most families have a bag of outgrown clothes sitting in a closet waiting for somebody to want it, and the exchange usually goes both ways.

Choose clothes that last longer than one size

A few small choices at the point of buying add months to how long something fits.

Adjustable waistbands, elasticated backs, roll-up cuffs, straps that extend, and overalls instead of fitted pants all stretch across a growth spurt. Darker colors and patterns hide stains far better than pale ones, which matters more than it sounds for anybody under six.

Buying one size up at the start of a season is the oldest trick in the book and still the best one, provided the fit isn’t so loose that the child trips over it. Check the fabric too, since a cotton blend with a little stretch survives more washes than thin pure cotton at the same price.

Make things last once they’re home

Half the clothing budget disappears into things that fell apart or got ruined rather than things that were outgrown.

Washing at lower temperatures, turning jeans inside out, air drying instead of tumbling, and treating stains the same day all add wear to a garment. Shoes last longer with a quick clean and a dry out after wet days, and a sewing kit for buttons, hems, and the odd seam saves plenty of items that would otherwise be thrown out.

Name labels are worth the few minutes they take, since a sweater lost at school is a cost nobody budgets for, and lost property is full of unnamed ones.

Shop on a schedule rather than on impulse

Most overspending on kids’ clothes happens in small amounts, picked up here and there because something was cute or on offer.

Two planned shops a year, after the drawer sort, cover the real gaps, with a small amount set aside each month for the things that break or get lost in between. End-of-season sales are where the money goes furthest, and buying the next size up then means you’re never shopping in a hurry.

Keep one short list on your phone of what each child needs, and check it before buying anything. It’s dull, and it’s the single thing that stops a wardrobe from filling up with clothes nobody chose to buy.

Let kids have a say

The cheapest garment in the house is the one that never gets worn, and that’s almost always something a child dislikes.

Giving them a choice between two or three options you’re happy with avoids that, and it works from about three years old. Older children can be given a budget for one item they have their heart set on, which teaches the arithmetic and tends to make them look after it.

Do all of this for a year, and the wardrobe ends up smaller, cheaper, and better suited to the weather. The clothes still get outgrown, because that part never changes, but far less money leaves the house along with them.

When a loved one denies memory loss, missed medications, unsafe driving, or repeated questions, family conversations can become tense quickly. Denial may protect someone from fear, embarrassment, or losing independence. It may also reflect anosognosia, a brain-related inability to recognize changes. Arguing rarely creates insight, but calm communication and practical safeguards can reduce conflict. The following steps help families respond with patience while addressing safety and medical needs.

Recognize what denial can mean

Dementia describes changes in memory, thinking, judgment, language, and daily tasks. Alzheimer’s disease is one cause, while vascular dementia and frontotemporal dementia are other types. Dementia is different from normal aging, especially when problems interfere with finances, driving, medication, cooking, or familiar routes.

Families should distinguish emotional denial from lack of insight. A person who feels frightened may reject concerns to preserve a sense of control. Someone with anosognosia may genuinely fail to recognize impairment because brain changes affect self-awareness. Both situations require patience, not accusations. Learning more about dementia denial helps families respond to the condition instead of treating resistance as stubbornness.

Track specific changes

General statements such as “Something is wrong” often invite an argument. Specific observations create a clearer basis for a medical discussion. Caregivers should record dates, examples, and safety concerns in a simple notebook or secure document.

Useful observations include:

  • Repeating the same question or story within a short period.
  • Missing bills, making duplicate payments, or giving money away.
  • Leaving appliances on or forgetting familiar cooking steps.
  • Missing medications or taking an extra dose.
  • Getting lost on a familiar route.
  • Showing sudden difficulty with bathing, dressing, or meal preparation.

A written record helps a clinician assess patterns and identify changes that family members might overlook during brief visits.

Speak without starting a fight

Choose a quiet time when the person is rested. Morning often works better than late afternoon, when fatigue and confusion can increase. Sit at eye level, use a calm voice, and discuss one concern at a time.

Lead with the person’s feelings rather than correcting every detail. “That sounds frustrating” creates more cooperation than “You forgot again.” Replace accusations with shared actions, such as “Let’s check the calendar together” or “Let’s make medication easier.”

Offer two choices instead of an open-ended demand. “Would you like to call the doctor today or tomorrow morning?” keeps them involved while moving the conversation forward. If the discussion becomes heated, pause and return later. A short break often works better than repeated explanations.

Involve a doctor early

A primary care clinician should evaluate new memory or behavior changes. Depression, medication effects, sleep problems, infections, thyroid conditions, and other health issues can affect thinking. A medical assessment also helps determine whether dementia is present and what support the person needs.

When permitted, family members should send the clinician a private written note before the appointment. The note should describe changes, timing, medication concerns, driving incidents, and effects on daily life. The person may appear capable during a short visit, so detailed observations provide useful context.

A doctor can recommend cognitive testing, medication reviews, safety guidance, and referrals. Early conversations also give families more time to discuss future care preferences while the person can participate.

Address immediate safety risks

Safety planning should match the actual risk, not an argument about whether dementia exists. If driving has become unsafe, arrange a formal driving evaluation and identify alternatives before a crisis occurs. Depending on the situation, family members may need to secure car keys, involve the clinician, or contact the state licensing authority.

Medication systems require similar attention. A locked dispenser, supervised dosing, or help from a trusted caregiver can prevent missed or repeated doses. Automatic bill payments and account alerts reduce financial errors, while reviewing online and telephone scams protects vulnerable adults.

At home, remove loose rugs, improve lighting, secure cleaning products, and add stove safeguards. Door alarms or identification bracelets can help someone who wanders. Each change should preserve dignity and independence wherever possible.

Build support before care needs grow

No one family member should carry every task alone. Relatives can divide responsibilities such as appointments, transportation, finances, meals, and regular check-ins. Predictable routines reduce daily decisions and give the person familiar reference points.

If home support no longer manages safety or personal care, families should discuss memory care or other supervised settings early. Visits, financial planning, and care assessments take time, especially when a loved one rejects the need for help. A social worker, physician, or dementia support organization can guide those conversations.

Conclusion

A loved one’s refusal to acknowledge dementia does not remove the need for action. Family members should document concrete changes, speak with empathy, involve a clinician, and address immediate risks without waiting for agreement. Small adjustments, such as supervised medications or safer transportation, protect independence while reducing preventable harm. The next practical step is to record three recent examples and share them privately with the person’s doctor before the next appointment.

After a flight, blocked ears can make conversation, music, and everyday sounds feel distant. The pressure usually comes from a temporary mismatch between cabin pressure and the pressure behind the eardrum. Most cases improve with simple actions during descent or after landing, but severe pain or lasting hearing changes need medical attention. Knowing why airplane ear occurs helps travelers respond calmly, avoid harmful ear cleaning, and prepare for future flights. The first step is recognizing the pressure problem.

Travelers who need to unclog their ears after flying should focus on pressure equalization rather than inserting objects into the ear canal. Swallowing, yawning, and gentle jaw movement help open the Eustachian tubes. A practical guide to unclog your ears after flying explains these steps alongside the reasons pressure builds during takeoff and landing. This information helps travelers choose safe relief options.

Why ears feel blocked

Air pressure changes fastest during takeoff and descent. The middle ear sits behind the eardrum, while the Eustachian tube connects it with the back of the nose and throat. Normally, that tube opens during swallowing or yawning, allowing air to move and pressure to balance. When the tube doesn’t open quickly, the eardrum stretches inward or outward, causing fullness, muffled hearing, or pain.

Risk factors

Congestion raises the risk because swollen tissue narrows the Eustachian tube. Colds, allergies, sinus inflammation, and an existing ear infection can interfere with pressure equalization. Earwax doesn’t cause cabin pressure changes, but a heavy buildup can block the ear canal and worsen the feeling of fullness. Children face added risk because their Eustachian tubes are smaller.

Symptoms to watch

Symptoms usually include fullness, pressure, muffled hearing, or mild pain in one or both ears. Some travelers notice ringing or popping as pressure shifts. Severe dizziness, sudden hearing loss, or bleeding require urgent assessment because they can indicate more than typical airplane ear. Knowing when symptoms began helps a clinician quickly assess the cause.

Relief during and after flight

The safest first response is to swallow frequently during descent. Sipping water, chewing gum, sucking on hard candy, or yawning keeps the jaw and throat moving. Travelers can also pinch the nose, close the mouth, and blow gently for one or two seconds, then stop. This Valsalva maneuver should never cause forceful pain, because excessive pressure can injure the eardrum.

A nasal decongestant can reduce swelling for travelers with congestion, but it requires label-directed use and medical advice for some conditions. Oral decongestants also carry restrictions and drug interactions. A nasal spray does not remove earwax or treat an infection. Travelers should avoid inserting cotton swabs, keys, or other objects, which can push wax deeper or damage the canal.

When to seek care

Most airplane ear symptoms improve within hours or a few days as the Eustachian tube resumes normal function. Seek medical evaluation if pain becomes severe, hearing loss persists, or fluid or blood drains from the ear. Dizziness, persistent ringing, fever, or worsening pressure also warrant prompt attention. An ear, nose, and throat specialist can inspect the eardrum and check for infection, fluid, wax, or injury.

Prevent future discomfort

Preparation starts before boarding. Travelers with a cold, allergies, or repeated airplane ear issues should discuss flight plans and congestion treatment with a clinician. During descent, staying awake makes swallowing easier than sleeping through the pressure change. Children can drink from a bottle or use a pacifier during takeoff and landing, while adults can keep water or gum available. Good hydration supports regular swallowing, but it cannot correct a blocked tube on its own.

What not to do

Forceful pressure maneuvers create more risk than relief. Travelers should not blow hard against a tightly pinched nose, insert objects into the ear, or use leftover prescription medicine without guidance. Ear candles have no established role in clearing pressure and can burn the skin. Decongestant use also requires care for people with certain heart, blood pressure, or medication concerns.

Conclusion

Airplane ear pain usually reflects a temporary pressure imbalance, not a permanent problem. Swallowing, yawning, gentle jaw movement, and a careful Valsalva maneuver often restore comfort after landing. Congestion, earwax, infection, and smaller Eustachian tubes increase the chance of symptoms. The practical next step is simple: equalize pressure during descent, avoid objects in the ear canal, and seek medical care if pain, drainage, dizziness, or hearing loss continues beyond a few days.









