scroll top

Housing, food, child care, student loans, everything feels more expensive. If you’re going to invest time and money in a career, you probably want two things: solid pay and a job that won’t disappear overnight.

You don’t have to be a surgeon or a tech executive to earn in the $80,000–$90,000 range. Plenty of steady, in-demand careers land there and come with strong job security, especially in health care, safety, and essential services.

Most of these roles do require specific training or a degree, but many offer flexible schedules, career ladders, and work you can feel good about. Here are 15 jobs that typically pay at least $80,000 per year and are expected to stay in demand for years.

Registered nurse

mature nurse in a hospital
Image Credit: Shutterstock

Registered nurses (RNs) are the backbone of hospitals, clinics, home health agencies, and outpatient centers. They monitor patients, give medications, coordinate care, and act as the main point of contact between doctors and families. Recent wage data puts average RN pay around $86,070 per year, or just over $40 per hour.

Nursing has a strong outlook because of an aging population, chronic illness, and ongoing nurse shortages in many regions. Hospitals, clinics, schools, long-term care facilities, and telehealth companies all hire RNs, and it’s common to see sign-on bonuses or shift differentials for nights and weekends.

You’ll need an associate or bachelor’s degree in nursing plus a license. From there you can specialize, emergency, pediatrics, oncology, intensive care, and more, or move into management, education, or advanced practice. If you want a people-focused job that’s needed everywhere from big cities to rural towns, nursing is one of the most reliable ways to earn in the mid-$80,000s and have your skills stay relevant.

Respiratory therapist

Respiratory therapist
Image Credit: Shutterstock

Respiratory therapists help people who have trouble breathing because of asthma, COPD, pneumonia, or other lung and heart conditions. They manage ventilators, give breathing treatments, and respond to emergencies. The median annual wage is about $80,450.

This role is critical in hospitals, especially in intensive care units and emergency departments, but respiratory therapists also work in sleep clinics, home health, and rehab centers. Demand tends to stay strong because respiratory illness is common, and older adults often need breathing support.

You typically need at least an associate degree in respiratory therapy and a state license. Many programs are two years, and you can add a bachelor’s later for management or teaching roles. If you like hands-on patient care, technology, and shift work with overtime opportunities, respiratory therapy offers a steady path into an $80,000-plus career.

Physical therapist

Physical Therapist
Image Credit: Shutterstock

Physical therapists (PTs) help people recover from injuries, surgeries, and chronic conditions so they can move better and live with less pain. They design exercise programs, perform hands-on treatments, and coach patients through the long slog of recovery. Average PT salary is just over $85,000 per year.

The job market has been strong for years because of aging baby boomers, sports injuries, and the push to treat pain without relying only on medications. PTs work in hospitals, outpatient clinics, home health, schools, and sports and orthopedic practices. Many go on to run their own clinics or work as highly paid specialists.

You’ll need a Doctor of Physical Therapy (DPT) degree and a license, which usually means about seven years of school total (bachelor’s plus DPT). It’s a lot of education, but PT can offer a long-term, flexible career with mid-five-figure starting pay that often climbs into the $80,000–$90,000 range after a few years in the field.

Dental hygienist

Dental hygienist
Image Credit: Shutterstock

Dental hygienists clean teeth, take X-rays, apply sealants and fluoride, and screen for gum disease. They’re often the person you spend the most time with during a dental visit. Average annual pay is around $89,890 in the United States.

Demand stays high because preventive dental care is a regular, ongoing need. Hygienists work mostly in dentist offices, and many enjoy part-time schedules that still pay well. Some states allow hygienists to work independently in certain settings, creating even more flexibility.

Most hygienists complete a two- or three-year associate degree program and pass licensing exams. That’s relatively short schooling for a career that commonly pays in the low- to mid-$80,000s with good benefits. If you like health care but prefer predictable hours and a calmer work environment than a hospital, this is a solid option.

Diagnostic medical sonographer

Diagnostic medical sonographer
Image Credit: Shutterstock

Diagnostic medical sonographers use ultrasound equipment to create images of organs, blood vessels, and tissues. They’re involved in everything from prenatal scans to checking for heart and liver problems. The median annual wage is about $89,340.

Sonographers work in hospitals, imaging centers, and doctor’s offices. Because ultrasound doesn’t use radiation, it’s often the first choice for many types of imaging, which helps keep demand strong. Specializing in areas like cardiac or vascular sonography can boost your earning power and make you even more in demand.

You can enter the field with a two-year associate degree or a four-year bachelor’s in diagnostic medical sonography, plus certification. The job is technical and patient-facing: you’ll be on your feet, positioning patients and operating equipment, not sitting at a computer all day. If you’re comfortable with science, anatomy, and people, this path can get you into the mid-$80,000s with room to grow.

MRI technologist
MRI technologist
Image Credit: Shutterstock

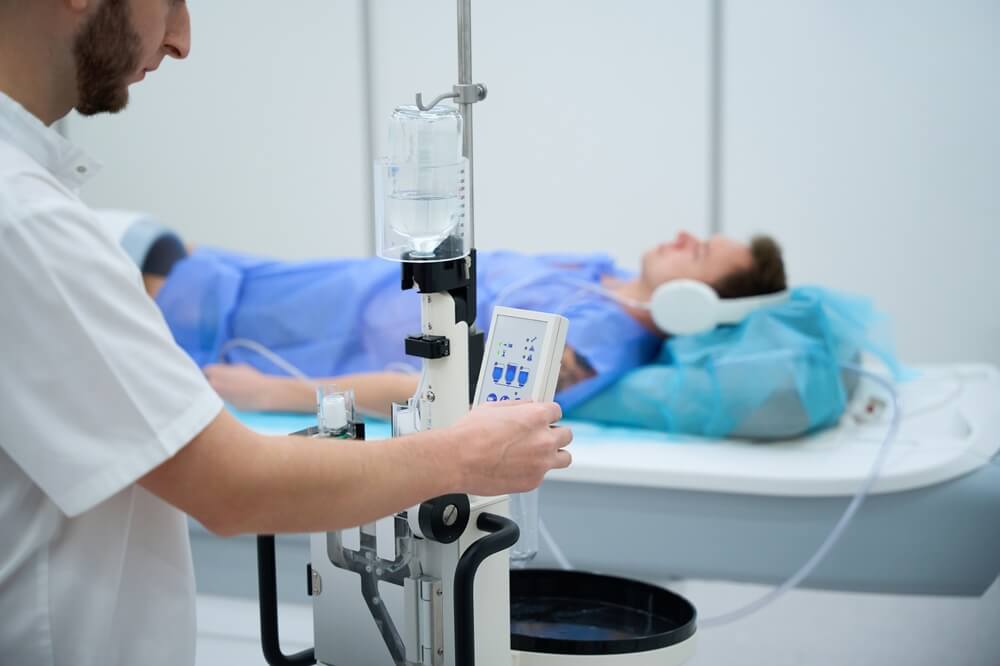
Magnetic resonance imaging (MRI) technologists operate MRI scanners to create detailed images that help diagnose everything from torn ligaments to brain tumors. They position patients, set up imaging sequences, and work closely with radiologists. Median annual pay is about $83,740.

MRI is a core tool in modern medicine, and hospitals can’t function without it. As imaging technology advances and more conditions are caught via scans, demand for experienced MRI technologists stays strong. Many technologists cross-train in CT or other modalities, which can further increase their income and job options.

Most people start with a radiologic technology program and then complete an MRI specialization, or enroll directly in an MRI technologist program. Certification is standard. If you like technology, problem-solving, and working directly with patients, this is a reliable way to earn in the low- to mid-$80,000s while doing work that’s central to patient diagnosis.

Audiologist

Audiologist
Image Credit: Shutterstock

Audiologists diagnose and treat hearing and balance disorders. They test hearing, fit and program hearing aids, and help patients manage tinnitus and other issues. Median annual pay is roughly $87,740.

Hearing loss is common as people age, and more children and adults are being screened for hearing issues earlier in life. That keeps audiologists busy in hospitals, private practices, ear-nose-throat clinics, and school systems. Hearing aid technology is also getting more sophisticated, which means patients rely on experts to get the most from their devices.

Audiologists typically need a Doctor of Audiology (AuD) degree and a state license. It’s a specialized field, but one with steady need and a lot of direct patient interaction. If you’re interested in communication, technology, and long-term relationships with patients, audiology can land you in the high-$80,000 range with strong job security.

School psychologist

School psychologist
Image Credit: Shutterstock

School psychologists support students’ mental health and learning. They assess for learning disabilities, ADHD, autism, and emotional challenges; they also consult with teachers and families about how to support each child. Median annual pay for school psychologists is about $84,940, with average earnings around $87,550.

Because schools are legally required to provide services for students with disabilities, this role is built into the system. Many districts struggle to hire enough school psychologists, especially in rural or high-need areas, which helps support pay and job security.

You’ll usually need a specialist-level degree (often called an EdS) or a doctorate in school psychology, plus state certification. In return, you get a predictable school-year schedule, decent benefits, and a salary that can climb into the upper-$80,000s with experience or leadership roles.

Occupational health and safety specialist

Hospital occupational health and safety specialist talking to dr
Image Credit: Shutterstock

Occupational health and safety specialists help keep workers safe on the job. They inspect workplaces, investigate accidents, review safety procedures, and make sure companies follow regulations. Median annual pay is around $83,910, and average pay is about $85,570.

These roles exist in manufacturing, construction, government, hospitals, and big corporate offices. Anytime there’s heavy equipment, chemicals, or large numbers of employees, someone has to be responsible for safety programs. That creates steady demand and a lot of transferability between industries.

Most specialists have a bachelor’s degree in occupational safety, industrial hygiene, environmental health, or a related field. Certifications like CSP (Certified Safety Professional) can raise your earnings. If you like the idea of preventing accidents, solving practical problems, and walking worksites instead of sitting at a desk all day, this is a reliable $80,000-plus career.

Environmental scientist

Environmental scientist
Image Credit: Shutterstock

Environmental scientists and specialists study how pollutants and other environmental issues affect people and ecosystems. They test soil and water, plan cleanup projects, and advise businesses and governments on how to reduce environmental damage. Median pay is about $80,060, while one major salary analysis puts the average around $88,006 per year.

Climate concerns, industrial pollution, and stricter environmental rules all create steady work in this field. Environmental scientists work for consulting firms, government agencies, engineering companies, and non-profits. Many specialize in areas like water resources, air quality, or waste management.

Most roles require at least a bachelor’s degree in environmental science or a related field, and some research or senior jobs prefer a master’s degree. If you care about public health and the environment, and you’re comfortable with data and fieldwork, this is a way to earn in the $80,000–$90,000 range doing work with a clear social purpose.

Fire inspector and investigator

Fire inspector
Image Credit: Shutterstock

Fire inspectors and investigators examine buildings to spot fire hazards, check that codes are followed, and investigate the cause of fires and explosions. It’s detailed work that blends inspection, interviewing, and technical analysis. Average annual pay is around $87,440, based on national wage data.

Many inspectors come from firefighting backgrounds and transition into inspection or investigation roles after years in the field. Others enter through code enforcement or engineering. Either way, communities will always need people to enforce fire codes and figure out why fires happen.

You usually need experience in fire service plus specialized training in inspection or investigation, along with state or local certifications. This work is often tied to government positions, which can mean solid benefits, pensions, and predictable raises on top of pay in the mid- to high-$80,000s.

Power plant operator

Power plant operator
Image Credit: Shutterstock

Power plant operators control and monitor the equipment that generates electricity. They adjust controls, track gauges, respond to alarms, and make sure power flows safely and reliably. Recent estimates put average pay for power plant operators around $81,990–$84,000 per year.

Keeping the lights on is not optional, so these jobs are considered essential. Power plants run 24/7, which means operators often work rotating shifts, nights, and holidays, and may earn overtime or shift differentials. As older operators retire, many utilities are looking for new talent willing to learn the systems and stay for the long term.

A high school diploma plus extensive on-the-job training was once enough, but today many employers prefer candidates with a technical associate degree, military experience, or prior work in industrial settings. If you like mechanical systems, don’t mind shift work, and want a stable role tied to core infrastructure, this is a strong $80,000-plus path.

Urban and regional planner

Urban and regional planner
Image Credit: Shutterstock

Urban and regional planners figure out how land should be used in cities and towns, where to put housing, roads, parks, and industrial areas. They analyze data, work with developers and community groups, and help write zoning rules. Median annual pay is about $83,720, with mean wages near $85,940.

As populations grow and communities try to manage traffic, housing shortages, and climate risks, planners are vital. Jobs exist in local and state government, consulting firms, and sometimes large private developers. Employment is projected to grow at least as fast as average over the next decade.

You typically need a master’s degree in urban or regional planning and may earn certification later. The work blends policy, data, and real-world tradeoffs. If you like thinking about how communities are built and want a stable government or consulting role in the mid-$80,000s, this is a good fit.

Logistician

Logistician
Image Credit: Shutterstock

Logisticians manage the flow of products, parts, or supplies from point A to point B. They coordinate purchasing, transportation, warehousing, and delivery to keep supply chains running smoothly. The median annual salary is about $80,880.

Recent years showed how critical logistics is when anything disrupts shipping or manufacturing. Businesses in retail, e-commerce, manufacturing, and government all need logisticians, and job growth is projected to be strong over the coming decade.

Most logisticians have a bachelor’s degree in supply chain management, business, or a related field. Experience with inventory systems, analytics tools, or warehouse operations can help you stand out. If you’re organized, calm under pressure, and like the idea of being the person who “makes it all move,” this field offers a clear path into the low-$80,000s with room to grow.

Line installer and repairer (electrical power)

Electrical power-line installer and repairer
Image credit: Heri Susilo via Unsplash

Electrical power-line installers and repairers build and maintain the lines that carry electricity from power plants to homes and businesses. They climb poles, work from bucket trucks, and repair lines after storms. In recent years, median annual pay for line installers and repairers has been reported around $85,420.

Utilities and contractors rely heavily on these workers, and the job cannot be done from a desk. It’s physically demanding and sometimes dangerous, but that’s part of why pay and benefits are strong. Overtime is common after storms or outages, which can push total earnings even higher.

Most people enter the field with a high school diploma and then complete an apprenticeship or employer training program. You’ll learn electrical theory, safety, and climbing skills. If you’re comfortable with heights, tools, and working outdoors in all weather, this is one of the more accessible paths to an $80,000-plus income with strong long-term demand.

Discover job hunting tips, ways to earn more, and flexible working options:

Practising job interview
Image Credit: Shutterstock

21 high-paying careers that desperately need workers, but nobody wants to do them: The pay is generous, but these jobs are searching for workers.

No background check jobs: 12 background friendly jobs: If you’re struggling to find a job due to past issues, here are jobs you can get without background checks.

15 remote jobs you probably didn’t know pay $150,000+ In 2026: High income and flexible work hours from home is not a myth — here are some remote-friendly careers.

You might have a random old cocktail shaker or glass set shoved in a box and think it’s just cute mid-century clutter. In reality, some of these pieces were made in tiny runs, by major designers, and have hardcore collectors fighting over them today.

That’s why a beat-up metal shaker or a dusty punch bowl can suddenly be a $500–$4,000 payday, if it’s the right maker and design, and it’s in decent shape.

While the allure of vintage barware is undeniable, modern innovation also brings sophisticated solutions for the aspiring or professional mixologist. For those looking to combine timeless technique with contemporary efficiency, exploring options like those found at Kobayashi Bartender Stations can elevate any home or professional setup. These modern interpretations ensure that crafting exquisite drinks remains both an art and a streamlined process.

Napier “Trombone” cocktail shaker

Napier “Trombone” cocktail shaker
Image Credit: Heritage Auctions

This is another wild Napier design from the 1930s that looks more like a sculpture than barware. The trombone shaker has a tall cylindrical body with a side handle and a long “slide” tube that gives it that musical-instrument feel. It’s usually silver-plated and stamped NAPIER with patent information on the underside.

Because far fewer of these exist than the penguin, collectors treat them almost like small works of art. In 2021, a Napier trombone shaker sold at auction for about $3,750.

If yours has heavy wear, missing parts, or a sloppy old repair, it won’t reach that level, but you’re almost certainly still in “serious cash” territory. Any trombone-form shaker with solid plating and readable markings is worth researching before you sell.

Napier clown-form cocktail shakers (pair)

Napier clown-form cocktail shakers
Image Credit: Shutterstock

Napier also made a pair of tall, clown-shaped cocktail shakers around the 1940s. These silver-plated figures have stylized clown faces and bodies, and they’re usually found as a matched pair around 12 inches tall. The bases are typically marked NAPIER with patent information.

Collectors love these because they hit two niches at once: barware and figural novelty design. A pair of clown-form Napier shakers sold in 2021 for about $4,250 at auction.

Single clowns, or pairs with plating wear or damage, can still bring strong money, often in the high hundreds. Watch for fakes: you want crisp metal details, proper Napier markings, and seams that look factory-made, not crude or filed.

Napier “Foursome” cocktail set with carrier

Napier “Foursome” cocktail set with carrier
Image Credit: Heritage Auctions

This one is a full set: four small individual shakers that sit in a wood-and-metal carrier, sometimes called a “Tantalus.” Each mini shaker has a dial on the lid listing classic cocktails, so you can set it to “Martini,” “Sidecar,” or other recipes. The bodies are typically silver-plated and marked NAPIER along with patent wording.

Because all four shakers and the carrier need to survive together, complete sets are much harder to find than single pieces. One Napier foursome set with carrier sold in 2021 for about $575 at auction.

Sets with heavy pitting, missing dials, or a damaged carrier may go for less, but still usually land well above “yard sale” prices. If your set has all four shakers, readable dials, and a solid-working caddy, you’re holding something collectors will care about.

Chase “Blue Doric” cocktail set with Viking mixer

Chase “Blue Doric” cocktail set with Viking mixer
Image Credit: Heritage Auctions

If you see bright cobalt blue glass paired with chrome, stop and look closer. Chase Brass & Copper made the “Blue Doric” cocktail set in the 1930s, with a stepped chrome tray, blue glass cups, and a tall “Viking” cocktail mixer with a chrome top. The cups and mixer often have clean, geometric lines that scream Art Deco.

Complete sets are scarce, and condition matters, chips, cloudiness, or mismatched parts will drag value down. But when all the pieces match and the chrome still shines, collectors show up. In 2021, a Blue Doric cocktail set with Viking mixer sold for about $937.50 at auction.

Even partial sets can be worth real money. A lone Viking mixer in good shape can bring strong bids on its own, especially if the glass is bright blue and the chrome lid still fits snugly.

Chase “Gaiety” chrome cocktail set

Chase “Gaiety” chrome cocktail set
Image Credit: Heritage Auctions

The Gaiety design is all streamlined chrome with colored enamel rings and a Bakelite finial. The classic set includes a tall cylindrical shaker with enamel bands and matching cordials. The bottom is usually marked with the Chase centaur logo and patent numbers.

Values bounce around depending on how complete and original the set is. A six-piece Gaiety set with shaker and glasses sold for about $375 in 2025.

Collectors pay more when the enamel bands are bright, the Bakelite finial isn’t cracked, and the chrome hasn’t been over-polished. A single Gaiety shaker can still fetch triple digits. A full set in sharp condition with multiple glasses and original tray can climb into the high hundreds.

Tiffany silver cocktail shaker with hunting scene

Tiffany silver cocktail shaker with hunting scene
Image Credit: Heritage Auctions

Not all valuable barware is mid-century. Some serious money sits in much earlier sterling silver pieces. One standout example: a late-19th-century Tiffany cocktail shaker engraved with a detailed hunting scene. It’s a tall, elegant shaker with finely etched animals and landscape, fully marked for Tiffany and sterling.

While most of us won’t casually find a Tiffany shaker in Grandma’s kitchen, it happens, especially if your family owned silver serving pieces. In 2021, a Tiffany silver cocktail shaker with hunting scene sold at auction for about $4,250.

Tiffany barware in sterling almost always has value, but engraved, figural, or rare designs can reach into the thousands. If you see the Tiffany mark on anything resembling a cocktail shaker, that’s a “get it appraised before you do anything” situation.

Gorham “artillery shell” cocktail shaker

Gorham “artillery shell” cocktail shaker
Image Credit: Heritage Auctions

This shaker looks exactly like what it sounds like: a World War I artillery shell turned into barware. Gorham’s shell shakers are tall, cylindrical, and usually made from brass and silver plate, with markings on the base like “Fac-simile eighteen pounder shrapnel shell.”

Collectors love them because they blend military history with bar culture. One artillery-shell cocktail shaker attributed to Gorham sold at auction for about $4,000 in 2021. Other examples have brought several thousand dollars in earlier sales.

Condition is crucial: dents, heavy polishing, or missing internal parts will drag the price down, but even flawed pieces can still be worth hundreds. Any shell-form shaker with military-style markings deserves a second look.

J.A. Henckels Zeppelin-form traveling bar set

J.A. Henckels Zeppelin-form traveling bar set
Image Credit: Heritage Auctions

Some of the wildest collectible barware is disguised as something else entirely. Henckels made a traveling bar in the shape of a Zeppelin airship in the late 1920s. The silver-plated “airship” opens up to reveal flasks, cups, and bar tools.

This is deep-collector territory. In 2021, a large Zeppelin-form traveling bar set sold at auction for about $4,250.

If you somehow have one of these, you’re not in “cute $100 curiosity” land, you’re in “talk to a specialist” territory. Even partial or damaged examples can be worth serious money because of how few were made and how many have been lost.

Middletown Silverware Co. sculptural cocktail shaker

Middletown Silverware Co. sculptural cocktail shaker
Image Credit: Heritage Auctions

Another sleeper piece from that same high-end market is a large sculptural cocktail shaker made by Middletown Silverware Co. in Connecticut. These shakers are tall, with bold geometric forms and multiple parts, usually silver-plated and marked with the company name and patent information.

One of these substantial shakers sold in 2021 for about $4,250

If you find a complex, multi-part silver-colored shaker with unfamiliar markings, don’t assume it’s generic. Photograph the marks and design and compare against online results, some of these obscure American makers have fierce followings and four-figure prices.

Culver “Valencia” 22k gold cocktail pitcher and glasses

Culver Valencia 7 Piece 22k Gold Cocktail Glasses & Pitcher Set
Image Credit: Nouveau-yeur via eBay

Culver’s mid-century glassware with 22k gold decoration is a huge category, but specific patterns like “Valencia” are especially desirable. Valencia pieces usually have a lattice/medallion design in gold with green accents. A typical cocktail set might include a tall pitcher and several highball or old-fashioned glasses with matching decoration.

These sets can sell in the low-to-mid hundreds when the gold is intact and not worn to dull brown. A single 1960s Culver Valencia cocktail pitcher has been offered close to $700 on the vintage market, and full sets with multiple glasses push higher.

If you find Culver pieces, look for the tiny Culver signature and run your finger lightly over the gold, it should feel raised and crisp. Faded, scratched gold lowers value, but complete matching sets still have collector appeal.

Culver “Azure” or other 22k gold cocktail sets

Culver “Azure” or other 22k gold cocktail sets
Image Credit: mic-481163 via eBay

Beyond Valencia, Culver made other 22k gold patterns that show up in valuable cocktail sets. “Azure” is one example: often blue glass with applied gold design, sometimes in a pitcher and roly poly glass combination. A nine-piece Azure set can include a double-spouted pitcher and six or more glasses, all with heavy gold decoration.

Because these were meant for everyday entertaining, complete sets are harder to find than single glasses. Clean sets with no chips and strong gold often sell in the few-hundred-dollar range, especially when all pieces match and the design is bold.

If you spot a group of matching, heavily gilded Culver pieces, resist separating them into “just glasses” and “just a pitcher.” The real money is in intact sets that tell a full story on a bar cart.

Fred Press mid-century cocktail caddy sets

Fred Press mid-century cocktail caddy set
Image Credit: Warehouse 414 via eBay

Fred Press is another name that gets mid-century barware people excited. His designs often use 22k gold in graphic patterns: suns, Trojan horses, maple leaves, and atomic motifs. A typical cocktail set might include a tall signed pitcher, a glass stirrer, and multiple matching glasses held in a brass caddy.

Some of these sets have sold in the mid-hundreds. For example, vintage Fred Press cocktail caddy sets in patterns like Sun Block have been offered around $300–$500, and similar sets have sold through vintage dealers and marketplaces in that range.

Look for the “Fred Press” signature on the glass, crisp gold that isn’t flaking, and a sturdy caddy. Even a single signed pitcher can have value, but a full, matching caddy set is what collectors really hunt for.

Murano glass decanter and cordial sets

Murano glass decanter and cordial sets
Image Credit: Freddie’s Treasure Chest via eBay

Not every valuable bar set is American. Vintage Murano decanter sets from Italy, usually a decorative decanter with five or six tiny matching glasses, can bring more than you’d guess, especially when they feature ruby or cobalt glass with applied gold and enamel flowers.

Prices vary widely depending on quality. Some everyday Murano-style sets have sold for modest amounts like £35–£40 at local auctions, while higher-end ruby crystal decanter and glass sets have sold around $100 or more.

The big money shows up in larger, more elaborate sets with heavy gold and complex shapes, but even simple ones are worth checking. If yours still has all the glasses, no chips, and rich color, you may have an easy little auction lot on your hands.

You’ve finally hit 65, you’re still working, and then the email lands: your job is ending, your hours are cut, or your company is changing plans. Suddenly that employer health coverage you’ve leaned on for years has an end date.

You know Medicare is “a thing” at 65, but the rules feel like a maze. Do you need Part A? Part B? A drug plan? Is COBRA enough? Will you get hit with lifetime penalties if you guess wrong? And what happens if HR says, “Don’t worry, you’re fine,” but they’re actually wrong?

Take a breath. You’re not the first person to lose job coverage mid-year at 65. The key is to work backward from the date your employer coverage ends and hit a few simple deadlines so you don’t have gaps or surprise penalties.

Start with one key date: when your job coverage actually ends

senior talking to nurse about medicare
Image Credit: Shutterstock

Everything in this process hangs on one date: the last day your employer plan covers you. That might be your last day of work, the end of the month, or even the end of the next month. You can’t guess. Ask HR or your benefits administrator, “What is the exact last day my group health coverage is active?” and get it in writing if you can.

There’s a big difference between “your last day at work is June 10” and “your insurance ends June 30.” Many plans cover you through the end of the month you leave. Others stop the day your employment ends. You need the day your coverage ends, not just your last shift.

Also ask whether your current plan is based on active employment or is a retiree plan. Medicare only gives you that special no-penalty window (called a Special Enrollment Period) when you lose coverage from current work, not when a retiree plan changes.

Once you know that last day, grab a calendar. You’ll plan your Medicare start date so it begins the very next day, and you’ll work backwards from there.

Know what each Medicare piece does before you sign up

Before you start forms, it helps to know what you’re actually buying.

Original Medicare has two main parts. Part A covers hospital care and some skilled nursing and is usually premium-free if you or a spouse worked enough years. Part B covers doctor visits, tests, outpatient care, and durable medical equipment, and it always has a monthly premium.

Medicare doesn’t cover most routine prescriptions on its own. That’s where Part D (a separate drug plan) comes in. You buy Part D from private companies. There’s also Medicare Advantage (Part C), which bundles Parts A and B, and usually Part D, into one plan run by a private insurer.

If you stick with Original Medicare, you can add a Medigap (supplement) policy that helps pay deductibles and co-insurance. Your best shot at getting Medigap without health questions is during the first six months after you’re both 65 or older and enrolled in Part B. After that, companies can usually deny you or charge more based on your health.

You don’t have to decide every detail today, but you do need to choose: Original Medicare with a drug plan (and maybe a supplement) or Medicare Advantage. That choice affects what you sign up for and when.

Your 8-month Special Enrollment window for Parts A and B

Medicare written on clipboard

If you worked past 65 and were covered by a group health plan from that job (or your spouse’s job), Medicare gives you a safety net: an eight-month Special Enrollment Period (SEP) for Part B and premium Part A. That SEP starts the month your employment ends or the month your group coverage ends, whichever comes first.

Important: that clock runs whether you take COBRA or a retiree plan or not. COBRA or retiree coverage does not count as active employer coverage and does not extend your eight-month SEP.

If you miss that eight-month window, you usually have to wait for the General Enrollment Period (January 1–March 31). Your coverage then starts the first of the month after you enroll, and you’ll probably pay a lifelong Part B late-enrollment penalty: 10% added to your Part B premium for every full 12 months you should have had Part B but didn’t.

So yes, you technically have eight months. But if you want no gap in coverage, you’ll usually act much sooner.

If your employer coverage ends June 30, here’s your simple timeline

Let’s use your June 30 date as an example.

If your group coverage ends June 30, you want Medicare to start July 1. When you enroll in Part A and B during a Special Enrollment Period, your coverage starts the first day of the month after you enroll.

That means:

If you enroll in May or anytime in June, you can ask for your Part A and B to start July 1, lining up right after your employer plan ends. Apply online through Social Security or call them and tell them your last day of employer coverage is June 30 and you want Medicare to begin July 1.

If you wait and enroll in July, your Medicare starts August 1. That leaves you with a full month (July) where your old plan is gone and Medicare hasn’t started. You could buy COBRA or a Marketplace plan for that gap, but you’d be paying out of pocket for something you could have avoided by enrolling a little earlier.

Your eight-month SEP for Part B runs from July through February. But if you want a smooth hand-off, circle June 30 on your calendar and aim to have your Medicare application done no later than early June.

Part D and Medicare Advantage: shorter deadlines, bigger penalties

Parts A and B give you that eight-month runway. Drug coverage does not. If you had “creditable” prescription coverage through your employer plan (most large employer plans count), you get a shorter window once that coverage ends.

For Part D, if you go 63 days or more without drug coverage that’s as good as Medicare’s standard plan, Medicare can add a penalty to your Part D premium. The penalty is 1% of the national base premium for every month you went without creditable coverage, and it’s usually permanent.

For most people losing employer coverage, there’s a 63-day Special Enrollment Period to join a Part D plan or a Medicare Advantage plan with drug coverage, starting the day after your job-based coverage (or employer drug coverage) ends.

Back to our June 30 example: your drug coverage ends June 30, so your 63-day clock starts July 1. If you enroll in a Part D or Medicare Advantage plan in June and ask it to start July 1, you’re golden. If you wait until August or September, you may be pushing into penalty territory and living with that cost every month going forward.

Why COBRA and retiree coverage don’t buy you more time

COBRA written on clipboard with calculator
Image Credit: Shutterstock

When you leave a job, HR often talks about COBRA or a retiree medical plan. These can be useful to fill short gaps, but they’re not a free pass to ignore Medicare.

Under Medicare’s rules, only coverage from current, active employment lets you delay Part B without penalty. COBRA and retiree plans are considered “former employer” coverage, not current. That means your eight-month Part B Special Enrollment Period clock starts when your actual job coverage ends, even if you elect COBRA and keep the same card.

That’s where people get burned. They think, “I’ll just stay on COBRA for 18 months and deal with Medicare later.” Eighteen months is longer than your eight-month SEP. By the time COBRA ends, your penalty-free window is over. You may have to wait for the General Enrollment Period, go months with Medicare as primary but not enrolled, and pay lifetime surcharges.

COBRA or a retiree plan can still be helpful as secondary coverage after you enroll in Medicare. Just don’t use them as a reason to delay Medicare Part B.

Watch the HSA trap when you’re near 65

If you’ve been on a high-deductible health plan at work and putting money into a Health Savings Account (HSA), there’s a sneaky trap when you move to Medicare.

Once you’re enrolled in any part of Medicare, even just premium-free Part A, you can’t keep making or receiving HSA contributions. On top of that, when you sign up for Part A after 65, Medicare can backdate your Part A coverage up to six months (but not earlier than the month you turned 65).

Any HSA contributions made during those retroactive months count as “excess contributions” and can be hit with a 6% excise tax every year until you fix them.

Simple rule of thumb: if you’re 65 or older and planning to enroll in Medicare on July 1, stop HSA contributions roughly six months before you apply so there’s no overlap. You can still spend your existing HSA on Medicare premiums (except Medigap), copays, and other allowed medical costs.

This is one of those quiet traps that can blow up a tax year, so it’s worth a calendar reminder.

Choosing between Original Medicare plus a supplement and Medicare Advantage

Medicare advantage written on notepad and American flag
Image Credit: Shutterstock

As your job coverage ends, you have two main paths.

With Original Medicare, you enroll in Parts A and B through Social Security. You add a standalone Part D drug plan. Then, if you can afford it, you consider a Medigap policy to cover some or most of the 20% that Original Medicare doesn’t pay. Your Medigap six-month “no health questions” window starts the first month you’re 65 or older and have Part B. Miss that, and you may have to pass medical underwriting later.

With Medicare Advantage, once you’re in Parts A and B, you pick a private plan that bundles hospital, medical, and usually drug coverage. Many have lower premiums than Medigap but use networks and copays instead. Losing employer coverage gives you a Special Enrollment Period to join an Advantage plan or Part D plan, generally starting when your group coverage ends. Coverage usually starts the first of the month after the plan gets your request.

You don’t have to know every detail right away. But in that month or two before your employer plan ends, you do need to at least decide: Original + Part D (plus maybe Medigap), or Advantage. As you make that decision, remember Medicare doesn’t cover everything. Costs like funeral expenses or unpaid medical bills can quickly fall on family members once employer coverage ends. Because of this risk, many seniors look into simple policies designed for these situations, such as options available through AccuQuote That decision decides which applications you fill out and which deadlines matter.

Don’t assume HR handled it, you have to enroll yourself

One of the harshest surprises people have at 65 is realizing HR doesn’t sign them up for Medicare. The company’s job is to manage the employer plan. Medicare enrollment is your job, done through Social Security or the official Medicare channels.

HR can be helpful, but they don’t always know the Medicare rules, especially around COBRA, retiree coverage, and late-enrollment penalties. Some people have been told they could “just stay on COBRA and sign up for Medicare later,” only to end up with denied claims and lifetime surcharges because Medicare should have been primary.

Before your coverage ends, talk to HR, but also talk to someone whose entire job is Medicare. The State Health Insurance Assistance Program (SHIP) offers free, unbiased Medicare counseling in every state.

Between HR and SHIP, plus your own calendar, you’ll have a much clearer picture than if you just assume “they handled it.”

If you already delayed too long, how to limit the damage

If you’re reading this and realizing your employer coverage ended a while ago and you never started Medicare, don’t freeze. Fix it.

Your first move is to contact Social Security and ask about enrolling in Part A and B as soon as possible. If you’re outside your Special Enrollment Period, you’ll likely have to use the General Enrollment Period (January 1–March 31). Under newer rules, your coverage starts the first day of the month after you enroll, instead of waiting until July like in the past.

You may owe a Part B late-enrollment penalty, and if you went more than 63 days without creditable drug coverage, a Part D penalty too. Those are frustrating, but they’re usually cheaper than going uninsured or paying full price for major care.

In the meantime, look at COBRA, Marketplace plans, or short-term coverage if you can qualify, just so you’re not walking around fully bare. Then, once Parts A and B start, add a drug plan or Advantage plan as soon as you’re allowed. Ask SHIP or a local counselor to help you map it out.

Losing job coverage at 65 in the middle of the year is stressful, but it doesn’t have to wreck your health security. Get the real end date of your employer plan. Use your eight-month window for Part B, but aim for coverage to start the day after your job plan ends. Remember that COBRA and retiree plans don’t stop the Medicare clock, and HSAs need special care.

Learn how to stretch your retirement savings and maximize your Social Security benefits for a comfortable retirement:

planning for retirement
Image Credit: Shutterstock

18 ways to stretch your retirement savings without feeling poor: The goal isn’t to pinch every penny — it’s to protect the big stuff and trim quiet leaks. Here are simple moves that keep freedom high and stress low.

18 budgeting rules that actually work for people over 50: Money habits change as we age. In this post, discover budgeting rules that fit your income and shift of priorities when you’re over 50.

15 clever strategies to maximize your Social Security benefits: Use the facts in this post to make choices that raise your monthly check for years.


Paying off your mortgage feels like crossing a finish line. You expect your monthly budget to open up, and some of it does. But then the other costs of owning a home keep creeping higher.

Property taxes, insurance, utilities, repairs, none of that stops just because the bank is off the deed. In a lot of places those costs are rising faster than incomes, especially with inflation, higher construction costs, and more extreme weather.

Property taxes that never stop

property tax written on paper with a calculator
Image Credit: Shutterstock

Your property tax bill doesn’t care whether you have a mortgage. It’s based on your home’s assessed value and your local tax rate, and both can change over time. If home values in your area jump or your city raises rates to pay for schools, police, or roadwork, your bill rises too. A simple 1.5% tax rate on a $400,000 home is $6,000 a year, and that number can grow as assessments and rates go up.

Some places have caps or senior freezes that slow how fast taxes can rise, but they don’t erase them. In high-growth or high-cost areas, homeowners worry these rising annual bills can reach thousands a year and push long-term residents out if their income doesn’t keep up.

To keep this under control, check if you qualify for any exemptions or reductions, common ones are for seniors, disabled homeowners, veterans, or a primary residence exemption. Call your local tax office and ask what relief programs exist, what the deadlines are, and what paperwork they need. If you think your assessment is way too high compared with similar homes nearby, you can also ask how to appeal it. Even a small reduction helps when this bill hits every single year.

Homeowners insurance that keeps getting more expensive

homeowners insurance
Image Credit: Shutterstock

Once your mortgage is gone, your lender stops requiring insurance, but dropping your policy is risky. At the same time, premiums have been climbing in many places thanks to higher rebuilding costs and more extreme weather. One analysis of U.S. data found that home insurance premiums rose about 8–9% in a single year, and climate-related disasters are pushing prices even higher in many regions.

If you’ve owned your home for a while, you may also find that your current coverage isn’t enough to rebuild at today’s prices. Some owners raise their coverage limits, add flood or wind coverage, or bump liability limits after paying off the house, all of which can raise the bill again.

To save, don’t auto-renew without looking around. Get quotes from at least three companies, ask about discounts for alarms, water-leak sensors, newer roofs, or bundling with auto insurance. Raise your deductible only to a level you could actually cover in an emergency. And if your area is getting hit with weather-related jumps, ask your agent to show you side-by-side options: one that keeps your current coverage, and one that trims extras so you see the trade-off clearly.

Coastal Florida owners face extra questions: wind/hail or named‑storm deductibles, separate flood insurance, and whether you need a rental endorsement if you list a 30A home on Airbnb or VRBO. For a local breakdown of limits and hurricane deductibles — plus what’s actually covered versus excluded — see this guide to Santa Rosa Beach homeowners insurance, which explains short‑term rental protections, wind and flood options, and how to compare quotes from regional carriers. It’s especially useful if your insurer has raised rates or tightened underwriting along the Gulf.

Power and heat when you’re home more

Electricity bill
Image Credit: Shutterstock

Electricity and gas bills don’t stop when the mortgage ends. In fact, they often go up as you spend more time at home, working from home, retiring, or caring for family. On top of that, energy prices have been a big part of recent cost-of-living spikes in many countries.

Even if your usage stays the same, rate hikes from your utility company show up in your bill. New fees for grid upgrades, renewable energy projects, or fuel costs can all be added in. The result is a slow drip higher, year after year, that feels like it came out of nowhere.

To fight it, start with the low-hanging fruit: switch to LED bulbs, seal drafts around doors and windows, and use programmable thermostats to avoid heating or cooling an empty house. Ask your utility if they offer free or low-cost energy audits; many will send someone out to point out leaks and bad insulation. Also check for budget billing or “level pay” programs so your winter spikes get spread across the year, making the bill easier to handle even if the total doesn’t drop.

Water, sewer, trash, and new “mystery” service fees

water dripping onto money
Image Credit: Shutterstock

Water, sewer, and trash used to be boring line items. Now they’re creeping up as cities replace aging pipes, deal with droughts or floods, and pay higher labor and fuel costs. In many places, local governments are adding new fees for stormwater, recycling, or “environmental services” on top of basic water bills.

Your usage might not change much after your mortgage is paid off, but rates can. Some utilities also charge tiered prices, so if you use more than a baseline amount, watering a yard, filling a pool, or running an in-home business, the extra gallons cost more per unit. Those tiers get adjusted over time, often without much notice.

You can’t control the base rates, but you can use less. Fix leaks quickly, install low-flow showerheads and toilets when something needs replacing, and water lawns in the early morning or evening to reduce waste. If you live somewhere that allows it, rain barrels and native plants can dramatically cut watering needs. When you see a new fee on the bill, call and ask what it is and whether there’s a cheaper service level, senior discount, or hardship program.

HOA and condo dues that only go one way

condo
Image Credit: Shutterstock

If your home is in a condo building, townhouse complex, or planned community, your mortgage payoff doesn’t touch your homeowner association (HOA) or condo fees. Those dues cover things like building insurance, shared utilities, landscaping, snow removal, pools, and long-term maintenance. As costs for those services go up, so do your dues. It’s common for HOA fees to reach hundreds of dollars a month, especially in amenity-heavy communities.

HOAs also build “reserves” to pay for big repairs like roofs, siding, and parking lots. When reserves are low or projects come in higher than planned, owners can get hit with special assessments — big one-time bills on top of regular dues. Those hits often show up years after you’ve paid off the mortgage.

You can’t opt out, but you can be proactive. Read the annual budget and reserve study, and actually go to meetings or read the minutes. If reserves look thin, assume dues or assessments will rise and plan for it. If you’re thinking of moving into a new community now, ask for at least two years of financials and minutes before you buy. Healthy reserves and a history of small, steady increases are a lot easier to live with than surprise five-figure assessments.

Routine maintenance as the house gets older

plumbing house maintenance
Image Credit: Shutterstock

A paid-off house is usually an older house. That means more wear and tear: peeling caulk, aging plumbing, sticking doors, gutter clogs, tiny leaks you don’t see until they become big ones. One nationwide estimate found homeowners spent an average of about $2,458 in a year on routine maintenance alone, over $200 a month, on things like cleaning, small repairs, HVAC servicing, and pest control.

These aren’t dramatic expenses, which is why they sneak up on people. It’s $150 for a plumber here, $300 for a dryer repair there, $500 to fix a small leak that would have cost $2,000 if you’d waited. As tradespeople raise their rates to keep up with inflation and demand, each visit costs more.

To keep this manageable, make a simple home maintenance calendar: check gutters every fall, change filters every three months, flush the water heater once a year, walk the house after big storms. Catching things early keeps them cheaper. If you’re handy, pick one basic skill to learn each year, like caulking, basic painting, or replacing faucet cartridges. And if you’re not handy, get a few trusted pros in your phone now, so you’re not calling the most expensive option in a panic later.

Big-ticket replacements: roof, HVAC, windows, and appliances

putting in new windows
Image Credit: Shutterstock

The stuff that makes your home livable does not last forever. Roofs, furnaces, air conditioners, water heaters, and major appliances all have lifespans. One estimate puts average roof replacement around $9,000, and typical appliance replacements over $2,000 each when you factor in installation.

After your mortgage is gone, you’re more likely to be in that window where everything starts aging out at once. Appliances often last 9–15 years. HVAC systems may give you 15–20 if they’ve been maintained. If your house was built or remodeled in one burst, a lot of parts will hit end-of-life together, which means higher costs packed into a few years.

You can’t time everything perfectly, but you can prepare. Look up the age of your roof, furnace, AC, and big appliances and write it down. Check typical lifespans and start a “replacement fund” where you send money every month. Some experts suggest saving 1%–4% of your home’s value each year toward maintenance and replacements; adjust that up or down based on your house and your budge, When something is clearly limping along, shop for replacements before it fully dies so you’re not stuck paying top dollar in an emergency.

Yard, tree, and snow care

man shovelling snow
Image Credit: Shutterstock

You may have handled yard work yourself when you were younger. As time goes on, health changes or simple burnout can push you toward paying for lawn mowing, leaf cleanup, tree trimming, or snow shoveling. Those services are getting more expensive too, as companies face higher fuel, equipment, and labor costs.

One estimate put lawn mowing at anywhere from $50 to $250 per visit, and tree trimming around $1,800 on average, depending on the size of the job. If you live somewhere with harsh winters, snow removal on top of that can turn your “free and clear” yard into a few hundred dollars a month in busy seasons.

To keep it in check, be selective. Maybe you hire help only for heavy jobs like major pruning, big leaf cleanups, or deep snow, and keep light mowing or shoveling for yourself. Talk to neighbors about sharing a service to get a better rate. If your lot is large, you might convert some grass to low-maintenance ground cover, gravel paths, or native plants that need less care and water. And if you’re aging in place, be honest about when it’s safer to hire out heavy ladder or chainsaw work instead of risking a fall.

Pest control and home safety checks

pest controller
Image Credit: Getty Images via Unsplash

As homes age and weather patterns change, unwanted guests, termites, ants, mice, raccoons, can find their way in more easily. Regular pest control visits, termite inspections, radon tests, chimney cleanings, and safety checks on things like gas lines and fireplaces all add to the “owning a home” column.

These costs often rise over time as more areas deal with invasive pests or tighter safety standards. For example, some cities now recommend or require more frequent inspections after certain types of storms or floods, which means more appointments and more service fees.

You don’t need every service every year, but you do need a plan. Focus on the big risks where you live: termites in warm, humid areas; radon in some colder regions; chimney and flue issues if you burn wood or gas. Ask your neighbors what problems are common on your block. Calling one trusted company for a yearly check can cost less than multiple emergency visits when a problem gets bad. If you’re on a tight budget, check whether your city or county offers free or low-cost inspections for things like radon or lead.

Internet, phone, and streaming that slowly balloon

paying Internet bill
Image Credit: Getty Images via Unsplash

Your house may be paid off, but your internet, phone, and streaming services are not. Over the last few years, many households have watched these bills creep from a basic internet-plus-phone plan to a stack of streaming subscriptions, faster speeds, and maybe a home security connection too. For a lot of owners, these “non-mortgage” bills are now one of the bigger monthly costs of living in the home.

Price hikes don’t always show up as a clear line item; they’re often baked into “promotions ending” or small annual increases. Add a new streaming service here and a faster speed tier there, and suddenly you’re paying as much as a car payment every month.

Once a year, take an hour and audit your services. List everything: internet, cell phones, any landline, each streaming service, cloud storage, and device protection plans. Cancel what you don’t use. Call your internet and phone providers and ask about cheaper plans, loyalty discounts, or bundling. If you’re on a fixed income, see if you qualify for low-income or senior internet programs in your area. The goal isn’t to get to zero, it’s to be very sure you’re only paying for what you actually need.

Home security and “smart home” extras

putting up security camera
Image Credit: Shutterstock

After paying off the house, many people get more serious about protecting it. That can mean security cameras, alarm systems, smart locks, smoke and carbon-monoxide detectors that connect to an app, and sometimes paid monitoring. These can reduce your risk and sometimes lower insurance premiums, but they also add new monthly or annual costs.

Security companies love monthly subscriptions. So do smart-home platforms. A few $10 and $20 charges for monitoring, cloud video storage, or extra sensors can add up quickly, especially when you forget what you signed up for. If you buy new gear over time, add in battery replacements and occasional upgrades.

To control this, decide what problem you’re really trying to solve. If you mainly want to know when packages arrive and keep an eye on the driveway, a simple camera with free local storage might be enough. If you’re worried about fire or carbon-monoxide, focus on hard-wired, interconnected detectors first. When you do pay for monitoring, make a note of the renewal date and compare options each year, just like insurance. Safety matters, but throwing gadgets at anxiety gets expensive fast.

Aging-in-place upgrades and accessibility fixes

grab rail installed in bathroom
Image Credit: Shutterstock

A paid-off home is often the place you want to stay as you get older. That usually means spending money to make it safer and easier to live in. Think grab bars in the bathroom, better lighting, non-slip flooring, wider doorways, ramps, and lever-style door handles. None of this is free.

Even small changes add up. A basic set of grab bars and a handheld shower might run a few hundred dollars with installation. Bigger projects, like converting a tub to a walk-in shower, adding a ramp, or moving a laundry room to the main floor, can reach into the thousands. Construction costs have risen in recent years, so labor and materials for these projects cost more than they did a decade ago.

The trick is to plan early instead of waiting for a crisis after a fall or health scare. Start with low-cost, high-impact fixes: brighter bulbs, clear walkways, grab bars, and sturdy railings. Ask your doctor or local senior center whether there are home-safety programs, grants, or low-interest loans for accessibility changes. Some nonprofit and government programs help older adults with basic modifications, especially for safety-related work.

Permits, inspections, and little local taxes you forgot about

Piggy bank with safety helmet on a pile of paperwork
Image Credit: Shutterstock

As a homeowner, you’re tied into your local government in a bunch of small ways that don’t disappear with your mortgage. Need to replace a deck, add a gable shed, or upgrade electrical work? Many cities require permits and inspections, each with fees. Some areas add annual charges for things like fire district coverage, streetlights, or stormwater management to your tax bill or utility statement.

Individually, these don’t look huge. A $150 permit here, a $90 inspection there, a $10 monthly stormwater fee you barely notice. Over time, they raise the true cost of owning the home, especially if you’re doing more projects now that you’re not sending money to a lender every month.

Before you start a project, call your city or county building department and ask exactly what permits and inspections are required and what they cost. Sometimes, doing two related projects at once lets you pay for one permit instead of two. When you look at your tax bill or utility statement, read the itemized charges; if you don’t know what something is, ask. Knowing which fees are fixed and which can be avoided helps you plan instead of getting blindsided.

Expert advice on buying a home, including buying tips, home repair strategies, and loans for single moms.

buying a home
Image Credit: Shutterstock

12 first-time home buyer grants: With a 30% increase in real estate prices over the past two years, buying your first home can be challenging. This is an updated list of home buyer grants and assistance programs for first-time homeowners.

9 low-income home loans: Affordable mortgage options and support programs available for people with modest incomes looking to buy a house.

20 resources for free home repair for low-income families: Need to make repairs in your home but don’t have the money? There is help available. In this post, you’ll learn about resources for free home repairs or low-cost home repairs

Losing your license doesn’t just mean “no driving.” It can mean no job, no way to get your kids to school, and no easy way to get to court to fix the mess that got you suspended in the first place.

Maybe you missed a court date, couldn’t afford a ticket, or fell behind on child support. Maybe it’s been so long that you honestly don’t remember what started it. Now you’re stuck choosing between driving illegally or staying home and losing income.

You are not the only one. Millions of people in the U.S. have had their licenses suspended over unpaid fines and fees, not dangerous driving. This isn’t about being a “bad driver.” It’s about money, court rules, and paperwork. The good news: there are real places to get help, and a lot of the steps are boring but doable.

Get crystal clear on why your license is suspended

Before anyone can help you, you need one thing: the exact reason your license is suspended. Not a guess, not what your cousin said. The real code and case numbers.

Start with your state DMV or driver’s license agency website. Many states let you check your license status online for free or a small fee, or you can call or visit in person. Some DMV sites even list each suspension, the date, and the “reason code,” plus which court or agency put it on your record.

Write everything down. For each suspension, note the date, the code or description, and what court or agency is listed. Common reasons include failure to pay traffic tickets, failure to appear in court, unpaid court fines and fees, child support arrears, DUI or other criminal charges, too many points, or not having insurance after a crash. Different reasons lead to very different solutions.

If the DMV record is confusing, call and ask them to walk through it with you, line by line. Stay calm and take notes. Your goal today is just to get a clean list of what’s on your record and who you need to deal with.

If you’re already suspended, here’s what to do this week

driving licences from difference states
Image Credit: Shutterstock

Think in short time frames. If your license is already suspended, your “this week” goal is to line up the right offices and see what can move fast.

First, pull your DMV record and list each court case or agency tied to your suspensions. Then, call the clerk’s office for the oldest or biggest one and say something simple like, “My license is suspended for this case number. I want to clear it. What do I need to do?” Have a pen ready; they handle calls like this all the time.

Second, ask about payment plans, ability-to-pay hearings, or license reinstatement events in that court. Many states now allow courts to reduce or restructure fines based on your income, or to clear suspensions once you’re on a plan instead of after you pay every dollar.

Third, repeat that process with each court or agency showing on your DMV record. It’s annoying, but every suspension you clear moves you one step closer to getting your license back.

If you got a warning letter but can still drive, use that grace period

If you received a notice saying “your license will be suspended on X date” but the date hasn’t hit yet, you have a little breathing room. Use it.

Call the court or agency listed on the letter before the suspension date and tell them you want to take care of the problem. Sometimes just showing up and setting a payment plan or a new court date is enough to stop the suspension from kicking in. With child support, for example, most states send several notices and offer a chance to catch up or make an agreement before they actually suspend your license.

This is the best time to ask about ability-to-pay hearings, community service alternatives, or reduced fines. Once the suspension is active, you usually have to jump through more hoops to undo it.

Match the type of debt to the right kind of help

driver getting a traffic ticket
Image Credit: Shutterstock

Not all suspensions are treated the same. Knowing what bucket your problem falls into helps you ask the right questions.

If it’s unpaid traffic tickets or missed court dates, you’re usually dealing with traffic or municipal court. These suspensions often say “failure to appear” or “failure to pay.” Courts may lift the suspension if you come in, get a new court date, or sign a payment plan, especially if this is older debt. Some states and counties have even wiped out old traffic debt and reinstated licenses in bulk when they changed the law.

If it’s court fines and fees from a criminal case, you’re likely in the criminal clerk’s office. Some states still suspend licenses for unpaid criminal court costs; others have stopped but still require you to pay what you owe. Ask about payment plans, waivers, or converting part of the debt to community service.

If it’s child support, you’ll be dealing with the child support enforcement agency, not the traffic court. All 50 states can suspend licenses for unpaid child support, but they also have ways to get your license back if you start paying again or sign a catch-up plan.

If it’s DUI or serious driving offenses, the rules are tighter. You may have to finish a court-ordered program, show proof of treatment, install an ignition interlock, and carry special “SR-22” insurance on top of paying fines and reinstatement fees. In these cases, you often need a lawyer or public defender to walk you through the exact steps for your state.

The point is: the type of suspension decides which office you call first, what you ask for, and how much flexibility they have.

Use court clerks and “ability-to-pay” hearings to get fines under control

Court clerks are not your enemy. They’re the front door to the system, and they know exactly what that judge in that courthouse expects.

When you call or go to the clerk’s office, tell them you’re trying to clear a suspension and you can’t pay everything at once. Ask if your court offers:

Ability-to-pay or hardship hearings, where a judge looks at your income and may lower fines, waive add-on fees, or switch part of what you owe to community service. Courts in many states are now required to consider someone’s ability to pay before jailing them over fines.

Affordable payment plans that will lift the license suspension once you make a first payment or sign an agreement, instead of waiting until the full balance is paid.

Bring proof of income, bills, benefits, and anything else that shows your real situation. Be honest. This isn’t about proving you’re perfect; it’s about proving you’re not refusing to pay, you just can’t pay it all right now.

Watch for amnesty days and license reinstatement events

Many courts and DMVs now run special events to help people get licenses back. They sometimes cut fines, waive collection fees, and fast-track your paperwork if you show up and deal with your debt.

In Florida, “Operation Green Light” events let people with suspended licenses pay overdue tickets and court fines and have collection fees waived, often with the chance to reinstate their license the same day. Some counties set up payment plans during these events and immediately clear suspensions once you’re on the plan.

Other states have run traffic ticket amnesty programs that cut old ticket debt, reduce interest, and reinstate licenses when people pay a lower lump sum Ohio and other states have passed laws wiping out certain debt-based suspensions and forgiving reinstatement fees for hundreds of thousands of drivers.

These programs are usually local and time-limited. To find them, search for your county name plus “license reinstatement event,” “Operation Green Light,” or “ticket amnesty,” or call your clerk’s office and ask if anything like that is planned.

man receiving legal aid
Image Credit: Shutterstock

If your license is tied up in court debt, you do not have to figure this out alone. There are lawyers and clinics whose whole job is untangling fines and fees.

Legal aid groups and pro bono programs in many states run “driver’s license restoration” projects. In North Carolina, for example, the Pro Bono Resource Center coordinates lawyers to help people lift suspensions for unpaid fines and fees and move them toward license restoration.

The paperwork can be harder than it looks, especially when an old court balance has been sent to collections or the records do not match. A lawyer’s office such as McCready Law can be one place to ask what documents the court needs before you file anything. Bring your suspension notice, payment receipts, probation paperwork and any letters from the clerk so the person helping you can see the whole timeline. Ask whether you need proof of payment, a compliance letter, or a separate reinstatement application, because those are not always the same form.

If your suspension comes from a criminal case, your old public defender’s office may be able to answer questions or point you to someone who can, especially if you still have active probation. Some law schools run clinics where supervised law students help people with traffic debt and reinstatement forms at no cost.

To find this kind of help, search “legal aid” plus your state and “driver’s license” or “fines and fees.” You can also ask the court clerk, “Are there any local programs that help people restore their licenses?” They often know the names.

Look for nonprofit “license restoration” and fines-and-fees projects

Beyond legal aid, there’s a whole world of nonprofits focused on ending debt-based suspensions. They don’t just push for new laws; many of them work directly with people one-on-one.

The Free to Drive campaign, led by groups like the Fines and Fees Justice Center, tracks license suspension laws and pushes states to end suspensions for unpaid fines and fees. In some places, these same organizations partner with courts to fix old cases, clean up records, and help people apply for reinstatement.

Search your state name plus “driver’s license restoration program,” “fines and fees justice,” or “court debt relief.” If you see a project run by a legal nonprofit, community foundation, or state bar, that’s a good sign. These folks can often tell you which judges are open to ability-to-pay hearings, what paperwork you need, and where people like you have had success locally.

Work directly with child support enforcement if that’s the issue

child support enforcement
Image Credit: Shutterstock

If your letter or DMV record mentions child support, that’s a separate problem from tickets, and it usually needs a separate plan.

All 50 states have laws that allow suspension of driver’s, professional, and other licenses for unpaid child support. The process often looks like this: you fall behind, you get notices, you’re offered a chance to set up a payment plan or attend a hearing, and only if you don’t respond do they move to suspend.

To fix it, contact your local child support office as soon as you can. Ask what amount you need to pay or what agreement you need to sign to get your license back or stop a pending suspension. In many states, if you pay a set portion of the arrears or stick to a payment plan for a few months, they can send the DMV a release so your license can be reinstated.

If you truly cannot pay what they’re asking, ask about a modification of your child support order so the monthly amount matches your current income. Legal aid or a family law clinic can often help with those forms.

Follow your state’s license restoration steps and handle reinstatement fees smartly

Clearing court cases and child support issues is only half the job. Most states also have a license restoration or reinstatement process through the DMV. That process might include reinstatement fees, forms, and sometimes a waiting period.

Some states let you pay reinstatement fees online once your court holds are lifted.Others require you to mail in a re-application fee and wait for approval, especially after a revocation or DUI. A few states, like Virginia and Ohio, have stopped suspending licenses just for unpaid court fines and costs and have even wiped out reinstatement fees for those older suspensions.

Always check your DMV’s “license reinstatement” or “driver license restoration” page and follow it step by step. If you’re short on cash, ask if your state has any reinstatement fee amnesty or reduction programs. Some will cut fees in half or more if you qualify for public assistance or meet certain income limits.

If you’re confused, bring your DMV printout, court receipts, and letters to a legal aid office or relicensing clinic. Having everything in one folder makes it much easier for someone to spot what’s missing.

Do not ignore collection letters or keep driving “just a little”

handing over driving license
Image Credit: Shutterstock

When you’re broke and stressed, it’s tempting to toss collection letters and keep driving to work “just until I fix this.” The problem is that both can make your situation worse.

If a ticket or court fine gets sent to collections, extra fees pile on top of what you already owe. Some states add 25% or more in collection costs, which can be waived only during special amnesty events

Driving on a suspended license can turn a money problem into a criminal charge. A new ticket for “driving while suspended” can mean more fines, longer suspension time, and even jail in some states. It also makes judges and clerks less patient when you finally do show up to fix things.

You’re not a bad person if you’ve driven while suspended. You did what you thought you had to. But from today forward, every mile you drive with a suspended license is a risk that can cost you more money and delay getting legal again. The sooner you start a real plan, the sooner that pressure lifts.

Keep everything in writing and check your status until you’re back on the road

Restoring a license is rarely one phone call. It’s a series of small moves: calling, going to court, setting plans, making payments, filing forms. The best thing you can do is turn this into a paper trail you control.

Keep a folder with your DMV record, every court notice, every payment receipt, and notes from phone calls. Write down the date, who you talked to, and what they said you needed to do next. Bring that folder to every appointment, every court date, every legal aid visit.

After you’ve paid what you agreed to and the court says they’ve lifted the suspension, don’t just assume everything is fixed. Check your license status again with the DMV online or by phone. Sometimes there are multiple holds from different courts, or a reinstatement fee that still needs to be paid before you are fully legal.

Maybe you’re staring down rent, daycare, and a credit card bill that never seems to shrink. A four-year degree doesn’t feel realistic, but you still need real money, not another $18-an-hour “opportunity.”

There are careers where you can get job-ready in about a year, work in the real world (not just behind a screen), and eventually earn around $50 to $60 per hour. Most of these require serious effort, licensing exams, and a couple of years of experience before you hit top pay, but the training programs themselves are measured in months, not years.

Here are 14 options that are growing, rely on human judgment and hands-on skills, and are a lot harder to replace with AI than yet another online marketing job.

Diagnostic medical sonographer

Diagnostic medical sonographer
Image Credit: Shutterstock

Diagnostic medical sonographers use ultrasound equipment to capture images of organs, blood flow, and pregnancies. It’s patient-facing work that requires steady hands, empathy, and the ability to think on your feet while you’re scanning. Recent federal wage data puts median pay around $89,020 per year, or roughly $43 per hour, and experienced sonographers, especially in high-cost cities or doing specialty or travel work, can move into the $50–$60 per hour range.

You don’t always need another full degree to get in. Several schools offer 12-month diagnostic medical sonography certificates for people who already have related college credits or a previous clinical background. Boise State, the University of Utah and others run one-year programs that combine online coursework with clinical rotations.

Demand is strong thanks to an aging population and more doctors using ultrasound instead of more invasive tests. Federal projections show sonography jobs growing faster than average over the next decade. Once licensed, you can boost your rate further by adding specialties like vascular, echo, or high-risk OB.

MRI technologist

MRI technologist
Image Credit: Shutterstock

MRI technologists run powerful magnets and imaging software to create detailed cross-sectional images of the body. You’re positioning patients, calculating protocols, and working closely with radiologists, all of which rely on human judgment. National data shows median pay for MRI techs in the low-to-mid $40s per hour, with higher-paid techs in hospitals, nights, and travel contracts often earning the equivalent of $50–$60 per hour.

If you already have a radiography or allied-health background, there are MRI certificate programs that take about 12 months or less. Schools like the College of DuPage and others offer “just under 12-month” MRI programs designed for working techs.

The job outlook is solid, imaging is used in almost every specialty now. Growth is projected to stay above average as the population ages and more conditions are diagnosed and monitored with MRI. And while software can help read scans, you still need a human on-site to run the machines safely and manage real people who are anxious, in pain, or claustrophobic.

Radiation therapist

Radiation therapist
Image Credit: Shutterstock

Radiation therapists deliver targeted radiation treatments for cancer patients. You’re operating complex linear accelerators, aligning patients to millimeter-level accuracy, and double-checking treatment plans with oncology teams. Recent government data shows a median salary of about $101,990 per year, which works out to just under $50 per hour, and many therapists in big systems earn well into the $50–$60 per hour range.

Full degree paths can take longer, but there are 12-month hospital-based radiation therapy certificate programs if you already have radiologic technology or another qualifying background. Examples include WVU Hospitals, Chattanooga State, and large cancer centers that run one-year radiation therapy schools.

Cancer care isn’t going anywhere, and radiation therapy is projected to keep growing along with other oncology specialties. This role is tightly regulated, deeply patient-facing, and depends on judgment, troubleshooting, and communication, all things that don’t hand over easily to automation.

Nuclear medicine technologist

Nuclear medicine technologist
Image Credit: Shutterstock

Nuclear medicine technologists prepare and administer small doses of radioactive materials, then use special cameras to track how organs and tissues function. It’s highly technical work with strict safety rules. Recent wage data shows median earnings around $92,500 per year, with top technologists making over $50 per hour at the 75th percentile and close to $60 per hour at the 90th percentile.

There are multiple 12-month certificate options, especially if you already have an associate degree in radiography, nursing, or another allied-health field. Programs at Chattanooga State, the University of Cincinnati, Mayo Clinic, and others offer one-year nuclear medicine technology certificates that qualify you for national board exams.

Workforce surveys show ongoing shortages and high vacancy rates in nuclear medicine, which supports strong demand and pay over the next decade.

Respiratory therapist

Respiratory therapist
Image Credit: Shutterstock

Respiratory therapists manage ventilators, breathing treatments, and critical-care support for patients with asthma, COPD, pneumonia, and other lung issues. COVID pushed this role into the spotlight, and demand hasn’t really slowed. Recent data shows median pay in the high $70,000s to low $80,000s per year, with the top 10% earning more than $100,000, roughly the $50-per-hour neighborhood for higher-paid therapists.

Some schools run one-year accelerated respiratory care programs for students who have already finished general education and science prerequisites. For example, Nebraska Methodist College partners with Mary Lanning Healthcare on a 12-month respiratory care program that gets you to licensure after three intensive semesters.

Job growth is projected to stay above average as the population ages and chronic lung disease rises. You’re working at the bedside, making real-time decisions about airways and ventilators, work that has to be done in person and coordinated with physicians and nurses. AI might help with charting and protocols, but it can’t show up at 3 a.m. to intubate a crashing patient.

Commercial pilot (non-airline)

Commercial pilot
Image Credit: Shutterstock

Commercial pilots fly charter planes, air tours, cargo flights, and medical transport. They’re responsible for flight planning, navigation, weather decisions, and passenger or cargo safety. Federal data puts median pay for commercial pilots (excluding airline captains) well into the six-figure range, roughly the equivalent of $50–$60 per hour on a full-time schedule, with experienced captains earning more.

Full airline-pilot career paths can take years, but flight schools routinely advertise programs that take 9–12 months to go from zero experience to commercial pilot with the ratings needed for entry-level jobs, especially if you train full time. Many pilots then build hours as flight instructors or in smaller operations before jumping to higher-paying charter or corporate roles.

Automation has been creeping into cockpits for decades, but regulators still require human pilots in command. You’re making judgment calls about storms, maintenance issues, and emergencies in real time, not something anyone is handing over to a chatbot.

Elevator and escalator installer and repairer

repairing an elevator
Image Credit: Shutterstock

Elevator and escalator techs install, maintain, and repair lifting systems in offices, hospitals, high-rises, and malls. It’s physical, safety-critical work that combines mechanics, hydraulics, electrical systems, and troubleshooting. Recent data shows median pay around $106,580 per year, or roughly $51 per hour, with experienced techs earning significantly more.

Most people enter through a paid apprenticeship that lasts several years, but you can get into a pre-apprenticeship or basic trades program in under 12 months. Those programs teach foundational electrical and mechanical skills that make you a stronger candidate for the full union or contractor apprenticeship.

The job outlook is very strong. Recent federal projections show employment for elevator and escalator technicians growing much faster than average over the next decade, with continued demand driven by new construction and the need to modernize older buildings.

Electrical power-line installer and repairer

Electrical power-line installer and repairer
Image credit: Heri Susilo via Unsplash

Power-line workers build and maintain the high-voltage lines that keep the lights on. They climb poles and towers, operate bucket trucks, and repair damage after storms, often in tough conditions. National numbers show median pay around the upper $80,000s per year, and many lineworkers earn the equivalent of $50–$60 per hour once you include overtime, emergency call-outs, and high-voltage premiums.

You can start with a 6–12 month lineworker training or “line school” certificate, then move into a utility or contractor apprenticeship. Many community and technical colleges offer one-year power-line technology programs that feed directly into those apprenticeships.

Job growth for electrical power-line installers is projected to be faster than average, and utilities across the country report ongoing shortages as older workers retire.

HVACR technician

HVACR technician
Image Credit: Shutterstock

HVACR technicians install and repair heating, cooling, and refrigeration systems in homes and businesses. This is hands-on diagnostic work: you’re crawling in attics, reading gauges, interpreting electrical diagrams, and talking directly with customers. While the average wage is lower, the billing rate for HVAC labor is firmly in $70–$150 per hour territory, especially for residential service and emergency calls.

Plenty of trade schools and community colleges offer 6–12 month HVACR programs that qualify you for entry-level helper or junior tech roles. A typical path is a nine-month daytime program plus an EPA refrigerant-handling certification, then on-the-job training with a contractor.

Recent federal projections show HVAC jobs growing faster than average, helped by construction, climate extremes, and stricter efficiency rules. This is deeply physical, local work that can’t be automated away or shipped overseas, broken AC still needs a human tech on the roof.

Electrician

electrician working in the home
Image Credit: Shutterstock

Electricians install, maintain, and repair wiring, panels, and electrical systems in homes, businesses, and industrial sites. You’re reading blueprints, meeting code, and solving real-time problems when “nothing works” and the electrician is the only one who can figure it out. For residential service, typical customer rates range from $50 to $130 per hour across the U.S.

Most electricians start with a 6–12 month pre-apprenticeship or electrical technology certificate at a trade school, then move into a 3–5 year paid apprenticeship. That sub-one-year program gives you the math, code basics, and safety training contractors want when they hire helpers.

Electrician jobs are projected to grow faster than average, boosted by construction, renewable energy, and EV infrastructure. Skilled trades overall are seeing lower unemployment than many white-collar fields as AI hits office jobs harder than hands-on work

Plumber

older plumber working in bathroom
Image Credit: Shutterstock

Plumbers install and repair pipes, fixtures, water heaters, gas lines, and more. It’s messy, in-demand work that touches every building with indoor plumbing. While wages vary, customer billing rates for plumbers in 2025–2026 typically run $75–$150 per hour, with many journeyman and master plumbers charging $100+ per hour for standard service and more for emergencies.

You can get started with a 6–12 month plumbing technology certificate that teaches pipefitting, codes, and basic installation, then move into a paid apprenticeship. Many community colleges and trade schools advertise “nine-month plumbing diploma” programs as a direct pipeline into local contractors. Once you’re licensed and have some years under your belt, you can bump your rate further by specializing in commercial work or starting your own shop

Job growth for plumbers is steady, and trades overall are facing worker shortages as older workers retire and fewer young people go into the field. That shortage helps support higher hourly rates, especially for people willing to handle after-hours and emergency calls.

Court reporter and real-time captioner

Court reporter
Image Credit: Shutterstock

Court reporters and captioners use specialized stenography equipment to create verbatim transcripts of trials, depositions, and live broadcasts. It’s intense, high-skill work that hinges on human listening, shorthand, and accuracy. Federal data shows median pay around $67,310 per year, but the top 10% earn more than $127,000, easily in the $50–$60 per hour equivalent range, especially when you add per-page transcript fees.

Many court-reporting schools and online programs are structured as 12-month certificates or diplomas, though it may take longer in real life to reach the necessary speed. You’ll spend months drilling shorthand, accuracy, and legal terminology, then move into internships and certification exams. Once you’re licensed, you can work for courts, agencies, or as a freelance reporter or captioner.

The job outlook is steady rather than explosive, but demand stays strong because very few people finish the programs and pass the speed tests. That shortage makes skilled reporters valuable, and AI speech-to-text still struggles with accents, crosstalk, and the legal accuracy standards required in court.

Commercial diver

commercial diver
Image Credit: Call Me Fred via Unsplash

Commercial divers work underwater on construction, inspections, welding, and repairs for bridges, ships, oil and gas projects, and offshore wind. It’s one of the most physically demanding jobs on this list, and one of the best-paid for specialists. Experienced offshore and saturation divers can earn $1,000 to $1,500 per day or more, which easily translates into $50–$60+ per hour on long projects.

Training is surprisingly short. Many HSE-approved or similar commercial diving schools run intensive 8–13 week programs that qualify you for entry-level inshore or offshore work, though you’ll still need to build hours and certifications.

The work is boom-and-bust with oil and construction cycles, but renewable energy and offshore infrastructure are adding new demand. This is about as “hands-on” as it gets, you’re literally in the water, using tools and judgment in an environment where no robot or AI is going in your place anytime soon.

Discover job hunting tips, ways to earn more, and flexible working options:

Practising job interview
Image Credit: Shutterstock

21 high-paying careers that desperately need workers, but nobody wants to do them: The pay is generous, but these jobs are searching for workers.

No background check jobs: 12 background friendly jobs: If you’re struggling to find a job due to past issues, here are jobs you can get without background checks.

15 remote jobs you probably didn’t know pay $150,000+ In 2026: High income and flexible work hours from home is not a myth — here are some remote-friendly careers.