Planning post-work living requires a realistic assessment of current household expenditures. Future retirees often struggle to pinpoint the exact monthly income needed to cover recurring bills and maintain comfort. Navigating inflation, changing healthcare fees, and shifting daily priorities creates uncertainty for long-term budget planning. Establishing clear target figures allows you to build a secure cushion for your post-career years.
Setting your baseline monthly budget
Effective retirement planning begins with identifying core living expenses. Fixed expenditures like housing costs, property taxes, utility bills, and groceries form the primary foundation of monthly cash requirements. Many financial planners suggest targeting roughly 70 to 80 percent of pre-retirement earnings to maintain standard comfort levels.
Discretionary spending patterns often shift dramatically once full-time employment ends. Travel plans, entertainment choices, and personal hobbies can boost monthly expenses during early years of freedom. Tracking current daily spending habits provides a realistic baseline for projecting future financial needs.
Setting realistic targets involves looking closely at recurring family expenses. Subscriptions, vehicle maintenance, and household goods require steady cash flow throughout the year. Categorizing these line items keeps monthly projections organized and accurate.
Evaluating potential social security benefits
Social Security payments serve as a key foundation for millions of older Americans each year. When testing numbers using an annuity calculator in your planning spreadsheet, seeing how guaranteed cash flows fit into a monthly balance sheet becomes far clearer. Having a predictable income baseline reduces financial stress during volatile market cycles.
Personal retirement accounts work alongside guaranteed government benefits to fill income gaps. Combining personal investments with federal monthly payments creates a reliable financial structure. Balancing these sources protects long-term portfolio stability.
Understanding claim timing remains a crucial component of benefit maximization. Filing at age 62 results in lower monthly checks compared to delaying until full retirement age. Taking time to map out claiming strategies yields higher lifetime payouts.
Understanding federal benefit guidelines
Federal announcements confirm that Social Security and Supplemental Security Income payouts for 75 million recipients will rise by 2.8 percent in 2026. This regular cost-of-living adjustment helps offset price increases across daily household items. Reviewing personal benefit statements gives a clear picture of expected monthly income.
Maximizing monthly government checks depends heavily on lifetime earnings history and claim age. Official agency figures indicate that individuals reaching full retirement age in 2026 can receive a maximum benefit of $4,152 per month. Workers with lower lifetime earnings or earlier filing dates receive smaller monthly distributions.
Delaying claims past full retirement age increases payouts by 8 percent annually until age 70. This automatic increase provides strong motivation for individuals remaining employed longer. Coordinating claim dates with a spouse helps optimize total household cash flow across decades.
Factoring medical costs into your plan
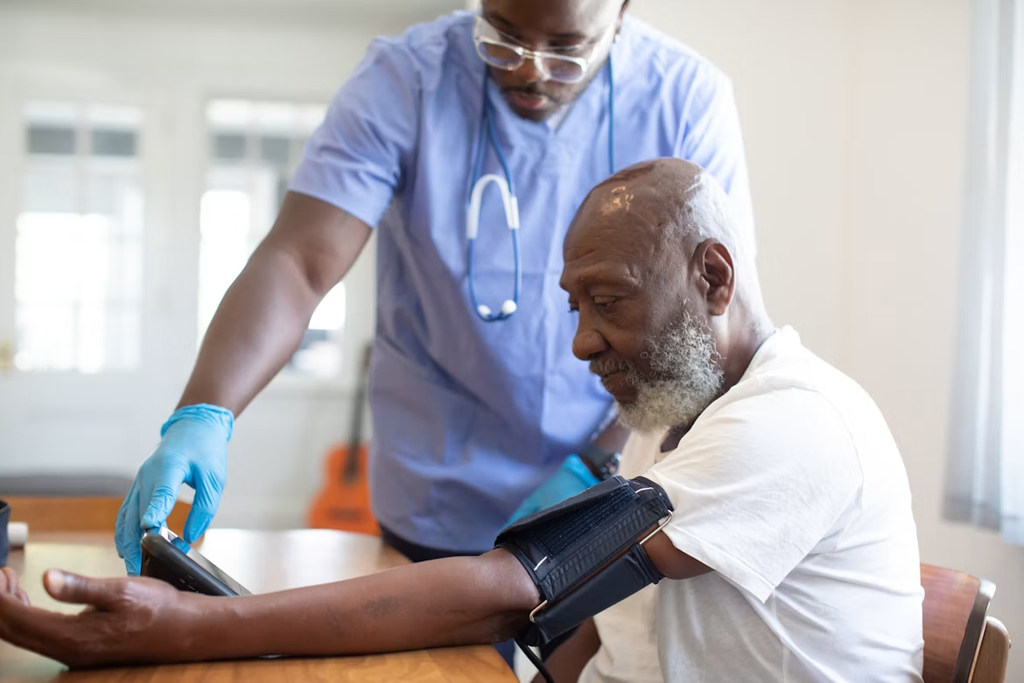
Healthcare expenses represent one of the largest variables in any post-career financial plan. Premium payments for Medicare coverage, supplemental policies, and out-of-pocket prescription costs add up quickly. Planning for medical expenses avoids sudden drains on long-term investment accounts.
A thorough medical budget ought to include space for several recurring categories:
- Medicare premiums and supplemental coverage policy fees
- Prescription medications and routine pharmacy expenses
- Out-of-pocket dental, vision, and hearing care costs
- Emergency health funds for unexpected treatments
Long-term care insurance offers another layer of financial protection against extended medical stays. Comparing coverage options early prevents unexpected care costs from eroding personal savings. Dedicating specific funds to healthcare maintains budget stability.
Managing housing expenses and mortgages
Housing remains the largest single line item for most households entering retirement. Paying off a primary mortgage before leaving employment eliminates a major monthly cash obligation. Property taxes, home insurance, and routine upkeep continue regardless of mortgage status.
Downsizing to a smaller property or relocating to an area with lower property taxes offers substantial financial relief. Some retirees choose renting to eliminate property maintenance responsibilities and unexpected repair bills. Weighing physical upkeep against potential rental adjustments helps clarify long-term residential choices.
Location plays a huge role in determining total housing expenses throughout retirement. Utility costs, regional tax rates, and home maintenance prices vary widely by region. Choosing a low-cost region stretches monthly retirement dollars significantly.
Navigating inflation and purchasing power
Rising costs for goods and services steadily erode purchasing power across long retirement spans. A comfortable monthly allowance today will purchase less ten or twenty years down the road. Factoring steady inflation rates into annual withdrawal calculations safeguards personal living standards.
Growth-oriented investments help portfolio balances keep pace with rising consumer prices. Maintaining modest exposure to broad market equities balances short-term stability with long-term capital preservation. Fixed-income assets alone struggle to match compounding cost increases.
Diversifying portfolios across asset classes mitigates inflation risks effectively. Real estate holdings, equities, and inflation-indexed bonds provide steady inflation protection. Adjusting asset allocations periodically keeps purchasing power intact.
Building alternative income streams
Relying solely on savings withdrawals can expose portfolios to market downturns early in retirement. Diversifying income channels creates extra safety buffers for monthly household budgets. Alternative cash flows provide peace of mind during extended market dips.
Consider these common income channels to supplement monthly savings:
- Dividend-paying stock portfolios or indexed funds
- Rental property cash flows or real estate investment trusts
- Part-time consulting work or flexible project roles
- Immediate or deferred payout structured investments
Side projects and consulting provide both financial rewards and social engagement. Working a few hours per week generates extra monthly spending money. Supplemental cash flow reduces reliance on portfolio withdrawals.
Creating a flexible withdrawal strategy
A structured withdrawal strategy ensures personal savings endure throughout retirement years. The classic 4 percent withdrawal guideline provides a simple starting point for annual portfolio draws. Adjusting withdrawal rates based on annual market performance preserves core portfolio capital.
Holding 12 to 24 months of living expenses in cash reserves prevents selling assets during market slumps. Cash buffers allow investment portfolios time to recover without disrupting regular income needs. Reviewing withdrawal amounts periodically keeps financial strategies on solid footing.
Dynamic withdrawal rules allow retirees to spend more during market upturns and trim back during down years. Staying flexible protects long-term wealth and maintains financial comfort. Working with financial advisors refines withdrawal calculations effectively.
Finding appropriate monthly retirement income numbers requires balancing personal lifestyle preferences with sound mathematical reality. Evaluating expected Social Security distributions, medical expenses, and housing obligations establishes clear financial targets. Adjusting savings habits today creates enduring financial independence tomorrow. Careful planning and periodic budget reviews help you enter retirement years with complete confidence in your financial future.