A prison sentence takes away a person’s freedom of movement, but it does not erase the Constitution. People held in New York jails and state prisons keep protections against cruel treatment, against retaliation for complaining, and against being denied basic medical care. The gap between that principle and daily life inside a facility is where most civil rights disputes begin.
Those disputes tend to look small at first. A request for medication goes unanswered, a staff member escalates a routine pat frisk, or a grievance disappears. Over weeks or months, the small events can add up to a legal claim, and the way the early steps are handled often shapes everything that follows.
The Eighth Amendment bars cruel and unusual punishment, and courts have read it to cover more than outright beatings. It reaches conditions of confinement, failures to protect people from other inmates, and medical neglect that rises above ordinary negligence. The Fourteenth Amendment does similar work for people held before trial, who have not been convicted of anything and cannot be punished at all.
Other protections are narrower than most people assume. A person inside can still practice a religion, send and receive legal mail, and speak to a lawyer, although prison officials may regulate those activities when they can point to a real security reason. Practical guidance from the legal community, including resources from Jacob D. Fuchsberg Law, usually starts by separating rights that officials may restrict from rights they may not touch.
The distinction matters because courts give corrections staff a good deal of room on security decisions. A lockdown, a cell search, or a transfer can be lawful even when it is unpleasant. A claim gets stronger when the facts show that staff acted out of punishment, indifference, or a wish to retaliate.
How a claim usually gets built
Most federal civil rights suits by people in custody are brought under Section 1983, which allows a lawsuit against officials who violate constitutional rights while acting for the government. The statute does not guarantee a win, and it does not erase the defenses that officials raise, such as qualified immunity. It simply opens the courthouse door for a person who can describe what happened and who did it.
As it turns out, the hardest part is often proving what staff knew. A medical neglect case, for example, depends on whether a nurse or physician understood that a serious condition existed and chose to ignore it. Records of sick call requests, medication logs, and outside hospital visits become the backbone of the case because they show timing and notice.
Witnesses matter as well, and they are harder to secure inside a facility. Other incarcerated people may have seen an assault or heard a threat, but they can be transferred or reluctant to come forward. Photographs of injuries, written statements taken early, and an accurate timeline can keep a claim from turning into one person’s word against a uniformed staff.
The grievance step that decides many cases
Federal law adds a hurdle that surprises many families. Under the Prison Litigation Reform Act, a person in custody generally has to use the facility’s internal grievance process before going to court, and courts have treated that requirement strictly. In New York State prisons, the first step is a written complaint to the grievance clerk, which is typically due within 21 days of the incident.
The process does not end with the first answer. A person who is unhappy with the outcome has to appeal through the later levels, including review at the state level, and each step has its own short deadline. A skipped appeal or a late filing can give the defense a reason to ask for dismissal before any judge looks at the facts.
All the same, the rule has limits. Courts have excused the requirement when a grievance process was not truly available, for instance when staff refused to accept a complaint or when instructions were so unclear that no ordinary person could follow them. Keeping copies of every complaint, every response, and every date is the simplest way to preserve that argument if it is ever needed.
State-court options exist alongside the federal route. Claims against the state for negligence, such as unsafe conditions or inadequate supervision, are usually heard in the Court of Claims rather than in an ordinary trial court. The choice of forum affects the defendants, the available remedies, and the procedural steps, so many cases are planned with both paths in view from the start.
Injuries, medical care, and the paper trail
Injuries inside a facility raise questions that outside accident cases rarely do. Someone hurt in an assault, a fall in a poorly maintained area, or a use of force incident may be dealing with the same staff who caused the harm and who control the medical records. Many families first learn the details through a phone call, a letter, or a rumor, and the written record is thin.
That is one reason a prisoner civil rights attorney will often ask relatives to gather information right away. The useful items include dates of injury, names or badge numbers of staff, the housing unit, and any incident or misbehavior reports issued afterward. Those reports sometimes contain statements that help the person later, even when they were written to justify discipline.
Medical care deserves separate attention. Chronic conditions such as diabetes, heart disease, or seizure disorders need regular treatment, and a missed dose or a delayed referral can cause lasting damage. When the delay follows repeated requests, the sequence of requests becomes evidence that staff were on notice.
Pressure, retaliation, and speaking up
Complaining carries risk inside a facility, and the law recognizes that. Retaliation for filing a grievance or a lawsuit is itself a constitutional violation, even if the original complaint turns out to be weak. Common examples include sudden cell moves, loss of a job assignment, a string of misbehavior tickets after a complaint, or interference with mail.
Proving retaliation takes a pattern, because a single adverse event can usually be explained as routine. Timing helps, and so does a record showing that discipline began soon after a complaint reached a particular officer. Courts look closely at whether the action would have happened anyway, so detailed dates carry real weight.
Families sometimes worry that pursuing a claim will make life harder for a loved one still inside. That worry is reasonable, which is why many lawyers talk about the order of steps: protect the person, document the problem, use the grievance system, and then decide on a lawsuit. Information on the topic from lawyers for inmates in ny often lays out that sequence so relatives know what to expect.
The people outside the walls often hold more power than they realize. They can request a copy of an incident report, ask the facility for a status check on a medical issue, and keep a written log of every phone call and visit. They can also contact the state’s oversight bodies, which receive complaints about conditions and sometimes inspect facilities.
Lawyers can help with the next layer, including public records requests and the review of grievance files. A lawyer may also speak with the person directly through approved channels, which matters when the facts are disputed. Early contact is helpful because video footage and logs are often kept for a limited time before they are overwritten.
Most of all, a family can keep the story consistent. Dates, names, and descriptions that stay the same across letters, calls, and statements are easier for a court to believe than accounts that shift as details are remembered. The paper trail built in the first few weeks is frequently the strongest evidence a case ever has.
Prison walls do change what a person can do, but they leave the basic duty of the government intact: to keep people it holds reasonably safe and to treat their serious medical needs as real. Cases move forward when someone writes things down, meets the deadlines, and keeps asking. That steady effort is usually what separates a claim that gets heard from one that never leaves the file drawer.
Navigating daily life as a single parent requires meticulous budgeting and unwavering resilience. When an unexpected collision occurs, the delicate financial balance of a single-income household can fracture instantly.
According to national traffic safety data, over 16,000 motor vehicle crashes occur every day across the United States. For a single mother juggling rent, groceries, and childcare, a sudden crash introduces severe economic instability that extends far beyond initial property damage.
Managing immediate medical bills and vehicle expenses
The arrival of emergency room bills and urgent care invoices can overwhelm household finances before physical healing even begins. Insurance deductibles and out-of-pocket medical fees create immediate cash flow crises for families operating without a financial safety net. Understanding the average economic costs associated with varying injury severities helps parents anticipate the true magnitude of post-collision medical debt. When vehicles are rendered inoperable, transportation costs spike immediately through rental cars or rideshare services needed to get children to school.
Replacing or repairing a primary vehicle forces many parents to dip into funds originally designated for household essentials. Without reliable transportation, maintaining employment or attending medical follow-up appointments becomes logistically impossible. Creditors rarely pause billing cycles while families sort out insurance disputes, intensifying the psychological burden on injured parents.
Handling lost income and childcare pressures
Recovery time following a collision often forces missed work hours and lost wages. Single mothers rarely have paid sick leave banks that can absorb weeks of forced inactivity.
Reviewing the specific financial pressures single mothers face reveals how hourly wage losses quickly snowball into unpaid utility bills and housing instability. Furthermore, physical injuries frequently prevent parents from performing routine caregiving tasks, requiring temporary paid assistance for childcare.
Navigating these complex wage loss claims requires professional insight into liability and insurance coverage limits from specialists in your area. Working alongside a knowledgeable car accident attorney in Baton Rouge helps Louisiana residents clarify how lost wages and rehabilitation expenses factor into total compensation settlements, and equivalent experts can be found in every other region of the country. Contacting these specialists sooner rather than later is advised, regardless of the case you’re facing.
To stabilize day-to-day household operations during recovery, consider implementing the following practical measures:
Document every missed shift and secure formal wage verification letters from your employer
Request itemized medical statements to track out-of-pocket expenses accurately
Explore temporary community assistance programs designed for families facing medical crises
Rebuilding household reserves after a collision
A sudden cash shock can completely deplete a family emergency fund in a matter of days. Research on how unexpected cash shocks drain household savings demonstrates that most households lack sufficient liquid reserves to cover a major unexpected crisis. Rebuilding this financial cushion requires a deliberate shift in monthly budgeting priorities until insurance settlements or legal compensation are finalized.
Negotiating payment plans with medical providers can keep accounts out of collections while claims are pending. Many healthcare systems offer hardship policies or reduced rates for patients managing uninsured balances after an accident. Taking proactive steps to pause non-essential subscription services or renegotiate utility rates can free up vital cash for groceries and rent.
Understanding legal compensation and rights
Insurance adjusters often push for rapid, low-ball settlements that fail to account for long-term medical care or ongoing rehabilitation needs. Single mothers deserve full compensation that covers future physical therapy, psychological counseling, and lost earning capacity. Experienced legal representation ensures that insurance companies do not take advantage of a vulnerable parent during a difficult recovery period. Baton Rouge residents facing aggressive insurer tactics can benefit greatly from securing local legal guidance before signing any release forms.
Failing to account for future medical complications can leave families financially stranded years later. Comprehensive injury claims cover both economic damages, like medical bills, and non-economic damages, like pain and suffering. Working with a dedicated advocate levels the playing field against corporate legal teams.
Navigating long-term disability and financial recovery options
Beyond immediate hospital stays and property damage, car accidents often introduce long-term physical limitations that impair a single mother’s earning capacity for months or even years. Spinal injuries, chronic neck strain, and traumatic brain injuries frequently require sustained physical therapy and vocational retraining. When temporary or permanent disability prevents a parent from returning to their former career, exploring Social Security disability benefits, private income protection insurance, and structured legal settlements becomes an essential line of defense.
Understanding how to bridge the financial gap between short-term medical leave and long-term recovery prevents severe disruption to household stability. Legal professionals often collaborate with financial planners and medical experts to calculate lifetime loss of earning capacity during settlement negotiations.
Securing a structured settlement can provide predictable, tax-free monthly payments that cover ongoing therapy expenses while ensuring essential household bills remain fully paid throughout the child’s developmental years. Taking time to evaluate these long-term financial options protects a single-parent household from the lasting economic ripple effects of a crash.
Restoring financial stability for your family
Overcoming the financial aftermath of a motor vehicle collision demands patience, organization, and strategic planning. By auditing insurance policies and securing proper legal representation, single mothers can reclaim their financial footing and protect their family’s future.
For more on managing household budgets, review our other blog posts on financial planning. Taking informed action today ensures long-term security for you and your children.
A locked lounge with a mini fridge is nice. A lot of offices still hand you a storage closet, or nothing. The empty still has to happen. If you are already at your desk when the clock hits, the session is not “find a room first.” It is finish it where you are sitting.
A wearable pump at your desk is the version you put on before you sit down. Both hands stay on the keyboard. There is no table of bottles and tubes. This piece is about one session you can complete, not about picking gear for the whole quarter.
Meetings move. The closet is occupied. Someone booked the only spare office for a call that runs long. Skipping because there is no lactation room is how the afternoon gets fuller and the next session hurts more. The goal today is a sealed empty you can pour from, not a perfect room.
That does not mean you pump in a hallway with no way to get the cups on. You still need a minute somewhere private to seat them. You do not need that room for the whole 15 to 20 minutes.
Put it on before you sit down
Do it in a stall, a single office, or your car in the garage before you walk to the bullpen. Center the nipple. Seat the rim. Bra over the cup. Clothes back on. Then walk to the desk and start.
Starting at the desk while you are still fiddling with the rim is how the first five minutes become a leak and a restart. If the seal hisses, fix it before you open the laptop. A crooked cup at 9 a.m. stays crooked through the stand-up.
If pumping hurts, stop and speak to your doctor or a lactation consultant. A tight workday is not a reason to ignore pain that makes you peel the cup off.
What a short desk session can cover
Count what you actually have. A 20-minute block between meetings can cover a normal empty if the cups were already on. A five-minute gap cannot, unless you started before you sat and you are only finishing.
Do not chase a huge lunchtime output by staying on the cup for 40 minutes at your desk. Two solid sessions plus the morning and evening empties is a normal full-time pattern. One heroic dump that breaks your calendar is not.
Notes on a session at an open desk come down to the same practical pieces: a seal that holds, a layer that does not show a wet spot, and a level you can stay on. This article is not about whether anyone hears the motor. It is about finishing before the next invite lands.
Pouring without a lounge
You still need somewhere to pour. A single-person bathroom, a spare office, or the car again. The desk session ends when the motor stops. The milk still needs a bag or bottle and a label.
A small cooler under the desk or in a drawer is the bridge to the work fridge. Pour, label the time, cool it promptly. Leaving a bottle on the desk while you “just” answer one Slack message is how milk gets wasted and valves dry wrong.
Wait for a lactation room
Already on at the desk
When the meeting moves
The gap disappears
The session was already running
Your hands
Both on bottles and tubes
Free for typing until pour time
Pour time
Same as the session
A separate two-minute trip
What that desk day needs from a wearable
For this kind of day, the pump has to stay in the bra through a walk from the car, a cardigan, and a video call where you are on mute. Battery for one full session plus a little left. Parts you can rinse at lunch so dried milk is not tomorrow’s hiss.
A wearable for a desk day is a longer read with more models and packing context. For one session with no room, the short list is: put it on before the desk, start low, pour somewhere you can actually do it, and fridge the milk before the afternoon runs away.
That is different from choosing how to equip an entire return-to-work month. Today you only need the session to finish.
Common questions
Can you pump at a desk with no lactation room?
Yes, if the cups are on before you sit and you have a place to pour afterward. You need privacy to get dressed, not privacy for the whole empty. The session runs at the desk. The pour happens in a stall, a spare office, or your car.
When should the cups go on?
Before you reach the open floor. Seat them where you still have space and light. A crooked rim at the desk is harder to fix without leaving the room you do not have.
How long should a desk session be?
About 15 to 20 minutes once milk is moving is a normal empty. Staying on for 40 minutes to chase ounces usually means the seal was never good, or the calendar will break anyway.
Where does the milk go?
Pour into a bag or bottle, label it, and get it into a fridge or a cold cooler. The work fridge is fine when you have access. A bottle left on the desk is not a plan.
Is this the same as picking a pump for the whole job?
No. This is how to finish one session when you are already at the desk. A longer setup question, what you wear every day and how many empties you need, is a different conversation.
Bottom line
With no lactation room, put a wearable pump on before you sit down and finish the session at the desk. Pour somewhere you can, label the milk, and cool it. One sealed empty beats waiting for a room that never opens.
Managing every household expense on a single income stretches your attention and your budget thin. Between groceries, childcare, utility bills, and unexpected school projects, you constantly monitor outgoing dollars while making sure your family stays ahead.
When traditional financial institutions chip away at your paychecks with unexpected charges, balancing your household ledger feels twice as steep. Moving your cash into streamlined digital deposit hubs allows you to shield your funds, capture higher growth, and keep every dollar working directly for your family.
Why do legacy bank charges hurt single-earner households so deeply?
Running a home solo means your cash flow absorbs every shock without a second income to soften the landing. When an unexpected expense forces your balance beneath a branch limit, legacy institutions penalize you immediately rather than offering breathing room.
Research from the National Consumer Law Center revealed that total annual overdraft and non-sufficient funds fees climbed past $12 billion across the country. That enormous extraction happens quietly through recurring penalties that strike family accounts during moments of tightest liquidity.
You feel that strain when small automatic utility debits or grocery charges trigger multiple tiered charges in a single 24-hour cycle. Those deductions trigger secondary penalties, creating an artificial deficit that pulls your attention away from parenting and routine budget planning.
How do you transition your family funds away from legacy institutions?
Moving away from a lifelong branch bank feels daunting when your direct deposits and automatic bill drafts run on autopilot. Taking a systematic, step-by-step approach simplifies the switch and keeps your family finances stable throughout the transition.
You begin by mapping out your active bills, identifying recurring monthly subscriptions, and opening your replacement account before closing legacy relationships. When establishing a dedicated emergency fund and daily liquidity buffer, taking minutes to open a checking account online allows solo parents to bypass traditional branch fees entirely. Once your modern account is fully operational, you can migrate incoming deposits with minimal paperwork.
Selecting platforms that align with solo-parent priorities
Every digital platform offers specific perks, ranging from cashback debit rewards to automated round-up savings tools. Selecting the right fit means evaluating which platform features match your household routine.
Review network access: Verify that the digital platform belongs to a nationwide fee-free automated teller machine network like Allpoint or MoneyPass for easy cash access.
Examine direct deposit requirements: Confirm whether premium interest rates or early deposit clearing require specific monthly payroll thresholds.
Check customer service channels: Prioritize hubs that offer responsive chat, phone support, and comprehensive online help centers for rapid problem resolution.
Inspect joint access options: Choose platforms that allow secondary debit cards or supervised sub-accounts if you have teenagers helping with household shopping.
How do surprise overdraft charges trap solo parents in defensive cycles?
Juggling school schedules, doctor appointments, and job deadlines demands absolute focus. When a recurring software charge or recurring insurance payment clears hours before your bi-weekly direct deposit registers, traditional accounts slap your balance with an overdraft assessment.
Data gathered by the Federal Reserve indicates that 12% of American households incurred an overdraft charge in 2025, with penalties hitting families earning under $25,000 at nearly double that frequency. The structural design of legacy branch banking extracts capital precisely when solo earners require flexible grace periods.
Paying twenty-five to thirty-five dollars for a five-dollar deficit turns a modest grocery purchase into an expensive financial blow. That penalty disrupts your confidence, forcing you into emergency calculations just to keep basic pantry items stocked.
What features make digital deposit hubs practical for single mothers?
Managing household logistics leaves zero time for sitting in branch lobbies or standing in teller lines. Digital-first platforms build their entire banking experience around mobile usability, instant notifications, and automatic safeguards that fit a busy parent’s schedule.
You control deposit allocations, bill payments, and debit card switches directly from your phone screen while preparing dinner or waiting in the school pick-up line. That immediate control removes friction and restores peace of mind to your daily routine.
Streamlining daily transactions with mobile-first convenience
Digital accounts modernize basic banking tasks by replacing paper deposit slips and physical checks with camera-based check readers and real-time transaction alerts. You know the exact second a payment clears or an invoice gets settled.
Automate recurring obligations: Schedule rent, utility payments, and childcare drafts from one dashboard so you never miss due dates or accrue late fees.
Toggle security settings: Freeze misplaced debit cards instantly from your phone app without spending thirty minutes waiting on an overseas customer service hotline.
Segment target savings: Allocate spare funds into dedicated digital sub-envelopes designed for upcoming school clothes, medical copays, or holiday travel.
Track daily spending: Receive immediate push notifications after every debit card swipe to monitor balances without opening manual spreadsheets.
How do high-yield savings spaces build your emergency cushion?
Single earners understand that unexpected mechanical trouble or dental procedures can throw monthly projections into disarray. Accumulating an emergency reserve serves as an active shield against credit card debt or high-interest payday borrowing.
Traditional branch accounts typically offer minuscule interest rates that fail to counterbalance annual cost-of-living increases. Digital hubs operate without physical real estate expenses, passing their operational savings back to account holders through competitive annual percentage yields on basic liquidity.
Turning idle balances into active income streams
When your primary deposit accounts yield competitive rates, your reserve cash produces modest passive income each month. That interest compounds continuously, accelerating your progress toward a three-month safety cushion without requiring extra gig work.
Watching your cash balance grow by meaningful dollar increments every month reinforces healthy saving habits. You transform your bank account from a passive holding tank into an active tool for long-term household wealth.
How does financial regulatory reform support digital banking transitions?
Consumer advocates and federal regulators continuously monitor financial institutions to expose practices that drain working-class family resources. Increased oversight creates broader accountability across the consumer finance market.
An analysis by the Consumer Financial Protection Bureau projected that capping excessive bank penalties could save fee-paying American households an average of $225 annually. Those savings provide single mothers with additional cash to direct toward retirement contributions, after-school activities, or emergency reserves.
Understanding changing rules around convenience charges
Federal oversight has encouraged transparent digital platforms to build competitive advantages around zero-penalty policies. Modern hubs demonstrate that financial institutions can operate profitably without relying on surprise account deductions.
Knowing your rights under federal electronic fund transfer regulations empowers you to reject predatory fee structures. You deserve banking services that protect your earnings rather than capitalizing on short-term timing mismatches.
Image Credit: Bethany Beck via Unsplash
Embracing digital banking tools gives you clean transparency, reliable liquidity buffers, and absolute control over your money. Eliminating punitive fee barriers allows you to build a secure financial foundation that serves your family for years to come.
The cabinet above the refrigerator in a lot of family homes holds the same quiet mess: a mismatched pile of bowls, a few chipped mugs, a percolator nobody has plugged in for decades. Somewhere in that pile there may be a piece of 1960s kitchen history that people now pay real money for.
Most of what came out of 1960s kitchens is still cheap, and plenty of it is just old. But a smaller group of patterns, appliances and cookware has built a following, and a clean example of the right one can bring anywhere from $30 to a few hundred dollars. The trick is knowing which piece you are holding.
Condition decides almost everything. Worn-off patterns, chips, missing lids and cracked parts turn a $200 find into a $20 one, and later reissues of several of these designs are easy to confuse with the real thing. Start with the bottom of each piece, because that is where the maker’s mark and the clues to its age usually are.
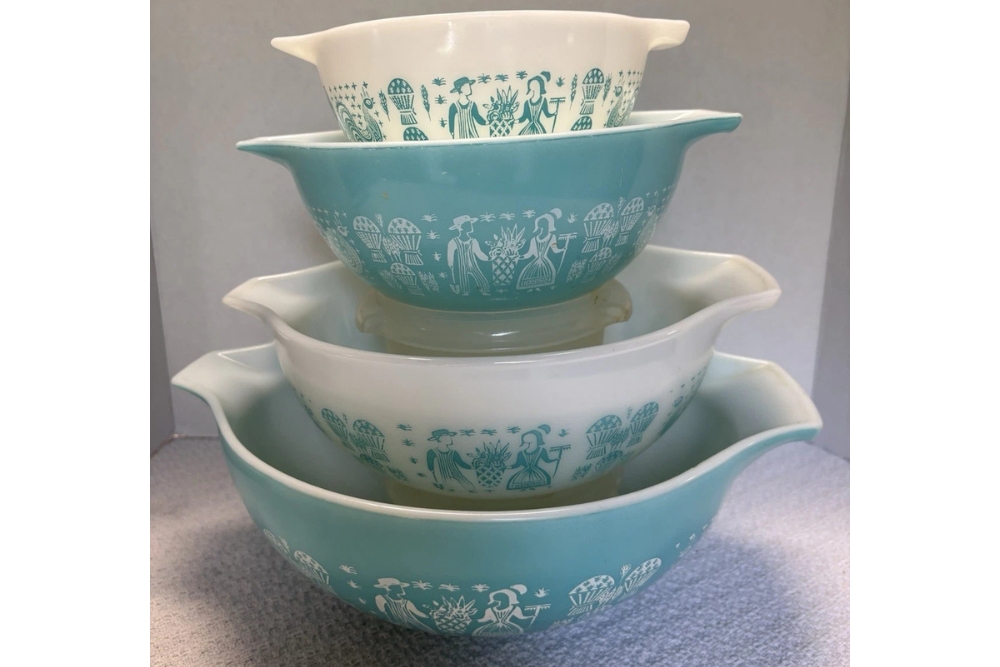
If your mom or grandmother baked in the 1960s, one of these may have lived on her counter: a stack of nesting bowls with a turquoise pattern on white glass. Pyrex made Butterprint from 1957 to 1968, and a complete four-bowl set in clean condition typically runs $175 to $275. A never-used three-bowl set can reach about $280.
The print is where the money is. Years of dishwasher cycles leave it gray, faded and scratched, and a set in that shape is worth a fraction of those numbers. Chips on the rims and on the pouring spouts of the Cinderella-style bowls cut the price too. A short set is the most common problem, because one bowl usually got broken or given away decades ago. Set the bowls side by side and make sure the turquoise matches.
Flip each bowl over and look for PYREX in all capital letters, the mark on older production. Newer Pyrex with a lowercase logo is a different product, and a single heavily used bowl with a worn print is worth much less than a matched set.
2. Fiesta medium green dinnerware
image credit: peppersantiques via eBay
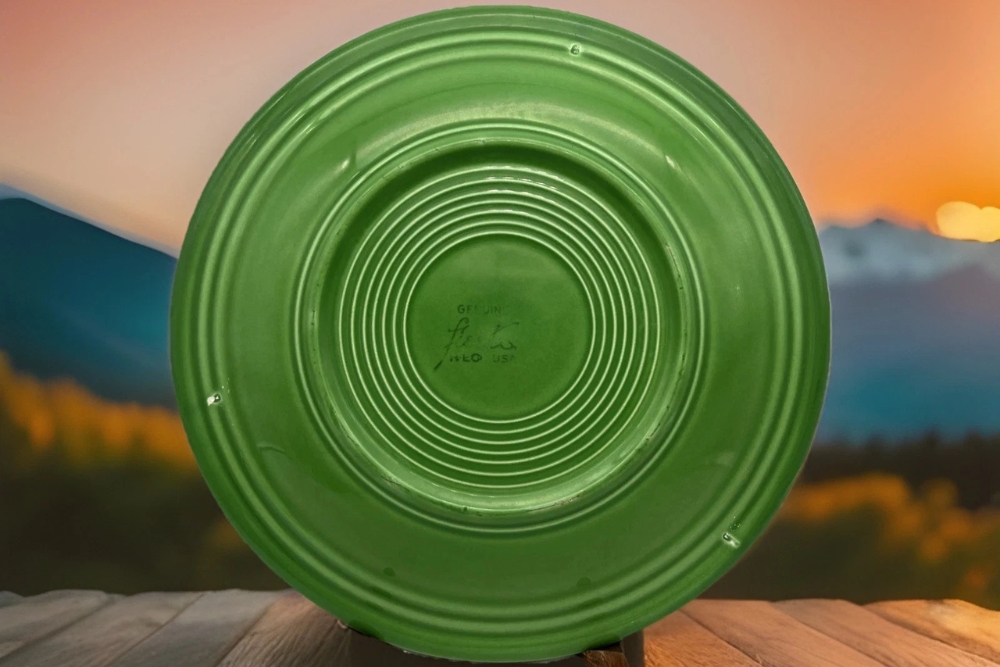
Homer Laughlin’s original Fiesta ran for decades, and the green that came near the end of that run is the one collectors chase hardest. Medium green was made in reduced amounts, which makes it the most prized color of the vintage line. Plates in the shade go for $55 to $100, a pair of salt and pepper shakers with their corks runs about $72, and a ring-handle mug lands near $40. A clean teapot can climb to $475, and cream soup bowls in this green are some of the most wanted pieces of all.
Check the bottom for the Fiesta mark, then look hard at the glaze. Chips on rims and footrings, fine cracks called crazing, and gray utensil marks across the middle of plates all pull the price down. Homer Laughlin relaunched Fiesta in 1986, and the newer pieces come in a different range of colors, so a green plate with a modern look is not the same thing.
Plain cups and saucers in this color bring much less than plates and serving pieces, so a full place setting is worth more than the sum of odd leftovers.
3. Revere Ware copper-bottom pots from before 1968
image credit: mikejboxingblackburn via eBay
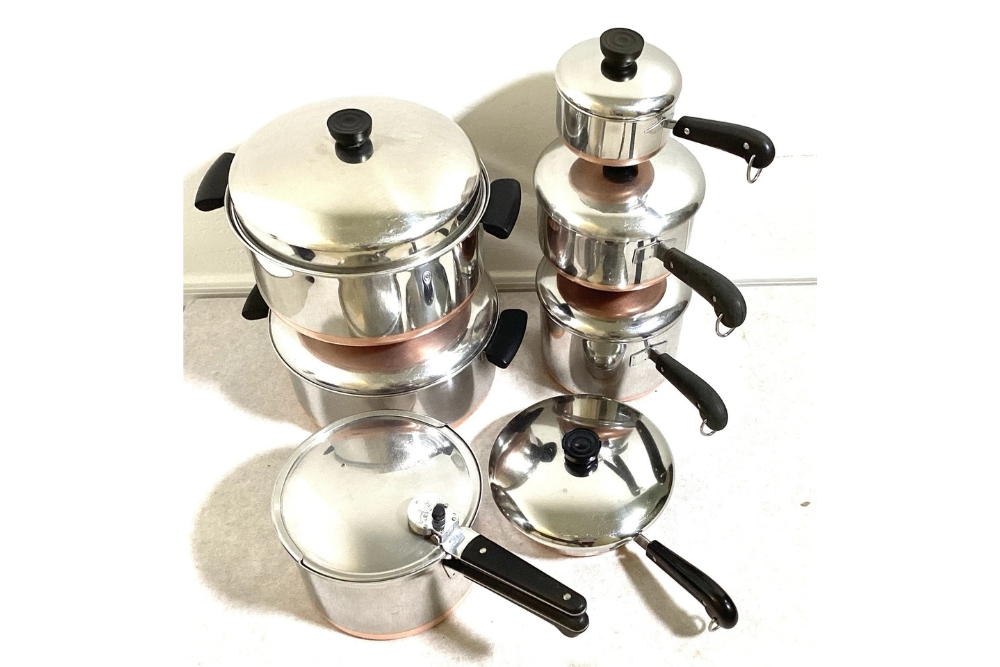
That mismatched set of pots in the back of the cabinet may be worth more than the nonstick pan beside it. Revere Ware made before 1968 has a left-facing Revere silhouette inside a two-line circle stamped on the bottom, a mark that was dropped after that year. Single pieces like a skillet or small stock pot run $30 to $50, and a big 12 to 16 quart stock pot goes for $110 to $120.
Matched sets are where the numbers get better. A 14-piece set runs about $190 to $200, a 16-piece set around $325, and a 20-piece set climbs to roughly $390.
Check the stamp on every pot and lid, because sets labeled vintage often mix older pieces with later ones, and later pieces made overseas are worth much less. Copper bottoms can look dull or stained and still sell fine. Dents, wobbly handles, warped bases and lids that do not belong to the pot are what pull the price down, and a lone pot with a worn stamp is a $30 item at best.
4. McCoy Coalby black cat cookie jar
image credit: nomad_treasures86 via eBay
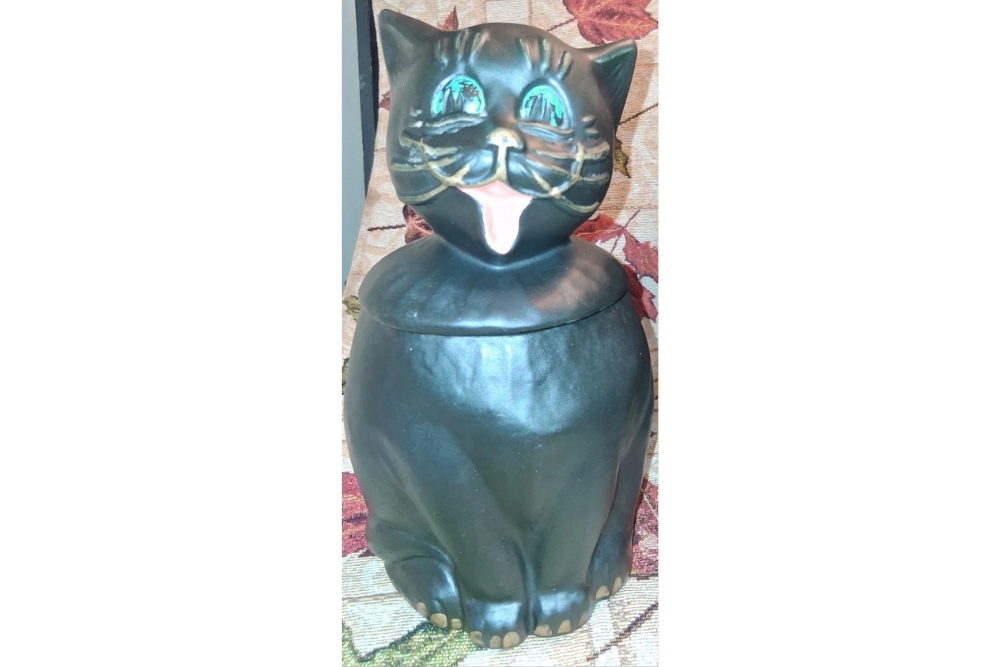
The Coalby cookie jar had a short run. McCoy made it in 1967 and 1968, and that brief production is a big part of why it holds its price. A jar in good shape typically goes for $100 to $280, with worn or chipped examples at the bottom and clean ones at the top.
The marks are easy to check. Turn it over and look for USA and the mold number 207 pressed into the bottom. The jar stands about 11 inches tall, feels weighted, and has a muted, non-shiny glaze with sharp raised whiskers and eyebrows. An unglazed ring of clay on the base is normal for the original.
McCoy pottery has been copied, and reproductions run at least six percent smaller and lighter than the real thing, so bring a tape measure if you are paying real money. The lid should fit well with no repairs. Chips on the ears, a cracked lid rim or a jar with a worn glaze sell for far less than a clean one.
5. Heath Ceramics Coupe dinner plates
image credit: serious_coder via eBay
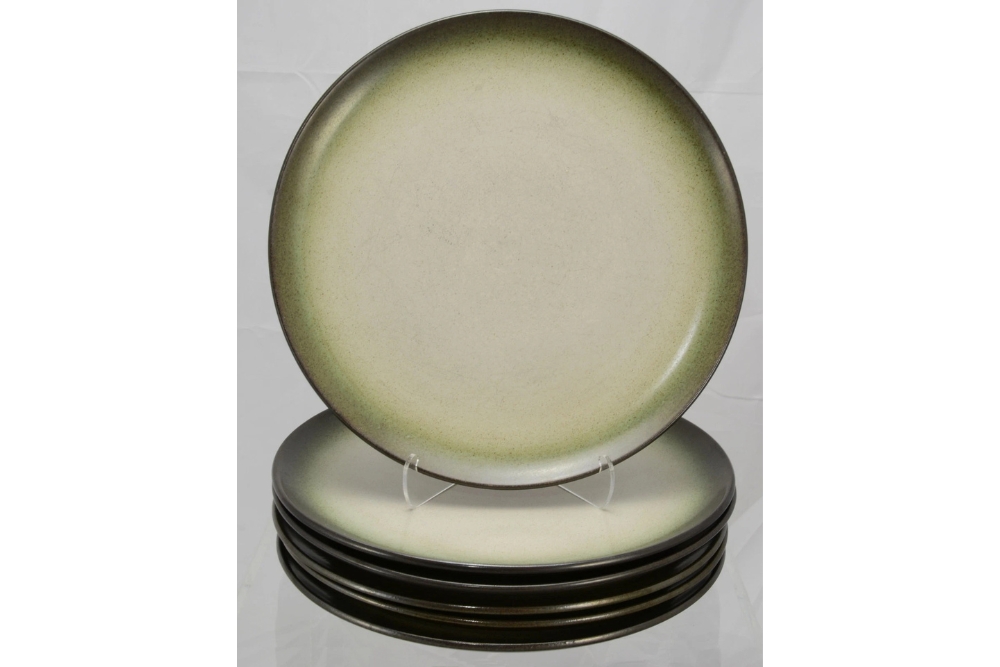
Edith Heath’s California pottery has kept the Coupe line in constant production since the late 1940s, which means a Heath plate in your cabinet could date from any decade since. The soft, matte glazes in colors like sand and sea are the ones people look for. Sets of the older plates run about $30 to $40 a plate: six Sea and Sand dinner plates bring $240 and a set of four runs $160. Four brown stacking bowls with rims go for about $145.
Heath still makes Coupe today, so a new plate can look nearly the same as an old one. Look for the Heath name stamped on the bottom, then check for the wear that only time leaves, like faint scratches on the foot ring.
Chips on the rim, deep knife marks and glaze that has crazed all lower the price. Matching colors matter, and a single plate is worth less than its share of a full set.
6. Pyrex Pink Gooseberry bowls and casseroles
image credit: fatherandsonsbluelightspecial24 via eBay
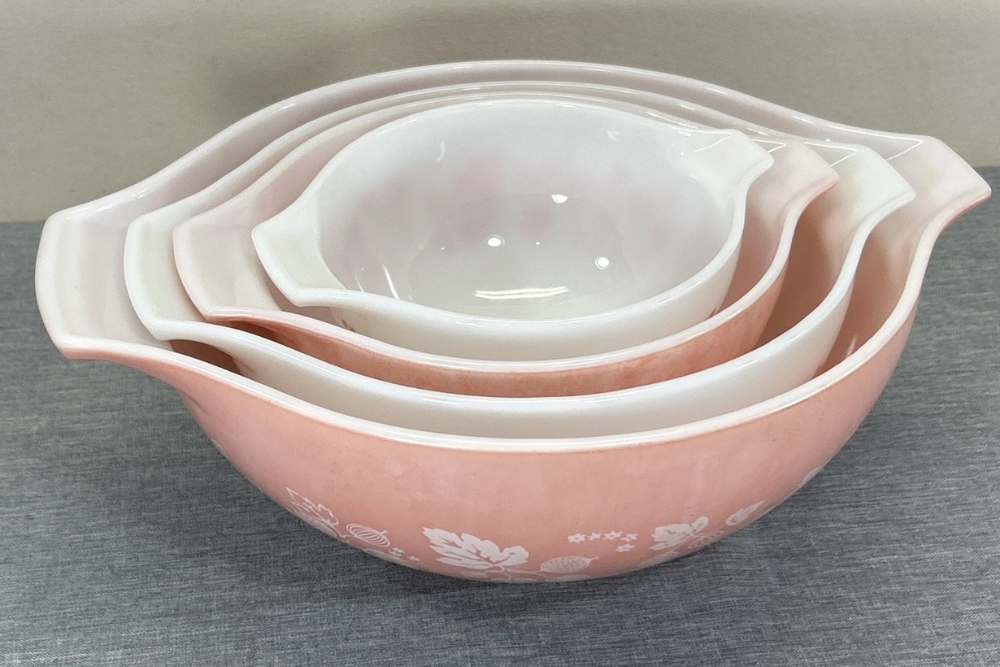
Pink Gooseberry is one of the Pyrex patterns people spot across a room. Pyrex made it from 1957 to 1966, and the pink print appeared on only a handful of pieces: the Cinderella-style mixing bowls, the casserole sets and the refrigerator dishes. Single pink bowls run $65 to $80, a casserole pair with both lids is worth around $120, and a refrigerator set with its lids goes for about $150.
Condition decides where a piece lands in those ranges, or whether it makes the cut at all. Pink fades in the dishwasher, so hold each piece up to a bright light and look for even color rather than a washed-out or blotchy print. Chips along the handles and spouts are common. A casserole missing its lid drops to about $54.
A boxed, never-used set of four bowls is in a different league and can run well past $1,000, but a worn, mismatched set will not come close. Check the bottom for PYREX in all capital letters, since newer glass with a lowercase logo is not the same product.
7. CorningWare Blue Cornflower percolator
image credit: uwinitall via eBay
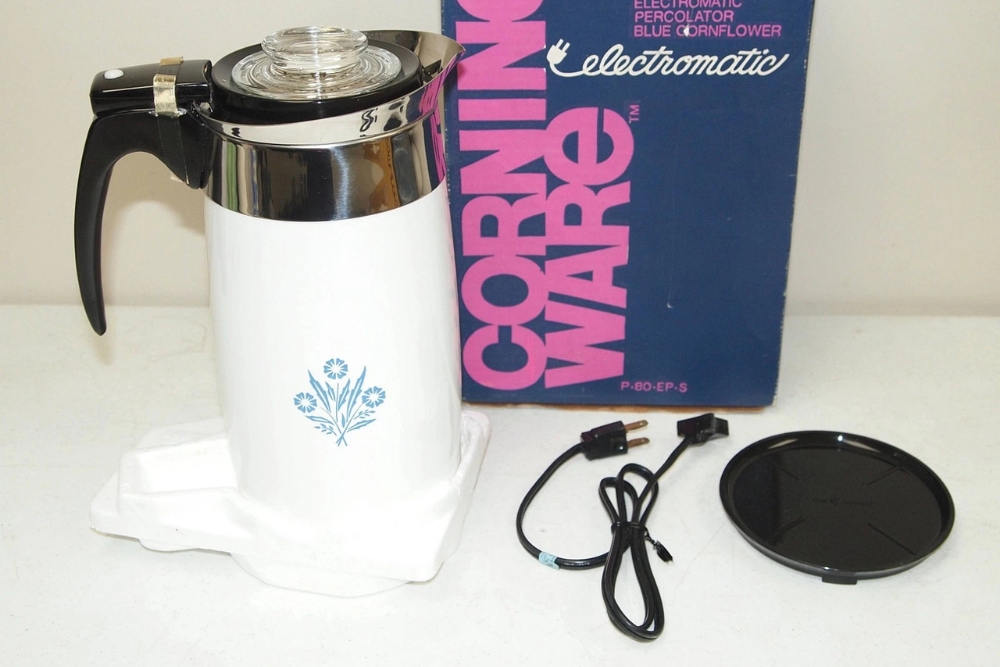
CorningWare’s blue cornflower pattern launched in 1958 and stayed in production until 1988, so it sat in a lot of kitchens during the 1960s. Casserole dishes are everywhere and do not bring much. The percolators are the better find. A complete 6-cup P-166 electric percolator goes for $165 to $190, a 10-cup Electromatic runs about $125, and a 6-cup stovetop percolator lands between $45 and $100.
Completeness is the whole game with a percolator. It needs its stem, basket, lid and, on the electric models, an intact cord, and a missing part cuts the price. Test the cord and plug on any electric model before you price it, and do not plug in one with frayed wiring. Check the glass-ceramic for chips around the spout and rim, and look at the blue flowers for scratches that have worn through the print.
Originals are marked Corning Ware as two words or carry the word Pyroceram on the bottom. The 2018 anniversary pieces were made from stoneware, not Pyroceram, so they are worth far less than the originals.
8. Fire-King Jane Ray jadeite dishes
image credit: qualityreplacementsfast! via eBay
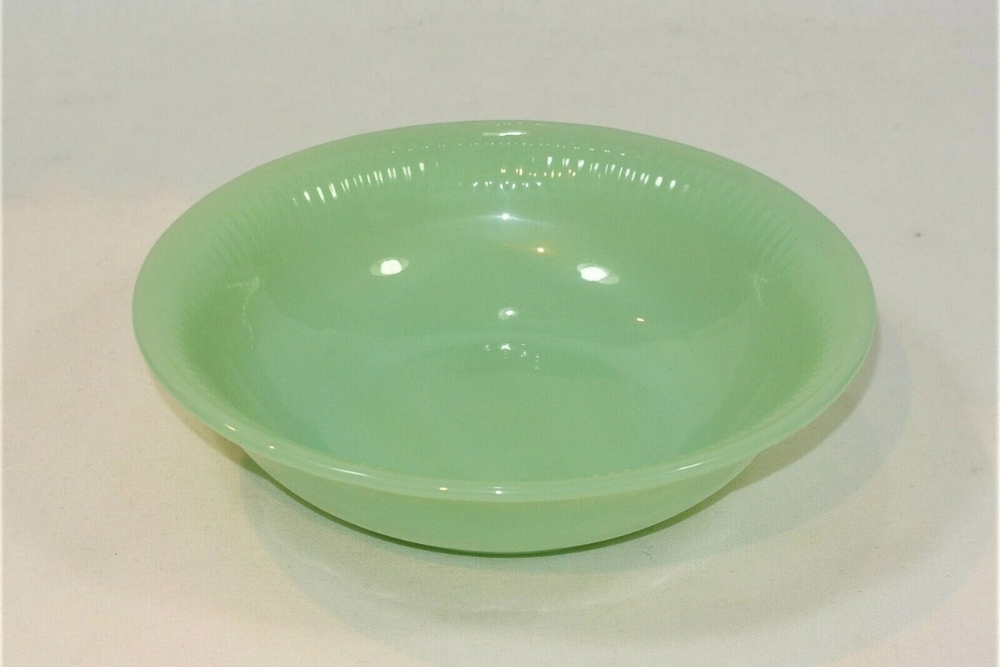
Anchor Hocking made the ribbed, pale green Jane Ray pattern from about 1945 to 1963, and plenty of it ended up in family cabinets. A set of four fruit bowls runs about $72, five soup bowls land near $55, and a creamer and lidded sugar bowl go for about $42. A set of ten dinner plates reaches $120 or more.
Most single pieces are worth $10 to $20, so the money is in matched sets. Look for chips on the rims, because jadeite chips easily, and for gray scratches from metal utensils that will not wash off. A cup without its saucer, or one plate from a broken set, is worth a fraction of a complete place setting.
Glass in a similar green has been made since the original run ended, so check the bottom for the Fire-King mark and feel the weight. Pieces from the original run carry that mark. If a set looks heavily used, with dull rims and a web of knife scratches, price it as everyday dishes, not as a collection.
9. Dansk Kobenstyle enamel cookware
image credit: jogenpogue via eBay
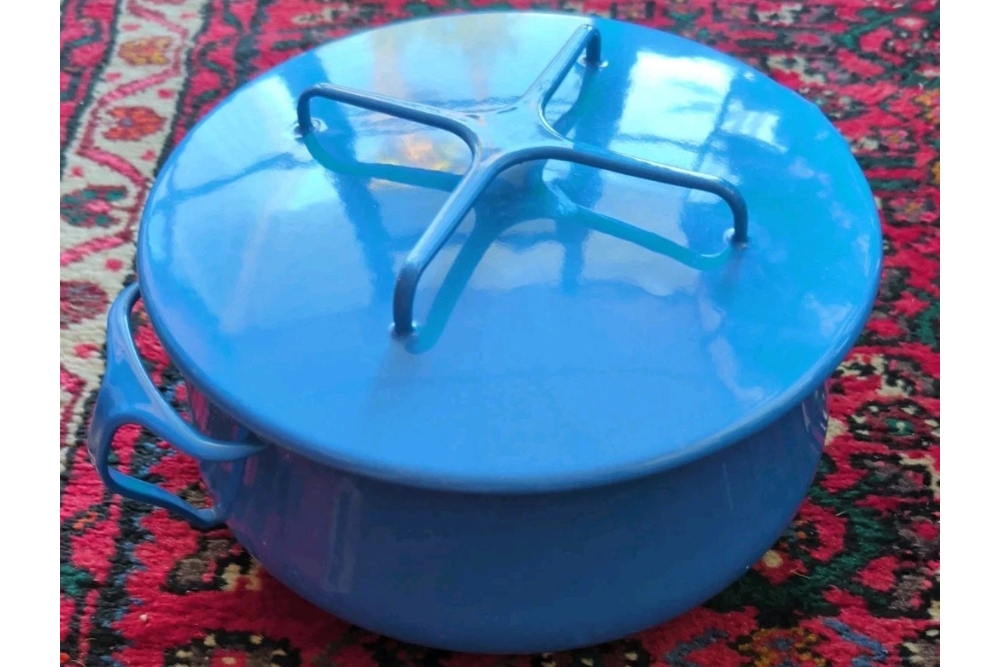
Jens Quistgaard designed Kobenstyle for Dansk in the mid-1950s, and the bright enamel pots and pans stayed in kitchens for years afterward. A large 6-quart casserole in blue that was never used can reach $180.
The stamp on the bottom tells you a lot. Originals are marked Dansk Designs Denmark, sometimes with the initials IHQ for Quistgaard, and a Dansk International stamp points to after 1965. A piece marked Thailand is modern and worth much less.
Chips are the main condition problem. A chip on the cooking surface or a rim rusting through the enamel can cut the price in half, and pieces missing their lids or matching parts bring far less than complete ones. Bright colors in clean enamel are the ones buyers pay for. Check the handles and the lid too, because a pot with a cracked handle or a mismatched lid is a harder sell.
10. Kit-Cat Klock jeweled model
image credit: kellsthriftco via eBay
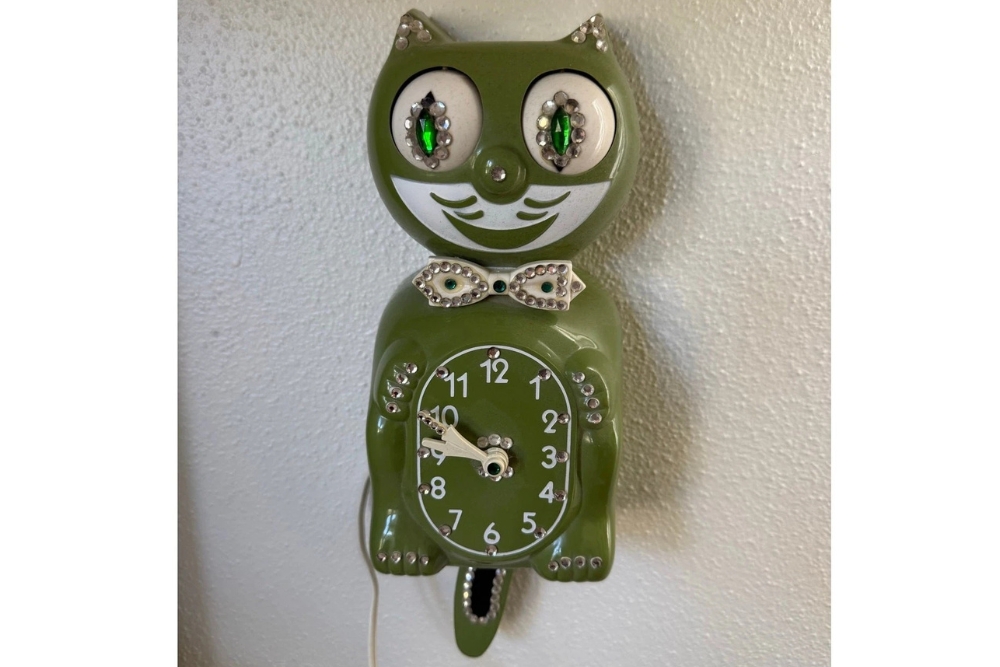
The black cat with the swinging tail and rolling eyes has hung on kitchen walls since the 1930s, and the version to look for from the 1960s is the one with sparkly crystals. The company added genuine crystals to some clocks in the 1960s. Working jeweled models in the D8 style typically run $75 to $125, and one still in its original box lands near $92.
Plug it in before you price it. The 1960s clocks are electric, and the eyes and tail should both move smoothly. Frayed cords, missing crystals, a replaced motor and a repaired or missing tail all lower the price. The paint on the body should be even, not touched up.
The company redesigned the clock for battery power in the late 1980s, so a battery-run cat is newer and worth less. The original models ran on household current.
11. Pyrex Pink Daisy oval casseroles
image credit: sandmannvintage via eBay
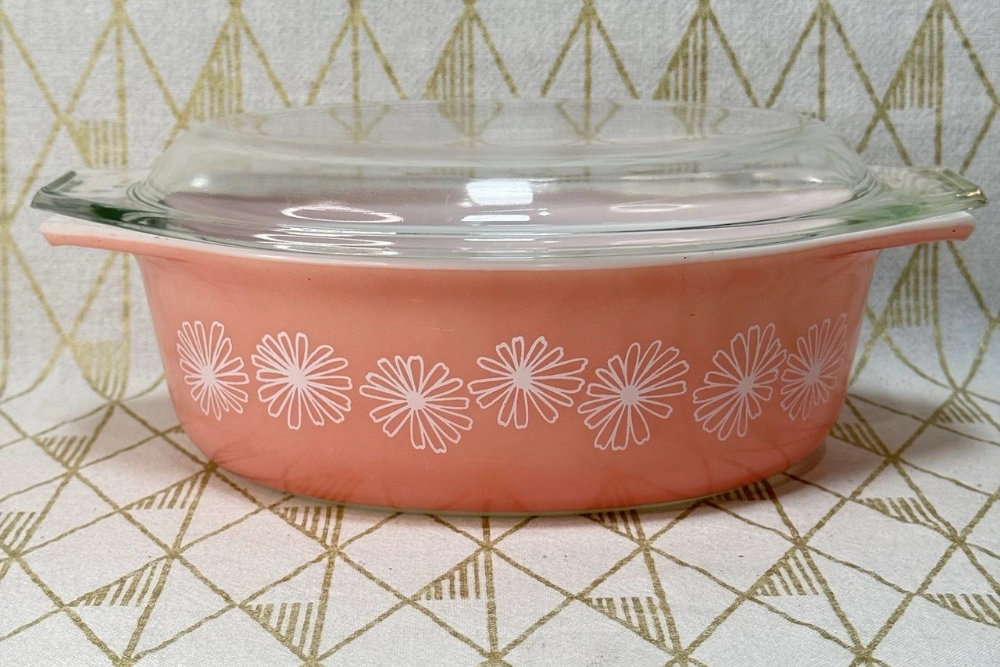
Pyrex made Pink Daisy from 1956 to 1963, mostly on oval casseroles, divided dishes and open bakers. The common 1.5-quart oval casserole with its lid typically runs $55 to $75. A divided casserole with a lid goes for about $110, and the 2-quart size reaches around $175.
The lid matters more than most people expect. A casserole with its original glass lid is worth noticeably more than the dish alone, and a mismatched lid from another pattern does not count. Run a finger around the rim and handles to check for chips, and look for gray scratches inside the dish from years of knife use.
Pink prints rub off in the dishwasher, so hold the dish up to the light and look for an even pattern with no bare spots. Check the bottom for PYREX in all capital letters, because lowercase marks belong to newer glass. A dish with a faded print or a missing lid belongs at the bottom of the range.
12. Fire-King jadeite restaurant ware mugs
image credit: hikarichiba-store via eBay
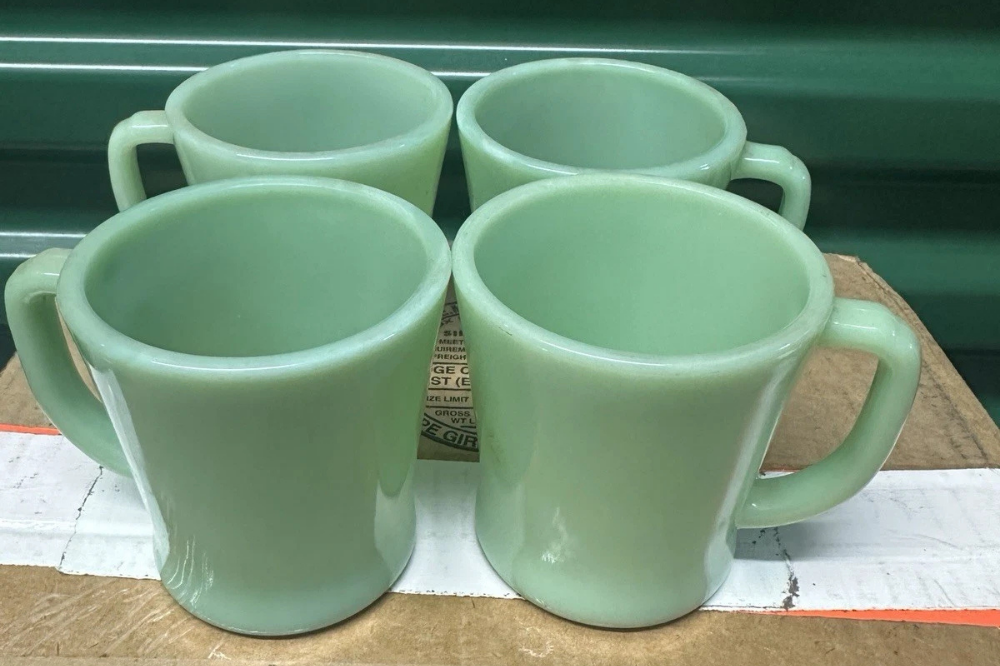
The thick green mugs that diners used for coffee are a lasting favorite. Anchor Hocking made jadeite restaurant ware from about 1948 to 1967, so many of them came out of 1960s kitchens and diners. Single mugs in either the C-handle or D-handle shape run $25 to $42.
Matching shapes help the price. A set of mugs that share the same handle style and shade of green is worth more than a mixed bunch. Check the rims and handles for chips, and look inside for the gray marks that spoons leave behind.
Jadeite-colored glass has been reproduced, so look at the weight and the mark on the bottom. Old restaurant ware is heavy and thick, so compare any mug you are unsure about with one you know is original. A mug with a chip on the rim or a crack at the handle is worth much less than a clean one.
13. Copco enameled cast iron by Michael Lax
image credit: curatedtreasurespnw via eBay
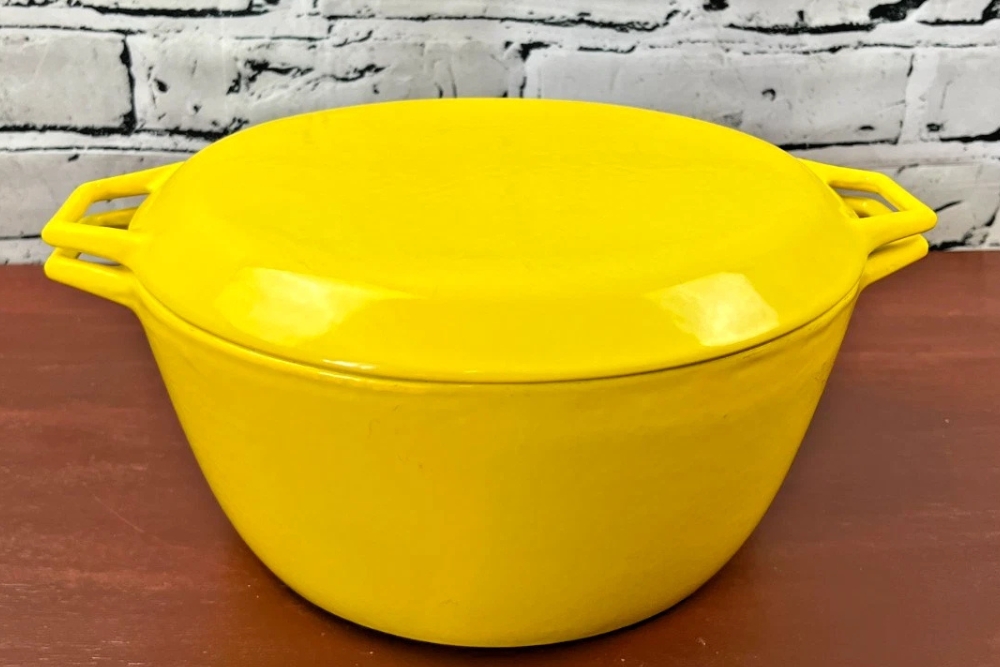
Designer Michael Lax began creating Copco enameled cast iron in 1960, and the colorful pans with their wooden handles are easy to spot at estate sales. A Dutch oven in a bright color can reach $100, while smaller pieces like a skillet, a fondue saucepan or an au gratin dish run $38 to $50. A burnt orange Dutch oven goes for closer to $37.
Size and color explain the difference. Larger pots in yellow or blue bring more than small dishes in common colors. Look for the Copco name and the word Denmark on the bottom, along with Michael Lax.
Enamel chips are the main problem, especially on the inside of the pot where food touches. Handles that are cracked, loose or dried out hurt the price too, and a pot with a missing lid is hard to sell. Rust at the rim and heavy staining inside leave a pan worth a fraction of a clean one.
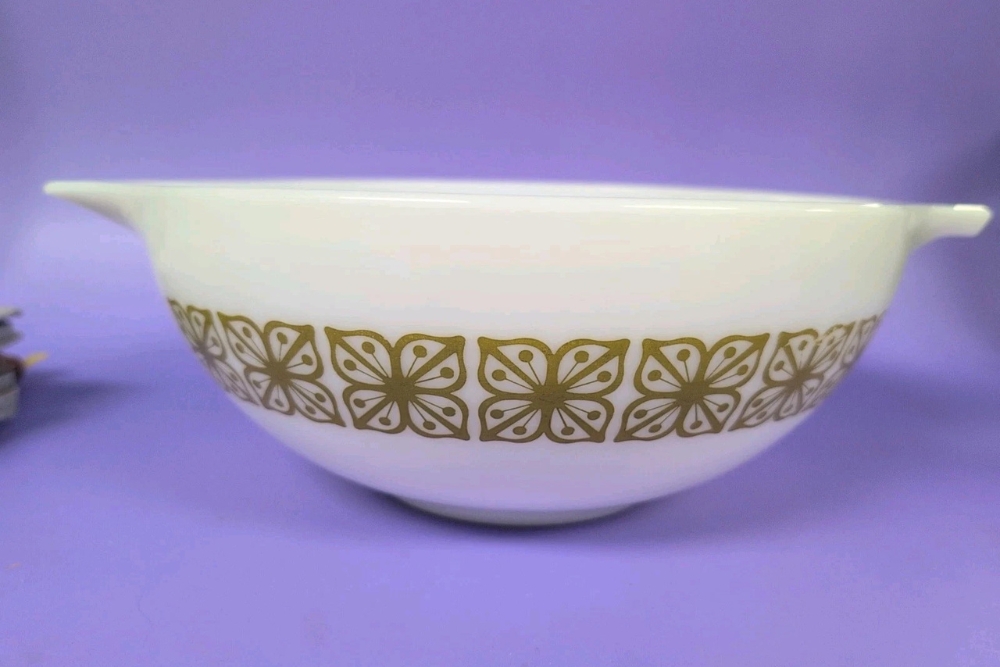
14. Pyrex Verde nesting bowls
image credit: ashorb126 via eBay
Pyrex made Verde from 1967 to 1972, with a green floral print on white glass. A full set of four nesting bowls can reach $180, and the 2-quart round casserole from the stamp program runs about $124. Partial sets are a different story, with two or three bowls going for $30 to $50.
The word complete matters here. Sellers often pair mismatched bowls from different patterns or colors, so check that the green and the print match across the set. Fading from the dishwasher turns the print pale, and chips around the rims are easy to miss until you run a finger over them.
Look for PYREX in all capital letters on the bottom. Common worn bowls with faded prints bring far less, and a bowl that has been used and washed for fifty years is rarely worth more than a few dollars on its own. If you find a single Verde bowl at a thrift store, check the shelves nearby for the other sizes, because sets are often split up and priced piece by piece.
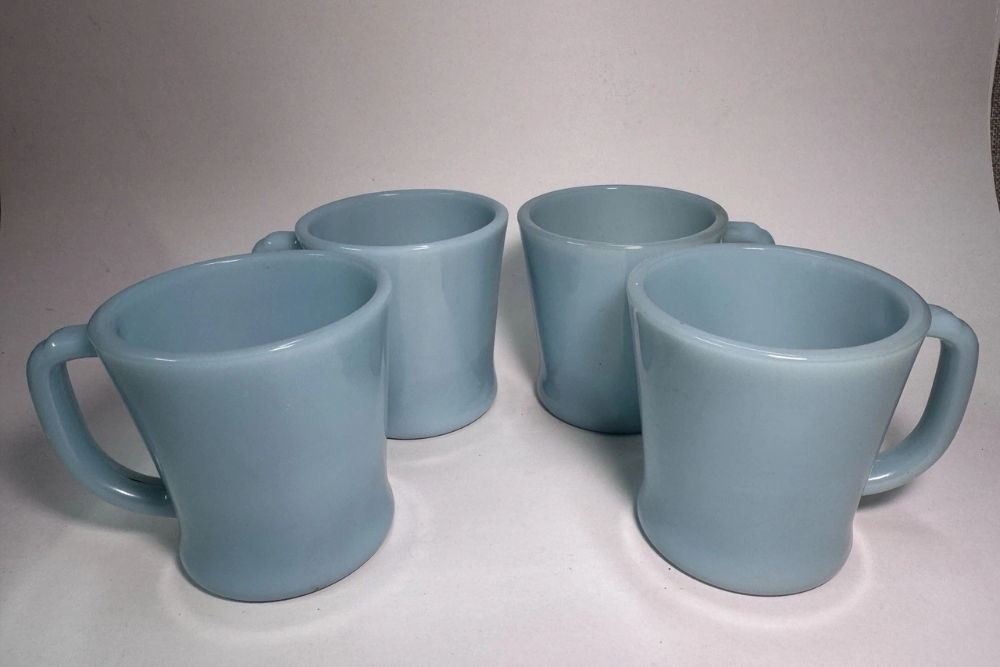
15. Fire-King turquoise blue D-handle mugs
image credit: lisaash via eBay
Anchor Hocking’s turquoise blue Fire-King was made from about 1956 to 1962, and the D-handle mugs are the pieces most likely to turn up in a cabinet. A single mug runs about $30 and a set of four goes for $125 to $130.
The color should be even and bright. Faded glass, chips on the rim, cracks near the handle and a cloudy look from years of washing all push the price toward the bottom.
Matching sets are worth the most. Buyers want mugs that match in shade and in handle shape, and a mixed bunch brings less than a set offered together. Look for the Fire-King or Anchor Hocking mark on the bottom, and keep in mind that look-alike blue glass from other makers is not the same thing. Check the base of each mug too, where years of stacking and shelf wear leave rings and scratches.
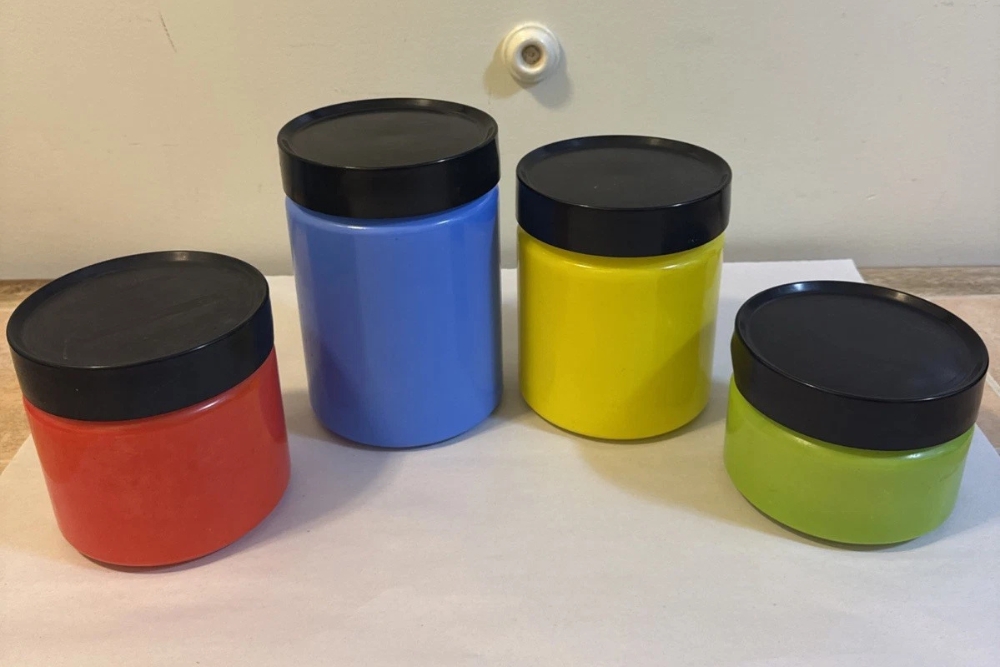
16. Fire-King milk glass canisters
image credit: dempseysdeals_87 via eBay
Anchor Hocking’s Fire-King canisters were a colorful fixture of 1960s and 1970s kitchens, with a milk glass interior and a bright outer color in solid and ombre shades of blue, yellow, orange and green. A single canister typically runs $20 to $45, and a full set can reach nearly $300.
The set is the thing. The original canisters came with black plastic lids, and those lids go missing, crack and warp. A canister without its lid is worth much less, and a full matching set in good color is the only version that gets near the top of the range. Test the lid for a snug fit.
Look on the bottom for the anchor over the letter H, which can be hard to see after years of wear. Chips on the rim, worn color and cloudiness inside lower the price. Other Fire-King canisters, like the all-white Harvest Grape, are different patterns with their own prices.
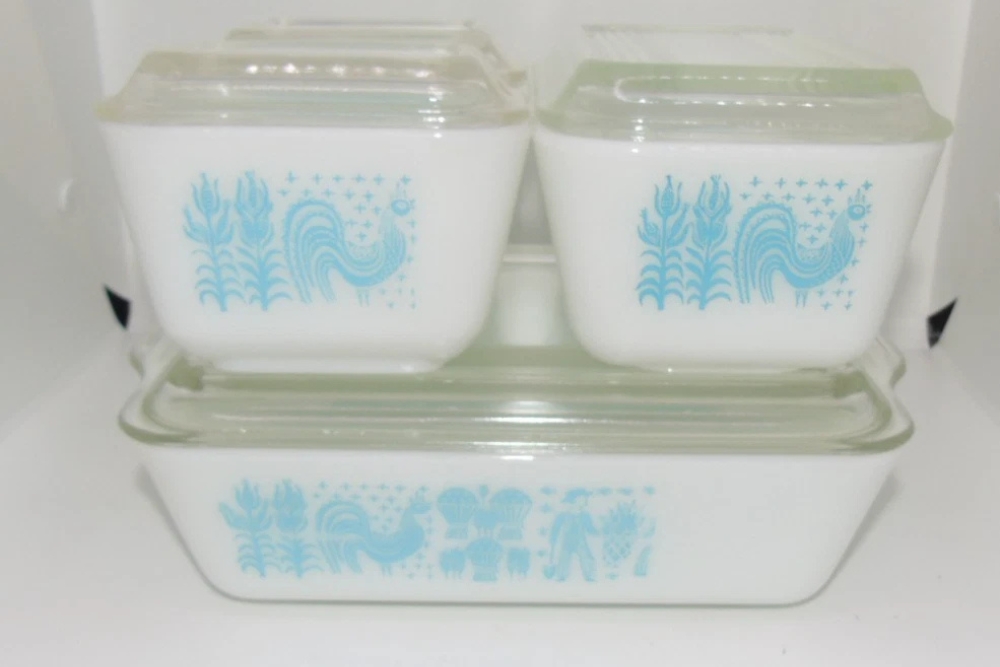
17. Pyrex Butterprint refrigerator dishes
image credit: froggreenefrog via eBay
Everyone remembers the bowls, but the same Butterprint pattern turns up on stacking refrigerator dishes that people tend to overlook. They were made in the same 1957 to 1968 window, and a set of three with every lid typically goes for $90 to $150. A set of two with lids runs closer to $60.
The lids are the whole story. They crack, chip and disappear, and a dish without its lid is worth well under half of a complete one. The dishes come in 501, 502 and 503 sizes, and a set that includes all three nests together neatly.
Check inside for knife scratches and stains, and run a finger around each rim for chips. Dishwasher fade appears quickly on the turquoise, so look for an even print. Check each dish for PYREX in all capital letters. Dishes with a worn print, a missing lid or a mismatched color are worth much less than a bright, complete set.
18. Fire-King Peach Lustre dinnerware
image credit: purplemonk via eBay
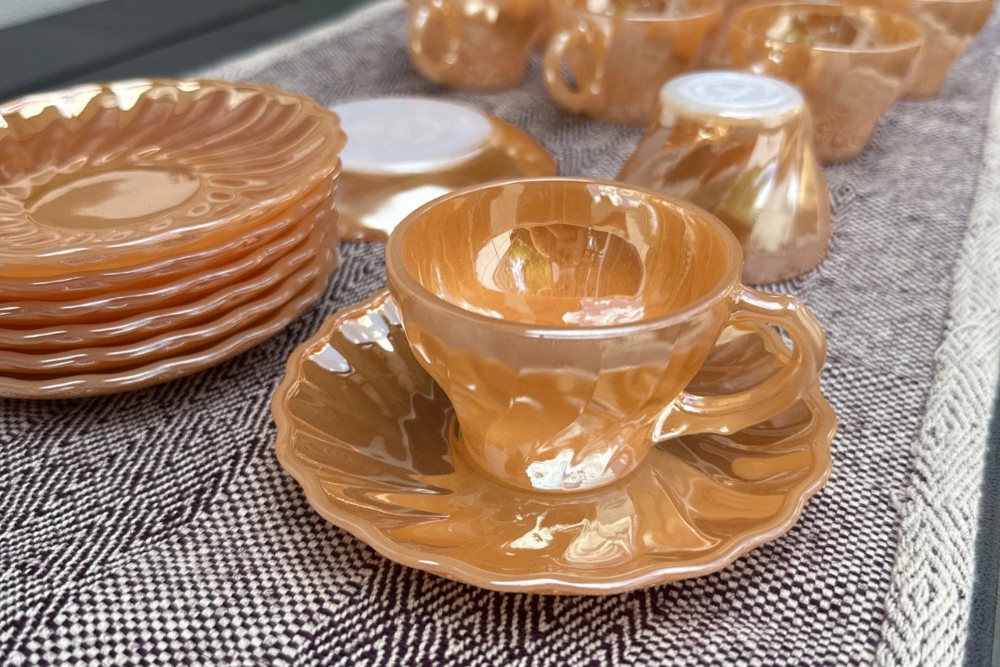
The soft, shimmery pink-orange finish of Peach Lustre was made from about 1952 to 1963, so plenty of it was on 1960s tables. A set of eight swirl cups and saucers runs about $79, and three nesting swirl bowls land near $80.
That makes it one of the lower-priced finds, but sets add up. The lustre finish is the whole look, and it wears. Dishwashers leave it dull and scratched, so tilt each piece under a light and look for an even shimmer. Chips on the rims and cracks around the cup handles knock the price down.
Look for the Fire-King or Anchor Hocking mark on the bottom, because other makers’ peach-tinted glass is worth less. Single plates and odd cups from broken sets bring much less than a matched service, so keep complete sets together. Buyers tend to look for matching cups, saucers and plates, and a full box of it is easier to price than a few loose pieces.
19. Pyrex Golden Acorn casserole
image credit: flvintagedeals via eBay
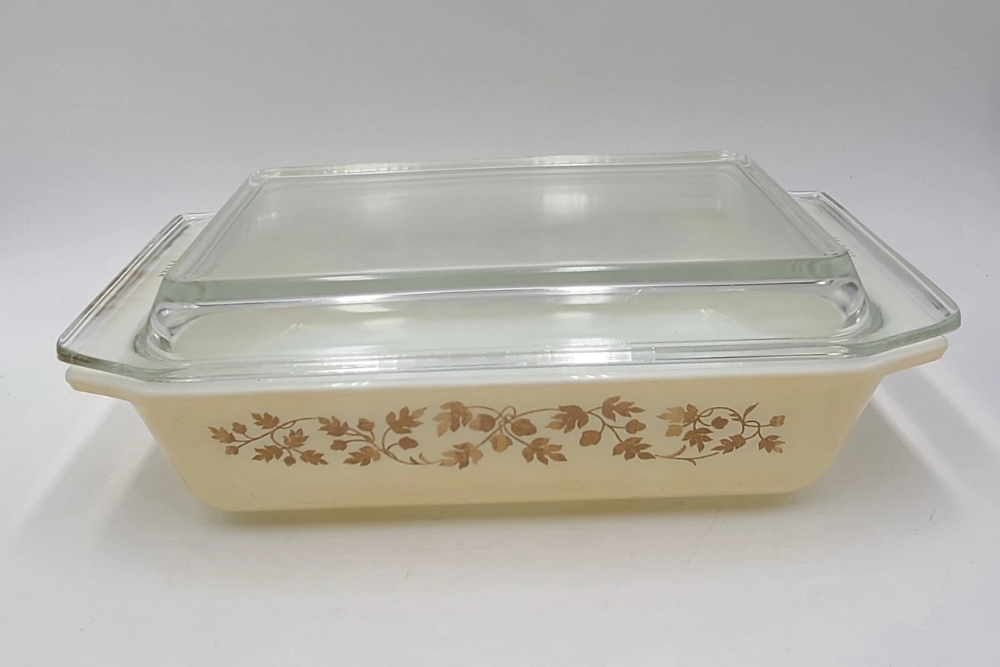
Pyrex made Golden Acorn from 1960 to 1964, a short run that puts it squarely in the early 1960s. The 2-quart casserole server with its lid runs about $48 to $70, a loaf dish with a lid lands near $69, and the smaller space saver casseroles go for $31 to $50.
The acorn and leaf print is the part to protect. It is easy to scrub off, and a dish with bare patches or a dull, brownish print is worth far less. Check the lid carefully, since a casserole with its original lid is worth noticeably more than the dish alone. Run a finger around the rims and handles for chips.
Check the bottom for PYREX in all capital letters, and look for the number 575 or 578 on the base, which are among the common sizes. Dishes with a faded print or no lid bring much less, so this is a smaller find than the bowls, but a clean one still beats the donation pile.
20. Fire-King Azur-ite swirl plates
image credit: dexman1952 via eBay
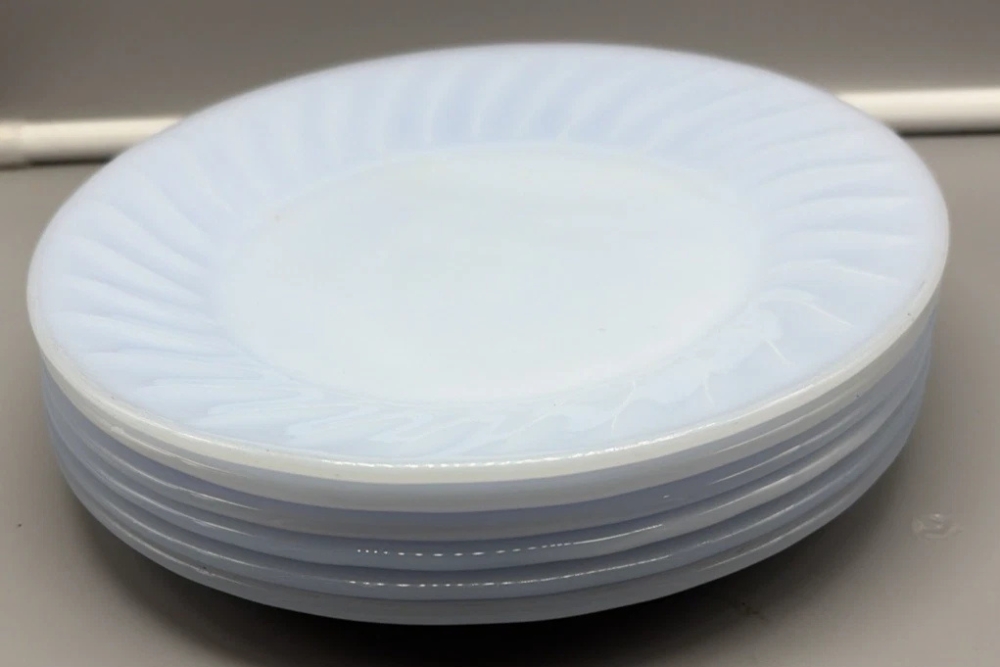
Azur-ite was made primarily in the 1960s, a pale blue Fire-King glass. A set of six swirl salad plates runs about $30, four Charm dinner plates go for around $70, and a partial service with cups, large plates and small plates reaches $72. Two large platters can bring $99.
Platters and larger pieces are worth more than plates and bowls, and sets are worth more than singles. Look for the soft blue tint to be even. Faded glass, scratches from metal utensils, chips on the rims and cloudy patches from years in the dishwasher all lower the price.
Shape names can be confusing here, since Swirl and Charm both appear in the color. Check the bottom for the Fire-King or Anchor Hocking mark. A lone saucer or a plate with a chipped edge brings only a few dollars, so the pieces that pay off are the matched stacks and the big serving platters. Keep any set you find together, because buyers look for matching cups, saucers and plates.
21. Tupperware Millionaire line atomic shakers
image credit: marjoricomella-sis0 via eBay
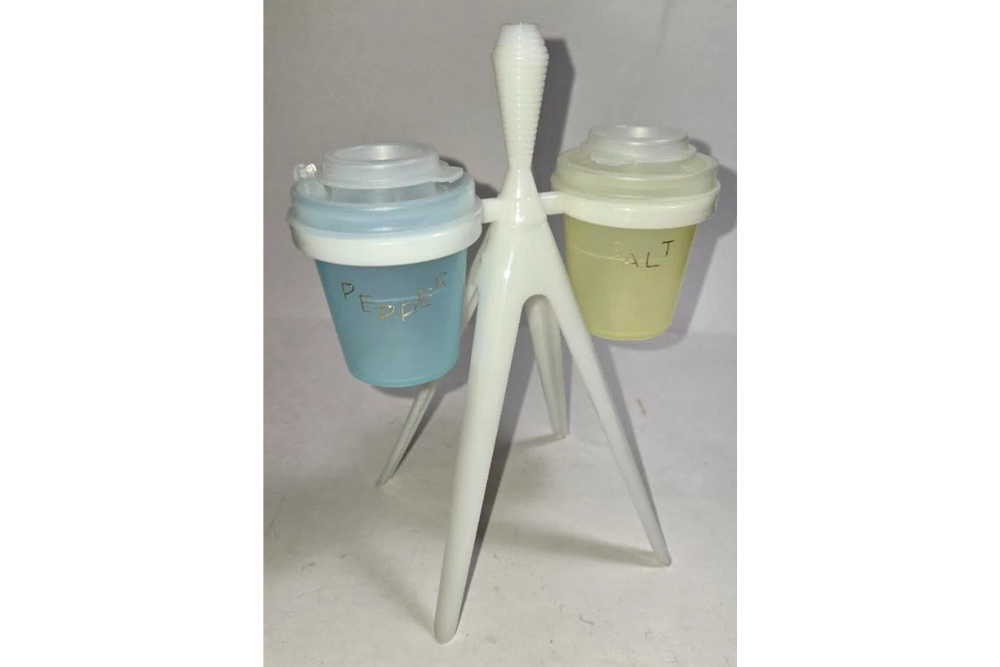
Tupperware’s Millionaire line was carried in department stores rather than through home parties, and the atomic-style salt and pepper shakers on a tripod caddy are a fixture of the 1950s and 1960s. A set typically runs $30 to $50, and the large round cake carrier goes for around $35.
These are the smallest finds here, but they are fun to spot. The pastel colors should be bright, and the printed lettering should still be readable. Fading, cracked plastic, a missing toothpick holder on top of the caddy and warped lids all push the price down. A complete set with every piece matching sells for more than a pair of loose shakers.
Treat them as display pieces. Plastic from this era may not be safe for food, so most buyers want them for a shelf or a retro kitchen. Later Tupperware in similar shapes is worth far less, so check that the pieces have the pastel colors and the atomic shapes of the original line.
Before anything from the kitchen goes into a donation bag, turn it over and read the bottom. A maker’s mark and a pattern name are usually enough to tell a $5 dish from one worth a few hundred.
You spend years building a career, then watch a chatbot do half of it for free. That’s the situation a lot of people are in right now, people who did everything right and still watched their department shrink down to a login.
Meanwhile, the construction industry says it needs to add roughly 349,000 more workers in 2026 just to keep up with the work it already has booked, and the plumbing trade alone is on pace for 550,000 unfilled jobs by 2027. Nobody has built software that can snake a drain, rewire a breaker box, or sit with someone’s dying parent.
If you’ve been laid off, you’re worried you might be next, or you’re just tired of watching entire teams get replaced by a server somewhere, it makes sense to want work tied to a body in a room, not a login.
None of the 18 jobs below need a four-year degree, and a few of them you could start training for before the year is out.
Electricians make a median $63,190 a year, and employment is projected to grow 9% between 2025 and 2035, with about 72,700 openings a year once you count retirements and people leaving the trade. That’s a job nobody can outsource to a call center, and nobody can prompt an AI model to do instead.
The entry path is a paid apprenticeship, usually four to five years, combining roughly 2,000 hours a year of on-the-job training with classroom instruction. You earn while you learn, and most states require passing a license exam once you finish. It’s a longer runway than a weekend certification, but it ends in a trade that construction firms are actively short on. The industry, electricians very much included, says it needs about 349,000 more workers in 2026 just to keep pace with the work already on the books.
Wiring a house, troubleshooting a panel, and running conduit through a wall all require a person standing in that room with tools in their hands. A recession doesn’t change that, and neither does a new AI model.
Plumber
Image Credit: Shutterstock
A plumber’s median pay sits at $63,800 a year, with 7% job growth projected through 2035 and about 42,000 openings a year. Like electrical work, it runs on paid apprenticeships rather than a four-year degree, typically four to five years combining on-the-job hours with technical instruction, followed by a state license exam.
The trade is short-staffed in a way that should worry anyone who owns a house. One industry analysis found plumbers and plumbing manufacturers together support $442 billion in economic activity and 1.8 million jobs, while a separate study projects the country is on pace for 550,000 unfilled plumbing positions by 2027.
A burst pipe doesn’t wait for the economy to recover, and it doesn’t care whether you’re flush with cash or barely making rent. Somebody has to show up and fix it, and that somebody gets paid regardless of what the stock market is doing.
HVAC technician
Image Credit: Shutterstock
Heating and cooling techs make a median $61,010 a year, and the trade is actually losing workers faster than it’s gaining them. One industry analysis found HVAC employment slid from 441,200 in 2023 to 425,200 in 2024, even as demand keeps climbing and the field needs roughly 40,100 workers a year just to replace people who retire or leave.
Getting in doesn’t require a traditional degree. Most people go through a trade school program lasting six months to two years, or an apprenticeship that pays while you train. Nearly every technician needs an EPA certification for handling refrigerants, and many states require a license on top of that.
Furnaces break in January and air conditioners die in July, and neither one cares what’s happening in the broader economy. If anything, people hold onto an aging system longer when money is tight, which means more repair calls, not fewer, for the technician who shows up to fix it instead of replace it.
Welder
Image Credit: Shutterstock
Welders earn a median $53,750 a year. The government’s own growth projection for this trade is modest, just 2% through 2035, so this isn’t a pick based on an exciting headline number. It’s worth picking because of what’s underneath that number: about 40,300 openings a year, most of them created by people retiring out of the trade, not by the job disappearing.
Industry-specific research backs that up at a bigger scale. Data tied to the American Welding Society projects the country will need 320,500 new welding professionals by 2029, roughly 80,000 people a year, to replace an aging workforce.
You can get in with a high school diploma plus a welding program at a trade school or community college, and some employers run their own apprenticeships. OSHA requires safety training on top of that. It’s a trade that builds and repairs things you can touch, bridges, pipelines, manufacturing equipment, none of which get fixed by a language model.
Pest control technician
Image Credit: Shutterstock
Pest control workers make a median $45,250 a year, with 6% job growth projected through 2035 and about 13,700 openings a year. It’s one of the easiest trades on this list to break into. Most technicians start with nothing more than a high school diploma and less than three months of on-the-job training in a specialty like termite control, rodent control, or fumigation. Most states do require a license, which usually means finishing a short training course and passing an exam.
Nobody decides to live with termites or a mouse problem because the economy is uncertain. If anything, people who can no longer afford to move handle their pest problems instead of ignoring them, since the alternative is watching things get worse inside the house they’re stuck in.
This is also about as automation-proof as work gets. Spotting where carpenter ants are nesting, setting bait correctly, and sealing entry points in a crawl space all require a person physically inspecting a physical building, something no app can do from the outside.
Automotive mechanic
Image Credit: Shutterstock
Automotive service technicians earn a median $50,620 a year, with 5% job growth projected through 2035 and about 66,200 openings a year. Most people get in through a postsecondary automotive technology program, though some start as a trainee or technician’s helper with just a high school diploma and work their way up.
This trade actually tends to get busier, not slower, when money is tight. The average vehicle on US roads is now 12.8 years old, a record high, because new and used cars have gotten expensive enough that people are holding onto what they already own and paying to keep it running instead of replacing it. That’s a direct boost to repair shops, since an older car needs more frequent and more complicated repairs than a new one.
A diagnostic scanner might point toward a problem, but someone still has to physically pull the part, test it, and swap it out. That part of the job hasn’t changed in a century, and it isn’t about to start now.
Medical assistant
Image Credit: Shutterstock
Medical assistants make a median $45,690 a year, and the job is projected to grow 13% between 2025 and 2035, described by the government as much faster than average, with about 109,700 openings a year. That’s one of the strongest growth numbers on this entire list.
Most people train through a certificate program lasting about a year or two, which includes supervised hands-on practice in a clinic. Some employers will hire someone with just a high school diploma and train them on the job over several months instead.
People get sick and need checkups in every kind of economy, and clinics aren’t cutting the staff who take vitals, prep patients, and draw blood just because the markets are down. This is also squarely a hands-on job. Taking someone’s blood pressure, giving an injection, or getting a nervous patient settled before a procedure requires a real person standing next to them, not an app or a script.
Home health aide
Image Credit: Shutterstock
Home health and personal care aides earn a median $35,800 a year, and the job is projected to grow 18% between 2025 and 2035, one of the fastest growth rates of any job in the country. Most jobs ask for a high school diploma, and some don’t even require that. Training is typically short and on the job, though aides working for certified home health or hospice agencies need formal training plus a standardized competency test.
The demand behind this one isn’t going anywhere. The US population age 65 and older grew 13% between 2020 and 2024, reaching 61.2 million people, and older adults now outnumber children in 11 states and nearly 45% of counties nationwide.
Families need someone to help an aging parent bathe, dress, take medication on time, and simply not be alone all day, and that need doesn’t pause during a downturn. If anything, it gets more acute, since fewer families can afford a nursing home and more of them are trying to keep a parent at home instead.
Licensed massage therapist
Image Credit: Shutterstock
Massage therapists earn a median $58,450 a year, with 15% job growth projected through 2035 and about 20,400 openings a year. Training happens at a massage school, not a four-year college, combining classroom work with hands-on practice, and nearly every state requires passing a licensing exam afterward.
This isn’t a luxury purchase for most of the people booking appointments. One national industry survey found roughly a quarter of men and about one in five women had gotten a massage in the past year, and the top reasons people gave were soreness and stiffness, chronic pain management, and stress, not pampering.
A massage therapist works with their hands on another person’s actual body, reading where the tension is and adjusting pressure in real time. That’s about as far from a job AI can do as work gets, and it’s also work that doesn’t move overseas or get consolidated into a call center.
Personal trainer
Image Credit: Shutterstock
Fitness trainers and instructors make a median $47,160 a year, with 7% job growth projected through 2035. This is one of the faster paths into a new career on this entire list. A certification like the NASM-CPT is self-paced, and most people finish it in roughly four to twelve weeks, with no prior fitness background or degree required, plus a CPR and AED certification on the side.
The client base is bigger than most people assume. About 77 million Americans, one in four people age six and older, belonged to a gym or fitness studio in 2024.
A good trainer watches how someone actually moves, catches a knee about to buckle under a squat, and adjusts a program on the spot based on what they see. That kind of real-time correction, from someone standing right there, is not something an app on a phone screen can replace.
Hairstylist or barber
Image Credit: Shutterstock
Barbers, hairstylists, and cosmetologists earn a combined median $35,880 a year, with 7% job growth projected through 2035 and about 80,300 openings a year. The path in runs through a state-approved cosmetology or barber program, followed by a licensing exam that every state requires.
Haircuts are one of the more recession-resistant personal purchases there is, because most people treat them as maintenance, not a luxury they can skip indefinitely. The US hair salon industry is estimated at $60 billion a year, even after a slight dip in spending in 2025.
This is also a trade built entirely on repeat, local relationships. A client picks a stylist they trust with their actual hair and keeps coming back to that same person for years, which makes it one of the steadier small businesses someone can build without a storefront, a warehouse, or a business degree. Tips add another layer of income on top of the base pay, and a stylist who builds a loyal chair can often rent a booth and keep a much bigger share of what they earn than an hourly employee ever would.
Mobile pet groomer
Image Credit: Shutterstock
There’s no single clean national salary figure for mobile pet grooming specifically, so be skeptical of anyone who promises you one. The closest government number is the broader “animal caretakers” category, with a median of $35,360 a year and 11% job growth projected through 2035. One real mobile-groomer job listing we found, in Louisville, Kentucky, advertised pay of $400 to $1,200 a week.
You don’t need a degree or a license in most states to start grooming. Most groomers learn the trade by working under someone experienced, and attending a formal grooming school is optional, not required.
Pet spending kept climbing even through recent economic turbulence. The US pet industry hit $158 billion in 2025, on pace to reach $165 billion in 2026, and 95 million US households now own a pet. People cut back on plenty of things before they cut back on their dog’s nails getting trimmed.
Dog walker or pet sitter
Image Credit: Shutterstock
Dog walking and pet sitting mostly run through apps now, and because almost everyone doing it is an independent contractor rather than a tracked employee, there’s no government salary figure the way there is for a licensed trade. One earnings analysis pegged typical pay at $15 to $35 per walk, with average monthly earnings around $2,980 for someone doing it regularly, though app-based walkers tend to land toward the lower end of that range once the platform takes its cut.
Getting started through an app like Rover requires being at least 18 years old and signing on as an independent contractor rather than an employee. No prior experience is required, which makes this one of the fastest jobs on this list to actually start.
Dog ownership keeps climbing. 53% of US households now own a dog, up from 51% the year before, and most of those owners still work full days away from home. Someone has to let the dog out at 1pm, and that’s not a task you can hand to a chatbot.
House cleaner
Image Credit: Shutterstock
Maids and housekeeping cleaners earn a median of $35,510 a year as employees, though someone running their own cleaning business and managing a small team typically earns more than that baseline. No state license is required to clean houses, just a general business license, and a surety bond is worth getting since it signals trustworthiness to new clients.
The demand driver here is simple. 49.6% of married-couple families had both spouses employed in 2024, which means roughly half of all two-parent households have nobody home during the day to scrub a bathroom or vacuum a living room.
Most cleaners build a client list through word of mouth, a Google Business Profile, and neighborhood apps, then grow from there. It’s one of the lowest-cost businesses on this list to start, since the real requirements are supplies, reliability, and a willingness to do physical work inside somebody else’s house that nobody has figured out how to automate.
Landscaper
Image Credit: Shutterstock
Grounds maintenance workers earn a median $40,080 a year, with 5% job growth projected through 2035 and about 162,500 openings a year, more annual openings than almost any other job on this list. Starting your own lawn care or landscaping business costs more upfront than most of the other jobs here, with equipment and a truck running $12,000 to $85,000 or more depending on how big you start. Some areas require a permit if you’re applying pesticides or herbicides.
The industry itself is enormous. US landscape services generated an estimated $188.8 billion in 2025 across nearly 693,000 businesses and more than 1.4 million employees.
Grass keeps growing whether the economy is booming or not, and a yard that gets ignored for a season turns into a much bigger, more expensive problem than a weekly mow would have been. That makes landscaping one of those services people cut back on slowly and reluctantly, not all at once.
Junk removal hauler
Image Credit: Shutterstock
Nobody has published a reliable national income figure for solo junk removal operators, and you should be wary of any website that gives you one. What’s verifiable is how cheap this is to start. A used pickup and trailer can get you going for a few thousand dollars, commercial auto insurance runs around $76 a month, general liability coverage adds roughly $50 a month, and a business license plus hauling permit typically costs $30 to $500 depending on where you live.
You can run this as an independent operator setting your own prices, as a franchise that hands you leads for a cut of each job, or as a subcontractor picking up overflow jobs for an established hauler.
This trade has a genuine recession twist to it. The broader waste and recycling sector pulled in an estimated $104.63 billion in 2024, and junk removal specifically tends to get busier, not slower, when people are downsizing, clearing out a relative’s house, or dealing with a foreclosure, all things that happen more, not less, when the economy sours.
Handyman
Image Credit: Shutterstock
General maintenance and repair workers earn a median $49,590 a year as employees, with 4% job growth projected through 2035. Most states don’t require a dedicated handyman license, but a general contractor’s license kicks in once a single job crosses a dollar threshold, roughly $1,000 in Arizona, Nevada, and California, $2,500 in Georgia, and $3,000 in Utah. Electrical, plumbing, and HVAC work still need their own trade license regardless of the job’s size. Starting one typically costs $2,000 to $10,000 for basic tools and a vehicle.
The demand case here is about what people are willing to put off and what they aren’t. A recent survey found 71% of homeowners said they were focused on preventative home maintenance this year, and the same 71% said they’d delayed a planned project because of the economy.
That’s the handyman’s whole opportunity in one sentence. The leaky faucet still gets fixed. The bigger remodel gets pushed to next year.
Funeral service worker
Image Credit: Shutterstock
Funeral service workers earn a combined median $61,410 a year, with morticians and funeral directors at $55,010 and embalmers around $58,780. The lowest-barrier entry point is funeral attendant, which pays a median of $35,680 a year and doesn’t require the mortuary science degree that directors and embalmers need. Becoming a licensed funeral director or embalmer typically means an associate’s degree, a one- to three-year internship, and a state licensing exam, usually with a minimum age of 21.
There are 15,401 operating funeral homes in the US, about three-quarters of them family owned, and the field is growing at a steady 4% through 2035, about as fast as the average for all jobs.
This is the plainest recession-proof argument on this entire list. People die in good economies and bad ones, and their families need someone to handle the arrangements either way. That need doesn’t fluctuate with the unemployment rate, and it isn’t something anyone wants handled by software.
None of these jobs are glamorous, and most of them involve getting your hands dirty in some literal sense. That’s also exactly why they’re still here.