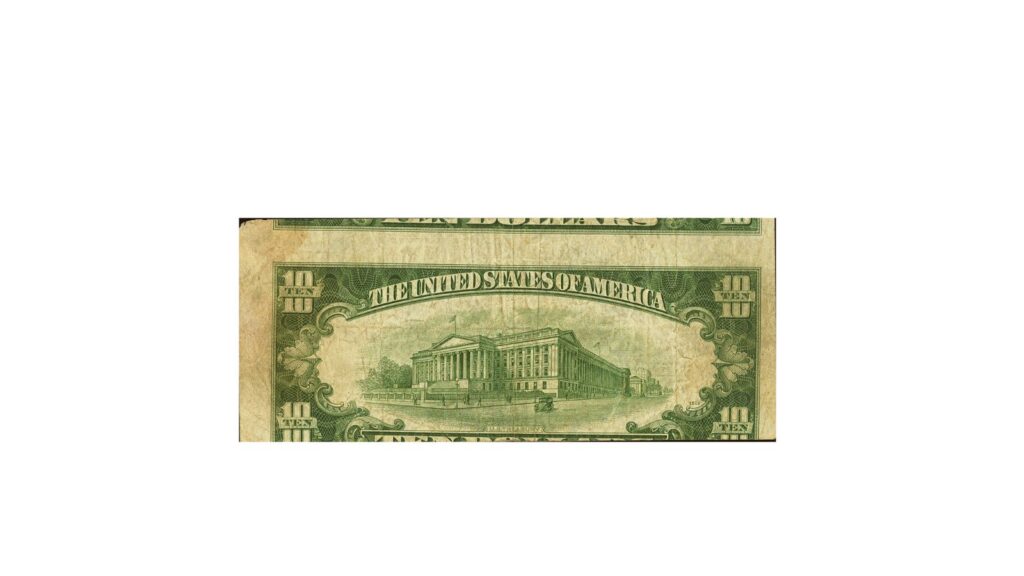
You’re counting out change for a garage sale, or going through a shoebox of bills your grandfather kept in his sock drawer, and something looks off. The seal is brown instead of green. There’s a strange word stamped across the back. The portrait looks like Hamilton, but the whole bill feels wrong somehow. Before that $10 note goes back into circulation, it’s worth a second look.
The ten has gone through more redesigns than almost any other US bill, gold certificates, silver certificates, wartime emergency notes, and a run of brown and yellow seals that all look unfamiliar if you’ve never handled one. Most of what turns up is still just worth ten dollars. But a few categories below apply to a bill sitting in your wallet right now, not just to old currency pulled from an estate.
The Bureau of Engraving and Printing runs a tight quality control process, but mistakes still slip through. A misaligned print, where the design shifts off center or the margins come out uneven, is the most common error and the least dramatic, typically worth $25 to $500 depending on how far off it is. Ink smears are more eye-catching. A small dark blotch might add $50 to a bill’s value, while a dramatic streak across the whole note can push it well past $1,000. A $10 bill with a heavy, full-width ink smear has brought around $700 in the past.
Check both sides of any bill you get in change, especially fresh ones straight from a bank. Look at the margins, the serial numbers, and the ink itself for anything that looks off compared to a normal bill. Genuine errors are mechanical mistakes from the printing process, not damage from wear, and not alterations someone made later. Washing, bleaching, or trimming a bill to fake an error destroys its value rather than creating it. For anything that looks like a serious error, professional grading from PMG or PCGS protects the value and confirms it’s real.
2. A $10 bill with a fancy or low serial number
Image Credit: Heritage Auctions
Every bill has an eight digit serial number printed twice on the front, and collectors chase specific patterns regardless of denomination. A ladder, where the digits run in order like 12345678, is the rarest and can bring anywhere from $9 to $10,000 depending on how clean the sequence is. Repeaters, radars that read the same forward and backward, and solid numbers where every digit matches all carry smaller but real premiums, often a few dollars up to a few hundred. Low serial numbers matter too. Anything under 100 can bring $10 to over $1,000, and a true 00000001 can bring as much as $15,000.
This is the one item on this list that applies to money you might be holding right now. The pattern matters more than the bill itself, so a $10 note with a ladder serial number is worth roughly the same as a $1 or $20 with the identical pattern. Check the two serial numbers on the front of any bill before you spend it. It takes a few seconds and costs nothing.
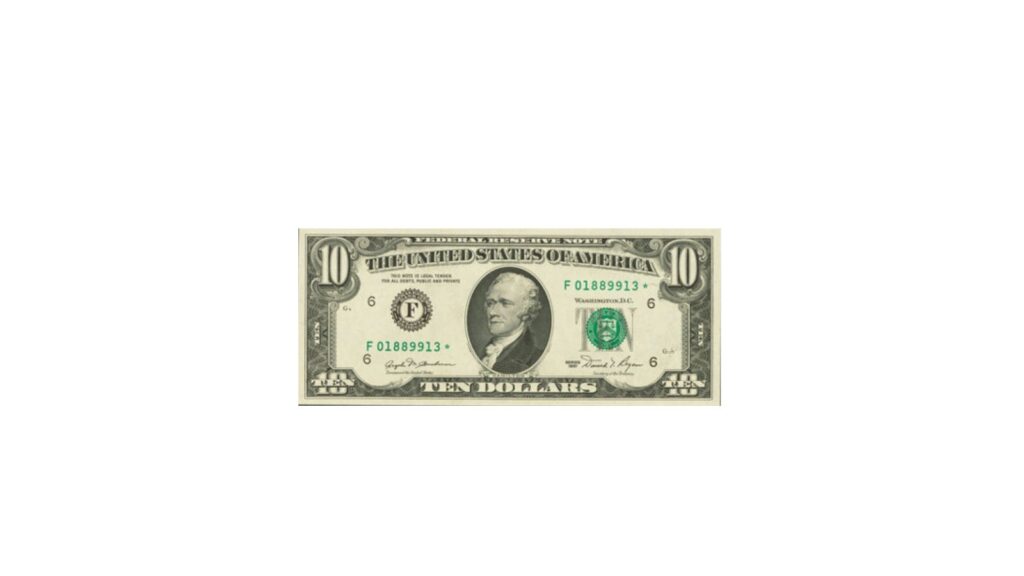
3. A $10 star note from a small print run
Image Credit: Heritage Auctions
When a sheet gets damaged during printing, the Bureau replaces it with a star note, identified by a small star symbol at the end of the serial number instead of a letter. Most modern $10 star notes are common and worth close to face value in circulated condition, maybe $10 to $15. Crisp uncirculated examples run a bit higher, generally $15 to $30. The number that actually moves the price is the print run size for that specific series and Federal Reserve district. When the run comes in at 640,000 notes or fewer, especially the smaller runs of 320,000, 160,000, or 80,000, the premium can climb to $25 to $60 or more depending on condition.
Finding the run size takes a little digging. You need the series year printed near the portrait and the full serial number including the prefix letters, then you can look up the specific print run for that combination. Older star notes tend to have smaller runs and higher premiums, but a modern star note from an unusually small batch can still outperform an older one from a large print run. Keep any star note flat in a sleeve rather than folded in a wallet, since condition affects the value as much as rarity does.
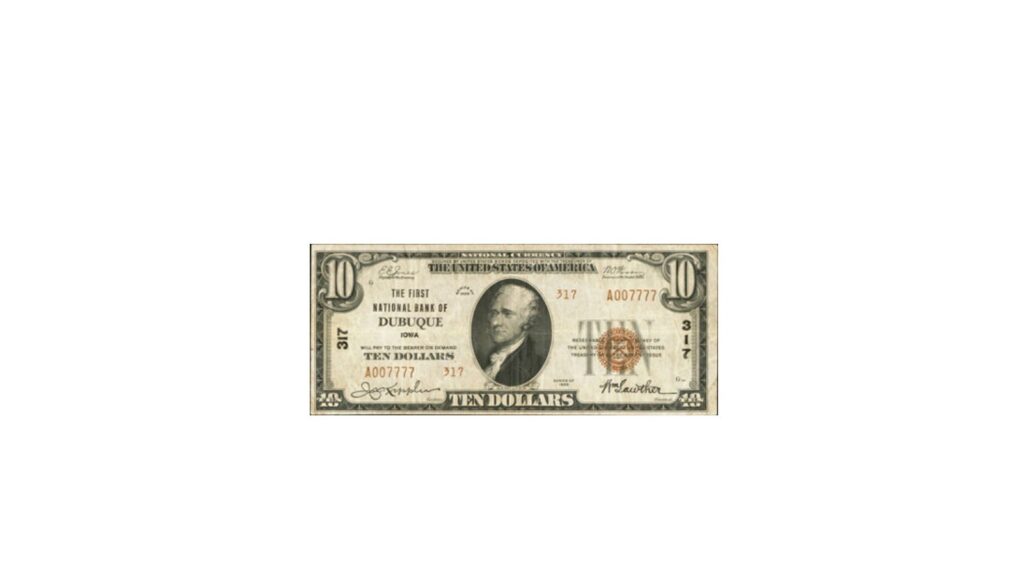
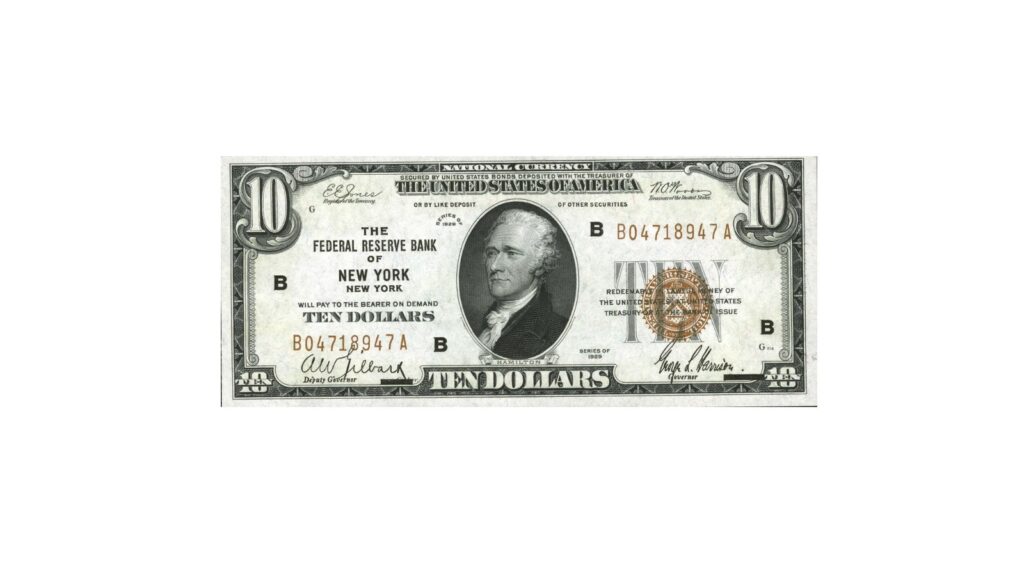
4. A 1929 $10 bill with a brown seal
Image Credit: Heritage Auctions
Two entirely different types of currency share this look, and telling them apart matters for value. Federal Reserve Bank Notes have “Federal Reserve Bank” printed in the bank title and a bold letter stamped four times on the bill. A common, non-star example in average circulated condition is worth about $20, while a bill that’s never been folded can bring $100 or more.
National Bank Notes are the other type, printed with the words “national bank” in the title and a serial number tied to the issuing bank’s charter. These depend heavily on which bank issued them. A note from a common bank typically brings $40 to $100, one from a slightly scarcer bank can reach $250, and notes from genuinely rare small town banks sometimes exceed $500. Before assuming a brown seal ten is worthless, look up the charter number and bank name printed on it. That single detail, more than the bill’s condition, is what separates a $40 note from a $500 one.
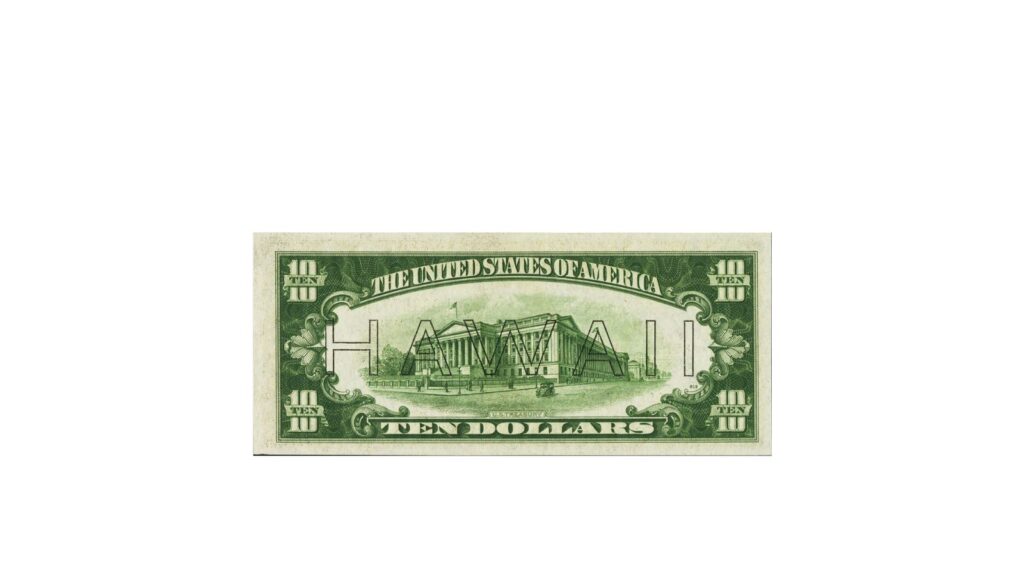
5. A 1934A $10 Hawaii note
Image Credit: Heritage Auctions
After the attack on Pearl Harbor, the Treasury feared a Japanese invasion of Hawaii and issued specially marked currency so it could be declared worthless if captured. These notes carry a brown seal and brown serial numbers, with the word HAWAII stamped in bold outline letters across the back and smaller overprints on the front. They circulated only in the islands from 1942 to 1944.
A standard circulated example is worth about $50 today, while a choice uncirculated note starts around $300 and climbs from there with grade. The design is simple compared to some wartime issues, with no rare block varieties to chase, which keeps it more of a solid historical piece than a jackpot find. Check that the brown seal and serial numbers are genuinely brown rather than the standard green seal, and confirm the HAWAII overprint appears clearly on both the front and back. Given how many of these were printed and how often they turn up in estate collections from Pacific veterans’ families, this is one of the more realistic wartime notes to actually own.
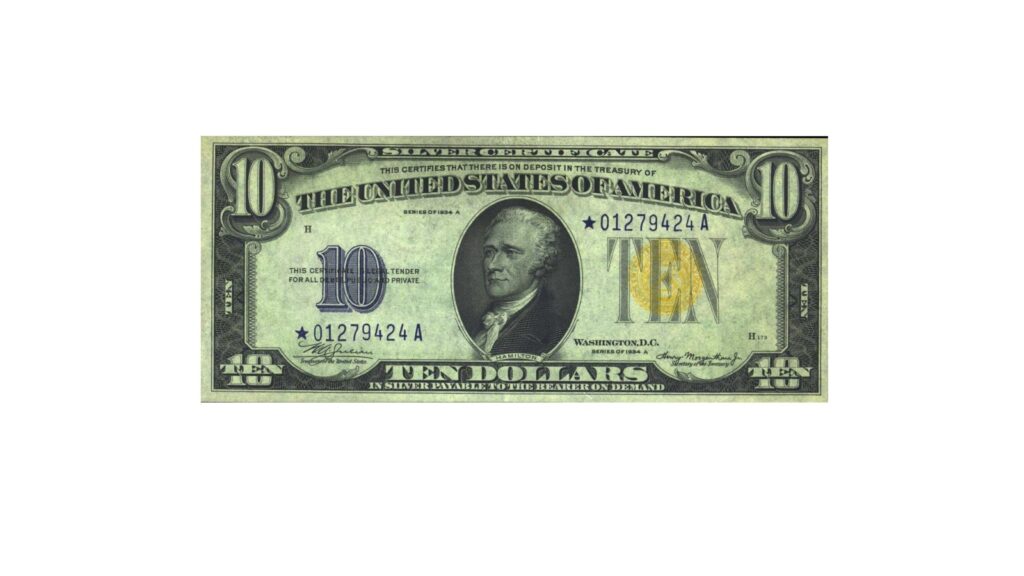
6. A 1934A $10 North Africa note
Image Credit: Heritage Auctions
A companion to the Hawaii notes, this yellow seal silver certificate was issued for American troops in the North African and European theater starting in 1942, again so it could be voided if enemy forces captured large amounts of it. A circulated 1934A example typically brings around $30, with uncirculated notes starting near $200 and rising slowly.
There’s a rarer sibling worth knowing about. The plain “1934” version, without the A, is genuinely scarce and circulated examples start at $1,500. Because the two look almost identical, some fakes are made by removing the A from a common 1934A note to pass it off as the rare version, so any plain 1934 North Africa note should be checked closely for disturbed paper near the series date before anyone pays a premium for it. For most people, what turns up is the common 1934A, still a genuine piece of WWII history and worth setting aside rather than spending.
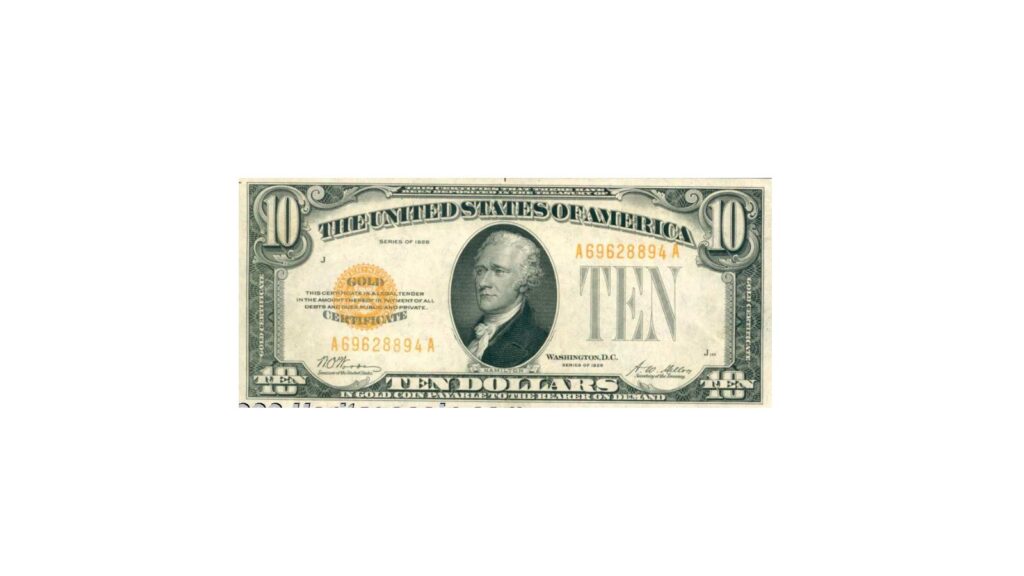
7. A 1928 $10 gold certificate
Image Credit: Heritage Auctions
Before 1933, this bill could be exchanged for actual gold at a bank, which is why it carries a bright yellow gold seal instead of the familiar green one. It was the smallest denomination gold certificate ever issued in the small size format, which meant the Bureau printed a huge number of them, and that volume keeps common examples affordable today.
A lightly circulated example is worth around $75, while uncirculated notes climb into the hundreds and the scarcest high grade examples have reached close to $9,800. Star note replacements are worth considerably more than a standard bill in the same condition. Confirm the seal is genuinely gold or yellow rather than green before getting excited, since a worn green seal Federal Reserve Note can look similar under bad lighting. This is a good starter piece for anyone curious about old currency because genuine examples aren’t hard to find, even if the truly high grade ones are.
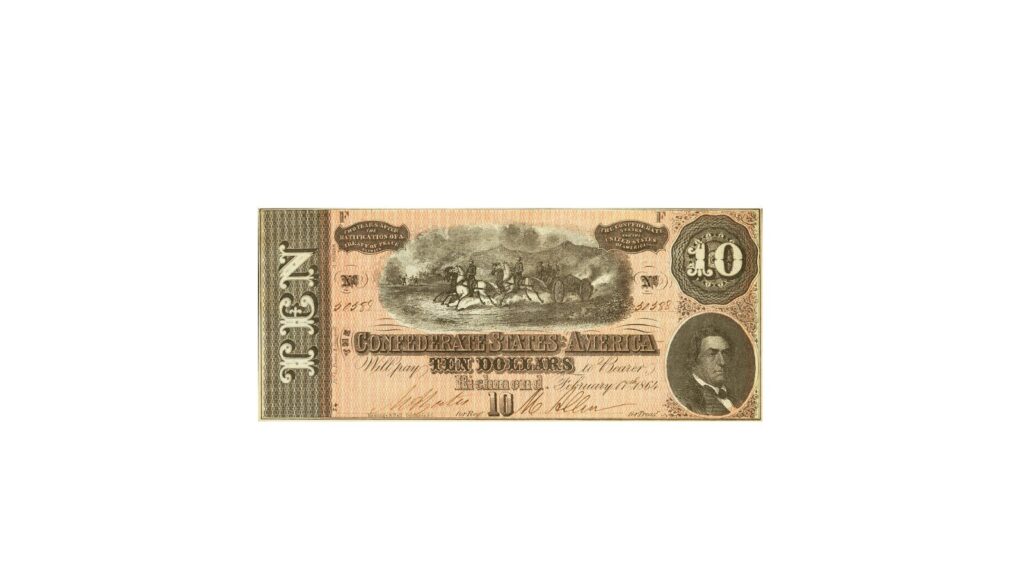
8. A 1864 Confederate $10 note
Image Credit: Heritage Auctions
Not every valuable old ten in a family collection is federal currency. Confederate notes from the Civil War era show up regularly in estate sales and inherited paper, and the February 1864 ten dollar issue, featuring cavalry pulling a cannon into battle, is one of the more commonly encountered types. Depending on condition, these range from about $12 to $4,000, with most surviving examples landing toward the lower end of that range.
The bigger risk here isn’t overvaluing a worn note. It’s mistaking a reproduction for the real thing. A large share of Confederate $10 bills that circulate among the public today are 20th century souvenir reprints with no collector value, and certain serial numbers are known to only appear on reproductions. Genuine notes were hand numbered and hand signed by Confederate treasury officials, so look closely at the signatures and the texture of the paper before assuming you’ve found something valuable. If the numbers match a known reproduction batch, it’s a neat piece of history, just not a financial one.
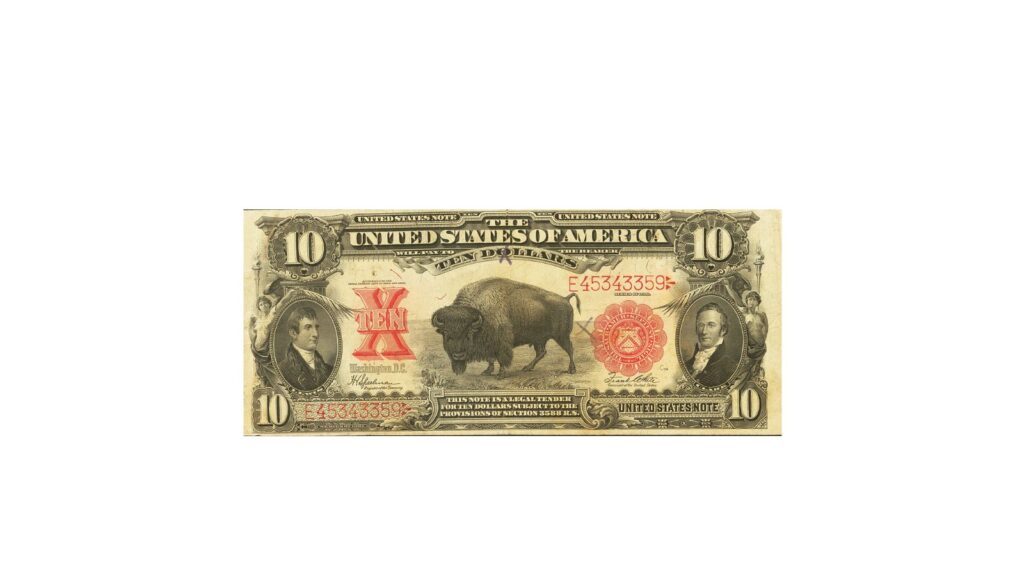
9. A 1901 $10 Bison legal tender note
Image Credit: Heritage Auctions
Nicknamed for the American bison stamped across its center, flanked by portraits of Lewis and Clark, this large size note is nearly twice the size of a modern bill and instantly recognizable. It isn’t especially rare in absolute terms, since it circulated for two decades, but condition swings the price dramatically.
A heavily worn example with tears or writing typically brings a few hundred dollars or less. One in fine to very fine condition, the grade most commonly found, usually brings $500 to $1,000, and a crisp, lightly folded example can reach $1,000 to $3,000. Choice uncirculated notes start around $5,000 and climb from there. Star note replacements are rare enough on their own to start near $1,500 regardless of condition. Check for tape, missing corners, or repairs, since any restoration work collapses the value even on an otherwise good looking note. This is one of the more satisfying pieces to own precisely because it’s genuinely findable, not a needle in a haystack.
For Americans abroad considering a move away from DIY tax software, the reasons can be practical: less time, more complicated finances and questions that an automated interview does not resolve. For a parent managing work, children and life in another country, getting answers can matter as much as the preparation fee.
Software still works well for many straightforward returns. The decision to seek help often begins when circumstances change. A separation, new job, overseas pension or freelance income can turn a task into something that deserves another look.
A low software price is appealing when one income supports the household. But the checkout amount does not capture the hours spent collecting records, researching unfamiliar terms and checking whether an answer applies abroad.
Picture a hypothetical single mother in Germany opening her return after bedtime. She has a local salary, a small freelance project and savings for her child. The software asks a reasonable question about foreign accounts. She is unsure which accounts count.
Finding those facts can take the evening.
Paying for help can be a way to protect time, although it should fit the household budget rather than create another financial strain.
Family changes can make familiar answers unreliable
A change in relationship or custody arrangements can affect filing status and who may claim a child. Reusing last year’s answers without checking them can carry an outdated assumption into a new return.
Being a single parent does not automatically qualify someone for head of household status. Requirements generally include being unmarried or considered unmarried, paying more than half the cost of maintaining the home and having a qualifying person.
Parents living apart may also need to review where the child lived and whether any release of a dependency claim applies. Different benefits can follow different rules.
A preparer should ask about these details sensitively and explain what documentation matters. The goal is an accurate return, without making parents guess how family arrangements translate into tax categories.
A smaller tax bill is not the only calculation
Parents abroad may need to compare foreign-income relief with potential child-related benefits. A return showing no US income tax does not necessarily mean every available benefit has been considered.
The Foreign Earned Income Exclusion can shelter qualifying overseas earnings, but claiming it prevents a taxpayer from claiming the refundable Additional Child Tax Credit. The IRS guidance on choosing the exclusion explains that restriction.
The Foreign Tax Credit may offer another approach when qualifying foreign income taxes have been paid. Whether it produces a better outcome depends on the family’s circumstances, credit eligibility and previous elections.
This is where help with US expat tax filing can be useful. A professional can explain the trade-offs instead of leaving a parent to assume that excluding the largest possible amount always gives the best result.
Ordinary overseas accounts can raise unfamiliar questions
A local bank account or workplace pension may feel like a routine part of life. US reporting can treat it differently from the country where the family lives.
Foreign account reporting may involve FBAR, Form 8938 or both when their respective requirements are met. These are separate obligations, and a zero income-tax balance does not automatically remove them.
Some overseas investment funds can also require specialised reporting. A savings product marketed as tax-efficient locally should not be assumed to receive matching US treatment.
Software may support the necessary forms, but users still need to identify their accounts and investments correctly. That is one reason a parent might request a review even after years of successful DIY filing.
Human support should provide clear answers
The benefit of professional preparation depends on the service actually provided. Paying more does not guarantee better explanations or relevant international experience.
Ask whether the preparer regularly handles clients in your country, families with children and the types of income you receive. Find out who reviews the return and whether questions are answered directly or through a support team.
A useful answer explains the relevant facts and the proposed treatment in everyday language. If a question needs further investigation, the preparer should say so.
Good support also includes a clear document list and realistic communication expectations. Repeated requests for the same information can undermine the time saving that motivated the switch.
The quote should match the household’s needs
Request a written quote that identifies included returns, schedules and foreign account reports. Ask what costs extra, including amendments, planning conversations and assistance with tax notices.
There may be a middle option between fully independent filing and ongoing professional preparation. A consultation or review can help resolve a specific issue, depending on what the provider offers.
Avoid budgeting around a promised refund before eligibility has been established. The service should explain its fee independently of optimistic estimates.
Keep copies of records and completed returns, and review the final figures before signing. Hiring help does not remove the need to understand what is submitted.
DIY can still be the right choice
A straightforward return, supported forms and confidence in the rules can make DIY software a sensible option. Seeking help becomes more attractive when uncertainty consumes time or important family details need interpretation.
The practical choice is the one that supports both compliance and the household’s capacity. Parents do not need to prove financial independence by handling every tax question alone.
Financial planning for American families is becoming more complex. Rising costs, changing tax rules, evolving investment options, and new government programs are forcing families to rethink how they save, invest, and prepare for the future.
For many households, financial planning is no longer just about building retirement savings. Families are now considering how to fund education, transfer wealth to the next generation, manage tax exposure, and create long-term financial security.
Recent changes in tax policy have also introduced new savings tools designed to help families build wealth earlier in life. One example is the introduction of new child investment accounts known as Trump Accounts, which are intended to encourage long-term saving for children.
Understanding how these changes fit into an overall financial strategy can help families make more informed decisions.
Why financial planning is changing for modern families
Traditional financial planning often focused on three major goals: buying a home, saving for retirement, and paying for children’s education.
Today, families face additional challenges, including:
Higher living costs
Longer retirement periods
Changing tax regulations
Increased investment choices
The need for multigenerational wealth planning
Families are also becoming more aware that financial decisions are connected. Choosing one type of savings account or investment strategy can affect future taxes, retirement income, and inheritance planning.
For example, parents saving for a child’s future may need to consider whether a 529 plan, custodial account, retirement account, or newer savings option provides the best long-term benefits.
The rise of tax-advantaged savings options
Tax advantages have become an important part of financial planning. Many families are looking beyond traditional savings accounts and exploring investment vehicles that allow money to grow more efficiently.
Common tax-advantaged accounts include:
401(k) retirement plans
Traditional and Roth IRAs
529 education savings plans
Health Savings Accounts (HSAs)
Child-focused investment accounts
Each option has different rules regarding contributions, withdrawals, taxes, and eligibility.
A financial plan should not focus only on how much money is saved but also on how those savings will be taxed in the future.
For example, contributing to a traditional retirement account may provide tax benefits today, while Roth accounts may provide tax-free withdrawals later. The right choice depends on a family’s income, goals, and expected future tax situation.
What are trump accounts and how could they affect family planning?
A newer addition to the financial planning landscape is the introduction of Trump Accounts.
What are Trump Accounts? They are tax-advantaged investment accounts designed to help families save for children’s financial futures. These accounts are intended for eligible children and allow funds to grow over time through investments.
Trump Accounts represent a shift toward encouraging families to begin investing earlier. Instead of waiting until adulthood to start building wealth, these accounts aim to provide children with an early financial foundation.
Some key features include:
Designed for children under age 18
Long-term investment growth potential
Government contributions for eligible children
Additional contributions from parents, employers, or other contributors may be allowed depending on the rules
For families, the main benefit is the opportunity to introduce long-term investing at an early stage. However, these accounts should be considered alongside other financial tools rather than viewed as a replacement for existing strategies.
How families should compare different savings strategies
No single financial product works for every family.
When deciding how to save, families should consider:
Financial goals
A family saving for college may prioritize flexibility and education benefits, while a family focused on wealth transfer may prioritize long-term investment growth.
Tax treatment
Understanding whether contributions are deductible, whether growth is tax-deferred, and how withdrawals are taxed can significantly affect the final outcome.
Time horizon
The longer money remains invested, the more important compound growth becomes. Starting early can create a significant advantage over time.
Family circumstances
Income level, number of children, employment benefits, and existing investments all influence which strategy makes sense.
The growing importance of multigenerational planning
Many families are now thinking beyond their immediate financial needs and focusing on wealth transfer.
This includes:
Helping children build financial independence
Planning inheritances
Protecting family assets
Reducing unnecessary taxes
Starting financial conversations early can help children understand saving, investing, and responsible money management.
New tools like child investment accounts may also encourage families to think about financial planning as a long-term process rather than a series of separate decisions.
Why tax planning should be part of financial planning
Financial decisions often have tax consequences.
A family may have multiple sources of income, investments, retirement accounts, and savings vehicles. Without proper planning, tax obligations can reduce the amount of wealth that remains available for future goals.
Important areas to review include:
Retirement contribution strategies
Investment tax treatment
Education savings options
Estate and inheritance considerations
Changes in tax laws
Tax planning should happen throughout the year, not only when filing a tax return.
Preparing for the future financial landscape
The future of financial planning will likely involve more personalized strategies, greater focus on tax efficiency, and increased use of investment tools designed for different stages of life.
Families should regularly review their financial plans to ensure they still match their goals. A strategy that works today may need adjustments as income, family circumstances, and tax laws change.
New programs such as Trump Accounts may provide additional opportunities, but they are only one part of a complete financial plan.
Final thoughts
The financial planning landscape for American families is changing. Families now have more tools available to save, invest, and build long-term wealth, but they also face more complex decisions.
Understanding how different accounts work, how taxes apply, and how each option fits into a broader strategy can help families make better financial choices.
Whether planning for retirement, education, or generational wealth, the most effective approach is usually a coordinated plan that considers both today’s needs and tomorrow’s goals.
You’ve got the keys, the truck is gone, and somewhere under all those boxes is a coffee maker you’re too tired to dig out. This is usually the moment people start thinking about the fun stuff. Paint colors. That one shelf in the kitchen that’s never quite in the right spot. Maybe a new couch.
It’s also the moment a short list of unglamorous jobs quietly decides whether next year is smooth or expensive. Here’s one most people never think about: you have no idea how many keys exist for your own front door. The sellers might have handed you two, but a house that’s changed hands a few times can have copies scattered around with an old real estate agent, a contractor who redid the kitchen a few years back, or a neighbor who used to feed the cat. That’s not a reason to panic. It’s a reason to spend one afternoon fixing it before you unpack another box.
Rekeying a lock usually runs somewhere between $15 and $30 per lock if you hire a locksmith, and less than that if you buy a rekey kit and do it yourself over a weekend. Replacing the hardware entirely costs more, but it’s worth it if the deadbolt sticks, the finish is worn through, or you’d rather just start clean with new mechanisms on every door.
Don’t stop at the front door. Back doors, side entries off the garage, and any sliding door leading to a patio all need the same treatment. If the house came with a keypad or smart lock, reset it to a brand new code right away instead of assuming the previous owner wiped every code before handing over the keys. People forget this constantly, and it’s the whole point of doing it in week one.
While a locksmith is already there, ask them to check your window locks too, especially on ground floor rooms and anything near a fire escape or deck. And skip the fake rock or the spare key under the mat. Whoever lived there before you may already know exactly where it is.
Reset the garage door opener’s code
Image Credit: Shutterstock
A garage is one of the easiest ways into a house, and a lot of people never think about who else might still be able to open theirs. Older garage door openers use a fixed code that never changes, which means any remote programmed to that code, including ones from years ago, can still let someone in. Newer systems use a rolling code that changes every time you press the button, which is much harder to duplicate.
If you’re not sure which kind you have, check the opener’s manual or look up the model number online. Either way, reprogram the remotes and reset the keypad code as soon as you move in. It takes about ten minutes and it closes off an entry point that a surprising number of new homeowners never think to check.
While you’re in there, test the auto-reverse safety feature by placing a piece of wood on the ground where the door closes. A properly working door should reverse the moment it touches the wood instead of continuing to press down. If it doesn’t, that’s a separate repair worth calling a professional for, since it’s a real hazard for kids and pets, not just a security gap.
Swap the mailbox for a locking one
Image Credit: Shutterstock
Your mailbox sits at the curb, unattended, for hours at a time, and it often holds exactly the kind of paperwork identity thieves are after: bank statements, new checks, tax documents, prescription notices. Local police departments recommend getting a locking mailbox as one of the simplest ways to cut that risk down, along with picking up mail promptly and keeping the box itself in good repair.
A locking mailbox costs anywhere from $40 to a few hundred dollars depending on the style, and installation is usually a weekend project if you’re comfortable with a shovel and quick-set concrete. If you travel often or you’re the type who lets mail pile up for a few days at a time, this is one of the cheapest security upgrades you can make.
Check with your local postmaster before you buy, since some mail carriers won’t deliver to boxes that don’t meet certain size and approach specifications. And if you’re expecting checks, new cards, or anything else worth stealing, don’t leave it sitting in the box overnight even with a lock. Bring it in the same day it arrives whenever you can.
Check the age of every smoke detector
Image Credit: Shutterstock
Smoke detectors don’t last forever, even the hardwired ones. The sensors lose sensitivity as dust and grime build up inside them over the years, and consumer safety officials recommend replacing every smoke alarm once it hits ten years old, regardless of whether it still beeps when you test it.
Flip each detector over and look for a manufacture date stamped on the back. If you can’t find one, or the house has clearly had the same detectors since the last decade, replace all of them now rather than one at a time. It’s a small expense, usually $10 to $25 per unit, and it’s one of the few home repairs where waiting has an actual body count attached to it. While you’re up there, make sure there’s one in every bedroom, outside each sleeping area, and on every level of the house, including the basement.
Test each one with the button on the front once you’ve got them installed, and don’t just assume a beep means it works. A weak or delayed beep can be a sign of a dying battery even in a unit that’s technically still under ten years old.
Add carbon monoxide detectors where you don’t have them
Image Credit: Shutterstock
Carbon monoxide is odorless, colorless, and can kill you in your sleep, which is exactly why so many homes still go without proper detection. If your house has a furnace, water heater, fireplace, or attached garage, you need a working CO detector on every level and near sleeping areas, full stop. Unlike smoke alarms, CO detectors have a shorter shelf life, and the same safety officials who set the ten year rule for smoke alarms recommend swapping out CO alarms every five years.
Combination smoke and CO units exist and can simplify this, but check the CO sensor’s individual expiration separately since it often runs out well before the smoke sensor does. A basic plug-in CO detector costs around $20 to $40. Given what’s at stake, this isn’t a corner worth cutting to save a few dollars.
Early carbon monoxide exposure can look a lot like the flu, with headaches, dizziness, and nausea that seem to fade when you leave the house and come back once you’re home again. If everyone in the house gets sick around the same time and it improves when you’re out, treat that as a real signal to get the air tested, not a coincidence to shrug off.
Replace the fire extinguisher if it’s past its date
Image Credit: Shutterstock
An old fire extinguisher isn’t just useless in a fire, it can actually fail to discharge properly when you need it most. State fire marshals recommend replacing a home fire extinguisher once it’s more than ten years old, and that clock starts from the manufacture date stamped on the canister, not from when you bought it or moved into the house.
Check the pressure gauge too. It should read in the green zone, and if it doesn’t, replace the unit regardless of its age. Keep at least one multipurpose extinguisher in the kitchen and one in the garage, and don’t mount them directly above the stove or the dryer where heat could damage them over time. A new extinguisher runs $20 to $50, which is nothing compared to what it can save you in a small kitchen fire that gets out of hand.
Look for the ABC rating on the label, which covers ordinary combustibles, flammable liquids, and electrical fires all in one unit. That’s the kind you want for general home use rather than one rated for a single fire type.
Get GFCI outlets in the kitchen and bathrooms
Image Credit: Shutterstock
Ground fault circuit interrupters cut power in a fraction of a second if they sense current going somewhere it shouldn’t, which is exactly the kind of protection you want in rooms where water and electricity share close quarters. Safety regulators have long pointed to kitchens and bathrooms as the areas of greatest risk for electrocution in the home, along with basements, garages, and outdoor outlets.
If your house predates the outlets being required, you don’t need to rewire the whole electrical panel to fix this. A licensed electrician can swap standard outlets for GFCI versions in an afternoon, or you can start with inexpensive plug-in adapters while you save up for the permanent fix. Either way, don’t treat this as optional just because the old outlets still work fine on the surface.
Test the ones you already have. Every GFCI outlet has a small test and reset button on the front, and pressing test should cut power immediately, with reset bringing it back. Do this once a month, since a GFCI that’s failed internally can look completely normal while offering none of the protection it’s supposed to.
Find out if your home has aluminum wiring
Image Credit: Shutterstock
This one only applies to a specific slice of houses, but it matters a lot if yours is one of them. An estimated two million homes were built with aluminum branch wiring between 1965 and 1973, and that wiring is prone to loose, overheating connections that regular copper wiring doesn’t have.
Look at your home’s build year first. If it falls in that window, have a licensed electrician check the panel and outlets for aluminum conductors, which are usually marked “AL” or “Aluminum” along the cable. Warning signs include warm outlet covers, flickering lights, or a faint burning smell near switches. The fix isn’t cheap, often running several thousand dollars for a full repair, but it’s the kind of thing you want to know about before it becomes an insurance problem or worse.
Don’t try to inspect the panel yourself if you’re not trained for it. Opening a breaker box exposes live components, and this is one job where the cost of a professional is a lot smaller than the cost of a mistake.
Swap the washing machine hoses for braided steel
Image Credit: Shutterstock
Rubber supply hoses are one of the most common and most expensive things to go wrong in a house, mostly because they fail quietly, usually while nobody’s home. Home insurers paid out nearly $30 million in a single recent year on claims tied to washing machine hose failures, and a burst hose can put out roughly 650 gallons of water an hour. Leave for a weekend and come home to a flood.
The fix costs less than $20 and takes ten minutes. Buy a set of braided stainless steel hoses, which hold up far better than rubber, and swap them onto both the hot and cold connections. Even braided hoses are best replaced every three to five years, so mark it on a calendar rather than assuming they’ll last forever once installed.
While you’re back there, get in the habit of turning off the water supply valves whenever the washer sits idle for more than a few days, especially if you’re leaving town. It’s an extra step most people skip, but it removes the pressure that causes hoses to fail in the first place.
Replace the toilet flapper and fill valve
Image Credit: Shutterstock
A worn toilet flapper is one of the sneakiest ways to waste water, since a slow leak often makes no sound at all. Across the country, leaky fixtures like this cause the average home to waste more than 9,000 gallons of water a year, which shows up as a water bill that’s roughly ten percent higher than it needs to be.
Flappers cost about $5 to $15 and take fifteen minutes to swap with basic tools. If you want to test whether yours is the culprit, drop a few drops of food coloring into the tank and check the bowl ten minutes later without flushing. Any color in the bowl means water is leaking past the flapper. Fill valves are just as cheap to replace and worth doing at the same time if the toilet runs constantly or takes forever to stop filling.
Do this in every bathroom, not just the one you use most. Guest bathrooms and half baths are the easiest place for a slow leak to run unnoticed for months, since nobody’s in there often enough to hear it.
Check your water heater’s age
Image Credit: Shutterstock
A tank water heater that fails doesn’t usually give much warning, and when it goes, it tends to go all at once, sending gallons of water across your floor. A typical storage tank water heater lasts 10 to 15 years, so the first thing worth doing is finding the serial number on the unit’s sticker and looking up its manufacture date.
If yours is already past the ten year mark, don’t wait for a leak to force your hand. Start budgeting for a replacement now and keep an eye out for rust-colored water, a rumbling or popping sound during heating, or moisture pooling at the base of the tank. Catching it early means you get to choose the timing and the model instead of scrambling for whatever a plumber can install same day during an emergency.
Flushing the tank once a year clears out sediment that builds up at the bottom and makes the unit work harder than it needs to. It’s a job most homeowners can do themselves with a garden hose and about twenty minutes, and it can add real years to the tank’s working life.
Test your water pressure and add a regulator if needed
Image Credit: Shutterstock
High water pressure feels great in the shower and is hard on everything downstream of your meter. Most plumbing codes require a pressure reducing valve once incoming pressure tops 80 pounds per square inch, since sustained pressure above that level can damage pipes, water heaters, toilets, and appliance connections over time.
A pressure gauge that screws onto an outdoor spigot costs about $10 and gives you a reading in seconds. If you’re above 80 psi, or even getting close, a licensed plumber can install a pressure reducing valve near the main shutoff for a few hundred dollars. It’s a small job that quietly protects every fixture and appliance in the house for years afterward.
Banging pipes when you shut off a faucet, toilets that run louder than they should, or fixtures that wear out faster than the ones in your last place are all signs worth paying attention to. If your home already has a pressure reducing valve, it’s still worth checking, since these valves wear out over time and can fail without any obvious warning, quietly letting pressure creep back up to damaging levels.
Put a battery backup on the sump pump
Image Credit: Shutterstock
If your basement has a sump pump, its whole job is to keep water out during the exact storms that also tend to knock out power. A pump with no backup power is a pump that shuts off right when you need it most. Just one inch of floodwater can cause roughly $25,000 in damage to a home, and most standard homeowners policies don’t cover flooding at all.
A battery backup system typically costs $150 to $500 for the unit, plus installation if you’re not doing it yourself. It kicks in automatically the moment the primary pump loses power or fails outright, buying you hours instead of minutes. If your sump pump is more than seven years old, this is also a good time to have it inspected, since pumps that age tend to fail quietly long before anyone notices.
Test the whole system a couple of times a year by pouring a bucket of water into the pit and watching the float switch trigger the pump. It’s a five minute check that tells you whether the setup will actually work the next time a storm rolls through and the power flickers off.
Cover the outdoor faucets before the first freeze
Image Credit: Shutterstock
Exterior faucets sit right up against the coldest part of your house, and if water is trapped inside the pipe when temperatures drop, it can freeze, expand, and split the line open somewhere you can’t easily see. The break often doesn’t show itself until spring, when you turn the faucet on for the first time and water sprays out somewhere unexpected, sometimes inside a wall.
Before the first hard freeze of the season, disconnect and drain any garden hoses, then slide an insulated foam cover over each spigot. If your home has an interior shutoff valve for the outdoor lines, close it and drain the line from outside too. Foam covers cost a few dollars each at any hardware store, and taking twenty minutes to do this in the fall can save you a plumber’s visit and a soaked drywall repair come spring.
If your outdoor faucets are the older style rather than a frost-proof model, ask a plumber about swapping them during any other work being done on the house. Frost-proof spigots set the shutoff valve further back inside the wall, away from the cold, and they’re a small upgrade that removes this whole problem going forward.
Change the HVAC filter and figure out its size
Image Credit: Shutterstock
Most homeowners have no idea what size filter their furnace or air handler takes until the old one is already falling apart. Find that number now, write it somewhere you’ll actually remember, and buy a few filters in bulk so you’re never stuck improvising. Home maintenance experts generally recommend swapping filters every one to three months, with pets or heavy use on the shorter end of that range.
A clogged filter forces your system to work harder to move the same amount of air, which drives up your energy bill and shortens the life of the equipment. It’s one of the cheapest maintenance habits in the entire house, usually $10 to $20 per filter, and it’s also one of the easiest to forget until something starts running loud or blowing weak.
Set a recurring reminder on your phone rather than trusting yourself to remember. Higher MERV ratings filter out more dust and allergens, but check your system’s manual first, since some older units aren’t built to handle the airflow restriction that comes with a denser filter.
Clean out the dryer vent
Image Credit: Shutterstock
Lint building up inside a dryer vent is a fire risk, not just an efficiency problem. Fire officials report roughly 15,600 structure fires a year tied to clothes dryers, with failure to clean the dryer and its vent system named as the single biggest contributing factor in around a third of those fires.
If you don’t know when the vent was last cleaned, or your dryer has always taken longer than it should to finish a load, that’s your sign. A rigid metal duct is safer than a flexible plastic one, so swap it out if your dryer still has the flimsy accordion-style tubing. Professional vent cleaning runs $100 to $200, or you can rent a vent cleaning kit and do it yourself for under $40 if you’re comfortable pulling the dryer away from the wall.
Check the outside vent hood too, not just the duct inside the house. Birds and rodents build nests in these more often than people expect, and a blocked exterior flap causes the exact same buildup and overheating risk as a clogged interior vent.
Add weatherstripping around doors and windows
Image Credit: Shutterstock
Drafts around doors and windows are one of the biggest quiet drains on a heating and cooling bill. Federal energy officials estimate that 10 to 20 percent of a home’s annual energy costs get lost to air leaks and drafts, a lot of which comes from gaps around doors, windows, and other openings that are cheap and fast to seal.
Run your hand around door and window frames on a windy day and you’ll usually feel exactly where the leaks are. Weatherstripping and caulk together cost under $30 for most homes and pay for themselves within a year in lower utility bills. It’s not a glamorous project, but it’s one of the few home upgrades where the return shows up almost immediately on your next statement.
Check less obvious spots too, like the attic hatch, electrical outlets on exterior walls, and where pipes or wiring pass through the foundation. These gaps rarely get noticed during a walkthrough, but they add up to real losses over a full year of heating and cooling.
Install a smart or programmable thermostat
Image Credit: Shutterstock
A thermostat that’s still set the way the previous owner left it is money leaking out of the house every single day. Certified smart thermostats save the average household more than 8 percent on heating and cooling, which works out to roughly $50 a year, just by adjusting temperatures automatically based on your schedule and habits.
Installation is usually a thirty minute job if your home already has compatible wiring, and most models walk you through the setup with a phone app. Basic units start around $100, though many utility companies offer rebates that knock a chunk off that price. Even a simple programmable thermostat without the smart features will get you most of the savings if you’re not ready to deal with an app.
Someone in your house still has a Tamagotchi in a drawer, dead since around 1998, because feeding a digital egg every twenty minutes was never going to survive homework and dinner. Somewhere else there’s a grey PlayStation with a tangle of controller cords, or a Motorola flip phone nobody had the heart to throw out. None of it looked like money at the time. It looked like stuff that got old fast.
The 1990s built a lot of things designed to be swapped out within a few years, which is exactly why the ones that survived intact are worth checking now. This was the decade of the first mainstream home internet devices, the first pocket digital pets, and a genuine console war, and almost none of it was built with the next thirty years in mind. Condition and completeness decide most of what something is worth here. A grimy, untested console pulled out of a closet is worth a fraction of the same thing with its box, cables, and manual still with it.
The original Tamagotchi launched in Japan in November 1996 and hit the US the following year, and it became the toy every kid was smuggling into school inside a coat pocket. Bandai has re-released the design more than once since, most notably a 2017 anniversary version and the newer Tamagotchi Uni line, so before getting excited about a find, check that the shell shape and printed logo match the mid to late 90s original rather than a modern reissue.
Sealed, unopened original units in common shell colors typically bring $30 to $75, while rarer patterns and Japan-only variants push considerably higher. A used, working example without its original packaging is worth much less, usually in the ten to twenty dollar range, since the real premium lives almost entirely in unopened examples.
Test carefully before assuming a unit still works. These ran on tiny watch batteries that were never meant to last decades, and corrosion around the battery terminals is common. A clean screen with no dead pixels and responsive buttons is what separates a display piece from something a collector will actually pay for.
2. Nintendo 64, Funtastic color console (1996 to 2000)
Image Credit: Shutterstock
The standard grey Nintendo 64 that launched in 1996 is common enough that most working examples aren’t worth much beyond a nostalgia buy. What changed the math was Nintendo’s 1998 decision to sell the console in translucent “Funtastic” colors: Jungle Green, Atomic Purple, Watermelon Red, and a few others, each one showing off the circuit board right through the shell.
A standard grey console in loose, working condition runs around $60 to $90, while Funtastic-colored consoles trend closer to $150 to $250 depending on the shade and how clean the translucent plastic has stayed. The real grail here is the orange and yellow Pikachu Edition console released alongside the Pokémon launch in North America, which regularly climbs past $800 working and considerably more complete in box.
Stick drift on the analog stick is the most common failure and a straightforward repair, so don’t write off a console just because the stick feels loose. Yellowing knocks value down on the grey shell. On the colored consoles, cracking or heavy fading of the translucent plastic is the bigger red flag, since it’s much harder to disguise than a scuffed grey case.
3. Original Sony PlayStation (SCPH-1001, 1995)
Image Credit: Shutterstock
Sony’s first PlayStation launched in the US in September 1995, and the specific early model numbered SCPH-1001 is the one audio hobbyists still hunt for, since it’s the only version with separate RCA jacks for audio and video rather than one combined cable. More than 100 million units sold worldwide over its lifespan, so a loose console on its own isn’t rare.
A working, loose original PlayStation typically brings $40 to $60, while a complete example with its box, controller, and manuals climbs to $90 to $150. Factory-sealed, never-opened consoles are a different category entirely and can reach several hundred dollars, though genuinely sealed examples from this era don’t turn up often.
The most common failure is the CD laser wearing down, so a console that struggles to read discs isn’t necessarily broken beyond repair, just in need of a lens cleaning or replacement. Check that the memory card slot covers are intact, since these are frequently missing or cracked, and confirm the console actually boots a disc before treating a “for parts” listing as a bargain.
4. Motorola StarTAC (1996)
Image Credit: Shutterstock
The StarTAC was the first true flip phone most Americans ever held, small enough that Motorola marketed it as “wearable,” and it sold around 60 million units worldwide over its production run. That volume means most examples aren’t scarce, but clean, working units with an intact hinge and screen have become a real nostalgia item.
A clean, working StarTAC in black typically brings $40 to $90, and examples that still have the original box, charger, and belt clip push toward $130 to $150. Rarer color variants, including gold and blue models sold through specific carriers, bring meaningfully more than the standard black.
Battery packs from this era rarely hold a charge anymore, so don’t judge a phone as broken just because it won’t power on with its original battery. The external LCD screen and the flip hinge are the parts most likely to show wear. A phone locked to a defunct carrier network still carries full collector value, since almost nobody is buying these to actually make calls.
5. Game Boy Color, Pokémon Pikachu special edition (1998)
Image Credit: Shutterstock
Nintendo released several Pokémon-themed Game Boy Color consoles around the launch of Pokémon Red and Blue in North America, and the yellow and blue Pikachu-themed shell is the most recognizable of the bunch. It’s a genuinely findable piece for anyone who was a kid in the late 90s, since Nintendo produced real volume rather than a tiny limited run.
Clean, working examples with an unmodified shell run $100 to $180, and units that still include the original box and inserts push higher. The console’s popularity means it has also been extensively refurbished and re-shelled by sellers, so a listing describing “new shell” parts is telling you the unit isn’t in its original factory condition, which matters to purists even when the price looks similar.
Check the screen for dead pixels or a persistent green tint, both common on units this age, and confirm the speaker still produces clean sound. Battery leakage from AA batteries left inside for years is one of the most common causes of corrosion damage on the circuit board, so inspect the battery compartment closely before buying.
6. Diamond Rio PMP300 (1998)
Image Credit: Shutterstock
Before the iPod existed, the Rio PMP300 was the device that made MP3 players mainstream, holding about an hour of music on 32 megabytes of memory. Its September 1998 launch triggered a lawsuit from the recording industry that tried to block its sale entirely, a fight Diamond ultimately won, which helped clear the legal path for the digital music players that followed it.
Working, tested examples run $30 to $120 depending on completeness, and factory-sealed, unopened units are a genuine rarity that can climb into four figures with the right buyer. The parallel port cable used to connect it to a computer is frequently missing from surviving units and worth tracking down separately for a display-ready set.
The battery compartment door is the unit’s most famous design flaw and the part most likely to be cracked or missing entirely on a survivor. The silver control disc in the center also commonly falls off or loses its coating. A player with both intact, plus a legible screen, is in noticeably better shape than most examples still floating around.
7. Apple iMac G3, Bondi Blue (1998)
Image Credit: mow-motor-law_nippon via eBay
The original Bondi Blue iMac, launched in May 1998, was the first product released under Steve Jobs’s return to Apple and the machine that killed the beige desktop computer as a default. Its translucent case and total absence of a floppy drive were considered genuinely radical at the time.
A clean, fully working Bondi Blue iMac with its keyboard and mouse typically runs $150 to $250, while units missing accessories or showing heavy yellowing bring less. Later special editions in colors like Blue Dalmatian or Flower Power, made in smaller numbers toward the end of the G3 line, command meaningfully more than the original Bondi Blue when clean and working.
Yellowing of the translucent plastic is nearly universal on these machines and, while it can be reversed with effort, most buyers price a yellowed unit lower regardless. The internal capacitors on the logic board are a known failure point on machines this age, so a unit that won’t power on at all may need board-level repair rather than a simple fix. Confirm it boots to the desktop before assuming full function.
8. Nokia 8110 “banana phone” (1996)
Image Credit: vintagethinks via eBay
Nokia’s curved, slide-cover 8110 earned its nickname from its banana-like shape, but it earned its collector status from a single scene in “The Matrix,” where Neo receives one moments before the cover snaps open on its own. In reality the cover slides manually, but the film cemented the phone’s identity regardless.
Preowned examples in decent condition typically range from $55 to around $200 depending on how clean the slide mechanism is and whether the phone still holds a charge, and factory-sealed examples in original packaging bring considerably more from serious collectors.
Check that the sliding cover moves smoothly without catching, since the spring mechanism is the part most likely to wear out after decades of use. Battery contacts commonly corrode if a battery was left inside during long-term storage. Because the phone is locked to older 2G networks in most regions now, buyers are purchasing it as a display piece and film prop rather than a working phone, so cosmetic condition matters more than function.
9. Sega Saturn console (1995)
Image Credit: Shutterstock
Sega’s Saturn launched in the US in May 1995, four months ahead of its planned date, in a move meant to steal a march on the PlayStation. It didn’t work commercially, and the Saturn was discontinued by 1998, which means clean surviving consoles are less common than you’d expect from a major console launch.
A loose, working Saturn console typically brings $80 to $130, and complete examples with the box, controller, and cables climb to $200 to $300. Japanese-market Saturns, identifiable by their different button colors and region-locked games, are collected somewhat separately from US models and carry their own premium among import collectors.
The console’s biggest mechanical weakness is its CD drive belt and laser assembly, both of which degrade with age and are a common source of “won’t read discs” listings. A console that powers on and shows the Sega logo but won’t load a game may just need a belt replacement rather than being genuinely dead. Check the controller cords for fraying near the connector, a frequent failure point on original Saturn pads.
10. PalmPilot Personal or Professional (1996 to 1997)
Image Credit: Shutterstock
Before smartphones existed, the PalmPilot was the device that convinced a generation of office workers they needed a digital calendar in their pocket. Its Graffiti handwriting system, a simplified single-stroke alphabet, let it compete with Apple’s more ambitious and more expensive Newton by doing far less, far faster.
A working PalmPilot without its box typically brings $20 to $50, while a complete set with the charging cradle, stylus, and manuals reaches $80 to $130. Factory-sealed, never-opened units are a genuine rarity and have brought $200 or more with the right buyer.
The screen is worth inspecting closely, since scratches from the stylus are extremely common after years of use and are hard to fully polish out. Confirm the unit powers on with fresh AAA batteries before assuming it’s dead, since these ran for weeks on standard batteries and a “won’t turn on” listing is often just drained cells. The plastic stylus that shipped with each unit is small and frequently lost, so a complete one adds real value to an otherwise ordinary example.
11. Game Boy Pocket, rare colors (1996)
Image Credit: emher6665 via eBay
The Game Boy Pocket shrank Nintendo’s original 1989 handheld into something that actually fit in a jean pocket, with a sharper screen and a slimmer design. Nintendo sold it in a wide range of colors, including a clear shell that showed off the circuit board, well ahead of the more famous colored Game Boy Color that followed two years later.
Common colors like red, green, and black in working condition typically bring $50 to $90, while the clear and gold metallic variants, produced in smaller numbers, run closer to $100 to $180 in clean condition. Complete examples with the original box push higher still.
The power LED, which was missing on early Pocket units and added back in a 1997 revision, is worth checking, since a working light is a small detail that tells you which production run you have. Yellowing is less common on the Pocket than on the earlier grey Game Boy, but any cracking around the cartridge slot from repeated cartridge swaps is a real value hit.
12. Sega Game Gear (1991)
Image Credit: Shutterstock
Sega’s answer to the Game Boy launched in the US in 1991 with a full color screen years before Nintendo’s handhelds caught up, at the cost of battery life so short it earned a reputation for draining six AA batteries in a few hours flat. That trade-off is part of what makes a genuinely working example satisfying to find today.
A working console typically brings $40 to $90, and a complete example with the case, cables, and games can reach $150 to $200 in clean condition. Rare colorways, including a translucent yellow limited release, bring considerably more when verified authentic.
The capacitors on the internal power board are notorious for leaking and corroding the circuit board over time, and a console that won’t power on at all is very often a capacitor problem rather than a dead unit. Screen brightness fades on original units, so a dim display doesn’t necessarily mean the unit is broken. A listing describing a console as “recapped” has had this common repair already done, which is generally a plus.
13. Casio QV-10 digital camera (1995)
Image Credit: chrissieexx via eBay
The QV-10, released in Japan in 1995, was the first consumer digital camera with a built-in color LCD screen, a feature so novel at the time that it’s preserved today in Japan’s National Museum of Nature and Science as a historically significant piece of technology. Its swiveling lens let people take the first true digital selfies years before the word existed.
Despite its historical importance, the market for it stays modest. Working examples trend between $10 and $60 depending on cosmetic condition, and they show up on secondhand marketplaces regularly enough that patience usually turns up a clean one.
Confirm the LCD screen actually displays an image before buying, since a dead screen essentially defeats the camera’s whole selling point. It runs on four AA batteries, and corrosion from batteries left inside for years is a common cause of a camera that won’t power on. Minor revisions labeled QV-10A through C are printed on a label on the base, though collectors don’t treat any version as meaningfully rarer than another.
14. Sony MZ-1 MiniDisc Walkman (1992)
Image Credit: tactile_media via eBay
Sony’s MZ-1, released in Japan in late 1992, was the very first MiniDisc player and recorder ever sold, launching a format Sony hoped would replace the cassette entirely. It never caught on the way Sony wanted with American shoppers, but MiniDisc became genuinely popular in Japan and among audio enthusiasts elsewhere through the rest of the decade.
Clean, tested MZ-1 units are the piece serious format collectors chase, and working examples typically run $300 to $700 depending on cosmetic condition and whether the original recording microphone is included. More common later MiniDisc Walkman models from the mid to late 90s, which most people are actually likely to find, bring far less, usually $40 to $120 working.
The drive belt inside these units dries out and cracks with age, a common cause of a unit that powers on but won’t spin a disc. Confirm playback and recording both function, since these were sold as combination devices and a player-only unit is worth less than a full recorder. The original leather carrying case and shoulder strap, when present, add real value to a complete set.
15. Tiger Electronics handheld LCD game (1990s)
Image Credit: Rediscovered_Treasures41510 via eBay
Tiger’s line of single-game LCD handhelds, covering everything from Batman and X-Men to Sonic the Hedgehog and The Lion King, carried a retail price around twenty dollars each throughout the 90s and became a staple of car trips and waiting rooms. Hasbro reissued several of these designs starting in 2020, so check the packaging date and print quality carefully, since a modern reissue can look nearly identical to the original at a glance.
A working original from the 90s typically brings $10 to $25 loose, and a factory-sealed original example in good packaging can bring $75 to $100 or more, since sealed originals are considerably scarcer than the loose units most people find.
These ran on cheap AA or AAA batteries that frequently leaked over the decades, so battery compartment corrosion is the single biggest condition issue to check before buying. Confirm the LCD segments all display correctly, since dead pixels or missing segments are common and hard to repair. Complete units with their original box and instructions are considerably scarcer than the toy alone.
16. Apple Newton MessagePad 100 or 110 (1993 to 1994)
Image Credit: nicsel38 via eBay
Apple’s Newton MessagePad launched in 1993 as one of the company’s boldest and most mocked products, a handwriting-recognition PDA that arrived years before the technology behind it was reliable enough to deliver on its promise. It’s remembered today as an early, rocky step toward the iPhone more than a decade later.
Working units without the original box typically bring $70 to $150, and later, more capable models like the MessagePad 2000 and 2100 run $200 to $400 in clean, working condition. A genuinely rare clear-cased developer edition MessagePad 110, handed out at an Apple conference in 1994, is worth well over $1,300 in complete condition, though that’s a true grail rather than something most people will stumble across.
The stylus is small and frequently missing from surviving units, and its absence is worth factoring into any price you’re offered. Rechargeable battery packs from this era rarely still hold a charge, so test any unit with fresh batteries before assuming it’s dead. The screen’s pressure-sensitive digitizer can lose accuracy over time, worth checking if you plan to actually use the handwriting recognition rather than just display the unit.
17. Sega Dreamcast console (1999)
Image Credit: Shutterstock
Sega’s last home console launched in the US in September 1999 to genuine excitement and strong early sales, only for it to be discontinued less than two years later after Sega exited the hardware business entirely. That short production run is part of why clean examples now carry real collector interest.
A working console typically brings $80 to $130, and complete examples with the controller, VMU memory unit, and original cables bring $150 to $250 depending on condition. The console’s swirl logo box art and orange packaging make a boxed example immediately recognizable to anyone who remembers it.
The GD-ROM disc drive is the console’s most common failure point, since the laser assembly wears down and struggles to read discs after enough use, much like the CD-based consoles that came before it. A console that powers on but shows a black screen or refuses to read any disc likely needs the drive serviced rather than being a lost cause. Check that the VMU memory unit’s small screen still displays correctly if one is included, since it has its own battery and LCD that can fail independently of the console.
18. Nintendo Virtual Boy (1995)
Image Credit: Shutterstock
Nintendo’s Virtual Boy was a commercial failure almost from the moment it launched in 1995, discontinued within a year after complaints about its red-and-black display and reports of headaches and eye strain from extended play. That short life span, combined with only twenty-two games ever released for it, has made it the most valuable home console Nintendo ever put its name on among collectors today.
A loose, working console typically brings $250 to $350, and a complete example with the original box, stand, and manuals climbs toward $450 to $550, with pristine examples pushing past that. This is squarely a grail item rather than something most people will stumble across, but enough units were sold that a genuine find isn’t impossible.
The foam eyepiece that presses against the user’s face degrades badly over thirty years and is almost always replaced on a well-kept unit, which isn’t a dealbreaker to buyers. The display itself uses red LEDs rather than a traditional screen, and burned-out rows of LEDs, visible as dark lines across the image, are a serious defect collectors specifically test for. Confirm both the console and controller function together, since the tabletop stand assembly is also frequently incomplete on surviving units.
A major life event like a divorce, a move, or a career shift can reshape your daily reality overnight, making a structured approach to household cash flow essential for the nation’s 7.3 million single mothers. Rebuilding your financial foundation solo requires taking stock of your immediate assets, eliminating unnecessary expenses, and setting up clean account structures to maintain control. These concrete steps restore stability and ensure your money supports your new path forward.
The first step in resetting your finances is gaining complete clarity on your active accounts. You need to inventory every checking account, savings account, credit card, and outstanding balance to get an accurate view of your net worth. Separating shared accounts into individual accounts protects your independence and streamlines tracking your daily spending.
Updating primary and contingent beneficiaries on your retirement accounts, life insurance policies, and transfer-on-death accounts ensures your assets are distributed according to your current wishes. If in-person account help would be useful and you’re based in Texas, you can find your nearest UFCU branch to ask questions and review available banking services. Aligning account titles and beneficiary designations prevents administrative delays and protects your family’s future.
Build emergency reserves and audit recurring expenses
Establishing a cash cushion protects single parents from unexpected expenses without resorting to high-interest debt. Research shows that women see their household income cut in half in the year following a divorce, which underscores the urgent need for a dedicated safety net. Millions of single parents adjust to single-income households every day and benefit from automating micro-savings to build a reserve over time.
A practical audit of your ongoing operational costs helps free up cash flow quickly:
Cancel subscription services and unused gym memberships immediately
Negotiate lower rates on auto insurance policies and household utilities
Redirect subscription savings directly into your emergency reserve account
Review your fixed expenses line by line to find immediate opportunities to reduce overhead. Streamlining these monthly costs provides extra margin to fund your cash reserves and handle sudden unexpected bills without stress.
Establish a simple monthly money routine
Sustaining long-term stability relies on a predictable, easy-to-follow monthly money routine. Grouping your spending into basic categories like housing, child needs, debt payoff, and savings gives you full visibility into where your money goes, even if you’re sharing parenting duties. Experts specializing in financial planning for single parents after divorce recommend scheduling a monthly calendar check-in to review upcoming expenses and adjust for seasonal changes.
Automating recurring bills and monthly savings transfers reduces daily stress and eliminates late fees. Reviewing your cash flow regularly helps you stay on track, adapt to variable costs, and make informed choices about your future.
Next steps for long-term security
Managing your household finances solo becomes far easier when you establish a clear routine and clean account structures. Once you complete your basic checklist, consider consulting an accredited financial planner or reading specialized budgeting guides to explore long-term investing strategies. Read more tips and guides for single moms on our site to get your life on stable footing.