scroll top

You open your banking app to check your balance before payday, and three charges catch your eye: $14.99 for a streaming service you thought you’d canceled, $9.99 for an app you downloaded once for a road trip two years ago, and $34.99 for a meal kit you haven’t ordered from since spring.

The average American is now paying $111 a month on subscriptions, or $1,332 a year, and that figure is up 23 percent from a year ago. About $252 of that goes to subscriptions nobody is actually using anymore.

Retirement accounts don’t usually get wrecked by one bad decision. They get worn down over decades by purchases that each felt too small to question, starting with the ones renewing on your card every single month without asking your permission again.

The subscriptions you forgot you’re paying for

subscription renewed
Image Credit: Shutterstock

Streaming apps get most of the blame, but the pattern shows up everywhere: a meditation app from a stressful month, a cloud storage upgrade for one project that finished a year ago, a magazine on your tablet you haven’t opened since you signed up. Eight video and music streaming platforms have raised their prices since the start of 2026 alone, including a $2-a-month increase on standard Netflix and another $2 tacked onto YouTube Premium.

None of these charges feels big enough to fight over. That’s the design. Subscriptions are built to sit quietly on autopay, renewing every month without you having to say yes again. Redirect that $111 a month into a retirement account instead, and at a 7 percent annual return, the assumption used in official retirement plan fee modeling, you’d have well over $130,000 after 30 years, on top of whatever your employer matched along the way.

Pulling up a full year of bank and card statements and checking every recurring charge against something you actually used this month usually turns up two or three worth canceling immediately.

Food delivery apps and their built-in markup

food delivered from delivery app
Image Credit: Getty Images via Unsplash

Ordering delivery instead of cooking reads as a $5 or $10 splurge. It usually isn’t. Researchers who priced the same McDonald’s order across the 100 largest U.S. cities found that a meal costing $36.95 in the restaurant averaged $57.87 once it went through a delivery app, a markup that’s grown nearly 8 percent since 2023. DoorDash came out as the most expensive option, charging $63.21 for the same order, 71 percent more than picking it up yourself.

That markup is baked into layers most people never add up in their head: a delivery fee, a service fee, taxes calculated on the inflated total, and a tip on top of all of it. Order that way twice a week and the app fees alone can run past $1,000 a year, money that never touches your grocery budget, your emergency fund, or your 401(k).

None of this means delivery is off limits. It means treating it as the premium service it actually is, rather than a cheap convenience, changes how often you reach for it.

Buy now, pay later for things you don’t need
Buy now, pay later
Image Credit: Shutterstock

Splitting a $60 purchase into four payments of $15 sounds harmless, and for a genuine emergency it can be. The trouble is how often it’s used for things that were never urgent in the first place. Sixteen percent of U.S. adults used a buy now, pay later loan in the past year, up from just 10 percent when tracking began in 2021, and 26 percent of those users made at least one late payment.

This matters most for people already living close to the edge: among adults who could cover less than $100 of an emergency out of savings, 18 percent had a buy now, pay later payment trigger an overdraft or non-sufficient-funds fee. That’s a purchase you didn’t have the cash for, financed by a loan you also didn’t have the cash for, generating a bank fee on top of both.

Stacking several of these plans across different apps and retailers makes it easy to lose track of what’s actually due each week, which is precisely how a stack of “free” installment plans turns into real debt.

The extended warranty at checkout

extended warranty and bank notes
Image Credit: Shutterstock

The pitch always sounds reasonable: a few extra dollars now to avoid a repair bill later. The economics tell a different story. Industry analysts estimate that sellers typically keep 50 to 70 percent of what you pay for an extended warranty as pure profit, compared with retail profit margins of just 8 to 15 percent on the electronics and appliances the warranties are attached to.

The people selling you the warranty have far better data than you do on how often that specific product actually breaks, and they price accordingly. Most items fail either very early, while the manufacturer’s original warranty still covers it, or well past the extended warranty’s term. The stretch in between, the part you’re paying to insure, is usually the safest stretch of the product’s life.

Setting aside what you would have spent on warranties in a separate account and using it only when something actually breaks almost always leaves you ahead, because you keep the money the retailer would have kept instead.

The store credit card for ten percent off

using store card to pay for goods
Image Credit: Shutterstock

A cashier offers 15 percent off today’s purchase for opening a store card, and it looks like free money. The card itself is where the real cost hides. The average retail credit card now charges 30.14 percent interest, with store-only cards averaging 31.64 percent, both roughly one and a half times higher than the 20.12 percent national average for credit cards overall. Some cards, including ones from Saks, Kay Jewelers, and Victoria’s Secret, charge 35.99 percent.

Carry a balance on one of these cards past the first statement and the introductory discount is gone within a month or two, replaced by an interest rate that makes the original price look like the deal. Card issuers can charge this much because retail cards are marketed as easy to get, and they know most cardholders won’t shop around before saying yes at the register.

If you can pay the balance off in full every single month, the discount really is free. If there’s any chance you can’t, the numbers turn against you fast.

Overdraft fees on your checking account

worrying about overdraft fees
Image Credit: Shutterstock

An overdraft fee gets charged the moment your balance can’t cover a debit card swipe, an automatic bill payment, or a check, and the bank covers it anyway, for a price. The average overdraft fee is $26.77, and 94 percent of bank accounts still charge one despite years of public pressure to get rid of them.

A rule finalized by the Consumer Financial Protection Bureau in 2024 would have capped most overdraft fees at $5, but Congress overturned that rule in 2025, so the fee stays at whatever your bank sets. One overdraft rarely derails anyone. A pattern of them, three or four a year at close to $27 each, is money that could otherwise sit in an IRA earning interest instead of covering a coffee run your balance couldn’t quite handle.

Free tools most banks already offer, low-balance text alerts and automatic transfers from savings, prevent most of these fees without costing you anything.

Out-of-network ATM withdrawals

freestanding ATM
Image Credit: Shutterstock

Pulling $40 in cash from the wrong machine can cost you twice: once from the ATM’s own surcharge, and again from your own bank’s fee for using an ATM outside its network. The combined cost of an out-of-network withdrawal hit a record $4.86 this year, the third straight year the fee has set a new high, up from $4.77 the year before.

Do that once a week and you’re paying more than $250 a year for the privilege of accessing your own money. It’s an easy fee to dismiss in the moment, since it rarely registers as more than pocket change, which is exactly why it survives untouched in most people’s budgets year after year.

Most major banks now publish in-network ATM locators in their apps, and a growing number of online banks reimburse out-of-network fees automatically, so the fix here is usually a five-minute app search rather than a lifestyle change.

Carrying a balance instead of paying it off

man stressed about credit card balance
Image Credit: Shutterstock

Making the minimum payment feels manageable because the number on the statement is small. The balance behind it usually isn’t. Households that carry credit card debt from month to month now owe $11,149 on average, up more than 3 percent from the year before. At today’s national average card rate of roughly 20 percent, carrying that balance for a full year costs around $2,240 in interest alone, money that produces nothing and builds nothing.

Nearly half of Americans with a balance say carrying credit card debt has simply become normal, which is part of what makes it so easy to keep doing. Every dollar that goes to interest on last year’s purchases is a dollar that isn’t available to catch up on this year’s retirement contribution, and the two compete directly for the same paycheck.

Paying even $50 more than the minimum each month, applied to the highest-rate card first, usually cuts years off the payoff timeline without requiring a full budget overhaul.

Lottery tickets and scratch-offs
lottery scratchcards
Image Credit: Shutterstock

A five-dollar scratch ticket picked up with gas or groceries doesn’t register as a real expense. Across the country it adds up to real money. Roughly half of Americans buy at least one ticket a year, and total lottery spending runs around $103 billion annually, with the average consumer in states that sell tickets spending about $321 a year on them.

Swap a $25-a-month habit of a Powerball ticket and a scratch-off for a low-cost index fund earning an average 10 percent return, and that money grows to more than $56,000 after 30 years. The lottery pays out real prizes to real winners, but the odds are built so that the state, not the player, comes out ahead on average, which is exactly why it funds public budgets so reliably.

The occasional ticket for a jackpot that’s actually captured your interest isn’t the problem here. It’s the routine, habitual purchase that quietly competes with real savings.

The daily coffee run

Starbucks coffee
Image credit: W il via Unsplash

A daily latte on the way to work rarely gets budgeted as a real line item, which is exactly how it becomes one of the biggest. A daily latte habit now runs $1,800 to $2,200 a year, driven up by a coffee market that’s seen the steepest price increases in decades, including grocery bean prices that jumped roughly 21 percent year over year. Add a second coffee in the afternoon, or upgrade to a specialty drink on weekends, and that annual total climbs well past $3,000, one small charge at a time.

Run that same $1,800 to $2,200 a year at a 7 percent long-run annual return, the assumption used in official retirement account modeling, for 30 years and you land somewhere between $180,000 and $220,000, more than most people have saved for retirement by the time they actually retire.

Brewing the same coffee at home costs closer to $1 a cup. Keeping the ritual while moving it out of the drive-through line usually closes most of that difference without anyone feeling deprived.

Shopping to feel better

shopping in Dollar Tree
Image Credit: Shutterstock

Buying something after a bad day is one of the most common, least judged forms of spending there is, which is part of why it’s so easy to underestimate. Sixty-three percent of Americans say their emotions influence their purchases, and nearly three-quarters of them say it’s led them to spend more than they meant to.

A new top or a package on the porch can really lift a hard day, and there’s nothing wrong with that on its own. The problem shows up when the pattern repeats often enough that it becomes the main coping tool for stress, boredom, or a bad week at work, because at that point the spending is being driven by a feeling that has nothing to do with whether the purchase is actually worth the money.

Noticing the mood before you open the app, and giving yourself a short pause before checking out, doesn’t remove the impulse. It just puts a decision back in the loop where there wasn’t one before.

One-tap purchases you didn’t plan to make

buying online
Image Credit: Shutterstock

Saved payment methods and one-click checkout were built to remove every bit of friction between wanting something and owning it, and they work exactly as designed. Over half of U.S. adults, 54 percent, made at least one unplanned purchase during the 2025 holiday season alone, and more than 1 in 5 adults spent over $1,000 on a single unplanned purchase.

Zoomed out across a full year, the average American now makes close to 10 impulse purchases a month, spending $281.75 a month, or $3,381 a year, on things that weren’t on any list before they were bought. That figure has climbed back up after a brief dip a couple of years ago, as shopping apps got better at pushing personalized recommendations at exactly the right moment.

Deleting saved card details from the apps you browse most, so checkout takes an extra thirty seconds, is a small piece of friction that consistently cuts down on purchases you’d never have started from scratch.

Upgrading your phone every year or two

man on smartphone
Image Credit: Shutterstock

More than half of new smartphones sold in the United States now carry a price tag of at least $800, and a growing share of buyers aren’t waiting long to replace them. A quarter of likely smartphone buyers now expect to replace their device within one to two years, up from just 15 percent two years earlier.

Modern phones are more durable than the ones from a decade ago, and most people’s actual usage hasn’t changed enough to justify replacing a phone that still works well. The upgrade cycle keeps shrinking anyway, driven by carrier trade-in offers that make a new phone feel free, when in reality that “free” phone is usually financed through a 24 to 36 month payment built into the monthly bill.

Stretching a phone’s life by even one additional cycle, and buying the previous generation instead of the newest release, routinely saves several hundred dollars a year without any real loss in what the phone can do.

The timeshare that sounded like a good idea
timeshare written on beach
Image Credit: Shutterstock

A timeshare presentation is built around one week of vacation, but the bill never actually stops. The average buyer now pays $23,160 for the timeshare itself and $1,480 a year in mandatory maintenance fees, and that annual fee climbs whether or not you ever use the week you bought.

One widely cited industry study found that 85 percent of timeshare owners regret the purchase, and resale values usually collapse to a fraction of what was paid, since most timeshares resell for somewhere between zero and 10 percent of their original price. Exiting a contract, even one you’ve fully paid off, can take months of paperwork or a paid exit service, and the maintenance fees keep coming due the entire time you’re trying to leave.

A week of paid rental at a comparable resort, booked fresh each year with no ongoing obligation, is almost always cheaper over any stretch longer than a few years, and it comes with an exit whenever you want one.

Not getting your full employer match
pay day circled on calendar
Image Credit: Shutterstock

An employer match is the closest thing to guaranteed money most people will ever be offered, and a striking number leave part of it on the table anyway. More than one in five employees, 21 percent, don’t contribute enough to get their full company match, and roughly half of that group is only one or two percentage points of pay away from claiming all of it.

Employer contributions have climbed to a record 4.7 percent of pay on average, which means someone earning $60,000 a year and missing the full match could be walking away from close to $2,800 in free money annually. Over a career, with growth, that shortfall compounds into one of the largest sums most workers leave on the table without ever making an active decision to do it.

Checking your plan’s match formula against your own contribution rate takes about five minutes on most benefits portals, and it’s one of the few fixes on this list that costs nothing extra out of your own paycheck.

Cashing out an old 401(k)
401K
Image Credit: Shutterstock

Leaving a job comes with a form asking what to do with the 401(k) you’re leaving behind, and taking the cash looks like the simplest option. It’s also the most expensive one: 85 percent of workers who cash out their 401(k) at a job change drain the entire balance, rather than rolling any of it into a new account, and the retirement system as a whole would hold nearly $2 trillion more over the next 40 years if that money stayed invested instead.

The cash-out isn’t just taxed as ordinary income. Anyone under 55 who separates from an employer also owes a 10 percent early withdrawal penalty on top of that tax bill, so a chunk of what looked like a windfall disappears before the rest ever reaches a bank account.

A rollover into an IRA or a new employer’s plan takes one phone call and keeps every dollar working, without the tax hit or the penalty.

Borrowing from your 401(k) to cover a purchase
401K
Image Credit: Shutterstock

A 401(k) loan is often sold as borrowing from yourself, which makes it feel safer than it actually is. Nearly 40 percent of participants with access to a loan option have used one to cover a current purchase, and the risk shows up the moment that person changes jobs: 86 percent of participants who leave their employer with an outstanding 401(k) loan end up defaulting on it, because the full remaining balance typically comes due almost immediately after separation.

A defaulted loan is treated exactly like a cash withdrawal: it’s taxed as ordinary income and hit with the same 10 percent penalty if you’re under 59 and a half, on top of every dollar of investment growth that balance no longer earns. The cumulative cost of this pattern is estimated at roughly $2 trillion in lost retirement savings over the next decade across the workforce.

If a major purchase truly can’t wait, a personal loan or a home equity line usually costs less in the long run than the risk of turning retirement savings into taxable income on the way out the door.

High-fee funds sitting untouched in your plan
saving in 401K
Image Credit: Shutterstock

Most people pick a fund in their 401(k) once, during onboarding, and never open the fund menu again. That single decision can be worth more than any single contribution choice. One modeling example used in official retirement plan fee disclosures makes the stakes plain: a $25,000 account balance left untouched for 35 years, earning 7 percent a year, grows to $227,000 if fees run 0.5 percent annually, but only $163,000 if fees run 1.5 percent. A single percentage point of fees, the kind of difference between an index fund and an older actively managed one, cost that saver 28 percent of their final balance.

Plenty of 401(k) menus still carry funds with expense ratios well above 1 percent sitting next to nearly identical index options charging a fraction of that, and most participants have no idea which one they’re actually holding, because the fee gets deducted quietly from returns rather than billed separately.

Most plan providers list every fund’s expense ratio on the same page where you’d change your contribution rate, and swapping a high-fee fund for a lower-cost equivalent with a similar strategy is usually a same-day change.
Child support is the part of a divorce people assume is negotiable and the part that turns out to be arithmetic. California runs it through a statewide formula, and the room for discussion is much narrower than most people expect walking in.

Knowing which inputs the formula actually uses is what lets you prepare for a realistic number rather than a hoped-for one.

The formula runs on two numbers

California’s guideline calculation is driven principally by each parent’s income and by the proportion of time each parent has primary physical responsibility for the children. The state revised the guideline as part of a package of changes that became operative on September 1, 2024.

Everything else adjusts around those two inputs.

Timeshare is a percentage, not a description

Parents describe their arrangement in words. The formula takes a percentage, and small changes in it move the support figure noticeably.

This is why the parenting schedule and the support number are not separate negotiations, however much they feel like it. They are the same negotiation viewed from two angles.

The guideline amount is presumed correct

Courts treat the calculated figure as the right answer, and departing from it requires a stated reason falling within the categories the statute recognizes.

That is worth knowing before you spend energy negotiating toward a number the formula will not produce. The productive conversations are about the inputs, not about the output.

What counts as income is broader than a paycheck

This is where the most common miscalculation happens, usually in the direction of underestimating.

The statutory definition

Family Code section 4058 defines annual gross income as income from whatever source derived, and then lists examples: commissions, salaries, royalties, wages, bonuses, rents, dividends, pensions, interest, trust income, annuities, workers’ compensation, unemployment and disability benefits, social security benefits, severance pay, veterans benefits not based on need, and military housing and food allowances.

For a self-employed parent it means gross receipts reduced by the expenditures required to operate the business, which is not the same figure as the one on a tax return. Business deductions that are legitimate for tax purposes are frequently added back for support purposes.

When a parent is not working

The section allows the court to consider earning capacity rather than actual income. Where a parent’s income is unknown, the court is directed to consider earning capacity. Where it is known, the court may consider earning capacity instead, in its discretion, consistent with the children’s best interests.

In assessing capacity the court looks at assets, residence, employment and earnings history, job skills, education, age, health, criminal record and other employment barriers, and the record of seeking work, alongside the actual local job market.

That last element matters. Earning capacity is not a theoretical salary. It has to be tied to work a person could realistically obtain.

The add-ons are separate, and two of them are mandatory

The guideline figure is not the whole obligation, and this is the piece single parents most often fail to claim.

What the court must order

Family Code section 4062 directs the court to order two categories as additional child support. The first is childcare costs actually incurred and related to employment, or to reasonably necessary education or training for employment skills. The second is the reasonable uninsured health care costs for the children.

Mandatory means the court orders them where the costs exist. These are typically shared between the parents rather than absorbed by one household.

What the court may order

The same section permits, without requiring, orders covering costs related to the children’s educational or other special needs, and travel expenses for visitation.

Travel is the one worth raising early where the other parent has moved any distance. It is easy to include at the outset and awkward to add later.

Special needs covers more ground than people assume, including tutoring and therapies that a child genuinely requires rather than merely benefits from.

Getting the order in place and keeping it accurate

An order is only useful if it reflects the present situation.

Get a temporary order early

Support can be ordered while the case is still running, and there is rarely a good reason to wait for a judgment. A household trying to hold itself together on one income for eight months, in the expectation of being made whole later, is a household that accumulates debt in the meantime.

Temporary orders are also easier to obtain than people expect, because they rest on current income figures rather than on resolving anything else in the case.

Support is modifiable, and that runs both ways

A material change in circumstances allows either parent to seek modification. A job loss, a significant raise, or a real change in the parenting schedule all qualify.

Parents commonly leave an order untouched for years past the point where it stopped matching reality, usually because reopening it feels like starting a fight. The gap only widens, and arrears do not accrue on an obligation nobody asked the court to update.

Use the state services where they help

California’s child support services program can open a case, establish an order, and handle collection and enforcement, including wage assignment. There is no charge for opening a case with them.

It is a slower path than private counsel in a contested matter, and a sensible one where the issue is collection rather than the amount.

Keep the records that prove the add-ons

Childcare invoices, receipts for uninsured medical costs, and proof of what was actually paid are what make an add-on claim straightforward instead of contested.

Where income is irregular, self-employed or hard to document on the other side, a divorce attorney in Orange County, California, will typically focus on establishing the income figure properly at the outset, because every later calculation is built on top of it.

You’re cleaning out a parent’s dresser drawer and find a rubber banded stack of twenties, some crisp, some soft with age, tucked behind old passports and expired coupons. Your first instinct is to count them and move on. Your second instinct, the one worth trusting, is to actually look at what you’re holding before it goes back into circulation.

Most old $20 bills are worth exactly $20. The Bureau of Engraving and Printing turns out more twenties than almost any other denomination, so plain, worn, ordinary ones stay ordinary. But the twenty has a stranger history than people realize. It went through gold certificates, a wartime emergency printing meant to be declared worthless if Japan invaded Hawaii, and decades of small design changes that collectors track down to the letter after the series year. Somewhere in that history is a real chance the bill in your hand is worth ten, fifty, or a thousand times what it says on the corner.

You could genuinely have one of these in a relative’s savings, a coin jar, an estate sale box of old papers, or a bill that’s been sitting folded in a wallet since the Clinton administration. Condition decides almost everything, so treat any candidate gently and skip the temptation to iron it flat or tape a torn corner.

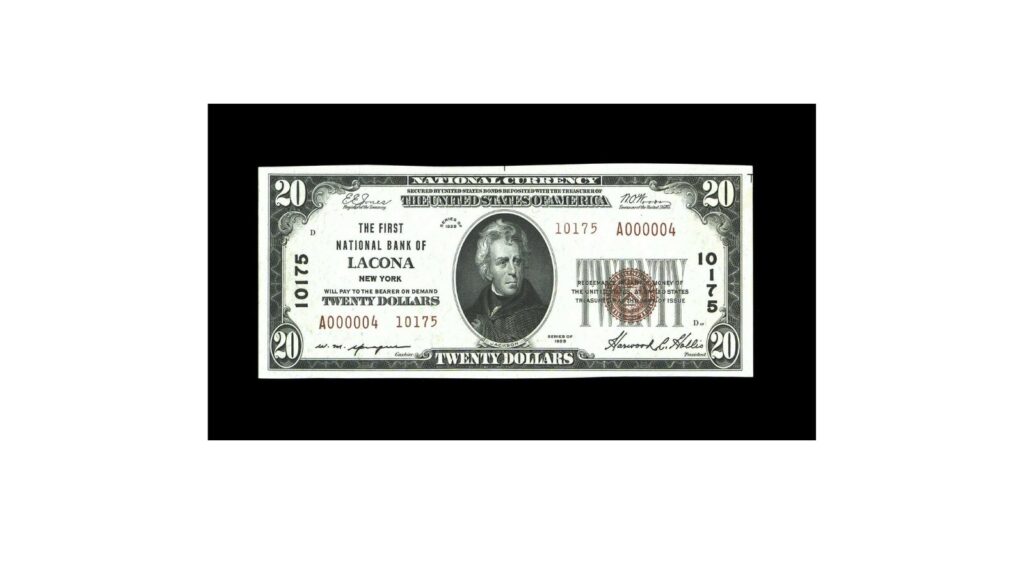
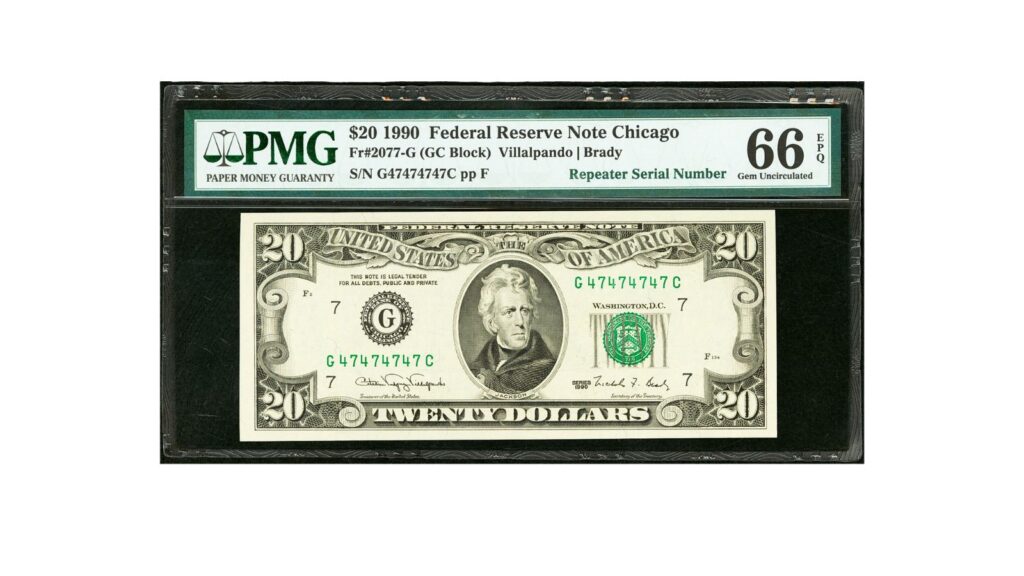
1. $20 bill with a solid, ladder, or repeater serial number

$20 repeater serial number
Image Credit: Heritage Auctions

Every $20 bill carries an eight digit serial number printed twice on the front, and most are meaningless strings nobody looks at twice. Occasionally the digits line up into something a collector actually wants: a solid number where every digit matches, something like 33333333, a ladder that climbs or falls in perfect sequence like 23456789, or a repeater where a short block of digits copies itself across the whole string.

These patterns are rare by definition, since only a handful of the roughly one hundred million serial numbers issued per series will ever line up this cleanly. On a $20 bill specifically, solid serial numbers add $200 to $1,500 or more over face value, ladders typically add $100 to $750, and simpler repeater or radar patterns bring a smaller but real premium in the $25 to $100 range. A star note with a fancy serial number on top pushes the price higher still.

Crisp, never folded bills bring multiples of what a worn one does, so if you spot a pattern like this, resist the urge to smooth out the folds or clean it up. Set it aside and get it in front of someone who buys currency for a living before you decide what it’s worth.

2. $20 bill with a low serial number

$20 low number
Image Credit: Heritage Auctions

Low serial numbers mark a bill as one of the very first off the press for that particular series and Federal Reserve district, and collectors chase them the way sports fans chase the number one jersey. A serial reading 00000001 through about 00000100 is genuinely uncommon, since most low runs get pulled aside by bank staff or collectors before they ever reach a cash register.

On $20 bills, numbers under 1,000 typically add $100 to $500 or more to the bill’s value, with the very lowest numbers, 00000001 through 00000010, pulling the strongest premiums. Once you’re past the first few thousand, the premium fades fast, and a number in the tens of thousands is essentially back to face value.

Check both printed copies of the serial number on the front, since they should match exactly. Condition still matters here just as much as it does with any other collectible twenty. A worn, heavily circulated bill with a low number is worth a fraction of a crisp uncirculated one with the same digits, so this is one case where it genuinely pays to leave the bill flat and untouched until you know what you have.

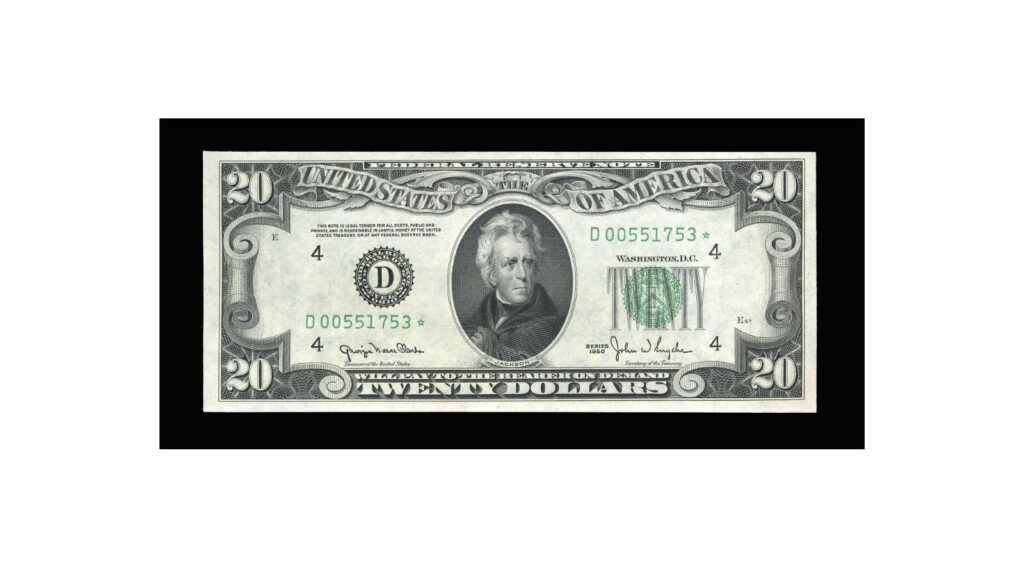
3. $20 star note from a small print run

$20 star note
Image Credit: Heritage Auctions

A star printed at the end of the serial number means the bill replaced one that was damaged or misprinted during production, and it’s the single easiest thing to check on any twenty in your wallet right now. Star notes exist for every series back to the 1930s, and they’re always scarcer than the regular run because they only get printed when something needs replacing.

What separates a valuable star note from a common one is the size of its specific print run. Some $20 star note runs from the last two decades total as few as 160,000 notes, compared to standard runs that can top three million. On modern series, that scarcity typically translates to a 5 to 15 percent premium over face value in circulated condition, more if the bill is crisp and uncirculated.

That’s not life changing money for a single note, but it costs nothing to check, and older star notes from the 1950s through 1970s carry meaningfully bigger premiums than modern ones, so the older the star, the more worth digging for.

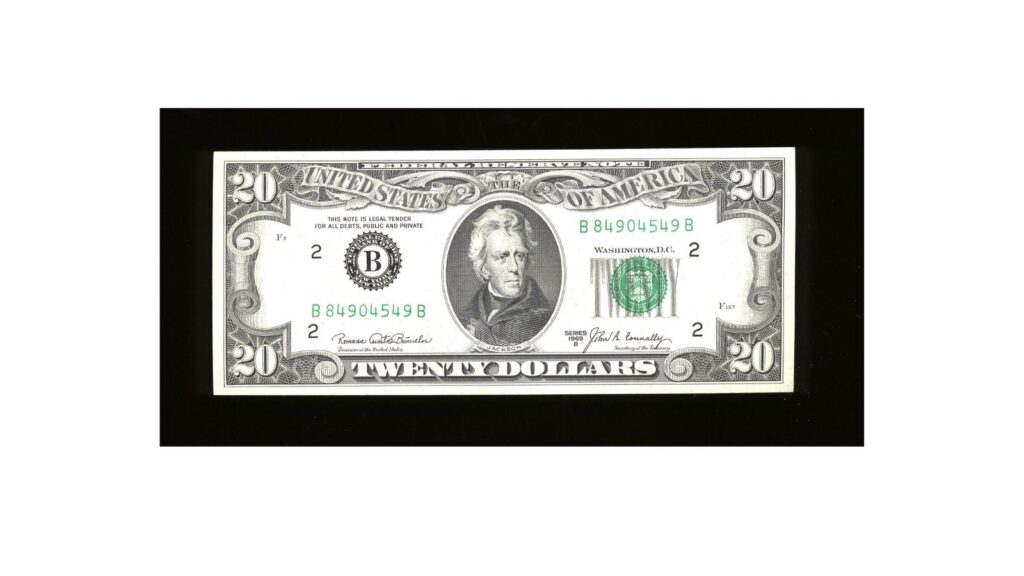
4. Series 1969B $20 bill

Series 1969B $20 bill
Image Credit: Heritage Auctions

Not every scarce twenty is decades older than its neighbors. The 1969B series sits in an awkward middle ground, recent enough that most people assume it’s just an old bill worth face value, and rare enough that it genuinely isn’t. The Bureau of Engraving and Printing ran a noticeably smaller print for this series than for the 1969, 1969A, and 1969C that surround it.

That smaller run shows up directly in the price. Circulated 1969B twenties typically bring $28 to $35, a real step up from the $20 to $25 you’d get for most bills from the same general era, and uncirculated examples climb to $55 to $85.

The series letter is printed in small type near the bottom right of the portrait, right after the year, so it’s easy to miss if you’re not specifically looking for it. Most people spending a bill from this era never check. A worn, heavily circulated 1969B still commands its premium, just at the lower end of the range, so a bill that’s clearly been through a few wallets isn’t disqualified the way it would be for rarer series.

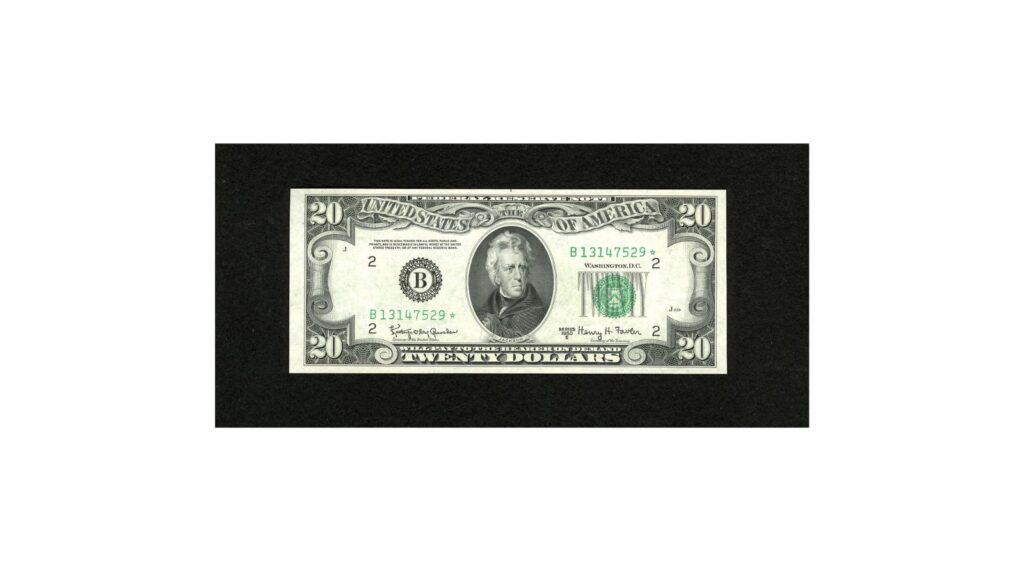
5. Series 1950E $20 bill

1950E $20 bill
Image Credit: Heritage Auctions

The 1950 series ran through five sub-variants, 1950 through 1950E, before the 1963 redesign that introduced the small head portrait people are used to seeing today. Of the five, 1950E is the scarcest, printed in smaller numbers and correspondingly harder to find now in any condition.

Circulated 1950E twenties bring $28 to $40, compared to $25 to $35 for most of the earlier 1950-series letters, and a crisp uncirculated example can reach $60 to $100. That’s a modest but genuine premium for a bill that looks, at a glance, exactly like every other twenty from the era.

Look for the series designation printed just below the series year, near the bottom right of Andrew Jackson’s portrait. The letter is small and easy to overlook if you’re not specifically checking for it. As with the rest of this era, condition does most of the heavy lifting on price, so a soft, well worn 1950E won’t reach anywhere near the top of its range. It’s easy to overlook precisely because it looks so unremarkable at first glance, which is exactly why it’s worth a second look.

6. $20 bill with a genuine printing error

$20 printing error
Image Credit: Heritage Auctions

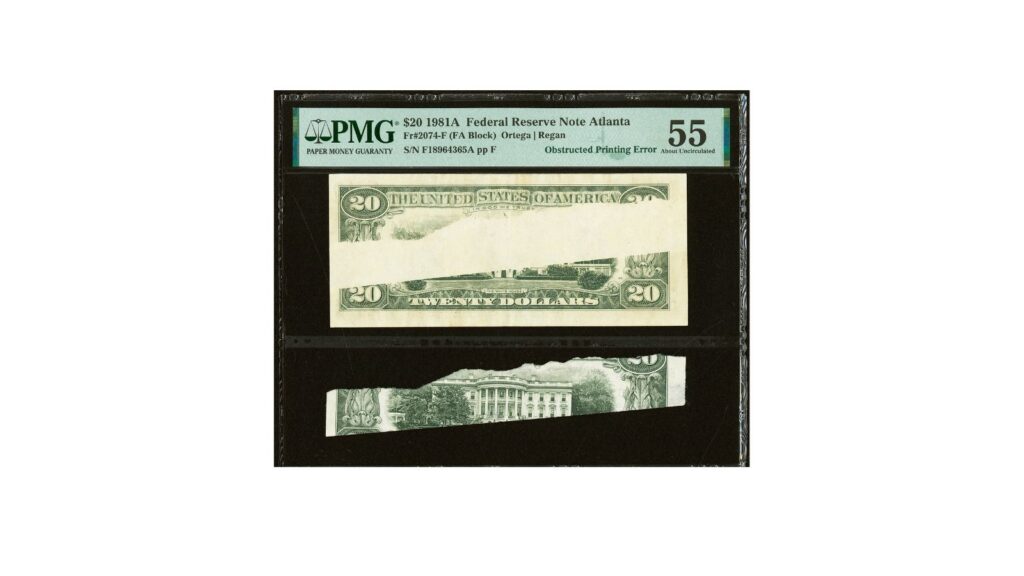
Twenties are the most heavily printed denomination in the country, which sounds like bad news for rarity but is actually good news for error hunters. More volume means more chances for something to go wrong on the press, and $20 error notes do turn up in ordinary circulation more often than people expect.

The most common types are ink smears, where loose ink from the intaglio press transfers onto the paper, off-center printing, where the design sits noticeably closer to one edge than it should, and misaligned overprints, where the seal or serial number lands in the wrong spot relative to the portrait. Minor smears and misalignments typically bring $25 to $60, while dramatic, full-width ink streaks or major misprints can reach $1,500 or more depending on how visually striking the error is.

Genuine errors happen at the Bureau of Engraving and Printing itself, not after the bill leaves the building, so anything that looks damaged, torn, stained, or altered after the fact isn’t an error, it’s just wear. If you think you have a real one, get it professionally graded before you sell it, since an authenticated error carries far more weight with serious buyers than an unverified one.

7. Series 1928 $20 federal reserve note

1928 $20 federal reserve note
Image Credit: Heritage Auctions

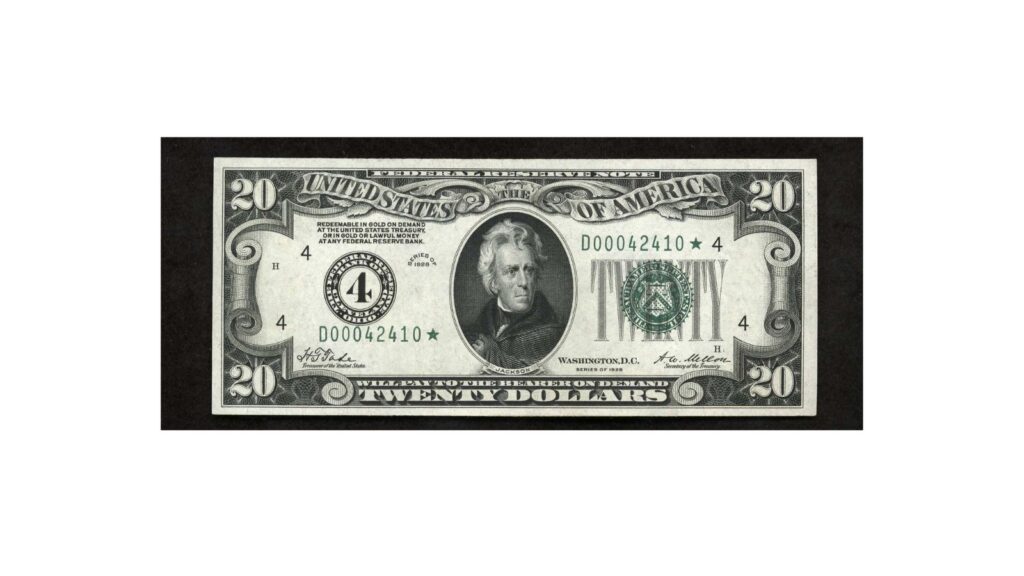
The 1928 series marked the first small-size $20 bills, shrunk down to the size we still use today after decades of larger currency. It’s also the first series to carry the phrase about being redeemable in gold printed across the top, a holdover from a monetary policy that wouldn’t survive the 1930s.

Because it was the first year of the new size and format, the plain 1928 series carries a real premium over the sub-series that followed it. Circulated examples typically bring $40 to $65, and uncirculated notes can reach $125 to $350, noticeably more than the 1928A and 1928B that came after as production ramped up and the notes became more common.

Check the series year in the bottom right of the portrait, and look for a plain green Treasury seal rather than the gold seal used on gold certificates from the same era. Paper this old is often brittle at the folds, so handle it by the edges and store it flat rather than folded if you plan to keep it rather than sell it.

8. 1928 $20 gold certificate

1928 $20 gold certificate
Image Credit: Heritage Auctions

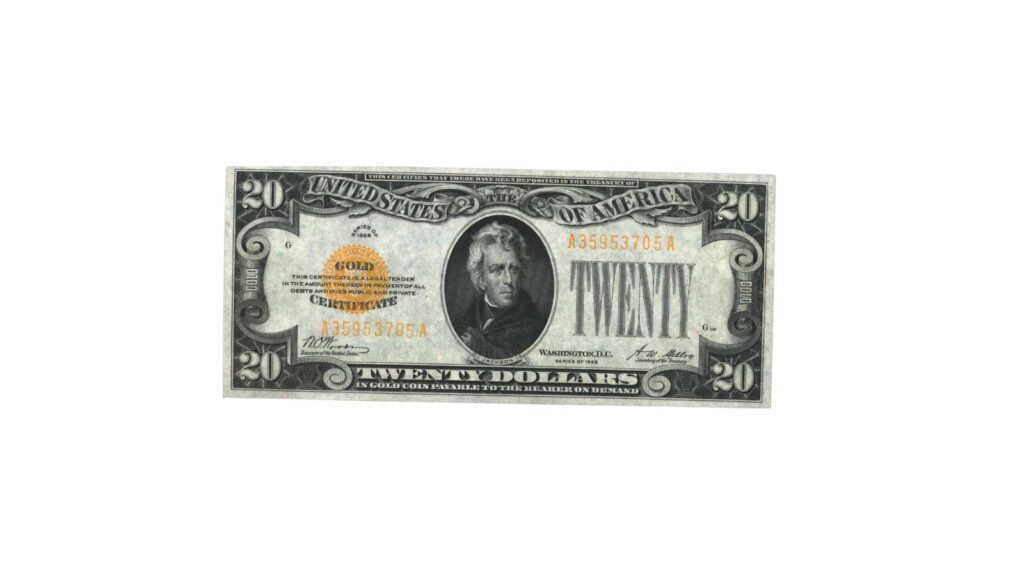
Gold certificates are where old $20 bills start looking genuinely different from the twenty in your wallet now. Instead of the familiar green Treasury seal, these carry a gold colored seal and gold colored serial numbers, and the text across the top reads redeemable in gold coin rather than the standard language.

These notes stopped being legal to privately hold in 1933, when the government recalled gold certificates as part of a broader move off the gold standard, and ownership wasn’t legalized again until 1964. That decades long gap is a big part of why fewer survived than you’d expect from something originally printed in large numbers. Worn, well circulated 1928 $20 gold certificates bring $50 to $150, and uncirculated examples climb to $400 to $800 or more.

These sometimes turn up in family collections from a grandparent who quietly held onto one for decades rather than turning it in during the recall. Check carefully for the gold seal before assuming a green seal bill is a gold certificate. The two are easy to confuse from across a room but obvious once you have it in hand.

9. Large-size 1914 $20 federal reserve note

Large size 1914 $20 federal reserve note
Image Credit: Heritage Auctions

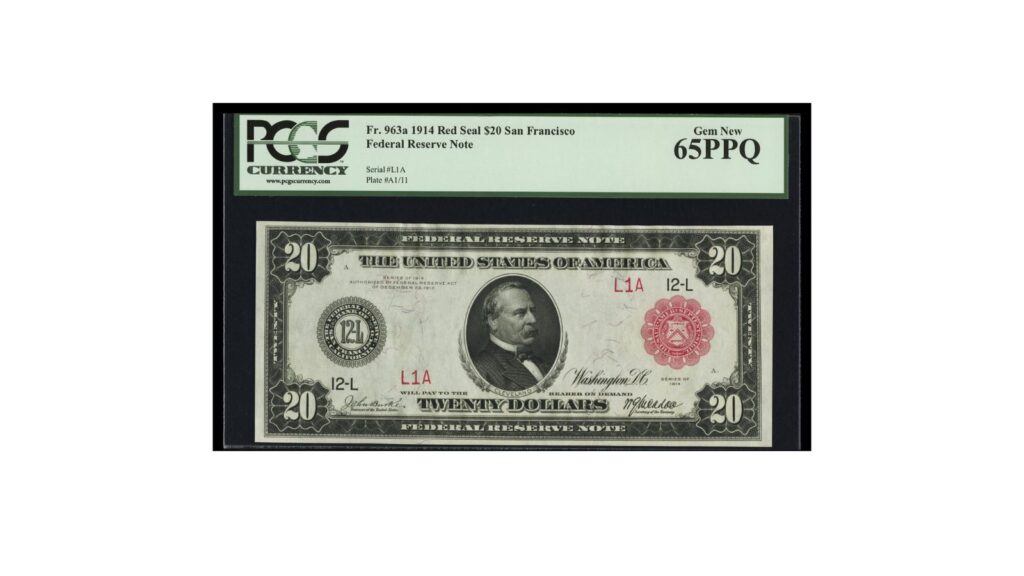
Before 1929, every American bill was noticeably bigger than the currency we use now, roughly 7.4 inches long compared to today’s 6.1, and the difference is obvious the moment you hold one next to a modern twenty. The 1914 series was the first $20 Federal Reserve Note ever issued, printed in two variants: an early red seal version and a more common blue seal that followed shortly after.

The red seal is the one to hope for. Red seal 1914 twenties typically bring $100 to $750 or more depending on condition and which Federal Reserve district issued them, while the more common blue seal brings $75 to $400. Notes from smaller, less active districts like Minneapolis or Dallas tend to sit at the higher end of these ranges.

Large-size notes from this era are over a century old, so brittleness and edge wear are common and expected rather than a red flag. What matters more is whether the paper has been trimmed down at some point to fit a modern wallet or frame, which happens more often than you’d think and meaningfully hurts the value.

10. Series 1929 $20 federal reserve bank note

1929 $20 federal reserve bank note
Image Credit: Heritage Auctions

This one gets confused with the more familiar Federal Reserve Note constantly, and the two really are different things. Federal Reserve Bank Notes were an emergency measure from 1933, created by taking existing national bank note printing plates and overprinting them for use by individual Federal Reserve Banks during the depths of the Depression, when the country badly needed more currency in circulation fast.

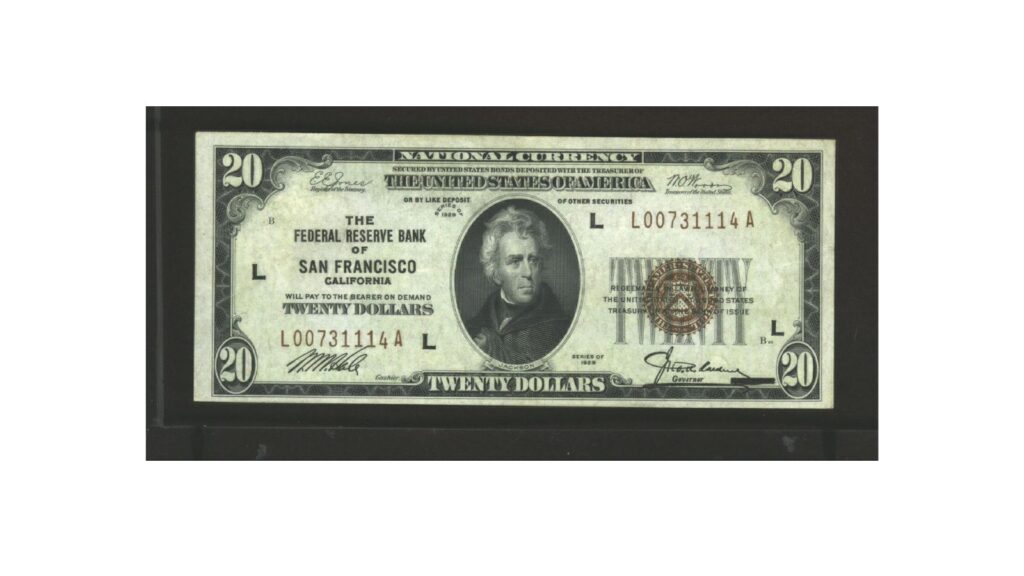
They’re identifiable by the brown Treasury seal and the specific Federal Reserve Bank named on the face, one of all twelve major banks from Boston to San Francisco. Most standard examples without a star or unusual serial number are common enough that circulated $20 notes bring around $30, with crisp, never folded examples reaching $100 or more. Star note replacements are the real prize here. Only around 300 star notes are known to survive across every denomination of this entire series, making a genuine $20 star from this issue a legitimate rarity.

Look for serial numbers with six or seven leading zeros too, which carry their own smaller premium separate from the star note rarity.

11. Hawaii overprint $20 bill

Hawaii overprint $20 bill
Image Credit: Heritage Auctions

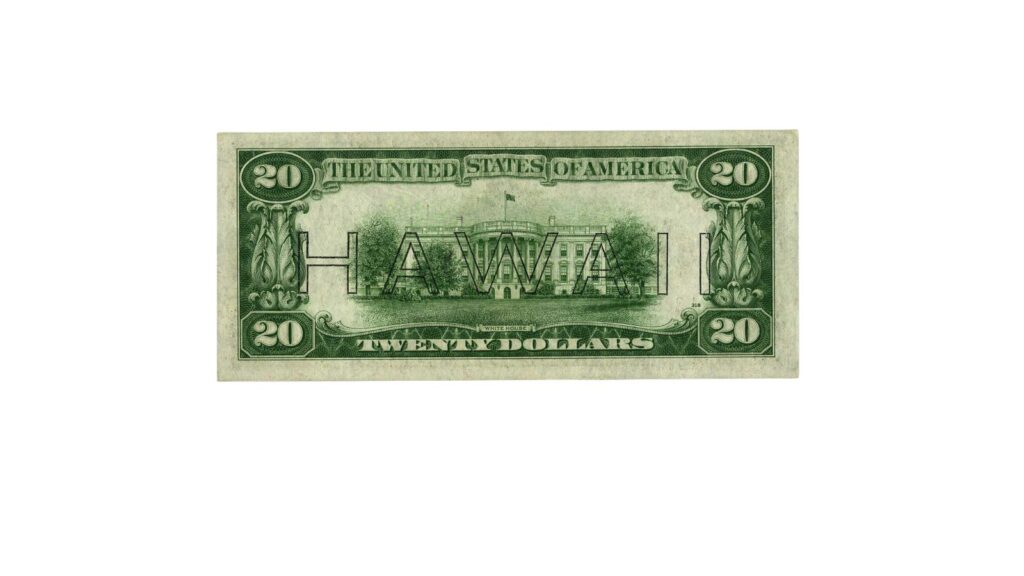
After Pearl Harbor, the government printed a special version of $20 bills specifically for circulation in Hawaii, overprinted with the word HAWAII in bold letters on both sides and stamped with a brown Treasury seal instead of the usual green. The idea was blunt: if Japan invaded and captured the currency, the government could instantly declare any Hawaii marked bill worthless.

The notes were recalled after the war, and what survived has become one of the most recognizable specialty issues in American currency. Circulated 1934A Hawaii twenties bring around $110 in very fine condition, climbing to roughly $230 in extremely fine, and $750 or more for a crisp uncirculated example. Star note replacements from this series are considerably rarer still and can reach well into four figures in top condition.

These do genuinely turn up in family collections, particularly from anyone who served in or passed through Hawaii during the war years. That said, a genuine example is still a real find rather than something to expect in an ordinary stack of inherited cash, so treat it as a pleasant surprise rather than a realistic bet.

Exciting doesn’t always mean well-paid. You don’t need a job that fulfils your thrill-seeking or joyful spirit. You need a job that gives you a decent-sized, stable paycheck that pays you enough to pursue the things you love, that excite you and fulfil you, when you’re not at work. And often, that means finding a boring, predictable job with a decent salary. In fact, some employers pay very well precisely because the work involves endless rules, inspections, logs, schedules, approvals, and problems that most people would rather not deal with.

The sweet spot is work where boring also means necessary. A computer can organize records or flag an odd number, but somebody still has to inspect the equipment, approve the batch, answer to regulators, handle a grievance, or decide whether a safety problem is serious enough to shut things down.

Many of these careers take a degree, license, or years of experience. They are not quick-money jobs. What they offer is something more useful: specialized work tied to healthcare, utilities, manufacturing, infrastructure, insurance, and regulation, where employers have a reason to keep experienced people around.

1. Regulatory affairs manager

Regulatory affairs senior manager
Image Credit: Shutterstock

If reading product regulations, checking labels, tracking rule changes, and reviewing submission packets sounds painfully dull, regulatory affairs may be exactly the point. These managers help pharmaceutical, medical device, chemical, and other regulated companies get products approved and keep them compliant after launch. A surprising amount of the day can involve change-control meetings, document reviews, deadline tracking, and making sure someone used the correct version of a form. Average pay is about $73 per hour.

The job pays because a missed requirement can delay a product launch or create a major compliance problem. Employers generally want a bachelor’s degree in science, engineering, healthcare, or another relevant field, plus several years of regulatory experience before moving into management. Demand is particularly solid because regulated companies cannot simply decide to stop doing this work when budgets tighten. Product registrations, manufacturing changes, inspections, and reporting requirements still have deadlines. The occupation is classified as a bright-outlook career, with strong growth and a large number of expected openings. Software can help organize submissions, but experienced people are still responsible for interpreting rules and defending decisions when regulators ask questions.

2. Environmental health and safety manager

Environmental health and safety manager
Image Credit: Shutterstock

An environmental health and safety manager can spend a startling amount of time on incident logs, inspection sheets, training records, chemical inventories, hearing-protection rules, and arguments about whether a guardrail is two inches too short. The work is common in factories, warehouses, construction companies, transportation operations, utilities, and large facilities. Average pay is around $59 per hour, with experienced managers often responsible for several sites or a large workforce.

You usually work your way up through safety, environmental, industrial hygiene, or operations roles. A bachelor’s degree is common, and professional safety credentials can help once you have field experience. The demand picture is unusually strong. Employment in the underlying occupational health and safety field is projected to grow 19% through 2035, with employers needing people to deal with new equipment, changing work practices, heat exposure, workplace injuries, and regulatory requirements. There is plenty of software for filling out forms and tracking incidents. It cannot walk through a loading dock, notice workers bypassing a safety device, question a supervisor, investigate an accident, and decide what needs fixing before somebody gets hurt.

3. Environmental compliance manager

Environmental compliance manager
Image Credit: Shutterstock

Environmental compliance managers live in a world of permits, wastewater limits, emissions records, hazardous-material inventories, sampling schedules, inspection deadlines, and corrective-action plans. You might work for a manufacturer, utility, construction company, engineering firm, waste operation, or another business that cannot afford to ignore environmental rules. Average pay is about $61 per hour. The routine can be heavy on calendars and checklists, especially when several facilities have different permits that expire at different times.

Most managers come from environmental science, engineering, chemistry, safety, or compliance backgrounds and build several years of practical experience before taking charge. The underlying environmental science field is projected to grow 6% through 2035, faster than the overall job market, as businesses and public agencies continue dealing with pollution, water quality, waste, permitting, and cleanup requirements. This work is difficult to eliminate because many obligations exist whether a company is expanding or merely keeping an old facility running. Monitoring systems can collect readings automatically, but people still have to interpret unusual results, investigate violations, speak with inspectors, decide what corrective action is needed, and put their name behind the company’s response.

4. Pharmaceutical quality assurance manager

Pharmaceutical quality assurance manager
Image Credit: Shutterstock

Pharmaceutical quality assurance is where excitement goes to be documented in triplicate. Managers oversee batch records, deviations, corrective actions, standard procedures, employee training, audits, investigations, and manufacturing changes. If a production worker used the wrong piece of equipment, a refrigerator drifted outside its allowed temperature, or somebody forgot a required signature, quality assurance gets involved. Average pay for a pharmaceutical quality assurance manager is about $63 per hour.

A science or engineering degree is common, followed by several years working in pharmaceutical manufacturing, laboratory operations, validation, or quality systems. The work tends to be steady because regulated drug manufacturing requires documented quality controls regardless of whether anyone finds the paperwork interesting. Manufacturing management overall is expected to maintain roughly average employment growth, with thousands of openings each year as experienced managers leave or retire. Pharmaceutical quality adds another layer of security because batches cannot simply be released without required reviews and investigations. Computer systems can spot missing fields and route approvals, but deciding whether a deviation could affect a drug’s quality, whether an investigation is adequate, or whether a batch should be rejected still carries serious human responsibility.

5. Food safety manager

Food safety manager
Image Credit: Shutterstock

A food safety manager can spend an entire career thinking about refrigerator temperatures, sanitation records, allergens, pest-control logs, metal detectors, supplier certificates, and whether employees washed something the correct way. These managers work for food manufacturers, processors, distribution operations, commercial kitchens, and companies that supply ingredients. Average pay is about $58 per hour.

The usual route is a degree in food science, microbiology, chemistry, agriculture, or a related field, followed by plant or quality experience. Some people rise through production and quality-control jobs instead. The repetitive parts of the role are exactly why employers need someone dependable doing it. Food plants run every day, contamination can trigger expensive recalls, and inspection requirements do not disappear because a company wants to cut administrative work. Plant management is projected to remain stable through the next decade, with about 17,000 openings annually across industrial production management. Food safety managers also have to investigate complaints, trace ingredients through production, question employees after a failure, and decide whether product should be held or released. Sensors can monitor a temperature. They cannot take responsibility for what happens after the alarm goes off.

6. Nursing home administrator

Nursing home administrator
Image Credit: Shutterstock

If your idea of dull involves staffing spreadsheets, inspection paperwork, vendor contracts, reimbursement issues, maintenance complaints, policy manuals, and yet another meeting about meal service, nursing home administration delivers. Administrators run skilled nursing and long-term care facilities rather than providing most bedside care themselves. They juggle staffing, budgets, resident complaints, licensing requirements, safety problems, and compliance reviews. Average pay is around $65 per hour.

This is usually a licensed management career, and requirements include higher education, supervised experience, and an administrator examination. Many people enter after working in healthcare administration, nursing, social services, or facility operations. The demand underneath the job is hard to miss. Medical and health services management is projected to grow 24% through 2035, with tens of thousands of openings expected each year as healthcare expands and the population gets older. Software can schedule employees and generate compliance reports, but somebody still has to deal with an inspector standing in the building, a staffing shortage before the night shift, an angry family, a broken boiler, and the consequences when the facility does not meet required standards.

7. Medical dosimetrist

Medical dosimetrist
Image Credit: Shutterstock

Medical dosimetrists do highly specialized cancer treatment planning, often spending long stretches at a workstation defining treatment areas, calculating radiation doses, comparing plans, and checking whether healthy tissue is receiving too much exposure. It is painstaking rather than dramatic. The patient may never know how many hours went into the plan before treatment begins. Average pay is about $61 per hour.

The path normally involves a bachelor’s degree plus an accredited medical dosimetry program and professional certification. Many dosimetrists come from radiation therapy backgrounds. Employment in radiation therapy is projected to grow at about the same pace as the overall workforce through 2035, and cancer treatment continues to create a steady need for specialized radiation planning. Planning software has become much more powerful and can generate possible treatment approaches faster than it once could. That does not eliminate the person responsible for reviewing anatomy, checking dose limits, discussing the plan with radiation oncologists and physicists, and catching something that does not make clinical sense. This is a good example of a job where technology changes the boring parts without removing the licensed expertise and human accountability surrounding them.

8. Clinical laboratory manager

Clinical laboratory manager
Image Credit: Shutterstock

A clinical laboratory manager oversees the place where blood, tissue, urine, and other specimens become test results. Daily work includes instrument quality checks, staffing schedules, proficiency testing, supply problems, procedure reviews, inspection preparation, and figuring out why a machine suddenly started producing questionable numbers. Average pay is around $64 per hour.

Managers generally start as medical laboratory scientists or technologists, then add supervisory experience and any credentials required for their laboratory. A bachelor’s degree is common. Employment among clinical laboratory professionals is projected to grow at about the overall average through 2035, with more than 20,000 openings expected each year because hospitals and laboratories continually need replacements as workers leave the field. Laboratories already use extensive automation, but that has not removed the need for trained people overseeing accuracy. An analyzer can process hundreds of samples. It cannot independently decide whether a quality-control failure invalidates yesterday’s results, manage a contamination investigation, prepare for an inspection, coach an employee who keeps making the same mistake, or take professional responsibility for whether the laboratory’s results can be trusted.

9. Aircraft maintenance manager

Aircraft maintenance program manager
Image Credit: Shutterstock

Aircraft maintenance managers are responsible for an enormous amount of work that passengers never see. They coordinate inspections, repair schedules, mechanic staffing, parts availability, maintenance records, airworthiness requirements, and the long list of routine checks needed to keep aircraft operating legally and safely. Much of the job is planning and documentation rather than standing dramatically beside a jet engine. Average pay is about $63 per hour.

Most managers first spend years as aircraft mechanics, avionics technicians, inspectors, or maintenance supervisors. Industry certification and hands-on experience matter because you need to understand what the crews underneath you are actually doing. Employment for aircraft and avionics maintenance workers is projected to grow 6% through 2035, with more than 13,000 openings expected each year. Aircraft also require scheduled work whether the economy is exciting or boring. Digital maintenance systems can track hours and flag an upcoming inspection, but the physical aircraft still has to be examined, repairs have to be verified, unusual defects need investigation, and qualified people have to decide whether equipment is safe to return to service. That accountability makes experienced maintenance leadership difficult to replace.

10. Building commissioning manager

Building commissioning manager
Image Credit: Shutterstock

Commissioning managers make sure new and renovated buildings actually work the way the plans say they should. That can mean witnessing tests on air handlers, pumps, electrical systems, fire alarms, controls, generators, lighting, and other equipment, then documenting every problem that needs correction. There are checklists for the checklists. Average pay is about $61 per hour.

People typically arrive from mechanical, electrical, controls, facilities, or construction backgrounds. Engineering or construction degrees are common, but extensive field experience can matter just as much. Demand gets support from a construction sector that increasingly uses sophisticated building controls and energy systems. Construction management employment is projected to grow 9% through 2035, with tens of thousands of openings a year. Commissioning is especially difficult to hand completely to software because somebody must be physically present when systems are started and tested. A computer may record that a damper moved or a pump started. The commissioning team still has to notice strange noises, bad airflow, incorrect wiring, conflicting control sequences, and systems that technically run but plainly do not operate the way the owner paid for them to operate.

11. Utilities field operations manager

Utilities field operations manager
Image Credit: Shutterstock

Utilities field operations managers oversee the crews who keep electric, gas, water, or similar systems working outside the office. The routine can involve work orders, equipment inspections, crew assignments, service interruptions, maintenance schedules, contractor coordination, safety meetings, and complaints about why a job has not been finished yet. Average pay is about $55 per hour.

This is often a promotion-from-within career. Managers may begin as technicians, lineworkers, operators, crew leaders, or supervisors and build deep knowledge of a utility’s equipment and procedures. The need for field work is expanding as aging systems are upgraded and electricity demand changes. Electrical line installation and repair employment, for example, is projected to grow 10% through 2035, with roughly 10,900 openings each year. The management jobs above those crews benefit from the same workload. Dispatch software can assign a truck, but it cannot climb into a damaged substation, inspect a failed piece of equipment, negotiate access with a property owner, or decide how to reorganize crews when a normal workday suddenly turns into an outage response.

12. Insurance loss control manager

Insurance loss control manager
Image Credit: Shutterstock

Insurance companies do not only calculate premiums. They also send people to factories, warehouses, construction sites, offices, and other properties to figure out what could burn, break, leak, collapse, injure somebody, or produce a large insurance claim. Loss control managers oversee that work, set inspection standards, review recommendations, and help underwriters understand risks. Average pay is about $62 per hour.

People often come from insurance, engineering, fire protection, occupational safety, industrial operations, or risk-control backgrounds. Several years of inspection or underwriting-related experience usually come before management. It is an oddly durable kind of work because insurers have a financial reason to know what they are covering before something expensive happens. Related loss-prevention management is classified as a bright-outlook occupation with strong projected demand and large numbers of openings. Cameras, sensors, and software can help identify obvious hazards, but real properties are messy. Somebody still has to walk the site, notice that employees routinely block a fire door, ask why sprinklers have not been inspected, understand an unusual manufacturing process, and decide whether a problem is minor or serious enough to change how an account is insured.

13. Labor relations manager

Labor relations manager
Image Credit: Shutterstock

Labor relations managers spend their days with collective bargaining agreements, grievance files, attendance rules, disciplinary procedures, seniority language, meeting notes, and disputes over what a contract sentence actually means. They work for manufacturers, transportation companies, healthcare systems, public agencies, utilities, and other employers with organized workers. Average pay is about $65 per hour.

A bachelor’s degree and years of experience in labor relations or human resources are common. Some people also have legal training, but being an attorney is not normally required. Broader human resources management is projected to grow 6% through 2035, with thousands of openings each year. Labor relations has another layer of staying power because collective bargaining, grievances, investigations, and disciplinary meetings depend heavily on people dealing with other people. Software can search a contract and summarize old cases. It cannot easily read the mood in a tense meeting, judge whether a supervisor is making a weak case, rebuild trust after a dispute, or decide whether pushing one interpretation of a contract is worth months of conflict. Much of the work is routine paperwork, but the decisions around that paperwork still carry real consequences.

14. Purchasing manager

Purchasing manager
Image Credit: Shutterstock

Purchasing managers oversee the unglamorous business of making sure an organization gets the materials and services it needs without paying too much or discovering six months later that the supplier cannot deliver. Days can disappear into vendor reviews, bids, contract renewals, inventory discussions, delivery problems, supplier scorecards, and negotiations over tiny details. Median pay for purchasing managers is $148,080 a year.

Many employers prefer a bachelor’s degree and want several years of experience as a buyer, purchasing agent, or procurement specialist before handing someone a department. Employment for purchasing managers is projected to grow 4% through 2035, while the broader purchasing field is expected to produce more than 50,000 openings each year. Procurement software can compare quotes and automate routine orders, but the manager still has to deal with shortages, poor quality, contract disputes, supplier failures, and negotiations where the cheapest bid may be the worst choice. Manufacturers, hospitals, government agencies, construction companies, distributors, and large service businesses cannot operate for long if critical supplies stop showing up. That makes experienced purchasing people far harder to dispense with than the paperwork-heavy nature of the job might suggest.

15. Industrial production manager

Industrial production manager
Image Credit: Shutterstock

An industrial production manager spends a lot of time caring about numbers such as units produced, hours of downtime, scrap rates, missed schedules, overtime, maintenance backlogs, and whether the night shift has enough people. They run part or all of a factory, coordinating workers and equipment so products come out on time and within quality standards. Median pay is $126,060 a year.

A bachelor’s degree is common, although experienced production workers can still climb through supervisor and management positions in some companies. Employers usually want years of plant experience because knowing how production works when everything goes wrong matters more than simply understanding a spreadsheet. Employment is projected to grow about as fast as the overall job market through 2035, with around 17,000 openings expected each year. Modern plants automate plenty of individual tasks, but factories also contain people, aging machinery, suppliers, safety rules, quality requirements, and customers who expect deliveries. When a machine goes down at midnight and tomorrow’s shipment is suddenly in jeopardy, somebody still has to decide what gets repaired first, whether overtime is justified, which orders move, and what to tell the customer.

16. Actuary

Actuary
Image Credit: Shutterstock

Actuaries spend their working lives measuring the odds of things most people would rather not think about. Insurance pricing, death rates, medical costs, disasters, pensions, investment assumptions, and future claims all become tables, models, reviews, and meetings about whether the assumptions are reasonable. Median pay is $130,000 a year, and the profession rewards people who keep passing a long sequence of difficult professional exams.

A bachelor’s degree with strong mathematics, statistics, economics, or finance coursework is the standard entry route. The exams can take years, but candidates usually begin working before finishing the full credential. Employment is projected to grow 9% through 2035, much faster than the overall market, as insurers and other organizations deal with healthcare costs, natural disasters, changing regulations, and new forms of financial risk. Computers already perform the heavy calculations. That has been true for years. The value of an actuary is increasingly in choosing assumptions, testing whether a model makes sense, explaining uncertainty, and putting professional judgment behind decisions involving huge sums of money. If spending Wednesday afternoon reviewing mortality assumptions sounds appropriately boring, the pay helps.

17. Pharmacist

pharmacist handing over prescription
Image Credit: Shutterstock

For many pharmacists, the day is far less dramatic than television medicine. It is prescription after prescription, interaction checks, insurance problems, inventory controls, controlled-substance records, patient questions, vaccinations, and making sure the medication in the bottle matches what the prescriber intended. Median pay is $140,910 a year.

Becoming a pharmacist requires a professional pharmacy degree and licensure, so this is a long training path rather than an easy career change. Once you are qualified, though, the work exists across hospitals, outpatient facilities, pharmacies, clinics, long-term care, and other settings. Employment is projected to grow 5% through 2035, with about 12,500 openings expected each year. Pharmacy has automated dispensing machines, electronic prescribing, interaction alerts, and increasingly sophisticated software. None of those systems removes the licensed professional responsible for catching a dangerous dose, questioning an unusual prescription, counseling a patient, handling controlled medications, or deciding whether an alert can safely be overridden. The routine can become extremely repetitive, especially in high-volume settings, but regulation and patient safety keep the human pharmacist firmly in the process.
18. Optometrist

Optometrist
Image Credit: Shutterstock

Optometry is one of the more orderly corners of healthcare. Much of a normal day can be a steady stream of eye charts, refractions, pressure checks, retinal examinations, contact lens fittings, and conversations about why somebody’s reading prescription changed again. Serious problems do turn up, but many appointments follow a familiar rhythm. Median pay is $136,570 a year.

The barrier to entry is substantial. You need a Doctor of Optometry degree and a license, so this is best suited to someone willing to commit to a professional healthcare career. Once qualified, demand looks healthy. Employment is projected to grow 10% through 2035, with an aging population creating more need for vision care and monitoring of eye diseases. Diagnostic devices can already measure refraction, photograph the retina, and flag suspicious findings. Patients still need a licensed clinician to examine the eye, interpret conflicting results, distinguish a routine vision change from disease, prescribe treatment, and make referrals when something looks wrong. Compared with emergency medicine or surgery, the schedule and patient flow can be strikingly predictable, which is part of the appeal for people who prefer steady clinical work over constant surprises.

September is when the household spending list starts growing again. Cooler-weather clothes come back into rotation, school lunches need filling, garages need reorganizing before winter, and suddenly that vacuum or mattress you have been ignoring all summer looks a lot harder to ignore.

Costco’s current warehouse savings run through September 20, 2026, with discounts across clothing, food, home goods, appliances, and electronics. The better buys are the ones that replace something you already need or cut the cost of a regular expense, not the giant pack you bought simply because it was there.

Prices are accurate at the time of publishing but may vary by store or sell out quickly.

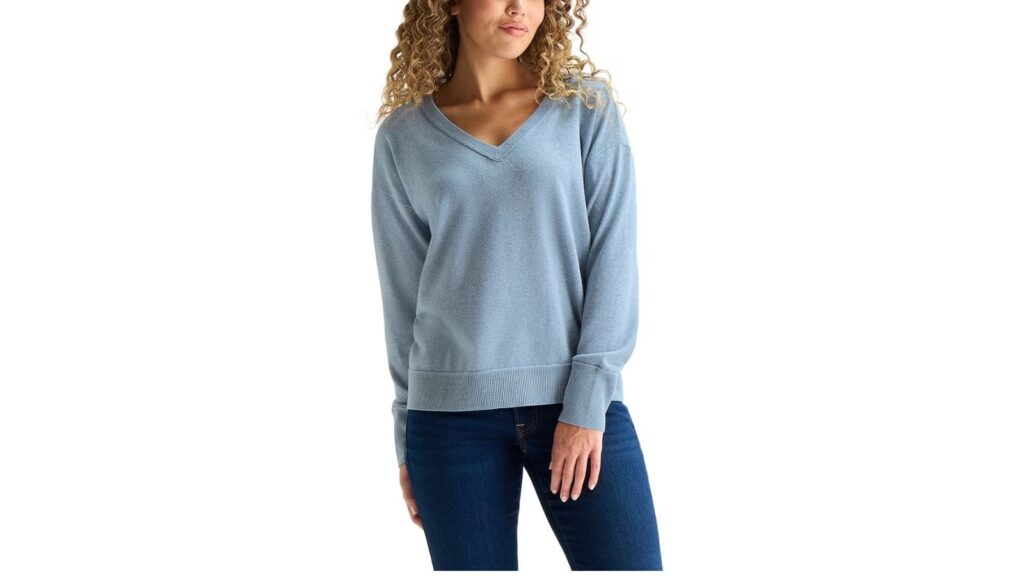
Lucky Brand women’s V-neck sweater

v neck sweater
Image Credit: Costco

A decent fall sweater for less than the price of many basic T-shirts is worth a look. The Lucky Brand V-neck is $12.99 during the current sale, which takes $4 off. It comes in several neutral and fall-friendly colors, including black, tan, light blue, and maroon.

The midweight fabric makes more sense for September than buying a heavy winter sweater too early. It can handle cool mornings over a T-shirt and still fit under a coat later. If you need to replace a stretched-out work or weekend sweater anyway, $12.99 is an easier hit to the clothing budget than waiting until colder weather pushes you toward pricier options.

Hilary Radley women’s crepe pants

crepe pants
Image Credit: Costco

Work pants can get expensive quickly, especially if you are rebuilding a wardrobe after living in jeans all summer. These Hilary Radley crepe pants are $12.99, $3 off the previous listed price. They have a mid-rise, slim leg, front pockets, and sizes up to 3X online.

Black, camel, and olive are practical enough to work with clothes already hanging in your closet, which matters more than buying something that needs three new tops to go with it. At this price, they are particularly useful for anyone heading back to an office, starting a new job, or simply needing one presentable pair of pants without turning it into a $60 purchase.

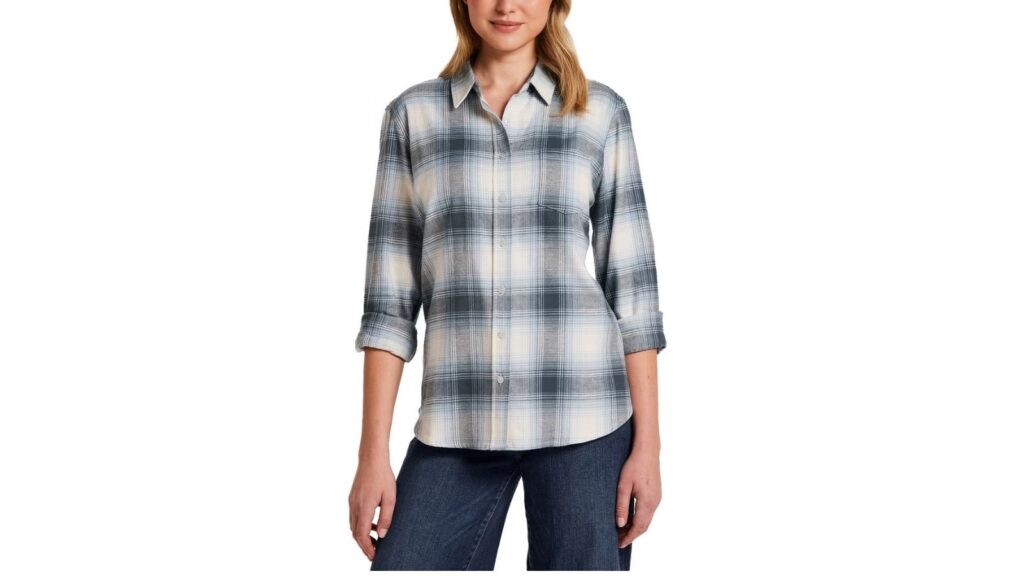
Weatherproof Vintage women’s flannel shirt

flannel shirt
Image Credit: Costco

Flannel earns its keep in fall because it works as both a shirt and a light outer layer. Weatherproof Vintage’s women’s version is down to $9.99, after a $3 discount. Costco notes that selection can vary by location, so colors and sizes may not be identical from warehouse to warehouse.

Ten dollars is a sensible price for something you can wear over tanks and tees now, then under a jacket when October gets colder. It is also cheap enough to use as a rough-and-ready layer for yard work, weekend errands, or camping instead of wearing out a nicer shirt. If your fall wardrobe already has plenty of flannel, obviously leave it there. Cheap duplicates are still duplicates.

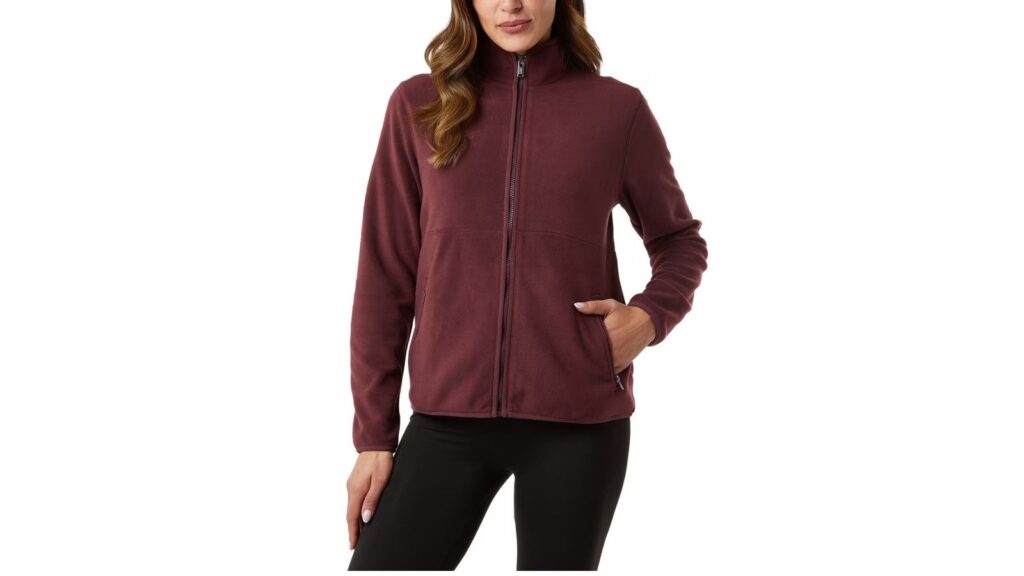
32 Degrees women’s fleece jacket

fleece jacket
Image Credit: Costco

A fleece jacket fills the awkward September gap between “too cold for short sleeves” and “absolutely not coat weather yet.” Costco has the 32 Degrees women’s fleece jacket for $11.99, which is $3 off during the current savings period.

This is the kind of inexpensive layer that makes sense for dog walks, school pickup, sports sidelines, and keeping in the car. More importantly, it can postpone the point when you start running the heat just because the house feels a little chilly first thing in the morning. You do not need a designer logo for a jacket whose main job is keeping your arms warm while taking the trash out.

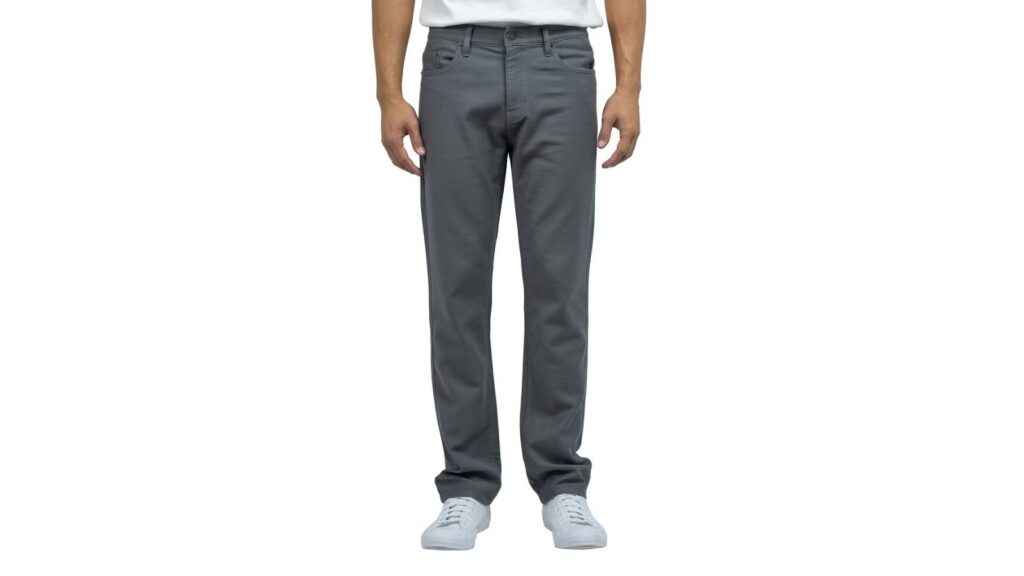
Jachs men’s 5-pocket pants

pants
Image Credit: Costco

If the jeans in your closet have reached the “technically still pants” stage, Costco has a low-cost replacement. Jachs men’s 5-pocket pants are $12.99 after a $2 discount. The five-pocket design gives them the everyday usefulness of jeans without pushing the price into premium-denim territory.

That makes them useful for work, errands, travel, or any wardrobe where one pair of pants ends up doing most of the heavy lifting. A $2 discount is not enormous, but the final price is the reason this one makes the cut. Replacing genuinely worn-out basics at $12.99 is easier on a clothing budget than treating fall as an excuse for a whole new wardrobe.

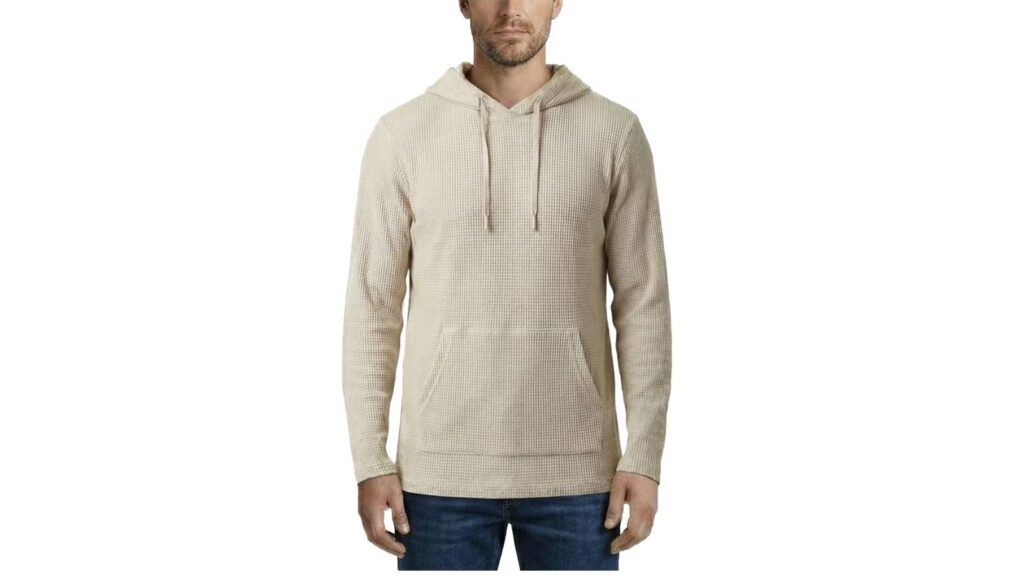
Rainforest men’s textured hoodie

hoodie
Image Credit: Costco

For an easy fall layer, the Rainforest men’s textured hoodie is currently $12.99, down $3. It is substantial enough to cover cool mornings without committing to a winter coat, and Costco offers it both in warehouses and online while supplies last.

The value here is straightforward. Hoodies get used hard, washed often, left in cars, and occasionally disappear into another family member’s closet. Paying around $13 for one you can wear repeatedly is more reasonable than spending several times that on a basic layer. It also works for anyone trying to stretch warm-weather clothes longer by adding one dependable piece rather than replacing half a wardrobe for fall.

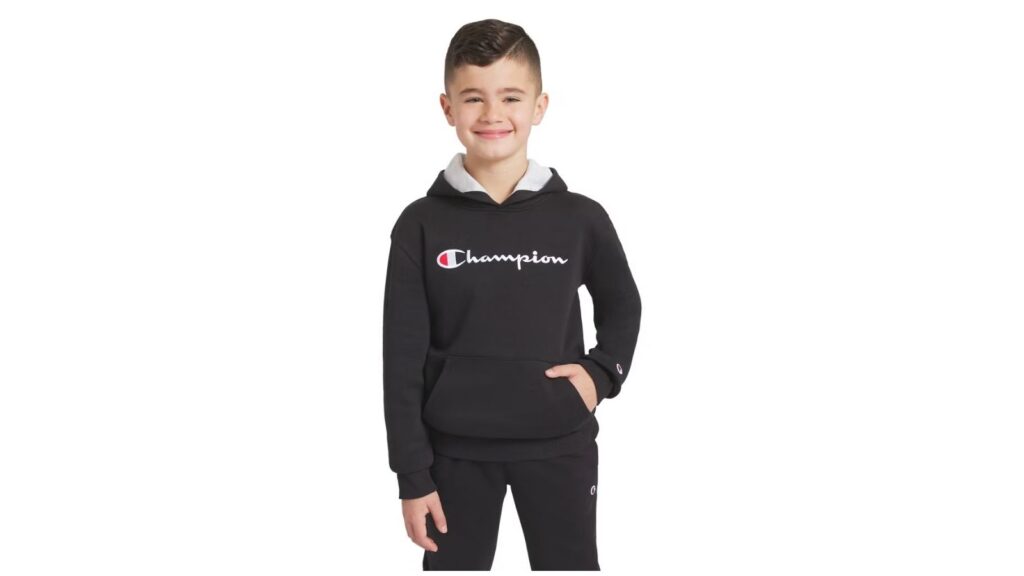
Champion youth hoodie

youth hoodie
Image Credit: Costco

Kids can outgrow fall clothes before they manage to wear them out, which makes a $7.99 Champion hoodie considerably easier to justify. Costco has taken $2 off for September, and selection varies by warehouse.

At under $8, this works well as the everyday sweatshirt that goes to school, practice, the playground, and everywhere else a nicer jacket is likely to get lost. Buying one inexpensive layer at the start of cooler weather can also give you time before paying for a heavier coat. That is especially useful when last year’s outerwear is suddenly two inches too short because children apparently conduct most of their growing while nobody is looking.

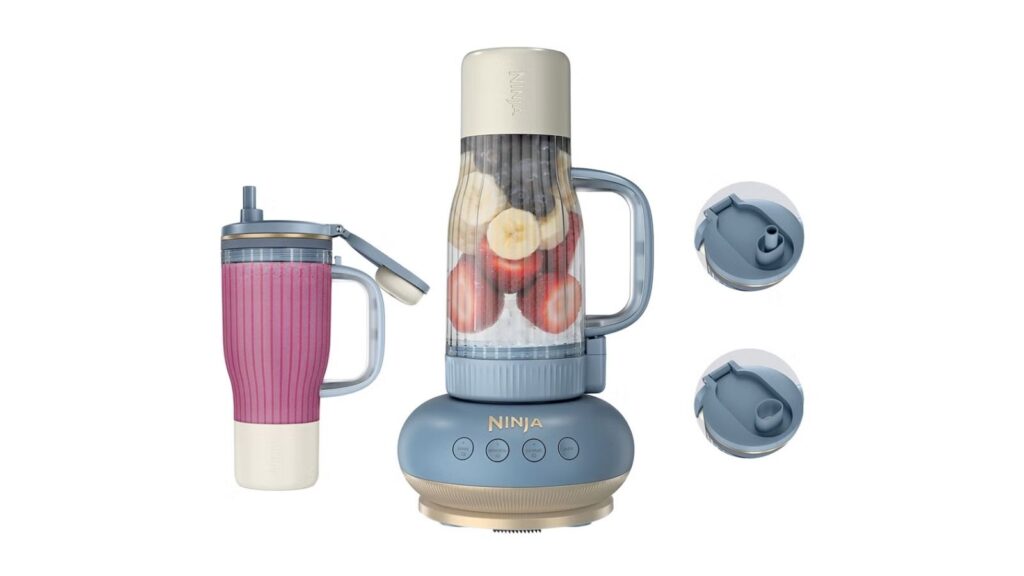
Ninja BlendBOSS tumbler blender

Ninja blender
Image Credit: Costco

If breakfast regularly gets skipped or bought on the way to work, a personal blender can earn its counter space. The Ninja BlendBOSS is $89.99 after a $30 discount and comes with two 26-ounce tumblers and straws.

Ninety dollars is not pocket change, so this deal only makes sense if you will actually use it. For households already buying smoothies, protein drinks, or bottled breakfast drinks several times a week, making them at home can put the machine to work quickly. The second tumbler also matters if two people are heading out in the morning. If you already own a perfectly good blender, save the $89.99 and keep using it.

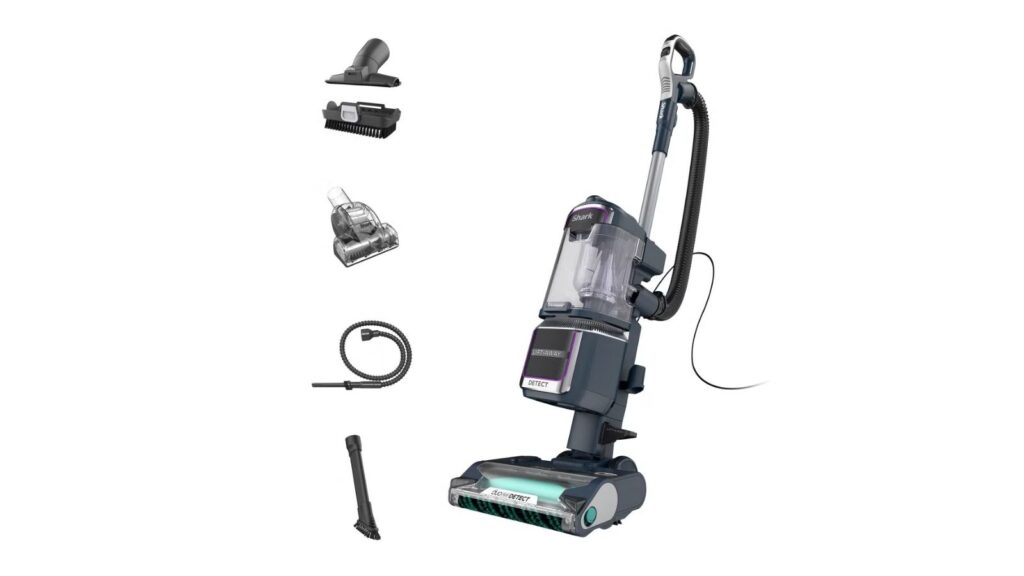
Shark Detect Performance upright vacuum

vacuum
Image Credit: Costco

A vacuum is not a fun fall purchase, but tracked-in leaves, pet hair, and muddy entryways do not care. Costco has the Shark Detect Performance Lift-Away upright vacuum for $239.99, which is $60 off. It includes Shark’s Lift-Away design and DuoClean Detect floor head.

This is a replacement purchase, not a reason to retire a vacuum that still works. But if your current one has lost suction, requires expensive repairs, or has become more duct tape than appliance, taking $60 off a machine you already needed is meaningful. The detachable design is useful for stairs and furniture, so one vacuum can handle jobs that might otherwise tempt you into buying a second handheld model.

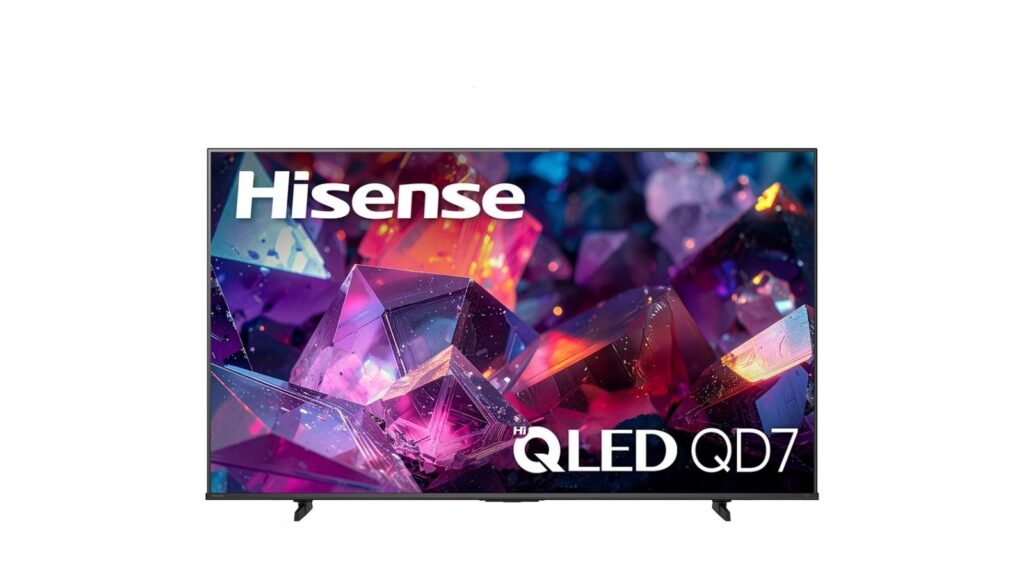
Hisense 55-inch QD7 smart TV

Hisense TV
Image Credit: Costco

Football season and longer evenings tend to make television deals more tempting, but size and price still matter. The 55-inch Hisense QD7 4K Hi-QLED smart TV is listed at $279.99. Costco also includes an Allstate protection-plan bundle for five years of total coverage.
That is a much easier number to absorb than four figures for a giant premium television, and 55 inches is large enough for many living rooms without requiring furniture rearrangement. This belongs on the list for someone replacing an old or failed set, not somebody who already has a perfectly functional TV. The included extended coverage adds value without creating another checkout-line add-on.

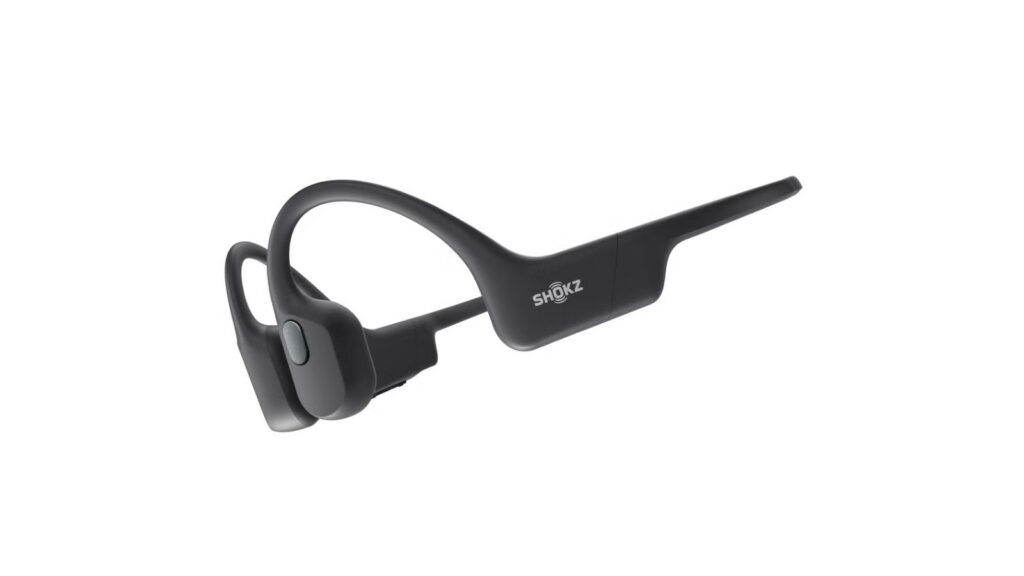
SHOKZ OpenRun SE headphones

headphones
Image Credit: Costco

Anyone moving workouts indoors and outdoors as the weather changes may appreciate headphones that leave the ears open. The SHOKZ OpenRun SE bone-conduction headphones are $69.99, $30 off. Costco lists up to eight hours of battery life plus quick charging.

The discount cuts nearly a third from the previous $99.99 price, which is the more interesting part of this deal. Open-ear headphones are useful for walking, running, commuting, or doing yard work when you still want to hear what is happening around you. They are not necessary if your current earbuds work fine, but $69.99 is a better point to replace a failing pair than paying full price later.

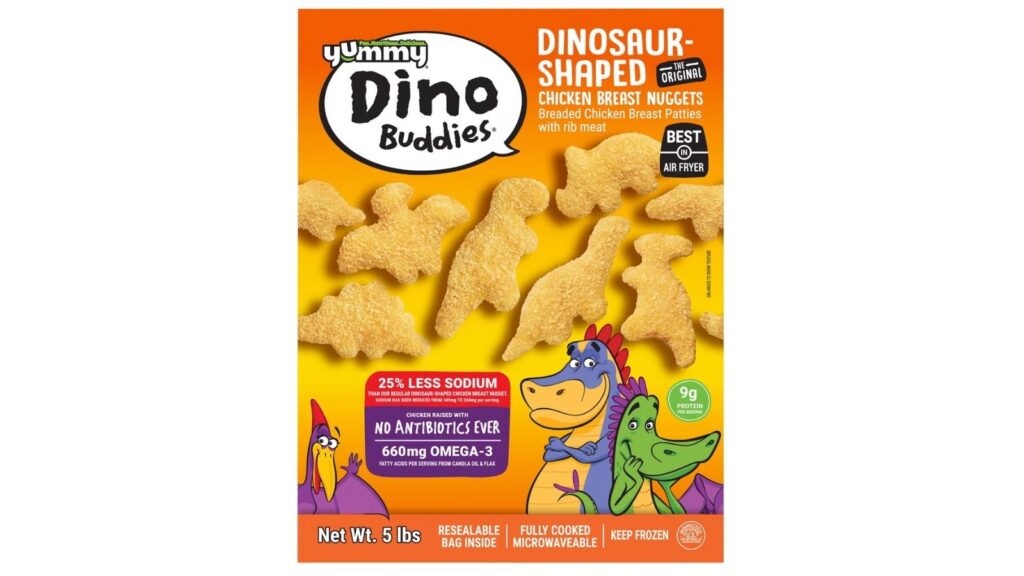
Yummy Dino Buddies chicken nuggets

dino chicken nuggets
Image Credit: Costco

A five-pound freezer bag of chicken nuggets is the sort of bulk purchase that can actually reduce spending when it replaces takeout. Yummy Dino Buddies are $10.99 during the September promotion, after a $4 discount. That works out to roughly $2.20 per pound.

For households feeding kids after school, on busy sports nights, or during those evenings when cooking has officially lost the vote, keeping an easy freezer option can prevent a $30 food-delivery order. The dinosaur shape is irrelevant to the budget, although it may help with picky eaters. Just make sure you have freezer room before buying five pounds of anything. Costco math stops working when food gets buried and forgotten.

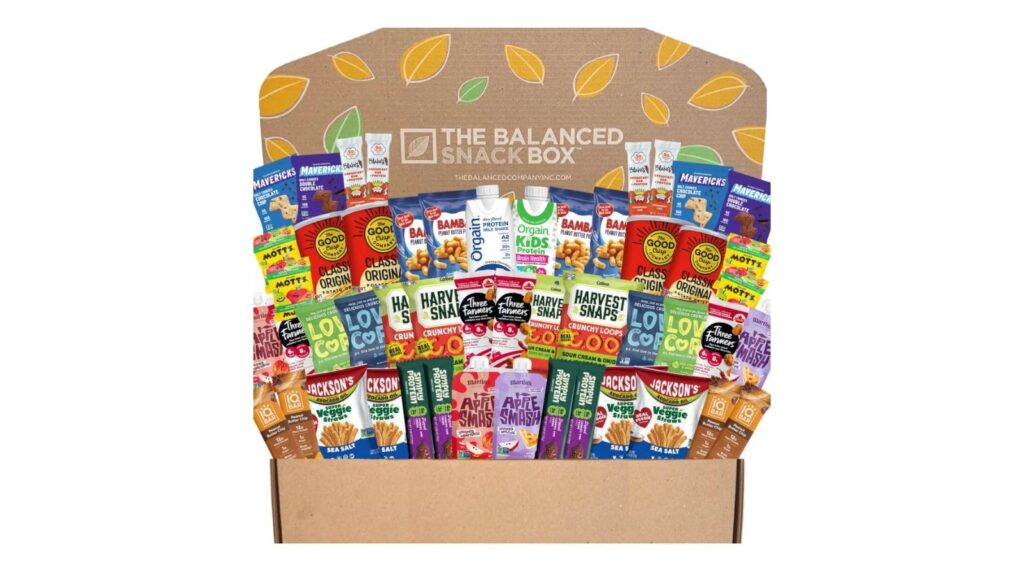
The Balanced Company snack box

snack box
Image Credit: Costco

Individually packed snacks cost more than buying one big bag, but convenience can still save money if it stops daily vending-machine or convenience-store runs. The Balanced Company’s 50-piece snack box is $29.99, a sizable $15 off. That comes to about 60 cents per snack.

This works best for lunchboxes, office drawers, road trips, or households where grab-and-go snacks genuinely get used. Fifty portions are a lot for one person, so check the assortment before committing. For families who routinely buy single snacks at checkout counters, though, 60 cents each gives you a predictable cost and removes one of those small purchases that somehow keeps appearing on the bank statement.

Crafted Classics K-Cup variety pack

K Cup pod
Image Credit: Costco

Single-serve coffee is never the cheapest way to brew, but Costco’s sale makes it less expensive for households already committed to a Keurig. The 72-count Crafted Classics variety pack is $29.99 after a $10 discount. That is roughly 42 cents per cup before milk or creamer.

Compare that with buying coffee on the commute and the budget case gets clearer very quickly. This is especially useful heading into cooler mornings when the temptation to stop for a hot drink gets stronger. If you use a drip machine or reusable pod, you can still brew for less, so there is no reason to switch systems just for this sale.
Pulmuone teriyaki stir-fry udon

Teriyaki Stir-fry Udon
Image Credit: Costco

Fast dinners are where grocery spending often wins or loses. Pulmuone’s teriyaki stir-fry udon is $5.99 after $2.70 off, giving you a refrigerated meal base for considerably less than ordering noodles from a restaurant.
The practical move is to treat it as a starting point. Add whatever vegetables are lingering in the crisper and a little leftover chicken, tofu, or egg, and one convenience item becomes a fuller dinner. At $5.99, it is cheap enough to keep around for nights when cooking from scratch is unrealistic. It also takes up far less freezer space than many Costco prepared foods, which matters if your kitchen is not warehouse-sized.

Sabatino’s Tuscan-style chicken piccata

Chicken Piccata
Image Credit: Costco

Sabatino’s fully cooked chicken piccata combines chicken breast with a lemon-caper sauce and sun-dried tomatoes, giving you most of dinner without the restaurant bill. The 32-ounce package is $10.49, down $3.50.

Pair it with pasta, rice, potatoes, or frozen vegetables and you can stretch it into a meal for several people without much work. That matters during the school-year rush, when convenience food is often cheaper than the alternative you actually reach for, which is takeout. A little over $10 for the main part of dinner leaves more room in the weekly food budget than multiple restaurant entrees.

Hillshire Farm slow-roasted turkey breast

turkey breast
Image Credit: Costco

Lunch meat is one of those routine purchases where a sale can actually matter. Costco’s two-pack of Hillshire Farm slow-roasted turkey breast contains 33 ounces total and is $8.89 after $4 off.

That works out to about 27 cents an ounce, and the two separate pouches make more sense than one giant open package if your household goes through lunch meat gradually. Sandwiches are hardly exciting, but packing them for school or work is generally kinder to the budget than buying lunch five days a week. If your family already uses turkey every week, this is exactly the kind of sale worth buying around rather than adding something new to the cart.

Starbucks Caramel Macchiato creamer

Starbucks Caramel Macchiato creamer
Image Credit: Costco

If flavored coffee is your small daily luxury, making it at home is where the savings are. Costco has the 58-ounce Starbucks Caramel Macchiato creamer for $5.49, which is $2.50 off.

The large bottle only makes sense if your household will finish it before it expires, so this is not a deal for occasional coffee drinkers. For someone already buying flavored drinks several mornings a week, though, $5.49 for many home servings is easier to defend than repeating a $5 coffee-shop order. September tends to bring back the urge for sweeter, warmer drinks. There is no rule saying they have to come in a paper cup with a tip screen.

Orgain kids nutritional protein shakes

Orgain Kids Protein
Image Credit: Costco

Prepacked drinks cost more than pouring something into a reusable bottle, but they can earn their place on hectic school mornings. Costco has 24 eight-ounce Orgain Kids chocolate protein shakes for $28.99, $9 off the regular listed price. That is about $1.21 per carton.

These make the most sense for families already buying individual shakes, not as a new expense invented by a sale. Keeping shelf-stable options around can be useful for rushed breakfasts, sports bags, or days when lunch comes home mysteriously untouched. At just over a dollar each, the Costco pack is easier to budget than repeatedly buying single bottles at a convenience store.

Serenity by Tempur-Pedic cooling pillow

Cooling Pillow
Image Credit: Costco

A worn-out pillow can make an otherwise decent mattress feel terrible. The Serenity by Tempur-Pedic Frost cooling memory foam pillow is $22.99 after a $7 discount.

That is a relatively low-cost way to address a bedding problem before deciding you need an entirely new mattress. It is also useful for warmer sleepers who still overheat even as nights get cooler. Pillows are personal, so no sale price guarantees comfort, but $22.99 is less painful than premium memory-foam options that can run much higher. If your current pillow still feels supportive and does not resemble a folded bath towel, you can safely skip the replacement.

Gorilla Rack five-tier industrial rack

Industrial rack
Image Credit: Costco

Fall garage cleanup becomes much easier when boxes can go upward instead of spreading across the floor. Costco has the Gorilla Rack five-tier industrial rack for $249.99, a hefty $100 off. It measures 72 inches long, 24 inches deep, and 84 inches high.

This is still a significant purchase, so it makes sense for a real storage problem, not aspirational organizing. For garages or basements where seasonal bins, tools, bulk paper goods, and holiday decorations are stacked on the floor, one strong rack can replace several smaller shelving units. The $100 discount matters most if you were already planning to buy serious storage before winter.

Greenmade 27-gallon clear storage bins

Clear Storage Bin
Image Credit: Costco

Seasonal storage is cheaper when you buy containers once and keep reusing them. An eight-pack of Greenmade 27-gallon clear bins is $99.99 online after $30 off, or about $12.50 per bin.

The clear sides save you from opening six containers to find one scarf, and 27 gallons is large enough for off-season clothes, bedding, decorations, or kids’ gear. Eight bins are also a lot of plastic to store, so apartment dwellers and anyone with limited closet space should measure first. For households already planning a basement, attic, or garage reorganization, buying a matching set on sale is more useful than collecting random containers one at a time.

Kohler Rodean kitchen faucet

kitchen faucet
Image Credit: Costco

A leaking or failing kitchen faucet is the sort of repair that eventually stops being optional. Costco has the Kohler Rodean pull-down kitchen faucet for $129.99 after a $40 discount, with additional finishes available online.

The sale is useful if replacement is already on your home-maintenance list, because waiting until a faucet fully quits tends to remove your ability to shop around. A pull-down sprayer also handles large pots and sink cleanup without requiring a separate side sprayer. This is not a decorative impulse buy at $130. It is a chance to save $40 on a fixture you expect to use several times every day for years.

Feit 48-foot LED string lights

LED string lights
Image Credit: Costco

Cooler evenings can extend patio season well into fall, and lighting is a cheaper upgrade than buying a whole new outdoor setup. Feit’s 48-foot LED string light set is $22.99, $6 off during the current sale.

One strand can add usable light over a deck, porch, balcony, or backyard seating area without the expense of permanent hardwired fixtures. The key is having a place you will actually use them. Twenty-three dollars is reasonable for extending an existing outdoor space into September and October, but less so if the box is destined to sit unopened until next summer. Measure the area first. Forty-eight feet can be either plenty or oddly short.

Zevo flying insect trap starter kit

Insect trap
Image Credit: Costco

Fruit flies and gnats have a way of lingering after summer, especially when fall produce starts piling up on the counter. The Zevo starter kit includes two devices and six cartridges for $31.99, after an $8 discount.

Two traps let you cover separate problem spots, such as the kitchen and a room with houseplants, without buying a second starter device. This is still a niche buy. If you do not have an insect problem, keep the $31.99. But for households already replacing disposable traps or repeatedly buying short-term solutions, getting the devices plus several refills in one discounted pack can lower the cost of dealing with a recurring nuisance.

Transitioning from standard employment to business ownership marks a major change in any career path. Many professionals reach a stage where traditional employment no longer provides complete satisfaction or financial freedom.

Owning a commercial enterprise allows individuals to direct their daily schedule and build long-term financial equity. Taking this path demands careful evaluation of personal strengths and available market options.

Explore key factors to consider when moving from career goals to business ownership, including planning, finances, and growth.
Image Credit: Unsplash

Aligning personal ambitions with financial objectives

Leaving corporate life starts with a desire for direct control over daily work. Exploring franchise investment opportunities helps candidates bridge the gap between structured corporate roles and complete commercial independence. Clear financial benchmarks make this change smoother for long-term planning.

Defining clear target numbers guides every decision during the initial search phase. Founders must calculate total liquid assets, personal risk tolerance, and required monthly household income. Aligning personal targets with brand performance indicators establishes a realistic path toward commercial growth.

Establishing strict investment boundaries protects personal wealth during early transition months. Calculating exact capital requirements keeps initial expectations grounded in reality.

Evaluating previous experience against new roles

Many corporate skills transfer directly into managing a commercial enterprise. Strategic planning, personnel management, and budget tracking form a solid base for running daily operations. New business owners leverage existing communication strengths to lead teams and serve customers effectively.

Around 65% of franchise owners report franchising as a career transition. Experienced workers bring valuable operational knowledge to turnkey business models. Corporate backgrounds provide useful structures for following proven brand systems.

Prior experience in project management can keep timelines intact during buildout phases. Leaders who excel at team management find immediate success guiding unit staff.

Analyzing capital requirements and startup budgets

Launching a new location calls for a thorough understanding of initial investment demands. Franchise fee structures, real estate leases, and initial inventory orders need direct upfront capital. Having extra working reserves protects operations during early months of lower initial revenue.

Lenders look closely at personal liquidity and credit ratings before issuing commercial financing options. Setting aside extra funding for initial payroll and local marketing expenses creates operational stability. Detailed financial planning prevents unexpected cash shortages during the launch phase.

Securing competitive loan terms keeps fixed monthly overhead manageable for early operations. Owners who map out complete capital budgets lower operational stress.

Scaling operations through multi-unit expansion

Growth plans extend beyond operating a single commercial location. Successful operators frequently establish multiple units across neighboring territories to increase market share. To better manage several branches, build strong supervisory teams and delegate daily tasks.

A recent industry report indicates that 54% of all franchise units belong to multi-unit operators. Expanding unit counts allows owners to pool regional marketing budgets and streamline inventory purchasing. Running multiple locations creates distinct economies of scale for ambitious entrepreneurs.

Multi-unit growth relies heavily on standardizing operational procedures across every store location. Store managers carry out daily routines, freeing owners to focus on expansion goals.

Adopting modern systems And operations tools

Point of sale systems, digital marketing campaigns, and automated inventory software save time and lower error rates. Choosing brands with modern technical platforms keeps operations competitive.

A corporate growth report notes that capital investment in online ordering, mobile apps, virtual training, and AI customer tools boosts operational efficiency. Automated tools simplify inventory tracking and employee scheduling. Technology allows operators to deliver consistent service on every customer interaction point.

Digital platforms offer immediate insights into daily sales performance and inventory levels. Automated reporting software lets managers react quickly to shifts in consumer demand.

Balancing risk management with brand systems

Independent startups face high failure rates during their initial 3 years. Joining an established network reduces risk through tested operational playbooks, recognized logos, and existing vendor discounts. Following proven systems protects capital while building brand presence. New owners should follow structured steps to lower operational risk during early stages:

  • Review disclosure documents carefully with legal counsel
  • Speak with existing owners regarding daily operational costs
  • Conduct thorough local demographic market research
  • Secure adequate working capital reserve funds before opening

Executing these steps prevents common operational pitfalls during early launches. Structured research forms a strong safety buffer before committing long-term resources.

Building long-term growth strategies

Long-term planning involves creating clear exit strategies right from the initial start date. Business owners must decide whether to build a multi-unit enterprise supported by multi entity cash flow forecasting software or run a single unit for cash flow. Planning 5 to 10 years ahead shapes daily decisions and reinvestment strategies.

Strong unit economics make commercial entities attractive assets for prospective buyers. Maintaining accurate financial statements simplifies future sales negotiations and business valuations. Long-term strategic focus turns daily operational effort into lasting financial value.

Building equity gives founders full flexibility when deciding to transition out of the enterprise. Clear valuation growth creates meaningful options for retirement or future investments.

Image Credit: Darina Belonogova via Pexels

Moving from employment to commercial ownership offers a proven path to personal autonomy and wealth generation. Proper financial evaluation, skill matching, and system adherence establish a firm foundation for growth. Thorough research and disciplined execution allow professionals to build enterprises that support their long-term career vision.