scroll top

Your mom texts a third time to make sure you landed, even though you told her you’d call once you were settled in. Your dad brings up your job change again, the one he still thinks was a mistake, right in the middle of dinner. On their own, moments like these are small. Stacked up over years, they’re exactly the kind of thing that quietly wears a relationship down.

At least one in four American adults have cut off contact with a family member entirely, and about one in ten of those rifts are between a parent and an adult child. Most of those breaks don’t start with one blowup. They start with years of exactly this kind of thing: advice nobody asked for, boundaries treated as an attack, old roles nobody agreed to keep playing into their thirties and forties.

Most parents doing these things are not cruel. They’re running on rules that made sense when their kid was twelve and never got updated for a 34-year-old with a mortgage, a job, and opinions of their own.

Unsolicited advice on everything

arguing with adult child
Image Credit: Shutterstock

Your adult child mentions a decision, a new apartment, a career change, how they’re handling their own kid’s tantrums, and before they finish the sentence, you’re already telling them what they did wrong and how to fix it. The decision is usually already made. The advice arrives too late to change anything, so all it really does is signal that you don’t trust their judgment.

There’s a real difference between advice someone asked for and advice you handed them because you had an opinion and a captive audience. If they wanted a second opinion, they would ask you for one. Waiting to be asked isn’t withholding love. It’s treating them like an adult who is allowed to run their own life, including the parts that don’t go the way you would have done them.

A simple fix: before you weigh in, ask whether they want feedback or just want you to listen. Most adult children will tell you honestly, and most of the time, they just want to be heard, not redirected.

Criticizing their partner

Repeated jabs at a spouse or partner, over how they load a dishwasher, what they do for work, or how they parent, puts your adult child in an impossible spot. They either defend the person they chose against the person who raised them, or they stay quiet and let it build up as resentment they can’t easily voice.

Neither option strengthens anything. It usually just means your adult child starts screening what they share with you, or starts limiting how much time you spend around their partner at all, to avoid another round of the same running commentary.

If there’s an actual safety or wellbeing concern, say it once, clearly, and then respect whatever they decide to do with that information. Ongoing commentary about small habits you personally dislike isn’t concern. It’s a way of staying in control of a relationship that isn’t yours to run anymore.

Remember that this person may be around for decades. Building a decent relationship with them now costs far less than years of tension at every holiday table.

Tracking their location just in case
phone location tracker
Image Credit: Shutterstock

One in four parents of young adults say they track their child’s location with a GPS app, at least occasionally, and that jumps to 42 percent for kids between 18 and 24. Parents are also more likely to track daughters than sons. “Just in case” is the justification, but tracking a grown adult’s movements treats them like a missing-persons risk instead of someone capable of getting home on their own.

Most adult children know the app is on. Most don’t say anything, because bringing it up seems like an overreaction to something small on its own. It isn’t small. It’s a daily reminder that you don’t fully believe they can be trusted with their own whereabouts, and that reminder builds up quietly over months and years.

If the worry is real, say it out loud and ask for what you actually need, whether that’s a text when they land or a call when they get home late. Monitoring someone’s location without asking is surveillance dressed up as love, even when the intent behind it is nothing but love.

Playing favorites and pretending you don’t
angry and disappointed parent with adult child
Image Credit: Shutterstock

Forty percent of Americans with siblings believe their parents had a favorite child, and the ones who believe it report far worse relationships with their parents than those who don’t, 47 percent satisfied compared with 68 percent. Adult children remember who got bailed out of a bad decision and who got a lecture for the identical mistake. They remember whose calls got returned first and whose achievements got the bigger reaction.

Denying it when it’s obvious is worse than the favoritism itself. Kids who felt like the less-favored one aren’t asking for a confession at dinner. They’re asking you to notice the pattern and actually change it, in real time, instead of insisting it was never there while doing it again the following week.

Favoritism rarely looks like an announcement. It looks like different rules, different tones of voice, and different levels of scrutiny applied to grown siblings who are all trying to be treated the same way by the same parent.

Comparing them to who they used to be

looking on laptop with adult child
Image Credit: Shutterstock

Bringing up the same story at every holiday, the rough teenage years, the college mess, the breakup you never liked, treats it as current evidence of who your adult child is now. It isn’t. People spend a decade or two becoming someone different, and most of that work happens without their parents watching closely or getting daily updates on it.

When you keep referencing an old version of them, you’re telling them you haven’t updated the picture, even after they’ve clearly changed jobs, relationships, habits, or an entire outlook on life. That’s a strange thing to hold onto for years after it stopped being relevant.

The version of them standing in front of you now is the one that matters. They would rather be seen for who they’ve built themselves into than reminded, again, of who they were at nineteen and hadn’t figured out yet.

If you want proof they’ve changed, look at the last five years instead of the first twenty. That’s where the actual evidence is, not in a story you’ve been retelling since before they moved out.

Treating their life like your report card
adult daughter and parent
Image Credit: Shutterstock

Seventy-one percent of parents say their children’s successes and failures reflect on the job they did as parents. That number explains a lot. It explains the overreaction to a normal job loss, the outsized pride over a promotion that has nothing to do with you, and the disappointment that’s really about your own image, not their actual circumstances.

Your adult child’s breakup, weight change, or career pivot is their life, not a performance review handed to you. When their wins have to validate you and their setbacks have to be explained away or defended by you at parties, they stop telling you things before they happen.

Separating your self-worth from their outcomes is the only way they’ll keep bringing you the hard stuff, instead of quietly managing what version of their life you get to hear about.

A useful test: when they tell you good news, is your first reaction about them, or about how it makes you look to your friends and siblings? The honest answer tells you a lot.

Bringing up money you gave them years ago

lending money to adult child
Image Credit: Shutterstock

Three-quarters of parents are currently supporting at least one adult child financially, even though 53 percent of those kids could cover their own basic needs without it. That kind of support is common, and for most families it’s given freely and happily at the time it’s offered.

The trouble starts when it resurfaces years later, during a fight about something else entirely, brought up as proof of how much you’ve sacrificed. Money that gets used that way stops feeling like a gift and starts feeling like a debt your kid didn’t know they were carrying.

If it was a gift, it stops being a bargaining chip the moment you hand it over. If it was meant as a loan, that needed to be a conversation with clear terms at the time, not a weapon pulled out during an unrelated argument about your grandkid’s bedtime.

Bringing up old generosity mid-argument doesn’t win the argument. It just teaches your adult child to keep future asks smaller, or to stop asking at all, so nothing can be used against them later.

Staying vague about the will
last will and testament
Image Credit: Shutterstock

Nearly half of parents haven’t told their adult children what they’ll inherit, or whether they’ll inherit anything at all, even though almost all families agree the conversation matters. Staying quiet doesn’t protect anyone from anything. It just means your kids find out the details during the worst week of their lives instead of a calm afternoon years earlier.

Vagueness also invites guessing, and people tend to guess in whatever direction fits the resentment or worry they already carry about money, siblings, and fairness. Silence doesn’t prevent conflict. It just delays it until you’re not around to help resolve it.

A plain, unemotional conversation about what’s in the will, while you’re healthy and everyone’s calm, removes most of that guesswork. It’s a hard conversation for about twenty minutes. The alternative is a hard conversation during a funeral, split between grieving siblings who each remember things differently.

You don’t have to disclose exact numbers if that feels too exposing. Even a broad overview of how things are structured and why gives your kids something solid to work with later, instead of nothing at all.

Assuming the relationship is fine

Seventy-seven percent of parents rate their relationship with their adult child as excellent or very good, but only 59 percent of those adult children say the same about the relationship from their side. That’s a significant gap, and most parents never think to check for it directly.

Smooth holidays and regular texts can coexist with real, unspoken frustration underneath. Somebody can show up to every birthday and still be quietly counting the things they wish you’d stop doing, without ever saying so, because the relationship has never felt like a safe place to bring it up.

If you’re assuming things are good because nothing has blown up, you might be missing what’s actually happening. Ask directly, and actually listen to the answer, instead of taking a quiet Thanksgiving as proof that everything between you is fine.

A simple, low-pressure question like “is there anything I do that bothers you” tends to open more doors than you’d expect, especially the first time you actually ask it and mean it.

Showing up without asking first
visiting adult children and grandchildren
Image Credit: Shutterstock

Your adult child runs their own household now, on their own schedule, sometimes with kids of their own to manage. Stopping by because you were “in the neighborhood” or because “it’s just five minutes” ignores that their home isn’t an extension of yours, and it was never meant to have an open-door policy just because you’re related by blood.

A text before you come over costs nothing and respects the fact that they might be in the middle of something you don’t know about: a nap schedule, a work call, a fight with their partner they’d rather not have you walk in on.

Ask first, every time, with no family exception built in. If they say now isn’t a good time, that isn’t rejection. It’s information about their actual life, which you don’t have full visibility into anymore, and don’t need to.

The same rule applies to keys you might still have from when they moved in. Holding onto access “just in case” after they’ve asked for it back sends a clear message about whose boundary actually counts here.

Parenting advice for their kids

Correcting your adult child’s discipline, food choices, or screen-time rules in front of their own kid undermines their authority in real time, in a way that’s hard to walk back once the grandkid has noticed. Grandkids catch on fast when Grandma’s rules seem to outrank Mom’s, and they will test that gap every chance they get.

Advice offered when asked is useful. You raised a kid yourself, and that experience carries real weight. But advice delivered as a running commentary on someone else’s parenting, unprompted, in front of the child being discussed, isn’t help at all.

It’s a power move dressed up as concern, and your adult child knows the difference between the two, even if they’re too polite to say so out loud in the moment.

If you disagree with a rule they’ve set, raise it privately, later, away from the kids entirely. In front of the grandchild, back your adult child up, even when you’d have handled it differently yourself.

Guilt trips about how often they call
on phone with son
Image Credit: Shutterstock

Most parents of young adults already text (73 percent) or talk on the phone (54 percent) with their child at least a few times a week, which means a missed day or two usually isn’t a sign of anything wrong. It’s just a busy week on their end.

Turning one unanswered call into a voicemail loaded with hurt, or a comment about how they “never check in anymore,” teaches them to dread picking up the phone rather than want to. That single guilt-laden message does more damage than the missed call ever would have.

There’s a real difference between being worried and using guilt to pull more attention out of someone. Adult children can usually tell which one they’re getting, and it changes how quickly they call back the next time.

If contact has actually dropped off and it’s bothering you, say that plainly instead of hinting at it through a sigh on voicemail. A direct ask lands better than a wounded one.
Your property tax bill went up again this year. Your Social Security check did not keep pace, and neither did your pension if you are lucky enough to have one. If you are 65 or older, you do not have to just accept the difference every time the bill arrives.
The median U.S. homeowner now pays $2,937 a year in property tax, and in states like New Jersey that median climbs past $9,000. For someone living on a fixed income, that bill does not get any easier to pay just because a paycheck stopped.

Every state runs at least one property tax break built specifically for older homeowners, and most people never file for it because nobody tells them it exists.

A tax credit that kicks in once your property tax outruns your income

property tax
Image Credit: Shutterstock

A circuit breaker credit works the way the name suggests: once your property tax crosses a set percentage of your income, the excess gets credited or refunded back to you. Massachusetts runs one of the most generous versions of this idea. Its Senior Circuit Breaker is a refundable credit worth up to $2,820 for homeowners and renters 65 and older whose property tax, plus half their water and sewer bill, adds up to more than 10% of their income.

Income has to stay under $75,000 for a single filer, $94,000 for head of household, or $112,000 for a married couple filing jointly, and it makes no difference whether you rent or own. Renters qualify by comparing 25% of their annual rent against that same 10% income threshold.

Because the credit is refundable, you can collect it even if you owe no state income tax and normally would not bother filing a return. You claim it on Schedule CB attached to your state tax return, and you have to file again every year to keep getting it. Dozens of other states run some version of a circuit breaker, though the trigger percentage, the income cap, and the maximum payout all vary by state, so check your own state’s department of revenue for the exact numbers.

A freeze that reimburses you every year your tax bill climbs

A tax freeze does not lower what you owe today. It locks in a baseline, usually the year you first qualify, and then pays you back for any increase above that baseline in the years that follow. New Jersey’s Senior Freeze reimburses eligible homeowners 65 and older for every dollar their property tax rises above their base year, as long as total income stays at or under $172,475 for the 2025 benefit year.

You have to have owned and lived in the home since at least the end of 2022, and the deadline to apply for the 2025 benefit is November 2, 2026. Miss a single year on income and you lose that year’s check, though New Jersey lets you keep your original base year if you slip back under the limit the following year.

Illinois runs a similar freeze on the assessed value itself rather than the dollar amount of the bill, and its income ceiling for the Senior Citizens Assessment Freeze just jumped to $75,000 for the 2026 tax year, up from $65,000. Neither freeze applies itself. You file a new application or affidavit with your county or state every single year to keep the benefit alive.

Letting the state front your tax bill instead of paying it yourself

pink and blue model house
Image Credit: Shutterstock

A property tax deferral is a loan, not a discount, but it can matter just as much to someone who is cash poor and equity rich. Oregon’s Department of Revenue will pay a qualifying senior’s county property taxes directly, then place a lien on the home for the amount advanced. Homeowners 62 and older with household income at or below $70,000 for the 2026 program year can apply, and the deferred balance accrues at a flat 6% simple interest, not compounded.

Nothing comes due while you stay in the home. The state gets repaid, principal plus interest, only when the property is sold, transferred, or the homeowner passes away without a surviving spouse still living there. That means less equity for whoever inherits the house, which is worth weighing against the cash flow relief now.

Washington, Minnesota, Massachusetts, and a handful of other states run comparable deferral programs, each with its own income cap and interest rate. A deferral makes the most sense for someone who plans to stay put for years and is not counting on the home’s full value passing to heirs untouched.

Trading volunteer hours for a lighter property tax bill

Massachusetts law lets any city or town adopt a program that lets residents 60 and older volunteer for the municipality in exchange for a reduction on their tax bill, with pay credited at the local minimum wage. Boston runs one of the largest versions, and qualifying homeowners there can work off up to $2,000 on their property tax bill through volunteer shifts at city departments, senior centers, and public events.

Applicants still need to meet Boston’s income limits, and hours worked cannot be shared with a spouse or family member whose name is not on the deed. The credit shows up as a line-item abatement on the actual tax bill rather than a separate check, and it stacks on top of any other exemption or deferral you already receive.

Because the program is optional for each city or town, whether it exists at all, and how much it is worth, depends entirely on where you live. Some towns cap the benefit far lower than Boston’s $2,000, and a few have not adopted the program at all. A call to your local council on aging or assessor’s office will tell you whether your community offers it.

A flat $50,000 knocked off your home’s taxable value

Some states skip the income test altogether and just hand qualifying seniors a flat dollar exemption. South Carolina’s Homestead Exemption removes the first $50,000 in fair market value of a primary residence from property tax entirely, for any homeowner over 65, totally and permanently disabled, or legally blind. There is no income limit attached.

On a typical South Carolina home taxed at the state’s residential assessment ratio, that exemption can wipe out several hundred dollars a year on its own, and it stacks on top of the separate 4% owner-occupied assessment ratio that already lowers the tax base for primary residences. You apply once through your county auditor’s office, not the assessor, and the exemption continues automatically as long as you still own and live in the home.

Because eligibility runs on age, disability, or blindness rather than income, a retired couple with a substantial pension qualifies on exactly the same terms as a retiree living on Social Security alone. That is unusual among senior property tax programs, most of which cut off well before six figures in household income.
Excluding part of your land and home from taxation entirely

older couple moving house
Image Credit: Shutterstock

Rather than a flat dollar exemption, some states carve out a share of your property’s value and remove it from the tax roll completely. North Carolina’s Elderly or Disabled Homestead Exclusion removes the greater of $25,000 or 50% of your home’s appraised value, plus up to one acre of the land underneath it, for homeowners 65 and older or totally and permanently disabled.

The catch is an income ceiling that resets every year with the Social Security cost-of-living adjustment. For the 2026 tax year, that limit sits at $38,800, counting Social Security, pensions, and every other source of income combined for you and your spouse. Go a dollar over and you lose the exclusion for that year, though you can reapply once income drops back under the line.
You file once with your county tax office by June 1, and the exclusion then renews automatically as long as your income and residency stay within the rules. North Carolina also offers a separate circuit breaker that caps your tax bill at a percentage of income instead, for homeowners who exceed the exclusion’s income limit but still qualify at a higher threshold, though you can only use one program at a time.
Wiping out the whole property tax bill on a fixed income

property tax bill
Image Credit: Shutterstock

A few states go further than a partial exemption and erase the bill completely for seniors near the bottom of the income scale. Alabama’s H-3 homestead exemption fully exempts homeowners 65 and older from all state, county, and school property tax, with no dollar cap on the exemption, as long as combined taxable income on the household’s federal return comes to $12,000 or less.
Even seniors who earn more than that threshold still get something: Alabama exempts every homeowner 65 and older from the entire state portion of property tax regardless of income, which in a state that already has some of the lowest property tax bills in the country can mean a very small final bill either way.

You file for the exemption through your county tax assessor rather than the state revenue department, and the applicable homestead type gets assigned based on the income documentation you provide. A homeowner who is permanently and totally disabled qualifies for the same full exemption at any age, with no income limit at all.

A senior-only cut to the school portion of your tax bill

School taxes are usually the single largest piece of a property tax bill, and New York’s Enhanced STAR exemption targets exactly that slice. Homeowners 65 and older with combined income at or below $110,750 for the 2026-2027 school year get a much larger exemption than younger homeowners receive under the Basic STAR program, applied against the first $88,500 of their home’s full value.

The benefit only reduces school district taxes, not county, town, or municipal taxes, except in New York City, Buffalo, Rochester, Yonkers, and Syracuse, where it works a little differently. As of 2026, the state automatically upgrades longtime Basic STAR recipients to Enhanced STAR once they turn 65, so many seniors no longer have to file a separate application for the switch.

New York City runs a second, separate benefit called the Senior Citizen Homeowners’ Exemption that cuts the city portion of the bill for income-qualified seniors, and it requires its own application through the city’s Department of Finance rather than the state. The two programs stack, and filing for one does not automatically enroll you in the other.

None of these programs apply themselves, and most of them run through a county tax assessor or auditor rather than the IRS. A short call to that office before your state’s filing deadline is often the only thing standing between you and money that already has your name on it.

Target’s Halloween shelves are filling up early this September, but you do not need a $100 animatronic to make the house feel ready for October. Some of the more useful new arrivals are sitting in the $5 to $25 range, including bathroom pieces, serving gear, lighting, porch decor, and a few decorations large enough to make a difference without buying five more things to go with them.

The better buys are the pieces you can reuse next year or put to work beyond a single Halloween party. A $5 serving bowl or $10 blanket earns its storage space more easily than another tiny trinket with nowhere to go.

Prices are accurate at the time of publishing but may vary by store or sell out quickly.

Ghost hand towel set

ghost hand towel set
Image Credit: Target

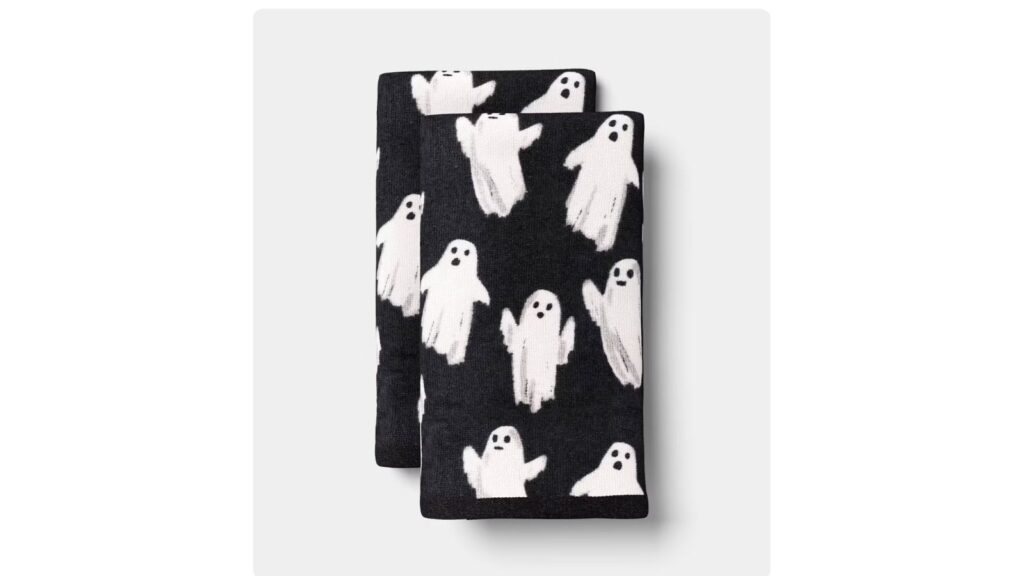
A seasonal bathroom update does not need to involve replacing half the room. Target’s two-pack of black-and-white ghost hand towels is $5, so you are paying $2.50 per towel for something that is both decorative and actually useful.

That makes more sense for a small space than buying countertop decor that only takes up room. Put one by the sink and keep the second in rotation when the first is in the wash. They also work for a guest bathroom where you want a little Halloween without committing to a full orange-and-black makeover.

Glow-in-the-dark jack-o’-lantern shower curtain

shower curtain
Image Credit: Target

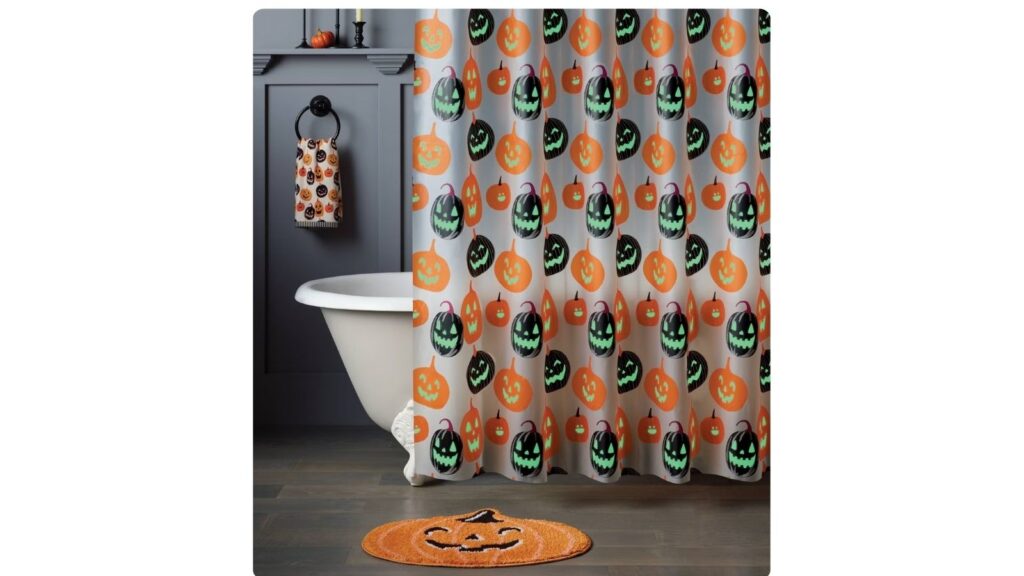
For $10, this PEVA shower curtain gives you a much bigger visual change than $10 worth of small shelf decorations. The orange-and-black jack-o’-lantern design also glows in the dark, which is an extra detail without requiring batteries or another outlet.

This is particularly useful in apartments, dorms, or smaller homes where you may not have a mantel or front porch to decorate. Swap the regular curtain for October, fold it flat afterward, and you have seasonal decor that barely takes up storage space.

Jack-o’-lantern bath rug

jack o lantern bath mat
Image Credit: Target

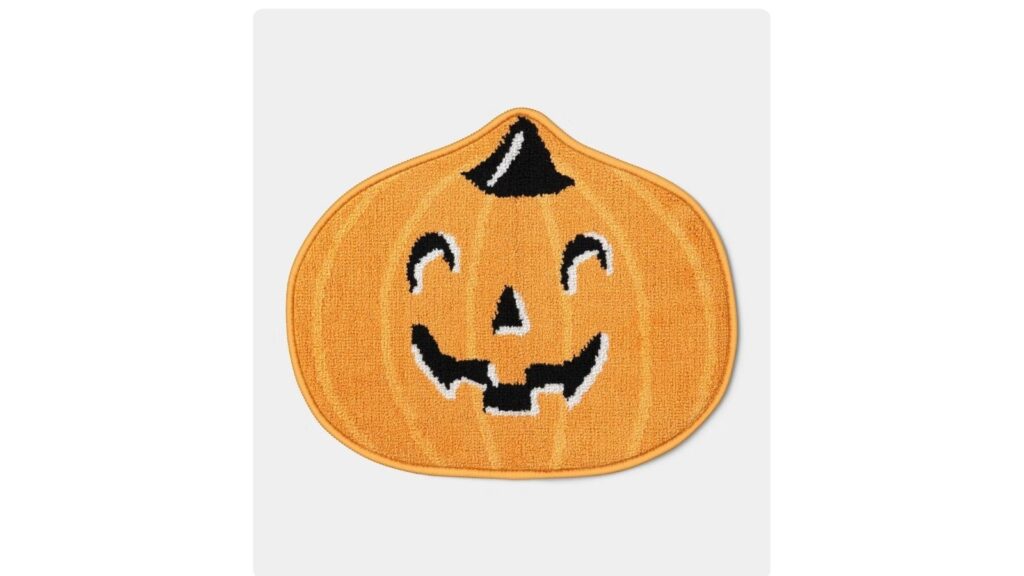
The shaped pumpkin bath rug costs $10 and measures roughly 18 by 22 inches. That is small enough for a powder room or apartment bathroom where a standard rectangular rug can eat up most of the floor.

It also does two jobs at once. You need something beside the tub or sink anyway, and the jack-o’-lantern shape supplies the seasonal decoration. That is a better use of a tight Halloween budget than buying something decorative and then still needing a bath mat.

Skeleton soap pump

skeleton soap pump
Image Credit: Target

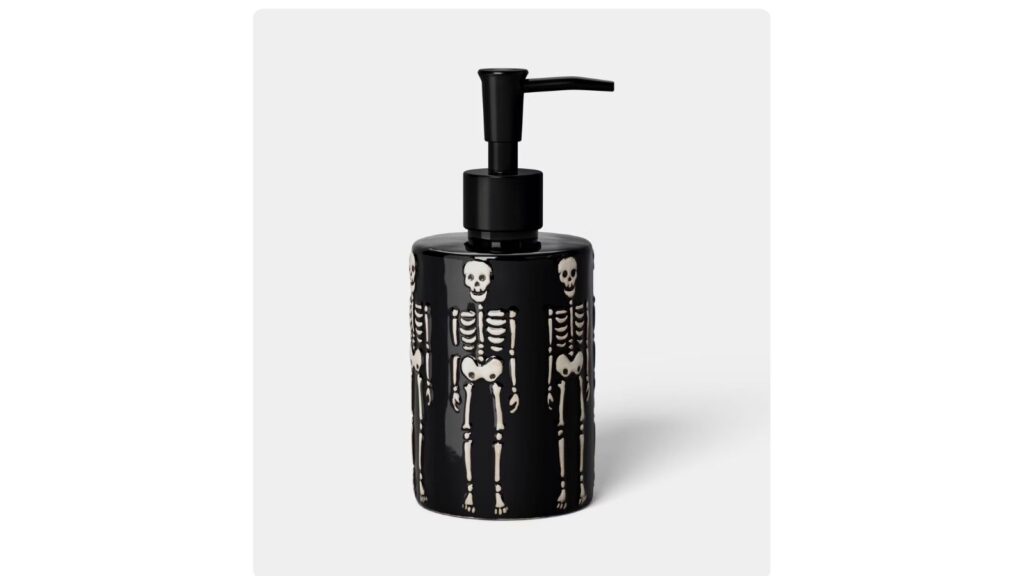
This black skeleton soap dispenser is $5, which puts it in the range of an ordinary refillable soap pump rather than pricier seasonal bathroom accessories.

The practical advantage is obvious: it earns its spot on the sink instead of competing for counter space with another decoration. Fill it with inexpensive bulk hand soap, bring it back out every September, and you have one less disposable themed product to buy each year. It is also an easy way to add Halloween to a bathroom when you do not want to store a full set of seasonal linens.

Ghost bathroom tray

Ghost bathroom tray
Image Credit: Target

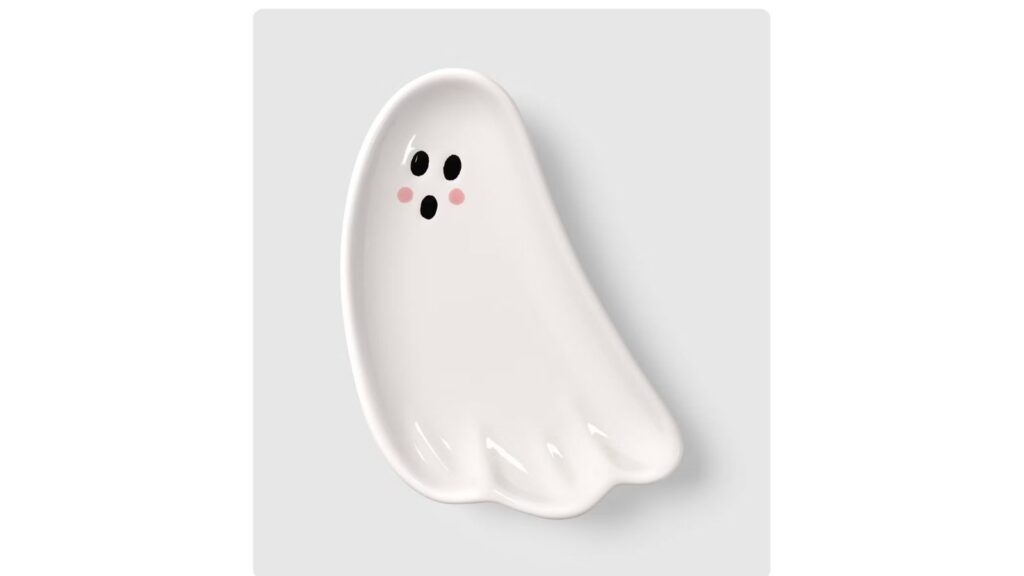
Target’s white ghost bathroom tray is $5. Use it to corral soap, perfume, rings, hair ties, or whatever normally wanders around the bathroom counter.

That makes this one easier to justify than purely decorative tabletop pieces. Small trays help make a cluttered counter look more organized, and the ghost shape brings in the Halloween part without sacrificing the function. It is especially sensible for a small bathroom where every object really does need a job.

Black cat throw pillow

Black Cat Throw Pillow
Image Credit: Target

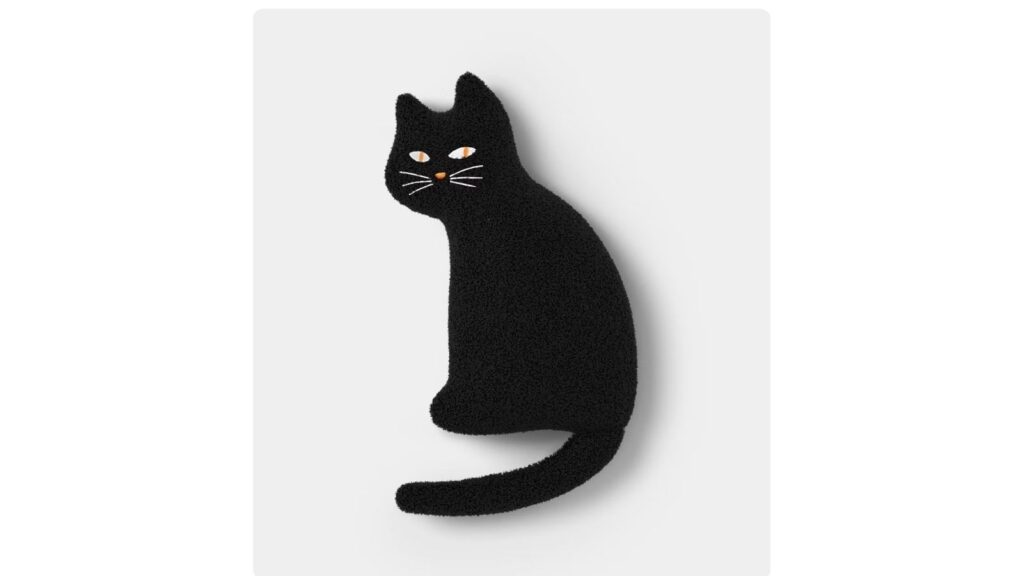
Seasonal pillows can get expensive fast, which is why this black cat shaped option stands out at $10. It is a full pillow rather than a cover, so there is nothing else you need to buy before tossing it on a sofa, chair, or bed.

One novelty pillow is also enough to make an existing neutral couch look more Halloween-ready. If storage is tight, this is the kind of purchase where stopping at one matters. A whole matching pillow collection gets bulky very quickly once November arrives.

Halloween throw blanket

Halloween throw blanket
Image Credit: Target

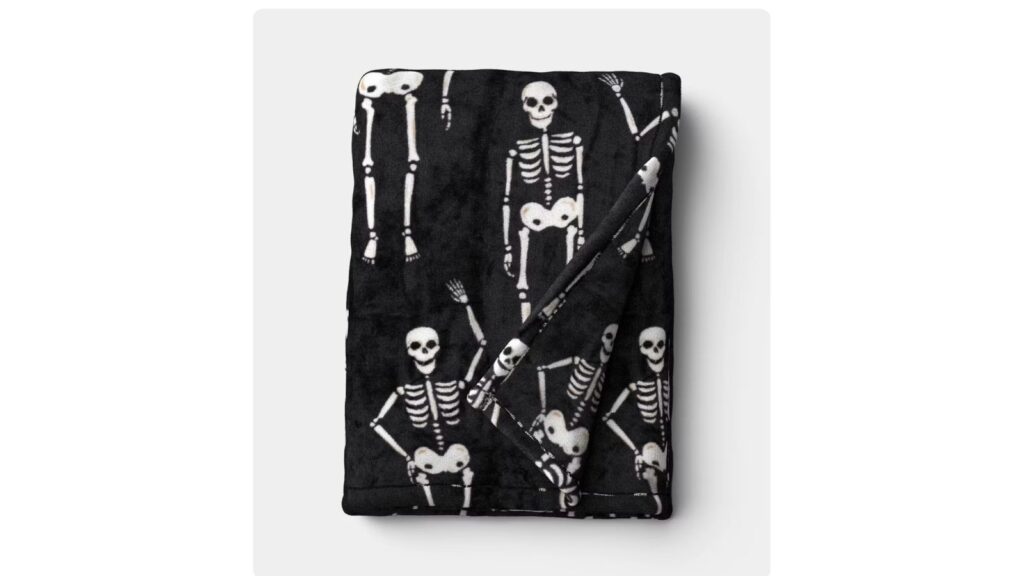
A $10 throw is one of the more practical ways to bring Halloween into a living room because you can actually use it on chilly nights. Target offers this one in several Halloween color and pattern combinations, all grouped under the same product.

The price is low enough for a seasonal blanket, but the useful part is that it can stay on the couch through most of fall instead of getting packed away immediately after Halloween. For families, it also gives kids something festive they can use for movie nights without adding another plastic decoration to the house.

Ghosty glass mug

ghost glass mug
Image Credit: Target

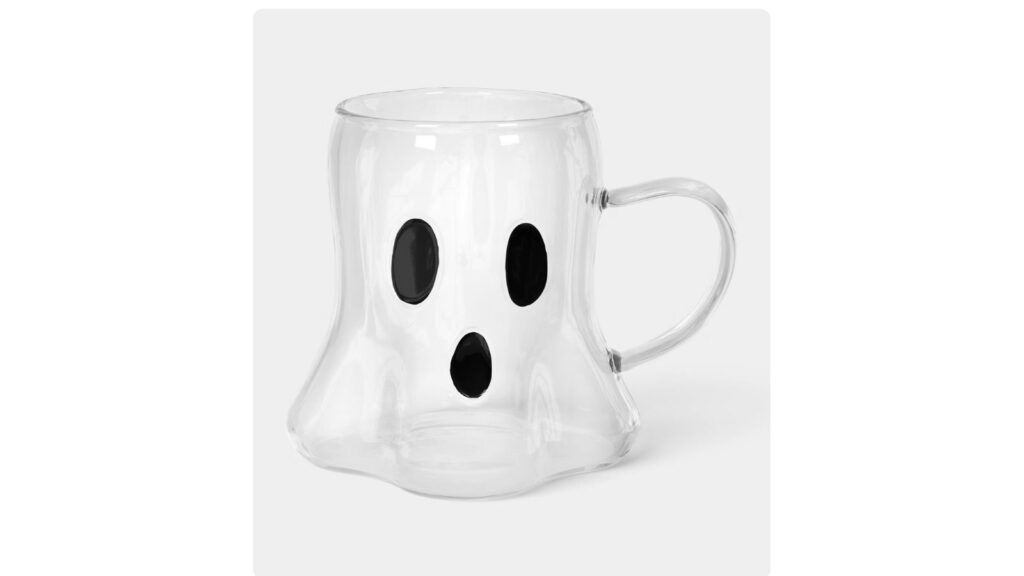
This ghost-shaped glass mug holds 14.5 ounces and costs $5. Target lists it for cold beverages, so despite the mug name, this is better treated as a glass for iced coffee, soda, or party drinks.

At five bucks, it works as a small host gift or an inexpensive way to make a Halloween movie night feel a little more fun. Just do not buy an entire cabinet’s worth because they are cute. One or two get the point across and leave you somewhere to put your normal glasses in November.

Ghost candy serving bowl

ghost serving bowl
Image Credit: Target

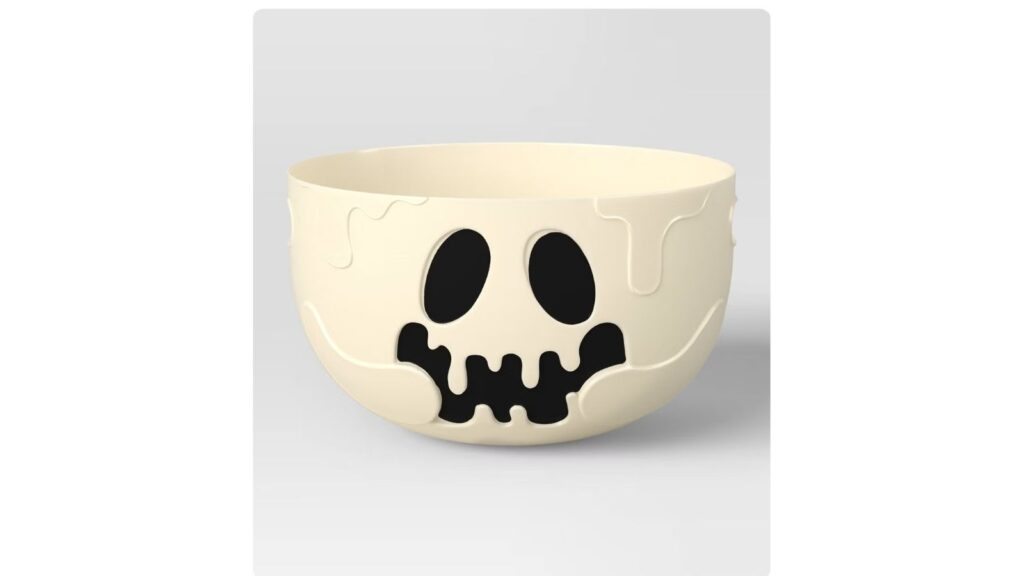
The three-liter ghost serving bowl is $5. It is BPA-free plastic with cutout handles, which makes it useful for carrying candy to the porch or passing snacks around at a party.

Three liters is enough capacity that this is not just a decorative candy dish. You can use it for wrapped treats, popcorn, chips, or kids’ party snacks, then wash it and pack it away for next year. Five dollars for a serving piece you can reuse is a much better deal than buying disposable Halloween bowls every October.

Large cauldron serving bowl

cauldron serving bowl
Image Credit: Target

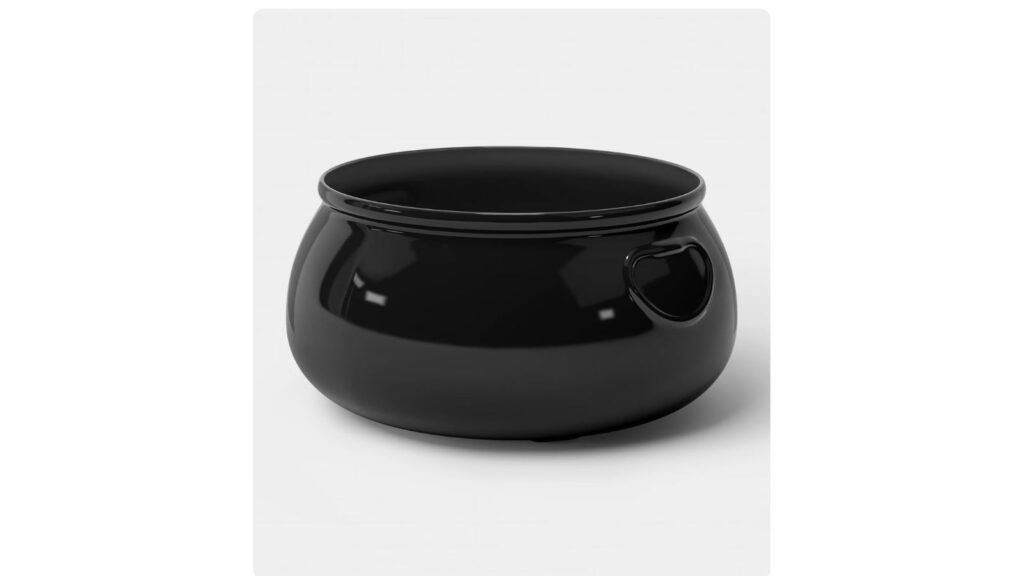
A black cauldron is about as Halloween-specific as serveware gets, but Target kept the price reasonable at $8. This one holds four quarts, giving you enough room for candy, chips, popcorn, or other party food.

The larger size is what makes it worth considering. Tiny themed bowls look nice but require constant refilling, while a four-quart container can actually handle trick-or-treat duty. It can also double as part of a tabletop display when it is not holding food, which saves you from buying a separate centerpiece.

Pumpkin drink dispenser

pumpkin drink dispenser
Image Credit: Target

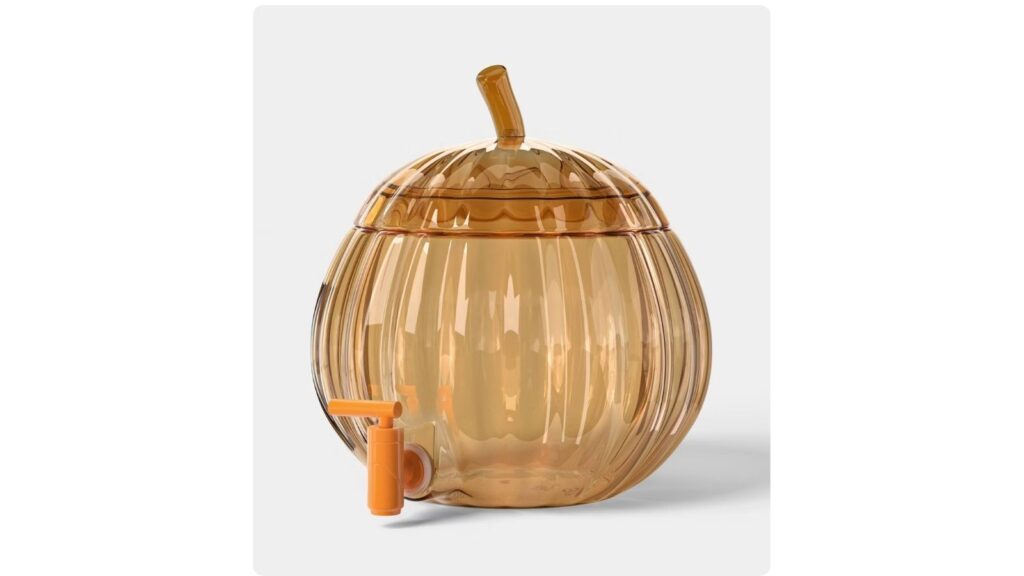
If you host Halloween parties, the two-gallon pumpkin drink dispenser is one of the more useful finds at $15. Two gallons is enough for a batch drink, lemonade, cider, or water without constantly refilling a pitcher.

This is more niche than a $5 bowl, so it only makes sense if you actually entertain. For someone who hosts every year, though, $15 for a reusable dispenser can replace disposable beverage containers and serve as part of the table decoration at the same time. That is exactly the sort of seasonal item that earns its shelf space.

Lit metal bat house

metal bat house
Image Credit: Target

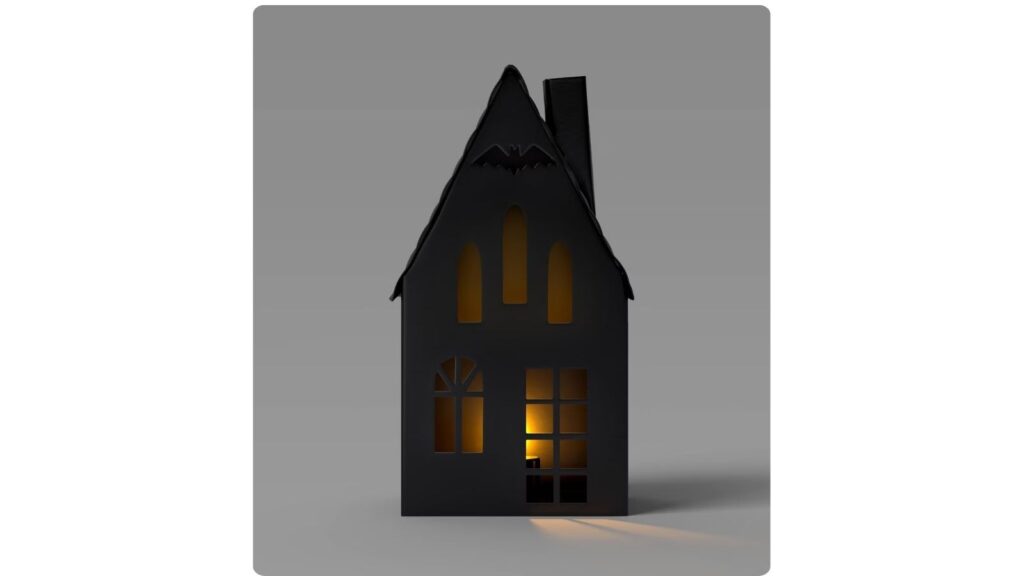
The small metal bat house is $5, and unlike a plain tabletop figurine, it lights up. That gives you a little more visual impact for the same price as many of Target’s nonlit Halloween accents.

Its small footprint is useful for anyone decorating a bookshelf, desk, mantel, or apartment windowsill. You do not need several houses to make it work, either. A single lit piece tucked among things you already own can do more than a row of tiny decorations that cost $5 apiece.

Plush spider

plush spider
Image Credit: Target

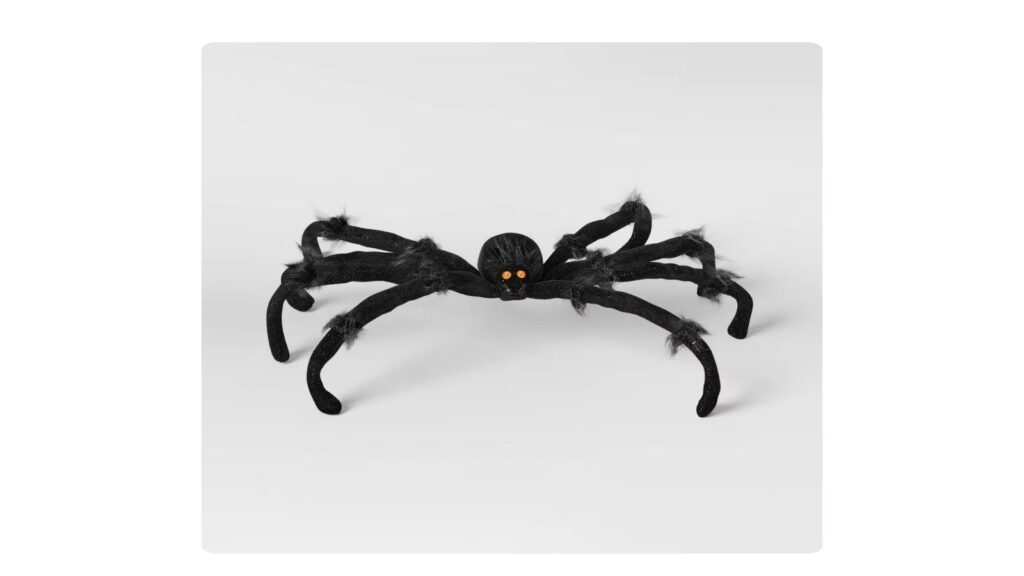
This black plush spider measures about 20 inches and comes in at $5. Its flexible legs let you change how it sits, which gives a cheap decoration more than one possible setup.

Put it over a bookshelf, wrap the legs around a stair rail, or perch it on the back of a chair. A prop that covers this much space for $5 stretches the decorating budget better than another palm-size object. Because it is soft, it is also easier to store than rigid oversized decor once Halloween is over.

Lit ghost cloche

Lit ghost cloche
Image Credit: Target

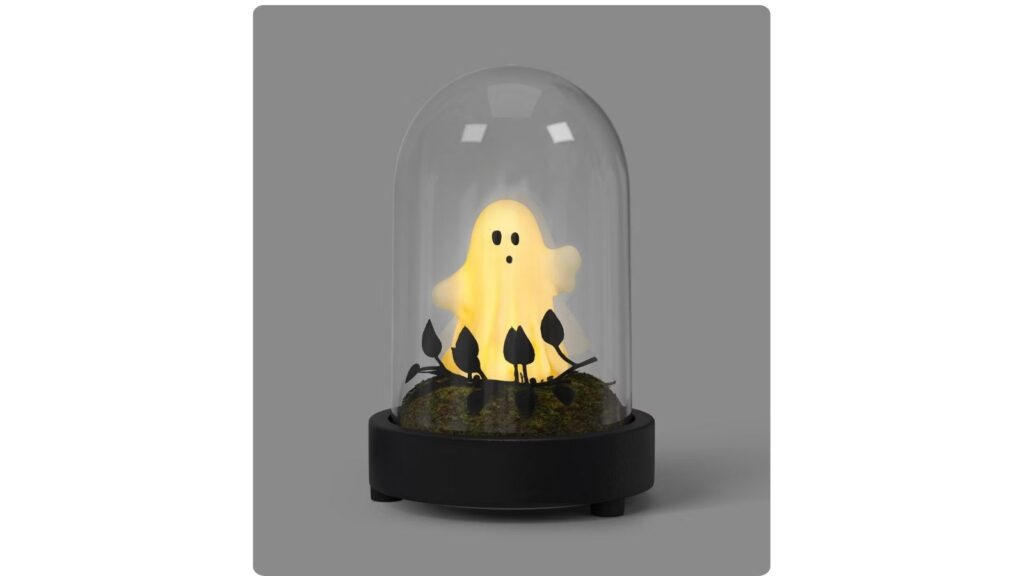
The little ghost under a clear dome costs $5 and lights up, so it gives you both a tabletop accent and a bit of ambient light for the price of one small decoration.

This is the sort of Halloween piece that works best when you need to fill one awkward spot, such as an entry table, office shelf, or kitchen counter corner. Buying one is inexpensive. Buying eight different $5 shelf decorations is suddenly a $40 decision, so this is a case where a single light-up piece can carry more of the room.

Pumpkin felt wreath

felt wreath
Image Credit: Target

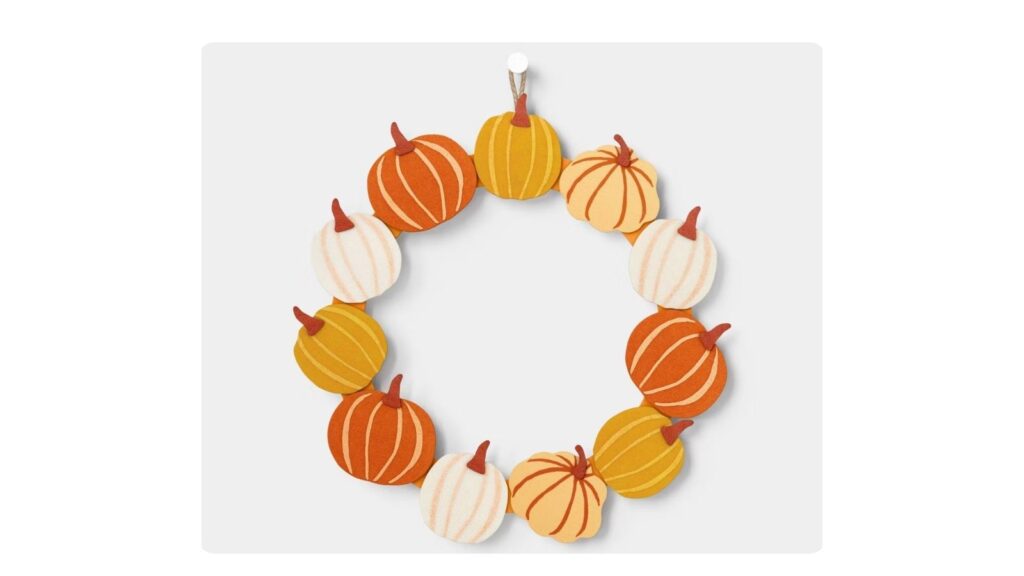
Front-door decor rarely lands at five dollars, which makes Target’s pumpkin felt wreath worth a look at $5. Felt also keeps it lightweight, so you do not need heavy-duty hardware just to hang it.

This is a particularly good fit for renters who want something festive without putting large stakes, inflatables, or other outdoor decorations around the property. Hang it, take it down after the season, and store it flat. That is a lot easier to deal with than bulky porch decor when closet space is already spoken for.

Mini filler pumpkins

mini pumpkins
Image Credit: Target

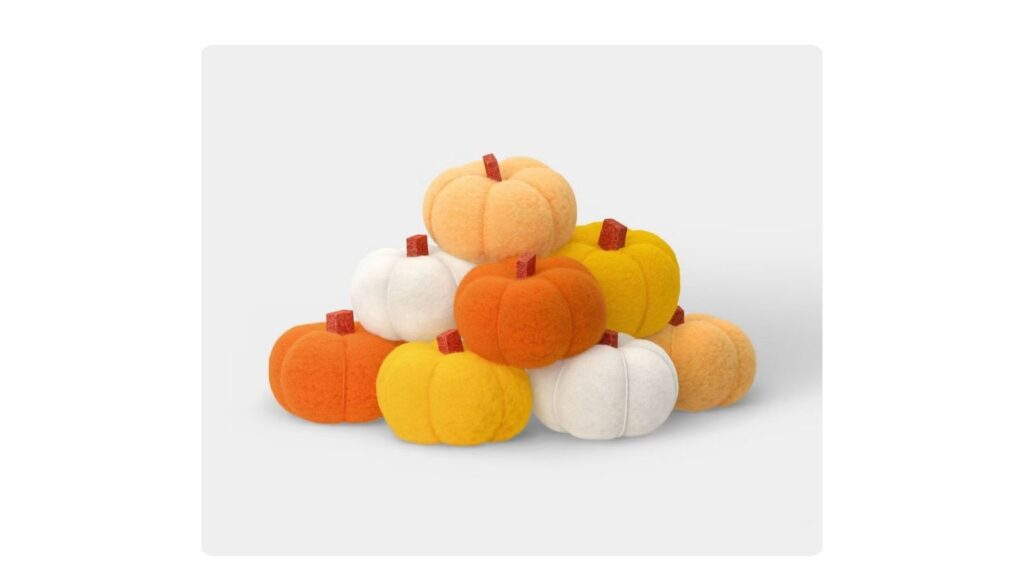
This eight-count bag of small decorative pumpkins costs $5, putting each pumpkin at well under a dollar.

The value here is flexibility. Spread them through an existing bowl, use them along a mantel, mix them with pinecones or leaves you already own, or add them to a table centerpiece. You are not locked into one decorative object or one room. They also store in a small bag when the season is over, an underrated advantage if you do not have a basement full of holiday bins.

Eerie hanging fabric

eerie fabric
Image Credit: Target

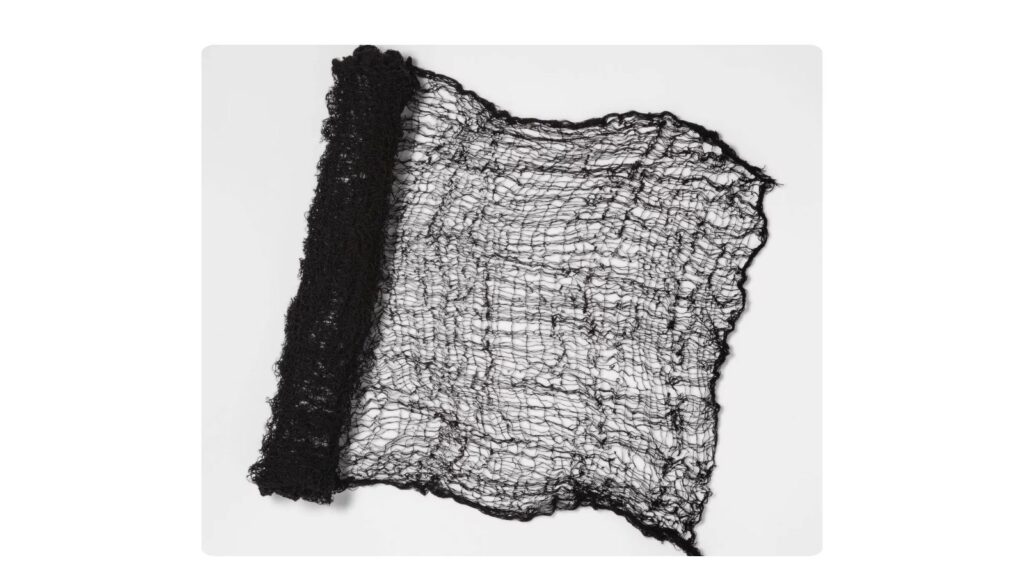
At nine feet long, this black Halloween fabric covers a surprising amount of space for $5. Drape it over a doorway, railing, porch furniture, shelves, or a party table to create a larger backdrop without buying multiple props.

This is one of the easiest ways to make a limited decorating budget look less limited. Large surfaces are what make a room or porch feel decorated, and fabric handles that job cheaply. Fold it up afterward and it takes almost no storage space compared with molded plastic decor.

Hanging witch hat decorating kit

witches hat decorating kit
Image Credit: Target

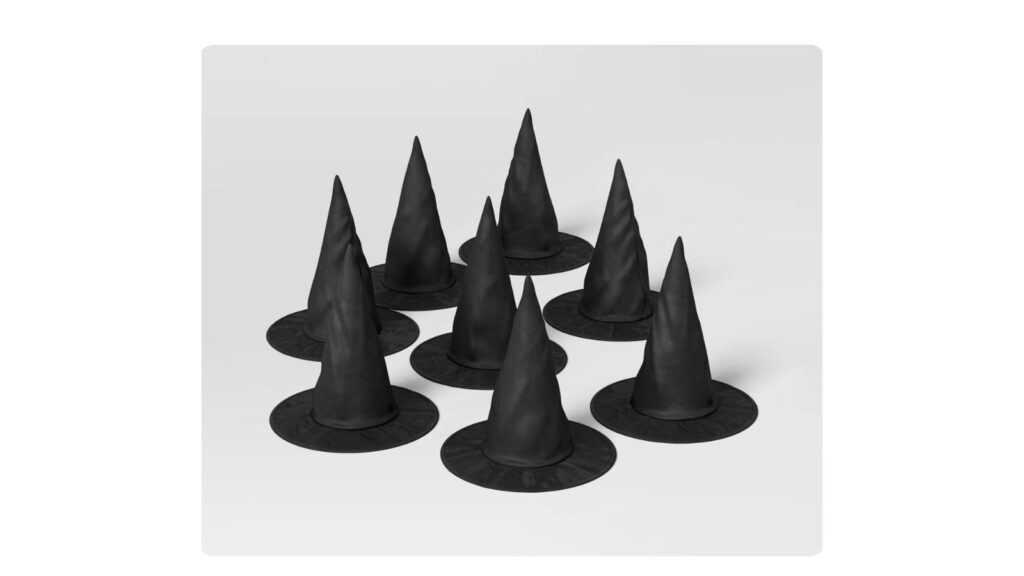
Target has dropped the eight-piece black witch hat decor kit to $10, down from its previous $12 price. That works out to $1.25 per hat for a set that can fill a ceiling, entryway, or party area.

Hanging decorations are useful because they make use of empty overhead space instead of adding more clutter to tables and counters. An eight-piece set also gives you enough repetition to make the effect intentional without buying several packages. For a party, that is a lot of coverage from one $10 box.

LED tea lights with timers

LED tea lights
Image Credit: Target

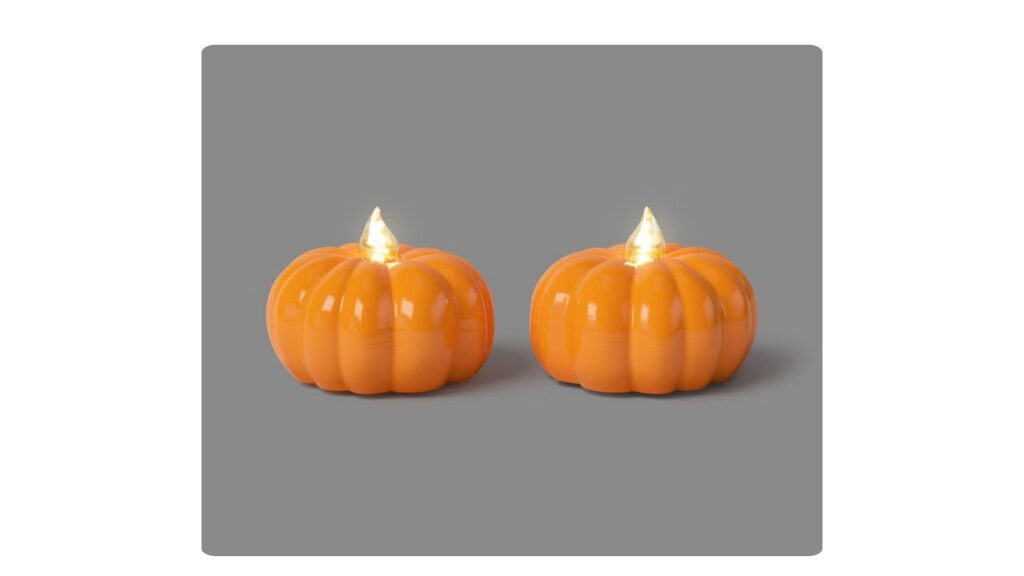
Open flames and Halloween decorations are not always a convenient combination, so Target’s two-pack of LED tea lights is useful at $5. The built-in timer means you can place them inside lanterns or decorations without switching them on and off every night.

They are especially handy if you already own candleholders, carved faux pumpkins, or jars that need light. Reusing those pieces with battery lights is cheaper than replacing them with new illuminated decor. Two lights for $5 is not flashy, but it is a practical seasonal buy.

Halloween LED string lights

halloween string lights
Image Credit: Target

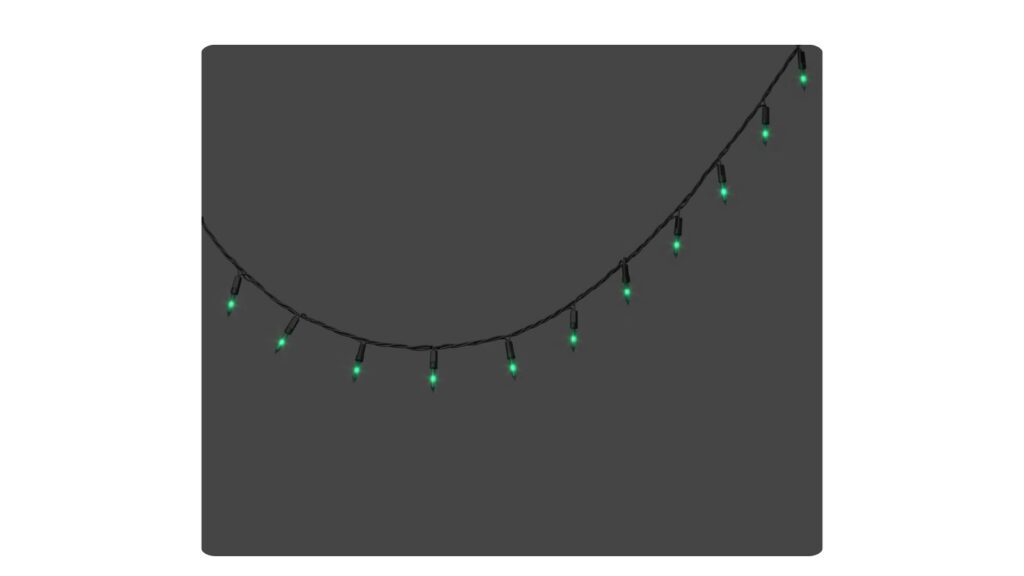
Target’s 100-count Halloween LED string lights are $7, with several Halloween color combinations available under the same listing.

A hundred lights for seven bucks gives you enough length to tackle a porch rail, window, doorway, or section of a room without buying several short novelty strands. They are also rated for indoor or outdoor use, which gives you more options from year to year. If your decorating budget is tight, lights are one of the easiest ways to cover a large area with one purchase.

Outdoor tombstone set

tombstone set
Image Credit: Target

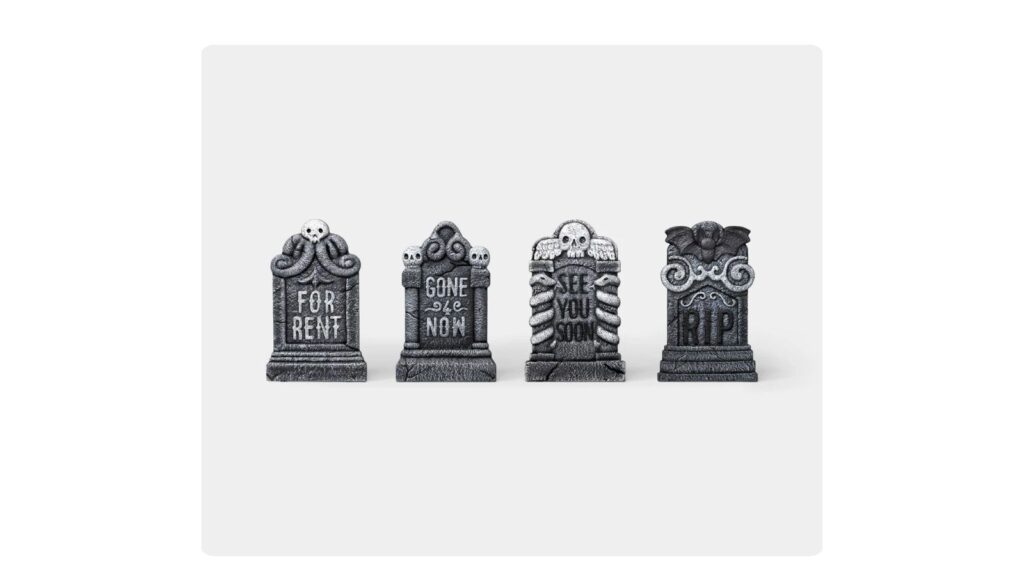
This four-pack of black-and-white tombstones costs $15. Instead of paying for cemetery pieces individually, you get enough in one box to create an actual grouping.

That matters with yard decor because one lonely tombstone tends to look exactly like one lonely tombstone. Four pieces can fill a garden bed, front lawn, or porch area without pushing the project into a much higher price bracket. Store them together afterward so the whole setup is ready to come back out next October.

Small skeleton set

skeleton set
Image Credit: Target

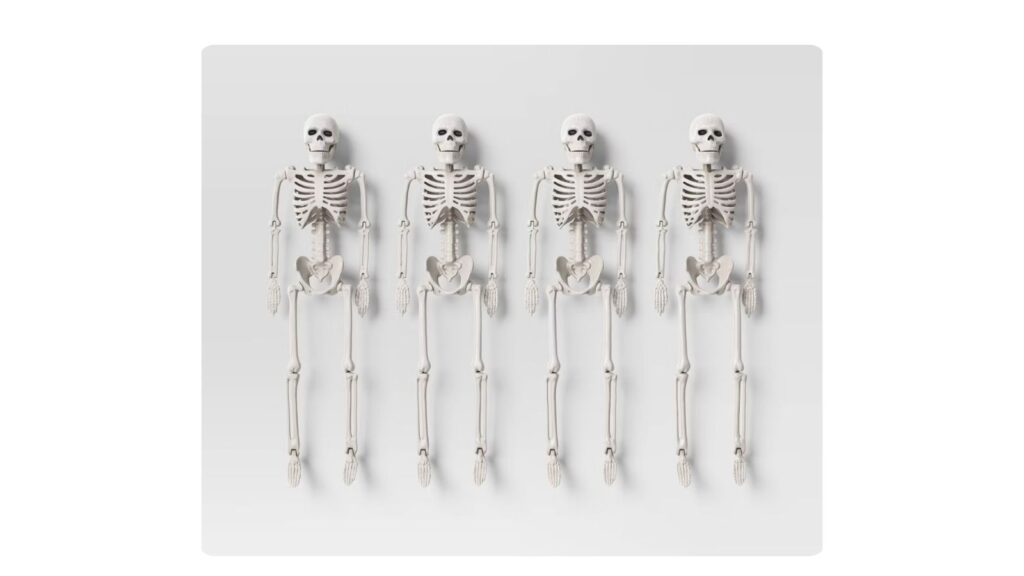
Four poseable skeleton decorations come together for $10. At about $2.50 each, the set gives you more flexibility than spending the same amount on one medium-size tabletop prop.

Use them together on a porch or separate them around the house. Because they are roughly 13 inches tall, they can sit on shelves, hang from displays, or become part of a larger graveyard setup without demanding much storage space afterward. This is one of the better options if you like rearranging your Halloween setup instead of recreating the exact same display every year.

Life-size poseable skeleton

poseable skeleton
Image Credit: Target

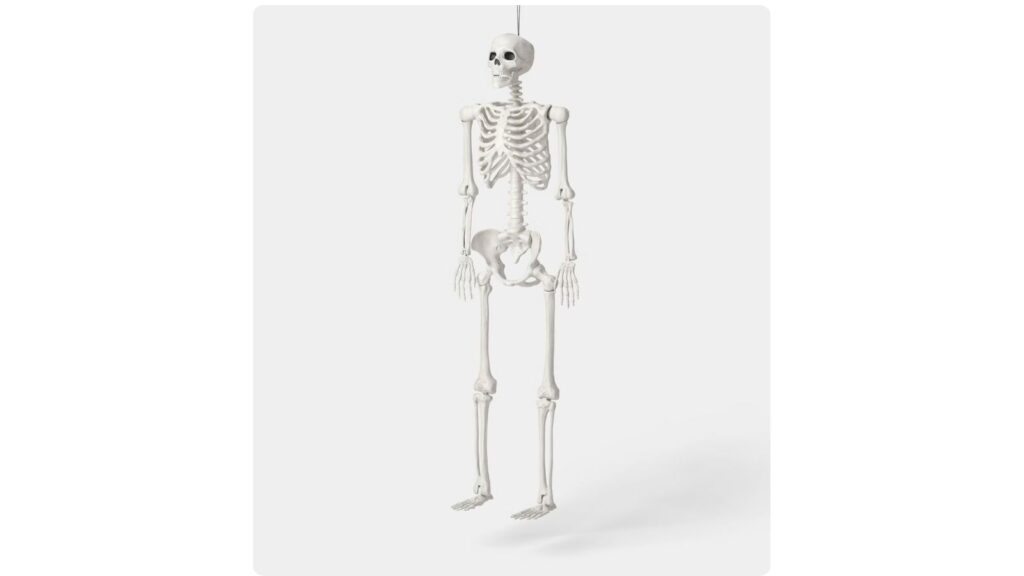
A five-foot poseable skeleton for $25 is one of the stronger values in Target’s larger Halloween decor. It can be used indoors or outside, and the adjustable joints let you change the setup instead of being stuck with one fixed pose.

Twenty-five dollars is more than the tabletop finds, but this is also big enough to serve as the main decoration rather than an accessory. Put it on a porch chair, by the front door, or at a party table and you can skip buying several smaller props to fill the same visual space.

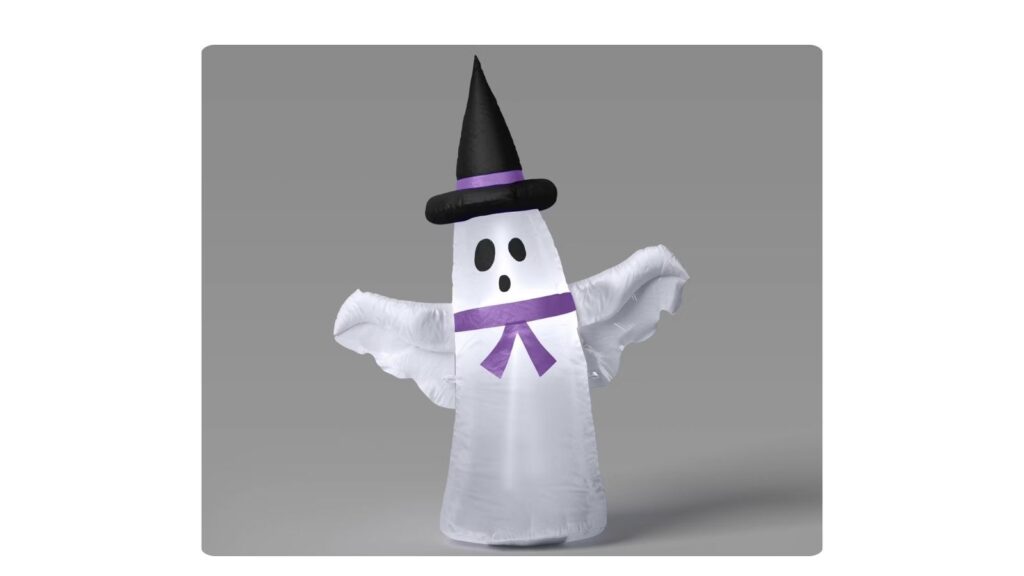
Standing ghost inflatable

inflatable ghost
Image Credit: Target

Outdoor inflatables often take a bigger bite out of the Halloween budget, but Target’s four-foot standing ghost is $20. It gives you a full-size yard or porch decoration without moving into the prices attached to giant displays.

An inflatable also solves the storage problem better than many rigid outdoor props because it collapses once the season ends. This one makes the most sense if you want a single noticeable outdoor piece and do not want to spend the rest of October building an entire yard scene around it.

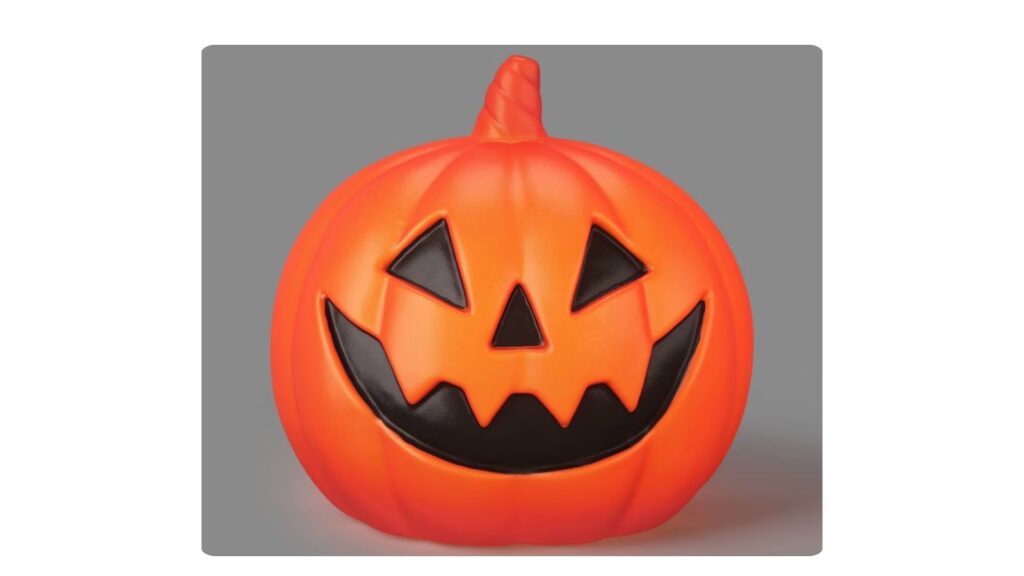
Lit pumpkin blow mold

lit pumpkin blow mold
Image Credit: Target

This eight-inch orange pumpkin blow mold lights up and costs just $5. That price is low enough to use it as a small porch, window, or tabletop light without treating it as a major seasonal purchase.

The classic pumpkin shape also gives it more staying power than a trend-specific decoration. Bring it back every October, or use it alongside real pumpkins without worrying about it rotting before Halloween arrives. For five dollars, the fact that it actually lights up gives it more presence than a similarly priced static figurine.

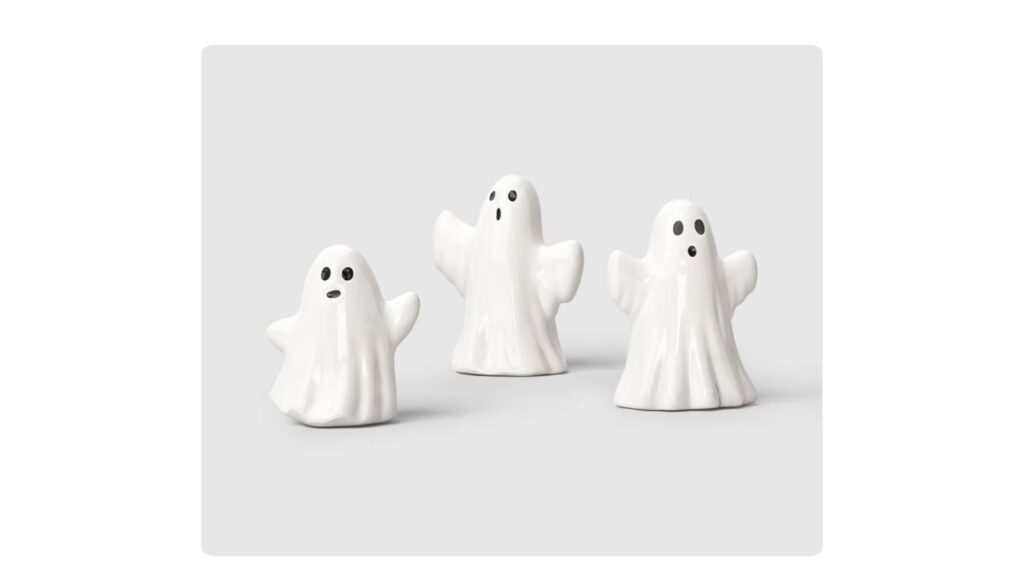
Ceramic ghost trio

ceramic ghosts
Image Credit: Target

Target’s set of three shiny ceramic ghosts is $5. That works out to about $1.67 per piece, and because they come as a coordinated set, you do not need to keep buying small accents just to make a shelf look finished.

Use the three together or split them between a mantel, bookshelf, and entry table. Ceramic also feels more substantial than disposable party decor at the same price. This is still a decorative purchase, not a necessity, but it is a reasonable one if you want several small pieces without spending $5 on each.

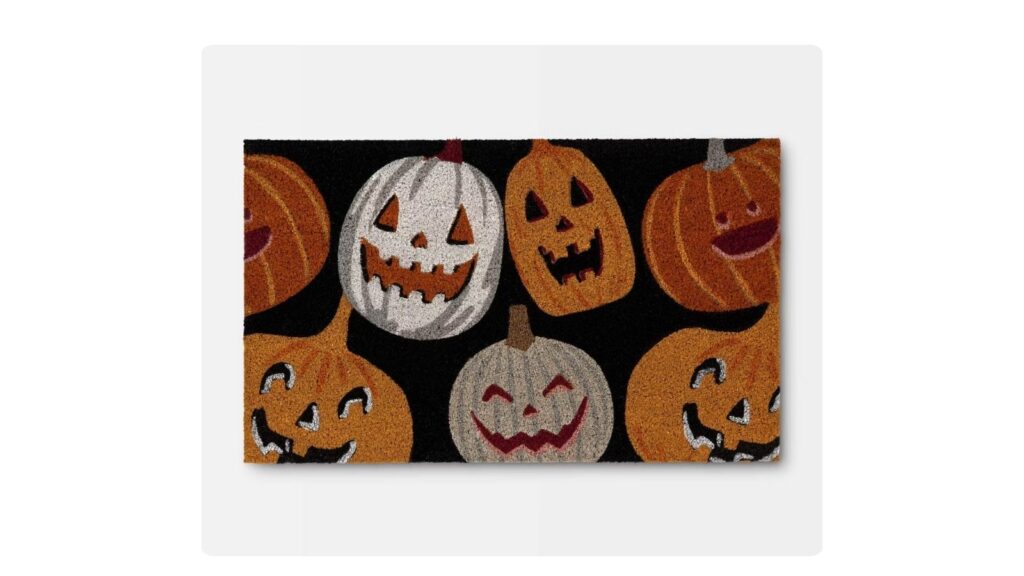
Jack-o’-lantern coir doormat

jack o lantern door mat
Image Credit: Target

The orange jack-o’-lantern coir mat is $13 and measures 18 by 30 inches, a standard size for most front doors.

A doormat is one of the easier seasonal purchases to justify because it replaces something you may already keep at the door instead of adding another object to the porch. The coir surface also means it still has a practical job when shoes are wet or dirty. If you only want one piece of outdoor Halloween decor, something visitors actually walk past and use makes more sense than several small lawn ornaments.

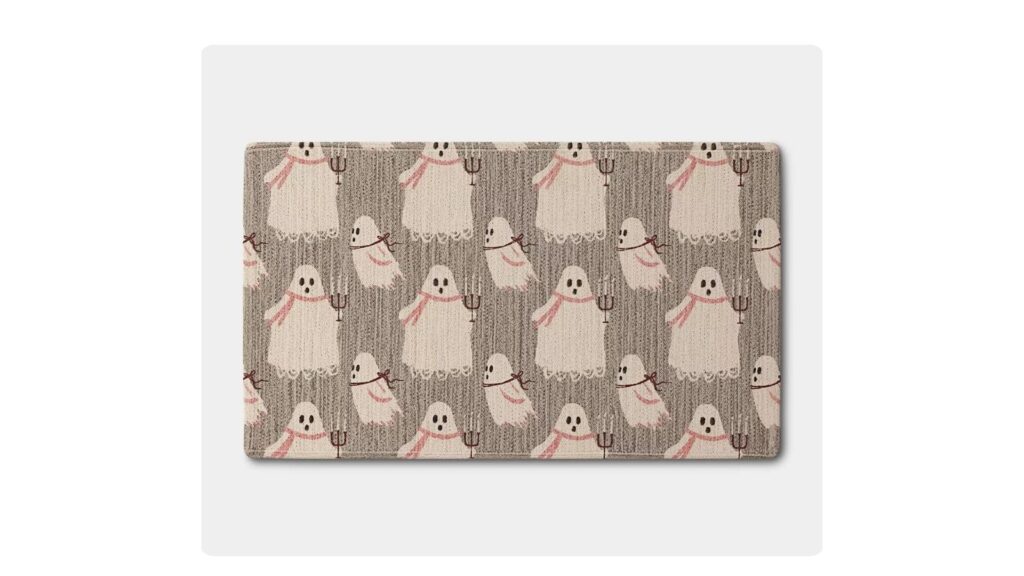
Reversible ghost floor mat

ghost floor mat
Image Credit: Target

This ghost-themed Bone Parlour floor mat is $13 and measures about 20 by 34 inches. The reversible design gives you more than one look from the same purchase.

Use it inside an entryway, kitchen, or other small area where a full-size seasonal rug would be too much. Because it is a functional floor covering rather than a display piece, it can stay out all October without using shelf or counter space. Reversibility also helps if you get bored with one side halfway through the month.

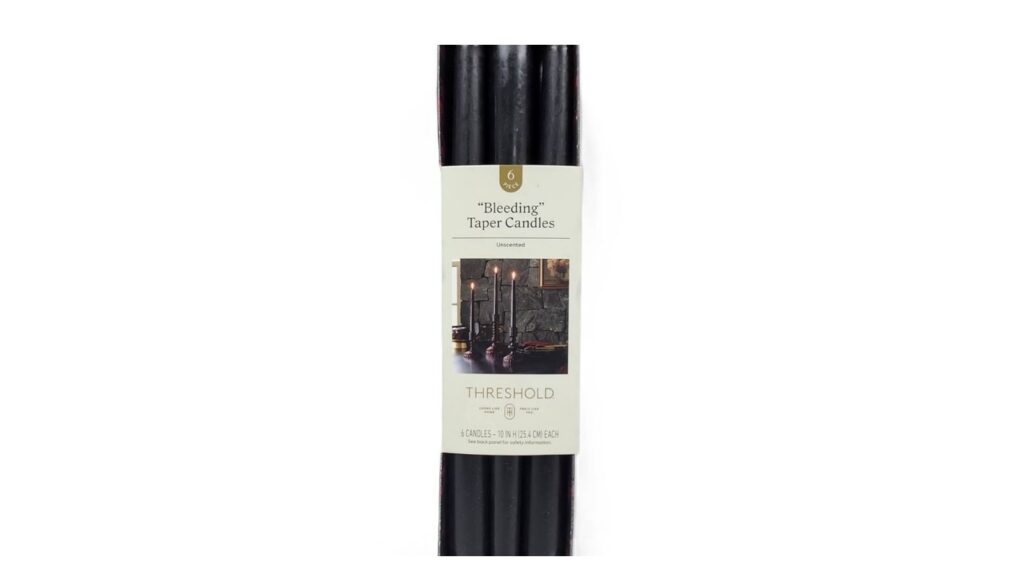
Bleeding taper candle set

Bleeding taper candles
Image Credit: Target

Threshold’s set of six black Halloween taper candles costs $10. That is about $1.67 per candle, so one package can fill several candleholders or cover a longer dining table.

This is best for someone who already owns taper holders. If you have to buy six holders too, the bargain disappears quickly. With holders already in the cupboard, though, changing the candles is an inexpensive way to turn everyday dining-room pieces into Halloween decor without storing another large seasonal centerpiece.

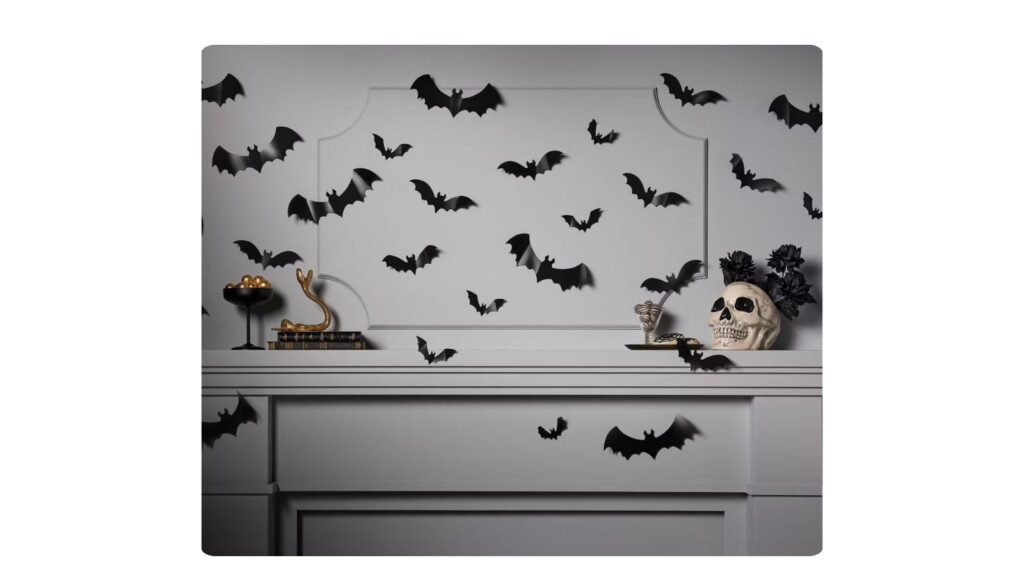
Bat wall decorating kit

Bat Wall Decorating Kit
Image Credit: Target

The bat wall decor kit includes 30 pieces for $10. Thirty bats gives you enough pieces to create a noticeable sweep across a wall, doorway, staircase, or party backdrop instead of scattering a few tiny decals around the room.

Wall decor is also useful when floor and surface space are limited. You can make a blank wall do the decorating without buying another table, shelf, or storage bin to hold the finished setup. At roughly 33 cents per bat, this is one of the cheaper ways to fill a large visual area with one package.

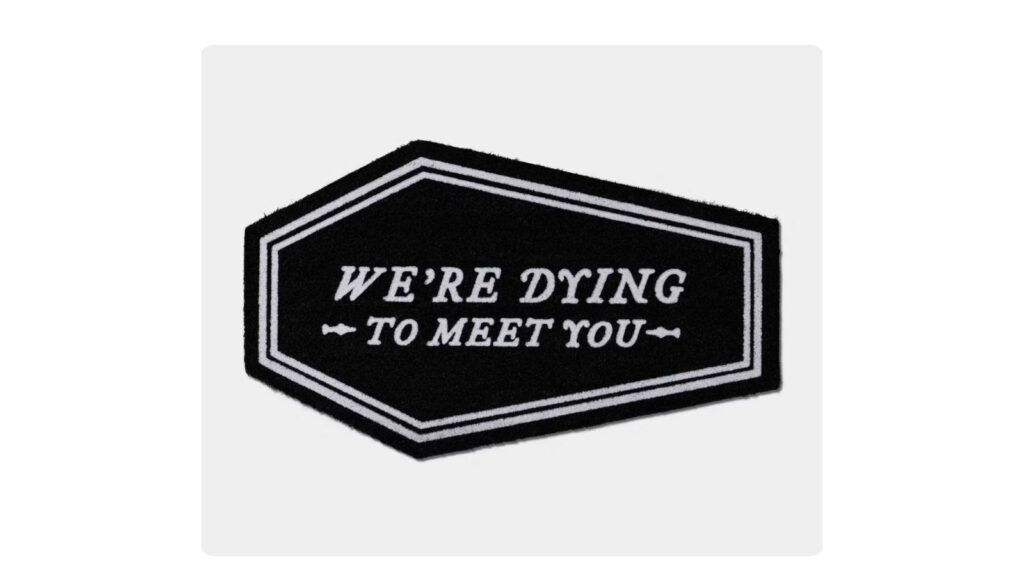
Musical coffin doormat

Musical coffin doormat
Image Credit: Target

If you want the front door to do more of the Halloween work, Target’s coffin-shaped musical doormat is $20. It measures about 18 by 30 inches and adds a sound effect rather than relying only on a printed design.

Twenty dollars is not the cheapest mat in the collection, but the added feature means it can replace both a regular seasonal doormat and a separate sound-making porch prop. That makes it a better value for someone building a small front-door display than buying several pieces that each do only one thing.

Finding jewelry items that transition seamlessly between morning meetings and evening dinners saves valuable preparation time. Modern personal style relies on flexible pieces that adapt to formal settings and casual weekends without requiring a complete wardrobe overhaul.

Building a versatile jewelry box means choosing items with clean lines, balanced proportions, and timeless appeal. Selecting items with lasting value allows anyone to feel polished at every event on their daily schedule.

Classic stud earrings for daily sophistication

Stud earrings remain a cornerstone of versatile styling for good reason. They lie flat against the earlobe and never catch on clothing or hair during busy workdays. A simple pair adds a subtle sparkle that brightens the face instantly.

Styling a pair of studs requires zero effort when switching from casual attire to evening wear. Investing in high-quality luxury diamond accessories provides a refined accent that complements crisp blazer jackets and flowing cocktail dresses. The clean silhouette maintains an understated elegance suitable for professional boardrooms or weekend brunches.

Solitaire designs featuring round or cushion cuts offer maximum brilliance in a compact form. Setting the stones in white gold or platinum gives them a cool modern tone. Wearing them daily establishes an effortless signature look.

Minimalist pendant necklaces that layer effortlessly

A delicate chain with a single pendant serves as an ideal bridge between casual and formal attire. Sitting right at the collarbone, it fills open necklines without overpowering an outfit. The minimalist design allows it to shimmer quietly under office lights.

An industry report highlights that simple chains, stud earrings, layered necklaces, and delicate bracelets create a timeless look suitable for any event. Styling a thin chain alone creates a crisp professional aesthetic for corporate meetings. 

Choosing lightweight metals guarantees comfort during extended periods of wear. Small geometric charms or tiny drop stones add personal personality without clashing against patterns. Flexibility makes a slender pendant necklace a daily staple.

Elegant tennis bracelets from morning to night

In line with flexible fashion choices, tennis bracelets offer a continuous row of light that moves naturally with the wrist. The fluid construction allows the piece to drape comfortably during long office hours.

A guide on jewelry collections observed that building a great collection centers on picking well-made items that hold value and fit actual daily life. High-quality craftsmanship keeps the settings secure through daily activities. 

Combining a slender tennis bracelet alongside a structured wristwatch creates a sophisticated contrast for professional environments. Removing the watch later leaves the bracelet to shine solo as an evening statement. That easy adaptability cements its status as a timeless favorite.

Bold gemstone accents in gold settings

Incorporating rich color into fine jewelry brings fresh energy to standard corporate and evening wardrobes. Deep emerald greens and rich sapphire blues stand out against neutral fabric colors like beige or navy. 

Fashion analysis for this year notes that rich greens, deep blues, and deep purples lead gemstone trends, particularly set in yellow gold. Warm gold settings emphasize the natural saturation of colorful center stones. 

Wearing a single gemstone ring creates a focal point that does not clutter your complete look. Pairing colorful stones with neutral outfits keeps the focus on artistic craftsmanship. The warmth of gold frames each gem with rich contrast.

Mixing metals for contemporary versatility

Combining silver tones with warm gold removes strict rules about matching accessories to handbag hardware or zipper details. A style commentary pointed out that blending gold and silver creates an interplay of warmth and color suited to match any mood. 

Blending metals works best when guided by clear design choices across your entire collection:

  • Stack two slim bands of contrasting metals on one finger.
  • Pair a white gold necklace with yellow gold hoop earrings.
  • Wear a multi-tone watch that features silver and gold links.

Balanced distribution prevents mixed metals from appearing accidental.

Two-tone pieces serve as anchors that unify other items in your collection. Selecting items with clean geometric shapes allows different metal tones to complement each other smoothly. 

Sustainable diamond choices for modern wardrobes

Modern shoppers increasingly seek out fine jewelry items that align with personal values without compromising on luxury appeal. Lab-created diamonds deliver identical optical brilliance and durability compared to traditional mined gems. 

An industry report observed that zero-emission lab-grown diamonds are increasingly sought after as shoppers opt out of traditional mined stone options. Choosing responsibly created gems adds extra satisfaction when wearing fine jewelry daily. 

Elongated diamond shapes like oval or emerald cuts offer a striking silhouette on studs and rings. Refined cuts catch light beautifully in natural sun and indoor settings. They provide lasting elegance across every occasion on your calendar.

Image Credit: RDNE Stock Project via Pexels

Selecting versatile jewelry items allows anyone to curate a functional collection that transitions smoothly from morning routines to night events. Concentrating on high-quality craftsmanship and balanced designs guarantees every item serves multiple wardrobe roles.

Simple studs, delicate pendants, and mixed-metal accents offer endless styling combinations. Investing in pieces that suit daily life brings confidence and timeless style to every outfit choice.

Starting a new venture demands grit, clarity, and deliberate strategic execution. Female business owners face unique financial decisions when transforming initial concepts into sustainable enterprises. Navigating early challenges successfully sets the baseline for long term growth.

Building commercial momentum requires far more than passion and extended working hours. Smart planning helps founders protect personal capital while establishing scalable systems. Developing some foundational habits creates lasting stability for future market expansion.

Learn what independent women should know about building a company, from planning and finances to leadership and sustainable growth
Image Credit: Pavel Danilyuk via Pexels

Setting up proper corporate structures early prevents severe legal complications as the firm grows. Business owners must separate personal wealth from company capital using dedicated bank accounts and registered legal entities. Maintaining clear boundaries protects personal assets from enterprise liabilities.

Choosing a qualified corporate service provider helps safeguard new ventures right from day one. Many founders partner with teams like Rosemont Partners to structure corporate governance properly and satisfy local regulatory standards. Having expert guidance early keeps daily operations fully compliant without consuming valuable leadership time.

Clean accounting records simplify tax filings and lower friction during future fundraising efforts. Maintaining detailed financial ledgers builds instant trust with external investors and commercial lenders. Organized financial bookkeeping provides clear visibility into daily cash flows.

Capitalizing on modern market shifts

Female entrepreneurship continues to reach record levels across multiple primary commercial industries. A business formation report revealed that 49 percent of startups launched were headed by female founders, representing a 69 percent increase over 5 years. The shift highlights growing autonomy in global commerce.

Capital requirements vary greatly depending on the chosen commercial business model. Independent owners often bootstrap initial validation phases prior to seeking external venture capital or private debt. Self-funding initial milestones allows leaders to retain greater equity.

Preserving equity during initial growth stages retains total control over company direction and corporate strategy. Leaders who retain major ownership rights maintain strong decision-making power during key growth phases. Protecting equity positions secures future financial independence.

Streamlining daily operations through workflows

Modern companies rely heavily on smart digital tools to handle routine administrative duties. Implementing solid software solutions reduces repetitive manual labor and allows small teams to deliver big outcomes. Standardizing operations creates room for high-level strategic thinking.

Streamlining internal operational workflows enables leaders to devote energy directly to revenue growth.

  • Automated customer relationship software
  • Cloud platform accounting and invoicing systems
  • Digital project management dashboards
  • Integrated scheduling applications

Documenting routine operational tasks helps companies scale without expanding payroll budgets too quickly. Written operating procedures deliver consistent quality across all client services. Standardized procedures make onboarding new employees seamless and efficient.

Adopting cutting-edge business technology

Adopting modern tools helps lean enterprises compete effectively against large established market players. A study on small business technology found 91 percent of respondents achieved greater commercial success after integrating artificial intelligence, with 28 percent saving at least $5,000 annually. Early tech adoption generates measurable financial advantages.

Automated platforms handle routine customer service inquiries and standard database updates smoothly. Removing repetitive administrative tasks grants operational teams extra time to focus on product quality. Directing human talent toward complex problem-solving yields superior results.

Technology investments must align directly with measurable performance goals and revenue targets. Software expenditures ought to boost daily productivity or expand client retention rates directly. Regular software audits keep operational costs minimal.

Building resilience and decision autonomy

Navigating unexpected market shifts demands rapid decision-making and strong executive confidence. Independent enterprise owners who evaluate market data quickly recover faster from economic shifts. Decisive leadership keeps team members focused during industry transitions.

Establishing clear operational boundaries protects personal energy and prevents executive exhaustion. Strategic founders prioritize high-impact sales channels instead of trying to manage every minor administrative problem directly. Delegating operational tasks strengthens organizational resilience.

Forming a trusted advisory council provides objective feedback during critical expansion milestones. Industry mentors offer fresh perspectives without interfering with daily managerial decisions. Outside guidance helps leaders evaluate calculated risks accurately.

Scaling revenue streams efficiently

Sustainable commercial growth relies on recurring payment models and high client retention. Building subscription packages or predictable retainer models generates steady cash flow during market fluctuations. Stable revenue streams reduce financial stress during quiet months.

Diversifying products or service offerings protects companies from overreliance on single client contracts. Multiple revenue streams build financial safety margins during broader economic slowdowns. Product diversification unlocks new customer segments naturally.

Reinvesting initial profits into core sales operations speeds up long-term market penetration. Smart capital reinvestment expands brand awareness while outlasting competitors who pause marketing campaigns prematurely. Strategic funding placement accelerates enterprise growth.

Image Credit: Gustavo Fring

Building an independent company requires clear planning, modern tools, and decisive execution. Founders who establish strong legal structures and embrace efficient tools position their firms for long term market leadership.

Taking full ownership of financial and operational decisions delivers true personal independence. With consistent execution and strategic support, turning early business concepts into thriving enterprises becomes fully achievable.

You log into your my Social Security account expecting a benefit estimate, and instead you get a flat statement: not enough credits to qualify. Or a parent, an aunt, an old coworker mentions they worked in the US for years and still can’t draw a dime of their own retirement money. The number that trips people up is 40. That’s how many Social Security credits it takes to collect retirement benefits on your own earnings record, and in 2026 each one costs $1,890 of taxed earnings, with a hard cap of four credits a year no matter how much you make.

This catches people in a lot of different situations. Immigrants who arrived in the US partway through their working life. People who spent years self employed or paid in cash. Parents who stepped out of the workforce for a decade and came back later than they planned. Workers who moved between short contracts, gig work, and jobs that never quite added up to a full year of covered wages.

Falling short of 40 credits doesn’t mean the years of paycheck deductions were for nothing. It usually means the benefit isn’t sitting behind the door you tried first, and there are more doors than most people are told about.

How the 40 credit rule actually works

social security
Image Credit: Shutterstock

A Social Security credit, sometimes called a quarter of coverage, is earned through taxed income rather than time on the clock. In 2026, $1,890 in wages or self employment income subject to Social Security tax earns one credit, and earning $7,560 or more in a year earns the maximum four. Nobody needs more than 40 credits for any Social Security benefit, retirement included, no matter how much they earned above that threshold.

Credits only answer one question: are you insured. They don’t set your monthly benefit amount. That figure comes from your 35 highest earning years, adjusted for inflation, so a worker with exactly 40 credits and a worker with 80 can end up with very different checks even though both cleared the eligibility bar. It helps to separate those two ideas early, because plenty of people assume more credits automatically means more money, and that isn’t how the formula works.

You can often earn what’s missing

older person working
Image Credit: Shutterstock

Credits don’t expire. Once you’ve earned one, it stays on your earnings record permanently, whether you stop working entirely, move overseas, or switch into a job that isn’t covered by Social Security. A worker who quit two credits shy of 40 isn’t starting over. A single stretch of part time covered work, even a partial year, can close that out.

Credits accumulate on total earnings for the year, not months worked. Someone who takes a part time job partway through the year and earns $5,670 by December would bank three credits, not four, because the total falls short of the $7,560 needed for all four. That’s still real progress if the record was sitting at 37 going in.

Before deciding whether more work is worth it, pull up your actual numbers. A my Social Security account shows your exact credit count and a year by year earnings history, and it’s also the fastest way to catch a missing or misreported year of wages. Those errors are more common than people expect, especially from small employers or short term jobs, and a correction can hand you a credit you already earned without a single extra day of work.

Check whether you can claim on someone else’s record

Social Security doesn’t only pay people with 40 credits of their own. A current spouse can claim on a working spouse’s record once married at least a year in most cases, and that spousal benefit can run as much as half of what the spouse gets at their own full retirement age, even if the person claiming never worked a single covered day.

Divorce doesn’t automatically cut off that option either. Someone who was married for at least 10 years and is currently unmarried can generally claim on a former spouse’s record once that spouse is old enough to qualify, and it costs the ex nothing: it doesn’t reduce their benefit or affect what a current spouse receives.

Widows and widowers have a separate path in. A surviving spouse can start survivor benefits as early as 60, or 50 if disabled, and a surviving divorced spouse qualifies the same way if the marriage lasted 10 years and they haven’t remarried before turning 60. None of these routes require the surviving or divorced spouse to have earned 40 credits themselves.

Disability and survivor rules use a shorter ladder

couple organising social security
Image Credit: Shutterstock

The 40 credit rule is specific to retirement benefits claimed on your own record. Disability works differently, and the younger you are, the less it takes. Someone disabled before age 24 generally needs just 6 credits earned in the 3 years before the disability began, and the required total rises gradually with age until it reaches 40 for people disabled at 62 or later. A worker in their 30s who assumes they haven’t paid in long enough to qualify for disability is often wrong.

Survivors get a similar break. If a worker dies before reaching 40 credits, a special rule lets their young children and the spouse caring for those children collect survivor benefits anyway, sometimes on as few as 6 recent credits. It’s one of the more overlooked corners of the system, mostly because it only comes up after a death, when few people are in a position to go looking for it.

Credits earned overseas can sometimes fill in what’s missing

Work performed abroad doesn’t automatically vanish from the calculation. The US has totalization agreements with close to 30 countries, including Canada, the United Kingdom, Germany, Japan, and Australia, designed to stop the same earnings from being taxed twice and to help workers who split a career between countries actually qualify for something.

The catch is that you need at least six quarters of US coverage before foreign coverage can be added to the total. Foreign credits don’t convert into US credits directly. Instead, SSA combines the two coverage periods only to establish that you’re insured, then pays a partial US benefit based on the share of your career actually completed in the US. A worker with 24 US credits and a decade of coverage in an agreement country might clear 40 combined and unlock a partial US benefit that wouldn’t have existed otherwise. It can also work out to two separate checks, since neither country hands its credits over to the other. Each side just uses the combined total to decide whether you’re covered, then pays its own share based on what you actually earned there.

The taxes you already paid don’t disappear, but they don’t come back as a refund either

filling in tax return on a computer
Image Credit: Shutterstock

Social Security isn’t a personal savings account with your name on it. It’s pay-as-you-go insurance, and today’s payroll taxes fund today’s beneficiaries. Coming up short of 40 credits doesn’t trigger a refund of the FICA or SECA taxes already withheld, no matter how close you got.

For people who can’t clear any of the paths above, there’s still Supplemental Security Income, a separate program that has nothing to do with work credits. SSI is based on financial need rather than earnings history, and in 2026 it pays up to $994 a month for an individual and $1,491 for a couple, with its own limits on income and resources, including a resource cap of $2,000 for a single applicant and $3,000 for a couple. It’s a lower payment than most people would get from a full Social Security record, but it’s not nothing, and it’s worth ruling in or out before assuming a shortfall leaves you with zero options.

What to actually do next

Start with your own numbers. Log into your my Social Security account and look at the full earnings history, not just the credit total, since a single mislabeled year can throw the count off in either direction. If you’re close, weigh whether another year or two of covered work, even part time, makes sense before you claim anything.

Then ask directly about the paths that don’t show up automatically online. Spousal, survivor, and totalization eligibility are rarely volunteered during a routine application, and a phone call or an in person appointment with SSA is still the most reliable way to find out whether one of them applies to your situation before you assume the answer is no. Bring your marriage and divorce paperwork, and any record of work performed outside the US, so the conversation doesn’t stall on missing documents.

Forty credits is the number everyone hears first, but it’s rarely the number that decides the outcome. A closer look at your earnings record, your marital history, or even a few years spent working abroad can turn a flat denial into an actual monthly check.