scroll top

Losing a spouse is hard enough without having to decode Social Security on top of it. For many widows and widowers, that survivor check is a big part of keeping the lights on and the mortgage paid.

As of early 2026, the average monthly Social Security benefit for a nondisabled widow or widower is about $1,925, so getting the rules right really matters. That’s money you could be counting on for the rest of your life.

The rules aren’t meant to trick you, but they are complicated. Your age, your late spouse’s age, remarriage, work, and even your kids can all change what you get and when.

If you understand a few key rules about survivor benefits, switching to your own retirement benefit, remarriage, and how age changes the math, you’ll be in a much better position to protect your income.

Understand what survivor benefits are

older person alone worried at the computer
Image Credit: Shutterstock

Survivor benefits are monthly payments based on your late spouse’s work record. If your spouse earned enough Social Security credits and paid Social Security tax, their record may now pay benefits to you, your children, and sometimes a dependent parent.

As a widow or widower, you can usually receive survivor benefits starting at age 60. If you are disabled, you may qualify as early as age 50. If you are caring for your late spouse’s child who is under 16 or has a qualifying disability, you may qualify at any age. Divorced surviving spouses can also qualify if the marriage lasted at least 10 years and other rules are met.

Survivor benefits are separate from your own retirement benefit. They are based on your spouse’s earnings history, not yours. You might eventually have three different numbers to compare: your survivor benefit, your own retirement benefit, and possibly a divorced survivor benefit on an ex-spouse’s record. That’s why it’s so important to ask Social Security to show you all the options you qualify for.

Know how your age when you claim changes your survivor check

man on phone claiming survivor benefits
Image Credit: Shutterstock

The age you first take survivor benefits can permanently change your check amount. In most cases, you can claim as early as age 60. But if you do, you usually get about 71.5% of what your late spouse would have received at their full retirement age. The percentage rises as you wait and can reach up to 100% if you wait until your survivor full retirement age (between 66 and 67, depending on your birth year).

This reduction is for life on that survivor benefit. If you start at 60 and lock in the 71.5% rate, every future cost-of-living increase is calculated on that smaller base. There is no extra growth for waiting after your survivor full retirement age; survivor benefits do not earn delayed retirement credits like your own retirement benefit does.

That does not mean taking benefits early is always wrong. If you truly need the money at 60, a reduced survivor benefit can still be a lifeline. The key is to understand the trade-off before you file. Ask Social Security for survivor benefit estimates at different starting ages and compare what it means for your income at 60, 70, and beyond.

Your spouse’s claiming age also affects what you get

sad older woman looking at a photo
Image Credit: Shutterstock

Your survivor benefit is connected to how and when your spouse claimed, or would have claimed, their own Social Security. If your spouse died before filing, your survivor benefit is based on what they would have received at their full retirement age, plus any delayed retirement credits if they worked and waited past that age. If they claimed early, the base amount for your survivor benefit may be lower.

There is also a “widow(er)’s limit” in the law. In many cases, your survivor benefit cannot be higher than what your spouse was actually getting, and it generally will not be lower than about 82.5% of their basic benefit, though the exact formula depends on both of your claiming ages. You do not have to remember that math, but you should know it exists.

This is why your spouse’s choices matter even if you are not yet retired. When the higher earner in a couple claims early, they are not only locking in their own smaller check, they may also be locking in a smaller future survivor benefit for you. When you talk with Social Security after a spouse dies, ask them to walk you through how they calculated your survivor amount so you can see what’s driving it.

You can’t collect both survivor and retirement benefits at the same time, but you can switch

widow and her children
Image Credit: Shutterstock

One of the most confusing parts of Social Security is how different benefits interact. As a widow or widower, you may be eligible for both a survivor benefit on your spouse’s record and a retirement benefit on your own record. Social Security will not stack these. You generally get whichever is higher, not both added together.

However, widows and widowers are treated differently from most other claimants. The “deemed filing” rule, which forces many people to file for all benefits at once, does not apply to survivor benefits. That means you can start with one type of benefit and switch to the other later if it will be higher. For example, you might take a reduced survivor benefit in your early 60s while letting your own retirement benefit grow with delayed retirement credits up to age 70, and then switch.

Switching is not automatic. You have to contact Social Security and file a new application to move from survivor to retirement, or the other way around. Before you decide, ask for written estimates for both benefits at different ages so you can see clearly which order gives you the most lifetime income.

Working while getting survivor benefits can cut your payments temporarily

working senior American
Image Credit: Shutterstock

If you are under full retirement age and working, the earnings test applies to survivor benefits just like it does to retirement benefits. In 2026, if you are under full retirement age all year, Social Security withholds $1 in benefits for every $2 you earn over $24,480. In the year you reach full retirement age, the limit is higher, $65,160 in 2026, and the withholding changes to $1 for every $3 you earn above that amount, in the months before you reach full retirement age.

Here is the important twist for widows and widowers: for the earnings test, Social Security uses your full retirement age for retirement benefits, not the earlier full retirement age used to calculate survivor benefits. So you might reach 100% of your survivor benefit at your survivor full retirement age, but still be subject to the earnings test until you hit your regular retirement full retirement age.

Money withheld because of the earnings test is not lost forever. Once you reach full retirement age, Social Security recalculates your benefit to give you credit for months when you did not receive checks. The real risk is short-term cash-flow. Before you claim survivor benefits while still working, ask Social Security how much will actually be paid out to you in the next 12 months based on your expected earnings.

Remarriage rules depend heavily on your age

older couple remarrying
Image Credit: Shutterstock

Remarriage does not automatically end your survivor benefits, but the timing matters a lot. In general, if you remarry before age 60, you usually cannot receive survivor benefits based on your late spouse’s record while that marriage is in place. If you are disabled, the cutoff age is 50. If you remarry at 60 or later (50 or later if disabled), you can usually keep survivor benefits on your late spouse’s record.

If you did remarry before 60 and that later marriage ends in death or divorce, you may regain eligibility for survivor benefits on your first spouse’s record. Your newer marriage may also give you rights to spousal or survivor benefits on your current spouse’s record. Social Security will look at every record you are eligible on and pay you whichever benefit is higher, but you will not get multiple full checks at once.

Because the rules are subtle, always tell Social Security about every marriage and divorce when you apply. Failing to report a new marriage or a marriage ending can lead to overpayments that you may be asked to repay later. It is better to over-share your history than to leave out something that could change your benefit.

Divorced widows and widowers have their own survivor rules

divorce
Image Credit: Freepik

If you are divorced and your ex-spouse dies, you may still qualify for survivor benefits on their record. In general, you must have been married to your ex for at least 10 years, be at least 60 (or 50 if disabled), and be unmarried, unless your later marriage occurred at 60 or older (50 or older if disabled).

You do not need your ex’s permission, and your claim does not reduce what anyone else gets. Your ex’s current spouse and children can also receive survivor benefits at the same time, subject to the overall family maximum for that worker’s record. Social Security can pay all eligible survivors as long as the combined total stays within that family cap, usually 150% to 180% of the worker’s basic benefit.

When you apply, be ready with your marriage and divorce dates, your ex-spouse’s Social Security number if you know it, and your own identifying documents. Make sure the person taking your application knows about every marriage that lasted at least 10 years. Many divorced widows and widowers are underpaid simply because no one mentioned a long-ago marriage.

Your children and the family maximum can change what you receive

sad teenager and parent hugging
Image Credit: Shutterstock

If you still have children at home when your spouse dies, they may also qualify for survivor benefits. Unmarried children can usually receive benefits until age 18, or up to 19 if they are still in high school full-time. Children with a qualifying disability that began before age 22 may qualify for survivor benefits longer.

Each eligible child can receive up to about 75% of your spouse’s basic benefit. A widow or widower caring for a child under 16 or with a disability may also receive a survivor benefit as a “widowed mother” or “widowed father.” But all of these checks are subject to the family maximum, which is usually between 150% and 180% of the worker’s full benefit. If the total for all survivors would exceed that limit, everyone’s benefits are reduced proportionally until the total fits under the cap.

That means your own survivor benefit may be lower while your children are also collecting, and then rise after they age out of benefits. This can surprise people who expect their own check to be a fixed number. When you apply, ask Social Security to show you how your household’s total benefits will change as each child hits age 16, 18, or 19 so you can plan ahead.

You must apply for survivor benefits, and the process still isn’t fully online

old person alone in wheelchair
Image Credit: Shutterstock

Social Security usually hears about a death from the funeral home, but that only stops your spouse’s checks. It does not start yours. To receive survivor benefits, you or someone on your behalf must contact Social Security and apply.

As of 2026, most widows and widowers still cannot complete a survivor claim purely through a self-service online form. Social Security’s own instructions for Form SSA-10, the widow’s, widower’s, and surviving divorced spouse’s benefit application, say you apply by calling the national number or visiting a local office. You can make an appointment, but it is not required. Independent guides and checklists still warn that survivor claims are taken by phone or in person, not through the same online process used for retirement benefits.

There is also a one-time lump-sum death payment of $255 that may be paid to a surviving spouse who lived with the worker, or to a child if there is no eligible spouse. You must apply for that within two years of your spouse’s death. When you call Social Security, ask about both the ongoing monthly survivor benefit and this one-time payment so nothing is missed.

10. Check your own record and revisit your plan over time

elderly person on laptop
Image Credit: Shutterstock

Even as a widow or widower, your own work record still matters. Your future retirement benefit, and any survivor benefits someone might receive on your record one day, are based on your lifetime earnings history. If a year of earnings is missing or too low because of a reporting error, your benefits can be permanently smaller unless you fix it.

The easiest way to keep an eye on this is to create a free “my Social Security” account. Once you are signed in, you can view your Social Security Statement, check your earnings year by year, and see estimates for your retirement and family benefits. If something looks wrong, an employer missing, or wages way off, you can ask Social Security to correct your record using old W-2s or tax returns.

Finally, remember that your best claiming strategy can change. New work, health problems, remarriage, a child aging out of benefits, or a change in the law can all shift what makes sense. It is fine to call Social Security more than once and ask for updated estimates. You do not need to become an expert; you just need to ask questions, take notes, and make choices that support your long-term income, not just this year’s bills.

Learn how to stretch your retirement savings and maximize your Social Security benefits for a comfortable retirement:
planning for retirement
Image Credit: Shutterstock

18 ways to stretch your retirement savings without feeling poor: The goal isn’t to pinch every penny — it’s to protect the big stuff and trim quiet leaks. Here are simple moves that keep freedom high and stress low.

18 budgeting rules that actually work for people over 50: Money habits change as we age. In this post, discover budgeting rules that fit your income and shift of priorities when you’re over 50.

15 clever strategies to maximize your Social Security benefits: Use the facts in this post to make choices that raise your monthly check for years.

Byline: Katy Willis

You don’t have to choose between making decent money and sleeping at night.

If your job has your shoulders up by your ears all day, it’s worth looking at work that’s calmer, predictable, and still pays at least $25 an hour. Low-stress doesn’t mean effortless. These roles all take skill and training. But they come with fewer emergencies, less chaos, and more control over your schedule.

Here are 18 jobs where the work is steady, the demand is real, and the typical pay falls roughly between $25 and $35 per hour, based on recent federal wage data.

Occupational therapy assistant

Occupational therapy assistant
Image Credit: Shutterstock

Occupational therapy assistants (OTAs) help people regain everyday skills after illness or injury. You might work with kids who have developmental delays, adults recovering from strokes, or older adults who want to stay independent at home. The work is hands-on, one-on-one, and usually happens in calm settings like outpatient clinics, schools, or rehab centers. Recent wage data puts the median pay for OTAs at about $32 per hour, or roughly $67,000 per year. Federal projections show this field growing much faster than average over the next decade thanks to an aging population.

Stress levels tend to be lower than in emergency or hospital nursing jobs because your focus is on gradual progress, not life-or-death decisions. To get started, you’ll need an associate’s degree from an accredited OTA program plus a state license. Schools list accredited programs through national accreditation directories. After graduation, you’ll take a national certification exam and then apply for state licensure through your state’s health board website. Many community colleges offer evening or part-time OTA tracks, which can help if you’re working or parenting while you train.

Physical therapist assistant

Physical therapist assistant
Image Credit: Shutterstock

Physical therapist assistants (PTAs) work under a physical therapist to help patients regain strength and movement after surgeries, injuries, or chronic conditions. You’ll guide people through exercise programs, stretches, and mobility work, usually in outpatient clinics, rehab centers, or home health. Median pay is about $29 per hour, or just over $64,000 per year. Employment projections show PTAs growing much faster than average as more people need rehab after orthopedic procedures or chronic conditions.

The pace is steady but not frantic. You’ll see patients by appointment, you know your schedule ahead of time, and you’re following treatment plans instead of making high-risk decisions on the fly. To qualify, you typically need an associate’s degree from an accredited PTA program and a state license. Accreditation listings are available through national physical therapy education directories. After graduating, you’ll take the PTA licensing exam, then apply for licensure with your state board. Many PT clinics are open to hiring new grads and offer on-the-job mentoring, so it’s realistic to move from school into work fairly quickly.

Clinical laboratory technologist or technician

Clinical laboratory technologist in lab
Image Credit: Shutterstock

If you prefer working behind the scenes, clinical lab tech roles are a solid bet. You run blood tests, analyze tissue samples, and operate lab equipment that helps doctors diagnose disease. It’s careful, methodical work that rarely involves face-to-face patient contact. The median wage is about $29 per hour, or around $61,000 per year. Federal projections show this field growing about as fast or faster than average, with steady demand driven by an aging population and expanded diagnostic testing.

This job tends to be quieter and more predictable than direct patient care. You’re still part of the healthcare team, but you’re in a lab, following established procedures and quality standards. To get in, many hospital labs will hire technicians with an associate’s degree in medical laboratory technology or a related science. Technologist roles usually need a bachelor’s degree. Look for programs accredited through national lab-science organizations. Certification from groups that credential medical laboratory professionals is often preferred or required. Once trained, you can work in hospitals, independent labs, public health departments, or large clinic systems.

Massage therapist

Massage therapist
Image Credit: Shutterstock

Massage therapists use touch to relieve pain, reduce stress, and help clients relax. You might work in a spa, wellness clinic, chiropractor’s office, or run your own small practice. Appointments are scheduled, one client at a time, in a dim, quiet room, about as far from a chaotic open office as you can get. Federal wage data puts median pay around $26.50 per hour, with many therapists earning more through tips, higher-priced sessions, or self-employment. Job growth is projected to be much faster than average over the next decade as more people use massage for wellness and pain management.

Most states require some combination of schooling and licensing. Typical training is a 500–1,000-hour massage therapy program at a vocational school or community college, often completed in under two years. State requirements and approved programs are listed through national massage boards and exam organizations. After school, you’ll likely take a licensing exam and apply through your state board. Many therapists also add short courses in prenatal massage, sports massage, or lymphatic drainage to charge higher rates without adding stress or overtime.

Dietitian or nutritionist

Dietitian
Image Credit: Shutterstock

Registered dietitians and nutritionists help people use food to manage conditions like diabetes, heart disease, food allergies, or digestive problems. The work is usually done in offices, clinics, schools, or community programs, places where schedules are predictable and emergencies are rare. The median annual wage is about $73,850, which works out to roughly $35 per hour. Employment is projected to grow faster than average as more healthcare systems focus on prevention and chronic disease management.

Stress is generally lower than in typical hospital nursing roles because your focus is on counseling, education, and long-term change. To become a registered dietitian, you’ll usually need a bachelor’s or master’s degree in nutrition or dietetics from an accredited program, plus supervised practice and a national credentialing exam. Some states license or certify nutrition professionals separately; requirements are listed on state health department sites. If you don’t want a full degree, there are also nutrition coach and dietetic technician paths that require shorter training and can still pay in the mid-$20s per hour depending on the employer.

Radiologic technologist

Taking an xray of a patients legs
Image Credit: Shutterstock

Radiologic technologists (sometimes called X-ray techs) operate imaging equipment that helps doctors diagnose broken bones, lung conditions, and other problems. You position patients, set up equipment, and capture images according to set protocols. The work is technical and patient-facing, but not usually as intense as emergency department nursing. Median pay for radiologic technologists is roughly in the mid-$30s per hour, with annual wages in the high $70,000s. Job growth is projected to be faster than average thanks to an aging population and expanded imaging use.

While there can be some rush when the hospital is busy, most of your day is scheduled imaging, not constant crises. To get into this field, you typically complete a two-year radiologic technology program at a community college or hospital-based school, then sit for a national certification exam. Accredited program lists are available through radiologic education accrediting agencies (https://www.jrcert.org). States often require licensure or registration, which you obtain through your state radiation control or health department after you pass the exam.

Hearing aid specialist

hearing aid specialist
Image Credit: Shutterstock

Hearing aid specialists test hearing, fit and adjust hearing aids, and coach patients on how to use their devices. Much of the work is conversational and patient-focused, done in quiet offices or hearing clinics. Recent wage data shows median pay around $29–30 per hour. Demand is strong and expected to keep rising as the population ages and more people seek treatment for hearing loss.

The environment is calm and structured: appointments, follow-ups, and detailed fitting work rather than emergencies. To get started, some states allow on-the-job training plus an exam, while others want a formal certificate or associate’s degree in hearing instrument science. Licensing rules are outlined by state licensing boards and hearing care associations. Many employers are willing to train motivated assistants and help them meet licensing requirements, especially in areas where it’s hard to find experienced specialists.

Librarian or media collections specialist

Librarian sorting out books
Image Credit: Shutterstock

Librarians and media collections specialists manage collections of books, digital resources, and media in schools, public libraries, colleges, and companies. Daily tasks can include answering reference questions, running community programs, and managing digital subscriptions. The median pay is about $31 per hour, or around $68,000 per year. Job growth is projected to be steady, roughly in line with the average for all occupations.

The work environment is typically quiet, structured, and predictable. You’ll have deadlines, budgets, events, curriculum, but you’re not dealing with trauma, sales quotas, or high-risk decisions. Most librarian roles require a master’s degree in library and information science from an accredited program, especially in public and academic libraries. Accredited program lists are published through national library associations. Some school library and specialized positions accept a bachelor’s degree plus a library certificate, which can be cheaper and faster, especially if you already work in education.

Archivist, curator, or museum technician

Curator
Image Credit: Shutterstock

Archivists, curators, and museum technicians care for historical documents, artworks, and artifacts. You might catalog collections, prepare exhibits, or maintain storage conditions. The median annual wage is about $57,100, or roughly $27 per hour. Employment is projected to grow about 6% over the next decade, faster than average, as museums and cultural institutions expand and replace retiring staff.

Stress here is more about deadlines for exhibits and grant cycles than angry customers or emergencies. Work happens in climate-controlled spaces with small teams and clear routines. Many archivist or curator roles call for at least a bachelor’s degree in history, art history, museum studies, or a related field; some positions prefer a master’s. Museum technician roles may accept a bachelor’s degree plus relevant experience or internships. Professional groups for archivists and museums share education and certification resources. Volunteering or interning in a local museum or archive is often the easiest way to get your foot in the door.

Surveying and mapping technician

Surveying and mapping technician
Image Credit: Shutterstock

Surveying and mapping technicians collect data about land, construction sites, and boundaries. You’ll use GPS, drones, and other instruments to measure distances and elevations, then help turn those into maps or site plans. Median pay is about $26 per hour. Projections show job growth roughly 5% over the next decade, a bit faster than average, especially in regions with strong construction activity.

This job can be a good fit if you like a mix of outdoor work and computer time. The stress level is moderate: you have deadlines tied to building projects, but you’re not dealing with emergencies or constant customer complaints. To enter the field, some employers hire with just a high school diploma and train you on the job. Others prefer a one- or two-year certificate or associate’s degree in surveying or geomatics from a community college or technical school. Professional surveying organizations provide information on education and state licensing requirements. Over time, you can move into more advanced roles or consider becoming a licensed surveyor.

Electrician

electrician working in the home
Image Credit: Shutterstock

Electricians install, maintain, and repair electrical systems in homes, businesses, and industrial buildings. Typical work includes wiring new construction, troubleshooting circuits, and upgrading service panels. Median pay is close to $30 per hour, or about $62,000 per year. Job growth is projected to be faster than average as new construction, renewable energy projects, and data centers increase demand for skilled electricians.

The work carries physical and safety demands, but many electricians find the stress manageable because the tasks are clear and hands-on. You’re solving practical problems, not juggling message overload or intense office politics. Most electricians learn through a paid apprenticeship lasting four to five years, combining classroom instruction with supervised work. Registered apprenticeship listings and general information are available through national apprenticeship directories. After your apprenticeship, you’ll take a licensing exam through your state or local licensing board. Once licensed, you can choose to work for a contractor, in industrial maintenance, or eventually start your own small business.

Heating, air conditioning, and refrigeration mechanic

HVAC Technician
Image Credit: Shutterstock

Heating, air conditioning, and refrigeration (HVAC/R) technicians install and service climate-control systems in homes, offices, and commercial buildings. That might mean putting in new units, doing seasonal maintenance, or fixing equipment that isn’t cooling or heating correctly. Median pay is about $27–28 per hour. Employment is projected to grow faster than average as buildings become more energy efficient and older technicians retire.

Peak seasons (heat waves, cold snaps) can be busy, but much of the work is scheduled maintenance. You’re usually working with one customer at a time, solving concrete problems. To get started, many people complete a one- to two-year HVAC program at a technical school or community college, then move into an entry-level tech role or apprenticeship. Industry groups and certification bodies share information on approved training and certifications such as EPA Section 608 for handling refrigerants. With experience, you can specialize in commercial systems, controls, or refrigeration to command higher pay while still avoiding office-style stress.

Industrial machinery mechanic

Industrial machinery mechanic
Image Credit: Shutterstock

Industrial machinery mechanics keep manufacturing equipment and production lines running. You inspect machines, replace worn parts, and troubleshoot breakdowns. It’s hands-on mechanical work, often in factories, food processing plants, or warehouses. Median pay is just under $30 per hour, with annual wages around $60,000. Job growth is projected to be much faster than average, as companies invest in automation and need skilled people to maintain complex equipment.

The environment can be noisy and physical, but the stress is different from customer-facing jobs. Your value is in keeping machines running, not in hitting sales quotas or answering emails all day. Many mechanics start with a high school diploma plus on-the-job training, then move into more advanced roles after completing a one- to two-year industrial maintenance or mechatronics program. Technical colleges and workforce programs offer these degrees and certificates, often in partnership with local employers. Industry skills groups also offer certifications in industrial maintenance and mechatronics. As you gain experience, you can specialize in robotics, packaging equipment, or specific manufacturing sectors.

Wind turbine technician

wind turbine technician
Image Credit: Shutterstock

Wind turbine technicians inspect, maintain, and repair wind turbines, usually on wind farms in rural or coastal areas. You climb towers, check electrical and mechanical systems, and perform routine maintenance. Median pay is close to $30 per hour, with annual earnings around $60,000. This job has one of the fastest projected growth rates of any occupation, driven by rapid expansion of wind energy.

The main stresses here are physical: heights, weather, and travel, not office politics or constant interruptions. If you enjoy being outside and working with your hands, it can feel less mentally draining than many desk jobs. Most wind techs complete a one- to two-year wind energy or turbine technology program at a community college or technical school. Wind-industry training organizations and safety groups share typical training outlines and standards. Employers then provide additional on-the-job training, including rescue and safety procedures. This is a niche field, but once you’re trained, your skills are in high demand.

Environmental engineering technologist or technician

Environmental engineering
Image Credit: Getty Images via Unsplash

Environmental engineering technologists and technicians help scientists and engineers monitor air, water, and soil quality. You might collect samples, run tests, or inspect industrial sites to make sure they meet environmental rules. Median pay is around $28 per hour. Demand is supported by ongoing environmental regulation and cleanup projects, as well as infrastructure investments.

Stress tends to be moderate: you deal with regulations and deadlines, but not with medical crises or angry crowds. Work is usually a mix of being in the field and in a lab or office, which helps the job feel less monotonous. Most roles require an associate’s degree in environmental science, environmental engineering technology, or a similar field from a community college or technical school. Look for programs accredited through engineering-technology accreditation organizations. Entry-level jobs often include on-the-job training in sampling methods, lab protocols, and regulatory software, and many techs move into more senior inspector or project-coordination roles over time.

Industrial engineering technologist or technician

Industrial engineering technologist
Image Credit: Shutterstock

Industrial engineering technologists and technicians help improve how factories, warehouses, and service operations run. You might time how long tasks take, map workflows, and help implement new layouts or processes so work is safer and more efficient. Median pay is about $32 per hour. Employment projections show modest growth, but companies still need these roles to cut waste and manage labor and equipment costs.

This work is more analytical than physically demanding. You’ll spend time on the shop floor observing, but also at a computer analyzing data, with fewer emotional stressors than customer-service or sales jobs. Most positions call for an associate’s degree in industrial engineering technology or a related field. Community colleges offer these programs, and some are accredited through engineering-technology accreditation bodies. With experience, techs sometimes transition into full industrial engineering roles, production management, or quality improvement positions, often with employers willing to help fund further education.

Mechanical engineering technologist or technician

Mechanical engineering technologist
Image Credit: Shutterstock

Mechanical engineering technologists and technicians support engineers who design and build machines, tools, and mechanical systems. You might help test prototypes, prepare CAD drawings, run performance tests, or document designs. Median pay is in the low-to-mid $30s per hour. Demand is tied to manufacturing, product development, and advanced industries like automotive and aerospace.

The stress level is typically manageable: you’re working on projects with timelines, not emergency calls. The work is technical and detail-oriented, but you usually have clear instructions and established design tools. Entry into this field usually requires an associate’s degree in mechanical engineering technology from a community college or technical institute. Many programs emphasize CAD, materials, and manufacturing processes and are accredited through engineering-technology organizations. Internships or co-op placements during school make it much easier to land a full-time role, and over time you can specialize in areas like HVAC design, automation, or product testing.

Calibration technologist or technician

Calibration technologist
Image Credit: Shutterstock

Calibration technologists and technicians make sure measuring instruments, like pressure gauges, scales, and sensors, are accurate. You’ll work in labs or manufacturing plants, using reference standards to test and adjust equipment. This is meticulous, quiet work where attention to detail matters more than speed. Median pay is about $32 per hour according to recent wage tables. Employers range from aerospace and medical device companies to testing labs and utilities, and demand is steady because every regulated industry needs accurate measurements.

This is one of the lower-drama technical jobs: no crowds, no emergencies, very little customer interaction. To enter the field, many techs complete a two-year degree in electronics technology, mechatronics, or instrumentation at a community college. Some people start as entry-level technicians and train on the job. Professional organizations offer a Certified Calibration Technician credential that can boost your pay and job security. With experience, you can move into quality management, lab supervision, or specialized work in industries with strict safety and compliance rules.

Discover job hunting tips, ways to earn more, and flexible working options:

Practising job interview
Image Credit: Shutterstock

21 high-paying careers that desperately need workers, but nobody wants to do them: The pay is generous, but these jobs are searching for workers.

No background check jobs: 12 background friendly jobs: If you’re struggling to find a job due to past issues, here are jobs you can get without background checks.

15 remote jobs you probably didn’t know pay $150,000+ In 2026: High income and flexible work hours from home is not a myth — here are some remote-friendly careers.

Byline: Katy Willis

You don’t have to own a team or sit courtside to have real NBA money in your house.

If you grew up watching Michael, Kobe, or LeBron, or have a parent who never threw anything away, there’s a chance something in a closet, attic, or the garage is worth far more than you think. The big headlines go to million-dollar jerseys and cards, but plenty of ticket stubs, bobbleheads, and mid-grade rookie cards quietly sell in the $40 to $1,000 range and up.

If you’re cleaning out old boxes or scrolling through estate-sale tables, it helps to know what actually sells, and what’s just old cardboard. Here are 18 specific NBA collectibles that have brought in real money, from “change your life” to “nice extra rent check.”

Limited-edition Kobe Bryant championship bobblehead

Kobe Bryant championship bobblehead
Image Credit: SoCal Collectibles and More via eBay

Stadium-giveaway and limited-edition bobbleheads sit in that sweet spot: cheap to get originally, surprisingly valuable later. One officially licensed Kobe Bryant “5 Rings” or championship-themed bobblehead from a numbered limited run has been offered and sold in the $150–$200 range, with one used example listed around $160+.

Collectors look for three things: low print runs (often printed on the base, like “27/500”), original box and packaging, and good paint with no chips. Kobe bobbleheads tied to specific achievements, rings, MVP, special nights, tend to do better than generic poses.

This is exactly the kind of thing sitting on office desks and bedroom shelves. Before you toss a dusty Lakers bobblehead into the yard-sale pile for $1, flip it over. If it’s numbered, features Kobe, and came from a special event or premium line, it may be worth enough to cover a tank of gas or a week of groceries.

Wilt Chamberlain’s 1961 Fleer rookie card

Wilt Chamberlain’s 1961 Fleer rookie card
Image Credit: Heritage Auctions

Wilt’s 100-point game will never be repeated, and his rookie card from the 1961 Fleer set is still the key to that classic issue. It shows him dunking in a Warriors uniform and is one of the most recognized basketball cards of the 1960s.

Completed-sale tracking shows mid-grade copies often landing in the $400–$2,000+ range, with some PSA 7 examples around or above $1,100 and lower grades still solidly in the hundreds.

You’re more likely to see this card in an older relative’s collection than at the local thrift store, but it does happen. Check for the 1961–62 Fleer logo and bright red and blue design. Even if the card looks rough, a crease, a soft corner, some edge wear, it can still be worth grading if it’s authentic. That’s the kind of “old junk” that quietly pays for a weekend getaway.

Kobe Bryant’s 1996–97 rookie Lakers jersey

Kobe Bryant’s 1996–97 rookie Lakers jersey
Image Credit: Heritage Auctions

First-season items are huge for stars, and Kobe’s rookie jersey is a textbook example. A purple Los Angeles Lakers jersey worn during his 1996–97 rookie year, photo-matched to multiple games including his preseason and regular-season home debut, sold in 2025 for $7 million.

That’s not a typical Kobe jersey, of course. What drives the price is the combination of “rookie,” “debut,” and clear documentation. The closer an item is to the beginning of a legend’s story, the more collectors want it. Jerseys with strong photo-match evidence and clear chain of ownership are where the huge numbers live.

Most people don’t have a debut jersey sitting around. But if a relative worked for the Lakers, a sponsor, or a local broadcaster in the 1990s and saved team gifts, it’s worth digging. Any game-worn Kobe item from his early years can bring in serious money, especially if you can connect it to a memorable night.

Autographed 1986–87 Fleer Michael Jordan rookie card

Autographed 1986–87 Fleer Michael Jordan rookie card
Image Credit: Heritage Auctions

Jordan’s 1986 Fleer rookie is the most famous basketball card ever made. Signed versions are even more intense. In 2025, a high-grade autographed copy of his 1986–87 Fleer rookie card sold for about $2.5 million.

That particular card was graded highly for both the card and the autograph, and there aren’t many like it. But even unsigned Jordan rookies can be worth real money. Price trackers based on completed sales show PSA 10 copies routinely into the six-figure range, with lower grades still selling for thousands.

If you find an old Jordan rookie in a shoebox, don’t touch the surface, don’t try to “press it flat,” and don’t wipe it. Put it in a sleeve and hard case if it isn’t already. Even a somewhat off-center or worn copy can fund a used car, a semester of community college, or a big dent in your credit cards.

Stephen Curry 2009 National Treasures rookie patch autograph

Stephen Curry 2009 National Treasures rookie patch autograph
Image Credit: Heritage Auctions

Modern collectors drool over high-end patch autos, and Steph Curry’s rookie cards are near the top of that list. A 2009 National Treasures Platinum rookie patch autograph numbered 5/5 and graded BGS 9 sold for $276,000 in a recent sale.

Even less extreme versions, higher serial numbers, lower grades, or different sets, can be worth tens of thousands. These cards stand out because they combine a game-worn patch, an on-card autograph, and very low print runs. If someone in your life was buying pricey hobby boxes in the late 2000s, there could be a serious Curry sitting in a plastic box right now.

Not all Curry rookies are lottery tickets. Many base cards and cheaper inserts sell in the $20–$200 range. But anything with a patch, serial number, or signature is worth checking against completed sales before you sell it for quick cash.

Kareem Abdul-Jabbar’s 1969 Topps “Lew Alcindor” rookie card

1969 Topps Lew Alcindor (Kareem Abdul-Jabbar) rookie
Image Credit: Heritage Auctions

Before he was Kareem, he was Lew Alcindor, and his 1969 Topps rookie is one of the pillars of vintage basketball collecting. High-grade copies are extremely tough, thanks to the tall card size and chipping on the colored borders.

Recent data based on graded sales shows PSA 10 copies reaching around $240,000. Mid-grade examples in PSA 6–7 have sold in the $1,500–$3,500 range, and even well-worn copies can clear several hundred dollars.

If you inherited a binder of “old tall basketball cards,” flip through carefully for Alcindor. The card shows a young Kareem in a Milwaukee Bucks uniform, with a bright yellow background and minimalist design. Centering, corner wear, and surface creases matter a lot, but even an average-looking copy can be worth enough to pay a utility bill or two.

1980 Topps Larry Bird / Julius Erving / Magic Johnson rookie card

1980 Topps Larry Bird Julius Erving Magic Johnson rookie card
Image Credit: Heritage Auctions

This weird three-panel card is a rookie for both Bird and Magic, and it also features Julius Erving. It comes in perforated panels that some kids tore apart, so intact cards in good shape are big money.

A high-grade PSA 9 example recently sold for about $16,600 Earlier, a top-grade copy sold for over $125,000. Even mid-grade examples often bring $400–$700 or more.

If you find a card with Bird on one end and Magic on the other, don’t panic if it’s off-center. That’s very common for this set. What matters most is that it’s untrimmed, not separated into individual panels, and not obviously fake. Even a “just OK” copy can bring in a few hundred dollars, much more than most ’80s cards.

Ticket stub from Michael Jordan’s NBA debut

Ticket stub from Michael Jordan’s NBA debut
Image Credit: Heritage Auctions

Old ticket stubs can be sneaky valuable, especially for historic games. Michael Jordan’s first regular-season game with the Bulls in 1984 is one of those moments. Families who went and saved their tickets are now cashing in.

In recent years, a group of four tickets from that debut has brought in a combined total close to $1 million, with one graded stub alone selling for about $341,600.

Not every debut stub is going to hit six figures. Condition (no heavy creases, writing, or missing corners), grading, and clear printing all matter. But this is exactly the kind of thing people toss into a shoebox and forget. If you or your parents went to Bulls games in the mid-’80s and kept stubs “for the scrapbook,” it’s worth checking the dates.

1998 NBA Finals Game 6 “Last Shot” ticket stub

1998 NBA Finals Game 6 “Last Shot” ticket stub
Image Credit: Heritage Auctions

Game 6 of the 1998 Finals is the night Jordan hit “The Shot” over Bryon Russell for his sixth title with the Bulls. Anything from that game is collectible, especially original ticket stubs in decent shape.

One graded ticket stub from that game sold in 2025 for about $2,257.

If you see a stub with “Bulls vs. Jazz” and a June 14, 1998 date, don’t let it sit in a junk drawer. Even lower-grade pieces with some wear can bring in a few hundred dollars. High-grade, slabbed examples climb higher. This is the kind of item you might still spot in a framed collage at a friend’s house or in a box of “old sports stuff” at an estate sale, and most people have no idea it’s more than just a memory.

Ticket stub from Kobe Bryant’s 81-point game

Ticket stub from Kobe Bryant’s 81-point game
Image Credit: Heritage Auctions

Kobe’s 81-point explosion against the Toronto Raptors in January 2006 is one of the wildest box scores in NBA history. Only a limited number of people were in that building, and fewer kept their ticket stubs.

Even a heavily worn, graded stub from that game has sold for around $256.

That price was for a low-grade example. Nicer stubs, full tickets, and anything paired with a good story (like photos or programs from the same night) can go much higher. If you’re a longtime Lakers fan, dig through any old frames, scrapbooks, or boxes labeled “tickets.” A small slip of paper from that game can easily cover groceries for the month.

Ticket stub from Michael Jordan’s last regular-season game at Chicago Stadium

Ticket stub from Michael Jordan’s last regular-season game at Chicago Stadium
Image Credit: Heritage Auctions

Not every valuable stub is from a Finals game. Sentimental milestones matter too. Jordan’s last regular-season game at old Chicago Stadium in 1993 is one of those “end of an era” nights.

A graded ticket stub from that game sold in 2024 for about $164.

That may not sound like much compared with multi-million-dollar jerseys, but it’s exactly the kind of find regular people actually have: a $10 ticket that quietly turned into more than a hundred bucks. Higher-grade or better-positioned seats can bring more. If your family has boxes labeled “Bulls stuff” from the early ’90s, flip through every old ticket before you toss them.

Sealed 1991 Michael Jordan Wheaties box

1991 Michael Jordan Wheaties box
Image Credit:
mattmcclanahan via eBay

Not everything has to be six figures. Even cereal can pay. A sealed 1991 Wheaties box featuring Michael Jordan, still unopened, has been listed and sold in the low-hundreds range, around $300 in at least one recent sale.

The big rule here: condition and seal. Collectors pay more for boxes that are crisp, with bright colors, sharp corners, and no crushing or stains. An opened, flattened box is still fun, but generally worth far less than a complete, unopened one. Also, watch for reprints or “commemorative” versions from later years.

If you know someone who hoarded promo cereal boxes in the ’80s and ’90s, check the stack. Jordan, early Shaq, and Dream Team boxes can all have modest but real value, especially when they’re still sealed and not sun-faded.

Shaquille O’Neal Lake Erie Monsters crossover bobblehead

Shaquille O’Neal Lake Erie Monsters crossover bobblehead
Image Credit: TinaF via eBay

Here’s a lower-dollar example that still beats pocket change. A quirky Shaquille O’Neal bobblehead produced for a Lake Erie Monsters hockey promotion, new in box, has been offered around $50–$60.

The value here comes from a few things: crossover appeal (NBA star plus minor-league hockey), a limited local giveaway, and fans who collect every odd Shaq item they can find. While this isn’t “pay off your car” money, it’s a realistic find in a thrift store or local online marketplace.

Bobbleheads like this show why it pays to look up anything that combines a big NBA name with a small or one-off promotion. Even if each piece only nets you $40–$80, a box of them from an old season-ticket holder can turn into a decent side hustle, or a quick emergency fund boost.

Strategies for making money outside of a traditional job:

freelance writer
Image Credit: Shutterstock

Where to sell sterling silver for the most money: In this post, you’ll learn about the difference between sterling silver and other types of silver, and find places to make the most money from selling your sterling.

What can I sell to make money (or resell)? 38 ideas: Dive into this article to discover things in your house you can sell for quick cash — and where to sell.

What sells quickly at pawn shops: In this post, you’ll find ways to navigate pawnshops, understand how they work and what items are most in demand.

Byline: Katy Willis

You spend decades paying into Social Security, and for most people that monthly check is a big chunk of retirement income. As of late 2025, the average retired worker’s benefit was about $2,071 a month. That’s not something you want to accidentally shrink.

The rules are complicated, and it’s easy to just convince yourself you’ll sort it out later. But some decisions you make in your 50s and 60s can permanently change the size of your check, and your spouse’s, for the rest of your life.

Claiming at 62 just because you can

social security and money
Image Credit: Shutterstock

You can turn on retirement benefits as early as age 62. The catch: if your full retirement age is 67 (which is the case for people born in 1960 or later), claiming at 62 permanently cuts your monthly check by about 30%. That smaller amount doesn’t “reset” later. Every future cost-of-living increase is based on that reduced benefit.

If you wait past full retirement age, you earn delayed retirement credits, roughly 8% more per year up to age 70 for many workers. For someone whose full retirement benefit at 67 would be $1,000, claiming at 62 could drop that to about $700. Waiting until 70 could boost it to around $1,240. That’s a huge difference over a 20- or 30-year retirement.

The mistake isn’t “claiming early is always bad” as plenty of people need the income or have health issues. The mistake is filing at 62 just because you’re allowed to, without running basic scenarios on your expected lifespan, other savings, and whether a higher check later might give you more breathing room.

Taking benefits while you still work and ignoring the earnings test

older worker working in a warehouse
Image Credit: Shutterstock

If you claim benefits before full retirement age and keep working, there’s a yearly earnings limit. In 2026, if you’re under full retirement age the limit is $24,480; Social Security withholds $1 in benefits for every $2 you earn above that amount. In the year you reach full retirement age, there’s a higher limit, $65,160 in 2026, and the withholding changes to $1 for every $3 above the limit.

These withheld checks aren’t gone forever; when you hit full retirement age, your benefit is recalculated to give you credit for months you didn’t actually receive benefits. But if you don’t plan ahead, you can be shocked to see your check drop or stop for months while you’re still paying the bills.

The earnings test doesn’t apply once you reach full retirement age, so the key is coordination. If you know you’ll keep working at a good income, it may make sense to delay claiming. If you really need to claim while working, keep a close eye on your expected wages for the year so you know how much of your check will actually show up and adjust your budget accordingly.

Letting gaps and low-earning years drag down your 35-year average

happy retired people on social security
Image Credit: Shutterstock

Your retirement benefit is based on your highest 35 years of earnings, adjusted for wage inflation. If you have fewer than 35 years in the workforce, Social Security fills the missing years with zeros. Caregiving breaks, long periods of part-time work, or time spent in jobs not covered by Social Security can all drag down that average.

On top of that, you need at least 40 “credits”, roughly 10 years of work, just to qualify for a retirement benefit at all. Many people hit the 10-year mark and think they’re set, but that’s just the minimum. If you have, say, 25 years of earnings and 10 zeros, a few additional years of decent wages can replace those zeros and meaningfully increase your lifetime benefit.

The mistake is assuming “I’ve already worked enough” without looking at how many years of earnings are on your record and how strong they are. Before you decide to fully stop working, look at your Statement and ask: would a few more years at higher pay replace low or zero-earning years and bump up my check.

Never checking or correcting your earnings record

worrying about taxes on earnings on social security
Image Credit: Shutterstock

Social Security doesn’t magically know what you earned; it relies on what your employers and the IRS report. If a year of earnings is missing or under-reported and you never catch it, your benefit will likely be lower for life. Social Security itself tells workers to regularly review their earnings history for mistakes.

You can see your full earnings record and projected benefits by creating a free “my Social Security” account online. If something looks off, an employer missing, wages way lower than you remember, you can ask for a correction. Social Security explains that you may need proof like W-2 forms, pay stubs, or tax returns, and you can use Form SSA-7008 to request a fix.

Waiting until you’re 65 to look at this stuff makes it harder to find old paperwork. A simple habit of checking your online Statement once a year can catch errors early, when you still have records and time on your side.

Missing spousal benefits when you’re married

older couple looking at social security
Image Credit: Shutterstock

If you’re married, your retirement check isn’t the only one that matters. A spouse with a lower benefit may be able to receive up to 50% of the higher earner’s full retirement benefit as a spousal benefit. That spousal amount is based on the higher earner’s benefit at full retirement age, not on delayed retirement credits, and it’s reduced if the spouse claims before their own full retirement age.

Many couples never ask about this. The lower-earning spouse files on their own record at 62, ends up with a small check, and assumes that’s all there is. In reality, Social Security will compare your own benefit to any spousal benefit you qualify for and pay the higher amount, but only if they know your spouse’s work record and your marital status.

If you’re married now or were married in the past, make sure you list that history clearly when you file and ask what spousal amount you qualify for. For many couples, coordinating who claims when, instead of both filing early on their own records, can mean hundreds of extra dollars per month for the household.

Missing divorced spousal benefits after a long marriage

divorce
Image Credit: Freepik

If you’re divorced, you may still be entitled to a benefit based on your ex’s work record, even if they’ve remarried and even if you haven’t spoken in years. In general, you may qualify if your marriage lasted at least 10 consecutive years, you’re 62 or older, your ex is at least 62 and eligible for benefits, and you’re currently unmarried.

The divorced spousal benefit can be up to 50% of your ex’s full retirement benefit, and your claim doesn’t reduce your ex’s check or their current spouse’s benefits. Yet plenty of divorced people never mention past marriages when they file. They assume it’s too messy, or they worry they need their ex’s permission. You don’t.

If you had one or more long marriages, write down the dates and keep your divorce paperwork handy before you apply. Tell the Social Security rep about each 10-plus-year marriage. Even if your own work history is strong, it’s worth asking what your divorced spousal benefit would be so you can compare especially if your ex was the higher earner.

Overlooking survivor benefits after a spouse dies

depressed older person
Image Credit: Getty Images via Unsplash

When a spouse dies, the surviving spouse and sometimes children may qualify for survivor benefits. A surviving spouse can often get up to 100% of the deceased worker’s benefit if they wait until full retirement age, or a reduced amount as early as age 60 (age 50 if disabled). Survivor benefits are based on the deceased worker’s benefit, including any delayed retirement credits they earned by waiting past full retirement age.

A common mistake is assuming, “I already have my own retirement benefit, so that’s that.” In fact, you usually get whichever is higher: your own retirement check or the survivor benefit. Widows and widowers can sometimes start one benefit early and switch to the other later, depending on the numbers and ages involved.

If you’ve lost a spouse or ex-spouse who had enough work credits, it’s worth asking Social Security to review your survivor options, even if you’re already receiving a benefit. Survivor rules are complex, but the potential increase to your monthly check can be substantial and lasts for life.

Remarrying without checking how it changes your benefits

older couple remarrying
Image Credit: Shutterstock

Love is not a financial plan, but marriage can change your Social Security picture. If you’re receiving (or expect to receive) divorced spousal or divorced survivor benefits based on a former spouse, getting remarried before age 60 can cut off those benefits in many cases. Remarrying at age 60 or later usually lets you keep survivor benefits based on a deceased spouse.

People often rush or delay remarriage based on half-true stories: “You’ll lose everything if you marry again,” or “It doesn’t matter what age you remarry.” The reality depends on the type of benefit (spousal vs survivor), your age, and whether your new spouse has a strong work record of their own. You may lose access to an ex-spouse’s record but gain a higher future benefit on your new spouse’s record.

You shouldn’t make big life choices only around Social Security. But if you’re widowed or divorced and close to age 60, it’s smart to understand how the timing of a remarriage could affect your current or future checks. A quick call to Social Security before you make it official can save you from surprises later.

Forgetting that your Social Security can be taxed

US dollars social security and a calculator
Image Credit: Shutterstock

Many retirees are shocked to learn that up to 85% of their Social Security benefits can be subject to federal income tax, depending on their “provisional income” basically, other income plus half of your Social Security. For single filers, taxes can kick in once provisional income passes $25,000; for married couples filing jointly, the threshold is $32,000.

That doesn’t mean the government takes 85% of your check. It means up to 85% of the benefit amount can be counted as taxable income, and then your normal tax bracket applies. Still, if you add part-time work, big IRA withdrawals, capital gains, and Social Security all in the same year, your after-tax benefit can be a lot smaller than you expected.

The mistake is not looking at taxes at all. A basic tax projection before you file, or whenever you plan big withdrawals, can help you decide whether to delay claiming, spread out withdrawals, or shift income between spouses to keep more of your check. Even if you can’t avoid taxes entirely, you can at least avoid being blindsided by a bill in April.

Ignoring how your claiming age affects your spouse’s future survivor check

older couple on computer with calculator
Image Credit: Shutterstock

In many couples, one spouse outlives the other by years or even decades. When one of you dies, the survivor usually keeps the higher of the two Social Security checks and the smaller check goes away. Survivor benefits can be up to 100% of the deceased worker’s benefit, including any delayed retirement credits that person earned.

That means the higher earner’s claiming decision doesn’t just affect their own lifetime income. If the higher earner files at 62 and locks in a smaller benefit, the surviving spouse may be stuck living on that reduced amount for the rest of their life. If that same higher earner can afford to delay until 70, the bigger check, boosted by delayed retirement credits of up to about 8% per year between full retirement age and 70, may later become the survivor’s check.

When you run the numbers, look at both lives, not just your own. In a couple where one spouse expects a longer life or has little savings of their own, it can make sense for the higher earner to delay claiming specifically to protect that future survivor income.

Not revisiting your benefits after major law changes

sad depressed older person
Image Credit: Freepik

Social Security rules don’t change every year, but when they do, the impact can be huge. In 2025, a major law, often referred to as the Social Security Fairness Act, ended the Windfall Elimination Provision and the Government Pension Offset, which had reduced or eliminated benefits for millions of people with “non-covered” government pensions (jobs that didn’t pay Social Security tax). News reports estimate that more than 3 million teachers, firefighters, police officers, and other public workers saw their benefits increase, with billions in retroactive payments issued in 2025.

If you or a spouse worked in a job that didn’t pay into Social Security and you were told for years that WEP or GPO would cut your benefit, it’s a mistake to assume that old estimate is still right. Your check may already have gone up, but if your situation is complicated, it’s worth checking your current benefit amount and asking Social Security to review your record under the new rules.

Even if you’re not affected by this particular law, the lesson stands: when there’s a big Social Security change in the news, or every few years as you near retirement, take another look at your Statement and your options. A quick review can reveal benefits you didn’t know you’d earned.

Skipping your online account and basic fraud protections

older couple talking at computer
Image Credit: Shutterstock

Your Social Security number is a prime target for scammers. One growing problem: criminals use stolen personal information to create “my Social Security” accounts in other people’s names and reroute benefits. Social Security now strongly encourages everyone to set up their own secure online account, which lets you view your Statement, check your earnings, and manage benefits.

Not having an account doesn’t keep you “off the grid.” It can actually make you more vulnerable, because a scammer might be the first to create one using your information. The agency has also tightened security, for example, stopping bank-account changes by phone and pushing people to make those changes online or in person to reduce fraud.

Creating an account through the official site, turning on extra security features, and being skeptical of emails or texts with “SSA” links are simple ways to protect your future checks. The mistake is waiting until something goes wrong to lock things down.

Learn how to stretch your retirement savings and maximize your Social Security benefits for a comfortable retirement:

planning for retirement
Image Credit: Shutterstock

18 ways to stretch your retirement savings without feeling poor: The goal isn’t to pinch every penny — it’s to protect the big stuff and trim quiet leaks. Here are simple moves that keep freedom high and stress low.

18 budgeting rules that actually work for people over 50: Money habits change as we age. In this post, discover budgeting rules that fit your income and shift of priorities when you’re over 50.

15 clever strategies to maximize your Social Security benefits: Use the facts in this post to make choices that raise your monthly check for years.

Byline: Katy Willis

You probably have a section of your closet that’s basically a storage unit: jeans that don’t fit, work dresses from three jobs ago, kid clothes they outgrew overnight. Together they add up to real cash that can cover boring, necessary stuff like groceries, co-pays, and one more chunk off a credit card.

The trick is matching the right items to the right site so you’re not wasting time on lowball offers or confusing fees. 

Poshmark

Poshmark logo
Image Credit: Poshmark, Public domain, via Wikimedia Commons

Poshmark is basically a giant online clothing swap with money involved. It’s best for mall and mid-range brands (think Old Navy through Madewell), plus athletic wear and trendy shoes. You snap a few photos, add size and brand details, set your price, and Poshmark sends you a prepaid shipping label when something sells. They keep a flat cut of each sale, 20% on items over $15, and a flat fee on smaller sales, and you keep the rest.

Poshmark works well if you’re willing to treat this like a casual side hustle. Sharing your listings inside the app, joining “Posh parties,” and cross-posting your closet on social all help items move faster. Grouping similar things into bundles (like three pairs of leggings in one listing) can justify a higher price and reduce how often you’re packing orders. If you have a closet full of recognizable brands in good condition, this is a straightforward way to turn them into cash without learning a complicated system.

thredUP

thredUP
Image Credit: thredUP, Public domain, via Wikimedia Commons

If you want the money but not the effort, thredUP is the “please just take the whole pile” option. You order a Clean Out Kit or print a prepaid label, stuff a big box or bag with clothes, and ship it in. thredUP handles photography, listings, pricing, and shipping to buyers. In exchange, they keep a large part of the sale price; your payout depends on brand, condition, and how fast it sells.

This makes sense for people with more time pressure than money pressure, busy parents, full-time workers, or anyone staring at ten trash bags of clothes. You won’t get top dollar for each item, but you also won’t be answering questions about inseams at 9 p.m. Focus on sending in in-season, name-brand pieces in excellent condition; fast fashion basics and worn items often get rejected or pay next to nothing. Check thredUP’s payout estimator before you ship so you’re not surprised by the numbers, and treat whatever comes in as “found money” for stuff that was just sitting there.

Depop

depop
Image Credit: Depop, Public domain, via Wikimedia Commons

Depop is part resale app, part social media. It’s especially strong for Y2K, streetwear, vintage, and anything that photographs well styled on a person. Listings live inside a feed-style profile, and buyers can like, message, and follow you. Depop charges a selling fee plus payment processing when an item sells, so price with that in mind.

Depop rewards a certain “look.” Think mirror selfies, clean backgrounds, and outfits instead of flat-lay piles. If you’re already taking selfies or outfit pics, you’re halfway there. This is a good fit if you have a strong sense of style and enjoy curating a little “shop”, not just dumping random clothes. Niche brands, band tees, and unique thrift finds can do really well here. To make it worth your time, batch list: photograph 10–20 items at once, write simple but keyword-rich descriptions (“black Nike tech fleece joggers men’s medium”), and be responsive to offers. It’s less ideal for basic work trousers and more for the fun stuff.

eBay

ebay logo
Image Credit: Lippincott Studio/Adrian Frutiger (typeface)., Public domain, via Wikimedia Commons

eBay is still the big, messy, powerful option if you want maximum reach. You can sell everything from Target basics to rare designer pieces, plus shoes, bags, and accessories. You choose auction or “Buy It Now,” set shipping, and eBay takes a cut, in clothing categories, typical fees land in the low-to-mid teens as a percentage of the total sale once you factor in their final value fee and fixed per-order charge.

Use eBay when you’ve got something that people might actually search for: a sold-out collaboration, plus-size styles with limited options elsewhere, or specific workwear brands. Look up completed listings before you price so you know what things actually sold for, not just what other sellers are dreaming about. Auctions can be great for truly in-demand pieces; for everything else, fixed price with “Best Offer” is safer. Shipping is where people lose money, so weigh items in the package and use eBay’s shipping calculator instead of guessing. Done right, eBay can pull in more per item than many apps, especially for higher-value pieces.

Mercari

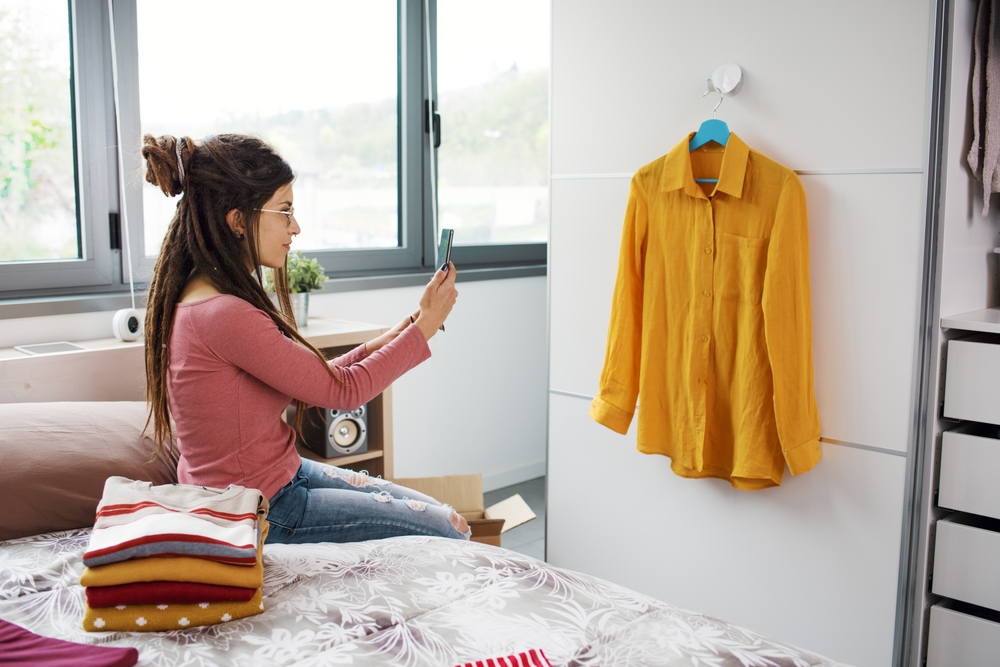
taking pictures of clothes to sell online
Image Credit: Shutterstock

Mercari is a simple, no-frills marketplace that’s big on secondhand fashion, shoes, and everyday stuff. You snap photos, write a short description, set your price, and choose whether you or the buyer pays shipping. When it sells, Mercari currently charges a 10% selling fee on the item price and buyer-paid shipping, and a separate buyer-side protection fee, still usually less cluttered than eBay’s fee maze.

Mercari works well if you want straightforward math and don’t care about “social” features. Everyday brands, kids’ clothes, and practical shoes move here if they’re priced right and photographed clearly. A lot of buyers filter by condition and free shipping, so build the cost of shipping into your price and label it “free” if you can. To protect your profit, avoid listing super-low-priced items one by one; either bundle or wait until you have a small pile to justify the time and fees. Respond quickly to questions and offers, serious buyers often move on fast.

Vinted

Vinted logo
Image Credit: Vinted, Public domain, via Wikimedia Commons

Vinted just expanded into the U.S. after dominating secondhand fashion in Europe, and it’s built around one big promise: no selling fees. Buyers pay a small “Buyer Protection” fee on top of your price, plus shipping, and you get the full list price when your item sells.

That alone makes Vinted a smart pick if you’re tired of watching 15–20% vanish in fees on other platforms. It’s good for mid-range brands, kids’ clothing, sneakers, and athleisure, anything clean, on-trend, and fairly priced. Because buyers pay their own fee, they’re extra sensitive to inflated prices; checking similar sold listings will help you land in the “feels fair” zone. Shipping is mostly handled through prepaid labels and drop-off points, which cuts down on post office drama. To avoid headaches, be extra honest about flaws and take clear photos; like every peer-to-peer platform, disputes about condition are a pain you don’t need.

Facebook Marketplace

Facebook Logo
Image Credit: Facebook Inc., Public domain, via Wikimedia Commons

Facebook Marketplace is the “cash in hand by tonight” option. It shines for bulky items like winter coats, boots, job interview outfits, and big kid clothing lots that are annoying to ship. You list the item, set a price, and decide whether you’re doing local pickup, shipping, or both. Facebook also supports shipping with checkout and built-in payments, charging a small selling fee on shipped orders.

Marketplace is best for people who want speed and are comfortable meeting buyers in person. Grouping kids’ clothes into size-labeled bundles (“25 pieces, boys 6–7, school and play clothes”) lets you move volume fast and saves parents a ton of time, which justifies your price. Safety matters here: meet in public, daylight-only, and stick to cash or through-the-app payments. If you have a lot to sell, join local buy/sell groups as well, they often have more serious shoppers than the general Marketplace feed.

Vestiaire Collective

Vestiaire Collective
Image Credit: Oeo9wlC, Public domain, via Wikimedia Commons

If you have actual designer piece, not “inspired by,” but the real thing, Vestiaire Collective is built for that. The platform focuses on pre-loved luxury fashion and accessories, with expert authentication and a global audience. Sellers list items, set prices, and ship to Vestiaire or directly to buyers depending on the item. Fees vary, but they’ve been pushing lower commissions and even zero-selling-fee promos on certain brands and price ranges.

Vestiaire makes sense if you own designer bags, coats, or clothing that you originally paid real money for. Their curation and authentication can justify higher resale prices than general sites, buyers feel safer spending big. Your job is to be meticulous: clear shots of labels, serial numbers, receipts if you have them, and honest condition notes. Because this is an international platform, be prepared for longer shipping windows and picky buyers. On the flip side, a single sold designer piece here can wipe out what you’d make from a whole pile of mall-brand tops on other apps.

The RealReal

selling clothes online
Image Credit: Shutterstock

The RealReal is another heavy hitter for high-end items. Instead of you handling listings, they operate as a managed consignment service: you ship or drop off your luxury clothes, handbags, jewelry, and shoes, they authenticate and list them, and you get paid once they sell. Their own materials say many items sell within about 30 days, which is appealing if you’re trying to free up cash quickly.

The RealReal is best when you have pieces from brands they love, think designer labels, not fast fashion, and you don’t want to deal with individual buyers. Commission rates vary by category and price, but you’re trading some potential profit for pure convenience and the trust their brand already has with high-end shoppers. Before you send anything, check their accepted brands list and estimated payouts so you don’t box up items they’ll reject. For big-ticket pieces cluttering your closet, this can be the least stressful way to turn them into a meaningful chunk of cash.

Grailed

girl taking photos of clothes to sell online
Image Credit: Shutterstock

Grailed started as a menswear resale platform but now includes women’s pieces and unisex styles, with a strong focus on designer, streetwear, and high-quality vintage. It’s where people hunt for specific brands and rare pieces, not random fast-fashion jeans. You list items with detailed brand and condition info; buyers can make offers or buy outright.

Use Grailed when you’ve got items that fashion nerds care about: heritage denim, archival pieces, limited collabs, or well-made basics from respected labels. Buyers tend to be picky but willing to pay if you provide good photos and measurements. Unlike more casual apps, there’s an expectation that you know what you’re selling; take a minute to research model names and fabric content. Fees are similar to other fashion marketplaces, so the real advantage is the audience, these are people actively searching for the brands you might otherwise undersell on a general site. One or two well-priced sales here can out-earn a whole stack of “meh” items listed elsewhere.

StockX

stock X logo
Image Credit: StockX, Public domain, via Wikimedia Commons

If your “old clothes” include serious sneakers or hype streetwear, StockX (https://stockx.com) treats them like a stock market. You don’t write flowery descriptions; you pick the exact item from their catalog, set an “ask” price, and wait for a buyer’s “bid” to match. When your shoes or streetwear sell, you ship them to StockX for verification before they go to the buyer. Every item is authenticated, which is a huge draw for buyers nervous about fakes.(StockX)

StockX works best for recognizable releases: Jordans, Dunks, Yeezys, collab sneakers, and some branded apparel or accessories. Before you list, check recent sale prices so you’re not underpricing something that quietly skyrocketed. Fees are higher than selling to a friend, but you’re paying for instant access to a global pool of sneakerheads who are used to market-level pricing. Condition rules are strict; most items must be new or near-new. If you’ve been sitting on deadstock sneakers or hype hoodies “for later,” this is a structured way to cash them out.

GOAT

selling sneakers online
Image Credit: Shutterstock

GOAT is another giant in sneaker resale, also branching into apparel and accessories. Like StockX, it authenticates items, but it offers both new and used listings and lets some sellers ship directly to buyers while others ship to GOAT first for verification. That mix can make it easier to move gently worn sneakers and streetwear.

GOAT is a good choice if you have sneakers with a little life on the soles but still in solid condition, or branded streetwear from labels that have a following. Upload clear photos, including soles and tags, and be honest about wear, buyers are used to seeing graded condition here. Because the platform focuses so heavily on authenticity, you may get higher offers than you’d see on more general apps for the same shoes. If you’re trying to decide between StockX and GOAT, it sometimes makes sense to cross-check prices and go where your specific item is selling faster and higher.

Etsy

Etsy
Brandlogos.net, Public domain, via Wikimedia Commons

Etsy isn’t just for handmade crafts. It’s also a major marketplace for true vintage clothing, items at least 20 years old, and upcycled or reworked pieces. If you’ve been thrifting for years or inherited older clothing that’s stylish again, Etsy gives you a way to reach people actively searching for “90s leather jacket” or “80s prom dress.”

Etsy makes the most sense if you want to build a small, curated shop rather than dump everything at once. You’ll pay listing fees plus a cut of each sale and payment processing, so this isn’t ideal for $8 fast-fashion tops. Focus on unique, high-quality vintage, plus altered or upcycled pieces where your labor adds value. Good photography and detailed keywords (“70s prairie dress floral medium,” not just “cute dress”) are crucial. The upside is that buyers come here ready to pay more for special pieces. If you treat it like a real micro-business, consistent branding, clear policies, thoughtful packaging, Etsy can turn your eye for vintage into steady extra income.

Whatnot

whatnot logo
Image Credit: Whatnot, Public domain, via Wikimedia Commons

Whatnot is a live shopping marketplace, imagine eBay plus TikTok. Sellers run live shows where they hold up items, chat with viewers, and auction pieces in real time. Clothing and fashion are big categories, and many sellers run themed shows like “all vintage tees” or “plus-size mystery bundles.” Standard seller fees include a commission on the sale price plus payment processing.

Whatnot is best for outgoing people who don’t mind being on camera and talking for an hour. If that sounds fun instead of terrifying, it can be a fast way to move a lot of clothing in one session and build regular customers. You don’t need fancy equipment, a phone, decent lighting, and a table or rack is enough to start. The key is energy and honesty: show flaws, answer questions, and keep the pace moving so buyers stay engaged. If you’re already sitting on bins of inventory from other platforms, a few live shows can clear space and generate cash without writing 50 separate listings.

Strategies for making money outside of a traditional job:

freelance writer
Image Credit: Shutterstock

Where to sell sterling silver for the most money: In this post, you’ll learn about the difference between sterling silver and other types of silver, and find places to make the most money from selling your sterling.

What can I sell to make money (or resell)? 38 ideas: Dive into this article to discover things in your house you can sell for quick cash — and where to sell.

What sells quickly at pawn shops: In this post, you’ll find ways to navigate pawnshops, understand how they work and what items are most in demand.

Byline: Katy Willis

If you grew up in the ‘80s or ‘90s, there’s a good chance there’s a shoebox of NBA cards somewhere in your house. Maybe your kids ripped packs during the Luka and Zion craze and left binders in their closet. It all feels like kid stuff until you hear that one card can cover a mortgage payment or wipe out a chunk of debt.

Most cards are still worth pennies. But a small group, especially older stars and rare rookie parallels, have turned into serious money, even in a softer market. In good condition and properly graded, some of these pieces of cardboard are selling for thousands, and a few are in full “life-changing money” territory.

1986 Fleer Michael Jordan rookie

1986 Fleer Michael Jordan rookie
Image Credit: Heritage Auctions

If you pulled this red-blue border rookie from a pack in the ‘80s, you’re sitting on one of the most recognizable sports cards on the planet. The 1986 Fleer #57 base rookie is the “must-have” Jordan card for many collectors, and prices reflect that status.

Recent online sales show raw (ungraded) copies with obvious wear still bringing around $2,000–$3,700, depending on eye appeal. One raw example sold for about $3,700 in February 2026. Mid-grade graded copies can reach the low five figures, and clean PSA 8s have been selling around $11,000. That’s real money for a single piece of cardboard.

If you think you have this card, do not try to “clean” it. Slip it into a soft sleeve and rigid holder and keep it away from heat and light. Centering, corners, and surface print dots make a big difference here. Before you pay for grading, compare yours to recent eBay and auction photos. If the edges are rough or badly off-center, you may be better off selling it raw instead of chasing a high grade that’s not realistic.

1980–81 Topps triple rookie of Larry Bird and Magic Johnson

1980–81 Topps triple rookie of Larry Bird and Magic Johnson
Image Credit: the-treasure-trove83 via eBay

This oddball card shows three players on one tall, perforated panel: rookie Larry Bird, veteran Julius “Dr. J” Julius Erving, and rookie Magic Johnson. It was meant to be torn into three little cards. Un-torn, nicely centered copies of this 1980–81 Topps scoring leaders card are now hobby royalty.

Collectors pay up for intact panels with clean perforations and good centering. Recent sales data shows ungraded but decent copies around $400–$500, while professionally graded mid-grade examples (PSA 6–7) sell close to $900. High-grade versions can jump into the many thousands.

If you find this card in a shoebox, the biggest killers are creases across the perforations, surface indentations, and kids having actually torn the three panels apart years ago. Don’t try to flatten or separate anything, just sleeve and protect it. Even lower-grade intact copies are desirable because there simply aren’t many left that survived as one piece.

1948 Bowman George Mikan rookie

1948 Bowman George Mikan rookie
Image Credit: Heritage Auctions

The 1948 Bowman #69 George Mikan is one of the earliest true NBA rookie cards. It’s small, black-and-white, and easy to overlook if you don’t know what you’re holding. But for vintage basketball collectors, this is the big man who started it all.

Because of age, most surviving copies are creased, rounded at the corners, or off-center. Even so, price guides built from recent sales show rough, ungraded examples in the several-thousand-dollar range. A nice high-grade copy graded SGC 8 sold for about $73,000 in early 2025. That’s more than many people spend on a new car.

Condition is everything here. Watch for heavy creases, paper loss on the back, and trimming (edges cut too sharp). If your card looks surprisingly clean for its age, it’s worth talking to a trusted local shop or a major auction house, because high-end vintage pieces like this usually sell best in big, well-advertised auctions, not in a random online listing.

1957 Topps Bill Russell rookie

1957 Topps Bill Russell rookie
Image Credit: Heritage Auctions

The 1957–58 Topps #77 Bill Russell is another tiny cardboard square with big money potential. It’s Russell’s first mainstream card and one of the key vintage basketball rookies.

Because the set was printed with rough cuts and poor centering, even average-looking examples are hard to find. Recent data based on completed sales shows ungraded Russell rookies around $2,700–$3,000, while graded copies climb quickly as condition improves. High-grade examples can hit tens of thousands of dollars at major auctions.

If you have one, check for severe off-centering (tiny border on one side), wax stains on the back, and surface wrinkles. This is another card where it’s usually worth paying for grading if the card looks sharp and crease-free. A professionally graded Russell rookie is much easier to sell to serious buyers and can be the centerpiece of a small collection.

1961 Fleer Wilt Chamberlain rookie

1961 Fleer Wilt Chamberlain rookie
Image Credit: Heritage Auctions

The 1961–62 Fleer #8 Wilt Chamberlain rookie comes from a colorful set that’s loved by vintage basketball fans. The bold red-blue border and simple action shot make it easy to recognize, even if you’re not a card nerd.

Completed-sale data shows that even low-grade, heavily played copies can bring more than $1,500, with one PSA 2 selling for around $1,600 in late 2025. Nicer examples with fewer creases and better color can move into the mid-four-figure range quickly. For many households, that’s enough to pay off a credit card or fund a small emergency.

Look closely at the red border as chips, color loss, and print dots are common. Centering is rarely perfect, so don’t panic if one border is thicker than the other. As with other vintage stars, preserve what you have rather than trying to “fix” it. Sleeves and a hard case are cheaper than losing hundreds of dollars by scratching the surface.

1969 Topps Lew Alcindor (Kareem Abdul-Jabbar) rookie

1969 Topps Lew Alcindor (Kareem Abdul-Jabbar) rookie
Image Credit: Heritage Auctions

In 1969, Kareem was still going by Lew Alcindor, and his tall, rounded-corner Topps rookie card looks more like a novelty sticker than a modern trading card. It’s easy to miss in a stack of old odd-sized cards.

Despite the quirky design, collectors know what it is. Recent sales built into price guides show mid-range ungraded copies bringing around $500, with some stronger raw examples and low-grade slabs pushing higher. High-grade copies can jump into the thousands because so many of these cards were damaged by kids peeling, bending, or trimming them decades ago.

Condition tips: make sure the card still has its original rounded corners (no home cutting), and check for paper loss on the back where it may have been taped or glued into a scrapbook. Even if it’s rough, this is not one to give to the kids or toss, a buyer may still pay hundreds for a worn but authentic example.

1996–97 Topps Chrome Kobe Bryant refractor rookie

1996–97 Topps Chrome Kobe Bryant refractor rookie
Image Credit: Heritage Auctions

Kobe’s 1996–97 Topps Chrome #138 refractor rookie is one of the iconic modern basketball cards. The shiny finish, Lakers colors, and refractor rainbow make it instantly recognizable to collectors.

Because the card is condition-sensitive, strong copies sell for real money. Recent sales show ungraded refractors routinely changing hands for thousands, and graded near-mint-to-mint copies jumping into five figures. One PSA 9 copy has sold north of $20,000 in recent months, with similar examples hitting the high-teens to low-$20,000s range at auction.

Like other Chrome-era cards, these scratch easily and often have surface issues straight from the pack. Hold the card under a strong light and tilt it to check for lines, haze, and print defects on the front. If your refractor looks clean and well-centered, grading can make a huge difference, but if you see obvious scratches, it may be smarter to sell raw and keep more of the profit.

1997–98 Metal Universe Precious Metal Gems Red Michael Jordan

1997–98 Metal Universe Precious Metal Gems Red Michael Jordan
Image Credit: Heritage Auctions

If there’s a non-rookie card that still makes collectors’ jaws drop, it’s the 1997–98 Metal Universe Precious Metal Gems (PMG) Red Michael Jordan, numbered out of just 90. Between the extreme scarcity, the bold green-red foil, and Jordan’s goat status, this card has become a true grail.

High-grade examples almost never come up, but even lower-grade copies have set records. A PMG Red Jordan in a graded holder sold in 2025 for around $650,000 at a major auction, showing how strong demand remains for this rare parallel.

If you think you’ve found one, double-check everything. Counterfeits and reprints are common. Look at serial numbering, foil color, and the exact card stock. This is not a card to sell raw to the first person who DMs you; you’d want authentication, grading, and a reputable auction house. Even heavily worn PMGs can be worth more than a luxury car.

2003–04 Topps Chrome LeBron James refractor rookie

2003–04 Topps Chrome LeBron James refractor rookie
Image Credit: Heritage Auctions

LeBron’s mainstream rookie picture has a few versions, but the 2003–04 Topps Chrome #111 refractor is one of the most chased. It’s a shiny upgrade over the base Chrome rookie and comes from a loaded draft class.

Recent completed sales show ungraded refractors selling from the mid-$4,000s up to around $8,000, depending on condition. A string of eBay sales in 2024 and 2025 saw raw and lightly graded copies closing between roughly $4,500 and $8,100. Top-graded PSA 10s and BGS 9.5s can reach well into the five-figure range.

This card is graded heavily, so buyers are picky. Surface dimples, edge chipping, and poor centering will cut your sale price fast. If your card has been sitting raw in a box for years, handle it carefully, use a clean sleeve and top-loader, and compare it closely to graded examples before spending money on grading fees.

2003–04 Upper Deck Exquisite RPA LeBron James 

2003–04 Upper Deck Exquisite RPA LeBron James
Image Credit: Heritage Auctions

At the very top of modern basketball cards sits the 2003–04 Upper Deck Exquisite Collection Rookie Patch Autograph (RPA) LeBron James, numbered to just 23 copies. It combines a jumbo patch, on-card autograph, and extremely low print run from a premium brand. Upper Deck

One parallel of this card graded BGS 9 with a 10 autograph sold privately in 2021 for about $5.2 million, tying the record for the most expensive sports card at the time. Another copy graded BGS 8.5 sold at auction in 2022 for roughly $885,000.

Chances are you don’t have one of the 23 RPAs sitting in a binder. But this card shows how far the very best modern rookies can go. If you ever come across any Exquisite LeBron with a patch and autograph, treat it gently and verify the exact card number and serial numbering before doing anything. Even “lesser” Exquisite LeBron cards can still bring six-figure prices.

2009–10 National Treasures Stephen Curry Logoman rookie 

2009–10 National Treasures Stephen Curry Logoman rookie 
Image Credit: Heritage Auctions

Stephen Curry’s 2009–10 Playoff National Treasures Rookie Logoman Autograph #206 is a one-of-a-kind card: NBA logo patch, on-card signature, and the only copy printed. It has become the modern template for a “holy grail” basketball card.

In 2021, this 1/1 Curry Logoman, graded PSA 8 with a 10 autograph, sold in a private transaction at a valuation of about $5.9 million, setting a record for any basketball card at the time. Later roundups of top sports card sales still list that $5.9 million Curry as one of the most valuable cards ever sold.

You’re not going to pull this from a random box, it’s already in the hands of high-end investors. But it’s worth knowing because it raises interest in all Curry National Treasures rookies, even the more common jersey-auto versions. If you spot any 2009 National Treasures Curry patch autograph in your collection, slow down and research before you sell, even if the patch doesn’t show the full Logoman.

2013–14 Panini Prizm Silver Giannis Antetokounmpo rookie

2013–14 Panini Prizm Silver Giannis Antetokounmpo
Image Credit: Castle_card via eBay

Giannis’s true rookie in the 2013–14 Panini Prizm set has several parallels, but the Silver Prizm #290 is the one most collectors gravitate toward. It’s a shorter-printed, shiny version of his base rookie that tracks closely with his rise from skinny prospect to MVP and champion. Panini

Recent data shows raw Silvers selling for a wide range, from about $1,000 to $2,600 depending on centering and surface. One ungraded Silver closed for about $2,600 in late 2025. PSA 10 copies are jumping much higher, with recent gem-mint sales around $7,500 and some big eye-appeal examples going for more.

Giannis Prizm Silvers are frequently counterfeited or altered, so compare your card to authenticated examples. Check the “Prizm” stamp on the back, the silver finish, and the subtle rainbow shine. Scratches and surface dimples will crush the grade, so it may not be worth grading a card that looks like it slid around loose in a shoebox for years.

2018–19 Panini Prizm Silver Luka Dončić rookie 

2018–19 Panini Prizm Silver Luka Doncic rookie
Image Credit: Heritage Auctions

Luka’s hobby popularity exploded fast, and his 2018–19 Panini Prizm Silver #280 has become one of the modern benchmarks for star rookies. It’s more attainable than his ultra-rare Logoman, but still expensive enough to matter for a regular household.

Recent sales show raw Silver Prizms closing between about $430 and $650, with one ungraded copy selling for $649 in February 2026. PSA 10s and other gem-mint grades can bring roughly $1,500 or more, while strong PSA 9s trade hands in the mid-hundreds. For a card that many people stashed in binders during Luka’s early years, that’s meaningful money.

When you examine a Luka Silver, tilt it under good light to look for print lines and fingerprint smudges. These glossy cards pick up tiny scratches easily. If it looks clean, centering is decent, and the corners are sharp, getting it graded could turn a $600 card into something closer to $1,500, but only if it lands a top grade.

1992 Topps Shaquille O’Neal rookie

Topps Shaquille ONeal rookie
Image Credit: Heritage Auctions

Not every “worth money” card has to be vintage. The 1992 Topps #362 Shaquille O’Neal rookie was mass-produced, but there’s still solid demand for clean copies, especially in top grades.

Recent sales data shows the regular base rookie selling raw for just a few dollars, but professionally graded gem-mint PSA 10 copies average around $140. That’s not retirement money, but it’s enough to cover a utility bill or a couple tanks of gas. Rarer Gold parallel versions, especially in strong grades, can go for even more.

If you’ve got Shaq rookies stacked in a box, pull out the ones with sharp corners, bright color, and no visible surface scratches. Those are the only ones worth considering for grading. Lower-grade copies are best sold as a small lot, think “Shaq rookie bundle”, which can bring in more than tossing them into a random bulk box.

Strategies for making money outside of a traditional job:

freelance writer
Image Credit: Shutterstock

Where to sell sterling silver for the most money: In this post, you’ll learn about the difference between sterling silver and other types of silver, and find places to make the most money from selling your sterling.

What can I sell to make money (or resell)? 38 ideas: Dive into this article to discover things in your house you can sell for quick cash — and where to sell.

What sells quickly at pawn shops: In this post, you’ll find ways to navigate pawnshops, understand how they work and what items are most in demand.

Byline: Katy Willis